
Contraception, menopause and bone care anchor demand
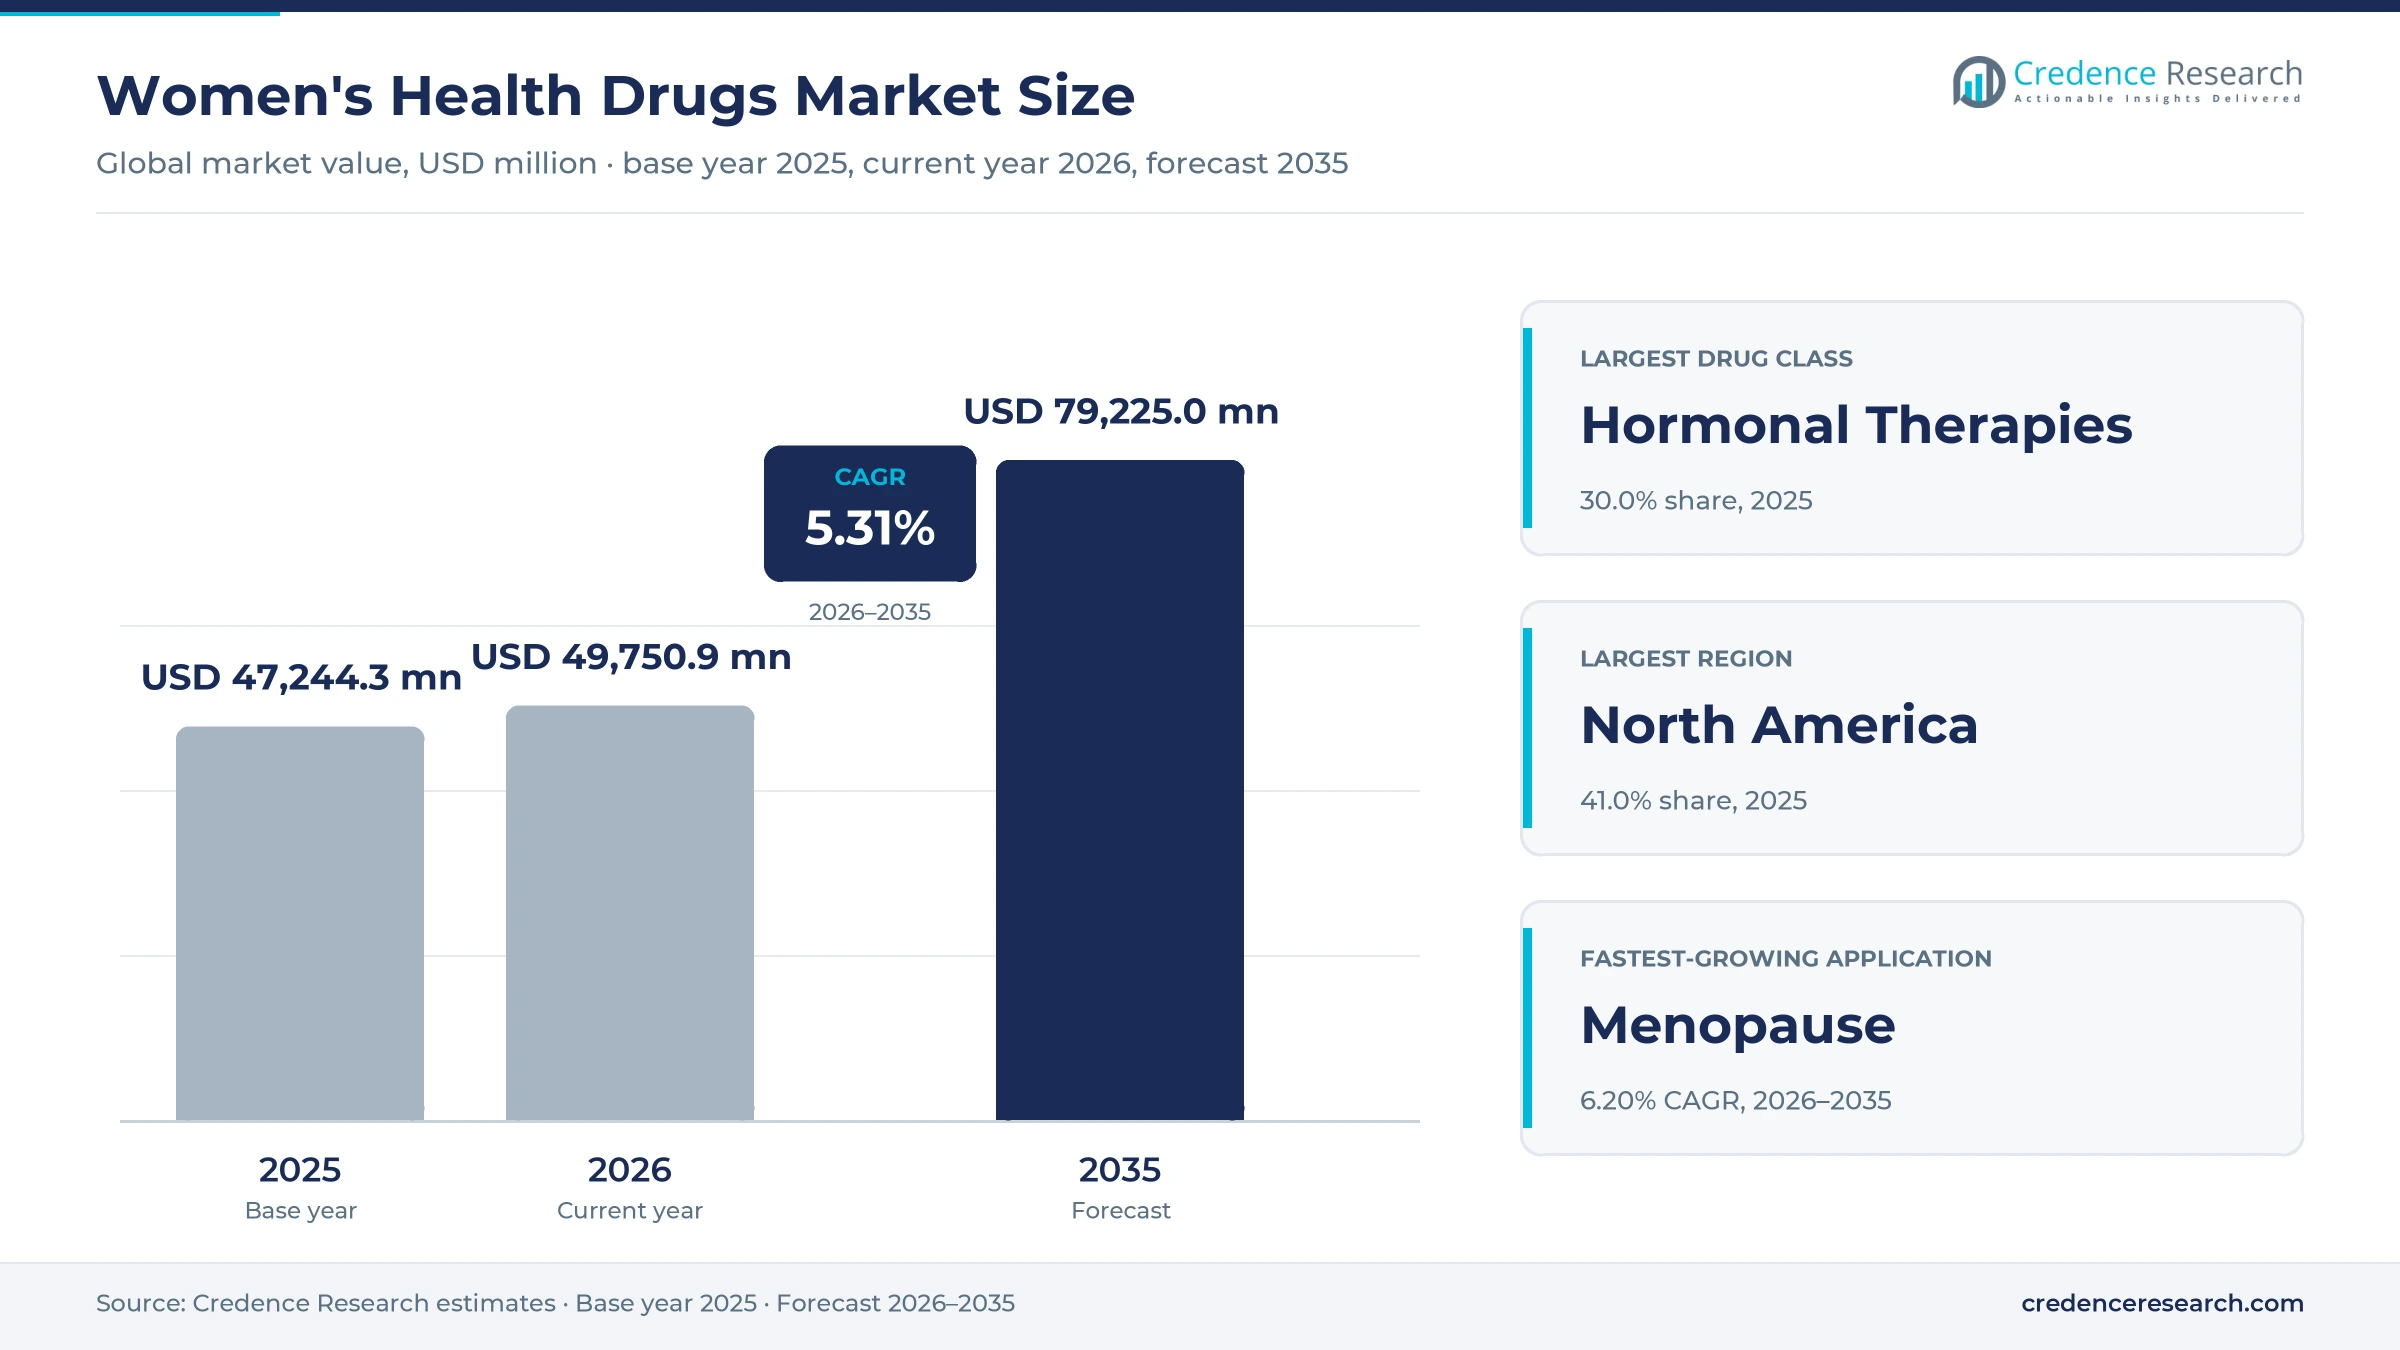
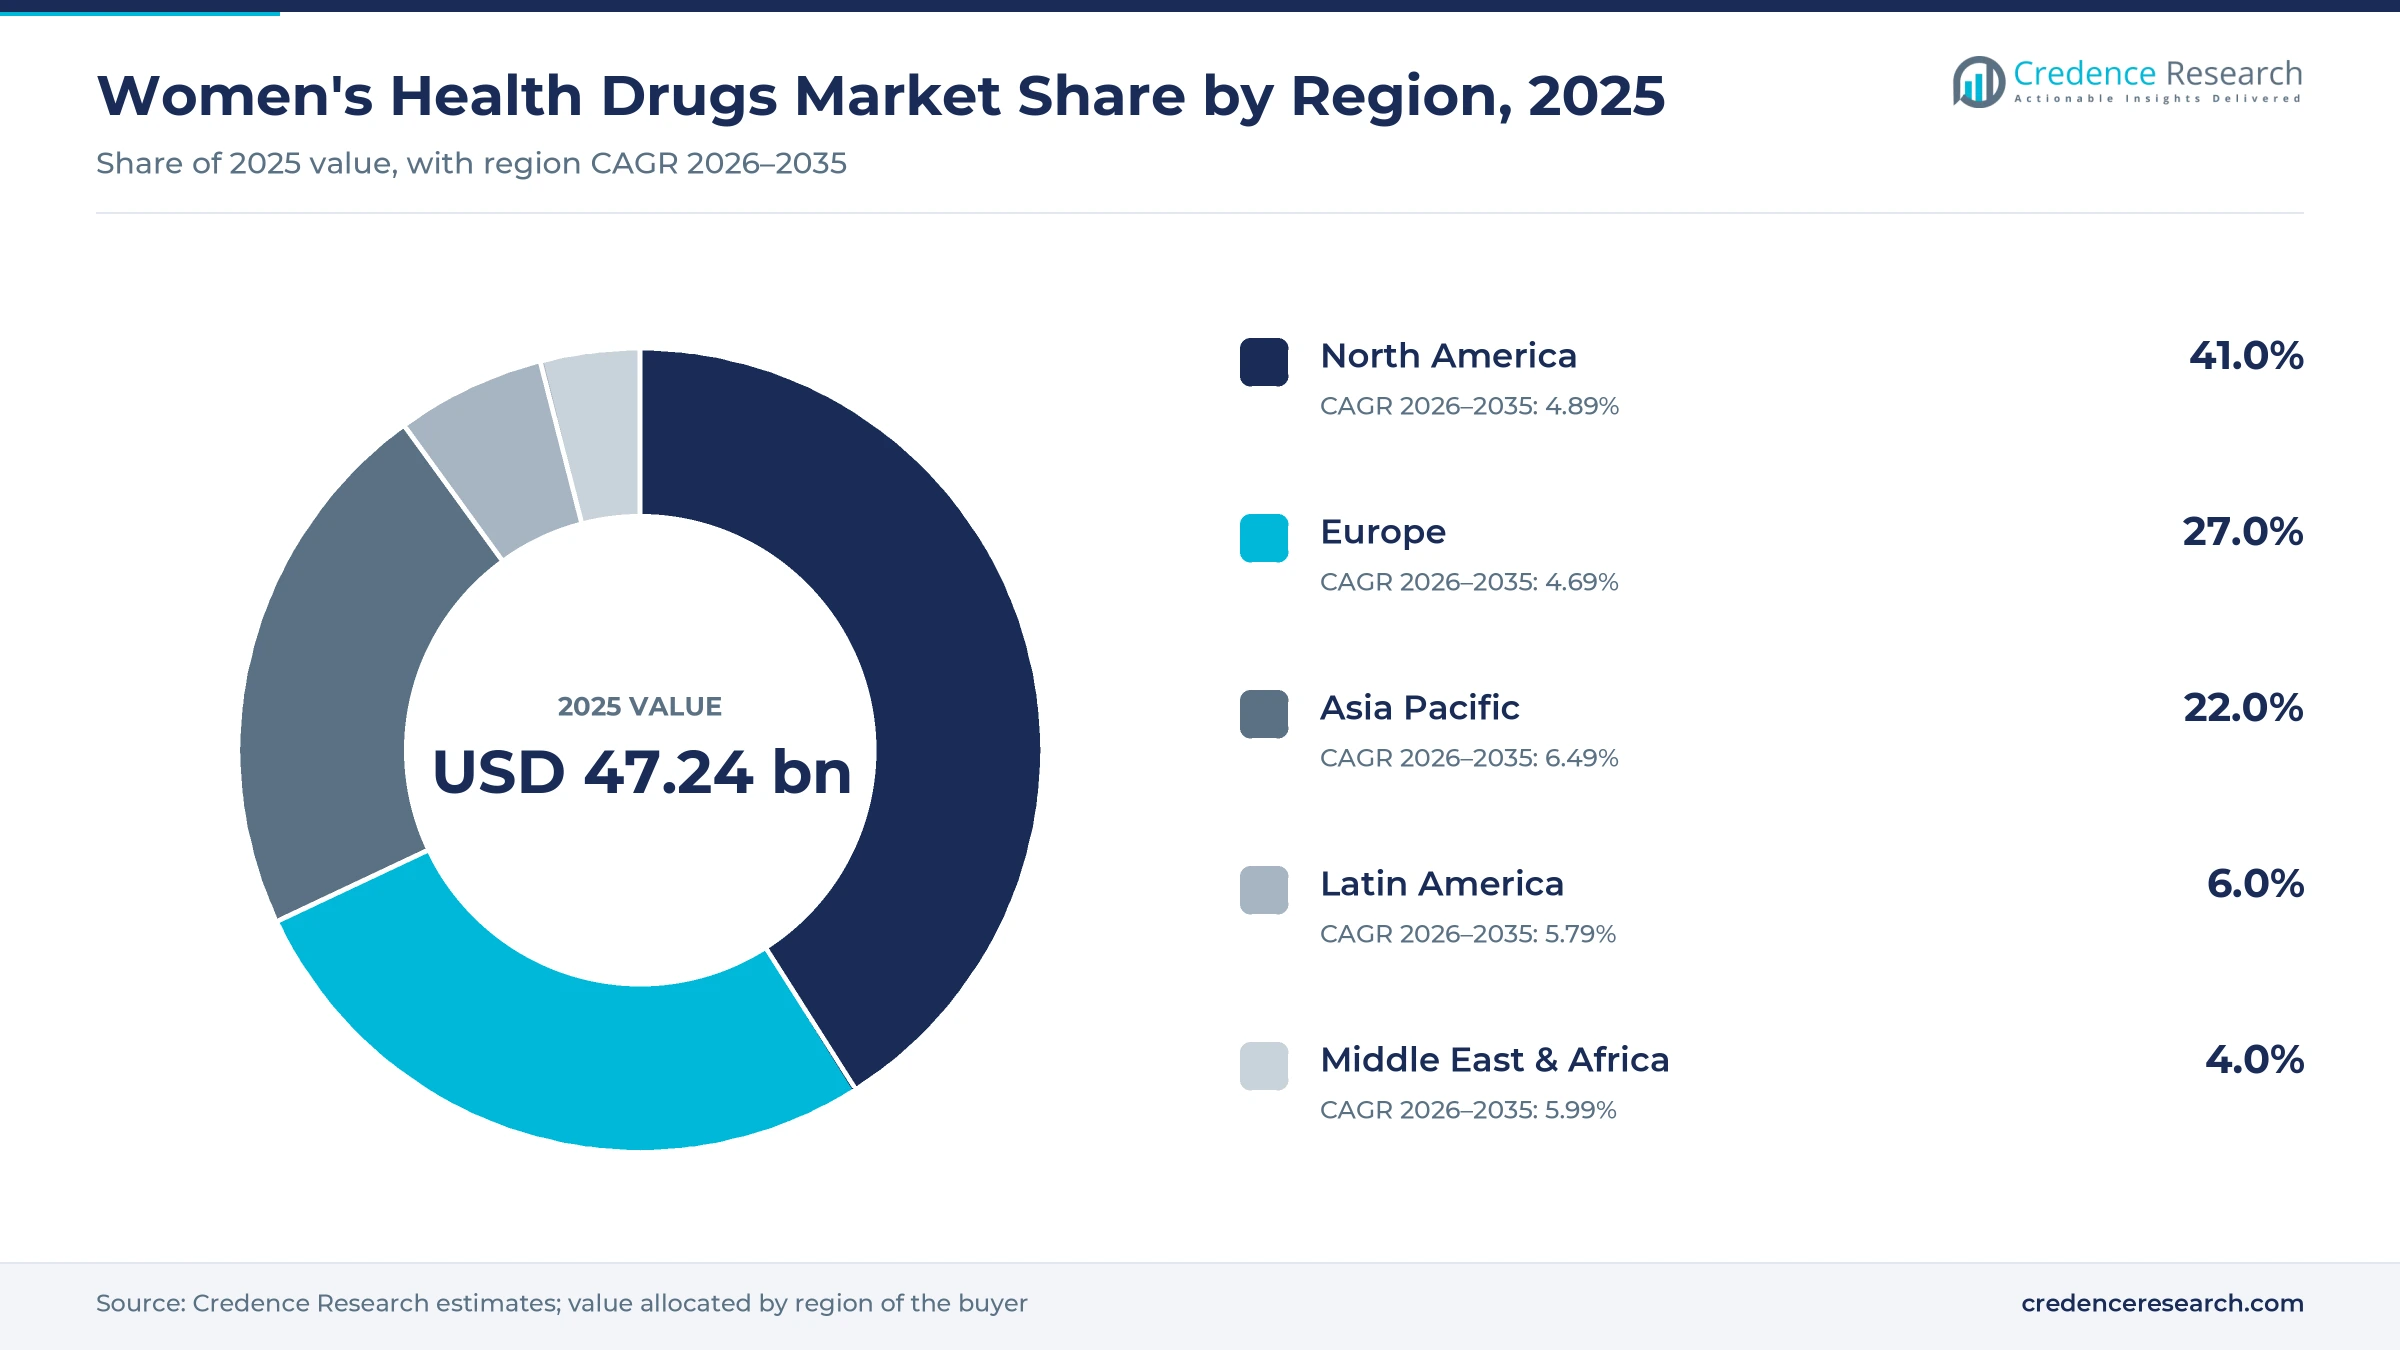
The global women's health drugs market was valued at USD 47.24 billion in 2025 and is projected to increase from USD 49.75 billion in 2026 to USD 79.22 billion by 2035, registering a CAGR of 5.31% during 2026–2035. Demand comes from the large number of women who use contraception, a growing population in and after menopause, and steady treatment of bone loss, infertility, endometriosis and polycystic ovary syndrome. North America held the largest regional share, 41.0% in 2025, because the United States combines high prescription use, branded menopause and bone therapies and broad insurance coverage. Asia Pacific is the fastest-growing region at 6.49% a year, as China, India and Southeast Asia widen access to family planning and fertility care. The regulatory picture changed in November 2025, when U.S. authorities began removing boxed warnings from menopausal hormone therapy labels. As a result, more women and doctors may consider hormone treatment for menopause symptoms.
Which medicines sit inside and outside the scope here?
Prescription and over-the-counter medicines used for female reproductive and post-reproductive conditions are counted here, including hormonal contraceptives, menopause therapies, bone health agents, fertility agents, GnRH modulators, symptom relief medicines and metabolic agents used for polycystic ovary syndrome. Values are based on manufacturer selling prices across branded, generic and biosimilar products.
Medical devices, diagnostic tests, fertility clinic services and dietary supplements sit outside the scope of this analysis. The value chain runs from active ingredient makers through originator, generic and biosimilar companies and distributors to hospital, retail and online pharmacies that dispense medicines to patients.
Women's Health Drugs Market Insights
- The women's health drugs market grows from USD 47.24 billion in 2025 to USD 79.22 billion by 2035, a 5.31% CAGR, as menopause, bone and fertility care expand.
- North America held 41.0% of global women's health drugs value in 2025, supported by high prescription use and branded therapies.
- Hormonal therapies led drug class spending with 30.0% of 2025 value, while symptom relief medicines grow fastest at 6.15% a year.
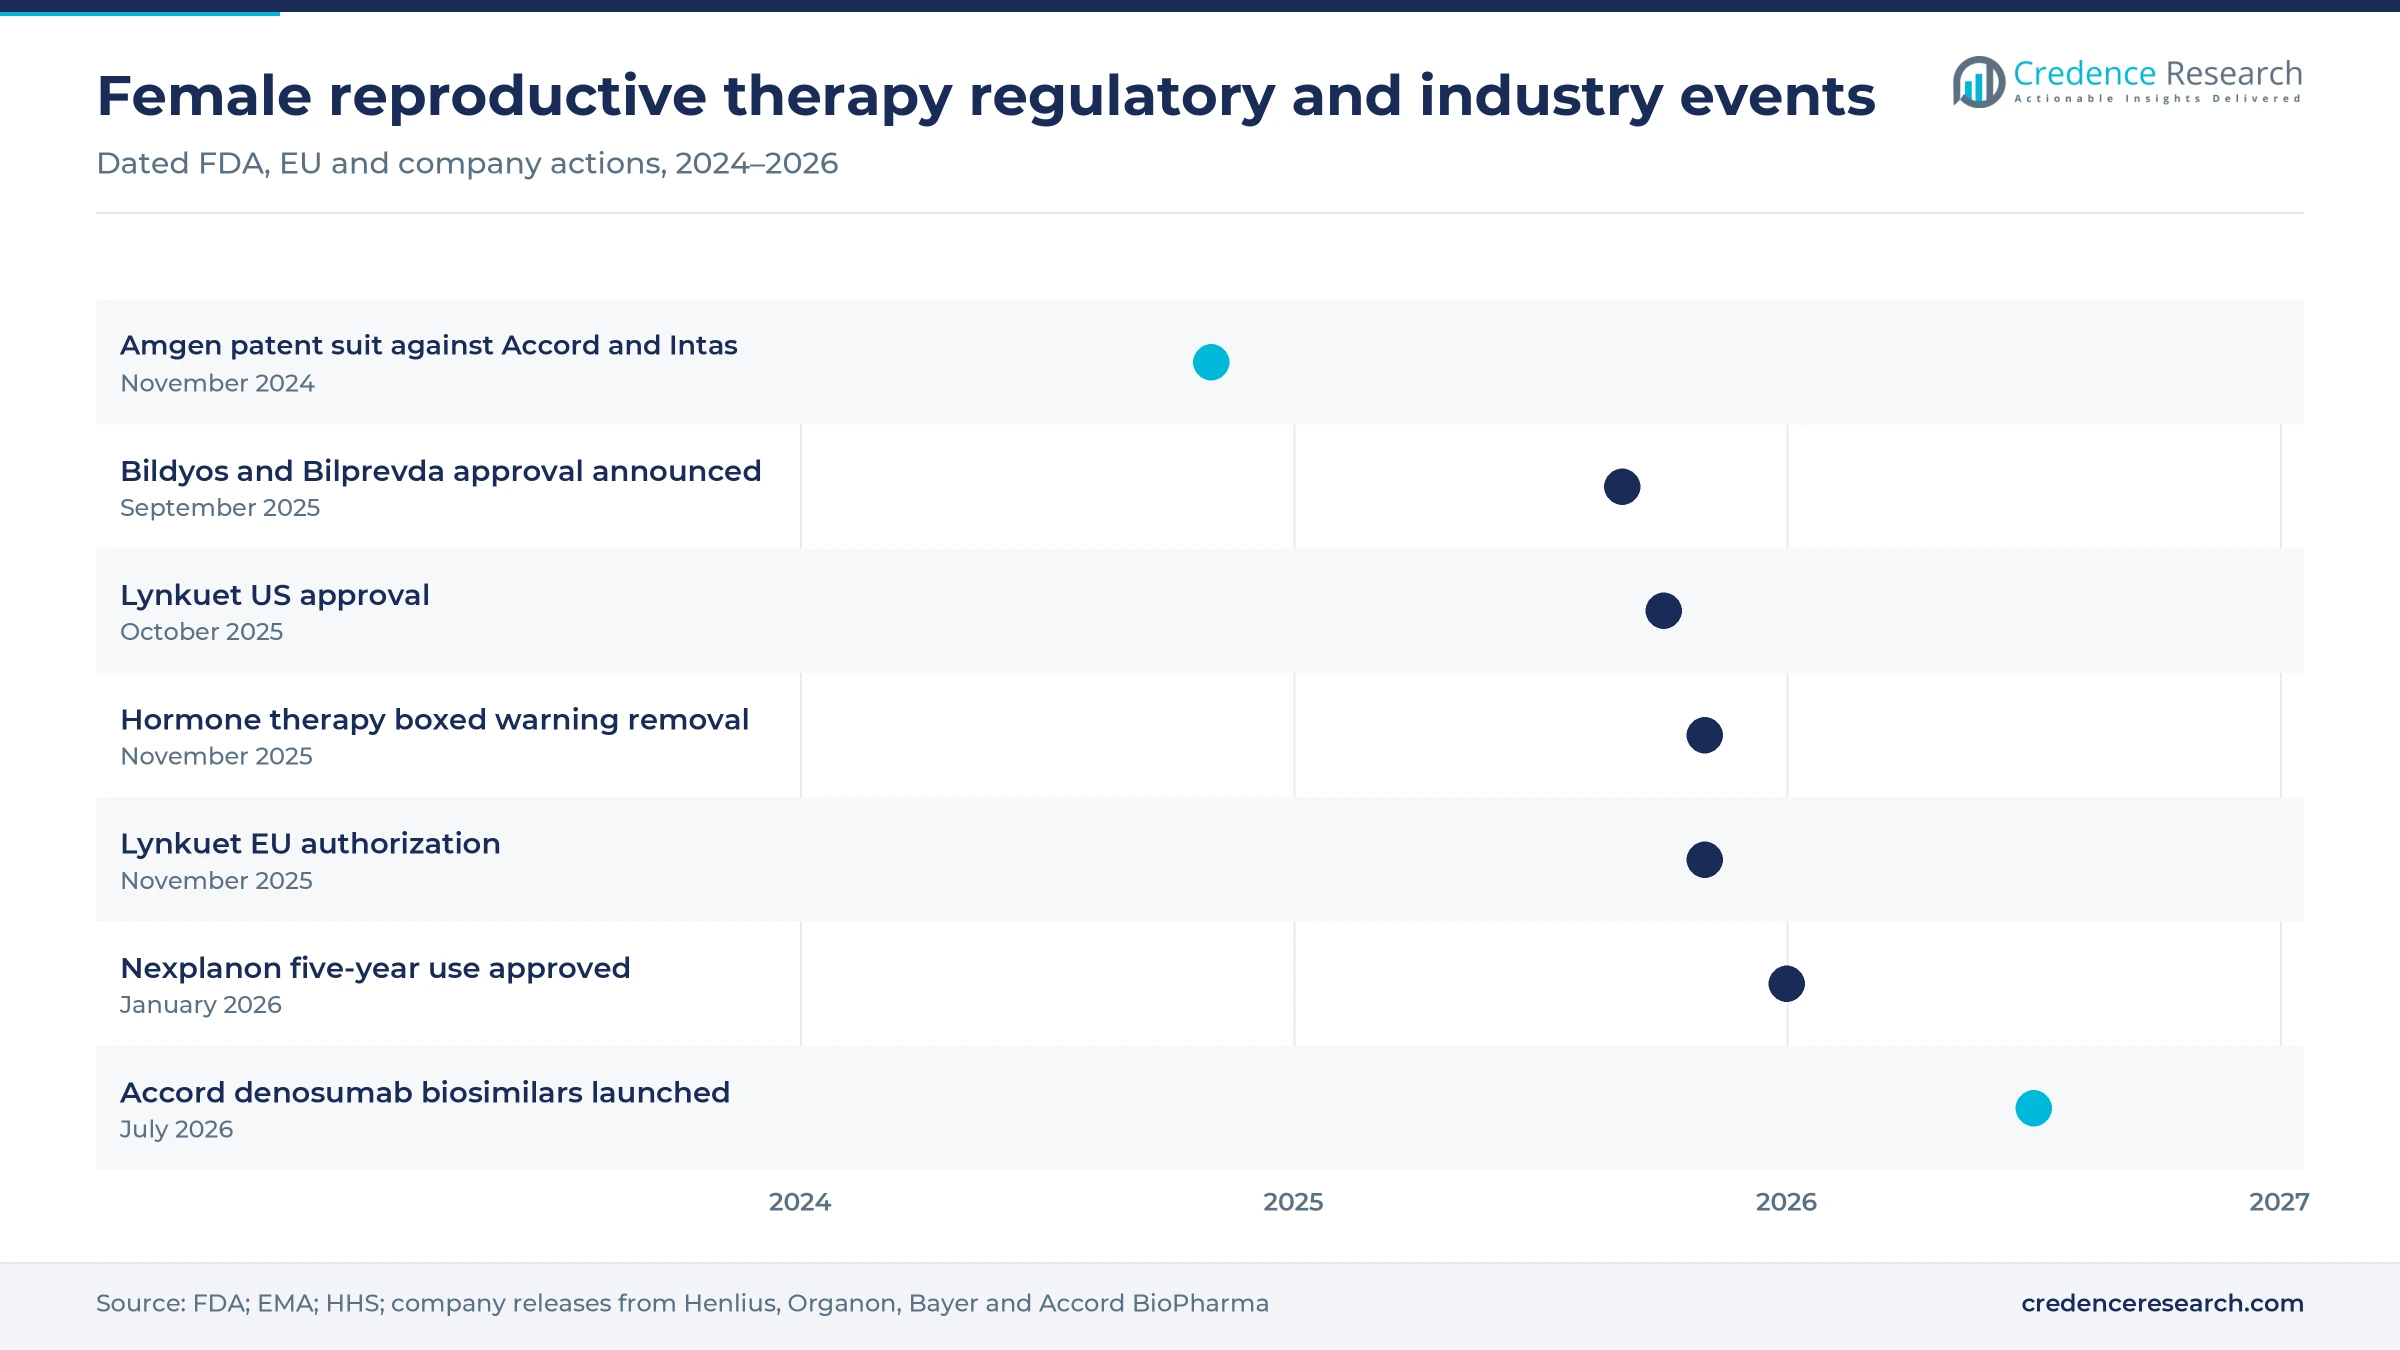
- In October 2025, the U.S. regulator approved Lynkuet from Bayer, the first dual neurokinin 1 and 3 receptor blocker for menopausal hot flashes.
- In November 2025, Accord BioPharma received U.S. approval for denosumab biosimilars, adding price competition in postmenopausal bone care.
Hormonal therapies lead while symptom relief grows fastest
Why do hormonal therapies lead drug class spending?
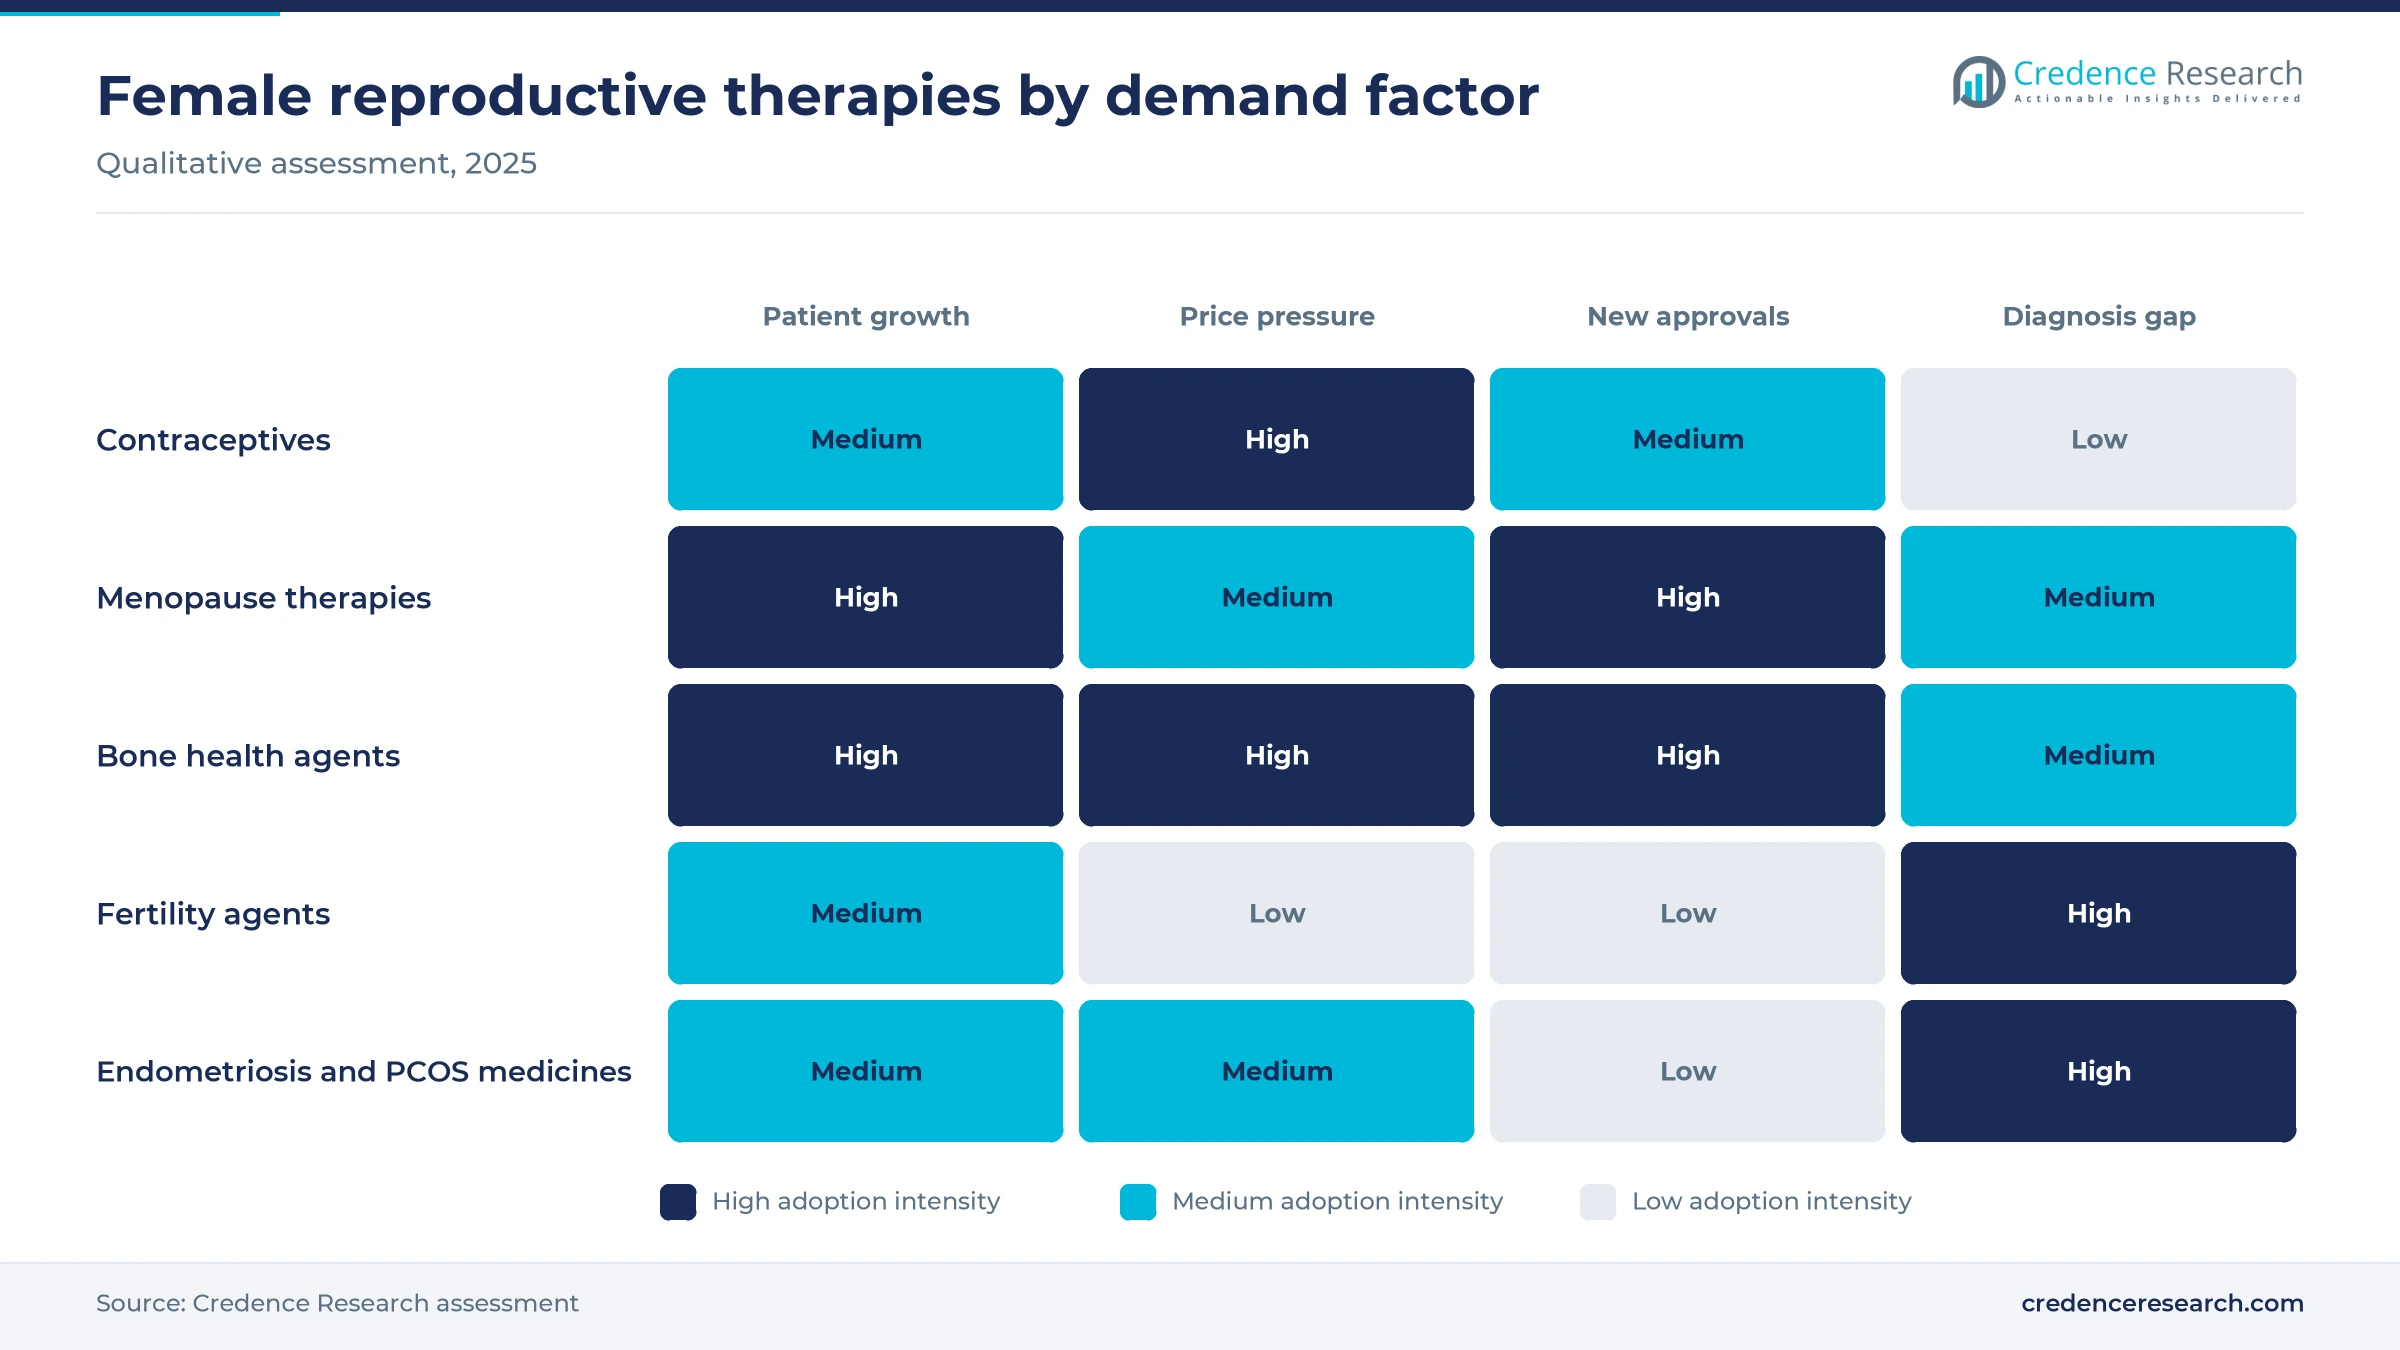
Based on drug class, the market is categorized into hormonal therapies, bone health agents, fertility agents, GnRH modulators, pain and symptom management, metabolic agents and others. Hormonal Therapies led with 30.0% of 2025 value, because contraceptives and menopause hormone products are used every day for many years. Pain and Symptom Management grows fastest at 6.15% a year, as non-hormonal medicines for hot flashes reach new patients.
Which conditions account for most prescriptions?
Based on application, the market is categorized into hormonal infertility, contraceptives, postmenopausal osteoporosis, endometriosis and uterine fibroids, menopause and polycystic ovary syndrome. Contraceptives led with 29.0% of 2025 value, because hundreds of millions of women use modern methods. Menopause grows fastest at 6.20% a year, as new non-hormonal options and revised hormone therapy labels widen treatment.
Where do patients collect these medicines?
Based on distribution channel, the market is categorized into hospital pharmacy, retail pharmacy, online pharmacy and others. Retail Pharmacy led with 46.0% of 2025 value, because women refill contraceptives and menopause medicines at local stores each month. Online Pharmacy grows fastest at 6.66% a year, as telehealth prescribing and home delivery of birth control spread.
| Segment Group | Leading Sub-segment | Share, 2025 | Fastest-growing Sub-segment | CAGR, 2026–2035 |
|---|---|---|---|---|
| By Drug Class | Hormonal Therapies | 30.0% | Pain and Symptom Management | 6.15% |
| By Application | Contraceptives | 29.0% | Menopause | 6.20% |
| By Distribution Channel | Retail Pharmacy | 46.0% | Online Pharmacy | 6.66% |
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Contraceptive need, menopause care and bone loss lift demand
How does contraceptive need sustain the largest application?
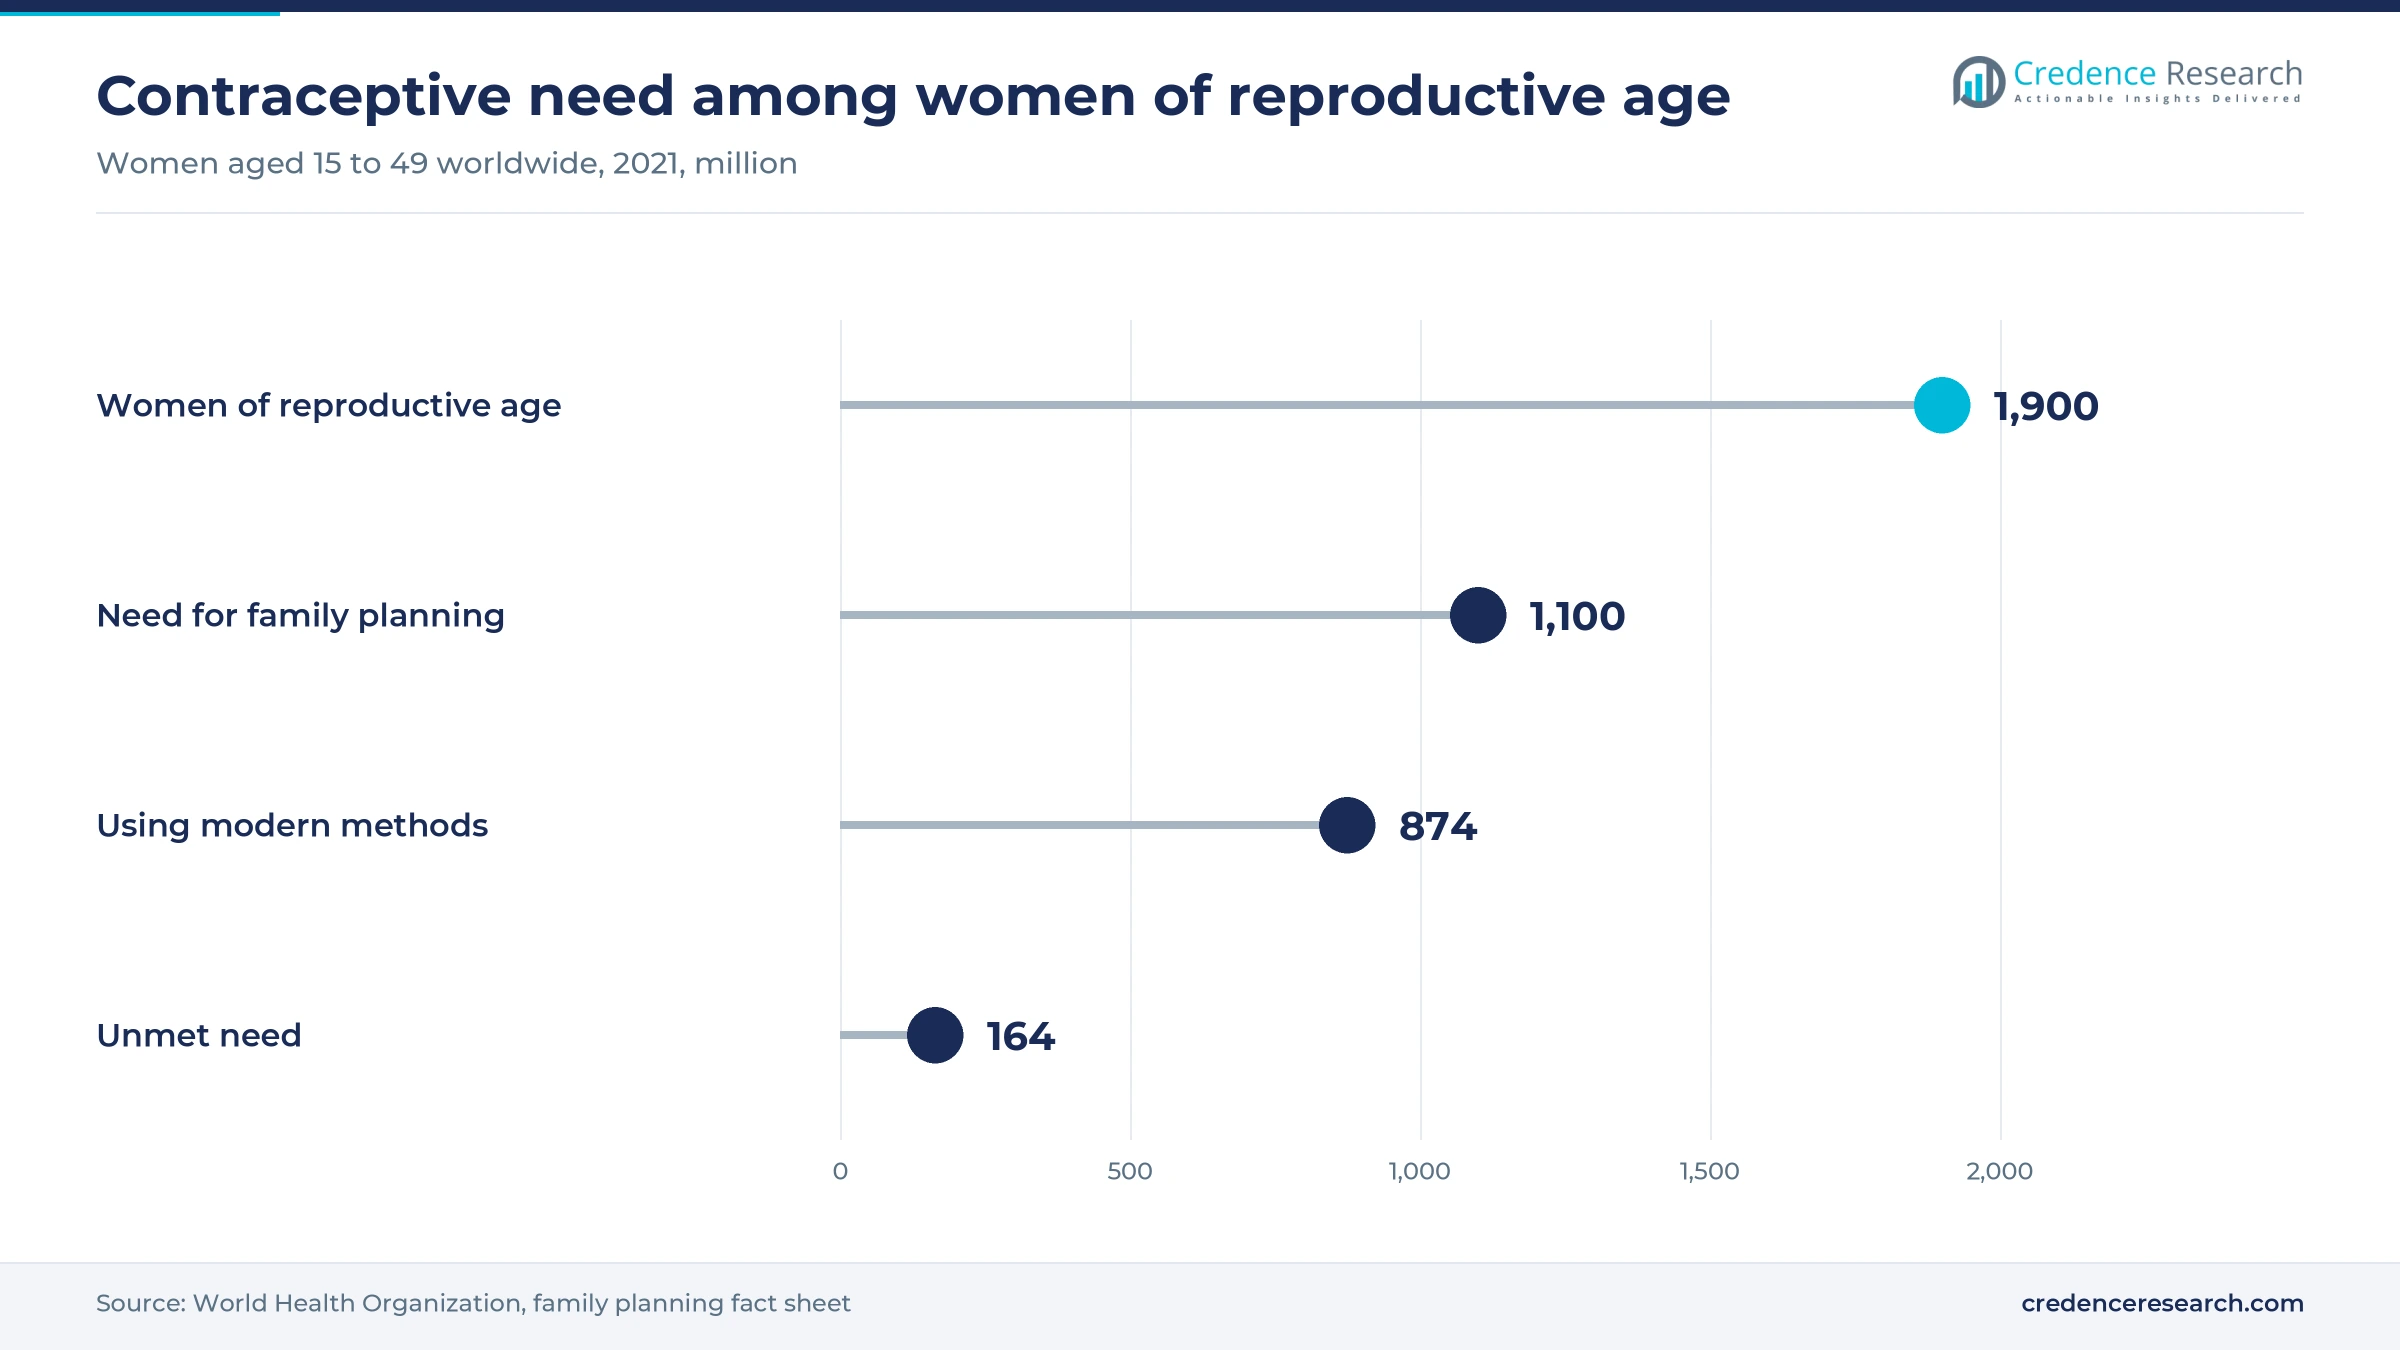
Hundreds of millions of women rely on modern contraception every year, which makes birth control the steadiest source of prescriptions. The World Health Organization reports that 874 million women used modern contraceptive methods in 2021, out of 1.9 billion women of reproductive age. The same source counts 164 million women with an unmet need for contraception, which leaves a large group still to reach. In January 2026, Organon received FDA approval to extend use of its Nexplanon implant to up to five years, which lengthens protection from a single procedure. As a result, contraceptive medicines held 29.0% of 2025 application value, the largest share of any condition.
Why does the menopause population support new prescriptions?
Most women reach menopause between the ages of 45 and 55, according to the World Health Organization, and many face hot flashes and sleep problems for years. On Oct. 24, 2025, the U.S. regulator approved Lynkuet from Bayer, based on the phase 3 OASIS program, as the first dual neurokinin 1 and 3 receptor blocker for moderate to severe hot flashes. The European Union granted marketing authorization for Lynkuet on Nov. 17, 2025. These approvals give women who cannot take hormones, including many breast cancer survivors, a new prescription option. As a result, menopause grows at 6.20% a year, the fastest rate among applications.
How does bone loss after menopause sustain long treatment courses?
Falling estrogen speeds bone loss in the years after menopause, so many women take bone medicine for long periods to prevent fractures. In September 2025, Henlius announced that the FDA had approved Bildyos and Bilprevda, biosimilars to Prolia and Xgeva, with Organon handling U.S. sales. Bildyos treats osteoporosis in postmenopausal women and in men, among other uses. Accord BioPharma then received FDA approval for its own denosumab biosimilars, Osvyrti and Jubereq, on Nov. 20, 2025. Postmenopausal women represent the largest patient group for these bone medicines, according to the companies. As a result, osteoporosis treatment remains a large part of spending, and Europe, with aging populations, still grows at 4.69% a year.
Why do undiagnosed reproductive conditions widen the treatment pool?
Endometriosis, polycystic ovary syndrome and infertility often remain hidden for years, so each gain in awareness adds treated patients. The World Health Organization estimates that endometriosis affects about 10% of reproductive age women, or 190 million worldwide. It also estimates that polycystic ovary syndrome affects 10% to 13% of reproductive-aged women, and up to 70% of them do not know they have the condition. The agency adds that about one in six people of reproductive age experience infertility in their lifetime. As a result, fertility agents and GnRH modulators grow faster than older hormone products, and Latin America grows at 5.79% a year.
Non-hormonal relief and bone biosimilars gain pace
How is non-hormonal symptom relief shifting menopause care?
Women who cannot or will not take hormones now have more prescription choices for hot flashes. Bayer gained U.S. approval for Lynkuet on Oct. 24, 2025, and European Union authorization followed on Nov. 17, 2025, covering vasomotor symptoms linked to menopause or to endocrine therapy for breast cancer. The drug blocks two neurokinin receptors that help control body temperature at night and during the day. Doctors can now offer these medicines to breast cancer survivors, who often must avoid estrogen. In turn, non-hormonal menopause options gain attention, and pain and symptom management grows at 6.15% a year, the fastest pace of any drug class.
Why is interest in hormone therapy rising again?
U.S. regulators changed their stance on menopausal hormone therapy in late 2025, after decades of class-wide warnings. On Nov. 10, 2025, the Department of Health and Human Services and the FDA announced actions to revise safety labels, including removal of boxed warnings. The review drew on studies published since the original Women's Health Initiative trials and on a July 2025 FDA expert panel. These changes may encourage more doctors to prescribe hormone replacement therapy for symptom relief. As a result, hormonal therapies remain the largest drug class, and North America, the largest region, grows at 4.89% a year through 2035.
Can denosumab biosimilars open wider bone care access?
Lower-priced copies of a leading bone medicine give generic makers a clear opening in postmenopausal care. Accord BioPharma, part of Intas, announced FDA approval for Osvyrti and Jubereq on Nov. 20, 2025, for all reference indications. Accord planned a U.S. launch in 2026 and launched both products by July 2026. Organon and Henlius also gained approval for their own versions in September 2025, so several suppliers now compete on price in the same U.S. market. As a result, more women may start bone treatment, while value growth in this class stays close to the overall market rate, because lower prices offset higher volumes.
Where can long-acting and online options add value?
Women increasingly want fewer refills and clinic visits, so suppliers of long-acting methods and online services can add value. Organon received FDA approval in January 2026 to extend use of its Nexplanon arm implant to up to five years, with data covering women with overweight or obesity. Telehealth services also let women renew contraceptives and menopause medicines from home. The WHO count of 164 million women with an unmet need for contraception shows how much room remains. As a result, online pharmacy grows at 6.66% a year, and Asia Pacific, with 22.0% of 2025 value, adds many new users each year.
Safety fears, diagnosis gaps and price cuts slow growth
How do lingering safety fears limit hormone use?
Many women and doctors still remember warnings about breast cancer and stroke from the Women's Health Initiative trials of the 2000s. Some patients avoid hormone therapy even after the U.S. label changes of November 2025. Outside the United States, regulators have not all made the same label changes, so prescribing habits differ by country. As a result, uptake of hormone therapy recovers slowly, and companies invest in education for doctors and patients.
Where do long diagnosis delays hold back treatment?
Endometriosis and polycystic ovary syndrome often take years to diagnose, because symptoms overlap with common menstrual complaints. Primary care doctors may lack the training or imaging access needed to confirm these conditions early, so referrals take time. Women in low-income countries usually face the longest delays before a confirmed diagnosis. In turn, many patients receive only pain relief rather than targeted endometriosis care or GnRH modulators, which delays effective treatment.
Why do generics and biosimilars squeeze branded prices?
Most oral contraceptives and older hormone products now sell as low-priced generics from companies such as Lupin, Teva and Mylan. Denosumab biosimilars launched in 2025 and 2026 add further price cuts in bone care. Public payers and insurers push patients toward the cheapest equivalent product, and pharmacies often switch brands automatically. As a result, value growth trails the growth in treated women, especially in mature markets such as Europe and Japan.
How do access and cost barriers limit use in poorer regions?
Women in many low- and middle-income countries pay for contraceptives, fertility agents and menopause medicines themselves. Fertility drugs carry high prices and are rarely covered by public insurance, so infertility treatment stays out of reach for many couples. Supply gaps in rural clinics also interrupt regular contraceptive use for many women. However, donor programs and local generic makers continue to widen access over time, especially for contraceptives.
North America leads as Asia Pacific expands fastest
| Region | Value, 2025 (USD billion) | Share, 2025 | CAGR, 2026–2035 |
|---|---|---|---|
| North America | 19.37 | 41.0% | 4.89% |
| Europe | 12.76 | 27.0% | 4.69% |
| Asia Pacific | 10.39 | 22.0% | 6.49% |
| Latin America | 2.83 | 6.0% | 5.79% |
| Middle East & Africa | 1.89 | 4.0% | 5.99% |
How do U.S. prescriptions and branded launches support leadership?
North America held a 41.0% share of 2025 value and grows at 4.89% a year through 2035. The United States drives this position, because branded menopause, bone and fertility medicines sell at high prices and most women have insurance coverage. The Lynkuet approval and revised hormone therapy labels in 2025 add new prescriptions. Generic and biosimilar entry still limits price growth for older products.
How do large populations and wider access lift Asia Pacific?
Asia Pacific held a 22.0% share of 2025 value and is the fastest-growing region at 6.49% a year. China and India have the largest populations of women of reproductive age, and both are widening access to family planning and fertility care. Japan and South Korea add demand for menopause and bone medicines as their populations age. Lupin, Intas and other regional generic makers supply much of the volume.
What shapes demand across Europe?
Europe held a 27.0% share of 2025 value and grows at 4.69% a year, the slowest pace of the five regions. Germany, France, Italy and the United Kingdom account for much of the spending, and Bayer and Ferring Pharmaceuticals are strong regional suppliers. National health systems buy through tenders and reference pricing that favor generics. However, the November 2025 European Union authorization of Lynkuet adds a new branded option.
Where is Latin America adding demand?
Latin America held a 6.0% share of 2025 value and grows at 5.79% a year through 2035. Brazil and Mexico lead regional demand, because both have large populations of women of reproductive age and growing private pharmacy chains. However, out-of-pocket costs still limit use of branded fertility and bone medicines.
How do Gulf health budgets and African supply gaps differ?
The Middle East and Africa held a 4.0% share of 2025 value and grows at 5.99% a year through 2035. Gulf states fund fertility care and modern pharmacies, while much of Africa relies on donor-supported contraceptive programs. Low-cost generics therefore offer the largest growth opening across the region.
Approvals, label changes and biosimilars since 2024
| Development | Status and market relevance |
|---|---|
| In September 2025, Henlius and Organon announced FDA approval of Bildyos and Bilprevda, denosumab biosimilars to Prolia and Xgeva. | Approved; Organon handles U.S. sales for postmenopausal bone care |
| In October 2025, the FDA approved Lynkuet from Bayer for moderate to severe hot flashes due to menopause. | Approved; first dual neurokinin 1 and 3 receptor blocker |
| In November 2025, U.S. health authorities announced the removal of boxed warnings from menopausal hormone therapy labels. | Label changes requested; may widen hormone therapy use |
| In November 2025, Accord BioPharma received FDA approval for Osvyrti and Jubereq, denosumab biosimilars. | Approved; U.S. launch completed by July 2026 |
| In January 2026, Organon received FDA approval to extend use of the Nexplanon implant to up to five years. | Approved; longer protection from one implant |
Neurokinin blockers, long-acting implants and biosimilars
- Neurokinin receptor blockers act on brain signals that control body temperature, which relieves hot flashes without estrogen.
- Long-acting implants release contraceptive hormone for up to five years, which removes the need for daily pills.
- Denosumab biosimilars copy a leading bone medicine at lower prices, which can widen access to fracture prevention.
- Oral GnRH modulators lower hormone levels with a daily pill, which helps manage endometriosis pain and uterine fibroid bleeding.
- Telehealth prescribing lets women renew contraceptives and menopause medicines online, which reduces clinic visits and refill gaps.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Originators and generic makers compete on access
Competition splits into branded originators, fertility specialists and generic makers, with a few companies active across several areas. Bayer AG and Organon & Co. lead branded contraception and menopause care, and Bayer added Lynkuet in 2025. Organon also sells denosumab biosimilars in the United States and the Nexplanon arm implant. Ferring Pharmaceuticals focuses on fertility and reproductive medicine, while Pfizer, Inc. supplies hormone and bone products. Teva Pharmaceutical Industries Ltd., Mylan N.V., Lupin Limited and Intas Pharmaceutical Ltd compete on low-cost generic contraceptives and biosimilars, often winning large pharmacy and tender contracts. Apothecus Pharmaceutical Corp. and Blairex Laboratories serve over-the-counter needs through retail and online stores. As a result, buyers weigh new mechanisms against price, and suppliers with broad portfolios win more pharmacy and payer contracts.
Companies profiled and their roles in this market
| Company | Type | Role in the market |
|---|---|---|
| Bayer AG | Originator | Contraceptives, menopause therapy and Lynkuet for hot flashes |
| Organon & Co. | Originator | Nexplanon implant, contraceptives and denosumab biosimilars |
| Pfizer, Inc. | Originator | Hormone therapy and bone health products |
| Ferring Pharmaceuticals | Specialist | Fertility and reproductive medicines |
| Teva Pharmaceutical Industries Ltd. | Generic | Low-cost contraceptives and hormone products |
| Mylan N.V. | Generic | Copies of contraceptives and hormone products |
| Lupin Limited | Generic | Oral contraceptive copies for the U.S. and other markets |
| Intas Pharmaceutical Ltd | Generic | Denosumab biosimilars through Accord BioPharma |
| Apothecus Pharmaceutical Corp. | Specialist | Over-the-counter contraceptive products |
| Blairex Laboratories | Specialist | Over-the-counter personal care products |
Menopause and bone care set the growth pace to 2035
Credence Research's view is that menopause and bone care will set the pace of growth through 2035, because the number of women in and after menopause keeps rising. The overall market grows at 5.31% a year, supported by contraception, new non-hormonal options and revised hormone therapy labels. Symptom relief medicines and online pharmacy grow faster than the market. Companies that pair new mechanisms with access programs will gain share, while generics and biosimilars will keep pressure on prices for older products.
How Credence Research sized female reproductive therapies
The report uses 2025 as the base year and 2026 to 2035 as the forecast period. Market values come from the Credence Research model, which builds spending by drug class, application, distribution channel and region. Regional and segment splits are Credence Research estimates informed by World Health Organization data, U.S. and European regulator records, clinical and legal publications and company press releases. No primary interviews or surveys were used in preparing this edition of the report.
Female reproductive and menopause therapy outlook to 2035
By 2035, the women's health drugs market is projected to reach USD 79.22 billion, with growth led by menopause care, bone health and fertility treatment. Hormonal therapies will remain the largest drug class, as contraceptives and hormone therapy stay in daily use. North America keeps the highest spending, while Asia Pacific adds the most newly treated women. Online pharmacy will take a larger share of value, because telehealth prescribing spreads. As a result, advantage will depend on new mechanisms, price and access.
Frequently Asked Questions
How big is the global women's health drugs market?
Which drug class leads spending?
Which region leads spending on these medicines?
Which application accounts for the most value?
What did the November 2025 hormone therapy label change do?
What recent approvals affect female reproductive therapies?
Who are the leading women's health drugs companies?
What restrains growth in female reproductive therapies?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Drug Class
- 1.2.1 Hormonal Therapies
- 1.2.2 Bone Health Agents
- 1.2.3 Fertility Agents
- 1.2.4 GnRH Modulators
- 1.2.5 Pain and Symptom Management
- 1.2.6 Metabolic Agents
- 1.2.7 Others
- 1.3 By Application
- 1.3.1 Hormonal Infertility
- 1.3.2 Contraceptives
- 1.3.3 Postmenopausal Osteoporosis
- 1.3.4 Endometriosis & Uterine Fibroids
- 1.3.5 Menopause
- 1.3.6 Polycystic Ovary Syndrome
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2025: USD 47.24 billion → 2035: USD 79.22 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Historical Period: 2018-2025
- 2.6.2 Base Year: 2025
- 2.6.3 Forecast Period: 2025-2035
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2025
- 3.3 Forecast Market Size, 2035
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Women's Health Drugs Market Trends and Developments
- 4.1 Historical Industry Development, 2018-2025
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Women's Health Drugs Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis, 2018-2025
- 5.2 Demand Forecast, 2025-2035
- 5.3 Production and Output Trend, 2018-2025
- 5.4 Production and Output Forecast, 2025-2035
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Women's Health Drugs Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends, 2018-2025
- 6.3 Pricing Outlook, 2025-2035
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Women's Health Drugs Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Women's Health Drugs Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Women's Health Drugs Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Women's Health Drugs Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Women's Health Drugs Market Outlook, 2025-2035
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2025: USD 47.24 billion → 2035: USD 79.22 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size, 2018-2025
- 11.1.4 Base-Year Market Size, 2025
- 11.2 Market Forecast, 2025-2035
- 11.2.1 Revenue Forecast to 2035
- 11.2.2 Volume Forecast to 2035
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Women's Health Drugs Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2025
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Drug Class - Market Size and Forecast, 2025-2035
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size, 2018-2025
- 12.3.3 Revenue Forecast, 2025-2035
- 12.3.4 Volume Forecast, 2025-2035
- 12.3.5 Base-Year Market Share, 2025
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Hormonal Therapies
- 12.3.7.2 Bone Health Agents
- 12.3.7.3 Fertility Agents
- 12.3.7.4 GnRH Modulators
- 12.3.7.5 Pain and Symptom Management
- 12.3.7.6 Metabolic Agents
- 12.3.7.7 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2025-2035
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size, 2018-2025
- 12.4.3 Revenue Forecast, 2025-2035
- 12.4.4 Volume Forecast, 2025-2035
- 12.4.5 Base-Year Market Share, 2025
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Hormonal Infertility
- 12.4.7.2 Contraceptives
- 12.4.7.3 Postmenopausal Osteoporosis
- 12.4.7.4 Endometriosis & Uterine Fibroids
- 12.4.7.5 Menopause
- 12.4.7.6 Polycystic Ovary Syndrome
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 Global Women's Health Drugs End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Women's Health Drugs Geographic Market Outlook, 2025-2035
- 14.1 Regional Market Size and Share, 2025
- 14.2 Regional Market Forecast, 2025-2035
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Women's Health Drugs Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2025-2035
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Women's Health Drugs Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2025
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2025-2035
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Bayer AG
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Organon & Co.
- 18.4 Pfizer, Inc.
- 18.5 Apothecus Pharmaceutical Corp.
- 18.6 Ferring Pharmaceuticals
- 18.7 Intas Pharmaceutical Ltd
- 18.8 Blairex Laboratories
- 18.9 Mylan N.V.
- 18.10 Lupin Limited
- 18.11 Teva Pharmaceutical Industries Ltd.
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

