
Market Overview
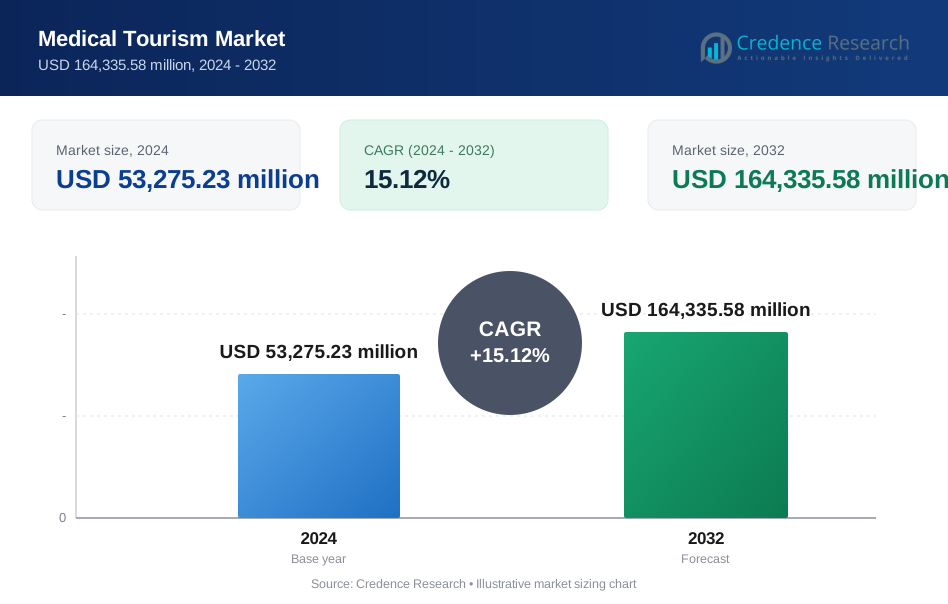
Global Medical Tourism Market size was valued at USD 53.28 Billion in 2024 and is anticipated to reach USD 165.50 Billion by 2032, at a CAGR of 15.12% during the forecast period (2024-2032).
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Medical Tourism Market Size 2024 | USD 53.28 Billion |
| Medical Tourism Market, CAGR | 15.12% |
| Medical Tourism Market Size 2032 | USD 165.50 Billion |
The Global Medical Tourism market is experiencing rapid growth due to rising healthcare costs in developed nations, increasing demand for high-quality yet affordable treatments, and advancements in medical infrastructure across emerging economies. Patients seek specialized procedures such as cosmetic surgery, dental care, and fertility treatments at lower costs, often combined with shorter wait times. Government initiatives supporting medical tourism, coupled with improved international travel connectivity, further drive market expansion. The growing adoption of telemedicine for pre- and post-treatment consultations enhances patient convenience and confidence in cross-border healthcare. Additionally, the rising prevalence of chronic diseases and aging populations contribute to increased outbound medical travel. Emerging trends, including AI-driven patient care, blockchain for secure health records, and accreditation of international hospitals, further strengthen the industry. Leading medical tourism destinations, such as India, Thailand, and Mexico, continue to attract international patients due to their cost-effective treatments and high standards of medical expertise.
The global medical tourism market is geographically diverse, with key destinations including Asia-Pacific, Europe, North America, and the Middle East & Africa. Asia-Pacific leads the industry, driven by countries like India, Thailand, South Korea, and Malaysia, which offer advanced medical treatments at competitive costs. Europe, particularly Germany, Spain, Hungary, and Turkey, attracts patients seeking high-quality specialized treatments such as orthopedic surgeries and dental care. North America primarily serves as a source of outbound medical tourists due to high treatment costs, while Mexico and Costa Rica cater to patients seeking affordable alternatives. In the Middle East, the UAE and Israel are emerging as prominent hubs for premium medical services. Key players in the global medical tourism market include MOHW Hengchun Tourism Hospital, Apollo Hospitals Enterprise Ltd., Bumrungrad International Hospital, Mount Elizabeth Hospitals, and Raffles Medical Group. These hospitals and healthcare providers offer state-of-the-art medical facilities, internationally accredited treatments, and strategic partnerships to attract international patients.
Market Insights
- The global medical tourism market was valued at USD 53.28 Billion in 2024 and is projected to reach USD 165.50 Billion by 2032, growing at a CAGR of 15.12% during the forecast period.
- The rising demand for cost-effective medical treatments and access to advanced healthcare facilities are key drivers fueling market growth.
- Increasing adoption of cutting-edge technologies such as robotic surgeries, AI-driven diagnostics, and telemedicine is shaping market trends.
- High-quality healthcare services, internationally accredited hospitals, and government support in leading medical tourism destinations enhance the competitive landscape.
- Long waiting times for treatments in developed nations and expensive healthcare costs drive patients to seek affordable medical care abroad.
- The Asia-Pacific region remains the dominant market due to its well-established healthcare infrastructure and lower treatment costs compared to Western countries.
- Strict regulatory policies, visa restrictions, and concerns over treatment quality in some destinations pose challenges to market expansion.
Report Scope
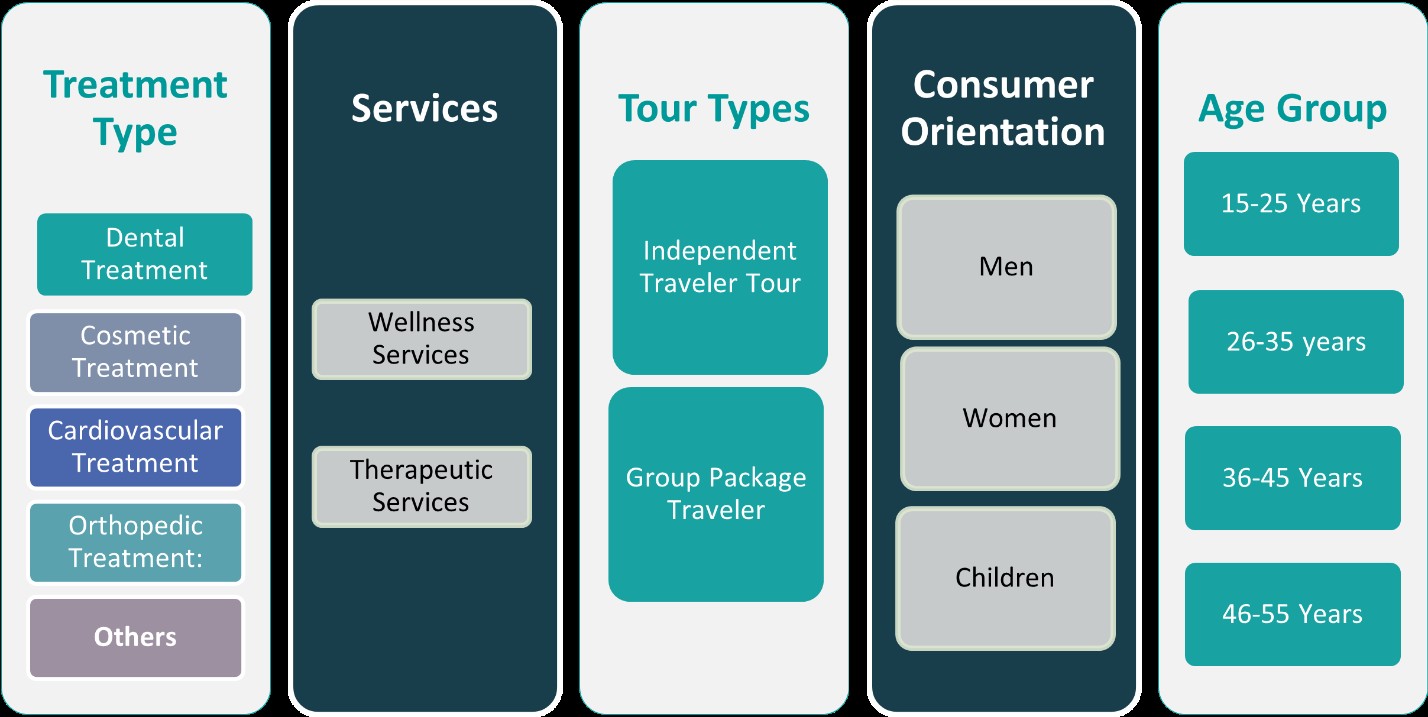
This report segments the Global Medical Tourism Market as follows:
Market Drivers
Rising Healthcare Costs in Developed Nations
The increasing cost of medical treatments in developed countries is a major driver of the global medical tourism market. In regions such as North America and Western Europe, healthcare expenses, including consultation fees, surgical procedures, and post-operative care, have surged significantly. For instance, a heart bypass surgery in the United States can cost upwards of $100,000, while the same procedure in India is available for as low as $10,000, according to reports from the Medical Tourism Corporation. Many patients, particularly those without comprehensive insurance coverage, seek more affordable alternatives in countries offering similar or superior healthcare services at a fraction of the cost. Additionally, high out-of-pocket expenses and long waiting times for elective procedures in developed nations push individuals to explore international healthcare options. This financial burden encourages medical travel to destinations where advanced treatments are available at lower prices without compromising quality, fueling market growth.
Advancements in Medical Infrastructure and Technology
The rapid development of medical infrastructure and technology in emerging economies plays a pivotal role in expanding the medical tourism industry. Many countries have invested heavily in state-of-the-art healthcare facilities, modern medical equipment, and internationally accredited hospitals to attract foreign patients. For instance, India has introduced robotic surgeries and AI-driven diagnostics in hospitals like Apollo and Fortis, ensuring high-quality medical care comparable to that in developed nations. Furthermore, the adoption of robotic surgeries, AI-driven diagnostics, and minimally invasive procedures enhances treatment precision and patient outcomes. Medical tourism destinations such as India, Thailand, and South Korea continue to integrate cutting-edge technology with skilled healthcare professionals, reinforcing their appeal to international patients.
Government Initiatives and Supportive Policies
Several governments worldwide actively promote medical tourism by implementing supportive policies, investing in healthcare infrastructure, and simplifying visa procedures for medical travelers. Countries such as Malaysia, Singapore, and the United Arab Emirates have introduced medical visas, specialized healthcare packages, and promotional campaigns to attract foreign patients. Financial incentives, tax benefits for healthcare providers, and partnerships with international insurance companies further boost medical tourism. Additionally, government-led accreditation programs ensure quality standards, enhancing the credibility of medical tourism destinations. These efforts collectively contribute to the rapid expansion of the industry by improving accessibility and trust in international healthcare services.
Increasing Demand for Specialized and Elective Procedures
The growing preference for specialized and elective medical procedures significantly drives medical tourism. Treatments such as cosmetic surgery, dental care, fertility treatments, and orthopedic procedures are in high demand, often motivating patients to seek medical care abroad due to affordability and shorter wait times. Additionally, the rising prevalence of chronic diseases, including cardiovascular conditions and cancer, has increased the need for advanced treatments available at leading medical tourism destinations. Many healthcare facilities in Asia, Latin America, and the Middle East offer cost-effective yet high-quality procedures, making them attractive choices for international patients. As more individuals become aware of these opportunities, the demand for cross-border healthcare services continues to grow, further strengthening the medical tourism market.
Market Trends
Growing Popularity of Cost-Effective and High-Quality Healthcare Services
The increasing cost of medical treatments in developed nations has led to a surge in medical tourism, with patients seeking affordable yet high-quality healthcare services abroad. Many countries in Asia, Latin America, and Eastern Europe offer medical procedures at a fraction of the cost compared to North America and Western Europe. For instance, a dental implant procedure in Mexico can cost as low as $1,000, compared to $5,000 in the United States, according to Patients Beyond Borders. This trend is particularly prominent for elective procedures such as cosmetic surgery, dental treatments, and fertility care. Additionally, the presence of internationally accredited hospitals and highly trained medical professionals in these destinations enhances patient confidence. The affordability factor, combined with shorter wait times and advanced medical technologies, continues to drive the growth of medical tourism worldwide.
Integration of Telemedicine for Seamless Patient Care
Telemedicine has emerged as a key trend in medical tourism, enabling patients to connect with healthcare providers across borders before and after undergoing treatment. For instance, Apollo Hospitals in India offers telemedicine services that allow international patients to consult specialists remotely before traveling for treatment. Virtual consultations help patients assess treatment options, receive second opinions, and plan medical trips efficiently. Post-treatment follow-ups conducted through telehealth platforms ensure continuity of care, reducing the need for additional travel. This integration of digital health solutions enhances patient confidence in medical tourism by improving accessibility and transparency. With increasing investments in telemedicine infrastructure, medical tourism providers are leveraging technology to offer remote diagnostics, treatment planning, and virtual rehabilitation services, further streamlining the patient journey.
Expansion of Medical Tourism Destinations and Services
While traditional medical tourism hubs like India, Thailand, and Mexico continue to dominate the market, new destinations are rapidly emerging to cater to international patients. Countries such as Turkey, the UAE, Malaysia, and South Korea are heavily investing in healthcare infrastructure, accreditation programs, and specialized medical treatments to attract foreign patients. These nations offer diverse medical services, including advanced oncology treatments, robotic surgeries, and regenerative medicine therapies. Additionally, wellness tourism-comprising holistic health retreats, Ayurveda treatments, and spa therapies-is becoming an integral part of medical tourism, appealing to patients seeking both medical and wellness solutions. This diversification of services and destinations is expanding patient choices and fostering greater competition within the industry.
Adoption of AI and Blockchain for Enhanced Patient Experience
Artificial intelligence (AI) and blockchain technology are transforming the medical tourism sector by improving patient management, data security, and treatment accuracy. AI-powered diagnostic tools help physicians offer personalized treatment recommendations, while blockchain enhances the security and accessibility of patient health records across international borders. The implementation of AI-driven chatbots and virtual assistants further streamlines patient interactions, appointment scheduling, and medical travel planning. These technological advancements enhance patient trust and convenience, making medical tourism a more efficient and secure option for international healthcare seekers. As technology continues to evolve, its role in optimizing medical tourism processes is expected to grow significantly.
Market Challenges Analysis
Regulatory and Legal Barriers Impacting Cross-Border Healthcare
One of the major challenges in the global medical tourism market is the complexity of regulatory and legal frameworks across different countries. Varying healthcare standards, licensing requirements, and medical malpractice laws create uncertainty for international patients seeking treatment abroad. For instance, the European Union's Cross-Border Healthcare Directive provides a framework for patients to access healthcare services in other EU countries, but it also highlights the challenges of navigating different legal systems and reimbursement policies. Many countries lack standardized regulations for medical tourism, leading to inconsistencies in patient rights, treatment quality, and legal recourse in case of medical complications. Additionally, differences in insurance policies often result in limited coverage for overseas treatments, placing a financial burden on medical tourists. Patients may also face challenges in obtaining medical visas due to strict immigration policies in some regions. These regulatory hurdles create barriers to seamless healthcare access, limiting the potential growth of medical tourism despite rising demand. Addressing these challenges requires enhanced international cooperation, accreditation systems, and policy frameworks that ensure patient safety and legal protection across borders.
Risks Associated with Treatment Quality and Post-Operative Care
Ensuring consistent treatment quality and post-operative care remains a significant challenge in medical tourism. While many destinations offer world-class healthcare facilities, some lack proper accreditation or standardized protocols, increasing the risk of subpar medical outcomes. Patients may face complications due to differences in medical procedures, infection control measures, and follow-up care protocols. Limited post-treatment support in the patient’s home country can also lead to challenges in managing recovery, particularly for complex surgeries and long-term treatments. Additionally, language barriers and cultural differences may create communication gaps between patients and healthcare providers, impacting treatment comprehension and decision-making. To address these concerns, international hospitals and governments must implement stringent accreditation systems, enhance patient education, and establish follow-up care collaborations with healthcare providers in the patient’s home country. By improving treatment transparency and aftercare services, the medical tourism industry can strengthen patient confidence and ensure better healthcare outcomes.
Market Opportunities
The global medical tourism market presents significant opportunities driven by advancements in healthcare infrastructure, rising demand for cost-effective treatments, and increasing patient mobility. Countries with well-established medical tourism sectors can further expand their market presence by investing in cutting-edge technologies such as robotic surgeries, AI-assisted diagnostics, and personalized treatment plans. The growing emphasis on holistic healthcare, including alternative medicine and wellness therapies, offers new avenues for medical tourism providers to attract international patients. Additionally, partnerships between hospitals, insurance companies, and travel agencies can enhance the patient experience by offering seamless medical travel packages that include treatment, accommodation, and post-operative care. Governments that implement supportive policies, such as streamlined visa processes and tax incentives for healthcare providers, can position their countries as preferred destinations for international patients seeking high-quality yet affordable medical treatments.
Furthermore, the increasing adoption of digital health solutions presents a transformative opportunity in the medical tourism sector. Telemedicine, AI-driven patient engagement tools, and blockchain-based medical record systems enable healthcare providers to offer pre-treatment consultations and post-operative follow-ups remotely, ensuring continuity of care for medical tourists. Emerging economies with rapidly developing healthcare infrastructure, such as Turkey, Malaysia, and the UAE, are well-positioned to attract patients from high-cost healthcare markets, including the US and Western Europe. Additionally, medical tourism providers can leverage branding and marketing strategies that emphasize their expertise, internationally accredited hospitals, and advanced medical procedures to build trust among global patients. As healthcare providers continue to enhance service quality, invest in international collaborations, and integrate technological advancements, the medical tourism market is expected to witness substantial expansion, creating new growth opportunities for stakeholders across the industry.
Market Segmentation Analysis:
By Treatment:
The global medical tourism market is segmented based on treatment types, including dental treatment, cosmetic treatment, cardiovascular treatment, orthopedic treatment, and others. Dental treatment is one of the most sought-after services in medical tourism due to its affordability and high-quality care in countries such as Mexico, Thailand, and Hungary. Many patients travel internationally for procedures like implants, veneers, and root canals, benefiting from cost savings and shorter wait times. Similarly, cosmetic treatments, including plastic surgery, skin rejuvenation, and weight-loss procedures, drive significant demand in destinations like South Korea and Brazil, known for their advanced aesthetic procedures. Cardiovascular treatments, including heart surgeries and angioplasties, also attract medical tourists seeking top-tier care at lower costs in countries such as India and Turkey. Orthopedic treatments, such as joint replacements and spinal surgeries, further contribute to market growth, particularly in regions with specialized medical expertise. The “others” category includes treatments like fertility procedures and cancer therapies, expanding the scope of medical tourism across multiple disciplines.
By Services:
Medical tourism is also segmented based on services, including wellness services and therapeutic services. Wellness services encompass holistic healthcare solutions such as Ayurveda, spa therapies, and alternative medicine, which attract individuals seeking preventive and rejuvenating treatments. Countries like India, Indonesia, and Switzerland have emerged as key destinations for wellness tourism, offering traditional therapies integrated with modern healthcare. On the other hand, therapeutic services focus on curative treatments, including rehabilitation, post-operative care, and chronic disease management. These services are gaining traction due to the increasing prevalence of lifestyle diseases and the growing demand for specialized recovery programs. Many hospitals and healthcare centers provide comprehensive therapeutic packages that combine medical treatments with wellness services, ensuring long-term health benefits for patients. The integration of personalized treatment plans, cutting-edge medical technologies, and holistic healthcare approaches enhances the appeal of medical tourism, positioning it as a cost-effective and high-quality alternative to domestic healthcare systems.
Segments:
Based on Treatment:
- Dental Treatment
- Cosmetic Treatment
- Cardiovascular Treatment
- Orthopedic Treatment
- Others
Based on Services:
- Wellness Services
- Therapeutic Services
Based on Tour Type:
- Independent Traveler Tour
- Group Package Traveler
Based on Consumer Orientation:
- Men
- Women
- Children
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis
Asia-Pacific
Asia-Pacific holds the largest share of the global medical tourism market, accounting for approximately 40% of the total market revenue. Countries such as India, Thailand, South Korea, and Malaysia are key destinations due to their advanced healthcare infrastructure, affordability, and internationally accredited hospitals. India is particularly known for its high-quality yet cost-effective cardiac, orthopedic, and cancer treatments, while Thailand and South Korea excel in cosmetic and dental procedures. Additionally, the presence of government initiatives, medical visa facilitation, and the integration of traditional therapies such as Ayurveda and acupuncture enhance the region's attractiveness to international patients. The Asia-Pacific region continues to experience steady growth due to continuous investments in healthcare infrastructure, medical technology advancements, and a growing network of internationally certified hospitals.
Europe
Europe holds a significant share of the medical tourism market, contributing approximately 25% of the total revenue. Countries such as Germany, Spain, Hungary, and Turkey have established themselves as top destinations for medical tourists seeking specialized treatments. Germany is a leading hub for advanced medical procedures, particularly in orthopedics, cardiology, and neurology, while Spain attracts patients for fertility treatments and cosmetic procedures. Hungary has emerged as a premier destination for dental tourism due to its cost-effectiveness and high standard of care. Turkey, with its strategic location between Europe and Asia, is a growing hub for various treatments, including hair transplants, plastic surgery, and bariatric procedures. The European market benefits from strong regulatory frameworks, state-of-the-art medical facilities, and a high level of patient trust in healthcare standards.
North America
North America holds around 20% of the global medical tourism market, driven primarily by outbound medical tourists from the United States and Canada seeking affordable treatments abroad. The high cost of medical procedures, long wait times, and insurance limitations in the U.S. push many patients to seek treatments in Mexico, Costa Rica, and the Caribbean. Mexico is a leading destination for dental care, bariatric surgery, and cosmetic procedures, offering cost savings of up to 70% compared to U.S. prices. Additionally, Canada’s universal healthcare system often results in long wait times for elective surgeries, prompting patients to travel internationally for faster medical access. While North America serves as a source of outbound patients, its advanced healthcare institutions also attract international patients for specialized and high-end treatments.
Middle East & Africa
The Middle East & Africa region accounts for approximately 15% of the market share, with countries such as the UAE, Israel, and South Africa emerging as prominent medical tourism destinations. The UAE, particularly Dubai and Abu Dhabi, has positioned itself as a leading hub for premium healthcare services, offering advanced cosmetic surgeries, fertility treatments, and wellness programs. Israel is recognized for its expertise in fertility treatments, oncology, and minimally invasive surgeries, attracting patients from Europe, the U.S., and neighboring countries. South Africa is gaining popularity for affordable and high-quality medical procedures, including orthopedic and cosmetic treatments, often combined with tourism experiences. Government investments, international hospital partnerships, and medical tourism-friendly policies are further strengthening the region’s market presence.
Key Player Analysis
- MOHW Hengchun Tourism Hospital
- Apollo Hospitals Enterprise Ltd.
- Bumrungrad International Hospital
- Mount Elizabeth Hospitals
- Raffles Medical Group
Competitive Analysis
The global medical tourism market is highly competitive, with leading players focusing on advanced healthcare infrastructure, cost-effective treatment packages, and international accreditation to attract medical tourists. Key players in the industry include MOHW Hengchun Tourism Hospital, Apollo Hospitals Enterprise Ltd., Bumrungrad International Hospital, Mount Elizabeth Hospitals, and Raffles Medical Group. These organizations offer specialized medical services, including cardiovascular, orthopedic, cosmetic, and dental treatments, catering to international patients seeking high-quality care at competitive prices. Strategic partnerships, technological advancements, and government support play a crucial role in enhancing the competitive positioning of these healthcare providers. Many hospitals collaborate with insurance companies, travel agencies, and medical facilitators to streamline patient experiences and improve accessibility. Additionally, digital health solutions, telemedicine services, and AI-driven diagnostics are being integrated to enhance patient engagement and pre-treatment consultations. Despite intense competition, factors such as accreditation from organizations like JCI, multilingual medical staff, and customized healthcare packages differentiate leading players in the evolving global medical tourism landscape.
Recent Developments
- In March 2025, Raffles Medical Group signed a strategic collaboration agreement with Shanghai Renji Hospital to establish a "dual circulation" service system. This partnership aims to promote cross-border healthcare services and position Shanghai as a hub for international medical tourism.
- In March 2025, MOHW Hengchun Tourism Hospital was highlighted as a key player in the global medical tourism market in a report projecting significant growth for the industry. The hospital continues to play a pivotal role in expanding medical tourism opportunities, particularly in Asia.
- In February 2025, Apollo Hospitals emphasized the need for a liberal visa policy to enhance India's medical tourism sector. The hospital is collaborating with the Indian government on the "Heal in India" initiative to attract international patients and streamline medical visa processes.
- In January 2025, Mount Elizabeth Hospitals unveiled new facilities under "Project Renaissance," which included expanded wards, upgraded critical care units, and additional single-bedded and negative pressure rooms. This expansion added 62 beds to its capacity and enhanced patient care infrastructure.
Market Concentration & Characteristics
The global medical tourism market exhibits a moderately high level of market concentration, with several leading healthcare providers dominating key destinations. The market is characterized by a strong presence of internationally accredited hospitals, government support for medical tourism, and a growing network of specialized healthcare facilities. Leading players focus on offering high-quality treatments at competitive prices, attracting patients from developed nations seeking cost-effective medical care. The market is also distinguished by the integration of advanced technologies, including AI-driven diagnostics, robotic surgeries, and telemedicine, enhancing treatment precision and patient experience. Additionally, strategic partnerships with travel agencies, insurance companies, and facilitators streamline patient journeys. The competitive landscape is influenced by factors such as accreditation, medical expertise, infrastructure quality, and post-treatment care. While Asia-Pacific remains the dominant region, Europe, North America, and the Middle East continue to expand their presence, catering to specific medical needs and luxury healthcare experiences for international patients.
Report Coverage
The research report offers an in-depth analysis based on Treatment, Services, Tour Type, Consumer Orientation and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The global medical tourism market is expected to witness steady growth, driven by rising healthcare costs in developed countries.
- Advanced medical technologies, including AI-driven diagnostics and robotic surgeries, will enhance treatment efficiency and patient outcomes.
- Governments in key medical tourism destinations will introduce favorable policies and infrastructure investments to attract international patients.
- The demand for cosmetic, dental, and fertility treatments will continue to rise as patients seek affordable and high-quality procedures abroad.
- Telemedicine and digital health solutions will streamline pre-treatment consultations and post-treatment follow-ups, improving patient engagement.
- Leading healthcare providers will focus on international accreditation, quality certifications, and multilingual support to enhance global credibility.
- Strategic collaborations between hospitals, insurance companies, and travel agencies will simplify the medical tourism process and boost patient inflow.
- The Asia-Pacific region will maintain its dominance, while Europe and the Middle East will see increasing market share with specialized healthcare services.
- Rising awareness about alternative treatments, including wellness and holistic therapies, will create new opportunities in medical tourism.
- Challenges such as visa restrictions, regulatory differences, and treatment quality concerns will require continuous improvements and global standardization efforts.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Healthcare Costs in Developed Nations
Escalating medical expenses and long wait times in countries like the US and Western Europe are prompting patients to seek affordable, high-quality treatments abroad, fueling outbound medical tourism.
Advancements in Medical Infrastructure and Technology
Emerging economies are investing in state-of-the-art hospitals, robotic surgeries, and AI-driven diagnostics, making them attractive destinations for international patients seeking advanced care at lower costs.
Government Initiatives and Supportive Policies
Many governments are actively promoting medical tourism through streamlined visa processes, healthcare investment, and international accreditation, making cross-border treatment more accessible and trustworthy.
Increasing Demand for Specialized and Elective Procedures
Patients are traveling internationally for specialized treatments such as cosmetic surgery, dental care, and fertility procedures, which are often more affordable and available with shorter wait times in leading medical tourism destinations.
Integration of Telemedicine and Digital Health Solutions
The adoption of telemedicine for pre- and post-treatment consultations enhances patient convenience and confidence, making it easier for patients to plan and manage cross-border healthcare journeys.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Global Medical Tourism?
What factors are driving the growth of the Global Medical Tourism?
What are the key segments within the Global Medical Tourism?
What are some challenges faced by the Global Medical Tourism?
Who are the major players in the Global Medical Tourism?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Services
- 1.2.1 Wellness Services
- 1.2.2 Therapeutic Services
- 1.3 By Tour Type
- 1.3.1 Independent Traveler Tour
- 1.3.2 Group Package Traveler
- 1.4 By Treatment
- 1.4.1 Dental Treatment
- 1.4.2 Cosmetic Treatment
- 1.4.3 Cardiovascular Treatment
- 1.4.4 Orthopedic Treatment
- 1.4.5 Others
- 1.5 By Consumer Orientation
- 1.5.1 Men
- 1.5.2 Women
- 1.5.3 Children
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 53,275.23 million → 2032: USD 164,335.58 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Medical Tourism Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Medical Tourism Market Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Supply Chain Structure and Procurement Trends
- 5.4 Supply-Demand Gap and Bottlenecks
- 5.5 Import Dependence and Sourcing Structure
- 5.6 Regional Supply and Demand Concentration
Chapter 6 Global Medical Tourism Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Pricing by Product and Market Segment
- 6.5 Geographic Pricing Differences
- 6.6 Key Input, Energy, Labor and Logistics Costs
- 6.7 Contract Pricing and Purchasing Models
- 6.8 Pricing Sensitivity and Competitive Positioning
- 6.9 Price, Margin and Profitability Implications
Chapter 7 Global Medical Tourism Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Medical Tourism Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Medical Tourism Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Data Protection, AI and Cybersecurity Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Medical Tourism Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Medical Tourism Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 53,275.23 million → 2032: USD 164,335.58 million)
- 11.1.2 Historical Market Size
- 11.1.3 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 CAGR and Year-on-Year Growth
- 11.2.3 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Medical Tourism Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Services - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Base-Year Market Share, 2024
- 12.3.5 Segment CAGR and Growth Drivers
- 12.3.6 Subsegment Market Size and Forecast
- 12.3.6.1 Wellness Services
- 12.3.6.2 Therapeutic Services
- 12.3.7 Subsegment Pricing and Adoption Trends
- 12.3.8 Leading Suppliers and Competition
- 12.3.9 Regional Demand and Opportunities
- 12.4 By Tour Type - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Base-Year Market Share, 2024
- 12.4.5 Segment CAGR and Growth Drivers
- 12.4.6 Subsegment Market Size and Forecast
- 12.4.6.1 Independent Traveler Tour
- 12.4.6.2 Group Package Traveler
- 12.4.7 Subsegment Pricing and Adoption Trends
- 12.4.8 Leading Suppliers and Competition
- 12.4.9 Regional Demand and Opportunities
- 12.5 By Treatment - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Base-Year Market Share, 2024
- 12.5.5 Segment CAGR and Growth Drivers
- 12.5.6 Subsegment Market Size and Forecast
- 12.5.6.1 Dental Treatment
- 12.5.6.2 Cosmetic Treatment
- 12.5.6.3 Cardiovascular Treatment
- 12.5.6.4 Orthopedic Treatment
- 12.5.6.5 Others
- 12.5.7 Subsegment Pricing and Adoption Trends
- 12.5.8 Leading Suppliers and Competition
- 12.5.9 Regional Demand and Opportunities
- 12.6 By Consumer Orientation - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Base-Year Market Share, 2024
- 12.6.5 Segment CAGR and Growth Drivers
- 12.6.6 Subsegment Market Size and Forecast
- 12.6.6.1 Men
- 12.6.6.2 Women
- 12.6.6.3 Children
- 12.6.7 Subsegment Pricing and Adoption Trends
- 12.6.8 Leading Suppliers and Competition
- 12.6.9 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Medical Tourism Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Medical Tourism Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Energy Efficiency and Resource Management
- 14.7 Sustainability, Recycling and Circularity
- 14.8 Technology Roadmap, 2024-2032
- 14.9 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Medical Tourism Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 MOHW Hengchun Tourism Hospital
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Financial Performance and Investment
- 17.2.6 Market Share and Competitive Position
- 17.2.7 Technology and Innovation Capabilities
- 17.2.8 Strategic Alliances or Partnerships
- 17.2.9 Recent Developments
- 17.2.10 Growth Strategy and Outlook
- 17.3 Apollo Hospitals Enterprise Ltd.
- 17.4 Bumrungrad International Hospital
- 17.5 Mount Elizabeth Hospitals
- 17.6 Raffles Medical Group
- 17.7 Fortis Healthcare
- 17.8 Cleveland Clinic
- 17.9 Gleneagles Hospital
- 17.10 Bangkok Hospital
- 17.11 Medicana International
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

