
Market Overview
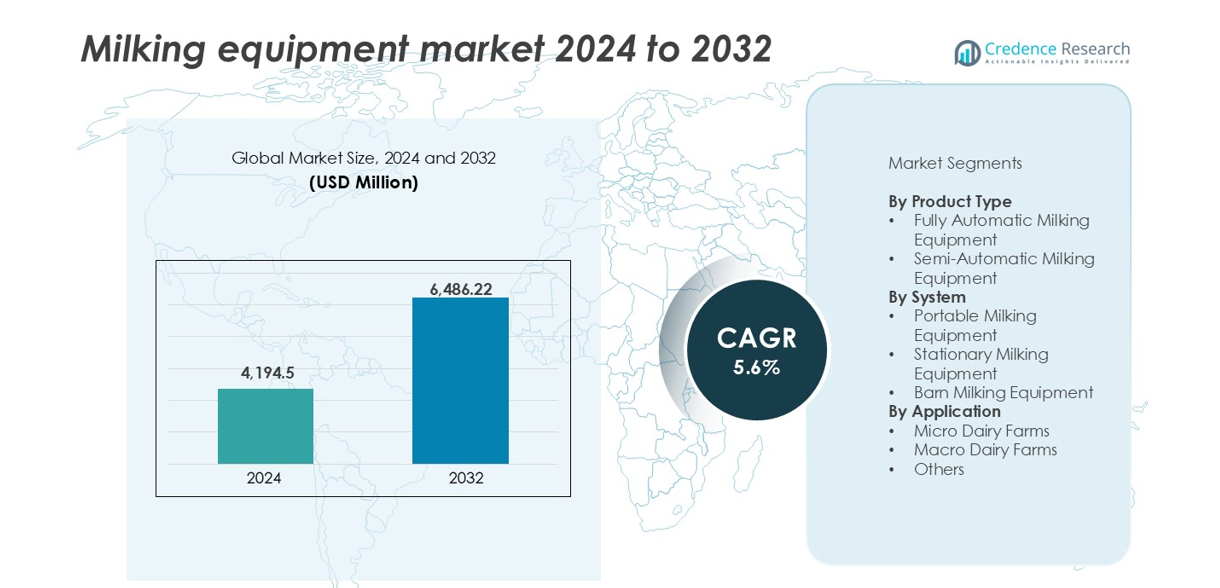
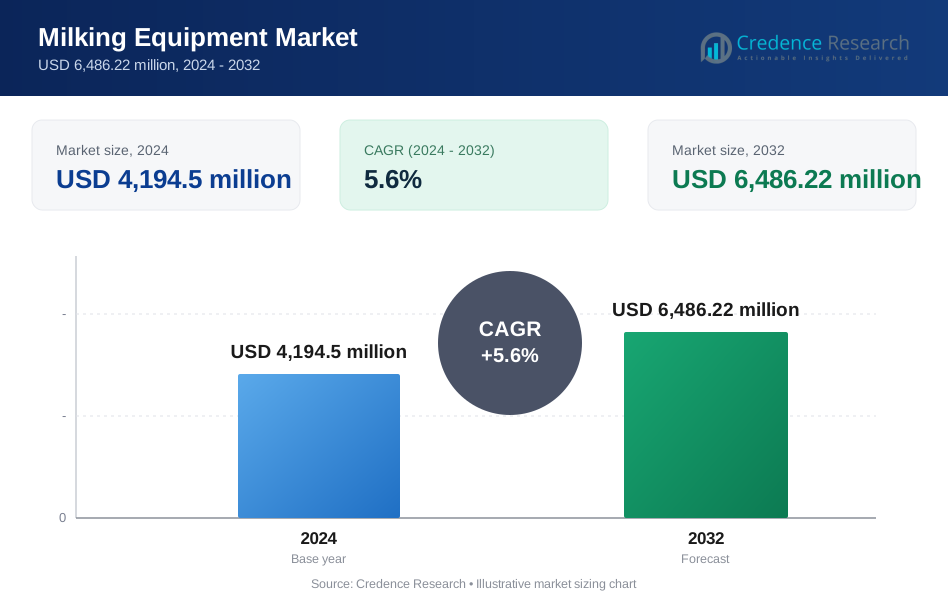
The Milking equipment market size was valued at USD 4,194.5 million in 2024 and is anticipated to reach USD 6,486.22 million by 2032, at a CAGR of 5.6% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Milking Equipment Market Size 2024 | USD 4,194.5 million |
| Milking Equipment Market, CAGR | 5.6% |
| Milking Equipment Market Size 2032 | USD 6,486.22 million |
The milking equipment market is led by established players such as Lely, GEA Group Aktiengesellschaft, BouMatic Robotics B.V., and Fullwood Packo, known for their advanced robotic and automated systems. These companies dominate in regions with mature dairy infrastructure, offering high-throughput solutions and precision herd management. Europe holds the largest regional market share at 32%, driven by strict animal welfare regulations and widespread automation adoption. Other notable companies include Agrifac Machinery BV, AMS-Galaxy, and regional suppliers like Vansun Technologies Pvt Ltd and Prompt Dairy Tech, which focus on cost-effective systems for emerging markets. Competitive focus centers on innovation, product reliability, and digital integration.
Market Insights
- The milking equipment market was valued at USD 4,194.5 million in 2024 and is projected to reach USD 6,486.22 million by 2032, growing at a CAGR of 5.6%.
- Rising automation in dairy farms and increasing labor costs are driving demand for fully automatic milking systems.
- Smart dairy trends like IoT integration, herd analytics, and robotic milking units are gaining strong traction globally.
- Lely, GEA Group, BouMatic Robotics, and Fullwood Packo lead the market, while regional players offer affordable systems for smaller farms.
- Europe holds the largest share at 32%, followed by North America at 28% and Asia-Pacific at 21%; by product type, fully automatic milking systems dominate due to efficiency and hygiene benefits.
Market Segmentation Analysis:
By Product Type
Fully automatic milking equipment holds the largest share in the milking equipment market. This segment dominates due to rising labor shortages, the need for consistent milking routines, and efficiency in large dairy operations. Farmers prefer automatic systems to boost productivity, ensure hygiene, and track milk yield digitally. These machines reduce manual labor, lower operating costs, and increase throughput. Semi-automatic systems continue to serve small and medium farms but lack the automation depth of high-end units. Full automation improves udder health through precision-controlled processes and optimal milking intervals. Demand for animal welfare and data-driven dairy management supports further adoption.
- For instance, DeLaval’s VMS™ V300 robotic milking system delivers over 3,000 liters of milk per robot per day, supporting real-time data tracking and automated teat cleaning.
By System
Stationary milking equipment leads the system segment with the highest revenue share. This preference stems from its integration in large dairy barns and fixed infrastructure, offering high throughput and consistent performance. Stationary setups suit high-volume operations where cows follow fixed routines. Portable milking equipment is more popular among small farms needing flexibility. Barn milking equipment, typically integrated into farm layouts, supports semi-automatic and automatic systems. Stationary units deliver lower maintenance downtime and better hygiene control, which appeals to commercial dairy producers. System selection depends on farm size, herd volume, and investment capacity, with large farms opting for durability and speed.
- For instance, BouMatic’s Xcalibur™ 360EX rotary milking system is designed for large-scale commercial dairy operations, accommodating between 40 and 150 stalls. At its maximum configuration, the system can process up to 1,200 cows per hour, supporting continuous 24/7 milking for herds exceeding 4,000 cows.
By Application
Macro dairy farms represent the dominant application segment with the largest market share. These operations benefit from economies of scale and invest in advanced milking systems to optimize yield and reduce labor. Macro farms demand fully automated, stationary units to handle high herd counts efficiently. Micro dairy farms adopt semi-automatic or portable units due to limited herd sizes and budget constraints. The “Others” category includes educational, research, and niche farms with tailored needs. Growth in commercial dairy farming and herd expansion in emerging markets fuels the macro segment. High milk demand and export opportunities further support advanced equipment adoption.
Key Growth Drivers
Rising Demand for Automation in Dairy Farming
The shift toward automation is a primary driver of the milking equipment market. Dairy farms face increasing labor shortages and pressure to maintain productivity. Fully automatic milking systems reduce dependency on manual labor while ensuring consistent milking cycles and higher hygiene standards. Automation also enables real-time monitoring of milk output, animal health, and equipment performance. Large farms benefit from improved efficiency, better udder health, and optimized operations through software integration. In emerging economies, rising herd sizes and dairy demand are prompting farmers to invest in automated systems. Governments and industry bodies are also encouraging mechanization to boost rural productivity. The ability to scale operations while reducing costs further reinforces the move toward automatic systems. This shift directly supports market growth, especially across North America, Europe, and parts of Asia.
- For instance, Lely’s Astronaut A5 robotic milking system records over 120 data points per cow per day, helping farmers optimize yield and detect health issues early.
Expansion of Large-Scale Commercial Dairy Farms
Commercial dairy operations continue to expand globally, fueling demand for advanced milking systems. Macro dairy farms require high-throughput equipment capable of processing hundreds of cows per day. These operations often deploy stationary, fully automated systems that optimize labor and improve yield quality. Increased consumer demand for dairy products, including milk, cheese, and yogurt, is pushing commercial farms to scale production efficiently. Countries like India, China, and Brazil are witnessing a rapid rise in organized dairy operations, backed by government incentives and private investments. The need to manage large herds, maintain milk hygiene, and meet regulatory standards drives the adoption of precision milking technology. Commercial farms view such investments as critical to achieving long-term profitability and export readiness. The growth of this segment has a direct impact on the sales of durable, high-capacity milking equipment.
- For instance, Fonterra operates rotary parlors in New Zealand capable of milking 54 cows every 8 minutes, with automated cleaning and real-time tracking.
Emphasis on Animal Welfare and Milk Quality
Growing awareness around animal health and milk hygiene standards drives investment in advanced milking equipment. Modern systems are designed to minimize stress on cows by using gentle milking techniques and ensuring timely milking intervals. Equipment with sensors and analytics features allows early detection of infections, irregularities, or yield drops. This improves animal well-being and ensures consistent milk quality. Regulatory pressure across the EU and the U.S. for safer dairy production practices accelerates the use of automated and hygienic milking solutions. Consumers are also increasingly aware of traceability, demanding clean-label dairy sourced from well-managed farms. As farms focus on improving cow comfort, disease prevention, and herd management, demand for smarter and cleaner equipment grows. These priorities align with market offerings such as robotic arms, automatic teat cleaning systems, and milk sampling technologies.
Key Trends & Opportunities
Integration of IoT and Data-Driven Dairy Management
IoT integration is reshaping milking operations through data analytics, cloud platforms, and remote monitoring tools. Modern milking systems now include smart sensors that track milk yield, temperature, cow activity, and equipment performance in real time. This shift allows farms to make data-backed decisions that improve productivity and animal health. Predictive maintenance alerts reduce downtime, while cloud-linked herd records streamline veterinary and breeding processes. Startups and established equipment vendors are investing in digital tools to offer complete herd management solutions. As smart farming gains momentum, the demand for connected milking systems will accelerate, especially in tech-ready dairy regions. The opportunity lies in offering scalable platforms tailored to both medium and large farms seeking performance visibility and cost control.
- For instance, DeLaval’s DelPro™ Farm Management platform and its integrated DeLaval Plus ecosystem process billions of data points daily across installations supporting over 5 million cows globally. This real-time analysis allows farmers to optimize milking intervals, maximize feed efficiency, and proactively manage cow health through advanced AI-driven insights.
Key Challenges
High Capital Costs and Return on Investment Concerns
The high upfront cost of milking equipment remains a significant barrier, especially for small and medium farms. Fully automated systems, while efficient, require substantial investment in hardware, installation, and training. Many dairy farmers struggle to justify the cost due to uncertain milk prices, volatile input costs, and slow payback periods. Financing options and government subsidies are not always accessible or sufficient in developing markets. In addition, some farmers remain cautious about technology adoption due to maintenance risks and lack of technical expertise. These factors limit the penetration of premium equipment into rural and fragmented markets. Without scalable, cost-effective models or rental options, equipment adoption may remain concentrated in wealthier regions.
Technical Complexity and Maintenance Burden
Advanced milking systems often involve complex mechanical and electronic components that require regular maintenance. For farmers unfamiliar with digital systems, this creates dependency on vendor support. Downtime due to technical issues can disrupt daily operations and reduce milk yield. In remote or underdeveloped areas, lack of access to trained technicians and spare parts further compounds the issue. Software glitches, sensor misalignment, or mechanical failures can erode trust in automation. Manufacturers must address these concerns by improving equipment reliability, offering robust training, and ensuring responsive service networks. Simplifying user interfaces and integrating auto-diagnostics may help mitigate maintenance-related challenges over time.
Regional Analysis
North America
North America accounts for around 28% of the global milking equipment market share in 2024. The U.S. leads this region with strong adoption of fully automated milking systems in large commercial dairy farms. High labor costs, advanced dairy infrastructure, and government support for precision agriculture drive automation. Canada also contributes with modern dairy practices and rising herd productivity. Integration of IoT in herd management supports demand for smart milking units. Regional players invest heavily in R&D and service networks. Consistent demand for premium dairy products and strong export orientation sustain growth across both stationary and robotic systems.
Europe
Europe holds the largest share of the global market at approximately 32% in 2024. Countries like Germany, the Netherlands, and France lead in the adoption of robotic and fully automatic milking systems. Strict regulations on animal welfare, milk hygiene, and sustainability drive investment in advanced technologies. European dairy farms focus on efficiency, environmental compliance, and herd health monitoring. Government subsidies and strong cooperative structures support smaller farms in adopting semi-automated systems. The region’s mature dairy sector continues to lead innovation in automation, waste reduction, and smart dairy management. Demand remains strong for energy-efficient, high-throughput equipment across EU markets.
Asia-Pacific
Asia-Pacific captures about 21% of the global milking equipment market in 2024 and is the fastest-growing region. Rapid urbanization, rising dairy demand, and government-backed modernization programs drive growth. China and India lead regional adoption, supported by large-scale dairy expansions and co-operative farming initiatives. Southeast Asian countries are witnessing increasing investments in portable and semi-automatic systems due to fragmented dairy structures. The shift from manual to mechanized milking improves productivity and milk safety. International players are localizing production and service centers to support long-term growth. Increasing consumer demand for quality dairy and herd traceability strengthens the market outlook.
Latin America
Latin America holds around 10% of the market share in 2024, with Brazil, Argentina, and Mexico leading regional demand. Expanding commercial dairy farms and higher milk yield targets fuel equipment adoption. Brazilian dairy processors invest in automation to meet domestic and export demand. Regional governments support dairy modernization through rural development schemes. Most farms still use semi-automatic and stationary systems, but interest in full automation is rising. Technical support, training, and cost-effective equipment are critical for further market growth. Economic fluctuations and import dependency for high-end equipment remain key barriers in smaller markets across the region.
Middle East & Africa (MEA)
MEA contributes approximately 9% to the global milking equipment market in 2024. Dairy development projects in South Africa, Egypt, and parts of the GCC drive equipment sales. Regional demand is primarily met by semi-automatic and portable systems, given the fragmented farm structure and climatic constraints. Government-led dairy self-sufficiency goals, especially in Saudi Arabia and the UAE, support investment in stationary systems. Africa sees gradual growth through NGO and cooperative-led modernization programs. Infrastructure challenges, funding gaps, and lack of skilled labor hinder faster adoption. However, rising urban milk consumption and food security concerns point to long-term market potential.
Market Segmentations:
By Product Type
- Fully Automatic Milking Equipment
- Semi-Automatic Milking Equipment
By System
- Portable Milking Equipment
- Stationary Milking Equipment
- Barn Milking Equipment
By Application
- Micro Dairy Farms
- Macro Dairy Farms
- Others
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The milking equipment market features a mix of global leaders and regional manufacturers focusing on automation, precision, and herd management technologies. Lely remains a top player with its robotic milking systems widely adopted in advanced dairy regions. GEA Group Aktiengesellschaft leverages its engineering expertise to offer integrated milking solutions and smart automation platforms. BouMatic Robotics B.V. emphasizes innovation in rotary and robotic milking units tailored for high-throughput farms. Fullwood Packo provides hybrid systems combining automation and herd comfort. Agrifac Machinery BV and AMS-Galaxy serve commercial farms with scalable milking solutions. Regional players like Kanters Holland BV, S.A. Christensen & Co., Vansun Technologies Pvt Ltd, Prompt Dairy Tech, and Bisstarr Milking Systems focus on cost-effective, semi-automatic, and portable systems catering to small and medium farms across Asia and Africa. Product reliability, after-sales support, and customization are key areas of competition. Leading firms are investing in IoT integration, mobile interfaces, and sustainability-driven innovations to strengthen market share.
Key Player Analysis
- Lely
- GEA Group Aktiengesellschaft
- BouMatic Robotics B.V.
- Fullwood Packo
- Agrifac Machinery BV
- AMS-Galaxy
- Kanters Holland BV
- A. Christensen & Co.
- Vansun Technologies Pvt Ltd
- Prompt Dairy Tech
- Bisstarr Milking Systems
Recent Developments
- In April 2024, Agrifac Machinery BV expanded the corporate sector of the firm in Seward, Nebraska. This development has provided a broader space for the firm in the competitive landscape.
- In October 2023, Lely partnered with Konrad Pumpe GmbH. This move helped farmers gain more flexibility in terms of automatic feeding.
Report Coverage
The research report offers an in-depth analysis based on Product Type, System, Application and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand for robotic milking systems will rise with labor shortages and large herd management needs.
- Integration of IoT and data analytics will enhance precision in milk yield tracking and herd health.
- Portable and semi-automatic systems will gain traction in small and mid-sized dairy farms.
- Sustainability-focused designs will drive development of energy-efficient and water-saving milking units.
- Growth in dairy exports will push commercial farms to invest in high-capacity milking technologies.
- Emerging markets will adopt modern equipment through government support and dairy infrastructure upgrades.
- Predictive maintenance features will reduce downtime and improve operational reliability on large farms.
- Cloud-based herd management platforms will support remote monitoring and compliance tracking.
- Manufacturers will focus on modular designs to serve both high-end and cost-sensitive segments.
- Rising consumer demand for clean-label dairy will increase investments in hygienic and automated milking systems.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Automation in Dairy Farming
Labor shortages and the need for consistent, hygienic milking routines are pushing dairy farms to adopt fully automatic milking systems. Automation reduces manual labor, increases throughput, and enables real-time monitoring of milk yield and animal health, driving market growth especially in developed regions.
Expansion of Large-Scale Commercial Dairy Farms
The global increase in macro dairy farms is fueling demand for high-capacity, stationary, and fully automated milking equipment. These operations require efficient, scalable solutions to optimize yield, reduce labor costs, and meet growing consumer and export demand for dairy products.
Emphasis on Animal Welfare and Milk Quality
Stricter regulations and consumer awareness around animal health and milk hygiene are prompting investment in advanced milking systems. Modern equipment with sensors and analytics ensures gentle milking, early detection of health issues, and consistent milk quality, supporting market expansion.
Integration of IoT and Data-Driven Dairy Management
The adoption of IoT-enabled milking systems allows for real-time data collection on milk yield, cow health, and equipment performance. This digital transformation enables predictive maintenance, improved herd management, and operational efficiency, making smart milking solutions increasingly attractive.
Government Support and Dairy Modernization Initiatives
In emerging markets, government-backed programs and incentives are encouraging the adoption of modern milking equipment. These initiatives aim to boost rural productivity, improve milk safety, and support the transition from manual to mechanized dairy operations, expanding the market base.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Milking equipment market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Milking equipment market projected to grow between 2024 and 2032?
What factors are driving the growth of the Milking Equipment Market?
What are the key segments within the Milking Equipment Market?
What are some challenges faced by the Milking Equipment Market?
Who are the major players in the Milking Equipment Market?
Which segment is leading the market share?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By System
- 1.2.1 Portable Milking Equipment
- 1.2.2 Stationary Milking Equipment
- 1.2.3 Barn Milking Equipment
- 1.3 By Application
- 1.3.1 Micro Dairy Farms
- 1.3.2 Macro Dairy Farms
- 1.3.3 Others
- 1.4 By Product Type
- 1.4.1 Fully Automatic Milking Equipment
- 1.4.2 Semi-Automatic Milking Equipment
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 4,194.5 million → 2032: USD 6,486.22 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Milking Equipment Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Milking Equipment Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Milking Equipment Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Milking Equipment Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Milking Equipment Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Milking Equipment Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Milking Equipment Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Milking Equipment Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 4,194.5 million → 2032: USD 6,486.22 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Milking Equipment Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By System - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Portable Milking Equipment
- 12.3.7.2 Stationary Milking Equipment
- 12.3.7.3 Barn Milking Equipment
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Micro Dairy Farms
- 12.4.7.2 Macro Dairy Farms
- 12.4.7.3 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Product Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Fully Automatic Milking Equipment
- 12.5.7.2 Semi-Automatic Milking Equipment
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Milking Equipment End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Milking Equipment Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Milking Equipment Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Milking Equipment Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Lely
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 GEA Group Aktiengesellschaft
- 18.4 BouMatic Robotics B.V.
- 18.5 Fullwood Packo
- 18.6 Agrifac Machinery BV
- 18.7 AMS-Galaxy
- 18.8 Vansun Technologies Pvt Ltd
- 18.9 Prompt Dairy Tech
- 18.10 Kanters Holland BV
- 18.11 Bisstarr Milking Systems
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

