
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Occupancy Sensor Market Size 2024 | USD 2,919.25 million |
| Occupancy Sensor Market, CAGR | 10.69% |
| Occupancy Sensor Market Size 2032 | USD 6,961.71 million |
Market Overview:
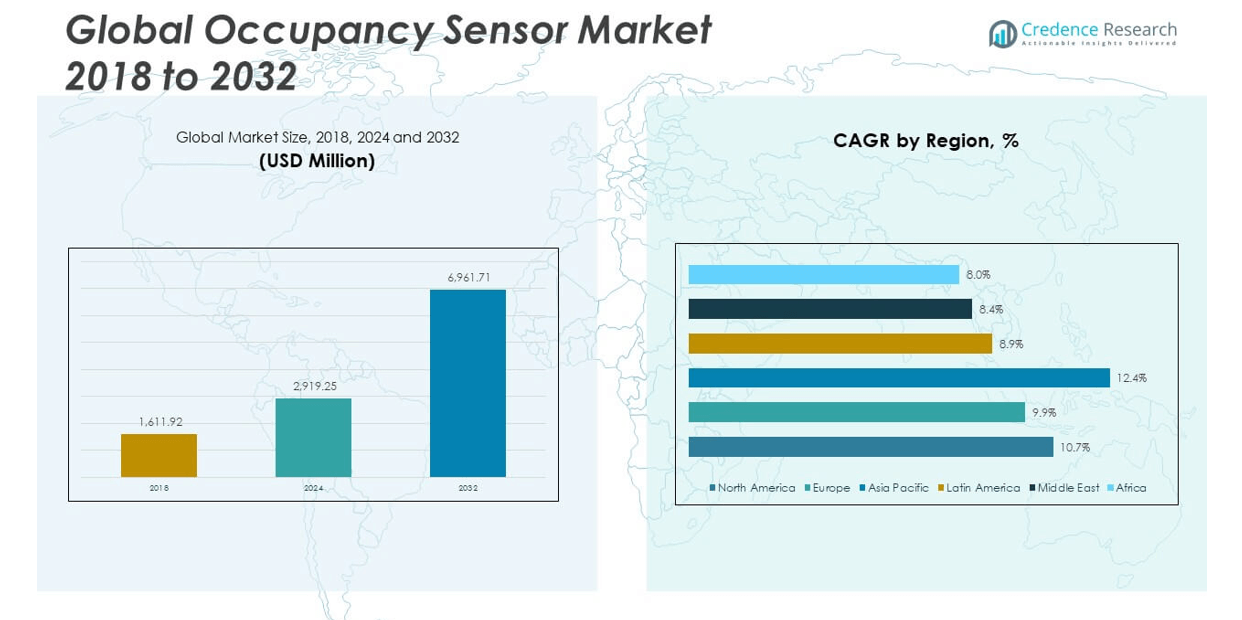
The Global Occupancy Sensor Market size was valued at USD 1,611.92 million in 2018 to USD 2,919.25 million in 2024 and is anticipated to reach USD 6,961.71 million by 2032, at a CAGR of 10.69% during the forecast period.
The global occupancy sensor market is primarily driven by the growing emphasis on energy efficiency across commercial, residential, and industrial sectors. As smart buildings and automation systems become more prevalent, occupancy sensors play a critical role in minimizing energy consumption by enabling intelligent control of lighting, HVAC, and security systems. Regulatory bodies across the U.S., European Union, and Asia-Pacific have introduced stringent building codes and energy-efficiency mandates, prompting widespread adoption of occupancy-based solutions. Technological advancements in infrared, ultrasonic, and dual-technology sensors have improved detection accuracy, response times, and integration capabilities with IoT platforms. Furthermore, the increasing use of artificial intelligence (AI) and machine learning algorithms in building management systems enhances real-time data analysis for space utilization and energy optimization. The rising demand for contactless and automated solutions in public infrastructure, especially in the wake of hygiene concerns post-pandemic, further boosts the market. Growing investments in smart city initiatives and sustainable infrastructure projects globally continue to fuel demand for occupancy sensors in lighting, ventilation, and energy management applications.
Regionally, North America holds the largest share of the global occupancy sensor market, driven by strong regulatory frameworks, early adoption of smart building technologies, and increased energy-saving initiatives across the United States and Canada. The U.S., in particular, benefits from government support for green buildings and advanced infrastructure for smart energy systems. Europe follows closely, with countries like Germany, the United Kingdom, and France actively implementing energy directives and modernizing legacy systems in both residential and commercial buildings. Meanwhile, the Asia-Pacific region is expected to witness the fastest growth during the forecast period, fueled by rapid urbanization, expanding industrialization, and aggressive investment in smart cities and energy-efficient buildings across China, India, Japan, and Southeast Asia. Technological advancements and growing awareness of sustainable practices in these countries support widespread adoption. Latin America and the Middle East & Africa are emerging markets in this domain, with increasing investments in smart infrastructure, construction, and energy management systems indicating strong potential for long-term growth.
Market Insights:
- The Global Occupancy Sensor Market grew from USD 1,611.92 million in 2018 to USD 2,919.25 million in 2024 and is projected to reach USD 6,961.71 million by 2032, expanding at a CAGR of 10.69%.
- Rising emphasis on energy efficiency and government-enforced building codes is driving large-scale adoption of occupancy sensors across commercial, residential, and industrial facilities.
- Advancements in infrared, ultrasonic, dual-technology, and AI-powered sensors are enhancing accuracy, detection speed, and integration with smart building systems.
- Post-pandemic demand for contactless solutions in public infrastructure has increased deployment of occupancy sensors in restrooms, transit hubs, and office entryways.
- Integration with IoT and wireless protocols such as Zigbee and LoRa enables real-time monitoring and control, supporting the growth of connected buildings.
- Performance challenges persist in high-interference environments, requiring sensor design improvements and better adaptability to complex spatial layouts.
- Regionally, North America leads the market share due to early smart building adoption, while Asia Pacific is the fastest-growing region, fueled by smart city investments and rising energy demands.
Market Drivers:
Rising Emphasis on Energy Efficiency and Smart Building Integration
Energy efficiency mandates and sustainability goals are key forces behind the growth of the Global Occupancy Sensor Market. Governments and regulatory agencies worldwide are enforcing stringent energy codes for residential and commercial buildings, prompting the adoption of occupancy-based lighting and HVAC control systems. These sensors significantly reduce electricity consumption by detecting human presence and automatically managing systems. The integration of occupancy sensors into building automation systems ensures cost savings and operational efficiency. With increased focus on net-zero energy buildings and LEED certifications, these sensors are becoming standard components in new construction projects. The Global Occupancy Sensor Market benefits from the push toward intelligent infrastructure and smarter energy consumption practices.
- For example, Lutron Electronics’ Vive wireless system integrates passive infrared (PIR) sensors that not only detect occupancy but also dynamically adjust lighting according to daylight availability, leading to measurable reductions in power consumption.
Expansion of IoT and Wireless Communication Technologies Across Facilities
The development of wireless communication technologies has transformed the performance and accessibility of occupancy sensors. Integration with IoT platforms enables centralized monitoring, remote access, and seamless control of multiple devices. These advancements support real-time occupancy tracking and enhance system responsiveness in dynamic environments such as offices, retail stores, and hospitals. The market benefits from protocols such as Zigbee, Z-Wave, and LoRa, which simplify installation and reduce infrastructure costs. Occupancy sensors are now core components in facility management systems that rely on automation and data analytics. This shift strengthens demand for compact, interoperable sensors across a range of end-use industries.
- For instance, Pressac’s wireless room occupancy sensors utilize passive infrared technology to detect motion within a 360-degree field of view up to 6 meters, transmitting real-time presence data via the EnOcean wireless protocol.
Adoption of AI-Based Analytics and Predictive Controls in Commercial Spaces
Artificial intelligence is revolutionizing the functionality of occupancy sensors by enhancing data interpretation and system intelligence. In commercial environments, sensors equipped with AI algorithms enable predictive control of lighting, ventilation, and security systems based on learned usage patterns. This not only improves occupant comfort but also ensures optimal energy performance throughout the facility. It supports data-driven decisions in workspace management and operational planning. The Global Occupancy Sensor Market is advancing rapidly due to the deployment of intelligent sensors that align with the evolving needs of smart cities and connected infrastructure. These solutions are increasingly valuable in large-scale enterprises, educational campuses, and healthcare centers.
Growth of Contactless Technologies in Post-Pandemic Infrastructure Design
The increased demand for hygienic, touch-free solutions has accelerated interest in occupancy sensors across multiple sectors. Building operators are prioritizing automation to minimize physical contact and enhance occupant safety. Occupancy sensors enable contactless control of doors, lighting, and restroom utilities, helping facilities meet health and safety standards. Public infrastructure such as airports, transit hubs, and government offices are adopting these technologies to ensure safer environments. It supports compliance with workplace guidelines and reduces dependence on manual operations. The expanding role of contactless systems in smart infrastructure contributes to the broader growth of occupancy sensors globally.
Market Trends:
Emergence of Multi-Sensor Fusion Technologies for Enhanced Accuracy
Advanced occupancy sensors are increasingly adopting multi-sensor fusion technologies that combine data from infrared, ultrasonic, microwave, and image recognition systems. This approach improves detection accuracy in complex environments by minimizing false triggers and enhancing responsiveness. Multi-sensor designs are gaining traction in high-traffic public areas, where variations in lighting, noise, and movement require more refined sensing. Manufacturers are developing integrated units that adjust to changing ambient conditions and deliver real-time data with higher reliability. The Global Occupancy Sensor Market is witnessing a transition from single-technology sensors to hybrid platforms that support diverse applications. It reflects a broader shift toward intelligent sensing systems that prioritize precision and adaptability.
Integration of LiDAR and 3D Imaging for Spatial Awareness
LiDAR and 3D imaging technologies are making inroads into occupancy sensing, offering advanced spatial recognition and real-time mapping capabilities. These technologies enable sensors to detect not only motion but also object size, count, and positioning within a space. This advancement allows for differentiated responses in areas like meeting rooms, classrooms, and retail zones, where occupancy density and layout vary. LiDAR-based sensors are becoming valuable in managing space utilization and people flow in large facilities. The integration of 3D imaging enhances sensor functionality in dynamic environments and supports predictive modeling. The Global Occupancy Sensor Market is evolving to include more sophisticated spatial analysis tools that go beyond traditional motion detection.
- For example, Ommatidia LiDAR’s Q-Series Laser RADARdemonstrates a leap in spatial awareness, integrating parallel LiDAR with 3D imaging and vibrometry. The system generates high-density point clouds with a spatial resolution of up to 1 mm and captures vibration data at up to 10 kHz, enabling real-time monitoring of object count, size, and precise positioning.
Growing Use of Edge Computing in Occupancy Sensing Solutions
Edge computing is reshaping occupancy sensing by enabling local data processing directly within the sensor or nearby gateways. This reduces latency, increases data security, and improves system responsiveness in real-time applications. Edge-enabled sensors operate efficiently without relying on constant cloud connectivity, making them ideal for critical infrastructure and remote environments. The trend supports decentralized building automation where immediate decision-making is essential. In the Global Occupancy Sensor Market, edge computing is opening new possibilities for smart lighting, emergency response, and environmental control systems. It empowers facilities to maintain performance and security while reducing dependence on centralized data centers.
- For instance, Edge-enabled occupancy sensors from companies like GAO Tek and deployments by major hotel chains (e.g., Marriott, Hilton) process data locally, reducing latency to under 50 milliseconds for real-time applications. These systems analyze occupancy, environmental, and equipment data at the edge, enabling immediate adjustments to lighting and HVAC controls.
Adoption of Battery-Free and Energy-Harvesting Sensor Designs
Battery-free and energy-harvesting technologies are gaining popularity in occupancy sensors, driven by demand for low-maintenance and sustainable solutions. These sensors generate power through kinetic, thermal, or solar energy, eliminating the need for frequent battery replacements. This trend is particularly relevant in large-scale installations and retrofitting projects where wiring or maintenance access is limited. Manufacturers are investing in self-powered sensor platforms that align with green building standards and long-term cost efficiency. It helps reduce operational disruption and supports continuous sensing in distributed networks. The Global Occupancy Sensor Market is embracing these innovations to support environmental goals and streamline infrastructure deployment.
Market Challenges Analysis:
Integration Complexities Across Diverse Building Environments and Legacy Systems
One of the key challenges facing the Global Occupancy Sensor Market is the difficulty of integrating new sensor technologies into existing building infrastructures and legacy systems. Many older facilities lack standardized wiring, communication protocols, or centralized control systems, making sensor deployment technically complex and costly. Compatibility issues arise when occupancy sensors must interface with varied lighting, HVAC, or automation platforms. Facility managers often delay adoption due to concerns over installation downtime, retrofit expenses, or disruption to daily operations. In commercial buildings with multiple vendors and platforms, seamless interoperability remains limited. It hampers large-scale implementation and limits the benefits of sensor-based energy management.
Performance Limitations in Dynamic and High-Interference Environments
Occupancy sensors often face detection inaccuracies in environments with fluctuating temperatures, noise levels, or unpredictable motion patterns. High ceilings, partitioned spaces, and areas with reflective surfaces can interfere with signal transmission or motion recognition, leading to false positives or missed occupancy detection. These limitations reduce reliability in settings like warehouses, hospitals, or open-plan offices where user movement is irregular. The Global Occupancy Sensor Market continues to grapple with fine-tuning sensor algorithms and hardware design to overcome such conditions. It requires ongoing R&D investments and customization to ensure consistent performance. Manufacturers must also address user concerns regarding privacy, especially with image-based and AI-enabled sensors in sensitive spaces.
Market Opportunities:
Rising Demand for Smart Cities and Intelligent Infrastructure Deployment
The growing global investment in smart cities presents a significant opportunity for the Global Occupancy Sensor Market. Governments and urban planners are prioritizing intelligent infrastructure that improves energy efficiency, public safety, and traffic management. Occupancy sensors play a critical role in smart lighting, automated public buildings, and transportation hubs. Their ability to provide real-time data supports responsive systems that adapt to human presence and activity levels. It positions occupancy sensors as essential tools in the urban digital transformation agenda. Demand is expected to accelerate as cities expand their adoption of data-driven solutions.
Expansion Across Emerging Markets and Untapped Commercial Sectors
Emerging economies in Asia Pacific, Latin America, and the Middle East offer strong growth potential due to rapid urbanization and rising infrastructure spending. Commercial sectors such as retail, hospitality, and healthcare are beginning to adopt sensor-based automation to enhance customer experience and operational efficiency. The Global Occupancy Sensor Market can leverage this demand by offering scalable, cost-effective, and wireless solutions suited for diverse building types. It also benefits from increasing awareness of energy savings and sustainability in these regions. Local manufacturing partnerships and supportive government policies can accelerate adoption and drive long-term market expansion.
Market Segmentation Analysis:
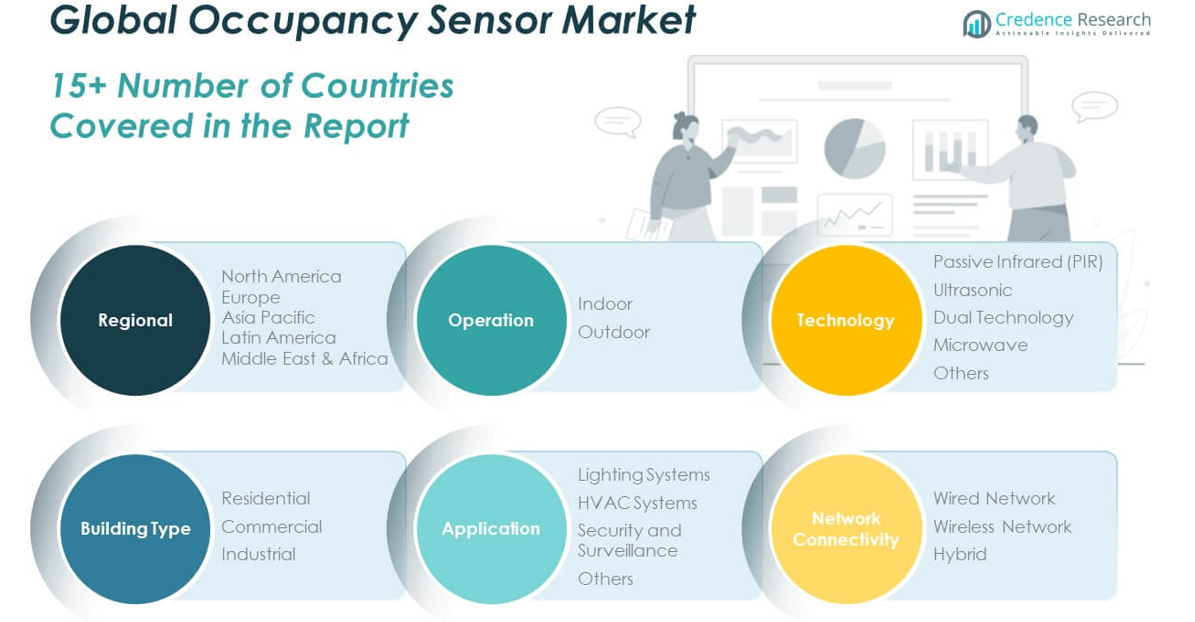
The Global Occupancy Sensor Market is segmented by operation, technology, building type, application, and network connectivity, each contributing to its growth trajectory.
By operation, the indoor segment holds a dominant share due to high adoption in offices, retail spaces, and residential buildings, while the outdoor segment is expanding in smart city and security applications.
- For instance, Signify’s Interact Officeplatform is widely deployed in office buildings and retail spaces. It uses integrated occupancy sensors to automate lighting and HVAC, reporting energy savings of up to 80% in large office installations.
By technology, passive infrared (PIR) sensors lead due to cost efficiency and simplicity, followed by ultrasonic and dual technology sensors that offer enhanced accuracy. Microwave sensors are gaining traction in complex environments, while the "others" category includes emerging sensor technologies.
- For example, Honeywell’s IS3000 Seriespassive infrared sensors are used globally in commercial and residential buildings for cost-effective motion detection, with documented installation in over 10 million sites.
By building type, the commercial segment dominates market share due to widespread use in corporate buildings, malls, and healthcare facilities. The residential segment is growing steadily with the rise of smart homes, and the industrial segment shows potential in automation and safety applications.
By application, lighting systems hold the largest share, with increasing demand for automated energy-saving solutions. HVAC systems and security and surveillance applications also see rising integration of occupancy sensors.
By network connectivity, wireless solutions are gaining preference due to flexibility and ease of installation, while wired networks retain relevance in large-scale commercial projects. Hybrid systems combine both for improved reliability. The Global Occupancy Sensor Market continues to evolve as adoption increases across all segments.
Segmentation:
By Operation:
- Indoor
- Outdoor
By Technology:
- Passive Infrared (PIR)
- Ultrasonic
- Dual Technology
- Microwave
- Others
By Building Type:
- Residential
- Commercial
- Industrial
By Application:
- Lighting Systems
- HVAC Systems
- Security and Surveillance
- Others
By Network Connectivity:
- Wired Network
- Wireless Network
- Hybrid
By Region:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America Occupancy Sensor Market
The North America Occupancy Sensor Market size was valued at USD 670.94 million in 2018 to USD 1,201.85 million in 2024 and is anticipated to reach USD 2,874.48 million by 2032, at a CAGR of 10.7% during the forecast period. North America holds the largest share of the Global Occupancy Sensor Market, accounting for approximately 38.7% of the global revenue in 2024. Strong regulatory frameworks, advanced infrastructure, and early adoption of smart building technologies drive regional dominance. The U.S. leads due to federal energy efficiency mandates, widespread integration of occupancy sensors in commercial real estate, and ongoing investments in building automation. Market growth is supported by favorable policies like the Inflation Reduction Act and Energy Star certifications, which encourage smart lighting and HVAC systems. It benefits from a high concentration of manufacturers, system integrators, and smart city projects focused on sustainability and automation.
Europe Occupancy Sensor Market
The Europe Occupancy Sensor Market size was valued at USD 479.29 million in 2018 to USD 838.15 million in 2024 and is anticipated to reach USD 1,887.41 million by 2032, at a CAGR of 9.9% during the forecast period. Europe contributes roughly 27% of the Global Occupancy Sensor Market in 2024, driven by rising energy conservation initiatives and strict building regulations such as the EU Energy Performance of Buildings Directive. Countries like Germany, the UK, and France are adopting smart technologies in residential and commercial sectors to meet sustainability targets. High penetration of green building certifications and government incentives is boosting the deployment of occupancy-based controls. It gains traction in retrofitting older infrastructure, with emphasis on automation and efficient energy use. Demand from healthcare, hospitality, and transportation sectors is also contributing to steady growth across the region.
Asia Pacific Occupancy Sensor Market
The Asia Pacific Occupancy Sensor Market size was valued at USD 314.70 million in 2018 to USD 617.03 million in 2024 and is anticipated to reach USD 1,663.88 million by 2032, at a CAGR of 12.4% during the forecast period. Asia Pacific holds nearly 19.9% of the Global Occupancy Sensor Market in 2024 and is the fastest-growing region. Rapid urbanization, expanding infrastructure, and increased investment in smart city development across China, India, Japan, and Southeast Asia are driving demand. Governments in the region are prioritizing energy efficiency and intelligent building standards to manage rising energy needs. The construction of commercial office buildings, metro rail stations, airports, and data centers is fueling sensor deployment. It benefits from rising awareness of automation and the growing middle-class population demanding smart living solutions.
Latin America Occupancy Sensor Market
The Latin America Occupancy Sensor Market size was valued at USD 72.91 million in 2018 to USD 130.32 million in 2024 and is anticipated to reach USD 273.48 million by 2032, at a CAGR of 8.9% during the forecast period. Latin America accounts for approximately 4.2% of the Global Occupancy Sensor Market in 2024. Countries such as Brazil, Mexico, and Chile are investing in modernizing infrastructure and adopting energy-saving technologies. Market growth is supported by the development of commercial real estate, hospitality, and public infrastructure projects that require automated lighting and climate control. It faces challenges in affordability and awareness, but improving regulatory frameworks and private sector participation are accelerating sensor integration. Demand is expected to rise steadily with increased focus on building safety and efficiency.
Middle East Occupancy Sensor Market
The Middle East Occupancy Sensor Market size was valued at USD 45.33 million in 2018 to USD 75.06 million in 2024 and is anticipated to reach USD 151.16 million by 2032, at a CAGR of 8.4% during the forecast period. The Middle East holds a 2.4% share of the Global Occupancy Sensor Market in 2024, driven by smart city initiatives in the UAE, Saudi Arabia, and Qatar. Governments are investing heavily in intelligent infrastructure as part of economic diversification plans. The use of occupancy sensors is increasing in airports, hotels, and large public buildings, where energy optimization and modern design standards are a priority. It is also benefiting from rising demand for sustainable cooling and lighting in extreme climate conditions. Growth is reinforced by collaborations between public institutions and technology providers.
Africa Occupancy Sensor Market
The Africa Occupancy Sensor Market size was valued at USD 28.77 million in 2018 to USD 56.83 million in 2024 and is anticipated to reach USD 111.30 million by 2032, at a CAGR of 8.0% during the forecast period. Africa represents approximately 1.8% of the Global Occupancy Sensor Market in 2024. The region is in the early phase of adoption, with market activity concentrated in South Africa, Nigeria, Kenya, and Egypt. Rising urban population, improving access to electricity, and growing awareness of energy conservation are driving demand. It is gaining momentum through donor-backed smart grid and green building projects. Despite infrastructural limitations, commercial and institutional developments are gradually incorporating automated systems. The long-term outlook remains positive with increasing focus on sustainable urban planning.
Key Player Analysis:
- Signify N.V. (Philips Lighting)
- Legrand S.A.
- Schneider Electric
- Johnson Controls International plc
- Honeywell International Inc.
- Eaton Corporation plc
- Acuity Brands, Inc
Competitive Analysis:
The Global Occupancy Sensor Market is highly competitive, driven by rapid technological advancements and growing demand for smart building solutions. Key players include Honeywell International Inc., Legrand SA, Johnson Controls, Schneider Electric, Signify N.V., and Texas Instruments Incorporated. These companies focus on expanding product portfolios, enhancing sensor accuracy, and integrating IoT and AI technologies. Strategic partnerships, mergers, and acquisitions are common, aimed at strengthening market presence and accelerating innovation. Startups and regional players are entering the market with cost-effective and energy-efficient solutions, intensifying competition across segments. It is witnessing increased investment in R&D to develop multi-sensor platforms and wireless connectivity features. Price competitiveness and compliance with regional energy efficiency standards remain critical factors for sustained growth. Companies that can deliver reliable, scalable, and interoperable solutions are expected to maintain a strong position in the evolving occupancy sensor landscape.
Recent Developments:
- In June 2025, Schneider Electric expanded its strategic partnership with NVIDIA to co-develop AI-driven systems tailored for data center infrastructure. The collaboration aims to integrate advanced occupancy sensing capabilities into AI-optimized cooling, power, and building management platforms, enhancing energy efficiency and smart automation.
- In April 2025, Johnson Controls released a study on its OpenBlue Smart Building Platform, which integrates real-time data visibility and AI-driven energy-saving recommendations. This platform is closely linked to occupancy sensors, as such technologies are essential for optimizing building performance and reducing operating costs through smart, automated responses to occupancy data.
- In March 2025, Texas Instruments introduced the MSPM0C1104 MCU and AMC series modulators designed for compact automation and robotics applications. These developments provide occupancy sensor manufacturers with smaller, more efficient microcontrollers and modulators that streamline device integration and improve sensor responsiveness.
Market Concentration & Characteristics:
The Global Occupancy Sensor Market exhibits moderate market concentration, with a mix of multinational corporations and regional players competing across varied application segments. It is characterized by rapid technological innovation, with firms focusing on integrating AI, IoT, and wireless communication into sensor platforms. The market features strong demand from commercial, industrial, and residential sectors, each requiring tailored solutions. Product differentiation through sensing technologies such as passive infrared, ultrasonic, and dual-technology sensors plays a key role in competitive positioning. It remains highly dynamic, with frequent product launches and continuous R&D investment driving evolution. Regulatory compliance, energy efficiency standards, and system interoperability influence buyer preferences and vendor strategies.
Report Coverage:
The research report offers an in-depth analysis based on operation, technology, building type, application, and network connectivity. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Rising adoption of smart building technologies will continue to drive sensor integration across commercial and residential projects.
- Increasing global energy efficiency mandates will push demand for automated lighting and HVAC systems.
- Advancements in AI and machine learning will enhance sensor accuracy and enable predictive control.
- Expansion of smart city infrastructure in emerging economies will create new market opportunities.
- Development of battery-free and energy-harvesting sensors will reduce maintenance costs and support sustainability goals.
- Edge computing capabilities in sensors will improve real-time responsiveness and data security.
- Growing use of LiDAR and 3D imaging technologies will support space utilization analytics in high-traffic environments.
- Collaboration between sensor manufacturers and automation platform providers will accelerate ecosystem integration.
- Demand for contactless and hygiene-focused automation will sustain growth in healthcare and public infrastructure.
- Regional diversification of manufacturing and supply chains will support scalability and reduce geopolitical risks.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Energy Efficiency Mandates and Smart Building Integration
Government-enforced building codes and sustainability goals are driving the adoption of occupancy sensors for automated lighting and HVAC control, helping reduce energy consumption and operational costs in commercial, residential, and industrial facilities.
Advancements in Sensor Technologies and AI Integration
Innovations in infrared, ultrasonic, dual-technology, and AI-powered sensors are improving detection accuracy, response times, and seamless integration with smart building and IoT platforms, making occupancy sensors more effective and appealing for modern infrastructure.
Expansion of IoT and Wireless Communication
The proliferation of wireless protocols like Zigbee, Z-Wave, and LoRa enables easier installation, centralized monitoring, and real-time control, supporting the deployment of occupancy sensors in both new and retrofit projects across diverse building types.
Post-Pandemic Demand for Contactless Solutions
Heightened hygiene concerns have accelerated the adoption of contactless automation in public infrastructure, with occupancy sensors enabling touch-free control of lighting, doors, and utilities in restrooms, transit hubs, and offices.
Growth of Smart Cities and Intelligent Infrastructure
Global investments in smart city initiatives and sustainable infrastructure projects are fueling demand for occupancy sensors, which are essential for energy management, space utilization, and responsive automation in urban environments.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current and projected size of the Occupancy Sensor Market?
Which sectors are adopting occupancy sensors the most?
Which region currently leads the Occupancy Sensor Market?
How are new technologies impacting the market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Operation
- 1.2.1 Indoor
- 1.2.2 Outdoor
- 1.3 By Technology
- 1.3.1 Passive Infrared (PIR)
- 1.3.2 Ultrasonic
- 1.3.3 Dual Technology
- 1.3.4 Microwave
- 1.3.5 Others
- 1.4 By Application
- 1.4.1 Lighting Systems
- 1.4.2 HVAC Systems
- 1.4.3 Security and Surveillance
- 1.4.4 Others
- 1.5 By Building Type
- 1.5.1 Residential
- 1.5.2 Commercial
- 1.5.3 Industrial
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 2,919.25 million → 2032: USD 6,961.71 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Occupancy Sensor Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Occupancy Sensor Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Occupancy Sensor Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Occupancy Sensor Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Occupancy Sensor Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Occupancy Sensor Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Occupancy Sensor Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Occupancy Sensor Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 2,919.25 million → 2032: USD 6,961.71 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Occupancy Sensor Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Operation - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Indoor
- 12.3.7.2 Outdoor
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Technology - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Passive Infrared (PIR)
- 12.4.7.2 Ultrasonic
- 12.4.7.3 Dual Technology
- 12.4.7.4 Microwave
- 12.4.7.5 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Lighting Systems
- 12.5.7.2 HVAC Systems
- 12.5.7.3 Security and Surveillance
- 12.5.7.4 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Building Type - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Residential
- 12.6.7.2 Commercial
- 12.6.7.3 Industrial
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Occupancy Sensor End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Occupancy Sensor Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Occupancy Sensor Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Occupancy Sensor Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Signify N.V. (Philips Lighting)
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Legrand S.A.
- 18.4 Schneider Electric
- 18.5 Johnson Controls International plc
- 18.6 Honeywell International Inc.
- 18.7 Eaton Corporation plc
- 18.8 Acuity Brands, Inc.
- 18.9 Texas Instruments Incorporated
- 18.10 Siemens AG
- 18.11 Lutron Electronics
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

