
Direct Fired Absorption Chiller Market Overview:
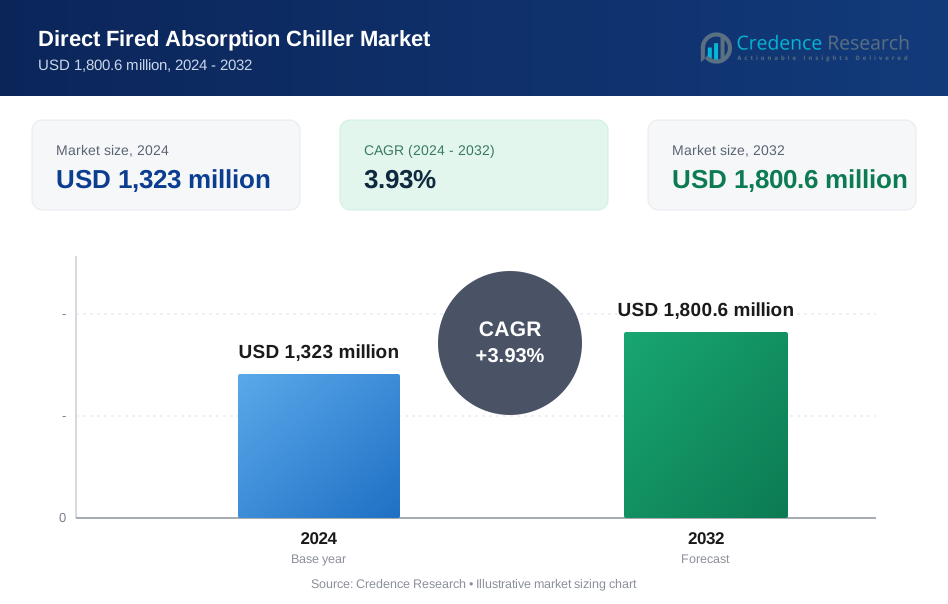
The direct fired absorption chiller market was valued at USD 1,323 million in 2024 and is projected to reach USD 1,800.6 million by 2032, expanding at a compound annual growth rate (CAGR) of 3.93% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Direct Fired Absorption Chiller Market Size 2024 | USD 1,323 million |
| Direct Fired Absorption Chiller Market, CAGR | 3.93% |
| Direct Fired Absorption Chiller Market Size 2032 | USD 1,800.6 million |
Direct Fired Absorption Chiller Market Insights
- Market growth is driven by rising demand for low-electricity cooling solutions, especially in industrial facilities, hospitals, and district cooling systems, where shifting load from power grids to gas-fired thermal energy improves energy security and operating stability.
- Key trends include increasing adoption of double-stage technology, which holds the dominant segment share due to higher efficiency, and growing interest in alternative fuels such as biogas and hydrogen blends to support long-term decarbonization goals.
- The competitive landscape is shaped by established global players focusing on high-capacity systems, advanced controls, and long-term service contracts, with competition centered on efficiency, reliability, and lifecycle cost optimization.
- Regionally, Asia-Pacific leads with around 34% market share, followed by North America at ~28% and Europe at ~24%, while systems above 500 kW dominate capacity segmentation, supported by large-scale industrial and district cooling applications.

Direct Fired Absorption Chiller Market Segmentation Analysis:
By Technology Type:
By technology type, double-stage direct fired absorption chillers dominate the market, accounting for the majority of installed capacity due to their higher coefficient of performance and superior thermal efficiency compared to single-stage systems. Double-stage units are widely adopted in large commercial buildings, district cooling networks, and industrial facilities where consistent high-load cooling is required. Their ability to achieve deeper cooling with optimized fuel utilization makes them economically attractive over long operating cycles. Single-stage chillers retain relevance in smaller installations and retrofit projects, but efficiency-driven procurement continues to favor double-stage configurations.
- For instance, Johnson Controls’ YORK® double-effect absorption chillers have been deployed in multi-building campus installations with individual unit capacities above 4,000 tons, operating on natural gas or fuel oil and designed for chilled water supply temperatures as low as 4 °C, supporting data centers, airports, and hospital complexes with round-the-clock cooling demand.
By Cooling Capacity:
By cooling capacity, the above 500 kW segment holds the dominant market share, driven by strong demand from district cooling plants, data centers, hospitals, and large manufacturing facilities. These high-capacity systems benefit from economies of scale, longer operating hours, and better fuel efficiency, making them suitable for centralized cooling applications. The 100–500 kW segment serves mid-sized commercial buildings and institutional facilities, while below 100 kW systems remain limited to niche applications. Rising urban infrastructure investments and industrial expansion continue to reinforce demand for high-capacity absorption chillers.
- For instance, Thermax has deployed direct-fired absorption chiller installations with individual unit cooling capacities exceeding 7,000 kW in large district cooling and industrial process applications, enabling centralized cooling across multiple buildings from a single energy center.
By Fuel Source:
By fuel source, natural gas is the dominant sub-segment, representing the largest share of direct fired absorption chiller installations due to its widespread availability, stable pricing, and cleaner combustion profile compared to liquid fuels. Gas-based systems are commonly deployed in regions with strong pipeline infrastructure and strict electrical peak-demand regulations. Diesel-powered units are used in fuel-constrained or remote locations, while biogas adoption is increasing in industrial and municipal settings seeking waste-to-energy integration. Hydrogen blends remain in early adoption stages, driven by long-term decarbonization initiatives.
Key Growth Driver
Rising Demand for Low-Electricity Cooling Solutions
One of the primary growth drivers for the direct fired absorption chiller market is the increasing need to reduce dependence on electricity-intensive cooling systems. As power grids face rising peak loads, especially in urban and industrial regions, end users are adopting gas-fired cooling technologies to manage energy costs and grid stability. Direct fired absorption chillers operate independently of large electrical inputs, making them particularly attractive for hospitals, district cooling networks, data centers, and industrial plants with continuous cooling demand. Their ability to shift cooling loads away from electricity toward thermal energy supports demand-side management strategies and enhances operational resilience. This advantage is increasingly relevant in regions experiencing frequent power constraints or high electricity tariffs, reinforcing adoption across commercial and industrial facilities.
- For instance, Broad Group has implemented gas-fired absorption chiller systems in industrial facilities where electrical infrastructure is limited, with individual chillers supporting cooling loads above 1,000 kW while electrical consumption remains comparable to that of standard lighting circuits, enabling uninterrupted operation during voltage fluctuations.
Expansion of Industrial and District Cooling Infrastructure
Rapid industrialization and urban infrastructure development are driving sustained demand for large-scale cooling systems, directly supporting the growth of direct fired absorption chillers. Industrial facilities such as refineries, chemical plants, food processing units, and manufacturing hubs require reliable, high-capacity cooling that can operate continuously under heavy thermal loads. Similarly, district cooling projects increasingly favor absorption chillers for centralized energy-efficient cooling across campuses, airports, and mixed-use developments. These systems offer long operational lifespans and stable performance under fluctuating load conditions. As governments and private developers invest in centralized cooling infrastructure to improve energy efficiency and reduce environmental impact, direct fired absorption chillers continue to gain traction as a proven solution for large-scale applications.
- For instance, Yazaki Energy Systems’ double-effect direct fired absorption chillers are designed with corrosion-resistant heat exchangers and solution management systems that support continuous operation over multi-decade service lives, with documented installations operating reliably beyond 20 years in industrial and institutional facilities.
Availability of Diverse Fuel Options and Energy Flexibility
The ability of direct fired absorption chillers to operate on multiple fuel sources significantly enhances their market attractiveness. Natural gas remains the dominant fuel due to its availability and cleaner combustion profile, but increasing adoption of biogas and fuel blends is expanding deployment opportunities. This fuel flexibility enables industrial users to integrate waste-derived fuels, improve energy security, and optimize operating costs. Facilities with access to captive gas supply or cogeneration systems benefit from improved overall energy efficiency when pairing absorption chillers with thermal energy sources. As energy diversification becomes a strategic priority for both public and private sectors, the adaptability of direct fired absorption chillers positions them as a resilient and future-ready cooling technology.
Key Trend & Opportunity
Integration with Decarbonization and Sustainability Initiatives
A major trend shaping the market is the alignment of direct fired absorption chillers with long-term decarbonization strategies. Organizations are increasingly seeking cooling solutions that support lower indirect emissions by reducing electricity consumption and enabling the use of cleaner fuels such as biogas or hydrogen blends. Absorption chillers are being incorporated into sustainable building designs, green industrial parks, and energy-efficient district cooling systems. This trend presents strong opportunities for manufacturers to develop next-generation systems optimized for alternative fuels and hybrid energy configurations. As regulatory frameworks emphasize emissions reduction and energy efficiency, adoption of thermally driven cooling systems is expected to accelerate.
- For instance, multiple government-backed district cooling projects in Asia and Europe have specified direct fired absorption chillers rated above 2,500 kW per unit as part of low-carbon energy master plans, reinforcing their role in long-term sustainable cooling infrastructure for urban and industrial developments.
Technological Advancements in Efficiency and System Control
Ongoing improvements in system design, heat exchanger performance, and digital control technologies are enhancing the efficiency and reliability of direct fired absorption chillers. Advanced automation, remote monitoring, and predictive maintenance capabilities are reducing operational complexity and improving uptime. These advancements are expanding the addressable market by lowering lifecycle costs and simplifying integration with existing building management systems. Opportunities are emerging in retrofit projects where older cooling systems are replaced with higher-efficiency absorption units. As performance optimization becomes a key purchasing criterion, manufacturers offering advanced, digitally enabled systems are well positioned to capture new demand.
- For instance, several recent industrial projects have specified direct fired absorption chillers equipped with condition-based maintenance algorithms that track vibration, solution purity, and burner ignition cycles, enabling early fault detection and supporting uninterrupted cooling for mission-critical manufacturing processes.
Key Challenge
High Initial Capital Investment and Installation Complexity
Despite their operational advantages, direct fired absorption chillers face challenges related to high upfront costs and complex installation requirements. These systems typically involve higher capital expenditure compared to conventional electric chillers due to specialized components, fuel infrastructure, and integration needs. Installation often requires additional space, gas supply arrangements, and skilled technical expertise, which can deter adoption in cost-sensitive or space-constrained projects. For smaller commercial facilities, the return on investment may be less immediately attractive, slowing penetration beyond large-scale applications. Addressing this challenge requires continued cost optimization, modular designs, and stronger value-based positioning by suppliers.
Sensitivity to Fuel Price Volatility and Supply Constraints
The performance economics of direct fired absorption chillers are closely linked to fuel availability and pricing, creating exposure to market volatility. Fluctuations in natural gas or diesel prices can impact operating costs and influence purchasing decisions, particularly in regions with unstable fuel supply chains. Additionally, limited access to gas infrastructure in certain geographies restricts market expansion. While alternative fuels such as biogas and hydrogen blends offer long-term potential, their availability remains uneven. Overcoming this challenge will depend on infrastructure development, diversified fuel strategies, and continued innovation to improve fuel efficiency and adaptability.
Regional Analysis
North America:
North America holds a market share of approximately 28% in the direct fired absorption chiller market, supported by strong adoption in hospitals, district cooling systems, universities, and industrial facilities. The region benefits from well-established natural gas infrastructure, enabling cost-effective deployment of gas-fired cooling solutions. High electricity tariffs during peak demand periods further encourage load shifting toward thermally driven systems. The United States dominates regional demand due to large-scale commercial buildings and industrial plants, while Canada contributes through institutional and district energy projects. Ongoing retrofitting of aging HVAC infrastructure continues to support steady market expansion.
Europe:
Europe accounts for around 24% of the global market, driven by stringent energy efficiency regulations and strong emphasis on reducing electrical grid dependency. Countries such as Germany, France, Italy, and the UK are key adopters, particularly in district heating and cooling networks and industrial facilities. The region shows growing interest in absorption chillers compatible with biogas and low-carbon fuel blends, aligning with decarbonization goals. High natural gas penetration and supportive policy frameworks for energy-efficient buildings sustain demand. However, adoption remains concentrated in large-scale applications where long-term efficiency gains justify higher capital investment.
Asia-Pacific:
Asia-Pacific represents the largest regional market with approximately 34% share, driven by rapid industrialization, urban infrastructure development, and expanding district cooling projects. China, Japan, South Korea, and India are major contributors, supported by growing commercial construction, manufacturing capacity, and energy demand management initiatives. High-capacity direct fired absorption chillers are widely deployed in airports, industrial parks, and large commercial complexes. The region’s increasing electricity demand and grid congestion strengthen the appeal of gas-fired cooling systems. Continued investments in urban development and industrial expansion position Asia-Pacific as the fastest-growing regional market.
Latin America:
Latin America holds an estimated 7% market share, with demand primarily concentrated in Brazil, Mexico, and Chile. Growth is supported by expanding commercial infrastructure, healthcare facilities, and selective industrial applications. Natural gas availability in certain countries enables adoption of direct fired absorption chillers, particularly for large buildings seeking to reduce electricity costs. However, market penetration remains moderate due to limited awareness, higher upfront costs, and uneven gas infrastructure across the region. District cooling projects and industrial modernization initiatives present gradual growth opportunities, especially in urban centers with rising cooling demand.
Middle East & Africa:
The Middle East & Africa region accounts for approximately 7% of the global market, driven by high cooling demand in hot climates and growing investments in large commercial and infrastructure projects. Countries such as Saudi Arabia, the UAE, and Qatar lead adoption, particularly in airports, hospitals, and district cooling systems. Abundant natural gas availability supports the use of direct fired absorption chillers to reduce electricity load during peak demand. In Africa, adoption remains limited but is gradually increasing in industrial and institutional projects. Extreme climate conditions and large-scale developments continue to support regional demand.
Direct Fired Absorption Chiller Market Segmentations:
By Technology Type
- Single-Stage
- Double-Stage
By Cooling Capacity
- Below 100 kW
- 100-500 kW
- Above 500 kW
By Fuel Source
- Natural Gas
- Diesel
- Biogas
- Hydrogen Blends
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the direct fired absorption chiller market is characterized by the presence of established HVAC and thermal energy solution providers competing on system efficiency, reliability, and lifecycle performance. Key players focus on high-capacity double-stage chillers tailored for industrial, district cooling, and large commercial applications, where long operating hours justify higher initial investment. Companies emphasize product differentiation through enhanced heat exchanger design, improved combustion efficiency, and advanced control systems that support stable operation and lower maintenance requirements. Strategic priorities include expanding service networks, strengthening aftermarket support, and offering customized solutions aligned with regional fuel availability. Market participants also invest in research and development to improve compatibility with alternative fuels such as biogas and hydrogen blends. Competitive intensity remains moderate, with long sales cycles and project-based procurement favoring experienced suppliers with proven installation track records and strong engineering capabilities.
Key Player Analysis
- Carrier
- Johnson Controls
- Trane
- Hitachi
- Panasonic
- LG
- BROAD Group
- Dalian Bingshan Engineering & Trading Co., Ltd.
- CONTINENTAL HOPE GROUP
- Simons Green Energy
Recent Developments
- In September 2025 ,Panasonic, in collaboration with Osaka Gas and Daigas Energy, announced the development of an industry-first absorption chiller capable of co-firing hydrogen and city gas. The newly developed unit supports a co-firing fuel ratio ranging from 0 to 100, enabling operation on pure hydrogen, pure city gas, or any blend of the two. The integrated hydrogen/city gas dual-use burner and combustion control unit suppress NOₓ emissions to below 40 ppm across the full combustion range, addressing key combustion and emissions challenges associated with hydrogen fuel use. Existing city gas–fueled absorption chiller units can be upgraded to this hydrogen-compatible configuration by replacing specific components such as the burner and fuel piping, facilitating flexible fuel strategy transitions.
- In October 2024, Johnson Controls-Hitachi Air Conditioning (JV) secured the Red Dot Award for Design Concept 2024 for its “airPure” system, indicating strategic innovation in HVAC control and UX design the same organizational focus enhancing broader systems including chillers.
Report Coverage
The research report offers an in-depth analysis based on Technology type, Cooling capacity, Fuel source and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Adoption of direct fired absorption chillers will increase in large commercial and industrial facilities seeking to reduce dependence on electricity-intensive cooling systems.
- Demand will remain strongest for high-capacity systems as district cooling and centralized infrastructure projects continue to expand.
- Double-stage technology will continue to dominate new installations due to superior thermal efficiency and operating performance.
- Integration with natural gas infrastructure will sustain market growth, particularly in regions with stable fuel supply.
- Use of alternative fuels such as biogas will gain momentum in industrial and municipal applications focused on energy recovery.
- Hydrogen blend compatibility will gradually emerge as a strategic differentiator for long-term decarbonization pathways.
- Manufacturers will focus on improving system efficiency, reliability, and lifecycle cost optimization.
- Digital monitoring and advanced control systems will become standard features to enhance operational performance.
- Retrofit and replacement of aging HVAC systems will create steady demand in mature markets.
- Growth will remain concentrated in Asia-Pacific, supported by urbanization, industrial expansion, and infrastructure development.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Direct fired absorption chiller, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Direct fired absorption chiller projected to grow between 2024 and 2032?
Which Direct fired absorption chiller segment held the largest share in 2024?
What are the primary factors fueling the growth of the Direct fired absorption chiller market?
Who are the leading companies in the Direct fired absorption chiller market?
Which region commanded the largest share of the Direct fired absorption chiller market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Direct Fired Absorption Chiller Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Direct Fired Absorption Chiller Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 1,323 million → 2032: USD 1,800.6 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Direct Fired Absorption Chiller Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Direct Fired Absorption Chiller Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Direct Fired Absorption Chiller Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Direct Fired Absorption Chiller Market Drivers
- 3.3 Direct Fired Absorption Chiller Market Restraints & Challenges
- 3.4 Direct Fired Absorption Chiller Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Direct Fired Absorption Chiller Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Direct Fired Absorption Chiller Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Direct Fired Absorption Chiller category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Direct Fired Absorption Chiller Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Direct Fired Absorption Chiller Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Direct Fired Absorption Chiller market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Direct Fired Absorption Chiller Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Direct Fired Absorption Chiller Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Direct Fired Absorption Chiller Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Direct Fired Absorption Chiller (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Direct Fired Absorption Chiller Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Direct Fired Absorption Chiller Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Direct Fired Absorption Chiller Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Direct Fired Absorption Chiller Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Direct Fired Absorption Chiller Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Direct Fired Absorption Chiller Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Direct Fired Absorption Chiller Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Direct Fired Absorption Chiller Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Direct Fired Absorption Chiller Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
