
Market Overview
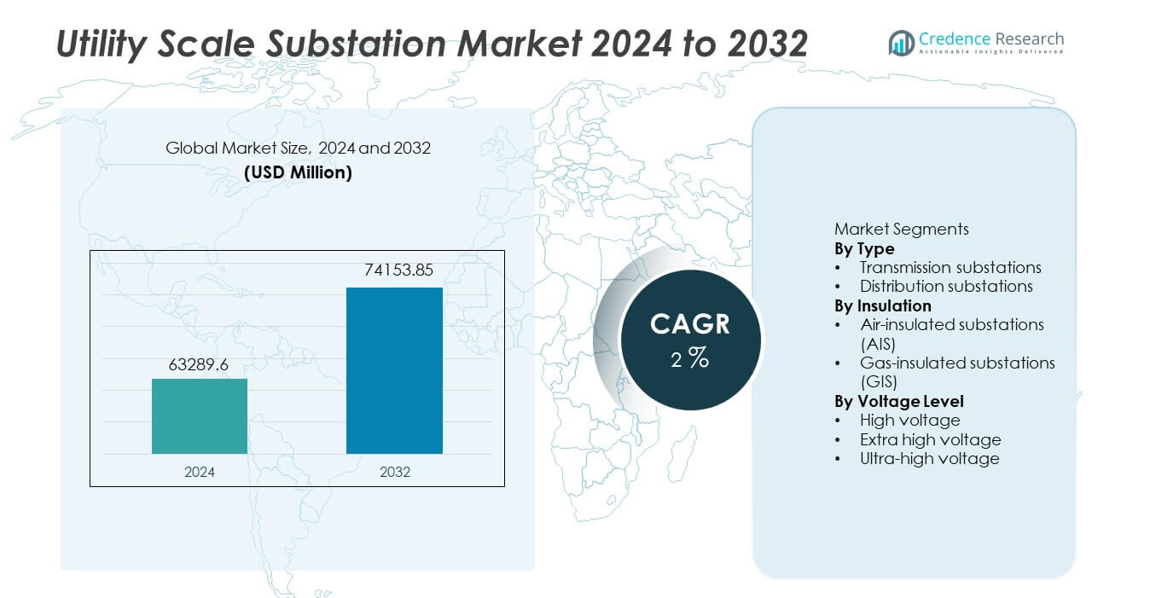
The Utility Scale Substation market was valued at USD 63,289.6 million in 2024 and is projected to reach USD 74,153.85 million by 2032, registering a CAGR of 2% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Utility Scale Substation Market Size 2024 | USD 63,289.6 million |
| Utility Scale Substation Market , CAGR | 2% |
| Utility Scale Substation Market Size 2032 | USD 74,153.85 million |
The Utility Scale Substation market features strong participation from Siemens Energy, ABB Ltd., Schneider Electric, General Electric, Hitachi Energy, Mitsubishi Electric Corporation, Eaton Corporation, Larsen & Toubro, Toshiba Energy Systems & Solutions, and Hyundai Electric & Energy Systems. These players compete through turnkey EPC capabilities, high-voltage engineering expertise, and advanced digital substation solutions. Asia Pacific leads the market with an exact share of 37.8%, supported by rapid transmission expansion, urbanization, and large renewable integration projects in China and India. North America follows with a 26.1% market share, driven by grid modernization, replacement of aging substations, and reliability investments. Europe holds a 24.4% share, supported by energy transition goals, cross-border interconnections, and adoption of gas-insulated substations. Competitive strength remains centered on reliability, automation, and large-scale project execution.
Market Insights
- The Utility Scale Substation market was valued at USD 63,289.6 million in 2024 and is projected to grow at a CAGR of 2% through the forecast period.
- Market growth is driven by transmission network expansion, renewable energy integration, urban electrification, and replacement of aging substation infrastructure across utility grids.
- Gas-insulated substations represent a segment share of 54.2% due to compact design, lower land requirements, and suitability for urban and high-density installations, while transmission substations dominate by type with a 61.7% share.
- Competitive activity remains strong, with global players focusing on digital substations, automation systems, and high-voltage reliability, while regional EPC firms compete through cost efficiency and localized execution.
- Asia Pacific leads the market with a 37.8% regional share, followed by North America at 26.1% and Europe at 24.4%, supported by grid modernization, renewable evacuation projects, and cross-border transmission development.
Market Segmentation Analysis:
By Type
The Utility Scale Substation market, by type, includes transmission substations and distribution substations, with transmission substations leading with a market share of 57.8%. Transmission substations play a critical role in stepping up or stepping down voltage for long-distance power transfer across regions. Utilities prioritize these substations to support grid expansion, interregional connectivity, and integration of large renewable energy projects. Rising electricity demand, cross-border power trading, and replacement of aging transmission infrastructure further drive demand. Distribution substations remain essential for local power delivery, but higher investment intensity and strategic importance position transmission substations as the dominant sub-segment.
- For instance, Siemens Energy deployed a 765 kV transmission substation in India supporting power transfer above 6,000 MW across regional grids.
By Insulation
Based on insulation, the market is segmented into air-insulated substations (AIS) and gas-insulated substations (GIS), with AIS accounting for a dominant share of 61.3%. Utilities widely deploy AIS due to lower capital costs, simpler design, and ease of maintenance in areas with sufficient land availability. AIS solutions remain preferred for large outdoor substations in rural and semi-urban regions. However, GIS adoption continues to rise in space-constrained urban environments. Ongoing grid expansion in developing regions and cost-sensitive projects continues to support the dominance of air-insulated substations.
- For instance, Hitachi Energy commissioned an air-insulated substation rated at 400 kV with short-circuit capacity exceeding 63 kA for a national grid expansion project. Gas-insulated substations gain traction in dense urban zones, but air-insulated systems remain widely adopted.
By Voltage Level
By voltage level, the market includes high voltage, extra high voltage, and ultra-high voltage substations, with extra high voltage substations holding the largest share at 48.6%. These substations support bulk power transmission across long distances with reduced losses. Utilities deploy extra high voltage infrastructure to connect large generation sources, including thermal, hydro, and renewable plants, to load centers. Growth in cross-regional transmission corridors and grid reinforcement projects strengthens demand. High voltage substations serve regional networks, while ultra-high voltage systems grow steadily with large-scale national grid projects.
Key Growth Drivers
Grid Modernization and Replacement of Aging Infrastructure
Utilities worldwide invest heavily in modernizing aging substation infrastructure. Many existing substations operate beyond designed lifespans and face reliability risks. Replacement and refurbishment projects drive sustained demand for utility scale substations. Modern substations improve operational efficiency, reduce outage risks, and support advanced grid control. Governments prioritize grid resilience to handle rising electricity demand and extreme weather events. Digital protection and automation upgrades further strengthen investment needs. This modernization focus remains a core driver for long-term market growth.
- For instance, ABB upgraded a national utility substation using Relion protection relays handling fault detection cycles below 20 milliseconds and supporting over 10,000 I/O signals within one control system.
Expansion of Transmission Networks and Power Interconnections
Rising electricity consumption and interregional power transfer requirements fuel transmission network expansion. Utilities build new substations to support long-distance and cross-border power flows. Integration of large generation assets requires robust substation infrastructure. Transmission corridors connecting renewable energy zones to load centers increase deployment. Power trading and grid interconnection projects strengthen demand. Substations play a central role in voltage control and system stability. This expansion trend strongly supports market growth.
- For instance, GE Vernova supplied substation equipment for a 500 kV transmission project designed to carry 3,000 MW and support fault clearing times below 40 milliseconds across interconnected grids.
Growth of Renewable Energy Integration
Large-scale renewable energy integration drives substation development. Wind, solar, and hydro projects require new grid connection points. Utility scale substations enable voltage transformation and grid synchronization. Variable generation increases demand for advanced protection and control systems. Utilities deploy substations to manage intermittency and maintain stability. Renewable energy targets accelerate infrastructure investment. This clean energy transition remains a key growth driver.
Key Trends and Opportunities
Rising Adoption of Gas-Insulated and Compact Substations
Utilities increasingly deploy gas-insulated substations in urban and space-constrained areas. GIS solutions reduce footprint while offering high reliability. Urbanization and land constraints accelerate adoption. Compact substations support underground and indoor installations. This trend creates opportunities for suppliers offering space-efficient designs. Growth in metropolitan grid upgrades supports continued demand. GIS adoption expands market opportunities.
- For instance, Mitsubishi Electric delivered a 300 kV gas-insulated substation featuring a compact bay design with busbar heights under 6.5 meters and rated continuous current capacity of 4,000 A, supporting high-density urban transmission networks.
Integration of Digital and Smart Substation Technologies
Digital substations gain traction across utility networks. Advanced sensors, communication systems, and automation improve monitoring and control. Utilities adopt digital substations to enhance reliability and reduce maintenance. Real-time data supports predictive maintenance and faster fault response. Smart grid initiatives drive adoption of digital solutions. Vendors offering integrated digital platforms gain competitive advantage. This trend opens new growth avenues.
- For instance, Schneider Electric implemented a digital substation using IEC 61850 process bus architecture, enabling protection response times below 10 milliseconds and integrating more than 5,000 real-time data points within a single control system.
Key Challenges
High Capital Investment and Long Project Timelines
Utility scale substations require significant upfront capital investment. Projects involve complex engineering and long approval cycles. Budget constraints delay execution in some regions. Land acquisition and regulatory clearances extend timelines. Utilities must balance cost with performance and reliability. Long project durations slow market turnover. Capital intensity remains a major challenge.
Complex Regulatory and Environmental Compliance
Substation projects face strict regulatory and environmental requirements. Compliance with safety, land use, and emission standards increases complexity. Permitting delays affect project schedules. GIS substations face scrutiny over gas handling and environmental impact. Utilities must address community and environmental concerns. Regulatory complexity increases development risk. This challenge affects deployment speed.
Regional Analysis
North America
North America holds a market share of 26.4% in the Utility Scale Substation market. Demand is driven by grid modernization and replacement of aging transmission and distribution infrastructure across the United States and Canada. Utilities invest in new substations to improve reliability, resilience, and outage management. Growth in renewable energy integration and cross-state power transfer increases substation upgrades. Expansion of data centers and electrification initiatives also support demand. Advanced automation and digital protection systems gain wider adoption. Stable regulatory frameworks and sustained utility spending support steady regional market growth.
Europe
Europe accounts for 23.8% of the global Utility Scale Substation market share. Strong focus on energy transition and decarbonization drives investments in transmission and distribution substations. Countries such as Germany, France, and the United Kingdom upgrade substations to support renewable integration and cross-border power flows. Aging infrastructure replacement remains a key driver. Urbanization increases adoption of compact and gas-insulated substations. Strict grid reliability and safety standards influence procurement. Ongoing interconnection projects and smart grid initiatives sustain regional market expansion.
Asia Pacific
Asia Pacific leads the market with a share of 34.7%. Rapid urbanization, industrial growth, and rising electricity demand drive large-scale substation deployment across China, India, Japan, and Southeast Asia. Governments invest heavily in transmission expansion and grid reinforcement. Integration of renewable energy and development of ultra-high-voltage corridors increase substation installations. Growing electrification and infrastructure development support sustained demand. Cost-effective construction and large project pipelines position Asia Pacific as the dominant and fastest-growing regional market.
Latin America
Latin America holds a market share of 8.1% in the Utility Scale Substation market. Growth is supported by grid expansion and renewable energy projects in Brazil, Mexico, and Chile. Utilities invest in substations to improve reliability and reduce transmission losses. Expansion of wind and solar capacity increases demand for new grid connection points. Budget constraints slow large-scale deployments, but ongoing infrastructure upgrades sustain moderate growth. Regulatory reforms and regional power integration projects support long-term market development.
Middle East & Africa
The Middle East & Africa region accounts for 7.0% of the global market share. Demand is driven by power infrastructure expansion in Gulf countries and electrification efforts across Africa. Large transmission projects and renewable energy developments increase substation installations. Utilities deploy substations to support industrial zones, urban growth, and grid stability. Harsh environmental conditions drive demand for robust and reliable designs. Long-term energy diversification plans and infrastructure investments support steady regional market progress.
Market Segmentations:
By Type
- Transmission substations
- Distribution substations
By Insulation
- Air-insulated substations (AIS)
- Gas-insulated substations (GIS)
By Voltage Level
- High voltage
- Extra high voltage
- Ultra-high voltage
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
Competitive landscape analysis highlights a capital-intensive and technology-driven market led by Siemens Energy, ABB Ltd., Schneider Electric, General Electric, Hitachi Energy, Mitsubishi Electric Corporation, Eaton Corporation, Larsen & Toubro, Toshiba Energy Systems & Solutions, and Hyundai Electric & Energy Systems. These players compete through turnkey EPC capabilities, advanced protection and control systems, and strong relationships with utilities and transmission operators. Leading companies focus on high-voltage and extra-high-voltage substations, digital automation, and reliability upgrades to support grid modernization. Investments in gas-insulated and compact substations address space constraints in urban areas. Global vendors leverage scale, engineering depth, and lifecycle services, while regional firms compete through localized manufacturing and cost efficiency. Strategic partnerships, long-term utility contracts, and participation in renewable integration and interconnection projects remain central to competitive positioning in the Utility Scale Substation market.
Key Player Analysis
- Siemens Energy
- ABB Ltd.
- Schneider Electric
- General Electric
- Hitachi Energy
- Mitsubishi Electric Corporation
- Eaton Corporation
- Larsen & Toubro
- Toshiba Energy Systems & Solutions
- Hyundai Electric & Energy Systems
Recent Developments
- In November 2024, Schneider Electric shared new “Virtual Substations” updates at Enlit 2024. Schneider also highlighted PowerLogic T300 RTU virtualization on the E4S platform.
- In May 2024, Siemens Energy announced a grid-expansion deal with Energinet. The scope covers high-voltage substation equipment for Denmark’s transmission upgrades.
- In April 2024, Hitachi Energy has secured an order from SP Energy Networks to design and implement an innovative power quality solution aimed at stabilizing the grid and enhancing the transmission of renewable energy from Scotland to England.
Report Coverage
The research report offers an in-depth analysis based on Type, Insulation, Voltage Level and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Grid modernization programs will continue to drive substation upgrades.
- Renewable energy integration will increase demand for new substations.
- Digital and automated substations will gain wider utility adoption.
- Gas-insulated substations will see higher deployment in urban areas.
- Transmission expansion will remain a key investment focus for utilities.
- Aging infrastructure replacement will support steady market demand.
- Asia Pacific will maintain leadership in new substation installations.
- Grid resilience and reliability investments will shape procurement priorities.
- EPC partnerships will play a critical role in large-scale projects.
- Competition will intensify through technology, service quality, and execution capability.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Utility Scale Substation market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Utility Scale Substation market projected to grow between 2024 and 2032?
Which Utility Scale Substation market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Utility Scale Substation market?
Who are the leading companies in the Utility Scale Substation market?
Which region commanded the largest share of the Utility Scale Substation market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Utility Scale Substation Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Utility Scale Substation Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 63,289.6 million → 2032: USD 74,153.85 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Utility Scale Substation Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Utility Scale Substation Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Utility Scale Substation Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Utility Scale Substation Market Drivers
- 3.3 Utility Scale Substation Market Restraints & Challenges
- 3.4 Utility Scale Substation Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Utility Scale Substation Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Utility Scale Substation Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Utility Scale Substation category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Utility Scale Substation Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Utility Scale Substation Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Utility Scale Substation market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Utility Scale Substation Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Utility Scale Substation Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Utility Scale Substation Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Utility Scale Substation (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Utility Scale Substation Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Utility Scale Substation Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Utility Scale Substation Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Utility Scale Substation Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Utility Scale Substation Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Utility Scale Substation Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Utility Scale Substation Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Utility Scale Substation Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Utility Scale Substation Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
