
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Walk-in Cooler and Freezer Market Size 2024 | USD 9520 Million |
| Walk-in Cooler and Freezer Market, CAGR | 5.9% |
| Walk-in Cooler and Freezer Market Size 2032 | USD 15059.29 Million |
Market Overview:
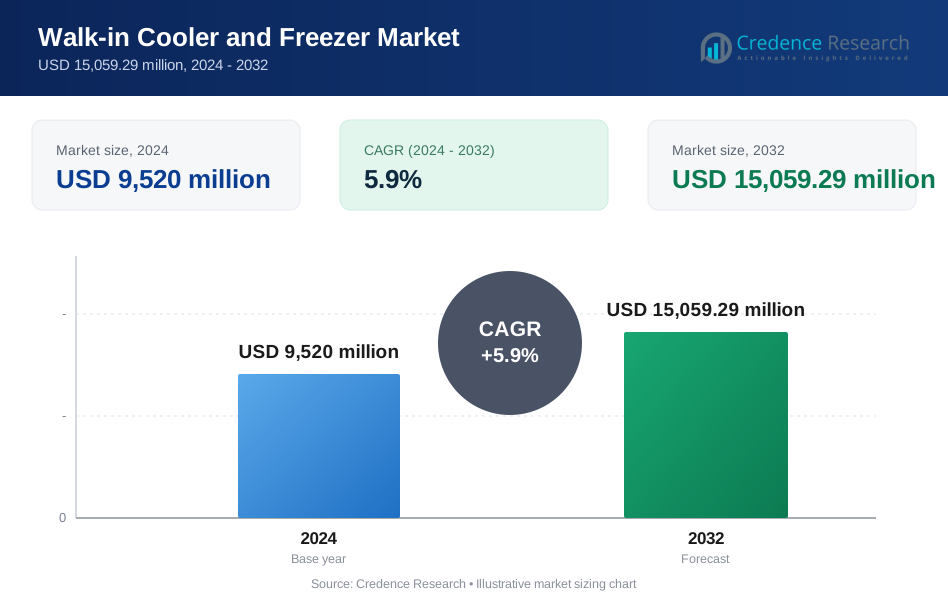
The Walk-in Cooler and Freezer Market is projected to grow from USD 9520 million in 2024 to an estimated USD 15059.29 million by 2032, with a compound annual growth rate (CAGR) of 5.9% from 2024 to 2032.
The expansion of the food and beverage industry and stringent food safety regulations are key drivers of the walk-in cooler and freezer market. Increasing consumer demand for frozen and perishable food items has necessitated the adoption of efficient cold storage solutions in supermarkets, convenience stores, and warehouses. In the pharmaceutical sector, the critical need for precise temperature control in the storage of vaccines, biologics, and temperature-sensitive drugs further fuels market demand. Additionally, advancements in cooling technologies, such as energy-efficient systems and IoT-enabled temperature monitoring, enhance the appeal and functionality of these solutions. The shift toward sustainability has driven the adoption of eco-friendly refrigerants and energy-saving designs, addressing environmental concerns and regulatory requirements. Urbanization, rising disposable incomes, and the proliferation of retail outlets globally further contribute to market growth, underlining the essential role of walk-in coolers and freezers in modern supply chains.
North America leads the global market, accounting for a substantial share due to its advanced retail infrastructure, adherence to strict food safety standards, and well-established cold chain logistics. The U.S. and Canada are major contributors, with strong demand from supermarkets, convenience stores, and the healthcare sector. Europe follows closely, driven by the adoption of cutting-edge technologies and a growing emphasis on sustainability. Countries like Germany, France, and the UK are pivotal markets within the region, fueled by stringent regulatory requirements in food and pharmaceuticals. The Asia-Pacific region is emerging as the fastest-growing market, bolstered by rapid urbanization, increased disposable incomes, and the expansion of quick-service restaurants and retail outlets in economies such as China, India, and Southeast Asia. Latin America and the Middle East & Africa are gradually gaining traction, supported by rising investments in cold storage infrastructure and increasing awareness of the benefits of temperature-controlled solutions. These regional dynamics reflect the diverse and evolving demands driving the walk-in cooler and freezer market globally.
Market Insights:
- The market is projected to grow from USD 9,520 million in 2024 to USD 15,059.29 million by 2032, registering a steady CAGR of 5.9%.
- The expansion of the food and beverage industry, coupled with stringent food safety regulations, is a key driver of market demand.
- Rising consumer preference for frozen and perishable food products necessitates the adoption of efficient cold storage solutions across retail and food service sectors.
- High initial investment costs and regulatory compliance challenges, particularly with eco-friendly refrigerants, act as significant market restraints.
- North America leads the market, supported by advanced retail infrastructure, strict quality standards, and robust cold chain logistics.
- The Asia-Pacific region is the fastest-growing market, fueled by urbanization, rising disposable incomes, and the proliferation of retail outlets in economies like China and India.
- Technological advancements in IoT-enabled temperature monitoring and energy-efficient designs enhance market appeal and sustainability efforts globally.
Market Drivers:
Rising Demand for Temperature-Controlled Storage Solutions
The growing demand for temperature-controlled storage across various industries is a primary driver for the walk-in cooler and freezer market. In the food and beverage sector, increasing consumption of frozen and perishable food products has necessitated reliable cold storage infrastructure. For instance, Kingspan's controlled environment solutions maintain optimal temperatures ranging from -40°F to 200°F, ensuring product integrity. Retailers, including supermarkets, convenience stores, and online grocery platforms, depend on walk-in coolers and freezers to maintain the quality and safety of their products. Similarly, restaurants and catering businesses require temperature-controlled units to store ingredients and prepared foods efficiently. This trend underscores the essential role of walk-in coolers and freezers in ensuring product integrity and meeting consumer expectations for freshness and safety.
Stringent Food Safety and Pharmaceutical Regulations
Regulatory frameworks focused on food safety and pharmaceutical storage are further accelerating the adoption of walk-in coolers and freezers. Compliance with global standards such as the FDA Food Code and Hazard Analysis Critical Control Point (HACCP) guidelines mandates the use of reliable cold storage systems. In the pharmaceutical industry, precise temperature control is critical for storing vaccines, biologics, and temperature-sensitive drugs. For example, Rinac's walk-in cold rooms maintain optimal temperatures of +2°C to +8°C for coolers and -18°C to -20°C for freezers, ensuring compliance with stringent storage requirements. As governments and health organizations emphasize cold chain infrastructure to meet healthcare needs, particularly in vaccine distribution, the demand for walk-in coolers and freezers continues to grow. These regulatory requirements ensure that businesses invest in high-quality storage solutions to avoid compliance violations and product losses.
Technological Advancements in Cooling Systems
Advancements in cooling technologies have significantly enhanced the functionality and efficiency of walk-in coolers and freezers. Innovations such as energy-efficient compressors, advanced insulation materials, and IoT-enabled temperature monitoring systems improve operational efficiency and reduce energy consumption. Smart cooling systems equipped with predictive maintenance and remote monitoring capabilities enable businesses to optimize performance while minimizing downtime. Additionally, the adoption of eco-friendly refrigerants aligns with global sustainability goals and addresses environmental concerns. These technological developments not only make walk-in coolers and freezers more efficient but also increase their appeal to environmentally conscious businesses.
Urbanization and Expansion of Retail Infrastructure
Rapid urbanization and the expansion of retail infrastructure worldwide are contributing to the increased adoption of walk-in coolers and freezers. The proliferation of supermarkets, hypermarkets, and quick-service restaurants in urban areas creates a steady demand for cold storage solutions. In developing regions, rising disposable incomes and shifting consumer preferences toward frozen and packaged foods further drive market growth. The e-commerce boom, particularly in grocery and food delivery services, has also amplified the need for temperature-controlled storage facilities to maintain product quality during transit and fulfillment. These trends highlight the growing reliance on walk-in coolers and freezers as essential components of modern supply chains.
Market Trends:
Adoption of Modular and Customizable Designs
The walk-in cooler and freezer market is witnessing a significant shift toward modular and customizable designs. Businesses increasingly prefer modular systems that allow for easy assembly, expansion, and reconfiguration to adapt to changing storage requirements. This trend is particularly prominent in industries such as retail and foodservice, where flexibility is critical to accommodate seasonal variations and inventory changes. Customization options, including temperature zones, shelving configurations, and size specifications, are gaining popularity as businesses seek tailored solutions to meet their unique operational needs. These advancements are enhancing user convenience while providing cost-effective scalability.
Increased Focus on Sustainability and Energy Efficiency
Sustainability has become a central focus in the walk-in cooler and freezer market, with businesses prioritizing energy-efficient and eco-friendly solutions. Manufacturers are adopting advanced insulation materials and high-efficiency compressors to minimize energy consumption while maintaining optimal cooling performance. For example, Kingspan's QuadCore® insulation technology offers up to 20% better thermal efficiency compared to traditional insulation materials. The use of natural and low-global-warming-potential (GWP) refrigerants is also on the rise, driven by stricter environmental regulations and growing corporate responsibility initiatives. Energy-efficient systems not only reduce operational costs but also align with sustainability goals, making them a preferred choice for businesses aiming to minimize their environmental impact.
Integration of Smart Technologies
The integration of smart technologies is transforming the walk-in cooler and freezer market, enabling businesses to achieve greater operational efficiency and control. IoT-enabled systems allow real-time monitoring of temperature, humidity, and energy usage, ensuring optimal storage conditions and reducing the risk of spoilage. For instance, Unity Cooling Systems Inc. integrates AI and IoT technologies in their walk-in freezers, allowing remote monitoring and adjustments to ensure product freshness. Predictive maintenance features powered by data analytics help prevent equipment failures by identifying potential issues before they occur, reducing downtime and maintenance costs. Remote management capabilities provide added convenience, particularly for multi-location operations, allowing users to monitor and control units from centralized platforms. These advancements reflect the growing demand for intelligent and automated solutions in cold storage.
Rising Demand in Emerging Markets
Emerging markets in regions such as Asia-Pacific, Latin America, and the Middle East & Africa are witnessing a surge in demand for walk-in coolers and freezers, driven by rapid urbanization and industrial growth. The expansion of retail infrastructure, including supermarkets and quick-service restaurants, is creating new opportunities in these regions. Additionally, improving cold chain logistics and rising investments in food storage infrastructure are supporting market growth. Governments and private sectors are also prioritizing cold storage solutions to enhance food security and reduce post-harvest losses, further boosting adoption. These trends indicate a strong growth trajectory for the walk-in cooler and freezer market in developing economies.
Market Challenges Analysis:
High Initial Investment and Operating Costs
The substantial initial investment required for installing walk-in coolers and freezers remains a significant restraint for the market. These systems involve considerable costs for procurement, installation, and customization, which can be prohibitive for small and medium-sized enterprises (SMEs). Additionally, the operational expenses, including energy consumption and maintenance, add to the overall cost of ownership. Businesses operating on tight budgets may find it challenging to justify these expenses, particularly in regions with high energy tariffs, limiting the adoption of such systems.
Environmental Concerns and Regulatory Compliance
The use of traditional refrigerants in cooling systems raises environmental concerns due to their high global warming potential (GWP) and ozone-depleting properties. Stricter regulations, such as those under the Kigali Amendment to the Montreal Protocol, mandate the phase-down of hydrofluorocarbons (HFCs), compelling manufacturers to transition to eco-friendly alternatives. While sustainable refrigerants are available, their adoption often involves higher costs and requires modifications to existing systems. These compliance pressures present challenges for both manufacturers and end-users, impacting market growth in cost-sensitive regions.
Space Constraints in Urban Areas
The increasing urbanization and shrinking commercial spaces pose challenges for installing walk-in coolers and freezers, particularly in densely populated areas. Businesses with limited floor space, such as small retail outlets and restaurants, struggle to accommodate these large systems without compromising operational efficiency. This constraint has driven demand for compact and modular solutions, but such systems often come with trade-offs in storage capacity and performance, limiting their utility in certain applications.
Technical and Maintenance Challenges
Walk-in coolers and freezers require regular maintenance to ensure optimal performance, including cleaning, refrigerant checks, and component replacements. Technical issues, such as refrigerant leaks or compressor failures, can lead to operational disruptions and product spoilage, resulting in significant financial losses. A lack of skilled technicians in certain regions exacerbates this issue, delaying repairs and increasing downtime. Addressing these challenges requires investments in training and support infrastructure, which can be a barrier for businesses in developing markets.
Market Opportunities:
The Walk-in Cooler and Freezer Market presents significant opportunities for growth, driven by the increasing global demand for temperature-controlled storage solutions across industries. The rising adoption of frozen and perishable food products, fueled by changing consumer preferences and expanding urbanization, underscores the need for efficient cold storage infrastructure. The food and beverage sector, along with quick-service restaurants and online grocery platforms, offers a lucrative market for manufacturers. Additionally, the pharmaceutical industry’s heightened focus on cold chain logistics, particularly for vaccines and biologics, creates substantial opportunities for innovation in precision temperature control. Emerging trends such as modular and energy-efficient designs further enhance the appeal of walk-in coolers and freezers, allowing businesses to meet both operational and sustainability goals.
Emerging economies in Asia-Pacific, Latin America, and the Middle East & Africa are poised to offer considerable growth potential due to rapid industrialization, improving cold chain infrastructure, and increasing disposable incomes. The expansion of supermarkets, hypermarkets, and food service chains in these regions drives the demand for walk-in coolers and freezers. Furthermore, advancements in smart technologies, such as IoT-enabled monitoring systems and predictive maintenance features, present opportunities for differentiation and value addition. By addressing key challenges such as high costs and environmental compliance, manufacturers can unlock untapped markets and position themselves for long-term success. The combination of growing demand and technological innovation ensures a positive outlook for the walk-in cooler and freezer market.
Market Segmentation Analysis:
The Walk-in Cooler and Freezer Market is segmented into various categories based on product type, place of use, technology, door type, application, sales channel, mounting type, and region, reflecting its diverse applications and adaptability to industry-specific requirements.
By Product Type, the market is categorized into walk-in coolers, walk-in freezers, and combo units (freezer + cooler). Combo units are gaining popularity due to their versatility in serving dual temperature needs, particularly in food retail and hospitality sectors.
By Place of Use, the market is segmented into indoor and outdoor units. Indoor units are widely used in commercial kitchens and laboratories, while outdoor units are preferred in industries requiring large-scale cold storage facilities.
By Technology, self-contained systems dominate smaller applications due to their ease of installation, while remote and multiplex condensing systems cater to larger, energy-efficient industrial operations.
By Door Type, hinged doors are the most common due to their cost-effectiveness, while power sliding and manual sliding doors are increasingly adopted for larger commercial setups and enhanced operational efficiency.
By Application, the market serves a broad range of industries, including cold storage warehouses, breweries, commercial kitchens, pharmaceuticals, floral storage, research laboratories, and retail food and beverages. Subcategories like supermarkets, hypermarkets, and convenience stores are key growth drivers.
By Sales Channel, the market is divided into OEMs and aftermarket, with OEMs leading due to increasing demand for new installations.
By Mounting Type, floor-mounted systems dominate, while non-floor-mounted systems cater to compact applications in smaller establishments.
Segmentation:
By Product Type:
- Walk-in Cooler
- Walk-in Freezer
- Combo (Freezer + Cooler)
By Place of Use:
- Indoor
- Outdoor
By Technology:
- Self-Contained
- Remote Condensing
- Multiplex Condensing
By Door Type:
- Hinged
- Power Sliding
- Manual Sliding
By Application:
- Cold Storage Warehouse
- Breweries
- Commercial Kitchen & Restaurants
- Floral Storage
- Pharmaceuticals
- Chemicals
- Research laboratories
- Hospitals & Mortuaries
- Mobile Refrigeration System
- Retail Food & Beverage
- Supermarket
- Hypermarket
- Convenience Stores
- Other Stores
By Sales Channel:
- OEM
- Aftermarket
By Mounting Type:
- Floor
- Non-floor
By Region:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
The Walk-in Cooler and Freezer Market demonstrates varying growth patterns across regions, influenced by industrialization, technological advancements, and economic development. North America leads the global market with a dominant share of approximately 35% in 2024, supported by a robust food and beverage industry, stringent food safety regulations, and advanced cold chain infrastructure. The United States is the largest contributor within this region, driven by high demand from supermarkets, convenience stores, and the pharmaceutical sector. Canada also plays a significant role, with strong adoption of energy-efficient cooling systems and IoT-enabled solutions.
Europe accounts for around 30% of the market, making it the second-largest region. The region's growth is fueled by increasing demand for frozen and packaged foods and a strong emphasis on sustainability. Countries like Germany, France, and the United Kingdom are at the forefront of the market, leveraging advanced manufacturing capabilities and adhering to strict environmental regulations. The adoption of natural refrigerants and energy-efficient cooling technologies is particularly prominent in this region, aligning with the European Union’s green initiatives.
The Asia-Pacific region is the fastest-growing market, holding a share of approximately 25%. Rapid urbanization, rising disposable incomes, and the expansion of supermarkets and quick-service restaurants drive growth in this region. China and India are key players, supported by growing investments in retail infrastructure and cold chain logistics. Japan and South Korea also contribute significantly, with their advanced technology adoption and emphasis on food safety. This region’s growth potential is further bolstered by the increasing need for cold storage solutions in the pharmaceutical sector, particularly for vaccine distribution.
Latin America and the Middle East & Africa collectively account for the remaining 10% of the market. Latin America’s growth is driven by expanding food retail chains and increasing awareness of cold storage benefits, with Brazil and Mexico leading the market. In the Middle East & Africa, growth is gradual but promising, supported by rising investments in food storage infrastructure and improving cold chain systems. These regions are also focusing on reducing food waste and enhancing food security, further driving the adoption of walk-in coolers and freezers.
Key Player Analysis:
- ABN Refrigeration Manufacturing (Ontario, Canada)
- Arctic Walk in Coolers & Walk-In Freezers (Miami, United States)
- Beverage Air (Winston-Salem, United States)
- Canadian Curtis Refrigeration Inc. (Vaughan, Canada)
- Danfoss A/S (Nordborg, Denmark)
- Emerson Electric Co. (St. Louis, United States)
- Everidge, Inc. (Plymouth, United States)
- Foster Refrigerator (Norfolk, United Kingdom)
- Hussmann Corporation (Bridgeton, United States)
- Imperial Brown Inc. (Gresham, United States)
- Intertek Group plc (London, United Kingdom)
- Kolpak (Parsons, United states)
- Master-Bilt Products, LLC. (Florida, United states)
- Nor-Lake, Inc. (Hudson, United States)
- Precision Refrigeration (Schuylerville, United States)
- SRC Refrigeration (Sterling Heights, United States)
- Standex International Corporation (Salem, United States)
- Stericox Sterilizer Systems India (Delhi, India)
- Viessmann (Allendorf, Germany)
Competitive Analysis:
The Walk-in Cooler and Freezer Market is highly competitive, with key players focusing on innovation, customization, and sustainability to maintain their market positions. Prominent companies such as Carrier, Daikin, Danfoss, and Hussmann dominate the market, leveraging advanced technologies and robust distribution networks to serve a broad customer base. These players invest heavily in research and development to offer energy-efficient and IoT-enabled cooling solutions, addressing the growing demand for operational efficiency and sustainability. Regional and local manufacturers contribute to the competitive landscape by providing cost-effective and tailored solutions, particularly in emerging markets. Strategic partnerships, mergers, and acquisitions are common, enabling companies to expand their product portfolios and geographic reach. The increasing emphasis on eco-friendly refrigerants and modular systems has further intensified competition, as players strive to align with environmental regulations and market trends. This dynamic environment ensures continuous innovation and growth opportunities within the market.
Recent Developments:
- In February 2024, Kinzie Capital Partners bolstered its position in the cold storage industry by acquiring Arctic Industries, a leading manufacturer of walk-in coolers, freezers, and cold storage panels. This acquisition is aimed at enhancing manufacturing capabilities and broadening market reach within the commercial refrigeration sector.
- In February 2024, Panasonic Europe expanded its CO2 refrigeration portfolio with the launch of a robust 20HP outdoor condensing unit. This new addition complements its existing 2HP, 4HP, and 10HP systems, catering to the stringent cooling demands of supermarkets and industrial process applications.
- In July 2024, Panasonic's Cold Chain Solutions Company further strengthened its European footprint by acquiring Area Cooling Solutions, a Polish manufacturer specializing in CO2 condensing units. This strategic acquisition highlights Panasonic's dedication to advancing sustainable cooling technologies and expanding its reach across the European market.
Market Concentration & Characteristics:
The Walk-in Cooler and Freezer Market exhibits a moderately fragmented structure, characterized by the presence of both global leaders and regional players. Established companies such as Carrier, Daikin, and Hussmann dominate the market due to their extensive product portfolios, strong brand recognition, and technological advancements. These players hold a significant share of the market, driven by their ability to cater to large-scale industries and multinational customers. Regional and local manufacturers contribute to the competitive landscape by offering customized and cost-effective solutions, particularly in emerging economies where affordability and adaptability are key considerations. The market is defined by rapid innovation, with companies focusing on energy efficiency, IoT-enabled systems, and sustainable refrigerants to meet evolving consumer demands and regulatory requirements. This dynamic interplay of global and regional players, along with continuous advancements in technology, shapes the competitive characteristics of the walk-in cooler and freezer market.
Report Coverage:
The research report offers an in-depth analysis based on By Product Type, By Place of Use, By Technology, By Door Type, By Application, By Sales Channel, By Mounting Type and By Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The market is projected to grow steadily, driven by increasing demand from the food and beverage and pharmaceutical sectors.
- Technological advancements in IoT and energy-efficient systems will transform operational efficiency and monitoring capabilities.
- Adoption of eco-friendly refrigerants will rise, driven by stricter environmental regulations and sustainability goals.
- Modular and customizable designs will gain traction, offering scalability and adaptability for various applications.
- Emerging markets in Asia-Pacific, Latin America, and Africa will present significant growth opportunities due to urbanization and retail expansion.
- The rise of e-commerce and online grocery platforms will increase demand for cold storage infrastructure.
- Investments in cold chain logistics will enhance market growth, particularly in pharmaceutical and vaccine storage.
- Compact and space-saving solutions will address urban space constraints and expand the market’s reach.
- Integration of predictive maintenance technology will reduce downtime and operational costs for businesses.
- Strategic partnerships and mergers will accelerate innovation and geographic expansion in the competitive landscape.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected growth of the walk-in cooler and freezer market?
What drives the demand for walk-in coolers and freezers?
Which region leads the global market?
What are the main challenges in the market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Walk-in Cooler and Freezer Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Walk-in Cooler and Freezer Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 9,520 million → 2032: USD 15,059.29 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Walk-in Cooler and Freezer Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Walk-in Cooler and Freezer Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Walk-in Cooler and Freezer Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Walk-in Cooler and Freezer Market Drivers
- 3.3 Walk-in Cooler and Freezer Market Restraints & Challenges
- 3.4 Walk-in Cooler and Freezer Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Walk-in Cooler and Freezer Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Walk-in Cooler and Freezer Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Walk-in Cooler and Freezer category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Walk-in Cooler and Freezer Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Walk-in Cooler and Freezer Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Walk-in Cooler and Freezer market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Walk-in Cooler and Freezer Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Walk-in Cooler and Freezer Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Walk-in Cooler and Freezer Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Walk-in Cooler and Freezer (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Walk-in Cooler and Freezer Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Walk-in Cooler and Freezer Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Walk-in Cooler and Freezer Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Walk-in Cooler and Freezer Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Walk-in Cooler and Freezer Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Walk-in Cooler and Freezer Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Walk-in Cooler and Freezer Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Walk-in Cooler and Freezer Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Walk-in Cooler and Freezer Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
