
Market Overview:
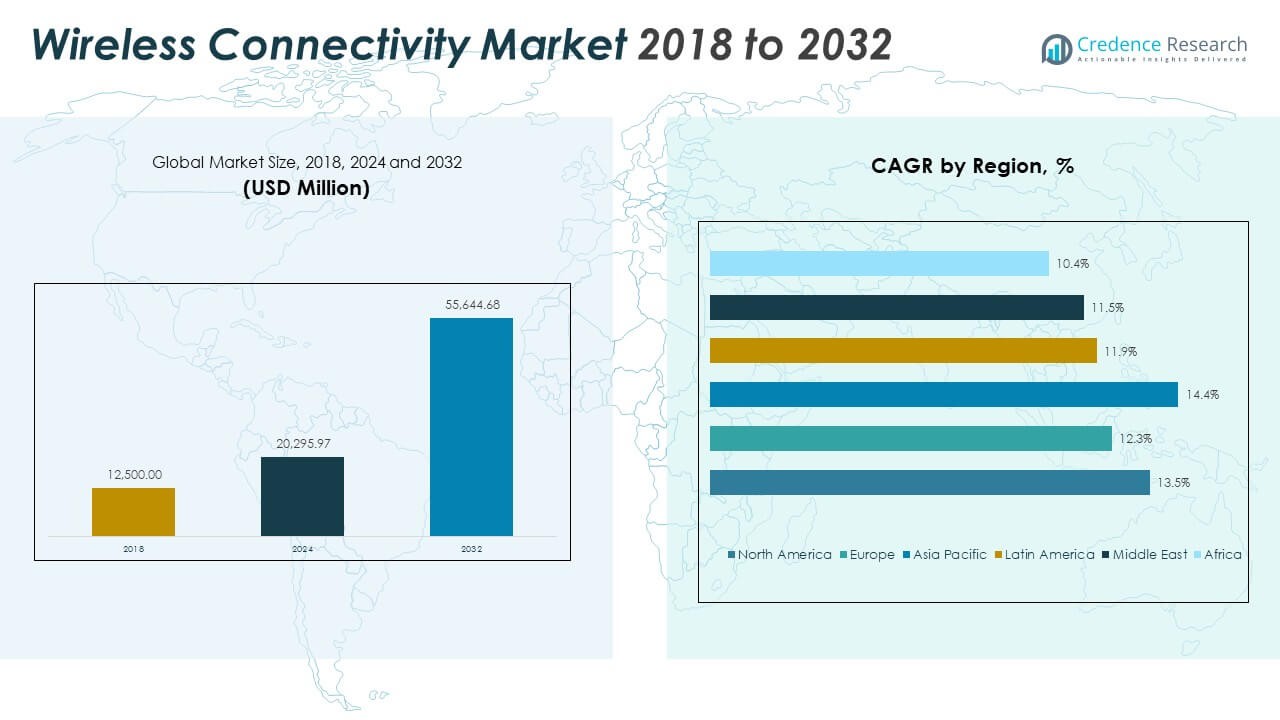
The Global Wireless Connectivity Market size was valued at USD 12,500.00 million in 2018 to USD 20,295.97 million in 2024 and is anticipated to reach USD 55,644.68 million by 2032, at a CAGR of 13.52% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Wireless Connectivity Market Size 2024 | USD 20,295.97 Million |
| Wireless Connectivity Market, CAGR | 13.52% |
| Wireless Connectivity Market Size 2032 | USD 55,644.68 Million |
The market growth is driven by the rising demand for smart devices, IoT solutions, and real-time data communication. Increasing adoption of wireless technologies such as Wi-Fi, Bluetooth, and Zigbee across industries including consumer electronics, healthcare, automotive, and manufacturing is fueling demand. Expanding deployment of 5G networks and growing need for reliable, low-latency connectivity solutions further strengthen market expansion.
North America leads the market due to early 5G adoption and strong IoT infrastructure. Asia-Pacific is an emerging region, driven by rising industrial automation and smart city initiatives in China, Japan, South Korea, and India. Europe shows steady growth, supported by advanced industrial connectivity and government-led digital transformation projects.
Market Insights:
- The Global Wireless Connectivity Market was valued at USD 12,500.00 million in 2018, grew to USD 20,295.97 million in 2024, and is projected to reach USD 55,644.68 million by 2032, expanding at a CAGR of 13.52%.
- Asia Pacific (37%), North America (32%), and Europe (17%) dominate due to early 5G adoption, industrial automation, and high IoT integration. These regions benefit from strong manufacturing bases and extensive digital infrastructure.
- Asia Pacific remains the fastest-growing region, supported by rapid smart city deployment, expanding telecom networks, and large-scale consumer electronics production.
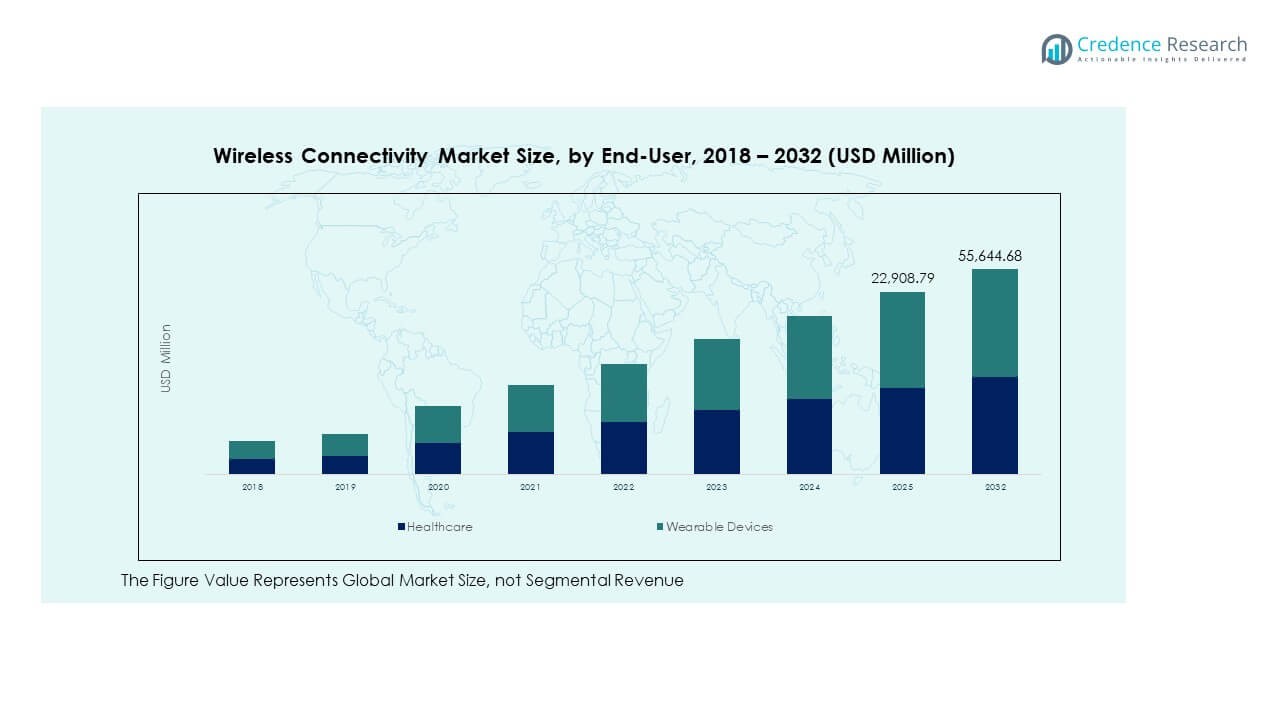
- Among end users, Healthcare accounts for about 40% share, driven by connected medical devices, remote monitoring, and telehealth solutions.
- Wearable Devices represent nearly 60% share, supported by rising fitness tracking demand, personal health awareness, and integration with smart ecosystems.
Market Drivers:
Rising Demand for IoT Devices and Smart Connectivity Solutions
The Global Wireless Connectivity Market is expanding due to the growing adoption of Internet of Things (IoT) devices across homes, industries, and cities. Smart homes, wearables, and connected vehicles are driving the need for seamless wireless communication. Rapid urbanization and digital transformation have led to the deployment of connected infrastructure. It benefits from the integration of Wi-Fi, Bluetooth, and Zigbee technologies to enable device interoperability. Industrial automation and real-time monitoring are boosting wireless technology investments. Increasing affordability of connected devices encourages adoption among small enterprises. Expanding government support for IoT development enhances market penetration. The demand for intelligent ecosystems continues to shape wireless technology evolution.
- For instance, Cisco’s IoT Control Center platform manages connectivity for over 250 million IoT devices across 32,000 enterprises, supporting real-time management and automation on mass scale deployments in 2025.
Expanding 5G Infrastructure and Low-Latency Network Demand
Deployment of 5G networks is accelerating growth in the Global Wireless Connectivity Market by enabling faster data transfer and reduced latency. Telecom operators are investing in network upgrades to support connected devices and applications. It supports industrial robotics, autonomous vehicles, and healthcare monitoring systems requiring uninterrupted communication. The expansion of 5G spectrum availability enhances efficiency across industrial and commercial environments. Enterprises adopt advanced wireless modules to meet performance standards of ultra-reliable networks. The increasing preference for edge computing strengthens the need for dependable wireless infrastructure. Governments worldwide are emphasizing digital connectivity initiatives. Continuous investments in 5G technology fuel long-term adoption and innovation.
- For instance, Ericsson and AT&T’s multi-billion-dollar partnership drove a 96% increase in 5G network traffic volume in 2024 and achieved up to 20% annual power efficiency gains at upgraded sites through open radio and cloud technologies, as verified by official statements and industry reports.
Growing Integration Across Consumer Electronics and Smart Devices
Consumer electronics remain a major contributor to the Global Wireless Connectivity Market due to widespread use of smartphones, tablets, and laptops. Manufacturers integrate wireless chipsets to improve user experience and device synchronization. It allows faster data transfer and supports smart assistants, streaming, and gaming platforms. Growth in wireless audio devices such as earbuds and smart speakers reinforces connectivity innovation. Cloud computing and data-sharing capabilities further increase dependency on wireless solutions. The surge in remote work and online education has elevated network reliability demands. Companies are prioritizing efficient power consumption and improved transmission range. These factors collectively elevate consumer engagement and product demand.
Adoption of Industrial Automation and Machine-to-Machine Communication
Industrial sectors are adopting machine-to-machine (M2M) communication to optimize operations and enhance productivity. The Global Wireless Connectivity Market benefits from the growing focus on predictive maintenance, real-time data exchange, and safety monitoring. Wireless protocols like Wi-Fi 6 and LoRaWAN are transforming smart manufacturing facilities. It facilitates energy-efficient data collection from remote equipment and sensors. Businesses in logistics and utilities rely on wireless solutions for improved tracking and operational control. Rising digitalization in oil and gas, agriculture, and construction further supports deployment. Investments in private industrial networks are expanding across developed and emerging economies. Continuous evolution in industrial IoT frameworks drives consistent growth in this segment.
Market Trends:
Emergence of Wi-Fi 6 and Wi-Fi 7 Standards Enhancing Network Efficiency
The Global Wireless Connectivity Market is witnessing a strong transition toward next-generation Wi-Fi technologies. Wi-Fi 6 and Wi-Fi 7 offer higher throughput, improved reliability, and efficient bandwidth utilization. It supports dense network environments such as airports, stadiums, and enterprises with multiple connected devices. The adoption of these standards is strengthening seamless communication across industries. Device manufacturers are integrating updated chipsets to support advanced connectivity protocols. Enterprises are upgrading infrastructure to ensure compatibility with new Wi-Fi generations. Growth in smart city and retail applications fuels deployment of high-speed networks. The continuous evolution of Wi-Fi standards remains a key trend shaping global wireless infrastructure.
- For instance, real-world tests using Cisco Catalyst 9800 series controllers demonstrated Wi-Fi 7 providing 47% higher throughput than Wi-Fi 6 with average measured rates reaching 747 Mbps; multi-link operation (MLO) ensured more efficient spectrum use and significantly improved latency at large-scale enterprise test sites.
Increasing Role of AI and Edge Computing in Wireless Networks
Integration of artificial intelligence and edge computing is transforming the operational landscape of the Global Wireless Connectivity Market. It enables faster data processing near the source, minimizing network congestion and latency. AI-driven analytics enhance real-time decision-making for smart factories, vehicles, and healthcare systems. The shift toward distributed computing is strengthening wireless network intelligence. Companies are developing AI-powered routers and IoT gateways to optimize data transmission. Edge solutions are crucial for applications requiring minimal delay and high security. Industries are increasingly leveraging hybrid connectivity frameworks. This trend promotes efficiency and scalability across network infrastructures.
- For instance, NVIDIA Jetson Thor, launched in August 2025, delivers up to 2,070 FP4 teraflops of AI compute and 128GB of memory, achieving 7.5x greater AI compute capacity and 3.5x higher energy efficiency versus its predecessor, and attracting global industry leaders such as Amazon Robotics and Medtronic for advanced robotics and healthcare deployments.
Rising Adoption of LPWAN Technologies for Wide-Area IoT Applications
Low-Power Wide-Area Network (LPWAN) technologies are gaining traction in the Global Wireless Connectivity Market. They support long-range communication while consuming minimal energy, ideal for IoT and industrial sensors. It is widely used in agriculture, smart metering, and asset tracking. LPWAN enables cost-effective connectivity for devices transmitting small data packets over large distances. Enterprises are deploying LPWAN networks to extend connectivity in rural and remote areas. Governments are supporting LPWAN-based initiatives to promote sustainable smart city development. Network operators are enhancing spectrum availability for IoT growth. The steady integration of LPWAN is broadening accessibility and connectivity in multiple sectors.
Growth of Connected Vehicle Ecosystems and V2X Communication
Connected vehicle technology is a major emerging trend within the Global Wireless Connectivity Market. It supports Vehicle-to-Everything (V2X) communication that improves road safety, traffic management, and autonomous driving. Automakers are integrating advanced wireless modules to connect cars with infrastructure and networks. It enables over-the-air updates and predictive diagnostics through high-speed data exchange. Governments are investing in smart transportation systems to enhance urban mobility. Advancements in cellular and satellite communication are driving vehicle connectivity improvements. The trend is fostering collaborations between telecom and automotive industries. Increasing focus on connected mobility continues to transform wireless communication standards.
Market Challenges:
High Infrastructure Costs and Spectrum Limitations Restricting Adoption
The Global Wireless Connectivity Market faces barriers due to high infrastructure development costs and limited spectrum availability. Network operators require large investments to deploy 5G and other wireless systems at scale. It impacts small enterprises and developing regions that lack capital-intensive capabilities. Spectrum congestion in urban areas leads to reduced transmission efficiency and interference issues. Managing multiple frequency bands for different wireless standards adds complexity. Governments are working to reallocate and auction new frequencies, yet regulatory delays hinder expansion. The cost of upgrading legacy systems further restricts rapid modernization. Balancing coverage, cost, and performance remains a major industry challenge.
Cybersecurity Risks and Data Privacy Concerns Impacting User Confidence
Rising cybersecurity threats pose significant risks to the Global Wireless Connectivity Market. Increased device interconnectivity raises exposure to unauthorized access and data breaches. It pressures companies to strengthen encryption and authentication protocols. Lack of uniform global security standards complicates interoperability. Businesses must continuously update firmware and adopt AI-based monitoring to mitigate risks. Data privacy concerns among consumers can limit trust in connected devices. Regulatory compliance across different regions adds further operational burden. Building secure wireless ecosystems is critical to sustaining user confidence and long-term adoption.
Market Opportunities:
Expansion of Smart Infrastructure and Connected Ecosystems
The Global Wireless Connectivity Market holds vast potential through the expansion of smart cities and connected infrastructure projects. Governments are investing in intelligent transportation, energy management, and surveillance systems. It creates opportunities for network providers and equipment manufacturers to deliver innovative connectivity solutions. Integration of IoT and cloud systems is driving efficiency in public and private sectors. Emerging markets are adopting digital infrastructure to support population growth and urban development. Partnerships between telecom companies and technology providers strengthen deployment capabilities. The move toward sustainable and connected environments continues to unlock commercial potential worldwide.
Advancements in Healthcare and Industrial Connectivity Applications
Wireless technologies are creating new opportunities in healthcare and industrial automation. The Global Wireless Connectivity Market benefits from increasing use of remote patient monitoring, robotic surgery, and smart manufacturing. It supports real-time communication between devices, improving efficiency and reliability. Industries are deploying private wireless networks to enhance safety and operational performance. Healthcare providers are embracing connected wearables and diagnostic systems for continuous monitoring. Expansion of Industry 4.0 initiatives boosts demand for seamless machine communication. These advancements open new pathways for innovation and revenue generation across multiple industries.
Market Segmentation Analysis:
By Type
The Global Wireless Connectivity Market is segmented into WLAN, WPAN, Satellite, LPWAN, and Cellular M2M wireless connectivity. WLAN dominates due to its broad use in enterprise networks, homes, and public infrastructure. WPAN, led by Bluetooth and Zigbee, is vital for personal devices and IoT ecosystems. Satellite wireless connectivity supports remote communication and critical operations in defense, logistics, and maritime sectors. LPWAN enables low-power, long-range connections ideal for smart metering and industrial IoT. Cellular M2M connectivity is expanding in automotive and manufacturing sectors, supporting real-time monitoring and automation. Each type serves distinct connectivity needs, shaping the market’s diverse growth base.
- For instance, Semtech’s LoRa technology, verified at IoT Solutions World Congress and supported by Omdia research in February 2025, powers over 410 million end nodes globally and accounts for more than 30% of all LPWAN connections across industrial and smart metering sectors.
By End User
The market serves healthcare, wearable devices, transportation and automotive, consumer electronics, building automation, and other end users. Healthcare uses wireless solutions for patient monitoring and telehealth integration. Wearable devices rely on Bluetooth and low-energy protocols for health tracking and connectivity. Transportation and automotive sectors adopt wireless systems for vehicle communication, diagnostics, and infotainment. Consumer electronics remain the largest user base, driven by smartphones, laptops, and smart appliances. Building automation applies wireless networks to control lighting, HVAC, and security systems efficiently. It supports digital transformation across industries through scalable and seamless connectivity solutions.
- For instance, Philips launched its next-generation Telemetry Monitor 5500 platform in September 2025, streamlining alarm management and wireless patient monitoring for hospital networks, enabling clinicians to track patient data enterprise-wide and reducing alarm burden across thousands of deployed devices in cardiac care.
Segmentation:
By Type
- WLAN Wireless Connectivity
- WPAN Wireless Connectivity
- Satellite Wireless Connectivity
- LPWAN Wireless Connectivity
- Cellular M2M Wireless Connectivity
By End User
- Healthcare
- Wearable Devices
- Transportation and Automotive
- Consumer Electronics
- Building Automation
- Other End Users
By Region
- North America
- S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Southeast Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East
- GCC Countries
- Israel
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Egypt
- Rest of Africa
Regional Analysis:
North America
The North America Global Wireless Connectivity Market size was valued at USD 4,062.50 million in 2018 to USD 6,506.76 million in 2024 and is anticipated to reach USD 17,811.96 million by 2032, at a CAGR of 13.5% during the forecast period. North America holds around 32% of the total market share. The region leads due to strong adoption of advanced communication technologies and early deployment of 5G networks. The presence of major technology firms in the U.S. drives innovation and infrastructure expansion. It benefits from growing IoT integration across smart homes, healthcare, and automotive sectors. Enterprises are investing heavily in network modernization and edge computing. Canada and the U.S. are advancing public safety networks and connected city initiatives. Government policies encouraging spectrum allocation and broadband expansion enhance market penetration. Consistent R&D efforts and early commercialization sustain North America’s leadership in wireless innovation.
Europe
The Europe Global Wireless Connectivity Market size was valued at USD 2,300.00 million in 2018 to USD 3,526.88 million in 2024 and is anticipated to reach USD 8,889.39 million by 2032, at a CAGR of 12.3% during the forecast period. Europe accounts for around 17% of the global share. The market benefits from strong industrial automation, digital transformation, and connected mobility programs. Germany, France, and the UK are leading adopters of IoT-driven manufacturing systems. It supports 5G infrastructure deployment to enhance energy, logistics, and public sector communication. European Union policies promoting data security and spectrum standardization aid growth. Smart city development projects are expanding wireless applications in transportation and energy management. The automotive sector’s focus on V2X communication strengthens adoption further. Technological collaborations and cross-border R&D initiatives drive innovation across the region.
Asia Pacific
The Asia Pacific Global Wireless Connectivity Market size was valued at USD 5,065.00 million in 2018 to USD 8,444.05 million in 2024 and is anticipated to reach USD 24,622.82 million by 2032, at a CAGR of 14.4% during the forecast period. Asia Pacific dominates with nearly 37% of the global market share. Rapid digitalization and expanding manufacturing bases in China, Japan, South Korea, and India are key drivers. It experiences strong demand for connected devices and industrial IoT platforms. Governments are promoting smart city initiatives and 5G rollout at scale. Rising disposable income supports consumer electronics growth and wearable adoption. Local semiconductor production and telecom investments enhance supply stability. The region is witnessing increasing collaborations between telecom and IT firms to strengthen connectivity. Urban infrastructure modernization continues to create major business opportunities across sectors.
Latin America
The Latin America Global Wireless Connectivity Market size was valued at USD 512.50 million in 2018 to USD 819.75 million in 2024 and is anticipated to reach USD 1,995.97 million by 2032, at a CAGR of 11.9% during the forecast period. Latin America represents about 5% of the total market share. The market is growing steadily, supported by expanding mobile broadband usage and digital transformation initiatives. Brazil and Mexico are key countries driving demand through large-scale telecommunication projects. It benefits from increased investments in network modernization and IoT applications. The consumer electronics segment is growing rapidly with higher smartphone and wearable adoption. Governments are focusing on bridging connectivity gaps in rural regions. Regional operators are collaborating with international players to deploy cost-effective 4G and 5G networks. Improving regulatory frameworks and digital inclusion programs strengthen the region’s connectivity ecosystem.
Middle East
The Middle East Global Wireless Connectivity Market size was valued at USD 350.00 million in 2018 to USD 519.44 million in 2024 and is anticipated to reach USD 1,230.05 million by 2032, at a CAGR of 11.5% during the forecast period. The Middle East contributes roughly 4% of the global market share. Strong investments in smart infrastructure, IoT, and automation drive market expansion. GCC countries lead adoption through smart city development and 5G implementation. It benefits from digital transformation across oil, gas, and logistics sectors. Governments are supporting data-driven operations to improve efficiency and sustainability. Telecommunications operators are investing in next-generation wireless technologies. Saudi Arabia and the UAE are prioritizing diversification through digital connectivity projects. Strategic partnerships between public and private sectors are accelerating technological advancement in the region.
Africa
The Africa Global Wireless Connectivity Market size was valued at USD 210.00 million in 2018 to USD 479.07 million in 2024 and is anticipated to reach USD 1,094.49 million by 2032, at a CAGR of 10.4% during the forecast period. Africa holds about 3% of the overall market share. The market is gradually developing with growing demand for mobile connectivity and digital services. Expansion of telecom infrastructure in Nigeria, South Africa, and Egypt is fueling growth. It is driven by affordable smartphones and low-cost data plans. Governments are investing in rural broadband and ICT inclusion programs. The rise of fintech and e-commerce platforms increases data traffic and connectivity needs. Satellite and LPWAN networks are extending coverage to remote areas. The region’s improving digital readiness presents long-term growth prospects for wireless technologies.
Key Player Analysis:
- Intel Corporation
- Texas Instruments Incorporated
- Qualcomm Incorporated
- Broadcom Inc.
- STMicroelectronics N.V.
- NXP Semiconductors N.V.
- Microchip Technology Inc.
- MediaTek Inc.
- Cypress Semiconductor Corporation
- Renesas Electronics Corporation
Competitive Analysis:
The Global Wireless Connectivity Market features intense competition with major semiconductor and connectivity firms leading innovation and growth. Companies are intensifying efforts to expand product portfolios, support new wireless standards like Wi-Fi 7 and 5G, and enhance IoT connectivity services. It requires sustained investment in research and development to maintain competitive advantage and respond to shifting technology trends. Firms that build strong partnerships across ecosystems, including device makers, cloud providers and telecom operators, gain strategic edge. Market players that offer differentiated solutions in LPWAN, satellite connectivity and private networks enjoy elevated market positioning. It drives mergers and acquisitions to scale capabilities and geographic presence. Widespread adoption of smart infrastructure and industrial IoT raises entry barriers for smaller vendors. Firms that deliver secure, flexible and scalable wireless modules establish long-term value in the competitive setting.
Recent Developments:
- In September 2025, Intel announced a landmark multi-generational partnership with NVIDIA to jointly develop custom data center and personal computing CPUs utilizing NVIDIA's NVLink technology. The collaboration aims to accelerate workloads in hyperscale, enterprise, and consumer markets, integrating NVIDIA’s accelerated computing stack with Intel’s CPU technologies. Notably, NVIDIA is investing $5 billion in Intel common stock, highlighting their long-term alliance for next-generation wireless and AI infrastructure solutions.
- Texas Instruments remains prominent in wireless connectivity. While there is no record of a major launch from October 2025, TI recently expanded its portfolio with Wi-Fi and Bluetooth modules for industrial and consumer IoT, offering mission-critical solutions for energy-efficient wireless connectivity competing directly in the IoT market against industry peers like Semtech and Silicon Labs.
Report Coverage:
The research report offers an in-depth analysis based on Type and End User segments. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Expansion of 5G private networks for enterprises and industrial sites
- Growth in LPWAN deployment for IoT in utilities, agriculture and logistics
- Increased satellite-based connectivity for remote regions and mobility
- Rising demand for Wi-Fi 7 and beyond in dense device environments
- Integration of edge computing with wireless modules for real-time responsiveness
- Growing adoption of connected vehicles and V2X communications
- Scaling of secure wireless ecosystems for healthcare, wearables and automation
- Deployment of modular, low-power wireless devices enabling new use cases
- Strategic consolidation among component vendors and connectivity platform providers
- Enhanced focus on sustainability and energy-efficient wireless connectivity solutions

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Proliferation of IoT Devices and Smart Connectivity
The rapid adoption of IoT devices in homes, industries, and cities is fueling demand for seamless wireless connectivity. Integration of technologies like Wi-Fi, Bluetooth, and Zigbee enables interoperability and supports the expansion of smart homes, wearables, and connected infrastructure.
Expansion of 5G Networks and Low-Latency Requirements
Accelerated deployment of 5G infrastructure is enabling faster data transfer and ultra-reliable, low-latency communication, which is critical for industrial automation, autonomous vehicles, and healthcare monitoring. This drives investments in advanced wireless modules and network upgrades.
Growth in Consumer Electronics and Wearable Devices
The widespread use of smartphones, tablets, laptops, and wearables is a major contributor to wireless connectivity market growth. Manufacturers are integrating advanced wireless chipsets to enhance user experience, device synchronization, and support for smart assistants and streaming.
Industrial Automation and Machine-to-Machine Communication
Industries are increasingly adopting wireless protocols such as Wi-Fi 6 and LPWAN for real-time monitoring, predictive maintenance, and operational efficiency. This trend is particularly strong in manufacturing, logistics, and utilities, driving demand for robust wireless solutions.
Smart City Initiatives and Digital Transformation
Government-led smart city projects and digital transformation initiatives are expanding the deployment of wireless networks in transportation, energy management, and public safety. These efforts create new opportunities for network providers and technology vendors to deliver innovative connectivity solutions.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Global Wireless Connectivity Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Global Wireless Connectivity Market projected to grow between 2025 and 2032?
Which Global Wireless Connectivity Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Global Wireless Connectivity Market?
Who are the leading companies in the Global Wireless Connectivity Market?
Which region commanded the largest share of the Global Wireless Connectivity Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 WLAN Wireless Connectivity
- 1.2.2 WPAN Wireless Connectivity
- 1.2.3 Satellite Wireless Connectivity
- 1.2.4 LPWAN Wireless Connectivity
- 1.2.5 Cellular M2M Wireless Connectivity
- 1.3 By End User
- 1.3.1 Healthcare
- 1.3.2 Wearable Devices
- 1.3.3 Transportation and Automotive
- 1.3.4 Consumer Electronics
- 1.3.5 Building Automation
- 1.3.6 Other End Users
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 20,295.97 million → 2032: USD 55,644.68 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Wireless Connectivity Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Wireless Connectivity Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Wireless Connectivity Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Wireless Connectivity Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Wireless Connectivity Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Wireless Connectivity Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Data Protection, AI and Cybersecurity Compliance
- 9.8 Upcoming Policy Changes and Market Implications
Chapter 10 Global Wireless Connectivity Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Wireless Connectivity Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 20,295.97 million → 2032: USD 55,644.68 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Wireless Connectivity Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 WLAN Wireless Connectivity
- 12.3.7.2 WPAN Wireless Connectivity
- 12.3.7.3 Satellite Wireless Connectivity
- 12.3.7.4 LPWAN Wireless Connectivity
- 12.3.7.5 Cellular M2M Wireless Connectivity
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By End User - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Healthcare
- 12.4.7.2 Wearable Devices
- 12.4.7.3 Transportation and Automotive
- 12.4.7.4 Consumer Electronics
- 12.4.7.5 Building Automation
- 12.4.7.6 Other End Users
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 Global Wireless Connectivity End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Wireless Connectivity Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Wireless Connectivity Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Wireless Connectivity Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Intel Corporation
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Texas Instruments Incorporated
- 18.4 Qualcomm Incorporated
- 18.5 Broadcom Inc.
- 18.6 STMicroelectronics N.V.
- 18.7 NXP Semiconductors N.V.
- 18.8 Microchip Technology Inc.
- 18.9 MediaTek Inc.
- 18.10 Cypress Semiconductor Corporation
- 18.11 Renesas Electronics Corporation
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

