
Market Overview
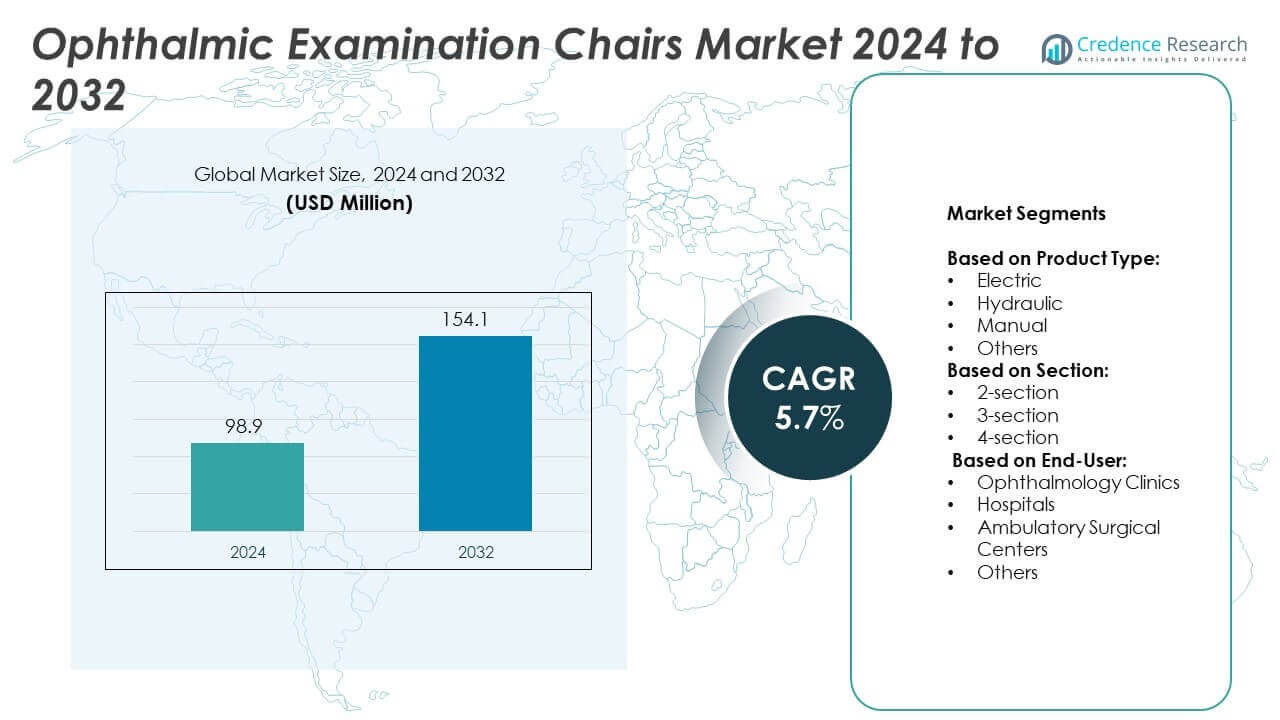
The Ophthalmic Examination Chairs Market was valued at USD 98.9 million in 2024 and is expected to reach USD 154.1 million by 2032, growing at a CAGR of 5.7% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Ophthalmic Examination Chairs Market Size 2024 | USD 98.9 Million |
| Ophthalmic Examination Chairs Market , CAGR | 5.7% |
| Ophthalmic Examination Chairs Market Size 2032 | USD 154.1 Million |
The Ophthalmic Examination Chairs market is driven by increasing eye disorder prevalence, aging populations, and advancements in healthcare infrastructure. Technological innovations, such as electric and multi-functional chairs, improve both patient comfort and procedural efficiency. The demand for ergonomic designs and enhanced customization features is growing, especially in clinics and hospitals. As awareness of eye health rises globally, the market is poised for continued expansion, with emerging markets contributing to significant growth.
The Ophthalmic Examination Chairs market is expanding across key regions, with North America leading due to its advanced healthcare infrastructure and high demand. Europe follows closely, supported by a growing elderly population. Asia Pacific is experiencing rapid growth due to improving healthcare systems and increasing awareness. Key players driving innovation and market growth include Topcon Corporation, Haag-Streit USA, Coburn Technologies, and Lemi MD, offering advanced and ergonomic solutions tailored to evolving healthcare needs.
Market Insights
- The Ophthalmic Examination Chairs market was valued at USD 98.9 million in 2024 and is expected to reach USD 154.1 million by 2032, growing at a CAGR of 5.7% from 2025 to 2032.
- Increasing prevalence of eye disorders and an aging population are major drivers for the market's growth, leading to a higher demand for advanced eye care equipment.
- Technological advancements in electric and multi-functional chairs, along with rising demand for ergonomic designs, are major trends boosting market expansion.
- The market is highly competitive, with key players such as Topcon Corporation, Haag-Streit USA, Coburn Technologies, and Lemi MD leading the innovation in product offerings.
- Market restraints include the high initial investment and maintenance costs of advanced ophthalmic chairs, which could limit adoption in smaller clinics.
- North America holds the largest market share, followed by Europe, both of which benefit from strong healthcare infrastructure and a high focus on eye health.
- The Asia Pacific region is growing rapidly, driven by improving healthcare systems, government initiatives, and rising awareness of eye care in developing economies.
Market Drivers
Rising Prevalence of Eye Diseases and Disorders
The increasing incidence of eye diseases worldwide is a major driver for the Ophthalmic Examination Chairs market. Conditions such as age-related macular degeneration, diabetic retinopathy, and cataracts have seen a rise, especially in aging populations. Early detection and regular eye examinations are critical for managing these conditions, increasing the demand for specialized ophthalmic examination chairs. Hospitals and ophthalmology clinics are investing in advanced examination setups to cater to this growing need, driving market expansion.
- For instance, Topcon Corporation offers the OC-2400 chair with automated adjustment features, which enhances patient comfort and provides precise positioning, addressing the growing need for accurate diagnostics in cataract and diabetic retinopathy treatments.
Technological Advancements in Ophthalmic Examination Equipment
Continuous technological innovation in ophthalmic equipment plays a significant role in the Ophthalmic Examination Chairs market growth. The integration of automation, digital imaging, and ergonomic designs enhances the overall efficiency and comfort of examinations. These innovations improve diagnostic accuracy, making examination chairs with advanced features highly sought after. The demand for chairs that can seamlessly integrate with modern ophthalmic technologies is expected to continue rising.
- For instance, Coburn Technologies, Inc. offers the S4OPTIK 1800-CB chair, which features a pneumatically assisted pivot tilting mechanism with a one-handed release/control mechanism, allowing simple patient positioning up to a 40-degree recline.
Growing Adoption of Eye Care Services
There has been a global increase in the adoption of preventive healthcare services, especially eye care. More people are seeking regular eye checkups due to growing awareness about eye health. The Ophthalmic Examination Chairs market benefits from this trend as healthcare facilities invest in high-quality examination chairs to meet the rising patient volume. The shift toward preventive care in eye health leads to more frequent use of ophthalmic examination chairs in various settings.
Increasing Focus on Patient Comfort and Ergonomics
Patient comfort is becoming a top priority in healthcare settings, directly influencing the Ophthalmic Examination Chairs market. Manufacturers are focusing on designing chairs that offer adjustable features, improved ergonomics, and easy positioning for both patients and healthcare providers. The emphasis on patient experience and comfort, combined with the need for precise examination positioning, accelerates the adoption of specialized ophthalmic chairs in medical practices.
Market Trends
Integration of Advanced Technologies in Ophthalmic Examination Chairs
The integration of advanced technologies is one of the key trends shaping the Ophthalmic Examination Chairs market. Features such as electronic height adjustments, memory positioning, and automated functions are becoming increasingly common in ophthalmic chairs. These innovations enhance the efficiency of eye exams and ensure greater precision for healthcare professionals. The demand for these high-tech chairs is driven by the growing need for both comfort and accuracy during complex procedures, making them essential in modern ophthalmology practices.
- For instance, Haag-Streit USA introduced the FX-920 exam chair, which includes memory positions for consistent patient setup and integrated foot control for ease of use, enabling healthcare professionals to focus more on diagnostics while ensuring high accuracy in procedures.
Shift Towards Patient-Centric Design and Comfort
Patient comfort is a central focus for manufacturers in the Ophthalmic Examination Chairs market. Designs are evolving to prioritize ergonomics and ease of use, with features that enhance the overall patient experience during exams. This trend aligns with the broader shift in healthcare toward improving patient satisfaction and reducing discomfort. Adjustable headrests, backrests, and leg supports are now standard in many examination chairs, ensuring patients remain relaxed throughout the process.
- For instance, Mid Central Medical developed the MCM-5010 Contour Vertex Stretcher Chair. This specialized chair is designed to provide accurate head positioning and clear access for eye, ENT, and dental surgery. It features automated height adjustment, a lie-flat position, and forward/reverse tilt capabilities. The chair has a height range of 18–33 inches, a 660 lb weight capacity, and is powered by a long-life battery.
Increase in Adoption of Electric Examination Chairs
Electric ophthalmic examination chairs are gaining preference over manual models due to their enhanced functionality and ease of use. These chairs provide precise adjustments at the push of a button, reducing the physical strain on both the patient and the healthcare provider. The growing demand for electric models is driven by the need for more efficient, accurate, and customizable examination settings, particularly in busy healthcare environments where time and accuracy are crucial.
Rising Demand for Multi-Functional Ophthalmic Chairs
There is a growing trend toward multi-functional ophthalmic chairs designed to cater to a wide range of diagnostic and treatment needs. These chairs can be adapted for various procedures, from routine eye exams to more complex surgeries, improving their versatility. Healthcare providers are increasingly adopting these multi-purpose chairs to optimize space and equipment costs, as they offer flexibility and greater utility in different ophthalmic applications.
Market Challenges Analysis
High Initial Investment and Maintenance Costs
One of the key challenges in the Ophthalmic Examination Chairs market is the high initial cost associated with advanced models. These chairs are often equipped with sophisticated features, such as electric adjustments and integrated imaging systems, which come with a premium price tag. Many small or mid-sized healthcare facilities face difficulty justifying the investment due to budget constraints. Along with the purchase price, ongoing maintenance and servicing costs further add to the financial burden, making it challenging for smaller practices to adopt these technologies.
Space and Compatibility Limitations in Healthcare Settings
Another challenge is the space constraints within healthcare facilities, which can limit the adoption of advanced ophthalmic chairs. Many clinics or hospitals have limited space for additional equipment, making it difficult to accommodate larger or more feature-rich models. Furthermore, integrating new examination chairs with existing diagnostic equipment can sometimes present compatibility issues, requiring additional investment in supporting infrastructure. These challenges hinder the ability of some healthcare providers to fully leverage the benefits of modern ophthalmic examination chairs.
Market Opportunities
Growth in Preventive Eye Care Services
The increasing emphasis on preventive healthcare presents significant opportunities in the Ophthalmic Examination Chairs market. With rising awareness about eye health and the growing prevalence of eye-related disorders, more individuals are seeking regular eye examinations. This trend is driving demand for modern, efficient ophthalmic examination chairs in clinics and hospitals. Healthcare providers are focusing on upgrading their facilities to accommodate the growing patient volume, creating a market for advanced chairs that offer comfort and precision during eye exams. As preventive care becomes a priority, the need for specialized examination equipment will continue to rise.
Technological Advancements and Customization Options
Advancements in technology offer new opportunities for growth in the Ophthalmic Examination Chairs market. The introduction of smart chairs with built-in diagnostic tools and automated functions is likely to become more prevalent. Customization options, such as adjustable features and ergonomic designs, are also increasingly in demand, especially in specialized ophthalmic practices. These advancements cater to both the needs of healthcare professionals and patient comfort, encouraging adoption in a variety of settings. As innovation continues to shape the market, there will be growing opportunities for manufacturers to provide tailored solutions for different types of eye care facilities.
Market Segmentation Analysis:
By Product Type:
The Ophthalmic Examination Chairs market is segmented by product type into electric, hydraulic, manual, and others. Electric chairs hold the largest share due to their convenience and precision in adjustments. These chairs offer automated positioning, improving operational efficiency and patient comfort. Hydraulic chairs are also widely used due to their cost-effectiveness and ease of use. They are popular in smaller practices where budget constraints are a factor. Manual chairs, while less advanced, remain in demand for their simplicity and lower cost. "Others" category includes unique designs and configurations tailored to specific needs in specialized ophthalmic practices.
- For instance, Takagi Ophthalmic Instruments Europe Limited offers the UN-15 hydraulic chair, which is known for its reliable, smooth operation provided by a fail-safe sealed hydraulic system. According to Takagi's specifications, the seat can be adjusted in height from 555 mm to 805 mm (or approximately 21.9 to 31.7 inches). Manual chairs, while less advanced and lacking the powered assist, remain a popular option for clinics that prioritize a simpler design and lower initial cost.
By Section:
Ophthalmic examination chairs are also segmented based on section into 2-section, 3-section, and 4-section types. The 2-section chairs are most commonly used in general practice settings. These chairs offer basic functionality, making them cost-effective and space-efficient. 3-section chairs provide more flexibility in positioning, offering enhanced comfort during longer procedures. They are ideal for practices requiring more specialized examinations. The 4-section chairs, often found in high-end or specialized ophthalmology centers, offer maximum adjustability and comfort for both patients and healthcare providers. They are preferred in settings where prolonged use and precise adjustments are essential.
- For instance, AKRUS GmbH & Co. KG produces high-end patient chairs and mobile surgical beds with extensive positioning flexibility for specialized treatments in ophthalmology and other fields. The SC 5010 surgical chair features an infinitely adjustable backrest, various adjustable headrests, and often includes removable sections to support any patient position. AKRUS chairs are engineered for prolonged use and offer precise adjustments, making them a preferred choice in demanding clinical settings.
By End-User:
The Ophthalmic Examination Chairs market is further segmented based on end-users into ophthalmology clinics, hospitals, ambulatory surgical centers, and others. Ophthalmology clinics dominate the market due to the growing demand for specialized eye care services. Hospitals follow closely, driven by the high volume of patients requiring eye exams as part of routine checkups or pre-surgical evaluations. Ambulatory surgical centers (ASCs) represent a growing segment as more eye surgeries are performed in outpatient settings. The "others" category includes various healthcare facilities such as private practices, diagnostic centers, and mobile clinics. These segments are witnessing increased demand as the healthcare sector expands and adapts to changing patient needs.
Segments:
Based on Product Type:
- Electric
- Hydraulic
- Manual
- Others
Based on Section:
- 2-section
- 3-section
- 4-section
Based on End-User:
- Ophthalmology Clinics
- Hospitals
- Ambulatory Surgical Centers
- Others
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis
North America
North America dominates the ophthalmic examination chairs market with a substantial share of 44.5% in 2024. The region's strong healthcare infrastructure, high prevalence of eye disorders, and ongoing investments in advanced medical technologies contribute to its leading position. In particular, the United States has a high number of ophthalmology clinics and hospitals, which drives demand for specialized ophthalmic examination chairs. As the population ages, the need for regular eye exams and early detection of conditions such as cataracts and macular degeneration continues to rise. The increasing awareness of eye health, combined with advancements in diagnostic equipment and procedures, supports the region's market growth. With such a significant healthcare investment, North America is expected to maintain its dominant position for the foreseeable future.
Europe
Europe holds a significant share of the ophthalmic examination chairs market, accounting for 32% in 2024. The region benefits from a robust healthcare system, technological advancements, and a large, aging population, particularly in countries like Germany, the UK, and France. The increasing prevalence of age-related vision impairments such as macular degeneration and cataracts further fuels demand for specialized ophthalmic equipment. European countries are investing heavily in modernizing their healthcare facilities to improve access to eye care services. Additionally, favorable reimbursement policies and the growing adoption of cutting-edge diagnostic tools contribute to the growth of the market. The emphasis on preventive care and eye health is likely to continue driving demand for ophthalmic examination chairs in the region.
Asia Pacific
The Asia Pacific region is experiencing rapid growth in the ophthalmic examination chairs market, with a projected share of 28.4% by 2030. The rise in eye-related disorders, fueled by aging populations and urbanization in countries like China and India, is a major factor in this growth. Many Asia Pacific countries are improving their healthcare infrastructure to meet the increasing demand for eye care services. Governments are implementing initiatives to expand access to eye care, such as funding for eye health programs and expanding ophthalmology services in rural areas. With a growing middle class and increasing healthcare expenditure, the region is poised for significant market expansion, with more patients seeking early detection and treatment for eye conditions. As healthcare systems continue to improve, the demand for advanced diagnostic tools, including ophthalmic examination chairs, is expected to rise.
Latin America
Latin America accounts for 8.5% of the ophthalmic examination chairs market in 2024, with Brazil and Mexico being the largest contributors. The region is witnessing increased investments in healthcare, with a growing focus on ophthalmic care. As more people in Latin America become aware of the importance of regular eye exams and treatments, the demand for specialized equipment is expected to grow. However, economic disparities between countries and limited access to advanced medical technologies pose challenges to faster adoption in some areas. The region's diverse healthcare systems also present varying levels of access to advanced ophthalmic equipment, affecting the speed at which new technologies are integrated into practices. Despite these challenges, healthcare reforms and growing investment in the medical sector are expected to drive continued growth in the coming years.
Middle East & Africa
The Middle East & Africa region represents a modest share of 6.5% in the ophthalmic examination chairs market. While the Gulf Cooperation Council (GCC) countries, such as Saudi Arabia, the UAE, and Qatar, are leading the way in adopting advanced healthcare technologies, the rest of the region faces significant challenges. In particular, Sub-Saharan Africa struggles with limited healthcare infrastructure and lower healthcare spending, which hinders widespread access to advanced ophthalmic equipment. However, the GCC countries are investing heavily in modernizing their healthcare systems and expanding access to eye care services, resulting in steady growth in demand for ophthalmic examination chairs. As healthcare infrastructure continues to improve and economic growth accelerates in the region, there will be more opportunities for market expansion in the Middle East & Africa.
Key Player Analysis
- Haag-Streit USA
- Lemi MD (Brusaferri & C. srl.)
- Takagi Ophthalmic Instruments Europe Limited
- AKRUS GmbH & Co. KG
- Topcon Corporation
- Coburn Technologies, Inc. (SDC Technologies, Inc.)
- Mid Central Medical
- Vermund Larsen A/S
- bon Optic Vertriebsges.mbH
- BTC SRL
Competitive Analysis
The ophthalmic examination chairs market is characterized by a competitive landscape featuring several key players. Topcon Corporation, Coburn Technologies, Inc. (SDC Technologies, Inc.), Haag-Streit USA, Takagi Ophthalmic Instruments Europe Limited, Mid Central Medical, AKRUS GmbH & Co. KG, Lemi MD (Brusaferri & C. srl.), bon Optic Vertriebsges.mbH, BTC SRL, and Vermund Larsen A/S are prominent companies in this sector. The market is characterized by a diverse range of products catering to various healthcare settings. Electric ophthalmic examination chairs are gaining popularity due to their ease of use and precise adjustments, making them suitable for modern ophthalmology practices. Manual chairs continue to be prevalent in smaller clinics and practices, offering affordability and simplicity. Hydraulic and pneumatic chairs are also utilized, providing a balance between cost and functionality. The ophthalmic examination chairs market is poised for continued growth, fueled by technological innovations, an aging population, and expanding healthcare access worldwide. Stakeholders in the industry are focusing on developing advanced, ergonomic, and cost-effective solutions to meet the evolving needs of eye care professionals and patients.
Recent Developments
- In 2024, Lemi MD (Brusaferri & C. srl.) introduced the DreaMed examination chair in March 2024, featuring electric adjustment, intuitive controls, and ergonomic design to reduce operator fatigue.
- In 2023, Topcon Corporation introduced the OC-2400 ophthalmic chair, featuring motorized tilt, illuminated controls, and FlashPort technology, enhancing functionality and patient comfort.
- In June 2023, Haag-Streit USA, a company involved in the manufacturing of ophthalmic diagnostic devices has announced the launch of the Reliance 6200 examination chair. This product launch is aimed at providing the optometrist with a broader choice, enabling efficient operation from both sides of the chair, and making it easy to access from any position among others.
Report Coverage
The research report offers an in-depth analysis based on Product Type, Section, End-User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The demand for ophthalmic examination chairs will continue to grow due to the increasing prevalence of eye disorders globally.
- Aging populations in developed countries will drive the need for regular eye exams and specialized examination equipment.
- Technological advancements in ophthalmic equipment will lead to more automated and precise examination chairs with enhanced features.
- Rising healthcare investments in emerging markets will increase the adoption of modern ophthalmic examination chairs.
- The integration of ergonomic designs to enhance patient comfort and improve healthcare efficiency will be a key trend.
- Healthcare facilities will increasingly adopt electric and multi-functional ophthalmic chairs for greater flexibility and ease of use.
- Demand for portable and compact ophthalmic examination chairs will grow, especially in mobile clinics and rural settings.
- Governments and healthcare providers will invest in upgrading infrastructure to meet the growing demand for ophthalmic services.
- The shift towards preventive eye care and early detection will result in higher adoption of advanced examination chairs in clinics and hospitals.
- The Middle East and Asia Pacific regions will see the fastest growth due to expanding healthcare access and rising disposable incomes.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Ophthalmic Examination Chairs market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Ophthalmic Examination Chairs Market projected to grow between 2025 and 2032?
Which Ophthalmic Examination Chairs market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Ophthalmic Examination Chairs market?
Who are the leading companies in the Ophthalmic Examination Chairs Market?
Which region commanded the largest share of the Ophthalmic Examination Chairs market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue) (Volume Where Applicable)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Ophthalmic Examination Chairs Scope – Segments & Subsegments Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 Industry Classification & Applicable Codes
- 1.5 Currency, Measurement Units & Valuation Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Ophthalmic Examination Chairs Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 98.9 million → 2032: USD 154.1 million)
- 2.1.2 Volume & Revenue – Global Totals (Volume Where Applicable)
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Ophthalmic Examination Chairs Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024 (Volume Where Applicable)
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Ophthalmic Examination Chairs Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Ophthalmic Examination Chairs Market Position in the Broader Industry Value Chain
- 3.1.2 Demand Structure & Purchasing Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Ophthalmic Examination Chairs Market Drivers
- 3.3 Ophthalmic Examination Chairs Market Restraints & Challenges
- 3.4 Ophthalmic Examination Chairs Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Ophthalmic Examination Chairs Value Chain Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.6.1.1 Key Input/Resource 1
- 3.6.1.2 Key Input/Resource 2
- 3.6.1.3 Key Input/Resource 3
- 3.6.2 Midstream – Core Operations & Value Creation
- 3.6.2.1 Operating Model & Process Overview
- 3.6.2.2 Key Operating Locations & Capabilities by Company
- 3.6.3 Downstream – Market Channels & End Users
- 3.6.3.1 Direct Sales & Customer Engagement Channels
- 3.6.3.2 Indirect Sales, Intermediaries & Partner Channels
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Ophthalmic Examination Chairs Supply Chain Analysis
- 3.8.1 Critical Input & Resource Availability Risk Assessment
- 3.8.2 Supplier & Operational Concentration Risk (Geographic Exposure)
- 3.8.3 Supply & Service Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Ophthalmic Examination Chairs category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Ophthalmic Examination Chairs Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Market Size × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute Revenue Growth Through 2032
- 4.3 Incremental Demand Opportunity
- 4.3.1 By Region – Incremental Demand Through 2032
- 4.3.2 Segment – Incremental Demand
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Priority Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Priority market opportunity scorecards reflect the geographic scope and strategic relevance of the study. Listed markets are indicative and may be adapted to the industry.
Chapter 5. Ophthalmic Examination Chairs Cross-Border Trade & Market Access Analysis
- 5.1 International Trade & Cross-Border Activity Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024) (Volume Where Applicable)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024) (Volume Where Applicable)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Category 1 (Applicable Classification Code)
- 5.2.2 Category 2 (Applicable Classification Code)
- 5.2.3 Category 3 (Applicable Classification Code)
- 5.2.4 Category 4 (Applicable Classification Code)
- 5.2.5 Category 5 (Applicable Classification Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Category 1 (Applicable Classification Code)
- 5.3.2 Category 2 (Applicable Classification Code)
- 5.3.3 Category 3 (Applicable Classification Code)
- 5.3.4 Category 4 (Applicable Classification Code)
- 5.3.5 Category 5 (Applicable Classification Code)
- 5.4 Cross-Border Pricing & Transaction Benchmarks
- 5.4.1 Export Pricing – Segment & Country
- 5.4.2 Import Pricing – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Cross-Border Trade & Delivery Routes
- 5.5.1 Cross-Border Trade/Delivery Route 1
- 5.5.2 Cross-Border Trade/Delivery Route 2
- 5.5.3 Cross-Border Trade/Delivery Route 3
- 5.5.4 Cross-Border Trade/Delivery Route 4
- 5.5.5 Cross-Border Trade/Delivery Route 5
- 5.6 Trade Policy & Market Access Impact Assessment
- 5.6.1 Tariff & Non-Tariff Barriers
- 5.6.2 Regional Trade & Economic Integration Frameworks
- 5.6.3 Bilateral & Multilateral Trade Agreements
- 5.6.4 Cross-Border Operating, Licensing & Localization Requirements
Note: This chapter applies where cross-border trade or delivery is relevant to Ophthalmic Examination Chairs. Goods, services, and digital offerings are assessed using applicable classifications and transaction measures. Import-export volumes, trade balances, and route analyses are included only where meaningful to the market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Ophthalmic Examination Chairs Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – the historical period vs. 2024
- 6.1.2 Leading, Mid-Sized & Emerging Player Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Ophthalmic Examination Chairs Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company (Volume Where Applicable)
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution (the historical period vs. 2024)
- 6.2.5 Company Market Share by Key Segment
- 6.2.6 Company Market Share by Customer Group
- 6.3 Operating Scale, Capacity & Infrastructure Analysis
- 6.3.1 Global Operating Scale & Supply Capacity
- 6.3.2 Resource Utilization & Operating Efficiency
- 6.3.3 Output, Service Delivery & Activity Metrics
- 6.3.4 Operating Footprint & Infrastructure Map
- 6.3.5 Planned Operational & Capacity Expansion
- 6.4 Ophthalmic Examination Chairs Competitive Benchmarking Matrix
- 6.4.1 Revenue, Growth, Profitability & Operating Metric Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Ophthalmic Examination Chairs (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Products, Services & Solutions in Ophthalmic Examination Chairs
- 6.5.3 Operational & Infrastructure Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Ophthalmic Examination Chairs Market – By Sales & Delivery Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032) (Volume Where Applicable)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share (Volume Where Applicable)
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region (Volume Where Applicable)
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Sales & Delivery Channel
- 8.2.2 By Competitive Positioning & Price Tier
Chapter 9. North America Ophthalmic Examination Chairs Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Ophthalmic Examination Chairs Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Ophthalmic Examination Chairs Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Ophthalmic Examination Chairs Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Ophthalmic Examination Chairs Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Ophthalmic Examination Chairs Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Ophthalmic Examination Chairs Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Supply, Output & Operating Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Demand, Adoption & Usage Assumptions
- Appendix F – Pricing & Revenue Metric Reference Tables
- Appendix G – Company Operations & Infrastructure Database
- Appendix H – Cross-Border Trade & Activity Data Tables (Where Applicable)
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
