
Market Overview:
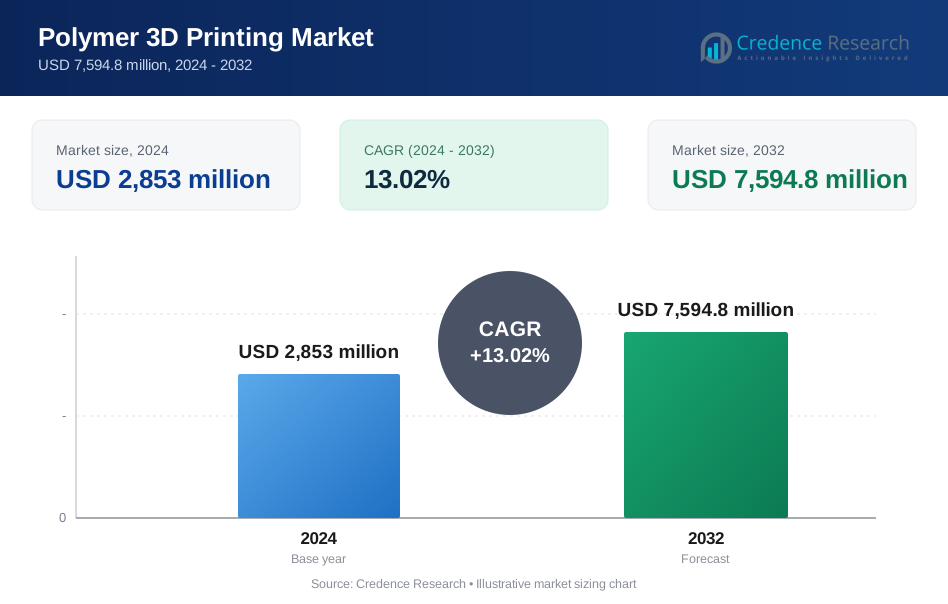
The Polymer 3D printing market is projected to grow from USD 2,853 million in 2024 to USD 7,594.8 million by 2032. The market is expected to expand at a CAGR of 13.02% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Polymer 3D Printing Market Size 2024 | USD 2,853 million |
| Polymer 3D Printing Market , CAGR | 13.02% |
| Polymer 3D Printing Market Size 2032 | USD 7,594.8 million |
Market growth is driven by rapid adoption in manufacturing and product design. Companies use polymer 3D printing for fast prototyping and short production runs. Advances in materials improve strength, heat resistance, and surface quality. Equipment costs continue to decline, improving access for small firms. Automation and software integration raise printing accuracy and speed. End users seek faster customization and reduced tooling needs. Sustainability goals also favor polymer printing due to lower waste. These factors collectively support steady market expansion.
North America leads the market due to early technology adoption and strong industrial demand. The United States supports innovation through aerospace, healthcare, and automotive use cases. Europe follows with strong adoption in Germany, the UK, and France, driven by advanced manufacturing. Asia Pacific is the fastest-growing region. China, Japan, and South Korea expand capacity through industrial automation. Emerging markets adopt polymer printing for cost-efficient local production.

Market Insights:
- The Polymer 3D printing market was valued at USD 2,853 million in 2024 and is projected to reach USD 7,594.8 million by 2032, expanding at a CAGR of 13.02% driven by rising industrial adoption and material innovation.
- North America (38%), Europe (28%), and Asia Pacific (25%) dominate due to early technology adoption, strong manufacturing bases, and active R&D ecosystems across aerospace, automotive, and healthcare sectors.
- Asia Pacific, with a 25% share, is the fastest-growing region, supported by rapid industrialization, expanding electronics manufacturing, and increasing investments in advanced production technologies across China, Japan, and South Korea.
- By material type, thermoplastics account for around 46% of total demand due to cost efficiency and versatility, while resins hold nearly 27% supported by precision and surface quality requirements.
- By technology, Fused Deposition Modelling holds about 42% share due to accessibility, while Selective Laser Sintering represents nearly 24%, driven by demand for complex and support-free part production.
Market Drivers:
Expansion Of Industrial Prototyping And Short Production Cycles
The Polymer 3D printing market benefits from rapid industrial prototyping demand. Manufacturers seek faster design validation across product lifecycles. Polymer printers reduce tooling dependence in early development stages. Engineers test complex geometries without production delays. Iteration speed supports faster product launches. Cost efficiency improves during low-volume production. Design flexibility supports innovation across sectors. These factors strengthen adoption across industrial users.
- For instance, Stratasys reports that FDM systems enable same-day prototype iteration, replacing tooling lead times that typically extend several weeks in traditional methods.
Rising Demand For Lightweight And Customized Components
End users prefer lightweight polymer components for performance gains. Automotive and aerospace firms prioritize weight reduction strategies. Polymer materials support complex internal structures. Customization meets diverse application requirements. Short-run production suits specialized component needs. The Polymer 3D printing market aligns with flexible manufacturing goals. It enables rapid changes without retooling costs. Demand continues across advanced manufacturing environments.
For instance, Airbus uses polymer 3D printed cabin parts that cut component weight by up to 30%, supporting fuel efficiency and design flexibility.
Growth In Healthcare And Medical Device Applications
Healthcare adoption accelerates due to patient-specific requirements. Polymer printing supports customized implants and surgical tools. Medical firms value precision and repeatability. Rapid turnaround improves patient care workflows. Regulatory clarity improves confidence in polymer-based devices. Material biocompatibility expands clinical use cases. The Polymer 3D printing market benefits from this shift. It supports scalable medical production.
Declining Equipment Costs And Broader Technology Access
Printer prices decline across entry and mid-level systems. Small firms gain access to advanced manufacturing tools. Training and software improvements simplify adoption. Polymer systems require lower operational expertise. Supply chains benefit from decentralized production models. The Polymer 3D printing market gains wider penetration. It supports startups and contract manufacturers. Accessibility remains a key growth driver.
Market Trends:
Shift Toward Distributed And Localized Manufacturing Models
Manufacturers adopt localized production strategies for resilience. Polymer printing supports on-demand part creation. Inventory dependence reduces across supply chains. Local facilities shorten delivery timelines. Custom production meets regional requirements. The Polymer 3D printing market aligns with decentralization trends. It supports flexible manufacturing networks. Adoption rises across distributed facilities.
- For instance, HP states that its Multi Jet Fusion technology can produce functional polymer parts up to 10 times faster than conventional SLS, enabling localized production hubs.
Increasing Use Of Digital Part Libraries And Virtual Inventories
Companies store designs in secure digital formats. Physical inventory converts to digital stock. Polymer printers enable instant part fabrication. Downtime reduces during maintenance operations. Digital workflows improve supply reliability. The Polymer 3D printing market integrates with smart manufacturing systems. It supports virtual inventory strategies. This trend reshapes spare part management.
- For instance, Materialise supports certified digital part libraries for aerospace customers, allowing approved polymer parts to be printed on demand instead of warehoused.
Integration With Automation And Smart Factory Systems
Factories connect polymer printers with automated workflows. Robotics handle part removal and post-processing. Software platforms manage print queues efficiently. Data analytics improve quality control. Smart factories demand flexible production tools. The Polymer 3D printing market fits Industry 4.0 frameworks. It supports connected manufacturing environments. Integration trends continue to strengthen.
Rising Preference For Multi-Material And Functional Printing
Users demand parts with varied mechanical properties. Multi-material polymer systems meet this need. Functional components replace visual prototypes. Electrical and thermal features gain importance. Design complexity increases across applications. The Polymer 3D printing market adapts through system upgrades. It supports functional end-use parts. Material diversity remains a key trend.
Market Challenges Analysis:
Material Performance Limitations In Demanding Applications
Polymer materials face strength and heat constraints. Some industries require metal-like performance. Long-term durability raises concerns for end-use parts. Qualification processes remain complex. Performance gaps limit adoption in critical environments. The Polymer 3D printing market addresses these issues gradually. It invests in material development. Challenges persist across high-stress applications.
Process Consistency And Quality Standardization Issues
Print quality varies across machines and operators. Process control requires skilled oversight. Repeatability remains a concern for mass production. Certification standards vary by region. Quality assurance increases operational complexity. The Polymer 3D printing market faces customer scrutiny. It must ensure consistent output. Standardization efforts continue across the industry.
Market Opportunities:
Expansion Into Consumer Products And Custom Manufacturing
Consumer brands seek mass customization capabilities. Polymer printing supports personalized product designs. Short production runs fit consumer demand patterns. Fashion and lifestyle products adopt rapid manufacturing. Design updates reach markets faster. The Polymer 3D printing market benefits from customization trends. It supports creative product differentiation. Consumer adoption opens new revenue streams.
Growth Potential In Education And Small Enterprise Adoption
Educational institutions invest in polymer printing tools. Training programs build future workforce skills. Small enterprises adopt printers for niche production. Local manufacturing reduces entry barriers. Innovation ecosystems gain momentum through access. The Polymer 3D printing market expands its user base. It supports grassroots manufacturing growth. Long-term adoption potential remains strong.
Market Segmentation Analysis:
By Material Type
Thermoplastics dominate due to strength, recyclability, and broad industrial use. These materials support functional parts and rapid iteration cycles. Resins serve applications that need fine detail and smooth surfaces. Elastomers address demand for flexible and impact-resistant components. Composites enable higher stiffness and durability for demanding uses. Material choice depends on performance needs and cost targets. The Polymer 3D printing market reflects steady material diversification. It supports wider end-use adoption across industries.
- For instance, BASF supplies PA6 and PA12 polymer powders for SLS that meet mechanical strength requirements for industrial housings and tooling components.
By Technology
Fused Deposition Modelling leads due to low cost and ease of use. This method suits prototyping and basic production tasks. Stereolithography delivers high precision and smooth finishes. Selective Laser Sintering supports complex geometries without support structures. Digital Light Processing offers speed and consistency for batch output. Technology selection aligns with part complexity and volume. The Polymer 3D printing market shows balanced demand across platforms. It supports both entry and industrial systems.
- For instance, EOS GmbH reports that its SLS systems using PA12 achieve tensile strength above 48 MPa, supporting durable end-use industrial parts.
By Application / End-use
Prototyping remains the primary application due to speed and flexibility. Production use expands for short runs and customized parts. Aerospace adopts polymer printing for lightweight components. Automotive firms use it for tooling and interior parts. Healthcare relies on customization and precision. Consumer goods benefit from design freedom and fast updates. The Polymer 3D printing market serves diverse end users. It enables efficient and flexible manufacturing paths.
Segmentation:
- By Material Type
- Thermoplastics
- Resins
- Elastomers
- Composites
- By Technology
- Fused Deposition Modelling (FDM)
- Stereolithography (SLA)
- Selective Laser Sintering (SLS)
- Digital Light Processing (DLP)
- By Application / End-use
- Prototyping
- Production
- Aerospace
- Automotive
- Healthcare
- Consumer Goods
- By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
- North America
Regional Analysis:
North America
North America holds the largest share of the Polymer 3D printing market, accounting for around 38% of global revenue. The region benefits from early technology adoption across industrial sectors. Strong demand comes from aerospace, healthcare, and advanced manufacturing. The United States leads due to high R&D spending and mature additive ecosystems. Canada supports growth through academic and industrial collaboration. The Polymer 3D printing market gains from strong material innovation. It maintains leadership through continuous technology upgrades.
Europe
Europe represents about 28% of the global market share. Germany, the UK, and France drive regional demand through industrial automation. Automotive and aerospace firms rely on polymer printing for tooling and lightweight parts. Strong regulatory support promotes advanced manufacturing adoption. Material development remains a regional strength. The Polymer 3D printing market benefits from engineering expertise. It shows stable growth across Western Europe.
Asia Pacific, Latin America, and Middle East & Africa
Asia Pacific accounts for nearly 25% of the Polymer 3D printing market. China, Japan, and South Korea expand use in electronics and automotive sectors. Rapid industrialization supports technology uptake. Latin America holds around 5%, led by Brazil and Mexico. Cost-focused manufacturing drives selective adoption. The Middle East & Africa contribute about 4%, supported by industrial diversification. It shows early-stage but steady progress.
Key Player Analysis:
- Stratasys
- 3D Systems
- BASF
- Arkema
- HP
- EOS GmbH
- Formlabs
- Markforged
- Materialise
- Evonik
Competitive Analysis:
The Polymer 3D printing market shows strong competition among global technology providers and material specialists. Leading players compete on printer performance, material breadth, and software integration. Companies focus on reliability and scalability to serve industrial users. Material suppliers strengthen positions through advanced polymer formulations. Hardware firms expand portfolios to cover prototyping and production needs. Strategic partnerships support ecosystem development. The Polymer 3D printing market rewards firms with strong application expertise. It favors players that balance innovation with cost control.
Recent Developments:
- In November 2025 at Formnext, HP Additive Manufacturing unveiled the HP IF 600HT industrial filament 3D printer, marking the company's entry into filament-based additive manufacturing. Scheduled for release in the first half of 2026, with a larger model (HP IF 1000 XL) planned for the second half of 2026, this modular system features swappable extruders designed for high-temperature polymers and targets aerospace, automotive, and medical applications. HP confirmed the general availability of HP 3D HR PA 11 Gen2, offering up to 80% powder reusability and up to 40% lower variable part costs. Additionally, HP announced expanded partnerships with Continuum Powders and TECNALIA to develop OptiPowder M247LC, a low-carbon nickel superalloy for aerospace and energy applications. The company also introduced the Additive Manufacturing Network (AMN), a data-driven program designed to connect global parts demand with qualified service providers.
- In September 2025, EOS Partners GmbH acquired a majority stake in FLEXiCODE GmbH and FLEXiCODE Schweiz AG, an IT services provider specializing in the IFS ecosystem. Earlier in April 2025, EOS and Godrej Enterprises Group announced a strategic partnership focused on developing additive manufacturing solutions for the Indian aviation and space industries, with plans to establish AM-based design and production capabilities for functionally improved components. Furthermore, in September 2025, aerospace and defense company Ursa Major expanded its investment in EOS metal additive manufacturing technology by acquiring three additional AMCM M 450-4 FLX systems, demonstrating confidence in EOS's proven laser powder bed fusion technology.
- In July 2025, Stratasys released GrabCAD Print Pro 2025, an advanced software platform designed to streamline additive manufacturing workflows. This software release enables operators to create complex fixtures without requiring CAD tools, reducing preparation time from days to hours. The platform consolidates multiple software licenses into a single interface and supports all five Stratasys technologies alongside select third-party powder bed fusion and stereolithography systems. Additionally, in November 2025, Stratasys announced a series of innovations across its FDM, SAF, and P3 DLP platforms, expanding material choices and improving throughput. Earlier in 2025, at the RAPID + TCT conference in April, Stratasys introduced ToughONE material, a breakthrough for PolyJet 3D printing that provides increased strength and functional properties for production applications.
- In March 2025, 3D Systems completed the sale of its Geomagic software portfolio to Hexagon's Manufacturing Intelligence Division for $123 million, with approximately $100 million in net proceeds strengthening the company's balance sheet. This strategic divestiture allows 3D Systems to concentrate on core additive manufacturing software platforms including 3D Sprint, 3DXpert, and Oqton Industrial Manufacturing OS. The company intends to leverage artificial intelligence and automation capabilities to enable accelerated adoption of 3D printing technologies in high-volume production environments.
Report Coverage:
The research report offers an in-depth analysis based on Material Type and Technology segments. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Industrial users will expand polymer 3D printing from prototyping into regular production workflows.
- Material suppliers will develop stronger and more heat-resistant polymer grades for demanding applications.
- Printer manufacturers will improve system reliability to support continuous industrial use.
- Software platforms will enhance print management, quality control, and design optimization.
- Custom manufacturing will gain wider acceptance across consumer and industrial products.
- Healthcare applications will increase due to demand for patient-specific solutions.
- Small and mid-sized enterprises will adopt polymer printers as costs continue to decline.
- Sustainability goals will encourage adoption due to reduced material waste.
- Regional manufacturing hubs will strengthen through localized additive production.
- Competitive intensity will increase as new entrants target niche applications.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Polymer 3D printing market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Polymer 3D printing market projected to grow between 2025 and 2032?
Which Polymer 3D printing market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Polymer 3D printing market?
Who are the leading companies in the Polymer 3D printing market?
Which region commanded the largest share of the Polymer 3D printing market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 2,853 million → 2032: USD 7,594.8 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Polymer 3D Printing Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Polymer 3D Printing Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Polymer 3D Printing Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Polymer 3D Printing Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Polymer 3D Printing Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Polymer 3D Printing Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Polymer 3D Printing Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Polymer 3D Printing Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 2,853 million → 2032: USD 7,594.8 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Polymer 3D Printing Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Polymer 3D Printing Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Polymer 3D Printing Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Polymer 3D Printing Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

