
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Metal Additive Manufacturing Market Size 2024 | USD 5860 Million |
| Metal Additive Manufacturing Market, CAGR | 13.4% |
| Metal Additive Manufacturing Market Size 2032 | USD 16025.15 Million |
Market Overview:
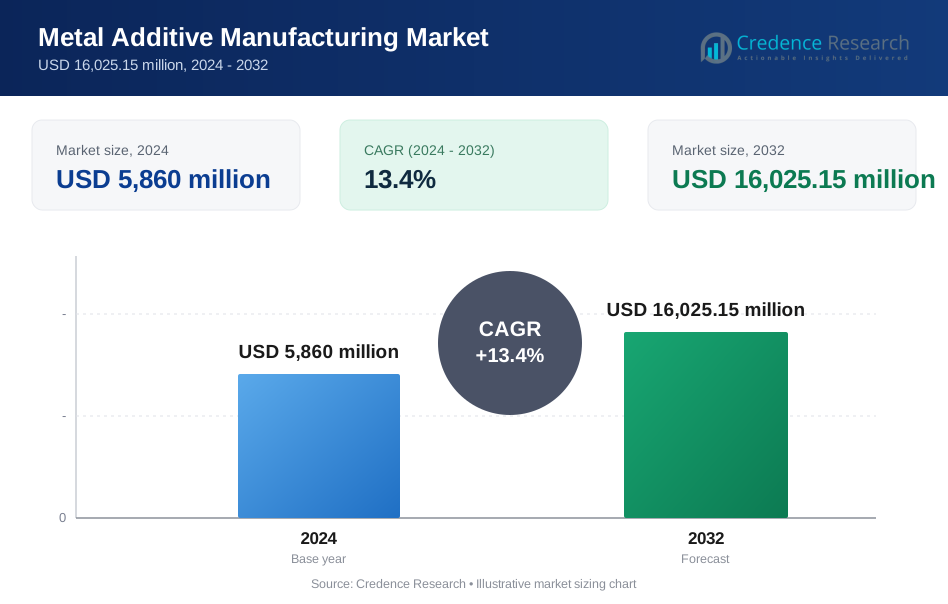
The Metal Additive Manufacturing Market is projected to grow from USD 5860 million in 2024 to an estimated USD 16025.15 million by 2032, with a compound annual growth rate (CAGR) of 13.4% from 2024 to 2032.
Key drivers of the metal additive manufacturing market include the rising demand for customized and lightweight components, advancements in metal AM technologies, and increasing investments in research and development. Aerospace and defense sectors continue to be major contributors, leveraging metal AM for component weight reduction and design optimization. The medical field is also witnessing increased adoption, especially for creating patient-specific implants and surgical tools. Furthermore, the shift toward Industry 4.0 and the integration of digital manufacturing solutions are supporting the adoption of metal AM in industrial production. Material innovation, enhanced printing speeds, and declining costs of metal powders and AM systems are further encouraging the adoption of metal additive manufacturing across a wider range of applications.
Regionally, North America dominates the metal additive manufacturing market due to the strong presence of key industry players, well-established aerospace and defense sectors, and robust investment in advanced manufacturing technologies. The United States, in particular, is a leader in R&D activities and large-scale adoption of metal AM. Europe follows closely, supported by Germany, the United Kingdom, and France, which are fostering innovation in automotive and industrial manufacturing. The Asia-Pacific region is expected to register the fastest growth over the forecast period, driven by expanding manufacturing capabilities in China, Japan, South Korea, and India. Government initiatives, rising industrial automation, and growing interest in sustainable production methods are boosting the adoption of metal AM technologies across these regions. As infrastructure, expertise, and investment continue to evolve, the global metal additive manufacturing market is poised for sustained expansion.
Market Insights:
- The metal additive manufacturing market is expected to grow from USD 5,860 million in 2024 to USD 16,025.15 million by 2032, at a CAGR of 13.4%.
- Aerospace and defense industries are leading adopters of metal AM due to their need for lightweight, high-performance components.
- Advancements in technologies such as SLM, EBM, and DMLS are enabling precision manufacturing and expanding AM applications beyond prototyping.
- The growing demand for customization and rapid product iteration is driving adoption across healthcare, automotive, and industrial sectors.
- North America dominates the market, while Asia-Pacific is projected to witness the fastest growth due to industrial expansion and supportive policies.
- High equipment costs, material limitations, and lack of global standards remain key challenges limiting broader adoption, especially among SMEs.
- Continued investment from governments and private sectors, along with Industry 4.0 integration, is creating long-term growth opportunities for the market.
Market Drivers:
Advancements in Metal Additive Manufacturing Technologies
Technological innovation is one of the most significant drivers of the metal additive manufacturing market. Over the past decade, improvements in metal 3D printing technologies, such as Selective Laser Melting (SLM), Electron Beam Melting (EBM), and Direct Metal Laser Sintering (DMLS), have enhanced the precision, scalability, and cost-efficiency of metal AM processes. These advancements have enabled the production of complex and high-performance components with reduced lead times and minimal material waste. Enhanced print speeds, improved layer resolution, and innovations in post-processing techniques have expanded the feasibility of using metal AM in end-use production rather than just prototyping. The continuous evolution of AM systems is strengthening their value proposition across diverse industries.
Rising Demand in Aerospace, Automotive, and Healthcare Sectors
The increasing adoption of metal additive manufacturing in critical industries such as aerospace, automotive, and healthcare is fueling market growth. In aerospace and defense, metal AM is used to produce lightweight and complex parts that meet strict performance and safety standards, thereby improving fuel efficiency and reducing emissions. The automotive industry leverages metal AM for rapid prototyping, tooling, and small-batch production of intricate parts that would be costly or impossible to produce using traditional methods. In healthcare, the technology is gaining traction for the production of patient-specific implants, prosthetics, and surgical tools, improving outcomes through personalized treatment solutions. For example, GE Aviation has used 3D printing to create fuel nozzles, reducing weight and increasing fuel efficiency. As these sectors continue to prioritize innovation and customization, the demand for metal AM is expected to increase substantially.
Customization and Design Flexibility
One of the primary advantages of metal additive manufacturing is its ability to produce customized and geometrically complex parts without the need for specialized tooling or molds. This design flexibility is particularly valuable in industries that require rapid iteration, low-volume production, and tailored solutions. Engineers and designers can now develop components with optimized internal structures, integrated functionalities, and enhanced mechanical properties that would be unachievable using conventional manufacturing methods. This capability reduces product development cycles and supports on-demand manufacturing, aligning with the growing trend of mass customization in modern manufacturing environments. The flexibility and speed offered by metal AM are key enablers of competitive advantage for businesses seeking to innovate rapidly.
Growing Investments and Government Support
Rising investments from both public and private sectors are accelerating the development and adoption of metal additive manufacturing technologies. Governments across North America, Europe, and Asia-Pacific are introducing supportive policies, funding programs, and research initiatives to promote advanced manufacturing and digital transformation. For example, the University of Waterloo in Ontario, Canada, has received a $5 million investment to support the creation of the Consortium for Sustainable Scale-up in Metal Additive Manufacturing (CSS-MAM). Industry leaders are also increasing capital expenditure to scale up AM production capabilities, enhance supply chain resilience, and maintain technological leadership. Strategic collaborations between manufacturers, research institutions, and technology providers are driving material development, process optimization, and application-specific innovations. This favorable investment climate is expected to sustain the growth momentum of the metal additive manufacturing market in the coming years.
Market Trends:
Transition from Prototyping to Full-Scale Production
A key trend shaping the metal additive manufacturing market is the shift from prototyping to full-scale production. Initially adopted for rapid prototyping due to its speed and design flexibility, metal AM is now being integrated into serial production lines. Industries such as aerospace and automotive are utilizing metal 3D printing to manufacture final-use parts, including engine components, structural brackets, and heat exchangers. This transition is supported by advancements in machine reliability, repeatability, and quality assurance. For instance, Northrop Grumman has utilized metal additive manufacturing (AM) to produce components such as coldplates, achieving significant reductions in production time and cost. As manufacturers aim to reduce production cycles and respond to fluctuating market demands, the scalability of metal AM is proving to be a strategic asset in high-mix, low-volume production environments.
Expansion of Material Portfolio
The metal additive manufacturing market is witnessing a rapid expansion in the range of materials available for use. While early adoption primarily relied on stainless steel and titanium, the market now includes high-performance alloys such as Inconel, cobalt-chrome, tool steels, and aluminum-based powders. This broader material portfolio is opening new possibilities for applications in energy, defense, and heavy equipment industries. For instance, Inconel alloys are being used in gas turbine parts due to their high-temperature resistance, while aluminum alloys are gaining traction in the automotive sector for lightweight structural components. The development of proprietary alloys by AM companies is further enhancing the versatility and mechanical properties of 3D printed parts.
Integration with Traditional Manufacturing and Supply Chains
Another prominent trend is the growing integration of metal additive manufacturing into traditional manufacturing workflows and global supply chains. Rather than replacing conventional methods entirely, metal AM is increasingly being used in conjunction with casting, CNC machining, and injection molding to optimize production efficiency. Hybrid manufacturing systems that combine additive and subtractive processes in a single machine are gaining popularity, enabling manufacturers to produce complex geometries with high surface quality. Furthermore, metal AM is being leveraged to produce tooling, molds, and jigs, thereby reducing lead times and costs in traditional processes. This synergistic approach is enhancing overall manufacturing flexibility and responsiveness.
Rise of Digital Manufacturing Ecosystems
The emergence of digital manufacturing ecosystems is significantly influencing the metal additive manufacturing market. Companies are investing in software platforms that enable digital part design, simulation, real-time monitoring, and quality assurance. For example, Optomec’s LENS Print Engine integrates additive and subtractive processes on a single machine, enabling manufacturers to produce complex geometries with high precision and surface quality. Cloud-based solutions and digital twins are being deployed to manage AM workflows, optimize designs for additive production, and ensure consistency across multiple facilities. This digitization is also facilitating decentralized production models, where parts are manufactured closer to the point of use, reducing logistics costs and improving supply chain resilience. The convergence of metal AM with data analytics, machine learning, and smart factory principles is reshaping the future of industrial manufacturing.
Market Challenges Analysis:
High Initial Investment and Operational Costs One of the primary restraints in the metal additive manufacturing market is the high cost associated with acquiring and maintaining advanced AM equipment. For instance, professional metal 3D printers, such as those utilizing Direct Metal Laser Sintering (DMLS) or Selective Laser Melting (SLM), can cost between $100,000 and $500,000 or more, while larger industrial systems may exceed $1 million. In addition to equipment costs, there are expenses related to facility setup, safety infrastructure, and skilled labor. Operational costs remain elevated due to the high price of metal powders, maintenance of sensitive components, and energy-intensive processes. These financial barriers limit adoption, particularly among small and medium-sized enterprises that may not have the resources to invest in large-scale implementation.
Material and Process Limitations Despite advancements in metal AM materials, the availability of compatible and high-performance alloys remains limited compared to traditional manufacturing. Each metal and alloy requires specific processing parameters, and not all materials are optimized for additive manufacturing. Additionally, issues such as residual stresses, porosity, and anisotropic mechanical properties can affect the reliability and performance of printed components. Ensuring repeatability and part quality across different batches continues to be a technical challenge. These limitations necessitate extensive testing and certification processes, particularly in regulated industries like aerospace and medical, which slows down the adoption rate.
Lack of Standardization and Regulatory Frameworks The absence of global standards and regulatory frameworks presents another challenge for the metal AM industry. With varying quality benchmarks and certification requirements across industries and regions, manufacturers face complexities in achieving compliance. This lack of harmonization hinders scalability and increases the burden on organizations to establish internal validation procedures. Efforts by industry bodies and standardization organizations are underway, but widespread adoption of unified protocols is still evolving, creating uncertainty for businesses seeking to integrate metal additive manufacturing into their operations.
Market Opportunities:
The metal additive manufacturing market presents significant growth opportunities driven by the increasing demand for innovation, customization, and efficiency in manufacturing processes. As industries such as aerospace, automotive, medical, and energy continue to seek lightweight, high-strength components with complex geometries, metal AM offers a transformative solution. The ability to produce parts with optimized designs, reduced material waste, and shorter lead times positions metal AM as a key enabler of next-generation manufacturing. Emerging economies are also showing rising interest in adopting advanced manufacturing technologies, creating new revenue streams for AM equipment manufacturers, material suppliers, and service providers. Moreover, the growing interest in sustainability and decentralized production is likely to accelerate the adoption of metal AM, particularly for applications that demand lower environmental impact and on-demand production capabilities.
Another promising opportunity lies in the expansion of industry-specific applications and the development of novel materials tailored for additive processes. In the healthcare sector, for instance, the demand for personalized implants and surgical tools is creating a robust pipeline for innovation. In the defense and aerospace industries, the shift toward digital inventory and on-site part production enhances supply chain resilience and mission readiness. Additionally, advancements in software, automation, and AI-driven quality control are making metal AM systems more accessible and reliable, encouraging wider adoption across different scales of operation. As industries continue to integrate digital manufacturing solutions into their workflows, the metal additive manufacturing market is poised to capitalize on the evolving needs of modern production ecosystems.
Market Segmentation Analysis:
The metal additive manufacturing market is segmented across four key dimensions: type, component, end-user industry, and technology. Each segment plays a vital role in shaping the market’s growth and adoption trends across industries.
By type, Powder Bed Fusion holds the largest market share due to its high precision and suitability for complex part geometries, particularly in aerospace and medical applications. Binder Jetting is gaining momentum for its speed and cost-effectiveness, especially in prototyping and industrial-scale production. Direct Energy Deposition is favored for large-scale repairs and hybrid manufacturing, while Bound Powder Extrusion is emerging as a cost-efficient alternative for low-volume production. The Others segment includes niche and evolving methods that continue to find specialized applications.
By component segment, Systems dominate in revenue contribution, driven by growing adoption of industrial-grade 3D printers. Materials follow closely, as demand for diverse and high-performance metal powders increases. Service and Parts are expanding rapidly, supported by the rise in contract manufacturing and maintenance services.
By end-user industry, Aerospace leads due to the critical need for lightweight, durable, and custom-designed components. Automotive is increasingly adopting metal AM for prototyping, tooling, and performance parts. The Healthcare sector is rapidly integrating AM for patient-specific implants and surgical instruments. The Others category includes energy, defense, and industrial manufacturing.
By technology, Laser-Based Technologies account for the largest share, owing to their widespread use and high precision. Electron Beam-Based, Cold Spray, and Hybrid Systems are evolving to meet specialized manufacturing requirements across advanced industrial applications.
Segmentation:
By Type
- Powder Bed Fusion
- Binder Jetting
- Direct Energy Deposition
- Bound Powder Extrusion
- Others
By Component
- Systems
- Materials
- Service and Parts
By End-User Industry
- Aerospace
- Automotive
- Healthcare
- Others
By Technology
- Laser-Based Technologies
- Electron Beam-Based Technologies
- Cold Spray Technologies
- Hybrid Systems
Regional Analysis:
The metal additive manufacturing market exhibits strong growth potential across major global regions, with North America, Europe, and Asia-Pacific leading in technology adoption and market share. In 2024, North America held the largest share of the global metal AM market, accounting for 37.2%. This dominance is largely driven by the presence of established aerospace, defense, and healthcare industries in the United States and Canada. These sectors are at the forefront of adopting metal AM technologies for prototyping, tooling, and production of critical components. Government support, investment in research and development, and a mature industrial ecosystem further strengthen North America's leadership position in the market.
Europe followed closely, capturing a 31.8% share of the global metal additive manufacturing market. Countries such as Germany, the United Kingdom, France, and Italy are driving regional growth through their advanced engineering capabilities and strong focus on innovation in the automotive and industrial manufacturing sectors. Germany, in particular, is a hub for metal AM technology development and machine production, supported by a highly skilled workforce and strong academic-industrial collaboration. The European Union’s initiatives to promote digital manufacturing and sustainability are also accelerating the adoption of metal AM across the region.
The Asia-Pacific region accounted for 23.5% of the global market and is expected to experience the fastest growth over the forecast period. Countries like China, Japan, South Korea, and India are investing heavily in advanced manufacturing technologies to strengthen their domestic production capabilities. China is rapidly expanding its metal AM infrastructure for applications in aerospace, automotive, and defense, supported by government-led initiatives and funding programs. Japan and South Korea are also contributing to regional growth through material innovation and precision manufacturing technologies.
Latin America and the Middle East & Africa regions collectively accounted for the remaining 7.5% of the global market. While adoption is currently at a nascent stage, these regions are gradually recognizing the potential of metal AM, particularly in sectors such as oil and gas, construction, and healthcare. Strategic collaborations, training programs, and infrastructure development are expected to support the future expansion of metal AM technologies in these emerging markets.
Key Player Analysis:
- Trumpf Inc.
- Lincoln Electric Additive Solutions
- Hoganas AB
- EOS GmbH
- Stratasys Ltd.
- Company 6
- Company 7
- Company 8
- Company 9
- Company 10
Competitive Analysis:
The metal additive manufacturing market is characterized by intense competition among established players and emerging innovators striving to enhance technological capabilities and expand market presence. Leading companies such as EOS GmbH, 3D Systems Corporation, GE Additive, SLM Solutions, and Renishaw plc dominate the market through comprehensive product portfolios, advanced printing technologies, and strategic partnerships. These players invest heavily in research and development to improve print quality, material range, and system scalability. Startups and regional firms are also gaining traction by offering specialized solutions and cost-effective services tailored to niche applications. The market is witnessing increased consolidation through mergers, acquisitions, and collaborations aimed at strengthening global distribution networks and accelerating innovation. Competitive differentiation is largely driven by technological advancements, reliability of systems, and post-processing capabilities. As the industry matures, companies that can offer end-to-end additive manufacturing solutions and demonstrate value in production-scale applications are expected to maintain a strong competitive edge.
Recent Developments:
- In January 2025, amace Solutions, a subsidiary of Ace Designers Ltd. and one of India's leading metal additive manufacturing machine builders, partnered with the National Centre for Additive Manufacturing (NCAM). This collaboration aims to advance research, development, and adoption of metal AM technologies, empowering industries with cutting-edge 3D printing solutions. The partnership focuses on advancing research, driving adoption, developing applications, and enhancing skill development in the metal additive manufacturing sector.
- In June 2024, i3D MFG, one of the largest metal additive manufacturing organizations in North America, signed a letter of intent to purchase twelve ultra-productive 4-laser EOS M 400-4 metal 3D printers from EOS, a leading supplier of responsible manufacturing solutions. This acquisition signifies a significant expansion of i3D MFG's metal additive manufacturing capabilities.
- In March 2024, EOS launched the newest member of its EOS M 290 family, the EOS M 290 1kW. This new Laser Powder Bed Fusion (LPBF) metal additive manufacturing platform is designed with serial production in mind, offering enhanced capabilities for industrial-scale metal 3D printing.
- In March 2025, EOS GmbH expanded its metal powder range for the Oil & Gas and semiconductor industries by introducing two new metal powders for use in its Laser Beam Powder Bed Fusion (PBF-LB) Additive Manufacturing machines. The company launched EOS NickelAlloy IN718 API, designed for high-stress oil and gas applications, and EOS Nickel NiCP, ideal for use in semiconductor industries.
Market Concentration & Characteristics:
The metal additive manufacturing market exhibits moderate to high market concentration, with a few dominant players holding significant market share due to their technological expertise, global reach, and extensive product offerings. Companies such as GE Additive, EOS GmbH, and 3D Systems have established strong footholds by consistently innovating and forming strategic partnerships with key industries. Despite this concentration, the market remains dynamic, with new entrants introducing specialized technologies and materials to address evolving industry needs. The market is characterized by rapid technological advancements, high capital requirements, and a growing emphasis on integrated digital manufacturing solutions. Customization, precision, and efficiency are critical success factors driving product development and customer adoption. Additionally, the increasing demand for end-use production, particularly in aerospace, medical, and automotive sectors, is reshaping the competitive landscape. As the technology matures, standardization and scalability will play pivotal roles in shaping future market dynamics and entry barriers.
Report Coverage:
The research report offers an in-depth analysis based on type, component, end-user industry, and technology It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The metal additive manufacturing market is projected to grow significantly, driven by increasing industrial adoption for end-use production.
- Advancements in multi-material printing and high-performance alloys will broaden application areas across critical sectors.
- Integration of AI and machine learning will enhance process optimization, real-time monitoring, and predictive maintenance.
- Expansion of cloud-based design and simulation tools will streamline digital workflows and accelerate product development.
- Decentralized manufacturing models will gain traction, enabling localized, on-demand production across global supply chains.
- Regulatory advancements and standardization efforts will improve quality assurance and promote wider industry acceptance.
- Reduced costs of metal powders and AM systems will enhance accessibility for small and medium enterprises.
- Growth in aerospace, defense, and medical industries will remain pivotal in driving demand for precision and customization.
- Strategic partnerships and M&A activity will increase as companies seek to scale capabilities and enter new markets.
- Sustainability initiatives will fuel adoption as manufacturers seek to minimize material waste and energy consumption.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Advancements in Metal Additive Manufacturing Technologies
Continuous improvements in technologies such as Selective Laser Melting (SLM), Electron Beam Melting (EBM), and Direct Metal Laser Sintering (DMLS) are increasing precision, scalability, and cost-efficiency, enabling broader adoption of metal AM for both prototyping and end-use production.
Expansion in Aerospace, Automotive, and Healthcare Applications
Aerospace and defense sectors are leveraging metal AM for lightweight, complex components, while automotive and healthcare industries are adopting it for rapid prototyping, tooling, and patient-specific implants, driving significant market growth.
Customization and Design Flexibility
Metal AM allows for the production of highly customized and geometrically complex parts without the need for specialized tooling, supporting rapid iteration and on-demand manufacturing, which is increasingly valued across multiple industries.
Growing Investments and Government Support
Public and private sector investments, along with supportive government policies and funding for research and development, are accelerating the adoption and scaling of metal additive manufacturing technologies globally.
Integration with Industry 4.0 and Digital Manufacturing
The shift toward digital manufacturing ecosystems, including the use of cloud-based design, simulation tools, and real-time monitoring, is enhancing the efficiency and scalability of metal AM, making it a key enabler in modern, smart manufacturing environments.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Metal Additive Manufacturing Market?
What factors are driving the growth of the Metal Additive Manufacturing Market?
What are the key segments within the Metal Additive Manufacturing Market?
What are some challenges faced by the Metal Additive Manufacturing Market?
Who are the major players in the Metal Additive Manufacturing Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Powder Bed Fusion
- 1.2.2 Binder Jetting
- 1.2.3 Direct Energy Deposition
- 1.2.4 Bound Powder Extrusion
- 1.2.5 Others
- 1.3 By Component
- 1.3.1 Systems
- 1.3.2 Materials
- 1.3.3 Service and Parts
- 1.4 By Technology
- 1.4.1 Laser-Based Technologies
- 1.4.2 Electron Beam-Based Technologies
- 1.4.3 Cold Spray Technologies
- 1.4.4 Hybrid Systems
- 1.5 By End-User Industry
- 1.5.1 Aerospace
- 1.5.2 Automotive
- 1.5.3 Healthcare
- 1.5.4 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 5,860 million → 2032: USD 16,025.15 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Metal Additive Manufacturing Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Metal Additive Manufacturing Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Metal Additive Manufacturing Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Metal Additive Manufacturing Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Metal Additive Manufacturing Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Metal Additive Manufacturing Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Metal Additive Manufacturing Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Metal Additive Manufacturing Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 5,860 million → 2032: USD 16,025.15 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Metal Additive Manufacturing Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Powder Bed Fusion
- 12.3.7.2 Binder Jetting
- 12.3.7.3 Direct Energy Deposition
- 12.3.7.4 Bound Powder Extrusion
- 12.3.7.5 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Component - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Systems
- 12.4.7.2 Materials
- 12.4.7.3 Service and Parts
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Technology - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Laser-Based Technologies
- 12.5.7.2 Electron Beam-Based Technologies
- 12.5.7.3 Cold Spray Technologies
- 12.5.7.4 Hybrid Systems
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By End-User Industry - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Aerospace
- 12.6.7.2 Automotive
- 12.6.7.3 Healthcare
- 12.6.7.4 Others
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Metal Additive Manufacturing End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Metal Additive Manufacturing Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Metal Additive Manufacturing Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Metal Additive Manufacturing Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 EOS GmbH
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 GE Additive
- 18.4 3D Systems Corporation
- 18.5 SLM Solutions
- 18.6 Renishaw plc
- 18.7 Trumpf Inc.
- 18.8 Stratasys Ltd.
- 18.9 Hoganas AB
- 18.10 Lincoln Electric Additive Solutions
- 18.11 Desktop Metal
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

