
Glass, dental, reef and isotope uses shape demand
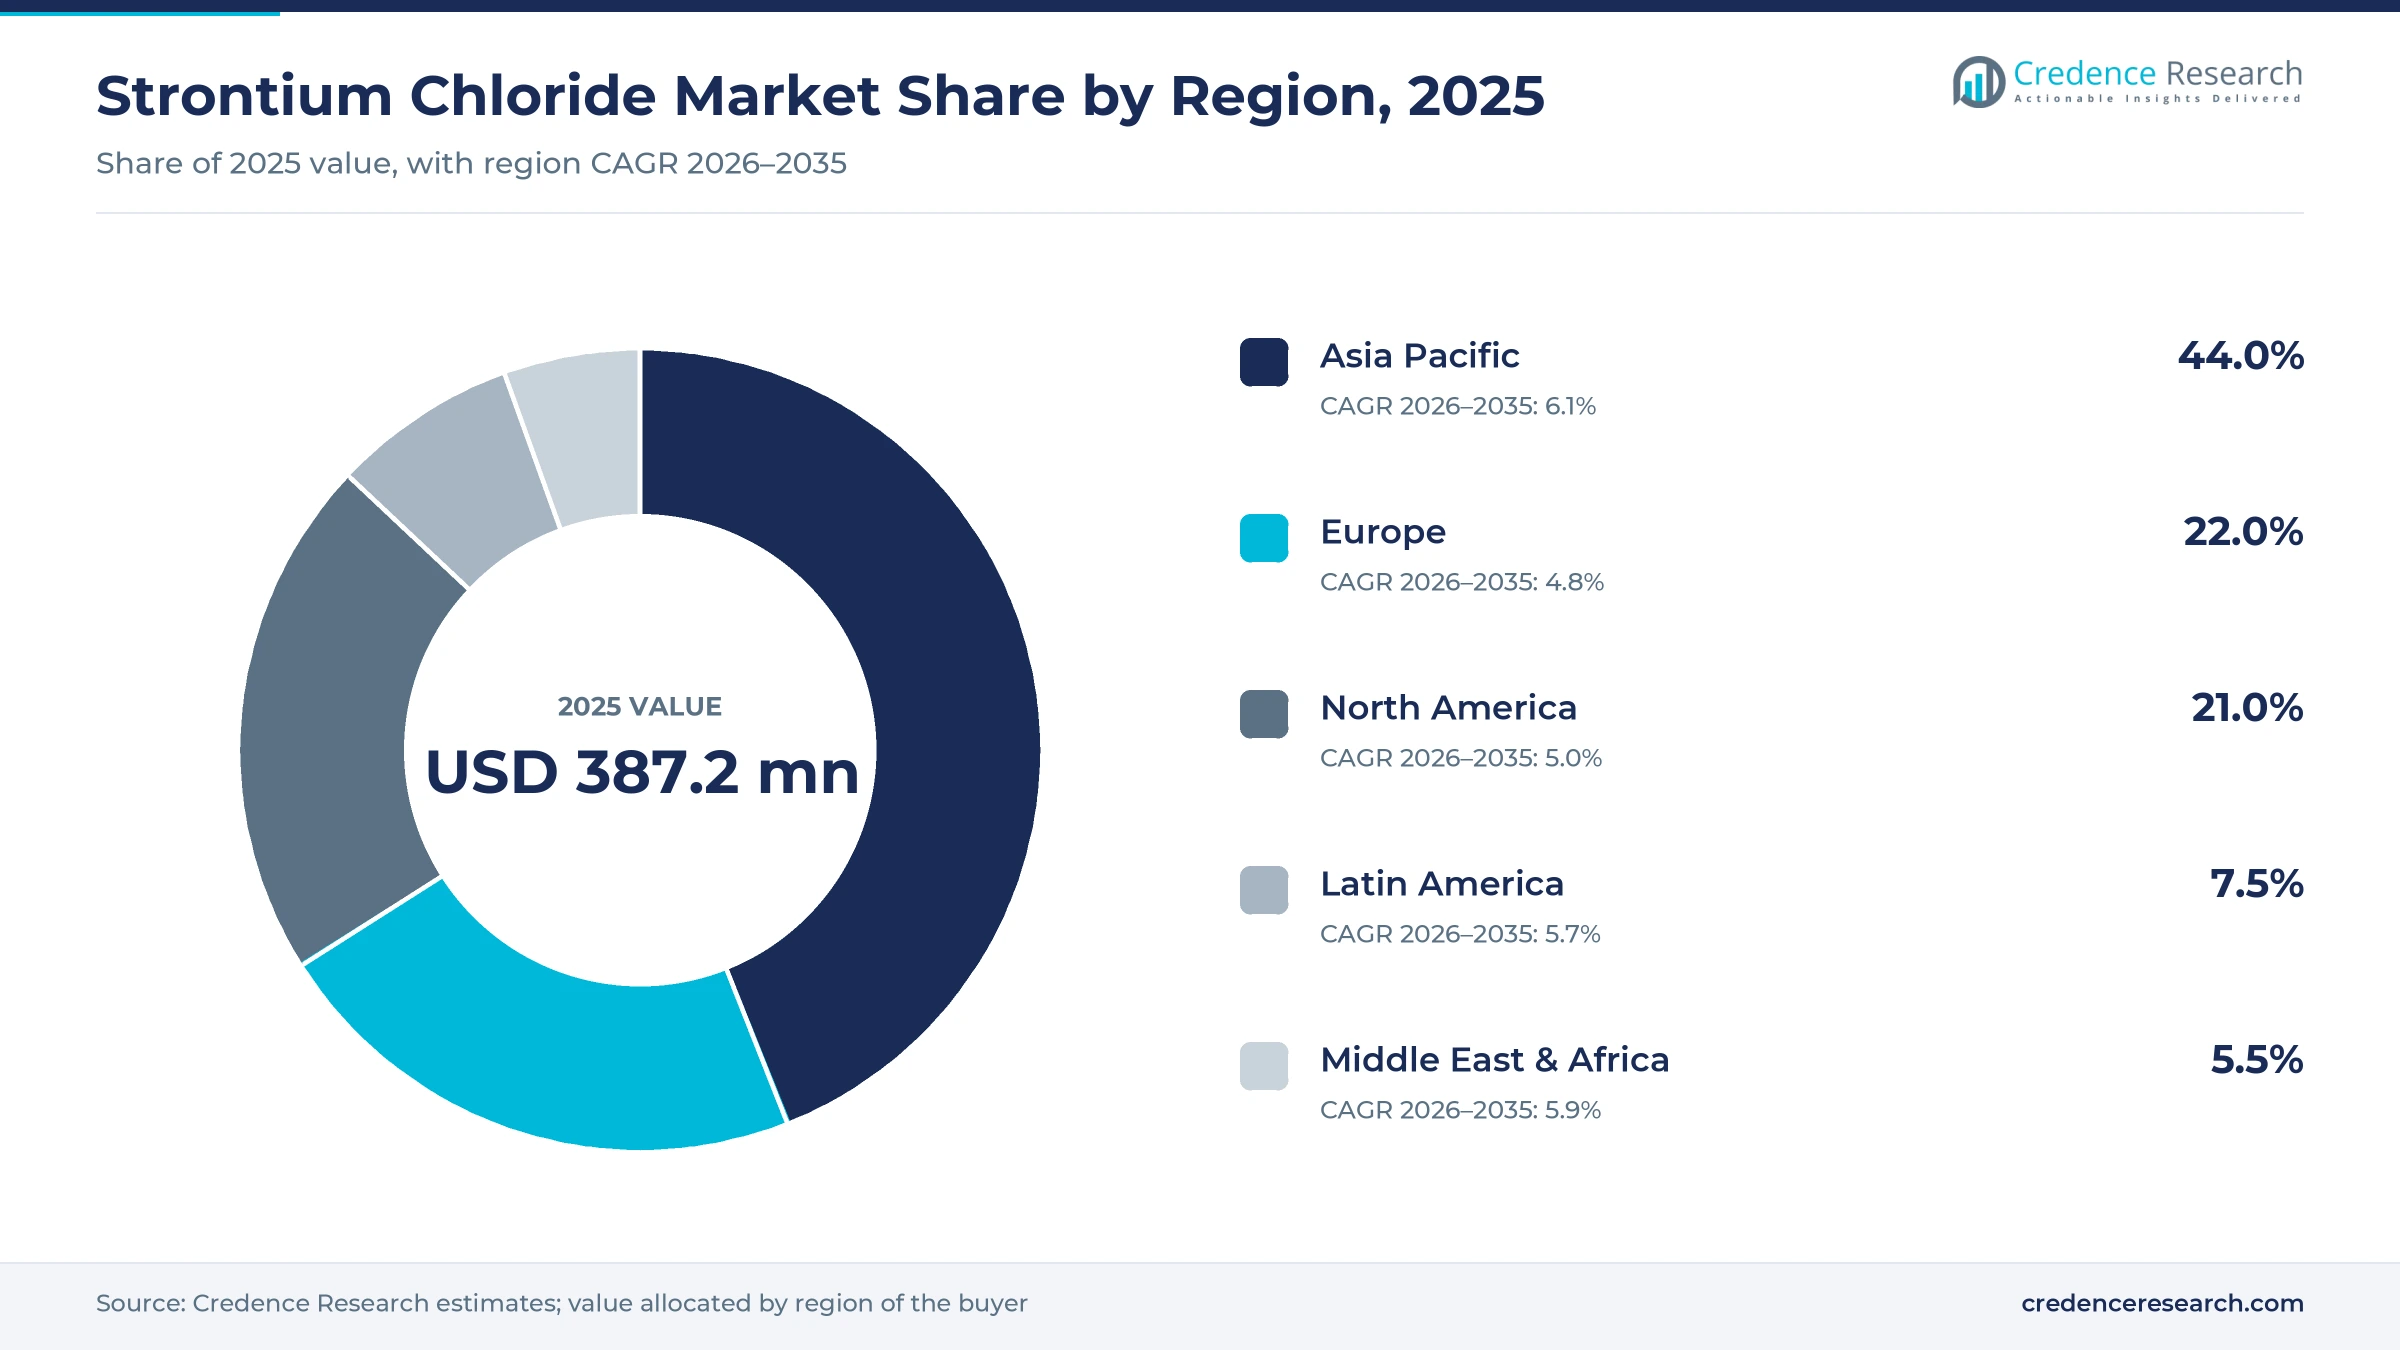
The global strontium chloride market was valued at USD 387.2 million in 2025 and is projected to increase from USD 408.5 million in 2026 to USD 661.4 million by 2035, registering a CAGR of 5.50% during 2026–2035. Demand comes from makers of display glass and magnetic materials, metallurgical users, desensitizing toothpaste brands, reef aquarium supplement makers, laboratories and the small radiopharmaceutical supply of Sr-89 chloride for cancer bone pain. Asia Pacific held the largest regional share, 44.0% in 2025, and is also the fastest-growing region at 6.0% a year, because Chongqing hosts integrated strontium salt plants close to local celestite. The supply base tightened in 2025 after Chinese plant shutdowns, a port blast in Iran and a fire at a Mexican carbonate plant pushed strontium carbonate, the main feedstock, to about double its late 2024 price. Buyers now weigh feedstock origin and purity, since high-purity grades and anhydrous material earn a clear premium over industrial hexahydrate.
What strontium chloride is used for and which grades count
The estimate counts strontium chloride hexahydrate and anhydrous strontium chloride sold in standard and high-purity grades for display and specialty glass, metallurgy, dental care, reef aquariums, laboratories and newer uses such as thermal energy storage. Sr-89 chloride solution for bone pain is counted at its supply value, while strontium carbonate, nitrate, acetate and gluconate sit outside the estimate.
Most industrial buyers purchase bagged hexahydrate in multi-ton lots from Chinese producers, while toothpaste and supplement makers buy qualified grades on annual terms. Laboratories buy kilogram packs through catalog suppliers, which carry far higher prices per kilogram than bulk material and explain much of the value in the purer grades.
Strontium Chloride Market Insights
- The market is valued at USD 387.2 million in 2025 and is projected to reach USD 661.4 million by 2035, growing at a 5.50% CAGR on glass, dental and reef aquarium demand.
- Asia Pacific led with 44.0% of 2025 value and grows fastest at 6.0% a year, as Chongqing producers convert local celestite into strontium salts.
- Glass-making and Metallurgy held 34.0% of 2025 value, because Chinese glass and magnetic material makers buy industrial hexahydrate, as Chongqing producers' application lists show.
- U.S. imports of strontium compounds rose about 14% in 2025 to an estimated 4,200 metric tons of strontium content, and the country mines no strontium.
- Anhydrous strontium chloride grows fastest at 6.3% a year from 2026 to 2035, as reef dosing products and energy storage research use the dry salt.
Industrial grades lead while high-purity anhydrous grows
Why do standard grades lead while high-purity grades grow faster?
Based on type, the market is categorized into standard grade, at 99% purity, and high-purity grade, at 99.5% or more. Standard Grade material led with 63.0% of 2025 value because glass, magnetic material and paint makers accept industrial hexahydrate, and Chongqing Yuanhe Fine Chemical lists an industrial grade with an annual capacity of 7,500 metric tons. High-Purity Grade material grows faster at 6.2% a year as laboratories and electronics researchers ask for tighter metal limits, and Noah Chemicals lists a 99.5% hexahydrate while ProChem sells anhydrous grades up to five-nines purity.
Why does hexahydrate lead while anhydrous grows fastest?
Based on form, the market is categorized into hexahydrate and anhydrous strontium chloride. Hexahydrate held 71.0% of 2025 value because it crystallizes directly from hydrochloric acid solutions and costs less to make, and dental formulas also specify this form, as the drivers show. Anhydrous material grows fastest at 6.3% a year as dry dosing and sorption uses expand, with Brightwell Aquatics listing anhydrous strontium chloride as the ingredient of its Strontion-P reef supplement, which Bulk Reef Supply lists at USD 22.49 for a 300 g pack. Chongqing Yuanhe Fine Chemical sells both forms from its plant in Dazu.
Why does glass and metallurgy lead while newer uses grow fastest?
Based on application, the market is categorized into glass-making and metallurgy, sea water aquaria, dental care, treatment of bone cancer and others. Glass-making and Metallurgy led with 34.0% of 2025 value because Chongqing Yuanhe Fine Chemical lists glass and magnetic material makers among the buyers of its industrial chloride, while Red Star's wider strontium salt sales show the same downstream pull, mostly through carbonate. Others, a category that covers thermal energy storage, ammonia sorbents, pigments and reagents, grows fastest at 6.4% a year as Chalmers University researchers reported 3D-printed strontium chloride monoliths in 2025.
| Segment Group | Leading Sub-segment | Share, 2025 | Fastest-growing Sub-segment | CAGR, 2026–2035 |
|---|---|---|---|---|
| By Type | Standard Grade | 63.0% | High-Purity Grade | 6.2% |
| By Form | Hexahydrate | 71.0% | Anhydrous | 6.3% |
| By Application | Glass-making and Metallurgy | 34.0% | Others | 6.4% |
Feedstock carbonate and purity set the price ladder
Strontium chloride prices follow the cost of strontium carbonate, which converters dissolve in hydrochloric acid, so the doubling of Chinese carbonate prices between late 2024 and mid-2025 fed directly into bulk chloride offers. Chinese producers quote industrial hexahydrate as negotiable with two-ton minimum orders, so bulk contract prices are not public and the bulk range below is a Credence Research estimate. Purity and pack size widen the ladder sharply, because catalog suppliers sell kilogram packs at more than 100 times the bulk price per ton, which is where reagent sellers earn most of their margin.
| Grade or reference | Typical price or fee | Basis |
|---|---|---|
| Celestite ore, Chongqing mine supply | About RMB 1,100 per metric ton | Red Star investor log, first-quarter 2026 |
| Strontium carbonate feedstock, China | RMB 8,000 to 16,000 per metric ton | Guidechem, September 2024 and June 2025 |
| Industrial hexahydrate, 99%, bulk | About USD 1,200-2,000 per metric ton | Credence Research estimate from feedstock and conversion cost |
| Reef supplement, anhydrous, 300 g | USD 22.49 per pack | Bulk Reef Supply list price for Brightwell Strontion-P, November 2026 |
| Reagent hexahydrate, 99% extra pure, 1 kg | USD 235 per kilogram | Thermo Fisher Scientific catalog, November 2026 |
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Chinese glass lines, reef dosing and Sr-89 keep demand firm
Chinese display glass and magnet lines absorb industrial grades
Industrial hexahydrate remains the volume base of this market, because Chinese glass and magnetic material makers buy it by the ton. Chongqing Yuanhe Fine Chemical lists magnetic materials, liquid crystal glass, paint and toothpaste as uses of its chloride line, which has an annual capacity of 7,500 metric tons. Red Star said in a March 2026 investor session that magnetic materials, LCD glass substrates, metal smelting and pyrotechnics are the main downstream uses of its strontium salts, a range led by carbonate. Ceramic ferrite magnets take 14% of U.S. strontium use, U.S. Geological Survey data show, although that demand runs mainly through strontium carbonate, so chloride sellers reach magnet makers only where the chloride route suits their process. Producers next to Chinese glass lines win steady multi-ton orders.
Reef aquarium dosing keeps a steady specialty outlet
Reef aquarium keepers dose strontium because corals and calcifying algae draw it down from the water along with calcium. Seachem says natural seawater holds about 8 to 10 mg/L of strontium and recommends testing and dosing until tanks reach 8 to 12 mg/L. Brightwell Aquatics uses anhydrous strontium chloride in its Strontion-P dry supplement, which shows how supplement makers buy the dry form for concentrated products. Each 5 mL dose of a liquid supplement per 80 L of water raises strontium by about 0.6 mg/L, Seachem says, so larger reef tanks consume steady volumes. Suppliers that can deliver low heavy-metal grades in small lots gain repeat business from supplement brands, which sell at retail prices far above the chemical cost.
Desensitizing toothpaste keeps qualified dental demand
Dental care remains a qualified outlet because strontium ions block exposed dentin tubules and reduce sensitivity to cold and touch. Haleon lists 10% w/w strontium chloride hexahydrate as the active ingredient of Sensodyne Original in the Middle East, where the brand claims long-lasting protection for sensitive toothpaste users. Chinese producers also market hexahydrate directly as a toothpaste desensitizing ingredient, as Chongqing Yuanhe's application list shows. Hexahydrate, the form these formulas use, held 71.0% of 2025 value. Suppliers that pass oral care audits hold multiyear contracts, because brand owners rarely requalify an active ingredient once a formula is registered.
Federal isotope supply keeps Sr-89 chloride therapy within reach
Sr-89 chloride keeps a small but high-value outlet in cancer bone pain care, because the isotope behaves like calcium and concentrates in bone metastases. The DOE Isotope Program said in May 2024 that global Sr-89 supply is declining and that it is increasing output from the High Flux Isotope Reactor at Oak Ridge National Laboratory. The program ships Sr-89 as strontium chloride in 0.1 N hydrochloric acid with radionuclidic purity above 99.8%. An Oncology Nursing Society reference sheet of December 2025 lists a standard dose of 148 MBq. Radiopharmacies that secure federal isotope supply can serve oncology centers that want a non-opioid pain option.
Energy storage tests, Chinese consolidation, new sourcing
Energy storage research shifts attention to anhydrous salt
Materials researchers are shifting toward strontium chloride as a reversible sorbent for heat and ammonia storage, because the salt takes up and releases water or ammonia at moderate temperatures. A Journal of Materials Chemistry A paper published in August 2025 tracked how strontium chloride pellets crack and change phase during hydration cycles for thermal energy storage use. Chalmers University researchers reported 3D-printed monoliths with 60% strontium chloride that stored 488 mg of ammonia per gram over 20 cycles. Both studies are at laboratory stage, so commercial volume remains unproven, and the anhydrous growth rate rests mainly on reef and reagent demand rather than on storage. Producers that can certify dry, low-impurity salt in ton lots would be first in line for pilot storage systems.
Chinese strontium salt producers consolidate under safety rules
Chinese producers are shifting toward fewer, larger plants as safety rules retire older carbonization lines. China's emergency management authorities required producers using intermittent carbonization to upgrade within a year from March 2024, and Guidechem reported that Hebei Xinji Chemical, with 60,000 metric tons of carbonate capacity, filed for bankruptcy reorganization on Oct. 21, 2024. China held about 205,000 metric tons of carbonate capacity at the end of 2024, the same report said. Chloride converters that own carbonate lines and local ore, such as the Chongqing producers, gain bargaining power over buyers that relied on smaller plants, while glass and toothpaste makers face fewer qualified sources.
High-purity grades open room in research and electronics
Laboratories, battery and electronics researchers create an opening for high-purity grades, where buyers pay for certified metal limits rather than for strontium content. ProChem lists three anhydrous grades that reach five-nines purity, which shows how far refiners now push trace metal control. Noah Chemicals sets a USD 2,500 minimum order for its custom lots, so small buyers often turn to catalog houses instead. Thermo Fisher Scientific lists a 1 kg pack of extra pure hexahydrate at USD 235, the reagent price shown in the pricing table. Producers able to certify trace metals and supply in kilogram to ton lots can capture those reagent margins.
North American buyers look for supply beyond China
U.S. buyers create an opening for non-Chinese strontium supply, because the country has mined no strontium since 1959 and stopped large-scale carbonate production in 2006, according to the U.S. Geological Survey. Defense Production Act funding announced in 2024 for domestic output of strontium nitrate, oxalate and peroxide, which serve pyrotechnics and defense uses, may lift carbonate and ore imports. Germany and Mexico supplied 51% and 41% of U.S. imports of strontium compounds from 2021 to 2024, the channel through which chloride enters the country. Chloride producers with Mexican or European feedstock can offer U.S. dental, aquarium and reagent buyers shorter and more secure supply chains than imports from Chongqing.
Carbonate price spikes and thin clinical evidence weigh
Carbonate price spikes squeeze chloride converters
Converters that buy strontium carbonate on the open market face the sharpest cost pressure in this market. The carbonate price doubling shown in the pricing table did not stop in June 2025, because spot offers in China reached RMB 18,000 to 19,000 per metric ton in August 2025, ferrite magnet maker HS Magnet reported. Small converters on fixed-price supply contracts absorb the increase until their terms reset, while integrated producers with their own ore pass it on.
Celestite supply rests on a few countries and ports
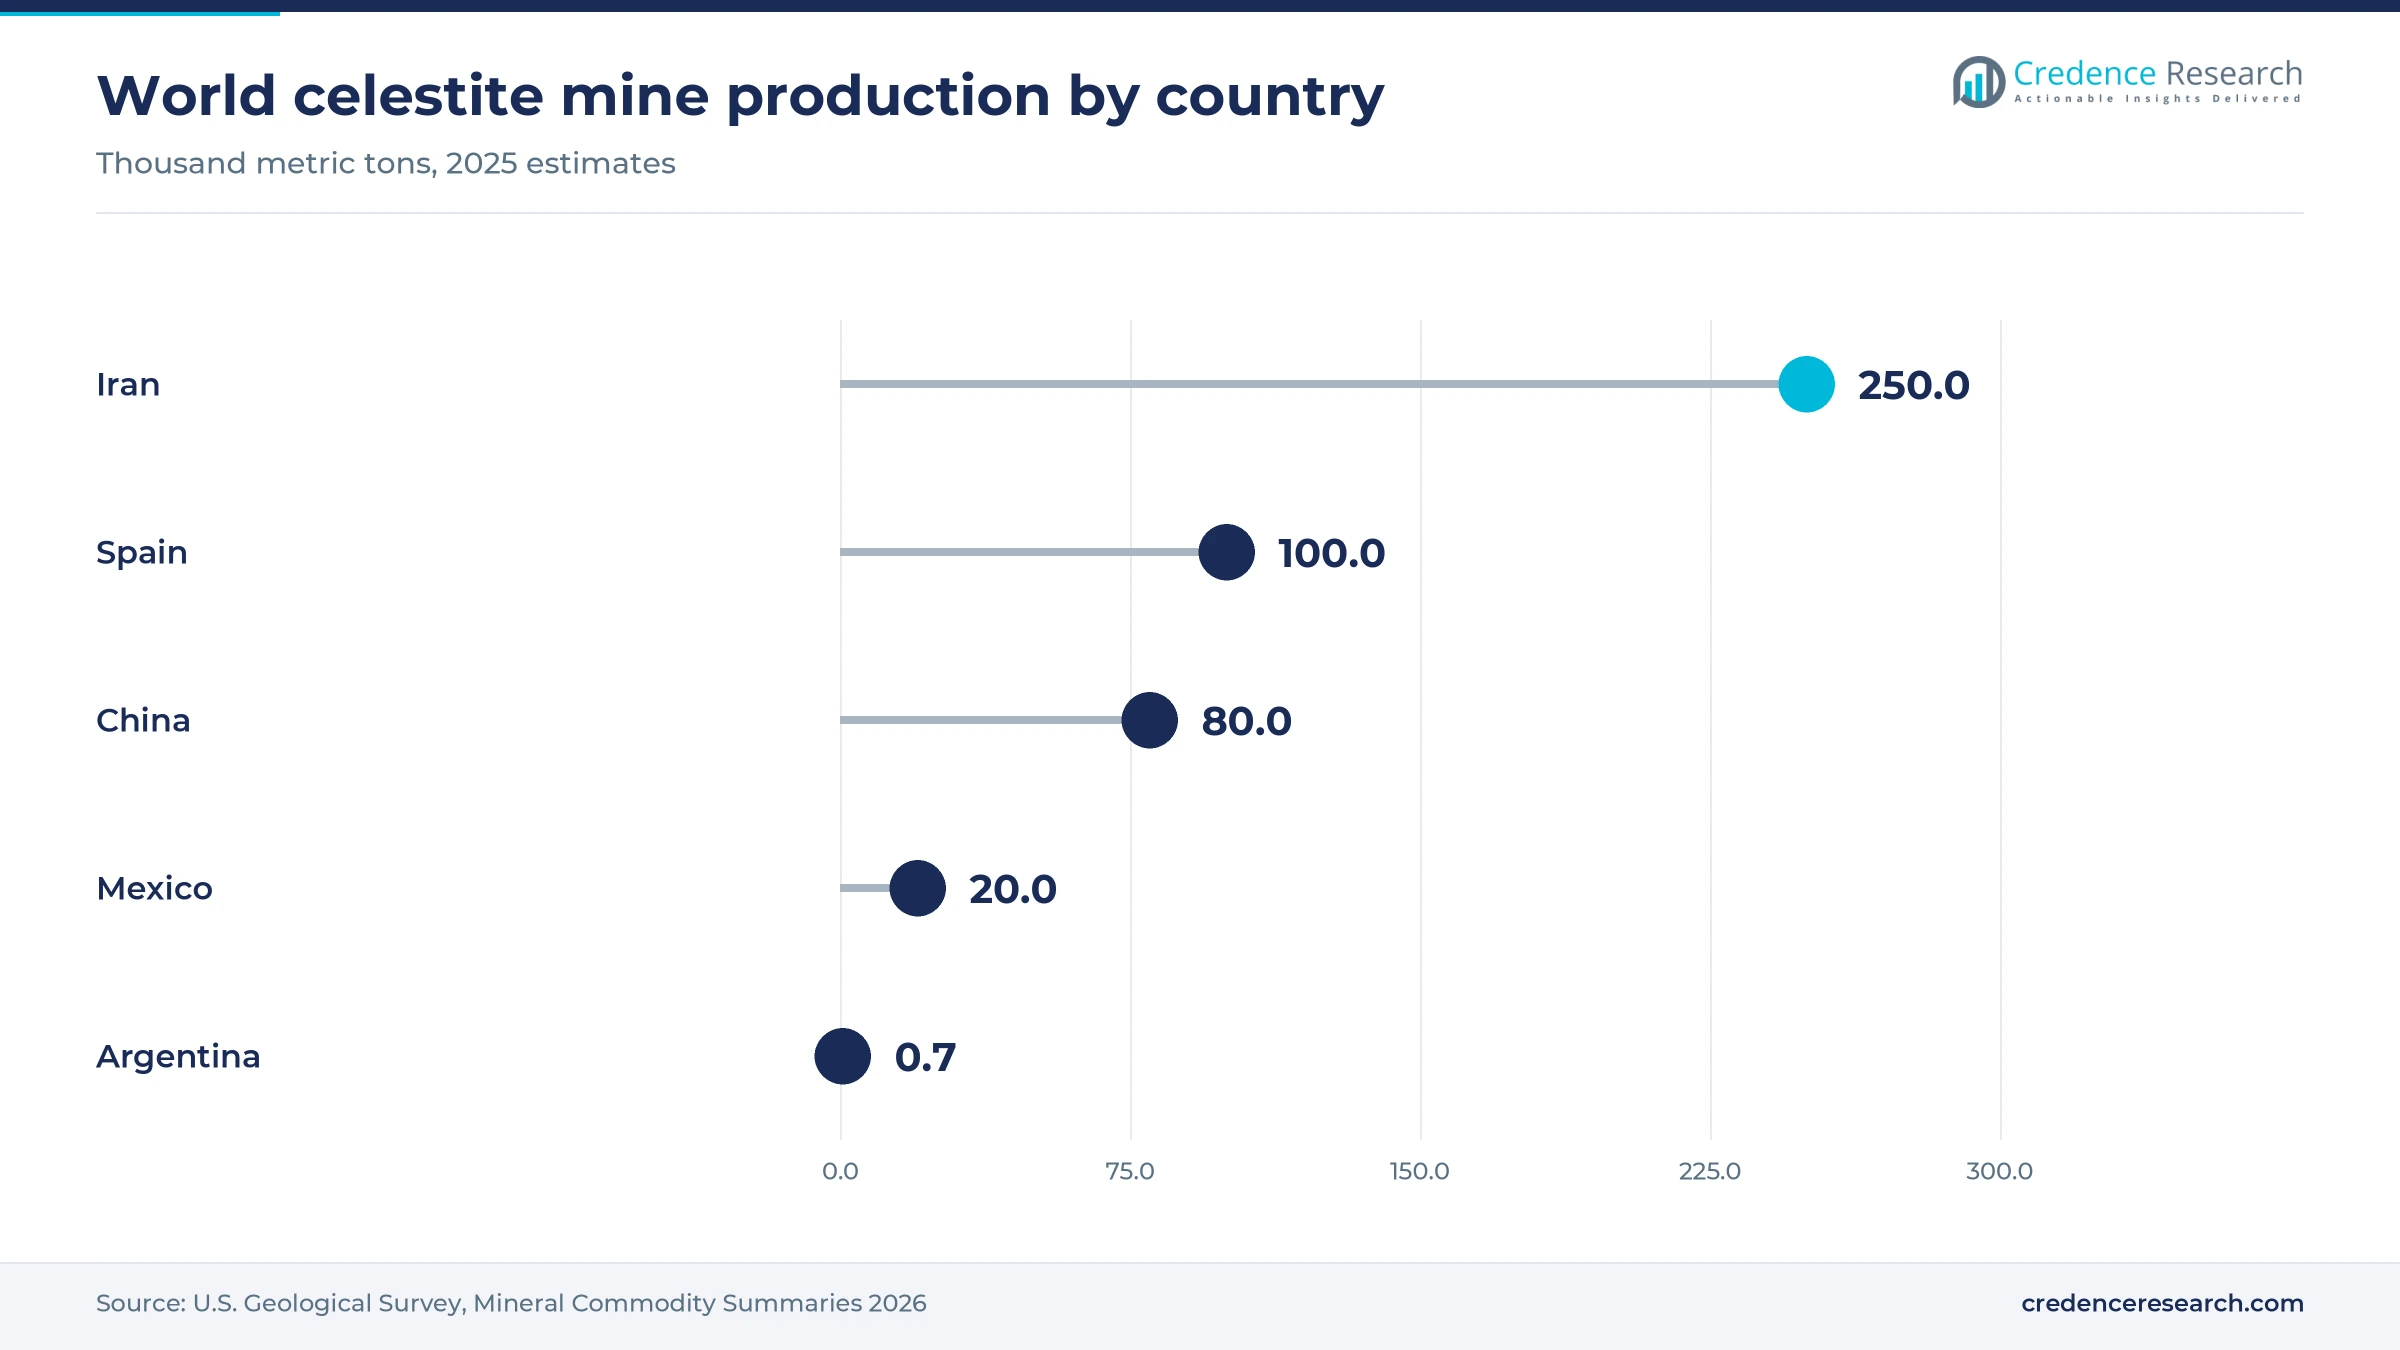
Ore supply is concentrated, which leaves chloride makers exposed to single events far from their plants. Iran supplied about 250,000 of the 450,000 metric tons of world celestite output in 2025, according to the U.S. Geological Survey, and a port explosion in Iran in April 2025 disrupted exports, Guidechem reported. Chinese converters that rely on imported high-grade ore are most exposed, while plants using local Chongqing or Spanish ore face less risk.
Thin clinical evidence and rival actives limit dental growth
Dental demand is capped because evidence for strontium desensitizers is weaker than brand claims suggest. A systematic review in the International Journal of Dentistry found only 1 strontium study among seven trials and called the evidence for both strontium and potassium salts minimal. Strontium chloride suppliers to oral care brands are most exposed, because many formulas now use potassium nitrate, stannous fluoride or strontium acetate instead.
Sr-89 drug availability stays uncertain for oncology buyers
Commercial supply of Sr-89 chloride injection is uncertain, which limits growth in the bone cancer segment. Drugs.com lists Metastron, approved on June 18, 1993, and a generic approved on Jan. 6, 2003, as discontinued and not commercially available. Hospitals that still use the therapy depend on isotope supply and on compounding capacity, while newer radiopharmaceuticals for bone metastases compete for the same oncology budgets.
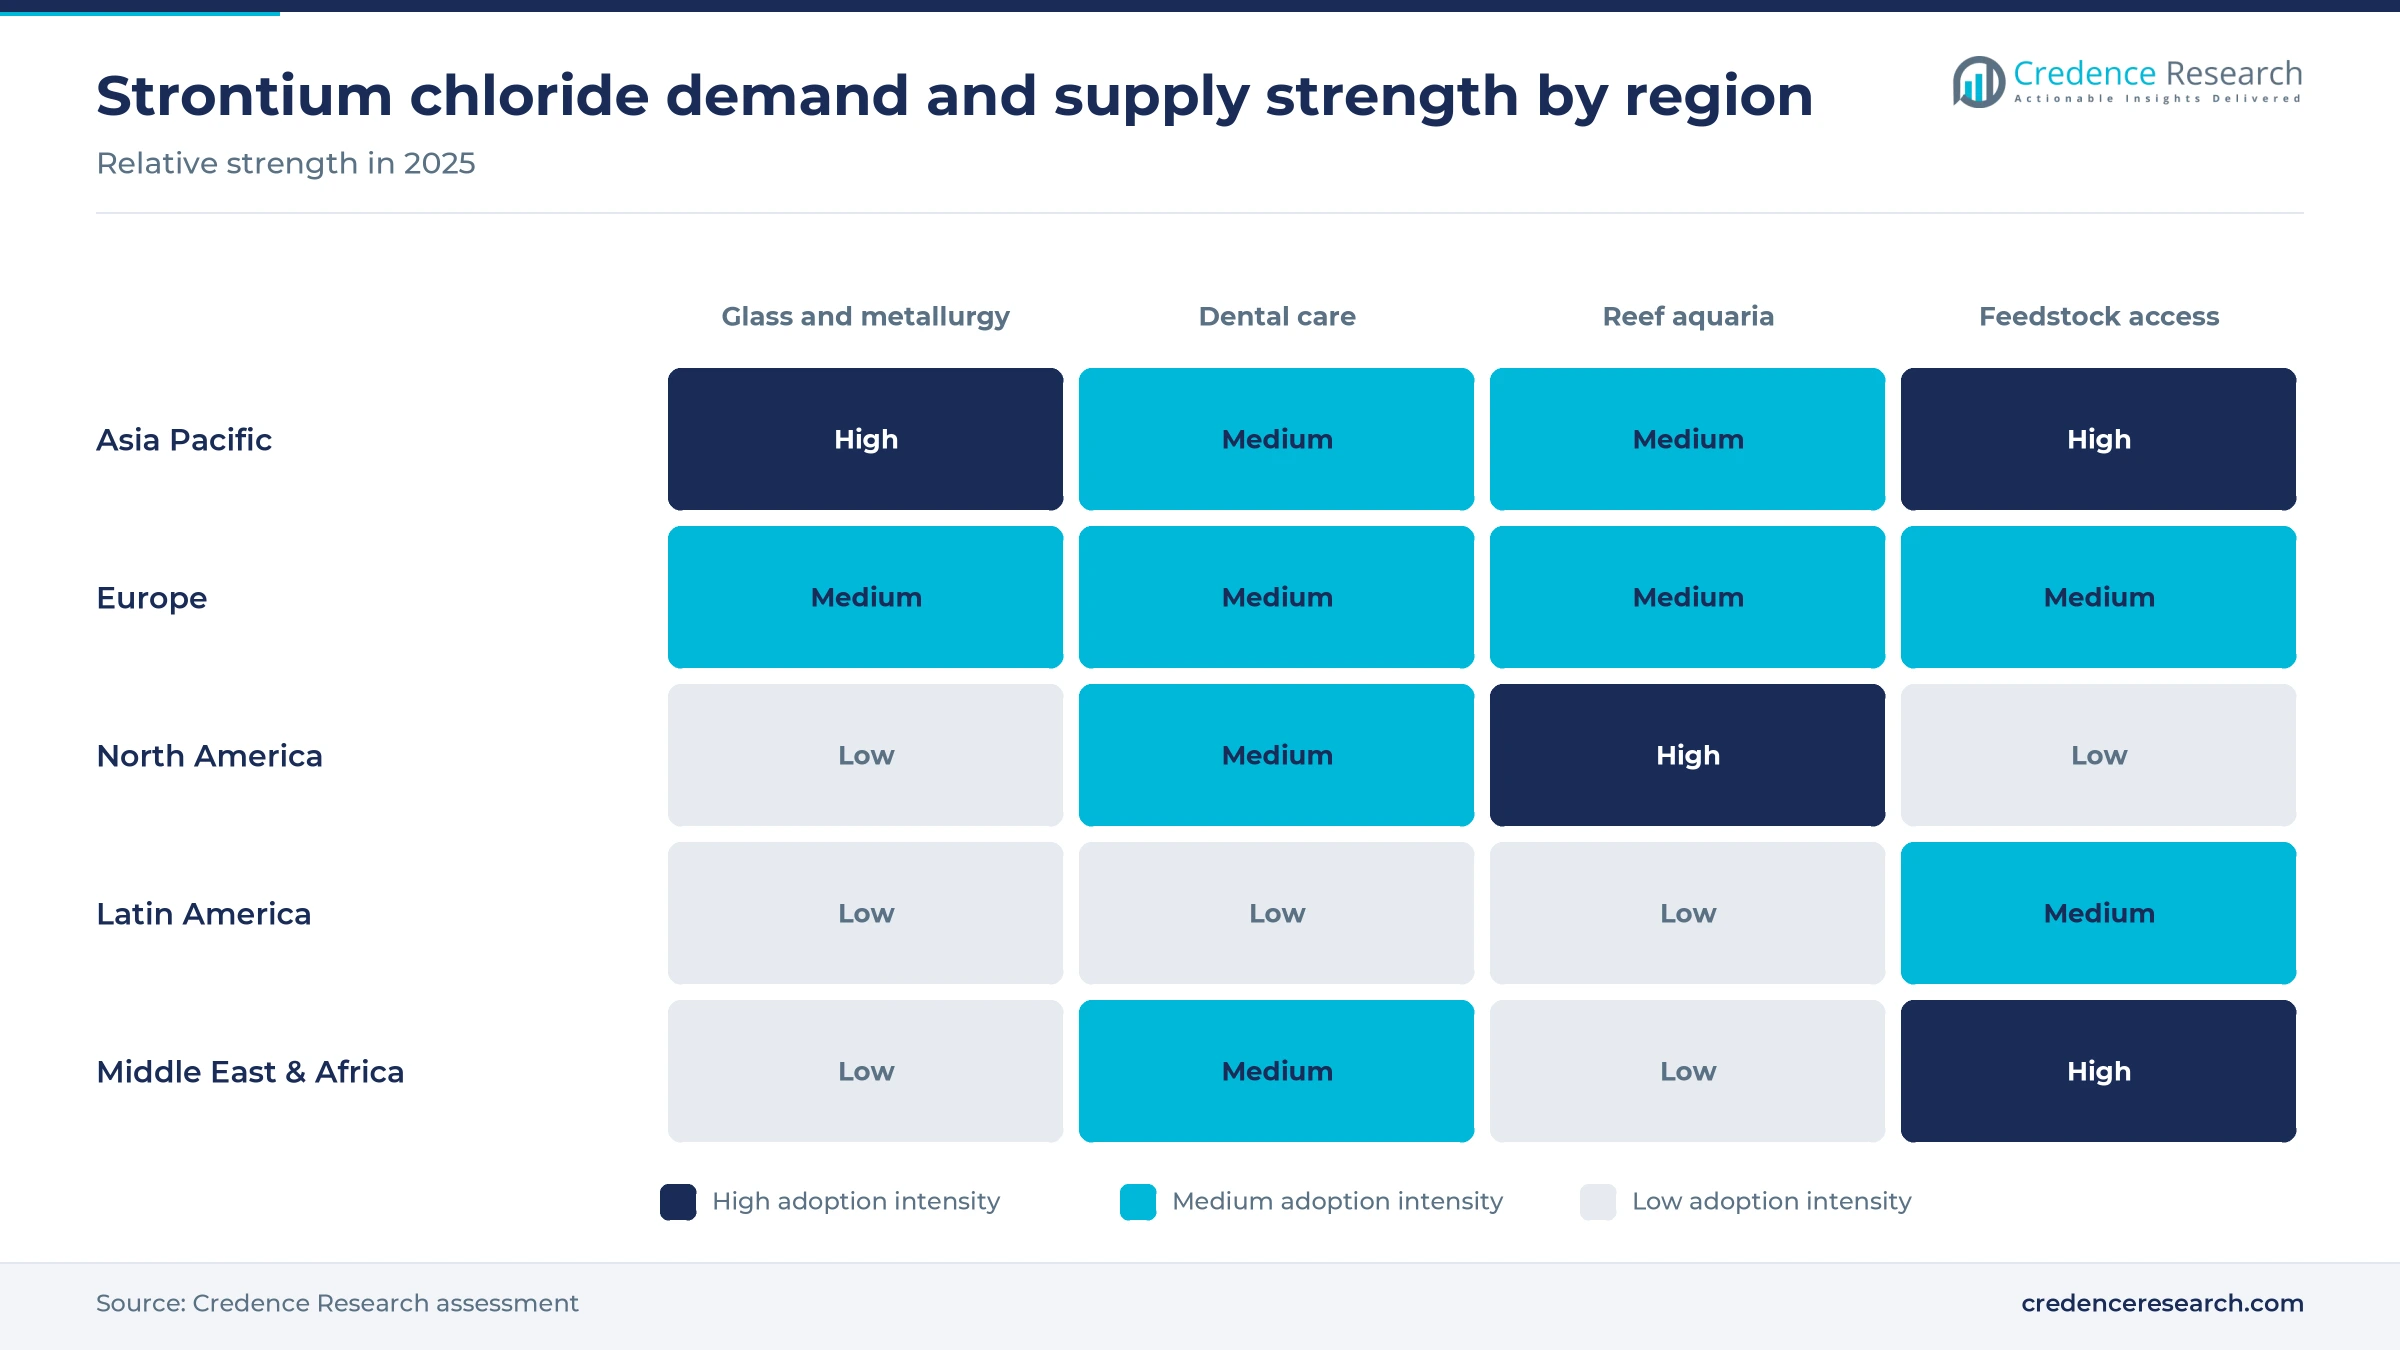
Asia Pacific leads on Chongqing salt plants and ore
| Region | Value, 2025 (USD million) | Share, 2025 | CAGR, 2026–2035 |
|---|---|---|---|
| Asia Pacific | 170.4 | 44.0% | 6.0% |
| Europe | 85.2 | 22.0% | 4.8% |
| North America | 81.3 | 21.0% | 5.0% |
| Latin America | 29.0 | 7.5% | 5.7% |
| Middle East & Africa | 21.3 | 5.5% | 5.8% |
Asia Pacific leads on Chongqing salt plants and local ore
Asia Pacific held 44.0% of 2025 value and grows fastest at 6.0% a year, because China combines celestite mining, carbonate plants and chloride converters with large glass and magnet industries. China mined about 80,000 metric tons of celestite in 2025, the U.S. Geological Survey estimates. Red Star buys celestite mostly from local Chongqing mines and prices it quarterly against carbonate and imported ore. Japanese and South Korean glass and electronics makers add demand, but no public data separate their chloride purchases from carbonate, so their weight in the regional share is a Credence Research estimate.
Europe draws on Spanish ore and German carbonate
Europe held 22.0% of 2025 value and grows at 4.8% a year, the slowest rate, because local demand rests on dental, reagent and specialty glass buyers rather than on bulk glass lines. Spain mined about 100,000 metric tons of celestite in 2025 and is the only EU producer of a material the EU listed as critical in 2020. Química del Estroncio in Cartagena has nominal capacity of 35,000 metric tons of carbonate and 6,000 metric tons of nitrate a year, and Kandelium makes carbonate in Bad Hönningen, Germany, which it supplies for uses that include chloride production.
North America imports all of its strontium
North America held 21.0% of 2025 value and grows at 5.0% a year, because the U.S. strontium market depends entirely on imports. U.S. imports of strontium compounds rose about 14% to an estimated 4,200 metric tons of strontium content in 2025, with Germany supplying 51% and Mexico 41% of compound imports from 2021 to 2024. Demand centers on dental, aquarium and reagent grades, while drilling fluids, which use celestite rather than chloride, account for 65% of U.S. strontium use, so chloride is a small part of U.S. strontium demand. Sr-89 production at Oak Ridge gives the region the only identified federal isotope source.
Latin America rides on Mexican ore and carbonate plants
Latin America held 7.5% of 2025 value and grows at 5.7% a year, because chloride demand there is small and poorly documented, while Mexico matters mainly as a feedstock supplier to North American and Chinese converters. Mexico produced about 20,000 metric tons of celestite in 2025, the U.S. Geological Survey estimates, and supplied nearly all U.S. celestite imports. A fire damaged Kandelium's Monterrey carbonate plant, with 40,000 metric tons of capacity, in 2025. No chloride converter was identified in the region, so local buyers import their chloride and this share carries a wide error range.
Middle East & Africa holds ore but little conversion
Middle East & Africa held 5.5% of 2025 value and grows at 5.8% a year, because chloride use there is small even though Iran mines the largest share of world celestite. Iranian output rose to about 250,000 metric tons in 2025 from 200,000 in 2024, but no Iranian chloride producer was identified, so that ore feeds carbonate makers abroad rather than local chloride demand. Demand comes mainly from dental care, where the Sensodyne Original formula noted in the drivers is sold in the UAE and Saudi Arabia. Public data on regional chloride consumption are thin, so the estimate rests on dental product registrations and import patterns.
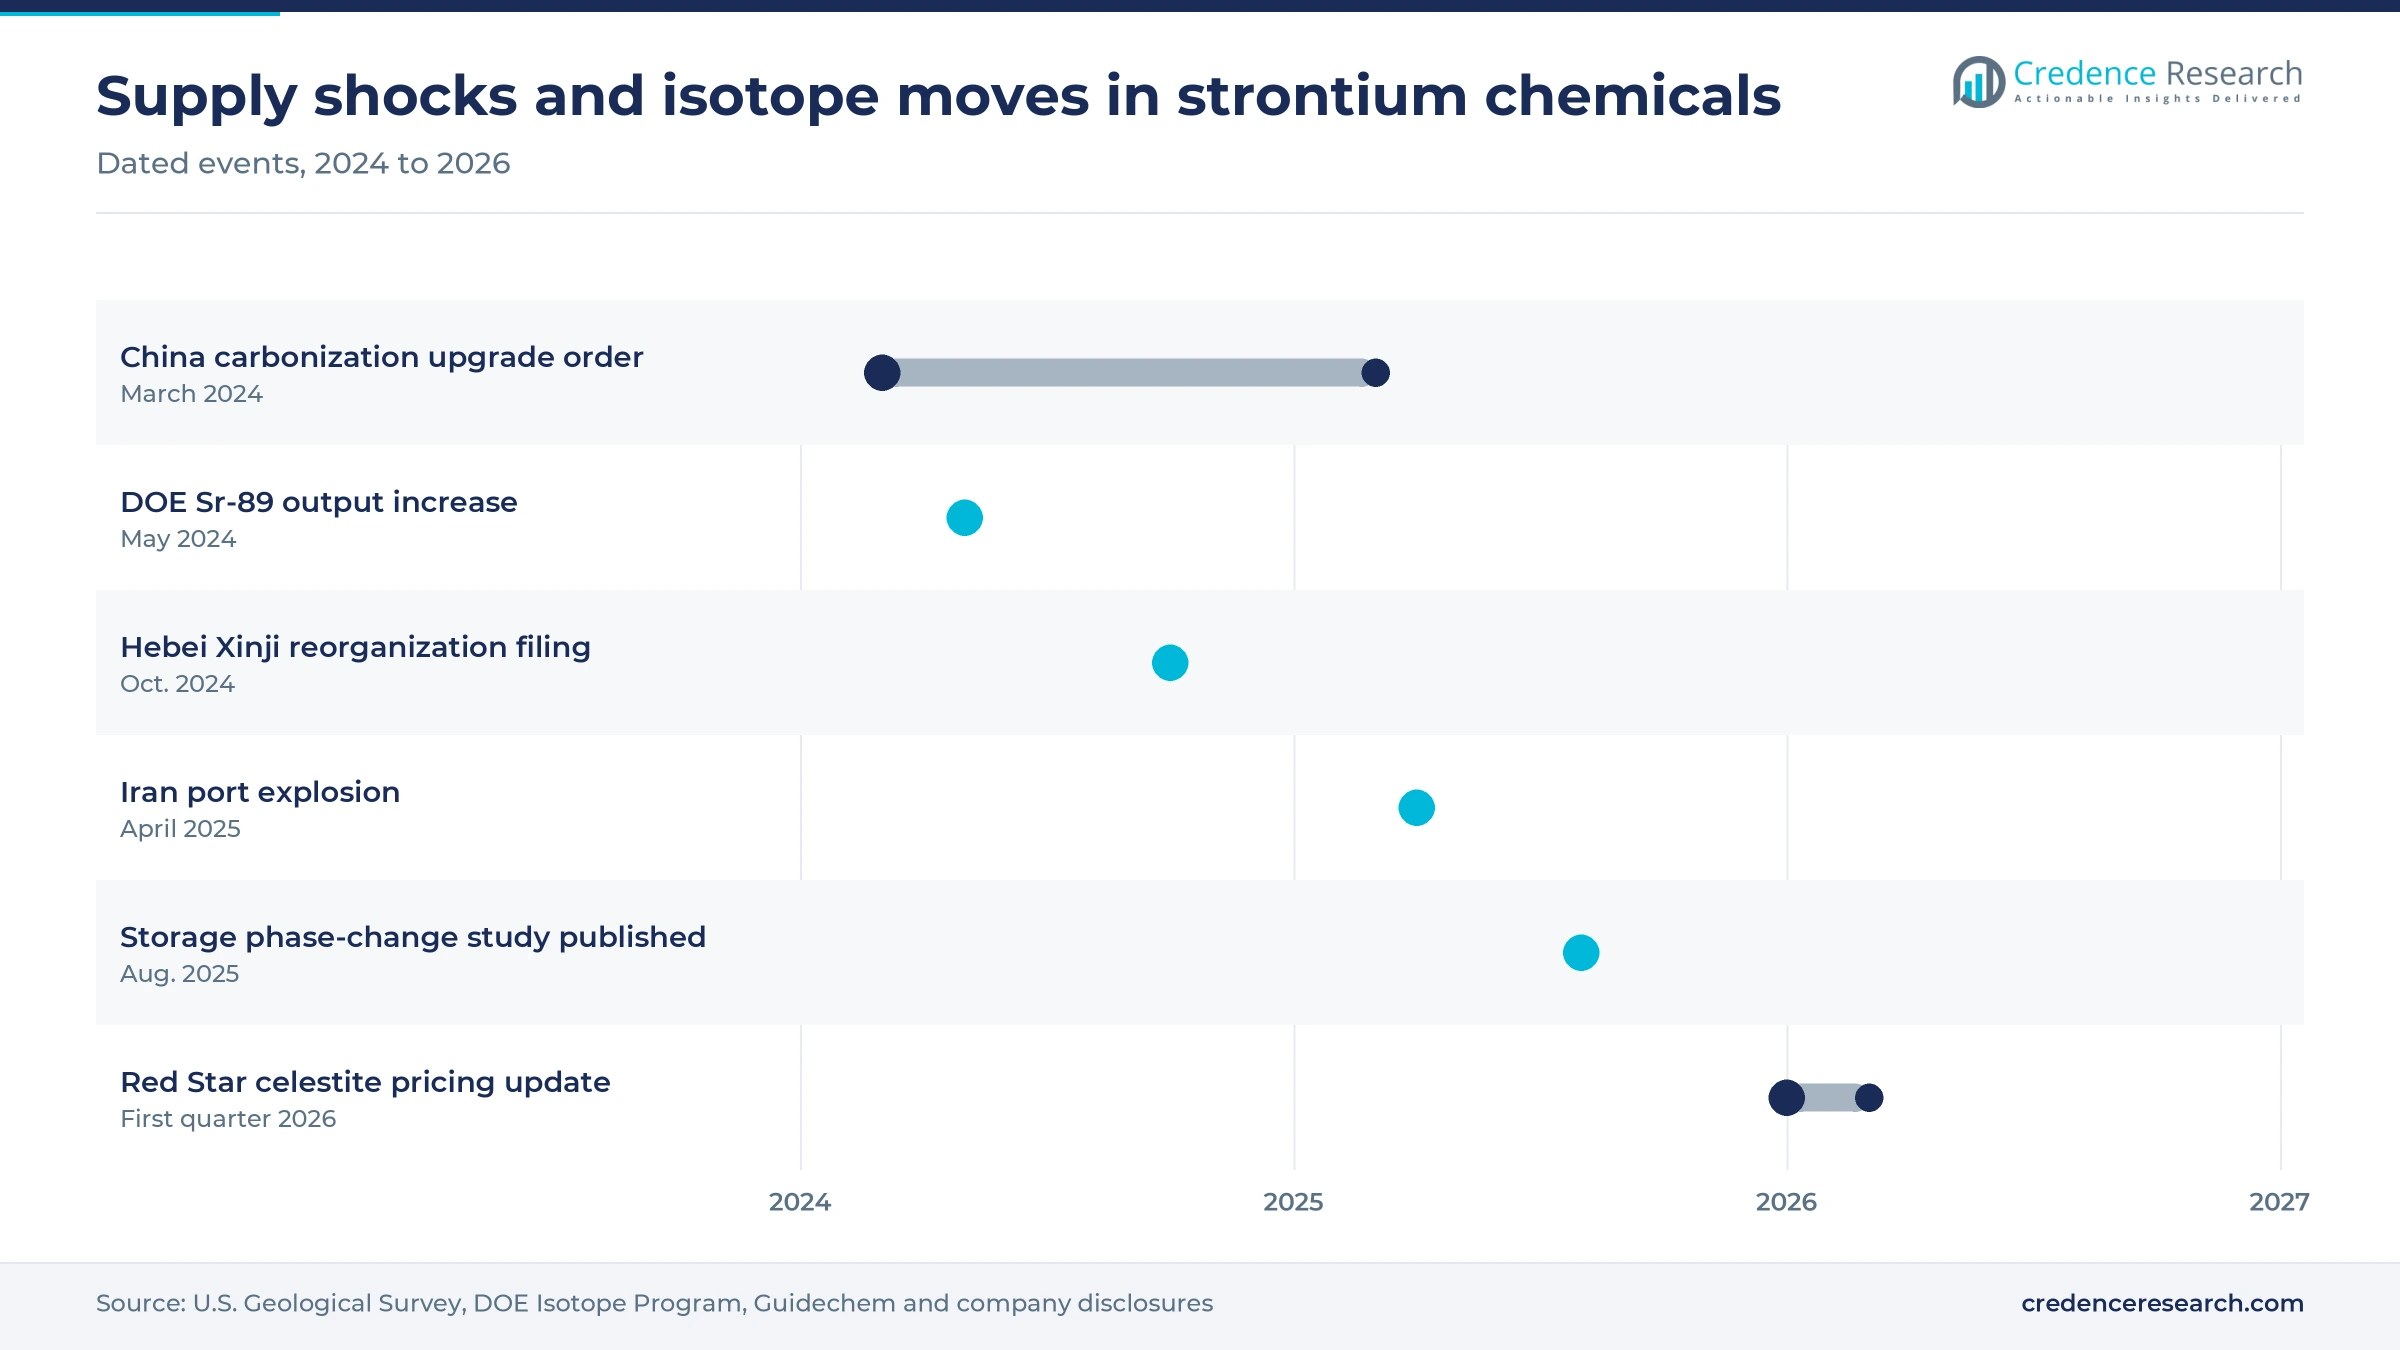
Supply shocks and isotope moves marked 2024 to 2026
| Development | Status and market relevance |
|---|---|
| In March 2024, China's emergency management authorities ordered strontium carbonate producers using intermittent carbonization to upgrade their lines within a year. | Regulatory order with a one-year deadline; it forced upgrades or shutdowns and tightened feedstock for chloride converters. |
| In May 2024, the DOE Isotope Program announced that it was increasing Sr-89 production at Oak Ridge as global supply declined. | Announced production increase; it supports continued supply of Sr-89 chloride for bone pain therapy. |
| In October 2024, Hebei Xinji Chemical, with 60,000 metric tons of strontium carbonate capacity, filed for bankruptcy reorganization. | Court filing; it placed a large Chinese carbonate supplier under court-supervised restructuring during a tight market. |
| In April 2025, an explosion at an Iranian port disrupted exports of high-grade celestite used by Chinese strontium producers. | Supply disruption, completed event; it tightened high-grade ore supply to Chinese converters. |
| In August 2025, the Journal of Materials Chemistry A published a study of how strontium chloride changes structure during hydration cycles for thermochemical energy storage. | Peer-reviewed research, laboratory stage; it maps the phase transitions that a commercial storage material would have to withstand. |
Celestite conversion and hydrochloric acid routes
- Celestite reduction or conversion turns strontium sulfate ore into carbonate, and Red Star recovers sulfur from the hydrogen sulfide its barium and strontium salt lines release.
- Hydrochloric acid dissolution reacts strontium carbonate with acid to form chloride solution, which makes carbonate cost and acid supply the largest operating inputs of a plant.
- Crystallization and drying yields hexahydrate crystals at industrial purity, while further heating removes the water to make anhydrous material for dry products and sorbents.
- Recrystallization and trace metal control lifts material to reagent and five-nines purity for laboratory, dental and research uses, where certification adds more value than tonnage.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Chinese converters and reagent houses split the market
Competition in this market turns on feedstock access, purity certification and lot size rather than on list price. Chongqing Yuanhe Fine Chemical and other Chongqing producers sell industrial hexahydrate in multi-ton lots to glass, magnet, paint and toothpaste makers. Merck KGaA through Sigma-Aldrich, Thermo Fisher Scientific and Solstice Advanced Materials sell reagent and extra pure grades in kilogram packs. American Elements, Noah Chemicals and ProChem supply high-purity and custom grades, while Anmol Chemicals serves Indian and export buyers. Solvay sold its barium and strontium business to Latour Capital under a deal announced in November 2020, and the business now operates as Kandelium, which makes the carbonate feedstock. Toothpaste and supplement brands such as Haleon and Brightwell Aquatics are buyers, not suppliers, so they are not profiled. The eight companies profiled below all sell strontium chloride directly to buyers.
How is the supply side organized and where do margins sit?
The supply side of this market has three layers with very different economics. Ore miners and carbonate makers such as Kandelium, Química del Estroncio and Red Star control the feedstock. Chinese converters such as Chongqing Yuanhe Fine Chemical dissolve carbonate in hydrochloric acid and sell industrial hexahydrate by the ton at thin margins. Reagent suppliers such as Merck, Thermo Fisher Scientific, Solstice Advanced Materials, ProChem and Noah Chemicals repack or refine smaller volumes at high prices per kilogram. Entry barriers sit in ore access, purity certification and oral care qualification.
Companies profiled and their roles in this market
| Company | Type | Role in the market |
|---|---|---|
| Chongqing Yuanhe Fine Chemical Co., Ltd. | Local manufacturer, China | Makes industrial hexahydrate and anhydrous strontium chloride in Dazu, Chongqing |
| Merck KGaA (Sigma-Aldrich) | Reagent supplier | Sells strontium chloride hexahydrate reagent grades through its Sigma-Aldrich catalog |
| Thermo Fisher Scientific Inc. | Reagent supplier | Sells hexahydrate and anhydrous strontium chloride in technical to extra pure grades |
| Solstice Advanced Materials | High-purity chemicals supplier | Sells extra pure strontium chloride hexahydrate for laboratory and industrial use |
| American Elements | Specialty materials supplier | Supplies strontium chloride solids and solutions in high-purity and custom grades |
| Noah Chemicals | Specialty inorganic supplier | Sells high-purity and ACS reagent strontium chloride hexahydrate in custom lots |
| ProChem, Inc. | Specialty inorganic supplier | Sells anhydrous strontium chloride in three purity grades up to five nines |
| Anmol Chemicals | Local manufacturer, India | Makes and exports strontium chloride in technical and pharmacopeia grades |
Ore access and purity decide who earns margin
Credence Research's view is that ore access and purity, more than end-use demand, will decide which suppliers earn margin in this market. Glass, magnet, dental and reef uses grow steadily, but the 2025 supply shocks showed how quickly feedstock costs can jump. Chinese converters with local ore can hold share in industrial grades, while reagent suppliers keep the best margins through certification and small packs. Dental and aquarium brands should qualify a second chloride source outside one province, and producers that certify anhydrous grades are best placed for storage uses.
Earlier estimate rolled forward and tested on tonnage
The report uses 2025 as the base year and forecasts to 2035. The earlier Credence Research estimate for 2024 was rolled forward one year at its own growth rate and tested against an estimate of industrial tonnage multiplied by bulk prices, plus reagent, dental, aquarium and isotope grades valued at listed prices. Regional and segment shares are Credence Research estimates based on ore and carbonate locations, converter capacity and end-use evidence. Sources include the U.S. Geological Survey, the DOE Isotope Program, company filings, catalogs and product data, peer-reviewed studies and trade press. No interviews or surveys were conducted for this update of the estimate.
Purer grades and Asian supply carry growth to 2035
Growth to 2035 depends on feedstock stability and on how fast purer grades find new uses. The base case assumes celestite and carbonate supply settles after the 2025 disruptions, so bulk chloride prices ease but stay above 2024 levels. Glass and magnet demand in China should keep industrial hexahydrate in the lead, while reef dosing and reagent buyers lift anhydrous and high-purity grades. Dental use should grow slowly as other actives compete, and energy storage research could add volume after 2030 if pilot systems prove durable.
Feedstock costs and specialty uses set the range of outcomes
The spread of outcomes depends mainly on whether celestite and carbonate supply normalizes after the 2025 shocks, and on how quickly energy storage and high-purity uses move from laboratories to commercial orders. Lasting high feedstock prices would push some dental and glass buyers toward other strontium salts or other actives. Commercial adoption of strontium chloride sorbents and steady Sr-89 supply form the main upside.
| Scenario | CAGR, 2026–2035 | Value, 2035 | What has to hold |
|---|---|---|---|
| Downside | 4.1% | USD 586.5 million | Carbonate prices stay near 2025 highs and dental formulas keep moving to other actives |
| Base | 5.50% | USD 661.4 million | Ore supply normalizes and glass, reef and reagent demand grows steadily |
| Upside | 6.6% | USD 726.1 million | Sorption storage reaches pilot orders and Sr-89 chloride supply widens in oncology |
Frequently Asked Questions
How big is the strontium chloride market?
What is strontium chloride used for?
Which application holds the largest share?
How large is the U.S. strontium market?
What does a strontium chloride production plant need?
Which region leads the market?
What restrains the strontium chloride market?
Who are the main strontium chloride suppliers?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Standard Grade
- 1.2.2 High-Purity Grade
- 1.3 By Form
- 1.3.1 Hexahydrate
- 1.3.2 Anhydrous
- 1.4 By Application
- 1.4.1 Glass-making and Metallurgy
- 1.4.2 Dental Care
- 1.4.3 Sea Water Aquaria
- 1.4.4 Treatment of Bone Cancer
- 1.4.5 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2025: USD 387.2 million → 2035: USD 661.4 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Historical Period: 2018-2025
- 2.6.2 Base Year: 2025
- 2.6.3 Forecast Period: 2025-2035
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2025
- 3.3 Forecast Market Size, 2035
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Strontium Chloride Market Trends and Developments
- 4.1 Historical Industry Development, 2018-2025
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Strontium Chloride Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis, 2018-2025
- 5.2 Demand Forecast, 2025-2035
- 5.3 Production and Output Trend, 2018-2025
- 5.4 Production and Output Forecast, 2025-2035
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Strontium Chloride Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends, 2018-2025
- 6.3 Pricing Outlook, 2025-2035
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Strontium Chloride Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Strontium Chloride Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Strontium Chloride Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Strontium Chloride Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Strontium Chloride Market Outlook, 2025-2035
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2025: USD 387.2 million → 2035: USD 661.4 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size, 2018-2025
- 11.1.4 Base-Year Market Size, 2025
- 11.2 Market Forecast, 2025-2035
- 11.2.1 Revenue Forecast to 2035
- 11.2.2 Volume Forecast to 2035
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Strontium Chloride Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2025
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2025-2035
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size, 2018-2025
- 12.3.3 Revenue Forecast, 2025-2035
- 12.3.4 Volume Forecast, 2025-2035
- 12.3.5 Base-Year Market Share, 2025
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Standard Grade
- 12.3.7.2 High-Purity Grade
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Form - Market Size and Forecast, 2025-2035
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size, 2018-2025
- 12.4.3 Revenue Forecast, 2025-2035
- 12.4.4 Volume Forecast, 2025-2035
- 12.4.5 Base-Year Market Share, 2025
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Hexahydrate
- 12.4.7.2 Anhydrous
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2025-2035
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size, 2018-2025
- 12.5.3 Revenue Forecast, 2025-2035
- 12.5.4 Volume Forecast, 2025-2035
- 12.5.5 Base-Year Market Share, 2025
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Glass-making and Metallurgy
- 12.5.7.2 Dental Care
- 12.5.7.3 Sea Water Aquaria
- 12.5.7.4 Treatment of Bone Cancer
- 12.5.7.5 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Strontium Chloride End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Strontium Chloride Geographic Market Outlook, 2025-2035
- 14.1 Regional Market Size and Share, 2025
- 14.2 Regional Market Forecast, 2025-2035
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Strontium Chloride Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2025-2035
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Strontium Chloride Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2025
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2025-2035
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Chongqing Yuanhe Fine Chemical Co., Ltd.
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Merck KGaA (Sigma-Aldrich)
- 18.4 Thermo Fisher Scientific Inc.
- 18.5 Solstice Advanced Materials
- 18.6 American Elements
- 18.7 Noah Chemicals
- 18.8 ProChem, Inc.
- 18.9 Anmol Chemicals
- 18.10 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

