
Safety studies and biologics programs anchor regional demand
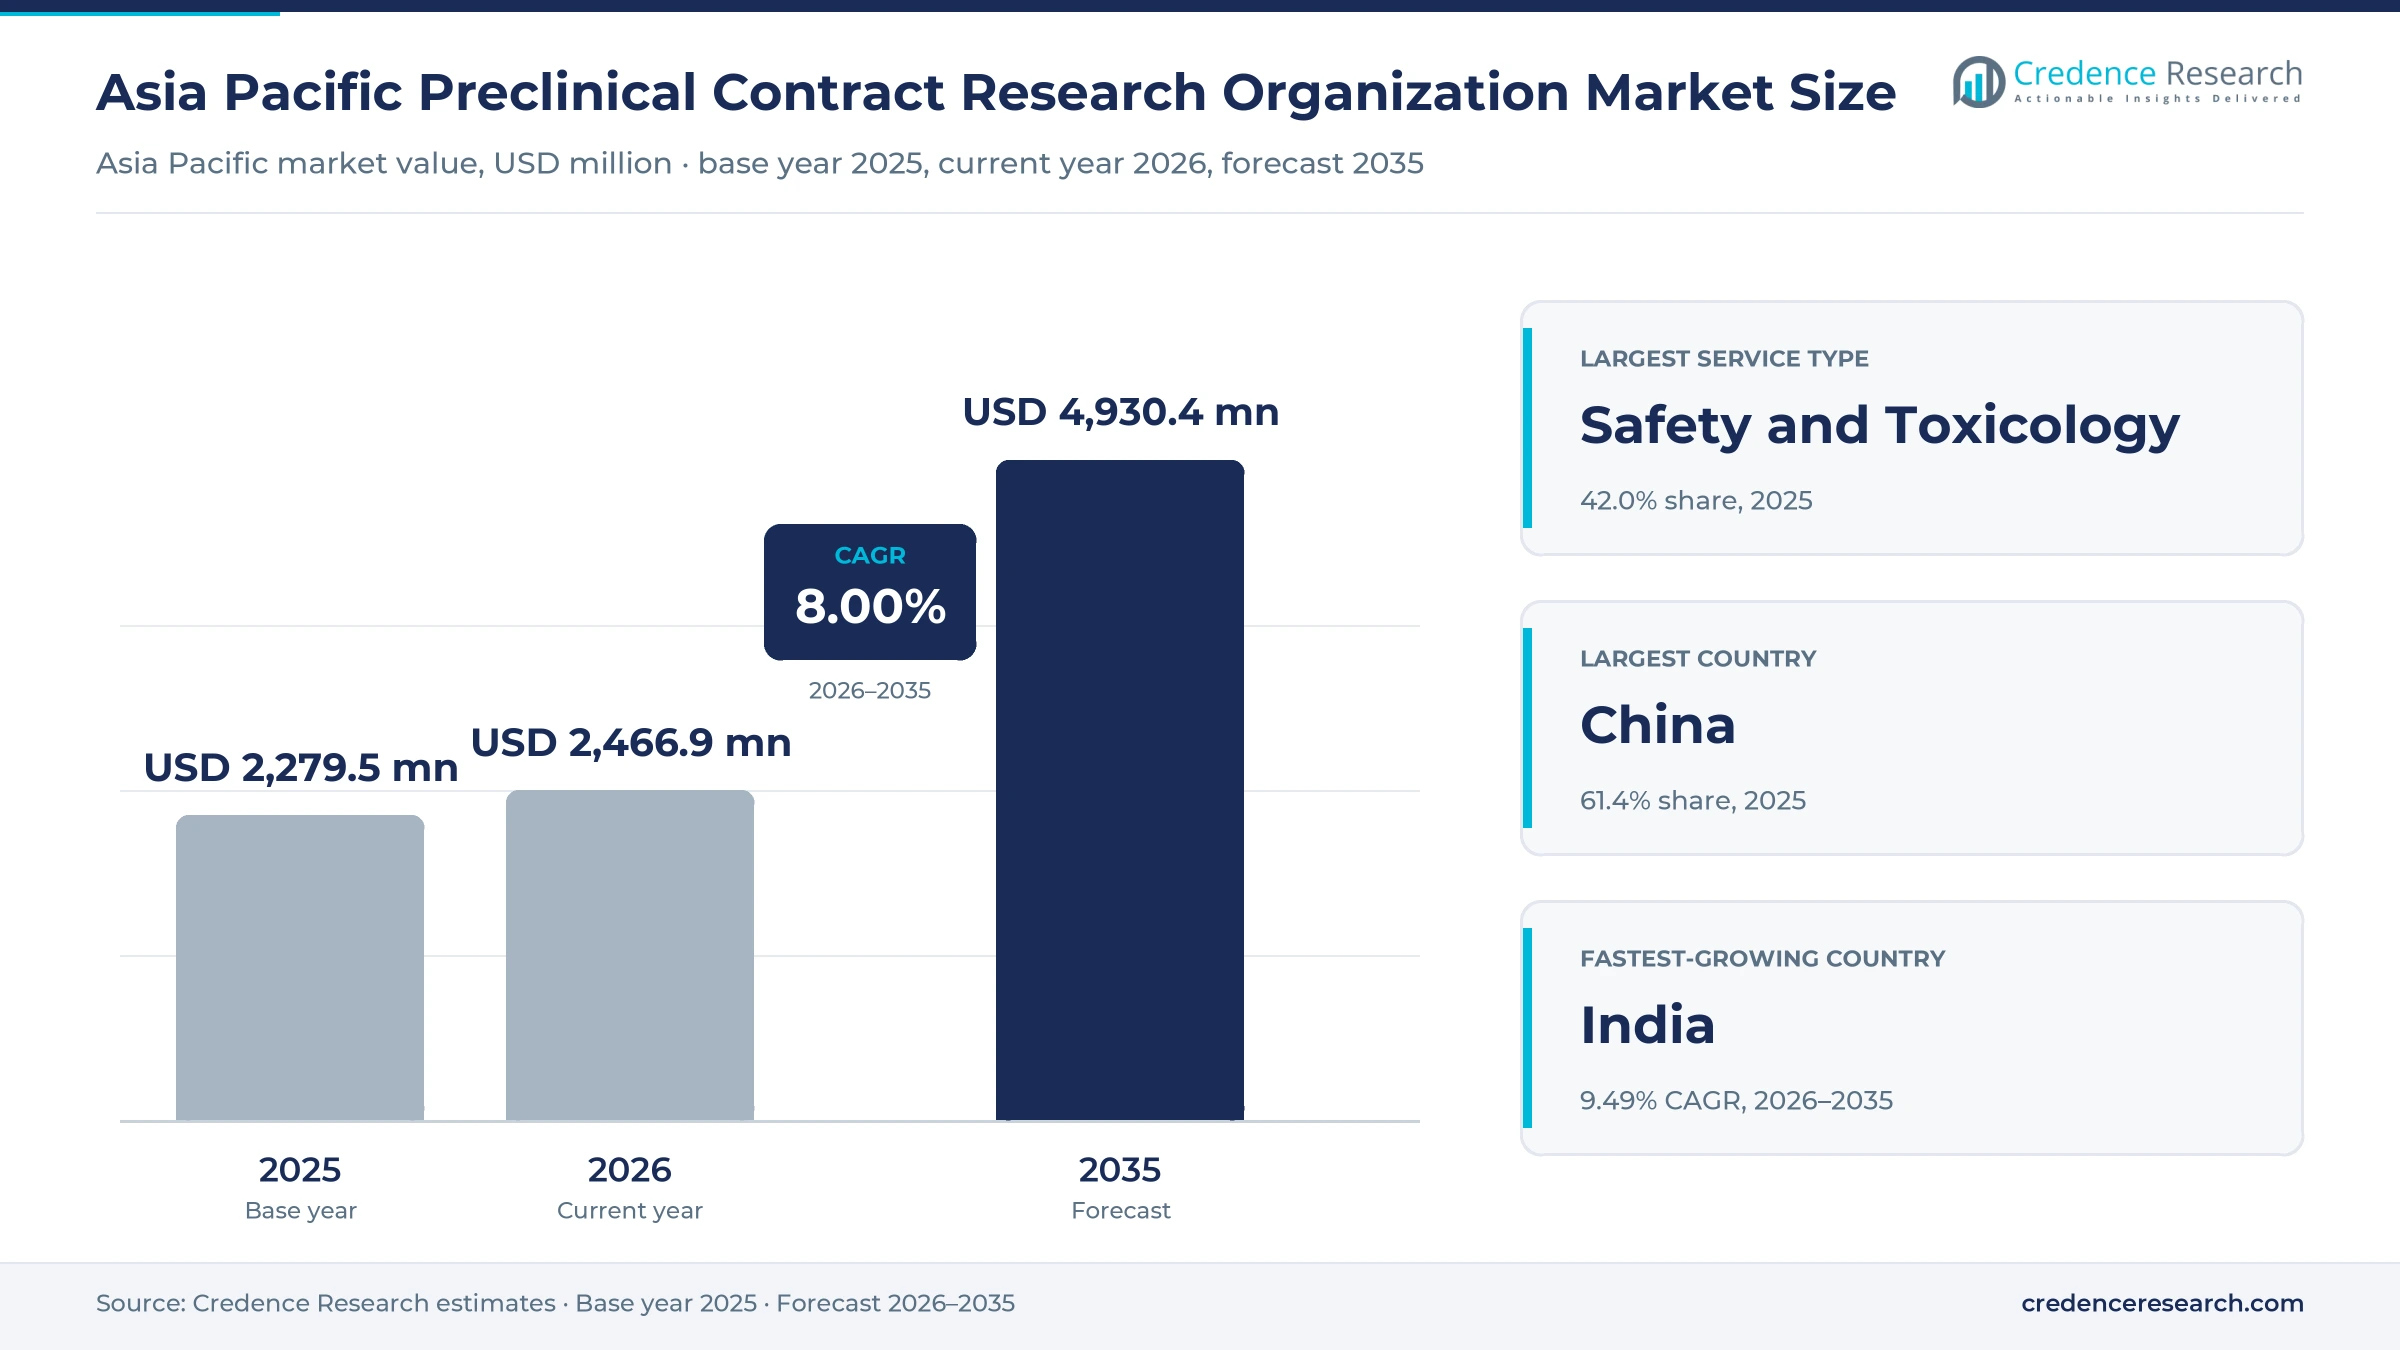
The Asia Pacific preclinical contract research organization market was valued at USD 2.28 billion in 2025 and is projected to increase from USD 2.47 billion in 2026 to USD 4.93 billion by 2035, registering a CAGR of 8.00% during 2026–2035. Demand comes from drug developers that send toxicology, pharmacokinetic and pharmacology studies to laboratories in China, India, Japan and South Korea, where animal capacity, scientific staff and costs suit large study programs. China held the largest country share, 61.4% in 2025, because its integrated laboratory groups run the most GLP toxicology capacity and serve both domestic and Western sponsors. India is the fastest-growing country at 9.49% a year, as its GLP facilities produce data accepted across OECD members. Regulation is also changing study design, and the U.S. Food and Drug Administration published a roadmap in April 2025 to reduce animal testing in preclinical safety studies.
Which preclinical studies and sponsors does the regional estimate cover?
The estimate measures fees paid to contract research organizations for safety and toxicology, DMPK and ADME, safety pharmacology and discovery biology studies performed at laboratories in the Asia-Pacific region. Sponsors buy these studies through fee-for-service contracts, dedicated full-time-equivalent teams and milestone-based agreements, either directly or through a lead CRO that subcontracts part of the work.
The estimate excludes clinical trial services, drug manufacturing, chemistry-only synthesis contracts and studies that sponsors run in their own laboratories. The value chain runs from animal breeders, reagent suppliers and instrument makers through GLP and non-GLP test facilities to regulators that review the resulting data in China, Japan, South Korea, India, Australia and export markets.
Asia Pacific Preclinical Contract Research Organization Market Insights
- The Asia Pacific preclinical contract research organization market was valued at USD 2.28 billion in 2025 and is projected to reach USD 4.93 billion by 2035, registering a CAGR of 8.00% during 2026–2035.
- China held a 61.4% share of 2025 value, because its integrated groups run the largest GLP toxicology and primate study capacity in the region.
- Safety and toxicology led service demand with a 42.0% share of 2025 value, because every investigational new drug filing needs repeat-dose and genetic toxicity data.
- China's drug regulator issued Announcement No. 86 on Sept. 9, 2025, setting a 30-working-day review for clinical trial applications of eligible innovative drugs.
- The BIOSECURE Act became U.S. law on Dec. 18, 2025, which pushes Western sponsors to qualify second laboratory suppliers across the region.
Safety and toxicology lead while discovery biology rises
Why does safety and toxicology lead service demand?
Based on service type, the market is categorized into safety and toxicology, DMPK and ADME, safety pharmacology and discovery biology. Safety and Toxicology led with a 42.0% share of 2025 value, because repeat-dose, genetic and reproductive toxicity studies are mandatory before first-in-human dosing. Discovery Biology grows fastest at 8.55% a year, as biotech sponsors outsource disease models and in vivo pharmacology earlier in their programs.
How do biotech and pharma sponsors divide customer demand?
Based on customer type, the market is categorized into established pharmaceutical sponsors, biotechnology sponsors and academic and public research sponsors. Established Pharmaceutical Sponsors led with a 46.0% share of 2025 value, because large companies place multi-study programs under long framework agreements. Biotechnology Sponsors grow fastest at 8.74% a year, as venture-funded companies in China, South Korea and Japan lack in-house animal facilities.
Why does oncology lead application demand?
Based on application, the market is categorized into oncology, neurological disorders, cardiometabolic disorders and infectious and immune disorders. Oncology led with a 40.0% share of 2025 value, because antibody, antibody-drug conjugate and cell therapy pipelines in the region focus heavily on solid tumors. Cardiometabolic Disorders grow fastest at 8.82% a year, as obesity and diabetes programs move into safety testing.
How does GLP status shape delivery model demand?
Based on delivery model, the market is categorized into GLP study delivery, non-GLP study delivery and mixed GLP program delivery. GLP Study Delivery led with a 48.0% share of 2025 value, because pivotal toxicology studies submitted to regulators must follow good laboratory practice. Mixed GLP Program Delivery grows fastest at 8.60% a year, as sponsors buy screening and pivotal studies as one package.
| Segment Group | Leading Sub-segment | Share, 2025 | Fastest-growing Sub-segment | CAGR, 2026–2035 |
|---|---|---|---|---|
| By Service Type | Safety and Toxicology | 42.0% | Discovery Biology | 8.55% |
| By Customer Type | Established Pharmaceutical Sponsors | 46.0% | Biotechnology Sponsors | 8.74% |
| By Application | Oncology | 40.0% | Cardiometabolic Disorders | 8.82% |
| By Delivery Model | GLP Study Delivery | 48.0% | Mixed GLP Program Delivery | 8.60% |
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Complex modalities and globally accepted GLP data
How does complex therapeutic development lift study volumes?
Antibodies, conjugates and nucleic acid drugs need longer, species-specific safety programs than small molecules, so their growth drives outsourced study demand across the region. JOINN Laboratories reported that antibody-related contracts rose 20% and small nucleic acid and ADC contracts rose more than 50% in the first half of 2025, The Bamboo Works reported. The same publisher noted that more than 70% of large-molecule drugs need monkeys in preclinical testing. China's drug regulator also approved 48 first-in-class innovative drugs in 2024, up from 40 in 2023, according to an NMPA report published in March 2025. As a result, safety and toxicology work holds a 42.0% share of 2025 value, the largest among service types.
Why does internationally usable laboratory evidence matter?
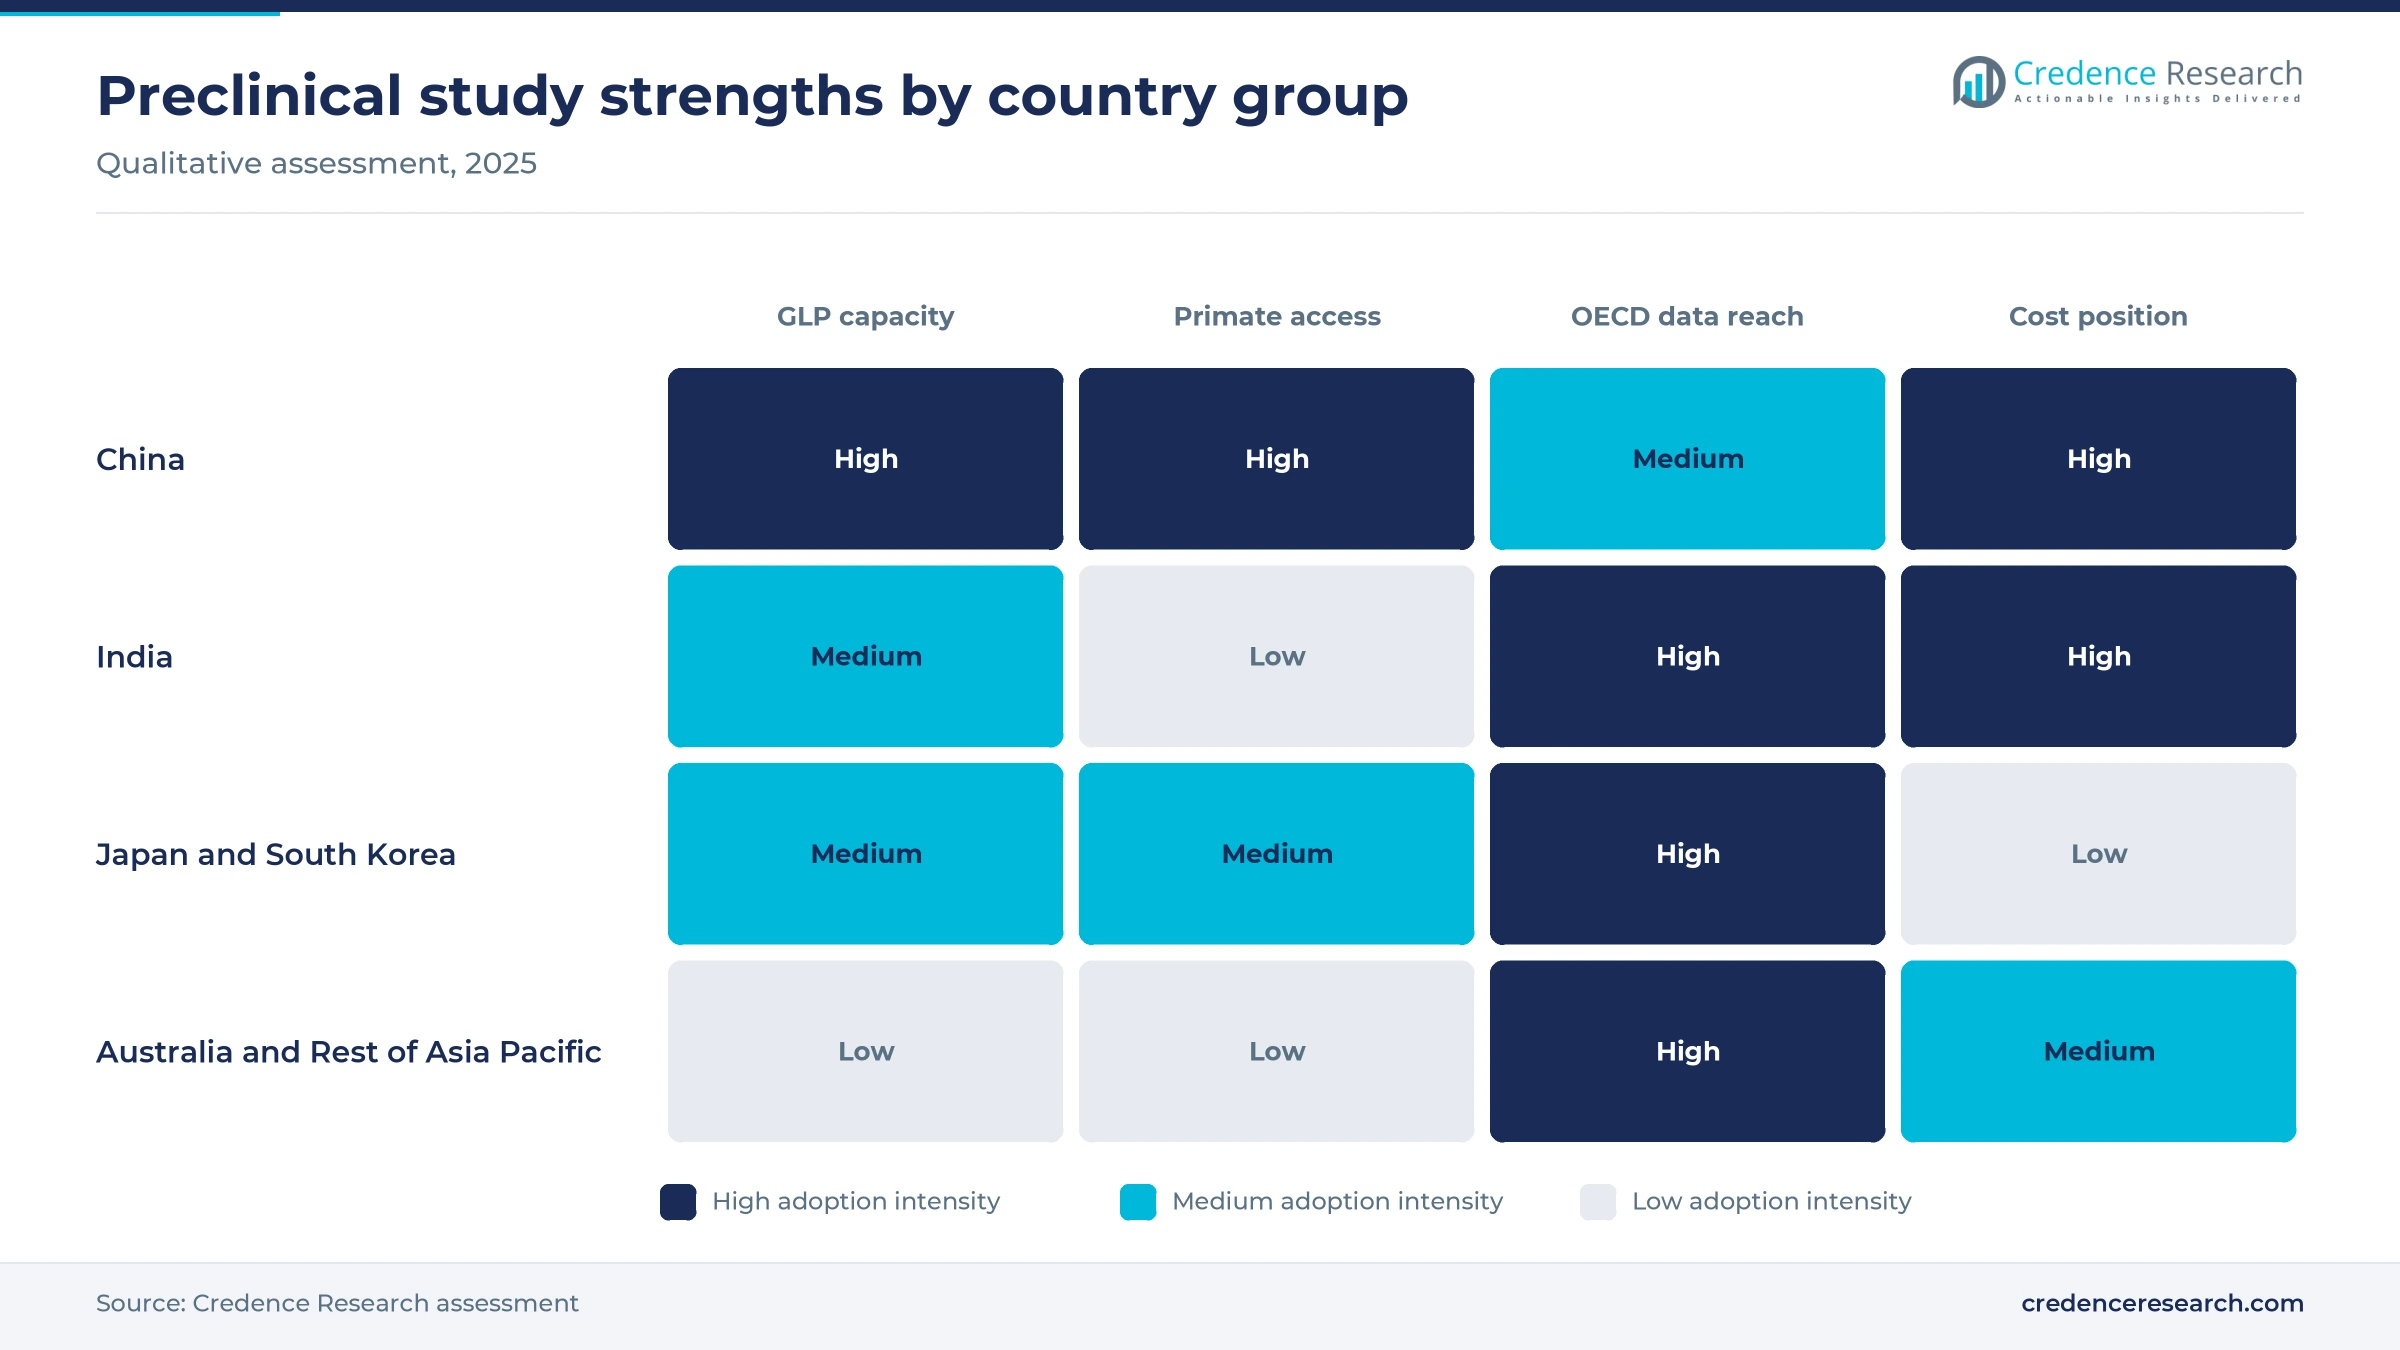
Internationally usable laboratory evidence matters, because sponsors only outsource pivotal studies to laboratories whose data regulators in the United States, Europe and Japan will accept. India, Malaysia, Singapore and Thailand are full adherents to the OECD Mutual Acceptance of Data system, so GLP studies run there are accepted across member countries. India's national GLP authority listed 58 certified test facilities on its Oct. 3, 2025 register, including Syngene, Jubilant Biosys and Aurigene. WuXi AppTec said in March 2026 that its Suzhou and Shanghai testing facilities passed multiple FDA, OECD, NMPA and PMDA inspections. In turn, GLP study delivery holds a 48.0% share of 2025 value.
Why are sponsors qualifying a second laboratory?
Western sponsors now want a second qualified laboratory outside a single country, which spreads demand across more providers in the region. The BIOSECURE Act became law on Dec. 18, 2025, inside the fiscal 2026 defense bill, and the White House budget office must publish a full list of covered companies by Dec. 18, 2026, Latham & Watkins reported. Shin Nippon Biomedical Laboratories reported that overseas orders rose to 43.4% of its nonclinical intake in the year to March 2026, up from 38.4%. Pharmaron added more than 950 new customers in 2025, which shows how widely sponsors now spread study work. As a result, laboratories in Japan and India with accepted GLP data win a larger part of second-supplier programs.
Why do faster clinical trial reviews in China pull studies forward?
Sponsors must finish safety packages before they can use shorter filing windows, so quicker trial reviews in China move preclinical study demand earlier in each program. The National Medical Products Administration issued Announcement No. 86 on Sept. 9, 2025, setting a 30-working-day review for eligible innovative drug trial applications. Priority review in China also cuts the standard 200-working-day limit to 130 days, according to the same regulator's March 2025 report. WuXi AppTec counted 2,901 molecules in Phase I or preclinical stages in its small-molecule pipeline at the end of 2025. Consequently, Chinese laboratories capture most of the growth in domestic safety packages for these programs.
Non-animal methods and primate costs reshape study design
Shift toward non-animal methods in safety packages
A shift toward non-animal methods is changing how safety packages are designed, because regulators now invite human-relevant data alongside animal studies. The U.S. Food and Drug Administration announced on April 10, 2025 a plan to reduce, refine or replace animal testing for monoclonal antibodies and other drugs. India amended its New Drugs and Clinical Trials Rules in 2023 to allow organoids, organ-on-chip models and computational methods, Business Today reported in February 2026. A landscape report released in India on Feb. 5, 2026, said validated non-animal methods can cut development costs by 70% to 90% in some product areas. As a result, demand for organ-on-chip systems rises inside regional contract laboratories.
Rising primate costs reshape biologics study budgets
Rising primate costs are reshaping biologics study budgets, because monkeys remain the main test species for antibodies and many conjugates. Cynomolgus monkey prices in China rose from about 80,000 yuan at the start of 2025 to more than 130,000 yuan by year-end, The Bamboo Works reported after the year closed. JOINN Laboratories holds a reserve of roughly 25,000 laboratory monkeys, which gives it a supply advantage when prices climb. Shin Nippon Biomedical Laboratories breeds its own primates in Kagoshima and reported record nonclinical order intake in the year to March 2026. As a result, sponsors pair smaller animal studies with in vitro toxicology assays to control costs.

Japan drug-loss policy opens nonclinical work
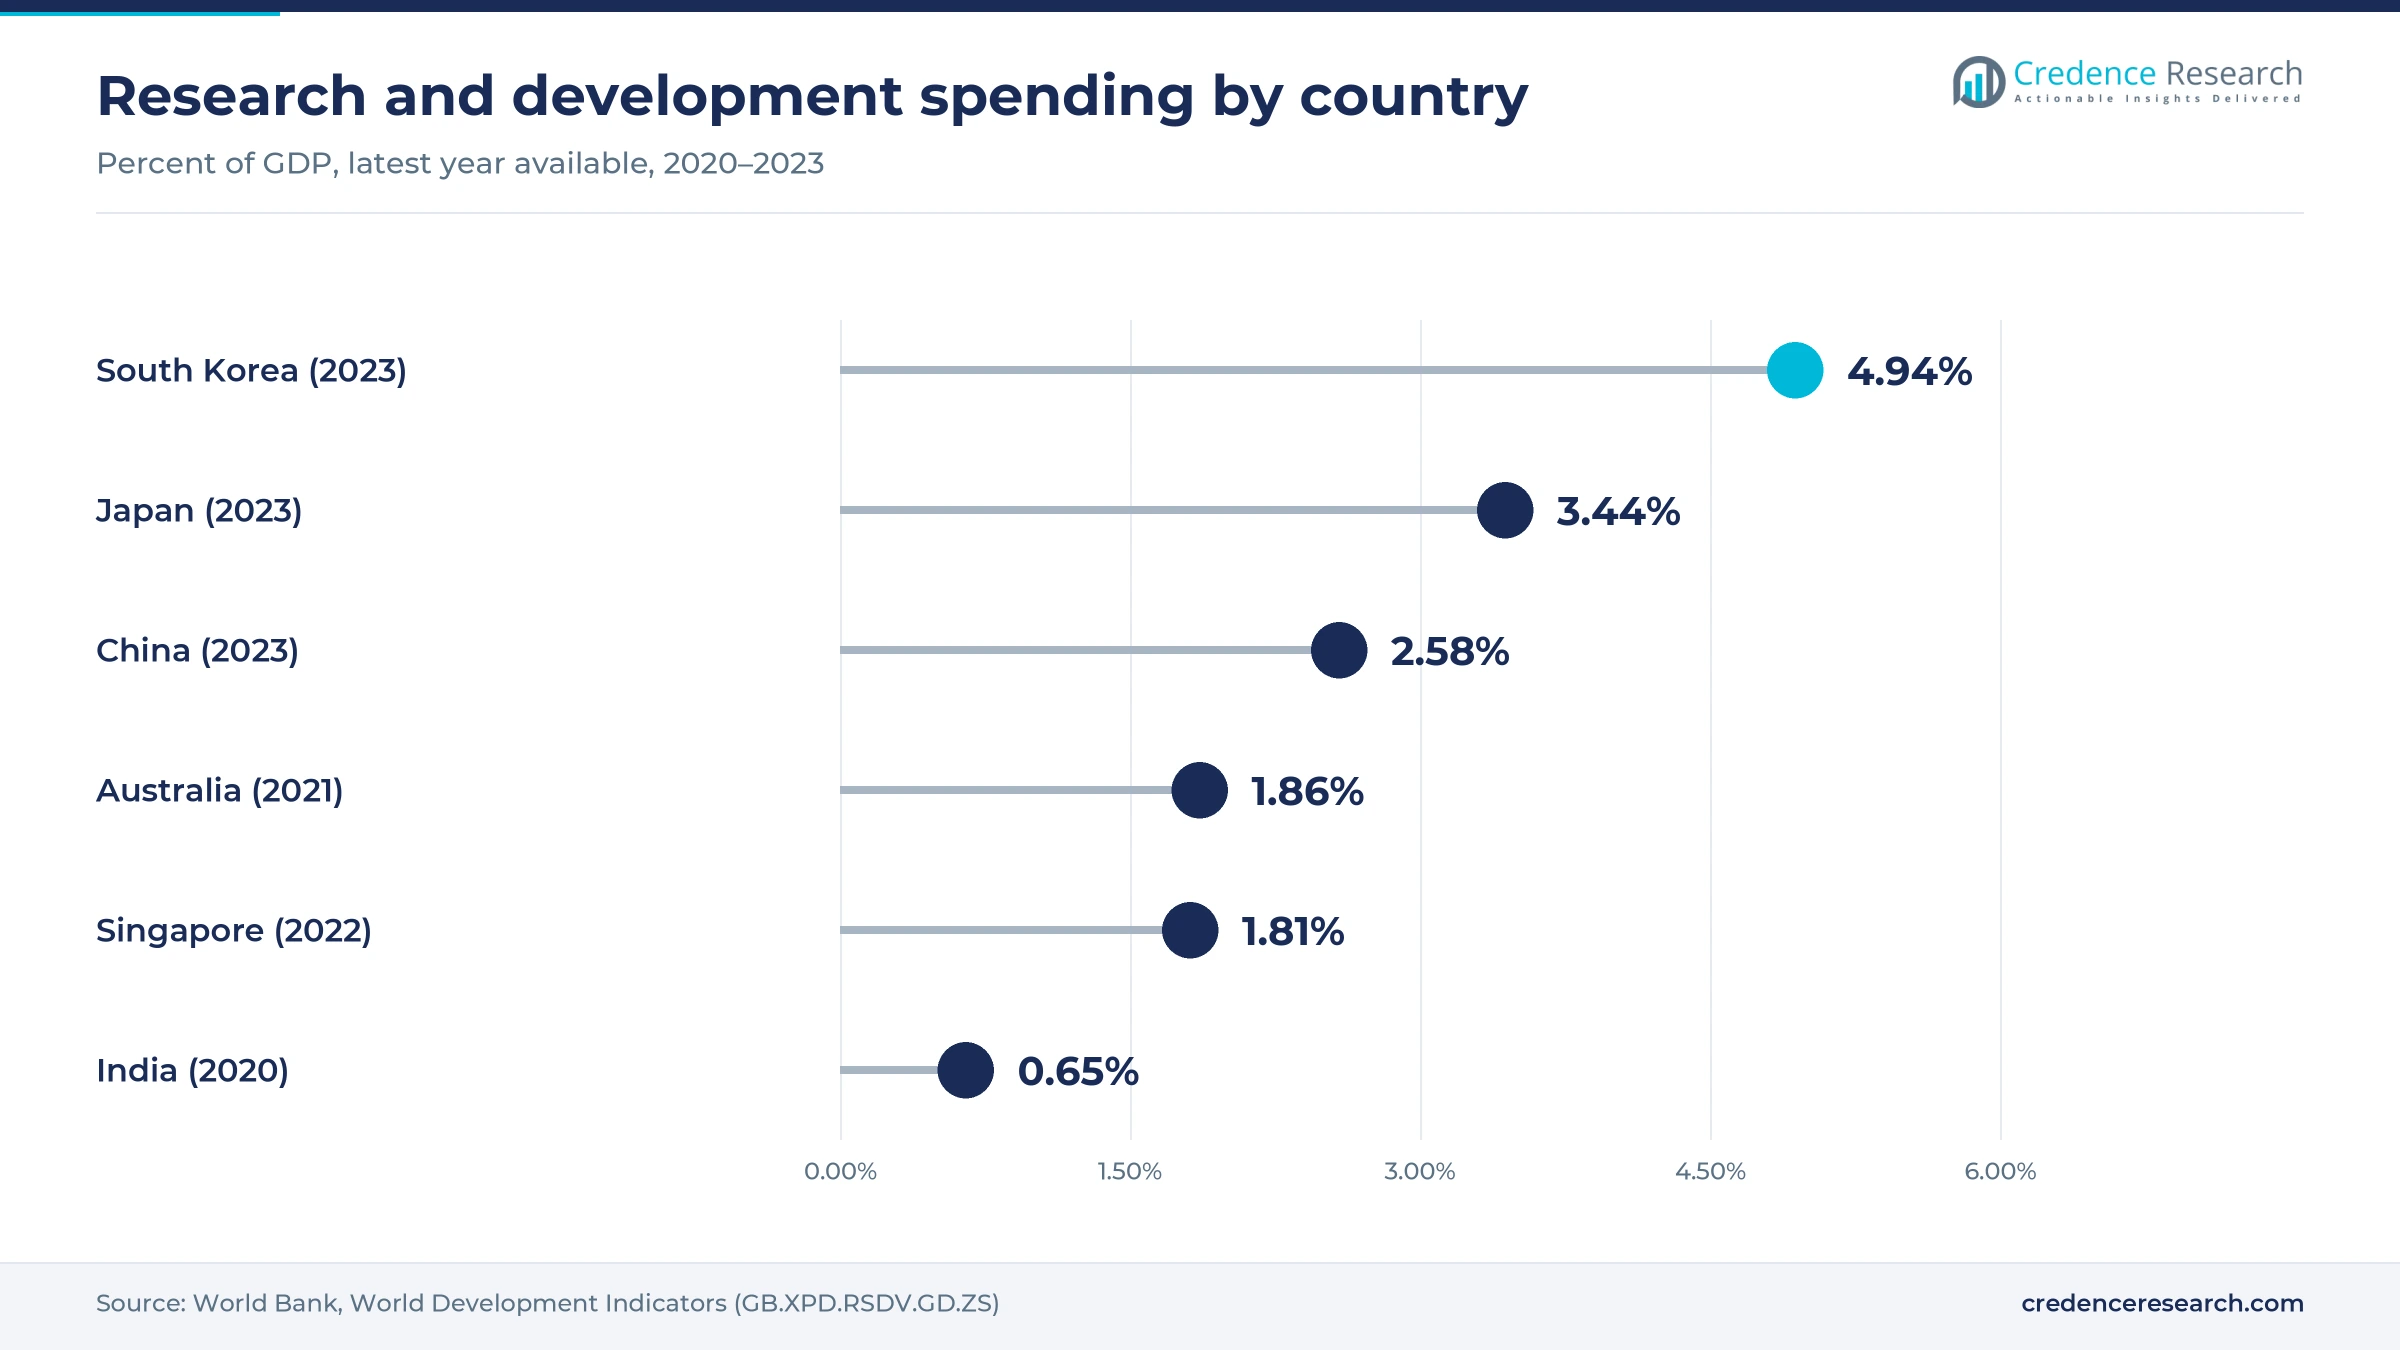
Japan's drug-loss policy opens new nonclinical work, because the government wants more startups to develop drugs that are unavailable in the country. The National Healthcare Policy Secretariat set a plan on July 30, 2024, to start development of the 86 drug-loss products identified in 2023 by fiscal 2026. The same plan aims to double private investment in drug discovery startups between 2023 and 2028. Japan also spent 3.44% of GDP on research and development in 2023, according to World Bank data. In turn, Japan and South Korea hold a 20.4% share of 2025 value, and domestic biotech sponsors need outsourced toxicology.
India GLP capacity creates an export opening
India's GLP capacity creates an export opening, because certified laboratories there combine OECD data acceptance with lower study costs. Aurigene Pharmaceutical Services received a national GLP certificate for human and veterinary pharmaceuticals in August 2025, valid until August 2028. The Union Cabinet approved the BioE3 policy on Aug. 24, 2024, to support biomanufacturing, bio-AI hubs and biofoundries, All India Radio reported. Syngene International lists about 5,200 scientists on its corporate website, which shows the depth of trained staff available to sponsors. As a result, India grows fastest among the countries covered, and certified laboratories there add work alongside wider healthcare outsourcing in India.
Primate supply, pricing pressure and policy risk weigh
Primate supply shortages raise study costs
Primate supply shortages raise study costs, because breeding colonies cannot expand quickly when biologics pipelines grow. Tight monkey supply in China was expected to last into early 2026, which lifts prices for antibody and conjugate programs. Smaller laboratories without their own colonies are hit hardest, since they must buy animals at market prices. Larger providers respond by holding animal reserves and by adding cell-based and computational methods to reduce the number of animals used in each program.
Price competition squeezes laboratory margins
Price competition squeezes laboratory margins, because Chinese providers expanded capacity sharply during the pandemic years and then faced slower biotech funding. The Bamboo Works reported that this capacity build-up caused intense price competition and lower contract prices for JOINN Laboratories. Smaller providers are most exposed, since they lack the scale to absorb discounts on standard toxicology studies. Many providers now focus on new modalities and integrated programs, where technical demands support better pricing.
U.S. policy risk clouds sponsor decisions
U.S. policy risk clouds sponsor decisions, because the BIOSECURE Act lets the federal government designate biotechnology companies of concern through an annual list process. No contract research company in the region was designated when the law took effect, yet sponsors with federal contracts must still review their supplier exposure. Chinese providers are most affected, since some Western sponsors now split programs between several countries. Providers respond with data security audits, overseas sites and transparent ownership disclosures.
Validation gaps slow non-animal method adoption
Validation gaps slow the adoption of non-animal methods, because regulators still lack detailed acceptance criteria for many new tests. India allowed these methods in 2023, yet limited guidance has kept them out of most formal approval submissions so far. Laboratories that invest early in organoids and organ chips therefore carry costs before revenue follows. Providers reduce this risk by running new methods alongside standard animal studies until regulators publish clear validation guidance.
China leads while India grows fastest
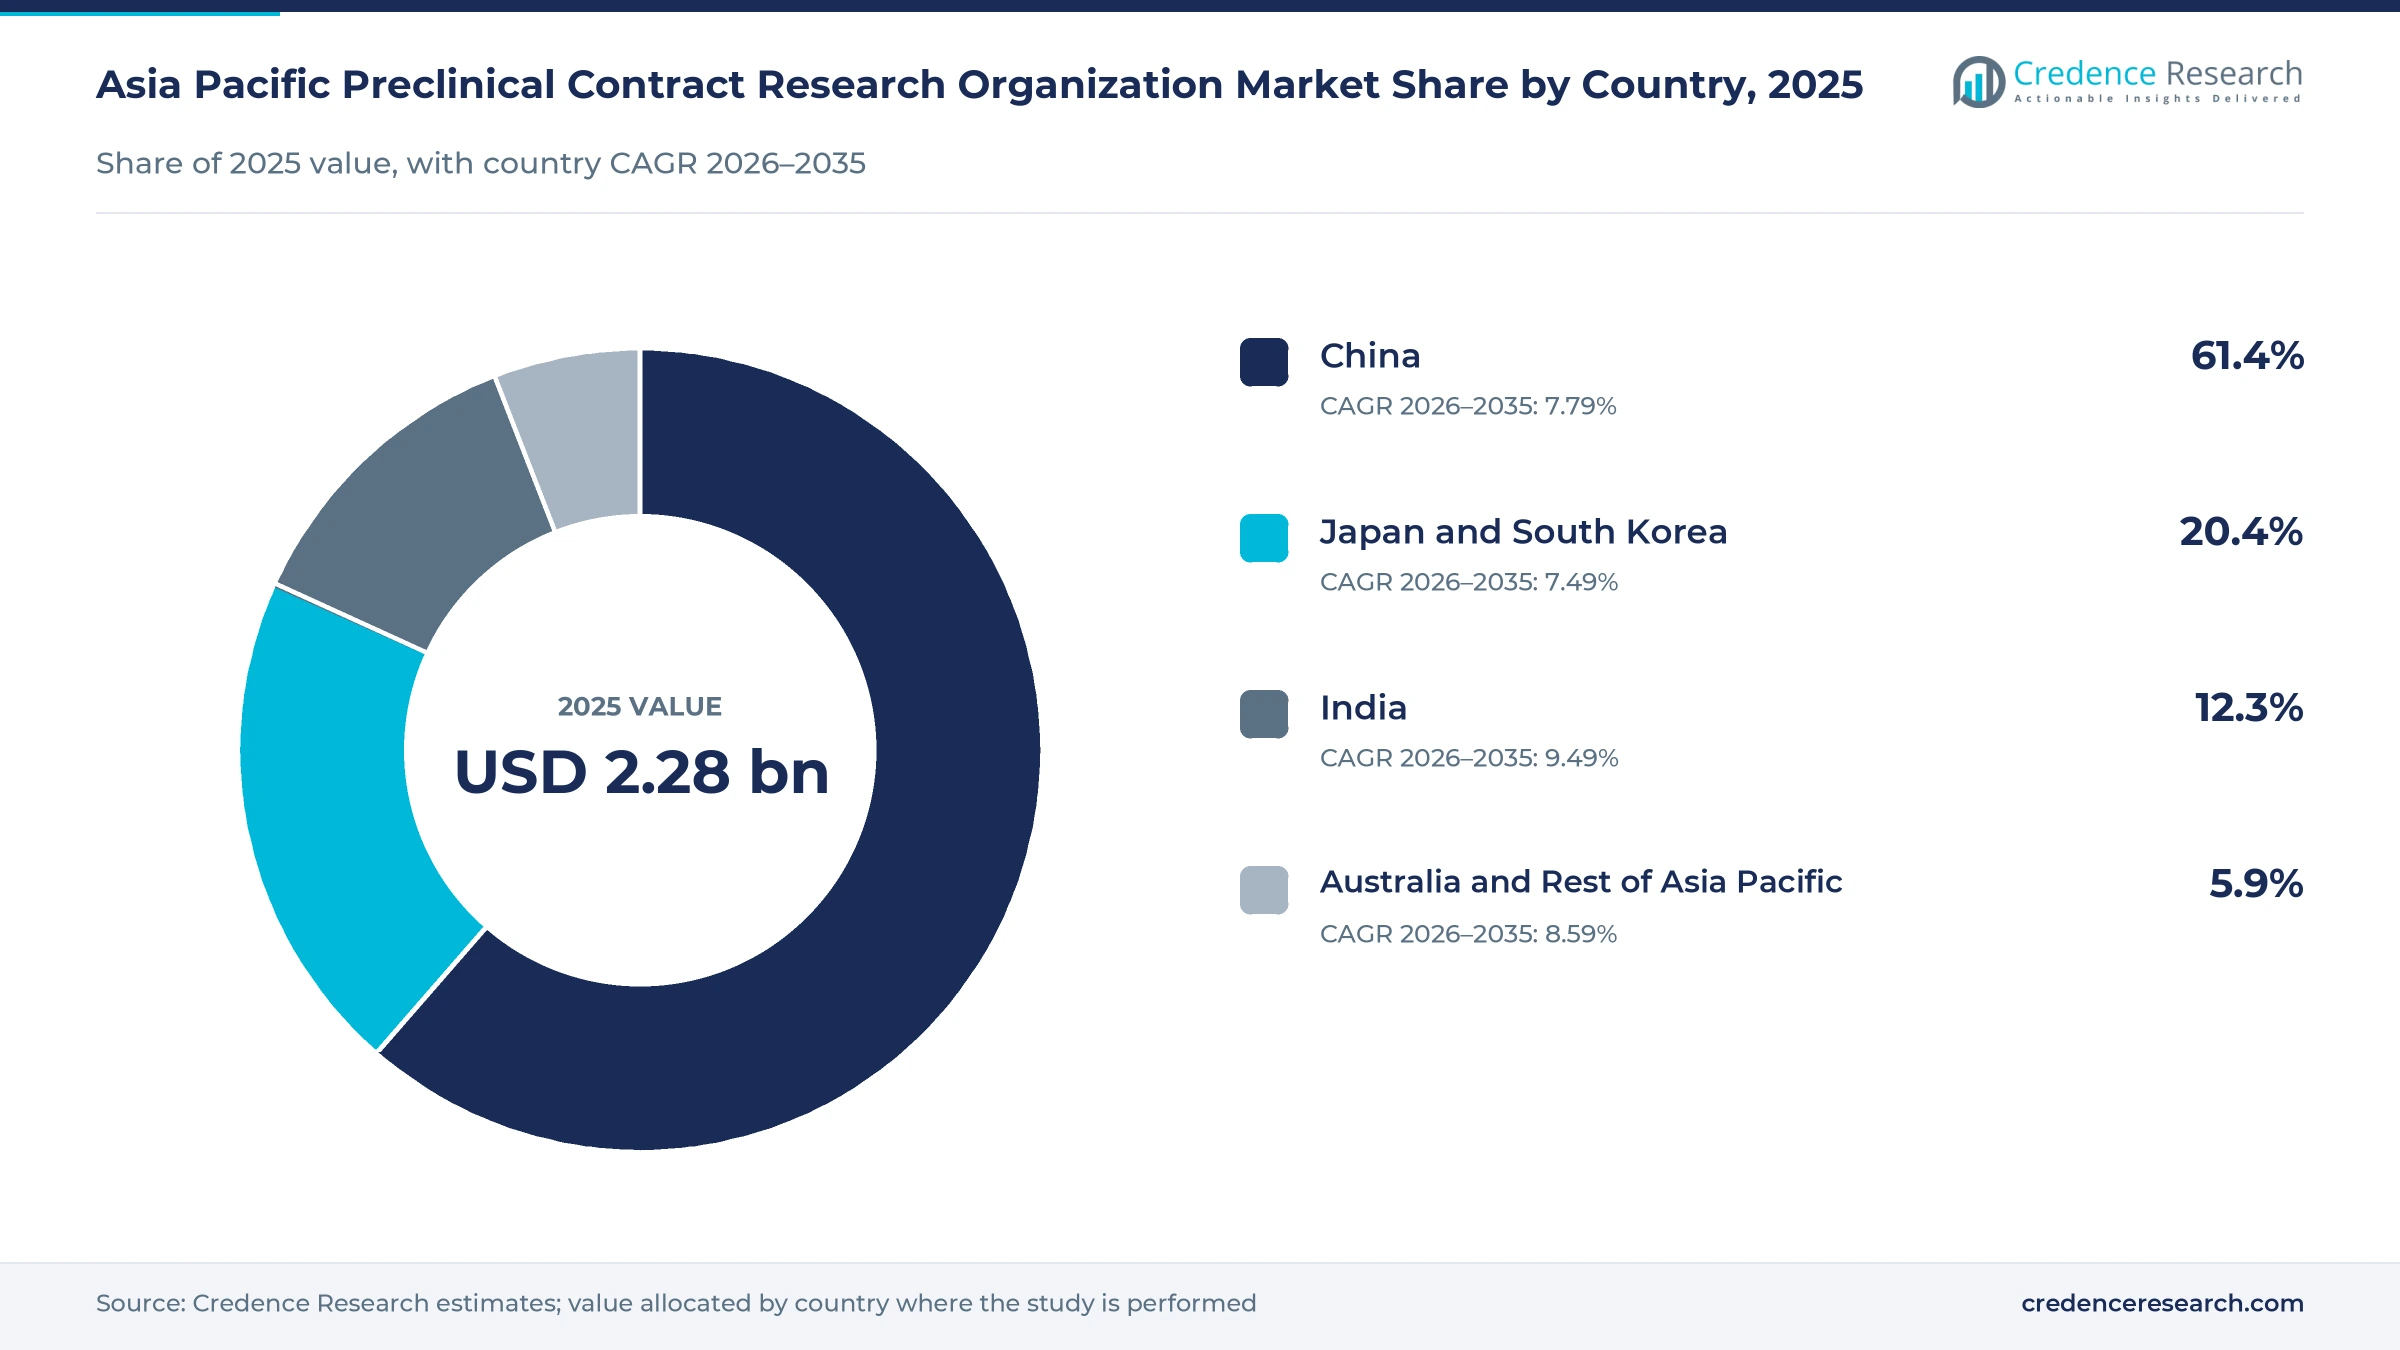
| Country | Value, 2025 (USD billion) | Share, 2025 | CAGR, 2026–2035 |
|---|---|---|---|
| China | 1.40 | 61.4% | 7.79% |
| Japan and South Korea | 0.47 | 20.4% | 7.49% |
| India | 0.28 | 12.3% | 9.49% |
| Australia and Rest of Asia Pacific | 0.13 | 5.9% | 8.59% |
China leads on integrated GLP and primate capacity
China held 61.4% of 2025 value and grows at 7.79% a year, because its integrated groups combine chemistry, DMPK, toxicology and primate studies on large campuses. WuXi AppTec, Pharmaron and JOINN Laboratories run GLP facilities that serve domestic biotech companies and Western sponsors alike. Shorter clinical trial reviews under Announcement No. 86 encourage Chinese sponsors to finish safety packages sooner. However, rising monkey prices and U.S. policy risk push some Western sponsors to split programs with laboratories in other countries.
Japan and South Korea grow with domestic biotech programs
Japan and South Korea held 20.4% of 2025 value and grow at 7.49% a year, because both countries pair large pharmaceutical companies with growing biotech sectors. South Korea spent 4.94% of GDP on research and development in 2023, the highest ratio among the countries covered, according to World Bank data. Shin Nippon Biomedical Laboratories reported four preferred agreements with major Japanese drug companies in May 2026. Japan's drug-loss plan also adds new startup programs that need outsourced toxicology.
India grows fastest on OECD-accepted GLP data
India held 12.3% of 2025 value and grows at 9.49% a year, the fastest rate among the countries covered, because its GLP laboratories produce data accepted across OECD members. The national GLP register listed 58 certified test facilities in October 2025, covering pharmaceuticals, chemicals and medical devices. Syngene International, Jubilant Biosys and Aurigene Pharmaceutical Services appear on that register and serve global sponsors. As a result, Western sponsors that seek a second supplier outside China increasingly test Indian laboratories.
Australia and Rest of Asia Pacific add niche capacity
Australia and Rest of Asia Pacific held 5.9% of 2025 value and grow at 8.59% a year, because they offer specialist laboratories rather than large toxicology campuses. Australia gives small companies a refundable research tax offset at the company tax rate plus an 18.5% premium, according to the Australian Taxation Office. Singapore became the first non-OECD Asian full adherent to the OECD data acceptance system in January 2010.
Inspections, certifications and capacity moves, 2024–2026
| Development | Status and market relevance |
|---|---|
| In July 2024, Japan's National Healthcare Policy Secretariat set a drug discovery action plan to address 86 drug-loss products. | Policy; creates new startup programs that need outsourced toxicology |
| In July 2025, Pharmaron completed installation of an accelerator mass spectrometry system at its Ningbo campus for innovative drug research. | Operational; supports microdosing and human ADME studies |
| In August 2025, Aurigene Pharmaceutical Services received a national GLP certificate for human and veterinary pharmaceuticals in India. | Certified; valid until August 2028 |
| In September 2025, China's National Medical Products Administration issued Announcement No. 86 on 30-working-day clinical trial reviews. | In force; pulls safety packages forward for eligible innovative drugs |
| In March 2026, WuXi AppTec reported that its Suzhou and Shanghai testing facilities passed FDA, OECD, NMPA and PMDA inspections. | Completed; supports acceptance of its GLP data in major markets |
Organ chips, computational toxicology and AMS tools
- Organ-on-chip and organoid models reproduce human liver, heart and immune tissue, which lets laboratories screen toxicity before animal studies begin.
- Computational toxicology uses AI-based models to predict drug distribution and side effects, which the FDA named in its April 2025 roadmap.
- Accelerator mass spectrometry measures tiny doses of labeled drugs in human and animal samples, and Pharmaron commissioned such a system in Ningbo in July 2025.
- Data security and quality systems protect sponsor data and study records, and WuXi AppTec reported ISO/IEC 27001 certification at 20 main sites in China.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Integrated Chinese groups face Indian and Japanese rivals
Contract research organization competition centers on GLP acceptance, primate access, study turnaround and the ability to run integrated programs from discovery biology through pivotal toxicology. WuXi AppTec and Pharmaron compete as integrated groups that link chemistry, DMPK and safety assessment on large campuses in China, and Pharmaron also runs sites in the U.K. and the U.S. JOINN Laboratories specializes in safety evaluation and holds a large primate reserve, which matters for antibody and conjugate programs. Shin Nippon Biomedical Laboratories is a leading Japanese nonclinical provider with its own breeding colonies and a rising share of overseas orders. Syngene International competes from Bengaluru with discovery and safety services backed by OECD-accepted GLP status. Providers increasingly win work through preferred-supplier agreements, regulatory inspection records and data security audits rather than price alone.
Companies profiled and their roles in this market
| Company | Type | Role in the market |
|---|---|---|
| WuXi AppTec | Integrated CRO | Drug safety evaluation and laboratory testing from Suzhou and Shanghai facilities |
| Pharmaron | Integrated CRO | DMPK, in vivo pharmacology and safety assessment across China, the U.K. and the U.S. |
| JOINN Laboratories | Safety specialist | GLP toxicology and primate studies for antibodies, conjugates and nucleic acid drugs |
| Syngene International | Integrated CRO | Discovery biology and safety assessment from GLP-certified laboratories in India |
| Shin Nippon Biomedical Laboratories | Nonclinical specialist | Japanese nonclinical studies with in-house primate breeding in Kagoshima |
Credence Research view on regional preclinical outsourcing
Credence Research's view is that preclinical contract research organization demand in the region will keep growing faster than the wider drug development budget, because biologics, conjugates and nucleic acid drugs need longer and more specialized safety programs. China will remain the largest supplier of study capacity, yet its share will ease slightly as Western sponsors qualify second laboratories in India, Japan and South Korea. Providers with their own primate colonies, OECD-accepted data and credible non-animal methods will win the most demanding programs. Pricing will stay under pressure for standard studies, so growth will favor integrated packages and new modality work.
How the regional preclinical study estimate was built
The report on preclinical contract research organization services uses 2025 as the base year and forecasts values for 2026 through 2035 from the Credence Research market model. Country, service, customer, application and delivery model splits are Credence Research estimates based on laboratory capacity, sponsor pipelines and public company disclosures. Inputs include regulator announcements from the NMPA, FDA and India's national GLP authority, OECD records, World Bank research spending data, government policy documents and company filings and releases. The report does not rely on interviews or surveys, and every dated fact cited comes from a public source.
Biologics pipelines and GLP reach carry demand to 2035
The market is projected to reach USD 4.93 billion by 2035, growing at an 8.00% CAGR during 2026–2035. Biologics, conjugates and nucleic acid drugs will keep safety and toxicology work at the center of demand, while discovery biology grows fastest as biotech sponsors outsource earlier. India will gain share through OECD-accepted GLP data and lower costs, and China will keep its lead through scale and primate access. Non-animal methods will spread gradually as regulators publish validation guidance, which will change the mix of studies rather than reduce total outsourcing.
Frequently Asked Questions
How big is the Asia Pacific preclinical contract research organization market?
Which country leads the regional preclinical CRO market?
Which country grows fastest in the regional preclinical CRO market?
Which service type leads demand for preclinical studies?
How does the BIOSECURE Act affect preclinical outsourcing in Asia Pacific?
How are non-animal methods changing preclinical studies in the region?
Why are primate costs important for this market?
Which companies are active in the Asia Pacific preclinical CRO market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Service Type
- 1.2.1 Safety and Toxicology
- 1.2.2 DMPK and ADME
- 1.2.3 Safety Pharmacology
- 1.2.4 Discovery Biology
- 1.3 By Customer Type
- 1.3.1 Established Pharmaceutical Sponsors
- 1.3.2 Biotechnology Sponsors
- 1.3.3 Academic and Public Research Sponsors
- 1.4 By Application
- 1.4.1 Oncology
- 1.4.2 Neurological Disorders
- 1.4.3 Cardiometabolic Disorders
- 1.4.4 Infectious and Immune Disorders
- 1.5 By Delivery Model
- 1.5.1 GLP Study Delivery
- 1.5.2 Non-GLP Study Delivery
- 1.5.3 Mixed GLP Program Delivery
- 1.6 By Country
- 1.6.1 China
- 1.6.2 India
- 1.6.3 Japan and South Korea
- 1.6.4 Australia and Rest of Asia Pacific
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2025: USD 2.28 billion → 2035: USD 4.93 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Historical Period: 2018-2025
- 2.6.2 Base Year: 2025
- 2.6.3 Forecast Period: 2025-2035
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2025
- 3.3 Forecast Market Size, 2035
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Asia Pacific Preclinical Contract Research Organization Market Trends and Developments
- 4.1 Historical Industry Development, 2018-2025
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Asia Pacific Preclinical Contract Research Organization Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis, 2018-2025
- 5.2 Demand Forecast, 2025-2035
- 5.3 Production and Output Trend, 2018-2025
- 5.4 Production and Output Forecast, 2025-2035
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Asia Pacific Preclinical Contract Research Organization Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends, 2018-2025
- 6.3 Pricing Outlook, 2025-2035
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Asia Pacific Preclinical Contract Research Organization Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Asia Pacific Preclinical Contract Research Organization Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Asia Pacific Preclinical Contract Research Organization Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Asia Pacific Preclinical Contract Research Organization Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Asia Pacific Preclinical Contract Research Organization Market Outlook, 2025-2035
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2025: USD 2.28 billion → 2035: USD 4.93 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size, 2018-2025
- 11.1.4 Base-Year Market Size, 2025
- 11.2 Market Forecast, 2025-2035
- 11.2.1 Revenue Forecast to 2035
- 11.2.2 Volume Forecast to 2035
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Asia Pacific Preclinical Contract Research Organization Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2025
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Service Type - Market Size and Forecast, 2025-2035
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size, 2018-2025
- 12.3.3 Revenue Forecast, 2025-2035
- 12.3.4 Volume Forecast, 2025-2035
- 12.3.5 Base-Year Market Share, 2025
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Safety and Toxicology
- 12.3.7.2 DMPK and ADME
- 12.3.7.3 Safety Pharmacology
- 12.3.7.4 Discovery Biology
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Customer Type - Market Size and Forecast, 2025-2035
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size, 2018-2025
- 12.4.3 Revenue Forecast, 2025-2035
- 12.4.4 Volume Forecast, 2025-2035
- 12.4.5 Base-Year Market Share, 2025
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Established Pharmaceutical Sponsors
- 12.4.7.2 Biotechnology Sponsors
- 12.4.7.3 Academic and Public Research Sponsors
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2025-2035
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size, 2018-2025
- 12.5.3 Revenue Forecast, 2025-2035
- 12.5.4 Volume Forecast, 2025-2035
- 12.5.5 Base-Year Market Share, 2025
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Oncology
- 12.5.7.2 Neurological Disorders
- 12.5.7.3 Cardiometabolic Disorders
- 12.5.7.4 Infectious and Immune Disorders
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Delivery Model - Market Size and Forecast, 2025-2035
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size, 2018-2025
- 12.6.3 Revenue Forecast, 2025-2035
- 12.6.4 Volume Forecast, 2025-2035
- 12.6.5 Base-Year Market Share, 2025
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 GLP Study Delivery
- 12.6.7.2 Non-GLP Study Delivery
- 12.6.7.3 Mixed GLP Program Delivery
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 By Country - Market Size and Forecast, 2025-2035
- 12.7.1 Segment Definition and Scope
- 12.7.2 Historical Market Size, 2018-2025
- 12.7.3 Revenue Forecast, 2025-2035
- 12.7.4 Volume Forecast, 2025-2035
- 12.7.5 Base-Year Market Share, 2025
- 12.7.6 Segment CAGR and Growth Drivers
- 12.7.7 Subsegment Market Size and Forecast
- 12.7.7.1 China
- 12.7.7.2 India
- 12.7.7.3 Japan and South Korea
- 12.7.7.4 Australia and Rest of Asia Pacific
- 12.7.8 Subsegment Pricing and Adoption Trends
- 12.7.9 Leading Suppliers and Competition
- 12.7.10 Regional Demand and Opportunities
- 12.8 Segment Growth Comparison
- 12.9 Segment Attractiveness and Priority Matrix
Chapter 13 Asia Pacific Preclinical Contract Research Organization End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Asia Pacific Preclinical Contract Research Organization Geographic Market Outlook, 2025-2035
- 14.1 Regional Market Size and Country-Level Shares, 2025
- 14.2 Country Market Size Comparison, 2025
- 14.3 Country Market Forecasts, 2025-2035
- 14.4 Subregional Industrial and Demand Clusters
- 14.5 Intra-Regional Pricing and Cost Differences
- 14.6 Cross-Border Trade and Supply Networks
- 14.7 Regional Supply and Demand Balances
- 14.8 Country Opportunity Comparison and Prioritization
Note: Every listed country is covered on the structure shown under the first country.
Chapter 15 Asia Pacific Preclinical Contract Research Organization Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2025-2035
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Asia Pacific Preclinical Contract Research Organization Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2025
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2025-2035
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 WuXi AppTec
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Pharmaron
- 18.4 JOINN Laboratories
- 18.5 Syngene International
- 18.6 Shin Nippon Biomedical Laboratories
- 18.7 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

