
Trusted off-patent brands keep a premium at the counter
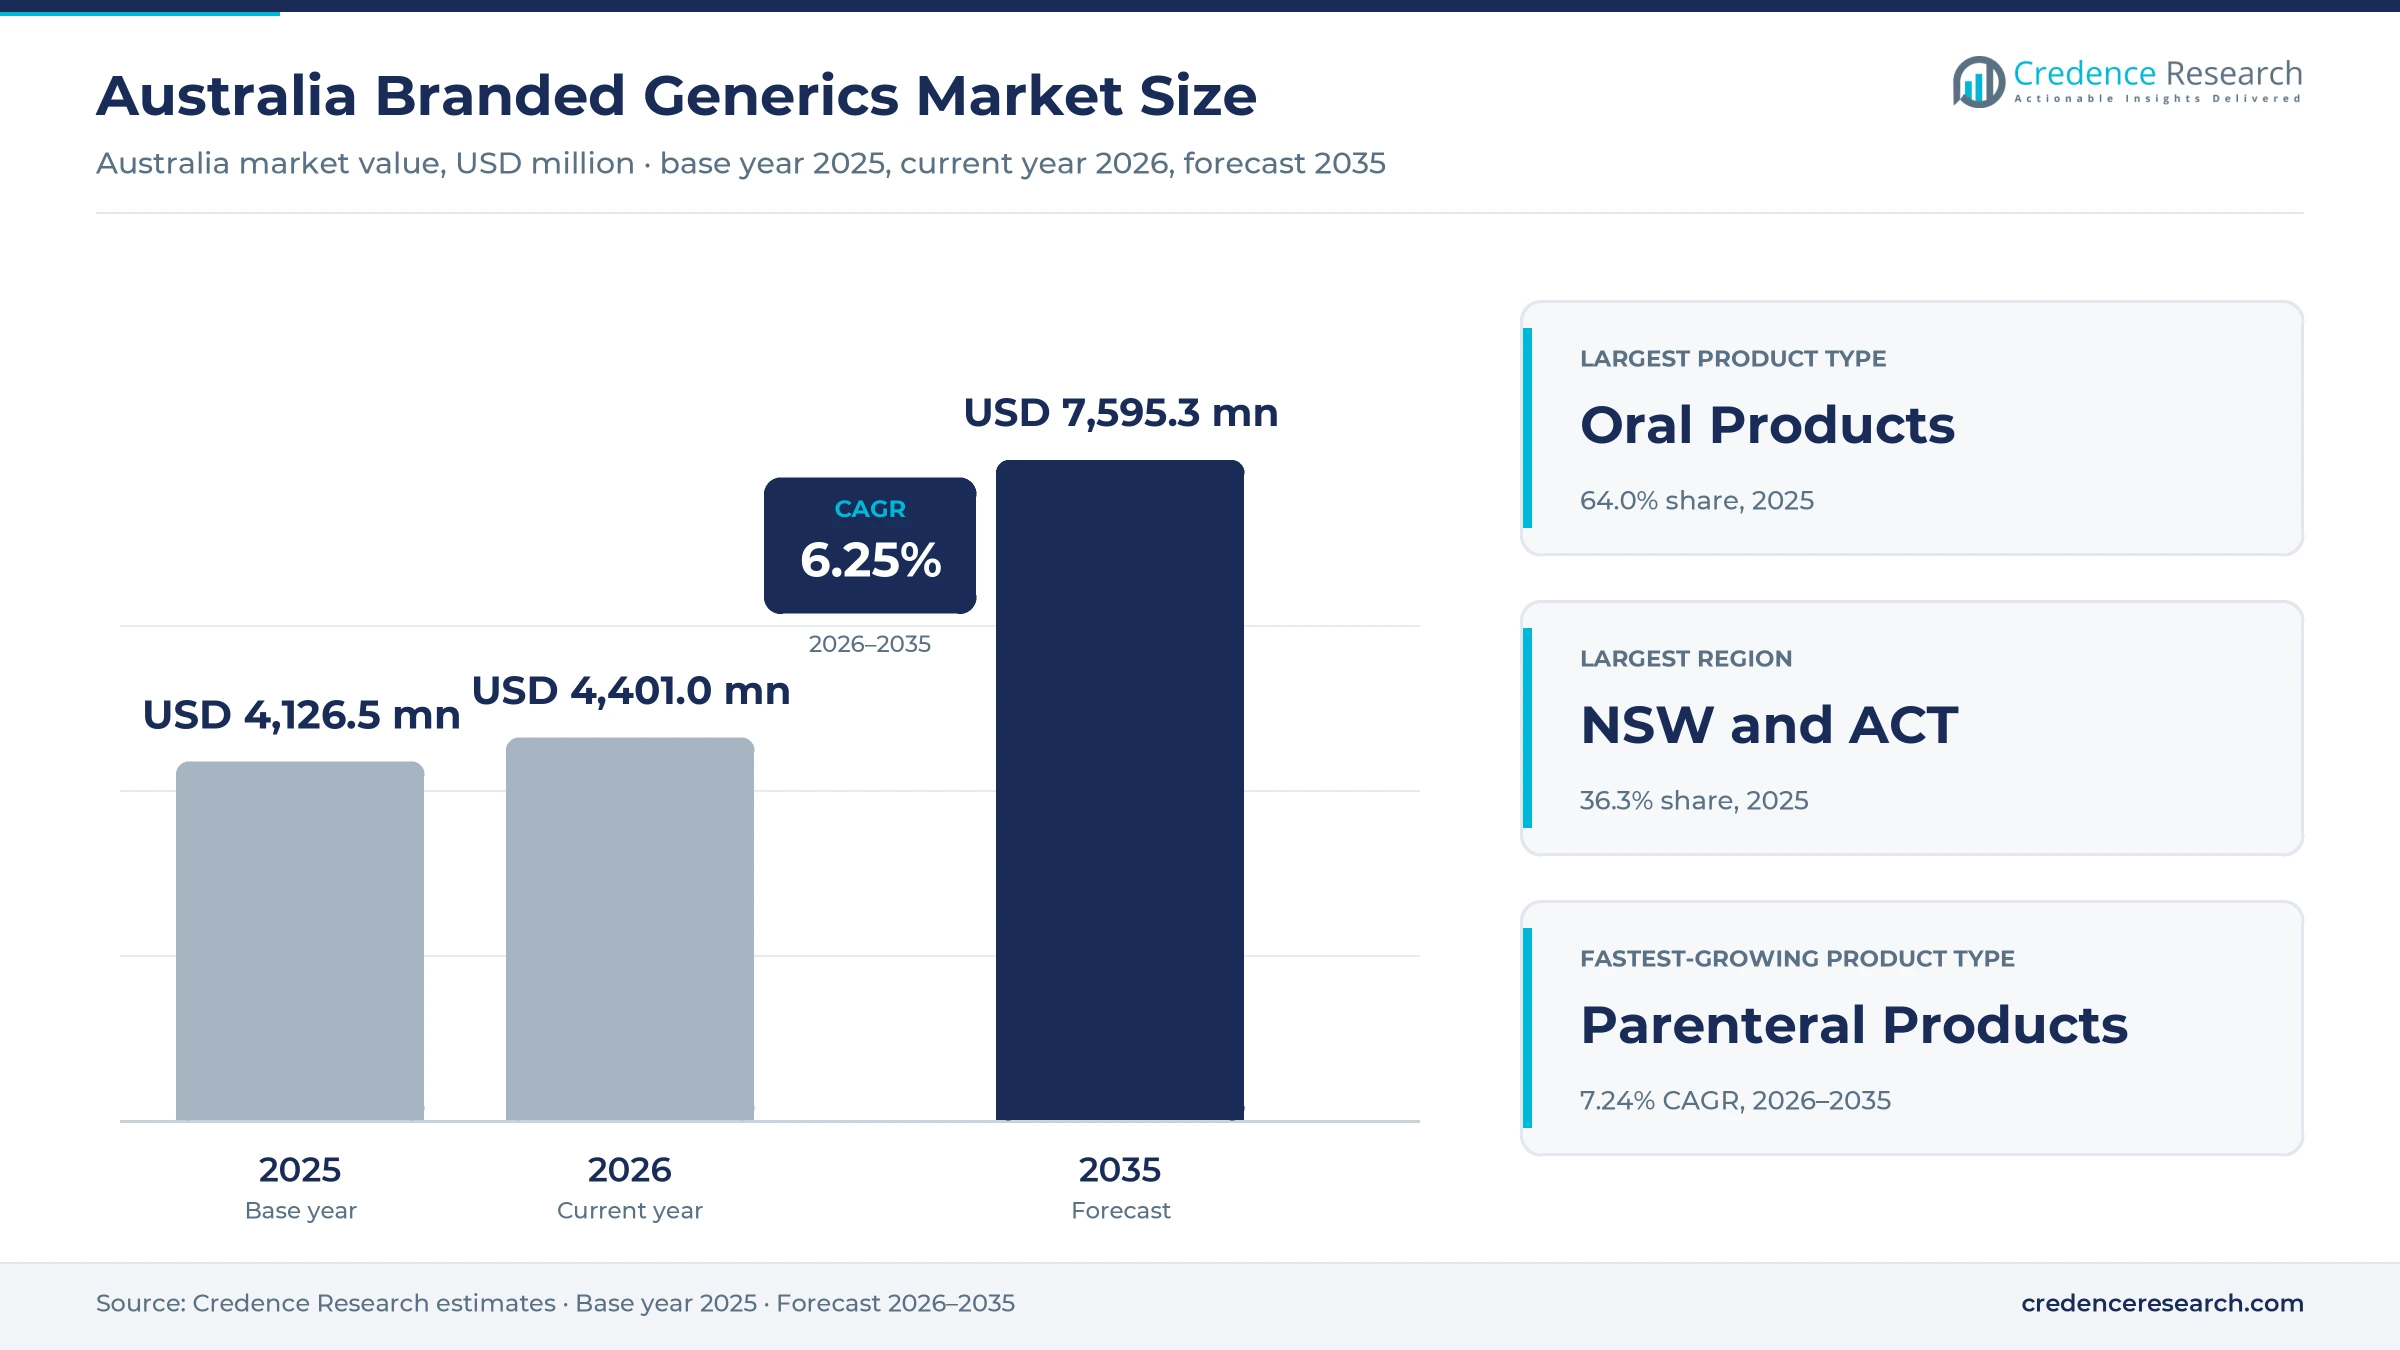
The Australia branded generics market was valued at USD 4.13 billion in 2025 and is projected to increase from USD 4.40 billion in 2026 to USD 7.60 billion by 2035, registering a CAGR of 6.25% during 2026–2035. Demand comes from Australians who refill the same cholesterol, blood pressure, reflux and mental health medicines for years, and from shoppers who choose familiar pain, allergy and digestive brands at the pharmacy shelf. Because prescribers and patients often stay with a brand they trust after patent expiry, off-patent originator brands and named generic ranges keep a price premium over the cheapest equivalent. New South Wales and Australian Capital Territory held the largest regional share, 36.3% in 2025, while Western and Central Australia is the fastest-growing region at 6.54% a year. In turn, the cut in the general PBS co-payment to AUD 25 from Jan. 1, 2026, narrows the out-of-pocket gap between premium brands and lower-priced equivalents at the dispensary.
Which medicines does the branded off-patent estimate include?
The estimate measures the value of off-patent medicines sold in Australia under a brand name at manufacturer selling prices. It counts originator brands that have lost exclusivity, generic ranges marketed under their own trade names, branded biosimilars and branded non-prescription medicines sold through pharmacies and grocery stores, whether supplied through the PBS, private prescriptions or hospital contracts.
The estimate excludes medicines still protected by patents or data exclusivity, unbranded commodity generics sold under the active ingredient name, complementary medicines and vitamins, compounded products and veterinary medicines. The value chain runs from overseas and local manufacturers through Australian sponsors and full-line wholesalers to pharmacies, while state health services buy hospital volumes through tenders.
Australia Branded Generics Market Insights
- The Australia branded generics market was valued at USD 4.13 billion in 2025 and is projected to reach USD 7.60 billion by 2035, registering a CAGR of 6.25% during 2026–2035.
- New South Wales and Australian Capital Territory held a 36.3% share of 2025 value, in line with the largest share of PBS government medicine cost in 2024-25.
- Oral products led product types with a 64.0% share of 2025 value, because statins, acid suppressants and antidepressants dominate repeat dispensing in community pharmacies.
- Aspen Pharmacare announced on Dec. 29, 2025, the sale of its Asia Pacific business outside China, including Australia, to BGH Capital for AUD 2.37 billion.
- Arrotex Pharmaceuticals and Pfizer Australia agreed in February 2026 that Arrotex will market the originator brand Enbrel to Australian pharmacies, hospitals and prescribers.
Oral brands lead while parenteral products grow fastest
Why do tablets and capsules hold most branded value?
Based on product type, the market is categorized into Oral Products, Parenteral Products, Topical Products and Inhaled and Ophthalmic Products. Oral Products led with a 64.0% share of 2025 value, because daily tablets for cholesterol, blood pressure, reflux and depression make up most repeat prescriptions. Parenteral Products grow fastest at 7.24% a year, as branded biosimilars of denosumab and aflibercept join hospital and specialist supply.
Which therapy areas carry the highest brand loyalty?
Based on disease area, the market is categorized into Cardiometabolic Disorders, Oncology, Central Nervous System Disorders, and Respiratory and Remaining Therapeutic Areas. Cardiometabolic Disorders led with a 34.0% share of 2025 value, because statins and blood pressure brands top PBS script counts. Oncology grows fastest at 7.76% a year, as supportive-care biologics and older injectable cancer medicines move into branded off-patent supply.
How do PBS scripts, shelves and tenders split sales?
Based on channel, the market is categorized into PBS Community Prescription, Private Community Prescription, Pharmacy OTC and Hospital Procurement. PBS Community Prescription led with a 52.0% share of 2025 value, because most branded prescriptions are subsidized and dispensed in community pharmacies. Hospital Procurement grows fastest at 7.03% a year, as state health services tender branded biosimilars and injectable medicines for public hospitals.
Why do older Australians account for most branded use?
Based on end user, the market is categorized into Paediatric Patients, Working-Age Adults and Older Adults. Older Adults led with a 53.0% share of 2025 value and grow fastest at 6.63% a year, because people aged 65 and over take several long-term medicines at once. Working-age adults remain the main buyers of branded pain, allergy and cold medicines at the pharmacy shelf.
| Segment Group | Leading Sub-segment | Share, 2025 | Fastest-growing Sub-segment | CAGR, 2026–2035 |
|---|---|---|---|---|
| By Product Type | Oral Products | 64.0% | Parenteral Products | 7.24% |
| By Disease Area | Cardiometabolic Disorders | 34.0% | Oncology | 7.76% |
| By Channel | PBS Community Prescription | 52.0% | Hospital Procurement | 7.03% |
| By End User | Older Adults | 53.0% | Older Adults | 6.63% |
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Chronic refills, brand renewal and pharmacy shelf trust
How does recurring chronic therapy sustain branded refills?
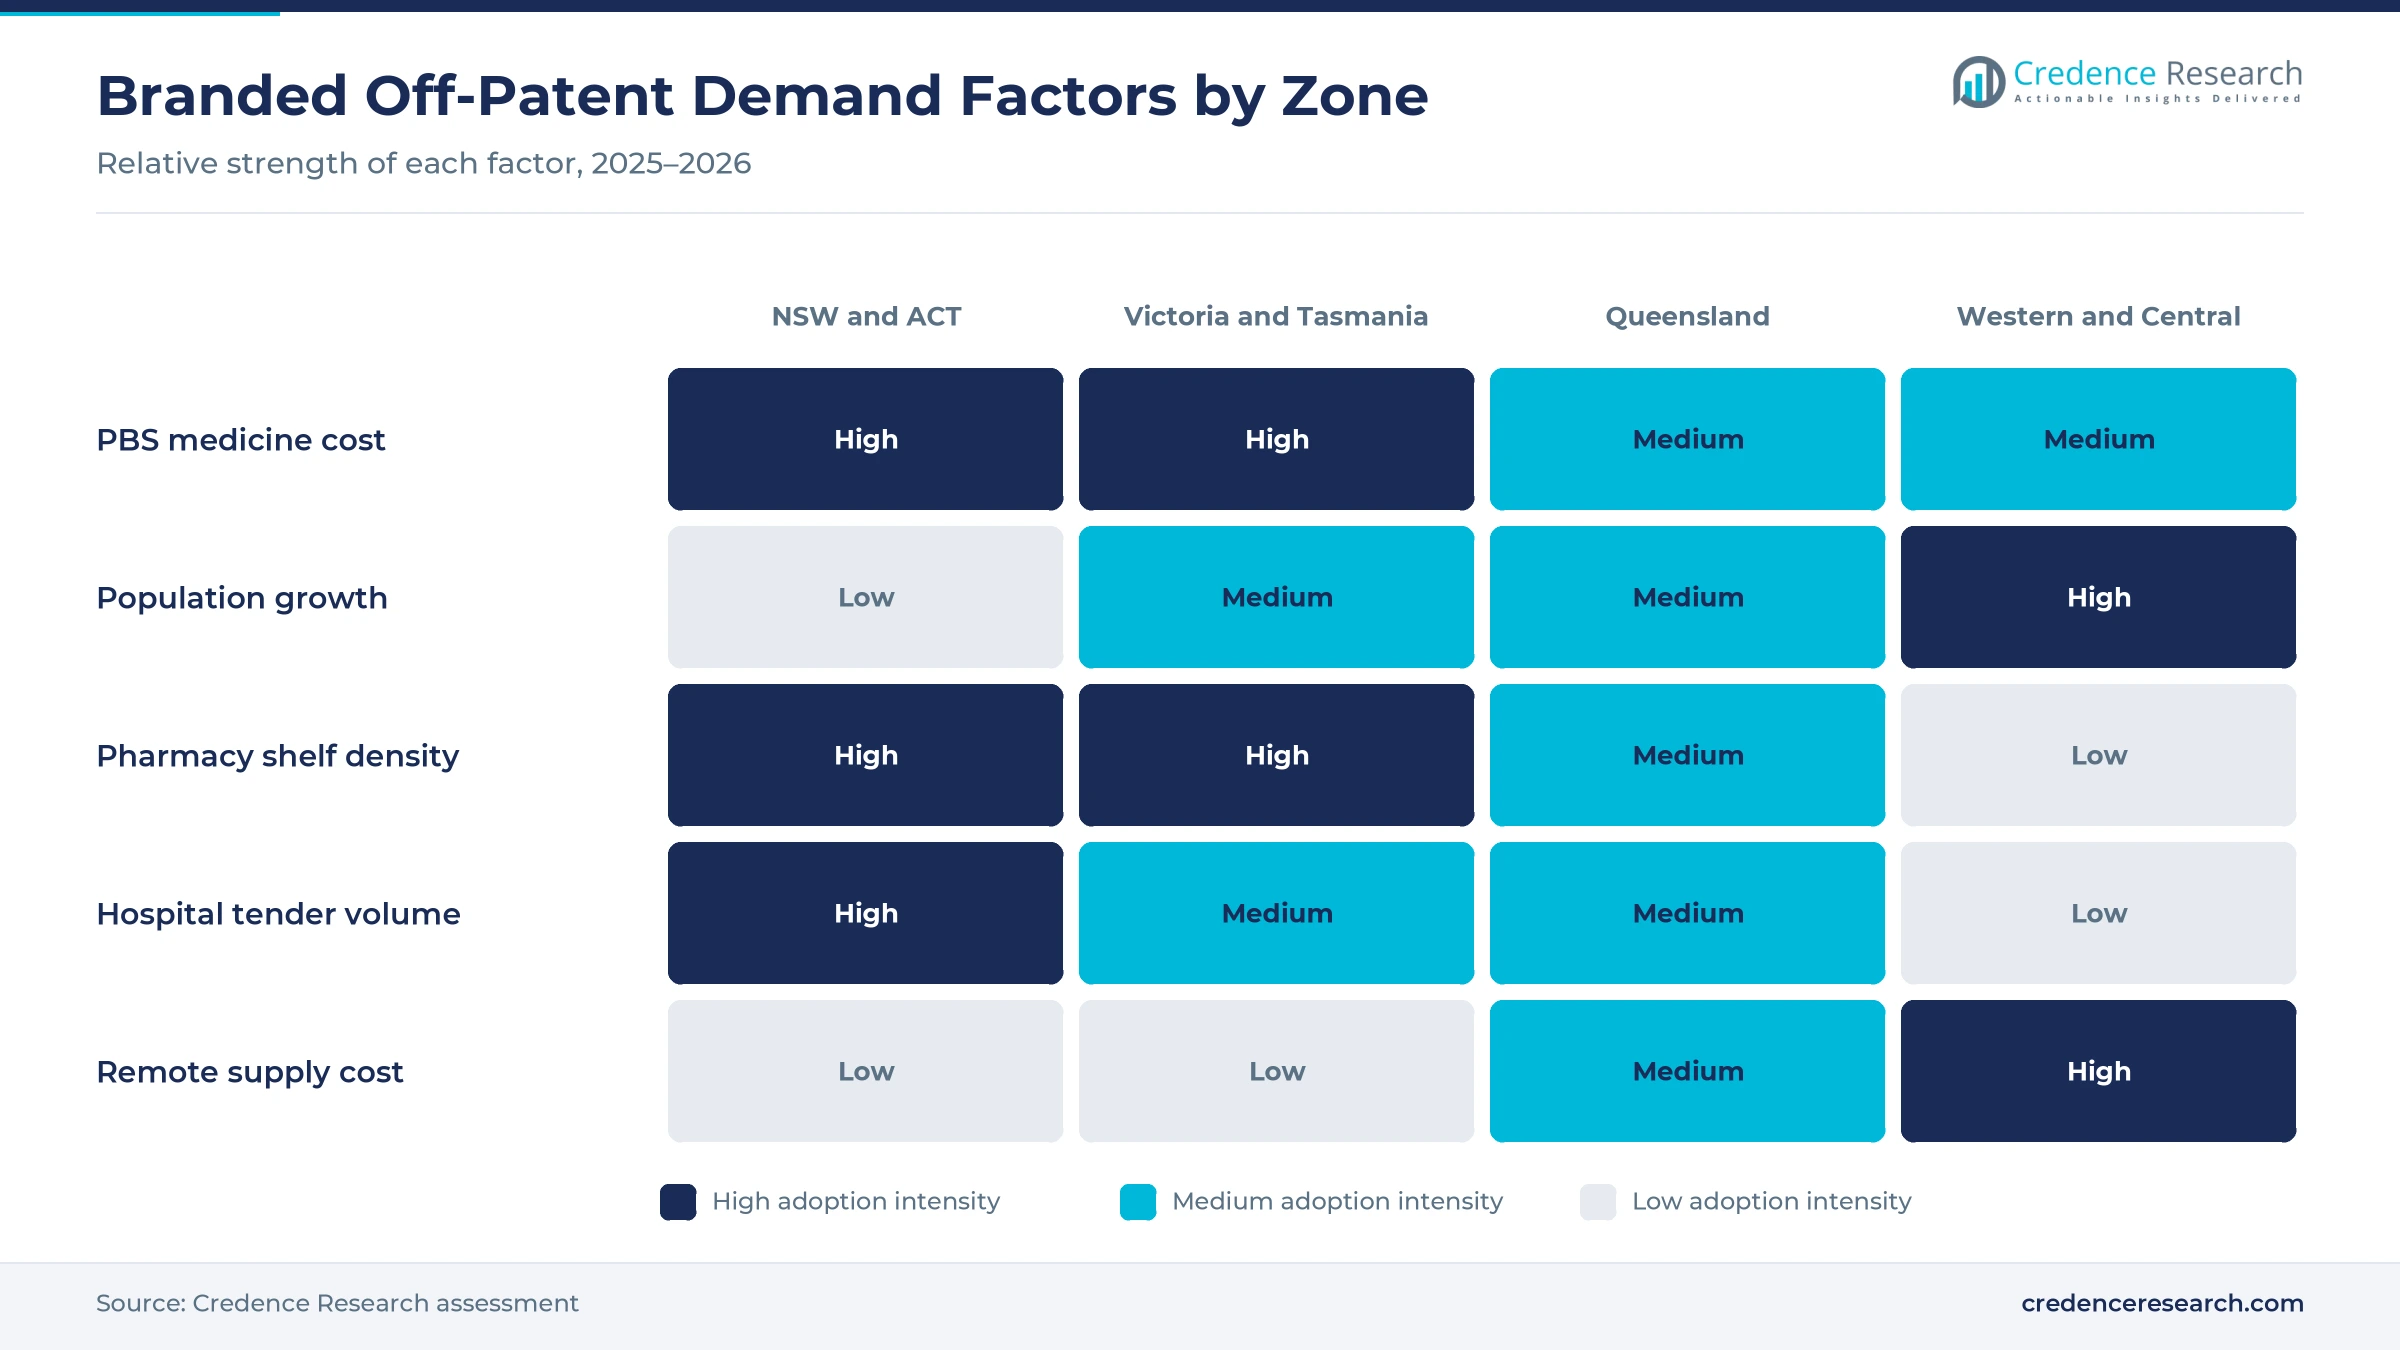
Long-term treatment keeps patients on the same brand for years, which gives off-patent brand owners steady refill demand. One in two Australians, or 12.6 million people, had at least one chronic condition in 2022, according to the Australian Bureau of Statistics, and mental and behavioral conditions affected 26.1% of the population. PBS tables for 2024-25 show that rosuvastatin led prescription volume with 16.0 million scripts, followed by atorvastatin at 11.1 million, and both molecules are sold under originator and named generic brands. Metformin and other diabetes treatment options add further daily refills. As a result, Cardiometabolic Disorders held 34.0% of 2025 value.
Why does off-patent portfolio renewal add new branded value?
Each wave of patent expiry moves another group of trusted medicines into branded off-patent supply, which renews the portfolio that sponsors can market. The Department of Health, Disability and Ageing lists 39 biosimilar brands across 16 active ingredients subsidized on the PBS as of Feb. 1, 2026. Pearce IP reports that Sandoz's denosumab brands Wyost and Jubbonti were listed on Aug. 1, 2025, as the first biosimilars of Prolia and Xgeva. The same law firm reports that Sandoz's Afqlir became the first PBS-listed aflibercept biosimilar on Feb. 1, 2026. In turn, Parenteral Products grow fastest at 7.24% a year.
How does established OTC brand recognition protect premiums?
Familiar pharmacy brands keep a price premium because shoppers pick names they have used for years over unfamiliar equivalents. Haleon ANZ, which markets Panadol, Voltaren, Centrum and Sensodyne, marked three years as a standalone company in August 2025 after its July 2022 demerger from GSK, according to Pharmacy Daily. Patients themselves paid AUD 1.7 billion toward PBS medicines in 2024-25, or 8.3% of total medicine cost, according to PBS data. Opella, the former Sanofi consumer arm, became a standalone company after Sanofi and CD&R closed their transaction on April 30, 2025, with Sanofi keeping a 48.2% stake, and Opella sells Telfast, Buscopan and Dulcolax in Australia. As a result, Pharmacy OTC brands hold their price premium even when cheaper equivalents sit on the same shelf.
How do lower co-payments and 60-day scripts lift dispensing?
Affordability reforms reduce the cost of each repeat prescription, which helps patients stay on treatment and keeps branded refills moving. The PBS Expenditure and Prescriptions Report for 2024-25 records AUD 19.1 billion in government medicine spending, up 7.4% from 2023-24, across 226 million subsidized prescriptions and 5,164 listed brands. Since Sept. 1, 2023, doctors can prescribe a 60-day supply of selected PBS medicines, and the health department expected more than 300 medicines to qualify by September 2024. The general patient co-payment then fell to AUD 25 on Jan. 1, 2026, while the concession co-payment stays at AUD 7.70 until 2029. In turn, community pharmacies remain the main outlet for these subsidized repeat prescriptions.
Licensing deals, biosimilars and an older patient base
Why are originator brands shifting to local partners?
Global owners are handing mature brands to local partners and investors, which shifts who markets branded off-patent medicines in Australia. Pharmacy Daily reported that Arrotex Pharmaceuticals and Pfizer Australia agreed on Feb. 12, 2026, that Arrotex will market Enbrel to community pharmacies, hospital pharmacies and prescribers. Aspen Pharmacare announced on Dec. 29, 2025, the sale of its Asia Pacific business outside China, including Australia, to BGH Capital for AUD 2.37 billion, and it announced completion on May 29, 2026. Generic Health also began trading as Lupin AU from April 2, 2026, to align with its global parent. As a result, sponsors with deep pharmacy networks gain more branded licensing deals.
How is the rise of branded biosimilars changing hospital supply?
Branded biosimilars are spreading from arthritis drugs into bone, eye and immunology care, which moves more hospital and specialist value into branded off-patent supply. The federal biosimilar list shows Nepexto and Erelzy etanercept brands added in 2025, and Ixifi infliximab added on Nov. 1, 2025. Steqeyma became the first ustekinumab biosimilar and Omlyclo the first omalizumab biosimilar on the PBS on Aug. 1, 2025. Fresenius Kabi withdrew its Idacio adalimumab biosimilar from Australia from Aug. 1, 2024, for commercial viability reasons, according to Pearce IP, which shows that not every launch holds share. In turn, Hospital Procurement grows fastest at 7.03% a year.
Can an older population open more branded refill demand?
A larger older population creates an opening for brands that patients and carers already trust for daily treatment. Australians aged 65 and over made up 18.1% of the population in 2025, up from 17.4% in 2023, according to the World Bank. The ABS National Health Survey found that about 79% of people aged 65 and over had at least one chronic condition in 2022, which raises the number of daily medicines per person. Concession cardholders filled 196.7 million subsidized prescriptions in 2024-25, 87.0% of the PBS total. As a result, Older Adults held 53.0% of 2025 value, and suppliers that offer dose packing and consistent pill appearance can win loyal patients.
Is reliable local supply an opening for branded sponsors?
Repeated shortages create an opening for sponsors that hold local stock or make medicines in Australia. The TGA issued Serious Scarcity Substitution Instruments in 2025 and 2026 for Presolol labetalol, Catapres clonidine and Zimstat simvastatin, which let pharmacists swap brands without prior prescriber approval. Asthma Australia reported that GSK expects Ventolin Nebules shortages to last until August and December 2026, depending on strength. The Strategic Agreement with the Generic and Biosimilar Medicines Association, which runs from July 1, 2022, to June 30, 2027, includes a Medicines Supply Security Guarantee with mandatory stock levels. In turn, local contract manufacturing capacity becomes a selling point.
Statutory price cuts, shortages and OTC pack limits
How do statutory price cuts compress branded margins?
PBS pricing rules reduce the subsidized price of a molecule once cheaper brands compete, so branded sponsors must justify any premium on top of a falling base price. The 2022 Strategic Agreements were expected to generate net savings of about AUD 1.9 billion through statutory pricing changes. As a result, patients pay the brand premium themselves, and many switch when a pharmacist offers an equivalent brand. Sponsors respond with patient support programs, pack design and pharmacy trading terms.
Why do shortages expose import-dependent brands?
Most branded off-patent medicines are made overseas, so factory problems, freight delays and demand spikes abroad can leave Australian pharmacies without a familiar brand. Every shortage invites substitution, and a patient who moves to another brand during a shortage may not return. The TGA's Serious Scarcity Substitution Instrument for Zimstat simvastatin shows how a shortage can move patients to another brand of a widely used statin. Sponsors reduce this risk by holding more local stock, qualifying second sources and packing medicines in Australia.
How do OTC pack limits reshape analgesic sales?
Tighter rules on popular non-prescription medicines can reduce pack sizes and shift sales between retail channels. From Feb. 1, 2025, the Therapeutic Goods Administration limited paracetamol packs in supermarkets and convenience stores to 16 tablets and cut open-shelf pharmacy packs to 50 tablets. As a result, branded analgesic owners lost some grocery volume and had to redesign blister packs. In Queensland and Western Australia, pharmacy packs larger than 16 tablets are kept behind the counter, so more sales pass through a pharmacist.
Why does active ingredient prescribing weaken brand pull?
Prescriptions in Australia name the active ingredient first, and pharmacists may offer any equivalent brand unless the prescriber blocks substitution. This makes cheaper equivalents visible at every dispensing, so branded products must earn loyalty rather than rely on habit. As a result, originator brands lose share faster in price-sensitive groups. Sponsors counter with recognizable packaging, consistent supply and education for pharmacists and prescribers.
NSW and ACT lead while western and central zones climb
| Region | Value, 2025 (USD billion) | Share, 2025 | CAGR, 2026–2035 |
|---|---|---|---|
| New South Wales and Australian Capital Territory | 1.50 | 36.3% | 5.99% |
| Victoria and Tasmania | 1.09 | 26.3% | 6.29% |
| Queensland | 0.84 | 20.3% | 6.39% |
| Western and Central Australia | 0.71 | 17.1% | 6.54% |
Why do NSW and ACT lead branded medicine spending?
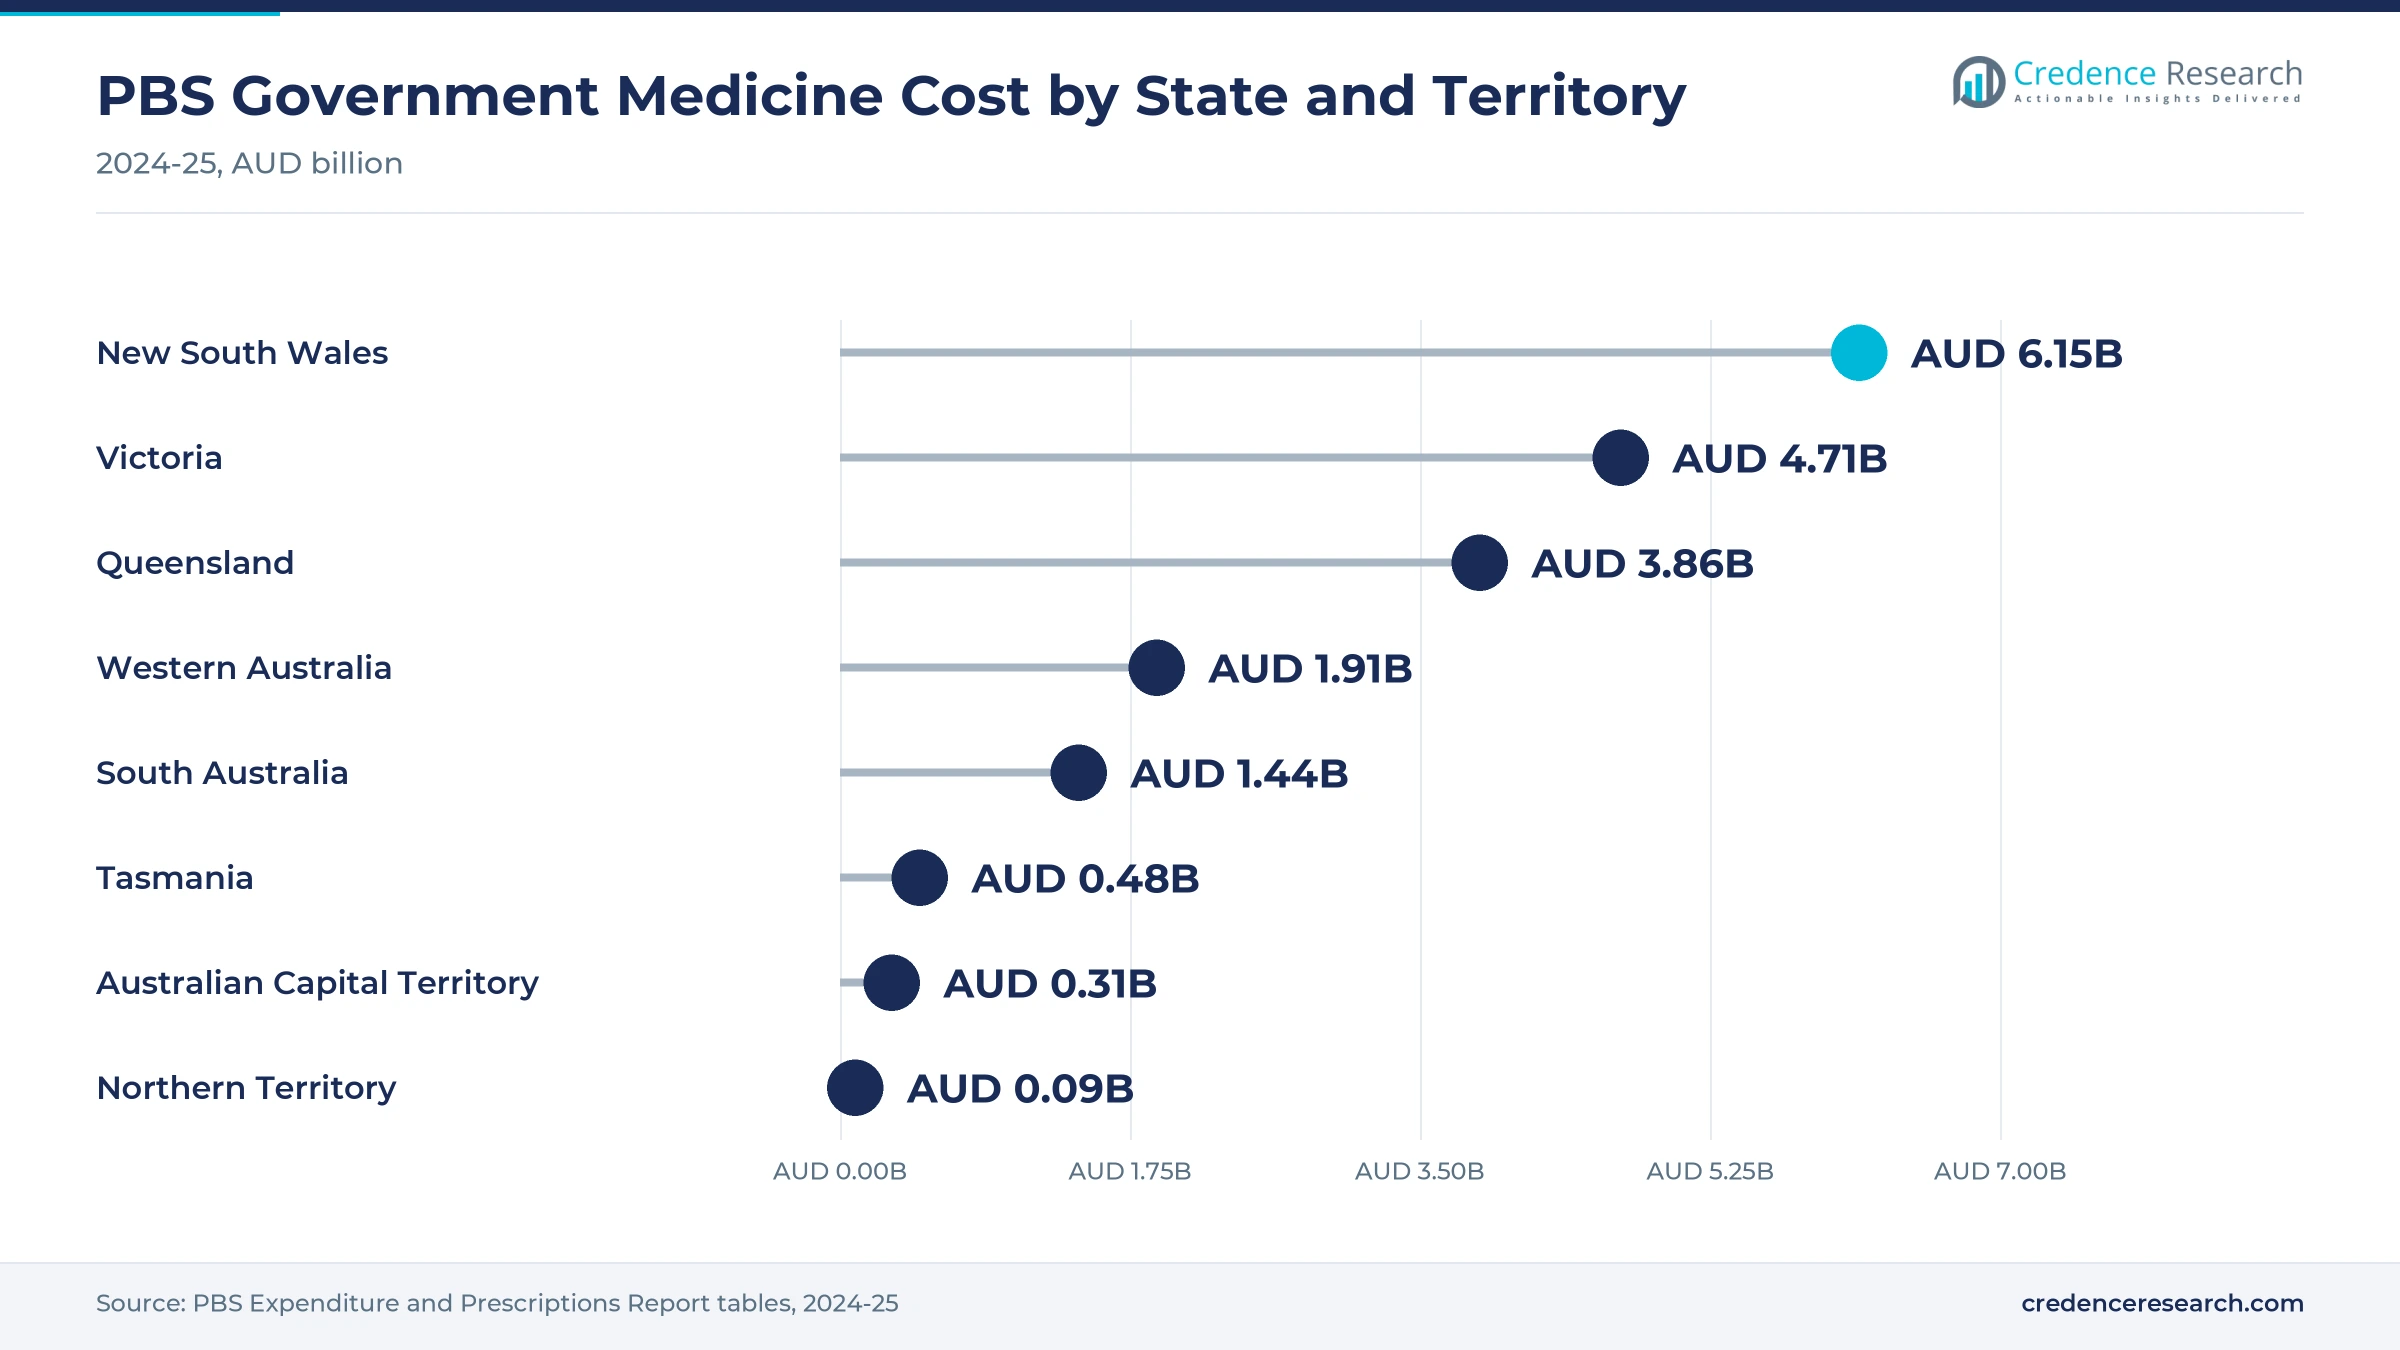
New South Wales and Australian Capital Territory held 36.3% of 2025 value and grow at 5.99% a year, because the zone holds the largest population of any state and the national capital. PBS tables show government medicine cost of AUD 6.1 billion in New South Wales and AUD 0.3 billion in the Australian Capital Territory in 2024-25. The ABS estimates that New South Wales grew 1.1% to 8.67 million residents in the year to March 31, 2026, so the zone grows more slowly than the national average.
Why does Victoria's population growth lift its zone?
Victoria and Tasmania held 26.3% of 2025 value and grow at 6.29% a year, as Victoria adds residents quickly while Tasmania grows slowly. PBS tables show government medicine cost of AUD 4.7 billion in Victoria and AUD 0.5 billion in Tasmania in 2024-25. Victoria grew 1.6% to 7.15 million residents in the year to March 31, 2026, while Tasmania had the slowest growth at 0.6%.
How do coastal retirees support Queensland demand?
Queensland held 20.3% of 2025 value and grows at 6.39% a year, as the state added 90,100 residents to reach 5.74 million in the year to March 31, 2026. PBS government medicine cost in Queensland reached AUD 3.9 billion in 2024-25 across 47.3 million subsidized prescriptions. Queensland grew 1.6% in the year to March 31, 2026, matching the growth rate of Victoria and outpacing New South Wales. As a result, coastal towns with many retirees sustain refills of cardiometabolic brands.
Why do western and central zones grow fastest?
Western and Central Australia held 17.1% of 2025 value and grows fastest at 6.54% a year, because Western Australia has the fastest-growing population in the country. The ABS reports that Western Australia grew 2.1% to 3.10 million residents in the year to March 31, 2026, while South Australia grew 1.0% and the Northern Territory 1.5%. PBS government medicine cost in the three jurisdictions totaled about AUD 3.4 billion in 2024-25, and new suburbs around Perth add steady refill demand.

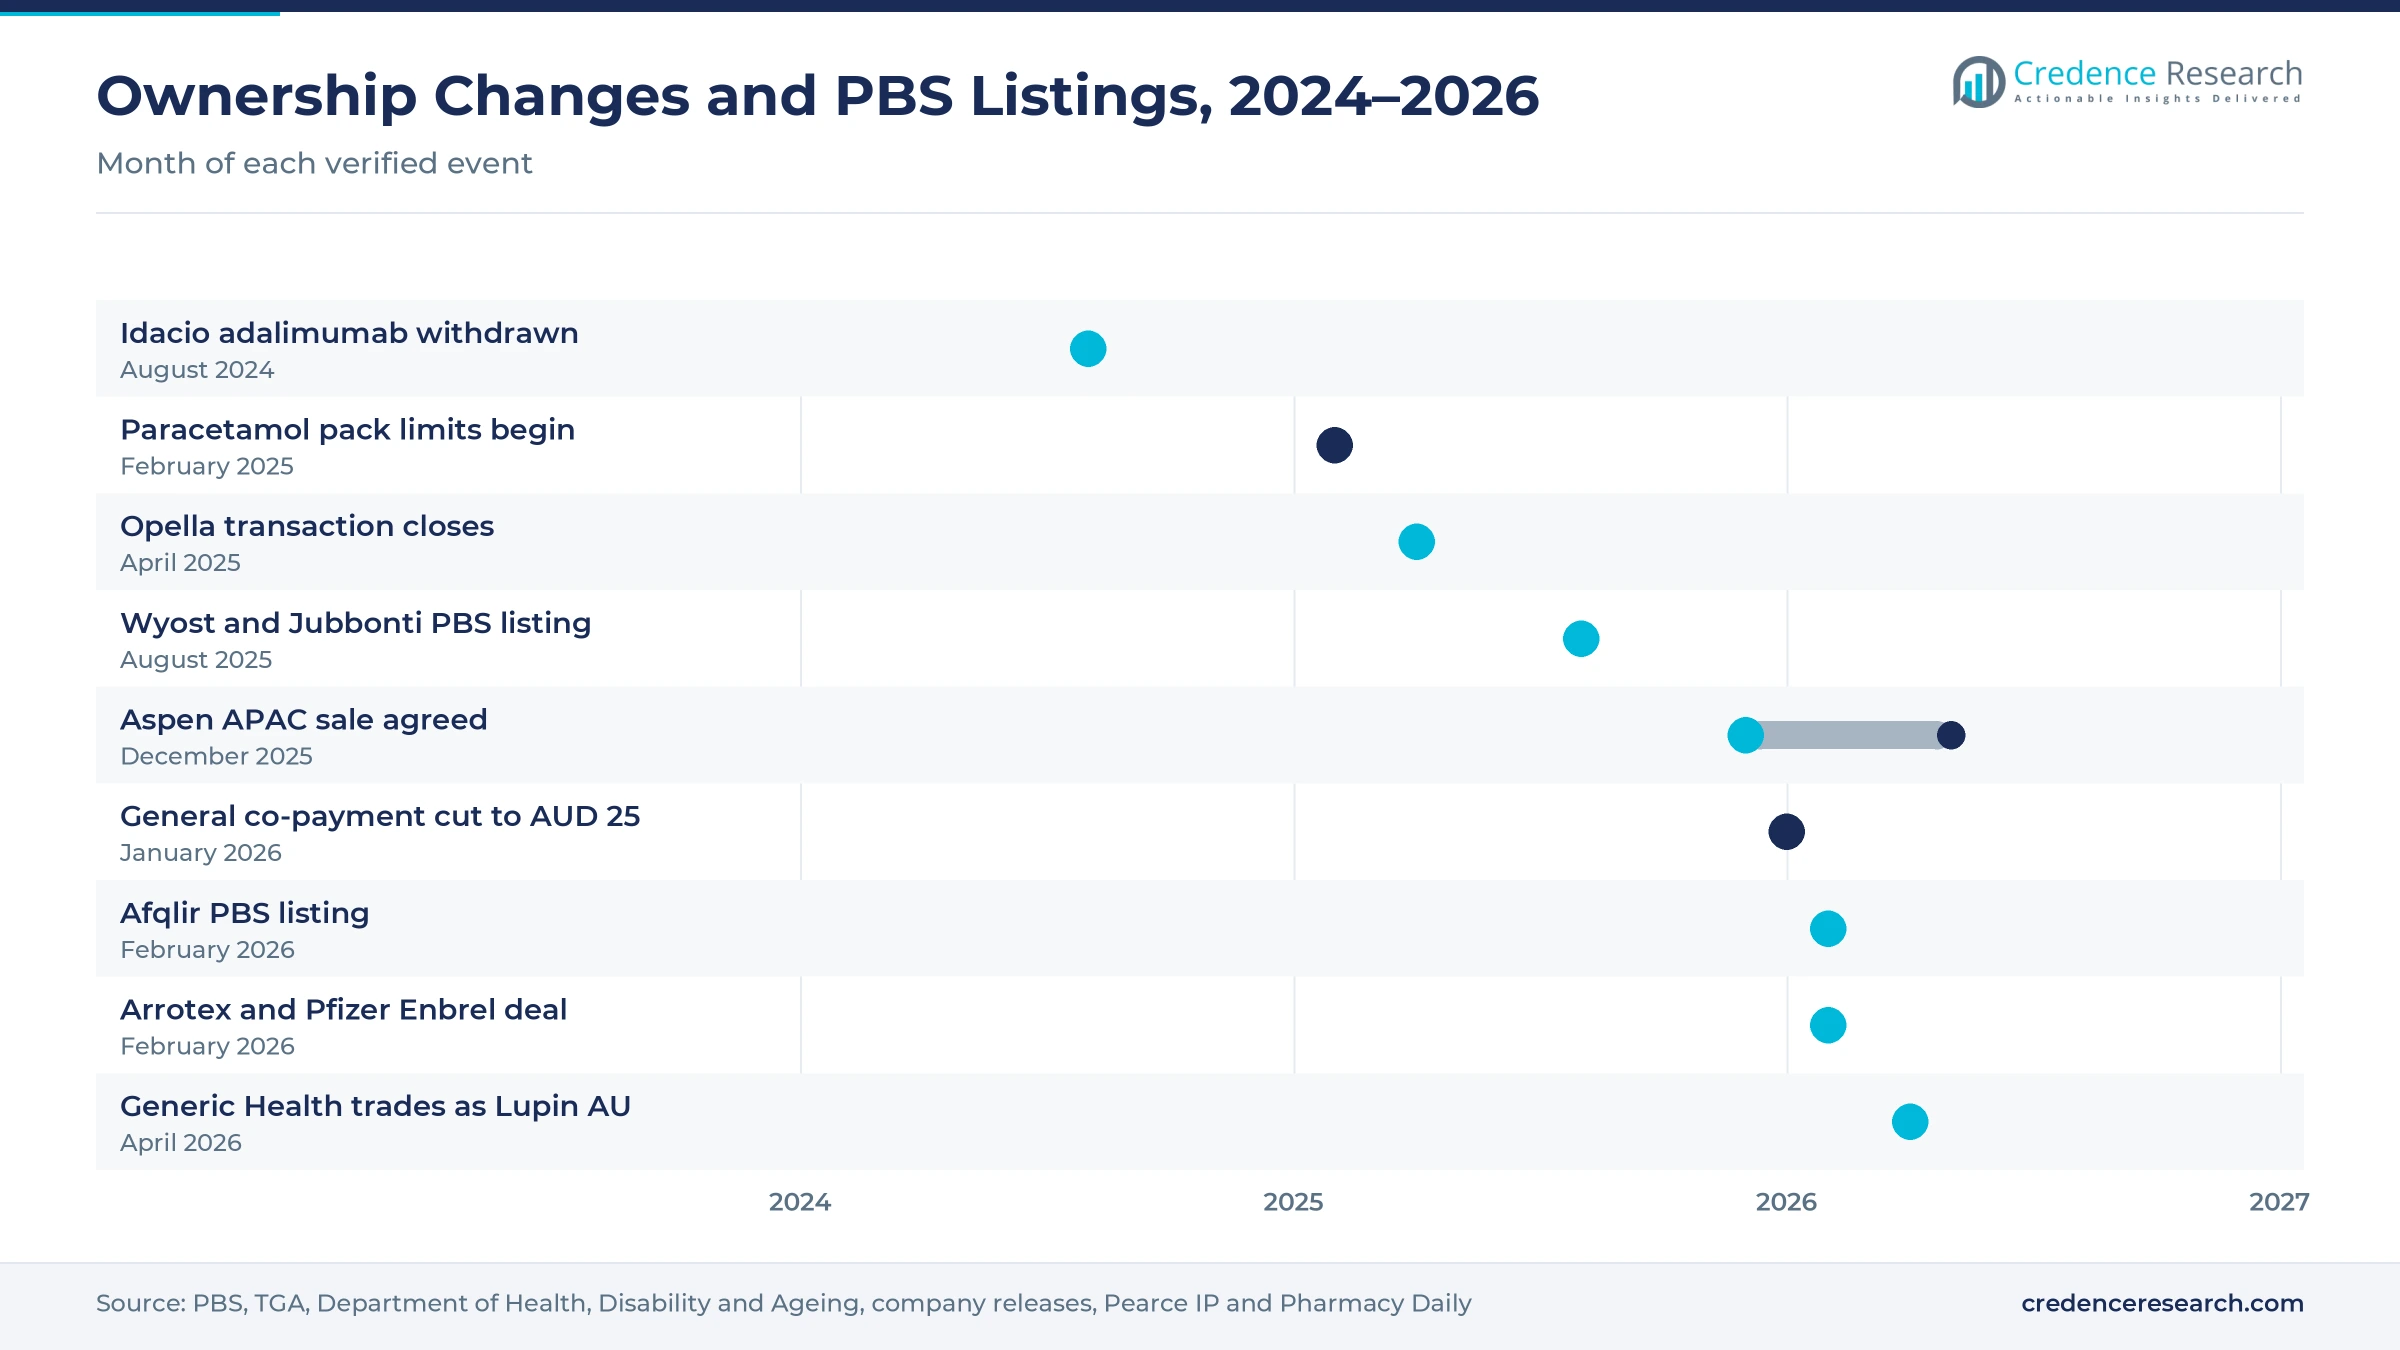
Ownership changes and PBS listings, 2024–2026
| Development | Status and market relevance |
|---|---|
| In April 2025, Sanofi and CD&R closed the Opella transaction, making the owner of Telfast, Buscopan and Dulcolax a standalone consumer health company. | Created a separate owner for leading pharmacy brands |
| In August 2025, Sandoz's denosumab biosimilars Wyost and Jubbonti became the first biosimilars of Prolia and Xgeva listed on the PBS. | Extended branded biosimilar competition into bone care |
| In December 2025, Aspen Pharmacare agreed to sell its Asia Pacific business outside China, including Australia, to BGH Capital for AUD 2.37 billion. | Completed in May 2026 under new local private equity ownership |
| In February 2026, Arrotex Pharmaceuticals and Pfizer Australia agreed that Arrotex will market Enbrel to pharmacies, hospitals and prescribers. | Added an originator biologic to a local partnership platform |
| In April 2026, Generic Health began trading as Lupin AU to align its Australian business with its global parent. | Unified the local brand with the parent company name |
Substitution and pricing rules decide brand choice
- Brand substitution flags let pharmacists swap equivalent brands with patient consent unless the prescriber marks that substitution is not permitted.
- Brand premiums are the extra amount a patient pays above the PBS price for a chosen brand, which tests how much loyalty a brand holds.
- Serious Scarcity Substitution Instruments allow pharmacists to dispense a listed alternative without prior prescriber approval when a named medicine is scarce.
- Modified-release and complex delivery formats such as extended-release tablets, pens and prefilled syringes help brands stand apart, linking value to drug delivery formats that patients find easier to use.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Local licensors and global groups compete on trust
Competition for branded off-patent medicines in Australia combines local licensing specialists, global originators and consumer health groups. Arrotex Pharmaceuticals added Pfizer's Enbrel to its partnerships platform in February 2026. Viatris Australia states that it offers more than 450 formulations and employs about 800 people. Haleon Australia sells Panadol, Voltaren and Centrum, while Opella, the former Sanofi consumer arm, sells Telfast, Buscopan and Dulcolax. Sandoz Australia has listed Wyost, Jubbonti and Afqlir as branded biosimilars on the PBS since 2025. Fresenius Kabi Australia withdrew its Idacio adalimumab biosimilar from August 2024 for commercial viability reasons, and GSK Australia supplies Ventolin Nebules, which face shortages through 2026. Aspen's Australian business moved to BGH Capital in May 2026, and Generic Health now trades as Lupin AU. Rivals compete on brand trust, supply reliability, pharmacy trading terms and the speed of new off-patent launches.
Which companies shape branded off-patent supply in Australia?
| Company | Type | Role in the market |
|---|---|---|
| Arrotex Pharmaceuticals | Local licensing partner | Markets Pfizer's Enbrel to pharmacies, hospitals and prescribers from February 2026 |
| Viatris Australia | Off-patent brand owner | Offers more than 450 formulations with about 800 local employees |
| Haleon Australia | Consumer health brand owner | Sells Panadol, Voltaren, Centrum and Sensodyne through pharmacies and retailers |
| Sanofi Australia (Opella) | Consumer health brand owner | Opella sells Telfast, Buscopan and Dulcolax as a standalone consumer health company since April 2025 |
| Sandoz Australia | Biosimilar and generic maker | Listed Wyost, Jubbonti and Afqlir biosimilars on the PBS in 2025 and 2026 |
| Aspen Pharmacare Australia | Branded off-patent supplier | Sold to BGH Capital in a deal completed in May 2026 |
| Generic Health | Named generic supplier | Trades as Lupin AU from April 2026 |
| Fresenius Kabi Australia | Injectable and biosimilar supplier | Withdrew its Idacio adalimumab biosimilar from August 2024 |
| GSK Australia | Originator brand owner | Supplies Ventolin Nebules, which face shortages through 2026 |
Credence Research view on branded off-patent demand
Credence Research's view is that Australian branded off-patent value will grow steadily, because an older population takes more daily medicines and trusted brands keep a premium at the pharmacy. Growth will come mostly from parenteral and specialist products, as branded biosimilars for bone, eye and immunology care reach the PBS. Ownership changes in branded generics, from the Aspen sale to new licensing deals with local partners, will decide who markets mature brands. However, active ingredient prescribing and frequent shortages will keep testing loyalty, so supply reliability will matter as much as brand recognition.
How the national branded off-patent estimate was built
The report uses 2025 as the base year on a calendar basis, and market values come from the Credence Research model. That model combines PBS expenditure and prescription statistics, state population data, chronic disease prevalence data and company product information. Segment splits, zone shares and zone growth rates are Credence Research estimates. Sources used are government agencies, official statistics, international organizations, legal publications, trade publications and company publications, and no interviews or surveys were conducted.
Older patients and injectables shape value to 2035
Value across Australian branded off-patent medicines is expected to reach USD 7.60 billion by 2035, a 6.25% CAGR during 2026–2035, as an older population, lower co-payments and new branded biosimilars lift demand. Growth should be strongest in Western and Central Australia, where population growth is fastest, and in hospital procurement of injectable brands. Oral products will remain the largest group, while pharmacy shelf brands keep loyal buyers. Sponsors that combine trusted names with reliable local stock should gain share through 2035.
Frequently Asked Questions
How big is the Australia branded generics market?
Which product type leads branded off-patent sales in Australia?
Which region leads branded off-patent spending in Australia?
How does the lower PBS co-payment affect branded medicines?
Why do patients stay with branded off-patent medicines?
Which therapy area leads branded off-patent value?
Which companies compete in branded off-patent medicines in Australia?
What are the main challenges for branded off-patent sponsors?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Product Type
- 1.2.1 Oral Products
- 1.2.2 Parenteral Products
- 1.2.3 Topical Products
- 1.2.4 Inhaled and Ophthalmic Products
- 1.3 By Disease Area
- 1.3.1 Cardiometabolic Disorders
- 1.3.2 Oncology
- 1.3.3 Central Nervous System Disorders
- 1.3.4 Respiratory and Remaining Therapeutic Areas
- 1.4 By Channel
- 1.4.1 PBS Community Prescription
- 1.4.2 Private Community Prescription
- 1.4.3 Pharmacy OTC
- 1.4.4 Hospital Procurement
- 1.5 By End User
- 1.5.1 Paediatric Patients
- 1.5.2 Working-Age Adults
- 1.5.3 Older Adults
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2025: USD 4.13 billion → 2035: USD 7.60 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Historical Period: 2018-2025
- 2.6.2 Base Year: 2025
- 2.6.3 Forecast Period: 2025-2035
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2025
- 3.3 Forecast Market Size, 2035
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Australia Branded Generics Market Trends and Developments
- 4.1 Historical Industry Development, 2018-2025
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Australia Branded Generics Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis, 2018-2025
- 5.2 Demand Forecast, 2025-2035
- 5.3 Production and Output Trend, 2018-2025
- 5.4 Production and Output Forecast, 2025-2035
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Australia Branded Generics Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends, 2018-2025
- 6.3 Pricing Outlook, 2025-2035
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Australia Branded Generics Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Australia Branded Generics Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Australia Branded Generics Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Australia Branded Generics Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Australia Branded Generics Market Outlook, 2025-2035
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2025: USD 4.13 billion → 2035: USD 7.60 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size, 2018-2025
- 11.1.4 Base-Year Market Size, 2025
- 11.2 Market Forecast, 2025-2035
- 11.2.1 Revenue Forecast to 2035
- 11.2.2 Volume Forecast to 2035
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Australia Branded Generics Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2025
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Product Type - Market Size and Forecast, 2025-2035
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size, 2018-2025
- 12.3.3 Revenue Forecast, 2025-2035
- 12.3.4 Volume Forecast, 2025-2035
- 12.3.5 Base-Year Market Share, 2025
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Oral Products
- 12.3.7.2 Parenteral Products
- 12.3.7.3 Topical Products
- 12.3.7.4 Inhaled and Ophthalmic Products
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Disease Area - Market Size and Forecast, 2025-2035
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size, 2018-2025
- 12.4.3 Revenue Forecast, 2025-2035
- 12.4.4 Volume Forecast, 2025-2035
- 12.4.5 Base-Year Market Share, 2025
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Cardiometabolic Disorders
- 12.4.7.2 Oncology
- 12.4.7.3 Central Nervous System Disorders
- 12.4.7.4 Respiratory and Remaining Therapeutic Areas
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Channel - Market Size and Forecast, 2025-2035
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size, 2018-2025
- 12.5.3 Revenue Forecast, 2025-2035
- 12.5.4 Volume Forecast, 2025-2035
- 12.5.5 Base-Year Market Share, 2025
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 PBS Community Prescription
- 12.5.7.2 Private Community Prescription
- 12.5.7.3 Pharmacy OTC
- 12.5.7.4 Hospital Procurement
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By End User - Market Size and Forecast, 2025-2035
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size, 2018-2025
- 12.6.3 Revenue Forecast, 2025-2035
- 12.6.4 Volume Forecast, 2025-2035
- 12.6.5 Base-Year Market Share, 2025
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Paediatric Patients
- 12.6.7.2 Working-Age Adults
- 12.6.7.3 Older Adults
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Australia Branded Generics End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Australia Branded Generics Geographic Market Outlook, 2025-2035
- 14.1 Domestic Market Distribution and Demand Clusters
- 14.2 State- or Province-Wise Market Size and Forecast, 2025-2035
- 14.3 City and Metropolitan Market Outlook
- 14.4 Industrial, Manufacturing and Commercial Clusters
- 14.5 Geographic Concentration of Key End Users
- 14.6 Local Pricing and Purchasing Differences
- 14.7 Domestic Production Facilities and Capacity Map
- 14.8 Local Infrastructure and Project Pipeline
- 14.9 State-Level Policy and Incentive Differences
- 14.10 Subnational Investment Hotspots and Opportunities
- 14.11 Distribution and Logistics Networks
- 14.12 Domestic Competitive Footprint
Chapter 15 Australia Branded Generics Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2025-2035
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Australia Branded Generics Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2025
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2025-2035
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Arrotex Pharmaceuticals
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Viatris Australia
- 18.4 Haleon Australia
- 18.5 Aspen Pharmacare Australia
- 18.6 AstraZeneca Australia
- 18.7 Sanofi Australia
- 18.8 Sandoz Australia
- 18.9 GSK Australia
- 18.10 Generic Health
- 18.11 Fresenius Kabi Australia
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

