
Gene silencing and mRNA medicines reach wider use
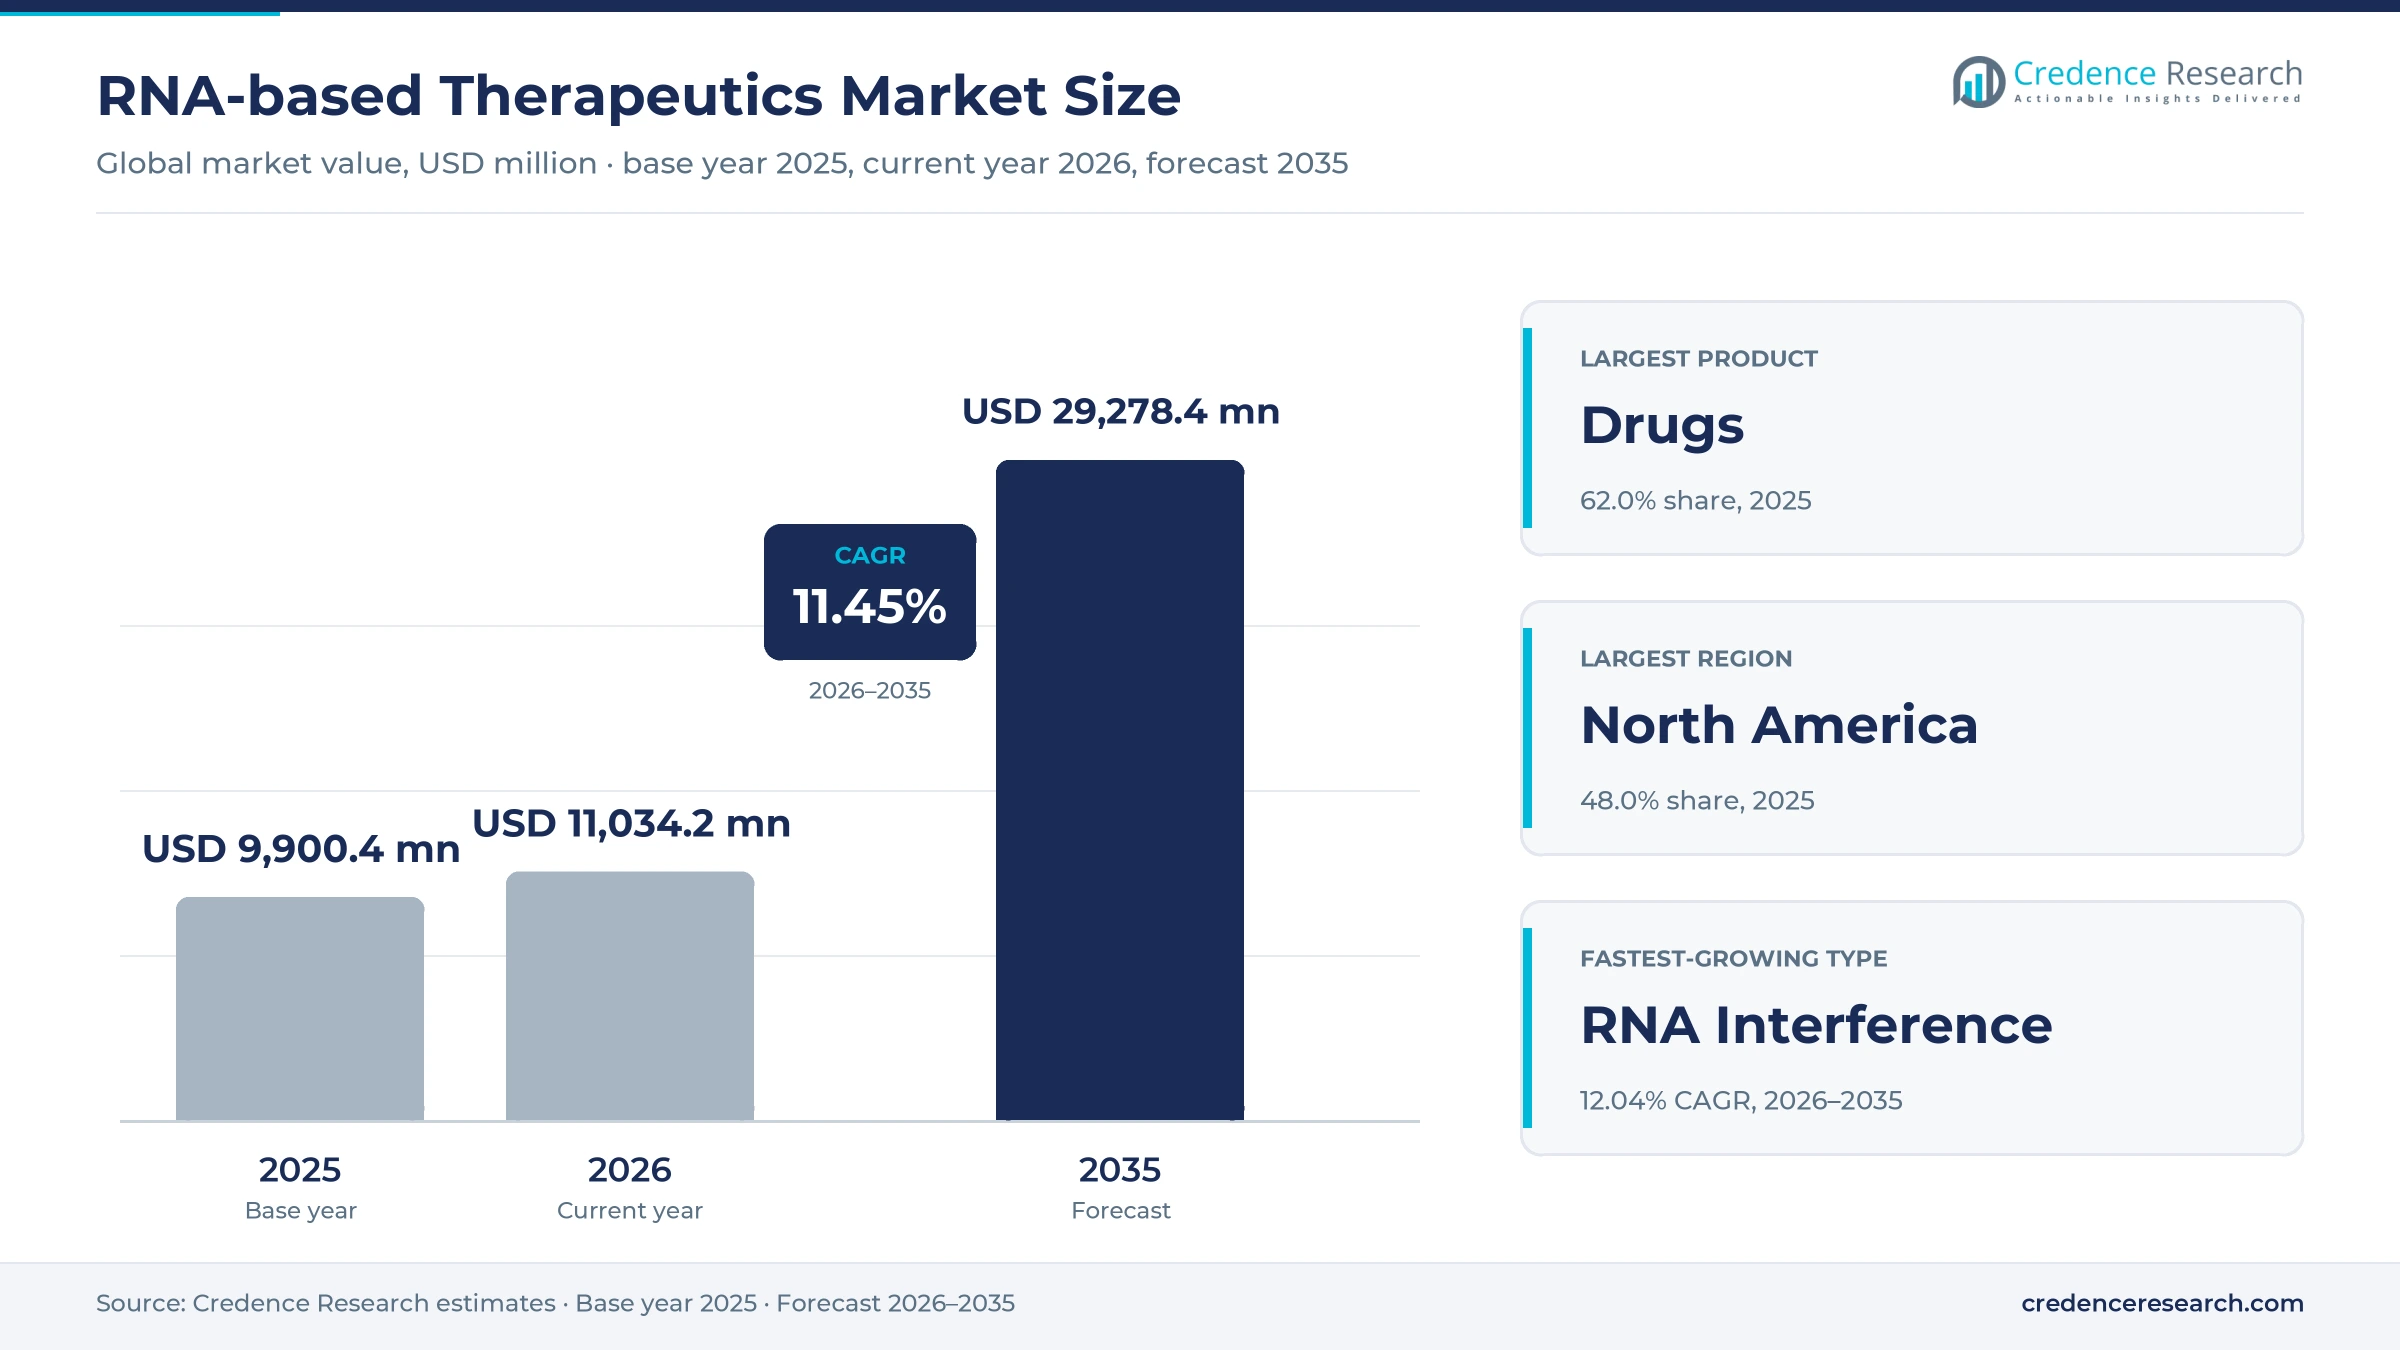
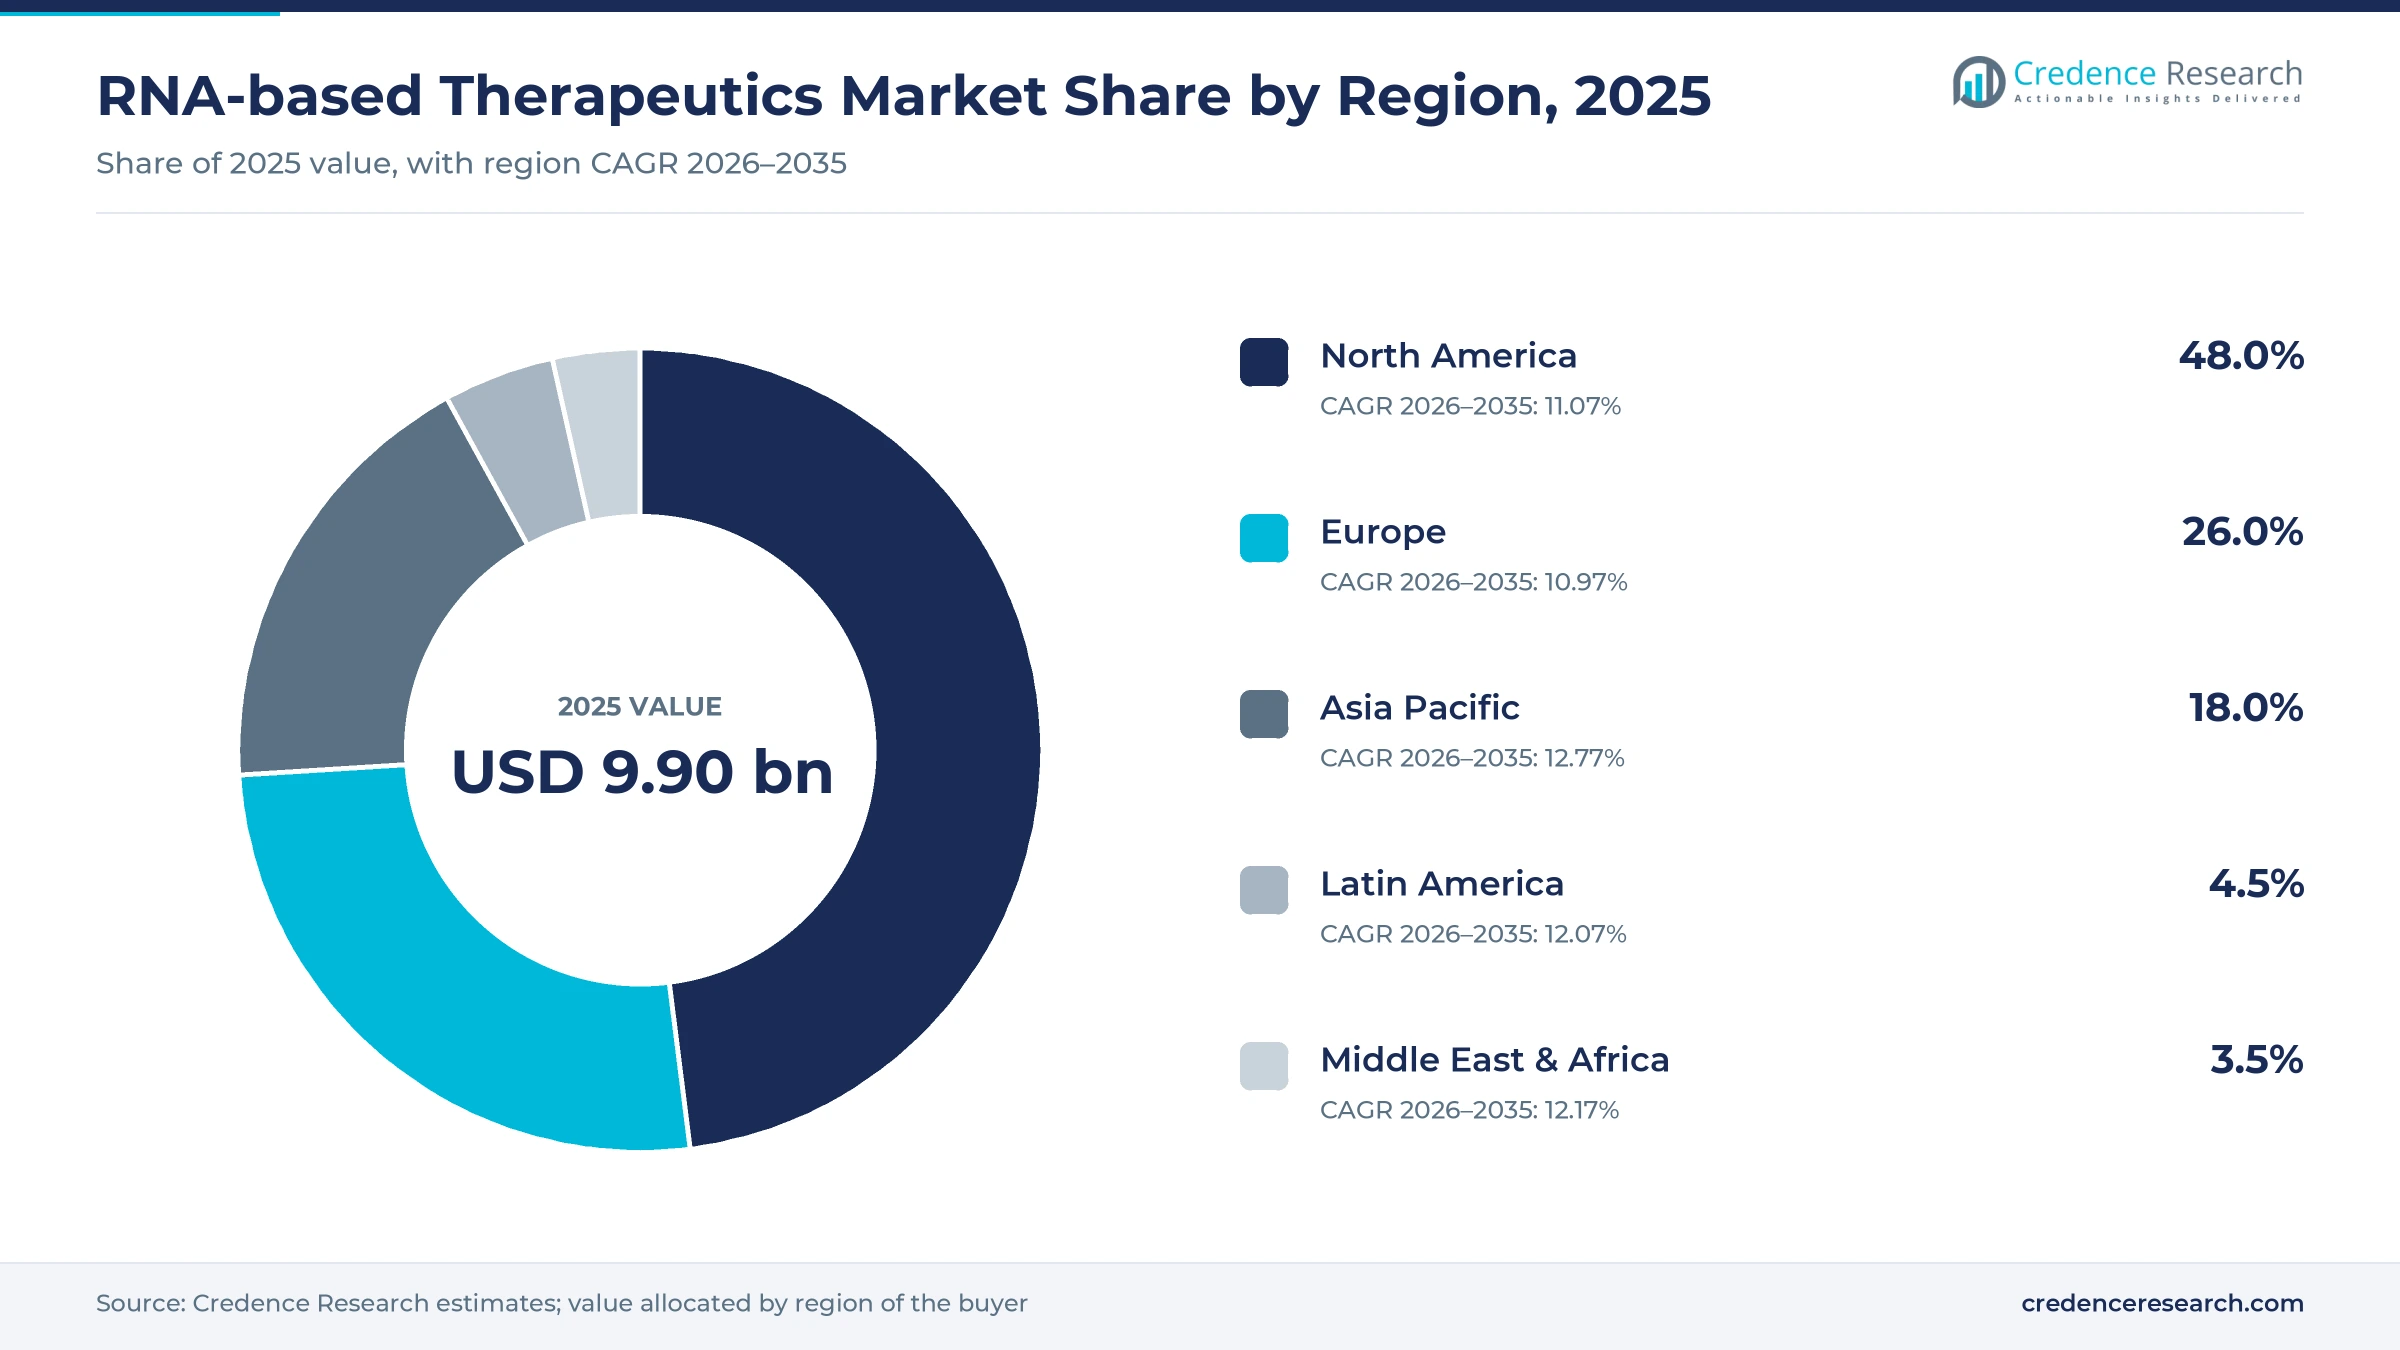
The global RNA-based therapeutics market was valued at USD 9.90 billion in 2025 and is projected to increase from USD 11.03 billion in 2026 to USD 29.28 billion by 2035, registering a CAGR of 11.45% during 2026–2035. Demand comes from small interfering RNA and antisense medicines for rare inherited disorders, heart disease and blood disorders, together with messenger RNA vaccines for respiratory infections. North America held the largest regional share, 48.0% in 2025, because most approved products launched first in the United States and carry high specialty prices there. Asia Pacific is the fastest-growing region at 12.77% a year, as China, Japan and South Korea expand local development and manufacturing. The commercial picture changed in March 2025, when the FDA approved the first siRNA medicine for hemophilia, dosed only once every two months. As a result, gene silencing moved further into common chronic conditions with large treated populations.
Which RNA medicines and vaccines does this analysis cover?
The analysis counts approved medicines and vaccines whose active ingredient is RNA or a synthetic strand that binds RNA, including small interfering RNA, antisense oligonucleotides, messenger RNA vaccines and related designs. Values are based on manufacturer selling prices for products bought by hospitals, specialty centers and research institutes.
Small molecules that target RNA, laboratory reagents, extraction kits and contract synthesis services sit outside the scope of this analysis. The value chain runs from platform developers and nucleotide suppliers through fill and finish plants to specialty distributors, hospital pharmacies and vaccination programs that reach patients.
RNA-based Therapeutics Market Insights
- The RNA-based therapeutics market grows from USD 9.90 billion in 2025 to USD 29.28 billion by 2035, an 11.45% CAGR as siRNA and antisense medicines reach larger patient groups.
- North America held 48.0% of global RNA medicine value in 2025, supported by early U.S. launches and specialty pricing.
- Drugs led product spending with 62.0% of 2025 value, while RNA interference grows fastest among types at 12.04% a year.
- In March 2025, the FDA approved Qfitlia, the first siRNA medicine for hemophilia A or B, given once every two months.
- In February 2026, Novartis completed its acquisition of Avidity Biosciences, adding muscle-directed antibody oligonucleotide conjugates to its pipeline.
Drugs lead as RNA interference gains the fastest
Why do drugs lead over vaccines in RNA medicine spending?
Based on product, the market is categorized into vaccines and drugs. Drugs led with a 62.0% share of 2025 value, because siRNA and antisense medicines for rare conditions carry high annual prices per patient. Drugs also grow fastest at 11.93% a year, as new labels add heart and blood disorders. Vaccine demand stabilized after the pandemic peak, yet newer messenger RNA vaccines for RSV and COVID-19 keep a sizable seasonal base.
Why does RNA interference grow fastest among types?
Based on type, the market is categorized into RNA interference, RNA antisense and other designs, which include messenger RNA. RNA Interference led with a 40.0% share of 2025 value and also grows fastest at 12.04% a year, because liver-targeted siRNA medicines need only two to six doses each year. Antisense medicines keep a strong position in neuromuscular and lipid disorders, while messenger RNA sits mainly in respiratory vaccines.
Why do rare genetic diseases grow fastest among indications?
Based on indication, the market is categorized into infectious diseases, rare genetic diseases and other conditions. Infectious Diseases led with a 40.0% share of 2025 value, because messenger RNA vaccines for COVID-19 and RSV still reach millions of adults each season. Rare Genetic Diseases grow fastest at 12.26% a year, as new approvals cover inherited lipid, blood, swelling and amyloid disorders that had few treatment options.
Why do specialty centers grow fastest among end users?
Based on end use, the market is categorized into hospital, specialty centers and research institutes. Hospital settings led with a 55.0% share of 2025 value, because infusions, first doses and many vaccinations happen there. Specialty Centers grow fastest at 11.95% a year, as hemophilia, amyloidosis and angioedema clinics manage long-term siRNA and antisense patients. Research institutes buy smaller volumes mainly for use in clinical studies.
| Segment Group | Leading Sub-segment | Share, 2025 | Fastest-growing Sub-segment | CAGR, 2026–2035 |
|---|---|---|---|---|
| By Product | Drugs | 62.0% | Drugs | 11.93% |
| By Type | RNA Interference | 40.0% | RNA Interference | 12.04% |
| By Indication | Infectious Diseases | 40.0% | Rare Genetic Diseases | 12.26% |
| By End Use | Hospital | 55.0% | Specialty Centers | 11.95% |
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Rare disease need and long dosing gaps lift demand
How does unmet need in rare disease lift demand for gene silencing?
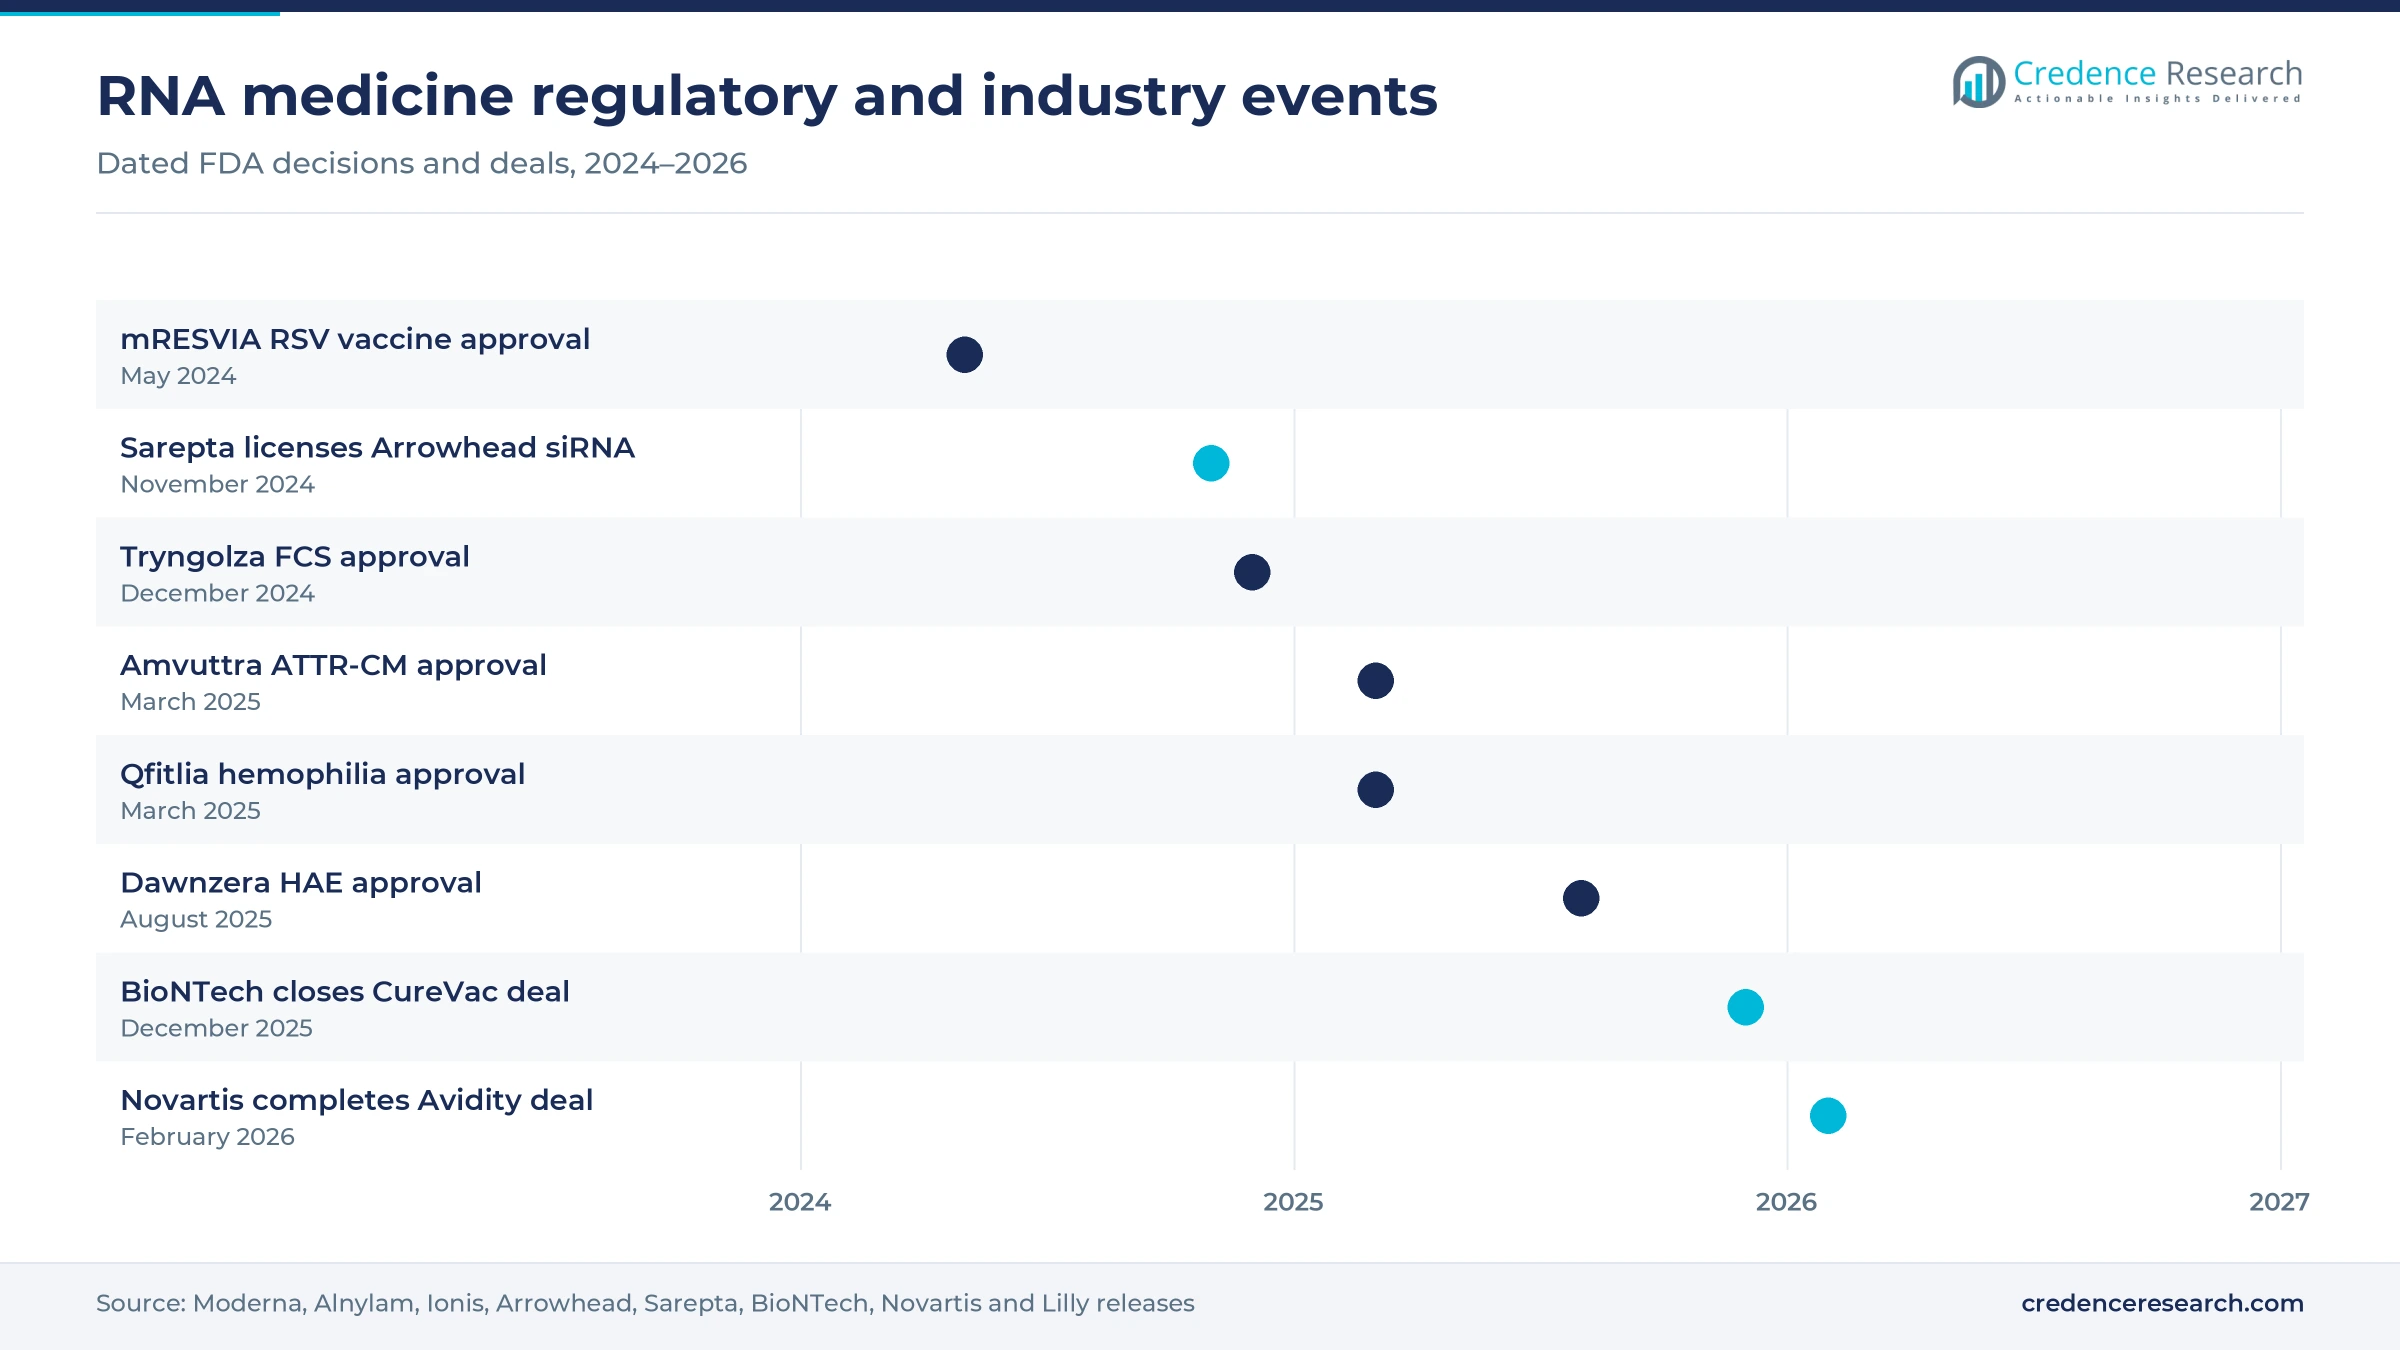
Unmet need in rare disease lifts demand for gene silencing, because RNA medicines can switch off a faulty gene product directly. The U.S. National Center for Advancing Translational Sciences counts about 10,000 known rare diseases affecting an estimated 25 million to 30 million people in the United States. The agency also notes that only about 5% of rare diseases have an FDA-approved treatment. In December 2024, Ionis received FDA approval for Tryngolza as the first treatment for adults with familial chylomicronemia syndrome. As a result, rare genetic diseases grow fastest among indications at 12.26% a year, as each new label reaches patients who previously had no approved medicine and stay on treatment for many years.
Why do long dosing intervals widen use of siRNA medicines?
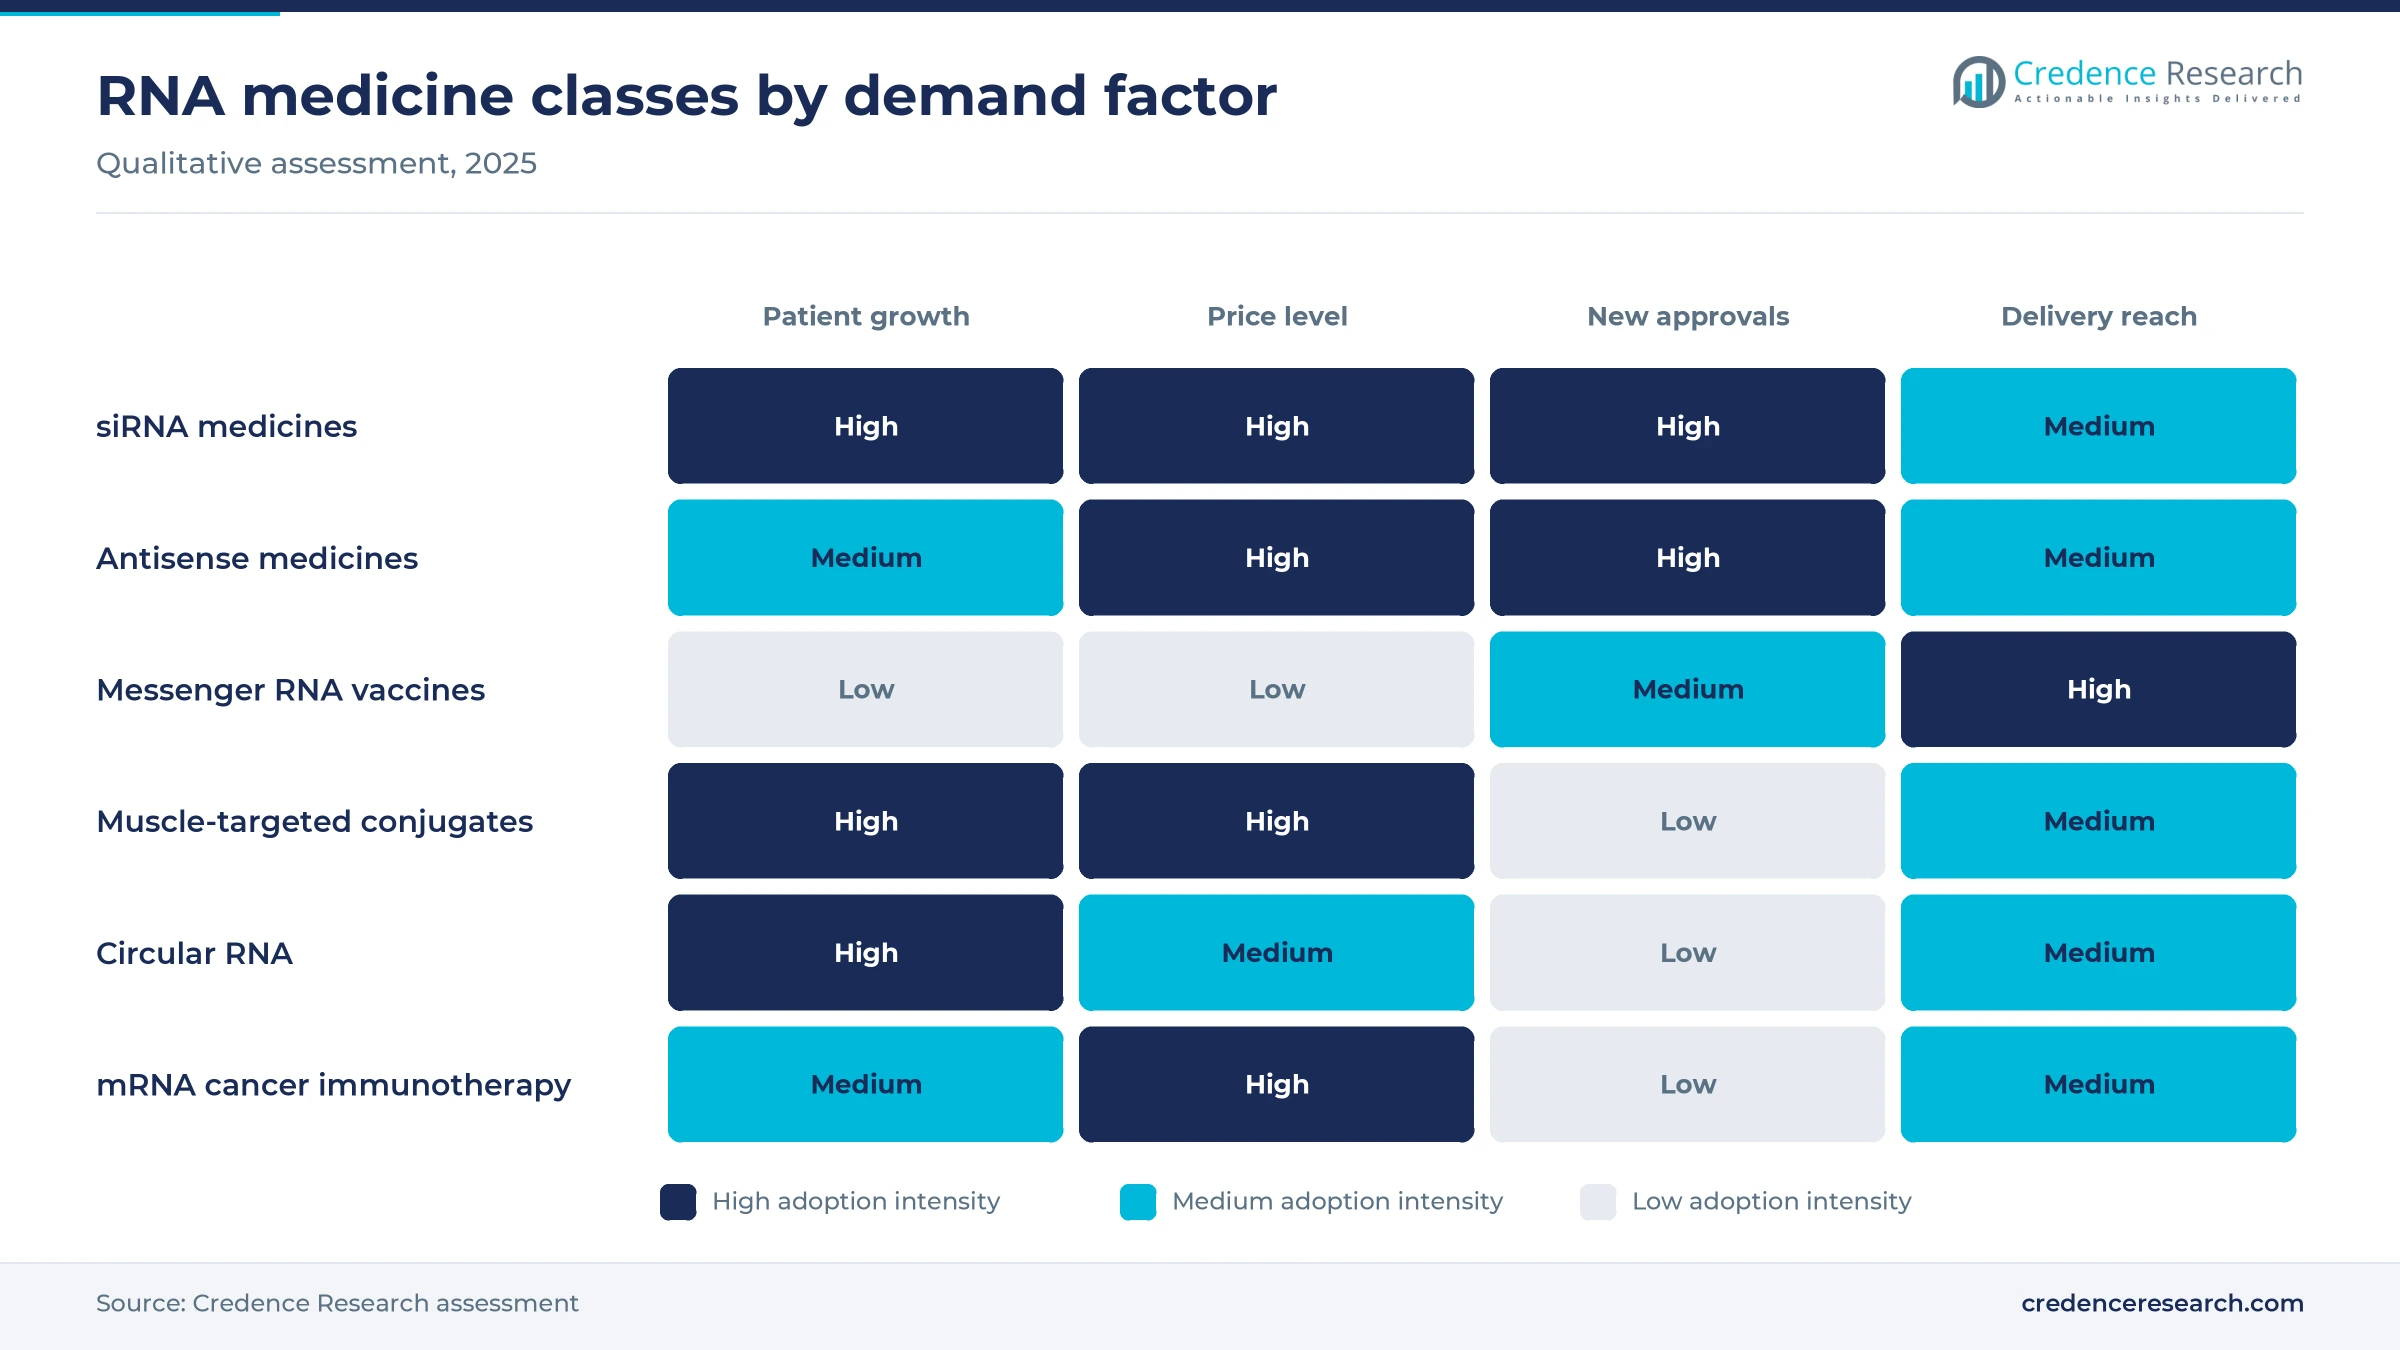
Long dosing intervals widen use of siRNA medicines, because patients can replace frequent infusions with a few injections each year. In March 2025, Alnylam announced FDA approval of Qfitlia for hemophilia A or B, given once every two months in patients 12 years and older. Qfitlia was described as the first siRNA medicine approved for hemophilia, and Sanofi holds global commercial rights. In November 2025, Arrowhead received FDA approval for Redemplo, an siRNA medicine given once every three months for familial chylomicronemia syndrome. In turn, RNA interference grows fastest among types at 12.04% a year, while established hemophilia care faces a new low-frequency option for patients with or without inhibitors.
How do new mRNA vaccine approvals sustain the vaccine base?
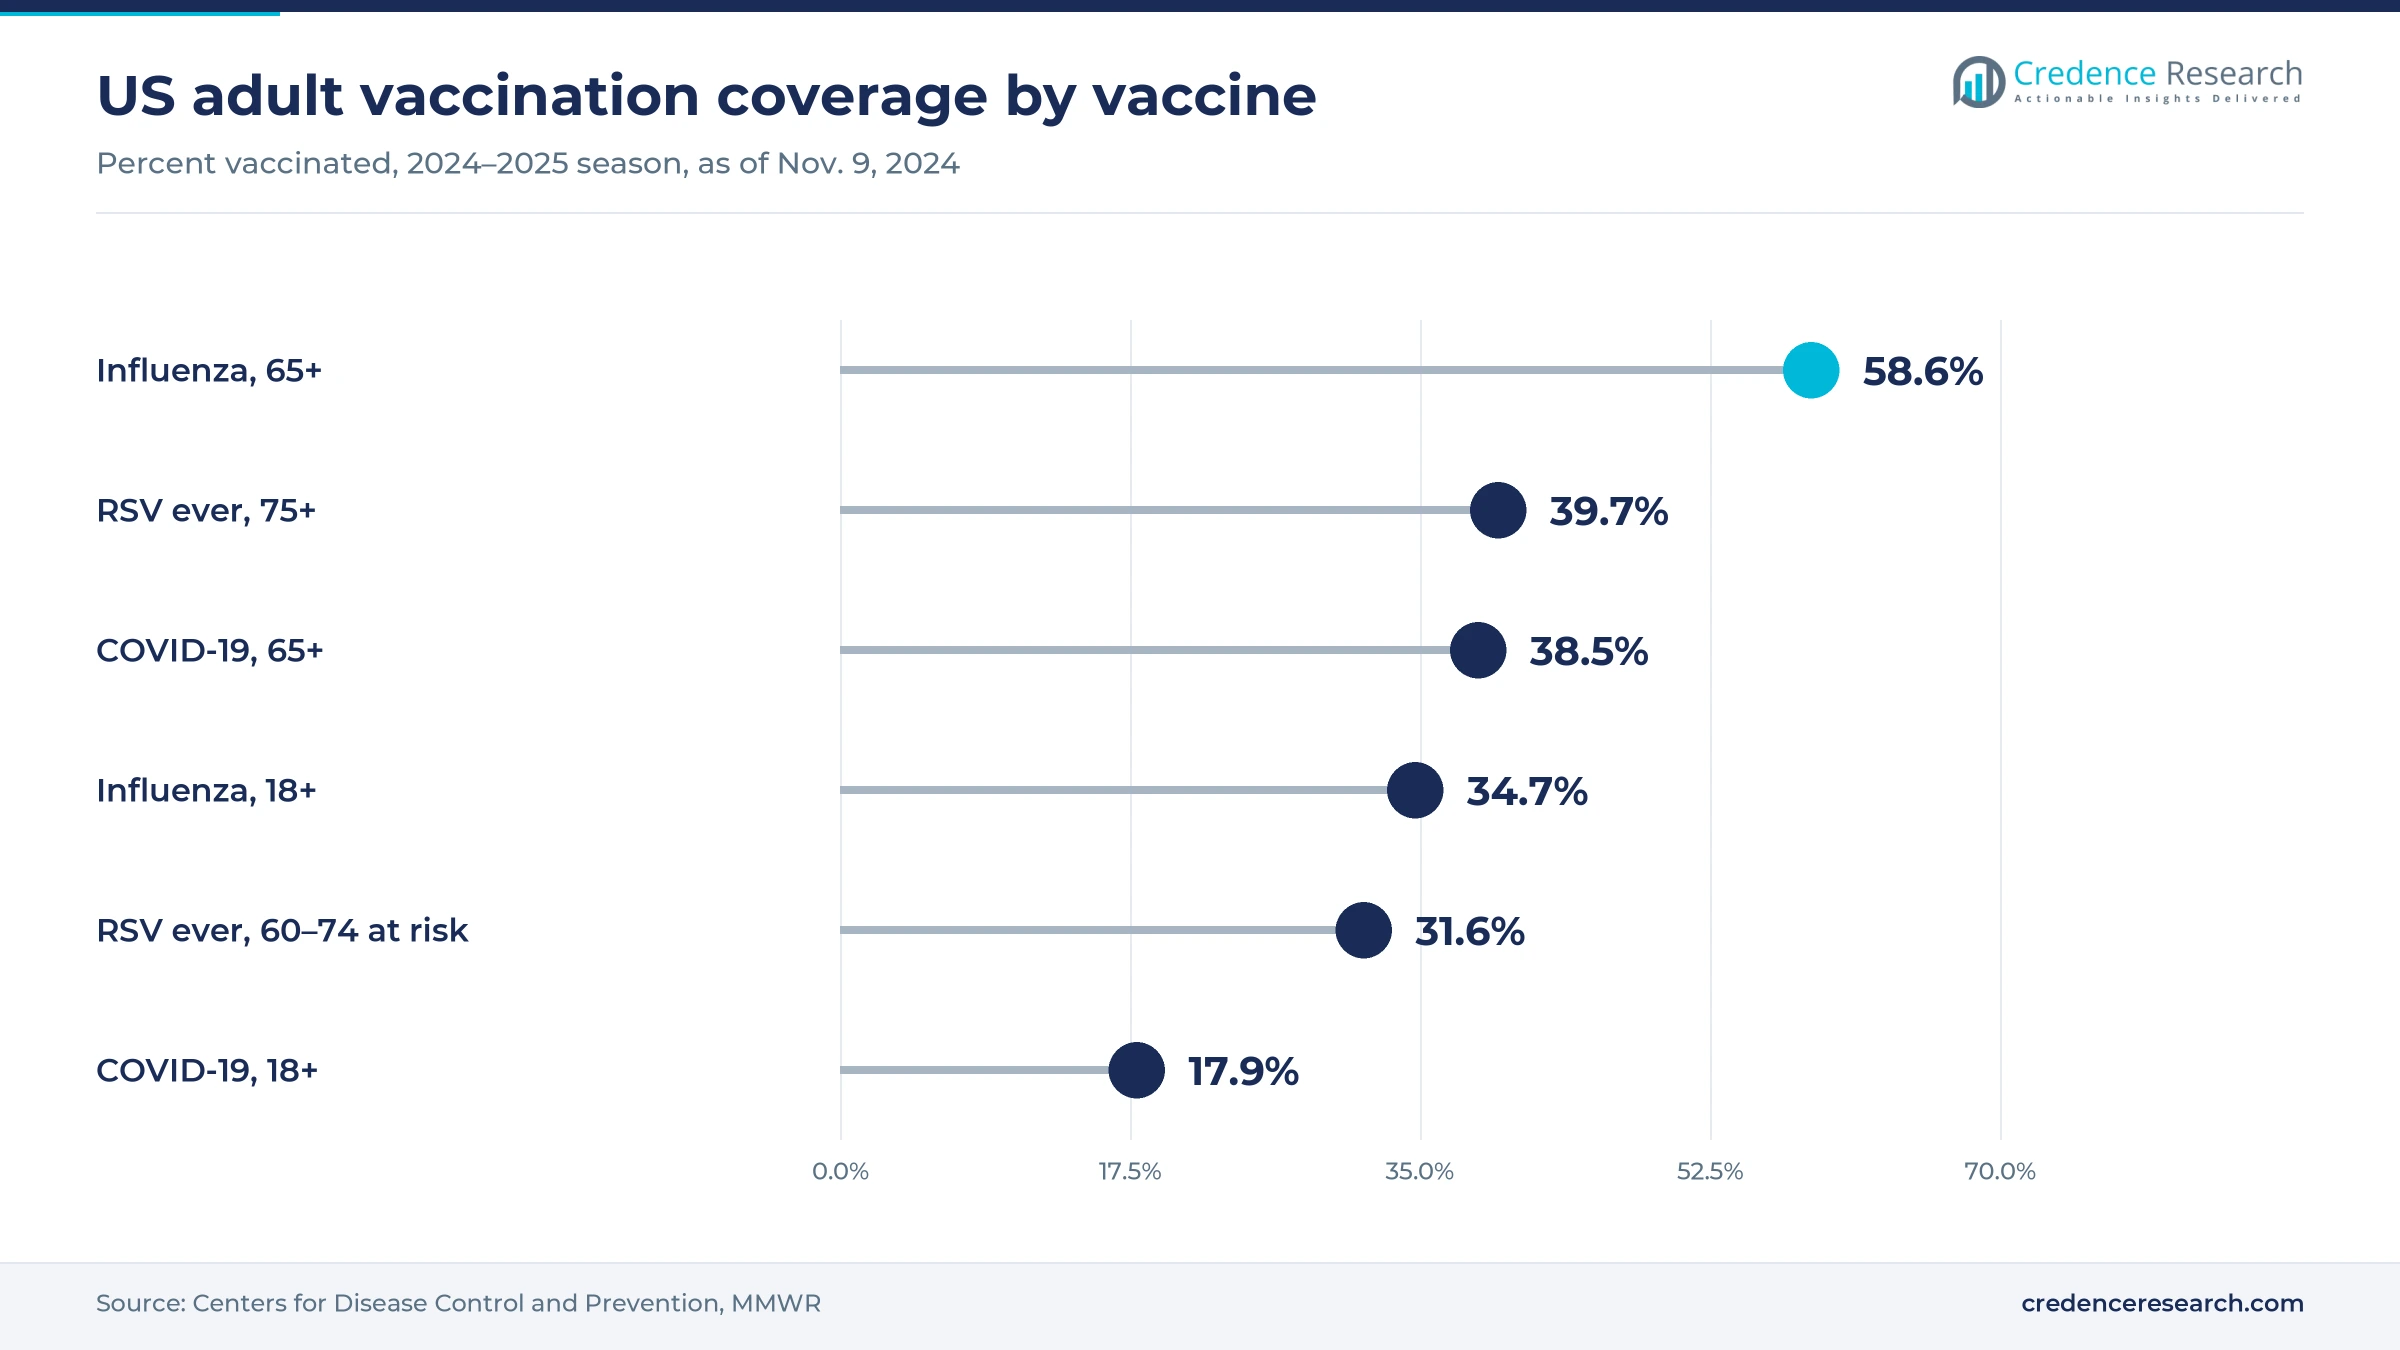
New messenger RNA vaccine approvals sustain the vaccine base, because the platform now covers more than one respiratory virus. On May 31, 2024, the FDA approved Moderna mRESVIA for RSV in adults aged 60 and older, the first messenger RNA vaccine for a disease other than COVID-19. In May 2025, Moderna received FDA approval for mNEXSPIKE, its third approved product. However, the Centers for Disease Control and Prevention estimated that 38.5% of adults aged 65 and older had received a 2024 to 2025 COVID-19 vaccine by early November 2024. As a result, vaccines keep a large seasonal base among older adults, while yearly uptake and new respiratory labels set the pace of vaccine demand.
Why are large acquisitions funding RNA pipelines?
Large acquisitions are funding RNA pipelines, because big drugmakers want proven delivery platforms rather than single products. On Feb. 27, 2026, Novartis completed its acquisition of Avidity Biosciences at USD 72.00 per share, valuing the company at about USD 12 billion. In November 2024, Sarepta licensed seven siRNA programs from Arrowhead, paying USD 500 million upfront plus a USD 325 million equity investment. In December 2025, BioNTech closed its acquisition of CureVac to strengthen messenger RNA design, delivery and manufacturing. In turn, well-funded owners can run larger trials, which lifts the number of late-stage programs aimed at muscle, brain and lung diseases through 2035.
Heart disease labels and in vivo cell therapy emerge
How is gene silencing shifting toward heart disease?
Gene silencing is shifting toward heart disease, because cardiac patient groups are far larger than classic rare disorders. On March 20, 2025, Alnylam received FDA approval for Amvuttra to reduce cardiovascular death, hospital visits and urgent heart failure visits in adults with transthyretin amyloidosis cardiomyopathy. In December 2024, Tryngolza became the first approved treatment for familial chylomicronemia syndrome, a severe lipid disorder. In November 2025, Redemplo joined it as a quarterly siRNA option, and Arrowhead estimates about 6,500 people in the United States have the condition. As a result, cardiometabolic labels are becoming a core source of growth for drugs, as each label adds patients who need lifelong treatment.
Why is in vivo cell therapy emerging on circular RNA?
In vivo cell therapy is emerging on circular RNA, because the approach lets a patient's body make engineered immune cells without outside processing. On Feb. 9, 2026, Lilly agreed to acquire Orna Therapeutics in a deal valued at up to USD 2.4 billion, including milestone payments. Orna pairs engineered circular RNA with lipid nanoparticles, and its lead program ORN-252 is a CD19-targeting in vivo CAR-T candidate. Lilly plans to test ORN-252 in autoimmune diseases driven by B cells. BioNTech also cited mRNA cancer immunotherapy as a reason for buying CureVac in 2025. In turn, other designs, including messenger and circular RNA, are moving from vaccines into immune and cancer treatment.
Can muscle-targeted conjugates open neuromuscular demand?
Developers have a clear opening in neuromuscular disease, because conjugates can carry RNA medicines into muscle tissue rather than only the liver. Novartis said the Avidity deal added three late-stage programs for genetic neuromuscular diseases built on antibody oligonucleotide conjugates. Sarepta licensed Arrowhead programs for facioscapulohumeral muscular dystrophy and myotonic dystrophy type 1 in November 2024. That deal also covers spinocerebellar ataxias, Huntington's disease and idiopathic pulmonary fibrosis, which widens targets beyond muscle. Better delivery also lifts demand for oligonucleotide synthesis capacity at contract plants. As a result, muscle and brain programs are expected to add new late-stage candidates for inherited diseases through 2035.
Where can prophylactic RNA medicines add new value?
Prophylactic RNA medicines can add new value in swelling and bleeding disorders, because steady prevention replaces emergency treatment. In August 2025, Ionis received FDA approval for Dawnzera to prevent attacks of hereditary angioedema in patients aged 12 and older. In its trial, Dawnzera cut monthly attacks by 81% versus placebo over 24 weeks, with dosing every four or eight weeks. The condition affects roughly 1 in 50,000 people worldwide and drives 15,000 to 30,000 U.S. hospital visits each year. In turn, specialty centers that manage chronic prophylaxis grow fastest among end users at 11.95% a year, as patients move to longer intervals.
Delivery limits, costs and vaccine fatigue slow uptake
Why do delivery limits keep many targets out of reach?
Delivery limits keep many targets out of reach, because most approved siRNA medicines rely on liver uptake. Reaching muscle, brain, lung and tumor tissue needs new conjugates or lipid carriers that are still in trials. Each new delivery method also needs its own safety data and manufacturing process before regulators accept it. As a result, many diseases with clear genetic causes remain without an RNA option, even as acquisitions fund work on delivery beyond the liver. Developers that solve tissue reach first will gain a long lead in brain and muscle disorders.
How do high prices limit access outside the United States?
High prices limit access outside the United States, because rare disease medicines often cost hundreds of thousands of dollars each year. European health technology reviews often take a year or more before national coverage begins. Payers in Asia and Latin America cover few of these products, and many patients pay out of pocket or go untreated. In turn, value stays concentrated in North America, while companies test outcome-based contracts, tiered pricing and managed access programs to widen reach in other regions.
Why does lower vaccine uptake weigh on messenger RNA sales?
Lower vaccine uptake weighs on messenger RNA sales, because seasonal COVID-19 vaccination has fallen sharply since 2021. Narrower U.S. eligibility rules for COVID-19 vaccines in 2025 also limited the population covered by default. Public trust in new vaccine technologies also varies widely between countries and age groups. As a result, vaccine makers depend on new respiratory, combination and cancer programs to replace lost volume, while governments buy smaller seasonal orders than in earlier years.
How do manufacturing and patent complexity raise costs?
Manufacturing and patent complexity raise costs, because RNA medicines need specialized synthesis, purification and cold chain handling. Lipid nanoparticle and modified nucleotide patents have led to long legal disputes between developers. Smaller companies must license several delivery and chemistry technologies before a product can launch. In turn, newcomers face higher entry costs and longer timelines, which favors large platform owners with in-house plants, broad patent estates and experienced regulatory teams.
North America leads as Asia Pacific gains pace
| Region | Value, 2025 (USD billion) | Share, 2025 | CAGR, 2026–2035 |
|---|---|---|---|
| North America | 4.75 | 48.0% | 11.07% |
| Europe | 2.57 | 26.0% | 10.97% |
| Asia Pacific | 1.78 | 18.0% | 12.77% |
| Latin America | 0.45 | 4.5% | 12.07% |
| Middle East & Africa | 0.35 | 3.5% | 12.17% |
Why do early U.S. launches keep North America in the lead?
North America held 48.0% of 2025 value and grows at 11.07% a year through 2035. The United States drives this position, because Qfitlia, Amvuttra for cardiomyopathy, Tryngolza, Dawnzera and Redemplo all received FDA approval between December 2024 and November 2025. Alnylam Pharmaceuticals, Inc., Ionis Pharmaceuticals, Inc., Moderna, Inc. and Sarepta Therapeutics, Inc. are based in the country. Specialty pricing and commercial insurance support high spending per treated patient.
How does Europe balance platform strength with price control?
Europe held 26.0% of 2025 value and grows at 10.97% a year through 2035. Novartis AG and Sanofi are based in the region, and BioNTech completed its acquisition of Curevac SE in Germany in December 2025. However, health technology reviews and national price negotiations delay coverage for many rare disease medicines. This keeps regional growth below the global average despite strong research capacity.
Why do China and Japan drive Asia Pacific growth?
Asia Pacific held 18.0% of 2025 value and is the fastest-growing region at 12.77% a year. China and Japan are building local siRNA and messenger RNA capacity, and Sirnaomics develops RNA interference candidates from the region. Large patient populations with lipid, liver and viral diseases offer room for new labels. Wider insurance coverage for rare disease medicines also supports demand.
Why are vaccination programs central in Latin America?
Latin America held 4.5% of 2025 value and grows at 12.07% a year through 2035. Brazil and Mexico lead regional spending, where public vaccination programs account for much of the messenger RNA volume. Access to rare disease medicines depends on court orders and public tenders in several countries.
Why does access remain uneven across the Middle East and Africa?
The Middle East and Africa held 3.5% of 2025 value and grows at 12.17% a year through 2035. Gulf states fund specialist centers and genetic screening, while much of Africa relies on donor vaccination programs. This gap limits access to siRNA and antisense medicines outside major cities.
Approvals and deals in gene silencing since 2024
| Development | Status and market relevance |
|---|---|
| In November 2024, Sarepta Therapeutics licensed seven clinical and preclinical siRNA programs from Arrowhead Pharmaceuticals. | Signed; USD 500 million upfront plus USD 325 million equity investment |
| In March 2025, the FDA approved Qfitlia, the first siRNA medicine for hemophilia A or B, developed by Alnylam and Sanofi. | Approved; given once every two months for patients 12 and older |
| In March 2025, Alnylam received FDA approval for Amvuttra in transthyretin amyloidosis with cardiomyopathy. | Approved; label covers cardiovascular death and hospitalization reduction |
| In December 2025, BioNTech closed its acquisition of CureVac to strengthen messenger RNA design and manufacturing. | Completed; remaining shares to follow through compulsory acquisition |
| In February 2026, Novartis completed its acquisition of Avidity Biosciences, and Lilly agreed to acquire Orna Therapeutics. | Completed and announced; both deals target new RNA delivery platforms |
Conjugates, lipid carriers and circular designs advance
- Liver-targeted conjugates attach sugar groups to siRNA strands, which allows dosing every two to six months under the skin.
- Antibody oligonucleotide conjugates link RNA strands to antibodies, which carries the medicine into muscle tissue.
- Lipid nanoparticles protect messenger and circular RNA during delivery, which supports vaccines and in vivo cell therapy.
- Circular RNA designs lack free ends that enzymes attack, which can extend protein production inside cells.
- Modified nucleotides reduce unwanted immune reactions, which improves tolerability for repeated doses.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Platform owners compete on delivery and dosing gaps
Competition is led by platform owners that control both chemistry and delivery. Alnylam Pharmaceuticals, Inc. leads RNA interference with several approved liver-targeted medicines, while Ionis Pharmaceuticals, Inc. leads antisense medicines for lipid, swelling and neurological disorders. Moderna, Inc. and Pfizer, Inc. compete in messenger RNA vaccines, and BioNTech added Curevac SE in December 2025. Novartis AG, Sanofi and Sarepta Therapeutics, Inc. combine licensing and acquisitions with their own specialty sales networks. Orna Therapeutics brings circular RNA under Lilly ownership, while Sirnaomics develops RNA interference candidates in Asia. Partnerships remain common, because smaller developers license programs to companies with global sales forces and payer experience. As a result, companies compete on dosing intervals, tissue reach beyond the liver, outcome data in larger diseases, patent strength and manufacturing scale, and each new heart or muscle label tests how well a platform performs in broader patient groups.
Companies profiled and their roles in this market
| Company | Type | Role in the market |
|---|---|---|
| Moderna, Inc. | Platform owner | mRESVIA and mNEXSPIKE messenger RNA vaccines |
| Pfizer, Inc. | Diversified | Messenger RNA vaccines with BioNTech |
| Alnylam Pharmaceuticals, Inc. | Platform owner | Amvuttra and Qfitlia siRNA medicines |
| Novartis AG | Diversified | Avidity antibody oligonucleotide conjugates |
| Ionis Pharmaceuticals, Inc. | Platform owner | Tryngolza and Dawnzera antisense medicines |
| Sanofi | Diversified | Global rights to Qfitlia for hemophilia |
| Sarepta Therapeutics, Inc. | Specialist | Licensed Arrowhead siRNA programs |
| Orna Therapeutics | Specialist | Circular RNA in vivo CAR-T candidate ORN-252 |
| Curevac SE | Specialist | Messenger RNA design, now part of BioNTech |
| Sirnaomics | Specialist | RNA interference candidates |
Gene silencing drugs set the pace to 2035
Credence Research's view is that gene silencing drugs will set the pace of growth through 2035, because each new siRNA or antisense label reaches patients who stay on treatment for years. The overall market grows at 11.45% a year, supported by rare disease approvals, heart disease labels and long dosing intervals. Vaccines keep a meaningful seasonal base, yet drugs gain share every year. Companies that move RNA medicines beyond the liver into muscle and brain tissue will win the most new value.
How Credence Research sized RNA medicine spending
The report uses 2025 as the base year and 2026 to 2035 as the forecast period. Market values come from the Credence Research model, which builds spending by product, type, indication, end use and region. Regional and segment splits are Credence Research estimates informed by U.S. government statistics, FDA decisions and company press releases and regulatory filings. No primary interviews or surveys were used in preparing this edition of the report.
RNA medicine outlook to 2035
By 2035, the RNA-based therapeutics market is projected to reach USD 29.28 billion, with growth led by siRNA and antisense medicines for rare, lipid and heart disorders. Drugs will widen their lead over vaccines, as quarterly and twice-yearly dosing reaches larger patient groups. North America keeps the highest spending per patient, while Asia Pacific adds the most new capacity. Circular RNA and muscle-targeted conjugates will open new disease areas. As a result, advantage will depend on delivery reach, outcome data and manufacturing scale.
Frequently Asked Questions
How big is the global RNA-based therapeutics market?
Which product leads the RNA-based therapeutics market?
Which region leads RNA medicine spending?
Which type of RNA medicine grows fastest?
What RNA medicines did the FDA approve in 2025?
Why are drugmakers buying RNA platform companies?
Who are the leading RNA-based therapeutics companies?
What restrains growth in RNA medicines?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Product
- 1.2.1 Drugs
- 1.2.2 Vaccines
- 1.3 By Type
- 1.3.1 RNA Interference
- 1.3.2 RNA Antisense
- 1.3.3 Others
- 1.4 By Indication
- 1.4.1 Infectious Diseases
- 1.4.2 Rare Genetic Diseases
- 1.4.3 Others
- 1.5 By End Use
- 1.5.1 Hospital
- 1.5.2 Specialty Centers
- 1.5.3 Research Institutes
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2025: USD 9.90 billion → 2035: USD 29.28 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Historical Period: 2018-2025
- 2.6.2 Base Year: 2025
- 2.6.3 Forecast Period: 2025-2035
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2025
- 3.3 Forecast Market Size, 2035
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global RNA-based Therapeutics Market Trends and Developments
- 4.1 Historical Industry Development, 2018-2025
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global RNA-based Therapeutics Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis, 2018-2025
- 5.2 Demand Forecast, 2025-2035
- 5.3 Production and Output Trend, 2018-2025
- 5.4 Production and Output Forecast, 2025-2035
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global RNA-based Therapeutics Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends, 2018-2025
- 6.3 Pricing Outlook, 2025-2035
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global RNA-based Therapeutics Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global RNA-based Therapeutics Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global RNA-based Therapeutics Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global RNA-based Therapeutics Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global RNA-based Therapeutics Market Outlook, 2025-2035
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2025: USD 9.90 billion → 2035: USD 29.28 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size, 2018-2025
- 11.1.4 Base-Year Market Size, 2025
- 11.2 Market Forecast, 2025-2035
- 11.2.1 Revenue Forecast to 2035
- 11.2.2 Volume Forecast to 2035
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global RNA-based Therapeutics Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2025
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Product - Market Size and Forecast, 2025-2035
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size, 2018-2025
- 12.3.3 Revenue Forecast, 2025-2035
- 12.3.4 Volume Forecast, 2025-2035
- 12.3.5 Base-Year Market Share, 2025
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Drugs
- 12.3.7.2 Vaccines
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Type - Market Size and Forecast, 2025-2035
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size, 2018-2025
- 12.4.3 Revenue Forecast, 2025-2035
- 12.4.4 Volume Forecast, 2025-2035
- 12.4.5 Base-Year Market Share, 2025
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 RNA Interference
- 12.4.7.2 RNA Antisense
- 12.4.7.3 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Indication - Market Size and Forecast, 2025-2035
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size, 2018-2025
- 12.5.3 Revenue Forecast, 2025-2035
- 12.5.4 Volume Forecast, 2025-2035
- 12.5.5 Base-Year Market Share, 2025
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Infectious Diseases
- 12.5.7.2 Rare Genetic Diseases
- 12.5.7.3 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By End Use - Market Size and Forecast, 2025-2035
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size, 2018-2025
- 12.6.3 Revenue Forecast, 2025-2035
- 12.6.4 Volume Forecast, 2025-2035
- 12.6.5 Base-Year Market Share, 2025
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Hospital
- 12.6.7.2 Specialty Centers
- 12.6.7.3 Research Institutes
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global RNA-based Therapeutics End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global RNA-based Therapeutics Geographic Market Outlook, 2025-2035
- 14.1 Regional Market Size and Share, 2025
- 14.2 Regional Market Forecast, 2025-2035
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global RNA-based Therapeutics Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2025-2035
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global RNA-based Therapeutics Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2025
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2025-2035
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Moderna, Inc.
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Pfizer, Inc.
- 18.4 Alnylam Pharmaceuticals, Inc.
- 18.5 Novartis AG
- 18.6 Ionis Pharmaceuticals, Inc.
- 18.7 Sanofi
- 18.8 Sarepta Therapeutics, Inc.
- 18.9 Orna Therapeutics
- 18.10 Curevac SE
- 18.11 Sirnaomics
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

