
Biologics and targeted launches drive high-cost therapy
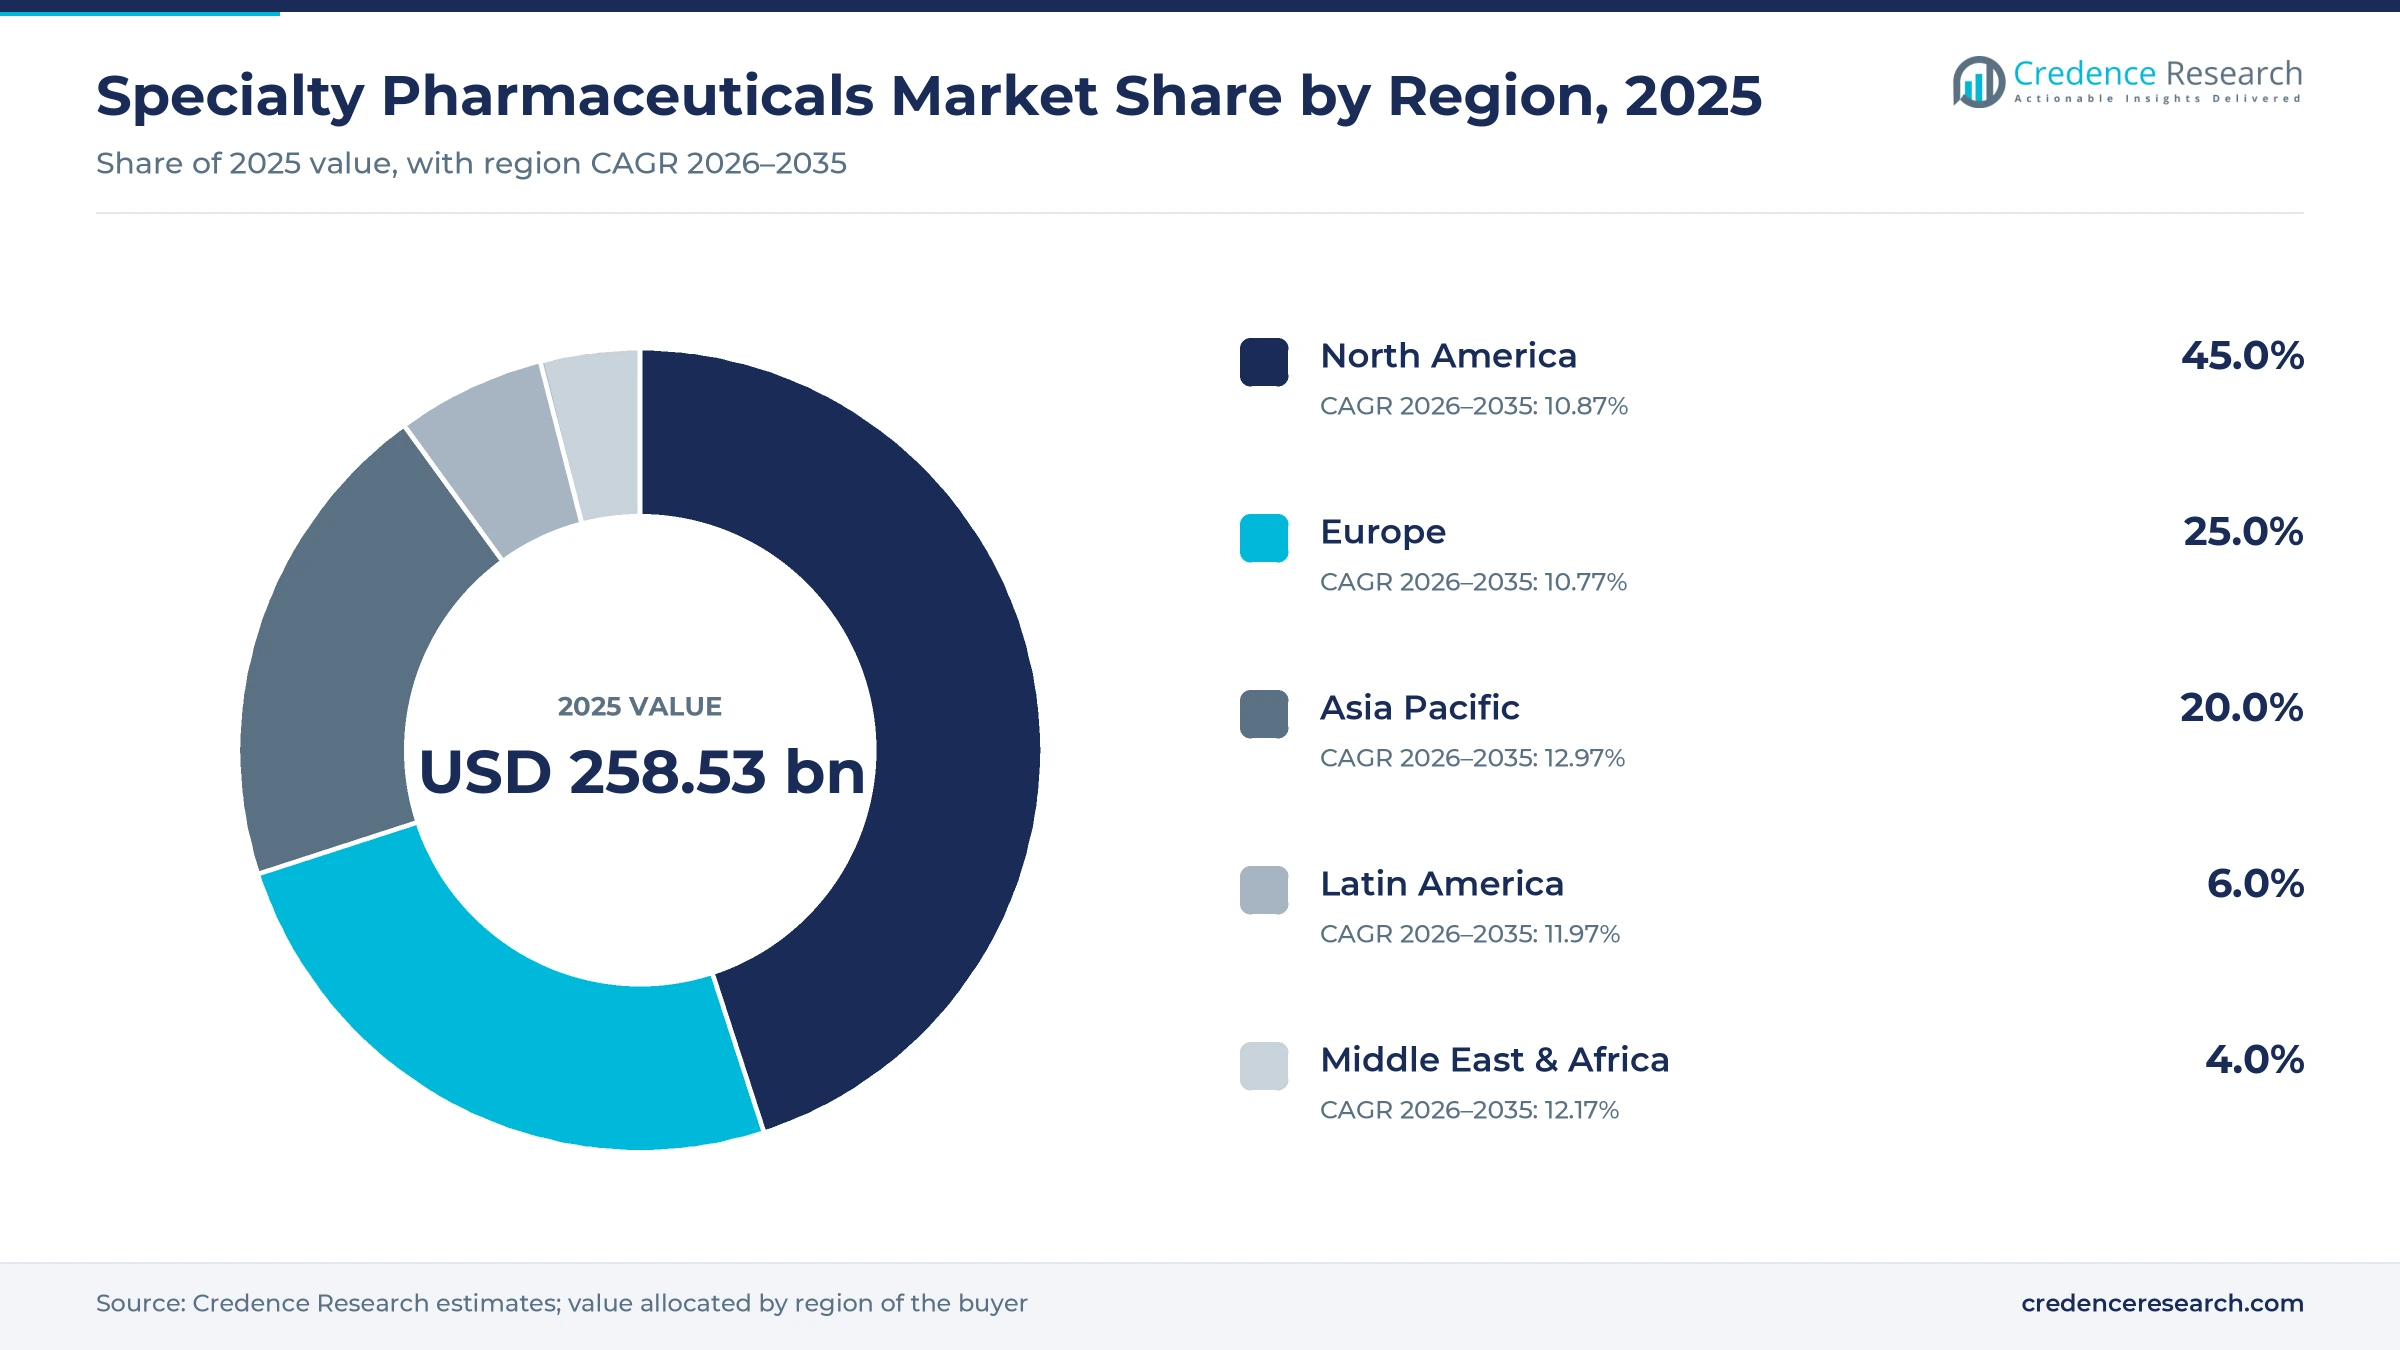
The global specialty pharmaceuticals market was valued at USD 258.53 billion in 2025 and is projected to increase from USD 288.04 billion in 2026 to USD 761.98 billion by 2035, registering a CAGR of 11.41% during 2026–2035. Spending rises because cancer, immune disease, obesity and rare conditions need complex medicines that require special handling, monitoring and payer approval. North America held the largest regional share, 45.0% in 2025, because the United States launches most new biologics first and pays the highest prices for them. Asia Pacific is the fastest-growing region at 12.97% a year, as China, Japan, South Korea and India widen reimbursement for targeted cancer and immune therapies. Pricing policy is also changing, since negotiated Medicare prices for 15 more medicines, including semaglutide brands, take effect in January 2027. As a result, growth leans on new launches and treated patient numbers more than on list price increases.
Which high-cost medicines and channels does this analysis count?
The analysis counts high-cost medicines for complex, chronic or rare conditions, including biologics, small-molecule targeted drugs, gene and cell therapies and peptide medicines. These products often need cold-chain handling, injection or infusion, patient monitoring and prior authorization by payers before dispensing.
Traditional generics, over-the-counter medicines and vaccines bought by public immunization programs sit outside the value counted here. The value chain runs from discovery and clinical trials through biologic manufacturing and limited distribution networks to hospital, retail and online pharmacies that dispense and support each therapy.
Specialty Pharmaceuticals Market Insights
- The specialty pharmaceuticals market grows from USD 258.53 billion in 2025 to USD 761.98 billion by 2035, an 11.41% CAGR as new biologics and targeted therapies reach patients.
- North America held 45.0% of global value in 2025, because the United States launches most new medicines first at high prices.
- Oncology led applications with 34.0% of 2025 value, while gene and cell therapy grows fastest among drug classes at 16.37% a year.
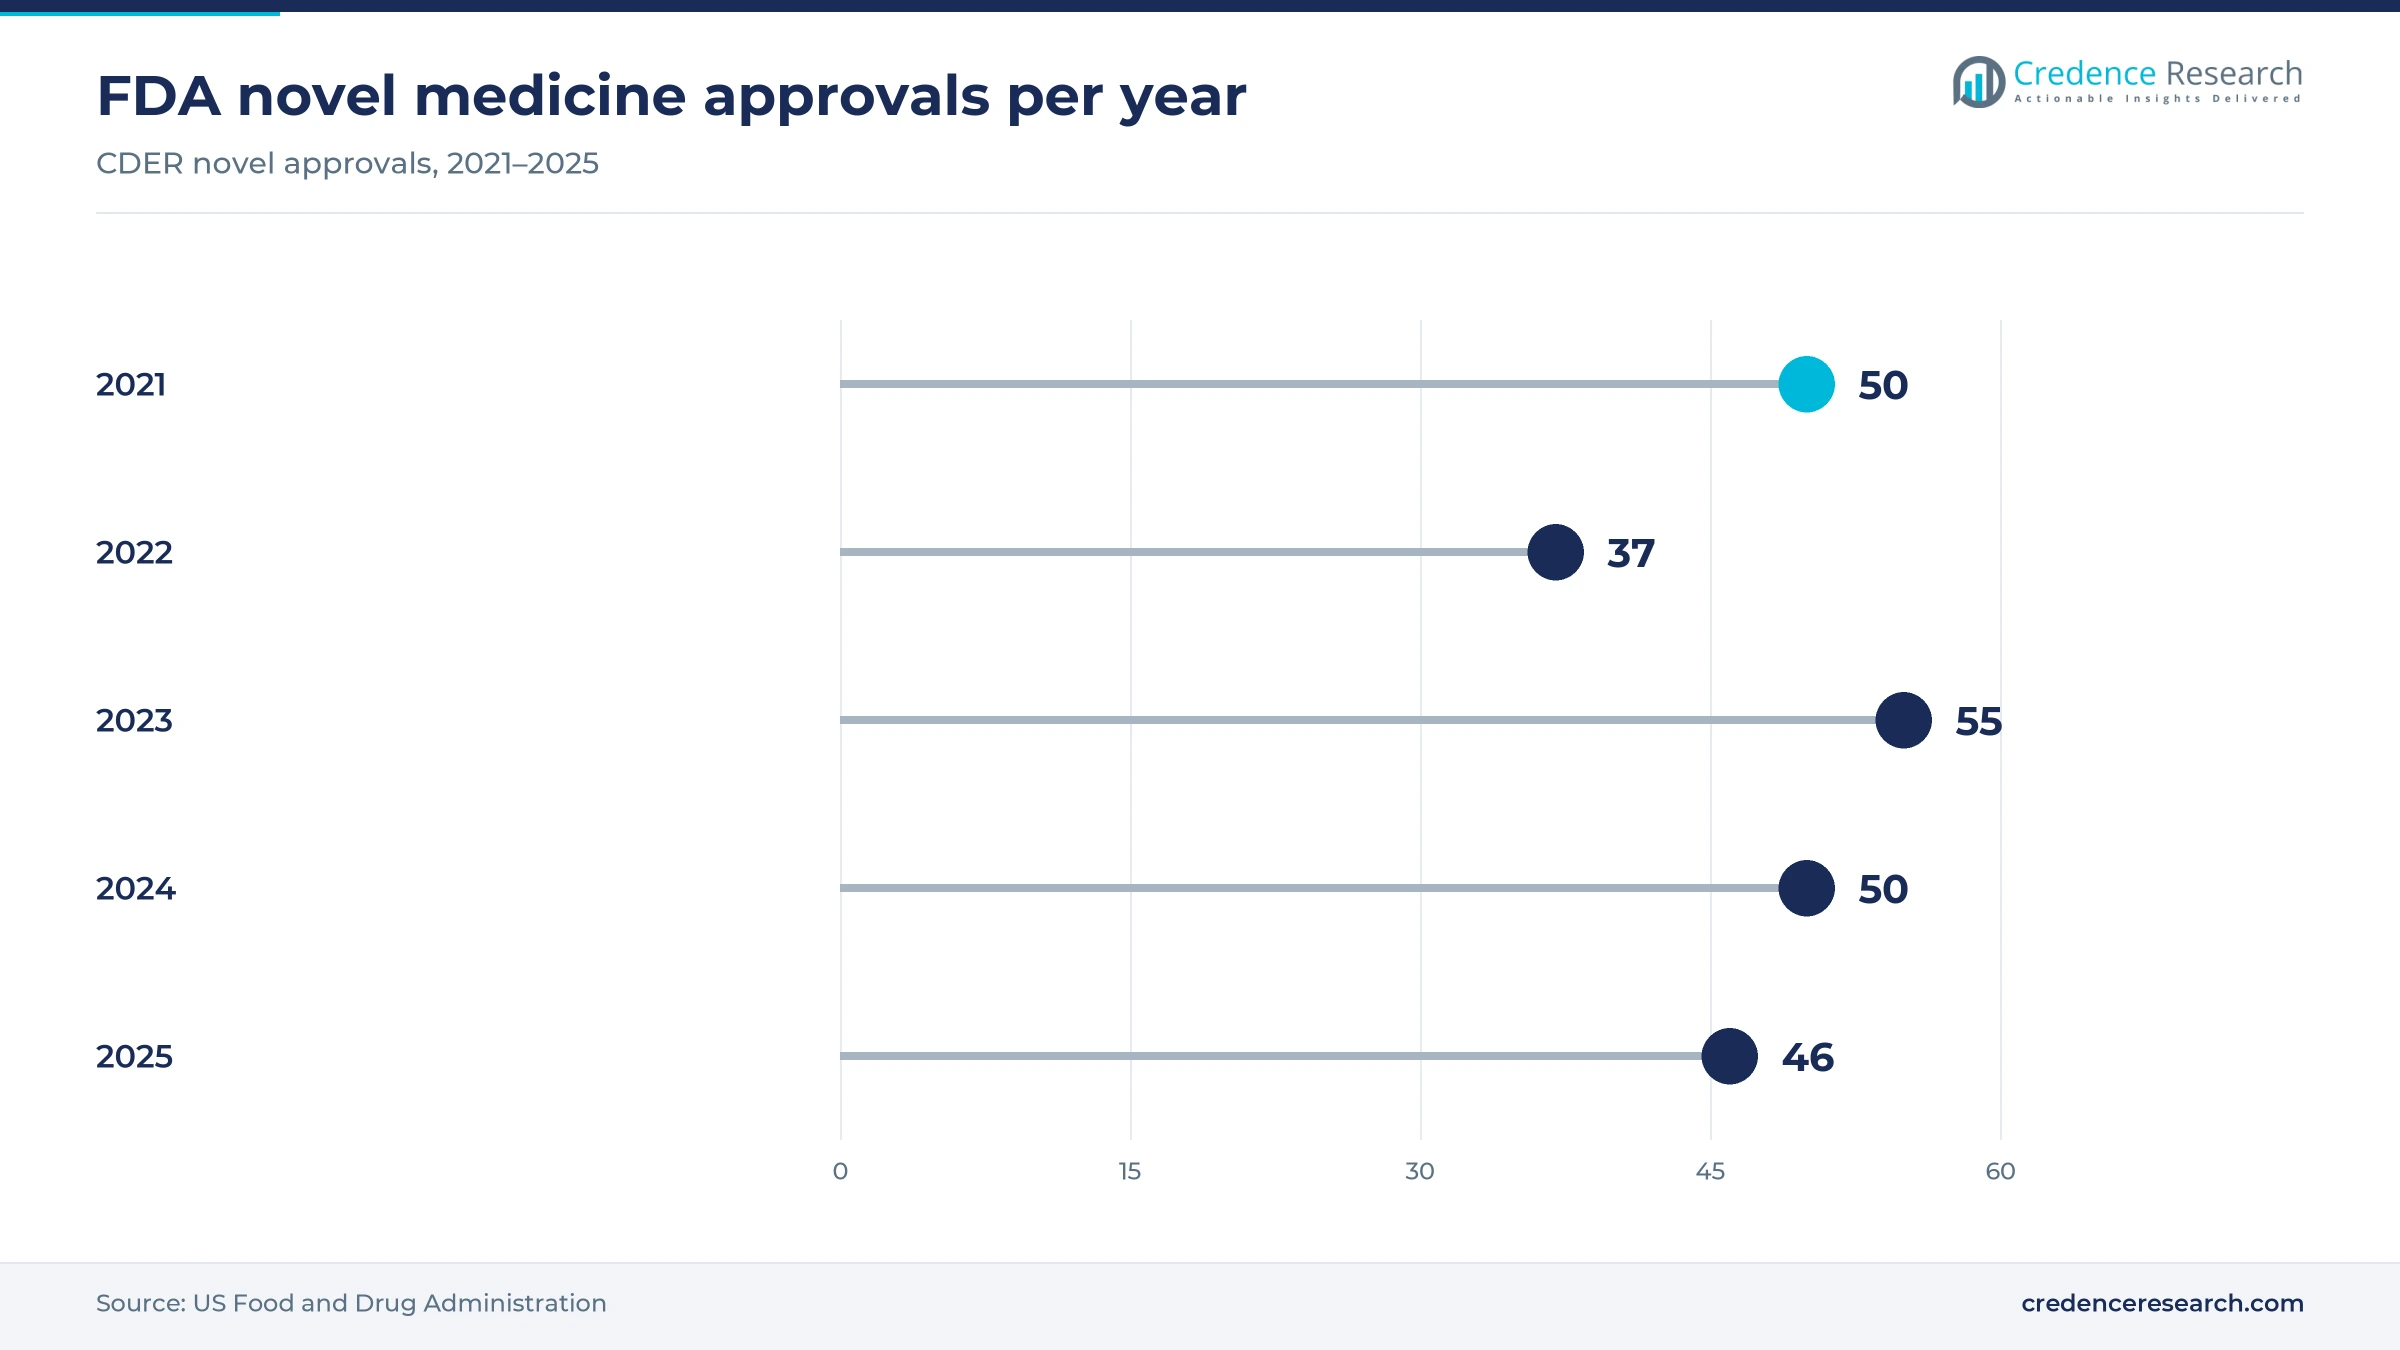
- The FDA drug center approved 50 novel medicines in 2024 and 46 in 2025, with targeted cancer and neurology therapies among the most valuable.
- Negotiated Medicare prices for 15 more medicines take effect in January 2027, with semaglutide brands set at a maximum fair price of $274.
Oncology and biologics lead while gene therapy grows fastest
Which therapy areas account for most spending?
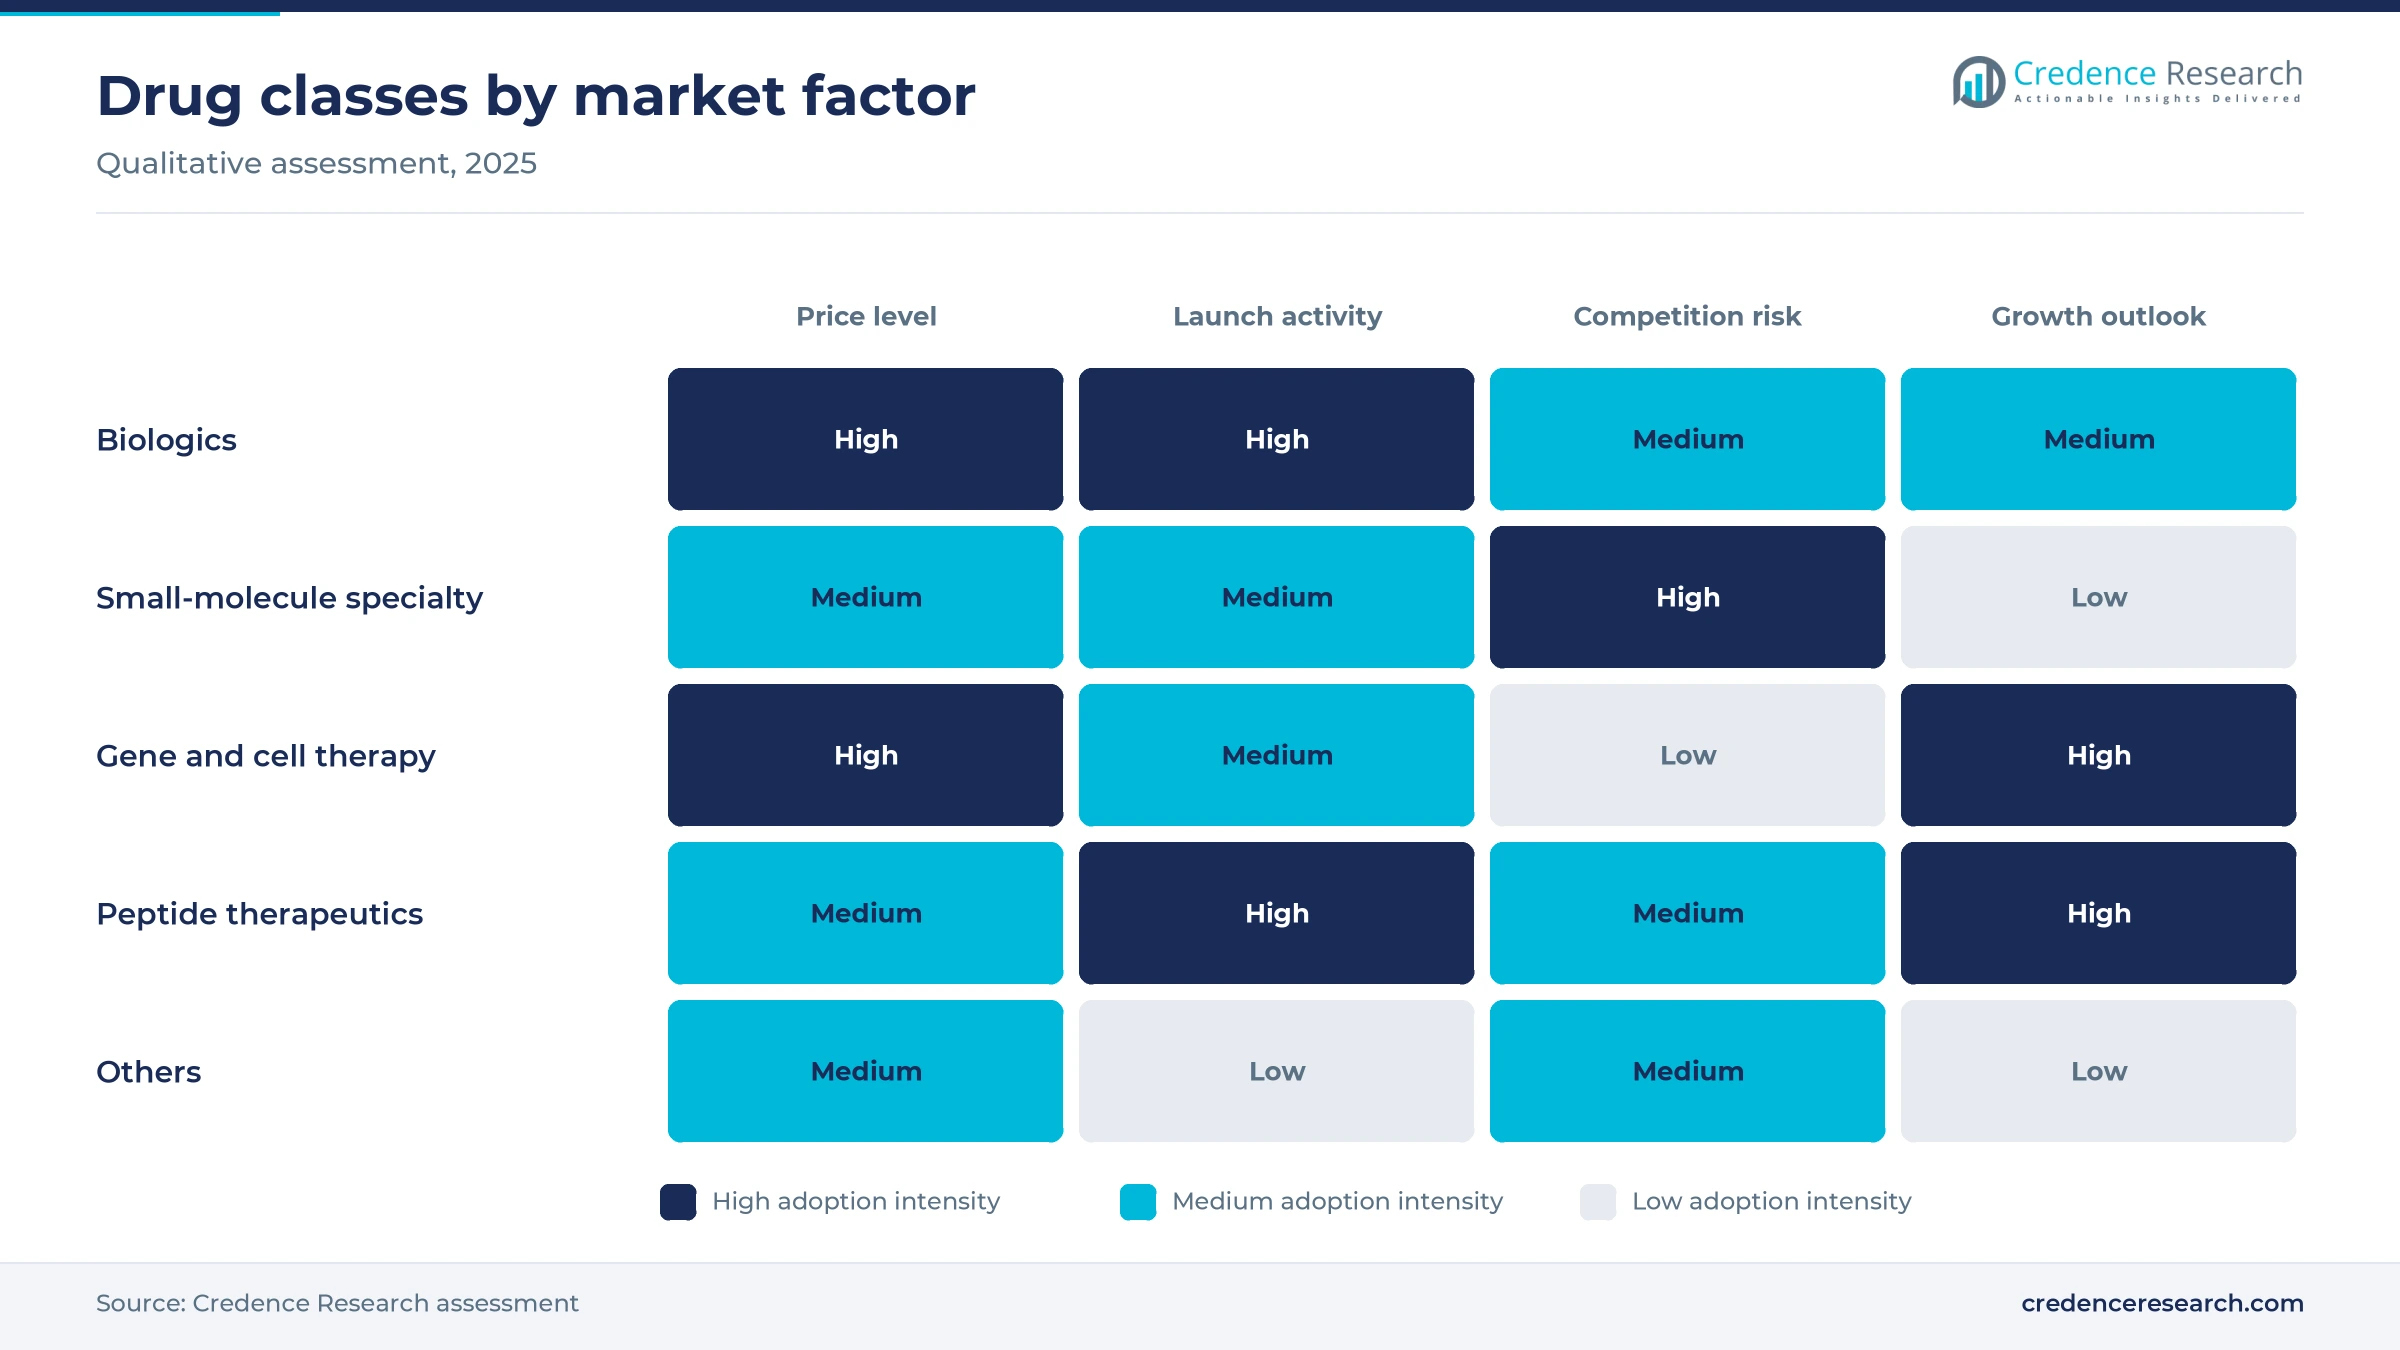
Based on application, the market is categorized into oncology, immunology, endocrinology, neurology, rare and orphan disorders and others. Oncology led with 34.0% of 2025 value, because targeted drugs, antibodies and conjugates carry high prices across many tumor types. Endocrinology grows fastest at 12.49% a year, as incretin medicines for diabetes and obesity reach more patients. Immunology remains the second-largest therapy area through the 2035 forecast year.
How do biologics, small molecules and gene therapies split value?
Based on drug class, the market is categorized into biologics, small-molecule specialty drugs, gene and cell therapy, peptide therapeutics and others. Biologics led with 55.0% of 2025 value, because antibodies and fusion proteins dominate cancer and immune care. Gene & Cell Therapy grows fastest at 16.37% a year, as regulators clear more one-time treatments for inherited and blood disorders. Peptide medicines also gain share from rising diabetes and obesity treatment demand.
Where do patients receive high-cost medicines?
Based on distribution channel, the market is categorized into hospital pharmacies, retail pharmacies and drug stores and online pharmacies. Retail Pharmacies & Drug Stores led with 46.0% of 2025 value, because self-injected biologics and oral cancer drugs move through community and specialty counters. Online Pharmacies grow fastest at 13.38% a year, as mail-order programs ship refrigerated refills to homes. Hospital pharmacies handle infused cancer, neurology and rare disease therapies that need clinical supervision.
| Segment Group | Leading Sub-segment | Share, 2025 | Fastest-growing Sub-segment | CAGR, 2026–2035 |
|---|---|---|---|---|
| By Application | Oncology | 34.0% | Endocrinology | 12.49% |
| By Drug Class | Biologics | 55.0% | Gene & Cell Therapy | 16.37% |
| By Distribution Channel | Retail Pharmacies & Drug Stores | 46.0% | Online Pharmacies | 13.38% |
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Cancer burden, steady approvals and metabolic demand
How does the cancer burden raise demand for targeted drugs?
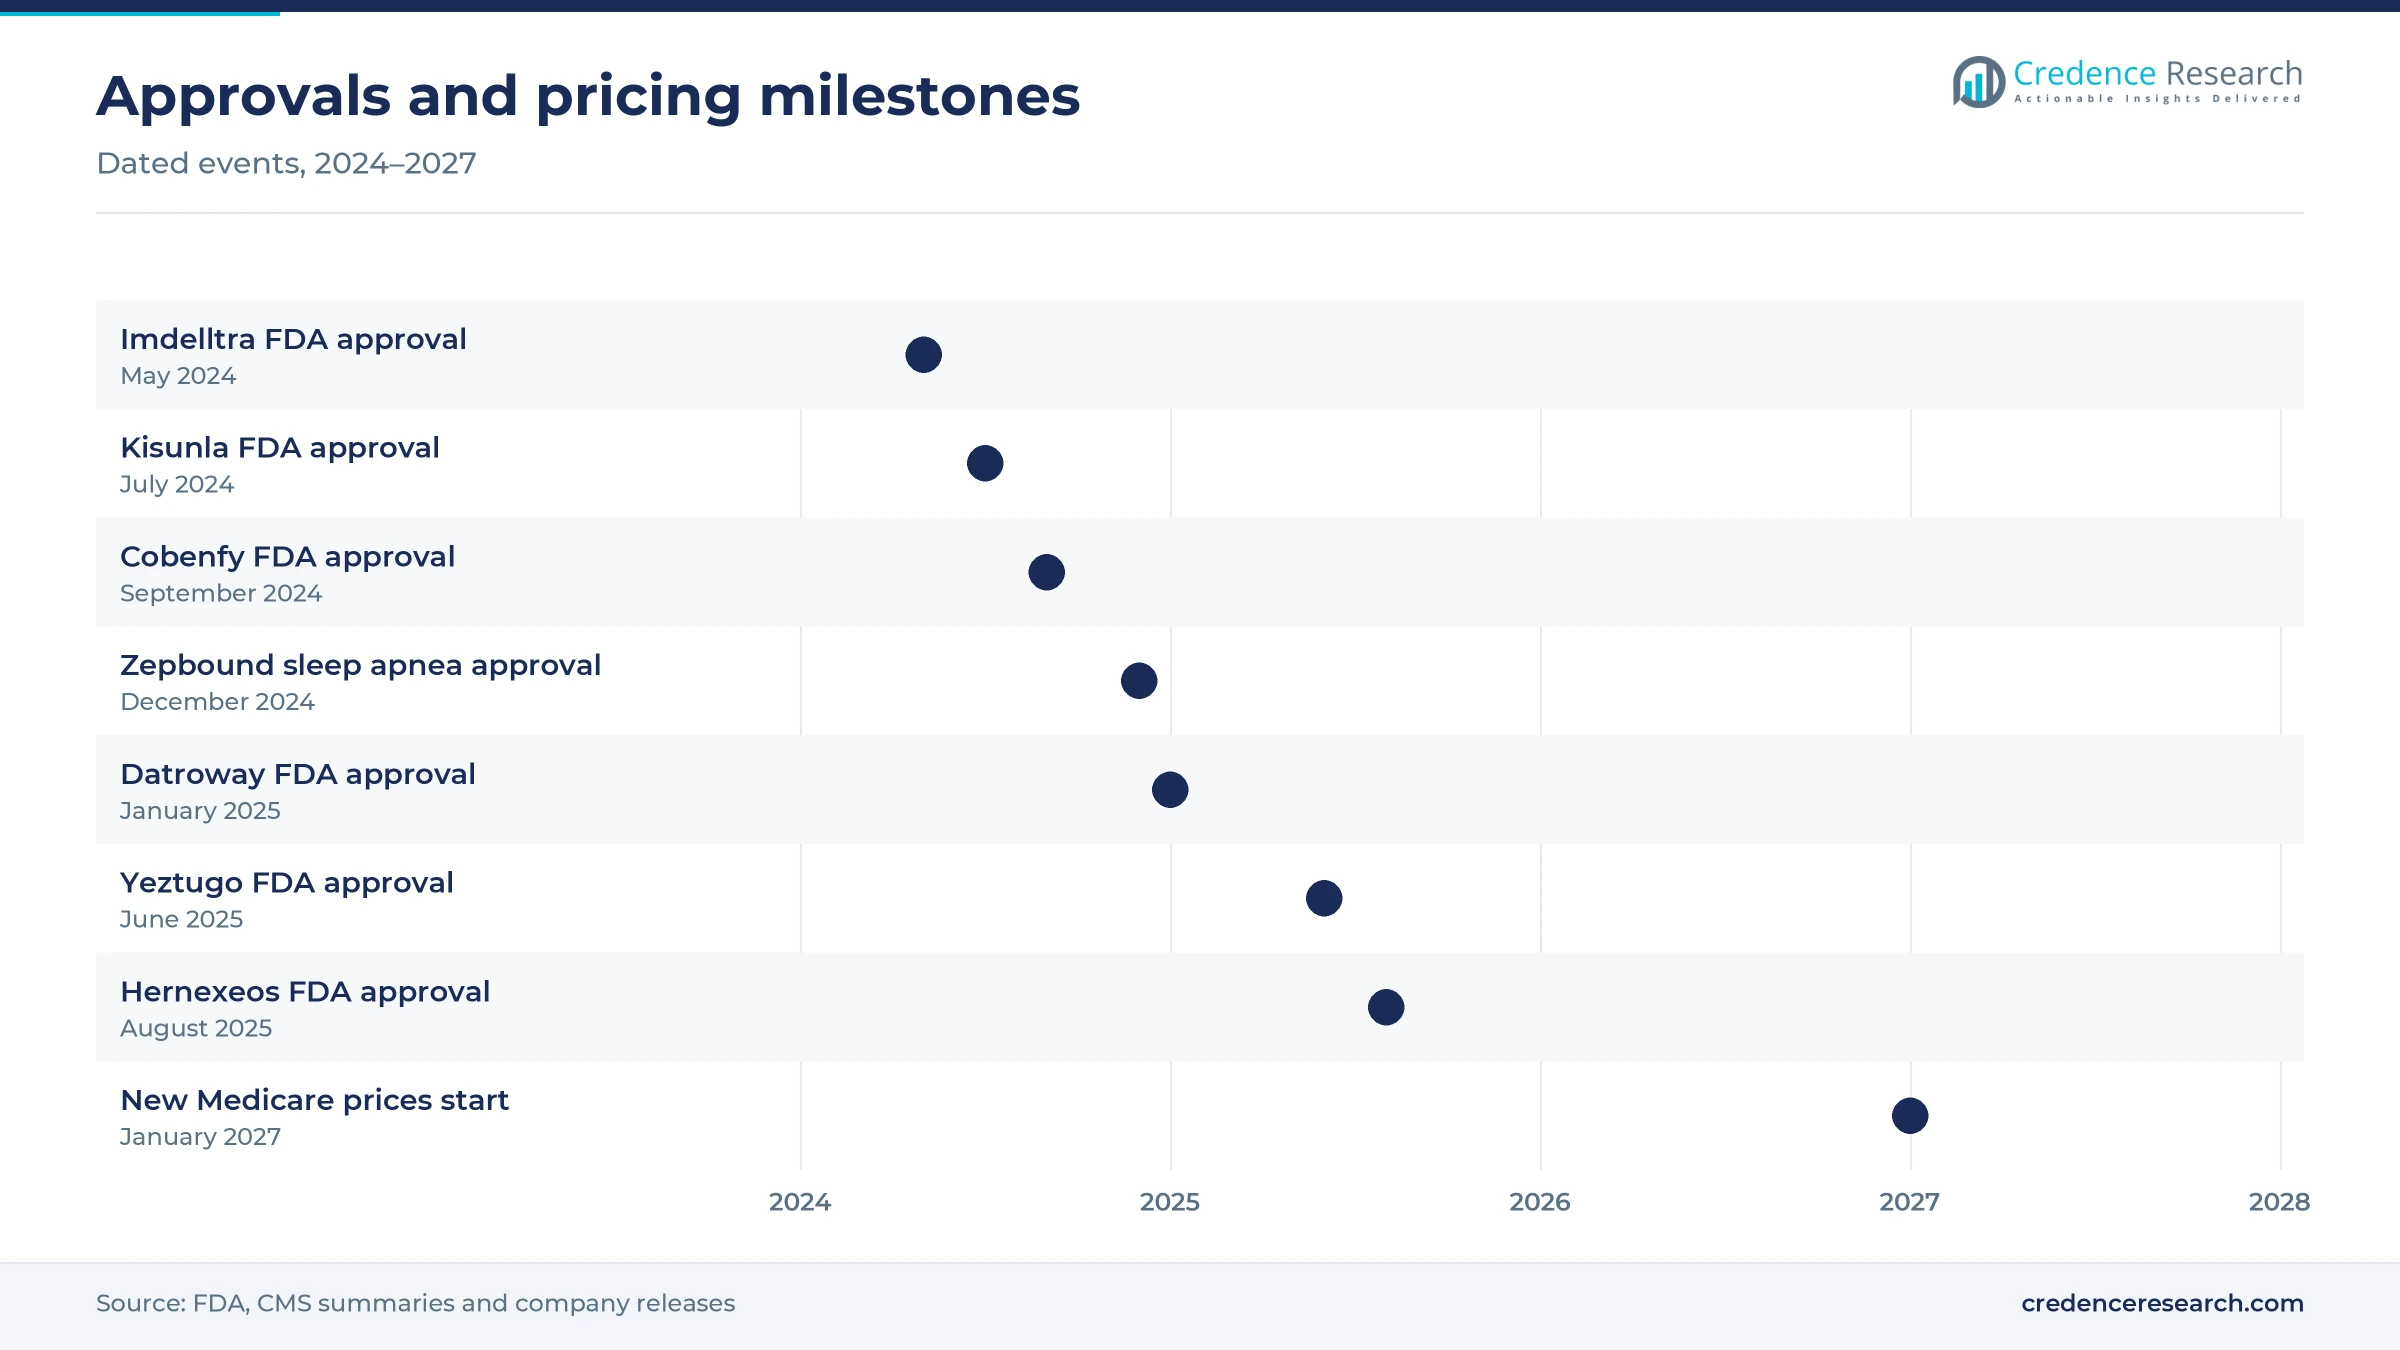
The cancer burden is the largest demand driver, because tumors need long courses of targeted drugs, antibodies and immunotherapies after diagnosis. The World Health Organization reports that cancer caused nearly 10 million deaths in 2024, close to one in six deaths worldwide. In May 2024, the FDA approved Amgen's Imdelltra for extensive-stage small cell lung cancer, a hard-to-treat tumor with few options. In January 2025, AstraZeneca's Datroway gained approval for HR-positive, HER2-negative breast cancer and AbbVie's Emrelis followed in May 2025 for a form of lung cancer. As a result, oncology drugs keep the leading application share at 34.0% of 2025 value.
Why do steady novel approvals keep lifting spending?
Steady novel approvals lift spending, because each new mechanism enters at a premium price and often treats patients with no prior option. The FDA drug center approved 50 novel medicines in 2024 and 46 in 2025, according to its list of 2025 novel approvals. In August 2025, Boehringer Ingelheim's Hernexeos gained approval for a form of non-small cell lung cancer, while Lilly's Inluriyo followed in September 2025 for ESR1-mutated breast cancer. In June 2025, CSL's Andembry was approved as a once-monthly preventive treatment for hereditary angioedema. In turn, launch volume adds new high-cost courses each year across cancer, immunology and rare disease treatment.
How is metabolic disease adding peptide demand?
Metabolic disease adds peptide demand, because diabetes and obesity affect hundreds of millions of adults who need long-term therapy. The WHO reports that the number of people living with diabetes rose from 200 million in 1990 to 830 million in 2022. More than half of adults aged 30 and over with diabetes were not taking medication for it in 2022, which leaves a large untreated pool. In December 2024, the FDA approved Lilly's Zepbound for moderate to severe obstructive sleep apnea in adults with obesity, widening its use. As a result, endocrinology grows fastest among applications at 12.49% a year, and GLP-1 receptor agonists lift peptide therapeutics.
Why are neurology launches adding new demand?
Neurology launches add new demand, because Alzheimer's disease and schizophrenia have long lacked new mechanisms of action. In July 2024, the FDA approved Lilly's Kisunla for early symptomatic Alzheimer's disease, adding an amyloid-targeting antibody that patients receive by infusion. In September 2024, Bristol Myers Squibb's Cobenfy gained approval as a new treatment for schizophrenia in adults, which the company described as the first new pharmacological approach to the disease in decades. Both products need specialist diagnosis, regular monitoring and payer review, which places them firmly in high-cost channels. The FDA drug center counted both medicines among its 50 novel approvals in 2024, a year that also included Imdelltra. Both launches need trained specialists, so access widens as more clinics add capacity. In turn, infusion centers and specialist clinics expand capacity for these therapies.
Long-acting injectables, price negotiation and online fills
How is the rise of long-acting injectables changing care?
The rise of long-acting injectables is changing care, because fewer doses improve adherence and cut clinic visits for chronic patients. In June 2025, Gilead announced FDA approval of Yeztugo, a twice-yearly lenacapavir injection for HIV prevention that gives six months of protection per dose. CSL's Andembry, approved in June 2025, is dosed once a month and can be self-administered with an autoinjector by patients aged 12 and older. Lilly's Kisunla and other infused antibodies also run on monthly schedules in infusion centers. Peptide therapeutics grow at a strong pace as weekly incretin pens spread across diabetes and obesity care. As a result, makers compete on dosing convenience as much as on clinical effect.
Is government price negotiation shifting brand revenue?
Government negotiation is shifting brand revenue, because large public payers now set prices for older high-spend medicines. CMS has announced maximum fair prices for 15 more Medicare Part D medicines that take effect on Jan. 1, 2027, according to a pharmacists' association summary. Ozempic, Rybelsus and Wegovy share a negotiated maximum fair price of $274 under the program. The same summary estimates $685 million in out-of-pocket savings for Part D enrollees under the standard benefit. In turn, originators plan lifecycle strategies around negotiation eligibility, while North America grows at 10.87% a year, slower than other regions.
Where can gene and cell therapies open new value?
Gene and cell therapies offer a clear opening, because one-time treatments can replace years of chronic care for inherited disorders. The FDA biologics center lists more than 40 approved cellular and gene therapy products, including Zevaskyn, Kebilidi, Tecelra and Aucatzyl. Gene and cell therapy grows fastest among drug classes at 16.37% a year through 2035, from a small base in 2025. Treatment centers, outcomes-based contracts and specialized logistics are expanding to support these products in the United States and Europe. As a result, gene therapy developers and contract manufacturers gain room to scale as more centers qualify to deliver treatment.
Can online pharmacies capture refrigerated refills?
Online pharmacies create a growth opening, because many biologics are self-injected at home and refilled every few weeks. Online pharmacies grow fastest among channels at 13.38% a year, as insurers and manufacturers push mail-order programs. Retail pharmacies and drug stores held 46.0% of 2025 value, so small shifts in fill habits move large sums between channels. Weekly incretin pens and monthly immune therapies suit cold-chain home delivery with nurse support. A monthly therapy means about 12 refrigerated shipments per patient each year, which rewards reliable logistics. In turn, online operators can win long-term patients in endocrinology, immunology and oncology, where adherence services matter most.
Price pressure, biosimilar entry and complex handling
How do price controls restrain brand revenue?
Price controls restrain brand revenue, because public payers now cap what they pay for high-spend medicines. Medicare negotiated prices expand to 15 more medicines from January 2027, including semaglutide brands. Europe and Japan already use health technology assessment and reference pricing to hold launch prices down. As a result, companies must prove clear clinical benefit over existing options to secure premium prices.
Why does biosimilar entry erode biologic sales?
Biosimilar entry erodes biologic sales, because several competitors can launch once patents on a reference antibody expire. Immune and cancer antibodies with large sales face this pressure through the late 2020s. Payers then move stable patients to lower-cost versions through formulary changes and step rules. Originators therefore need steady launches and new formulations simply to hold revenue, and biosimilar makers gain volume as hospitals and insurers switch patients at contract renewals.
Why do high upfront costs slow gene therapy uptake?
High upfront costs slow gene therapy uptake, because payers must fund a one-time price that can exceed years of chronic care. Many insurers lack long-term outcome data to judge value at launch. Treatment also requires qualified centers, specialized staff and careful patient selection. As a result, uptake depends on outcomes-based contracts and installment payment models that remain uncommon outside a few markets.
How do handling needs raise delivery costs?
Handling needs raise delivery costs, because many biologics need cold-chain storage, special shipping and patient training. Limited distribution networks restrict which pharmacies can dispense certain products. Prior authorization and benefit checks delay first doses for many patients. Health systems are responding with hub services, nurse support and digital tools that track adherence and shipments, which shortens the time from prescription to first dose.
North America leads value as Asia Pacific grows fastest
| Region | Value, 2025 (USD billion) | Share, 2025 | CAGR, 2026–2035 |
|---|---|---|---|
| North America | 116.34 | 45.0% | 10.87% |
| Europe | 64.63 | 25.0% | 10.77% |
| Asia Pacific | 51.71 | 20.0% | 12.97% |
| Latin America | 15.51 | 6.0% | 11.97% |
| Middle East & Africa | 10.34 | 4.0% | 12.17% |
Why does North America hold the largest regional share?
North America held a 45.0% share of 2025 value and grows at 10.87% a year through 2035. The United States launches most new biologics, targeted cancer drugs and gene therapies first, and pays the highest prices. Specialty pharmacies, pharmacy benefit managers and prior authorization shape which products reach patients. Medicare negotiation from 2026 and 2027 trims spending on some mature brands, so new launches carry more of the growth in the region.
What shapes high-cost medicine spending across Europe?
Europe held a 25.0% share of 2025 value and grows at 10.77% a year, the slowest pace of the five regions. Health technology assessment bodies review cost effectiveness before national payers list new medicines. Germany, France, Italy, Spain and the United Kingdom account for most regional value. However, AstraZeneca, GSK, Bayer and Boehringer Ingelheim keep major research and manufacturing bases in the region, which supports early access programs and clinical trials.
How fast is Asia Pacific adding patients?
Asia Pacific held a 20.0% share of 2025 value and is the fastest-growing region at 12.97% a year. China widens national reimbursement listings for targeted cancer and immune therapies each year. Japan and South Korea adopt new biologics quickly through national insurance. India and Southeast Asia add patients as private hospitals expand oncology and specialist care, while local biosimilar makers lower the cost of older antibodies.
Where is Latin America adding demand?
Latin America held a 6.0% share of 2025 value and grows at 11.97% a year through 2035. Brazil and Mexico lead regional spending, with public systems buying biologics through tenders and private patients paying in retail pharmacies.
What limits growth in the Middle East and Africa?
The Middle East and Africa held a 4.0% share of 2025 value and grows at 12.17% a year through 2035. Gulf states fund modern hospitals that adopt oncology and rare disease therapies quickly.
Approvals for cancer, neurology and rare disease since 2024
| Development | Status and market relevance |
|---|---|
| In September 2024, the FDA approved Bristol Myers Squibb's Cobenfy for schizophrenia in adults. | Approved; new mechanism in psychiatry |
| In August 2025, the FDA approved Boehringer Ingelheim's Hernexeos for a form of non-small cell lung cancer. | Approved; targeted oral therapy in lung cancer |
| In September 2025, the FDA approved Lilly's Inluriyo for ESR1-mutated advanced or metastatic breast cancer. | Approved; oral estrogen receptor degrader |
| In June 2025, Gilead announced FDA approval of Yeztugo for HIV prevention with twice-yearly dosing. | Approved; long-acting injectable prevention |
| In October 2025, Bayer announced U.S. approval of Lynkuet for moderate to severe menopausal vasomotor symptoms. | Approved; nonhormonal option in women's health |
Modalities reshaping high-cost treatment
- Antibody-drug conjugates such as Datroway and Emrelis deliver a toxic payload to tumor cells, which supports premium pricing in oncology.
- Bispecific T-cell engagers such as Imdelltra link immune cells to tumors, which requires monitored administration in hospital settings.
- Gene and cell therapies offer one-time treatment for inherited and blood disorders, which shifts payment toward outcomes-based contracts.
- Long-acting injectables such as twice-yearly lenacapavir reduce dosing frequency, which improves adherence in prevention and chronic care.
- Incretin peptides such as tirzepatide act on GLP-1 and GIP receptors, which widens use across diabetes, obesity and sleep apnea.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Originators compete on pipelines, platforms and access
Competition in the market centers on research-driven originators with large biologic and targeted drug pipelines. AbbVie, Amgen, AstraZeneca and Bristol Myers Squibb compete in oncology and immunology, and each added new approvals in 2024 or 2025. Eli Lilly leads in incretin medicines and added Kisunla in neurology and Inluriyo in breast cancer. Gilead competes in HIV treatment and prevention, with twice-yearly Yeztugo approved in 2025. CSL Behring and BioMarin compete in plasma, hematology and rare disease therapies, while Biogen focuses on neurology. Bayer, Boehringer Ingelheim and GSK compete across cardiology, oncology, respiratory and women's health. Payers and pharmacy benefit managers use formulary placement to push prices down. However, first-in-class launches still win fast uptake when no alternative treatment exists.
Companies profiled and their roles in this market
| Company | Type | Role in the market |
|---|---|---|
| AbbVie | Originator | Immunology, oncology and neuroscience medicines, including Emrelis |
| Amgen | Originator | Oncology, inflammation and bone medicines, including Imdelltra |
| AstraZeneca | Originator | Oncology, respiratory and rare disease medicines, including Datroway |
| Bayer AG | Originator | Cardiology, oncology and women's health medicines, including Lynkuet |
| Biogen | Originator | Neurology and rare neuromuscular disease medicines |
| BioMarin | Originator | Rare genetic disease medicines and gene therapy |
| Boehringer Ingelheim | Originator | Oncology, respiratory and cardiometabolic medicines, including Hernexeos |
| Bristol Myers Squibb | Originator | Oncology, immunology and neuroscience medicines, including Cobenfy |
| CSL Behring | Originator | Plasma-derived and recombinant therapies, including Andembry |
| Eli Lilly | Originator | Incretin, neurology and oncology medicines, including Zepbound, Kisunla and Inluriyo |
| Gilead Sciences | Originator | HIV, liver disease and oncology medicines, including Yeztugo |
| GSK plc | Originator | Respiratory, HIV, oncology and vaccine portfolio |
Launch volume outweighs price gains through 2035
Credence Research's view is that launch volume, rather than price, will carry most growth through 2035. The market grows at 11.41% a year as cancer burden, metabolic disease and steady FDA approvals add treated patients. Medicare negotiation in the United States and health technology assessment in Europe limit gains on mature brands. The strongest openings sit in gene and cell therapy, long-acting injectables and online dispensing, while biosimilar entry pressures older biologics. Companies with broad pipelines and strong patient support services are best placed to gain share.
How Credence Research built the high-cost medicine model
The report uses 2025 as the base year and 2026 to 2035 as the forecast period. Market values come from the Credence Research model, which builds spending by application, drug class and distribution channel. Regional and segment splits are Credence Research estimates informed by FDA approval lists, World Health Organization statistics, Medicare program summaries and company releases. No primary interviews or surveys were used in preparing this edition of the report.
Oncology, biologic and gene therapy outlook to 2035
By 2035, the specialty pharmaceuticals market is projected to reach USD 761.98 billion, with growth led by Asia Pacific, gene and cell therapy and online dispensing. Oncology will remain the largest application as targeted drugs and conjugates spread across tumor types. Incretin medicines keep endocrinology growing fastest, while biosimilars pull prices down on older antibodies. North America keeps the highest spending per patient, and Asia Pacific adds the most new patients over the decade as insurance coverage widens.
Frequently Asked Questions
How big is the global specialty pharmaceuticals market?
Which region leads specialty pharmaceuticals spending?
Which application leads the market?
Which drug class grows fastest?
How many novel medicines did the FDA approve recently?
How does Medicare price negotiation affect the market?
Who are the leading specialty pharmaceuticals companies?
Which distribution channel grows fastest?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Application
- 1.2.1 Oncology
- 1.2.2 Immunology
- 1.2.3 Endocrinology
- 1.2.4 Neurology
- 1.2.5 Rare & Orphan Disorders
- 1.2.6 Others
- 1.3 By Drug Class
- 1.3.1 Biologics
- 1.3.2 Small-molecule Specialty Drugs
- 1.3.3 Gene & Cell Therapy
- 1.3.4 Peptide Therapeutics
- 1.3.5 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2025: USD 258.53 billion → 2035: USD 761.98 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Historical Period: 2018-2025
- 2.6.2 Base Year: 2025
- 2.6.3 Forecast Period: 2025-2035
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2025
- 3.3 Forecast Market Size, 2035
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Specialty Pharmaceuticals Market Trends and Developments
- 4.1 Historical Industry Development, 2018-2025
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Specialty Pharmaceuticals Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis, 2018-2025
- 5.2 Demand Forecast, 2025-2035
- 5.3 Production and Output Trend, 2018-2025
- 5.4 Production and Output Forecast, 2025-2035
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Specialty Pharmaceuticals Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends, 2018-2025
- 6.3 Pricing Outlook, 2025-2035
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Specialty Pharmaceuticals Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Specialty Pharmaceuticals Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Specialty Pharmaceuticals Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Specialty Pharmaceuticals Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Specialty Pharmaceuticals Market Outlook, 2025-2035
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2025: USD 258.53 billion → 2035: USD 761.98 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size, 2018-2025
- 11.1.4 Base-Year Market Size, 2025
- 11.2 Market Forecast, 2025-2035
- 11.2.1 Revenue Forecast to 2035
- 11.2.2 Volume Forecast to 2035
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Specialty Pharmaceuticals Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2025
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Application - Market Size and Forecast, 2025-2035
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size, 2018-2025
- 12.3.3 Revenue Forecast, 2025-2035
- 12.3.4 Volume Forecast, 2025-2035
- 12.3.5 Base-Year Market Share, 2025
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Oncology
- 12.3.7.2 Immunology
- 12.3.7.3 Endocrinology
- 12.3.7.4 Neurology
- 12.3.7.5 Rare & Orphan Disorders
- 12.3.7.6 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Drug Class - Market Size and Forecast, 2025-2035
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size, 2018-2025
- 12.4.3 Revenue Forecast, 2025-2035
- 12.4.4 Volume Forecast, 2025-2035
- 12.4.5 Base-Year Market Share, 2025
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Biologics
- 12.4.7.2 Small-molecule Specialty Drugs
- 12.4.7.3 Gene & Cell Therapy
- 12.4.7.4 Peptide Therapeutics
- 12.4.7.5 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 Global Specialty Pharmaceuticals End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Specialty Pharmaceuticals Geographic Market Outlook, 2025-2035
- 14.1 Regional Market Size and Share, 2025
- 14.2 Regional Market Forecast, 2025-2035
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Specialty Pharmaceuticals Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2025-2035
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Specialty Pharmaceuticals Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2025
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2025-2035
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 AbbVie
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Amgen
- 18.4 AstraZeneca
- 18.5 Bayer AG
- 18.6 Biogen
- 18.7 BioMarin
- 18.8 Boehringer Ingelheim
- 18.9 Bristol Myers Squibb
- 18.10 CSL Behring
- 18.11 Eli Lilly
- 18.12 Gilead Sciences
- 18.13 GSK plc
- 18.14 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

