
Fried chicken chains anchor demand as visitors and apps grow
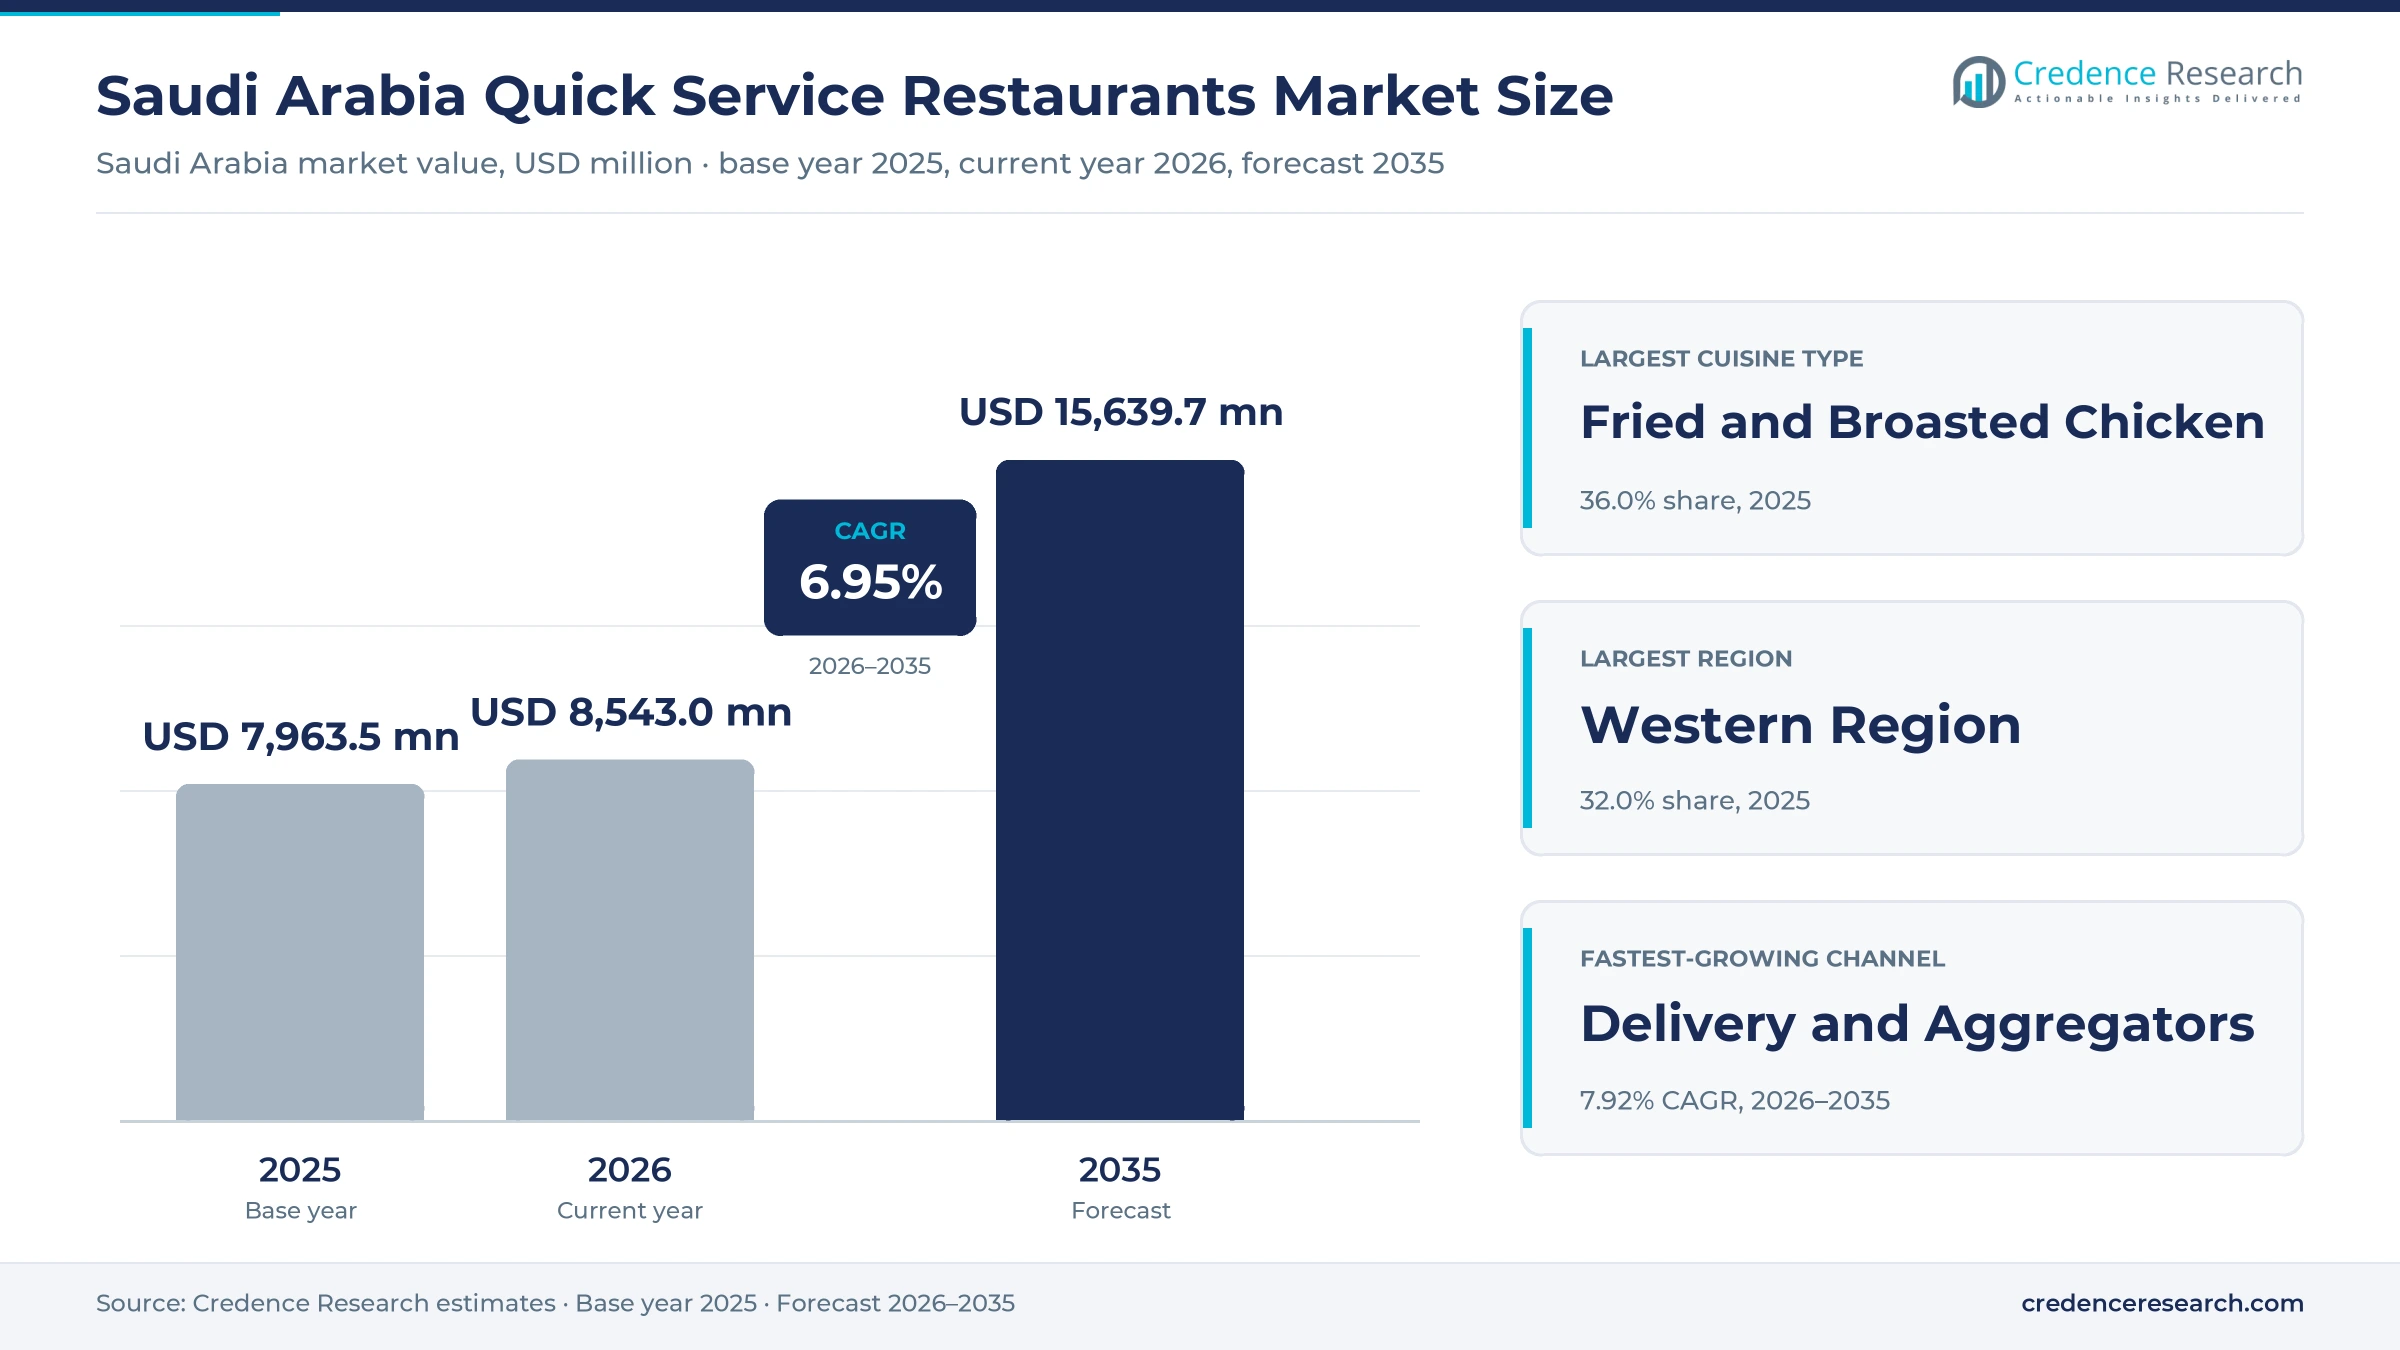
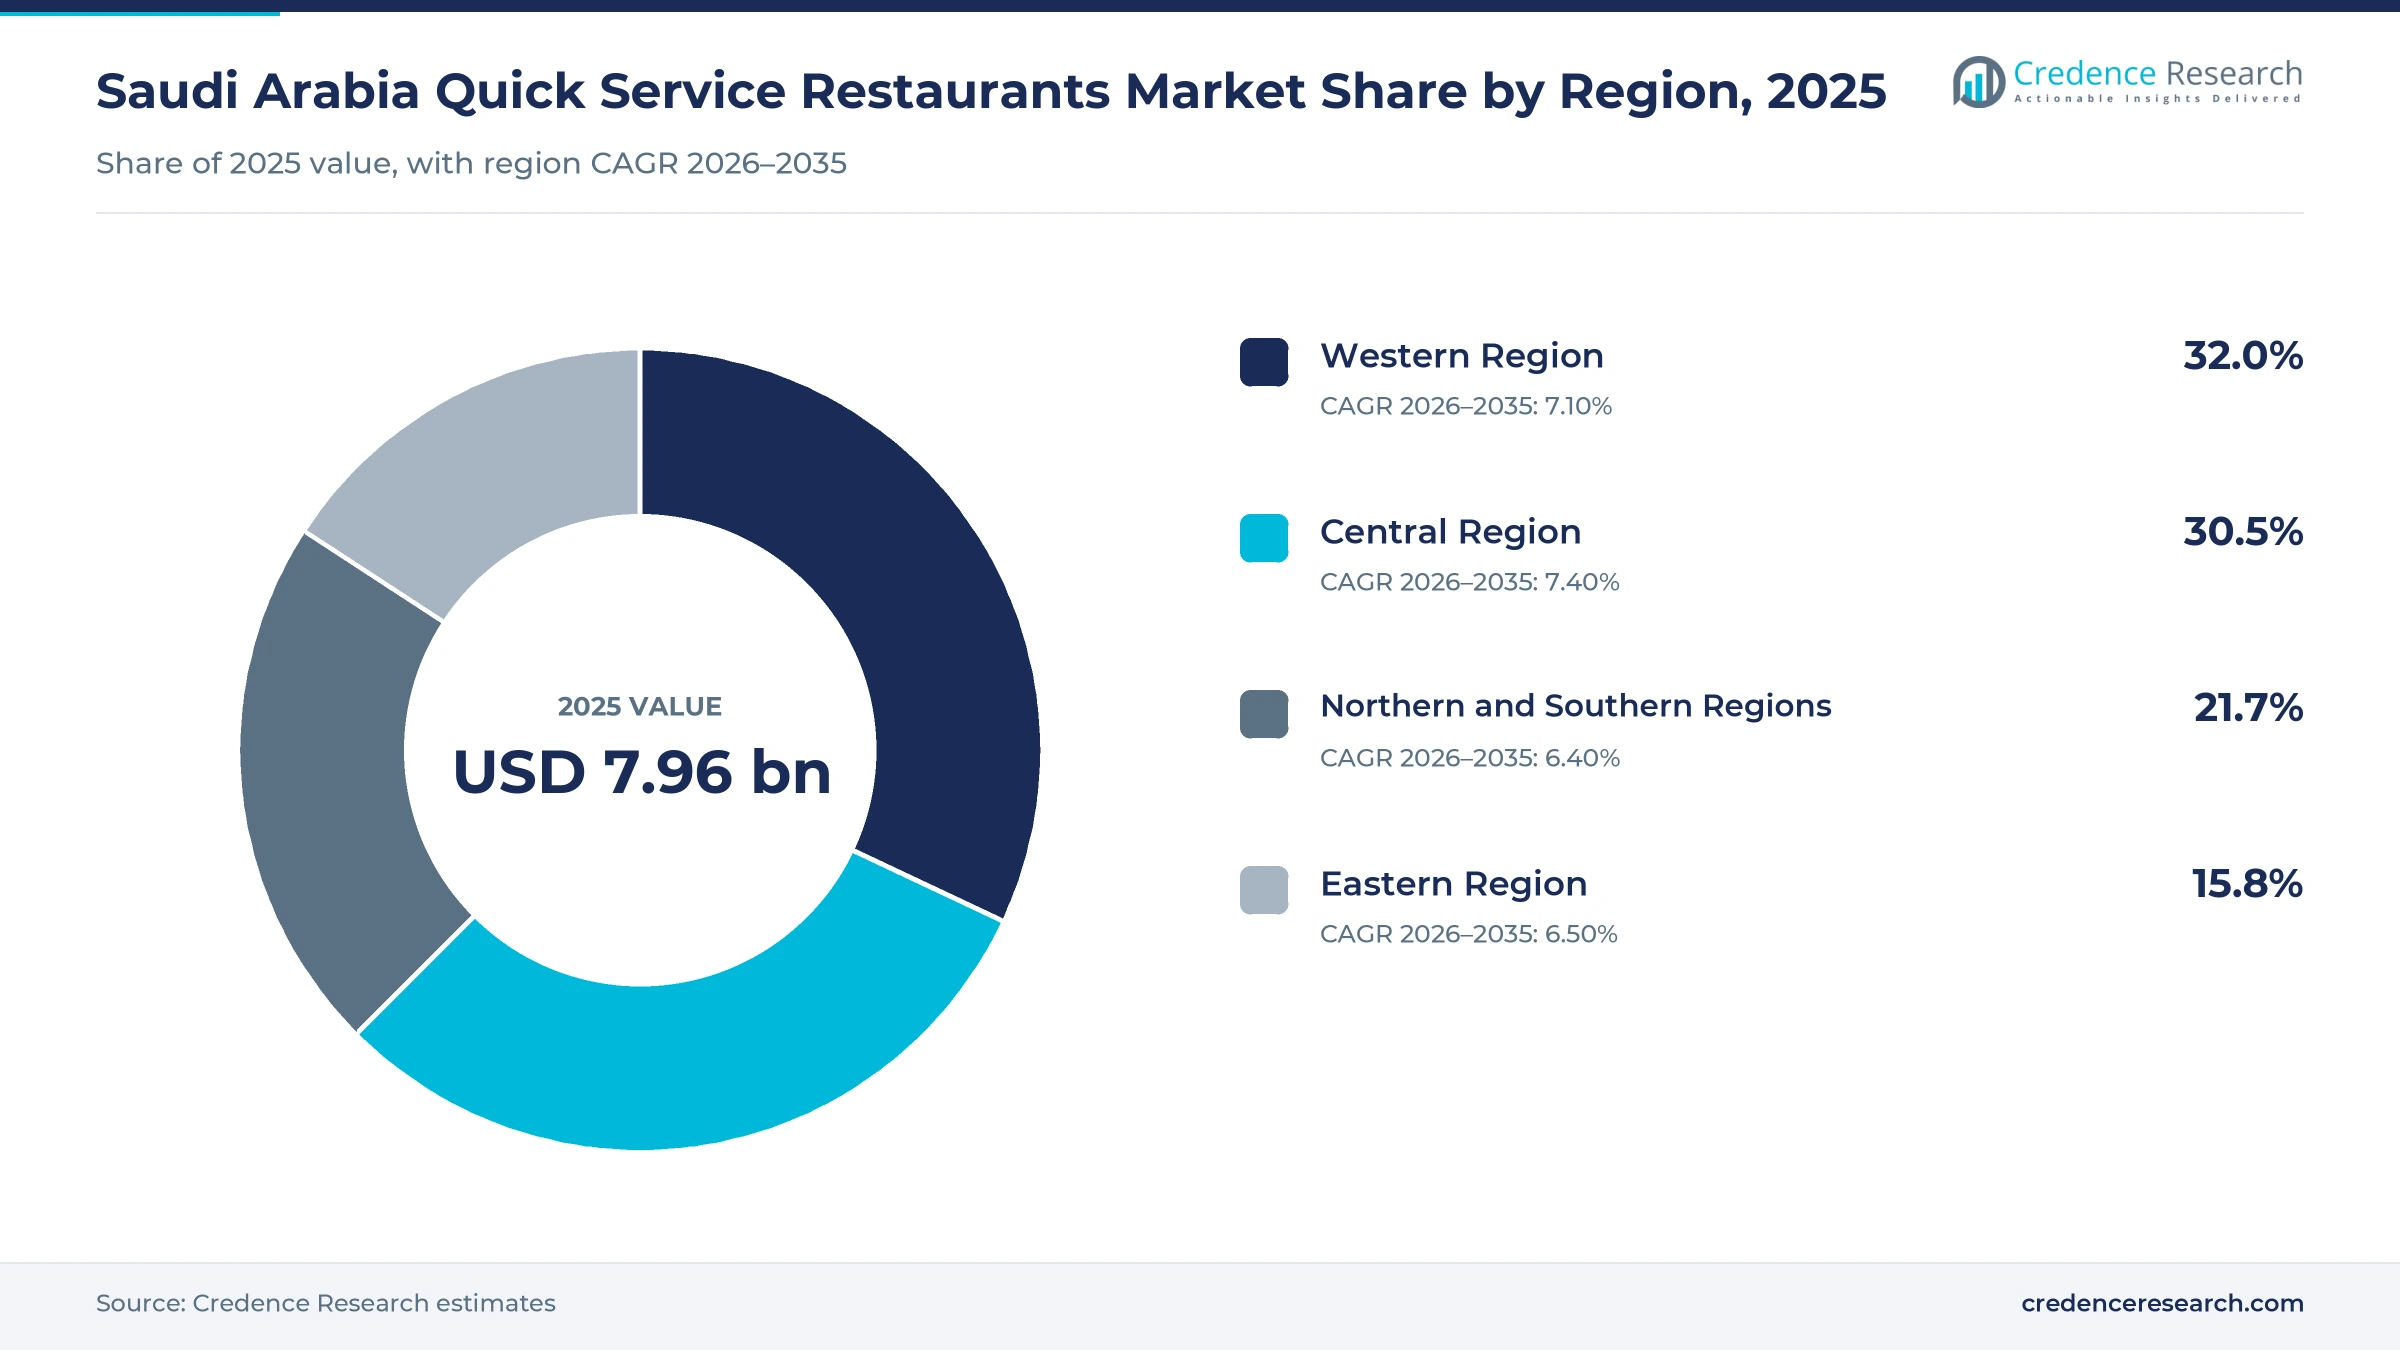
The Saudi Arabia quick service restaurants market was valued at USD 7.96 billion in 2025 and is projected to increase from USD 8.54 billion in 2026 to USD 15.64 billion by 2035, registering a CAGR of 6.95% during 2026–2035. Demand comes from a young, urban population that eats out often, from millions of pilgrims and leisure visitors, and from households that order meals through delivery apps. The Western Region held the largest regional share, 32.0% in 2025, because Makkah, Madinah and Jeddah serve pilgrims and tourists all year. The Central Region is the fastest-growing region at 7.40% a year, as Riyadh adds new districts, offices and entertainment venues. In turn, the Saudi Food and Drug Authority required food outlets and delivery platforms to show salt, caffeine and calorie details on menus from July 1, 2025, which pushes chains to reformulate and relabel their offers.
Which fast-dining formats and outlets does the estimate cover?
The estimate measures consumer spending at quick service outlets in Saudi Arabia that sell fried and broasted chicken, burgers, pizza, shawarma and other local fast meals for dine-in, takeaway, drive-through and delivery. It covers company-owned outlets, franchised outlets and cloud kitchens run by local and international brands.
The estimate excludes full-service restaurants, cafes that mainly sell coffee, hotel banquets, institutional catering and packaged food sold in supermarkets. The value chain runs from meat, poultry and flour suppliers through central kitchens and franchise operators to outlets, delivery platforms and diners.
Saudi Arabia Quick Service Restaurants Market Insights
- The Saudi Arabia quick service restaurants market was valued at USD 7.96 billion in 2025 and is projected to reach USD 15.64 billion by 2035, registering a CAGR of 6.95% during 2026–2035.
- The Western Region held a 32.0% share of 2025 value, because Makkah, Madinah and Jeddah serve pilgrims, tourists and large resident populations.
- Fried and broasted chicken led with a 36.0% share of 2025 value, because local chicken chains are everyday staples for families.
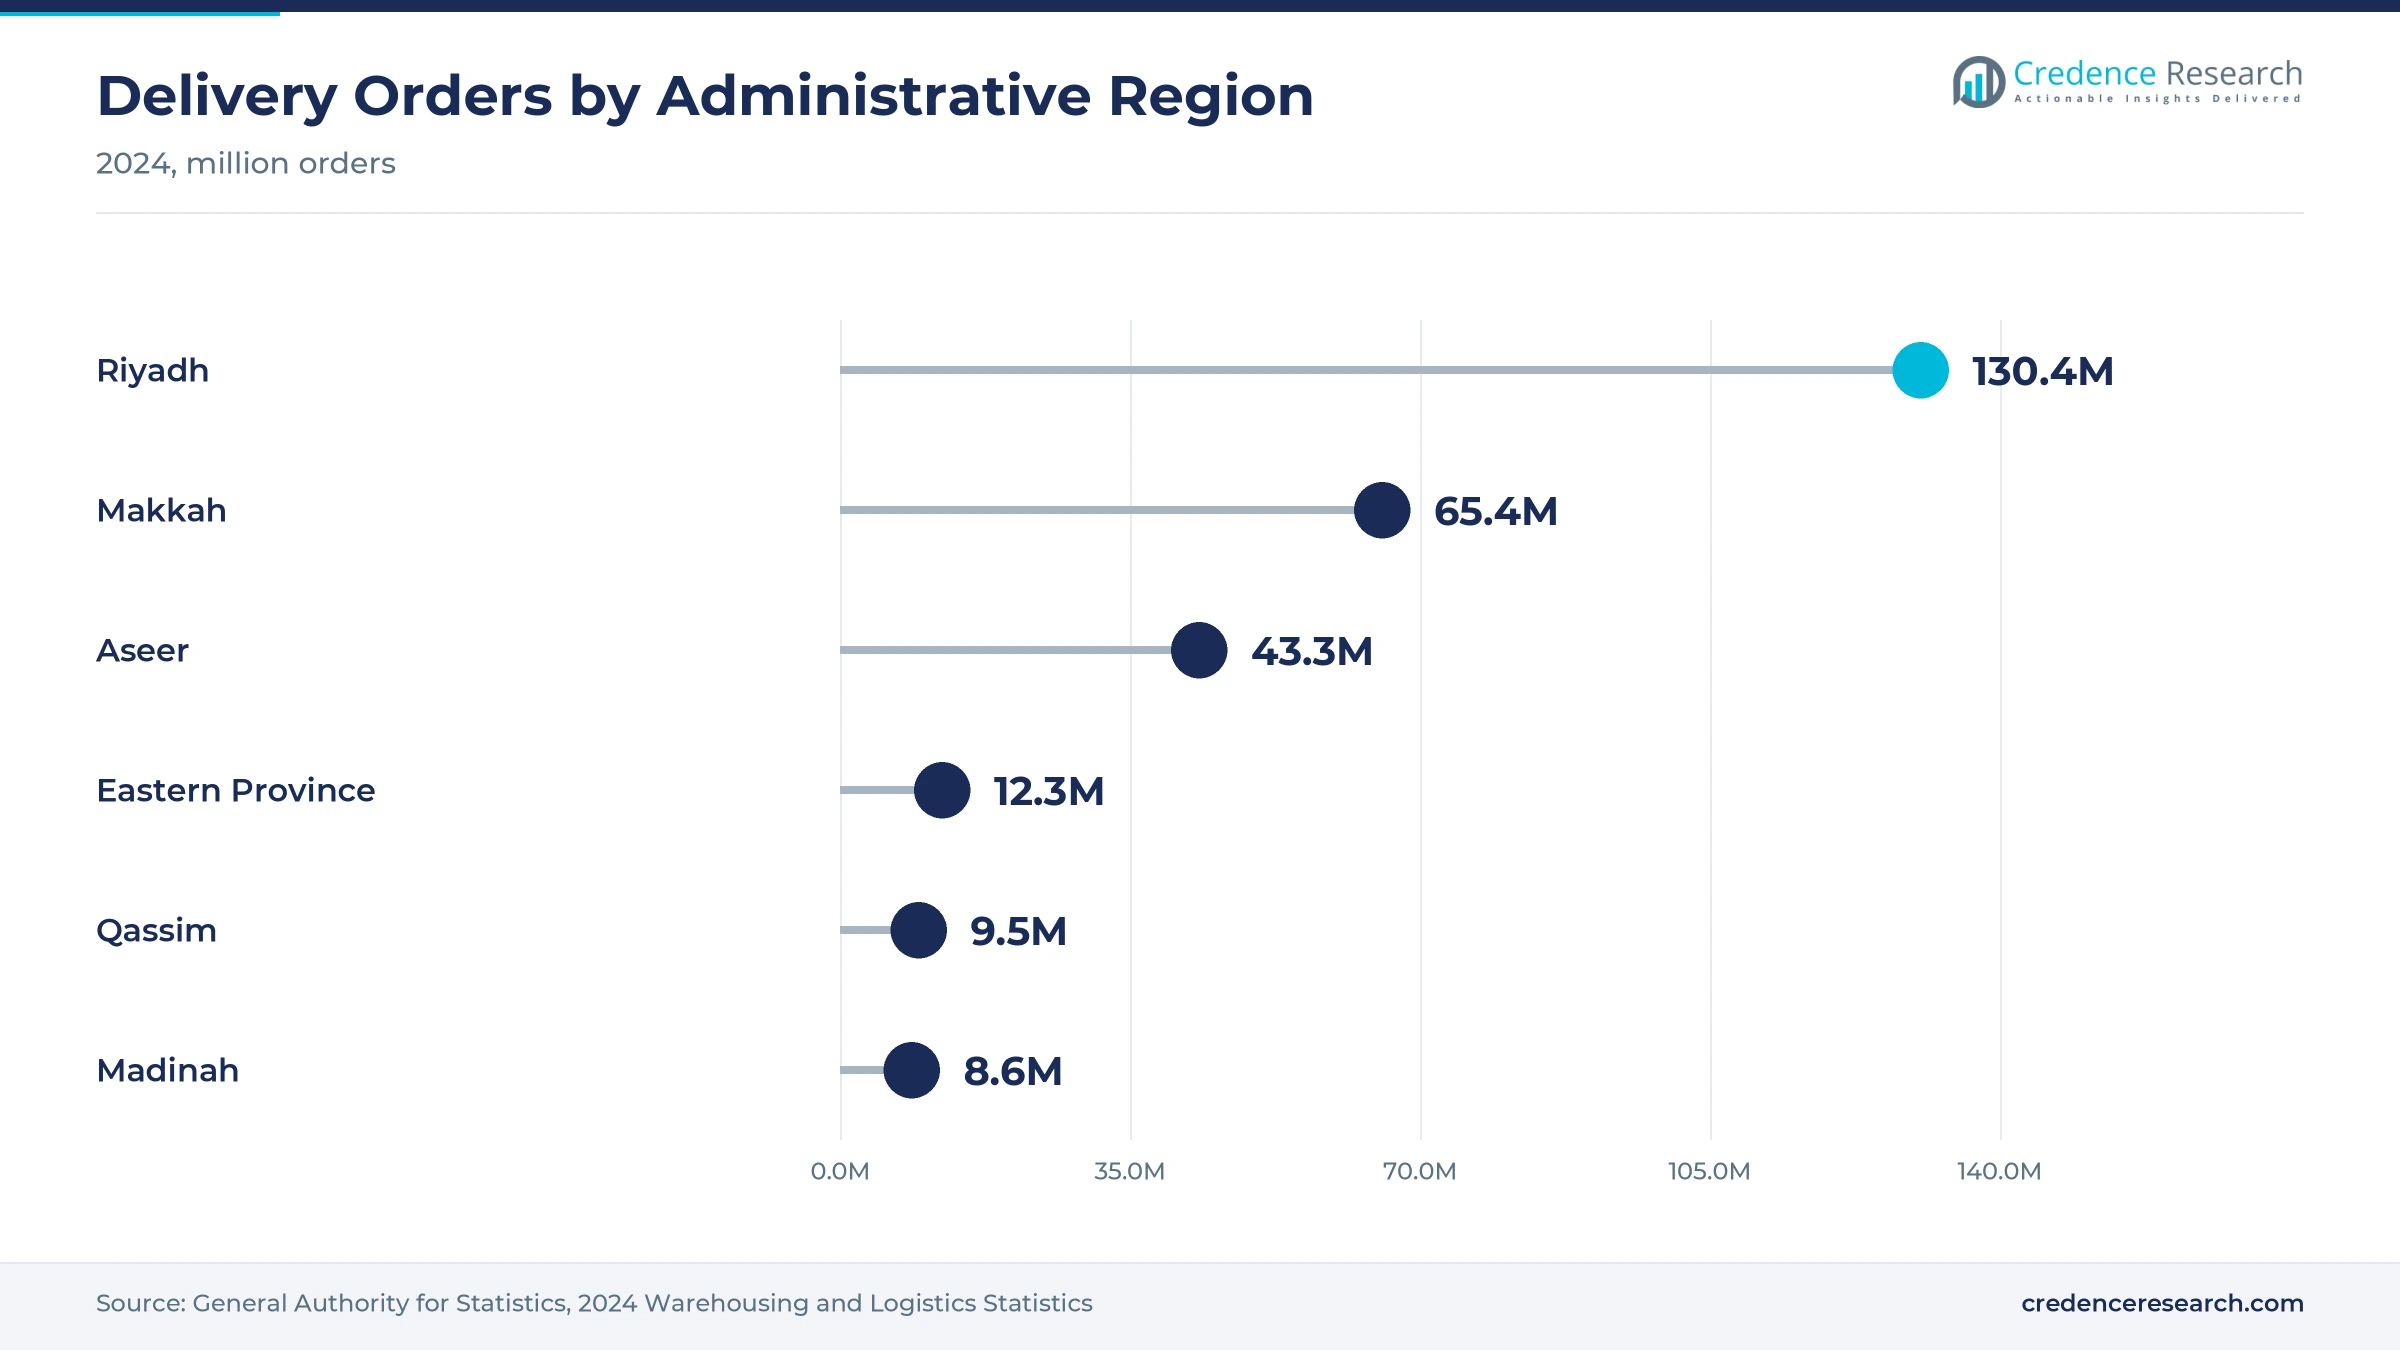
- Licensed delivery providers executed 288.1 million orders in 2024, and Riyadh alone accounted for 130.4 million of them.
- Saudi Arabia received 115.9 million domestic and inbound tourists in 2024, an increase of 6% compared with 2023.
Fried chicken leads while local shawarma grows fastest
Why does fried chicken hold the largest share?
Based on cuisine type, the market is categorized into fried and broasted chicken, burgers, pizza and Italian QSR, and shawarma and local QSR. Fried and Broasted Chicken led with a 36.0% share of 2025 value, because local chicken chains are everyday staples for families and pilgrims. Shawarma and Local QSR grows fastest at 7.69% a year, as homegrown shawarma brands open in malls, airports and new districts.
How fast is visitor spending rising?
Based on customer type, the market is categorized into Saudi nationals, resident expatriates, leisure tourists and religious visitors. Saudi Nationals led with a 56.0% share of 2025 value, because citizens make up the largest group of regular diners. Leisure Tourists grow fastest at 9.25% a year, as events, theme parks and visa reforms bring more visitors.
Which channels bring meals to diners fastest?
Based on distribution channel, the market is categorized into dine-in, takeaway, drive-through and delivery and aggregators. Dine-In led with a 30.0% share of 2025 value, because families still gather at mall food courts and outlets. Delivery and Aggregators grow fastest at 7.92% a year, as apps, online ordering systems and rider fleets widen reach. Drive-through lanes also gain share as chains open pads along highways in growing suburbs.
How are cloud kitchens changing outlet models?
Based on service model, the market is categorized into company-owned outlets, single-country franchise, multi-brand franchise groups and cloud and satellite kitchens. Company-Owned Outlets led with a 46.0% share of 2025 value, because the largest local chains run their own outlets. Cloud and Satellite Kitchens grow fastest at 9.08% a year, as brands cook for delivery without full dining rooms.
| Segment Group | Leading Sub-segment | Share, 2025 | Fastest-growing Sub-segment | CAGR, 2026–2035 |
|---|---|---|---|---|
| By Cuisine Type | Fried and Broasted Chicken | 36.0% | Shawarma and Local QSR | 7.69% |
| By Customer Type | Saudi Nationals | 56.0% | Leisure Tourists | 9.25% |
| By Distribution Channel | Dine-In | 30.0% | Delivery and Aggregators | 7.92% |
| By Service Model | Company-Owned Outlets | 46.0% | Cloud and Satellite Kitchens | 9.08% |
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Pilgrims, new outlets and app ordering lift demand
How do tourism and pilgrimage visits expand meal demand?
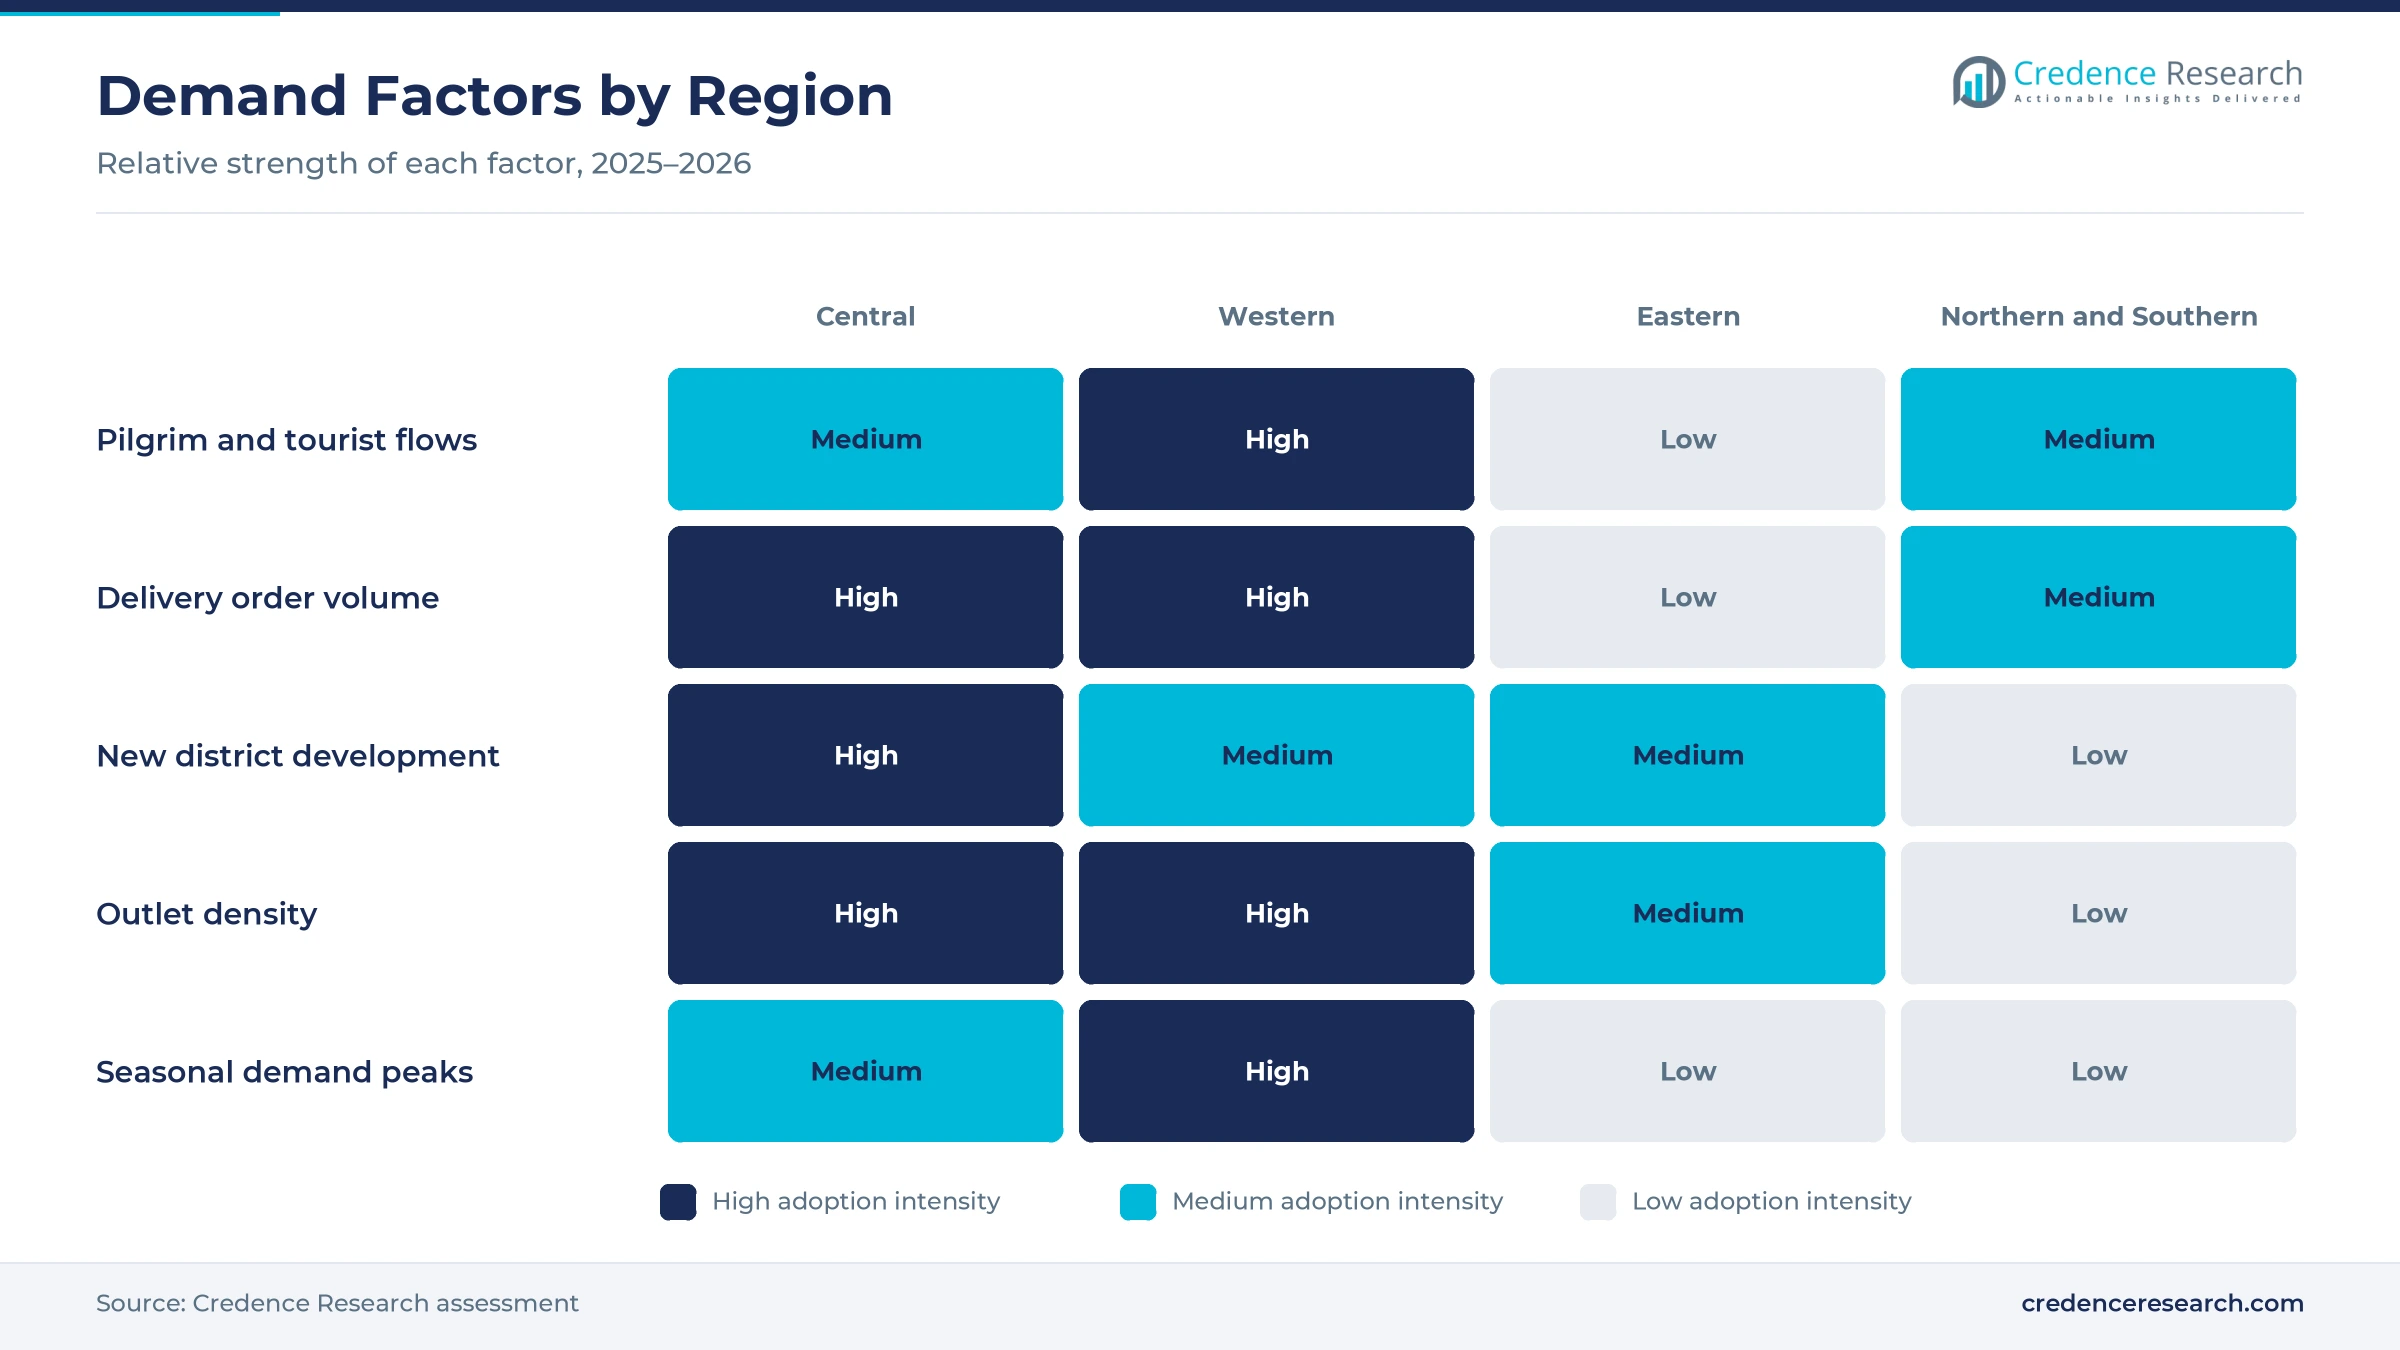
Tourism and pilgrimage growth expands meal demand, because visitors eat most meals outside and favor fast, familiar formats near holy sites, hotels and attractions. Saudi Arabia received 115.9 million domestic and inbound tourists in 2024, up 6% from 2023, and they spent about SAR 284 billion, according to the Ministry of Tourism. Makkah received 43.1 million of those tourists, and religious trips made up 41% of inbound visits. The Hajj season of 2025 drew 1.67 million pilgrims, of whom 1.51 million came from outside the Kingdom, according to the statistics authority. As a result, religious visitors and leisure tourists together grow faster than the market, with leisure tourists rising at 9.25% a year.
Why do new outlets and districts open new catchments?
Outlet development in new districts opens fresh catchments, because chains follow housing, offices and malls into growing suburbs and along highways. Americana Restaurants grew its network 4% to 2,746 restaurants by June 30, 2026, and expects 120 to 130 more stores by the end of the year, according to AGBI. Alamar Foods agreed on Sept. 30, 2025, to acquire 29 Domino's branches in Makkah and Taif, bringing its Saudi Domino's network to 325 outlets. Herfy Food Services runs more than 380 restaurants across the Kingdom. In turn, company-owned outlets keep 46.0% of 2025 value as chains add drive-through pads on main roads.
How does app delivery raise everyday ordering?
Digital delivery and convenience raise everyday ordering, because apps let households, office workers and students order fast meals at any hour. Licensed delivery providers executed 288.1 million orders in 2024, according to Argaam citing the statistics authority. The fourth quarter of 2024 recorded the highest volume at about 77.6 million orders, which shows steady growth through the year. The number of delivery drivers reached 181,300 in the fourth quarter of 2024, which widens coverage beyond city centers. As a result, delivery and aggregators grow at 7.92% a year, the fastest of all channels. Chains respond by adding delivery-only menus and packaging that keeps fried items crisp during longer trips.
Why does a growing non-oil economy support eating out?
A growing non-oil economy supports eating out, because new jobs in retail, hospitality and construction raise household incomes and time spent outside the home. Non-oil real GDP grew by 4.5% in 2024, driven by retail, hospitality and construction, according to the International Monetary Fund. The 2022 census counted 32.2 million residents, of whom 13.4 million were non-Saudis who often rely on affordable fast meals. Riyadh, Makkah and the Eastern Province held 68% of the population, which concentrates demand in large cities. In turn, Saudi nationals hold 56.0% of 2025 value, while resident expatriates keep value and mass market tiers busy.
Menu labels, new brands and kitchen hubs reshape dining
How is the shift to menu labeling changing recipes?
The shift to menu nutrition labeling is changing recipes, because diners can now compare salt, caffeine and calories before they order. The Saudi Food and Drug Authority required food outlets, cafes and delivery platforms to display nutritional details on menus from July 1, 2025, according to Gulf News. The rules also cover high-salt warnings and caffeine levels, in line with a maximum daily salt intake of 5 grams. Delivery apps had to show the same details, which affects 288.1 million yearly orders. As a result, chains reformulate sauces and add grilled and lighter items, and some test plant-based fast food options.
Why is the rise of new international brands significant?
The rise of new international brands is significant, because local operators now import fresh concepts to win younger diners who want variety. Kudu partnered with an Australian sushi chain in August 2025 to open 40 stores across Saudi Arabia by 2035, with the first locations in Riyadh from October 2025, according to Inside Retail. Alamar Foods took operational control of 29 Domino's branches in Makkah and Taif from October 2025. Americana said in July 2026 that premium menus lifted its first-half sales. In turn, multi-brand franchise groups grow faster than single-brand franchisees during 2026–2035, because they can share kitchens, supply contracts and delivery partnerships across several brands at once.
Can cloud kitchens open a low-cost growth path?
Cloud and satellite kitchens offer a low-cost growth path, because brands can serve delivery demand without paying for large dining rooms in prime locations. Riyadh recorded 130.4 million delivery orders in 2024, and Makkah recorded 65.4 million, which shows where kitchen hubs make sense. Aseer recorded 43.3 million orders in the same year, which points to delivery demand outside the largest cities. Fourth-quarter Riyadh orders reached about 36.7 million, the highest of any quarter. As a result, cloud and satellite kitchens grow at 9.08% a year, the fastest of all service models. Operators place these kitchens near dense housing so riders can reach more homes within short delivery windows.
Is automated ordering an opening for faster service?
Automated ordering offers an opening for faster service, because self-service screens and app pickup cut queues at peak hours during Ramadan, Eid and Hajj. The 2025 Hajj brought 1.67 million pilgrims into a few days of heavy demand, which strains counter staff. Delivery driver numbers reached 181,300 in late 2024, so outlets also need faster handoffs to riders. Many chains now install self-ordering kiosks and link them to point-of-sale terminals and kitchen screens. Riyadh hosted 20.5 million tourists in 2024, which adds visitors who prefer quick digital ordering in unfamiliar outlets. In turn, the Central Region leads early adoption, as Riyadh chains test new formats before rolling them out nationally.
Rents, staffing rules and price-sensitive diners test chains
How do rising rents squeeze outlet margins?
Rising commercial rents squeeze outlet margins, because new malls and busy streets in Riyadh and Jeddah charge premium rates. As a result, chains must sell more meals per outlet to cover fixed costs. Smaller local brands feel the pressure first, since they lack bargaining power with landlords. Operators respond with smaller footprints, drive-through pads on cheaper land and cloud kitchens that serve delivery only. Some chains also share sites with fuel stations to cut rent per outlet.
Why do staffing rules raise operating costs?
Staffing rules raise operating costs, because Saudization targets require chains to hire more Saudi nationals at higher wages. In turn, outlets that relied on lower-cost foreign workers face higher payrolls and training costs. Smaller franchisees find it hardest to adjust quickly across many outlets. Operators respond with training academies, automation at the counter and shift designs that suit Saudi job seekers. Over time, these steps can lower staff turnover and improve service quality.
How do price-sensitive diners limit menu price increases?
Price-sensitive diners limit menu price increases, because many families and expatriate workers switch to cheaper brands when prices rise. However, chicken, beef, packaging and delivery commissions keep getting more expensive. Value and mass market chains feel this tension most during slower months. Operators respond with value meals, loyalty apps, bundle deals and local sourcing that keeps costs under control. Some chains also renegotiate delivery commissions or push diners toward their own ordering apps.
Why does seasonal demand strain operations?
Seasonal demand strains operations, because Ramadan, Eid and Hajj create sharp peaks while summer heat cuts foot traffic in some cities. As a result, outlets in Makkah and Madinah need extra staff, stock and delivery riders for a few weeks each year. Smaller operators struggle to plan staff and stock for these swings. Chains respond with temporary kiosks, central kitchens and flexible staffing contracts that follow the calendar. Better demand forecasts from past seasons also help outlets order the right stock.
Western Region leads while central region grows fastest
| Region | Value, 2025 (USD billion) | Share, 2025 | CAGR, 2026–2035 |
|---|---|---|---|
| Western Region | 2.55 | 32.0% | 7.10% |
| Central Region | 2.43 | 30.5% | 7.40% |
| Northern and Southern Regions | 1.73 | 21.7% | 6.40% |
| Eastern Region | 1.26 | 15.8% | 6.50% |
Why does the Western Region hold the largest share?
The Western Region held a 32.0% share of 2025 value and grows at 7.10% a year, because Makkah, Madinah and Jeddah serve pilgrims, tourists and large resident populations. Makkah received 43.1 million tourists in 2024, more than any other destination in the Kingdom. Alamar Foods also bought 29 Domino's branches in Makkah and Taif in 2025. As a result, the region leads demand for chicken, burgers and pizza across all channels.
How is the central region adding the fastest growth?
The Central Region held a 30.5% share of 2025 value and grows fastest at 7.40% a year, because Riyadh keeps adding offices, housing and entertainment venues. Riyadh hosted 20.5 million tourists in 2024 and recorded 130.4 million delivery orders, the most of any region. Kudu opened its first Australian sushi outlets in Riyadh from October 2025. In turn, new brands and fast-casual dining formats often launch in the capital first.
Why do the Northern and Southern Regions matter for reach?
The Northern and Southern Regions held a 21.7% share of 2025 value and grow at 6.40% a year, because Aseer, Tabuk, Jazan and Hail have growing towns and tourist sites. Aseer recorded 43.3 million delivery orders in 2024, which shows strong demand outside the largest cities. However, lower population density keeps outlet counts smaller than in the main cities. As a result, chains use drive-through pads and delivery to reach these markets.
How fast is the Eastern Region growing?
The Eastern Region held a 15.8% share of 2025 value and grows at 6.50% a year, because Dammam, Khobar and Jubail host oil, industrial and port workers with steady meal demand. The region recorded 12.3 million delivery orders in 2024, fewer than Riyadh, Makkah and Aseer. Shawarmer and other local brands have expanded into the province. In turn, dine-in and drive-through outlets dominate purchases across the region.
Deals, brand launches and rule changes since 2024
| Development | Status and market relevance |
|---|---|
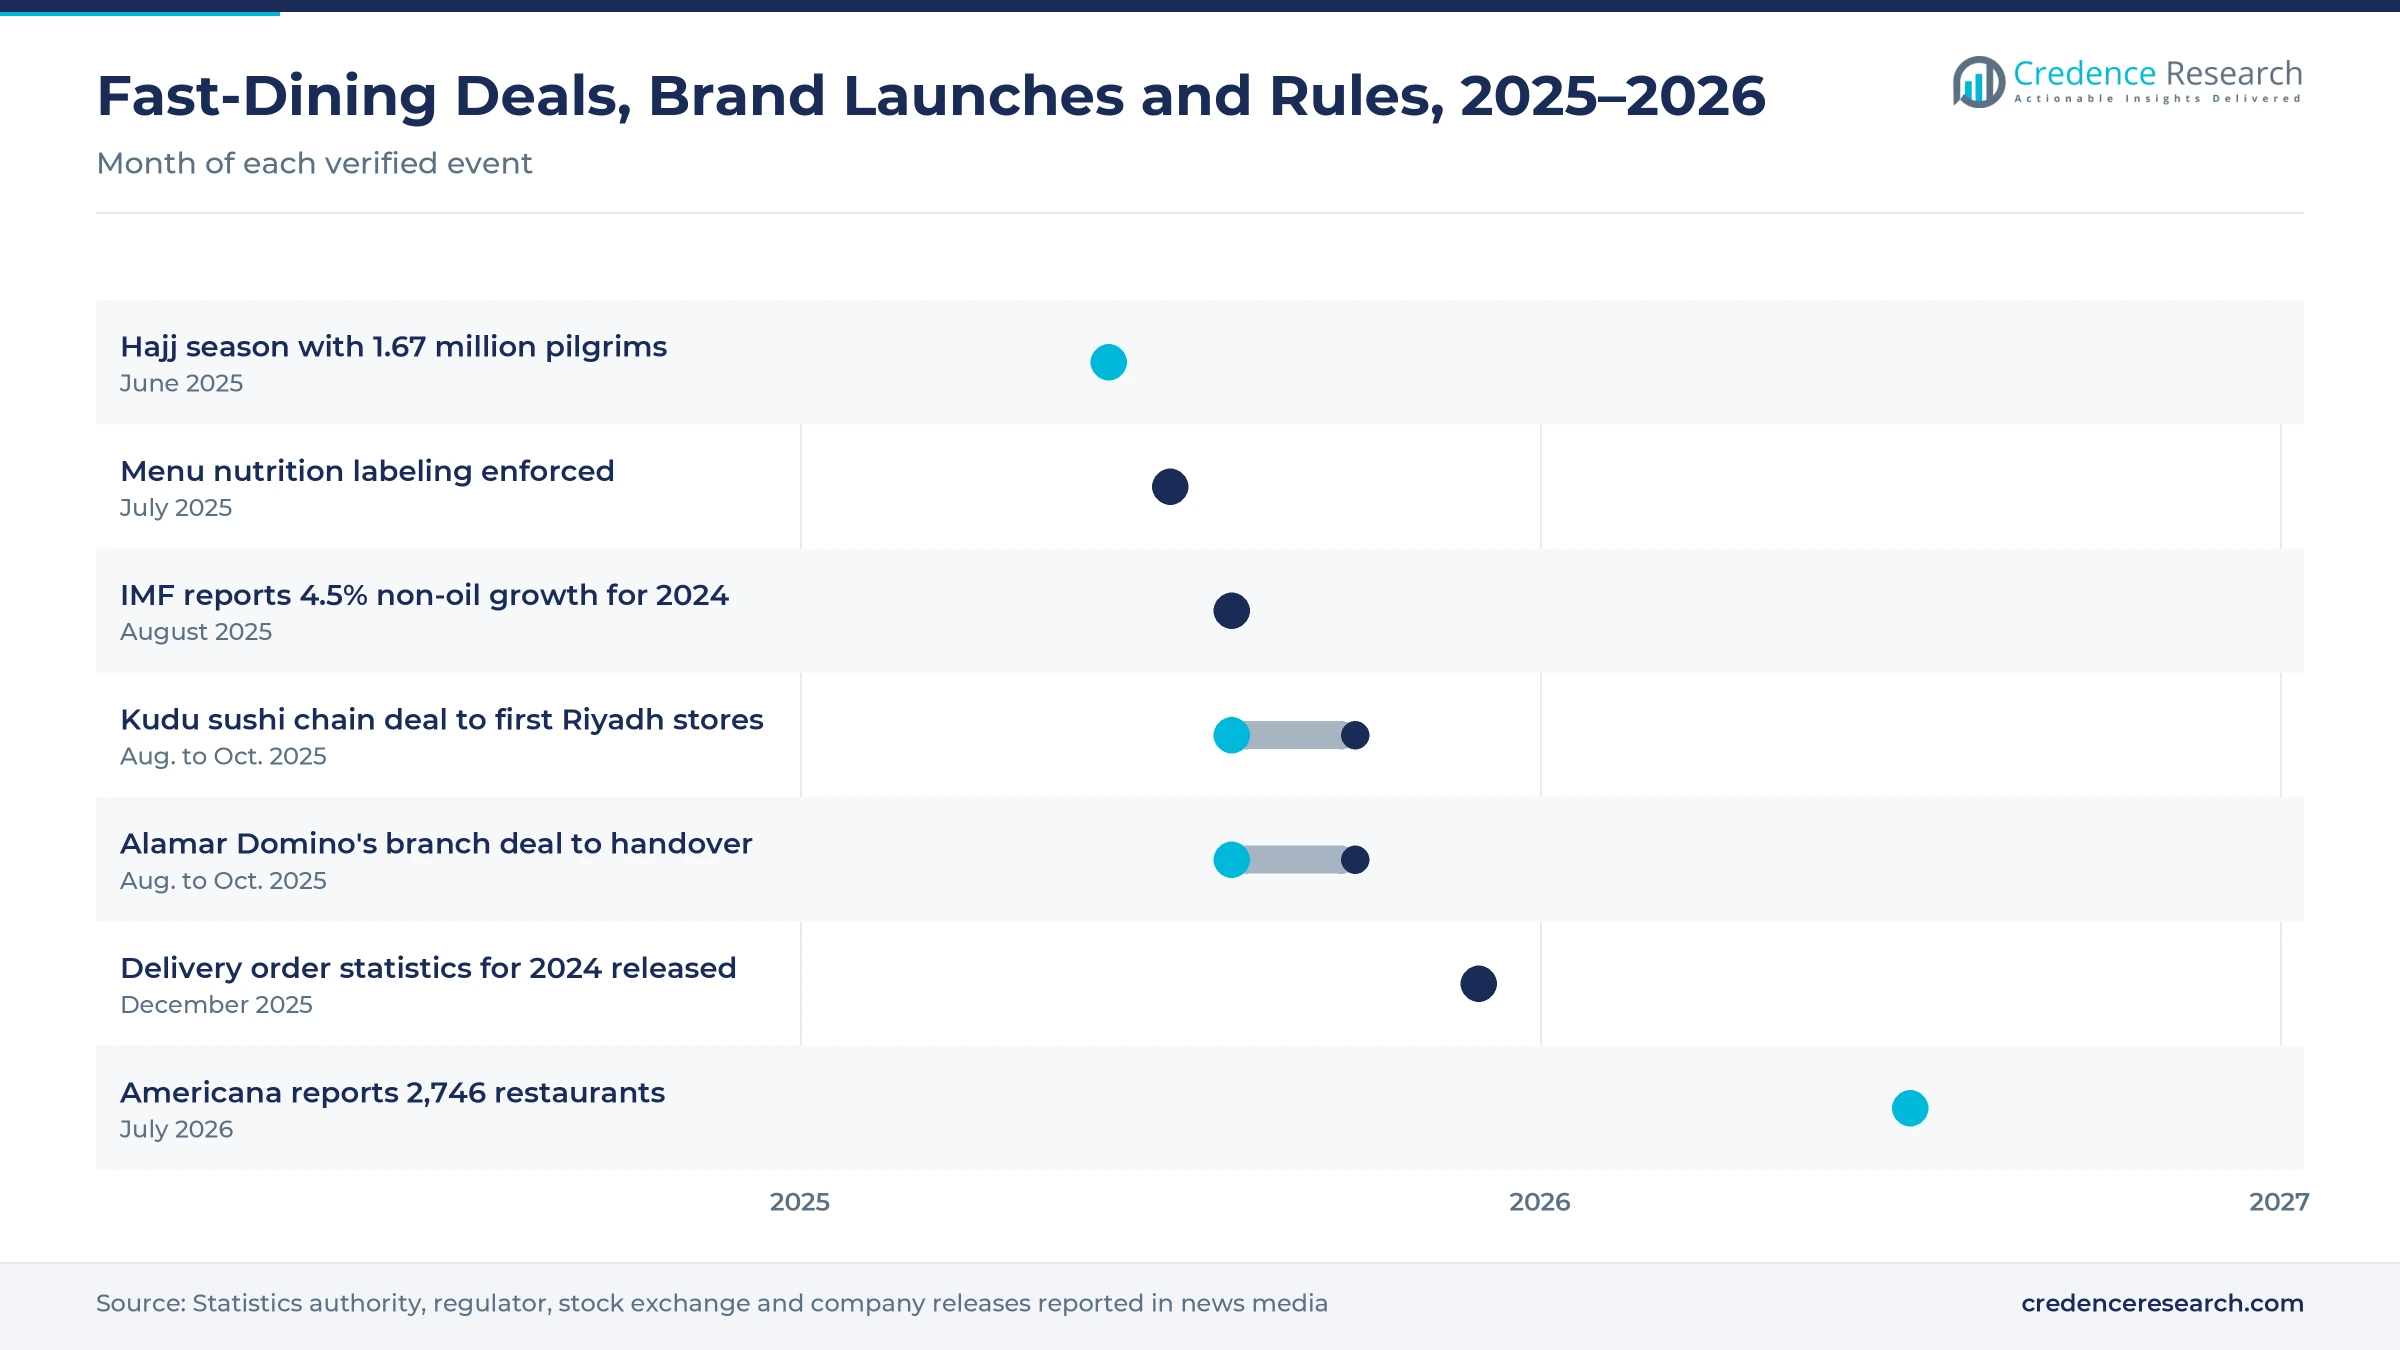
| In June 2025, the statistics authority reported that 1.67 million pilgrims performed Hajj, including 1.51 million from outside the Kingdom. | Confirms seasonal demand peaks in the Western Region |
| In July 2025, the Saudi Food and Drug Authority began enforcing menu nutrition labeling for food outlets and delivery platforms. | Pushes chains to relabel and reformulate menus |
| In August 2025, Kudu partnered with Sushi Sushi to open 40 stores across Saudi Arabia by 2035, starting in Riyadh. | Adds a new international brand to a local chain |
| In September 2025, Alamar Foods agreed to acquire 29 Domino's branches in Makkah and Taif for SAR 40 million. | Brings its Saudi Domino's network to 325 outlets |
| In July 2026, Americana Restaurants reported 2,746 restaurants as of June 30 and planned 120 to 130 more stores by year-end. | Signals continued outlet expansion |
Ordering apps, kiosks and kitchen systems speed service
- Delivery app integration sends app orders straight to kitchen screens, which cuts errors and keeps riders moving during peak hours.
- Self-ordering kiosks let diners browse menus with nutrition details and pay without queuing, which frees staff for food preparation.
- Kitchen display systems route each order to the right station and track cooking times, which keeps quality steady across outlets.
- Loyalty and payment apps store diner preferences and offer targeted deals, which lifts repeat visits and average order values.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Local and franchise chains compete on reach and speed
Competition is led by large homegrown chains and franchise operators that run many brands under one roof. Al Baik and Al Tazaj compete in fried and broasted chicken, while Kudu, Herfy and Burgerizzr compete in burgers and local meals. Americana Restaurants operates KFC and Pizza Hut and is dual-listed on the Saudi Exchange, while Alamar Foods runs Domino's and grew its network to 325 outlets in 2025. Shawarmer leads branded shawarma, and McDonald's and Subway compete through local franchise partners. Rivals compete on price, speed, outlet locations, delivery partnerships, loyalty apps and menu innovation. Because demand peaks around Ramadan, Eid and Hajj, chains with central kitchens, strong supply chains and outlets near holy sites and new districts usually win the most volume.
Which chains shape Saudi fast dining?
| Company | Type | Role in the market |
|---|---|---|
| Americana Restaurants | Multi-brand franchise operator | Runs KFC and Pizza Hut with 2,746 restaurants across its markets by June 2026 |
| Alamar Foods Company | Franchise operator | Runs 325 Domino's outlets in Saudi Arabia after a 2025 acquisition |
| Kudu Company for Food and Catering | Local chain | Partnered with an Australian sushi chain in 2025 to add 40 stores |
| Herfy Food Services Company | Local chain | Runs more than 380 restaurants and its own bakery and meat plants |
Credence Research view on fast dining in the Kingdom
Credence Research's view is that the Saudi fast-dining market will grow through more visitors, more delivery and new urban districts rather than through price increases alone. Fried and broasted chicken remains the largest value pool, while local shawarma formats, delivery and cloud kitchens add the fastest growth. Menu labeling rules and Saudization targets will raise standards and costs. Operators with central kitchens, strong apps and outlets near holy sites and new districts should gain the most, while rents and staffing costs keep pressure on margins.
How the national fast-dining estimate was built
The report uses 2025 as the base year on a calendar basis, and market values come from the Credence Research model. That model combines tourism and pilgrim statistics, delivery order data, census results, economic growth data and company releases. Regional shares follow the client zone definitions, while segment splits and growth rates are Credence Research estimates. Sources used are official statistics, regulator and International Monetary Fund releases, stock exchange filings and company releases reported in news media, and no interviews or surveys were used.
Visitors, delivery and new districts carry growth to 2035
The Saudi Arabia quick service restaurants market is expected to reach USD 15.64 billion by 2035, a 6.95% CAGR during 2026–2035, as visitors, delivery and new districts keep demand rising. Growth should be strongest in local shawarma formats, delivery and aggregators, cloud kitchens and the Central Region, because these areas gain most from Riyadh expansion and app ordering. Tourism and pilgrimage will keep the Western Region in the lead, while rents, staffing rules and price-sensitive diners could slow some operators.
Frequently Asked Questions
How big is the Saudi Arabia quick service restaurants market?
Which cuisine type leads Saudi fast dining?
Which region leads the Saudi market?
How large is food delivery in Saudi Arabia?
How do tourism and pilgrimage support fast dining?
What menu rules apply to fast-dining outlets?
Who are the leading companies in the Saudi market?
What are the main challenges for fast-dining chains in Saudi Arabia?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Cuisine Type
- 1.2.1 Fried and Broasted Chicken
- 1.2.2 Burgers
- 1.2.3 Pizza and Italian QSR
- 1.2.4 Shawarma and Local QSR
- 1.3 By Customer Type
- 1.3.1 Saudi Nationals
- 1.3.2 Resident Expatriates
- 1.3.3 Leisure Tourists
- 1.3.4 Religious Visitors
- 1.4 By Service Model
- 1.4.1 Company-Owned Outlets
- 1.4.2 Single-Country Franchise
- 1.4.3 Multi-Brand Franchise Groups
- 1.4.4 Cloud and Satellite Kitchens
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2025: USD 7.96 billion → 2035: USD 15.64 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Historical Period: 2018-2025
- 2.6.2 Base Year: 2025
- 2.6.3 Forecast Period: 2025-2035
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2025
- 3.3 Forecast Market Size, 2035
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Saudi Arabia Quick Service Restaurants Market Trends and Developments
- 4.1 Historical Industry Development, 2018-2025
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Saudi Arabia Quick Service Restaurants Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis, 2018-2025
- 5.2 Demand Forecast, 2025-2035
- 5.3 Production and Output Trend, 2018-2025
- 5.4 Production and Output Forecast, 2025-2035
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Saudi Arabia Quick Service Restaurants Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends, 2018-2025
- 6.3 Pricing Outlook, 2025-2035
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Saudi Arabia Quick Service Restaurants Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Saudi Arabia Quick Service Restaurants Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Saudi Arabia Quick Service Restaurants Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Saudi Arabia Quick Service Restaurants Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Saudi Arabia Quick Service Restaurants Market Outlook, 2025-2035
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2025: USD 7.96 billion → 2035: USD 15.64 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size, 2018-2025
- 11.1.4 Base-Year Market Size, 2025
- 11.2 Market Forecast, 2025-2035
- 11.2.1 Revenue Forecast to 2035
- 11.2.2 Volume Forecast to 2035
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Saudi Arabia Quick Service Restaurants Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2025
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Cuisine Type - Market Size and Forecast, 2025-2035
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size, 2018-2025
- 12.3.3 Revenue Forecast, 2025-2035
- 12.3.4 Volume Forecast, 2025-2035
- 12.3.5 Base-Year Market Share, 2025
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Fried and Broasted Chicken
- 12.3.7.2 Burgers
- 12.3.7.3 Pizza and Italian QSR
- 12.3.7.4 Shawarma and Local QSR
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Customer Type - Market Size and Forecast, 2025-2035
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size, 2018-2025
- 12.4.3 Revenue Forecast, 2025-2035
- 12.4.4 Volume Forecast, 2025-2035
- 12.4.5 Base-Year Market Share, 2025
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Saudi Nationals
- 12.4.7.2 Resident Expatriates
- 12.4.7.3 Leisure Tourists
- 12.4.7.4 Religious Visitors
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Service Model - Market Size and Forecast, 2025-2035
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size, 2018-2025
- 12.5.3 Revenue Forecast, 2025-2035
- 12.5.4 Volume Forecast, 2025-2035
- 12.5.5 Base-Year Market Share, 2025
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Company-Owned Outlets
- 12.5.7.2 Single-Country Franchise
- 12.5.7.3 Multi-Brand Franchise Groups
- 12.5.7.4 Cloud and Satellite Kitchens
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Saudi Arabia Quick Service Restaurants End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Saudi Arabia Quick Service Restaurants Geographic Market Outlook, 2025-2035
- 14.1 Domestic Market Distribution and Demand Clusters
- 14.2 State- or Province-Wise Market Size and Forecast, 2025-2035
- 14.3 City and Metropolitan Market Outlook
- 14.4 Industrial, Manufacturing and Commercial Clusters
- 14.5 Geographic Concentration of Key End Users
- 14.6 Local Pricing and Purchasing Differences
- 14.7 Domestic Production Facilities and Capacity Map
- 14.8 Local Infrastructure and Project Pipeline
- 14.9 State-Level Policy and Incentive Differences
- 14.10 Subnational Investment Hotspots and Opportunities
- 14.11 Distribution and Logistics Networks
- 14.12 Domestic Competitive Footprint
Chapter 15 Saudi Arabia Quick Service Restaurants Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2025-2035
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Saudi Arabia Quick Service Restaurants Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2025
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2025-2035
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Al Baik Food Systems Company
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 McDonald's Saudi Arabia Franchise System
- 18.4 Americana Restaurants
- 18.5 Kudu Company for Food and Catering
- 18.6 Herfy Food Services Company
- 18.7 Shawarmer Food Company
- 18.8 Alamar Foods Company
- 18.9 Al Tazaj Fakieh
- 18.10 Burgerizzr
- 18.11 Subway Saudi Arabia
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

