
Market Overview
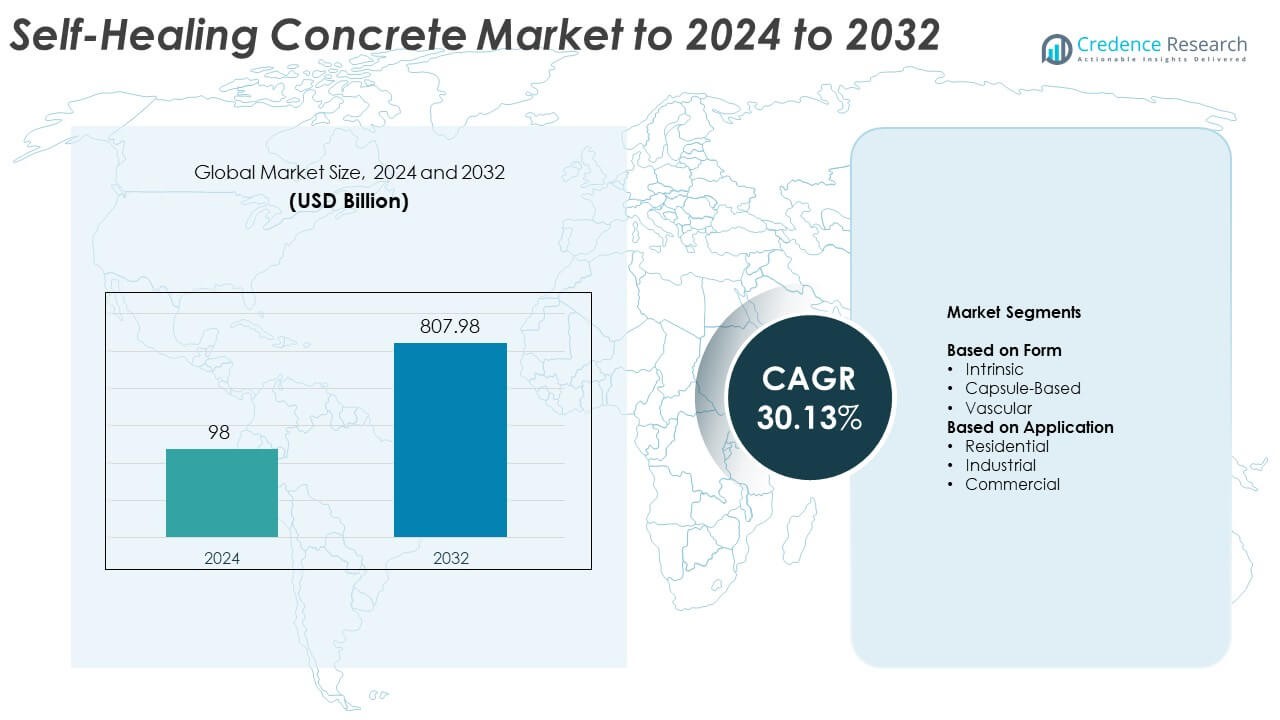
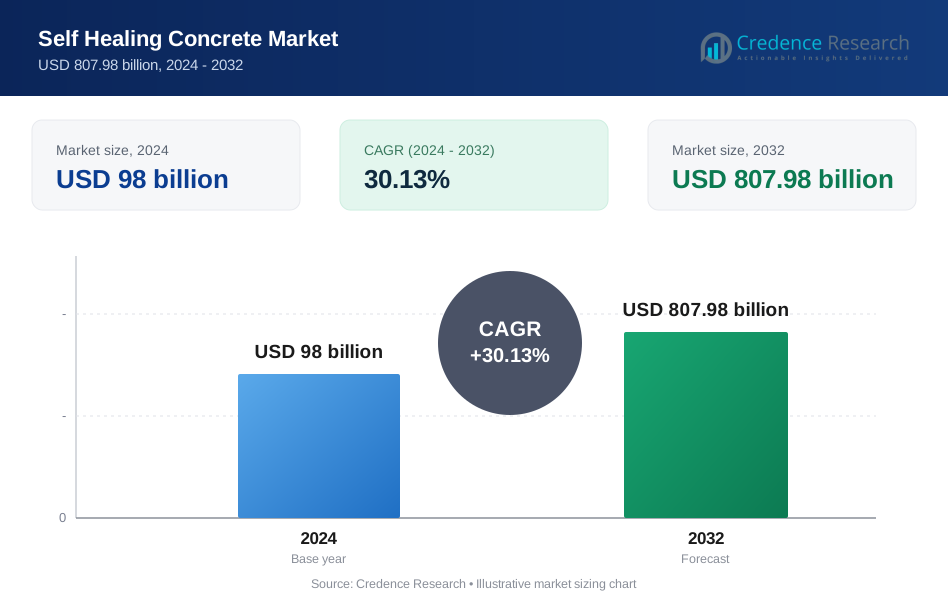
Self-Healing Concrete Market size was valued at USD 98 billion in 2024 and is anticipated to reach USD 807.98 billion by 2032, at a CAGR of 30.13% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Self-Healing Concrete Market Size 2024 | USD 98 Billion |
| Self-Healing Concrete Market, CAGR | 30.13% |
| Self-Healing Concrete Market Size 2032 | USD 807.98 Billion |
The self-healing concrete market is led by major companies such as Sika AG, BASF SE, CEMEX S.A.B. de C.V., RPM International Inc., Kryton International Inc., and GCP Applied Technologies Inc. These companies dominate through innovations in bacterial-based healing agents, mineral composites, and eco-friendly formulations that enhance concrete durability and reduce maintenance needs. North America leads the market with a 33.2% share in 2024, driven by extensive infrastructure renovation and sustainability-focused construction policies. Europe follows with a 28.5% share, supported by strong regulatory frameworks and early adoption of advanced construction materials.
Market Insights
- The global self-healing concrete market was valued at USD 98 billion in 2024 and is projected to reach USD 807.98 billion by 2032, expanding at a CAGR of 30.13%.
- Growing infrastructure modernization and rising focus on sustainable construction materials are key drivers enhancing adoption across commercial and residential projects.
- Increasing use of bacterial and mineral-based healing agents, along with integration of IoT monitoring, represents major technological trends.
- The market remains competitive, with leading players investing in R&D, production scalability, and partnerships to improve performance and cost efficiency.
- North America leads with 33.2% share, followed by Europe at 28.5% and Asia Pacific at 24.6%, supported by strong regulatory frameworks and expanding smart city developments.
Market Segmentation Analysis:
By Form
Intrinsic self-healing concrete dominates the market with around 52.4% share in 2024. This segment leads due to its ability to autonomously repair cracks through embedded healing agents such as bacteria and mineral precursors. The technology minimizes maintenance costs and extends infrastructure life, making it ideal for bridges, tunnels, and high-rise structures. Rising demand for durable and sustainable construction materials is driving the adoption of intrinsic formulations. Capsule-based and vascular systems are also gaining momentum as they offer controlled healing and easy scalability for large structural projects.
- For instance, Green-Basilisk BV documented a 36% reduction in shrinkage reinforcement in the Hulstkamp parking garage after using its bacteria-based self-healing agent.
By Application
Commercial construction holds the dominant share of about 46.7% in 2024, driven by the growing focus on sustainable and long-lasting materials for large-scale infrastructure. Self-healing concrete enhances structural integrity and reduces lifecycle costs, which is vital for commercial complexes, airports, and public facilities. The residential sector follows closely, supported by urban housing expansion and smart city initiatives. Industrial applications are also increasing as manufacturers integrate self-healing materials to prevent downtime and reduce repair frequency in factory floors and heavy-use infrastructure.
- For instance, Sika specifies its crystalline admixture can seal cracks up to 0.5 mm, a performance level used in commercial basements, tunnels, and parking decks.
Key Growth Drivers
Rising Infrastructure Modernization Projects
Expanding global infrastructure investments are fueling demand for self-healing concrete in highways, bridges, and tunnels. Governments are prioritizing durable materials to minimize maintenance and improve resilience against environmental stress. The material’s ability to autonomously repair micro-cracks enhances structural lifespan and reduces long-term repair costs, making it attractive for large-scale projects. Increased public spending in Asia-Pacific and Europe is significantly boosting adoption, supporting long-term market expansion and sustainability-focused construction standards.
- For instance, Premier Magnesia's magnesia-based admixture, PREVent-C, has been shown in published reports and industry trials to reduce shrinkage cracking by as much as 90 % when used in concrete at a 5 % addition rate.
Growing Focus on Sustainable Construction Materials
The global shift toward eco-friendly building solutions is accelerating the adoption of self-healing concrete. The material’s self-repairing property reduces waste, conserves resources, and aligns with green construction regulations. Builders and developers are adopting it to achieve lower carbon footprints and improved LEED certifications. With rising pressure from environmental policies and consumer preference for sustainable infrastructure, manufacturers are increasing production capacity for bio-based and mineral-induced self-healing systems.
- For instance, Xypex specifies its crystalline technology can seal static hairline cracks up to 0.5 mm in width in many of its product data sheets, a performance level that improves durability and reduces long-term repair materials in various concrete applications.
Advancements in Material Science and Biotechnology
Rapid innovation in material engineering and biotechnology has improved the efficiency of healing mechanisms in concrete. Integration of bacterial spores, encapsulated healing agents, and vascular networks allows faster crack closure and strength recovery. These advancements enhance product performance in both dry and humid environments, extending application scope across industrial and residential sectors. Continuous R&D investments by construction technology firms are making self-healing concrete more reliable, cost-effective, and suitable for large-scale deployment.
Key Trends & Opportunities
Integration of Smart Sensing and Monitoring Systems
The integration of IoT and sensor technologies is creating opportunities for predictive maintenance in self-healing structures. Embedded sensors detect structural stress and trigger healing agents before significant damage occurs. These smart materials support real-time monitoring, reducing downtime and enhancing building safety. The growing adoption of smart infrastructure and digital construction platforms will expand the role of sensor-enabled self-healing concrete in future infrastructure systems.
- For instance, Giatec Scientific lists SmartRock sensor accuracy at ±1 °C, with readings every 15 minutes and real-time strength via ASTM C1074 maturity.
Expansion in Smart City and Green Infrastructure Projects
Urbanization and smart city initiatives are promoting the use of advanced materials like self-healing concrete. Governments and developers are incorporating the technology in roads, bridges, and water systems to enhance durability and reduce emissions. The material’s self-repairing nature supports the long-term sustainability goals of smart cities. This trend is opening new opportunities for public-private partnerships and driving large-scale adoption in regions emphasizing environmental efficiency.
- For instance, BAM Infra reported a minimum 15-year design-life extension on a concrete bus lane after applying a self-healing repair treatment.
Key Challenges
High Production and Implementation Costs
The high cost of production and specialized installation limits large-scale adoption of self-healing concrete. Manufacturing requires advanced materials such as microcapsules or bacterial cultures, which increase overall project expenses. Additionally, skilled labor and specialized techniques add to construction costs. These economic barriers make it challenging for small and mid-scale projects to adopt the technology, especially in cost-sensitive markets.
Limited Awareness and Standardization Issues
Lack of awareness among builders and limited global standards for performance evaluation hinder market expansion. Many construction companies remain unfamiliar with the long-term benefits and application methods of self-healing materials. Absence of regulatory benchmarks for durability and testing slows down certification and project approvals. Establishing international standards and training programs is crucial to promote widespread adoption and ensure quality consistency.
Regional Analysis
North America
North America holds around 33.2% share of the self-healing concrete market in 2024. The region’s growth is driven by strong infrastructure investments and increasing adoption of sustainable construction materials. The United States leads due to extensive highway and bridge renovation projects that emphasize durability and reduced maintenance. Canada follows with rising usage in smart building initiatives and green-certified structures. Government focus on lowering lifecycle costs and carbon emissions supports broader adoption of advanced self-healing technologies across commercial and public infrastructure projects.
Europe
Europe accounts for nearly 28.5% share of the global market, supported by stringent environmental regulations and advanced construction practices. Countries such as the Netherlands, the United Kingdom, and Germany are early adopters of self-healing technologies in roads, tunnels, and heritage restoration. The European Union’s sustainability policies encourage use of materials that minimize repair frequency and resource waste. Expanding investments in research programs related to bio-based and mineral healing agents further strengthen market growth and position Europe as a leader in innovation-driven construction materials.
Asia Pacific
Asia Pacific captures about 24.6% share of the self-healing concrete market, emerging as one of the fastest-growing regions. Rapid urbanization, industrialization, and government-led infrastructure development in China, India, and Japan are key growth factors. Large-scale construction of transport networks, commercial complexes, and residential projects boosts product demand. Increasing focus on cost-effective, long-lasting materials supports regional expansion. The rise of public-private partnerships and foreign investments in sustainable construction projects further drives the adoption of self-healing technologies across the region.
Latin America
Latin America holds approximately 8.1% share in 2024, supported by steady growth in infrastructure modernization. Brazil and Mexico are leading markets, driven by investments in smart urban development and transport infrastructure. Construction companies are increasingly adopting sustainable materials to extend the lifespan of structures exposed to humidity and temperature variation. Government initiatives promoting green building standards and partnerships with international research institutes are gradually enhancing awareness and adoption of self-healing concrete solutions across commercial and residential segments.
Middle East & Africa
The Middle East and Africa region represents around 5.6% share of the self-healing concrete market. Growth is supported by expanding construction in the United Arab Emirates, Saudi Arabia, and South Africa, where governments focus on resilient and sustainable infrastructure. Increasing use of advanced materials in megaprojects such as smart cities, airports, and industrial zones enhances market potential. The region’s arid climate and large-scale structural projects create strong demand for durable materials capable of minimizing repair costs and improving long-term structural performance.
Market Segmentations:
By Form
- Intrinsic
- Capsule-Based
- Vascular
By Application
- Residential
- Industrial
- Commercial
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the self-healing concrete market is defined by established construction chemical manufacturers and specialized innovation-driven startups such as Sika AG, CEMEX S.A.B. de C.V., BASF SE, RPM International Inc., Kryton International Inc., Basilisk, Penetron, GCP Applied Technologies Inc., Oscrete (Christeyns UK Ltd.), and Hycrete Inc. (Broadview Technologies Inc.). Market players focus on material innovation, bacterial-based healing systems, and advanced mineral composites to improve efficiency and reduce lifecycle costs. Strategic partnerships with infrastructure developers and research institutes are strengthening their global presence. Companies are emphasizing scalable production methods and eco-friendly formulations to meet sustainable construction goals. Continuous R&D investments, regional expansion, and technological integration in smart infrastructure projects are further intensifying competition and shaping long-term market dynamics.
Key Player Analysis
- Sika AG
- CEMEX S.A.B. de C.V.
- BASF SE
- RPM International Inc.
- Kryton International Inc.
- Basilisk
- Penetron
- GCP Applied Technologies Inc.
- Oscrete (Christeyns UK Ltd.)
- Hycrete Inc. (Broadview Technologies Inc.)
Recent Developments
- In 2025, BASF SE developed and announced a novel bacterial-based self-healing concrete additive.
- In 2024, GCP Applied Technologies and Saint-Gobain's Chryso (operating together as Saint-Gobain Construction Chemicals) introduced the EnviroMix® Impact App.
- In 2023, Hycrete Inc. launched Hycrete Endure Cure, a water-based concrete curing agent designed to improve concrete durability.
Report Coverage
The research report offers an in-depth analysis based on Form, Application and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Increasing adoption of sustainable construction materials will drive large-scale use of self-healing concrete.
- Integration of AI and IoT in monitoring systems will enhance automated maintenance and durability.
- Rising infrastructure modernization projects will expand application across highways, tunnels, and bridges.
- Development of cost-efficient bacterial and mineral-based healing systems will make products more affordable.
- Growing smart city initiatives will accelerate deployment in commercial and residential construction.
- Collaboration between research institutes and manufacturers will boost material innovation and standardization.
- Expansion in 3D printing construction will open new opportunities for adaptive self-healing designs.
- Government policies promoting green and low-carbon materials will strengthen market penetration.
- Increasing investment in long-lasting infrastructure in emerging economies will support regional growth.
- Enhanced awareness and training among builders and engineers will drive wider market acceptance.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Self-Healing Concrete Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Self-Healing Concrete Market projected to grow between 2025 and 2032?
Which Self-Healing Concrete Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Self-Healing Concrete Market?
Who are the leading companies in the Self-Healing Concrete Market?
Which region commanded the largest share of the Self-Healing Concrete Market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Self Healing Concrete Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Self Healing Concrete Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 98 billion → 2032: USD 807.98 billion)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Self Healing Concrete Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Self Healing Concrete Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Self Healing Concrete Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Self Healing Concrete Market Drivers
- 3.3 Self Healing Concrete Market Restraints & Challenges
- 3.4 Self Healing Concrete Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Self Healing Concrete Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Self Healing Concrete Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Self Healing Concrete category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Self Healing Concrete Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Self Healing Concrete Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Self Healing Concrete market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Self Healing Concrete Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Self Healing Concrete Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Self Healing Concrete Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Self Healing Concrete (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Self Healing Concrete Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Self Healing Concrete Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Self Healing Concrete Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Self Healing Concrete Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Self Healing Concrete Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Self Healing Concrete Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Self Healing Concrete Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Self Healing Concrete Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Self Healing Concrete Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
