
Homes, offices and plants add value as China contracts
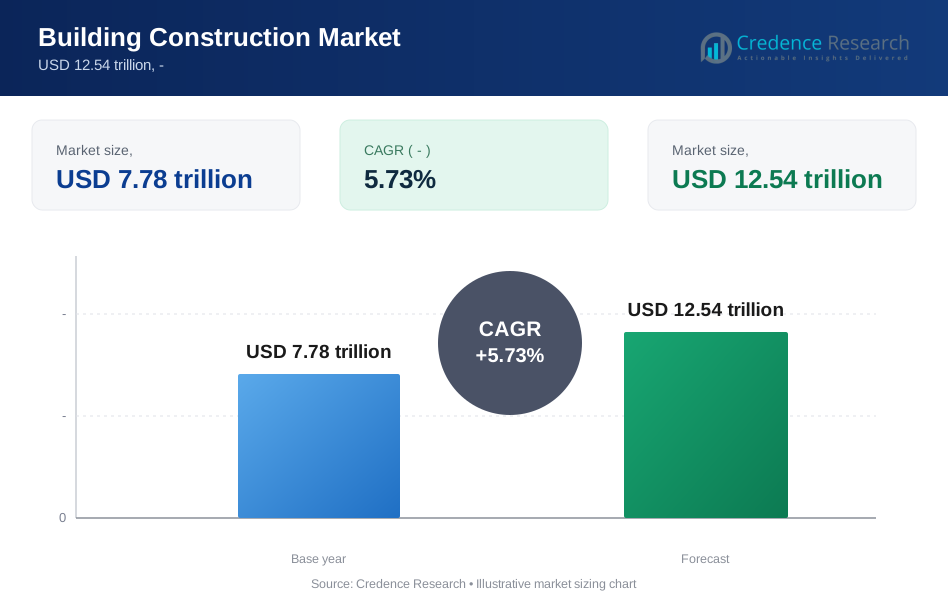
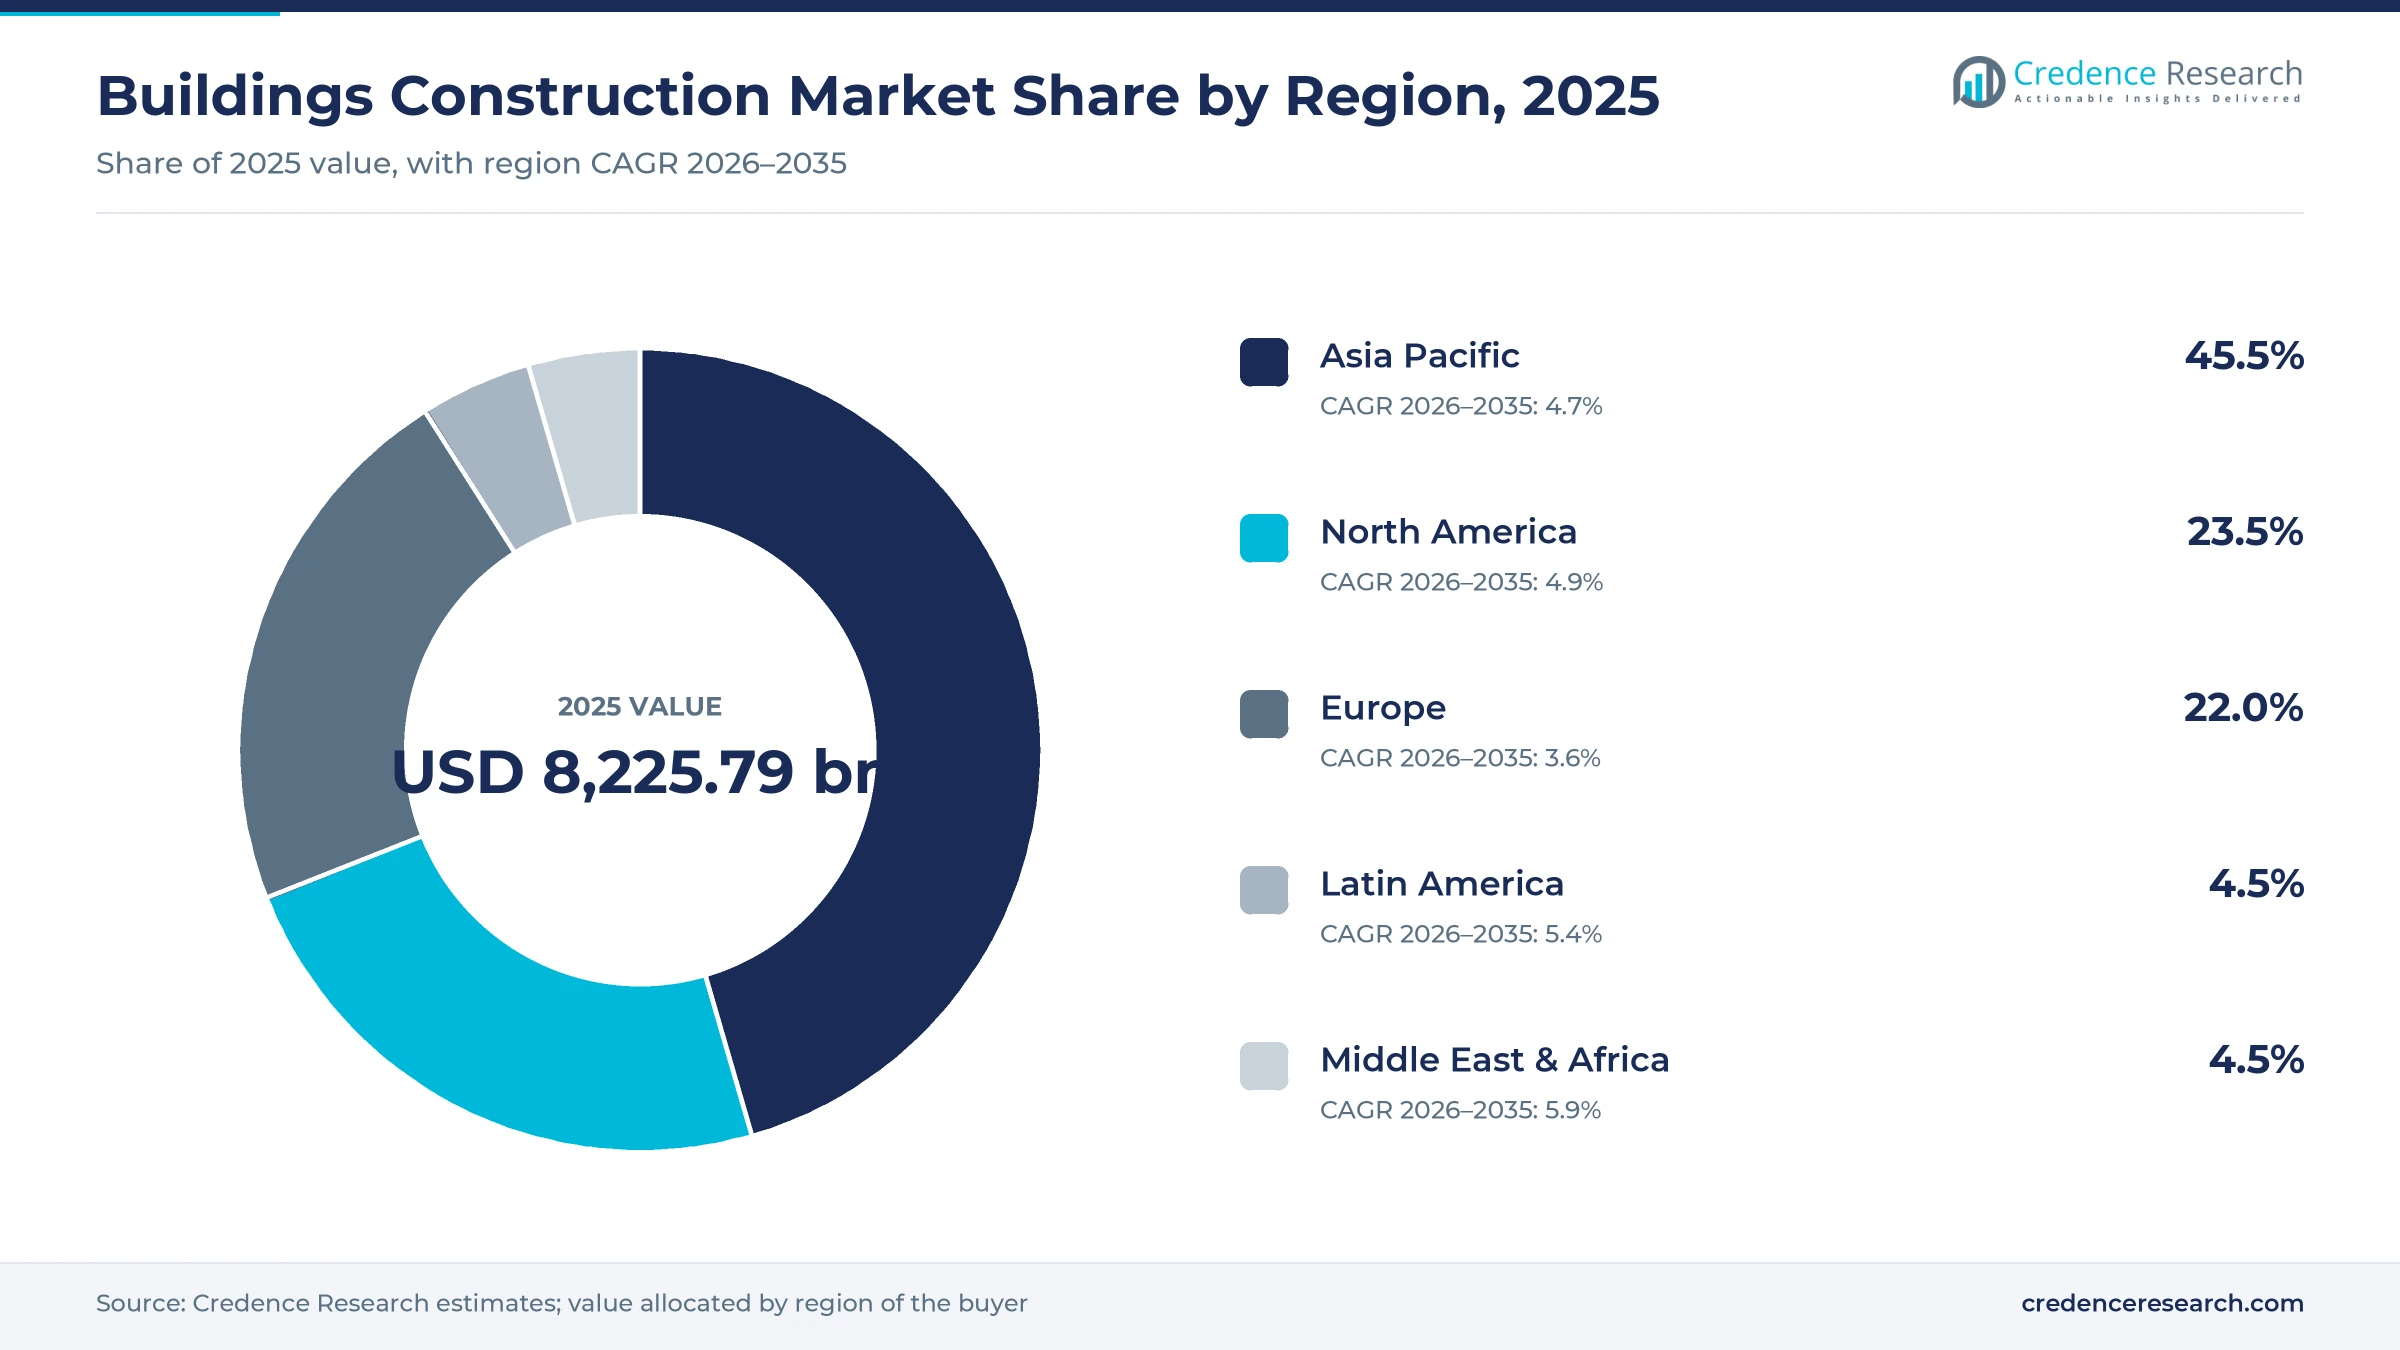
The global buildings construction market was valued at USD 8,225.79 billion in 2025 and is projected to increase from USD 8,604.18 billion in 2026 to USD 12,897.18 billion by 2035, registering a CAGR of 4.60% during 2026–2035. Value is the work put in place on residential, commercial, industrial and institutional buildings, both new projects and the renovation and repair of existing stock, paid for by households, developers, companies and public owners. Asia Pacific held the largest regional share, 45.5% in 2025, because China and India still build more floor space than any other countries, even as Chinese developer activity shrinks. Middle East & Africa is the fastest-growing region at 5.9% a year, led by Gulf public programs and housing shortfalls in Egypt and Nigeria. The most important commercial change is the shift in what gets built, as data halls, energy retrofits and subsidized housing replace speculative apartment towers as the main source of new contracts for large builders.
Work put in place on buildings, not land or property sales
The market counts the value of construction work on buildings, which covers labor, materials, equipment and contractor margin on new homes, apartment blocks, offices, shops, warehouses, factories, data centers, schools and hospitals. It also counts renovation, refurbishment and planned repair, because owners in mature economies now spend a large part of their building budgets on existing stock. Buyers range from single households hiring a local builder to sovereign funds tendering multi-billion-dollar programs.
Land purchases, property sales commissions, roads, bridges, rail, power plants and water networks are excluded, so the figures sit below total construction output. The value chain runs from owners and developers through designers and general contractors to specialist trades and materials suppliers, and margin depends on how much risk each party carries under its contract.
Buildings Construction Market Insights
- The global buildings construction market was valued at USD 8,225.79 billion in 2025 and reaches USD 12,897.18 billion by 2035 at a 4.60% CAGR.
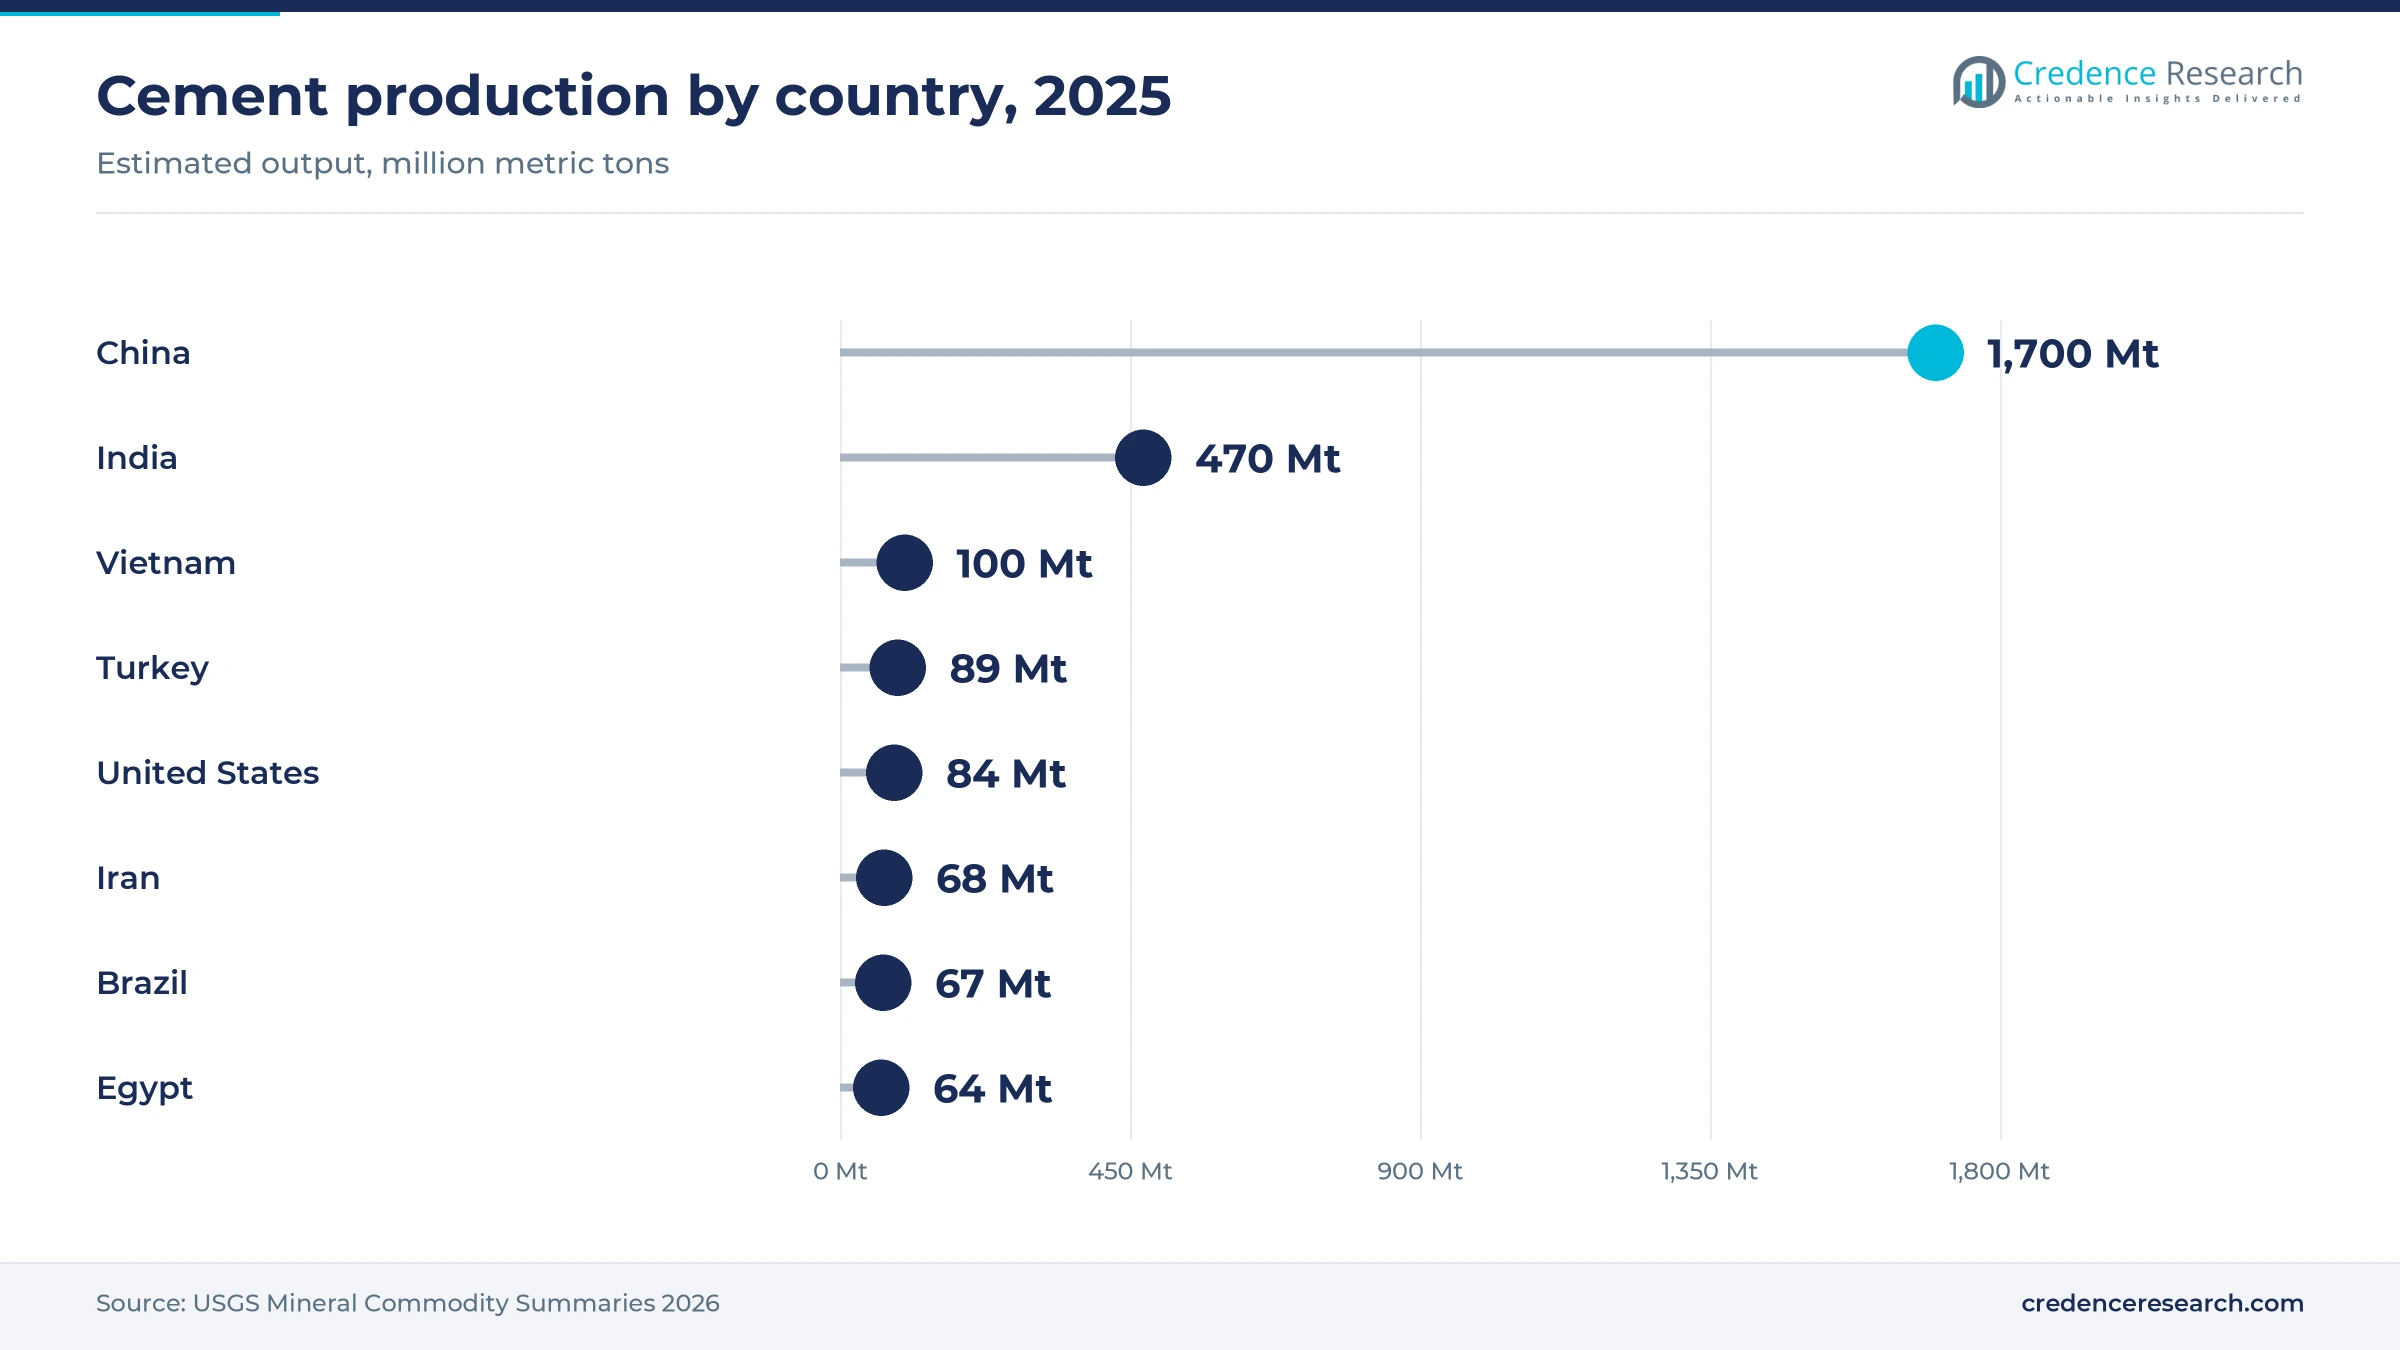
- Asia Pacific held 45.5% of 2025 value, because China and India produced more than half of the world's cement in 2025, according to the USGS.
- Residential work held 50.0% of 2025 value, as U.S. homebuilders still completed nearly 1.5 million housing units in 2025.
- China's real estate development investment fell 17.2% in 2025, according to the National Bureau of Statistics, the largest drag on new building volume.
- Data center work is the fastest new source of commercial contracts, with U.S. data center building spending at a USD 45 billion annual rate in December 2025.
Residential leads while commercial work grows fastest
New projects lead while renovation work grows fastest
Based on construction type, the market is categorized into new construction, renovation and refurbishment, and repair and maintenance. New Construction led with 56.0% of 2025 value because growing cities still add floor space faster than old stock is replaced, and U.S. builders completed 1,497,800 housing units in 2025, according to the Census Bureau. Renovation & Refurbishment grows fastest at 5.4% as EU member states had to transpose the recast energy performance directive by May 29, 2026, which turns energy upgrades into legal deadlines for owners of poorly rated buildings. Planned repair is steadier, since it follows the age of the stock.
Homes hold half of value while commercial work adds fastest
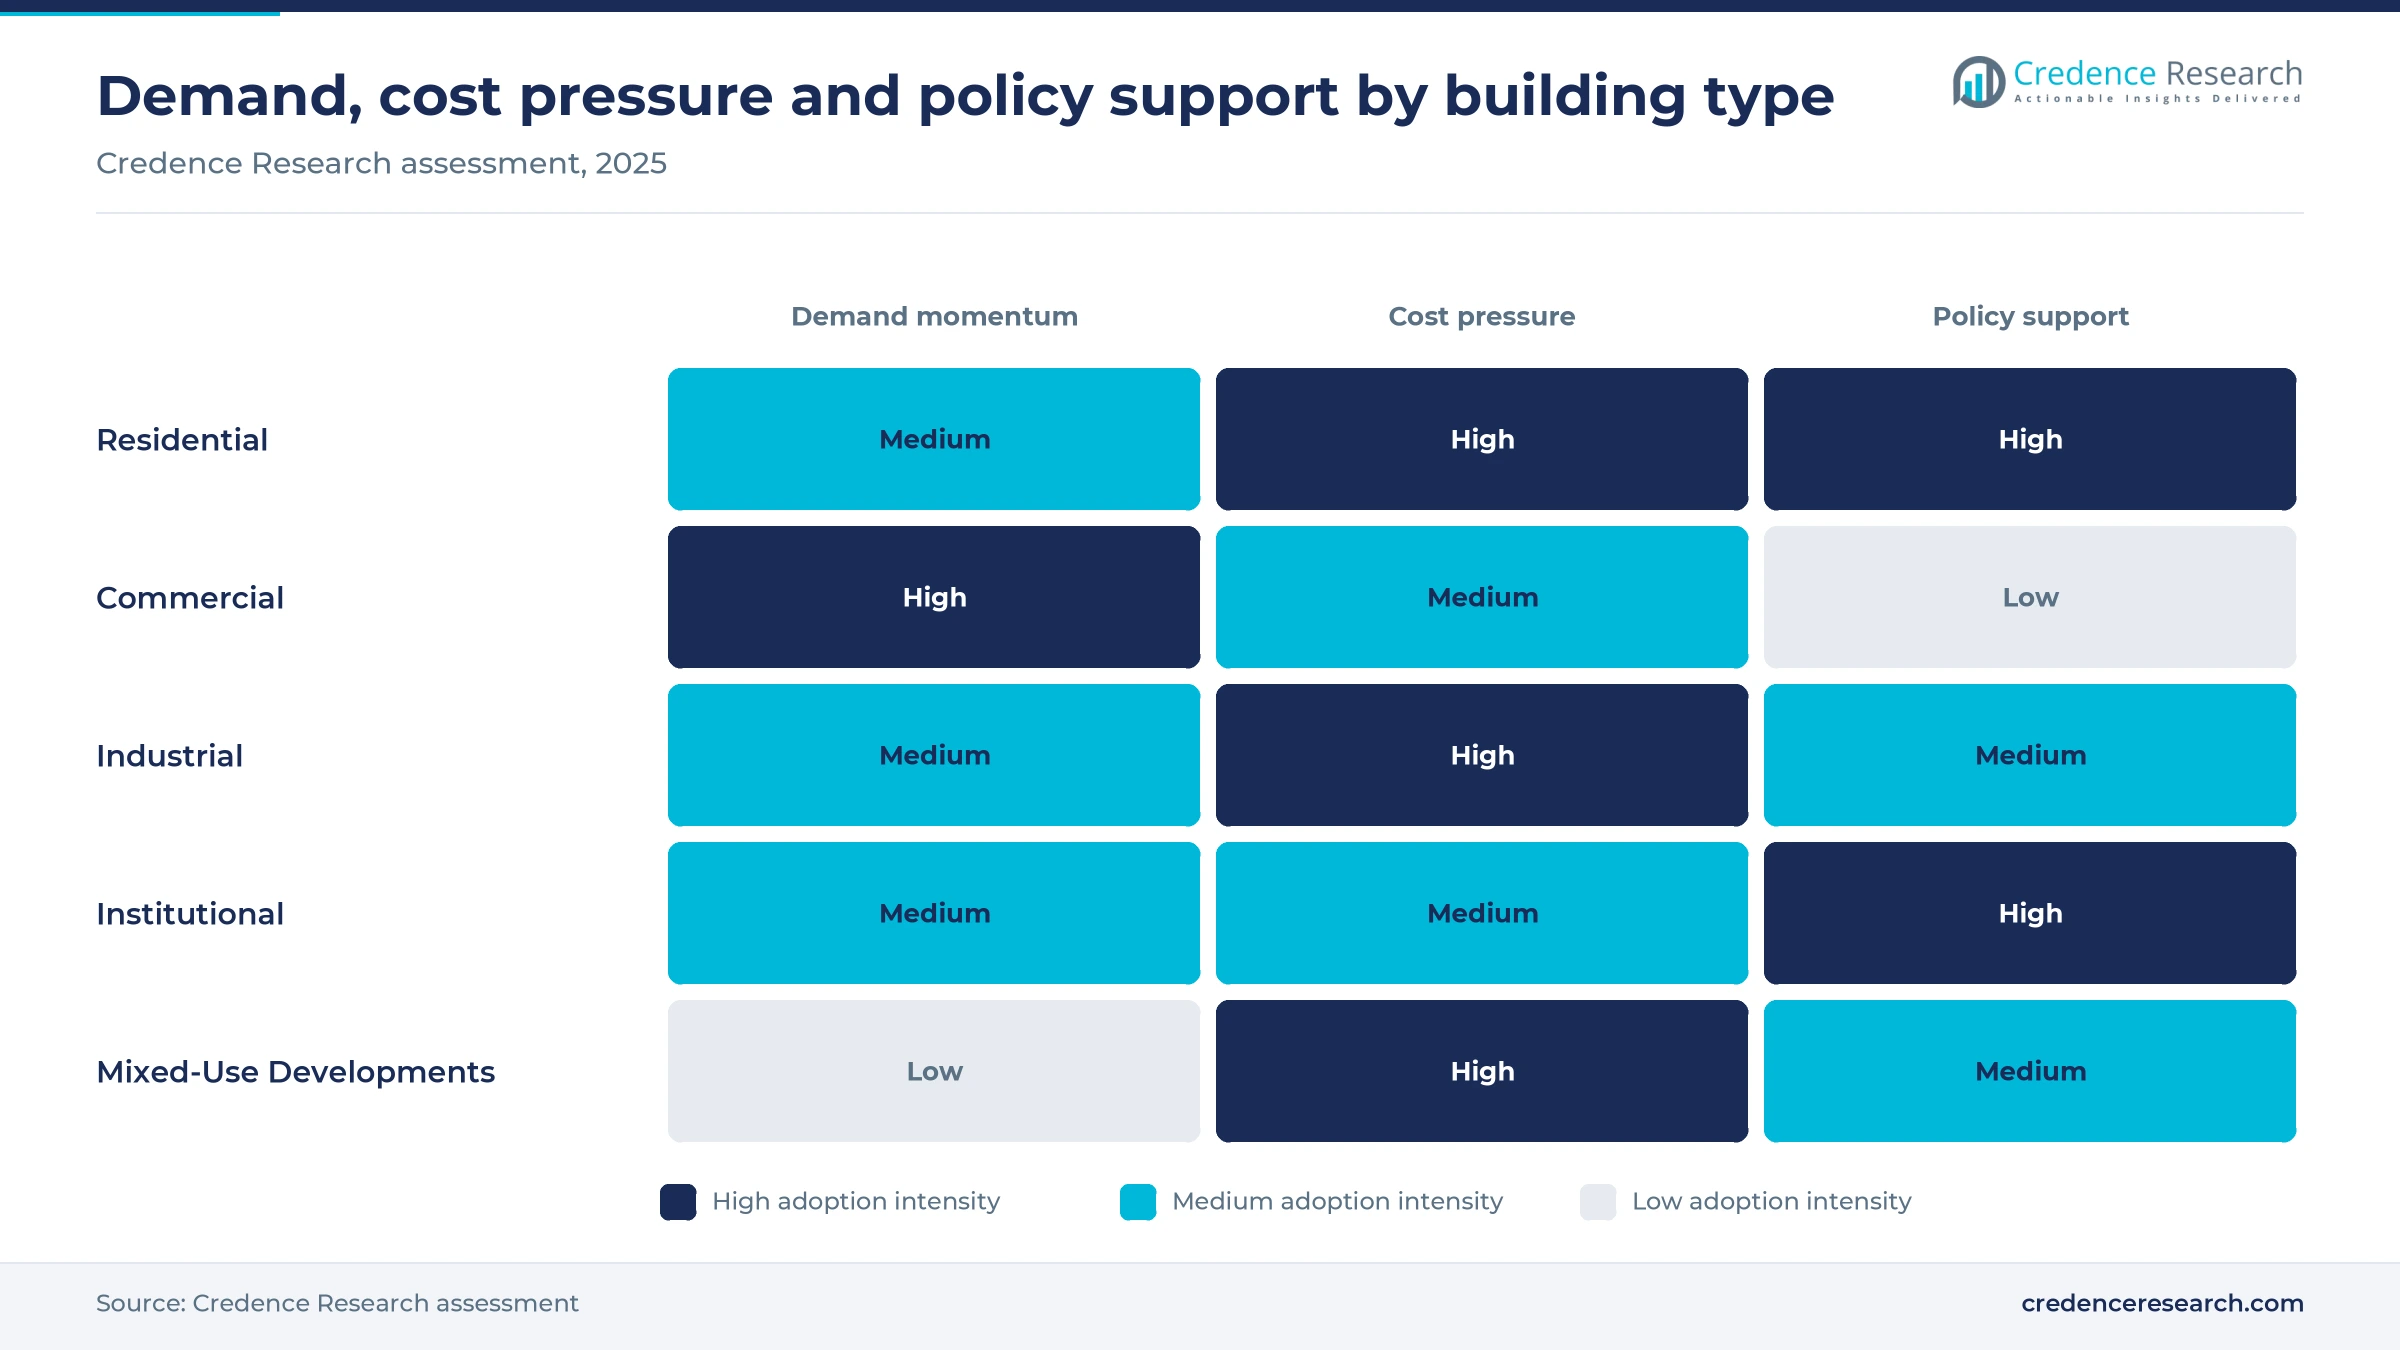
Based on building type, the market is categorized into residential, commercial, industrial, institutional and mixed-use developments. Residential led with 50.0% of 2025 value because housing is the largest building budget in every major economy, and U.S. residential construction alone reached USD 917.4 billion in 2025, more than half of U.S. building spending. Commercial grows fastest at 5.6% as data centers move into the commercial pipeline, and in October 2025 Obayashi said its U.S. unit Webcor had agreed to acquire GCON, a builder of data centers and semiconductor plants. Institutional work follows public budgets rather than rents or sales prices.
Site-built work dominates while modules grow quickest
Based on construction method, the market is categorized into traditional on-site and modular and prefabricated work. Traditional On-site led with 91.5% of 2025 value because cast-in-place concrete and site assembly remain the default for most homes and offices, and world cement output was about 3,800 million metric tons in 2025, according to the USGS. Modular & Prefabricated grows fastest at 6.8% as large contractors commit to factory methods, and a China State Construction subsidiary signed a strategic partnership with MODENA E&C on May 20, 2025, to deliver projects using Modular Integrated Construction. Road transport limits still cap the size of each module.
| Segment Group | Leading Sub-segment | Share, 2025 | Fastest-growing Sub-segment | CAGR, 2026–2035 |
|---|---|---|---|---|
| By Construction Type | New Construction | 56.0% | Renovation & Refurbishment | 5.4% |
| By Building Type | Residential | 50.0% | Commercial | 5.6% |
| By Construction Method | Traditional On-site | 91.5% | Modular & Prefabricated | 6.8% |
Cost per square meter varies threefold by building type
Building prices are set per project, usually as a lump sum or a guaranteed maximum price, so the cost per square meter depends on how much mechanical and electrical equipment a building holds. A hospital in France costs roughly a third as much per square meter as a U.S. data hall, where cooling and power systems dominate the bill. Inputs move the base cost, and the USGS put the average U.S. cement mill value at about USD 160 per metric ton in 2025, the same as in 2024. Builders with fixed-price contracts carry tariff and wage risk, which is why large owners increasingly accept cost-plus terms for complex buildings.
| Building or input | Typical price or fee | Basis |
|---|---|---|
| Portland cement, U.S. average mill value | About USD 160 per metric ton in 2025, flat on 2024 | USGS Mineral Commodity Summaries, January 2026 |
| Hospital building, Reims, France | About EUR 3,600 per m², EUR 210 million for 58,000 m² | Credence Research estimate from a VINCI release, June 2026 |
| Data center building, Virginia, U.S. | About USD 10,800 per m² incl. site work, USD 238 million for 22,000 m² | Credence Research estimate from a Skanska release, August 2026 |
| New U.S. single-family home | Construction 64.4% of sales price, lot 13.7%, builder profit 11.0% | NAHB cost survey, January 2025 |
| Imported softwood lumber, U.S. | 10% Section 232 tariff on top of existing duties from Oct. 14, 2025 | Presidential proclamation, summarized by Polsinelli |
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Housing programs, data halls and EU retrofits lift work
Subsidized housing programs fill Indian and Brazilian order books
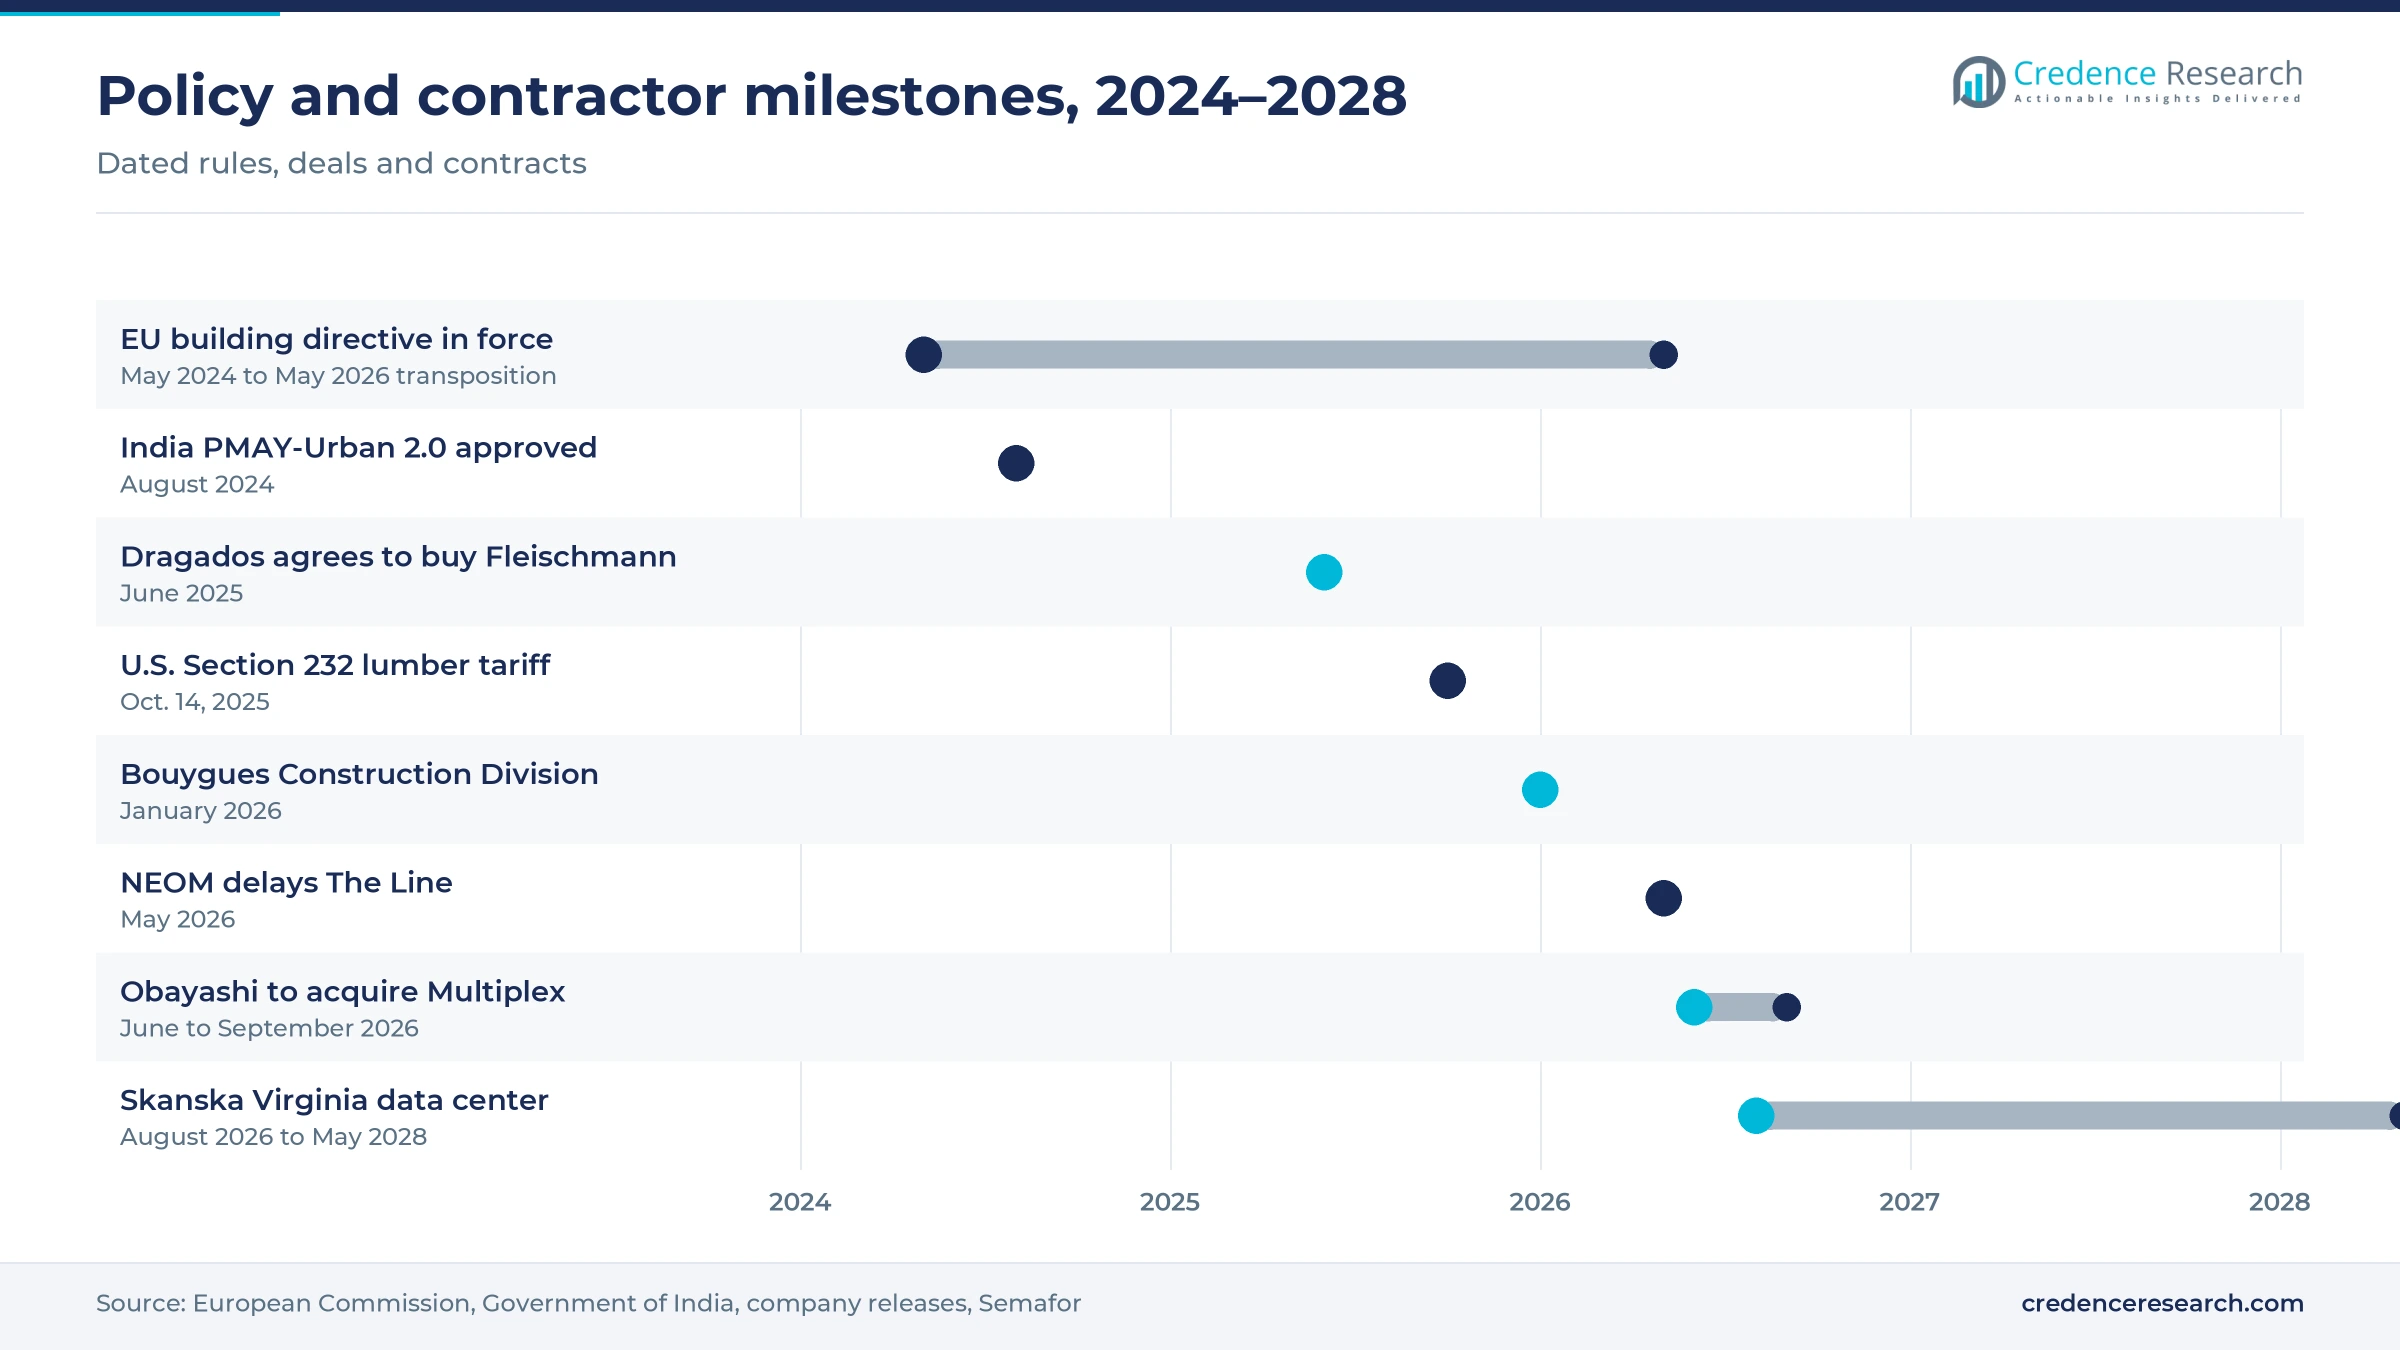
Public housing programs create the most predictable residential volume, because governments fix unit targets and pay part of each home's cost. India's cabinet approved Pradhan Mantri Awas Yojana-Urban 2.0 in August 2024 for one crore, or 10 million, urban homes, with 2.30 lakh crore rupees of central assistance over five years, according to All India Radio. Brazil had contracted more than 1.9 million Minha Casa Minha Vida units since 2023 and set a target of 3 million by the end of 2026, according to Agência Gov. A new income band for families earning 8,600 to 12,000 reais a month widened the program in 2025. These programs favor builders of mid-rise reinforced concrete blocks and suppliers of steel rebar, while their payment timing depends on public budgets.
Data center campuses move into the commercial pipeline
Data centers have become the most dynamic commercial building type, because cloud and AI operators order large shells with dense power and cooling on short schedules. U.S. data center construction reached a USD 45 billion annual rate in December 2025, up almost 30% from a year earlier, according to Census data reported by Marketplace. Skanska signed a contract on Aug. 13, 2026, for a second data center building with five data halls on a Virginia campus. Saudi Arabia's sovereign fund is also shifting spending toward ports and data centers, according to Semafor. Contractors with mechanical and electrical depth win this work, which is reshaping data center campuses into a separate specialty.
EU renovation law turns energy upgrades into deadlines
Europe's building law converts energy upgrades from optional spending into compliance work with dates attached. The recast directive requires minimum energy performance standards that reach the worst-performing 16% of non-residential buildings by 2030 and 26% by 2033, according to the European Commission. Member states must also cut average primary energy use in homes by 16% by 2030 and by 20% to 22% by 2035, with at least 55% of the cut from the worst homes. Buildings account for about 40% of energy used in the EU, the Commission says. Renovation contractors, facade specialists and installers of heat pumps gain the most, while owners of old offices face capital calls.
Measured housing shortfalls keep residential pipelines long
Housing shortfalls keep residential demand from collapsing even when interest rates rise, because the gap between households and homes keeps widening. About 3.4 billion people lack access to adequate housing, according to UN-Habitat's World Cities Report 2026, released May 19, 2026. In sub-Saharan Africa, 55% of households face excessive housing costs, the highest burden of any region in the same report. Germany approved 238,500 dwellings in 2025, up 10.8% but only about two-thirds of the pre-2022 average of roughly 350,000 a year, according to the Bundestag press service. These gaps favor builders that can deliver lower-cost units at volume, rather than premium developers that depend on strong sales prices.
Off-site methods and timber codes reshape delivery
Contractors are shifting toward factory work as site hours tighten
Contractors are shifting toward factory-built components to address labor limits on site, creating openings for prefabricated walls, bathroom pods and volumetric modules across housing, hotels and hospitals. Japan capped annual construction overtime at 720 hours from April 2024, and construction working hours fell by 31.1 hours in fiscal 2024, according to Nippon.com. Construction bankruptcies in Japan reached 1,924 in 2024, the highest since 2015, and those linked to labor shortages rose to 180 from 128, according to Japanese bankruptcy data cited by Global Construction Review. Modular and prefabricated work grows at 6.8% a year in the Credence Research model. Builders that own factories gain schedule certainty, while small site-based subcontractors lose share.
Tall timber codes and carbon disclosure are rising in importance
Building owners are shifting toward lower-carbon structures to address disclosure rules, creating openings for engineered wood in mid-rise offices, schools and apartments. The 2021 and 2024 International Building Codes allow Type IV-A mass timber buildings up to 18 stories, and 38 states have adopted these provisions, according to WoodWorks in April 2026. Under the EU directive, new buildings over 1,000 m² must disclose life-cycle global warming potential from January 2028 and all new buildings from January 2030. Buildings and construction produce 34% of global CO2 emissions, according to UNEP. Suppliers of cross-laminated timber and low-clinker concrete gain specification share as these disclosures begin.
Code gaps in emerging economies open work for certified builders
Builders and materials suppliers have an opening in emerging economies where new floor space is growing faster than the rules that govern it. More than 50% of newly built floor space in emerging and developing economies is not yet covered by building energy codes, according to UNEP's Global Status Report released in March 2025. Buildings and construction also consume 32% of global energy, according to the same report. Vietnam's cement output rose to about 100 million metric tons in 2025 from 91 million in 2024, according to the USGS, a sign of fast building growth. Developers that adopt codes early gain access to green finance and multilateral lending, while lenders gain lower long-term risk.
U.S. public owners offer steady institutional building work
Contractors exposed to weak private demand have an opening in public buildings, where budgets were approved before the housing slowdown. U.S. public construction rose 3.6% to USD 516.8 billion in 2025 while private construction fell 2.9%, according to the Census Bureau. Educational building work held at USD 138.1 billion in the same data, while health care building spending was flat, leaving room for hospital replacement programs. Public owners usually pay against certified progress, which lowers the working-capital strain that weak private demand places on contractors. School districts, states and hospital systems offer steady payments, and builders with bonding capacity and public procurement teams gain the most.
China, labor gaps, tariffs and approvals slow projects
China's property contraction removes the largest source of volume
China's developer slump removes volume that no other country can replace quickly. Real estate development investment fell 17.2% to 8,278.8 billion yuan in 2025, and newly started floor space fell 20.4% to about 587.7 million m², according to the National Bureau of Statistics. State-owned general contractors, cement producers and steel mills are most exposed, since housing starts feed their order books two to three years ahead. Exporters of contracting capacity are already forming partnerships abroad, as the modular agreement noted in the segments shows.
A shortage of trades caps how much work builders can take
Labor supply limits how many projects contractors can start, even where owners have funding. Associated Builders and Contractors said on Jan. 15, 2026, that the U.S. industry must attract 349,000 net new workers in 2026 to meet demand, according to Construction Executive. Roughly one-fifth of electricians are over 55, so retirements will tighten the trades that data centers need most. Small subcontractors without training programs are most exposed, while general contractors pass wage increases to owners through cost-plus terms.
Tariffs on wood products raise U.S. residential input costs
Tariffs raise the cost of framing and fit-out in U.S. homes, where timber frames are the norm. A 10% Section 232 tariff on imported softwood lumber took effect on Oct. 14, 2025, and the tariff on kitchen cabinets and vanities rose from 25% to 50% on Jan. 1, 2026, according to Polsinelli. Imports from the EU and Japan are capped at 15% and from the U.K. at 10%. Homebuilders selling to first-time buyers are most exposed, because they cannot pass the full cost on to price-sensitive buyers.
Slow safety approvals delay high-rise projects in England
Approval delays raise holding costs and push back revenue for developers of tall residential buildings in England. The Building Safety Regulator reported a median of 22 weeks to approve new higher-risk buildings between May and July 2026, and 32 weeks for complex cases, according to gov.uk. It still had 131 new-build cases in progress at the end of the period. Developers of tall apartment blocks and their lenders carry the cost, since construction cannot start before approval, which favors lower-rise schemes.
Asia Pacific holds the largest building pipeline
| Region | Value, 2025 (USD billion) | Share, 2025 | CAGR, 2026–2035 |
|---|---|---|---|
| Asia Pacific | 3,742.73 | 45.5% | 4.7% |
| North America | 1,933.06 | 23.5% | 4.9% |
| Europe | 1,809.67 | 22.0% | 3.6% |
| Latin America | 370.16 | 4.5% | 5.4% |
| Middle East & Africa | 370.16 | 4.5% | 5.9% |
Asia Pacific leads on Indian volume as China shrinks
Asia Pacific held 45.5% of 2025 value and grows at 4.7% a year, the largest pool even after the Chinese contraction noted in the challenges. India's cement output rose to about 470 million metric tons in 2025 from 440 million, according to the USGS, and Larsen & Toubro won orders in May 2026 for 10 residential towers of up to 55 floors in Hyderabad. The regional split is a Credence Research estimate scaled from national construction statistics and cement output, so the Asia Pacific value carries the widest margin, since Chinese building output is not published on the same basis as U.S. spending.
North America leans on data halls as housing slows
North America held 23.5% of 2025 value and grows at 4.9% a year. U.S. construction spending fell 1.4% in 2025, with private residential work down 2.6% to USD 905.2 billion, according to the Census Bureau. Housing starts also slipped in 2025, with single-family starts falling fastest, in the Census residential construction release. Data centers and public buildings carry growth instead, which keeps the region's rate below that of emerging markets, while contractors with mechanical and public procurement depth hold the strongest order books.
Europe grows slowest as renovation offsets weak new starts
Europe held 22.0% of 2025 value and grows at 3.6% a year, the slowest of any region. EU production in construction rose 0.5% in 2025 and was stable in the euro area, while building output in December 2025 was 0.7% lower than a year earlier in the EU, according to Eurostat. Germany completed about 251,900 dwellings in 2024, 14.4% fewer than in 2023, according to the Bundestag press service. Renovation required by the EU directive described in the drivers keeps European contractors busy, but mainly on smaller and more fragmented jobs.
Middle East and Africa grow fastest despite Gulf resets
Middle East & Africa held 4.5% of 2025 value and grows fastest at 5.9% a year, from a small base. Egypt's cement output rose to about 64 million metric tons in 2025 from 53 million in 2024, according to the USGS, and UN-Habitat puts housing shortages at about 28 million units in Nigeria and 19.5 million in Egypt. Saudi plans are being reset, and NEOM delayed further work on The Line until after 2030, according to Semafor in May 2026. Contractors tied to a single giga project carry the most risk.
Latin America grows on Brazilian housing and Chilean data halls
Latin America held 4.5% of 2025 value and grows at 5.4% a year. Brazil's housing program, described in the drivers, sets most residential volume, and Brazilian cement output rose to about 67 million metric tons in 2025 from 65 million, according to the USGS, while Mexico's fell to 42 million from 44 million. Chile's National Data Center Plan projects about USD 2.5 billion of investment over five years, according to ACS. Public data on non-residential building in the region are thin, so this share carries more uncertainty than most.
Contractors regroup and buy into digital buildings
| Development | Status and market relevance |
|---|---|
| In January 2026, Bouygues grouped Colas, Bouygues Construction and Bouygues Immobilier into a single Construction Division with about 100,000 employees, effective Jan. 1, 2026. | Completed reorganization; one division now bids for building, civil works and property development. |
| In June 2025, ACS Group, through Dragados, agreed to acquire 100% of Chilean contractor Fleischmann, which has more than 1,200 employees and a focus on data centers and industrial facilities. | Agreement announced; completion subject to regulatory approvals, adding data center capacity in Latin America. |
| In June 2026, Obayashi Corporation signed an agreement to acquire 100% of Multiplex Global, a builder operating in Australia, the U.K. and Canada, with the share transfer scheduled for late September 2026. | Share transfer agreement signed; extends a Japanese contractor into three English-speaking building markets. |
| In June 2026, VINCI Construction was awarded EUR 157 million of a EUR 210 million contract to build a 498-bed, 58,000 m² second building for the New Reims Hospital over 45 months. | Contract awarded; shows public hospital renewal as steady institutional work in France. |
| In August 2026, Skanska signed a USD 238 million contract for a second data center building on a Virginia campus, with construction from August 2026 to May 2028. | Contract signed and in order bookings; construction started, completion planned for May 2028. |
Modeling, modules, timber and controls change sites
- Building information modeling lets designers, contractors and owners share one coordinated model, which cuts clashes between structure and services before work reaches the site.
- Volumetric modules move fit-out of rooms, bathrooms and plant into factories, which shortens site schedules for hotels, hospitals and student housing.
- Mass timber replaces part of the concrete frame with cross-laminated panels and glued beams, which lowers embodied carbon and speeds erection on mid-rise buildings.
- Smart building controls connect heating, cooling, lighting and metering, which lets owners prove energy savings to regulators and tenants.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Local scale and balance sheets decide contract wins
Competition is local for most work and global only for the largest projects. Chinese state contractors dominate their home market and win abroad on financing and speed, while VINCI, Bouygues and ACS compete across Europe, the Americas and Australia through local brands. ACS operates in the United States through HOCHTIEF and Turner, one of the largest U.S. general builders. Japanese contractors such as Obayashi and Kajima combine strong home positions with acquisitions abroad, and Sekisui House builds homes in Japan and, through Richmond American, in 16 U.S. states. Larsen & Toubro leads high-rise residential and factory building in India. Bechtel builds advanced manufacturing plants, including the first phase of Micron's New York memory megafab, while D.R. Horton, the largest U.S. homebuilder by volume, leads single-family construction. Balance sheet strength matters because owners favor builders that can absorb cost overruns.
Fragmented trades sit under a few global general contractors
The supply side is organized in two distinct layers of firms. A small group of general contractors, led by China State Construction, VINCI, ACS through HOCHTIEF and Turner, Bouygues and the large Japanese builders, manages the largest projects and carries contract risk, while hundreds of thousands of specialist subcontractors supply the trades. Concentration is low, since even the largest groups hold small shares of national markets outside their home country. Entry barriers are bonding capacity, local licensing and safety records rather than technology. Margins are thin for general contractors and higher for specialists in mechanical, electrical and facade work, which explains why the large groups are buying those specialists.
Companies profiled and their roles in this market
| Company | Type | Role in the market |
|---|---|---|
| China State Construction Engineering Corporation | Full-line contractor | Housing, commercial towers and public buildings in China and abroad |
| VINCI | Full-line contractor | VINCI Construction builds hospitals, offices and housing across Europe |
| ACS Group (HOCHTIEF and Turner) | Full-line contractor | Turner and Dragados build commercial, data center and public buildings |
| Bouygues | Full-line contractor | Bouygues Construction builds offices, housing and public facilities in Europe and Asia |
| Skanska | Full-line contractor | Builds data centers, hospitals and commercial buildings in the U.S. and Nordics |
| Larsen & Toubro | Full-line contractor | Buildings and factories unit builds high-rise housing and industrial plants in India |
| Obayashi Corporation | Full-line contractor | Builds offices and plants in Japan; Webcor extends it abroad, and it has agreed to acquire Multiplex |
| Kajima Corporation | Full-line contractor | Builds offices, plants and housing in Japan, Asia and the U.S. |
| Sekisui House | Homebuilder | Builds prefabricated homes in Japan and site-built homes through Richmond American |
| Bechtel | Specialist | Builds semiconductor and advanced manufacturing plants, including Micron's New York megafab |
| D.R. Horton, Inc. | Homebuilder | Largest U.S. homebuilder by closings, focused on entry-level single-family homes |
Growth shifts from Chinese housing to data and retrofit
Credence Research's view is that the buildings construction market keeps growing in nominal terms while the source of growth moves away from Chinese apartment towers. Data center programs, EU renovation deadlines and subsidized housing in India and Brazil now set most new contract awards. Contractors with mechanical and electrical depth, factory capacity and public procurement experience are best placed, while builders tied to speculative housing or a single giga project carry the most risk. The main uncertainty is China, where official data show no recovery yet in developer starts.
Official spending data anchor the building estimate
The report uses 2025 as the base year and forecasts to 2035. Market values come from the Credence Research model, which starts from official construction spending and building statistics, including U.S. Census construction spending, China's National Bureau of Statistics, Eurostat and national housing data, and cross-checks them against cement output from the USGS. Regional and segment shares are Credence Research estimates built from the same data. Sources are public statistics, regulatory texts, company releases and trade association surveys; no interviews or surveys were conducted for this edition.
Nominal growth holds as the mix of buildings changes
The market is expected to reach USD 12,897.18 billion by 2035, growing at a 4.60% CAGR over 2026–2035. Growth is nominal and includes building cost inflation, so volume grows more slowly than value. Asia Pacific stays the largest region, with India taking over from China as the main source of new floor space, while the Middle East and Africa grow fastest from a small base. In mature markets, renovation and data center work take a larger share of contractor revenue each year, and builders that combine factory production with site skills gain share as trade shortages persist.
China and interest rates decide the range of outcomes
The range depends on how long the Chinese property contraction lasts and how quickly interest rates fall in the United States and Europe. A longer Chinese slump would cut the largest regional pool, while faster rate cuts would release delayed housing and office projects in the West. Data center and EU renovation work are the most stable parts of the outlook, since they rest on signed contracts and legal deadlines rather than on sales prices.
| Scenario | CAGR, 2026–2035 | Value, 2035 | What has to hold |
|---|---|---|---|
| Downside | 3.2% | USD 11,424.23 billion | Chinese starts keep falling to 2028 and Western rates stay high, delaying housing |
| Base | 4.60% | USD 12,897.18 billion | China stabilizes by 2027, data center programs hold and EU retrofits follow national plans |
| Upside | 5.6% | USD 14,050.27 billion | Rate cuts revive Western housing while India and Brazil meet their program targets on time |
Frequently Asked Questions
How big is the buildings construction market?
What is the growth rate of the building construction industry?
Which building type holds the largest share?
How fast is commercial construction growing?
Which region leads building construction?
What are the key building industry statistics for 2025?
What is holding back building construction?
Who are the leading building construction companies?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Construction Type
- 1.2.1 New Construction
- 1.2.2 Renovation & Refurbishment
- 1.2.3 Repair & Maintenance
- 1.3 By Building Type
- 1.3.1 Residential
- 1.3.2 Commercial
- 1.3.3 Industrial
- 1.3.4 Institutional
- 1.3.5 Mixed-Use Developments
- 1.4 By Construction Method
- 1.4.1 Traditional On-site
- 1.4.2 Modular & Prefabricated
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2025: USD 8,225.79 billion → 2035: USD 12,897.18 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Historical Period: 2018-2025
- 2.6.2 Base Year: 2025
- 2.6.3 Forecast Period: 2025-2035
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2025
- 3.3 Forecast Market Size, 2035
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Buildings Construction Market Trends and Developments
- 4.1 Historical Industry Development, 2018-2025
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Buildings Construction Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis, 2018-2025
- 5.2 Demand Forecast, 2025-2035
- 5.3 Production and Output Trend, 2018-2025
- 5.4 Production and Output Forecast, 2025-2035
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Buildings Construction Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends, 2018-2025
- 6.3 Pricing Outlook, 2025-2035
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Buildings Construction Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Buildings Construction Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Buildings Construction Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Buildings Construction Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Buildings Construction Market Outlook, 2025-2035
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2025: USD 8,225.79 billion → 2035: USD 12,897.18 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size, 2018-2025
- 11.1.4 Base-Year Market Size, 2025
- 11.2 Market Forecast, 2025-2035
- 11.2.1 Revenue Forecast to 2035
- 11.2.2 Volume Forecast to 2035
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Buildings Construction Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2025
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Construction Type - Market Size and Forecast, 2025-2035
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size, 2018-2025
- 12.3.3 Revenue Forecast, 2025-2035
- 12.3.4 Volume Forecast, 2025-2035
- 12.3.5 Base-Year Market Share, 2025
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 New Construction
- 12.3.7.2 Renovation & Refurbishment
- 12.3.7.3 Repair & Maintenance
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Building Type - Market Size and Forecast, 2025-2035
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size, 2018-2025
- 12.4.3 Revenue Forecast, 2025-2035
- 12.4.4 Volume Forecast, 2025-2035
- 12.4.5 Base-Year Market Share, 2025
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Residential
- 12.4.7.2 Commercial
- 12.4.7.3 Industrial
- 12.4.7.4 Institutional
- 12.4.7.5 Mixed-Use Developments
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Construction Method - Market Size and Forecast, 2025-2035
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size, 2018-2025
- 12.5.3 Revenue Forecast, 2025-2035
- 12.5.4 Volume Forecast, 2025-2035
- 12.5.5 Base-Year Market Share, 2025
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Traditional On-site
- 12.5.7.2 Modular & Prefabricated
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Buildings Construction Geographic Market Outlook, 2025-2035
- 13.1 Regional Market Size and Share, 2025
- 13.2 Regional Market Forecast, 2025-2035
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Buildings Construction Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2025-2035
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Buildings Construction Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2025
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2025-2035
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 China State Construction Engineering Corporation
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 VINCI
- 17.4 ACS Group (HOCHTIEF and Turner)
- 17.5 Bouygues
- 17.6 Skanska
- 17.7 Larsen & Toubro
- 17.8 Obayashi Corporation
- 17.9 Kajima Corporation
- 17.10 Sekisui House
- 17.11 Bechtel
- 17.12 D.R. Horton, Inc.
- 17.13 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

