
Small Caliber Ammunition Market Overview:
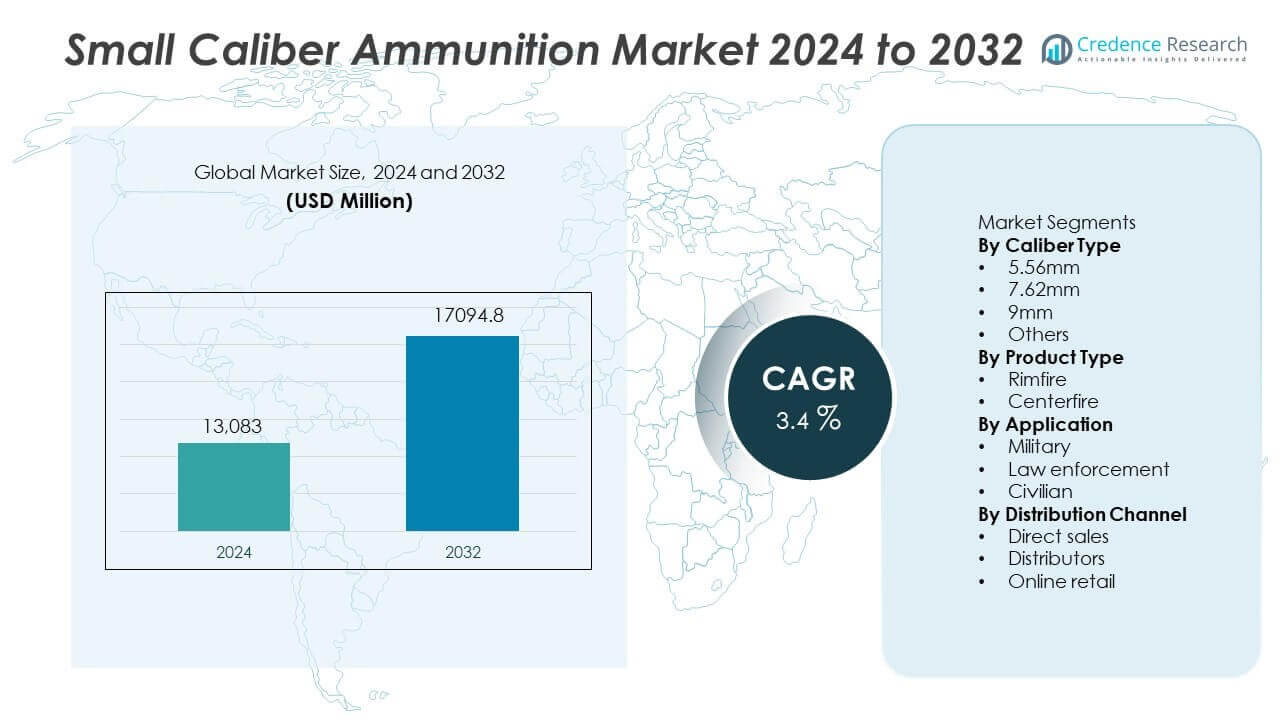
The Small Caliber Ammunition market was valued at USD 13,083 million in 2024 and is projected to reach USD 17,094.8 million by 2032, growing at a CAGR of 3.4% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Small Caliber Ammunition Market Size 2024 | USD 13,083 million |
| Small Caliber Ammunition Market, CAGR | 3.4% |
| Small Caliber Ammunition Market Size 2032 | USD 17,094.8 million |
Small Caliber Ammunition Market Insights
- Defense modernization programs and recurring training activities remain key growth drivers, with the military application segment leading with a market share of 56.8% due to continuous procurement and stockpiling requirements.
- Standardization of calibers and automation in manufacturing represent major market trends, while centerfire ammunition dominates product demand with a segment share of 72.4% because of higher reliability and operational performance.
- Competitive intensity remains high as established players secure long-term government contracts, though strict regulations and export controls act as key restraints limiting new market entry.
- Regionally, North America leads with a market share of 34.8%, followed by Europe at 26.1% and Asia Pacific at 22.7%, driven by defense spending, geopolitical tensions, and expanding domestic production.
Small Caliber Ammunition Market Segmentation Analysis:
By Caliber Type
By caliber type, the 5.56mm segment dominates the Small Caliber Ammunition market with a market share of 38.6%. Military forces widely use 5.56mm rounds due to standardization across NATO countries and high compatibility with assault rifles. The segment benefits from sustained defense procurement programs and ongoing infantry modernization initiatives. High accuracy, manageable recoil, and effective range support strong adoption in combat and training operations. Rising border tensions and regular military drills further reinforce demand. The 7.62mm segment follows, driven by higher penetration needs, while 9mm and other calibers maintain steady demand in secondary applications.
- For instance, Olin Corporation operates Lake City Army Ammunition Plant with an annual capacity exceeding 1.6 billion small-caliber rounds, supporting consistent 5.56mm supply.
By Product Type
By product type, centerfire ammunition holds the dominant position with a market share of 72.4%. Centerfire rounds offer higher reliability, superior firing consistency, and better performance under extreme conditions. Military and law enforcement agencies prefer centerfire ammunition for operational readiness and combat reliability. The segment benefits from advanced primer technologies and large-scale manufacturing efficiencies. Continuous investments in quality control and ballistic performance strengthen market leadership. Rimfire ammunition accounts for the remaining share, driven mainly by training, recreational shooting, and cost-sensitive civilian use, but limited power restricts broader defense adoption.
- For instance, General Dynamics Corporation implemented automated primer seating systems to enhance manufacturing consistency and significantly reduce defect rates in their munitions production.
By Application
By application, the military segment leads the market with a market share of 56.8%. Rising defense budgets, soldier modernization programs, and large ammunition stockpiling initiatives drive sustained demand. Armed forces require consistent supplies for training, deployment, and reserve inventories. Geopolitical instability and cross-border security concerns further support procurement volumes. Law enforcement holds the second-largest share, supported by internal security operations and tactical unit expansion. The civilian segment shows steady growth, driven by sport shooting and personal defense, but remains smaller due to regulatory controls and restricted access in many regions.
Key Growth Drivers
Rising Global Defense Spending
Governments continue to increase defense budgets across major regions. Military modernization programs drive steady ammunition procurement. Small caliber rounds remain essential for infantry readiness. Regular training exercises consume large ammunition volumes. Border tensions increase stockpiling needs. NATO members prioritize standardized calibers for interoperability. Asia-Pacific nations expand ground forces capacity. Middle East countries strengthen internal security forces. Defense contracts ensure long-term supply commitments. Stable government funding supports predictable demand. This driver provides consistent revenue visibility. Manufacturers benefit from multi-year procurement cycles. Production scale improves cost efficiency. Defense spending remains a core growth pillar.
- For instance, Northrop Grumman Corporation expanded its medium-caliber production lines by implementing automated loading systems to increase manufacturing capacity and efficiency.
Expansion of Law Enforcement and Internal Security Forces
Law enforcement agencies expand to address urban security challenges. Counterterrorism operations raise ammunition usage. Riot control and patrol duties require regular training. Small caliber ammunition supports daily operational readiness. Governments invest in police modernization programs. Tactical unit expansion increases specialized ammunition demand. Public safety initiatives support continuous procurement. Ammunition consumption rises through frequent qualification drills. Emerging economies strengthen internal security frameworks. Border policing drives sustained demand. Reliable supply chains become critical. Manufacturers align products with law enforcement standards. This driver ensures steady non-military demand.
- For instance, CBC Global Ammunition has operations providing ammunition to domestic security agencies and international law enforcement.
Growth in Civilian Shooting Sports and Training Activities
Shooting sports gain popularity across several regions. Civilian training ranges drive recurring ammunition consumption. Recreational shooting supports steady retail demand. Firearms training programs increase practice frequency. Sports shooting events expand participation levels. Youth training initiatives contribute to volume growth. Ammunition affordability influences repeat purchases. Indoor ranges increase usage consistency. Civilian demand remains resilient despite regulations. Product variety supports diverse user needs. Manufacturers target training-grade ammunition. Brand loyalty strengthens repeat sales. This driver supports balanced market growth.
Key Trends & Opportunities
Standardization of Military Calibers and Platforms
Armed forces standardize calibers across weapon systems. Standardization simplifies logistics and supply chains. Interoperability improves during joint operations. Bulk procurement reduces per-unit costs. NATO-aligned calibers dominate procurement strategies. Training and combat ammunition use the same standards. Weapon platform upgrades reinforce caliber alignment. Standard rounds improve inventory management efficiency. Manufacturers focus on high-volume standardized products. Production planning becomes more predictable. This trend supports operational efficiency. Long-term contracts favor compliant suppliers. Standardization creates scale-driven opportunities.
- For instance, BAE Systems plc supplies NATO-standard 5.56mm and 7.62mm ammunition validated across more than 20 allied weapon platforms during joint qualification programs.
Technological Improvements in Ammunition Manufacturing
Manufacturers invest in advanced production technologies. Automation improves output consistency. Quality control systems reduce defect rates. Precision manufacturing enhances ballistic performance. Improved propellants increase reliability. Lightweight materials support better handling. Process optimization lowers production costs. Energy-efficient plants improve sustainability. Digital monitoring enhances production traceability. Technology adoption supports higher throughput. These improvements attract defense buyers. Innovation creates differentiation opportunities. Manufacturing advances support long-term competitiveness.
- For instance, General Dynamics Corporation operates automated loading lines equipped with inline vision inspection systems that monitor production at high precision to ensure quality and safety standards are met.
Key Challenges
Strict Regulatory and Export Control Frameworks
Ammunition markets face complex regulatory environments. Export controls limit cross-border trade flexibility. Licensing requirements delay order fulfillment. Compliance costs increase operational expenses. Civilian sales face strict legal restrictions. Policy changes create demand uncertainty. International sanctions restrict supplier access. Documentation requirements slow supply chains. Smaller manufacturers face higher compliance burdens. Market entry barriers remain high. Regulatory risks affect investment decisions. Managing compliance becomes resource intensive. These challenges constrain market expansion.
Supply Chain Disruptions and Raw Material Volatility
Ammunition production depends on stable raw material supply. Metals and chemicals face price fluctuations. Geopolitical risks disrupt sourcing routes. Energy costs affect manufacturing expenses. Transportation delays impact delivery schedules. Inventory management becomes complex. Supplier concentration increases operational risk. Production planning faces uncertainty. Cost volatility pressures profit margins. Long-term contracts reduce flexibility. Manufacturers seek alternative suppliers. Supply resilience requires investment. These challenges demand strategic mitigation efforts.
Regional Analysis
North America
North America leads the Small Caliber Ammunition market with a market share of 34.8%. Strong defense spending and sustained procurement by the United States drive regional leadership. Military training programs consume large ammunition volumes each year. Law enforcement agencies maintain steady demand through regular qualification and tactical exercises. Civilian shooting sports and firearms training support additional volume growth. Established domestic manufacturing capacity ensures reliable supply chains. Long-term defense contracts improve production planning. Ongoing investments in ammunition modernization reinforce regional dominance and support consistent demand across military and security sectors.
Europe
Europe accounts for a market share of 26.1% in the Small Caliber Ammunition market. NATO standardization policies drive uniform caliber adoption across member states. Rising geopolitical tensions increase stockpiling and readiness programs. Eastern European countries expand military capabilities, supporting procurement growth. Law enforcement modernization and border security initiatives add stable demand. Civilian shooting sports contribute steady consumption. Strong domestic manufacturers and cross-border defense cooperation support supply continuity. Government-backed contracts and regional security strategies strengthen Europe’s long-term market position.
Asia Pacific
Asia Pacific holds a market share of 22.7%, driven by expanding military forces and rising defense budgets. Countries such as China and India invest heavily in infantry modernization. Border security challenges and regional tensions increase ammunition usage. Law enforcement expansion supports regular training demand. Civilian shooting remains limited but shows gradual growth in select markets. Domestic production capacity continues to expand, reducing import reliance. Government-led procurement programs ensure long-term demand stability and position Asia Pacific as a key growth region.
Middle East & Africa
The Middle East and Africa region represents a market share of 10.4%. Ongoing geopolitical instability drives consistent military procurement. Governments focus on readiness, counterterrorism, and border security operations. Law enforcement agencies increase training frequency to address internal security threats. Civilian demand remains restricted due to regulatory controls. Import dependence remains high, though local assembly initiatives are emerging. Strategic defense spending and security-driven procurement cycles sustain steady market activity across major countries in the region.
Latin America
Latin America accounts for a market share of 6.0% in the Small Caliber Ammunition market. Public safety concerns drive law enforcement ammunition consumption. Military demand remains stable, focused on training and border patrol activities. Civilian shooting sports support moderate demand in regulated markets. Governments invest in police modernization programs. Local manufacturing provides partial self-sufficiency and reduces import reliance. Budget limitations constrain large-scale expansion, but consistent procurement ensures stable demand across key regional markets.
Small Caliber Ammunition Market Segmentations:
By Caliber Type
- 5.56mm
- 7.62mm
- 9mm
- Others
By Product Type
- Rimfire
- Centerfire
By Application
- Military
- Law enforcement
- Civilian
By Distribution Channel
- Direct sales
- Distributors
- Online retail
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
Competitive landscape analysis highlights strong competition among Olin Corporation, BAE Systems plc, General Dynamics Corporation, CBC Global Ammunition, and Nammo AS. The market shows high entry barriers due to regulation and capital needs. Leading players focus on long-term military contracts to secure stable revenue. Product standardization strengthens scale advantages for large manufacturers. Defense clients prioritize reliability, quality consistency, and delivery assurance. Companies invest in capacity expansion to meet bulk procurement needs. Automation improves output efficiency and reduces defects. Strategic partnerships support regional supply access. Export compliance capabilities shape competitive positioning. Regional players serve domestic defense requirements. Innovation remains focused on manufacturing efficiency rather than product differentiation. Cost control and raw material sourcing remain critical. Competitive intensity stays high due to government tender-based procurement. Long-term contracts favor established suppliers with proven performance records.
Key Player Analysis
- Olin Corporation
- Northrop Grumman Corporation
- BAE Systems plc
- General Dynamics Corporation
- CBC Global Ammunition
- Nammo AS
- FN Herstal
- Denel PMP
- Elbit Systems Ltd.
- Poongsan Corporation
Recent Developments
- In April 2025, BAE Systems plc announced new energetics and propellant production methods.
- In September 2024, Northrop Grumman Corporation backed a Lithuanian propulsion and ammunition MOU.
- In June 2024, Olin Corporation, via Winchester, received a U.S. Army ammo contract change.
Report Coverage
The research report offers an in-depth analysis based on Caliber Type, Product Type, Application, Distribution Channel and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Military modernization programs will continue to drive consistent ammunition procurement.
- Defense training intensity will sustain high consumption levels across regions.
- Standardized calibers will strengthen large-scale manufacturing efficiency.
- Law enforcement expansion will support steady non-military demand growth.
- Automation will improve production reliability and cost control.
- Domestic manufacturing will increase to reduce import dependence.
- Geopolitical tensions will encourage long-term stockpiling strategies.
- Regulatory compliance will remain critical for supplier competitiveness.
- Civilian shooting activities will provide stable supplemental demand.
- Long-term government contracts will favor established manufacturers.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Small Caliber Ammunition market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Small Caliber Ammunition market projected to grow between 2024 and 2032?
Which Small Caliber Ammunition market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Small Caliber Ammunition market?
Who are the leading companies in the Small Caliber Ammunition market?
Which region commanded the largest share of the Small Caliber Ammunition market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 13,083 million → 2032: USD 17,094.8 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Small Caliber Ammunition Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Small Caliber Ammunition Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Small Caliber Ammunition Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Small Caliber Ammunition Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Small Caliber Ammunition Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Small Caliber Ammunition Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Small Caliber Ammunition Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Small Caliber Ammunition Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 13,083 million → 2032: USD 17,094.8 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Small Caliber Ammunition Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Small Caliber Ammunition Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Small Caliber Ammunition Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Small Caliber Ammunition Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

