
Military 3D and 4D Printing Market: USD 3.61 billion in 2025, Led by Navy and Air Force Programs
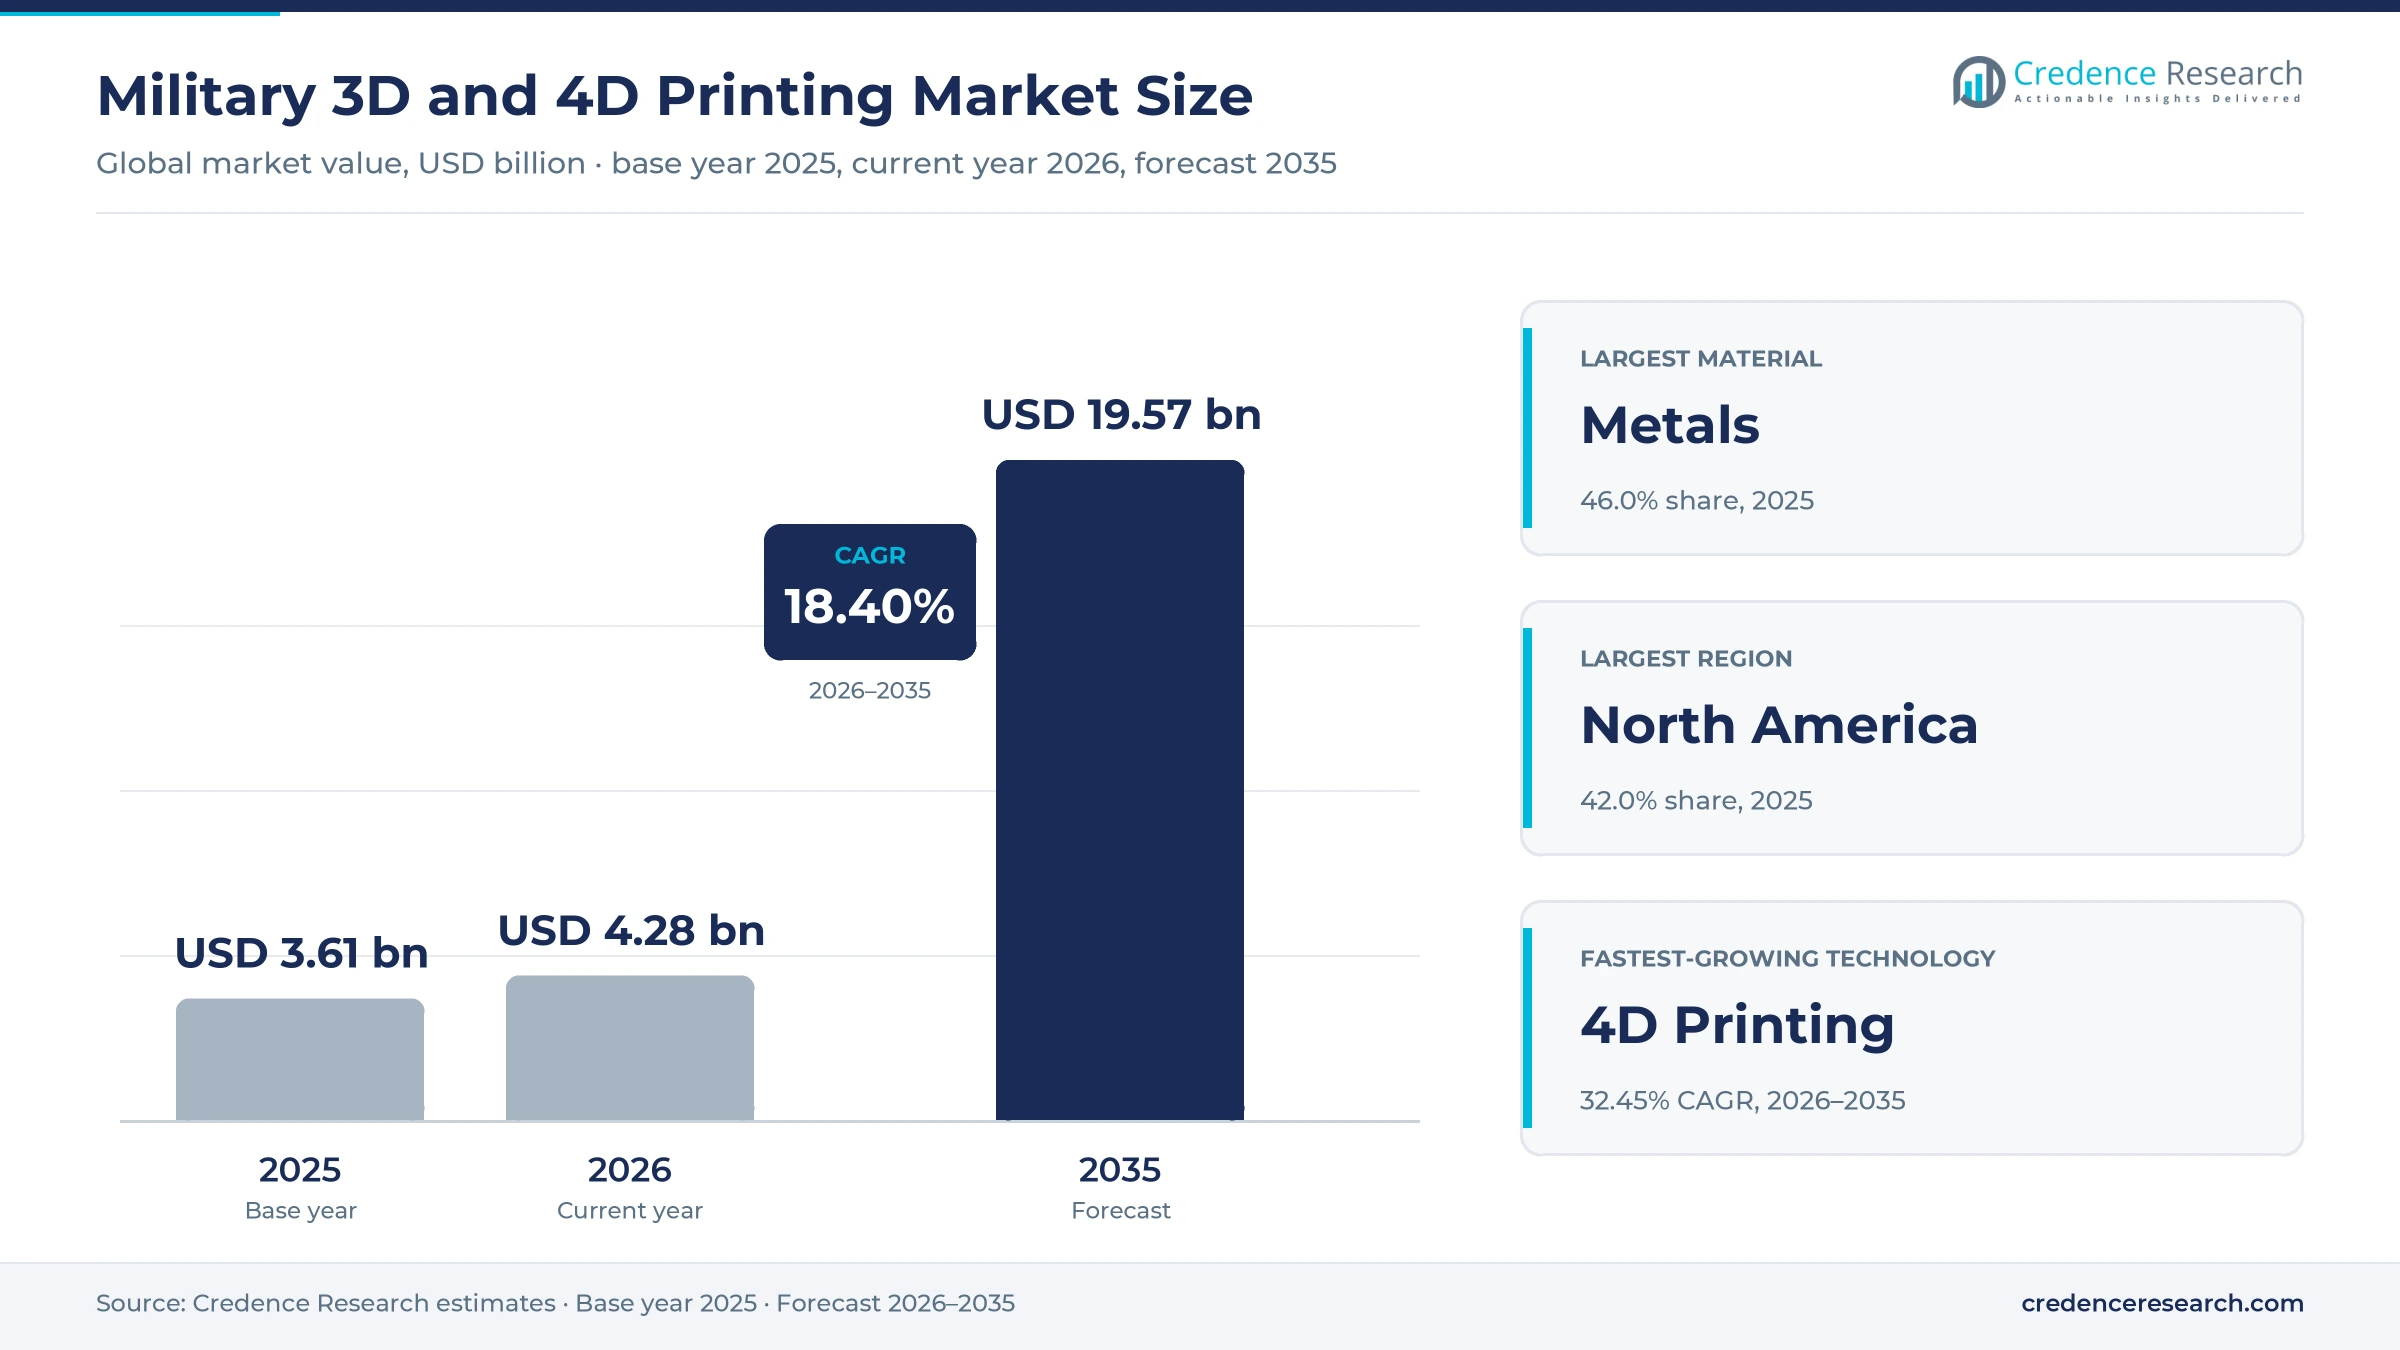
Valued at USD 3.61 billion in 2025, military 3D and 4D printing is moving out of test labs and into the supply chains of navies, armies and air forces. Credence Research expects USD 19.57 billion by 2035, a 18.40% CAGR over 2026–2035, with 2026 estimated at USD 4.28 billion. Growth comes from spare parts that are hard to source, ship repairs that cannot wait for a supplier, and funded programs that qualify printed metal parts for ships, aircraft and vehicles.
Most spending is still on polymer printers for prototypes and tools, but metal parts for submarines, carriers and aircraft engines are the fastest-rising source of value. Shape-changing 4D printing remains a small, research-led segment.
What does the market cover?
The market covers printers, materials, software and printing services bought by armed forces, defense laboratories, depots, shipyards and their suppliers. The scope includes:
- Polymer, metal, composite, ceramic and smart-material printing across material extrusion, vat photopolymerization, powder bed fusion, electron beam melting, binder jetting and 4D printing.
- Prototyping, direct manufacturing, tooling, maintenance and repair, and rapid restoration of damaged equipment.
- Airborne, land, naval and space or unmanned platforms.
The scope excludes the value of the finished platforms and any weapon or munition design. Values are in USD billion at current prices, allocated to the country of the buying force. Civil and defense aviation together are covered in the aerospace 3D printing market.
How was the estimate built?
All figures are Credence Research estimates, built from announced defense contracts, installed printer counts at depots and shipyards, material consumption per printer, service-bureau pricing and supplier disclosures.
Which program sets the pace?
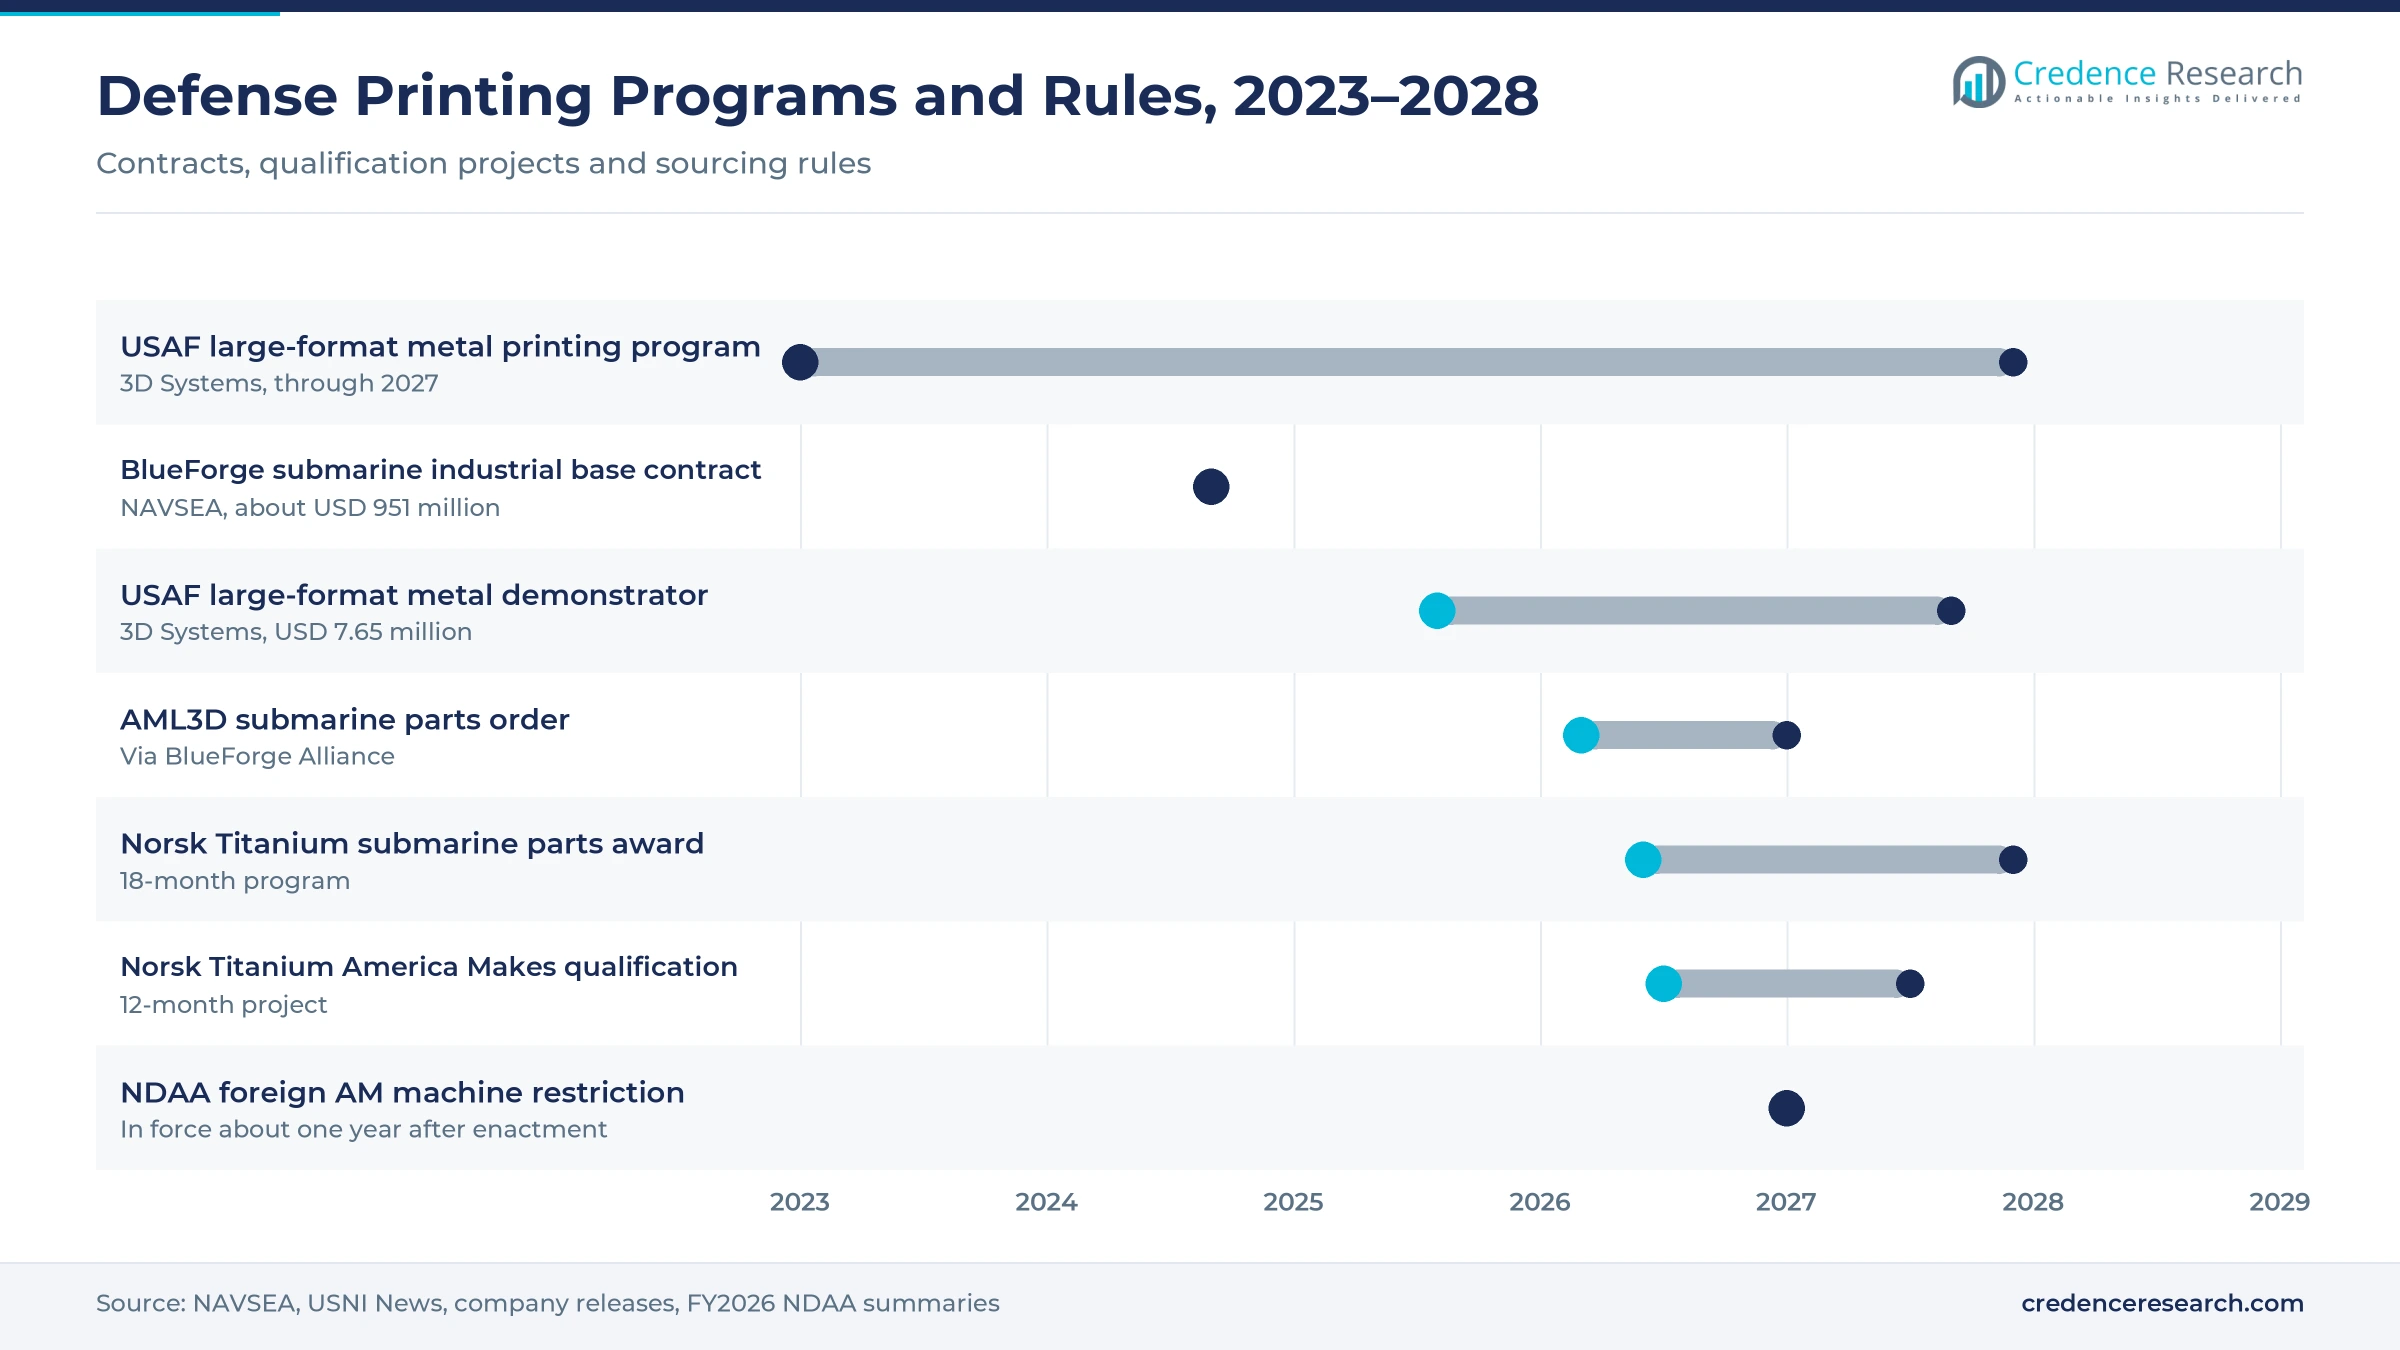
The US Navy is the largest single buyer. NAVSEA awarded the BlueForge Alliance a contract worth about USD 951 million in September 2024 to scale manufacturing technology, including additive manufacturing, for the submarine industrial base, as reported by USNI News.
Report Attributes
| Attribute | Details |
|---|---|
| Historical Period | 2018–2024 |
| Base Year | 2025 |
| Forecast Period | 2026–2035 |
| Market Size 2025 | USD 3.61 billion |
| Market Size 2026 (estimate) | USD 4.28 billion |
| Market Size 2035 (forecast) | USD 19.57 billion |
| CAGR (2026–2035) | 18.40% |
| Segments Covered | By Component, By Material, By Technology, By Application, By Platform, By End User |
| Regions Covered | North America, Europe, Asia Pacific, Latin America, Middle East & Africa |
| Companies Covered | Stratasys Ltd., 3D Systems Corporation, Engineering & Manufacturing Services, Inc., Norsk Titanium US Inc., 3T Additive Manufacturing Ltd., ExOne/Desktop Metal, EOS GmbH, Markforged, Inc., Optomec, Inc., American Elements Corporation |
Military 3D 4D Printing Market Insights
- The military 3D and 4D printing market was worth USD 3.61 billion in 2025 and is forecast to reach USD 19.57 billion by 2035, a 18.40% CAGR over 2026–2035.
- Credence Research estimates the market at USD 4.28 billion in 2026, the current year.
- On-demand expeditionary manufacturing is the strongest driver, adding about 5.0 percentage points to the forecast CAGR.
- Metals lead materials with a 46.0% share; smart materials grow fastest at 29.60% a year.
- Airborne platforms hold 38.0% of value; space and unmanned systems grow fastest at 21.91%.
- North America is the largest region at 42.0%; Europe grows fastest at 19.34%.
Metal Powder Bed Printing for Airborne Platforms Holds the Largest Value
Which component leads?
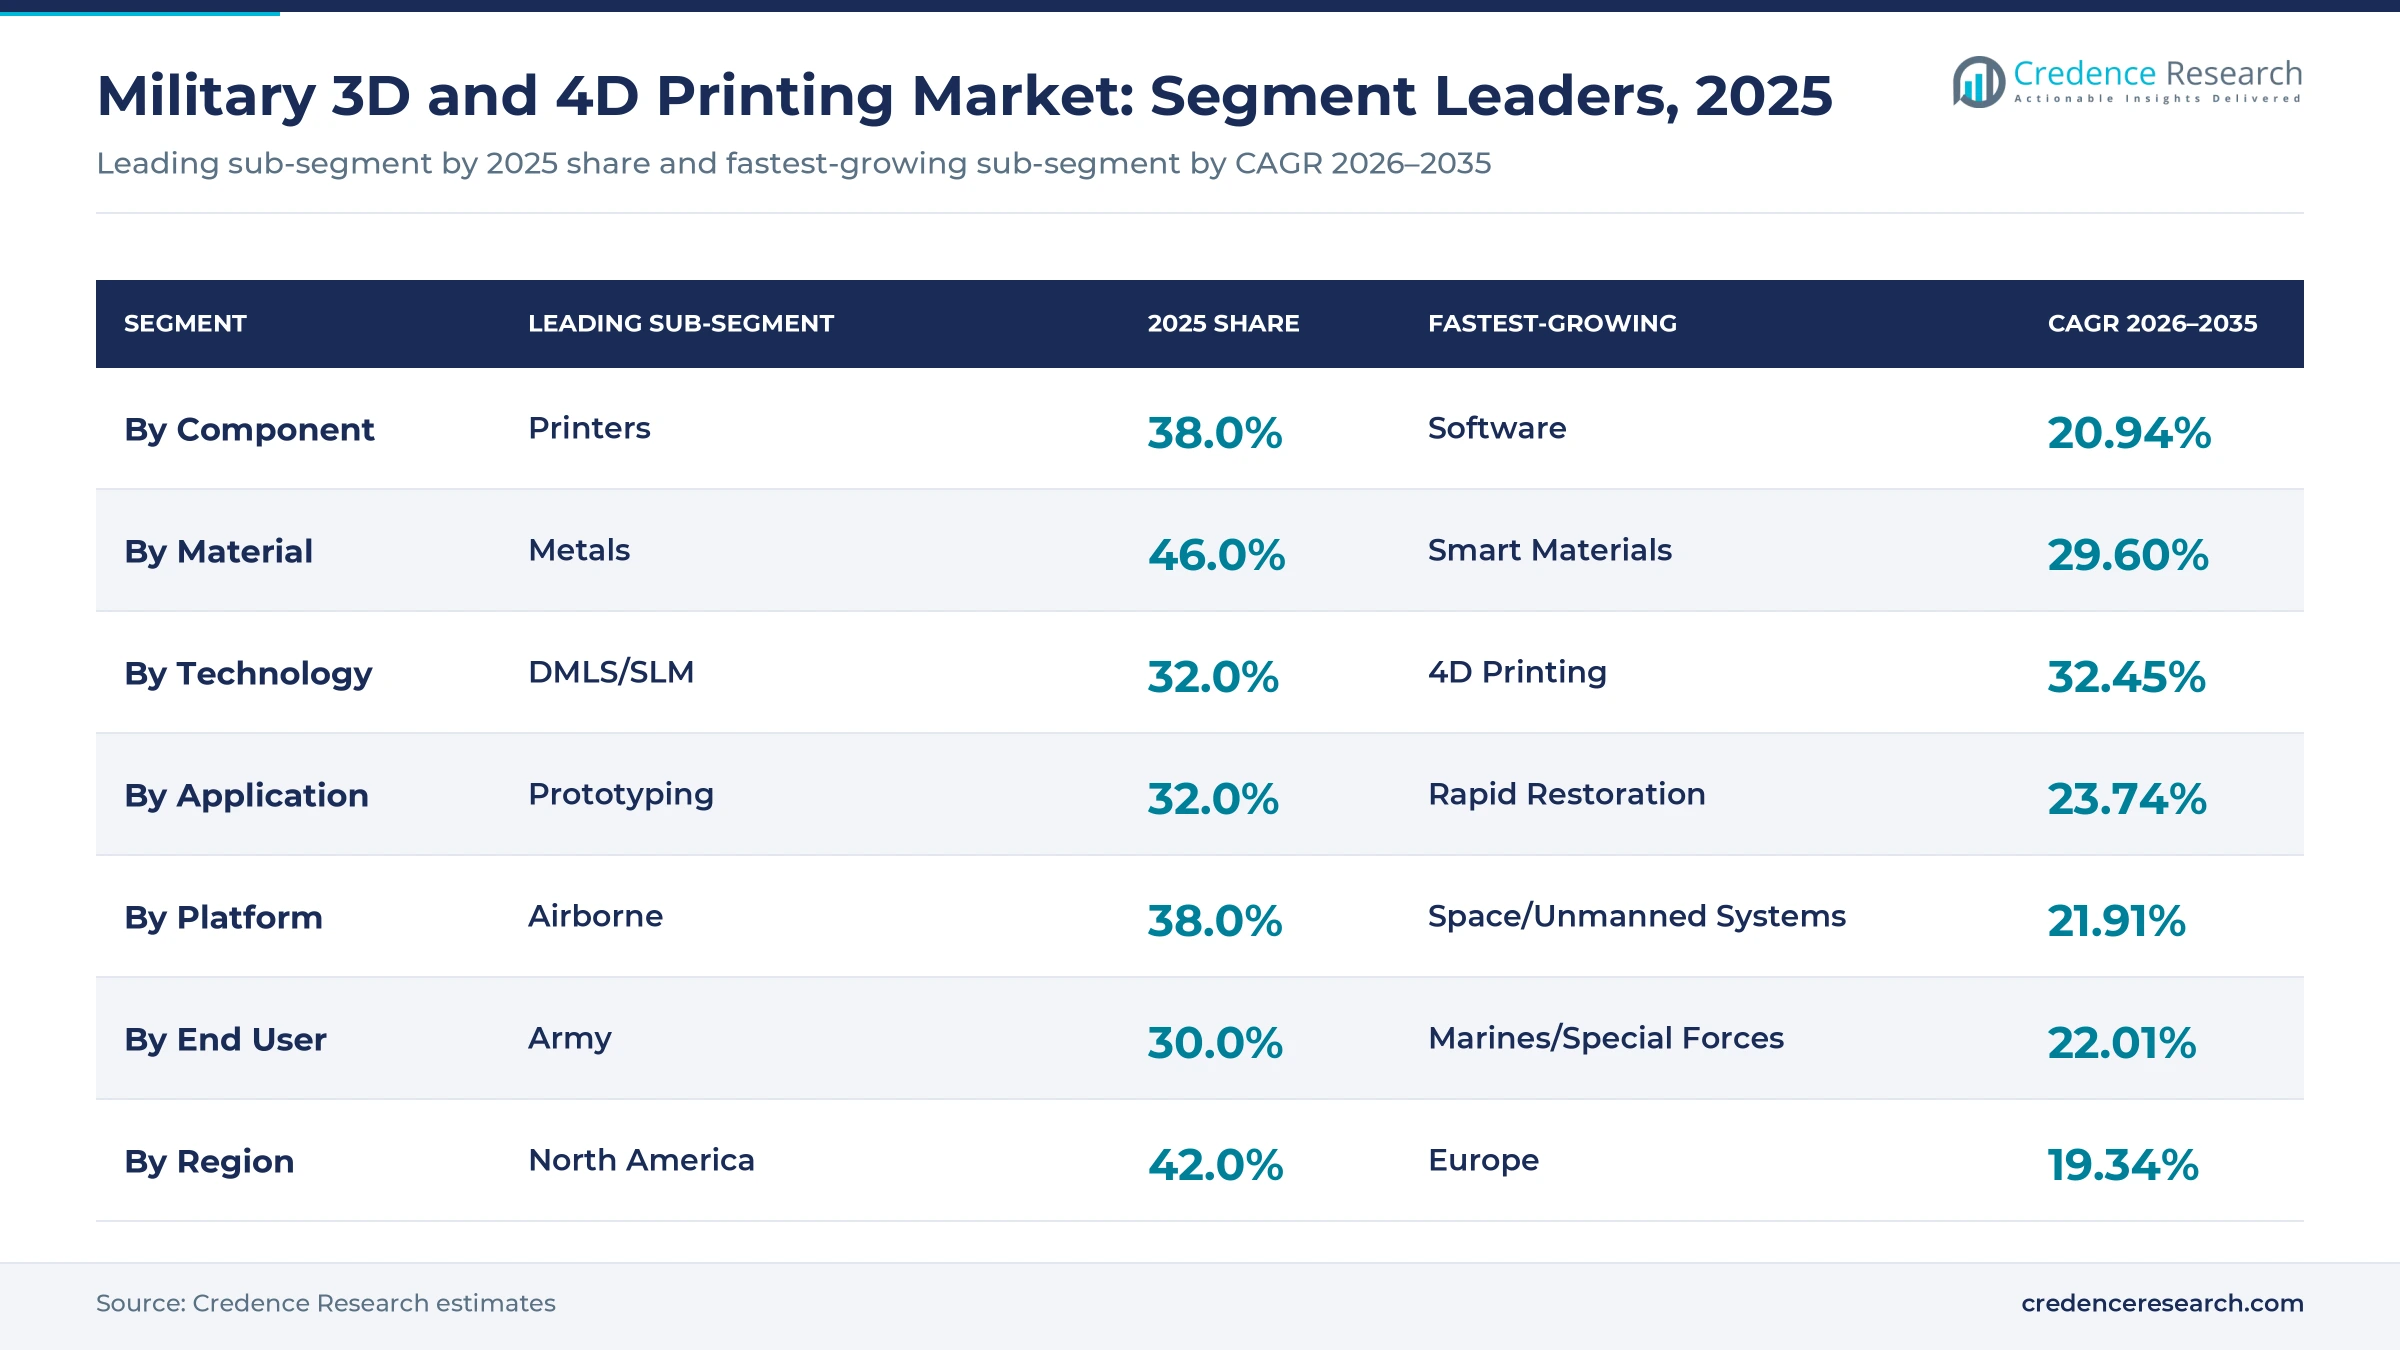
Printers lead with a 38.0% share in 2025, reflecting new metal and polymer systems at depots and shipyards. Services, including outsourced part production, follow closely. Software grows fastest at 20.94% a year as forces build digital part libraries.
Which material and technology lead?
Metals lead materials with a 46.0% share, ahead of polymers, composites, smart materials and ceramics. DMLS/SLM leads technologies with 32.0%, followed by FDM for polymer tools and prototypes. 4D printing grows fastest at 32.45% a year.
Which application leads?
Prototyping leads with a 32.0% share, followed by MRO and repair, direct manufacturing and tooling. Rapid restoration grows fastest at 23.74%.
Which platform and end user lead?
Airborne platforms lead with a 38.0% share because aircraft engines and structures use high-value metal parts. Space and unmanned systems grow fastest at 21.91% a year. The army is the largest end user with 30.0%, while marines and special forces grow fastest at 22.01%. Metal demand overlaps with the metal additive manufacturing market.
| Segment Group | Leading Sub-segment | 2025 Share | Fastest-growing Sub-segment | CAGR 2026–2035 |
|---|---|---|---|---|
| By Component | Printers | 38.0% | Software | 20.94% |
| By Material | Metals | 46.0% | Smart Materials | 29.60% |
| By Technology | DMLS/SLM | 32.0% | 4D Printing | 32.45% |
| By Application | Prototyping | 32.0% | Rapid Restoration | 23.74% |
| By Platform | Airborne | 38.0% | Space/Unmanned Systems | 21.91% |
| By End User | Army | 30.0% | Marines/Special Forces | 22.01% |
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Field Printing, Lighter Parts and Smart Materials Lift Spending
Why does expeditionary printing matter? (~+5.0% impact on forecast CAGR)
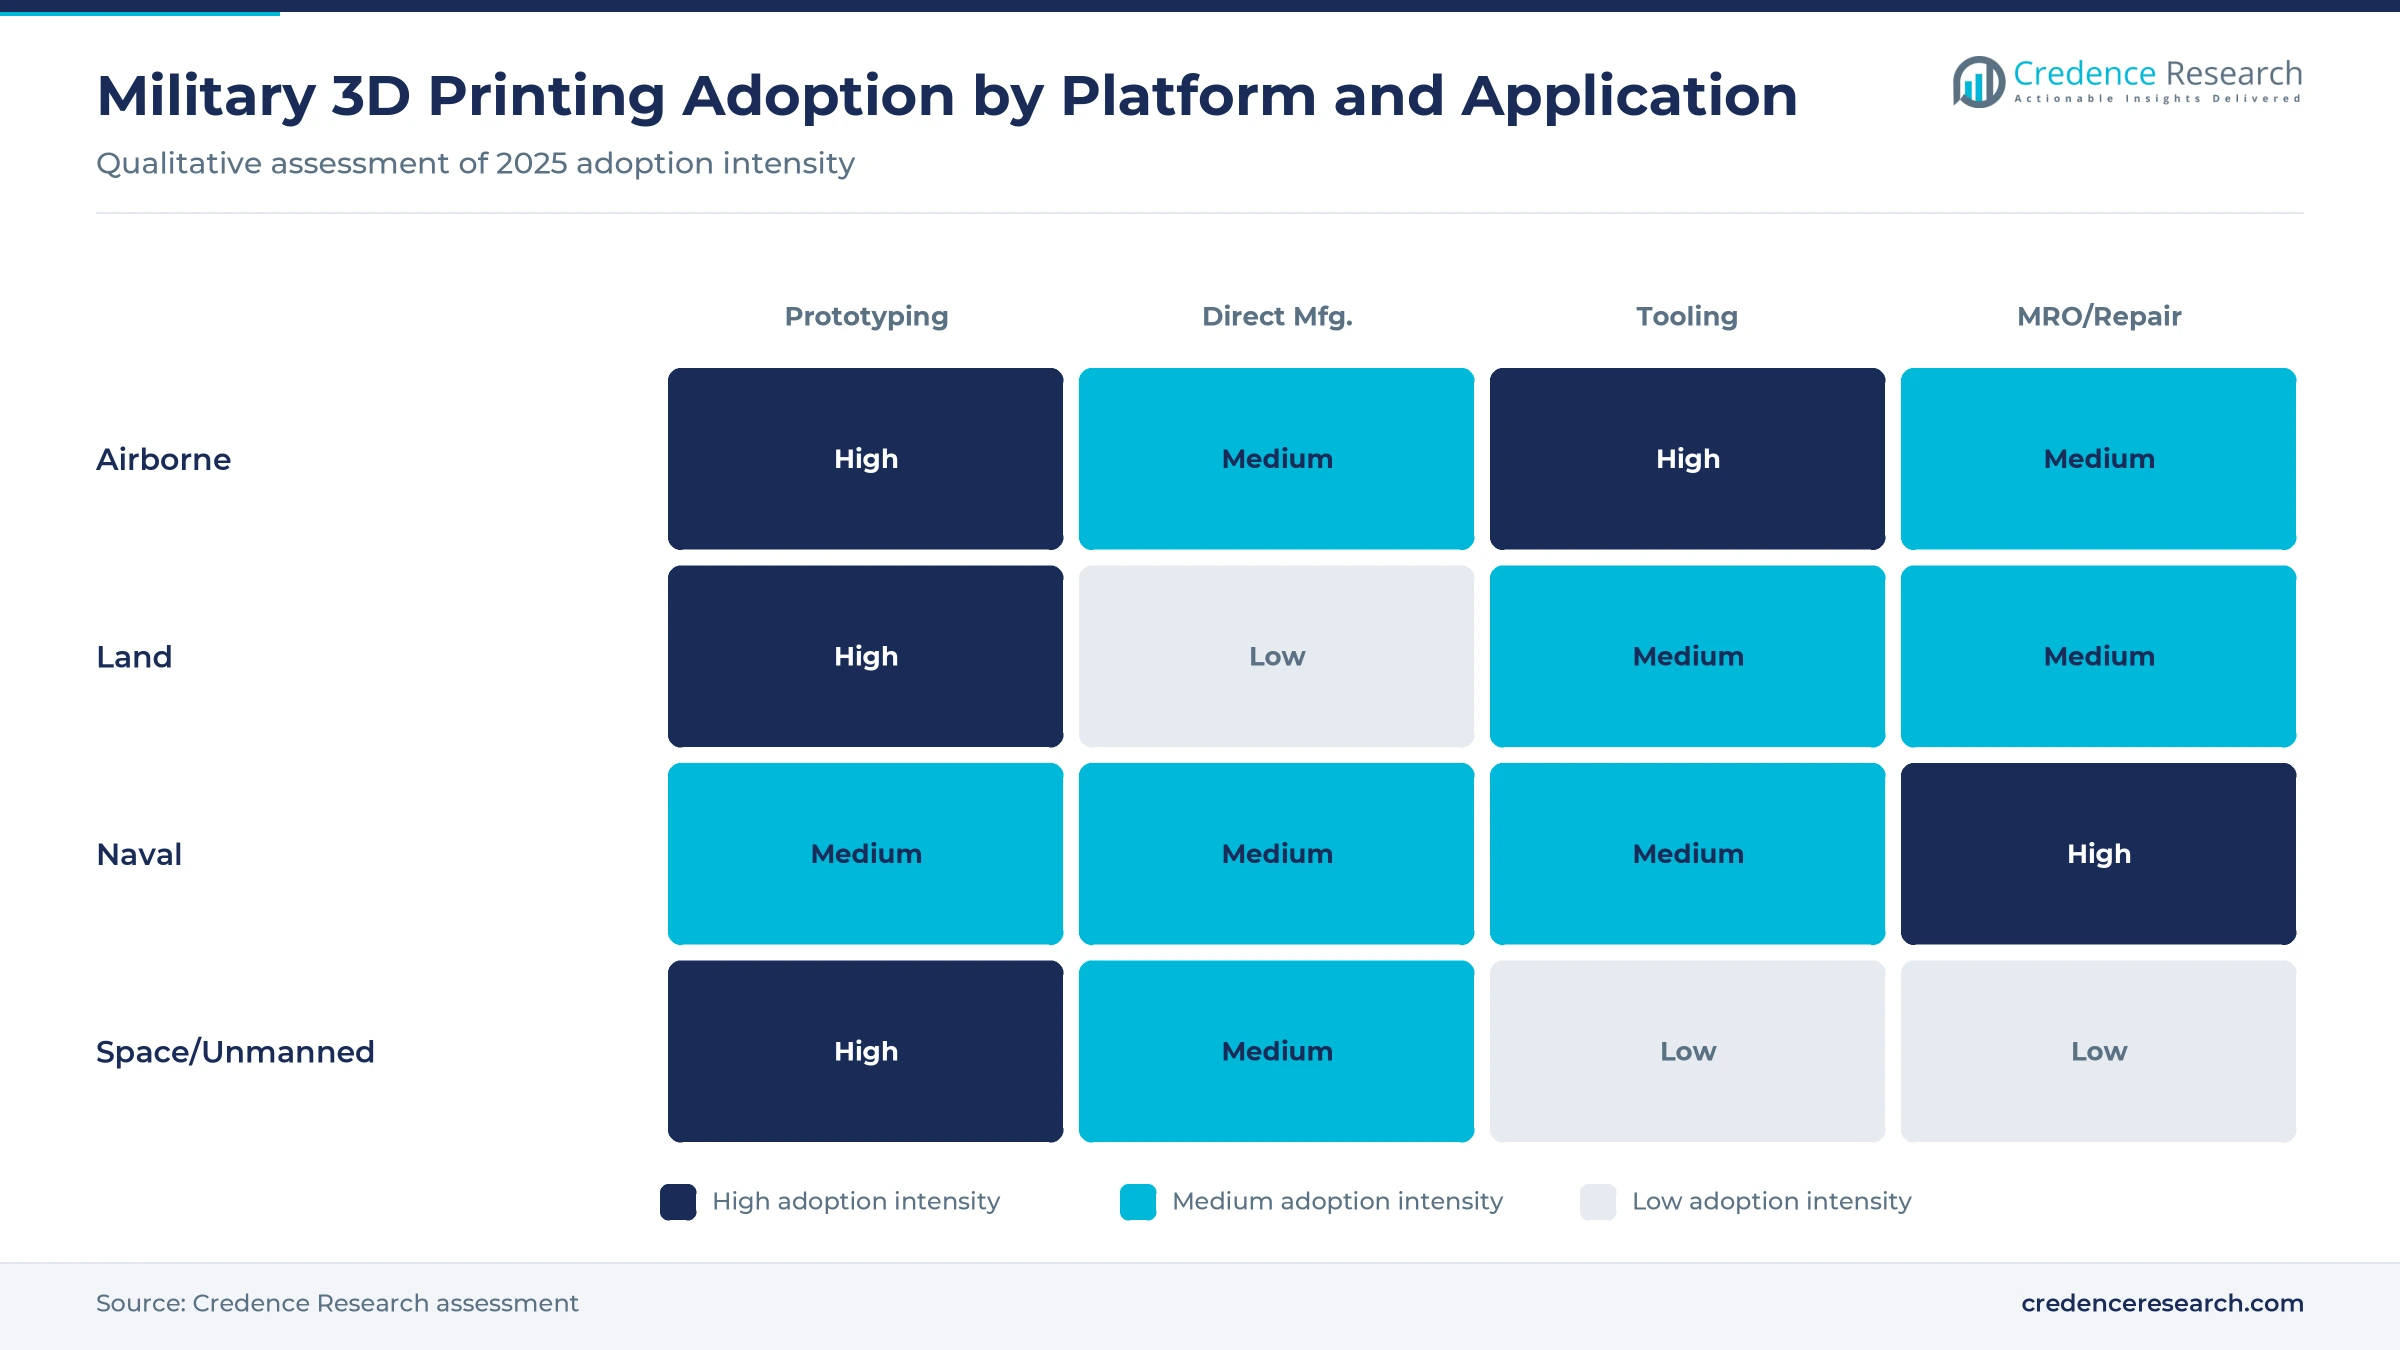
On-demand expeditionary manufacturing that cuts dependence on long supply chains is the strongest driver, adding about 5.0 percentage points to the forecast CAGR. Forces deployed far from depots wait weeks for simple parts, and a printer on a ship or at a forward base can close that gap. In August 2026, Marines printed more than 1,000 parts in two weeks aboard USS Essex during Pacific exercises, including a 5-meter foam hull built in about 16 working hours for about USD 11,000 of material. The Navy reports that its printing programs have already removed more than 1,400 days of cumulative maintenance delay. Prototyping still leads applications with a 32.0% share, MRO and repair ranks second, and rapid restoration grows fastest at 23.74% a year. The main limit is approval: each printed part still needs sign-off before it can be fitted to a specific system.
How do lighter parts and shorter lead times help? (~+3.8% impact on forecast CAGR)
Lightweighting, part consolidation and shorter lead times add about 3.8 percentage points to the forecast CAGR. Printing lets engineers merge several machined pieces into one part and source castings and forgings that no longer have a supplier. In 2025, the Navy installed the first printed metal valve manifold on a nuclear-powered aircraft carrier and cut testing requirements for printed parts by more than 60%, according to NAVSEA. New material specifications MIL-PRF-32802, 32803 and 32804 give shipyards a common basis for buying printed metal. Metals lead materials with a 46.0% share, and DMLS/SLM leads technologies with 32.0%.
What role do smart materials play? (~+2.6% impact on forecast CAGR)
Investment in smart materials and adaptive 4D-printed components adds about 2.6 percentage points to the forecast CAGR. 4D-printed parts change shape or properties after printing in response to heat, moisture or electrical signals, which could support self-deploying structures, adaptive seals and camouflage surfaces. Most work is still in defense laboratories and universities, so revenue is small. Smart materials are the fastest-growing material at 29.60% a year and 4D printing the fastest technology at 32.45%, both from low bases. The wider field is tracked in the 4D printing market and the smart materials market.
Domestic Sourcing, Large Metal Printers and Containerized Factories
Trend 1: Is sourcing moving onshore?
Yes. The FY2026 National Defense Authorization Act restricts the Department of Defense from buying additive manufacturing machines from covered foreign entities, starting one year after enactment. US and allied printer makers expect to gain share, and 3D Systems announced in January 2026 that it would expand its Littleton, Colorado site by up to 80,000 square feet for aerospace and defense work.
Trend 2: Are printers getting larger?
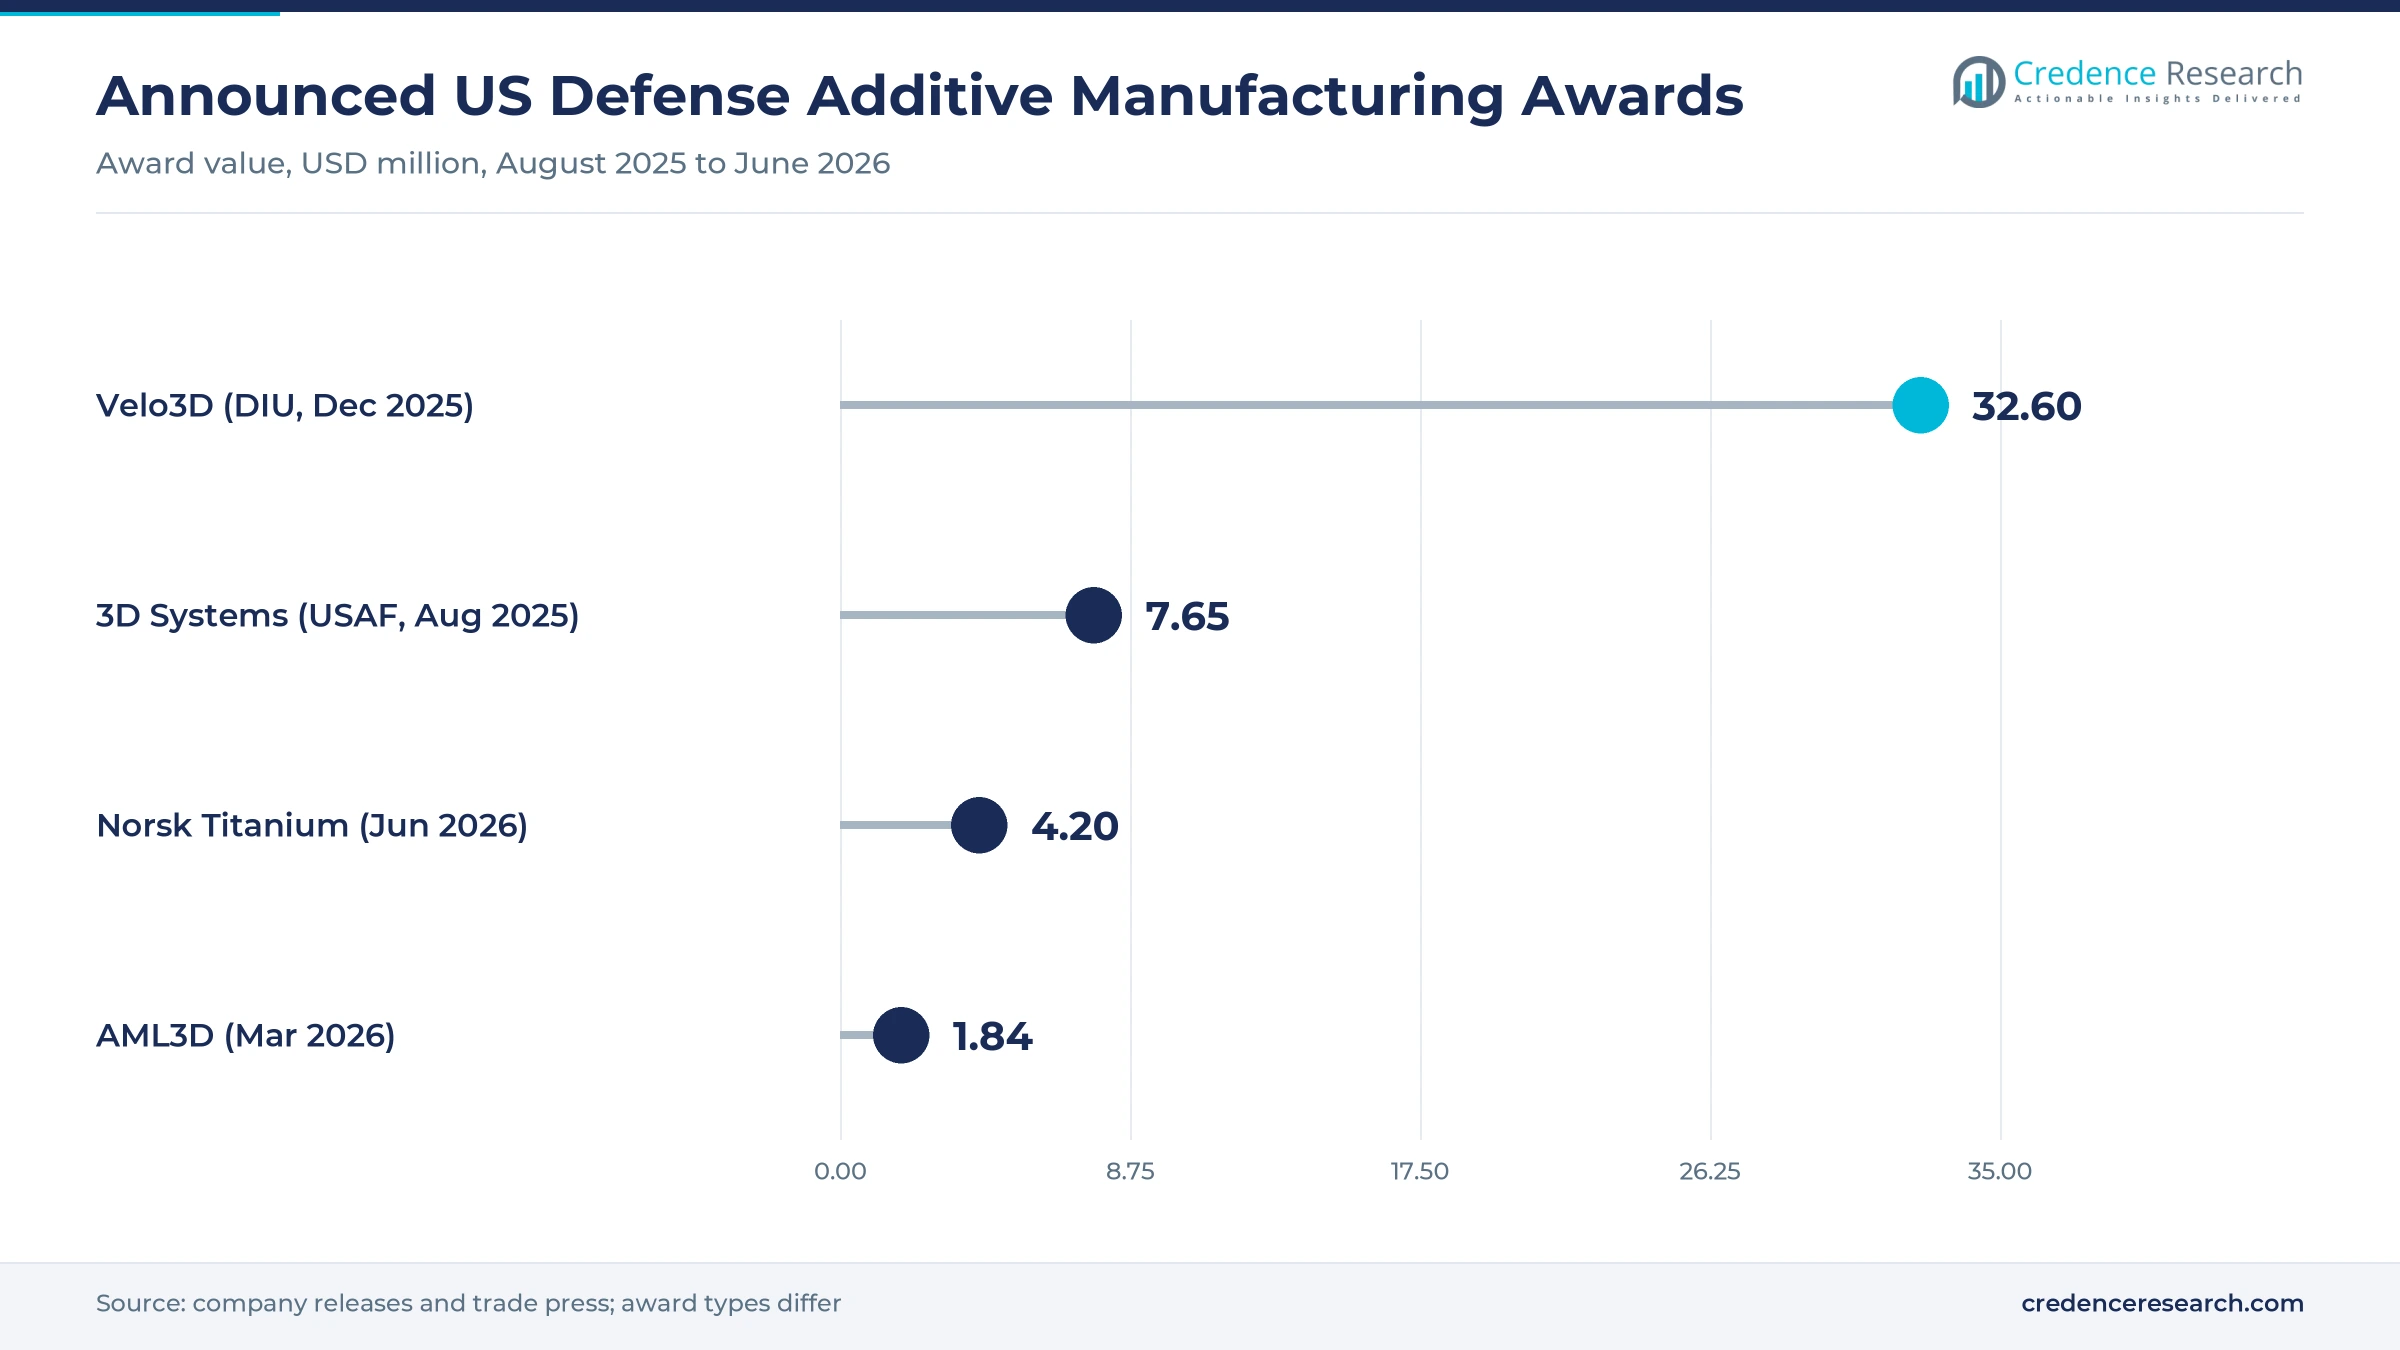
Yes. Large-format metal printers can replace castings for ship and vehicle parts. The US Air Force awarded 3D Systems a USD 7.65 million contract in August 2025 for a large-format metal printer demonstrator, as stated in the company's award release. Wire-fed processes for titanium and nickel-aluminum bronze are also scaling.
Trend 3: Are factories moving into containers?
Yes. Mobile print cells that fit in shipping containers can be placed on ships or at forward bases. The same units can print small drone frames, which links this market to the military drones market.
Trend 4: Is the supplier base consolidating?
Yes. Several printer makers have changed hands or restructured, and defense buyers now check supplier stability and ownership before standardizing on a platform.
Part Approval, Supplier Health and Data Security Slow Adoption
Why is qualification the main barrier?
Printers are easy to buy, but approval to fit a printed part is slow. Each part usually needs its own engineering review, and NAVSEA had more than 600 parts under review in early 2025 alongside 182 already approved. Without faster approval, many installed printers stay on prototypes and tools.
Are suppliers financially stable?
Not all. Desktop Metal, which owned ExOne, filed for Chapter 11 protection in July 2025, according to the Nano Dimension annual report. Revenue at some metal specialists has lagged far behind installed capacity, so buyers weigh vendor risk alongside price.
How serious is data security?
Digital part files are as sensitive as the parts themselves. Forces need secure file transfer, controlled printer access and traceable build records, which adds cost to every deployment.
Do materials limit adoption?
Yes. Military parts often need specific alloys, flame ratings or corrosion resistance, and only a few qualified powders and wires exist for each process.
Where are the opportunities?
Qualified digital spare-parts libraries offer the clearest opening. Suppliers that pair printers with approved part files, material data and inspection records can sell a complete package to depots and shipyards. The execution risk is the time and cost of qualification for each platform.
North America Leads on US Navy and Air Force Spending
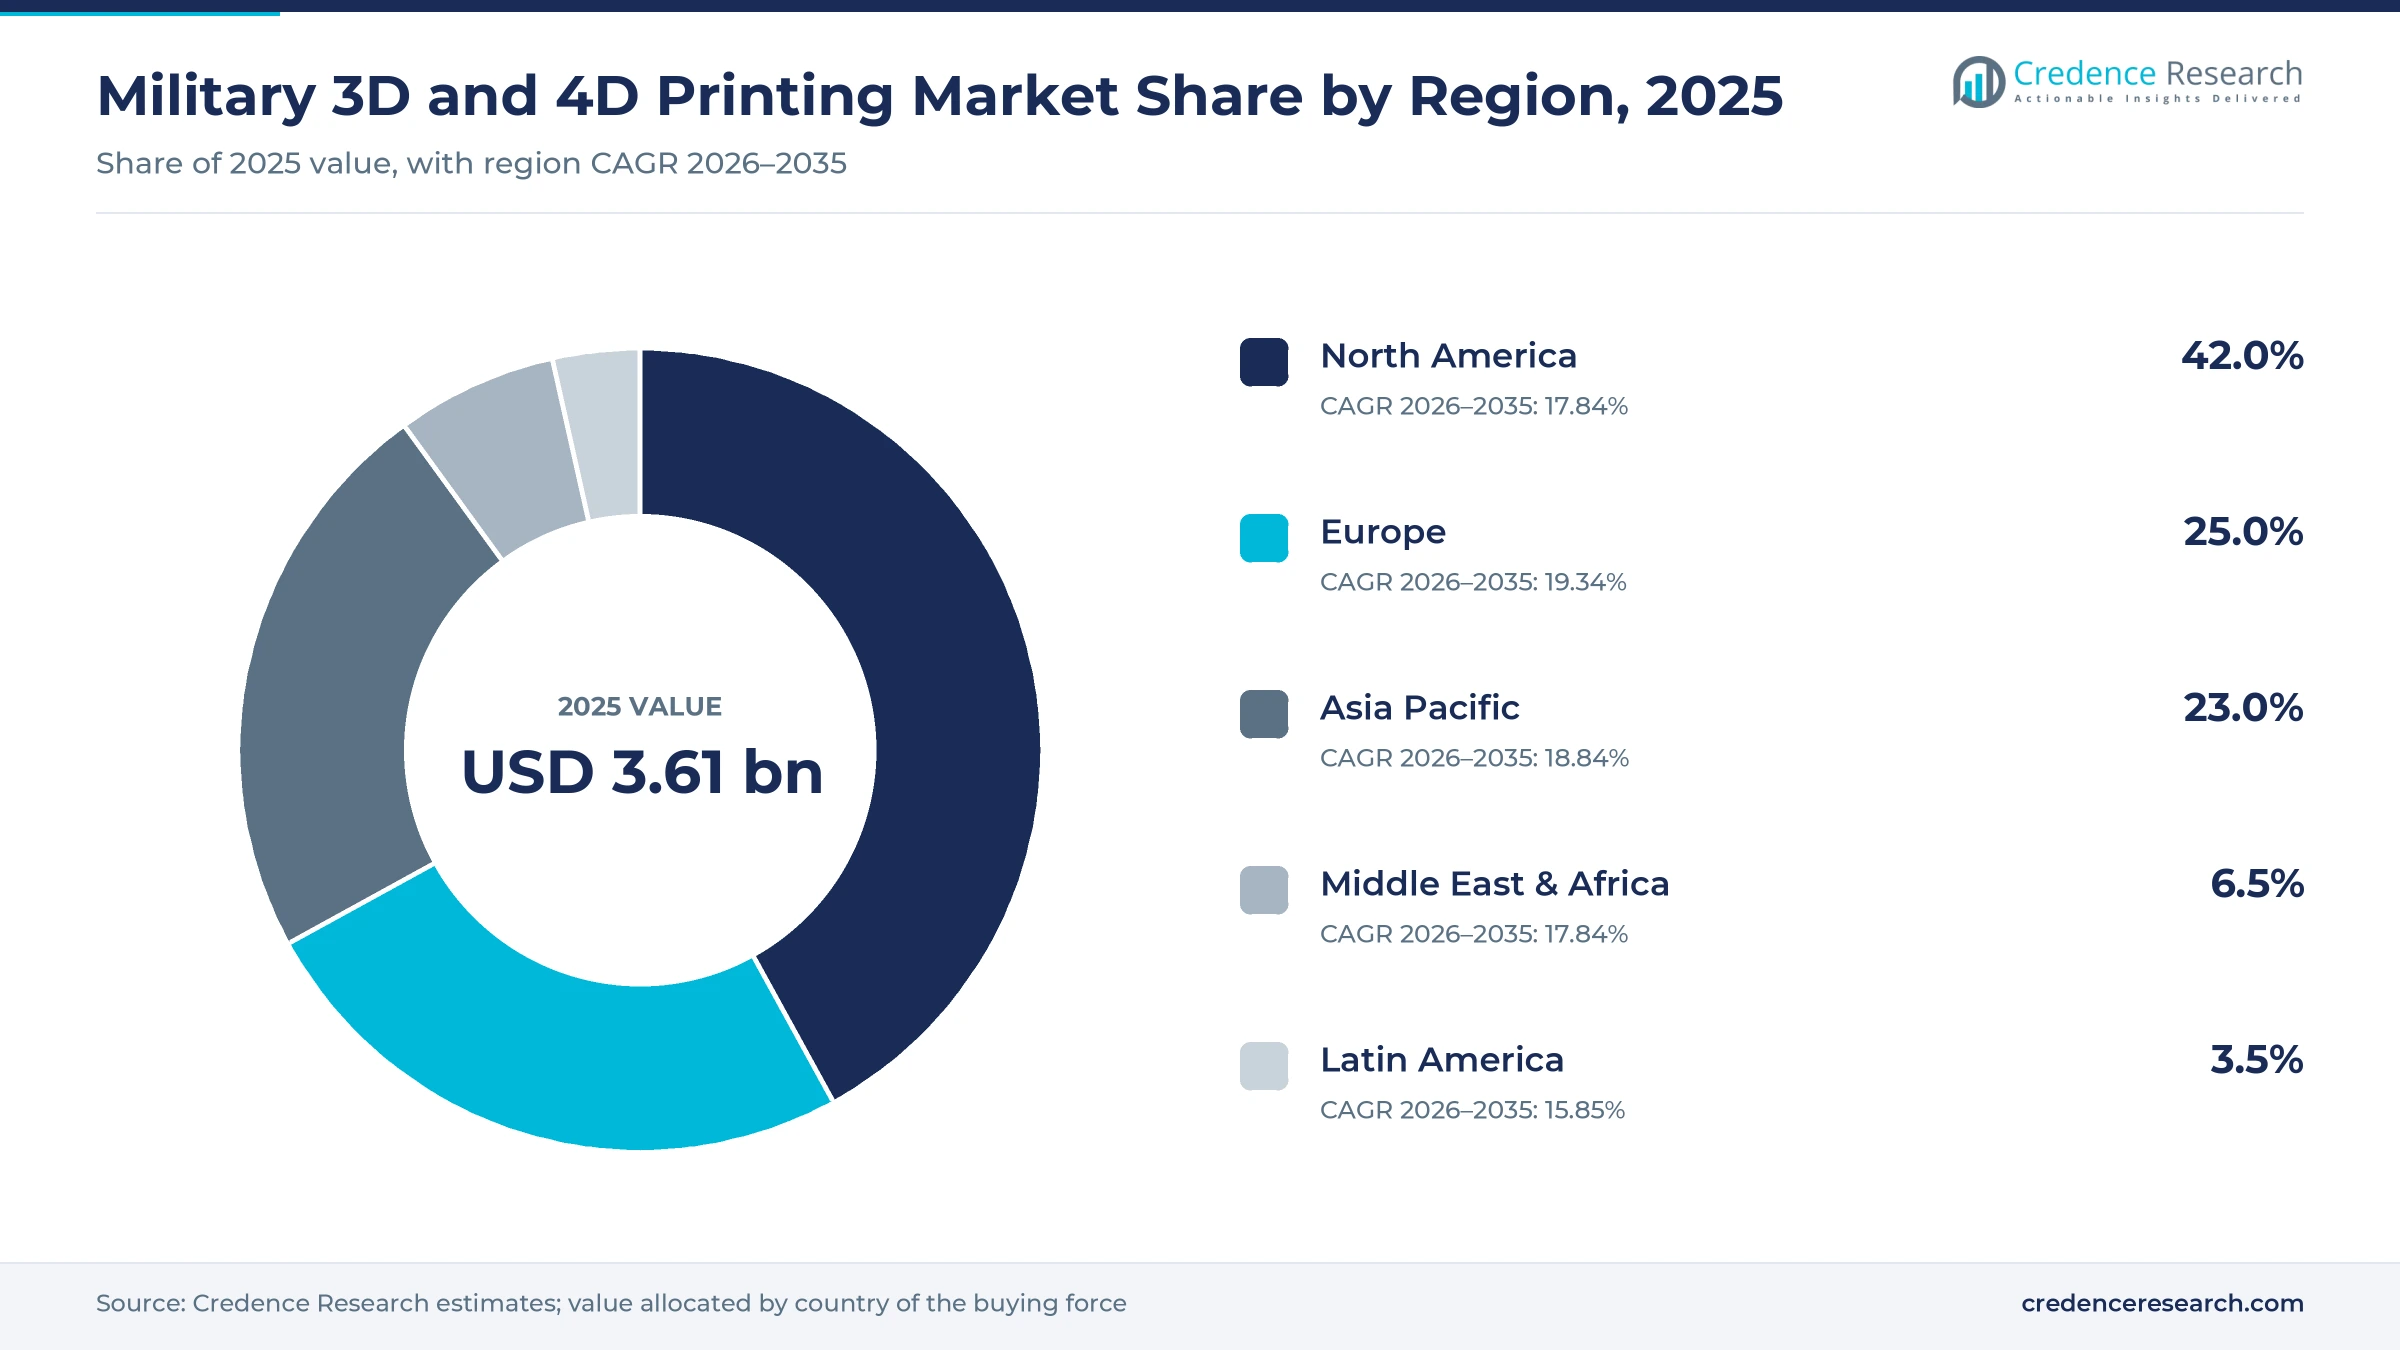
Value is allocated to the country of the buying force.
| Region | Share 2025 | CAGR 2026–2035 |
|---|---|---|
| North America | 42.0% | 17.84% |
| Europe | 25.0% | 19.34% |
| Asia Pacific | 23.0% | 18.84% |
| Middle East & Africa | 6.5% | 17.84% |
| Latin America | 3.5% | 15.85% |
Why does North America lead?
North America holds a 42.0% share in 2025 and grows at 17.84% a year. The US Navy, Air Force and Army fund qualification work, large printers and shipyard capacity, and the domestic-sourcing rule in the FY2026 defense bill favors US suppliers.
Why does Europe grow fastest?
Europe holds 25.0% and is the fastest-growing region at 19.34% a year. Rising defense budgets, spare-parts programs for fighter fleets and national printing frameworks in the United Kingdom and the Nordic countries support demand.
What drives Asia Pacific?
Asia Pacific holds 23.0% and grows at 18.84%. US forces print parts in Japan, Guam and South Korea during exercises, Australia supplies printed parts to the US submarine base, and AUKUS partners have installed printed metal parts on ships.
What about Latin America and the Middle East & Africa?
Latin America holds 3.5% and grows at 15.85%, mainly for maintenance of older aircraft. The Middle East & Africa region holds 6.5% and grows at 17.84%, supported by local manufacturing goals in Saudi Arabia and the UAE.
Contracts, Exercises and Acquisitions, 2025–2026
| Development | Status and why it matters |
|---|---|
| In August 2026, US Marines announced that they had printed more than 1,000 parts in two weeks aboard USS Essex during Pacific exercises. | Completed. Shows ship-based printing at scale. |
| In July 2026, Norsk Titanium was selected for an America Makes project to qualify its titanium process across US defense services. | Awarded. Speeds titanium part approval. |
| In June 2026, Norsk Titanium signed an award of about USD 4.2 million to produce titanium submarine parts over 18 months. | Awarded. Supports submarine supply. |
| In May 2026, Stratasys announced an agreement to acquire Markforged from Nano Dimension for about USD 42.5 million. | Announced. Consolidates defense printer supply. |
| In March 2026, AML3D signed an order of about USD 1.84 million for five submarine replacement components through the BlueForge Alliance. | Contracted. Adds allied wire-arc capacity. |
| In January 2026, 3D Systems announced an expansion of its Colorado site by up to 80,000 square feet for aerospace and defense. | Announced. Adds domestic capacity. |
| In December 2025, Velo3D signed a USD 32.6 million Defense Innovation Unit contract to qualify metal parts with the Navy. | Contracted. Funds large metal printing. |
| In August 2025, the US Air Force awarded 3D Systems a USD 7.65 million contract for a large-format metal printer demonstrator. | Contracted. Runs to September 2027. |
| In July 2025, Desktop Metal filed for Chapter 11 protection. | Restructuring. Raises vendor risk checks. |
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Printer Makers, Metal Specialists and Service Bureaus Compete for Qualified Programs
The market mixes large printer makers, metal process specialists and part producers. Ownership has changed often since 2024, and no share ranking is given because few suppliers report defense revenue separately.
Who are the main printer makers?
Stratasys Ltd. sells polymer printers and materials and runs Stratasys Direct, whose largest customers include military drone suppliers. Stratasys agreed in May 2026 to buy Markforged, Inc. from Nano Dimension for about USD 42.5 million, with closing expected in the second half of 2026. Markforged makes composite and metal printers used at bases and depots. 3D Systems Corporation supplies large-format metal printers to the US Air Force and is expanding production in Colorado. EOS GmbH supplies laser powder bed systems, and its printers have produced flown parts for the Saab Gripen fighter.
Who are the metal specialists?
Norsk Titanium US Inc. makes titanium parts with a wire-fed plasma process and is qualifying it for submarine and defense use. Optomec, Inc. sells directed-energy deposition systems used for repair. 3T Additive Manufacturing Ltd. is a UK producer of metal parts for aerospace and defense. American Elements Corporation supplies metal powders and materials. Engineering & Manufacturing Services, Inc. could not be confirmed as an active participant.
Which suppliers have restructured?
ExOne/Desktop Metal has been in Chapter 11 since July 2025, and ExOne's German and Japanese units were sold to a private investor. Velo3D and AML3D, not on the company list, hold US defense contracts for large metal parts.
How do suppliers compete?
Suppliers compete on qualified materials, build size, part quality records, cybersecurity and ability to operate in the field. Domestic manufacturing and clear ownership now count as heavily as printer price in defense tenders.
Frequently Asked Questions
How big is the military 3D and 4D printing market?
What is 4D printing in defense?
What drives the market?
Which material is largest?
Which region leads?
What holds the market back?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Component
- 1.2.1 Printers
- 1.2.2 Materials
- 1.2.3 Software
- 1.2.4 Services
- 1.3 By Material
- 1.3.1 Polymers
- 1.3.2 Metals
- 1.3.3 Composites
- 1.3.4 Ceramics
- 1.3.5 Smart Materials
- 1.4 By Technology
- 1.4.1 FDM
- 1.4.2 SLA
- 1.4.3 SLS
- 1.4.4 DMLS/SLM
- 1.4.5 EBM
- 1.4.6 Binder Jetting
- 1.4.7 4D Printing
- 1.5 By Application
- 1.5.1 Prototyping
- 1.5.2 Direct Manufacturing
- 1.5.3 Tooling
- 1.5.4 MRO/Repair
- 1.5.5 Rapid Restoration
- 1.6 By Platform
- 1.6.1 Airborne
- 1.6.2 Land
- 1.6.3 Naval
- 1.6.4 Space/Unmanned Systems
- 1.7 By End User
- 1.7.1 Army
- 1.7.2 Navy
- 1.7.3 Air Force
- 1.7.4 Marines/Special Forces
- 1.7.5 Defense Laboratories
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2025: USD 3.61 billion → 2035: USD 19.57 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Historical Period: 2018-2025
- 2.6.2 Base Year: 2025
- 2.6.3 Forecast Period: 2025-2035
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2025
- 3.3 Forecast Market Size, 2035
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Military 3D 4D Printing Market Trends and Developments
- 4.1 Historical Industry Development, 2018-2025
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Military 3D 4D Printing Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis, 2018-2025
- 5.2 Demand Forecast, 2025-2035
- 5.3 Production and Output Trend, 2018-2025
- 5.4 Production and Output Forecast, 2025-2035
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Military 3D 4D Printing Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends, 2018-2025
- 6.3 Pricing Outlook, 2025-2035
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Military 3D 4D Printing Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Military 3D 4D Printing Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Military 3D 4D Printing Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Military 3D 4D Printing Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Military 3D 4D Printing Market Outlook, 2025-2035
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2025: USD 3.61 billion → 2035: USD 19.57 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size, 2018-2025
- 11.1.4 Base-Year Market Size, 2025
- 11.2 Market Forecast, 2025-2035
- 11.2.1 Revenue Forecast to 2035
- 11.2.2 Volume Forecast to 2035
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Military 3D 4D Printing Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2025
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Component - Market Size and Forecast, 2025-2035
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size, 2018-2025
- 12.3.3 Revenue Forecast, 2025-2035
- 12.3.4 Volume Forecast, 2025-2035
- 12.3.5 Base-Year Market Share, 2025
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Printers
- 12.3.7.2 Materials
- 12.3.7.3 Software
- 12.3.7.4 Services
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Material - Market Size and Forecast, 2025-2035
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size, 2018-2025
- 12.4.3 Revenue Forecast, 2025-2035
- 12.4.4 Volume Forecast, 2025-2035
- 12.4.5 Base-Year Market Share, 2025
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Polymers
- 12.4.7.2 Metals
- 12.4.7.3 Composites
- 12.4.7.4 Ceramics
- 12.4.7.5 Smart Materials
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Technology - Market Size and Forecast, 2025-2035
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size, 2018-2025
- 12.5.3 Revenue Forecast, 2025-2035
- 12.5.4 Volume Forecast, 2025-2035
- 12.5.5 Base-Year Market Share, 2025
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 FDM
- 12.5.7.2 SLA
- 12.5.7.3 SLS
- 12.5.7.4 DMLS/SLM
- 12.5.7.5 EBM
- 12.5.7.6 Binder Jetting
- 12.5.7.7 4D Printing
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Application - Market Size and Forecast, 2025-2035
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size, 2018-2025
- 12.6.3 Revenue Forecast, 2025-2035
- 12.6.4 Volume Forecast, 2025-2035
- 12.6.5 Base-Year Market Share, 2025
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Prototyping
- 12.6.7.2 Direct Manufacturing
- 12.6.7.3 Tooling
- 12.6.7.4 MRO/Repair
- 12.6.7.5 Rapid Restoration
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 By Platform - Market Size and Forecast, 2025-2035
- 12.7.1 Segment Definition and Scope
- 12.7.2 Historical Market Size, 2018-2025
- 12.7.3 Revenue Forecast, 2025-2035
- 12.7.4 Volume Forecast, 2025-2035
- 12.7.5 Base-Year Market Share, 2025
- 12.7.6 Segment CAGR and Growth Drivers
- 12.7.7 Subsegment Market Size and Forecast
- 12.7.7.1 Airborne
- 12.7.7.2 Land
- 12.7.7.3 Naval
- 12.7.7.4 Space/Unmanned Systems
- 12.7.8 Subsegment Pricing and Adoption Trends
- 12.7.9 Leading Suppliers and Competition
- 12.7.10 Regional Demand and Opportunities
- 12.8 By End User - Market Size and Forecast, 2025-2035
- 12.8.1 Segment Definition and Scope
- 12.8.2 Historical Market Size, 2018-2025
- 12.8.3 Revenue Forecast, 2025-2035
- 12.8.4 Volume Forecast, 2025-2035
- 12.8.5 Base-Year Market Share, 2025
- 12.8.6 Segment CAGR and Growth Drivers
- 12.8.7 Subsegment Market Size and Forecast
- 12.8.7.1 Army
- 12.8.7.2 Navy
- 12.8.7.3 Air Force
- 12.8.7.4 Marines/Special Forces
- 12.8.7.5 Defense Laboratories
- 12.8.8 Subsegment Pricing and Adoption Trends
- 12.8.9 Leading Suppliers and Competition
- 12.8.10 Regional Demand and Opportunities
- 12.9 Segment Growth Comparison
- 12.10 Segment Attractiveness and Priority Matrix
Chapter 13 Global Military 3D 4D Printing End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Military 3D 4D Printing Geographic Market Outlook, 2025-2035
- 14.1 Regional Market Size and Share, 2025
- 14.2 Regional Market Forecast, 2025-2035
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Military 3D 4D Printing Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2025-2035
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Military 3D 4D Printing Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2025
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2025-2035
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Stratasys Ltd.
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 3D Systems Corporation
- 18.4 Engineering & Manufacturing Services, Inc.
- 18.5 Norsk Titanium US Inc.
- 18.6 3T Additive Manufacturing Ltd.
- 18.7 ExOne/Desktop Metal
- 18.8 EOS GmbH
- 18.9 Markforged, Inc.
- 18.10 Optomec, Inc.
- 18.11 American Elements Corporation
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

