
Spinosad Active Ingredient Market Overview:
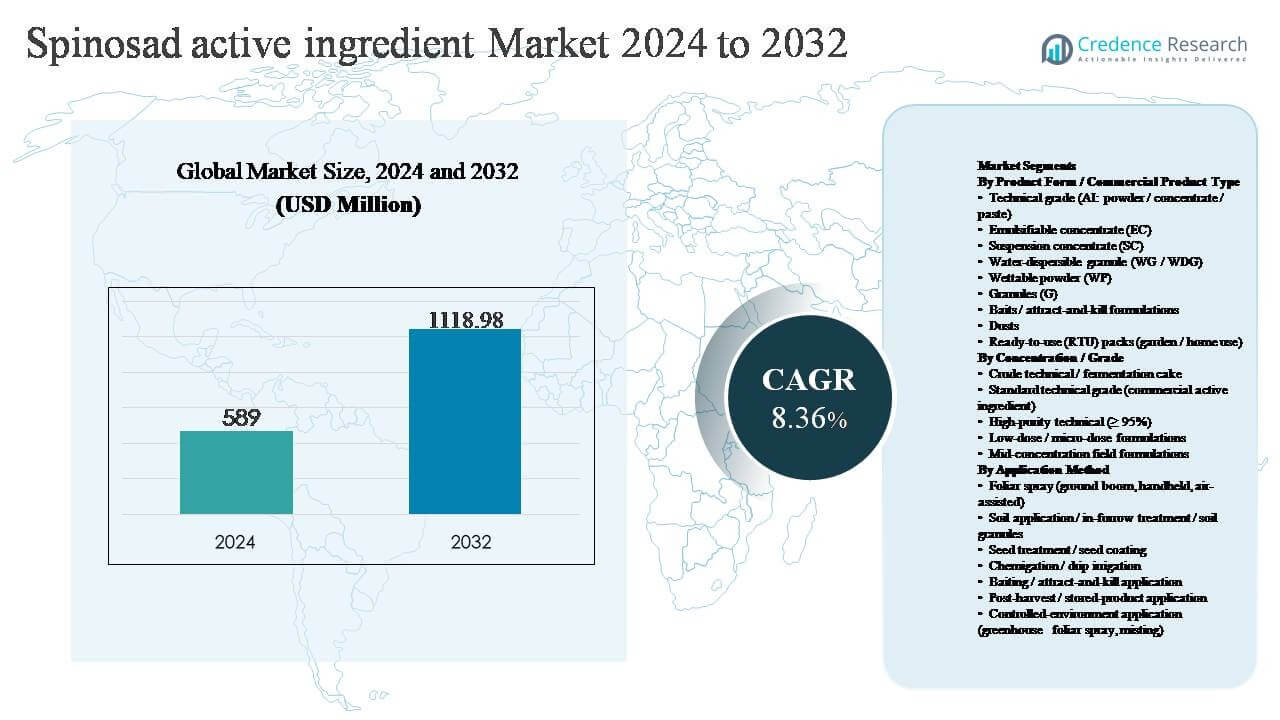
The global spinosad active ingredient market was valued at USD 589 million in 2024 and is anticipated to reach USD 1,118.98 million by 2032, expanding at a compound annual growth rate (CAGR) of 8.36% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Spinosad Active Ingredient Market Size 2024 | USD 589 million |
| Spinosad Active Ingredient Market, CAGR | 8.36% |
| Spinosad Active Ingredient Market Size 2032 | USD 1,118.98 million |
Spinosad Active Ingredient Market Insights
- Market growth is primarily driven by rising demand for low-residue, IPM-compatible insecticides, particularly in fruits, vegetables, and specialty crops, where spinosad’s selective mode of action and fermentation-based origin support regulatory compliance and export requirements.
- Key trends include a shift toward advanced formulations such as SC and WG/WDG, which together account for nearly 45-48% segment share, alongside growing adoption of low-dose formulations and expansion into greenhouse, urban pest control, and home-garden applications.
- The competitive landscape is shaped by leading agrochemical players focusing on formulation innovation, regulatory expansion, and regional partnerships, while fermentation complexity and intellectual property create moderate entry barriers for new participants.
- Regionally, North America leads with ~39% market share, followed by Europe (26-28%) and Asia Pacific (22-24%), with Asia Pacific emerging as the fastest-growing region due to expanding horticulture and tightening pesticide regulations.
Spinosad Active Ingredient Market Segmentation Analysis:
By Product Form / Commercial Product Type
By product form, suspension concentrate (SC) and water-dispersible granule (WG/WDG) formulations together represent the dominant sub-segment, accounting for approximately 45-48% of total market share. Their leadership is driven by superior formulation stability, reduced operator exposure, and compatibility with modern spraying equipment compared to emulsifiable concentrates and wettable powders. SC and WG/WDG products also support precise dosing and improved leaf adhesion, enhancing field efficacy. While baits, dusts, and RTU packs remain niche, they are increasingly adopted in urban pest control and home-garden applications due to ease of use and targeted pest action.
- For instance, BASF has commercialized numerous Suspension Concentrate (SC) formulations within its crop protection portfolio that meet industry standards for a 24-month shelf life at ambient temperatures. These formulations often undergo accelerated stability testing (e.g., 8 to 12 weeks at 40 °C) to predict long-term integrity, ensuring they maintain particle sizes between 3 and 5 micrometers to provide uniform spray distribution and prevent nozzle clogging."
By Concentration / Grade
By concentration and grade, standard technical grade spinosad (commercial AI) dominates the segment with around 50-55% market share, supported by its balance of cost efficiency, regulatory acceptance, and suitability for large-scale formulation. This grade is widely preferred by formulators supplying agricultural field applications. High-purity technical grades (≥95%) are gaining traction in export-oriented and specialty crop formulations, driven by residue compliance and premium crop requirements. Meanwhile, low-dose and micro-dose formulations are expanding steadily as growers seek reduced active ingredient loading while maintaining pest control performance.
- For instance, Corteva Agriscience manufactures commercial spinosad technical material derived from Saccharopolyspora spinosa fermentation with a typical assay range of 880-920 g/kg, enabling reliable downstream formulation into SC, WG, and bait products for large-scale agricultural use.
By Application Method
By application method, foliar spray applications hold the dominant position, accounting for nearly 60% of overall demand, driven by their effectiveness against lepidopteran pests and compatibility with integrated pest management programs. Ground boom and handheld foliar spraying remain standard across cereals, fruits, and vegetables due to rapid pest knockdown and flexible scheduling. Soil, seed treatment, and chemigation applications maintain moderate adoption in high-value crops, while baiting and attract-and-kill methods are expanding in horticulture and urban pest control. Controlled-environment applications are growing steadily with greenhouse crop intensification.
Key Growth Driver
Rising Demand for Bio-based and Reduced-Residue Insecticides
The spinosad active ingredient market is strongly driven by increasing demand for bio-based insecticides that offer high efficacy with low mammalian toxicity and minimal environmental persistence. Growers across fruits, vegetables, and specialty crops are shifting toward spinosad due to its natural fermentation origin and favorable residue profile, which supports compliance with strict maximum residue limits (MRLs) in export markets. Regulatory pressure on synthetic chemical insecticides, particularly organophosphates and certain pyrethroids, further accelerates substitution toward spinosad-based solutions. In addition, spinosad’s compatibility with integrated pest management (IPM) programs enhances its adoption, as it preserves beneficial insects when applied correctly. These factors collectively position spinosad as a preferred active ingredient for sustainable crop protection strategies.
- For instance, Certis Biologicals markets spinosad formulations that carry short regulatory re-entry intervals, with labeled REI values as low as 4 hours, enabling growers to resume field operations rapidly after application.
Expansion of High-Value Crop Cultivation
The growing cultivation of high-value crops such as fruits, vegetables, nuts, and greenhouse produce is a major driver for spinosad active ingredient demand. These crops require effective control of lepidopteran pests, thrips, and leafminers while maintaining premium quality and low residue levels. Spinosad’s selective mode of action and strong performance against resistant pest populations make it particularly suitable for these segments. Increased adoption of protected cultivation and intensive farming practices further supports demand, as spinosad performs well under controlled environments. Additionally, higher profit margins in specialty crops enable growers to invest in premium bio-insecticides, reinforcing spinosad’s market penetration.
- For instance, greenhouse trials referenced by Dow AgroSciences (now part of Corteva) demonstrated that spinosad maintains biological activity under controlled humidity and temperature regimes, achieving sustained pest control over 7-10 days after a single application in enclosed horticultural environments, supporting its suitability for intensive, high-value crop production systems.
Growth of Integrated Pest Management Adoption
Widespread adoption of integrated pest management systems significantly supports spinosad market growth. Agricultural stakeholders increasingly prioritize rotation of active ingredients with novel modes of action to manage insect resistance effectively. Spinosad’s unique nicotinic acetylcholine receptor activation differentiates it from conventional chemistries, making it a valuable rotation partner. Extension services, agronomists, and regulatory bodies actively promote IPM frameworks, further encouraging spinosad use. Its effectiveness at low application rates and compatibility with biological control agents strengthens its role in resistance-management strategies, particularly in regions facing chronic pest resistance challenges.
Key Trend & Opportunity
Shift Toward Advanced Formulations
A key trend in the spinosad market is the shift toward advanced formulations such as suspension concentrates and water-dispersible granules. These formats improve handling safety, shelf stability, and application efficiency compared to older emulsifiable or powder-based products. Formulation innovation enables better rainfastness, leaf adhesion, and controlled release, enhancing field performance. This trend creates opportunities for manufacturers to differentiate products through formulation technology rather than active ingredient changes. Demand for precision agriculture solutions further supports advanced formulations that integrate well with modern spraying systems.
- For instance, UPL Limited markets spinosad formulations, such as BADGE (45% SC), which are optimized for rapid uptake and effectiveness in orchard and vegetable systems. While high-performance Water Dispersible Granule (WG) formulations of spinosad are engineered by various manufacturers to achieve complete disintegration in water within 60 to 90 seconds, UPL primarily focuses on high-load suspension concentrates (SC) for these high-pressure spraying applications."
Expansion in Urban, Home, and Non-Crop Applications
The increasing focus on urban pest control, home gardening, and non-crop applications presents a growing opportunity for spinosad-based products. Ready-to-use packs and bait formulations are gaining traction due to ease of application and perceived safety among consumers. Public preference for reduced-toxicity pest control solutions in residential and public spaces supports broader adoption. This trend allows manufacturers to diversify beyond traditional agricultural markets and strengthen presence in retail and professional urban pest management channels.
- For instance, Nufarm Limited supplies spinosad-based products designed for turf, ornamentals, and amenity areas, with labeled re-entry intervals as short as 4 hours, enabling safe and rapid access to treated public and residential spaces.
Key Challenge
High Production and Formulation Costs
One of the primary challenges for the spinosad active ingredient market is its relatively high production cost compared to synthetic insecticides. Fermentation-based manufacturing requires controlled conditions, longer production cycles, and stringent quality controls, increasing overall costs. These factors can limit adoption in price-sensitive markets and staple crop segments. Additionally, advanced formulations further add to manufacturing and compliance expenses. Cost pressures may constrain penetration in developing regions where growers prioritize low-cost pest control solutions.
Resistance Risk and Application Sensitivity
Although spinosad offers a unique mode of action, improper or repeated use can lead to resistance development in certain pest populations. Managing resistance requires strict adherence to rotation guidelines, which may not be consistently followed by all growers. Moreover, spinosad’s performance is sensitive to application timing and environmental conditions, requiring technical knowledge for optimal results. Limited awareness and training can reduce efficacy perceptions, posing a challenge to sustained market growth despite strong underlying demand drivers.
Regional Analysis
North America
North America holds the leading position in the spinosad active ingredient market, accounting for approximately 38-40% of global market share. Strong adoption is driven by high penetration of integrated pest management programs, strict regulatory oversight on synthetic insecticides, and widespread cultivation of high-value fruits and vegetables. The United States dominates regional demand due to large-scale use in specialty crops, greenhouse production, and organic farming systems. Regulatory approvals and well-established extension services further support consistent application practices. Additionally, strong demand from professional turf, ornamental, and urban pest control segments reinforces North America’s leadership.
Europe
Europe represents around 26-28% of the global spinosad active ingredient market, supported by stringent environmental regulations and strong emphasis on sustainable agriculture. The region has actively phased out several conventional insecticides, accelerating adoption of bio-based alternatives such as spinosad. Demand is particularly strong in Mediterranean countries for fruits, vegetables, and vineyard applications, where residue compliance is critical. The growing organic farming footprint and high export orientation of European produce further drive usage. However, complex registration processes and country-specific regulatory requirements slightly moderate market expansion compared to North America.
Asia Pacific
Asia Pacific accounts for approximately 22-24% of global market share and is the fastest-growing regional market for spinosad active ingredients. Expansion is driven by rising horticultural output, increasing awareness of resistance management, and government initiatives promoting safer crop protection solutions. China and India are key contributors due to extensive vegetable and fruit cultivation, while Japan and Australia show strong adoption in high-value and controlled-environment agriculture. Growing export of residue-sensitive crops and gradual tightening of pesticide regulations are accelerating the shift toward bio-insecticides, positioning Asia Pacific as a major growth engine.
Latin America
Latin America holds about 7-9% of the global spinosad active ingredient market, supported by large-scale production of export-oriented crops such as fruits, vegetables, coffee, and sugarcane. Countries including Brazil, Mexico, and Chile are key demand centers, driven by the need for effective pest control solutions that meet international residue standards. Adoption is strongest in high-value crop segments, while price sensitivity limits broader penetration in staple crops. Increasing focus on resistance management and sustainable farming practices is gradually improving spinosad uptake across the region.
Middle East & Africa
The Middle East & Africa region accounts for approximately 4-6% of global market share, representing an emerging but steadily growing market. Demand is primarily driven by horticulture, greenhouse cultivation, and pest control in arid and semi-arid environments. Countries in the Gulf Cooperation Council and parts of North Africa show rising adoption due to increased protected agriculture and import-oriented quality standards. In sub-Saharan Africa, uptake remains limited by cost sensitivity and distribution constraints, although donor-supported sustainable agriculture initiatives are improving awareness and gradual market penetration.
Spinosad Active Ingredient Market Segmentations:
By Product Form / Commercial Product Type
- Technical grade (AI: powder / concentrate / paste)
- Emulsifiable concentrate (EC)
- Suspension concentrate (SC)
- Water-dispersible granule (WG / WDG)
- Wettable powder (WP)
- Granules (G)
- Baits / attract-and-kill formulations
- Dusts
- Ready-to-use (RTU) packs (garden / home use)
By Concentration / Grade
- Crude technical / fermentation cake
- Standard technical grade (commercial active ingredient)
- High-purity technical (≥ 95%)
- Low-dose / micro-dose formulations
- Mid-concentration field formulations
By Application Method
- Foliar spray (ground boom, handheld, air-assisted)
- Soil application / in-furrow treatment / soil granules
- Seed treatment / seed coating
- Chemigation / drip irrigation
- Baiting / attract-and-kill application
- Post-harvest / stored-product application
- Controlled-environment application (greenhouse foliar spray, misting)
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The spinosad active ingredient market is moderately consolidated, characterized by the presence of a limited number of technology owners alongside regional formulators and distributors. Leading players compete primarily on formulation innovation, regulatory approvals, and geographic expansion rather than price alone, due to the fermentation-based production complexity of spinosad. Companies with strong intellectual property portfolios and established manufacturing capabilities maintain a competitive advantage, particularly in supplying high-purity technical grades and advanced formulations. Strategic partnerships with local formulators enable wider market reach across Asia Pacific and Latin America. Competition is also shaped by investments in resistance-management positioning, product stewardship programs, and compatibility with integrated pest management systems. As regulatory scrutiny on conventional insecticides intensifies, established players continue to strengthen brand differentiation through sustainability credentials, consistent supply quality, and expanded registrations across high-value crop segments.
Key Player Analysis
- BASF SE
- Bayer CropScience
- Corteva Agriscience
- Syngenta Group
- FMC Corporation
- UPL Limited
- ADAMA
- Nufarm Limited
- Sumitomo Chemical / Certis entities
- Marrone Bio Innovations
Recent Developments
- In August 2025, Syngenta announced enhanced biological research initiatives, including the application of artificial intelligence to multi-omics datasets to identify traits for next-generation biostimulants and biologicals; this underscores its commitment to expanding biological and microbial-derived crop protection tools that relate to natural actives like spinosad.
- In May 2024, FMC Corporation announced a research agreement with AgroSpheres in May 2024 aimed at accelerating the discovery and development of novel bioinsecticides using advanced formulation and delivery technologies such as biodegradable micro-encapsulation. This initiative supports FMC’s broader commitment to biological crop protection tools that can complement natural insecticide actives.
Report Coverage
The research report offers an in-depth analysis based on Product Form / Commercial Product Type, Concentration / Grade, Application Method and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Adoption of spinosad will continue to expand as regulatory pressure on conventional insecticides accelerates globally.
- Demand will increase in high-value crops as growers prioritize residue compliance and export quality standards.
- Advanced formulations such as suspension concentrates and water-dispersible granules will gain wider acceptance.
- Low-dose and micro-dose formulations will see stronger uptake due to efficiency and resistance-management benefits.
- Integrated pest management programs will further strengthen spinosad’s role in rotation strategies.
- Greenhouse and controlled-environment agriculture will emerge as key growth application areas.
- Urban pest control and home-garden segments will contribute incremental demand through ready-to-use products.
- Manufacturers will focus on improving fermentation efficiency to enhance cost competitiveness.
- Strategic partnerships with regional formulators will support deeper penetration in emerging markets.
- Continued stewardship and resistance-management education will be critical for sustaining long-term market growth.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the spinosad active ingredient, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the spinosad active ingredient projected to grow between 2024 and 2032?
Which spinosad active ingredient segment held the largest share in 2024?
What are the primary factors fueling the growth of the spinosad active ingredient market?
Who are the leading companies in the spinosad active ingredient market?
Which region commanded the largest share of the spinosad active ingredient market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 589 million → 2032: USD 1,118.98 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Spinosad Active Ingredient Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Spinosad Active Ingredient Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Spinosad Active Ingredient Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Spinosad Active Ingredient Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Spinosad Active Ingredient Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Spinosad Active Ingredient Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Spinosad Active Ingredient Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Spinosad Active Ingredient Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 589 million → 2032: USD 1,118.98 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Spinosad Active Ingredient Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Spinosad Active Ingredient Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Spinosad Active Ingredient Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Spinosad Active Ingredient Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

