
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Seed Treatment Market Size 2024 | USD 7,427.40 million |
| Seed Treatment Market, CAGR | 12.81% |
| Seed Treatment Market Size 2032 | USD 20,814.16 million |
Market Overview
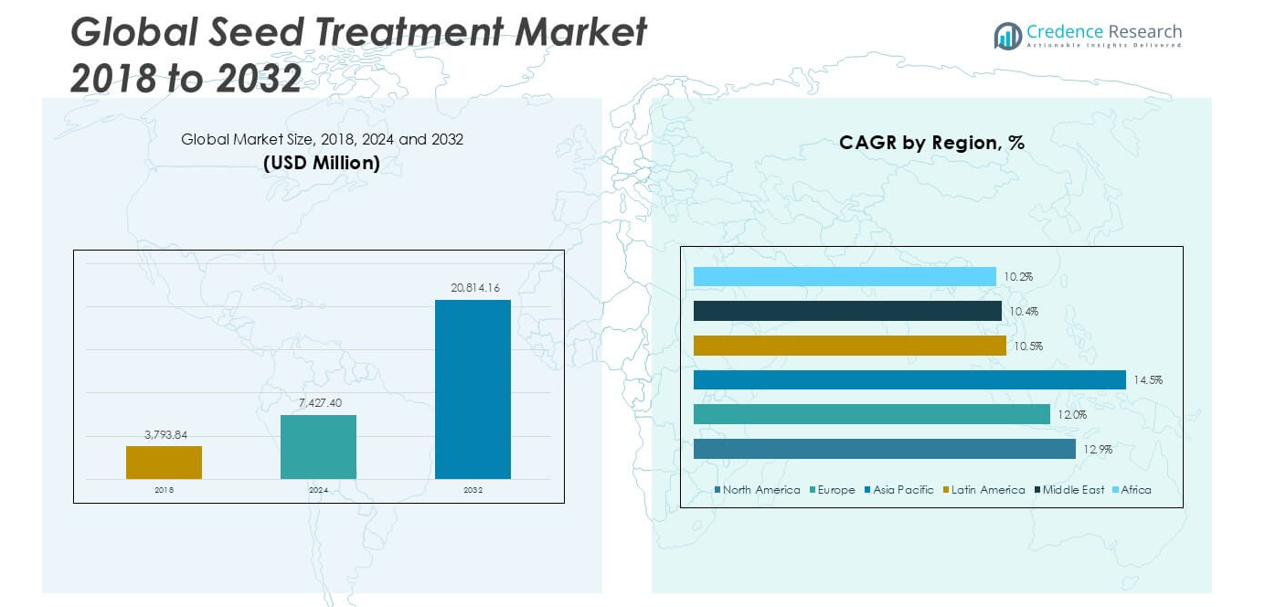
The Seed Treatment Market was valued at USD 3,793.84 million in 2018 and grew to USD 7,427.40 million in 2024. It is anticipated to reach USD 20,814.16 million by 2032, reflecting a compound annual growth rate (CAGR) of 12.81% during the forecast period.
The Seed Treatment Market is experiencing strong growth driven by the increasing need for higher crop yields, rising incidences of seed-borne and soil-borne diseases, and the global push for sustainable agriculture. Advances in seed treatment formulations, such as the development of combination products that include fungicides, insecticides, and micronutrients, enhance crop protection and improve germination rates. Regulatory emphasis on minimizing chemical use and protecting the environment encourages the adoption of targeted seed treatments over conventional methods. Farmers are increasingly recognizing the cost-efficiency and yield benefits of seed treatment technologies, which support better crop establishment and resilience against abiotic stress. The trend toward precision agriculture and integration of biological seed treatments is further shaping the market, as growers seek environmentally friendly solutions that meet regulatory standards and consumer expectations for food safety. This evolving landscape positions the Seed Treatment Market as a critical component in modern crop management strategies.
The Seed Treatment Market demonstrates significant regional diversity, with North America, Europe, and Asia Pacific serving as major centers of growth. North America benefits from advanced farming practices and widespread adoption of innovative seed protection technologies, while Europe emphasizes regulatory compliance and sustainable agriculture. Asia Pacific is witnessing rapid expansion due to growing commercial agriculture in countries like China and India. Latin America, the Middle East, and Africa are emerging markets, driven by increasing awareness and investments in crop productivity. Key players driving the Seed Treatment Market include Corteva Agriscience, Syngenta AG, and BASF SE. These companies lead through extensive research, diverse product portfolios, and global distribution networks. Bayer AG also holds a prominent position, focusing on next-generation solutions and digital agriculture platforms. Their ongoing investments in innovation and strategic partnerships help set industry standards and address the evolving needs of global agriculture.
Market Insghts
- The Seed Treatment Market was valued at USD 3,793.84 million in 2018, reached USD 7,427.40 million in 2024, and is projected to achieve USD 20,814.16 million by 2032, at a CAGR of 12.81%.
- Rising demand for higher crop yields and improved seed protection technologies is fueling market growth globally.
- Adoption of sustainable agriculture practices is encouraging the use of biological seed treatments alongside conventional synthetic chemicals.
- Integration of precision agriculture tools and digital platforms is a strong trend, enabling targeted seed application and improving farm efficiency.
- Major industry players such as Corteva Agriscience, Syngenta AG, BASF SE, and Bayer AG lead the competitive landscape with broad portfolios and continuous innovation.
- Complex regulatory frameworks and low awareness among farmers in emerging regions remain key restraints for the market, challenging product approval and adoption.
- North America, Europe, and Asia Pacific dominate the market, with the United States, China, and Germany representing major country-level growth centers, while Latin America, the Middle East, and Africa are seeing increased adoption and investment.
Market Drivers
Rising Demand for Enhanced Crop Yields Fuels Market Expansion
The drive to achieve higher agricultural productivity remains a central factor in the Seed Treatment Market. Farmers worldwide focus on improving crop yields to address the growing population and increased food demand. Seed treatments offer an effective solution by safeguarding seeds during early development stages, ensuring better germination and healthy plant growth. The use of treated seeds allows for uniform crop emergence and improved vigor. It helps reduce crop losses caused by pests and diseases, which directly contributes to higher output. Increasing awareness among farmers about the benefits of seed treatment further accelerates adoption across major agricultural economies.
- For instance, Syngenta reported that farmers using its Cruiser-treated maize seeds in Brazil observed an increase in average plant stands by 1,000 plants per hectare compared to untreated seeds.
Advancements in Seed Treatment Technologies Propel Growth
Technological progress in seed treatment formulations and application methods boosts the Seed Treatment Market. Modern seed treatments now include combinations of fungicides, insecticides, and micronutrients that protect against multiple threats and provide essential nutrients. It has enabled the development of products that deliver targeted protection without harming non-target organisms. Adoption of polymer coatings and precision application techniques ensures consistent coverage and minimized wastage. These innovations support sustainable agriculture by reducing the need for repeated field applications of agrochemicals. Continuous research and development by leading manufacturers drive the availability of next-generation solutions.
- For instance, BASF introduced Poncho/VOTiVO 2.0, which achieved a 40% reduction in application rates of active ingredients per hectare while maintaining pest control efficacy.
Stringent Regulations and Environmental Considerations Shape Adoption
Stringent regulations regarding chemical usage in agriculture have significant influence on the Seed Treatment Market. Governments and regulatory agencies enforce standards to limit the environmental impact of crop protection products. It encourages the use of safer, more efficient seed treatments as an alternative to broad-spectrum chemicals. Companies invest in developing eco-friendly biological treatments and low-toxicity products that comply with current and future regulations. This regulatory landscape supports the adoption of innovative solutions that balance effective pest control with minimal environmental footprint.
Shift Toward Integrated Pest Management and Precision Agriculture
The market is seeing a transition toward integrated pest management practices and precision agriculture, both of which highlight the value of seed treatment. Growers now prioritize data-driven farming and solutions that minimize resource inputs while maximizing crop health. It allows for more sustainable and targeted use of crop protection, aligning with modern agricultural practices. The adoption of precision sowing equipment and digital monitoring tools improves treatment effectiveness and crop outcomes. This trend supports long-term market stability and drives continuous innovation in seed treatment solutions.
Market Trends
Adoption of Biological Seed Treatments Gains Momentum
The growing interest in sustainable agriculture is driving demand for biological seed treatments across the Seed Treatment Market. Companies are investing in natural solutions, including microbial inoculants and plant extracts, to reduce reliance on synthetic chemicals. It aligns with consumer preferences for residue-free crops and supports regulatory compliance with environmental standards. The effectiveness of biological seed treatments in promoting plant health and resilience attracts both large-scale and smallholder farmers. Continued advancements in formulation technology improve product stability and shelf life. Expansion of research initiatives contributes to the development of innovative biological solutions tailored for specific crops and local conditions.
- For instance, Corteva Agriscience’s Utrisha N microbial seed treatment delivered an average yield increase of 0.6 tons per hectare in field trials for wheat and maize.
Integration of Precision Agriculture and Digital Tools
The integration of precision agriculture technologies is emerging as a key trend in the Seed Treatment Market. Farmers use digital tools, such as seed sensors and variable rate applicators, to ensure optimal seed coverage and dosage. It enhances efficiency, reduces product waste, and supports more uniform crop establishment. Companies develop seed treatments that are compatible with precision application systems, ensuring seamless adoption at the farm level. The growing role of data analytics in monitoring seed performance informs product improvements and best practices. These digital advancements help maximize return on investment for growers while supporting sustainable farming objectives.
- For instance, Bayer deployed its FieldView digital platform on more than 25 million hectares globally, enabling farmers to monitor seed performance and optimize treatment application rates.
Demand for Combination and Customized Seed Treatments Increases
The trend toward combination seed treatments, which include fungicides, insecticides, and micronutrients in a single formulation, is strengthening in the Seed Treatment Market. Growers seek comprehensive protection against multiple threats while ensuring ease of use. It reduces operational complexity and supports better crop outcomes through targeted protection. Customized seed treatments designed for specific crops or regions help address unique agronomic challenges. Companies are expanding their product portfolios to include tailored solutions that improve compatibility and performance under varying environmental conditions. This approach enables flexible and efficient crop management for farmers worldwide.
Focus on Regulatory Compliance and Food Safety Standards Intensifies
The Seed Treatment Market is experiencing a heightened focus on meeting regulatory compliance and food safety standards. Governments worldwide introduce stricter regulations to manage pesticide residues and environmental impact. It drives the development of safer, low-toxicity seed treatment products that align with global food safety goals. The traceability of treated seeds through the supply chain is improving, supporting transparency and quality assurance. Increased collaboration between manufacturers, regulatory bodies, and industry stakeholders promotes responsible product stewardship. This evolving regulatory environment fosters innovation and reinforces market credibility.
Market Challenges Analysis
Complex Regulatory Environment Restricts Product Development
The Seed Treatment Market faces significant challenges due to complex and evolving regulatory frameworks across major agricultural regions. Regulatory agencies continue to tighten rules concerning the registration and use of seed treatment chemicals, making product approval a lengthy and costly process. It often leads to delays in the launch of innovative solutions and restricts market access for smaller companies. Differing regional regulations create hurdles for global companies seeking to standardize their product offerings. The need to invest in extensive safety and efficacy testing further strains resources for manufacturers. Compliance demands also pressure companies to continuously reformulate products to meet changing standards.
Low Farmer Awareness and Limited Access Hinder Market Penetration
Limited awareness among farmers, especially in emerging economies, restricts the adoption of seed treatment technologies. Many growers lack access to reliable information and training on the benefits and application of advanced seed treatments. It creates a gap between technology availability and practical usage in the field. Inadequate distribution networks and high product costs can deter smallholder farmers from investing in treated seeds. Resistance to change and traditional farming practices further slow market expansion in some regions. The Seed Treatment Market must address these barriers to unlock its full growth potential.
Market Opportunities
Expansion of Biological Solutions Opens New Growth Avenues
The Seed Treatment Market is well-positioned to benefit from the rapid development and commercialization of biological seed treatment products. Growing demand for sustainable agriculture drives investments in bio-based solutions such as microbial inoculants, plant extracts, and biostimulants. It allows manufacturers to differentiate their portfolios while addressing regulatory pressures and consumer concerns around chemical residues. The potential to improve crop resilience and enhance yields with minimal environmental impact makes biological seed treatments attractive for large-scale and smallholder farmers alike. Ongoing research and innovation will continue to unlock new applications and crop-specific formulations. Companies that focus on these solutions stand to capture emerging market segments.
Digitalization and Precision Agriculture Present Untapped Potential
The integration of digital technologies and precision agriculture creates new opportunities for the Seed Treatment Market. Adoption of digital platforms, variable rate application systems, and data-driven decision tools enables farmers to optimize seed treatment use and improve overall farm productivity. It helps growers monitor seed performance, customize treatments, and track outcomes more effectively. Partnerships between seed companies, agtech firms, and research institutions can accelerate the development of advanced application techniques. These advancements support resource efficiency, sustainability, and higher returns for both producers and end-users. The shift toward smart agriculture is expected to drive long-term market growth.
Market Segmentation Analysis:
By Type:
The market features synthetic chemicals and biologicals. Synthetic chemicals dominate current usage, offering broad-spectrum protection and proven efficacy against a range of seed-borne and soil-borne pathogens. Their long-standing application, cost-effectiveness, and compatibility with large-scale farming practices support widespread adoption. Biologicals are gaining traction, driven by increasing demand for environmentally friendly alternatives and stringent regulatory requirements. Innovations in microbial and plant-based formulations are broadening the application of biological seed treatments across diverse crop types.
- For instance, Valent BioSciences expanded the use of its MycoApply microbial inoculants to 5 million hectares of soybean and corn in North America, reflecting the growing shift to biologicals.
By Function:
The Seed Treatment Market encompasses fungicides, insecticides, and nematicides. Fungicides represent a major share due to the prevalence of fungal diseases affecting seed quality and crop emergence. Their targeted use during the early growth stages helps maintain healthy stands and maximizes yield potential. Insecticides form the next significant segment, providing essential protection against seed and soil-dwelling insects that can damage seedlings. Nematicides are a smaller segment but play a critical role where nematode infestations threaten root health and crop productivity. Each functional segment is witnessing advances in formulation technology that enhance performance and minimize environmental risks.
- For instance, FMC’s ILeVO seed treatment demonstrated up to a 7% increase in soybean yield under high nematode pressure in multi-year field studies.
By Stage of Seed:
The market is segmented into on-farm and off-farm seed treatments. On-farm treatments allow growers flexibility and control over the timing and choice of products, supporting customization based on local pest pressures and agronomic conditions. Off-farm seed treatments, conducted by seed companies or specialized applicators, ensure precise dosing, high-quality coverage, and strict adherence to safety standards. This segment appeals to commercial growers seeking consistent and reliable seed protection with minimal operational complexity. The rise of contract farming and professional seed treatment services is expected to expand the off-farm segment further.
Segments:
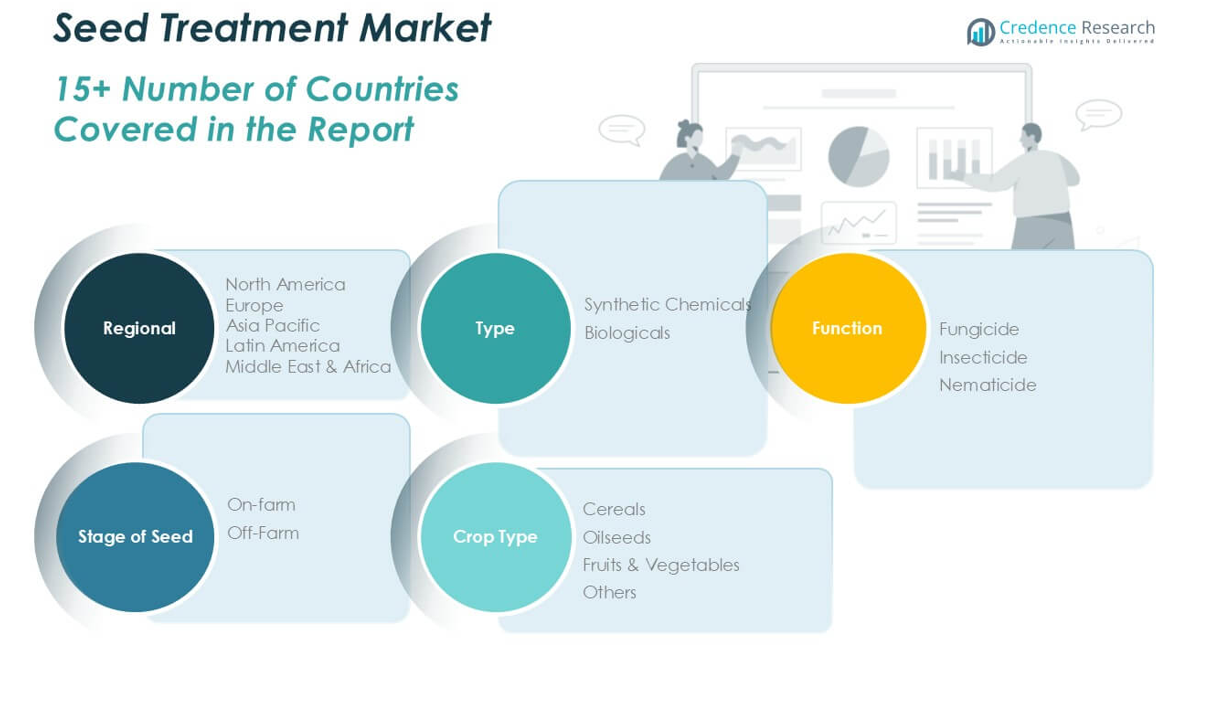
Based on Type:
- Synthetic Chemicals
- Biologicals
Based on Function:
- Fungicide
- Insecticide
- Nematicide
Based on Stage of Seed:
- On-farm
- Off-Farm
Based on Crop Type:
- Cereals
- Oilseeds
- Fruits & Vegetables
- Others
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis
North America Seed Treatment Market
North America Seed Treatment Market grew from USD 1,621.68 million in 2018 to USD 3,141.16 million in 2024 and is projected to reach USD 8,827.60 million by 2032, reflecting a compound annual growth rate (CAGR) of 12.9%. North America is holding a 38% market share. The United States leads the region, supported by advanced agricultural technology, high adoption of commercial seed treatment products, and a focus on sustainable farming. Canada also contributes significantly, driven by expanding grain and oilseed production. Market growth is supported by investments in precision agriculture and a strong network of seed distributors. The presence of major industry players reinforces the region’s competitive advantage.
Europe Seed Treatment Market
Europe Seed Treatment Market grew from USD 1,117.51 million in 2018 to USD 2,111.85 million in 2024 and is anticipated to reach USD 5,585.12 million by 2032, at a CAGR of 12.0%. Europe accounts for a 24% market share, with Germany, France, and the United Kingdom as key contributors. The region’s strict regulatory environment accelerates the shift toward biological seed treatments and integrated pest management solutions. Farmers in Europe prioritize sustainable practices, which drives demand for advanced, environmentally friendly products. Research initiatives and government incentives foster continued innovation and market expansion.
Asia Pacific Seed Treatment Market
Asia Pacific Seed Treatment Market grew from USD 741.09 million in 2018 to USD 1,570.71 million in 2024 and is set to reach USD 4,976.98 million by 2032, growing at the highest CAGR of 14.5%. Asia Pacific represents a 21% market share, led by China, India, and Australia. Rising food security concerns, rapid growth in commercial agriculture, and ongoing modernization of farming practices propel demand in this region. The adoption of seed treatment products is further driven by government support and education programs for farmers. Expanding acreage for key crops enhances market prospects.
Latin America Seed Treatment Market
Latin America Seed Treatment Market grew from USD 137.87 million in 2018 to USD 265.55 million in 2024 and is forecast to reach USD 632.60 million by 2032, registering a CAGR of 10.5%. Latin America holds a 3% market share, with Brazil and Argentina leading adoption. The expansion of soybean, corn, and cotton cultivation strengthens market fundamentals. Favorable climate conditions and increasing investment in crop protection technologies stimulate demand for both synthetic and biological seed treatments. Export-oriented agriculture also supports market development.
Middle East Seed Treatment Market
Middle East Seed Treatment Market grew from USD 104.16 million in 2018 to USD 186.05 million in 2024 and is estimated to reach USD 438.13 million by 2032, reflecting a CAGR of 10.4%. The Middle East accounts for a 2% market share. Countries such as Saudi Arabia and the United Arab Emirates invest in agricultural innovation and sustainable food production. Limited arable land and water scarcity drive demand for high-efficiency seed treatment solutions. Regional governments focus on modernizing the agricultural sector, opening opportunities for advanced crop protection products.
Africa Seed Treatment Market
Africa Seed Treatment Market grew from USD 71.53 million in 2018 to USD 152.08 million in 2024 and is projected to reach USD 353.74 million by 2032, at a CAGR of 10.2%. Africa contributes a 2% market share, with South Africa, Nigeria, and Egypt emerging as leading countries. Efforts to improve food security and promote the adoption of improved seeds support steady market growth. The transition from traditional to commercial agriculture is underway, with emphasis on crop productivity and resilience. Regional partnerships and training programs aim to boost awareness and utilization of seed treatment technologies.
Key Player Analysis
- Corteva Agriscience
- BASF SE
- Sumitomo Chemical Co. Ltd.
- Germain's Seed Technology, Inc.
- FMC Corporation
- Syngenta AG
- NuFarm Ltd.
- Bayer AG
- Croda International PLC
- UPL Ltd.
Competitive Analysis
The Seed Treatment Market features a highly competitive landscape shaped by leading players such as Corteva Agriscience, Syngenta AG, BASF SE, Bayer AG, FMC Corporation, UPL Ltd., Sumitomo Chemical Co. Ltd., Nufarm Ltd., Croda International PLC, and Germain’s Seed Technology, Inc. These companies command strong global presence through extensive product portfolios, broad distribution networks, and advanced research capabilities. They continuously invest in the development of innovative seed treatment solutions, including both synthetic and biological formulations, to address evolving farmer needs and regulatory requirements. Strategic collaborations, acquisitions, and partnerships support the expansion of market reach and technological advancement. Key players prioritize sustainability by introducing environmentally friendly products and focusing on integrated pest management practices. Their R&D efforts aim to enhance efficacy, crop safety, and ease of application, positioning them as preferred suppliers for commercial growers. The competitive environment also drives investment in digital agriculture platforms, enabling precision seed treatment and data-driven decision-making. These companies maintain brand reputation through robust customer support, farmer education initiatives, and strict quality control measures. Their commitment to innovation, sustainability, and customer value solidifies their leadership in the Seed Treatment Market, setting industry benchmarks and supporting continued global market growth.
Recent Developments
- In January 2023, Bayer formed a new partnership with Oerth Bio to enhance crop protection technology and create more eco-friendly crop protection solutions.
- In November 2022, Certis Belchim BV acquired the assets of Henry Manufacturing Limited in New Zealand. This includes its portfolio and pipeline of potassium fatty-acid salts, which have various applications in crop protection.
- In June 2022, AgriNova New Zealand Ltd was acquired by ADAMA Ltd. With this acquisition, ADAMA expanded its product line in the New Zealand market.
Market Concentration & Characteristics
The Seed Treatment Market exhibits a moderately high level of market concentration, with a few major multinational corporations commanding significant global share through well-established brands and extensive distribution networks. It is defined by strong innovation cycles, driven by advances in both synthetic and biological formulations tailored to diverse crop needs. The market is characterized by rapid technological evolution, with emphasis on sustainable agriculture, regulatory compliance, and farmer-centric solutions. Product differentiation is achieved through integrated pest management, targeted application methods, and digital technology integration for precision farming. The Seed Treatment Market also shows a dynamic shift toward environmentally friendly products and biological treatments, reflecting growing regulatory scrutiny and consumer demand for sustainable agriculture. It features high barriers to entry, including strict regulatory requirements and significant investment in research and development. Competitive dynamics encourage collaboration, strategic partnerships, and continuous portfolio expansion to address regional variations and evolving grower needs.
Report Coverage
The research report offers an in-depth analysis based on Type, Function, Stage of Seed, Crop Type and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The demand for seed treatment products will increase as farmers seek higher crop yields and improved plant health.
- Advancements in biological seed treatment solutions will gain traction due to regulatory support and sustainability goals.
- The adoption of combination seed treatments will rise as integrated pest and disease management strategies become standard.
- Precision agriculture technologies will drive the use of tailored seed treatment solutions for specific crop and soil needs.
- Growing concerns about chemical residues will accelerate the shift toward eco-friendly and residue-free seed treatment products.
- Climate change and unpredictable weather patterns will increase reliance on seed treatments that enhance stress tolerance.
- Seed treatment companies will focus on expanding portfolios to include micronutrient and biostimulant formulations.
- Strategic collaborations and partnerships among seed companies, agrochemical firms, and research organizations will intensify.
- Emerging markets in Asia-Pacific, Latin America, and Africa will offer significant growth opportunities for seed treatment providers.
- Continuous research and development will lead to innovative products that address evolving challenges in crop protection.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Need for Higher Crop Yields and Food Security
Global population growth and increasing food demand are pushing farmers to maximize productivity. Seed treatments help ensure better germination, uniform crop emergence, and healthier plant stands, directly supporting higher yields and food security.
Advancements in Seed Treatment Technologies
Innovations such as combination products (fungicides, insecticides, micronutrients) and precision application methods are improving efficacy and reducing environmental impact. These advancements make seed treatments more attractive and effective for modern agriculture.
Shift Toward Sustainable and Biological Solutions
Regulatory pressures and consumer demand for residue-free, eco-friendly crops are accelerating the adoption of biological seed treatments. These solutions help farmers comply with strict regulations while supporting sustainable farming practices.
Integration of Precision Agriculture and Digital Tools
The adoption of digital platforms and precision agriculture equipment enables targeted, efficient seed treatment application. This not only reduces waste and costs but also improves crop outcomes and supports data-driven farm management.
Stringent Regulatory Environment
Tighter regulations on chemical use in agriculture are encouraging the development and adoption of safer, low-toxicity seed treatments. This regulatory landscape is driving innovation and market growth, especially for biological and integrated pest management solutions.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Seed Treatment Market?
What factors are driving the growth of the Seed Treatment Market?
What are some challenges faced by the Seed Treatment Market?
Who are the major players in the Seed Treatment Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Synthetic Chemicals
- 1.2.2 Biologicals
- 1.3 By Function
- 1.3.1 Fungicide
- 1.3.2 Insecticide
- 1.3.3 Nematicide
- 1.4 By Crop Type
- 1.4.1 Cereals
- 1.4.2 Oilseeds
- 1.4.3 Fruits & Vegetables
- 1.4.4 Others
- 1.5 By Stage of Seed
- 1.5.1 On-farm
- 1.5.2 Off-Farm
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 7,427.40 million → 2032: USD 20,814.16 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Seed Treatment Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Seed Treatment Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Seed Treatment Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Seed Treatment Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Seed Treatment Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Seed Treatment Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Seed Treatment Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Seed Treatment Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 7,427.40 million → 2032: USD 20,814.16 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Seed Treatment Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Synthetic Chemicals
- 12.3.7.2 Biologicals
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Function - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Fungicide
- 12.4.7.2 Insecticide
- 12.4.7.3 Nematicide
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Crop Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Cereals
- 12.5.7.2 Oilseeds
- 12.5.7.3 Fruits & Vegetables
- 12.5.7.4 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Stage of Seed - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 On-farm
- 12.6.7.2 Off-Farm
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Seed Treatment Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Seed Treatment Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Seed Treatment Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Corteva Agriscience
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Syngenta AG
- 17.4 BASF SE
- 17.5 Bayer AG
- 17.6 FMC Corporation
- 17.7 UPL Ltd.
- 17.8 Sumitomo Chemical Co. Ltd.
- 17.9 Nufarm Ltd.
- 17.10 Croda International PLC
- 17.11 Germain's Seed Technology, Inc.
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

