
Resistant weeds and big winter crops sustain input spending
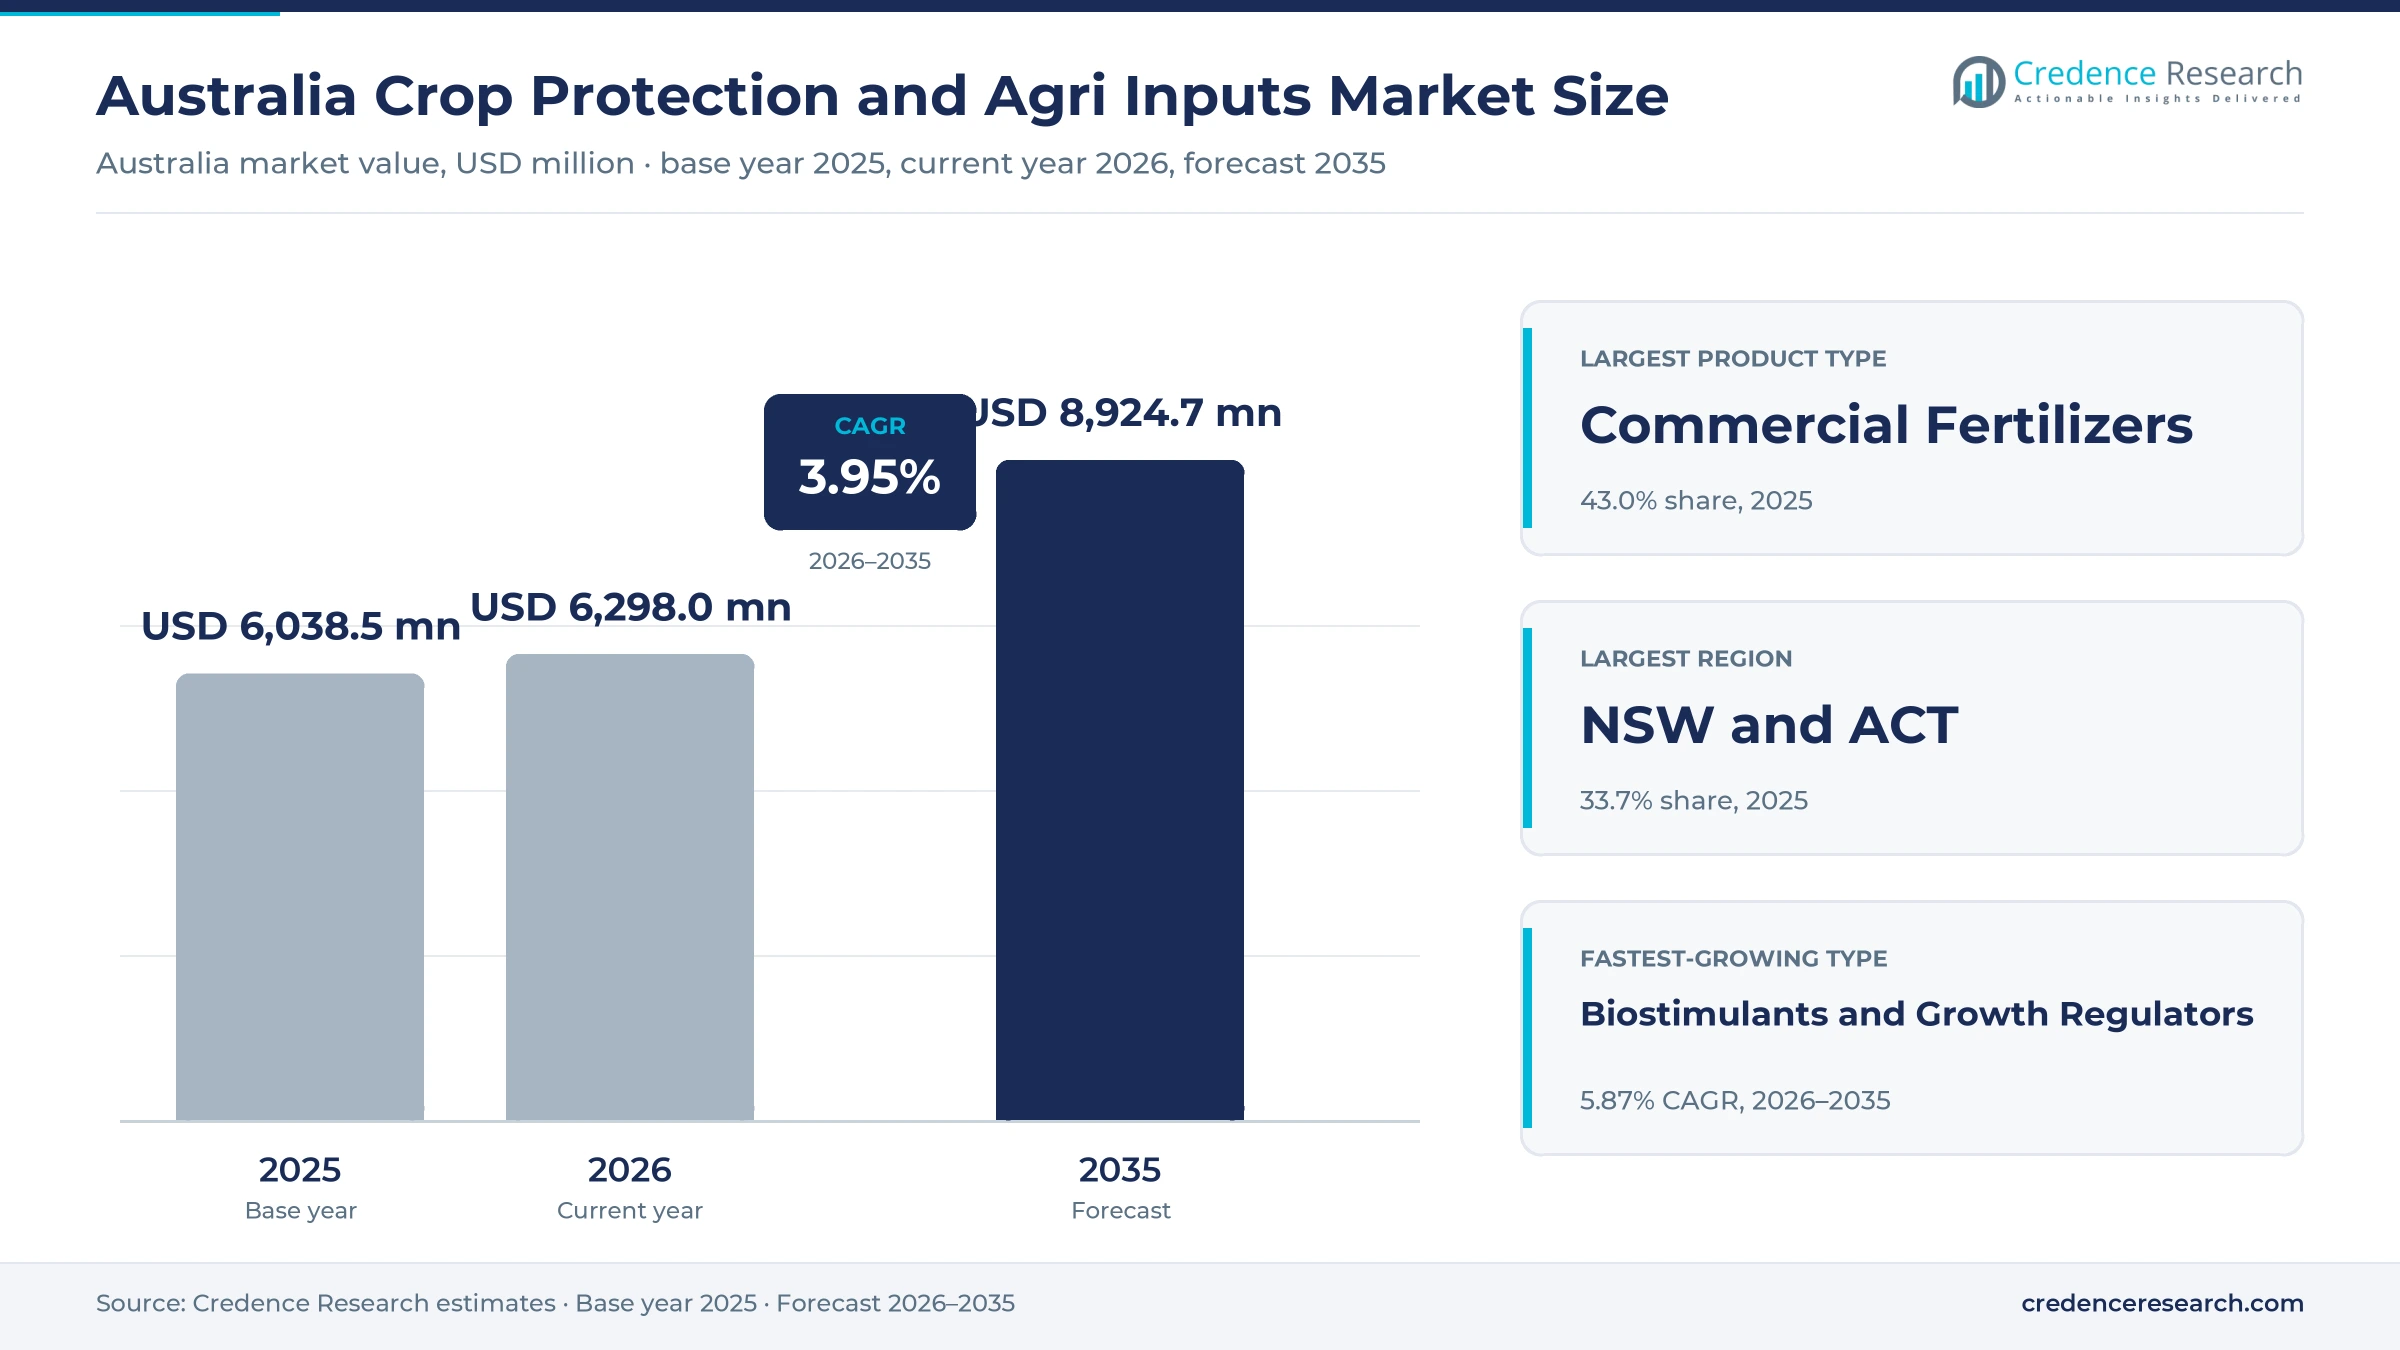
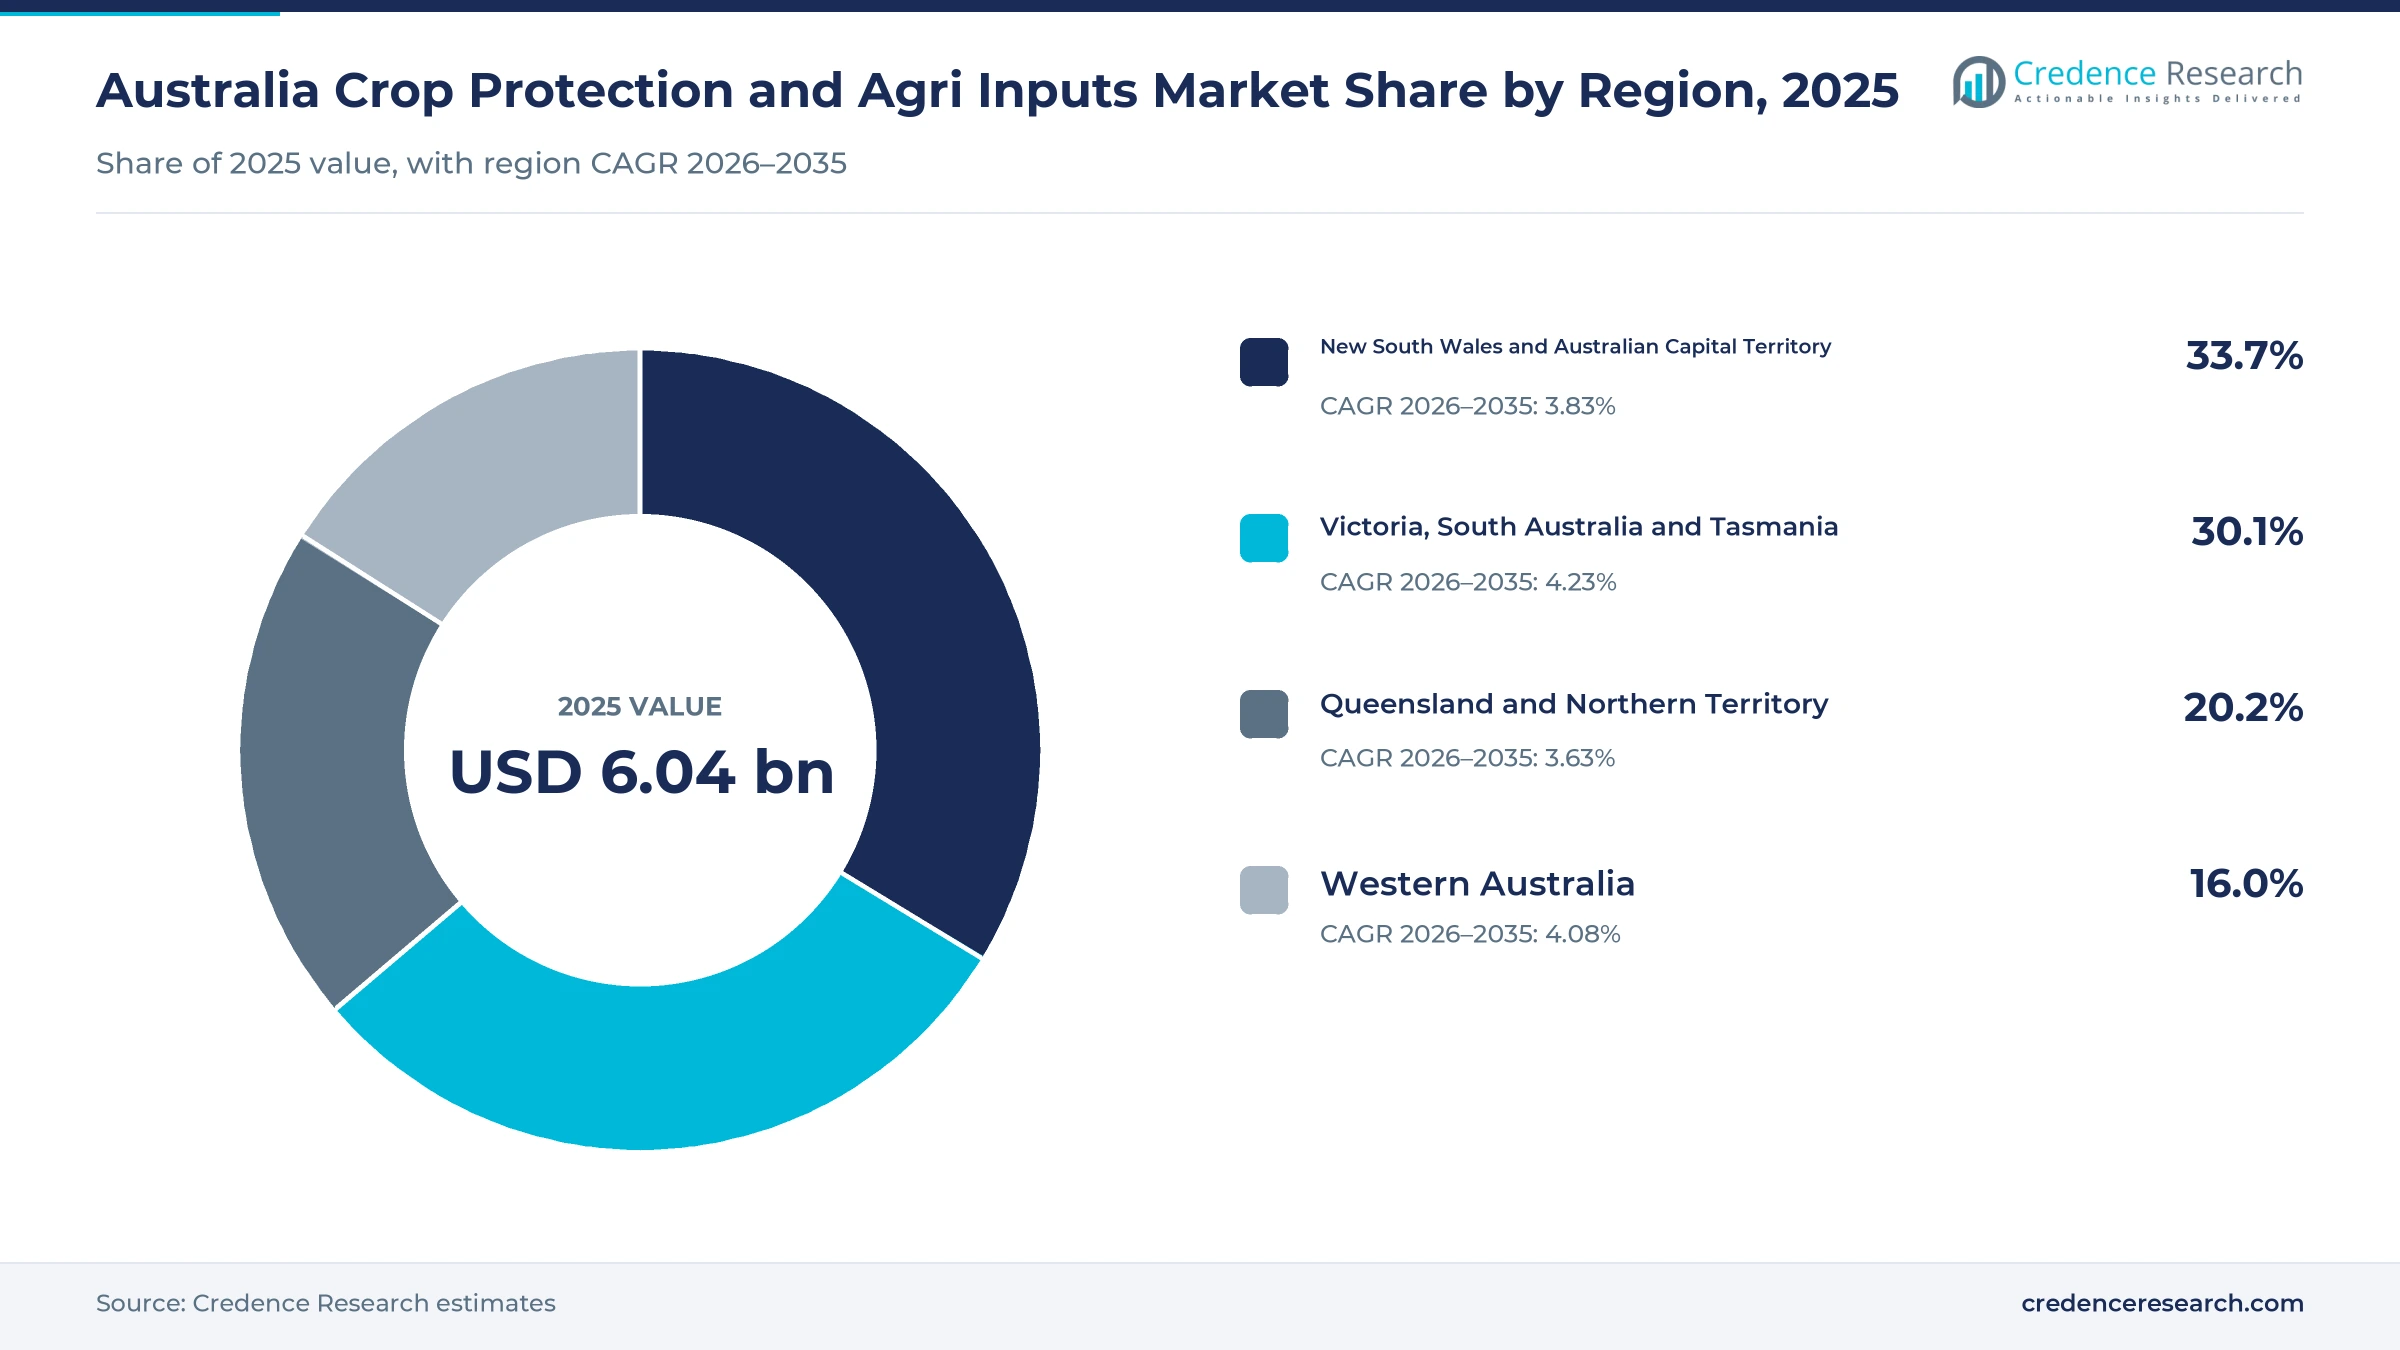
The Australia crop protection and agri inputs market was valued at USD 6.04 billion in 2025 and is projected to increase from USD 6.30 billion in 2026 to USD 8.92 billion by 2035, registering a CAGR of 3.95% during 2026–2035. Demand comes from owner-operated farms, corporate farming enterprises, contract operators and research growers that buy herbicides, fungicides, insecticides, fertilizer, seed and growth products for each winter and summer season. New South Wales and the Australian Capital Territory held the largest regional share, 33.7% in 2025, because the zone spans northern and southern grain belts as well as irrigated farming. Victoria, South Australia and Tasmania form the fastest-growing region at 4.23% a year, helped by strong southern seasons. In turn, tighter national rules on paraquat and diquat and a pipeline of new herbicide chemistry are changing which products growers rotate through their programs.
Which farm inputs does this Australian estimate count?
The estimate measures spending in Australia on crop protection products, commercial fertilizers, commercial seeds and biostimulants and growth regulators used on grains, oilseeds, pulses, horticulture, cotton, sugar and pasture. It covers pre-sowing, in-crop protection, in-crop nutrition and post-harvest field uses, bought through national retail networks, independent dealers, cooperatives, manufacturers and agronomist-led resellers.
The estimate excludes animal health products, fuel, machinery, irrigation water and agronomy fees billed separately. The value chain runs from global chemistry owners, local formulators, importers and seed breeders through port terminals, blending plants and rural branches to farms of every size across each state.
Australia Crop Protection and Agri Inputs Market Insights
- The Australia crop protection and agri inputs market was valued at USD 6.04 billion in 2025 and is projected to reach USD 8.92 billion by 2035, at a 3.95% CAGR during 2026–2035.
- New South Wales and the Australian Capital Territory held 33.7% of 2025 value, as the zone combines northern and southern grain belts with irrigated farming.
- Commercial fertilizers led product types with 43.0% of 2025 value, because growers must replace the nutrients removed by large winter grain and oilseed crops.
- The national regulator cut the maximum paraquat application rate from 1,150 to 231 grams per hectare on June 23, 2026, which pushes growers toward other knockdown options.
- Biostimulants and growth regulators grow fastest at 5.87% a year during 2026–2035, as an industry labelling code gives growers clearer product information.
Fertilizers lead as growth regulators gain fastest
Why do fertilizers still outweigh chemistry spending?
Based on product type, the market is categorized into crop protection products, commercial fertilizers, commercial seeds and biostimulants and growth regulators. Commercial Fertilizers led with 43.0% of 2025 value, because nitrogen, phosphorus and potassium are bought every season in large volumes. Biostimulants and Growth Regulators grow fastest at 5.87% a year, as growers test soil and plant health products alongside standard programs.
Which crops absorb most chemistry and nutrient spending?
Based on crop type, the market is categorized into grains, oilseeds and pulses, horticultural crops, cotton, sugar and specialist field crops, and pasture and forage crops. Grains, Oilseeds and Pulses led with 58.0% of 2025 value, because winter cereals and canola cover most cropped land. Horticultural Crops grow fastest at 4.39% a year, as fruit and vegetable growers spend more per hectare on protection and nutrition.
When in the season do growers spend the most?
Based on application, the market is categorized into pre-sowing and establishment, in-crop protection, in-crop nutrition and growth, and post-harvest field management. Pre-Sowing and Establishment led with 38.0% of 2025 value, because knockdowns, pre-emergent herbicides, seed and base fertilizer go on before or at seeding. In-Crop Nutrition and Growth grows fastest at 4.24% a year, as growers split nitrogen and add foliar products.
How do Australian growers buy their inputs?
Based on distribution channel, the market is categorized into national agricultural retail networks, independent dealers and cooperatives, manufacturer direct sales and agronomist-led resellers. National Agricultural Retail Networks led with 52.0% of 2025 value, because they bundle stock, credit, delivery and advice. Agronomist-Led Resellers grow fastest at 4.82% a year, as growers pay for paddock-level recommendations.
| Segment Group | Leading Sub-segment | Share, 2025 | Fastest-growing Sub-segment | CAGR, 2026–2035 |
|---|---|---|---|---|
| By Product Type | Commercial Fertilizers | 43.0% | Biostimulants and Growth Regulators | 5.87% |
| By Crop Type | Grains, Oilseeds and Pulses | 58.0% | Horticultural Crops | 4.39% |
| By Application | Pre-Sowing and Establishment | 38.0% | In-Crop Nutrition and Growth | 4.24% |
| By Distribution Channel | National Agricultural Retail Networks | 52.0% | Agronomist-Led Resellers | 4.82% |
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Resistance, broadacre scale and seed traits lift demand
How does herbicide resistance reshape chemistry purchases?
Weeds that survive older chemistry force growers to rotate modes of action and stack pre-emergent products, which raises the chemistry bill per hectare. A national survey found 16% of annual ryegrass populations resistant to glyphosate in 2020, up from 4% in 2013-17, with another 22% developing resistance, according to WeedSmart. FMC markets Overwatch as the only registered Group 13 herbicide in the broadacre market, with ryegrass control of up to 12 weeks in wheat, barley, canola and pulses. Bayer also filed icafolin-methyl with the national regulator in August 2026. As a result, crop protection products stay a core spending line, and demand for agrochemicals with newer modes of action keeps rising.
Why does broadacre production recovery keep volumes high?
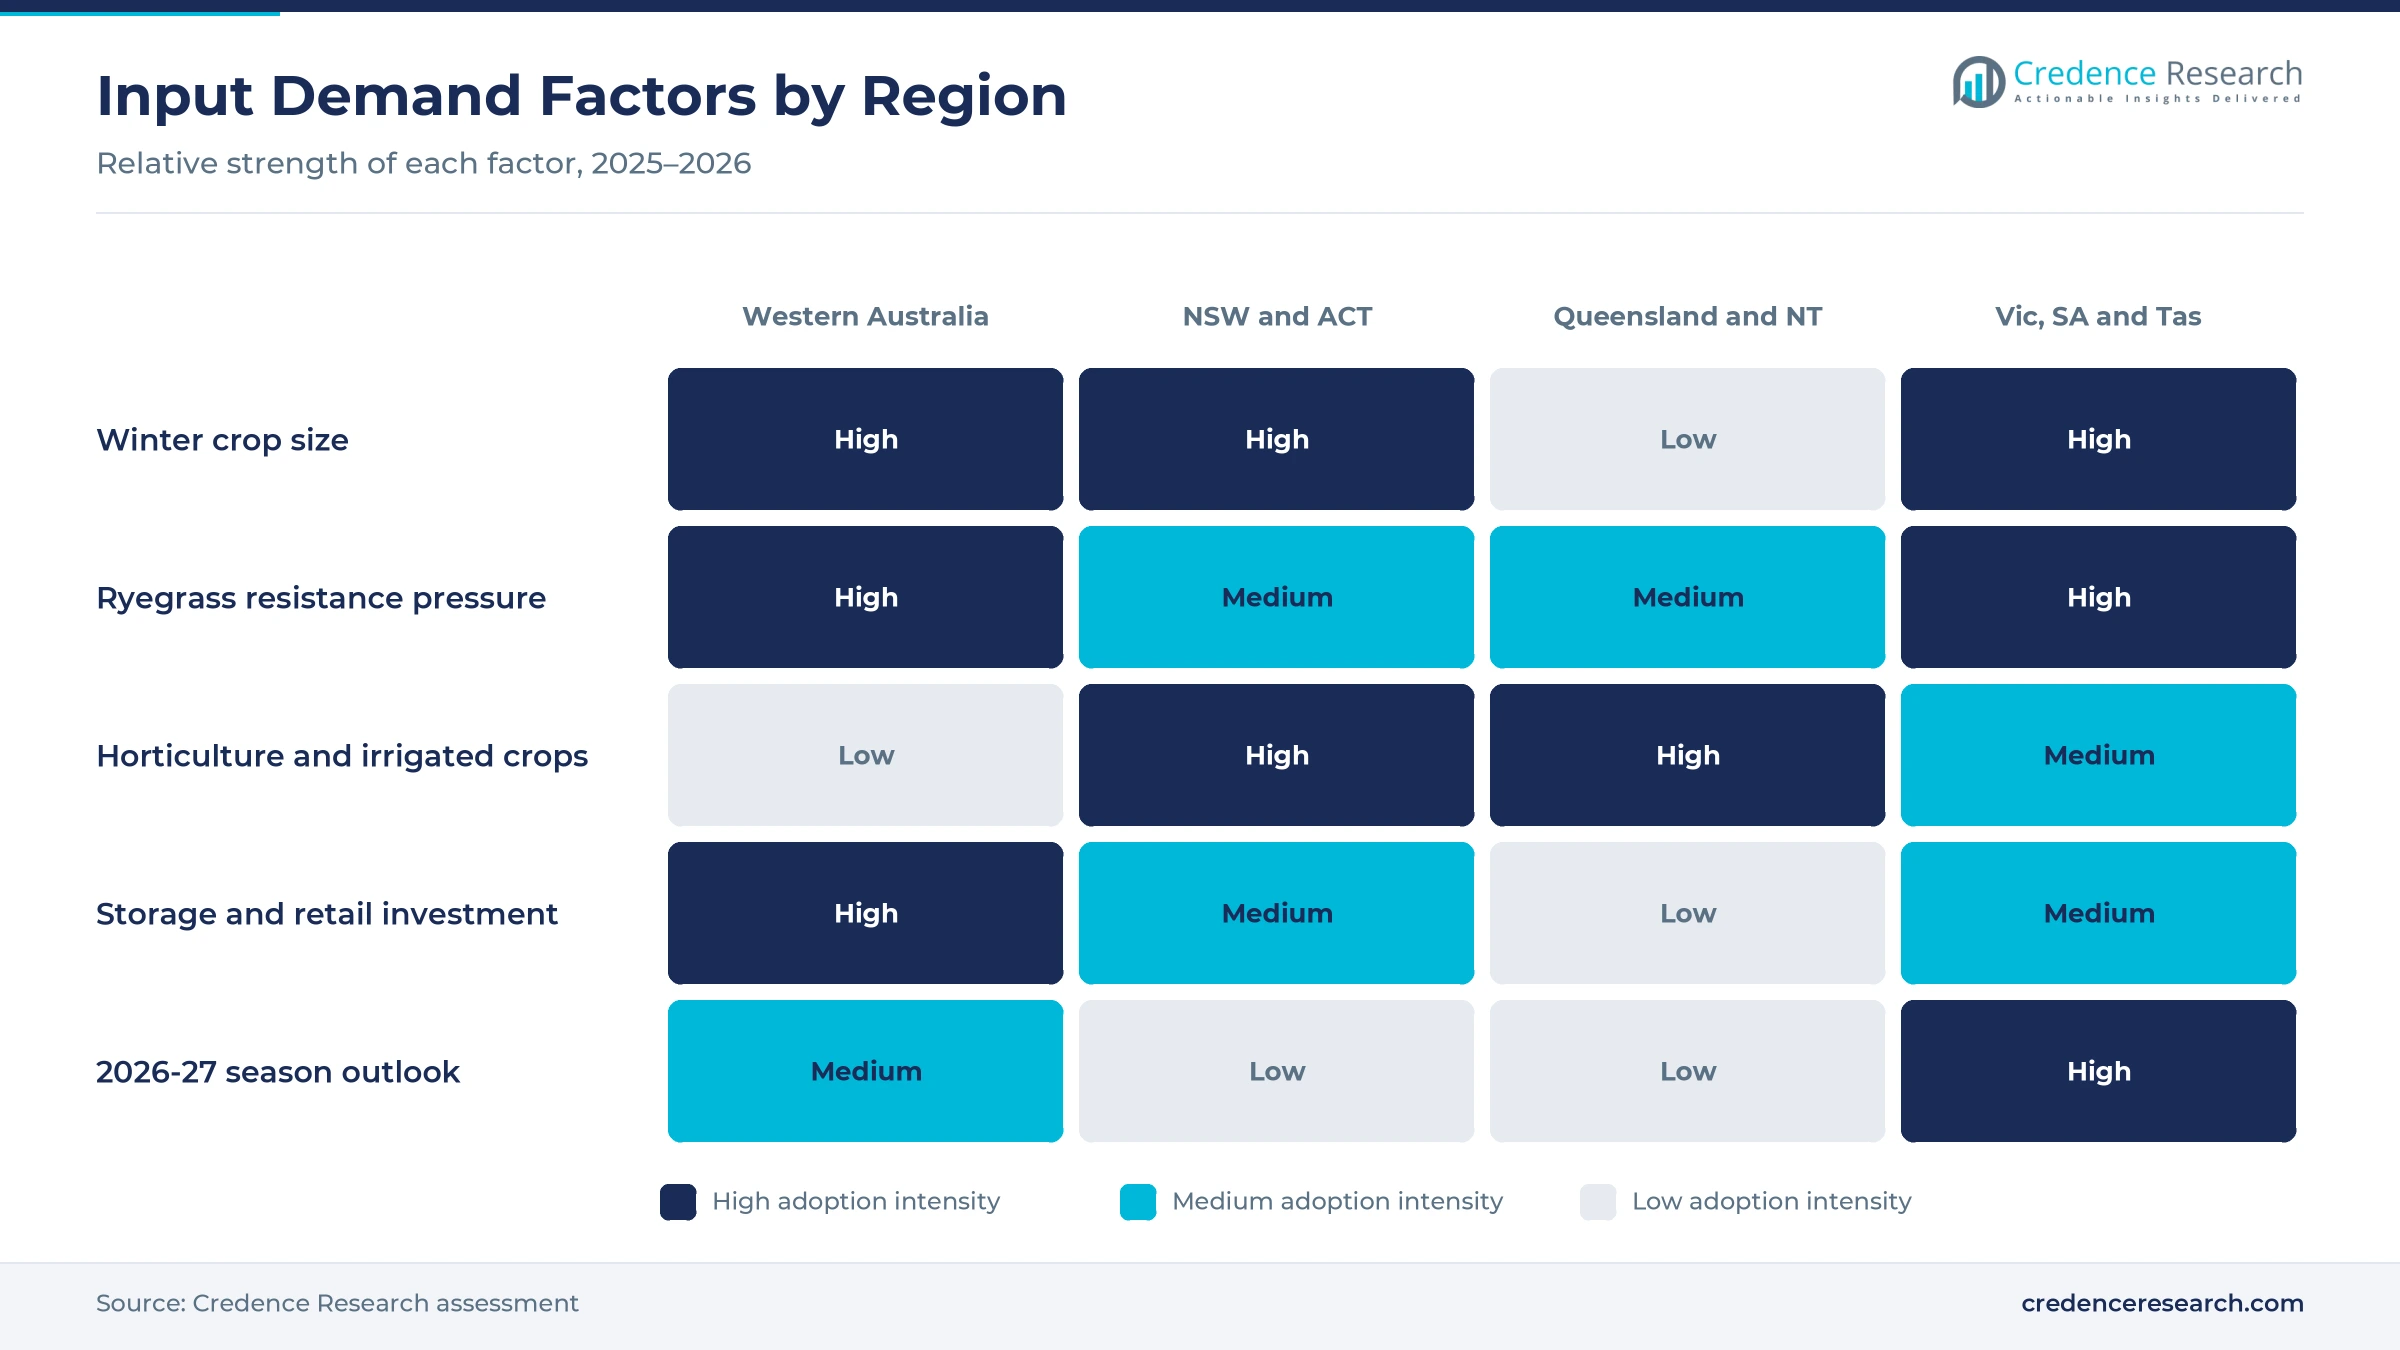
A record cropped area and strong southern seasons keep broadacre growers buying fertilizer, seed and herbicide at scale. The 2025-26 winter crop reached 68.4 million metric tons, up 13% and the second-largest on record, while planted area hit a record 25.2 million hectares, according to World Grain. Barley set a record at 16.3 million metric tons in that season, while canola rose 20% to 7.7 million metric tons. For 2026-27, the national winter crop forecast was revised upward in September to about 61 million metric tons, still the fourth-largest on record. Consequently, grains, oilseeds and pulses lead crop types with 58.0% of 2025 value.
How do seed traits and maturity choices lift seed spending?
Each new variety or hybrid carries its own herbicide package and sowing window, so growers spend more on commercial seeds and on the chemistry tied to each trait. Grains Australia added nine wheat varieties to its 2026-27 Wheat Variety Master List from Aug. 1, 2026, including Packer for early sowing in South Australia, Victoria and southern New South Wales. Corteva sells Optimum GLY canola in Australia through its Pioneer brand. In April 2026, BASF launched Liberty ULTRA glufosinate for InVigor LibertyLink canola, with a one-day plant-back interval to cereals, oilseeds and pulses. Because seed, trait and matching knockdown choices are all made before seeding, pre-sowing and establishment leads application types with 38.0% of 2025 value.
Why does rural retail consolidation widen grower access?
Larger rural networks can hold more stock, blend product near ports and offer agronomy at scale, which keeps inputs available at sowing. Elders acquired all shares in Delta Agribusiness on Nov. 4, 2025, and said the deal strengthens its ag tech, precision agriculture and farm advisory capabilities. Ridley Corporation announced on Oct. 1, 2025, that it had completed its purchase of Incitec Pivot Fertilisers, the fertilizer distribution business of Dyno Nobel. Nutrien Ag Solutions is building a AUD 70 million center at East Rockingham with 130,000 metric tons of bulk storage, about 20% more capacity for Western Australia. Consequently, national agricultural retail networks lead channels with 52.0% of 2025 value.
Price shocks and new knockdown chemistry reshape buying
How is fertilizer price volatility changing orders?
Global supply shocks are pushing growers to book fertilizer earlier and to split nitrogen between sowing and in-crop top-ups. The fertilizer price index rose more than 12% in the first quarter of 2026, its sixth increase in seven quarters, according to the World Bank. Urea climbed above USD 850 per metric ton in April 2026, up 80% since February, after disruption in the Strait of Hormuz, a route for nearly a quarter of global urea exports. The same analysis projects urea prices to rise nearly 60% in 2026 before easing in 2027. National forecasters reported that growers could still access inputs, though often at higher prices, and some favored canola over cereals for fertilizer. In turn, in-crop nutrition and growth spending grows at 4.24% a year.
Why is a shift toward new knockdown chemistry emerging?
Tighter rules on older knockdowns are opening space for glufosinate and new modes of action. The national regulator cut the maximum paraquat application rate from 1,150 to 231 grams per hectare on June 23, 2026, according to the APVMA, and it now requires enclosed mixing and loading for all uses. BASF launched Basta ULTRA in May 2026 as an alternative to glyphosate and paraquat in tree crops, vineyards and vegetables. Nufarm is working with KingAgroot to register flufenoximacil, a knockdown with a new mode of action, and targets approval before the end of the decade. As a result, growers will rebuild their knockdown programs around glufosinate and new modes of action through 2035.
Can biostimulants and growth regulators open new value?
Clearer product standards are turning soil and plant health products into a mainstream purchase for growers that want yield gains without extra chemical residues. Fertilizer Australia announced a voluntary biostimulant labelling code on Aug. 14, 2025, and gave members a one-year window to align product labels and information. Its first version covers microbial products and carbon-based products such as humic substances, with more categories planned later. The APVMA regulates traditional chemistry and biocontrol products, not biostimulants, so the code fills a gap in product information. UPL also planned a new bio-fungicide for the grape market in 2025, which widens biological options in horticulture. Consequently, biostimulants and growth regulators grow fastest among product types at 5.87% a year.
Is there room for agronomist-led and spot-spraying services?
Paddock-level advice and targeted spraying open a growth opportunity, because new rules reward precise application over blanket rates. The paraquat decision allows a higher rate for technology-assisted spot spraying, with that use capped at 30% of the treated area. UPL said in May 2025 that its sales team is key to bringing new cereal, canola and viticulture products to farmers through retailers and agronomists. Elders also tied its Delta purchase to precision agriculture and farm advisory services in November 2025. Grains Australia also lists 15 wheat varieties for removal in 2028, so growers need advice on replacement seed. As a result, agronomist-led resellers grow fastest among channels at 4.82% a year, as growers pay for recommendations that turn each input into measurable yield.
Dry northern seasons and older chemistry limits weigh
How do dry northern seasons cut chemistry volumes?
Northern districts face the weakest 2026 season, and smaller plantings there mean fewer spray passes and lower chemistry sales. The 2026-27 winter crop is forecast down 43.6% in Queensland and 30% in New South Wales. Nufarm also reported in May 2026 that dry weather across key Australian cropping regions weighed on its domestic crop protection volumes. As a result, retailers in dry districts carry more stock risk, and suppliers respond with flexible terms and smaller pack sizes.
Why do nutrient price spikes squeeze grower margins?
Fertilizer is often the largest cash cost on a grain farm, so any jump in global nutrient prices hits margins quickly. Diammonium phosphate prices rose more than 10% in April 2026, while potash prices were nearly 17% higher than a year earlier in the first quarter. Consequently, some growers cut rates or delay purchases, which puts yield at risk in good seasons. Retailers respond with forward contracts, soil tests and split applications that target nutrients where returns are highest.
How do new paraquat and diquat rules raise costs?
Existing paraquat and diquat stock must be phased out over two years, and labels change for products made from June 23, 2026, which adds compliance work for every grower and reseller. Backpack sprayers are being phased out for these products, and users must wear enhanced protective equipment. In turn, horticulture and vegetable growers that relied on these knockdowns must retrain staff and buy new equipment, while suppliers promote glufosinate and other options to fill the gap.
Will slow registrations leave resistance gaps open?
New chemistry takes years to reach Australian labels, while weeds keep adapting to the groups already in use. Bayer targets a launch of icafolin-methyl from 2028, subject to approval, and Syngenta had not registered its Virestina grass herbicide in Australia by April 2026. Meanwhile, paraquat resistance has started to appear in ryegrass, with two survey samples resistant and six developing resistance. Consequently, growers must stretch current groups through careful rotation and non-chemical weed control.
NSW and ACT lead while southern states grow fastest
| Region | Value, 2025 (USD billion) | Share, 2025 | CAGR, 2026–2035 |
|---|---|---|---|
| New South Wales and Australian Capital Territory | 2.03 | 33.7% | 3.83% |
| Victoria, South Australia and Tasmania | 1.82 | 30.1% | 4.23% |
| Queensland and Northern Territory | 1.22 | 20.2% | 3.63% |
| Western Australia | 0.97 | 16.0% | 4.08% |
Why do New South Wales and the ACT lead input demand?
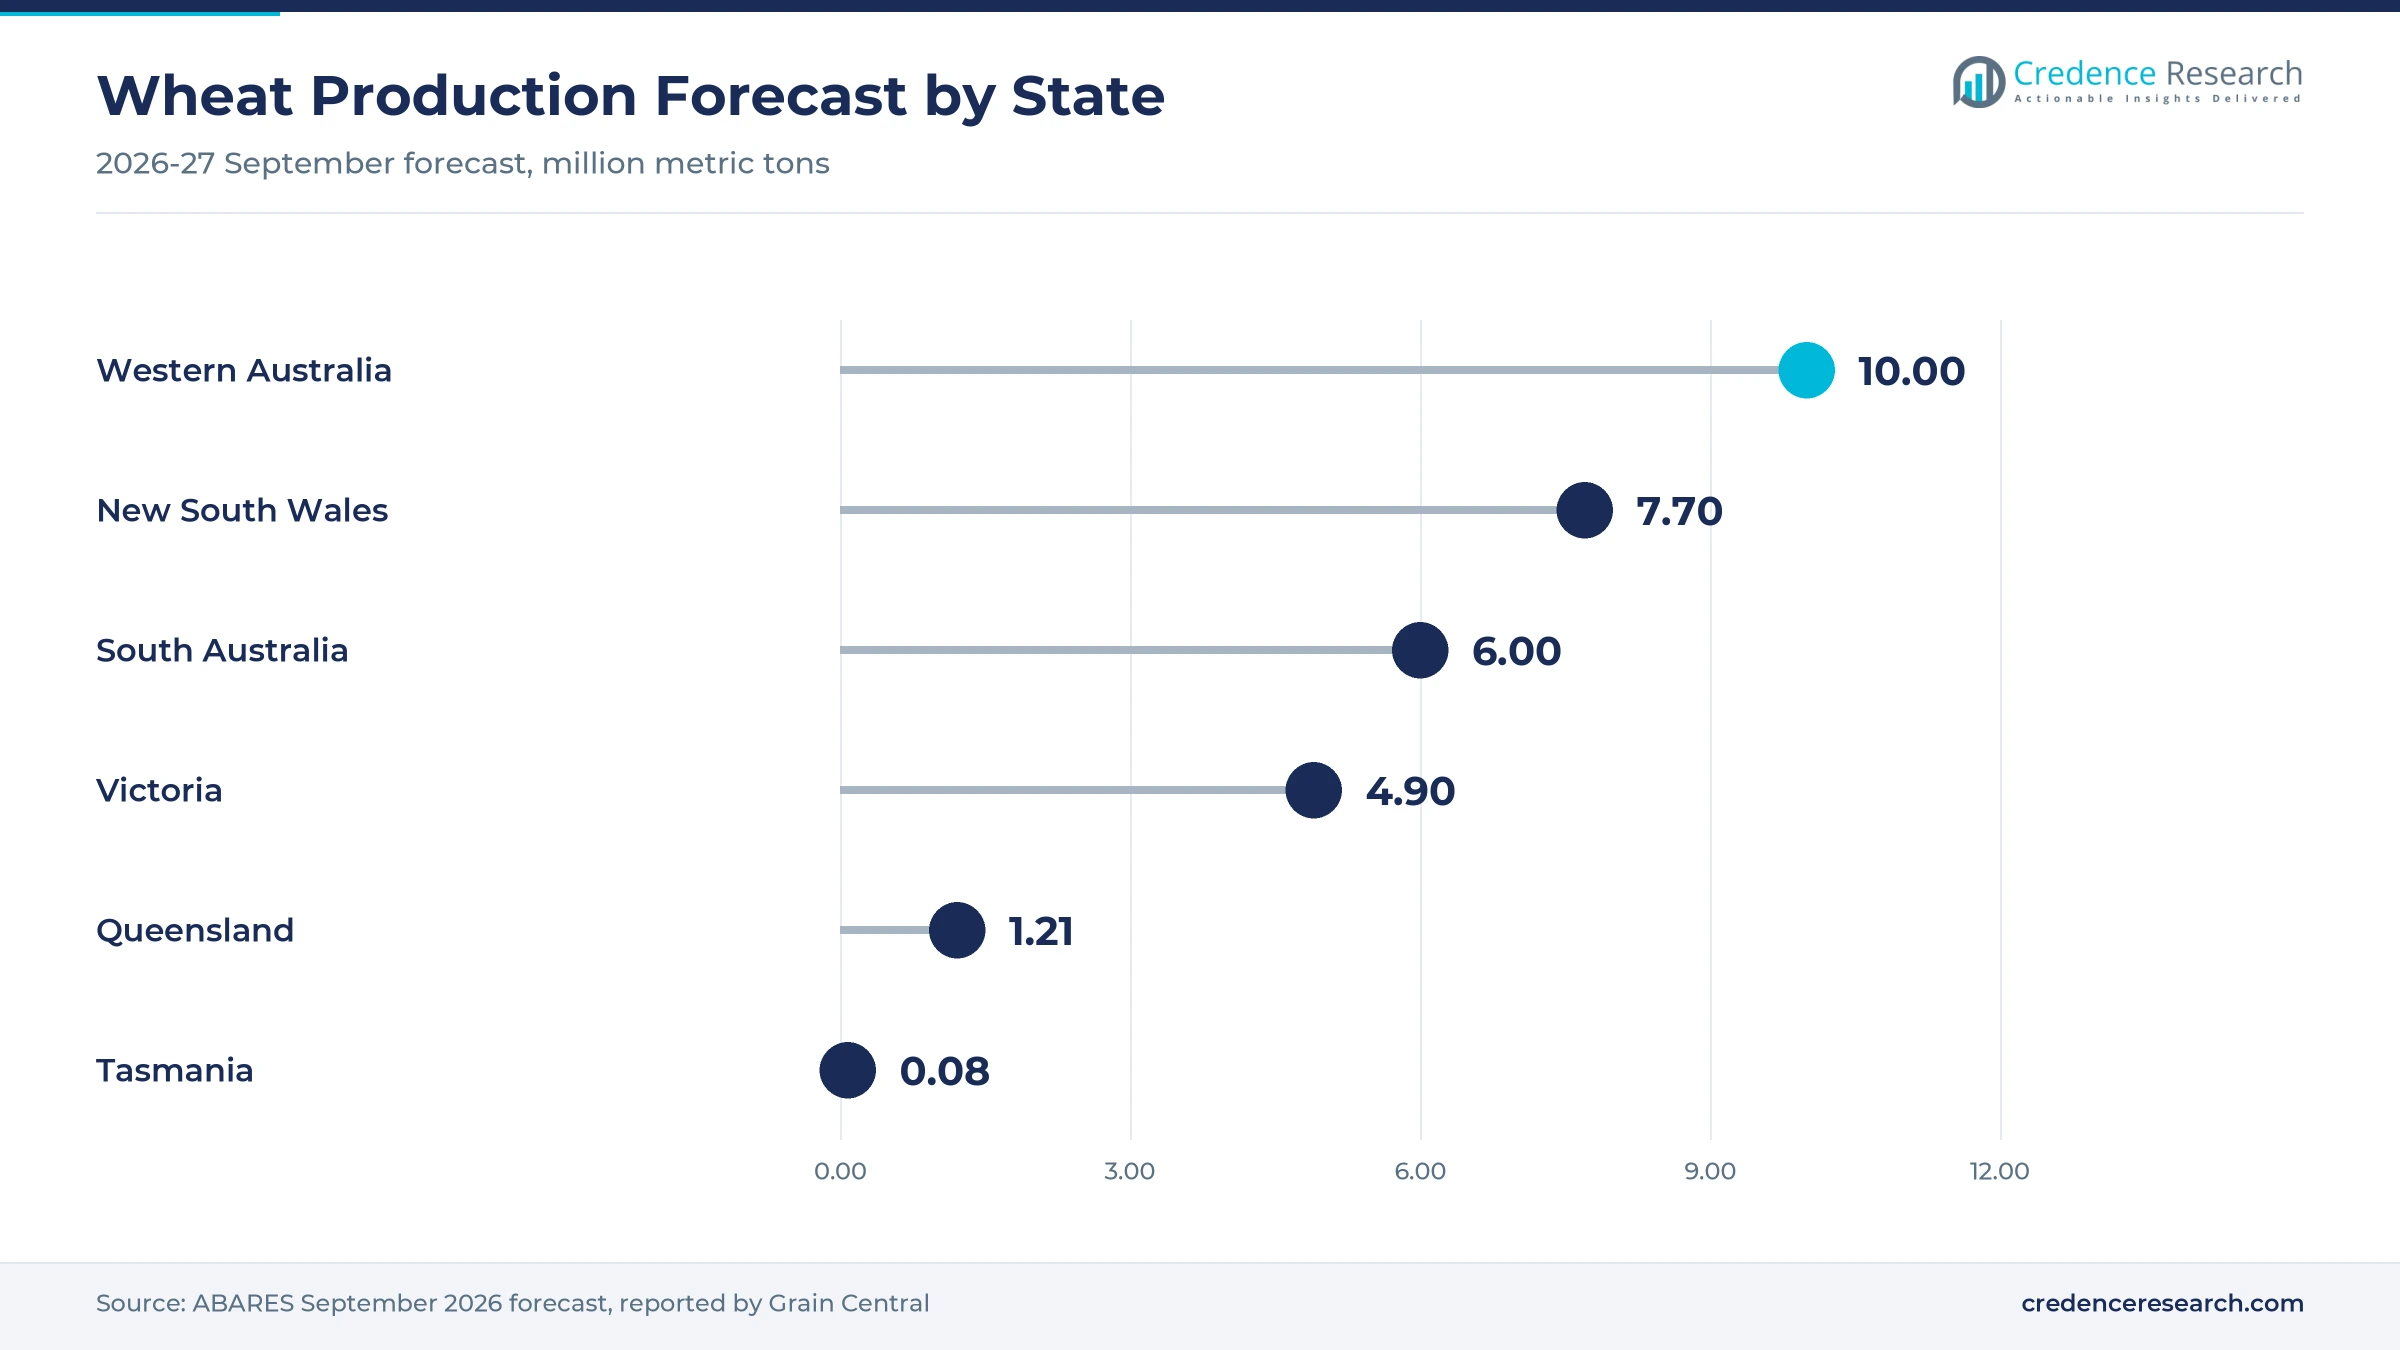
New South Wales and the Australian Capital Territory held 33.7% of 2025 value and grow at 3.83% a year. The state combines a southern grain belt with excellent 2026 conditions and a northern belt where conditions were poor. Its September wheat forecast was 7.7 million metric tons on 3.0 million hectares, alongside 1.2 million metric tons of canola. Consequently, this zone keeps the largest share of 2025 input value even as its total winter crop falls in 2026-27.
How do Victoria, South Australia and Tasmania lead growth?
Victoria, South Australia and Tasmania held 30.1% of 2025 value and grow fastest at 4.23% a year. South Australia's 2026-27 winter crop forecast rose to 11.3 million metric tons in September, up 24% from the June figure, while Victoria's crop is forecast up 12% on the previous season. Bayer also ran 2026 field trials of icafolin-methyl at Elmore in Victoria. As a result, demand here leans toward canola seed, barley nutrition and pre-emergent herbicides.
What role do Queensland and the Northern Territory play?
Queensland and the Northern Territory held 20.2% of 2025 value and grow at 3.63% a year. Queensland's September wheat forecast was 1.21 million metric tons on 650,000 hectares, and its total winter crop is forecast down 43.6% in 2026-27. Because winter grain is smaller here, spending relies more on summer crops, cotton, sugar and horticulture, which use more in-crop protection and tie demand to wet seasons.
How does Western Australia support broadacre volumes?
Western Australia held 16.0% of 2025 value and grows at 4.08% a year. The state has the largest wheat crop, forecast at 10.0 million metric tons for 2026-27, and 4.0 million metric tons of canola on 2.2 million hectares. Nutrien Ag Solutions runs more than 70 stores in the state and expects its East Rockingham center to operate in 2026. However, the state's winter crop is forecast down 16%, which tempers near-term volumes.
Retail deals, storage and herbicide filings, 2024–2026
| Development | Status and market relevance |
|---|---|
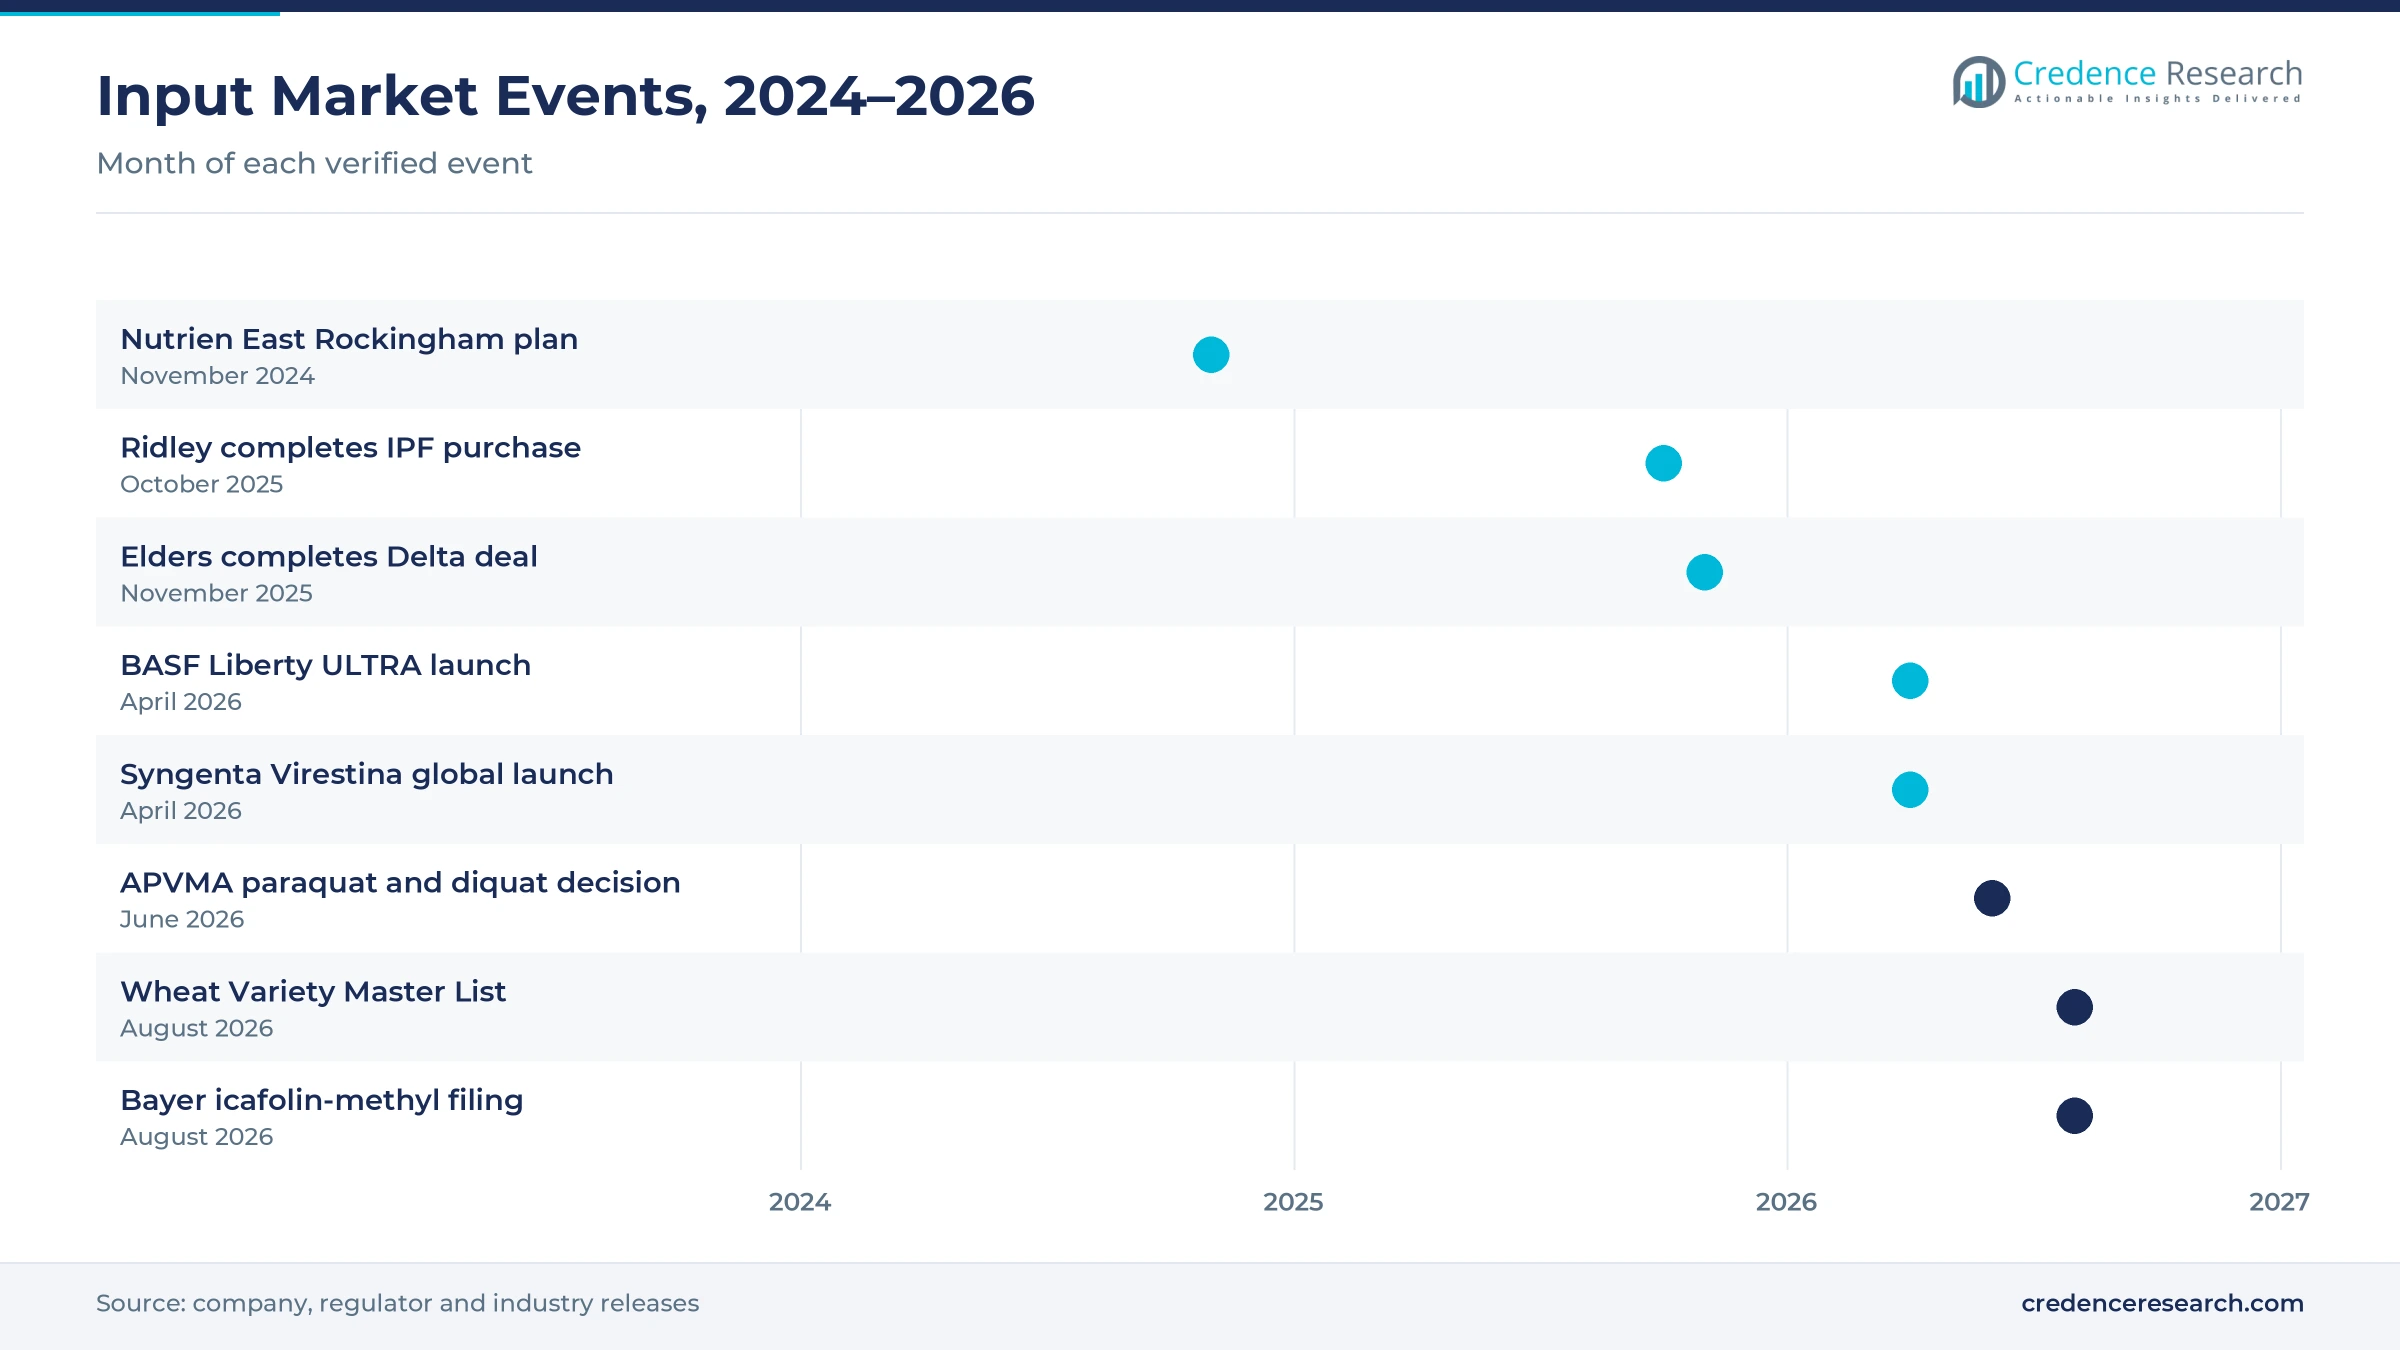
| In November 2024, Nutrien Ag Solutions confirmed a AUD 70 million bulk fertilizer center at East Rockingham, Western Australia, with 130,000 metric tons of storage. | Expected to operate in 2026 |
| In November 2025, Elders completed its acquisition of Delta Agribusiness, which keeps its own brand and management. | Widens agronomy and precision reach |
| In April 2026, BASF launched Liberty ULTRA glufosinate in Australia for InVigor LibertyLink canola. | Ties trait canola to new knockdown use |
| In June 2026, the APVMA issued final decisions that keep paraquat and diquat with sharply lower rates and new safety rules. | Two-year phase-out of existing stock |
| In August 2026, Bayer submitted icafolin-methyl for approval in Australia, targeting a launch from 2028. | Adds a future resistance tool |
Trait canola, group 13 chemistry and spot spraying
- Herbicide-tolerant canola traits such as Optimum GLY and InVigor LibertyLink link seed choice to specific knockdown programs, which widens weed control windows.
- Group 13 pre-emergent chemistry such as bixlozone in Overwatch adds a different mode of action against resistant annual ryegrass in winter crops.
- Technology-assisted spot spraying treats only weeds the sensors detect, which the paraquat rules recognize with a higher rate on up to 30% of treated area.
- L-isomer glufosinate formulations use lower rates and better droplet retention, which cuts handling, storage and transport needs on farms.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Rural networks and chemistry owners compete on agronomy
Competition is led by national rural networks, global chemistry owners and local formulators that pair products with agronomy. Nutrien Ag Solutions and Elders control large branch networks, with Elders adding Delta Agribusiness in November 2025, while Incitec Pivot Fertilisers now sits within Ridley Corporation. Bayer CropScience, Syngenta, BASF Agricultural Solutions, Corteva Agriscience and FMC compete through new chemistry and seed traits, including Bayer's icafolin-methyl filing, BASF's Liberty ULTRA launch and FMC's Overwatch. Nufarm, an Australian-listed formulator, is pursuing flufenoximacil with KingAgroot, while UPL is adding cereal, canola and viticulture products. Companies compete on access to new modes of action, stewardship programs, stock at sowing, credit terms and agronomy depth. In the Australia crop protection and agri inputs market, owning a fresh mode of action now matters as much as branch reach.
Companies profiled and their roles in this market
| Company | Type | Role in the market |
|---|---|---|
| Nutrien Ag Solutions | National rural network | Building a 130,000-metric-ton fertilizer center at East Rockingham |
| Elders | National rural network | Completed Delta Agribusiness acquisition in November 2025 |
| Incitec Pivot Fertilisers | Fertilizer distributor | Acquired by Ridley Corporation, completion announced October 2025 |
| Bayer CropScience | Chemistry and seed | Filed icafolin-methyl for approval in August 2026 |
| Nufarm | Local formulator | Registering flufenoximacil with KingAgroot |
| Syngenta | Chemistry and seed | Virestina grass herbicide not yet registered locally |
| BASF Agricultural Solutions | Chemistry and seed | Launched Liberty ULTRA and Basta ULTRA in 2026 |
| Corteva Agriscience | Seed and chemistry | Optimum GLY canola through the Pioneer brand |
| FMC | Chemistry owner | Overwatch, the only registered Group 13 broadacre herbicide |
| UPL | Chemistry owner | New cereal, canola and viticulture products |
Credence Research sees chemistry renewal setting pace
Credence Research's view is that Australian input spending will grow steadily through 2035, as growers protect large winter crops and manage resistant weeds. Commercial fertilizers should keep the largest product share, while biostimulants and growth regulators gain most from clearer labelling. New South Wales and Australian Capital Territory will remain the largest zone, although the southern states add demand fastest. Western Australia, with a 16.0% share of 2025 value, stays a large broadacre buyer of fertilizer and canola seed. However, the paraquat rules and a slow chemistry pipeline will reward suppliers that hold new modes of action. Suppliers that pair stock at sowing with paddock-level advice should gain share.
Crop area, input rates and prices anchor the model
The report uses 2025 as the base year on a calendar basis. Market values come from the Credence Research model, which combines crop area, production, input rates and price levels. Regional shares follow the client data set, while regional growth and segment splits by product type, crop type, application and distribution channel are Credence Research estimates. Sources used are national crop forecasts, World Bank price data, regulator decisions, weed resistance surveys, industry body releases and company announcements, and no interviews or surveys were used.
New modes of action and seed traits shape 2035 demand
The market is expected to reach USD 8.92 billion by 2035, a 3.95% CAGR during 2026–2035, as resistance management and seed traits keep input spending rising. Growth should be strongest in biostimulants and growth regulators, agronomist-led resellers and the southern states, while New South Wales and Australian Capital Territory keep the largest share. New herbicide chemistry from 2028 and the end of the paraquat transition will reshape knockdown programs. A potential icafolin-methyl launch from 2028 would add a new option for growers facing glyphosate-resistant ryegrass and support chemistry demand. In contrast, dry northern seasons or nutrient price spikes could slow spending in some years.
Frequently Asked Questions
How big is the Australia crop protection and agri inputs market?
Which region leads input demand in Australia?
Which region grows fastest?
Which product type holds the largest share?
Why does herbicide resistance matter for this market?
How do the new paraquat rules affect growers?
Who are the leading companies in this market?
What are the main risks to growth?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Product Type
- 1.2.1 Crop Protection Products
- 1.2.2 Commercial Fertilizers
- 1.2.3 Commercial Seeds
- 1.2.4 Biostimulants and Growth Regulators
- 1.3 By Crop Type
- 1.3.1 Grains, Oilseeds and Pulses
- 1.3.2 Horticultural Crops
- 1.3.3 Cotton, Sugar and Specialist Field Crops
- 1.3.4 Pasture and Forage Crops
- 1.4 By Application
- 1.4.1 Pre-Sowing and Establishment
- 1.4.2 In-Crop Protection
- 1.4.3 In-Crop Nutrition and Growth
- 1.4.4 Post-Harvest Field Management
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2025: USD 6.04 billion → 2035: USD 8.92 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Historical Period: 2018-2025
- 2.6.2 Base Year: 2025
- 2.6.3 Forecast Period: 2025-2035
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2025
- 3.3 Forecast Market Size, 2035
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Australia Crop Protection and Agri Inputs Market Trends and Developments
- 4.1 Historical Industry Development, 2018-2025
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Australia Crop Protection and Agri Inputs Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis, 2018-2025
- 5.2 Demand Forecast, 2025-2035
- 5.3 Production and Output Trend, 2018-2025
- 5.4 Production and Output Forecast, 2025-2035
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Australia Crop Protection and Agri Inputs Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends, 2018-2025
- 6.3 Pricing Outlook, 2025-2035
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Australia Crop Protection and Agri Inputs Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Australia Crop Protection and Agri Inputs Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Australia Crop Protection and Agri Inputs Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Australia Crop Protection and Agri Inputs Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Australia Crop Protection and Agri Inputs Market Outlook, 2025-2035
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2025: USD 6.04 billion → 2035: USD 8.92 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size, 2018-2025
- 11.1.4 Base-Year Market Size, 2025
- 11.2 Market Forecast, 2025-2035
- 11.2.1 Revenue Forecast to 2035
- 11.2.2 Volume Forecast to 2035
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Australia Crop Protection and Agri Inputs Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2025
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Product Type - Market Size and Forecast, 2025-2035
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size, 2018-2025
- 12.3.3 Revenue Forecast, 2025-2035
- 12.3.4 Volume Forecast, 2025-2035
- 12.3.5 Base-Year Market Share, 2025
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Crop Protection Products
- 12.3.7.2 Commercial Fertilizers
- 12.3.7.3 Commercial Seeds
- 12.3.7.4 Biostimulants and Growth Regulators
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Crop Type - Market Size and Forecast, 2025-2035
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size, 2018-2025
- 12.4.3 Revenue Forecast, 2025-2035
- 12.4.4 Volume Forecast, 2025-2035
- 12.4.5 Base-Year Market Share, 2025
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Grains, Oilseeds and Pulses
- 12.4.7.2 Horticultural Crops
- 12.4.7.3 Cotton, Sugar and Specialist Field Crops
- 12.4.7.4 Pasture and Forage Crops
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2025-2035
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size, 2018-2025
- 12.5.3 Revenue Forecast, 2025-2035
- 12.5.4 Volume Forecast, 2025-2035
- 12.5.5 Base-Year Market Share, 2025
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Pre-Sowing and Establishment
- 12.5.7.2 In-Crop Protection
- 12.5.7.3 In-Crop Nutrition and Growth
- 12.5.7.4 Post-Harvest Field Management
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Australia Crop Protection and Agri Inputs End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Australia Crop Protection and Agri Inputs Geographic Market Outlook, 2025-2035
- 14.1 Domestic Market Distribution and Demand Clusters
- 14.2 State- or Province-Wise Market Size and Forecast, 2025-2035
- 14.3 City and Metropolitan Market Outlook
- 14.4 Industrial, Manufacturing and Commercial Clusters
- 14.5 Geographic Concentration of Key End Users
- 14.6 Local Pricing and Purchasing Differences
- 14.7 Domestic Production Facilities and Capacity Map
- 14.8 Local Infrastructure and Project Pipeline
- 14.9 State-Level Policy and Incentive Differences
- 14.10 Subnational Investment Hotspots and Opportunities
- 14.11 Distribution and Logistics Networks
- 14.12 Domestic Competitive Footprint
Chapter 15 Australia Crop Protection and Agri Inputs Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2025-2035
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Australia Crop Protection and Agri Inputs Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2025
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2025-2035
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Nutrien Ag Solutions
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Elders
- 18.4 Incitec Pivot Fertilisers
- 18.5 Bayer CropScience
- 18.6 Nufarm
- 18.7 Syngenta
- 18.8 BASF Agricultural Solutions
- 18.9 Corteva Agriscience
- 18.10 FMC
- 18.11 UPL
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

