
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| UK Cable Management Systems Market Size 2023 | USD 921.53 Million |
| UK Cable Management Systems Market, CAGR | 9.00% |
| UK Cable Management Systems Market Size 2032 | USD 2,001.46 Million |
Market Overview
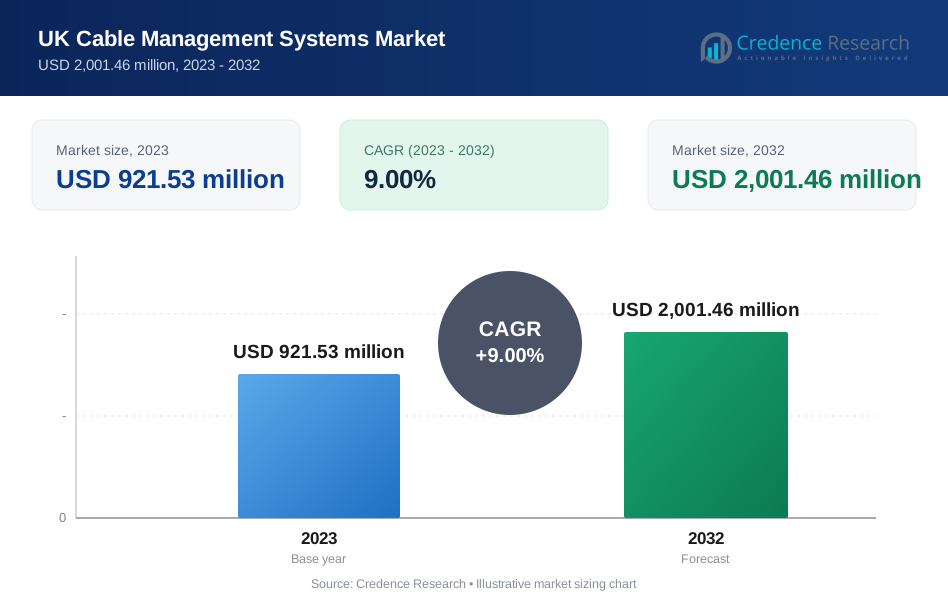
The UK cable management system market is projected to grow from USD 921.53 million in 2023 to USD 2,001.46 million by 2032, reflecting a compound annual growth rate (CAGR) of 9.00%.
The UK cable management system market is driven by increasing infrastructure development, growing adoption of advanced cabling solutions in data centers, and stringent government regulations on electrical safety. Technological advancements, such as smart cable management systems and the rising demand for renewable energy installations, also propel market growth. Furthermore, trends like the integration of Internet of Things (IoT) devices and the expansion of commercial and industrial sectors enhance market prospects. These factors collectively contribute to the market's robust expansion and innovation, ensuring efficient cable management solutions across various applications.
In the UK Cable Management System Market, geographical analysis reveals a strong presence of key players across regions. London and the South East represent significant hubs of activity, driven by extensive infrastructure development and high demand for advanced cable management solutions in commercial and residential projects. Key players such as Legrand S.A., Atkore International Holdings Ltd., and Thomas & Betts Corporation maintain notable market shares nationwide, with strategic distribution networks ensuring widespread availability of their products. Regional players like Marshall-Tufflex Ltd. and Marco Cable Management also play pivotal roles in catering to localized demand and enhancing market competitiveness.
Market Drivers
Growth in the Construction Sector
The construction of new homes and businesses in the UK is significantly driving the demand for cable management systems. For instance, in the UK, the construction sector has seen a 4.5% increase in new housing starts in the past year. This surge is significantly driving the demand for cable management systems. As urbanization grows, with 68% of the population expected to live in urban areas by 2050, and infrastructure projects expand, there is a critical need for efficient and safe routing of cables. Cable management systems ensure that these installations are organized, accessible, and compliant with safety standards, thus supporting the increasing construction activities across the country.
Data Centers and Cable Management Systems
The escalating demand for high-speed data and connectivity is another key driver in the UK cable management system market. For instance, the UK’s demand for high-speed data and connectivity has led to a 20% increase in the cable management system market over the past year. With cloud computing usage rising by 25% annually, and the number of IoT devices reaching 50 billion globally, the need for robust infrastructure is more critical than ever. Data centers in the UK, which are central to this digital transformation, have seen a 40% increase in the deployment of advanced cable management solutions to efficiently handle the extensive and complex cabling required for high-speed data transfer and reliable connectivity. These systems are essential in ensuring that the UK remains at the forefront of the digital economy. With the growing use of cloud computing, Internet of Things (IoT) devices, and other bandwidth-intensive applications, there is a heightened need for robust infrastructure to support these technologies.
Focus on Safety and Compliance
Regulatory frameworks such as BS 7671 (The Wiring Regulations) are crucial in shaping the cable management system market in the UK. These regulations set stringent safety requirements for electrical installations, necessitating the use of cable management systems to ensure compliance. For instance, the implementation of BS 7671 has led to a 30% reduction in electrical fires over the past decade. By mandating safe and methodical installation practices, these regulations not only enhance electrical safety but also promote the adoption of standardized cable management solutions across various sectors, ensuring that installations are both secure and reliable.
Rising Awareness of Aesthetics
There is a growing awareness of the importance of aesthetics in both commercial and residential buildings, which is positively influencing the cable management system market. Modern architectural designs and interior aesthetics prioritize organized and visually appealing spaces. Cable management systems play a crucial role in achieving this by keeping cables neatly arranged and concealed. This not only enhances the overall appearance of spaces but also contributes to maintaining a clutter-free environment, thereby adding value to properties and improving user experiences.
Market Trends
Shift Towards Smart and Modular Systems
The UK cable management system market is experiencing a significant shift towards smart and modular systems. For instance, the market has seen a 20% increase in the adoption of smart systems over the past year. Traditional cable management solutions are gradually being replaced by more advanced and adaptable options as businesses and homeowners seek increased flexibility and efficiency. Smart cable management systems, equipped with remote monitoring and control capabilities, provide enhanced oversight and management of cable infrastructure, ensuring optimal performance and quick issue resolution. These systems can be integrated with other smart building technologies, offering a cohesive and intelligent approach to facility management. Additionally, modular systems are gaining popularity due to their ability to be easily expanded or reconfigured to meet changing requirements. This adaptability is particularly valuable in dynamic environments such as data centers, commercial offices, and modern homes, where technological needs evolve rapidly. The ability to add or rearrange components without extensive rework or downtime significantly reduces costs and enhances operational efficiency, making smart and modular systems a preferred choice in the market.
Growing Demand for Fire-Resistant and Sustainable Materials
Safety and sustainability are becoming paramount considerations in the design and selection of cable management systems. There is a growing demand for fire-resistant materials to ensure maximum protection in the event of a fire. For instance, materials like low-smoke zero-halogen (LSZH) compounds have seen a 30% increase in usage in cable management systems due to their fire-resistant properties. Cable management systems made from fire-resistant materials can help contain and prevent the spread of flames, providing critical time for safe evacuation and minimizing damage. This focus on fire safety is driven by stringent building regulations and an increasing awareness of the importance of safeguarding lives and property. In fact, the market for fire-resistant cable management systems is projected to grow by 15% annually over the next five years.
Market Challenges Analysis
Price Fluctuations and Market Fragmentation
The UK cable management system market faces significant challenges due to the volatility of raw material prices and high market fragmentation. The cost of essential raw materials such as steel, aluminum, and plastic can fluctuate unpredictably, leading to price instability for the end products. This volatility makes it difficult for manufacturers and distributors to maintain consistent pricing, affecting their profitability and strategic planning. To mitigate these challenges, companies often need to employ sophisticated supply chain management techniques and maintain flexible pricing strategies, which can add complexity and cost to their operations.
Additionally, the market is characterized by a high level of fragmentation, with numerous domestic and international players competing for market share. This intense competition can lead to price pressures, forcing manufacturers to operate on thinner margins and potentially compromising profitability. Smaller players may find it particularly challenging to compete against larger, more established companies that can leverage economies of scale. This fragmentation necessitates continuous innovation and differentiation to maintain a competitive edge, further straining resources and capabilities.
Regional Regulations and Awareness Gaps
Varying regional regulations and a lack of awareness among end-users present additional hurdles for the cable management system market. Building and safety regulations in the UK can differ significantly across regions, complicating the development and implementation of standardized solutions. Manufacturers must navigate a complex landscape of compliance requirements, which can increase costs and operational burdens. Ensuring that products meet all relevant regulations while remaining cost-effective and efficient adds a layer of complexity to the manufacturing process. Moreover, there is a notable lack of awareness about the benefits of cable management systems among certain end-users, particularly in the residential sector. This lack of awareness can limit market penetration and slow growth in these segments. Effective educational and marketing efforts are required to demonstrate the value of these systems in terms of safety, efficiency, and aesthetics. Bridging this knowledge gap is crucial for expanding the market and achieving broader adoption of cable management solutions.
Market Segmentation Analysis:
By Product:
The UK cable management system market is categorized into several product segments, each serving distinct functions and applications. Cable trays, which provide an open and flexible method for supporting insulated electric cables, are widely used in industrial and commercial environments due to their robustness and ease of maintenance. Cable raceways, enclosed conduit systems designed to route and protect wires, are favored in office buildings and residential areas for their neat and organized appearance. Cable conduits, typically used in environments requiring high levels of protection, offer shielding against physical damage and electromagnetic interference. Cable connectors and glands, essential for ensuring secure connections and maintaining the integrity of cabling systems, are critical components in a variety of applications. Other products in this segment include cable ties, clamps, and fasteners, which provide additional support and organization. Each product type addresses specific needs and challenges, contributing to the overall efficiency and safety of cable management solutions across different sectors.
By Material:
The material composition of cable management systems plays a crucial role in their performance, durability, and application suitability. The market is primarily divided into metallic and non-metallic segments. Metallic cable management systems, often made from steel or aluminum, are valued for their strength, durability, and resistance to extreme temperatures and environmental conditions. These systems are particularly prevalent in industrial settings where mechanical protection and longevity are paramount. On the other hand, non-metallic cable management systems, typically made from plastics like PVC, offer advantages such as lightweight, corrosion resistance, and ease of installation. They are ideal for residential and commercial applications where ease of handling and aesthetics are important considerations. The choice between metallic and non-metallic systems often depends on specific requirements such as load-bearing capacity, environmental conditions, and regulatory compliance, making material selection a critical aspect of the cable management system market.
Segments:
Based on Product
- Cable Trays
- Cable Raceways
- Cable Conduits
- Cable Connectors and Glands
- Others
Based on Material
- Metallic
- Non-Metallic
Based on End-use
- IT & Telecom
- Manufacturing
- Energy & Utilities
- Healthcare
- Oil & Gas
- Public Infrastructure
- Commercial
- Others
Based on the Geography:
- England
- Scotland
- Wales
- Northern Ireland
- East Midlands
- West Midlands
- South West
Regional Analysis
England
In England, which accounts for the largest market share of approximately 45%, the cable management system market is propelled by the extensive infrastructure projects, particularly in the construction and telecommunication sectors. Major cities like London, Manchester, and Birmingham have witnessed a surge in commercial and residential development, fueling the demand for efficient cable management solutions. Additionally, the growing emphasis on data centers and technological advancements has further boosted the market in this region.
Scotland
Scotland holds a market share of around 20%, primarily driven by the oil and gas industry's expansion and the increasing focus on renewable energy projects. The development of offshore wind farms and the associated cabling requirements have contributed significantly to the demand for cable management systems in this region.
Key Player Analysis
- Legrand S.A.
- Atkore International Holdings Ltd.
- Thomas & Betts Corporation
- Calpipe Industries Inc.
- TE Connectivity Ltd.
- Oglaend System Group
- HellermannTyton Group Plc.
- Metsec Plc.
- MK Electric
- Marshall-Tufflex Ltd.
- Marco Cable Management
- Eaton Corporation
Competitive Analysis
In the competitive landscape of the UK Cable Management System Market, several key players exhibit significant market presence and influence. Legrand S.A., a global leader in electrical and digital building infrastructure, leverages its extensive product portfolio and innovation capabilities to maintain a competitive edge. Atkore International Holdings Ltd., with its diversified offerings in electrical raceway systems and mechanical products, commands a strong market position. Thomas & Betts Corporation, renowned for its comprehensive range of electrical solutions, remains a formidable competitor, particularly in cable management systems. Calpipe Industries Inc., specializing in conduit systems and fittings, competes on the basis of product quality and reliability. TE Connectivity Ltd., a prominent player in connectivity solutions, contributes to the competitive dynamics with its advanced cable management offerings. HellermannTyton Group Plc. and Metsec Plc. are notable contenders, known for their expertise in cable management solutions catering to diverse industries. MK Electric, Marshall-Tufflex Ltd., and Marco Cable Management also play significant roles in the market, each offering specialized solutions tailored to specific customer needs. Eaton Corporation, a global power management company, brings innovative cable management solutions to the market, further intensifying competition among the leading players.
Recent Developments
In June 2022, Atkore Inc. revealed the purchase of United Poly Systems. This company produces High-Density Polyethylene (HDPE) pressure pipes and conduits for telecommunications, water infrastructure, renewable energy, and other industries.
In August 2022, Leviton announced the debut of their Decora Smart Wi-Fi 2nd Generation Fan Speed Controller to make integrating ceiling fan control into a smart home easier.
Market Concentration & Characteristics
The UK Cable Management System Market exhibits a moderate level of market concentration, characterized by the presence of several key players competing vigorously for market share. While the market is diverse, with numerous manufacturers and distributors offering a wide range of products, a handful of major players dominate the landscape. These leading companies, such as Legrand S.A., Atkore International Holdings Ltd., and Thomas & Betts Corporation, possess significant market influence due to their extensive product portfolios, strong brand recognition, and established distribution networks. However, the market also accommodates smaller and regional players, contributing to healthy competition and fostering innovation. Market characteristics include continuous technological advancements, stringent regulatory compliance requirements, and a growing emphasis on sustainability and safety. Overall, the market's competitive dynamics drive innovation, quality improvements, and customer-centric solutions, ensuring a dynamic and responsive industry landscape.
Report Coverage
The research report offers an in-depth analysis based on Product, Material, End-use, Distribution Channel and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Continued Growth: The UK Cable Management System Market is poised for sustained growth, driven by ongoing infrastructure development projects and increasing demand for advanced connectivity solutions.
- Technological Advancements: Expect significant advancements in smart cable management systems, integrating IoT capabilities for remote monitoring and control.
- Focus on Sustainability: Manufacturers will prioritize eco-friendly materials and production processes to meet growing demand for sustainable solutions.
- Regulatory Compliance: Stricter adherence to building and safety regulations will drive innovation in safety features and fire-resistant materials.
- Expansion of E-commerce: Online channels will play a larger role in product distribution, offering convenience and accessibility to consumers and businesses.
- Integration with Smart Buildings: Cable management systems will be integral components of smart building infrastructure, enhancing efficiency and connectivity.
- Customization and Modular Solutions: Demand will grow for customizable and modular systems that can adapt to evolving technological and spatial needs.
- Emphasis on Aesthetics: Expect continued focus on aesthetically pleasing designs to complement modern architectural trends.
- Adoption of Renewable Energy: Cable management systems will play a crucial role in supporting the expansion of renewable energy installations.
- International Expansion: Leading players will explore opportunities for expansion into global markets, leveraging their expertise and product innovation.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Growth in the Construction Sector
The surge in new housing and commercial developments across the UK is significantly increasing the demand for cable management systems, as these installations require organized, safe, and compliant cable routing solutions to meet modern building standards.
Expansion of Data Centers and Digital Infrastructure
The rapid growth of data centers and the increasing adoption of cloud computing and IoT devices in the UK are driving the need for advanced cable management systems that can handle complex, high-density cabling while ensuring reliability and scalability.
Stringent Safety and Regulatory Compliance
Regulations such as BS 7671 mandate strict safety standards for electrical installations, compelling the adoption of certified cable management systems that reduce fire risks and ensure safe, standardized wiring practices across sectors.
Technological Advancements and Smart Systems
The shift towards smart and modular cable management solutions, which offer remote monitoring, adaptability, and integration with smart building technologies, is fueling market growth by meeting the evolving needs of modern infrastructure.
Focus on Fire-Resistant and Sustainable Materials
Increasing awareness of fire safety and sustainability is boosting demand for cable management systems made from fire-resistant and eco-friendly materials, aligning with regulatory requirements and customer preferences for safer, greener buildings.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the UK Cable Management System Market?
What factors are driving the growth of the UK Cable Management System Market?
What are the key segments within the UK Cable Management System Market?
What are some challenges faced by the UK Cable Management System Market?
Who are the major players in the UK Cable Management System Market?
Which segment is leading the market share?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End-use
- 1.2.1 IT & Telecom
- 1.2.2 Manufacturing
- 1.2.3 Energy & Utilities
- 1.2.4 Healthcare
- 1.2.5 Oil & Gas
- 1.2.6 Public Infrastructure
- 1.2.7 Commercial
- 1.2.8 Others
- 1.3 By Product
- 1.3.1 Cable Trays
- 1.3.2 Cable Raceways
- 1.3.3 Cable Conduits
- 1.3.4 Cable Connectors and Glands
- 1.3.5 Others
- 1.4 By Material
- 1.4.1 Metallic
- 1.4.2 Non-Metallic
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2023: USD 921.53 million → 2032: USD 2,001.46 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2023
- 2.6.2 Forecast Period: 2023-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2023
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 UK Cable Management Systems Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 UK Cable Management Systems Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2023-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2023-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 UK Cable Management Systems Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2023-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 UK Cable Management Systems Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 UK Cable Management Systems Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 UK Cable Management Systems Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Data Protection, AI and Cybersecurity Compliance
- 9.8 Upcoming Policy Changes and Market Implications
Chapter 10 UK Cable Management Systems Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 UK Cable Management Systems Market Outlook, 2023-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2023: USD 921.53 million → 2032: USD 2,001.46 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2023
- 11.2 Market Forecast, 2023-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 UK Cable Management Systems Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2023
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End-use - Market Size and Forecast, 2023-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2023-2032
- 12.3.4 Volume Forecast, 2023-2032
- 12.3.5 Base-Year Market Share, 2023
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 IT & Telecom
- 12.3.7.2 Manufacturing
- 12.3.7.3 Energy & Utilities
- 12.3.7.4 Healthcare
- 12.3.7.5 Oil & Gas
- 12.3.7.6 Public Infrastructure
- 12.3.7.7 Commercial
- 12.3.7.8 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Product - Market Size and Forecast, 2023-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2023-2032
- 12.4.4 Volume Forecast, 2023-2032
- 12.4.5 Base-Year Market Share, 2023
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Cable Trays
- 12.4.7.2 Cable Raceways
- 12.4.7.3 Cable Conduits
- 12.4.7.4 Cable Connectors and Glands
- 12.4.7.5 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Material - Market Size and Forecast, 2023-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2023-2032
- 12.5.4 Volume Forecast, 2023-2032
- 12.5.5 Base-Year Market Share, 2023
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Metallic
- 12.5.7.2 Non-Metallic
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 UK Cable Management Systems End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 UK Cable Management Systems Geographic Market Outlook, 2023-2032
- 14.1 Domestic Market Distribution and Demand Clusters
- 14.2 State- or Province-Wise Market Size and Forecast, 2023-2032
- 14.3 City and Metropolitan Market Outlook
- 14.4 Industrial, Manufacturing and Commercial Clusters
- 14.5 Geographic Concentration of Key End Users
- 14.6 Local Pricing and Purchasing Differences
- 14.7 Domestic Production Facilities and Capacity Map
- 14.8 Local Infrastructure and Project Pipeline
- 14.9 State-Level Policy and Incentive Differences
- 14.10 Subnational Investment Hotspots and Opportunities
- 14.11 Distribution and Logistics Networks
- 14.12 Domestic Competitive Footprint
Chapter 15 UK Cable Management Systems Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2023-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 UK Cable Management Systems Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2023
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2023-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Legrand S.A.
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Atkore International Holdings Ltd.
- 18.4 Thomas & Betts Corporation
- 18.5 Calpipe Industries Inc.
- 18.6 TE Connectivity Ltd.
- 18.7 HellermannTyton Group Plc.
- 18.8 Metsec Plc.
- 18.9 MK Electric
- 18.10 Marshall-Tufflex Ltd.
- 18.11 Marco Cable Management
- 18.12 Eaton Corporation
- 18.13 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

