
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
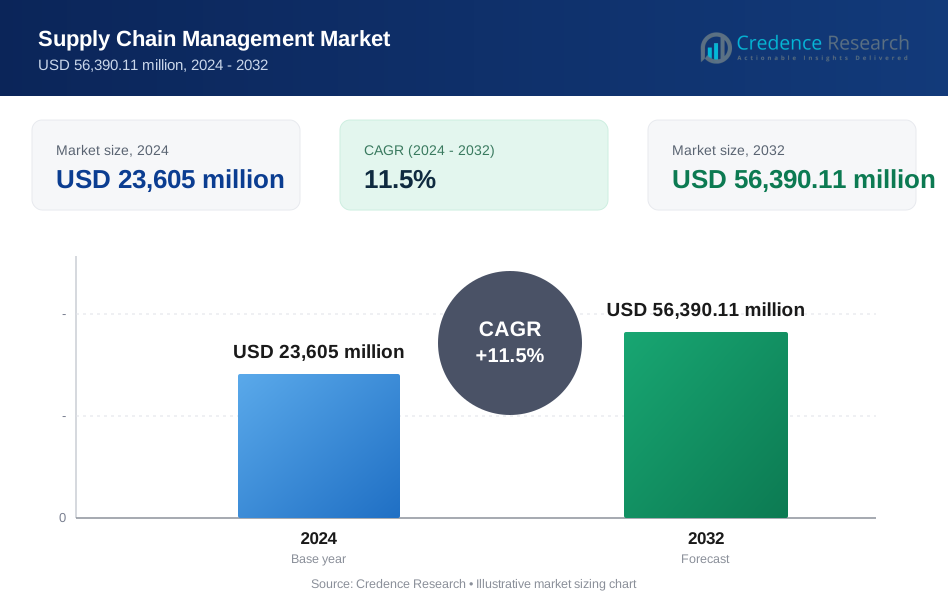
| Supply Chain Management Market Size 2024 | USD 23605 million |
| Supply Chain Management Market, CAGR | 11.5% |
| Supply Chain Management Market Size 2032 | USD 56390.11 million |
Market Overview:
The Supply Chain Management Market is projected to grow from USD 23605 million in 2024 to an estimated USD 56390.11 million by 2032, with a compound annual growth rate (CAGR) of 11.5% from 2024 to 2032.
Key drivers for the SCM market include rising globalization and the complexity of supply chains, which demand advanced technologies to improve transparency and mitigate risks. The advent of digitalization, IoT, artificial intelligence, and blockchain has revolutionized the industry, enabling companies to track assets in real-time, optimize logistics, and better manage inventory. The COVID-19 pandemic has underscored the importance of resilient supply chains, increasing the adoption of SCM solutions that can quickly adapt to disruptions. Furthermore, as companies prioritize sustainability, SCM platforms are evolving to include tools for monitoring and reducing environmental impact, aligning with consumer demand for eco-conscious practices. Collectively, these trends create strong momentum for SCM solutions, highlighting the importance of innovative and adaptable supply chain systems in today’s market landscape.
Regionally, North America and Europe dominate the SCM market due to their high adoption of technology and significant investment in supply chain infrastructure. North America, led by the United States, leverages advanced SCM solutions driven by robust e-commerce growth and a focus on improving customer experiences. Europe follows, with countries like Germany and the UK showing strong interest in automation and digital supply chain transformation, particularly within manufacturing. Meanwhile, the Asia-Pacific region is experiencing the fastest growth, driven by booming e-commerce markets in China and India, as well as increasing investments in digital infrastructure across Southeast Asia. Latin America and the Middle East are also emerging as promising markets, with governments and companies recognizing the need for supply chain efficiency amid expanding trade volumes and economic diversification efforts.
Market Drivers:
Increasing Complexity of Global Supply Chains:
The growing complexity of global supply chains is one of the primary drivers propelling the supply chain management (SCM) market forward. As companies expand into new markets and source materials from a diverse range of global suppliers, managing these complex, geographically dispersed supply chains has become challenging. The need for streamlined coordination across multiple regions has led businesses to adopt advanced SCM solutions that can integrate processes, track inventory in real-time, and enhance transparency. This complexity has amplified the importance of technologies that optimize sourcing, procurement, and distribution processes, ensuring efficient, responsive, and resilient supply chain networks.
Adoption of Digitalization and Emerging Technologies:
The digital transformation sweeping across industries is significantly impacting the SCM market. Technologies such as the Internet of Things (IoT), artificial intelligence (AI), and machine learning (ML) have revolutionized SCM by enabling real-time data tracking, predictive analytics, and automation. For example, IBM research indicates that supply chain executives anticipate significant investments in cognitive computing and cloud applications for digital operations in the coming years. IoT devices are widely used to monitor shipments and inventory levels, providing accurate and timely data across the supply chain. AI and ML applications in SCM allow for advanced demand forecasting, risk management, and automated decision-making, helping companies minimize human error and optimize operations. Blockchain technology is also gaining traction, especially for enhancing traceability and authenticity in sectors like food, pharmaceuticals, and luxury goods, which benefit from transparent, secure, and tamper-proof tracking systems.
E-Commerce Growth and Demand for Real-Time Visibility:
The rapid expansion of e-commerce, particularly accelerated by the COVID-19 pandemic, has intensified the demand for efficient and agile SCM solutions. E-commerce has transformed consumer expectations, with speed, convenience, and visibility becoming top priorities. This shift has led businesses to invest in SCM systems that enable real-time visibility and accurate tracking, offering customers transparency in order fulfillment. For instance, roughly 2.14 billion online shoppers made purchases worth a combined total of $4.9 trillion in 2021. As e-commerce continues to grow, so does the demand for SCM solutions that support last-mile delivery optimization, inventory management, and returns handling. The ability to manage increased order volumes while maintaining accuracy and speed has made SCM solutions essential for companies looking to compete in the digital economy.
Focus on Sustainability and Environmental Responsibility:
Environmental sustainability is emerging as a critical factor influencing supply chain decisions, with consumers, investors, and regulatory bodies calling for eco-friendlier practices. In response, companies are integrating sustainability into their supply chain operations, seeking to reduce carbon emissions, minimize waste, and use resources efficiently. SCM solutions now often include features for monitoring environmental impact, optimizing routes to lower fuel consumption, and managing sustainable sourcing practices. For instance, Mylan (now part of Viatris) launched a patient support program called Mylan Advocate for its trastuzumab biosimilar, offering financial assistance and educational resources. This trend aligns with corporate social responsibility goals and regulatory requirements aimed at reducing environmental footprints. As a result, the SCM market is seeing increased demand for solutions that support sustainability, making it a crucial driver in the industry’s evolution and attracting investment from organizations prioritizing green supply chain practices.
Market Trends:
Rise of Artificial Intelligence and Predictive Analytics:
One of the most prominent trends in the supply chain management (SCM) market is the integration of artificial intelligence (AI) and predictive analytics. Companies increasingly rely on AI-driven solutions to optimize inventory management, enhance demand forecasting, and streamline operations. Predictive analytics allows businesses to anticipate potential disruptions and proactively manage risks, helping maintain smooth operations and reducing downtime. Through AI, companies can utilize vast amounts of historical and real-time data to make data-driven decisions, increase accuracy in demand forecasting, and optimize production planning. This trend is strengthening as AI and analytics technologies become more accessible and integral to competitive SCM practices.
Expansion of Blockchain for Transparency and Traceability:
Blockchain technology is rapidly gaining traction in SCM due to its potential to improve transparency, traceability, and security within supply chains. In industries like pharmaceuticals, food, and luxury goods, where authenticity and traceability are critical, blockchain provides an immutable ledger that records every transaction, ensuring that data cannot be altered or tampered with. This level of transparency builds trust with consumers and allows companies to quickly trace the origin and movement of products. As regulatory requirements around transparency and accountability increase, particularly concerning ethically sourced and environmentally sustainable products, blockchain adoption in SCM continues to grow, transforming how goods are tracked and verified across the supply chain.
Growing Importance of Last-Mile Delivery Solutions:
As e-commerce and direct-to-consumer models expand, last-mile delivery solutions have become a major focus within SCM. The rise of online shopping has elevated consumer expectations for fast, flexible, and convenient deliveries, creating demand for SCM solutions that support last-mile efficiency. Companies are adopting advanced routing software, local warehousing strategies, and alternative delivery methods, such as drones and autonomous vehicles, to meet these expectations. Additionally, real-time tracking capabilities in last-mile logistics allow customers to monitor their shipments and enhance their purchasing experience. This emphasis on last-mile delivery optimization reflects a growing trend toward customer-centric supply chain models, particularly in urban areas where rapid delivery is increasingly seen as a competitive advantage.
Shift Toward Sustainable and Resilient Supply Chains:
Sustainability and resilience are becoming core tenets of supply chain management strategies. With increasing pressure from consumers, regulatory bodies, and investors to adopt environmentally friendly practices, companies are now implementing SCM solutions that promote sustainability. These solutions often feature carbon tracking, route optimization, and supply chain traceability to help organizations minimize their environmental footprint. For instance, companies are investing in resilience-focused SCM practices, such as diversifying suppliers, implementing risk management protocols, and building contingency plans to withstand disruptions. This dual focus on sustainability and resilience ensures that supply chains are both environmentally responsible and capable of adapting to unforeseen challenges, such as natural disasters or geopolitical shifts, positioning SCM as a pivotal element in future-proofing business operations.
Market Restraints and Challenges:
High Implementation and Maintenance Costs:
One of the key restraints in the supply chain management (SCM) market is the significant investment required for implementing and maintaining advanced SCM solutions. The adoption of technologies like AI, IoT, and blockchain requires substantial upfront capital, making it challenging for small and medium-sized enterprises (SMEs) to leverage these advanced tools. Additionally, the cost of maintaining and upgrading these systems to keep pace with technological advancements can strain budgets, especially as companies need to integrate new features and functionalities to remain competitive. These financial demands create barriers for smaller players and limit the scalability of SCM solutions in cost-sensitive markets.
Data Security and Privacy Concerns:
As supply chains become increasingly digital, data security and privacy concerns are also growing, acting as significant challenges within the SCM market. SCM platforms involve the exchange and storage of sensitive data, including supplier information, production details, and customer data. The risk of cyber-attacks and data breaches can deter companies from adopting cloud-based SCM solutions or sharing critical data across interconnected systems. Ensuring data security requires additional investment in cybersecurity measures, compliance with regulatory standards, and ongoing monitoring, which can be burdensome for organizations, particularly those operating across multiple regulatory jurisdictions.
Complexity of Integration and Interoperability Issues:
Integrating SCM solutions with legacy systems and ensuring interoperability between various supply chain components can pose major challenges. Many organizations rely on outdated infrastructure that may not be fully compatible with advanced SCM technologies, resulting in disruptions during implementation and prolonged adaptation periods. Achieving seamless integration requires specialized expertise and time, which can delay return on investment and reduce operational efficiency. Furthermore, the lack of standardized protocols across SCM systems can complicate data sharing between different platforms, creating inefficiencies and limiting the potential benefits of adopting advanced SCM solutions.
Market Segmentation Analysis:
The supply chain management (SCM) market is segmented by component, solution type, deployment mode, enterprise size, and industry vertical, each contributing uniquely to market dynamics and demand patterns.
By component, the market divides into solutions and services, with the solutions segment leading due to the widespread adoption of end-to-end SCM platforms that support comprehensive operational integration. The services segment, including consulting, implementation, and support, plays a critical role in facilitating seamless integration and optimizing performance across industries.
By solution type, the market includes transportation management systems, warehouse management systems, supply chain planning, procurement and sourcing, and manufacturing execution systems. Transportation and warehouse management systems dominate this segment as companies prioritize streamlined logistics and storage solutions to improve efficiency and meet rising e-commerce demands. Supply chain planning also shows strong growth potential, driven by the need for accurate forecasting and inventory optimization.
By deployment mode segment covers on-premise and on-demand/cloud-based options. Cloud-based SCM solutions are gaining traction due to their scalability, accessibility, and cost-effectiveness, making them particularly appealing for SMEs. However, large enterprises with high data security demands often prefer on-premise solutions.
By enterprise size, large enterprises are the primary adopters of SCM solutions, but the demand from SMEs is growing as cloud-based options make SCM more accessible.
By Industry verticals, including retail and consumer goods, healthcare, manufacturing, food and beverages, transportation and logistics, and automotive, reflect the diverse application of SCM solutions, with high demand in retail and manufacturing due to the need for efficient supply chain coordination.
Segmentation:
By Component
- Solution
- Service
By Solution Type
- Transportation Management System
- Warehouse Management System
- Supply Chain Planning
- Procurement and Sourcing
- Manufacturing Execution System
By Deployment Mode
- On-premise
- On-Demand/Cloud-Based
By Enterprise Size
- Large Enterprise
- SMEs
By Industry Vertical
- Retail and Consumer Goods
- Healthcare and Pharmaceuticals
- Manufacturing
- Food and Beverages
- Transportation and Logistics
- Automotive
- Others
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
North America holds a significant share in the global supply chain management (SCM) market, driven primarily by the rapid adoption of advanced technologies and the presence of key industry players. The United States and Canada lead the region, together accounting for approximately 35-40% of the global SCM market share. The high level of digitalization in sectors like retail, manufacturing, and healthcare fuels demand for SCM solutions that enhance operational efficiency and customer experience. Additionally, the region’s robust e-commerce industry and strong focus on optimizing logistics operations further boost demand for SCM systems. Government initiatives to enhance supply chain transparency and resilience also contribute to growth, particularly in light of recent global supply chain disruptions.
Europe
Europe is another prominent region in the SCM market, holding around 25-30% of the global market share. Countries such as Germany, the UK, and France lead this regional market, benefiting from well-established manufacturing sectors and strong e-commerce growth. The adoption of SCM solutions in Europe is heavily influenced by the need for efficiency in managing complex, multi-country supply chains. Additionally, stringent regulatory requirements, particularly around data protection and environmental sustainability, have encouraged companies to adopt SCM systems that can ensure compliance and promote transparency. European firms also prioritize sustainable supply chain practices, driving demand for SCM solutions that include tools for monitoring and reducing environmental impact.
Asia-Pacific
Asia-Pacific is the fastest-growing region in the SCM market, currently accounting for approximately 20-25% of the global market share. This growth is largely driven by expanding economies such as China, India, and Japan, where rapid industrialization, urbanization, and rising consumer demand drive the need for efficient supply chain operations. The region’s booming e-commerce market has led companies to invest in SCM solutions that enhance last-mile delivery and inventory management. Additionally, governments in the region are investing in digital infrastructure, which facilitates the adoption of cloud-based SCM solutions, especially among small and medium-sized enterprises (SMEs). The emphasis on regional trade agreements and investments in smart manufacturing further strengthens SCM adoption across industries.
Latin America and the Middle East & Africa
Latin America and the Middle East & Africa (MEA) together hold a smaller share of the SCM market, accounting for around 10-15% combined. In Latin America, Brazil and Mexico are the leading markets, with growth supported by the expansion of e-commerce and efforts to modernize logistics infrastructure. The region’s increasing participation in global trade encourages companies to adopt SCM solutions to manage complex cross-border supply chains. Meanwhile, in the MEA region, the focus on economic diversification, particularly in the Gulf countries, drives demand for SCM solutions across sectors like logistics, retail, and manufacturing. Although adoption remains slower than in other regions, government-led initiatives to strengthen supply chain resilience and reduce dependency on imports are expected to spur SCM market growth in these regions.
Key Player Analysis:
- Blue Yonder Group
- EPICOR SOFTWARE CORPORATION
- IBM Corporation
- Infor
- Kinaxis
- körber ag
- Manhattan Associates
- Oracle Corporation
- SAP SE
- THE DESCARTES SYSTEMS GROUP INC
Competitive Analysis:
The supply chain management (SCM) market is highly competitive, with major players like SAP SE, Oracle Corporation, IBM Corporation, and Manhattan Associates leading in market share. These companies leverage their extensive portfolios of advanced solutions, including AI-driven analytics, blockchain integration, and real-time tracking capabilities, to serve a wide range of industries. Key players focus on enhancing their platforms with cloud-based and mobile-friendly features, catering to both large enterprises and small and medium-sized businesses (SMEs). Emerging competitors and specialized providers also play a crucial role, especially in niche segments like last-mile delivery optimization and sustainable supply chain solutions. Partnerships, acquisitions, and strategic collaborations are common, as companies aim to expand their geographic presence and diversify their offerings. The market's competitive landscape is shaped by rapid technological innovation, emphasizing flexibility, resilience, and customer-centric features that meet the evolving demands of modern supply chains.
Recent Developments:
- In May 2023, Accenture and Blue Yonder, Inc. expanded their strategic partnership to enhance supply chains by combining Accenture’s technological expertise with Blue Yonder’s platform capabilities. Accenture’s cloud-native platform engineers and industry specialists are collaborating with Blue Yonder on the Blue Yonder Luminate Platform to develop solutions that provide end-to-end supply chain synchronization. This partnership focuses on creating a modular, digitized, and agile supply chain through co-innovation and leveraging emerging technologies like generative AI and robotic process automation.
- In April 2023, Oracle launched advanced artificial intelligence (AI) and automation capabilities to help customers optimize their supply chain management processes. These new features employ AI and automation to boost efficiency, streamline operations, and improve decision-making in supply chain management. The updates include enhanced quote-to-cash functionalities within Oracle Fusion applications, as well as new planning, usage-based pricing, and rebate management features in Oracle Fusion Cloud Supply Chain & Manufacturing (SCM).
- In May 2022, Kinaxis unveiled advancements in supply chain planning with the release of its new Planning feature, showcased at Kinexions 2022, the company’s annual supply chain innovation conference. This feature, part of the Kinaxis RapidResponse platform, incorporates an AI-driven analytical technique that can automatically determine the optimal combination of heuristics, optimization, and machine learning for concurrent planning.
Market Concentration & Characteristics:
The supply chain management (SCM) market is moderately concentrated, with a mix of large, established players and specialized vendors shaping its competitive landscape. Major companies like SAP SE, Oracle Corporation, IBM Corporation, and Manhattan Associates hold substantial market share due to their extensive offerings and established client bases across diverse industries. These dominant players set industry standards, particularly through advanced solutions integrating AI, IoT, and cloud technologies. The market is characterized by rapid technological innovation, as companies increasingly demand agile, scalable, and digitized solutions that address complex supply chain needs. Smaller and emerging firms play an essential role by offering niche, customized solutions, such as last-mile delivery optimization and sustainable supply chain management. The SCM market’s competitive dynamics are defined by partnerships, acquisitions, and product development, aimed at delivering enhanced functionality, modularity, and sustainability to meet evolving client demands across industries and regions.
Report Coverage:
The research report offers an in-depth analysis based on By Component, By Solution Type, By Deployment Mode, By Enterprise Size and By Industry Vertical. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Accelerated adoption of AI and machine learning will enhance predictive analytics, demand forecasting, and automation across supply chains.
- Increasing focus on sustainability will drive demand for SCM solutions that monitor environmental impact and optimize resource use.
- Rising e-commerce growth will boost last-mile delivery solutions, pushing companies to enhance real-time tracking and fulfillment capabilities.
- Blockchain technology adoption will expand, supporting transparency and traceability in sectors like pharmaceuticals and food.
- Cloud-based SCM solutions will continue growing, as businesses prioritize scalability, cost-efficiency, and accessibility for global operations.
- Integration of IoT will enable real-time asset tracking, improving inventory management and reducing supply chain disruptions.
- Expansion into emerging markets, particularly in Asia-Pacific, will fuel demand for agile, digital-first SCM systems.
- Partnerships and acquisitions will intensify as firms strive to innovate and broaden their SCM offerings across regions and industries.
- Automation, including robotics in warehouses, will drive efficiency and reduce operational costs in distribution and logistics.
- Increasing cyber threats will prompt stronger investments in data security within SCM systems, emphasizing data integrity and protection.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Increasing Complexity of Global Supply Chains
As companies expand internationally and source from diverse suppliers, managing complex, geographically dispersed supply chains requires advanced SCM solutions for real-time tracking, integration, and transparency, driving market growth.
Adoption of Digitalization and Emerging Technologies
The integration of IoT, AI, machine learning, and blockchain into SCM enables real-time data tracking, predictive analytics, and automation, making supply chains more efficient, resilient, and responsive to disruptions.
E-Commerce Growth and Demand for Real-Time Visibility
The rapid rise of e-commerce, especially post-pandemic, has heightened the need for agile SCM systems that support last-mile delivery, inventory optimization, and real-time order tracking to meet consumer expectations for speed and transparency.
Focus on Sustainability and Environmental Responsibility
Growing regulatory and consumer pressure for eco-friendly practices is pushing companies to adopt SCM solutions that monitor and reduce environmental impact, optimize resource use, and support sustainable sourcing.
Need for Supply Chain Resilience
Recent global disruptions have underscored the importance of resilient supply chains, prompting organizations to invest in SCM platforms that can quickly adapt to unforeseen events and ensure business continuity.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the size of Supply Chain Management Market?
What key factors are driving the SCM market growth?
Which regions lead the SCM market?
What challenges face the SCM market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Component
- 1.2.1 Solution
- 1.2.2 Service
- 1.3 By Solution Type
- 1.3.1 Transportation Management System
- 1.3.2 Warehouse Management System
- 1.3.3 Supply Chain Planning
- 1.3.4 Procurement and Sourcing
- 1.3.5 Manufacturing Execution System
- 1.4 By Deployment Mode
- 1.4.1 On-premise
- 1.4.2 On-Demand/Cloud-Based
- 1.5 By Industry Vertical
- 1.5.1 Retail and Consumer Goods
- 1.5.2 Healthcare and Pharmaceuticals
- 1.5.3 Manufacturing
- 1.5.4 Food and Beverages
- 1.5.5 Transportation and Logistics
- 1.5.6 Automotive
- 1.5.7 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 23,605 million → 2032: USD 56,390.11 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Supply Chain Management Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Supply Chain Management Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Supply Chain Management Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Supply Chain Management Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Supply Chain Management Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Supply Chain Management Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Data Protection, AI and Cybersecurity Compliance
- 9.8 Upcoming Policy Changes and Market Implications
Chapter 10 Global Supply Chain Management Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Supply Chain Management Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 23,605 million → 2032: USD 56,390.11 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Supply Chain Management Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Component - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Solution
- 12.3.7.2 Service
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Solution Type - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Transportation Management System
- 12.4.7.2 Warehouse Management System
- 12.4.7.3 Supply Chain Planning
- 12.4.7.4 Procurement and Sourcing
- 12.4.7.5 Manufacturing Execution System
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Deployment Mode - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 On-premise
- 12.5.7.2 On-Demand/Cloud-Based
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Industry Vertical - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Retail and Consumer Goods
- 12.6.7.2 Healthcare and Pharmaceuticals
- 12.6.7.3 Manufacturing
- 12.6.7.4 Food and Beverages
- 12.6.7.5 Transportation and Logistics
- 12.6.7.6 Automotive
- 12.6.7.7 Others
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Supply Chain Management End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Supply Chain Management Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Supply Chain Management Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Supply Chain Management Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 SAP SE
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Oracle Corporation
- 18.4 IBM Corporation
- 18.5 Manhattan Associates
- 18.6 Blue Yonder Group
- 18.7 Infor
- 18.8 Kinaxis
- 18.9 EPICOR SOFTWARE CORPORATION
- 18.10 körber ag
- 18.11 THE DESCARTES SYSTEMS GROUP INC
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

