
Market Overview
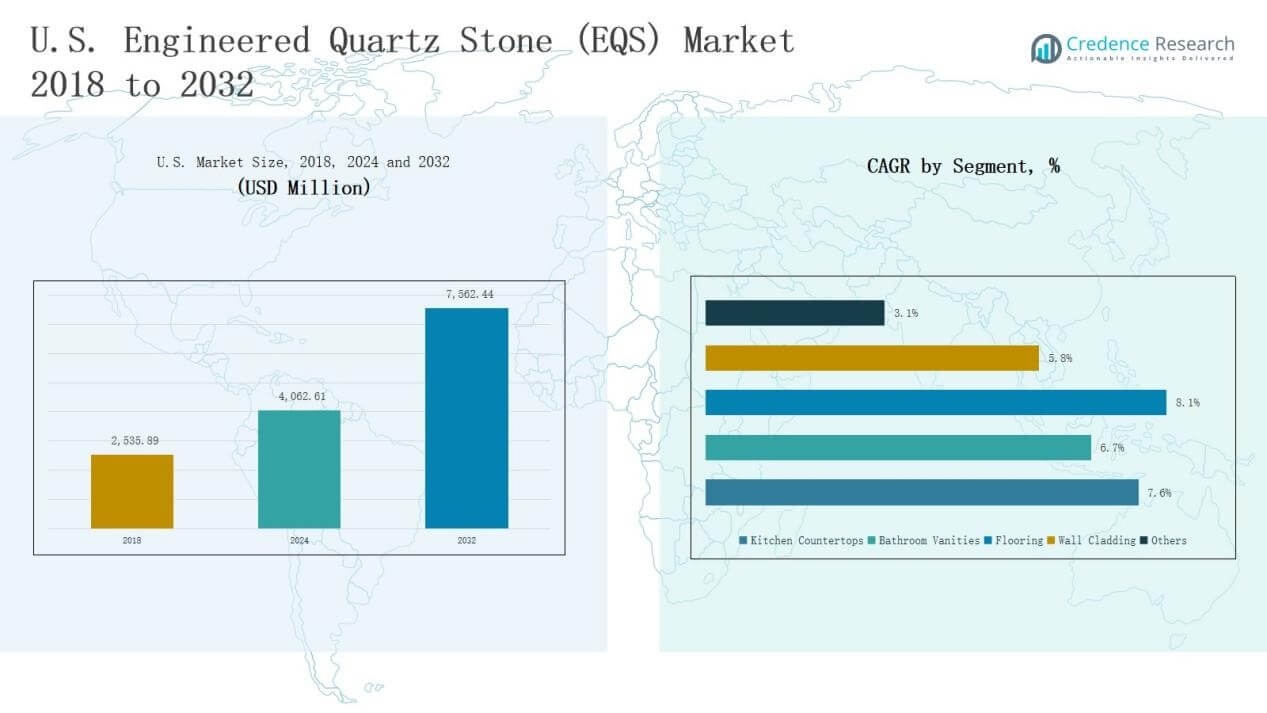
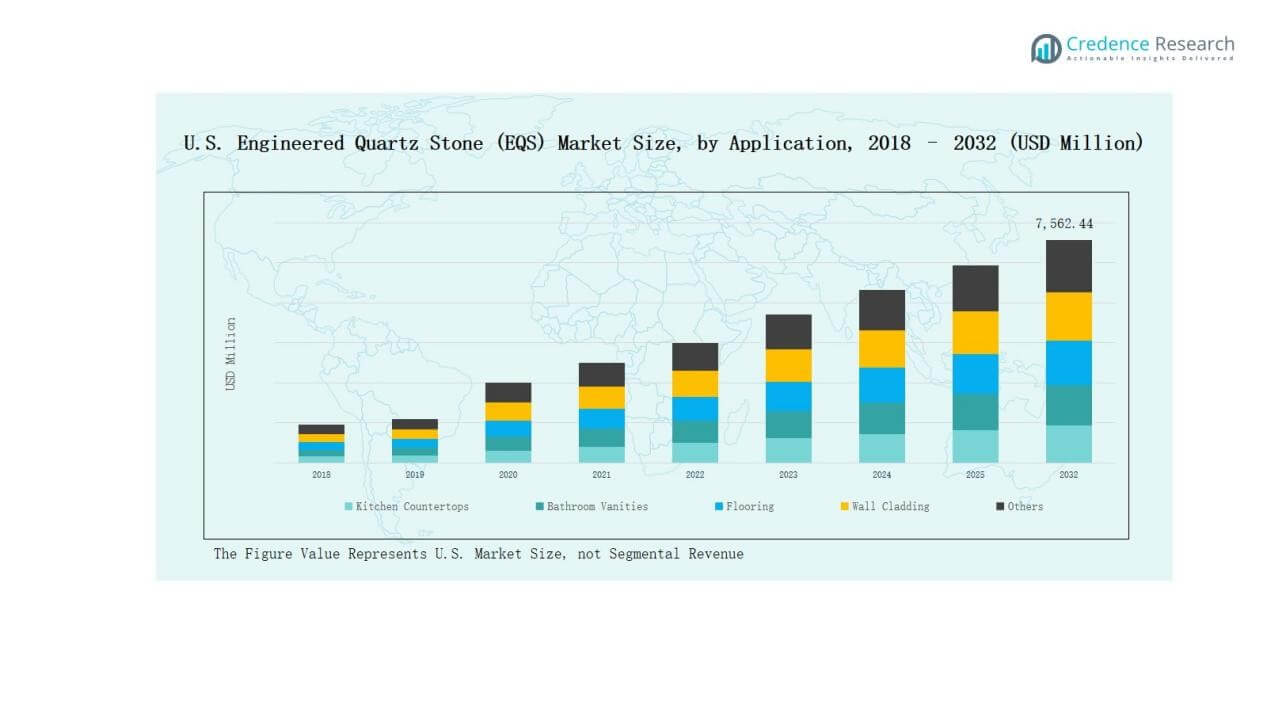
U.S. Engineered Quartz Stone (EQS) Market size was valued at USD 2,535.89 million in 2018, reached USD 4,062.61 million in 2024, and is anticipated to reach USD 7,562.44 million by 2032, at a CAGR of 7.52% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| U.S. Engineered Quartz Stone (EQS) Market Size 2024 | USD 4,062.61 Billion |
| U.S. Engineered Quartz Stone (EQS) Market, CAGR | 7.52% |
| U.S. Engineered Quartz Stone (EQS) Market Size 2032 | USD 7,562.44 Billion |
The U.S. Engineered Quartz Stone (EQS) Market is shaped by leading companies including Cambria, Caesarstone, Silestone, MSI Surfaces, HanStone Quartz, Corian Quartz by DuPont, Daltile ONE Quartz, Wilsonart Quartz, Vicostone, and LX Hausys Viatera. These players compete through product innovation, advanced finishes, sustainable solutions, and extensive distribution networks. They focus on expanding customization, eco-friendly designs, and partnerships with contractors and retailers to strengthen market presence. Regionally, the South led with 36% share in 2024, driven by rapid urban expansion, strong residential construction, and commercial development.
 Market Insights
- The U.S. Engineered Quartz Stone (EQS) Market grew from USD 2,535.89 million in 2018 to USD 4,062.61 million in 2024 and is expected to reach USD 7,562.44 million by 2032, growing at 7.52%.
- Kitchen countertops led applications with 47% share in 2024, followed by bathroom vanities at 23%, flooring at 15%, wall cladding at 9%, and others at 6%.
- Distributors and dealers dominated distribution channels with 41% share in 2024, while direct sales captured 28%, home improvement retailers 19%, and others including online platforms 12%.
- Regionally, the South held the largest share with 36% in 2024, while the Northeast contributed 24%, the West 22%, and the Midwest 18%.
- Key players include Cambria, Caesarstone, Silestone, MSI Surfaces, HanStone Quartz, Corian Quartz by DuPont, Daltile ONE Quartz, Wilsonart Quartz, Vicostone, and LX Hausys Viatera.
Market Segment Insights
By Application
In the U.S. Engineered Quartz Stone (EQS) Market, kitchen countertops dominated with 47% share in 2024, supported by high demand for durable, stain-resistant, and versatile surfaces in modern homes and remodeling projects. Bathroom vanities followed with 23% share, driven by resistance to moisture and growing preference for spa-like interiors. Flooring accounted for 15%, favored in commercial spaces for its durability, while wall cladding held 9%, mainly in luxury interiors. The “Others” category, including backsplashes and tabletops, represented 6%, offering niche growth opportunities.
For instance, Caesarstone introduced its Porcelain collection in the U.S., expanding options for countertops and wall applications with high heat and scratch resistance.
By Distribution Channel
Distributors and dealers led the market with 41% share in 2024, supported by broad networks that ensure accessibility across U.S. regions. Direct sales captured 28%, strengthened by bulk contracts with builders and contractors. Home improvement retailers held 19%, benefiting from DIY culture and consumer renovations, while the “Others” category, including online platforms and specialty outlets, accounted for 12%. These varied channels highlight the market’s strong reliance on both traditional distribution and emerging digital pathways for expansion.
For instance, Builders FirstSource expanded its distribution footprint by opening a new distribution yard in Sanford, Florida, aimed at improving material access for residential and commercial contractors.
Key Growth Drivers
Rising Demand for Residential Remodeling
The U.S. EQS market is strongly driven by increasing residential remodeling activities. Homeowners are upgrading kitchens and bathrooms with durable, non-porous, and low-maintenance surfaces. Engineered quartz meets consumer demand for style flexibility, offering designs that replicate marble and granite without the maintenance challenges. The surge in home improvement projects post-pandemic, combined with rising disposable incomes, has reinforced demand. Builders and contractors actively promote quartz over natural stone, citing its superior durability, consistent quality, and long-term cost advantages in residential installations.
For instance, Cosentino expanded its Silestone Ethereal line, offering new colors with HybriQ+ technology that integrates recycled materials and reduces silica content, directly targeting eco-conscious residential renovators.
Expansion of Commercial Infrastructure
Growing investment in commercial spaces such as hotels, offices, and retail outlets supports EQS adoption. Architects and contractors increasingly specify quartz for countertops, flooring, and reception areas due to its longevity and aesthetic consistency. The material’s resistance to heavy traffic, stains, and bacteria aligns with strict commercial standards. The hospitality and office sector’s focus on modern and sustainable interior designs strengthens demand. This infrastructure expansion, coupled with urban development initiatives, positions EQS as a preferred material for large-scale commercial projects across the U.S.
Shift Toward Sustainable Surfaces
Environmental awareness is boosting demand for sustainable materials, making engineered quartz attractive. Manufacturers increasingly integrate recycled glass, silica-free compositions, and eco-friendly resins to align with green building standards. Consumers prefer quartz surfaces due to their long lifespan, which reduces replacement frequency and waste generation. LEED-certified projects also encourage use of engineered quartz for energy-efficient and eco-compliant construction. This sustainability-driven demand enhances market growth, as suppliers innovate with new product lines featuring reduced water use, minimal emissions, and responsible sourcing practices.
For instance, Silestone by Cosentino rolled out its Sunlit Days series, the first carbon-neutral quartz collection, achieved through renewable energy use and certified offset programs.
 Key Trends & Opportunities
Growing DIY and Retail Segment
The rise of do-it-yourself culture in the U.S. presents opportunities for engineered quartz. Homeowners increasingly purchase ready-to-install quartz surfaces from home improvement retailers and online channels. Retail penetration offers consumers direct access to varied designs at competitive prices. Easy availability of mid-range options has expanded market reach, particularly among younger homeowners investing in first-time renovations. This trend supports growth for suppliers catering to the retail and online segment, making quartz more accessible and creating new sales pathways beyond dealer networks.
For instance, IKEA U.S. partnered with Caesarstone to supply durable quartz countertops in modular kitchen packages, giving customers customizable options tailored for self-installation.
Product Innovation and Customization
Product innovation continues to create opportunities in the U.S. EQS market. Manufacturers invest in advanced finishes, large-format slabs, and customizable edge profiles to appeal to premium buyers and designers. Color palettes inspired by natural stone, metallic finishes, and minimalist aesthetics are expanding adoption in both residential and commercial spaces. Customization enables alignment with evolving consumer preferences for unique interiors. Companies introducing crystalline silica-free and recycled-content surfaces strengthen their market positioning, catering to the dual demands of safety and sustainability.
For instance, Caesarstone launched a new crystalline silica-free quartz surface under its Mineral Surfaces Collection, engineered with sustainable materials to reduce health risks in fabrication.
Key Challenges
High Competition from Alternatives
The market faces challenges from substitute materials such as granite, marble, and solid surface composites. While engineered quartz offers advantages, natural stones maintain strong appeal in luxury projects due to their exclusivity and unique patterns. Solid surfaces and laminates also attract cost-sensitive buyers. This competitive landscape requires EQS suppliers to differentiate through pricing, design innovation, and sustainability features. Without strong marketing and awareness campaigns, quartz adoption may be restricted in certain customer segments favoring traditional or cheaper alternatives.
Supply Chain and Raw Material Costs
Volatility in raw material availability and pricing challenges market stability. Engineered quartz production relies on quartz aggregates, resins, and pigments, which are subject to global supply fluctuations. Rising energy and transportation costs further elevate production expenses. These factors pressure manufacturers to balance pricing with profitability. Disruptions, such as trade restrictions or shipping delays, can impact timely product delivery. Companies must adopt resilient supply chain strategies and explore local sourcing to mitigate risks and sustain competitive positioning in the U.S. market.
Regulatory and Environmental Compliance
Stringent regulations around crystalline silica exposure in manufacturing present challenges for EQS producers. Compliance with Occupational Safety and Health Administration (OSHA) standards requires significant investment in dust control, worker safety equipment, and updated processes. Non-compliance can result in penalties, reputational risks, and restrictions on market access. In addition, growing consumer awareness of health and environmental impacts forces companies to innovate toward silica-free and eco-friendly alternatives. Balancing compliance costs while maintaining profitability remains a major obstacle for market participants.
Regional Analysis
Northeast
The Northeast held 24% share in 2024 in the U.S. Engineered Quartz Stone (EQS) Market. It benefits from dense urban housing, premium kitchen remodeling, and strong adoption of luxury interiors in cities like New York and Boston. Demand is also supported by high disposable incomes and preference for durable, low-maintenance countertops. Architects and contractors promote quartz in multifamily housing and office projects. The region continues to lead in design-forward trends, making it a strong market for premium and customized surfaces.
Midwest
The Midwest accounted for 18% share in 2024, driven by steady residential construction and renovation projects across suburban areas. Engineered quartz is increasingly replacing laminate and solid surface materials due to its durability and cost efficiency. Growing awareness of sustainability and modern interior trends supports its use in mid-range housing projects. Commercial adoption also rises in hospitality and retail. The Midwest remains price-sensitive, yet it offers stable growth potential supported by its balanced mix of urban and suburban markets.
South
The South dominated with 36% share in 2024, establishing itself as the largest regional market. Strong population growth, urban expansion, and extensive new housing projects drive quartz demand. Kitchen countertops and bathroom vanities remain core applications, fueled by rising homeownership and large-scale residential developments. Builders and distributors play a vital role in promoting quartz as a standard in mid to high-end housing. Commercial growth in cities such as Atlanta, Dallas, and Miami further strengthens adoption, ensuring continued leadership.
West
The West contributed 22% share in 2024, shaped by strong consumer demand for sustainable and stylish surfaces. States like California emphasize eco-friendly building materials, giving quartz an edge over natural stone. High renovation spending and preference for premium interiors fuel adoption in both residential and commercial spaces. Quartz dominates kitchen countertop demand in urban areas, while growth in hospitality and tech-driven office projects adds momentum. The West continues to attract premium buyers, strengthening its importance in the national market.
 Market Segmentations:
By Application
- Kitchen Countertops
- Bathroom Vanities
- Flooring
- Wall Cladding
- Others
By Distribution Channel
- Direct Sales
- Distributors/Dealers
- Home Improvement Retailers
- Others
By Region
- Northeast
- Midwest
- South
- West
Competitive Landscape
The U.S. Engineered Quartz Stone (EQS) Market is highly competitive, with both domestic manufacturers and global brands shaping its growth. Leading players such as Cambria, Caesarstone, Silestone, MSI Surfaces, and HanStone Quartz maintain strong positions through extensive product portfolios, advanced finishes, and premium design offerings. Companies like Corian Quartz by DuPont, Daltile ONE Quartz, Wilsonart Quartz, Vicostone, and LX Hausys Viatera strengthen market presence through dealer networks, retail partnerships, and innovation in sustainable product lines. Competition is driven by design variety, durability, pricing strategies, and alignment with green building practices. Product differentiation through large-format slabs, crystalline silica-free solutions, and recycled-content materials is increasingly critical. Distributors and retailers further shape market dynamics by expanding access to diverse consumer groups. With rising demand from residential and commercial sectors, leading players continue to invest in customization, branding, and technological upgrades to secure long-term market advantage.
Key Players
- Cambria
- Corian Quartz (DuPont)
- Daltile ONE Quartz
- HanStone Quartz
- Caesarstone
- Silestone
- Wilsonart Quartz
- Vicostone
- MSI Surfaces
- LX Hausys Viatera
Recent Developments
- In May 2025, LOTTE Chemical partnered with EKO Stone to distribute Radianz Quartz across the U.S. Midwest.
- In August 2024, Vadara Quartz Surfaces launched four new distribution partnerships to expand its reach in the U.S. East Coast market.
- In April 2025, Cosentino introduced Silestone’s new “Hybrid Quartz,” blending minerals with recycled materials.
- In July 2025, Vicostone launched 10 new quartz colors for its Fall 2025 collection.
Report Coverage
The research report offers an in-depth analysis based on Application, Distribution Channel and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Kitchen countertops will continue to lead demand due to durability and design flexibility.
- Bathroom vanities will grow steadily with rising home renovation and wellness-focused interiors.
- Flooring applications will expand in commercial projects requiring long-lasting surfaces.
- Wall cladding will gain traction in luxury residential and hospitality developments.
- Distributors and dealers will remain the primary sales channel, ensuring wide market access.
- Home improvement retailers will grow with the rising do-it-yourself and retail renovation culture.
- Direct sales will strengthen through long-term partnerships with large builders and contractors.
- Sustainability-focused quartz products will gain preference in eco-conscious construction projects.
- Product innovation with customizable finishes and large slabs will drive premium adoption.
- Competitive pressure will increase as brands invest in branding, design variety, and safety features.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Residential Remodeling Boom
The surge in home renovation and remodeling projects, especially in kitchens and bathrooms, is fueling demand for engineered quartz stone due to its durability, low maintenance, and aesthetic versatility. Homeowners are increasingly choosing quartz over natural stone for its consistent quality and modern design options.
Commercial Infrastructure Expansion
Growing investments in commercial spaces such as hotels, offices, and retail outlets are driving adoption of engineered quartz stone for countertops, flooring, and wall cladding. The material’s resistance to heavy traffic, stains, and bacteria makes it ideal for high-use commercial environments.
Shift Toward Sustainable and Eco-Friendly Surfaces
Rising environmental awareness and green building standards are pushing manufacturers to develop quartz surfaces with recycled content, reduced silica, and eco-friendly resins. This aligns with consumer and regulatory demand for sustainable construction materials, boosting market growth.
Product Innovation and Customization
Manufacturers are investing in advanced finishes, large-format slabs, and customizable designs to meet evolving consumer preferences. Innovations such as silica-free and recycled-content quartz surfaces are attracting both residential and commercial buyers seeking safety and unique aesthetics.
Expansion of Distribution Networks
The dominance of distributors, dealers, and home improvement retailers ensures wide accessibility of engineered quartz stone across regions. The growth of DIY culture and online sales channels is further expanding market reach, making quartz surfaces more available to a broader customer base.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for U.S. Engineered Quartz Stone (EQS) Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the U.S. Engineered Quartz Stone (EQS) Market projected to grow between 2025 and 2032?
Which U.S. Engineered Quartz Stone (EQS) Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the U.S. Engineered Quartz Stone (EQS) Market?
Who are the leading companies in the U.S. Engineered Quartz Stone (EQS) Market?
Which region commanded the largest share of the U.S. Engineered Quartz Stone (EQS) Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Application
- 1.2.1 Kitchen Countertops
- 1.2.2 Bathroom Vanities
- 1.2.3 Flooring
- 1.2.4 Wall Cladding
- 1.2.5 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 4,062.61 million → 2032: USD 7,562.44 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 U.S. Engineered Quartz Stone Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 U.S. Engineered Quartz Stone Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 U.S. Engineered Quartz Stone Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 U.S. Engineered Quartz Stone Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 U.S. Engineered Quartz Stone Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 U.S. Engineered Quartz Stone Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 U.S. Engineered Quartz Stone Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 U.S. Engineered Quartz Stone Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 4,062.61 million → 2032: USD 7,562.44 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 U.S. Engineered Quartz Stone Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Application - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Kitchen Countertops
- 12.3.7.2 Bathroom Vanities
- 12.3.7.3 Flooring
- 12.3.7.4 Wall Cladding
- 12.3.7.5 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 Segment Growth Comparison
- 12.5 Segment Attractiveness and Priority Matrix
Chapter 13 U.S. Engineered Quartz Stone End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 U.S. Engineered Quartz Stone Geographic Market Outlook, 2024-2032
- 14.1 Domestic Market Distribution and Demand Clusters
- 14.2 State- or Province-Wise Market Size and Forecast, 2024-2032
- 14.3 City and Metropolitan Market Outlook
- 14.4 Industrial, Manufacturing and Commercial Clusters
- 14.5 Geographic Concentration of Key End Users
- 14.6 Local Pricing and Purchasing Differences
- 14.7 Domestic Production Facilities and Capacity Map
- 14.8 Local Infrastructure and Project Pipeline
- 14.9 State-Level Policy and Incentive Differences
- 14.10 Subnational Investment Hotspots and Opportunities
- 14.11 Distribution and Logistics Networks
- 14.12 Domestic Competitive Footprint
Chapter 15 U.S. Engineered Quartz Stone Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 U.S. Engineered Quartz Stone Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Cambria
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Caesarstone
- 18.4 Silestone
- 18.5 MSI Surfaces
- 18.6 HanStone Quartz
- 18.7 Corian Quartz (DuPont)
- 18.8 Daltile ONE Quartz
- 18.9 Wilsonart Quartz
- 18.10 Vicostone
- 18.11 LX Hausys Viatera
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

