EnQuest to sell UK North Sea business to NEO NEXT+ for up to $960 million
EnQuest has agreed to sell its entire U.K. upstream business, including the Kraken and Magnus fields and its operating role at the Sullom Voe Terminal in Shetland, to NEO NEXT+ for up to $960 million. The London-listed producer announced the deal on Nov. 18, 2026, one day after signing a share purchase agreement, and said the sale will leave it focused entirely on Southeast Asia once its pending Malaysian acquisitions close.
Key developments
- NEO NEXT+ Energy Upstream UK will buy all shares in EnQuest Britain Limited for $840 million in cash at completion, subject to closing adjustments, plus up to $120 million in contingent payments.
- The contingent element pays $0.20 per barrel of oil produced for each $1 that Brent averages above $75 a barrel in 2027, 2028 and 2029, and up to $100 million if the U.K. Energy Profits Levy is abolished or reduced before the end of 2029. Combined contingent payments are capped at $120 million.
- The perimeter covers the operated Magnus, Kraken and Greater Kittiwake Area assets, a non-operated interest in Golden Eagle, the undeveloped Bressay field, the Bentley discovery, the Sullom Voe Terminal operating interest, the Northern Leg Gas Pipeline and the Ninian Pipeline system.
- The business produced an average of 31,122 barrels of oil equivalent per day in 2025, 92% liquids, and held about 122 million barrels of oil equivalent of proven and probable reserves at the end of that year.
- The economic effective date is Jan. 1, 2027, and EnQuest expects completion in the first quarter of 2027.
Deal background
EnQuest was founded in 2010 as a U.K. North Sea specialist focused on mature fields. The disposal reverses that model. All U.K. decommissioning assets and liabilities move with EnQuest Britain Limited, along with the employees who support U.K. operations in Aberdeen, Shetland and offshore. At the end of 2025, the unit carried gross assets of $3.13 billion against total liabilities of $2.13 billion, covering decommissioning provisions, leases and other items, leaving net assets of $171 million.
The sale is tied to a second transaction. In June 2026, EnQuest agreed to buy interests in four offshore production sharing contracts in Malaysia from Petronas Carigali for up to $833 million, a deal large enough to count as a reverse takeover under U.K. listing rules, and expects it to complete on Dec. 31, 2026. Completion of the Malaysian deal is now a condition of the U.K. sale, together with approvals from the North Sea Transition Authority, clearance under the National Security and Investment Act, a Competition and Markets Authority review, lender consent and replacement of decommissioning security agreements. No shareholder vote is required for the disposal.
The buyer is itself the product of North Sea consolidation. NEO NEXT+ was formed in March 2026 when TotalEnergies merged its U.K. upstream business into NEO NEXT, with TotalEnergies taking a 47.5% stake in the enlarged company. At that time, the group described itself as the largest independent oil and gas producer on the U.K. Continental Shelf.
Industry implications
The transaction moves another tranche of mature U.K. production into the hands of a single large independent. Reuters reported that EnQuest is the latest producer to step back from the North Sea, following sales, mergers or retrenchment by ExxonMobil, Chevron, ConocoPhillips and Shell, while BP has put its own U.K. North Sea assets up for sale. EnQuest pointed to the uncertain U.K. investment environment as a driver of its decision.
The deal terms show how fiscal policy is now priced directly into asset sales. Up to $100 million of the consideration depends on Parliament abolishing or reducing the Energy Profits Levy, the windfall tax on oil and gas profits introduced in 2022. EnQuest also booked a $124 million non-cash tax charge in 2025 tied to the levy's extension. Buyer and seller are sharing the political risk through an earnout.
Competitive and supply chain implications
Control of Sullom Voe matters beyond EnQuest's own barrels. The terminal, together with the Ninian and Northern Leg pipeline systems, handles export flows for fields across the northern North Sea and West of Shetland. Moving operatorship to NEO NEXT+ places a key piece of shared midstream infrastructure inside a company that already runs a large portfolio of producing fields, giving it more influence over tariffs, maintenance planning and the timing of late-life decisions for third-party users.
For contractors, spending decisions become more concentrated. Drilling, subsea and decommissioning suppliers will now negotiate with a larger operator that can bundle work across assets. Decommissioning liabilities at Magnus, Kittiwake and Sullom Voe also transfer, so the eventual removal programs will be scheduled within NEO NEXT+'s wider portfolio rather than by a smaller, cash-constrained owner.
Regional implications
In Scotland, the immediate concern is continuity of jobs and operations in Aberdeen and Shetland. The release states that U.K. operations staff transfer with the business, but it does not give a headcount. Shetland's economy has close ties to Sullom Voe, and the identity of its operator will shape how long the terminal remains active as northern North Sea volumes decline.
In Southeast Asia, the effect runs the other way. After both transactions, EnQuest's remaining portfolio will sit in Malaysia, Vietnam, Brunei and Indonesia, plus its Veri Energy and carbon capture interests. On a 2025 pro forma basis, the company puts that business at about 70,000 barrels of oil equivalent per day, with 97% of proven and probable reserves under its own operation. For Malaysia, that means a Petronas partner whose capital is no longer split with the North Sea.
Credence Research analysis
The structure of this deal says as much as the price. EnQuest is handing over roughly $2.1 billion of liabilities, including future decommissioning obligations, in exchange for $840 million in upfront cash and a modest earnout. For a mid-sized producer, shedding those obligations may matter as much as the cash, because decommissioning security has tied up capital that could support production elsewhere. EnQuest's own figures show it is valuing the business at up to $9 per barrel of proven and probable reserves, a level that reflects both the age of the assets and the tax regime they operate under.
For the U.K. basin, the trend points toward fewer, larger operators running mature hubs and shared infrastructure. That can bring scale efficiencies and steadier stewardship of late-life assets, but it also concentrates the North Sea's remaining investment decisions in a small number of boardrooms. The Energy Profits Levy clause gives the government a clear signal: part of this transaction's value depends directly on future fiscal policy, and similar provisions are likely to appear in other North Sea deals while the levy remains in place.
What comes next
- EnQuest expects to complete its Malaysian acquisitions on Dec. 31, 2026, a condition of the U.K. sale.
- Regulators must sign off, including the North Sea Transition Authority, the National Security and Investment Act process and the Competition and Markets Authority.
- EnQuest plans to publish a supplementary prospectus and further disclosures required under U.K. listing rules before completion.
- Completion is targeted for the first quarter of 2027, with economics backdated to Jan. 1, 2027.
- The first possible oil price contingent payment falls due on March 1, 2028, based on 2027 Brent prices.
Sources
- EnQuest: Sale of UK Upstream Business to NEO NEXT+ for up to US$960 million (Nov. 18, 2026)
- EnQuest: Proposed acquisition of interests in four Malaysian PSCs (June 10, 2026)
- TotalEnergies completes merger of UK North Sea upstream assets with NEO NEXT (March 30, 2026)
- Reuters via BOE Report: EnQuest exits UK North Sea in $960 million sale (Nov. 18, 2026)
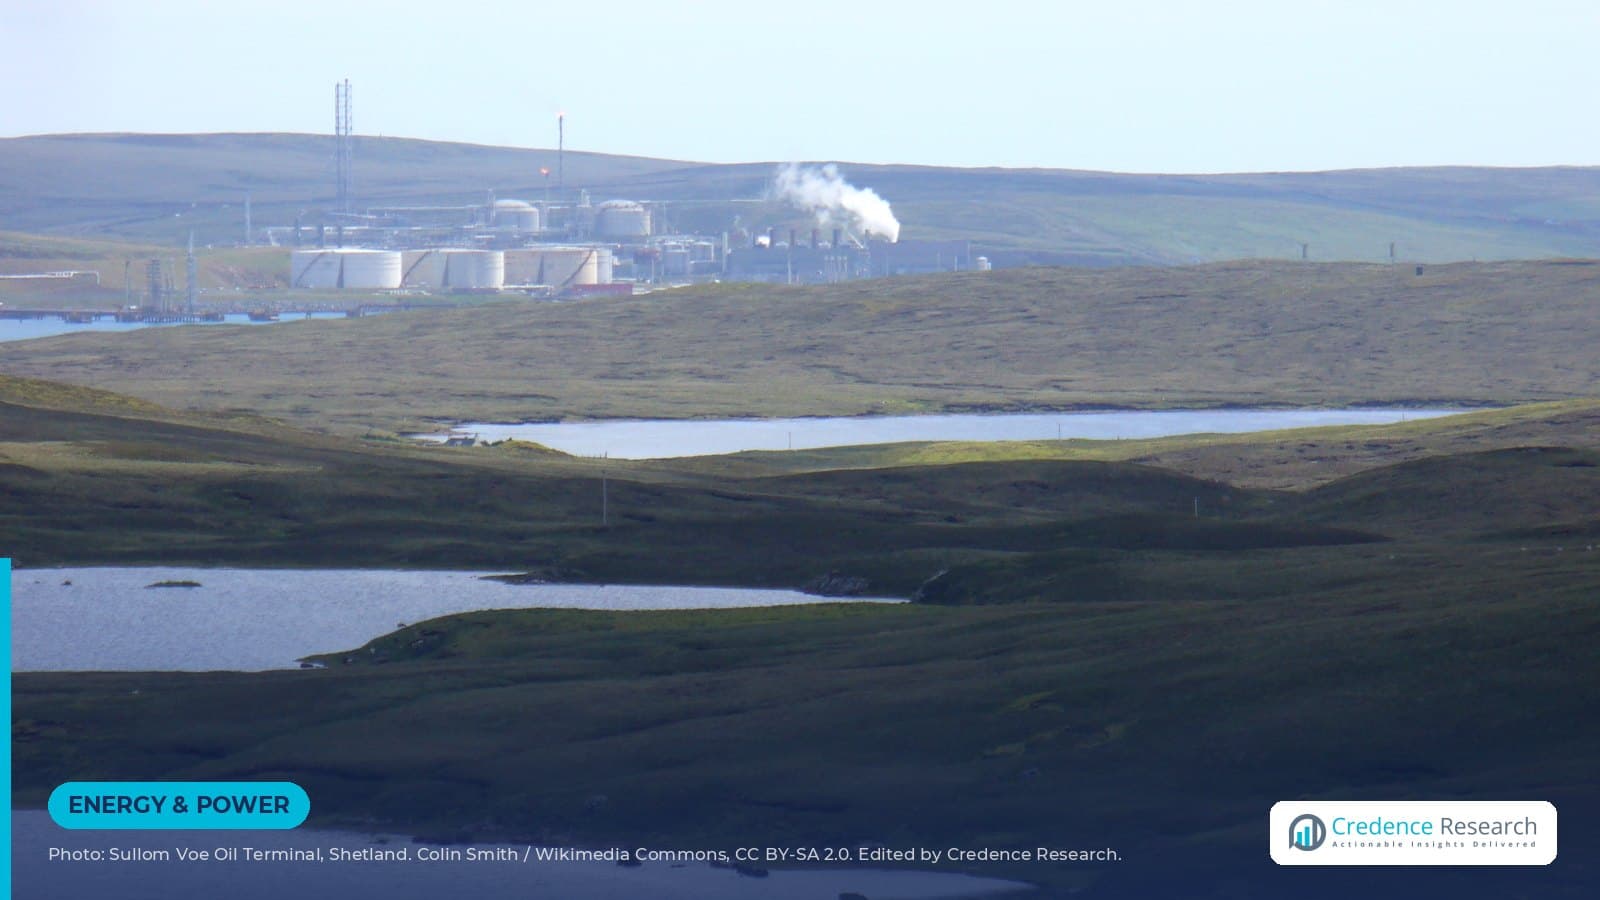
Image: Sullom Voe Oil Terminal, Shetland, by Colin Smith via Wikimedia Commons, CC BY-SA 2.0. Cropped and edited by Credence Research.

About the Author
Senior News Editor at Credence Research Inc