
Androgens and Anabolic Steroids Market Overview:
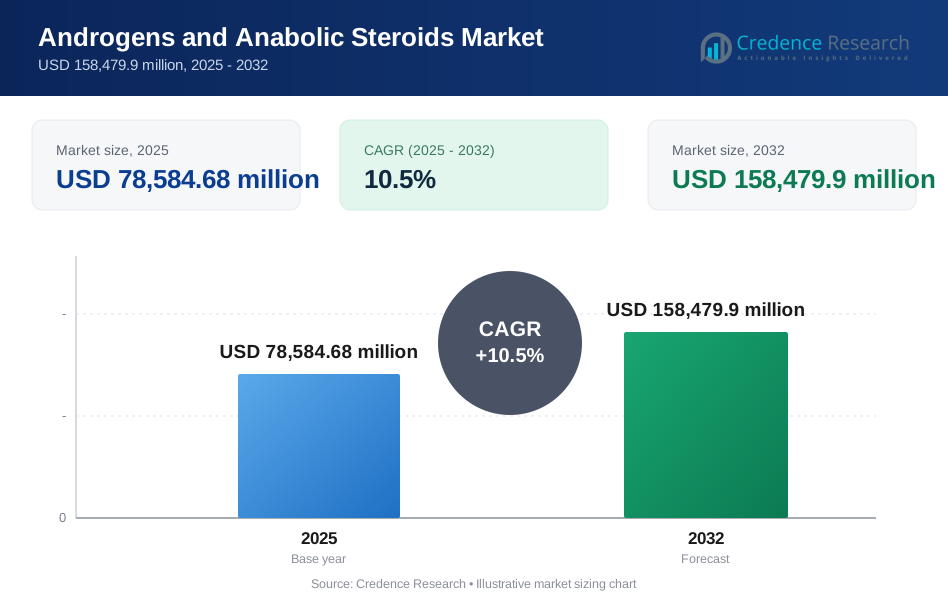
The Androgens and Anabolic Steroids Market is projected to grow from USD 78,584.68 million in 2025 to an estimated USD 158,479.9 million by 2032, with a compound annual growth rate (CAGR) of 10.5% from 2025 to 2032.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Androgens and Anabolic Steroids Market Size 2025 | USD 78,584.68 million |
| Androgens and Anabolic Steroids Market, CAGR | 10.5% |
| Androgens and Anabolic Steroids Market Size 2032 | USD 158,479.9 million |
Growth in this market is driven by rising diagnosis of hypogonadism, increasing awareness of age-related hormone decline, and broader access to structured endocrinology care. Physicians adopt clear clinical guidelines that support safe and regulated prescribing. Advanced formulations such as long-acting injectables and oral testosterone options improve adherence and expand patient choice. Therapeutic use in chronic disease–related muscle wasting strengthens demand across hospitals and specialty clinics. Growing interest in personalized hormone optimization encourages targeted treatment plans. Digital monitoring platforms enhance patient engagement and treatment continuity.
North America leads the market due to strong diagnostic penetration, established hormone therapy networks, and consistent physician oversight. Europe follows closely, supported by regulated prescription practices and rising awareness of male hormone health across major countries. Asia Pacific emerges as the fastest growing region driven by improving healthcare access in China, India, and Southeast Asia. Urbanization and expanding private healthcare systems encourage higher screening and treatment rates. Latin America demonstrates steady growth as endocrine services become more available. The Middle East and Africa show emerging potential with rising investment in specialty clinics and broader awareness of hormone imbalance.

Androgens and Anabolic Steroids Market Insights:
- The Androgens and Anabolic Steroids Market is projected to grow from USD 78,584.68 million in 2025 to USD 158,479.9 million by 2032, reflecting strong expansion driven by rising therapeutic demand.
- Clinical diagnosis of hypogonadism and age-related hormone decline increases treatment adoption, supported by structured guidelines and wider use of long-acting and oral testosterone therapies.
- Safety concerns, strict regulation, and risk of misuse create restraints, requiring controlled prescribing, monitoring protocols, and adherence to compliance frameworks.
- North America leads due to advanced endocrine care networks, while Europe maintains strong adoption under regulated healthcare systems.
- Asia Pacific emerges as the fastest-growing region as rising healthcare access, urbanization, and improved diagnostic capacity support wider use of hormone therapies.
Androgens and Anabolic Steroids Market Drivers:
Rising Clinical Diagnosis Of Hypogonadism And Age-Related Hormone Decline Across Adult Male Population
Growing awareness of testosterone deficiency increases patient visits to endocrine clinics. Physicians conduct routine hormone testing for fatigue, low libido, and muscle loss. Clear clinical guidelines support structured treatment pathways. Insurance coverage for hormone therapy expands patient access. Hospitals adopt standardized screening protocols for aging males. Public health campaigns highlight early symptom recognition. Broader access to laboratory diagnostics supports timely intervention. The Androgens and Anabolic Steroids Market benefits from stronger physician confidence in regulated therapeutic use.
Expanding Therapeutic Use In Chronic Disease-Related Muscle Wasting And Recovery Programs
Chronic illnesses such as cancer and HIV often lead to severe muscle loss. Clinicians prescribe anabolic agents to restore lean body mass. Post-surgical recovery programs include hormone therapy for select cases. Sports injury rehabilitation centers integrate supervised anabolic support. Clinical studies validate improvements in strength and mobility. Treatment protocols define safe dosage and monitoring standards. Specialist clinics guide patient adherence and follow-up. Demand rises within structured medical supervision frameworks.
- For instance, oxandrolone demonstrated an average lean body mass increase of 2.1 kg in controlled trials involving HIV-associated muscle wasting,
Advancement In Long-Acting Injectable And Transdermal Drug Delivery Systems
Pharmaceutical firms develop depot injections with extended dosing intervals. Long-acting formulations reduce frequent clinic visits. Transdermal gels provide steady hormone absorption. These systems improve patient compliance and convenience. Manufacturers invest in improved bioavailability profiles. Drug developers refine safety monitoring protocols. Controlled-release technologies enhance therapeutic stability. Healthcare providers prefer delivery formats that support adherence.
- For instance, Endo Pharmaceuticals’ Aveed® (testosterone undecanoate) delivers testosterone through a long-acting intramuscular injection with dosing intervals of approximately 10 weeks after the initial titration,
Growing Investment From Specialty Clinics And Hormone Therapy Centers Worldwide
Private hormone therapy centers expand service networks in urban areas. Specialty clinics focus on personalized treatment plans. Teleconsultation platforms support remote patient monitoring. Medical professionals receive targeted training in endocrine care. Clinics adopt digital record systems for therapy tracking. Structured follow-up visits improve treatment continuity. Public and private providers increase service capacity. These investments strengthen regulated access to androgen therapy.
Androgens and Anabolic Steroids Market Trends:
Shift Toward Personalized Hormone Optimization And Patient-Centric Treatment Models
Clinics adopt tailored dosing based on individual hormone profiles. Genetic and metabolic assessments guide therapy decisions. Physicians adjust regimens through regular lab reviews. Digital dashboards track patient response over time. Wellness-focused centers promote preventive hormone care. Patients seek data-driven insights into therapy outcomes. Customized protocols improve satisfaction rates. The Androgens and Anabolic Steroids Market reflects rising preference for personalized endocrine management.
Integration Of Digital Health Platforms For Monitoring And Compliance Tracking
Remote monitoring tools record patient-reported outcomes. Mobile applications remind users about dosage schedules. Secure portals enable lab result sharing with physicians. Telehealth visits reduce in-person appointment burden. Electronic prescription systems streamline refill processes. Data analytics support clinical decision refinement. Health systems integrate hormone therapy into broader digital ecosystems. Digital infrastructure enhances transparency and accountability.
Increased Focus On Regulatory Transparency And Ethical Prescription Practices
Healthcare authorities strengthen prescription audits. Providers adopt strict documentation standards. Pharmacies implement advanced verification systems. Educational programs inform clinicians about safe use guidelines. Sports bodies collaborate with medical regulators. Compliance frameworks reduce misuse risk. Public discourse emphasizes medical supervision. Industry participants prioritize responsible distribution channels.
- For instance, the World Anti-Doping Agency (WADA) conducted over 230,000 athlete samples in its global testing program,
Expansion Of Compounded And Specialty Formulations In Select Markets
Compounding pharmacies prepare customized dosage strengths. Specialty blends address patient-specific absorption needs. Clinicians explore alternative delivery forms within legal boundaries. Local pharmacies expand sterile compounding capabilities. Regulatory bodies oversee quality assurance standards. Patients request flexible therapy options. Healthcare providers monitor compounded product safety. Niche formulations create differentiated service offerings.
- For instance, the U.S. FDA reported that more than 7,500 compounding pharmacies operate nationwide under USP <797> sterile compounding standards,
Androgens and Anabolic Steroids Market Challenges Analysis:
Strict Regulatory Control And Risk Of Non-Medical Misuse Affect Market Stability
Government agencies enforce tight control over anabolic steroid distribution. Prescription monitoring programs track dispensing patterns. Unauthorized use in sports creates public scrutiny. High-profile misuse cases impact industry perception. Law enforcement actions disrupt illicit supply chains. Physicians exercise caution due to legal liabilities. Compliance costs increase operational burden for manufacturers. The Androgens and Anabolic Steroids Market must balance access with safety oversight.
Safety Concerns Related To Cardiovascular, Hepatic, And Endocrine Side Effects
Clinical literature reports risks linked to prolonged high-dose exposure. Patients require frequent laboratory monitoring. Adverse event reporting systems increase regulatory review. Negative media coverage shapes patient hesitation. Insurance providers scrutinize reimbursement policies. Healthcare professionals counsel patients on potential complications. Risk mitigation strategies demand structured follow-up care. Safety management remains central to long-term adoption.
Market Opportunities:
Development Of Safer Selective Androgen Receptor Modulators And Novel Molecules
Research pipelines explore targeted receptor modulation technologies. Selective compounds aim to reduce off-target effects. Clinical trials evaluate improved safety profiles. Biotech firms invest in next-generation hormonal agents. Partnerships between academia and industry expand innovation capacity. Regulatory pathways support novel drug approvals. Patent-protected molecules offer competitive advantage. Innovation creates scope for differentiated therapeutic options.
Emerging Demand In Developing Healthcare Systems With Expanding Endocrine Services
Healthcare infrastructure grows across Asia Pacific and Latin America. Private hospitals expand specialized endocrine units. Rising health awareness drives diagnostic testing rates. Urban clinics invest in hormone therapy programs. Medical education initiatives improve physician expertise. Cross-border pharmaceutical distribution networks expand reach. Public health systems integrate endocrine screening services. These factors create new growth avenues in underserved regions.
Androgens and Anabolic Steroids Market Segmentation Analysis:
By Indication
Hypogonadism leads demand in the Androgens and Anabolic Steroids Market due to rising diagnosis rates and structured hormone therapy guidelines. Anaemia treatment contributes steady use where anabolic agents support red blood cell production. Breast cancer applications focus on select hormone-responsive cases under strict clinical control. Other indications include muscle wasting linked to chronic illness, delayed puberty, and specific endocrine disorders. Physicians prefer evidence-based protocols that support safe long-term care. Treatment pathways expand across hospitals and specialty clinics. Growing awareness of hormone imbalance strengthens early diagnosis. It supports higher treatment penetration across adult populations.
- For instance, Bayer’s Nebido® (testosterone undecanoate) demonstrated sustained serum testosterone control for up to 12 weeks per injection in global clinical evaluations,
By Drugs
Testosterone remains the primary therapy due to broad clinical adoption and availability across multiple formulations. Methyltestosterone supports targeted use in selected endocrine disorders. Oxymetholone holds importance in managing severe anaemia and muscle wasting under monitored settings. Other drugs cater to niche therapeutic needs where alternative anabolic profiles are required. Pharmaceutical manufacturers focus on improved delivery formats and controlled-release technologies. Product differentiation strengthens competitive positioning. Regulatory oversight shapes prescribing patterns. The Androgens and Anabolic Steroids Market shows sustained reliance on established molecules with strong clinical validation.
By Type
Prescription drugs dominate due to strict regulatory control and required physician supervision. These therapies follow defined diagnostic criteria and structured monitoring protocols. OTC drugs represent a limited share where legal frameworks permit mild formulations for specific health needs. Prescription dominance reflects safety concerns and controlled distribution. Healthcare authorities enforce clear boundaries for medical use. Providers emphasize risk assessment and follow-up care. Strong governance supports safe therapy adoption. It ensures consistent quality standards across dispensing channels.
By Route of Administration
Oral products support convenience and wide patient acceptance. Parenteral formulations provide stable hormone levels and remain preferred for long-acting testosterone therapy. Other routes include transdermal systems and implantable options used in selective cases. Physicians align administration choice with patient lifestyle and therapeutic goals. Advances in delivery systems improve adherence. Safety monitoring protocols support optimal dose management. Diverse routes expand treatment flexibility. The Androgens and Anabolic Steroids Market benefits from innovations that enhance pharmacokinetic performance.
- For instance, Clarus Therapeutics’ Jatenzo®, the first FDA-approved oral testosterone undecanoate, showed a 87% responder rate achieving normal testosterone levels during pivotal studies.
By End-Users
Hospitals lead usage due to structured diagnostic facilities and specialist availability. Specialty clinics expand adoption through focused hormone therapy programs. Homecare settings support maintenance therapy for stable patients under supervision. Other settings include wellness centers that adhere to medical oversight standards. Providers emphasize individualized treatment planning. Strong coordination between clinicians and pharmacists ensures safe therapy continuation. Digital tools support remote monitoring. It strengthens care delivery across diverse environments.
By Distribution Channel
Hospital pharmacies manage prescriptions for newly diagnosed and complex cases. Retail pharmacies support broad access across urban and semi-urban areas. Online pharmacies grow due to rising demand for discreet ordering and home delivery under regulated frameworks. Other channels include specialty distributors that serve hormone clinics. Strict verification processes maintain safety compliance. Pharmacists guide patients on proper use and monitoring. Distribution networks prioritize secure handling of controlled substances. The Androgens and Anabolic Steroids Market benefits from streamlined supply chain integration.
Androgens and Anabolic Steroids Market Segmentation:
By Indication
- Hypogonadism
- Anaemia
- Breast Cancer
- Others
By Drugs
- Testosterone
- Methyltestosterone
- Oxymetholone
- Others
By Type
- Prescription Drugs
- Over-the-counter (OTC) Drugs
By Route of Administration
- Oral
- Parenteral
- Others
By End-Users
- Hospitals
- Specialty Clinics
- Homecare
- Others
By Distribution Channel
- Hospital Pharmacy
- Retail Pharmacy
- Online Pharmacy
- Others
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America holds the largest share of the Androgens and Anabolic Steroids Market due to strong diagnostic adoption, high endocrine care awareness, and established prescription oversight. The United States leads regional demand with clear treatment protocols and strong specialist availability. Canada follows with expanding hormone therapy programs and structured reimbursement pathways. Hospitals and specialty clinics drive high prescription volumes. Market penetration remains strongest among adult and elderly populations. It benefits from robust healthcare infrastructure and advanced monitoring systems.
Europe accounts for the second-largest share, supported by aging demographics and regulated hormone therapy practices across Germany, the United Kingdom, France, and Italy. Regulatory agencies enforce strict safety and prescription policies, which strengthen clinical confidence. Awareness of hormone imbalance grows across primary and specialty care settings. Demand rises for long-acting formulations that support stable hormone levels. Countries in Western Europe demonstrate higher adoption, while Eastern Europe shows steady growth. The Androgens and Anabolic Steroids Market expands through improving access to diagnostic services and therapeutic programs.
Asia-Pacific holds a fast-growing share driven by rising healthcare expenditure and expanding access to endocrine services. China and India lead growth with increasing diagnosis of hypogonadism and rising awareness of hormone health. Japan and South Korea contribute significant demand through advanced healthcare systems and specialist clinics. Southeast Asia shows measurable progress supported by private healthcare growth. Market penetration remains lower than Western regions but accelerates with urbanization and improved testing capacity. It gains momentum as regional regulatory frameworks strengthen. Middle East & Africa and South America hold smaller shares but demonstrate steady growth through private sector investment and expanding clinical networks.
Key Player Analysis:
- AbbVie Inc.
- Pfizer Inc.
- Teva Pharmaceuticals
- Endo Pharmaceuticals Inc.
- Bayer AG
- GlaxoSmithKline (GSK)
- Cipla Limited
- Sun Pharmaceutical Industries Ltd.
- Hikma Pharmaceuticals
- Antares Pharma Inc.
- Amneal Pharmaceuticals
- Clarus Therapeutics
- Viatris Inc.
- Aurobindo Pharma
- Zydus Cadila
Competitive Analysis:
The Androgens and Anabolic Steroids Market features a mix of multinational pharmaceutical companies, specialty hormone therapy providers, and compounding pharmacies. Leading firms compete through formulation innovation, regulatory compliance, and physician outreach programs. Long-acting injectables, transdermal systems, and improved bioavailability profiles remain central to product differentiation. Companies invest in clinical research to strengthen safety data and support broader physician adoption. Competitive pressure increases with the growth of online pharmacies and telehealth platforms that expand distribution under regulated frameworks. Strong brand presence, controlled manufacturing standards, and secure supply chains support market leadership. It encourages companies to refine patient support programs and enhance therapy monitoring capabilities.
Recent Developments:
- In February 2026, Grünenthal licensed exclusive Canadian rights for Nebido® (testosterone undecanoate), a long-acting injectable therapy for male hypogonadism, to Apotex's branded division Searchlight Pharma. This agreement includes upfront payments, regulatory milestones, and sales margins for Grünenthal, deepening their existing collaboration to expand access to testosterone replacement therapy in Canada.
Report Coverage:
The research report offers an in-depth analysis based on Indication, Drugs, Type, Route of Administration, End-Users, Distribution Channel, and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Rising diagnosis of hormone imbalance will increase treatment demand across clinical settings in the Androgens and Anabolic Steroids Market.
- Growth in long-acting formulations will strengthen patient adherence and support broader prescribing patterns.
- Digital monitoring tools will enhance therapy management and improve physician oversight.
- Expanding specialty clinics will increase access to personalized hormone programs.
- Adoption of advanced delivery systems will improve drug stability and therapeutic outcomes.
- Strong regulatory focus will shape ethical prescribing and controlled distribution.
- Pharmaceutical innovation will drive development of safer, targeted anabolic agents.
- Telehealth expansion will extend reach for follow-up consultations and dosage adjustments.
- Growing awareness among aging populations will support steady treatment uptake.
- Emerging markets will accelerate growth through rising healthcare investment and diagnostic capacity.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Androgens and Anabolic Steroids Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Androgens and Anabolic Steroids Market projected to grow between 2025 and 2032?
Which Androgens and Anabolic Steroids Market segment held the largest share in 2025?
What are the primary factors fueling the growth of the Androgens and Anabolic Steroids Market?
Who are the leading companies in the Androgens and Anabolic Steroids Market?
Which region commanded the largest share of the Androgens and Anabolic Steroids Market in 2025?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2025: USD 78,584.68 million → 2032: USD 158,479.9 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2025
- 2.6.2 Forecast Period: 2025-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2025
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Androgens and Anabolic Steroids Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Androgens and Anabolic Steroids Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2025-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2025-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Androgens and Anabolic Steroids Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2025-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Androgens and Anabolic Steroids Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Androgens and Anabolic Steroids Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Androgens and Anabolic Steroids Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Androgens and Anabolic Steroids Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Androgens and Anabolic Steroids Market Outlook, 2025-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2025: USD 78,584.68 million → 2032: USD 158,479.9 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2025
- 11.2 Market Forecast, 2025-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Androgens and Anabolic Steroids Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2025
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Androgens and Anabolic Steroids Geographic Market Outlook, 2025-2032
- 13.1 Regional Market Size and Share, 2025
- 13.2 Regional Market Forecast, 2025-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Androgens and Anabolic Steroids Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2025-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Androgens and Anabolic Steroids Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2025
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2025-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

