
Funeral spending shifts from burial to cremation
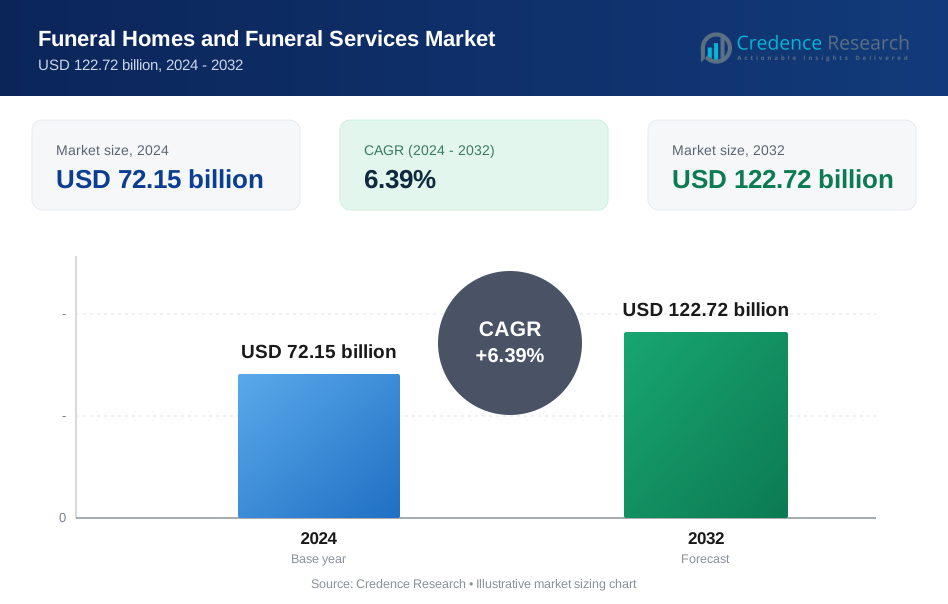
The global funeral homes and funeral services market was valued at USD 76.76 billion in 2025 and is projected to increase from USD 81.66 billion in 2026 to USD 142.60 billion by 2035, registering a CAGR of 6.39% during 2026–2035. Demand comes from older populations, prepaid planning and families that now compare cremation, burial and memorial packages online before they call a provider. North America held the largest regional share, 41.5% in 2025, because a dense network of corporate and independent funeral homes sells both at-need and preneed contracts. Asia Pacific is the fastest-growing region at 7.7% a year as Japan records close to 1.6 million deaths a year and operators in China and Australia professionalize care. The main commercial change is the steady move from burial to cremation, which lowers the average ticket per call while lifting memorial, urn and prepaid plan sales across most large markets.
What does the funeral homes and funeral services market include?
The market counts the fees families pay licensed funeral homes, crematories and cemetery operators for transfer of the deceased, embalming or refrigeration, viewing, ceremonies, cremation, burial and memorial events. It also counts preneed contracts funded through trusts or insurance policies once they are serviced, along with arrangement fees taken through websites and call centers. Most buyers are families acting within days of a death, while a growing share sign prepaid plans years ahead.
The market excludes standalone casket, urn and headstone manufacturing, florists that sell directly to consumers, and life insurance payouts that are not tied to a funeral contract. Within the value chain, funeral homes coordinate crematories, cemeteries, clergy, transport firms and software vendors, so pricing power sits with the provider that holds the family relationship.
Funeral Homes and Funeral Services Market Insights
- The market is valued at USD 76.76 billion in 2025 and is forecast to reach USD 142.60 billion by 2035, advancing at a 6.39% CAGR during 2026–2035 across all regions.
- North America accounted for 41.5% of 2025 value, supported by 1,487 Service Corporation International funeral locations at Sept. 30, 2025.
- Burial services led with 42.0% of 2025 value because caskets, vaults and cemetery property raise the ticket above cremation packages.
- The Financial Conduct Authority began regulating U.K. prepaid funeral plans on July 29, 2022, banning cold calling and commissions paid to funeral directors.
- Private capital keeps consolidating operators, with Park Lawn taken private by Viridian in August 2024 and Carriage Services buying Faith Chapel in September 2025.
Burial leads value while cremation grows fastest
Why does burial still lead funeral service value?
Based on service type, the market is categorized into burial, cremation, memorial and others. Burial led with 42.0% of 2025 value because a burial bundles casket, vault, plot and opening fees, and the National Funeral Directors Association put the U.S. median for a funeral with viewing and burial at $8,300 against $6,280 with cremation in December 2023. Cremation grows fastest at 7.8% a year as the association projects a U.S. cremation rate of 63.4% in 2025. Memorial events gain as families hold separate gatherings after a direct cremation.
How much of funeral planning is arranged in advance?
Based on category, the market is categorized into immediate need and pre-planned arrangements. Immediate Need arrangements led with 68.0% of 2025 value because most families still contract within days of a death, and Service Corporation International alone performed 269,504 funeral services in the first nine months of 2025. Pre-Planned arrangements grow fastest at 7.2% a year as monthly-fee plans spread, and Brazil's Grupo Zelo reported more than 600,000 active plan accounts covering 4.2 million people in a July 2022 LAVCA case study. Regulated prepaid plans in Britain, supervised by the Financial Conduct Authority since July 2022, support the same pre-planned demand.
How fast are online funeral arrangements growing?
Based on distribution channel, the market is categorized into offline and online. Offline sales led with 86.0% of 2025 value because arrangements are still signed in chapels, and Carriage Services said in September 2025 that its newly acquired Faith Chapel in Pensacola serves about 700 families a year through two funeral homes and a crematory. Online sales grow fastest at 8.7% a year as Tribute Technology says more than 9,000 funeral homes rely on its websites and software. Families now often compare package prices online before they call a funeral director.
| Segment Group | Leading Sub-segment | Share, 2025 | Fastest-growing Sub-segment | CAGR, 2026–2035 |
|---|---|---|---|---|
| By Service Type | Burial | 42.0% | Cremation | 7.8% |
| By Category | Immediate Need | 68.0% | Pre-Planned | 7.2% |
| By Distribution Channel | Offline | 86.0% | Online | 8.7% |
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Aging, preneed sales and consolidation lift demand
Rising deaths among older adults sustain service volumes
Mortality among older adults sets the floor for funeral volumes, and that floor is rising in most large markets. According to the United Nations World Population Prospects 2024, about 61.65 million people died worldwide in 2023. In the United States, heart disease caused 683,037 deaths and cancer caused 619,812 deaths in 2024, according to the National Center for Health Statistics. Japan recorded nearly 1.6 million deaths in 2024 against 686,061 births, Ministry of Internal Affairs and Communications data showed in August 2025. Because most of these deaths follow long illnesses, families increasingly arrive with written wishes and expect one provider to coordinate transfer, ceremony and disposition. As a result, demand for professional arrangements grows with each older cohort, whichever disposition the family chooses.
Preneed contracts lock in future funeral revenue
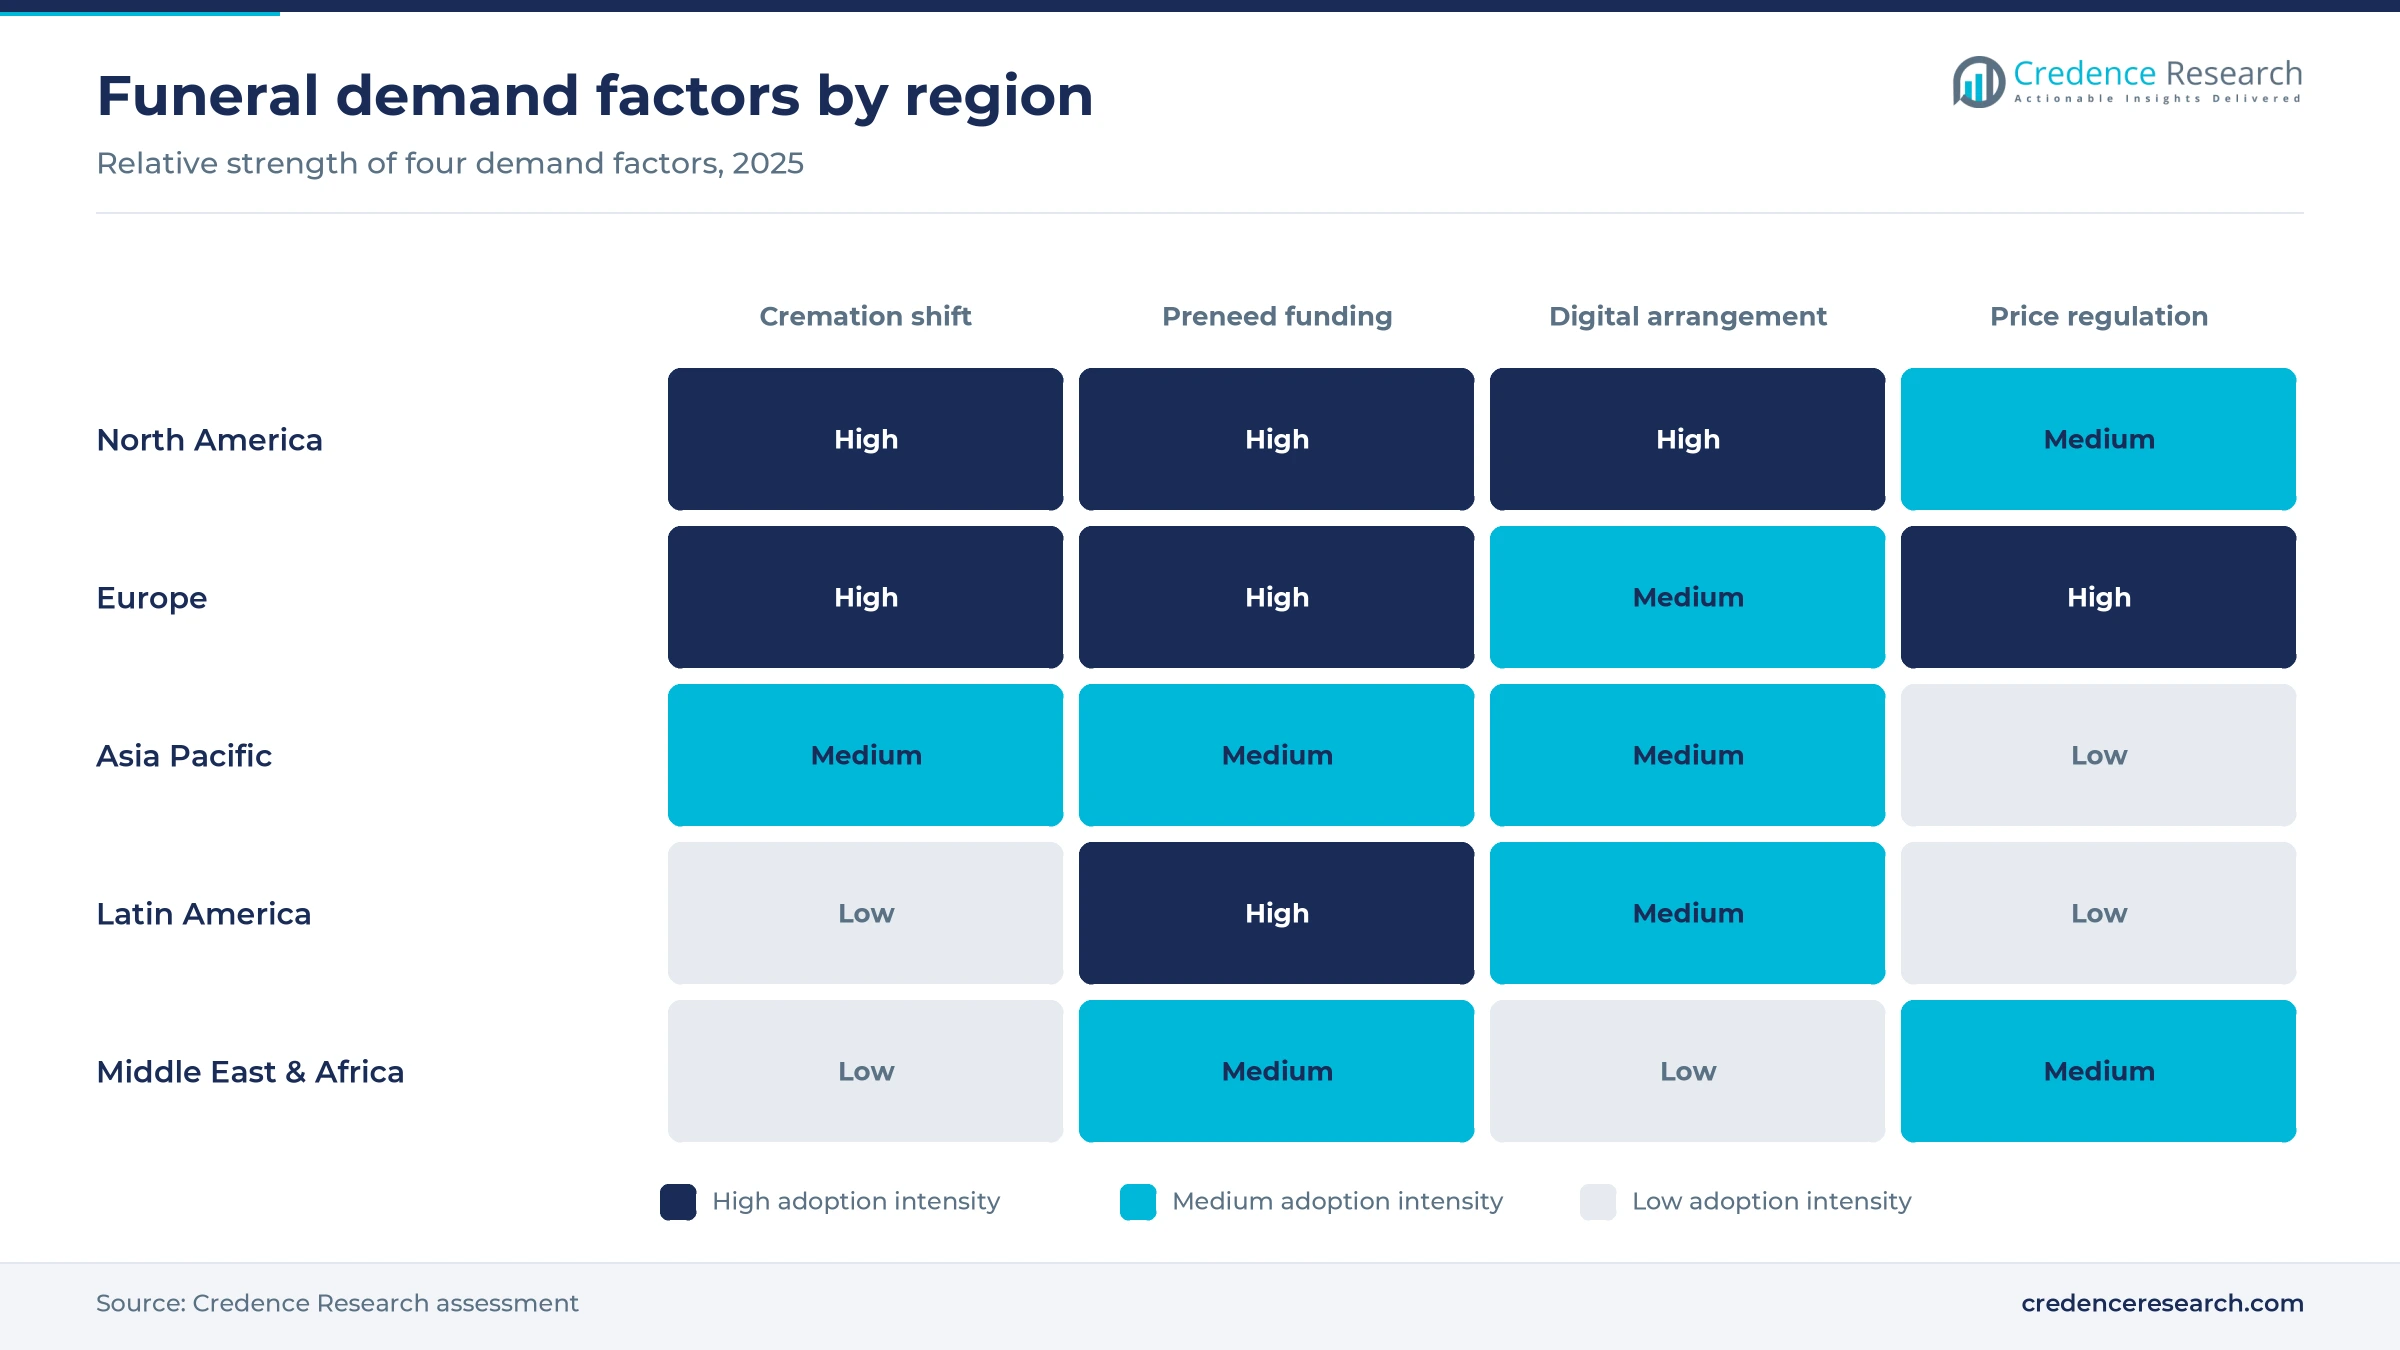
Prepaid contracts turn future funerals into current sales, and the largest operators are pushing them harder. Service Corporation International's third-quarter 2025 results showed core funeral preneed sales production up 8.7%, core contracts sold up 4.3% and comparable cemetery preneed sales up 9.6%. The same company is moving non-funeral-home preneed from trust-funded to insurance-funded contracts, a transition it expects to finish in 2026. Tribute Technology and Homesteaders Life Company announced on Oct. 23, 2025 an integration that loads preneed policy data into funeral home case files each night. In turn, Pre-Planned arrangements grow at 7.2% a year, the faster of the two category groups.
Consolidation brings capital to independent operators
Consolidators keep buying independent funeral homes, which brings capital for chapel upgrades, crematories and preneed sales teams. Carriage Services announced on Sept. 17, 2025 that it bought Faith Chapel Funeral Homes & Crematory in Pensacola, Florida, adding to a network of 164 funeral homes in 24 states and 28 cemeteries in nine states. Park Lawn completed its going-private sale to Viridian, owned by Homesteaders Life Company and Birch Hill Equity Partners funds, in August 2024, according to law firm Bennett Jones. In Australia, InvoCare agreed to a TPG Capital takeover in August 2023 covering more than 290 funeral home locations, InDaily reported. Acquirers usually keep local brand names, which protects the family relationships that bring repeat calls.
Consumer protection rules raise trust in prepaid plans
Regulators have tightened the rules on prepaid plans and price disclosure, and that has made families more willing to buy ahead. The Financial Conduct Authority took over regulation of U.K. prepaid funeral plans on July 29, 2022, banning cold calling and commissions paid to funeral directors and giving buyers a full refund within 30 days. The Competition and Markets Authority's 2021 order requires funeral directors and crematoria to show standard pricing information. In the United States, the Federal Trade Commission opened a rulemaking review on Oct. 20, 2022 that asks whether funeral providers should post prices online. Because protections are now clearer, plan sellers can market preneed contracts through regulated channels rather than door-to-door selling.
Direct cremation and green options reshape services
Cremation rises toward two-thirds of U.S. dispositions
Cremation is replacing burial as the default choice in the largest market, and the shift is spreading. The National Funeral Directors Association's 2025 Cremation & Burial Report projects a U.S. burial rate of 31.6% in 2025, and Kates-Boylston Publications reported that the association sees cremation reaching 82.3% by 2045. Service Corporation International's comparable cremation rate, including non-funeral-home channels, reached 64.4% in the third quarter of 2025. In China, civil affairs statistics compiled by CEIC Data show a cremation rate of 58.8% in 2021 with 5.97 million cremations across 1,774 funeral parlors. As a result, Cremation grows at 7.8% a year, while burial keeps value through cemetery property prices.
Direct cremation and unattended funerals gain share
Low-cost direct cremation is the fastest-moving format in Britain, where families separate the disposition from any memorial event. SunLife's 2025 Cost of Dying report put the average basic funeral at £4,285, up 3.5%, against £1,597 for a direct cremation, and found that one in five funerals is now a direct cremation, Funeral Service Times reported. The Competition and Markets Authority found in February 2024 that unattended funerals rose to 11% of funerals in 2023 from 8% in 2022, while reported revenue from them grew 12%. Providers respond by pairing direct cremation with a later memorial gathering at a hotel, garden or chapel. This keeps memorial packages relevant even when the cremation itself has no ceremony.
Green disposition laws open new service lines
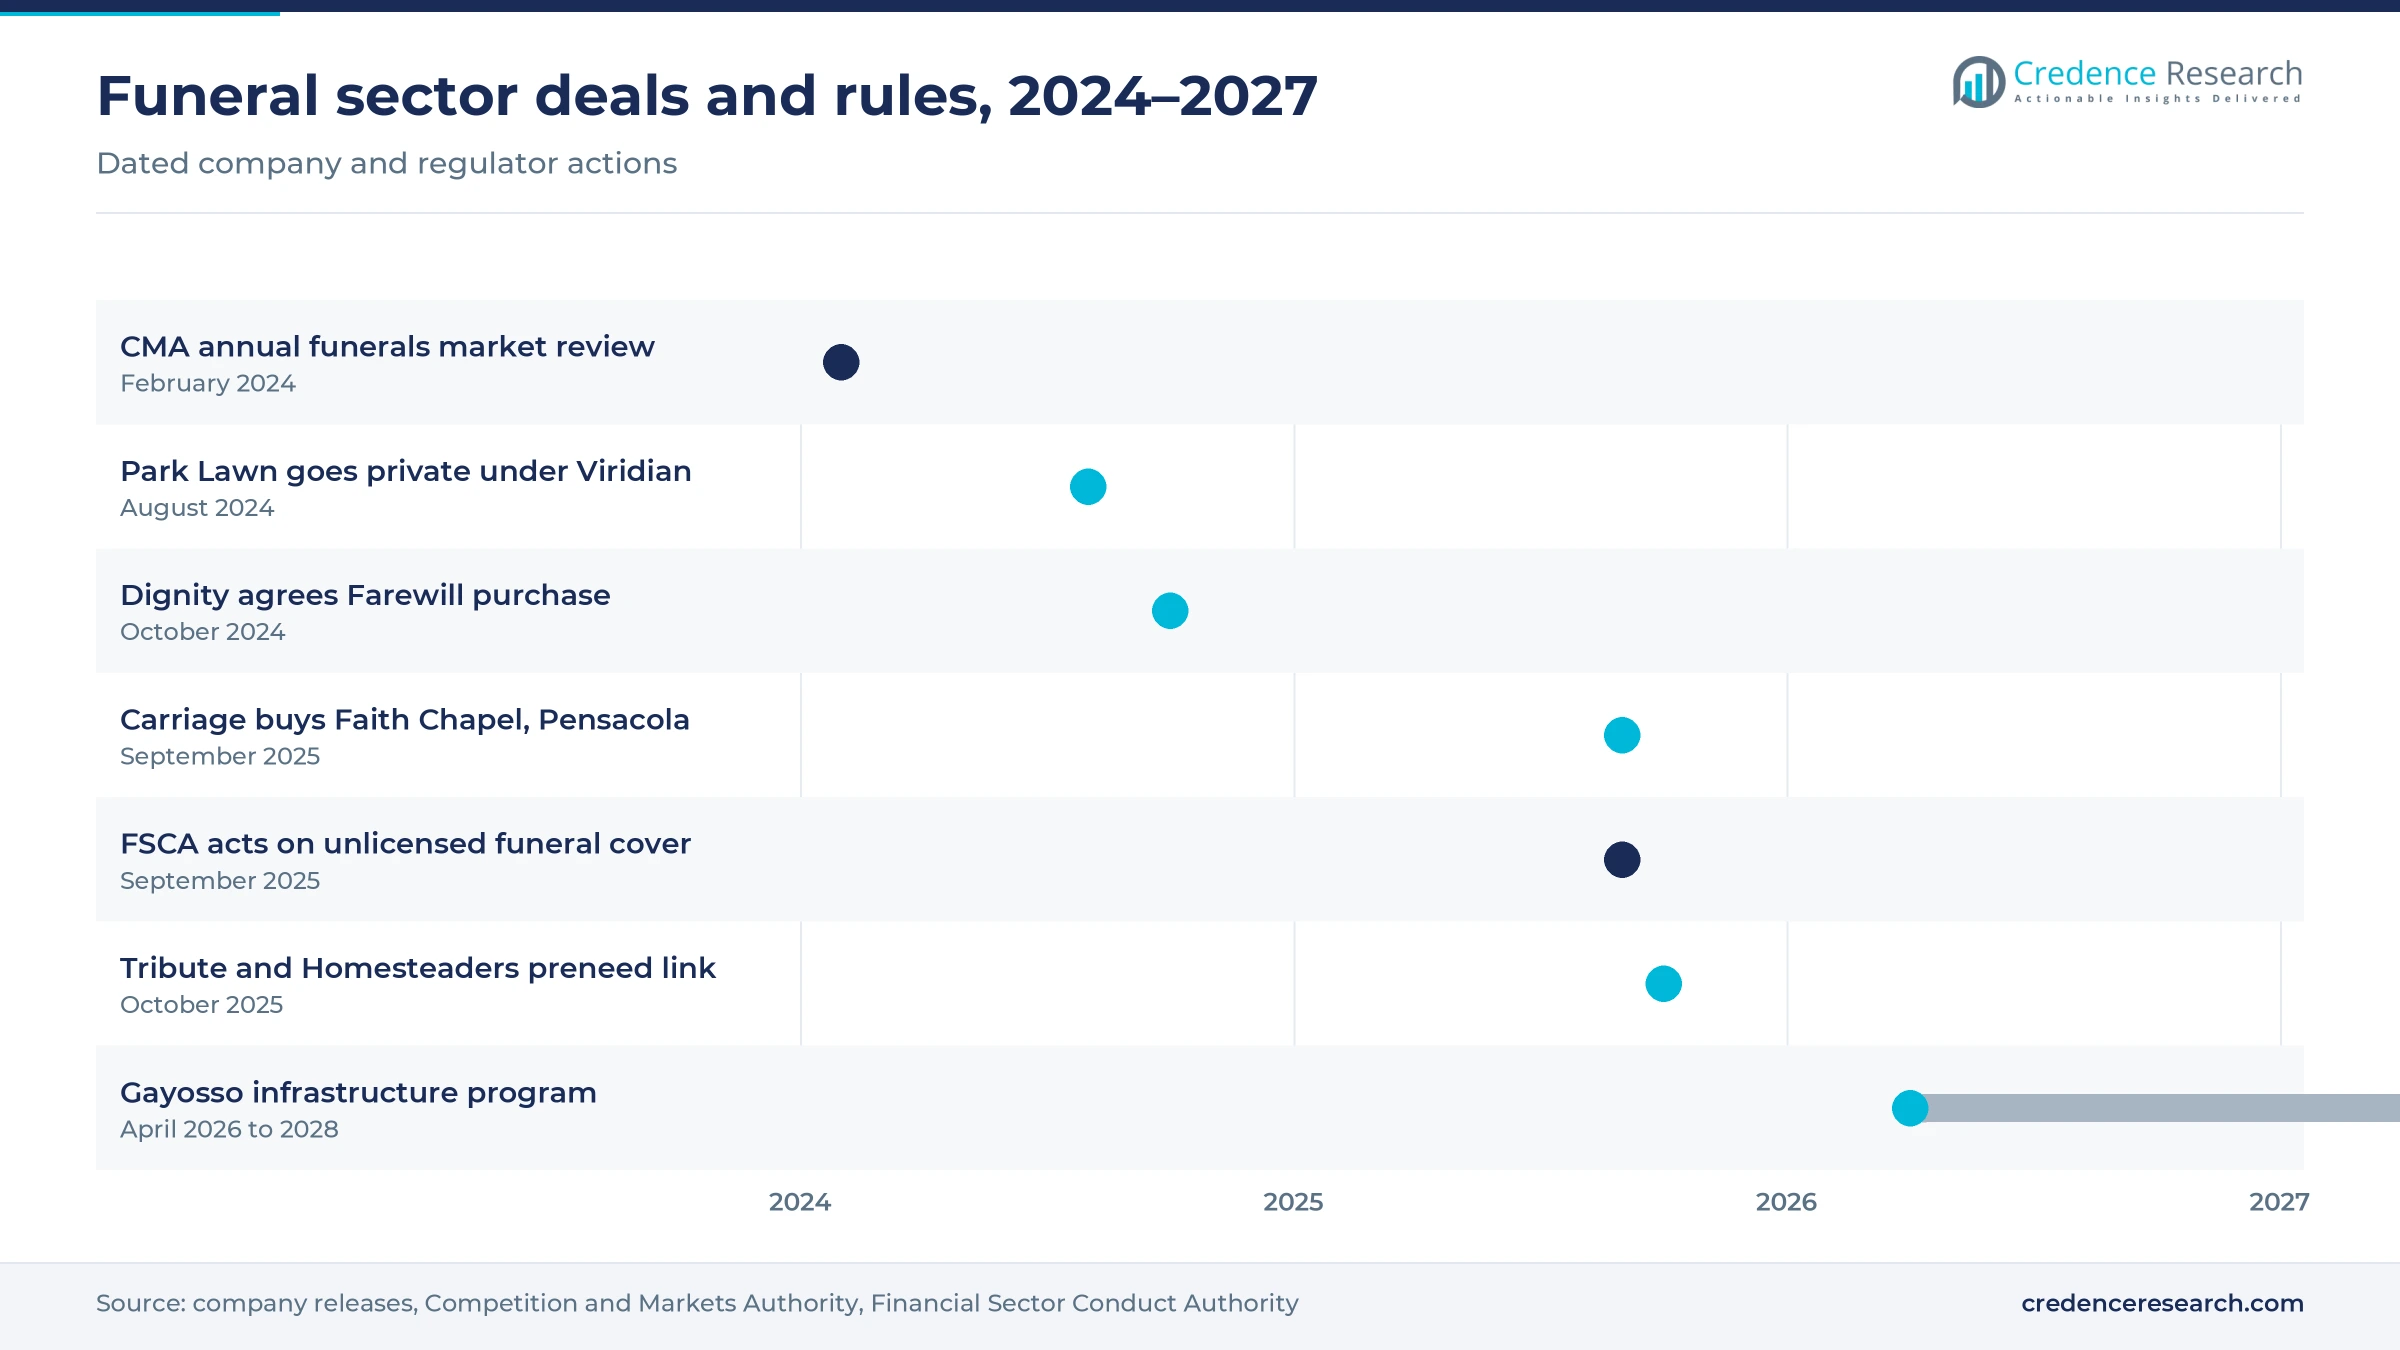
New disposition laws give funeral homes room to sell lower-impact options at premium margins. The National Funeral Directors Association lists 13 states that had legalized natural organic reduction by May 30, 2025, from Washington in 2020 to Georgia and Minnesota in 2025, with California's law taking effect in 2027. Nolo's state guide lists alkaline hydrolysis as legal in 26 states, including Maryland under rules effective Oct. 1, 2024. In Mexico, Grupo Gayosso said in April 2026 that it is expanding biodegradable urns and wicker caskets, El Cronista reported. Providers that license vessels early can win families who reject flame cremation or embalming, and they can charge for the longer process.
Digital arrangement tools create an online sales opening
Online arrangement and memorial tools are an opening for providers that still rely on walk-in sales. Dignity agreed in October 2024 to buy Farewill, an online provider of wills, probate, at-need funerals and prepaid plans, in a deal that valued the business at £12.9 million, the Association of Investment Companies reported. Grupo Gayosso launched a digital memorial app in November 2025 after investing more than MXN 5 million, according to El Cronista. The National Funeral Directors Association's 2025 Consumer Awareness and Preferences Study, released Oct. 2, 2025, found consumers embracing digital planning while still seeking a funeral director's guidance. As a result, Online sales grow at 8.7% a year.
Margin pressure and compliance gaps slow providers
Prices lag inflation and squeeze provider margins
Funeral prices have risen more slowly than operating costs, which squeezes margins at smaller homes. The National Funeral Directors Association reported on Dec. 8, 2023 that the U.S. median for a funeral with viewing and burial rose 5.8% over two years and the cremation median 8.1%, while general inflation reached 13.6%. In Britain, large chains charged just over £2,700 on average in 2023, a real-terms fall. Operators answer with leaner staffing, shared crematories and fewer underused chapels.
Death volumes normalize after pandemic peaks
Death volumes have fallen back from pandemic peaks, which leaves some operators with spare capacity. Service Corporation International's comparable funeral services fell 3.1% in the third quarter of 2025, and Propel Funeral Partners cited a temporary contraction in death volumes in its August 2025 results. In China, Fu Shou Yuan linked weaker first-half 2024 results to the unwinding of 2023 pent-up demand and a soft economy, the South China Morning Post reported. Operators respond by cutting overhead and selling more preneed contracts to younger families.
Unlicensed funeral policies erode buyer trust
Unregulated funeral cover still exposes buyers to losses in some markets. South Africa's Financial Sector Conduct Authority acted against four funeral firms that had collected more than R67 million in premiums without licensed underwriters, Business Report wrote on Sept. 18, 2025. In Britain, the Competition and Markets Authority said in February 2024 that just under 250 funeral directors were failing to comply with its pricing order. Such breaches slow the sale of prepaid plans and invite tighter supervision.
Online price disclosure raises compliance costs
Online price disclosure may add compliance work for small independents that still quote by phone. Federal Trade Commission staff found on Oct. 20, 2022 that fewer than 40% of reviewed funeral home websites showed any prices, and more than 60% showed little or no pricing information. The commission received 785 comments in its Funeral Rule review. Small firms would need updated websites, staff training and price audits, while larger chains already publish package prices.
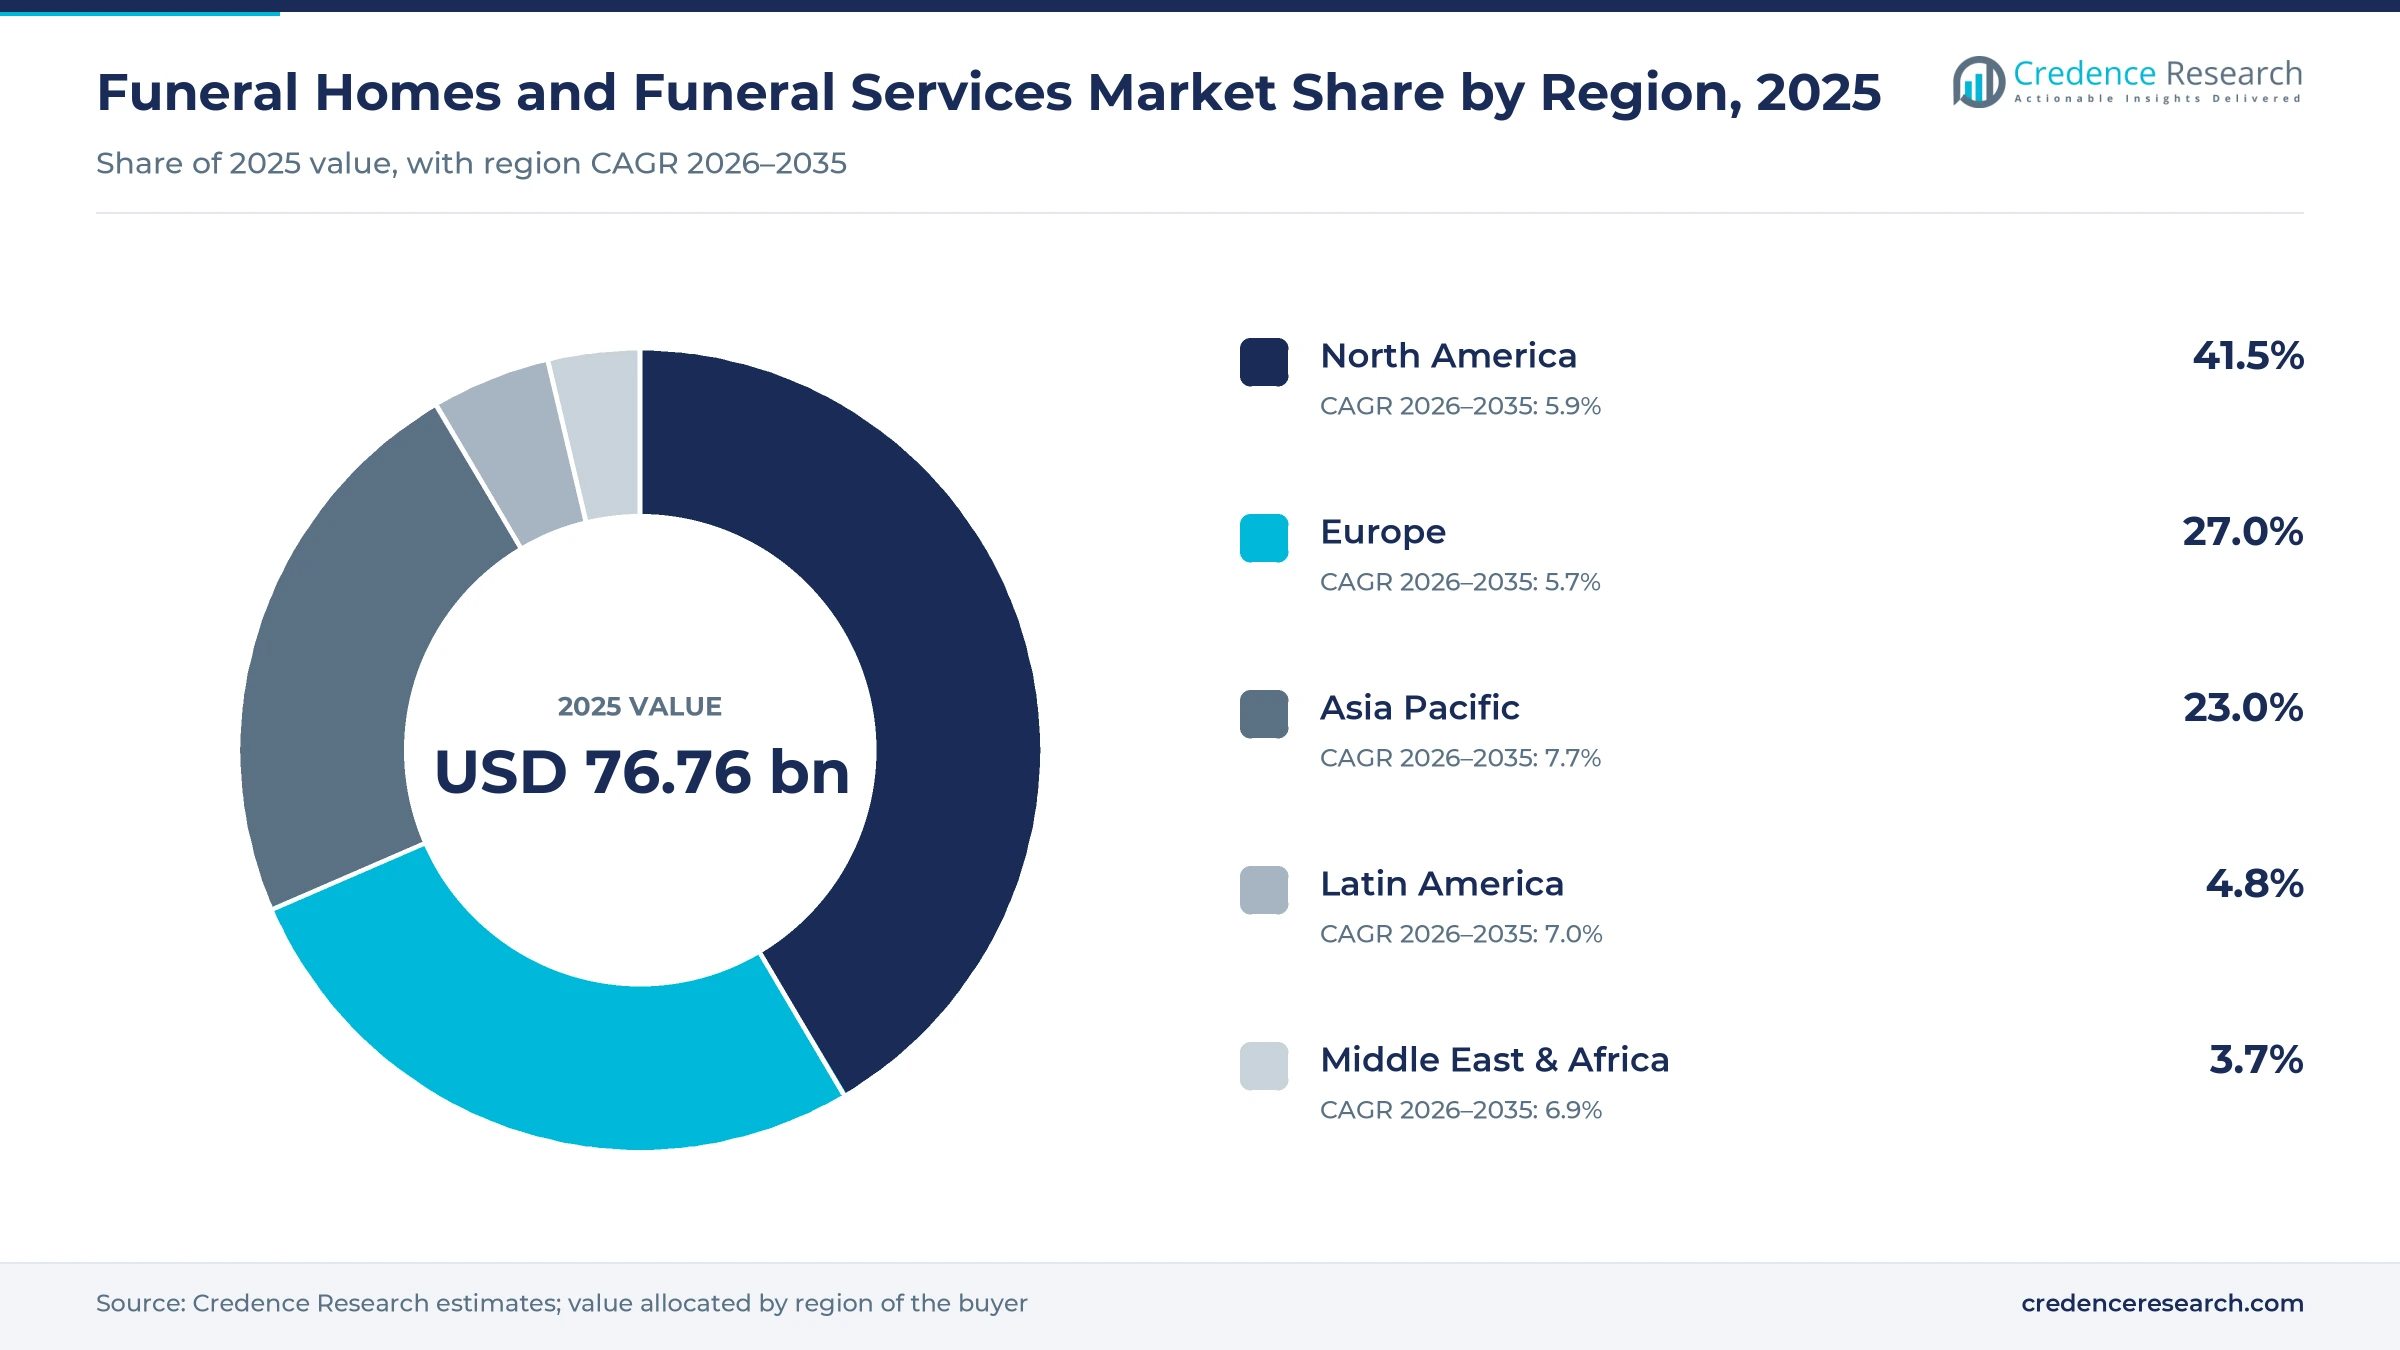
North America leads as Asia Pacific grows fastest
| Region | Value, 2025 (USD billion) | Share, 2025 | CAGR, 2026–2035 |
|---|---|---|---|
| North America | 31.86 | 41.5% | 5.9% |
| Europe | 20.73 | 27.0% | 5.7% |
| Asia Pacific | 17.65 | 23.0% | 7.7% |
| Latin America | 3.68 | 4.8% | 7.0% |
| Middle East & Africa | 2.84 | 3.7% | 6.9% |
North America leads on chains and preneed depth
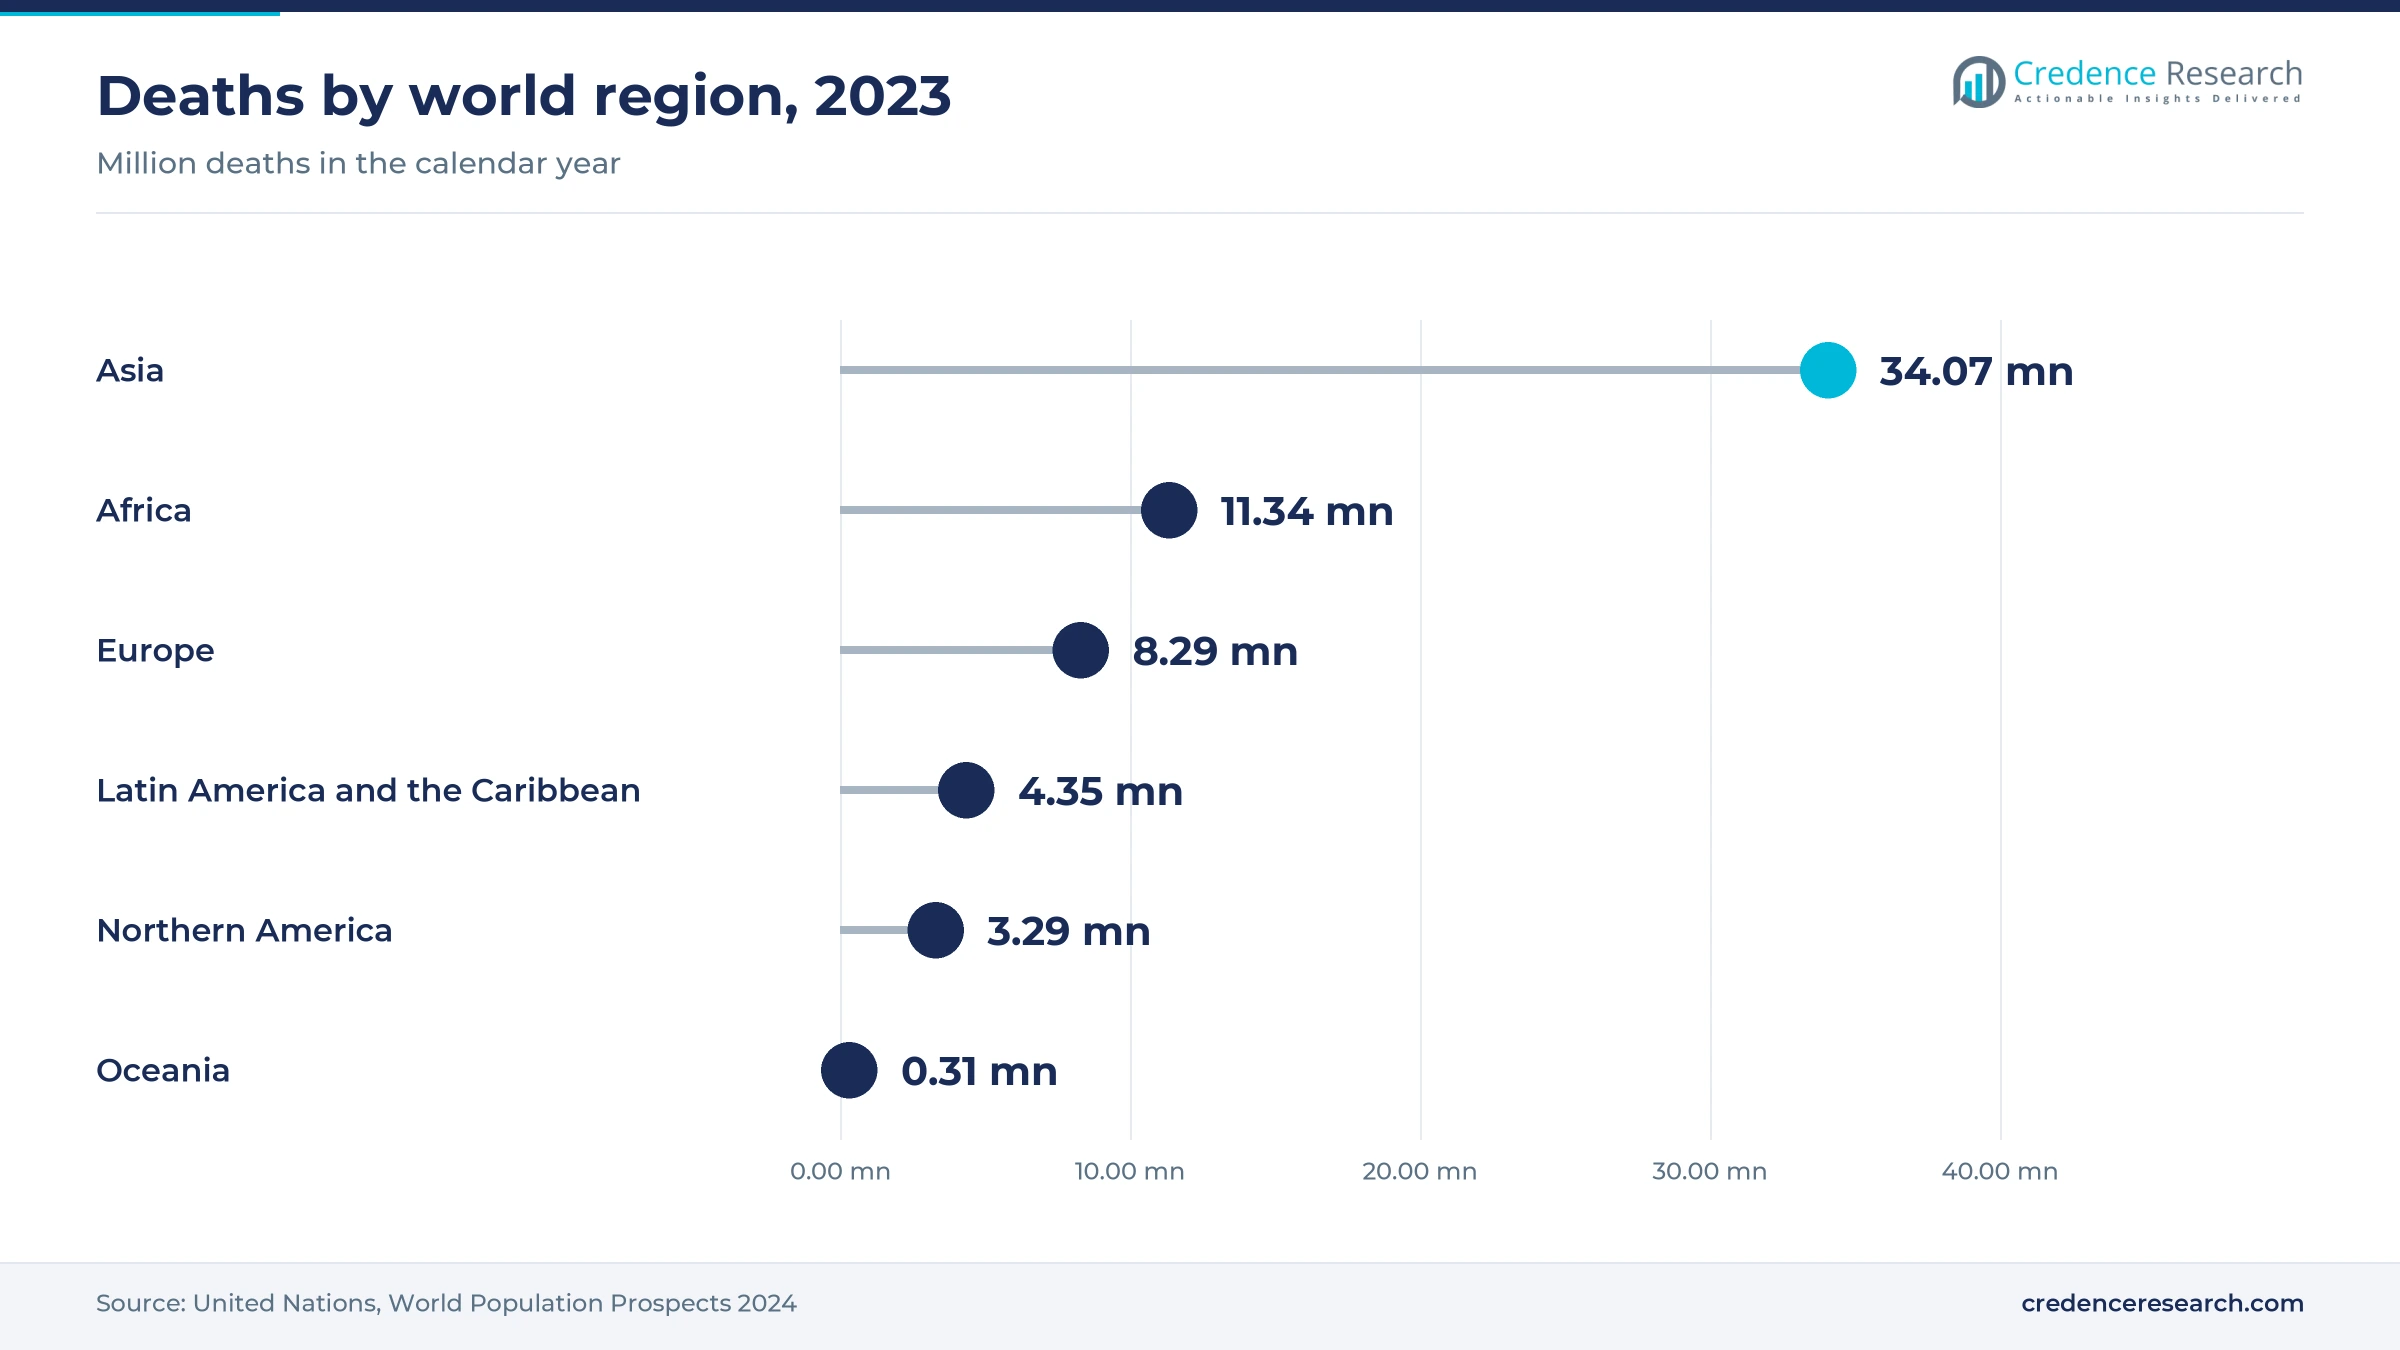
North America held 41.5% of 2025 value and grows at 5.9% a year. Service Corporation International alone ran 1,487 funeral service locations and 499 cemeteries across 44 states, eight Canadian provinces, the District of Columbia and Puerto Rico at Sept. 30, 2025. The United Nations counts about 3.29 million deaths in Northern America in 2023, and the high cremation rate is moving spending toward memorial and preneed products. StoneMor, renamed Everstory Partners in April 2023, went private under Axar Capital in November 2022 with 302 cemeteries and 74 funeral homes.
Europe grows steadily under tighter U.K. rules
Europe held 27.0% of 2025 value and grows at 5.7% a year, the slowest regional pace. The United Nations counts about 8.29 million deaths in Europe in 2023, which keeps call volumes high as populations age. In Britain, prepaid plans now sit under financial regulation, and Dignity's agreed purchase of Farewill adds online wills and probate to a national funeral chain. Direct cremation, chosen for one in five British funerals, holds average prices down and shifts spending toward later memorial events.
Asia Pacific grows fastest as aging deepens
Asia Pacific held 23.0% of 2025 value and is the fastest-growing region at 7.7% a year. Asia recorded about 34.07 million deaths in 2023, the largest regional total in United Nations data, and an aging population in Japan and China spends longer in elderly care before death. China had 4,373 funeral service institutions in 2021, and the South China Morning Post put an average grave plot above 100,000 yuan in 2024. In Australia, Propel Funeral Partners completed three acquisitions in fiscal 2025, while InvoCare operates under TPG Capital.
Latin America expands through plan-based models
Latin America held 4.8% of 2025 value and grows at 7.0% a year. The United Nations counts about 4.35 million deaths in Latin America and the Caribbean in 2023, and plan-based providers such as Grupo Zelo fund many funerals through monthly fees. Grupo Gayosso, with 150 years in Mexico, plans to invest MXN 1,000 million by 2028, expects to serve more than 100,000 families a year and plans to open Gayosso Nogalar in Nuevo León in the second half of 2026, El Cronista reported.
Middle East & Africa formalizes funeral cover
Middle East & Africa held 3.7% of 2025 value and grows at 6.9% a year. Africa recorded about 11.34 million deaths in 2023 in United Nations data, yet spending per funeral is far below the levels of Europe or North America. South Africa has the most formal market, where parlours often sell cover with their services, and one Orkney parlour had advised 275,870 policy clients by September 2024, according to the Financial Sector Conduct Authority. Licensing should move more of this spending to regulated providers.
Acquisitions and digital deals mark 2024 to 2026
| Development | Status and market relevance |
|---|---|
| In August 2024, Park Lawn completed its going-private sale to Viridian, owned by Homesteaders Life Company and Birch Hill Equity Partners funds. | Completed; adds private capital to a Canadian and U.S. funeral and cemetery network |
| In October 2024, Dignity agreed to acquire Farewill, an online wills, probate and funeral plan provider valued at £12.9 million. | Agreed; extends a U.K. chain into online arrangement and estate services |
| In September 2025, Carriage Services acquired Faith Chapel Funeral Homes & Crematory in Pensacola, Florida. | Completed; adds two funeral homes and a crematory in northwest Florida |
| In October 2025, Tribute Technology announced an integration with Homesteaders Life Company for preneed policy management. | Announced; brings preneed policy data into funeral home case files |
| In April 2026, Grupo Gayosso announced plans to invest MXN 1,000 million by 2028 in Mexican funeral infrastructure. | Planned; includes Gayosso Nogalar in Nuevo León in the second half of 2026 |
Software and new dispositions change funeral work
- Arrangement platforms link websites, obituaries and payments, and Tribute Technology supplies case management software and websites to many independents.
- Insurance-funded preneed replaces trust funding at Service Corporation International and depends on policy administration systems that sync with case files.
- Natural organic reduction converts remains into soil in licensed vessels and is now permitted in the 13 states listed by the National Funeral Directors Association.
- Alkaline hydrolysis uses water and alkali instead of flame, and Nolo lists it as legal in 26 states.
- Digital memorials extend ceremonies to distant relatives, and Grupo Gayosso launched its memorial app in November 2025.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Consolidators and plan providers shape competition
Competition is local in delivery but increasingly national in ownership. Service Corporation International, Carriage Services, Park Lawn and Everstory Partners buy established funeral homes and keep their names, because families choose a provider on reputation and location rather than brand. Dignity in Britain, InvoCare and Propel Funeral Partners in Australia, Fu Shou Yuan in China, Grupo Gayosso in Mexico and Grupo Zelo in Brazil follow the same pattern in their home markets. Scale lets these groups fund crematories, cemeteries and preneed sales teams, while independents compete on personal attention and lower overhead. Price transparency rules in Britain and the Federal Trade Commission review in the United States push all providers to publish clearer package prices. Technology vendors such as Tribute Technology supply the websites and case tools that let small homes match the online presence of chains, and private equity owners, including TPG Capital and Axar Capital, add capital for acquisitions.
Companies profiled and their roles in this market
| Company | Type | Role in the market |
|---|---|---|
| Service Corporation International | Consolidator | Largest North American operator, with 1,487 funeral locations and 499 cemeteries at Sept. 30, 2025 |
| Carriage Services Inc. | Consolidator | Runs 164 funeral homes in 24 states and 28 cemeteries; bought Faith Chapel in Pensacola in September 2025 |
| Park Lawn Corporation | Operator | Canadian and U.S. funeral, cemetery and cremation group taken private by Viridian in August 2024 |
| Everstory Partners | Cemetery operator | Formerly StoneMor, runs cemeteries and funeral homes in 23 states and Puerto Rico |
| Dignity Funerals Limited | Operator | U.K. funeral and prepaid plan provider that agreed to buy online provider Farewill in October 2024 |
| InvoCare Limited | Operator | More than 290 funeral locations in Australia, New Zealand and Singapore; owned by TPG Capital |
| Propel Funeral Partners | Consolidator | Australian and New Zealand acquirer that completed three acquisitions in fiscal 2025 |
| Fu Shou Yuan International Group | Cemetery and funeral operator | Chinese cemetery and funeral group with its largest market in Shanghai |
| Grupo Gayosso | Operator | Mexican funeral group with 150 years in the market, expanding into Nuevo León |
| Grupo Zelo | Funeral plan provider | Brazilian plan-based provider operating across 2,000 municipalities in 12 states |
Preneed and memorial sales offset lower tickets
Credence Research's view is that the market's value will keep rising even as the average ticket falls, because cremation lowers the price per call while preneed, memorial and cemetery sales lift total spending per family. Operators that combine chapels, crematories and insurance-funded preneed contracts are best placed, as Service Corporation International's cemetery preneed sales growth of 9.6% in the third quarter of 2025 shows. The risk sits with small independents that lack online pricing and capital for new disposition equipment. Buyers should expect more acquisitions in North America and Australia, and more plan-based growth in Latin America through 2035.
Death counts and price data anchor the estimates
The report uses 2025 as the base year and forecasts the market to 2035, with growth rates stated for 2026–2035. Market values come from the Credence Research model, which carries the prior Credence Research estimate forward at the same growth rate after checks against deaths, disposition mix and average prices. Regional and segment shares are Credence Research estimates built from public data, including United Nations death counts, National Funeral Directors Association cremation projections, company releases and regulator publications from the Competition and Markets Authority, Financial Conduct Authority and Federal Trade Commission. No interviews or surveys were conducted for this edition of the report.
Cremation and online arrangement define the outlook
Through 2035 the market is expected to grow from USD 81.66 billion in 2026 to USD 142.60 billion, with Asia Pacific adding volume fastest as aging populations rely more on professional providers. North America and Europe will see cremation take a larger share of calls, so value growth there depends on memorial events, cemetery property and prepaid plans. Natural organic reduction and alkaline hydrolysis should spread to more U.S. states, giving early adopters a premium service line. Online arrangement will become standard as regulators push price disclosure, and consolidators will keep buying independents that cannot fund new technology or crematories alone.
Frequently Asked Questions
How big is the funeral homes and funeral services market?
What share of funeral planning is arranged at the time of need?
How fast is the funeral cremation service segment growing?
Which region leads the funeral services market?
What are the key funeral industry statistics?
How is funeral home software changing funeral services?
Who are the leading companies in funeral homes and funeral services?
What are the main funeral industry trends?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Service Type
- 1.2.1 Burial
- 1.2.2 Cremation
- 1.2.3 Memorial
- 1.2.4 Others
- 1.3 By Category
- 1.3.1 Immediate Need
- 1.3.2 Pre-Planned
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2025: USD 76.76 billion → 2035: USD 142.60 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Historical Period: 2018-2025
- 2.6.2 Base Year: 2025
- 2.6.3 Forecast Period: 2025-2035
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2025
- 3.3 Forecast Market Size, 2035
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Funeral Homes and Funeral Services Market Trends and Developments
- 4.1 Historical Industry Development, 2018-2025
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Funeral Homes and Funeral Services Market Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis, 2018-2025
- 5.2 Demand Forecast, 2025-2035
- 5.3 Supply Chain Structure and Procurement Trends
- 5.4 Supply-Demand Gap and Bottlenecks
- 5.5 Import Dependence and Sourcing Structure
- 5.6 Regional Supply and Demand Concentration
Chapter 6 Global Funeral Homes and Funeral Services Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends, 2018-2025
- 6.3 Pricing Outlook, 2025-2035
- 6.4 Pricing by Product and Market Segment
- 6.5 Geographic Pricing Differences
- 6.6 Key Input, Energy, Labor and Logistics Costs
- 6.7 Contract Pricing and Purchasing Models
- 6.8 Pricing Sensitivity and Competitive Positioning
- 6.9 Price, Margin and Profitability Implications
Chapter 7 Global Funeral Homes and Funeral Services Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Funeral Homes and Funeral Services Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Funeral Homes and Funeral Services Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Data Protection, AI and Cybersecurity Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Funeral Homes and Funeral Services Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Funeral Homes and Funeral Services Market Outlook, 2025-2035
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2025: USD 76.76 billion → 2035: USD 142.60 billion)
- 11.1.2 Historical Market Size, 2018-2025
- 11.1.3 Base-Year Market Size, 2025
- 11.2 Market Forecast, 2025-2035
- 11.2.1 Revenue Forecast to 2035
- 11.2.2 CAGR and Year-on-Year Growth
- 11.2.3 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Funeral Homes and Funeral Services Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2025
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Service Type - Market Size and Forecast, 2025-2035
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size, 2018-2025
- 12.3.3 Revenue Forecast, 2025-2035
- 12.3.4 Base-Year Market Share, 2025
- 12.3.5 Segment CAGR and Growth Drivers
- 12.3.6 Subsegment Market Size and Forecast
- 12.3.6.1 Burial
- 12.3.6.2 Cremation
- 12.3.6.3 Memorial
- 12.3.6.4 Others
- 12.3.7 Subsegment Pricing and Adoption Trends
- 12.3.8 Leading Suppliers and Competition
- 12.3.9 Regional Demand and Opportunities
- 12.4 By Category - Market Size and Forecast, 2025-2035
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size, 2018-2025
- 12.4.3 Revenue Forecast, 2025-2035
- 12.4.4 Base-Year Market Share, 2025
- 12.4.5 Segment CAGR and Growth Drivers
- 12.4.6 Subsegment Market Size and Forecast
- 12.4.6.1 Immediate Need
- 12.4.6.2 Pre-Planned
- 12.4.7 Subsegment Pricing and Adoption Trends
- 12.4.8 Leading Suppliers and Competition
- 12.4.9 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 Global Funeral Homes and Funeral Services Geographic Market Outlook, 2025-2035
- 13.1 Regional Market Size and Share, 2025
- 13.2 Regional Market Forecast, 2025-2035
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Funeral Homes and Funeral Services Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Energy Efficiency and Resource Management
- 14.7 Sustainability, Recycling and Circularity
- 14.8 Technology Roadmap, 2025-2035
- 14.9 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Funeral Homes and Funeral Services Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2025
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2025-2035
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Service Corporation International
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Financial Performance and Investment
- 17.2.6 Market Share and Competitive Position
- 17.2.7 Technology and Innovation Capabilities
- 17.2.8 Strategic Alliances or Partnerships
- 17.2.9 Recent Developments
- 17.2.10 Growth Strategy and Outlook
- 17.3 Carriage Services Inc.
- 17.4 Park Lawn Corporation
- 17.5 Everstory Partners
- 17.6 Dignity Funerals Limited
- 17.7 InvoCare Limited
- 17.8 Propel Funeral Partners
- 17.9 Fu Shou Yuan International Group
- 17.10 Grupo Gayosso
- 17.11 Grupo Zelo
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

