
Market Overview:
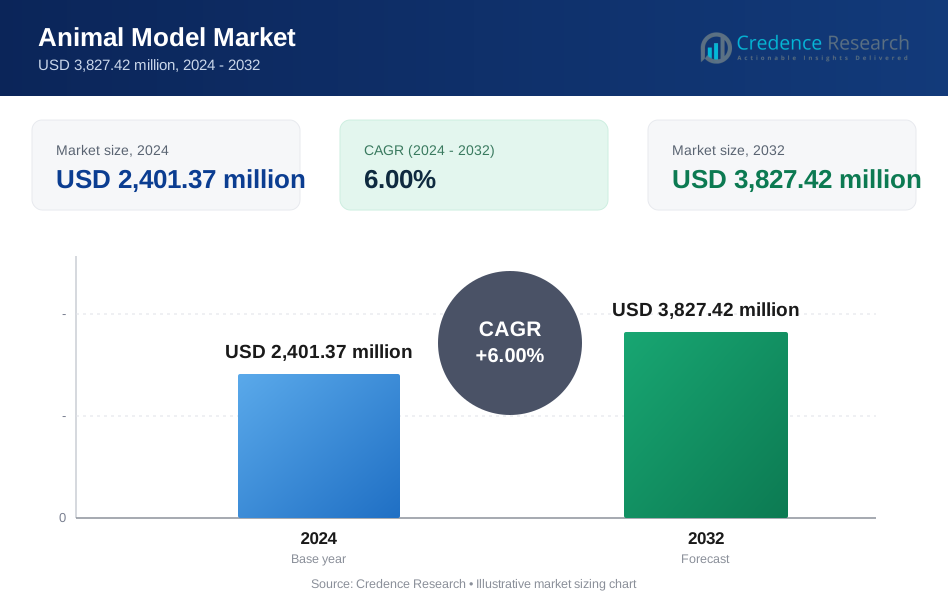
The Animal Model Market is projected to grow from USD 2,401.37 million in 2024 to an estimated USD 3,827.42 million by 2032, with a compound annual growth rate (CAGR) of 6% from 2024 to 2032.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Animal Model Market Size 2024 | USD 2,401.37 Million |
| Animal Model Market, CAGR | 6% |
| Animal Model Market Size 2032 | USD 3,827.42 Million |
The growing emphasis on preclinical testing and biomedical research continues to drive the Animal Model Market. Increasing prevalence of chronic and infectious diseases pushes pharmaceutical companies to develop safe and effective drugs through validated animal testing. Expanding government support for medical research and advancements in genetic engineering strengthen model accuracy. The adoption of transgenic and humanized animals for immunology, oncology, and neurological studies further supports market expansion.
North America leads the market, driven by strong research funding, developed healthcare infrastructure, and established pharmaceutical industries. Europe follows, supported by ethical research frameworks and rising academic collaborations. The Asia-Pacific region is emerging rapidly, supported by growing biotech investments, expanding R&D capabilities, and an increasing focus on translational medicine in China, India, and Japan.

Market Insights:
- The Animal Model Market is projected to grow from USD 2,401.37 million in 2024 to USD 3,827.42 million by 2032, at a CAGR of 6%.
- Rising investment in preclinical testing and biomedical research continues to fuel market expansion globally.
- Growing prevalence of chronic and infectious diseases increases the demand for reliable animal testing models.
- Advancements in genetic engineering enhance the accuracy and relevance of transgenic and humanized models.
- Ethical regulations and alternative research technologies pose moderate restraints on market growth.
- North America leads the market due to strong R&D funding and a developed research infrastructure.
- The Asia-Pacific region is emerging rapidly with growing biotechnology investments and expanding academic collaborations.
Market Drivers
Rising Demand for Preclinical Research in Drug and Vaccine Development
The growing need for accurate preclinical evaluation before human trials drives the Animal Model Market. Pharmaceutical and biotechnology companies use animal models to study drug efficacy, toxicity, and pharmacokinetics. Rising R&D spending in biologics, oncology, and neurological disorders strengthens the market’s foundation. Government agencies and global health organizations support animal-based research to accelerate medical innovation. Advanced models help predict clinical outcomes with improved reliability. It serves as a bridge between laboratory findings and human application. New infectious diseases further increase reliance on animal testing. The overall demand for predictive research tools continues to expand across multiple therapeutic areas.
Increasing Adoption of Genetically Engineered and Humanized Animal Models
Technological innovation in gene-editing tools like CRISPR has revolutionized model development. Researchers now replicate human genetic structures in animals with higher accuracy. These models offer deeper insight into disease pathways, aiding precision drug design. Growing use of humanized mice supports oncology and immunology research. Pharmaceutical firms adopt these models to shorten clinical trial timelines. It enhances data reproducibility and reduces unexpected trial failures. Continuous academic-industry partnerships promote advanced model creation. Expanding genetic engineering capabilities ensure the market’s sustained growth potential.
- For instance, The Jackson Laboratory supplies more than 13,000 mouse strains to over 2,400 organizations in 68 countries annually, making it the world’s single largest repository and supplier of genetically engineered and specialized mouse models for biomedical research.
Growing Government Support and Funding for Biomedical Research Programs
National institutes and research councils increase grants for biomedical innovation. These funds promote development of novel animal models and ethical experimentation standards. Public-private partnerships strengthen R&D infrastructure and improve laboratory efficiency. The Animal Model Market benefits from rising public health budgets and regional innovation initiatives. Regulatory agencies also encourage responsible testing under strict welfare norms. It encourages better-quality preclinical testing frameworks worldwide. Academic institutions invest heavily in translational medicine projects. Such initiatives enhance cross-border collaboration and knowledge exchange within research ecosystems.
- For instance, in September 2025, the US National Institutes of Health (NIH) awarded $87 million in contracts for the Standardized Organoid Modeling Center, advancing preclinical model development and marking a significant public commitment to innovation beyond traditional animal models.
Expanding Applications Across Biotechnology, Toxicology, and Academic Research
Animal models extend beyond drug discovery into toxicology, vaccine testing, and academic research. Universities use them to study genetic disorders and biological functions. Biotechnology companies depend on these systems to validate product safety. The versatility of models supports a wide spectrum of research purposes. It ensures data reliability before human trials and supports regulatory compliance. Continuous exploration of new model organisms expands research possibilities. Cross-disciplinary integration enhances overall experimental accuracy. These broad applications fuel the global momentum of scientific advancement.
Market Trends
Integration of Artificial Intelligence and Data Analytics in Preclinical Studies
AI-based analytics are transforming how preclinical results are interpreted and managed. Automated platforms analyze large datasets from animal experiments efficiently. It reduces errors and accelerates decision-making in drug development. Integration of predictive modeling improves study reproducibility and outcome precision. Machine learning tools identify disease correlations that manual methods miss. Research institutions adopt digital systems to manage experimental workflows securely. Data-driven insights enhance translational accuracy between animal and human trials. The shift toward AI adoption marks a defining trend for the Animal Model Market.
- For instance, Medidata, a leading provider of clinical trial data management, applied big data modeling techniques to a dataset of over 540 patients across multiple CAR T-cell therapy studies, successfully identifying lab biomarkers to predict risk of cytokine release syndrome a key improvement in safety prediction versus conventional methods.
Shift Toward Non-Mammalian and Alternative Biological Models
Growing ethical awareness encourages exploration of alternative species in research. Zebrafish, drosophila, and nematodes are increasingly used to replace mammals in specific studies. These models offer cost-effective, fast-replicating, and genetically transparent systems. Regulatory bodies promote their use to minimize ethical concerns. It enables faster screening of compounds without compromising biological relevance. Advances in imaging technologies enhance observation of disease mechanisms in small species. The shift diversifies research options while ensuring scientific credibility. This transition broadens the landscape of experimental biology worldwide.
Emergence of Personalized and Precision-Based Preclinical Testing
Personalized medicine research drives demand for custom-built animal models. Scientists create genetically tailored models that mirror patient-specific mutations. It supports precision drug evaluation for targeted therapies in oncology and rare diseases. Pharmaceutical developers rely on personalized models to improve trial predictability. Integration with omics technologies expands the precision research frontier. Regulatory bodies recognize these models as essential for advanced drug pipelines. Growing emphasis on patient-centric research aligns with this trend. Personalized modeling reinforces the Animal Model Market as a key enabler of precision healthcare.
Expansion of Contract Research Organizations Offering Specialized Animal Studies
Outsourcing preclinical testing to contract research organizations (CROs) is increasing globally. Companies prefer CROs for cost-efficient and time-bound model studies. It allows access to specialized expertise and high-end laboratory infrastructure. CROs provide custom testing services across toxicology, pharmacology, and genomics. Growing partnerships between biotech firms and CROs enhance testing capacity. Standardized practices improve the quality and comparability of global studies. The rise of CRO networks ensures faster R&D cycles and flexible operations. This outsourcing trend continues shaping the competitive landscape of biomedical research.
- For instance, CARE Research LLC, an established contract research organization, provides GLP-compliant multispecies toxicology and pharmacokinetics studies. Their animal facilities include surgical suites for implantable device research, and they support FDA, USDA, and EPA submissions, as detailed in their official service documentation and client case reports.
Market Challenges Analysis
Ethical Concerns and Regulatory Barriers in Animal Testing Practices
Rising ethical scrutiny challenges the Animal Model Market’s expansion. Advocacy groups and public sentiment demand reduction in animal use across research sectors. Strict regulatory frameworks impose lengthy approval procedures for experimentation. Compliance costs increase due to advanced welfare and safety standards. It compels laboratories to invest heavily in infrastructure modernization. Limited access to certain animal species restricts study diversity. Regulatory uncertainty across regions slows collaborative research initiatives. Balancing ethical obligations with scientific necessity remains a pressing challenge for researchers.
High Operational Costs and Limited Reproducibility in Experimental Outcomes
Developing and maintaining animal facilities requires significant capital and expertise. Specialized housing, veterinary care, and pathogen control elevate operational expenses. Inconsistent results across laboratories often reduce study reliability. It undermines data interpretation and increases development delays. Variations in animal genetics, handling, and environment contribute to discrepancies. Complex disease models further raise cost structures. Researchers face pressure to optimize reproducibility through advanced monitoring technologies. Achieving consistency while maintaining economic efficiency remains a persistent industry constraint.
Market Opportunities
Rising Demand for Humanized and 3D Tissue-Integrated Animal Models
The growing focus on translational medicine presents major growth avenues for the Animal Model Market. Humanized models combined with 3D tissue constructs enhance biological accuracy. They bridge the gap between traditional animal testing and human physiology. Research collaborations aim to standardize integrated model systems across laboratories. It promotes faster validation of innovative therapeutic platforms. Biotechnology startups invest in these hybrid systems for immunotherapy and gene therapy studies. Such models also support advanced biomarker discovery and targeted treatment development. Increasing funding toward these high-fidelity systems strengthens their commercial potential.
Expansion in Emerging Research Hubs and Cross-Sector Collaboration Initiatives
Asia-Pacific and Latin America are becoming global research hubs for biomedical innovation. Expanding pharmaceutical infrastructure attracts multinational investment in preclinical testing. Governments encourage academic-industry partnerships to build sustainable research ecosystems. It leads to knowledge sharing and greater innovation diversity across regions. Advances in digital tools simplify cross-border data exchange and collaboration. Regional talent growth further supports experimental research scalability. Local startups contribute fresh perspectives through niche model development. These opportunities collectively accelerate innovation and open new frontiers in life sciences.
Market Segmentation Analysis:
By Animal Type
Mice dominate the Animal Model Market due to their genetic similarity to humans, short breeding cycles, and adaptability in genetic modification. Rats follow, preferred for behavioral and neurological research because of their cognitive traits. Zebrafish and other aquatic models gain traction for cost-effective genetic studies and transparent embryonic development. Guinea pigs maintain relevance in immunology and infectious disease studies. Dogs, cats, monkeys, and rabbits remain vital for advanced pharmacokinetic and toxicology testing. It benefits from a diversified animal base supporting disease-specific and translational research outcomes.
- For instance, The Mouse Phenome Database, hosted by The Jackson Laboratory, catalogs hundreds of peer-reviewed phenotypic studies, contributing over 1,400 phenotypic measurements from more than 600 mouse strains, supporting standardized and transparent preclinical research worldwide.
By Application
Oncology remains the leading application segment, driven by global cancer research and drug pipeline expansion. CNS and metabolic disease research relies on rodent models for studying neurological pathways and diabetes-related mechanisms. Infectious and immunological disease studies use animal models for vaccine efficacy and immune response validation. Preclinical applications support new drug validation and safety profiling before human trials. Academic institutions use animals in R&D and specialized biological studies. Production and quality control segments maintain demand through biologics and biosimilar testing. It ensures a broad research application scope across healthcare disciplines.
- For instance, the National Cancer Institute’s Patient-Derived Models Repository (PDMR) provides a large collection of patient-derived xenograft (PDX) mouse models covering multiple cancer types, supporting preclinical research and global drug development efforts.
By End-User
Pharmaceutical and biotechnology companies represent the dominant end-user segment, utilizing animal models for drug discovery and regulatory testing. Academic research institutes contribute significantly through disease modeling and experimental research. Contract Research Organizations (CROs) provide cost-efficient, specialized animal testing services, meeting global demand for outsourced preclinical studies. Veterinary use forms a smaller but consistent segment for diagnostic and vaccine development in animal health. It supports collaboration across commercial, academic, and contract-based research structures, ensuring steady demand across multiple scientific and industrial domains.
Segmentation:
By Animal Type:
- Mice (leading segment)
- Rats
- Zebrafish / Others
- Guinea Pigs
- Dogs, Cats, Rabbits, Monkeys, Sheep, Hamsters, Birds, Cattle, Pigs, Amphibians (various other animal types)
By Application:
- Oncology (cancer research)
- CNS / Metabolic Diseases
- Infectious Diseases
- Immunological Diseases
- Research & Development (R&D)
- Production & Quality Control
- Preclinical Applications
- Academics and Other Research Areas
By End-User:
- Pharmaceutical & Biotechnology Companies (dominant end-user)
- Academic Research Institutes
- Contract Research Organizations (CROs)
- Veterinary Use (often a separate segment)
By Region:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America – Dominant Research and Development Hub
North America holds the largest share of the Animal Model Market, accounting for 41% of the global revenue in 2024. The region’s leadership is driven by its advanced biomedical research infrastructure, strong funding ecosystem, and a high concentration of pharmaceutical companies. The United States leads with extensive preclinical testing and strong regulatory frameworks from agencies such as the FDA and NIH. It benefits from the presence of leading contract research organizations offering specialized services. Continuous academic-industry collaborations strengthen innovation pipelines and boost translational research output. Canada contributes with growing investments in life sciences and ethical research initiatives. The regional market maintains a strong position supported by advanced laboratory technologies and skilled research talent.
Europe – Expanding Biopharmaceutical and Ethical Research Standards
Europe captures 28% of the Animal Model Market, supported by its robust biopharmaceutical sector and regulatory harmonization across member states. The region emphasizes animal welfare and ethical research, guided by REACH and EU Directive 2010/63/EU. The United Kingdom, Germany, and France are key contributors, driven by advanced R&D investments and academic partnerships. It maintains steady demand through disease modeling and toxicology research in pharmaceuticals and biotechnology. Public and private research grants sustain long-term innovation projects, while advanced facilities enhance experimental reproducibility. Collaborative frameworks across universities and CROs enable Europe to balance innovation with regulatory compliance. The region’s focus on alternative testing technologies complements ongoing reliance on validated animal models.
Asia-Pacific – Fastest Growing Region with Expanding Biotech Ecosystem
Asia-Pacific represents 22% of the global Animal Model Market and is expected to register the fastest growth through 2032. Rising healthcare expenditure and strong government funding fuel the region’s progress. China, India, and Japan lead in preclinical research due to growing pharmaceutical manufacturing and increasing disease prevalence. It benefits from cost-effective research services and expanding academic-industry collaborations. Local CROs strengthen global partnerships by offering competitive and high-quality testing capabilities. Regional infrastructure investments and technology adoption improve research scalability and reliability. The Asia-Pacific market continues evolving as a global innovation center for biomedical and pharmaceutical advancements.
Key Player Analysis:
- Charles River Laboratories International Inc.
- The Jackson Laboratory
- Taconic Biosciences, Inc.
- Envigo (now part of Inotiv)
- GenOway
- Janvier Labs
- Crown Bioscience Inc.
- Labcorp UK Ltd
- GemPharmatech
- Eurofins Scientific SE
- Biocytogen Pharma
- Cyagen Biosciences
- Trans Genic Inc.
- Hera BioLabs
- Harbour BioMed
Competitive Analysis:
The Animal Model Market features strong competition among global players focused on innovation, ethical compliance, and advanced research solutions. Key companies include Charles River Laboratories, Envigo, The Jackson Laboratory, Taconic Biosciences, and Genoway. These firms maintain leadership through extensive breeding facilities, genetic engineering expertise, and strategic partnerships with pharmaceutical and biotechnology companies. It emphasizes high-quality, reproducible animal models to support drug discovery and toxicology testing. Emerging players in Asia and Europe expand their presence through cost-efficient preclinical services and specialized genetic models. Continuous investments in automation, bioinformatics, and custom breeding programs enhance competitive positioning. The market’s structure reflects consolidation trends driven by acquisitions, collaborations, and R&D expansion to strengthen global research capabilities.
Recent Developments:
- In June 2025, Taconic Biosciences, Inc. entered into an exclusive license agreement with Helmholtz Munich to secure patented CRISPR/Cas9-based gene-editing technology for generating advanced genetically modified animal models.
- In May 2025, Charles River Laboratories International, Inc. and CHDI Foundation, Inc. extended their long-standing drug-discovery partnership, reinforcing their joint efforts in neurological disease modelling and preclinical testing.
Report Coverage:
The research report offers an in-depth analysis based on Animal Type, Application and End-User. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Growing demand for preclinical testing will continue driving advancements in genetic model development.
- Expansion of humanized and transgenic models will strengthen precision medicine research capabilities.
- Integration of AI and digital analytics will enhance reproducibility and data accuracy in preclinical studies.
- Rising investment in biotechnology will increase collaboration between academic and industrial researchers.
- Adoption of ethical and alternative testing standards will influence innovation across global research hubs.
- Expanding CRO networks will accelerate outsourcing of preclinical testing and improve market efficiency.
- Emerging economies will gain prominence through increased infrastructure investments in biomedical research.
- New applications in oncology and immunology will sustain market growth across pharmaceutical sectors.
- Continuous funding support from governments and agencies will promote sustainable research expansion.
- Global players will pursue acquisitions and partnerships to diversify service portfolios and strengthen market reach.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
```What is the current market size for Animal Model Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Animal Model Market projected to grow between 2024 and 2032?
Which Animal Model Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Animal Model Market?
Who are the leading companies in the Animal Model Market?
Which region commanded the largest share of the Animal Model Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 2,401.37 million → 2032: USD 3,827.42 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Animal Model Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Animal Model Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Animal Model Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Animal Model Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Animal Model Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Animal Model Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Animal Model Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Animal Model Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 2,401.37 million → 2032: USD 3,827.42 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Animal Model Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Animal Model Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Animal Model Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Animal Model Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

