
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| CAR-T cell therapy Market Size 2024 | USD 4,405 Million |
| CAR-T cell therapy Market, CAGR | 12.3% |
| CAR-T cell therapy Market Size 2032 | USD 11,142.53 Million |
Market Overview
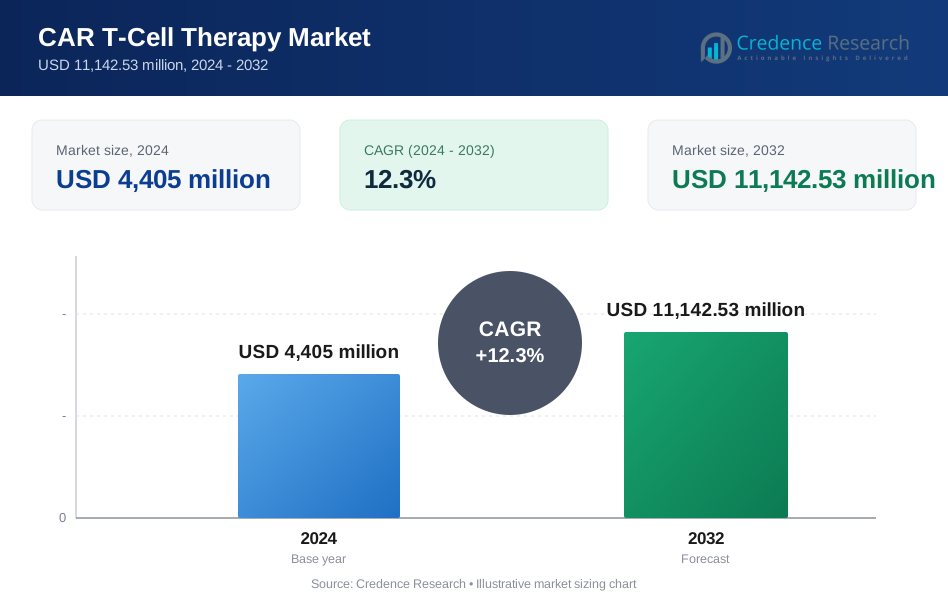
The CAR-T cell therapy Market is anticipated to grow significantly from USD 4,405 million in 2024 to USD 11,142.53 million by 2032, representing a robust compound annual growth rate (CAGR) of 12.3%.
The CAR-T cell therapy market is driven by the rising incidence of hematological malignancies, advancements in genetic engineering technologies, and increased investment in research and development. Growing awareness of the efficacy of CAR-T therapies in treating resistant cancers fuels demand, while ongoing clinical trials expand treatment indications. Additionally, strategic collaborations among pharmaceutical companies and academic institutions enhance innovation and accelerate product development. Trends such as the emergence of off-the-shelf CAR-T products and the integration of digital health solutions for patient monitoring are further shaping the market landscape, driving improved patient outcomes and accessibility to these advanced therapies.
The CAR-T cell therapy market is predominantly led by North America, accounting for a significant market share due to advanced healthcare infrastructure and robust research initiatives. Key players in this region include Bristol-Myers Squibb Company, Gilead Sciences, and Novartis AG, which are pioneering innovative therapies. In Asia, particularly China, companies like CARsgen Therapeutics and IASO Biotherapeutics are emerging players, expanding access to CAR-T treatments. The competitive landscape is marked by ongoing collaborations and research efforts aimed at enhancing therapy efficacy and accessibility across various cancer indications, driving growth in both established and emerging markets.
Market Drivers
Rising Cancer Prevalence
The increasing incidence of cancer globally is a significant driver of the CAR-T cell therapy market. For instance, the National Cancer Registry Programme (NCRP) in India reported a significant rise in cancer cases, highlighting the urgent need for effective treatments. As more individuals receive cancer diagnoses, the demand for effective treatments, such as CAR-T cell therapy, continues to grow. This rising prevalence underscores the urgent need for innovative therapeutic options that can offer hope to patients facing aggressive forms of cancer. The growing patient population seeking treatment further propels market expansion, as healthcare providers look for advanced solutions to address this pressing health crisis.
High Efficacy in Certain Cancers
CAR-T cell therapy has demonstrated remarkable efficacy in treating specific blood cancers, particularly acute lymphoblastic leukemia (ALL) and B-cell lymphomas. For instance, clinical trials and real-world data have shown high success rates of CAR-T therapies in achieving remission and improving patient outcomes. This effectiveness not only boosts confidence in the therapy but also encourages ongoing referrals from oncologists. As more success stories emerge, the market for CAR-T cell therapy continues to expand, solidifying its role in the oncology landscape.
Advancements in Technology
Ongoing research and development in CAR-T cell therapy are leading to significant technological advancements, enhancing safety, efficacy, and accessibility. Innovations in genetic engineering and manufacturing processes are streamlining therapy production and reducing costs, making CAR-T cell treatments more viable for a broader patient population. These advancements play a crucial role in driving market growth, as they facilitate the introduction of new therapies and improve the overall patient experience.
Favorable Regulatory Environment
Regulatory authorities worldwide are increasingly recognizing the transformative potential of CAR-T cell therapy, working to streamline approval processes for new treatments. This favorable regulatory environment fosters innovation and accelerates the commercialization of CAR-T therapies, expanding market access. Additionally, growing investment in research and development by pharmaceutical companies and academic institutions fuels innovation, driving the creation of new CAR-T therapies for various cancer types. As awareness of CAR-T therapy increases and new indications are explored, the market is expected to experience sustained growth.
Market Trends
Expanding Therapeutic Applications
CAR-T cell therapy is undergoing a significant transformation, moving beyond its initial focus on hematological cancers such as leukemia and lymphoma to address solid tumors. For instance, researchers are actively exploring the potential of CAR-T cell therapy for treating challenging conditions, including lung cancer, breast cancer, and glioblastoma. This expansion in therapeutic applications signifies a pivotal shift in the CAR-T landscape, as the approach seeks to offer hope to patients with previously limited treatment options. Additionally, the trend of combining CAR-T cell therapy with other treatment modalities, such as chemotherapy, immunotherapy, or targeted therapies, is emerging as a promising strategy. This combination approach aims to enhance therapeutic efficacy and overcome the resistance that can develop with monotherapies, paving the way for more comprehensive and effective cancer treatment regimens.
Technological Advancements
Significant technological advancements are shaping the future of CAR-T cell therapy, leading to the development of engineered CAR-T cells with enhanced targeting capabilities, improved persistence, and reduced side effects. Researchers are innovating by incorporating additional signaling domains and utilizing various types of T cells, as well as engineering CAR-T cells to secrete cytokines or other therapeutic agents. This evolution in CAR-T cell design aims to optimize therapeutic outcomes and improve patient safety. Furthermore, the rise of allogeneic CAR-T cell therapies-derived from healthy donor cells-offers the potential for off-the-shelf solutions. This approach not only reduces manufacturing time and costs compared to autologous therapies but also broadens access to CAR-T cell treatments. The integration of CRISPR-based gene editing technology is also making waves in the field, allowing scientists to modify T cells for enhanced functionality and a reduced risk of side effects. As these technological advancements continue to unfold, they promise to revolutionize CAR-T cell therapy, making it more accessible and effective for a diverse patient population.
Market Challenges Analysis
High Cost of Production and Limited Patient Access
The CAR-T cell therapy market faces significant challenges related to the high cost of production and limited patient access. The manufacturing process for CAR-T cells is complex, involving the collection, engineering, and expansion of a patient’s T cells. For instance, the Indian CAR-T therapy costs one-tenth that of comparable commercial products available globally, highlighting the high production costs involved. This individualized approach necessitates specialized facilities equipped with advanced technologies, as well as highly skilled personnel, all of which contribute to elevated production costs. Consequently, these factors drive the overall cost of CAR-T cell therapy to exorbitant levels. Such high treatment costs often restrict access to only a limited number of patients, particularly in low- and middle-income countries where healthcare budgets are constrained. Additionally, securing insurance reimbursement for CAR-T therapies can be complicated, as insurers may be hesitant to cover the expenses associated with a relatively new and experimental treatment. Geographic accessibility also poses a significant barrier; specialized treatment centers capable of administering CAR-T therapy are often limited to urban areas, leaving patients in rural regions without viable options for care.
Adverse Side Effects and Limited Efficacy Against Solid Tumors
Adverse side effects present another considerable challenge in the implementation of CAR-T cell therapy. One of the most serious complications is Cytokine Release Syndrome (CRS), a potentially life-threatening condition characterized by severe inflammation that can arise following treatment. Additionally, neurotoxicity can manifest in various neurological symptoms, including confusion, seizures, and even coma, underscoring the need for careful patient monitoring. Other side effects such as prolonged cytopenia, infection, and tumor lysis syndrome further complicate the therapy's safety profile. Moreover, CAR-T cell therapy exhibits limited efficacy against solid tumors, primarily due to the complex tumor microenvironment that hinders T cell infiltration. Solid tumors often exhibit antigen heterogeneity, complicating effective targeting. Furthermore, CAR-T cells risk damaging healthy tissues that share similar antigens, leading to off-target effects. Lastly, while CAR-T cell therapy can induce significant initial responses, the duration of these responses can be limited, necessitating repeated treatments. Cancer cells can also develop resistance mechanisms, such as antigen loss or downregulation, which undermine the long-term effectiveness of the therapy. Addressing these challenges is critical for enhancing the safety, accessibility, and overall impact of CAR-T cell therapy in oncology.
Market Segmentation Analysis:
By Target Indications:
The CAR-T cell therapy market is primarily segmented by target indications, which significantly influence treatment dynamics. Acute Lymphoblastic Leukemia (ALL) represents a crucial segment, as CAR-T therapies have demonstrated remarkable efficacy in pediatric patients, leading to high adoption rates. Diffuse Large B-cell Lymphoma (DLBCL) and Follicular Lymphoma are also significant segments, with numerous CAR-T therapies receiving regulatory approval and showing promising clinical outcomes. The demand for CAR-T therapies in Large B-cell Lymphoma and Mantle Cell Lymphoma continues to grow, driven by the need for effective treatments that address refractory cases. Additionally, Multiple Myeloma is emerging as a critical segment due to the potential for CAR-T cell therapies to improve patient outcomes. The "Others" category encompasses various hematological malignancies that may benefit from CAR-T therapies, reflecting a diverse and expanding treatment landscape.
By Target Antigens:
The segmentation of the CAR-T cell therapy market by target antigens reveals key drivers of growth and innovation. CD19 remains the most widely targeted antigen, particularly for blood cancers, as evidenced by the success of several CAR-T products. This segment has established a robust foundation for further advancements. BCMA (B-cell maturation antigen) is gaining traction in the Multiple Myeloma segment, with ongoing research leading to new therapies that target this antigen. CD20 is another important target antigen, primarily for B-cell malignancies, demonstrating substantial efficacy in clinical trials. The combination of CD19 and CD22 targeting is also gaining attention, as it addresses antigen escape mechanisms, enhancing treatment outcomes. The "Others" category includes emerging targets that may represent the next wave of CAR-T innovations, highlighting the dynamic and evolving nature of this market segment. Together, these antigens illustrate the diverse strategies employed in CAR-T cell therapy, driving ongoing research and development efforts.
Segments:
Based on Target Indications
- Acute Lymphoblastic Leukemia
- Diffuse Large B-cell Lymphoma
- Follicular Lymphoma
- Large B-cell Lymphoma
- Mantle Cell Lymphoma
- Multiple Myeloma
- Others
Based on Target Antigens
- CD19
- BCMA
- CD20
- CD19 / CD22
- Others
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America
North America dominates the CAR-T cell therapy market, accounting for over 45% of the global market. This significant share can be attributed to advanced healthcare infrastructure, substantial investments in research and development, and the presence of leading pharmaceutical companies. The United States, in particular, is a frontrunner in CAR-T therapy adoption, with several therapies approved by the Food and Drug Administration (FDA) and a growing number of clinical trials aimed at expanding treatment indications. The increasing prevalence of hematological cancers and the rising awareness of CAR-T therapies among healthcare professionals and patients are driving market growth in this region. Furthermore, favorable reimbursement policies and a robust regulatory environment support rapid commercialization, enabling broader patient access to CAR-T therapies.
Europe
In Europe, the CAR-T cell therapy market is witnessing rapid growth, with an expected market share of approximately 30%. The region is experiencing a surge in the adoption of CAR-T therapies, fueled by an increase in cancer incidence and advancements in technology. Countries such as Germany, the UK, and France are at the forefront, with several CAR-T therapies already approved by the European Medicines Agency (EMA). Collaborative efforts between academic institutions and biopharmaceutical companies are enhancing research and development, particularly for new CAR-T applications targeting solid tumors. Additionally, the European market benefits from increasing government initiatives aimed at improving healthcare access and funding innovative therapies. However, challenges such as reimbursement hurdles and the need for specialized treatment centers persist, necessitating ongoing efforts to ensure wider accessibility and affordability of CAR-T cell therapies across the continent.
Key Player Analysis
- Gilead Sciences, Inc. (US)
- ImmunoAct (India)
- Autolus Therapeutics (UK)
- Johnson & Johnson (US)
- Bristol-Myers Squibb Company (US)
- Novartis AG (Switzerland)
- Allogene Therapeutics (US)
- CRISPR Therapeutics (Switzerland)
- Wugen (US)
- IASO Biotherapeutics (China)
- JW (Cayman) Therapeutics Co. Ltd (China)
- CARsgen Therapeutics Holdings Limited (China)
- Cartesian Therapeutics, Inc. (US)
- Guangzhou Bio-gene Technology Co., Ltd (China)
- Celgene Corporation (US)
Competitive Analysis
The competitive landscape of the CAR-T cell therapy market is characterized by several leading players, including Bristol-Myers Squibb Company, Gilead Sciences, Inc., Novartis AG, Johnson & Johnson, CARsgen Therapeutics Holdings Limited, IASO Biotherapeutics, JW (Cayman) Therapeutics Co. Ltd, ImmunoAct, CRISPR Therapeutics, Autolus Therapeutics, Allogene Therapeutics, Cartesian Therapeutics, Guangzhou Bio-gene Technology Co., Ltd, and Wugen. These companies are engaged in robust research and development efforts, focusing on expanding the therapeutic applications of CAR-T therapies, particularly for solid tumors. Competitive strategies include technological advancements in CAR-T cell engineering and enhanced manufacturing processes to improve efficacy and reduce costs. Collaborations and partnerships with academic institutions and biotech firms are also prevalent, allowing for knowledge sharing and resource optimization. Additionally, these players are addressing challenges related to high production costs and patient access, ensuring they remain at the forefront of this rapidly evolving market.
Recent Developments
- In May 2024, The US FDA granted accelerated approval to BREYANZI (lisocabtagene maraleucel) for the treatment of adult patients with relapsed or refractory Follicular Lymphoma (FL) who have received two or more prior lines of systemic therapy.
- In April 2024, Bristol entered into a worldwide capacity reservation and supply agreement with Cellares to manufacture CAR T-cell therapies using Cellares’s automated & high-throughput manufacturing platform called Cell Shuttle.
- In January 2023, Gilead received approval from the US FDA for a change in manufacturing processes for YESCARTA (axicabtagene ciloleucel) to reduce the median turnaround time (TAT) in the US to 14 days from 16 days.
Market Concentration & Characteristics
The CAR-T cell therapy market exhibits a moderate to high concentration, dominated by a few key players who possess significant market share and influence. Major pharmaceutical companies, such as Bristol-Myers Squibb, Gilead Sciences, and Novartis, leverage their extensive resources and expertise to lead in research, development, and commercialization of CAR-T therapies. This market is characterized by rapid innovation, as companies continually invest in advanced technologies to enhance the efficacy and safety profiles of their products. The focus is not only on hematological malignancies but also on expanding applications to solid tumors, which presents both opportunities and challenges. Moreover, the regulatory landscape is evolving, with agencies increasingly recognizing the potential of CAR-T therapies, thereby facilitating faster approvals. However, high production costs and access barriers persist, prompting companies to explore novel reimbursement models and strategic partnerships to ensure wider patient accessibility and drive market growth in this dynamic sector.Top of Form
Report Coverage
The research report offers an in-depth analysis based on Target Indications, Target Antigens and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Continued advancements in CAR-T cell engineering are expected to enhance targeting precision and reduce side effects.
- Expansion of CAR-T cell therapies into solid tumors will significantly broaden treatment options for cancer patients.
- The development of allogeneic CAR-T therapies may provide off-the-shelf solutions, reducing manufacturing costs and time.
- Ongoing research into combination therapies will likely improve treatment efficacy and overcome resistance mechanisms.
- Increasing investments in CAR-T technology by pharmaceutical and biotech companies will drive innovation and market growth.
- Enhanced regulatory support will streamline approval processes, facilitating faster market entry for new therapies.
- Growing patient awareness and education will lead to increased demand for CAR-T cell therapies.
- Collaborations between academic institutions and industry leaders will foster breakthroughs in CAR-T research and development.
- Innovative reimbursement models will emerge to address high treatment costs and improve patient access.
- The global CAR-T cell therapy market is projected to expand significantly, reflecting rising cancer prevalence and demand for effective treatments.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Cancer Prevalence
The increasing global incidence of hematological malignancies, such as leukemia and lymphoma, is fueling demand for innovative therapies like CAR-T, as traditional treatments often fail in refractory cases.
High Efficacy in Certain Cancers
CAR-T cell therapies have demonstrated remarkable remission rates in specific blood cancers, notably acute lymphoblastic leukemia and B-cell lymphomas, driving adoption among oncologists and patients seeking effective alternatives.
Advancements in Genetic Engineering
Ongoing improvements in gene editing and cell manufacturing technologies are enhancing the safety, efficacy, and scalability of CAR-T therapies, making them more accessible and cost-effective for a broader patient population.
Favorable Regulatory Environment
Streamlined approval processes and supportive regulatory frameworks in major markets, particularly the US and Europe, are accelerating the commercialization and clinical adoption of new CAR-T therapies.
Strategic Collaborations and Investments
Partnerships between pharmaceutical companies, biotech firms, and academic institutions are fostering innovation, expanding research pipelines, and enabling the development of next-generation CAR-T products targeting both hematological and solid tumors.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the CAR-T Cell Therapy market?
What factors are driving the growth of the CAR-T Cell Therapy market?
What are the key segments within the CAR-T Cell Therapy market?
What are some challenges faced by the CAR-T Cell Therapy market?
Who are the major players in the CAR-T Cell Therapy market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Target Antigens
- 1.2.1 CD19
- 1.2.2 BCMA
- 1.2.3 CD20
- 1.2.4 CD19 / CD22
- 1.2.5 Others
- 1.3 By Target Indications
- 1.3.1 Acute Lymphoblastic Leukemia
- 1.3.2 Diffuse Large B-cell Lymphoma
- 1.3.3 Follicular Lymphoma
- 1.3.4 Large B-cell Lymphoma
- 1.3.5 Mantle Cell Lymphoma
- 1.3.6 Multiple Myeloma
- 1.3.7 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 4,405 million → 2032: USD 11,142.53 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global CAR T-Cell Therapy Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global CAR T-Cell Therapy Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global CAR T-Cell Therapy Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global CAR T-Cell Therapy Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global CAR T-Cell Therapy Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global CAR T-Cell Therapy Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global CAR T-Cell Therapy Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global CAR T-Cell Therapy Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 4,405 million → 2032: USD 11,142.53 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global CAR T-Cell Therapy Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Target Antigens - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 CD19
- 12.3.7.2 BCMA
- 12.3.7.3 CD20
- 12.3.7.4 CD19 / CD22
- 12.3.7.5 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Target Indications - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Acute Lymphoblastic Leukemia
- 12.4.7.2 Diffuse Large B-cell Lymphoma
- 12.4.7.3 Follicular Lymphoma
- 12.4.7.4 Large B-cell Lymphoma
- 12.4.7.5 Mantle Cell Lymphoma
- 12.4.7.6 Multiple Myeloma
- 12.4.7.7 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 Global CAR T-Cell Therapy Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global CAR T-Cell Therapy Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global CAR T-Cell Therapy Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Gilead Sciences, Inc.
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Bristol-Myers Squibb Company
- 17.4 Novartis AG
- 17.5 Johnson & Johnson
- 17.6 CARsgen Therapeutics Holdings Limited
- 17.7 IASO Biotherapeutics
- 17.8 JW (Cayman) Therapeutics Co. Ltd
- 17.9 ImmunoAct
- 17.10 CRISPR Therapeutics
- 17.11 Autolus Therapeutics
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.
