
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| In Vitro Toxicology Testing Market Size 2024 | USD 12,247.5 Million |
| In Vitro Toxicology Testing Market, CAGR | 11.2% |
| In Vitro Toxicology Testing Market Size 2032 | USD 28,634.25 Million |
Market Overview:
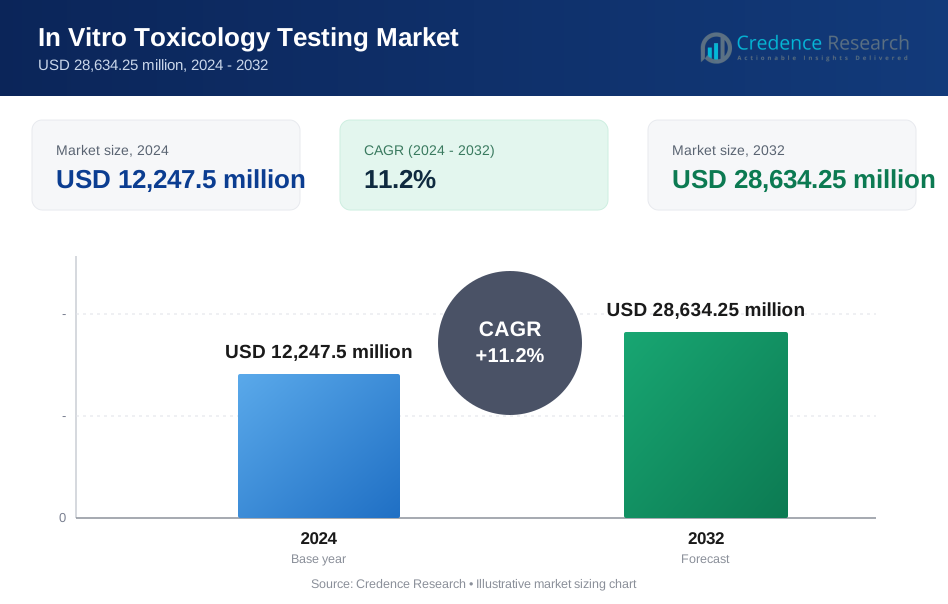
The In Vitro Toxicology Testing Market is poised for significant growth, with its size expected to increase from USD 12,247.5 million in 2024 to USD 28,634.25 million by 2032, reflecting a Compound Annual Growth Rate (CAGR) of 11.2% over the forecast period. This robust growth is driven by the increasing adoption of in vitro methods for toxicology testing, which offer several advantages over traditional in vivo methods, including reduced animal testing, cost-effectiveness, and faster results.
Several key factors are driving the growth of the In Vitro Toxicology Testing Market. The rising awareness and implementation of stringent regulations regarding animal testing have led to a shift towards alternative testing methods. Regulatory bodies, such as the European Union’s REACH (Registration, Evaluation, Authorisation, and Restriction of Chemicals) and the U.S. Environmental Protection Agency (EPA), are promoting the use of in vitro toxicology testing to ensure safety and compliance. Additionally, technological advancements in cell culture and high-throughput screening techniques are enhancing the accuracy and efficiency of in vitro tests. The growing focus on personalized medicine and the increasing demand for drug development and safety assessment further fuel the market’s expansion.
Geographically, North America dominates the In Vitro Toxicology Testing Market, holding the largest share due to the region’s advanced healthcare infrastructure, strong presence of key market players, and supportive regulatory environment. The United States, in particular, is a major contributor, driven by significant investments in research and development and the presence of leading pharmaceutical and biotechnology companies. Europe follows closely, with countries like Germany, the United Kingdom, and France leading the market, supported by stringent regulations and a strong focus on reducing animal testing. The Asia-Pacific region is expected to witness the highest growth rate during the forecast period, attributed to the expanding healthcare infrastructure, increasing investments in research and development, and rising awareness of alternative testing methods in countries like China and India.
Market Drivers:
Regulatory Push for Alternative Testing Methods:
One of the primary drivers of the In Vitro Toxicology Testing market is the growing regulatory pressure to reduce or eliminate animal testing in toxicology studies. Government agencies and regulatory bodies across the globe are increasingly advocating for alternative testing methods that do not involve the use of animals. For instance, the European Union's REACH (Registration, Evaluation, Authorisation and Restriction of Chemicals) regulation has stringent requirements for chemical testing, promoting the use of in vitro methods. Similarly, the U.S. Environmental Protection Agency (EPA) has set forth initiatives to minimize animal testing, encouraging the adoption of in vitro toxicology testing methods that are more ethical and can provide faster results.
Technological Advancements in Testing Methods:
Technological advancements in in vitro toxicology testing are significantly driving market growth. The development of more sophisticated and reliable in vitro models, such as 3D cell cultures and organ-on-a-chip technologies, has enhanced the accuracy and relevance of toxicity testing. For instance, companies are increasingly leveraging human-derived cell lines and advanced imaging techniques to simulate human responses to chemicals more precisely. These innovations not only improve the predictive power of toxicology tests but also reduce the time and cost associated with traditional in vivo methods, making them an attractive alternative for pharmaceutical and chemical industries.
Growing Awareness and Adoption in the Pharmaceutical Industry:
The pharmaceutical industry is increasingly adopting in vitro toxicology testing as part of its drug development process. With the high costs and ethical concerns associated with animal testing, pharmaceutical companies are turning to in vitro methods to screen for toxicity early in the drug development pipeline. For example, high-throughput screening techniques allow for the rapid assessment of potential toxic effects in a large number of compounds, helping to identify and eliminate harmful candidates before advancing to more costly and time-consuming in vivo studies. This shift is driven by the need to improve the efficiency of drug development while adhering to ethical standards.
Supportive Government Initiatives and Funding:
Government initiatives and funding are playing a crucial role in promoting the adoption of in vitro toxicology testing. Various governments and international organizations are providing grants and funding for research and development in this field to encourage the development of new, non-animal testing methods. For instance, the U.S. National Institutes of Health (NIH) and the European Commission have allocated significant resources to support the advancement of alternative toxicology testing methods. These initiatives not only help in the development of new testing technologies but also promote their adoption across different industries, thereby driving market growth.
Market Trends:
Adoption of 3D Cell Cultures and Organoids:
A significant trend in the In Vitro Toxicology Testing market is the increasing adoption of 3D cell cultures and organoids. These advanced models provide a more accurate representation of human tissues and organs compared to traditional 2D cell cultures. For instance, organoids can mimic the complex architecture of organs, allowing for more precise testing of drug toxicity and disease modelling. This trend is driven by the need for more reliable and human-relevant data, which is particularly important in the pharmaceutical and cosmetics industries, where regulatory bodies are demanding better predictive models for human safety.
Integration of Artificial Intelligence and Machine Learning:
The integration of artificial intelligence (AI) and machine learning (ML) into in vitro toxicology testing is revolutionizing the field by enhancing the analysis and interpretation of complex biological data. AI algorithms are increasingly being used to predict toxicological outcomes based on large datasets generated from in vitro experiments. For example, companies are utilizing AI to analyze high-throughput screening data, identifying potential toxic effects more quickly and accurately than traditional methods. This trend not only accelerates the testing process but also improves the precision of toxicity predictions, leading to better decision-making in drug development and chemical safety assessment.
Shift Towards Personalized Toxicology Testing:
Another emerging trend is the shift towards personalized toxicology testing, which involves the use of patient-derived cells to predict individual responses to drugs and chemicals. This approach is particularly relevant in the context of precision medicine, where the goal is to tailor treatments to individual patients based on their genetic and biological profiles. For instance, some research laboratories are developing in vitro models using cells derived from patients with specific genetic mutations, enabling more accurate assessments of drug toxicity and efficacy on a personalized level. This trend is expected to play a crucial role in reducing adverse drug reactions and improving patient safety.
Regulatory Encouragement for Alternative Methods:
Regulatory bodies are increasingly encouraging the use of alternative methods to animal testing, which is driving the adoption of in vitro toxicology testing. This trend is particularly evident in regions like the European Union, where regulations such as REACH and the Cosmetics Directive have established strict guidelines for chemical and cosmetic testing, favouring in vitro methods over animal models. For instance, the European Chemicals Agency (ECHA) has been actively promoting the use of in vitro assays as part of its regulatory framework. This shift is not only in response to ethical concerns but also to the growing recognition that in vitro methods can provide more human-relevant data, thereby improving the safety and efficacy of products brought to market.
Market Challenges Analysis:
High Cost of Equipment:
One of the primary challenges is the high cost of toxicology testing equipment. Advanced toxicology testing technologies, such as high-throughput screening (HTS) systems, are expensive, particularly for small and emerging countries that wish to purchase multiple instruments. This financial burden limits the widespread adoption of in vitro toxicology testing, especially in resource-constrained settings.
Limited Predictive Ability:
Another significant restraint is the limited predictive ability of in vitro testing compared to in vivo testing. While in vitro methods offer several advantages, they may not fully replicate the complex interactions that occur within a living organism. This limitation affects the accuracy and reliability of in vitro tests, posing a challenge to their adoption in regulatory and clinical settings.
Scarcity of In Vitro Models:
The scarcity of in vitro models to detect immunostimulants and autoimmunity also poses a challenge to the market. The development of reliable in vitro models for these specific endpoints is still in progress, limiting the scope of in vitro toxicology testing. This gap in available models affects the comprehensive assessment of toxicity and safety.
Technological Advancements and Adoption:
Technological advancements in toxicology testing are continuously evolving, but their rapid pace can limit the adoption rate. Healthcare facilities and research institutions may face challenges in keeping up with the latest technologies, leading to operational inefficiencies and increased costs. Additionally, the need for continuous training and updates further complicates the adoption process.
Regulatory Constraints:
Lastly, regulatory constraints can negatively impact the market. Compliance with stringent regulatory standards and obtaining necessary approvals for new in vitro testing methods can be time-consuming and costly. These regulatory hurdles can delay the introduction of innovative toxicology testing technologies, limiting market growth.
Market Segmentation Analysis:
By Type
The In Vitro Toxicology Testing Market is segmented by type into equipment, assay kits, consumables, software, and services. Consumables hold the largest market share due to the recurring need for reagents and other materials in toxicology testing procedures. Assay kits are also significant, driven by their extensive use in various testing applications.
By Technology
By technology, the market is categorized into cell culture, high-throughput screening (HTS), and toxicogenomics. Cell culture technology dominates the market, attributed to its widespread application in toxicity testing and drug development. High-throughput screening (HTS) is gaining traction due to its ability to rapidly test large numbers of samples, enhancing efficiency and reducing costs. Toxicogenomics, though emerging, offers promising potential in understanding the genetic basis of toxicity.
By End User
The market is also segmented by end user into pharmaceuticals and biopharmaceuticals, cosmetics and household products, food industry, and chemicals. Pharmaceuticals and biopharmaceuticals lead this segment, driven by the increasing demand for drug safety and efficacy testing. The cosmetics and household products segment are also significant, propelled by the growing emphasis on safety and regulatory compliance. The food industry and chemicals segment contribute to the market, focusing on the safety assessment of food additives and chemical substances.
Segmentations:
By Product Type
- Equipment
- Assay kits
- Consumables
- Software
- Others
By Technology
- PCR Technology
- Western Blot
- Cell Culture Technology
- Imaging Technology
- Screening Technology
- Others
By Method
- Cellular Assay
- Biochemical Assay
- In Silica
- Ex-vivo
By Application
- Neuro Toxicity
- Dermal Toxicity
- Cytotoxicity
- Others
By End-User
- Pharmaceuticals and Biopharmaceuticals
- Cosmetics and Household Products
- Food Industry
- Chemicals
- Others
By Region
- North America
- US
- Canada
- Mexico
- Europe
- Germany
- France
- UK
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of Middle East and Africa
Regional Analysis:
North America North America holds the largest share of the In Vitro Toxicology Testing market, accounting for approximately 40% of the global market. This dominance is primarily driven by the United States, which benefits from strong regulatory support for alternative testing methods, substantial investments in research and development, and the presence of major industry players. The U.S. Food and Drug Administration (FDA) and the Environmental Protection Agency (EPA) are at the forefront of encouraging in vitro methods to replace traditional animal testing. Additionally, the high adoption of advanced technologies, such as 3D cell cultures and artificial intelligence, further propels market growth in this region.
Europe Europe follows closely, capturing around 30% of the global market share. The region's leadership in in vitro toxicology testing is largely due to stringent regulatory requirements, such as the REACH regulation and the EU Cosmetics Directive, which mandate the use of non-animal testing methods. Countries like Germany, the United Kingdom, and France are key contributors to the European market, supported by well-established research institutions and significant government funding for the development of alternative testing methods. The European Chemicals Agency (ECHA) plays a critical role in promoting in vitro methods, ensuring compliance with safety and ethical standards.
Asia-Pacific The Asia-Pacific region is expected to witness the highest growth rate during the forecast period, currently holding about 20% of the global market share. This growth is driven by increasing government initiatives to modernize healthcare systems, rising awareness of animal welfare, and the rapid adoption of advanced testing technologies. Countries such as China, Japan, and South Korea are leading the way in implementing in vitro toxicology methods, supported by favourable regulatory environments and growing investments in biotechnology. The expanding pharmaceutical and cosmetics industries in these countries also contribute to the rising demand for in vitro toxicology testing.
Latin America and the Middle East & Africa Latin America and the Middle East & Africa collectively account for the remaining 10% of the global market share. In Latin America, Brazil and Mexico are emerging markets, with growing awareness and adoption of in vitro testing methods driven by increasing regulatory scrutiny and international collaborations. However, the market is still developing, with challenges related to infrastructure and funding. In the Middle East & Africa, the market is gradually expanding, particularly in countries like South Africa and the UAE, where governments are investing in healthcare innovation and aligning with global standards for safety and ethical testing. Despite these advancements, the market in these regions remains smaller compared to North America and Europe, primarily due to limited resources and slower adoption of new technologies.
Key Player Analysis:
- Thermo Fisher Scientific Inc.
- Laboratory Corporation of America Holdings
- Bio-Rad Laboratories, Inc.
- General Electric Company
- Eurofins Scientific
- Merck KGaA
- Charles River Laboratories International, Inc.
- Catalent, Inc.
- Evotec
- SGS S.A.
Competitive Analysis:
The In Vitro Toxicology Testing market is highly competitive, with several key players driving innovation and expansion. Leading companies such as Thermo Fisher Scientific, Merck KGaA, and Agilent Technologies dominate the market due to their extensive product portfolios, strong research and development capabilities, and global distribution networks. These companies leverage their advanced technologies, such as high-throughput screening and 3D cell culture systems, to maintain a competitive edge. Additionally, they actively engage in strategic partnerships and acquisitions to enhance their market presence and expand their offerings in emerging markets. Other notable players include Bio-Rad Laboratories, Charles River Laboratories, and Covance Inc., which focus on providing specialized testing services and developing novel in vitro models. The market is characterized by continuous technological advancements, regulatory pressures to reduce animal testing, and increasing investments in biotechnology, all of which contribute to the dynamic and competitive landscape.
Recent Developments:
- In 2024, Thermo Fisher Scientific introduced a new line of enhanced 3D cell culture products specifically designed for in vitro toxicology testing. These products are aimed at improving the accuracy of toxicity assessments by better mimicking human tissue environments. The company emphasized that these advancements will help researchers obtain more reliable data, reducing the need for animal testing.
- In 2023, Merck KGaA expanded its portfolio of AI-powered predictive toxicology tools. These tools are designed to analyze large datasets generated from in vitro experiments, improving the ability to predict potential toxic effects of new compounds. Merck’s development focuses on enhancing the speed and accuracy of toxicity screening, aligning with the industry's shift towards more data-driven approaches in toxicology.
- In 2022, Agilent Technologies launched a next-generation high-throughput screening (HTS) system for in vitro toxicology testing. This system significantly increases the speed at which large volumes of compounds can be screened for toxicity, making it an ideal solution for pharmaceutical companies looking to streamline their drug development processes. The system's integration with advanced data analytics tools also enhances its capability to detect subtle toxic effects early in the testing phase.
Market Concentration & Characteristics:
The In Vitro Toxicology Testing market is moderately concentrated, with several key players holding significant market shares due to their extensive product portfolios and strong research and development capabilities. Companies like Thermo Fisher Scientific, Merck KGaA, and Agilent Technologies dominate the market, leveraging their advanced technologies and global distribution networks to maintain a competitive edge. The market is characterized by continuous innovation, particularly in the development of 3D cell cultures, AI-powered predictive tools, and high-throughput screening systems. Additionally, the market is influenced by stringent regulatory frameworks that encourage the adoption of in vitro methods over traditional animal testing. Despite the dominance of a few large players, the market remains dynamic, with opportunities for growth driven by increasing demand for alternative toxicology testing methods and expanding adoption in emerging markets.
Report Coverage:
The research report offers an in-depth analysis based on Product Type, Technology, Method, and Application. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Increased adoption of 3D cell culture models and organ-on-a-chip technologies will enhance the physiological relevance of toxicity testing.
- Integration of artificial intelligence and machine learning will improve data analysis and predictive modelling capabilities.
- Expansion of applications beyond pharmaceutical testing into cosmetics, food additives, and environmental toxicology.
- Growing emphasis on personalized medicine will drive demand for more sophisticated and tailored toxicity testing approaches.
- Development of high-throughput screening methods will accelerate the pace of toxicity assessments for large compound libraries.
- Increased focus on alternatives to animal testing will boost investment in advanced in vitro technologies.
- Emergence of multi-organ models will enable better assessment of systemic toxicity and organ interactions.
- Integration of -omics technologies will provide deeper insights into molecular mechanisms of toxicity.
- Rising regulatory acceptance of in vitro methods will drive their adoption across various industries.
- Collaboration between academia, industry, and regulatory bodies will foster innovation and standardization of in vitro toxicology testing methods.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Regulatory Push for Alternative Testing Methods
Stringent regulations in regions like the EU and US are driving the adoption of in vitro toxicology testing as authorities seek to reduce or eliminate animal testing, ensuring compliance and ethical standards in chemical and pharmaceutical safety assessments.
Technological Advancements in Testing Methods
Innovations such as 3D cell cultures, organ-on-a-chip, and high-throughput screening are improving the accuracy, speed, and cost-effectiveness of in vitro toxicology testing, making these methods more attractive to industry stakeholders.
Growing Adoption in the Pharmaceutical Industry
Pharmaceutical and biopharmaceutical companies are increasingly integrating in vitro toxicology testing into their drug development pipelines to identify toxic compounds early, reduce development costs, and meet regulatory requirements for non-animal testing.
Supportive Government Initiatives and Funding
Governments and international organizations are providing grants and funding to accelerate the development and adoption of alternative toxicology testing methods, fostering innovation and expanding market reach.
Integration of Artificial Intelligence and Machine Learning
The use of AI and ML in analyzing complex biological data from in vitro tests is enhancing predictive accuracy and efficiency, enabling faster and more reliable toxicity assessments for new compounds.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the In Vitro Toxicology Testing Market?
What factors are driving the growth of the In Vitro Toxicology Testing Market?
What are some challenges faced by the In Vitro Toxicology Testing Market?
Who are the major players in the In Vitro Toxicology Testing Market?
Which segment is leading the market share?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End-User
- 1.2.1 Pharmaceuticals and Biopharmaceuticals
- 1.2.2 Cosmetics and Household Products
- 1.2.3 Food Industry
- 1.2.4 Chemicals
- 1.2.5 Others
- 1.3 By Technology
- 1.3.1 PCR Technology
- 1.3.2 Western Blot
- 1.3.3 Cell Culture Technology
- 1.3.4 Imaging Technology
- 1.3.5 Screening Technology
- 1.3.6 Others
- 1.4 By Application
- 1.4.1 Neuro Toxicity
- 1.4.2 Dermal Toxicity
- 1.4.3 Cytotoxicity
- 1.4.4 Others
- 1.5 By Product Type
- 1.5.1 Equipment
- 1.5.2 Assay kits
- 1.5.3 Consumables
- 1.5.4 Software
- 1.5.5 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 12,247.5 million → 2032: USD 28,634.25 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global In Vitro Toxicology Testing Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global In Vitro Toxicology Testing Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global In Vitro Toxicology Testing Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global In Vitro Toxicology Testing Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global In Vitro Toxicology Testing Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global In Vitro Toxicology Testing Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global In Vitro Toxicology Testing Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global In Vitro Toxicology Testing Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 12,247.5 million → 2032: USD 28,634.25 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global In Vitro Toxicology Testing Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End-User - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Pharmaceuticals and Biopharmaceuticals
- 12.3.7.2 Cosmetics and Household Products
- 12.3.7.3 Food Industry
- 12.3.7.4 Chemicals
- 12.3.7.5 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Technology - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 PCR Technology
- 12.4.7.2 Western Blot
- 12.4.7.3 Cell Culture Technology
- 12.4.7.4 Imaging Technology
- 12.4.7.5 Screening Technology
- 12.4.7.6 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Neuro Toxicity
- 12.5.7.2 Dermal Toxicity
- 12.5.7.3 Cytotoxicity
- 12.5.7.4 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Product Type - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Equipment
- 12.6.7.2 Assay kits
- 12.6.7.3 Consumables
- 12.6.7.4 Software
- 12.6.7.5 Others
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global In Vitro Toxicology Testing End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global In Vitro Toxicology Testing Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global In Vitro Toxicology Testing Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global In Vitro Toxicology Testing Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Thermo Fisher Scientific Inc.
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Merck KGaA
- 18.4 Agilent Technologies
- 18.5 Bio-Rad Laboratories, Inc.
- 18.6 Eurofins Scientific
- 18.7 Charles River Laboratories International, Inc.
- 18.8 Laboratory Corporation of America Holdings
- 18.9 Catalent, Inc.
- 18.10 Evotec
- 18.11 SGS S.A.
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

