
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Auger Drilling Market Size 2024 | USD 2,369.30 million |
| Auger Drilling Market, CAGR | 6.87% |
| Auger Drilling Market Size 2032 | USD 4,187.70 million |
Market Overview:
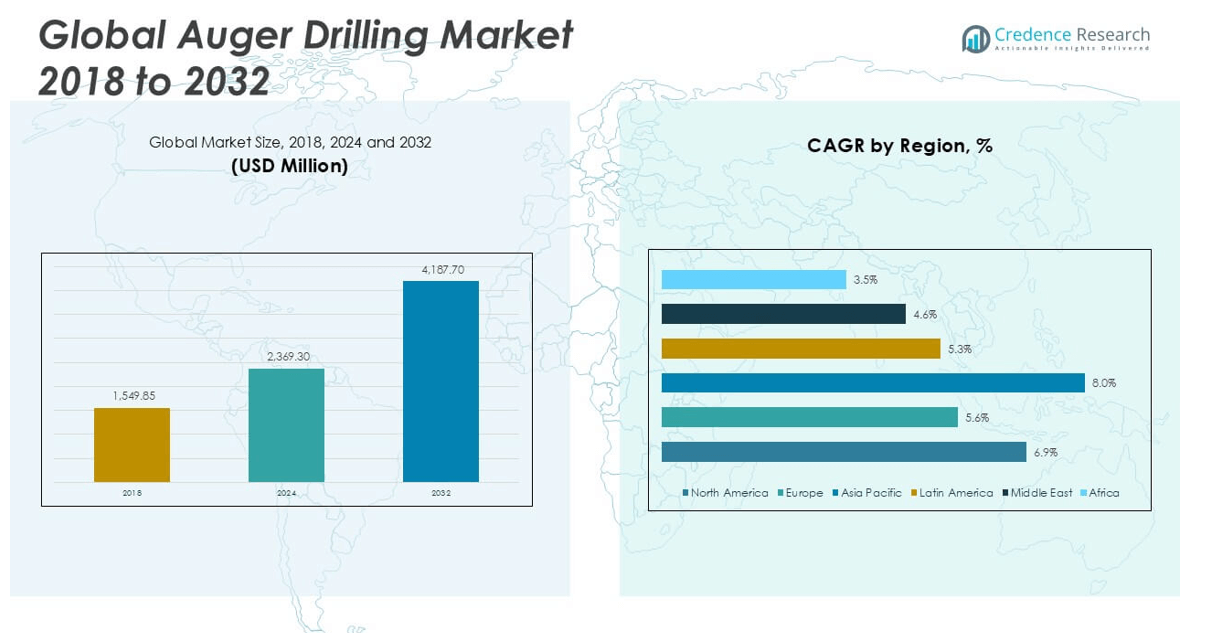
The Auger Drilling market size was valued at USD 1,549.85 million in 2018 to USD 2,369.30 million in 2024 and is anticipated to reach USD 4,187.70 million by 2032, at a CAGR of 6.87% during the forecast period.
The auger drilling market is led by prominent players such as Caterpillar Inc., Sandvik AB, Liebherr Group, Hitachi Construction Machinery, Soilmec S.p.A, Bauer Maschinen GmbH, and Atlas Copco AB, all of which focus on technological innovation, equipment durability, and global service networks. These companies maintain a competitive edge through diversified product offerings and strategic expansions across high-growth regions. North America emerged as the leading regional market in 2024, capturing approximately 42.3% of the global market share, driven by extensive infrastructure projects and ongoing utility developments. Asia Pacific follows closely, supported by strong demand from construction and mining sectors in emerging economies such as China and India. The competitive landscape is defined by continuous R&D investments, the introduction of electric and automated auger machines, and strategic collaborations aimed at expanding market reach and meeting varied end-user demands.
Market Insights
- The global auger drilling market was valued at USD 2,369.30 million in 2024 and is projected to reach USD 4,187.70 million by 2032, growing at a CAGR of 6.87% during the forecast period.
- Market growth is primarily driven by rising infrastructure development, increasing utility installations, and expanding mining and geotechnical survey activities across emerging and developed economies.
- Continuous Flight Auger Drilling dominates the type segment due to its efficiency in deep foundation and construction projects, while truck-mounted rigs hold the largest equipment share for their versatility and high mobility.
- Key players such as Caterpillar Inc., Sandvik AB, and Liebherr Group lead the competitive landscape through advanced technology integration and global expansion strategies, though high initial investment and operational costs restrain wider adoption.
- North America leads with a 42.3% market share, followed by Asia Pacific at 31.0%, driven by rapid urbanization, industrialization, and increasing investment in public infrastructure.
Market Segmentation Analysis:
By Type
The Continuous Flight Auger Drilling segment holds the dominant share in the auger drilling market by type, driven by its efficiency in creating deep, straight boreholes without the risk of collapse. This method is widely adopted in construction and geotechnical projects, as it enables faster drilling while maintaining borehole stability. Hollow Stem Auger Drilling also shows significant growth potential due to its effectiveness in environmental sampling and groundwater monitoring. The rising demand for precise and clean drilling in urban and environmental applications continues to propel these advanced auger types over conventional handheld or bucket augers.
- For instance, Liebherr’s LB 25 CFA system drills to depths up to 53.2 m in one pass using lattice‑boom carriers, ensuring borehole integrity and high throughput.
By Equipment
Among the equipment types, Truck-Mounted Auger Drilling Rigs lead the market with the highest revenue share, owing to their mobility, versatility, and widespread use in large-scale construction and infrastructure projects. These rigs offer superior reach and power, making them ideal for deep drilling in varied terrains. Crawler-Mounted rigs follow closely, favored for their stability in rough terrains such as mining and oil exploration sites. Meanwhile, mini and heavy-duty auger machines are gaining popularity in specialized tasks due to their targeted performance, further diversifying the market’s equipment landscape.
- For example, Sandvik’s DR416i crawler‑mounted blasthole drill delivers a single-pass depth of 21 m and total capacity up to 42.4 m, blending automation readiness with rugged design.
By Mounting
In terms of mounting, Truck-Mounted Augers dominate the market due to their enhanced portability and high operational efficiency across diverse applications such as utilities, construction, and oil exploration. These systems support rapid deployment and reduce downtime, making them a preferred choice for time-sensitive projects. Handheld or portable augers serve niche applications in agriculture and light-duty tasks, where maneuverability and ease of use are key. However, their market share remains limited compared to truck-mounted systems, which continue to expand due to infrastructure development and growing demand for mechanized drilling solutions.
Market Overview
Infrastructure Development Across Emerging Economies
Rapid infrastructure expansion in emerging economies is a major growth driver for the auger drilling market. Increasing investments in transportation, utilities, and commercial construction are creating substantial demand for efficient and reliable drilling techniques. Governments in countries such as India, Brazil, and Indonesia are prioritizing road networks, smart cities, and power infrastructure, fueling the need for versatile auger drilling equipment. The growing requirement for foundation drilling, pole installation, and geotechnical surveys is further accelerating the market's adoption of advanced auger drilling solutions.
- For instance, Soilmec’s SR‑145 hydraulic rig supports Continuous Flight Auger piles up to 36 m depth, handling pile diameters up to 1,200 mm, and operates with a 470 kW engine and 435 kNm torque enabling efficient execution of deep foundation and pole installation tasks in projects across India and Brazil.
Rising Demand for Environmental and Geotechnical Investigations
The growing emphasis on environmental protection and land assessment has increased the adoption of auger drilling for soil sampling and groundwater monitoring. Hollow stem and continuous flight augers are particularly favored for their accuracy and minimal environmental disturbance. Regulatory mandates and ESG compliance in sectors such as mining, construction, and oil exploration are driving the need for detailed geotechnical investigations. As industries prioritize safe land usage and sustainable practices, auger drilling continues to gain traction as a dependable and precise method for subsurface data collection.
- For instance, Soilmec’s SF‑65 CFA rig handles pile diameters up to 1,000 mm and depths of 27 m using a 205 kW engine and 165 kNm torque, delivering minimal disturbance during hollow-stem sampling operations in sensitive urban sites.
Technological Advancements in Auger Equipment
Technological innovation has significantly enhanced auger drilling capabilities, making equipment more efficient, automated, and adaptable to diverse terrain conditions. Integration of GPS, telematics, and real-time monitoring systems has improved operational precision and reduced human error. These advancements also enable predictive maintenance, enhancing machine uptime and reducing costs. Mini and heavy-duty auger machines equipped with advanced hydraulic systems are catering to a wider range of applications, from small-scale agriculture to large-scale infrastructure projects. Such innovations are boosting the operational value and market appeal of auger drilling equipment.
Key Trends & Opportunities
Shift Toward Electrified and Eco-Friendly Drilling Solutions
The market is witnessing a gradual shift toward electric-powered auger drilling machines to address environmental concerns and regulatory restrictions on diesel-powered machinery. Battery-operated and hybrid models are gaining popularity, particularly in urban construction zones with strict emission standards. This trend aligns with global sustainability goals and offers manufacturers the opportunity to differentiate through green technologies. The increasing availability of lightweight, energy-efficient augers is expected to open new opportunities, especially in noise-sensitive or emission-regulated environments.
- For instance, Sandvik’s DL422iE longhole drill rig operates with a 160 kW electric motor, drills boreholes up to 54 m in length, and achieves up to 4.4 km tramming distance on battery power using LFP chemistry.
Growing Demand in Utility and Renewable Energy Projects
Rising investments in grid modernization, solar farm installation, and wind energy projects are creating strong demand for auger drilling in utility-scale applications. These projects require foundation installation, pole setting, and cable trenching-processes well-suited for truck-mounted and heavy-duty auger rigs. With the global shift toward renewable energy infrastructure, auger drilling is positioned as a key enabling technology. This trend is particularly pronounced in North America and Europe, where utility upgrades and clean energy adoption are top priorities.
- For instance, the hybrid‑powered JCM180S anchor drilling rig by JCD features a 132 kW diesel engine paired with a 90 kW + 15 kW electric motor, generating maximum torque up to 13,600 Nm, enabling precise pole setting and trenching in renewable energy installations.
Key Challenges
High Initial Investment and Maintenance Costs
The substantial capital expenditure required for purchasing and maintaining auger drilling equipment poses a challenge, particularly for small and mid-sized contractors. Advanced rigs with hydraulic and electronic systems demand regular upkeep and skilled operators, increasing operational costs. Additionally, technological upgrades often involve expensive retrofits or complete replacement, discouraging adoption in cost-sensitive markets. This financial burden limits market penetration and slows down the transition to newer, more efficient drilling systems.
Operational Limitations in Hard Rock and Unstable Terrain
While auger drilling is effective for soft to medium-density soils, it faces performance limitations in hard rock formations or highly unstable ground. In such conditions, alternative methods like rotary drilling or down-the-hole (DTH) drilling are preferred. These limitations restrict the use of auger systems in certain geological zones, reducing their overall applicability. The lack of universal compatibility across soil types hinders market growth, especially in regions with diverse terrain conditions.
Shortage of Skilled Operators and Safety Concerns
A growing skills gap in operating sophisticated auger equipment presents a challenge for the industry. The need for trained professionals capable of handling advanced machines and adhering to safety protocols is increasing. Inadequate training can lead to inefficiencies, accidents, and equipment damage, affecting project timelines and contractor reputation. Safety remains a significant concern, particularly in urban and confined job sites, prompting stricter regulatory scrutiny and driving up compliance costs for operators.
Regional Analysis
North America
North America held the largest share of the global auger drilling market in 2024, accounting for approximately 42.3% of total market revenue. Valued at USD 1,003.87 million in 2024, up from USD 663.70 million in 2018, the market is projected to reach USD 1,779.35 million by 2032, growing at a CAGR of 6.9%. The growth is driven by robust infrastructure development, ongoing oil and gas exploration, and expanding utility grid installations across the United States and Canada. High adoption of truck-mounted augers and continuous investment in geotechnical projects contribute significantly to the region’s market dominance.
Europe
Europe accounted for a 17.7% share of the auger drilling market in 2024, with market size increasing from USD 290.36 million in 2018 to USD 419.65 million in 2024. The market is expected to reach USD 674.71 million by 2032, at a CAGR of 5.6%. Growth in this region is fueled by rising environmental regulations, which support the use of hollow stem augers for safe soil and groundwater investigation. Ongoing investments in urban development and renewable energy infrastructure in Germany, the UK, and France are also major contributors to market expansion across Europe.
Asia Pacific
Asia Pacific is the fastest-growing regional market, projected to expand at a CAGR of 8.0%, with its share rising to 31.0% in 2024. The market grew from USD 456.02 million in 2018 to USD 735.36 million in 2024 and is expected to reach USD 1,415.48 million by 2032. Strong demand stems from rapid industrialization, large-scale infrastructure projects, and mining operations in China, India, and Southeast Asia. Increasing government investment in public utilities and transportation projects further drives the use of advanced auger drilling machines, especially truck-mounted and heavy-duty variants.
Latin America
Latin America held a 4.8% share of the global auger drilling market in 2024, growing from USD 74.58 million in 2018 to USD 112.62 million in 2024. It is projected to reach USD 176.61 million by 2032, at a CAGR of 5.3%. The regional growth is supported by expanding agricultural activities, mining operations, and infrastructure modernization in countries such as Brazil, Chile, and Argentina. Increasing demand for portable and mini auger machines in rural and mid-scale applications is creating new opportunities for equipment manufacturers and drilling contractors in the region.
Middle East
The Middle East market was valued at USD 60.93 million in 2024, up from USD 43.59 million in 2018, and is expected to reach USD 90.94 million by 2032, growing at a CAGR of 4.6%. The region captured a 2.6% share of the global auger drilling market in 2024. Demand is driven primarily by utility installation, pipeline development, and energy exploration projects across Saudi Arabia, UAE, and Qatar. Truck-mounted and crawler-mounted rigs are increasingly being used in desert and rocky terrains, although harsh operating environments and low water tables present operational challenges.
Africa
Africa represented 1.6% of the global auger drilling market in 2024, with a market size of USD 36.88 million, up from USD 21.61 million in 2018. It is projected to reach USD 50.61 million by 2032, growing at a CAGR of 3.5%. The market growth is supported by gradual development in agriculture, water well drilling, and basic infrastructure in countries like Nigeria, South Africa, and Kenya. Handheld and portable augers dominate due to their affordability and simplicity. However, limited technological access and inconsistent project funding remain key hurdles to wider equipment deployment across the region.
Market Segmentations:
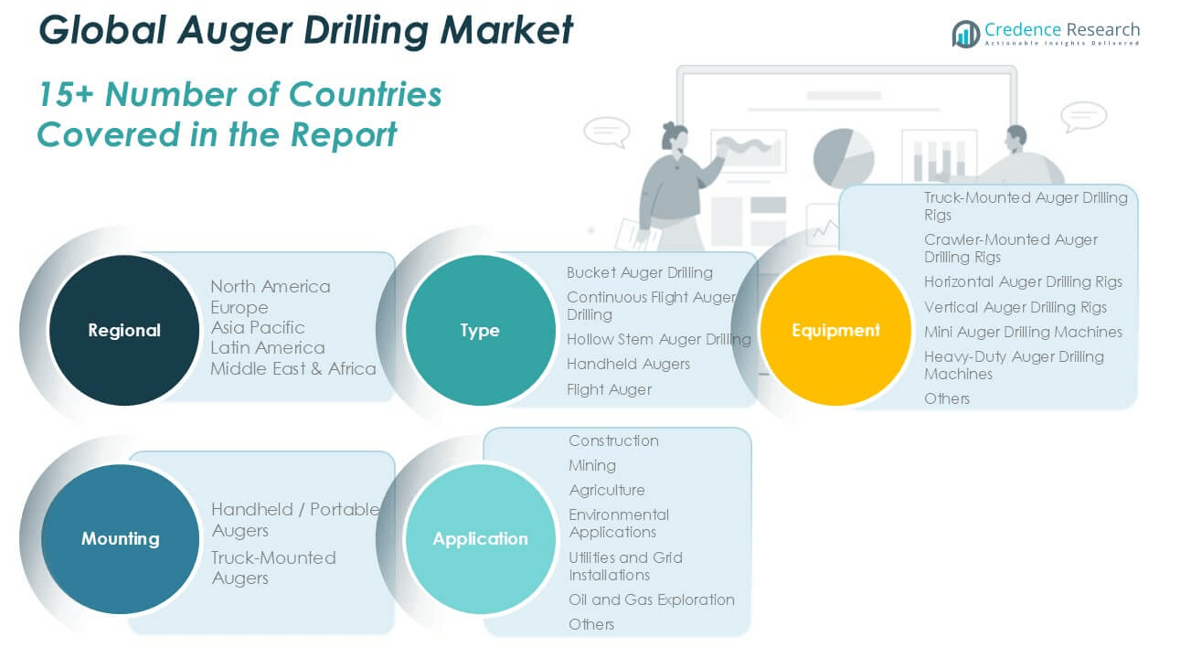
By Type
- Bucket Auger Drilling
- Continuous Flight Auger Drilling
- Hollow Stem Auger Drilling
- Handheld Augers
- Flight Auger
By Equipment
- Truck-Mounted Auger Drilling Rigs
- Crawler-Mounted Auger Drilling Rigs
- Horizontal Auger Drilling Rigs
- Vertical Auger Drilling Rigs
- Mini Auger Drilling Machines
- Heavy-Duty Auger Drilling Machines
- Others
By Mounting
- Handheld / Portable Augers
- Truck-Mounted Augers
By Application
- Construction
- Mining
- Agriculture
- Environmental Applications
- Utilities and Grid Installations
- Oil and Gas Exploration
- Others
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the auger drilling market is characterized by the presence of several global and regional players actively focusing on product innovation, strategic partnerships, and geographic expansion to strengthen their market positions. Leading companies such as Caterpillar Inc., Sandvik AB, Liebherr Group, and Hitachi Construction Machinery dominate through their extensive product portfolios, robust distribution networks, and technological expertise. These players continuously invest in R&D to develop advanced drilling rigs with enhanced efficiency, automation, and environmental compliance. Mid-sized firms like Soilmec S.p.A, Bauer Maschinen GmbH, and Junttan Oy cater to specialized applications such as foundation drilling and environmental sampling. Additionally, companies such as XCMG Group and Atlas Copco AB are expanding their presence in emerging markets, particularly in Asia Pacific and Latin America. The market also witnesses increasing competition from regional manufacturers offering cost-effective solutions tailored to local needs. This dynamic environment is driving continuous innovation and operational efficiency across the auger drilling industry.
Key Player Analysis
- Caterpillar Inc.
- Sandvik AB
- Soilmec S.p.A
- Bauer Maschinen GmbH
- Liebherr Group
- Hitachi Construction Machinery
- XCMG Group
- Atlas Copco AB
- Furukawa Rock Drill Co., Ltd.
- Junttan Oy
Recent Developments
- In May 2025, Caterpillar announced multiple updates to its Cat® Hydraulic Excavator line, which are widely used as carriers for auger drilling attachments in construction and mining. These updates focus on improved efficiency, advanced digital controls, and enhanced operator safety, aligning with industry trends toward automation and sustainability.
- In April 2025, At Bauma 2025, Hitachi Construction Machinery Europe introduced the LANDCROS Connect Fleet Management System and showcased a range of digital solutions, zero-emission machines, and autonomous excavators. These advancements aim to enhance productivity, connectivity, and sustainability in construction and drilling operations, supporting auger drilling applications indirectly through improved machine management and electrification.
- In March 2025, Hitachi announced the development of a technology to restore used hydraulic oil in construction machinery, including hydraulic excavators, which are often used in auger drilling applications. This initiative supports sustainability by enabling remanufacturing and reducing crude oil consumption. The technology combines oil purification with additive insertion, allowing hydraulic oil to be restored to company quality standards without full replacement. The first commercial use is in a medium-sized ZX135US-5B excavator, with plans to expand to more remanufactured equipment.
- In 2024, Soilmec introduced the SR-95 EVO drilling rig with smart auger control in the Asia Pacific region. This new rig is designed for Continuous Flight Auger (CFA) and piling operations, particularly in urban environments, and features advanced digital controls and real-time monitoring.
Market Concentration & Characteristics
The Auger Drilling Market exhibits a moderately concentrated structure, with a mix of global leaders and regional manufacturers competing across various segments. It is characterized by technological advancement, equipment durability, and customization based on application needs. Leading players such as Caterpillar Inc., Sandvik AB, and Liebherr Group hold significant shares due to their broad product portfolios and international reach. The market reflects strong demand for truck-mounted and continuous flight auger systems, which offer higher precision and operational efficiency. Demand concentration remains high in North America and Asia Pacific, where infrastructure and utility projects drive consistent equipment adoption. The market also features a growing emphasis on automation, safety enhancements, and eco-friendly systems, prompting innovation across product lines. Barriers to entry are moderate due to high capital investment and technical expertise requirements. Regional players gain traction by offering cost-effective and application-specific solutions. It remains competitive with steady growth opportunities across construction, mining, and environmental applications.
Report Coverage
The research report offers an in-depth analysis based on Type, Equipment, Mounting, Application and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The auger drilling market will continue to grow steadily due to increasing demand in infrastructure and utility projects.
- Advancements in automation and drilling technology will enhance operational efficiency and accuracy.
- The adoption of electric and hybrid auger machines will rise, driven by environmental regulations and emission targets.
- Continuous flight auger systems will gain more traction for deep foundation and geotechnical applications.
- Demand for truck-mounted rigs will remain strong due to their mobility and application flexibility.
- Asia Pacific will emerge as the fastest-growing region, supported by urbanization and industrial development.
- North America will maintain its leadership position due to sustained investment in construction and energy sectors.
- Portable and mini augers will see increased use in agriculture and small-scale projects.
- High equipment and maintenance costs may limit adoption among small and medium contractors.
- Strategic partnerships and localized manufacturing will shape competitive strategies for global players.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Infrastructure Development Across Emerging Economies
Rapid expansion of transportation, utilities, and commercial construction in emerging markets is fueling demand for efficient and reliable auger drilling equipment. Government investments in road networks, smart cities, and power infrastructure are driving the need for advanced drilling solutions for foundation and utility installation.
Technological Advancements in Auger Equipment
Integration of automation, GPS, telematics, and real-time monitoring systems has improved drilling precision, reduced human error, and enabled predictive maintenance. These innovations are making auger drilling more efficient, adaptable, and cost-effective for a wide range of applications.
Rising Demand for Environmental and Geotechnical Investigations
Stricter environmental regulations and the need for accurate land assessment are increasing the use of auger drilling for soil sampling and groundwater monitoring. Hollow stem and continuous flight augers are preferred for their minimal environmental disturbance and precision in sensitive projects.
Growth in Utility and Renewable Energy Projects
Modernization of utility grids and the expansion of renewable energy infrastructure, such as solar and wind farms, require extensive foundation and pole installation. Auger drilling is well-suited for these applications, supporting the market's growth in both developed and developing regions.
Shift Toward Electrified and Eco-Friendly Drilling Solutions
Environmental regulations and emission targets are driving the adoption of electric and hybrid auger drilling machines, especially in urban and emission-sensitive areas. This trend is opening new market opportunities and encouraging manufacturers to innovate with greener technologies.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Auger Drilling Market?
What are the key segments within the Auger Drilling Market?
What are some challenges faced by the Auger Drilling Market?
Who are the major players in the Auger Drilling Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Bucket Auger Drilling
- 1.2.2 Continuous Flight Auger Drilling
- 1.2.3 Hollow Stem Auger Drilling
- 1.2.4 Handheld Augers
- 1.2.5 Flight Auger
- 1.3 By Mounting
- 1.3.1 Handheld / Portable Augers
- 1.3.2 Truck-Mounted Augers
- 1.4 By Equipment
- 1.4.1 Truck-Mounted Auger Drilling Rigs
- 1.4.2 Crawler-Mounted Auger Drilling Rigs
- 1.4.3 Horizontal Auger Drilling Rigs
- 1.4.4 Vertical Auger Drilling Rigs
- 1.4.5 Mini Auger Drilling Machines
- 1.4.6 Heavy-Duty Auger Drilling Machines
- 1.5 By Application
- 1.5.1 Construction
- 1.5.2 Mining
- 1.5.3 Agriculture
- 1.5.4 Environmental Applications
- 1.5.5 Utilities and Grid Installations
- 1.5.6 Oil and Gas Exploration
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 2,369.30 million → 2032: USD 4,187.70 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Auger Drilling Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Auger Drilling Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Auger Drilling Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Auger Drilling Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Auger Drilling Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Auger Drilling Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Auger Drilling Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Auger Drilling Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 2,369.30 million → 2032: USD 4,187.70 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Auger Drilling Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Bucket Auger Drilling
- 12.3.7.2 Continuous Flight Auger Drilling
- 12.3.7.3 Hollow Stem Auger Drilling
- 12.3.7.4 Handheld Augers
- 12.3.7.5 Flight Auger
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Mounting - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Handheld / Portable Augers
- 12.4.7.2 Truck-Mounted Augers
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Equipment - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Truck-Mounted Auger Drilling Rigs
- 12.5.7.2 Crawler-Mounted Auger Drilling Rigs
- 12.5.7.3 Horizontal Auger Drilling Rigs
- 12.5.7.4 Vertical Auger Drilling Rigs
- 12.5.7.5 Mini Auger Drilling Machines
- 12.5.7.6 Heavy-Duty Auger Drilling Machines
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Application - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Construction
- 12.6.7.2 Mining
- 12.6.7.3 Agriculture
- 12.6.7.4 Environmental Applications
- 12.6.7.5 Utilities and Grid Installations
- 12.6.7.6 Oil and Gas Exploration
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Auger Drilling End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Auger Drilling Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Auger Drilling Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Auger Drilling Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Caterpillar Inc.
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Sandvik AB
- 18.4 Liebherr Group
- 18.5 Hitachi Construction Machinery
- 18.6 Soilmec S.p.A
- 18.7 Bauer Maschinen GmbH
- 18.8 Atlas Copco AB
- 18.9 XCMG Group
- 18.10 Furukawa Rock Drill Co., Ltd.
- 18.11 Junttan Oy
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

