
3D TSV and 2.5D Market: USD 9.46 billion in 2025, Tied to High-Bandwidth Memory
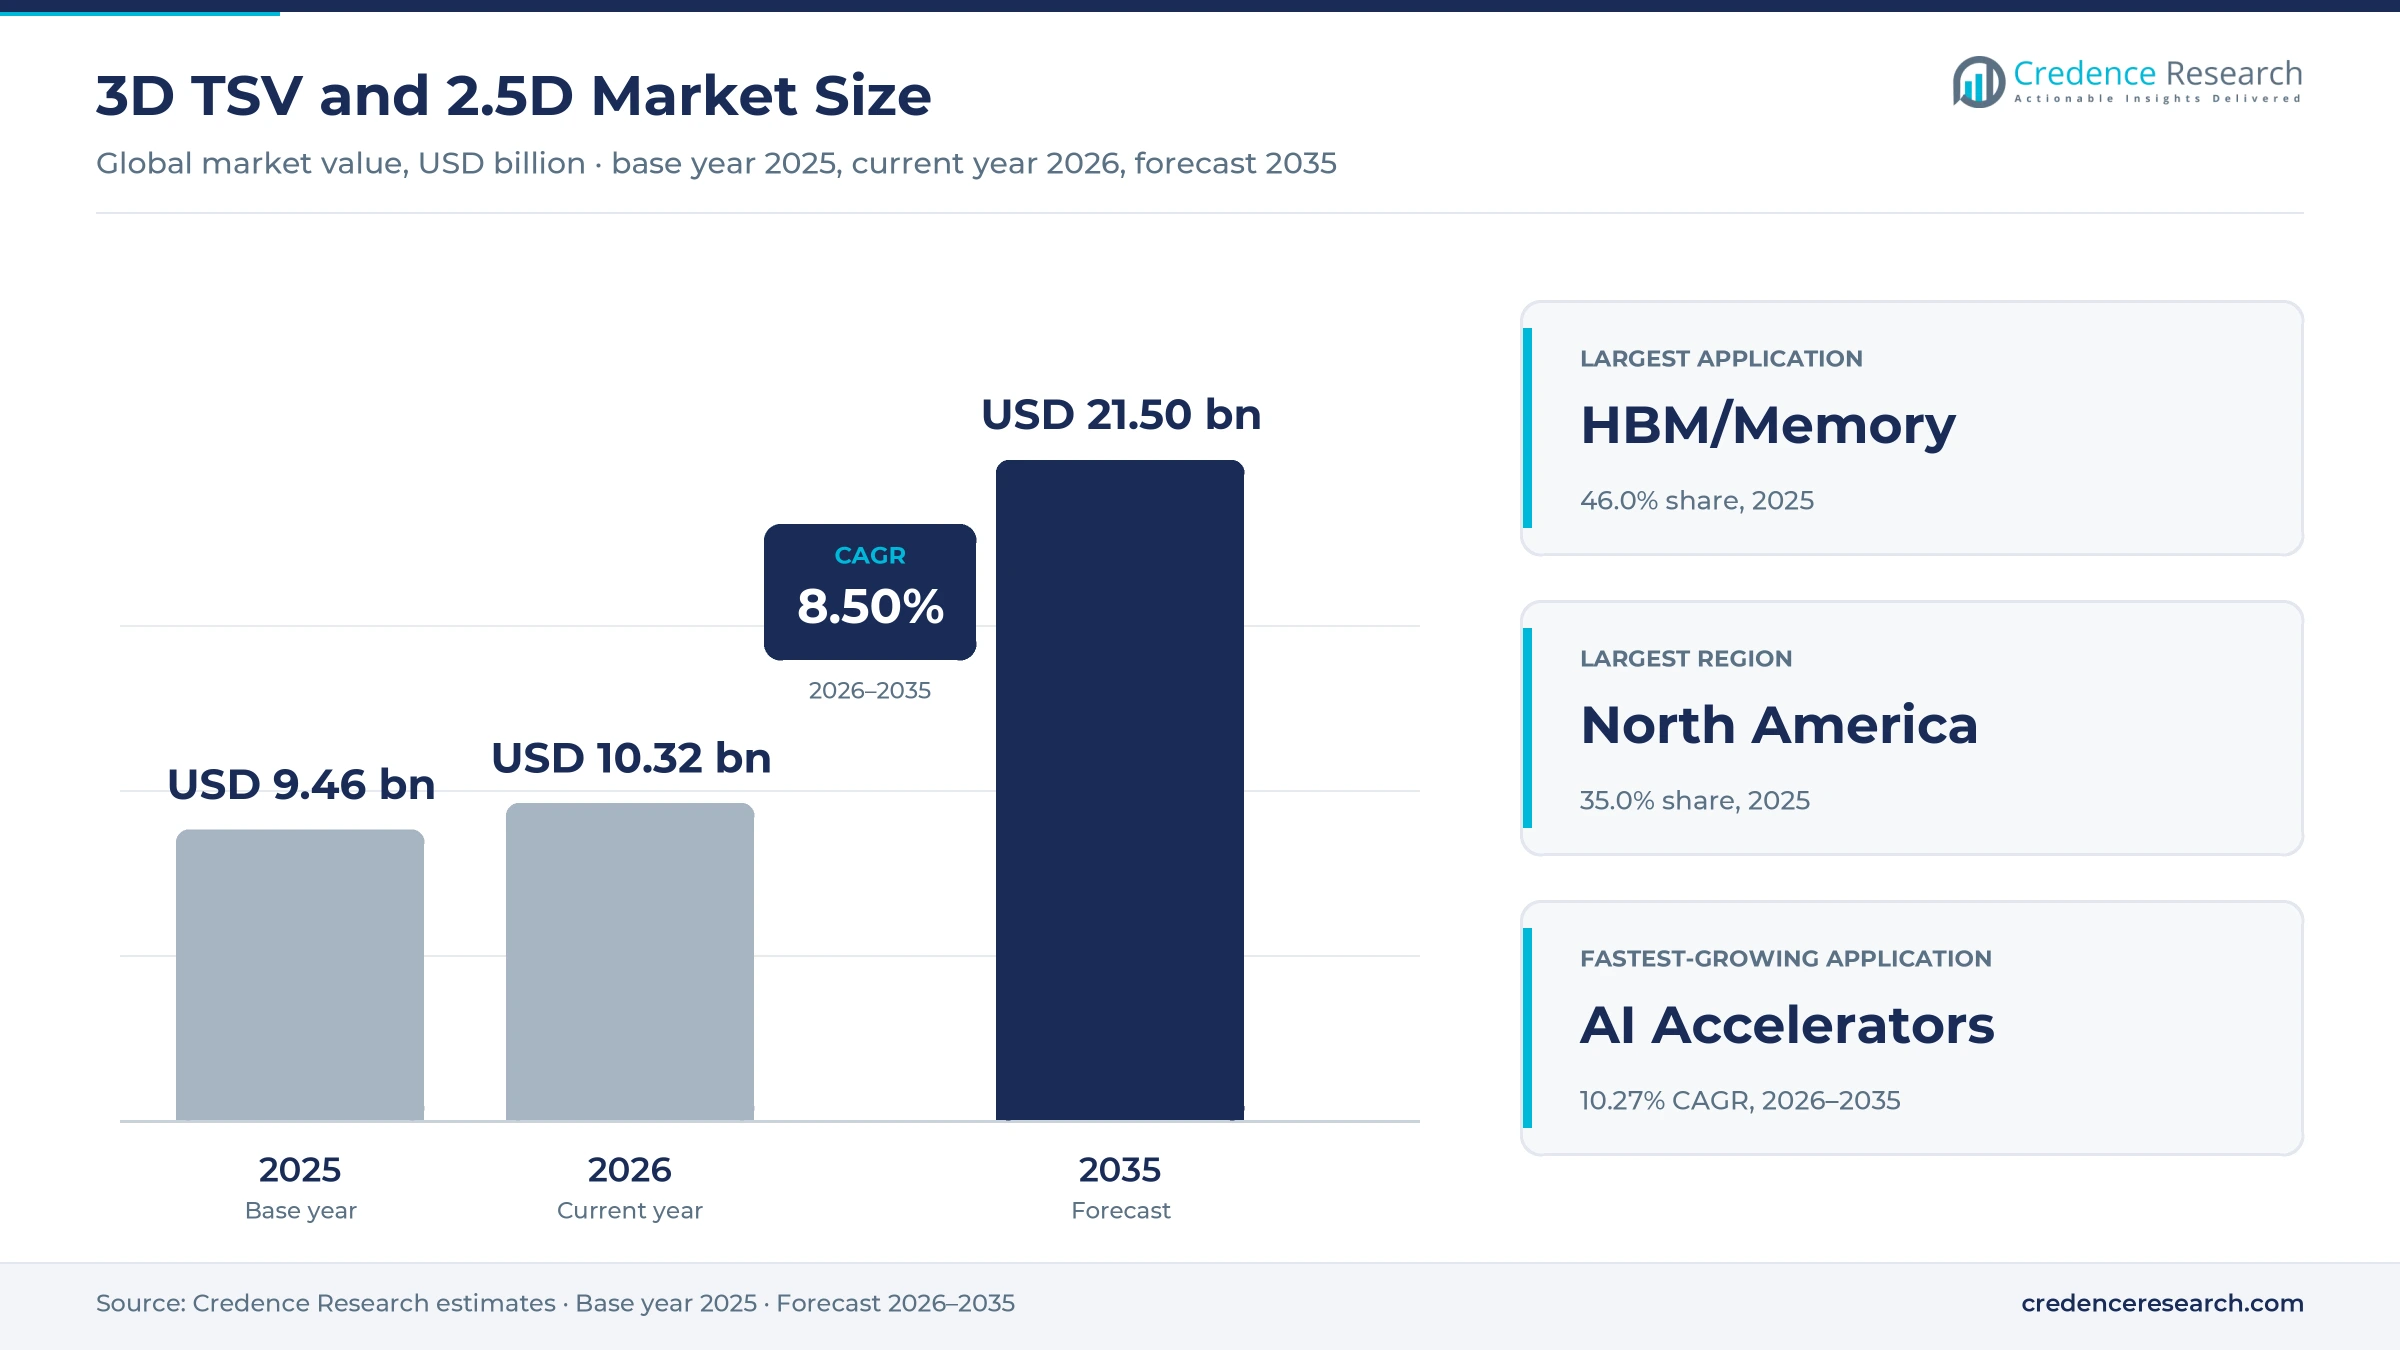
High-bandwidth memory and AI processors pushed the 3D TSV and 2.5D market to USD 9.46 billion in 2025. Credence Research forecasts USD 21.50 billion by 2035, a 8.50% CAGR over 2026–2035, and puts 2026 at USD 10.32 billion. Through-silicon vias (TSV), the vertical copper connections that run through a thinned silicon die, are what make stacked DRAM and silicon interposers possible.
Growth is strong but steadier than the wider advanced packaging market, because mature TSV uses such as image sensors grow slowly while HBM grows fast.
What does the market cover?
The market covers packaging and integration that relies on through-silicon vias or silicon interposers. The scope includes:
- 3D TSV stacks, including HBM memory, stacked logic and memory, and TSV-based image sensors, MEMS and RF devices.
- 2.5D integration on silicon interposers, including chip-on-wafer-on-substrate packages for AI accelerators.
- Die-to-wafer, wafer-to-wafer and die-to-die (chiplet) integration, by foundries, OSATs and integrated device makers.
The scope excludes bridge-based and redistribution-layer interposers that use no TSV, fan-out packages without vias, the value of the memory and logic dies, and equipment. Values are integration and packaging revenue in USD billion at current prices, allocated by the region of the buying customer. A broader view appears in the 2.5D and 3D semiconductor packaging market.
How was the estimate built?
All figures are Credence Research estimates, built from HBM and accelerator shipment trends, disclosed packaging capacity and typical TSV processing cost per wafer.
What do the indicators show?
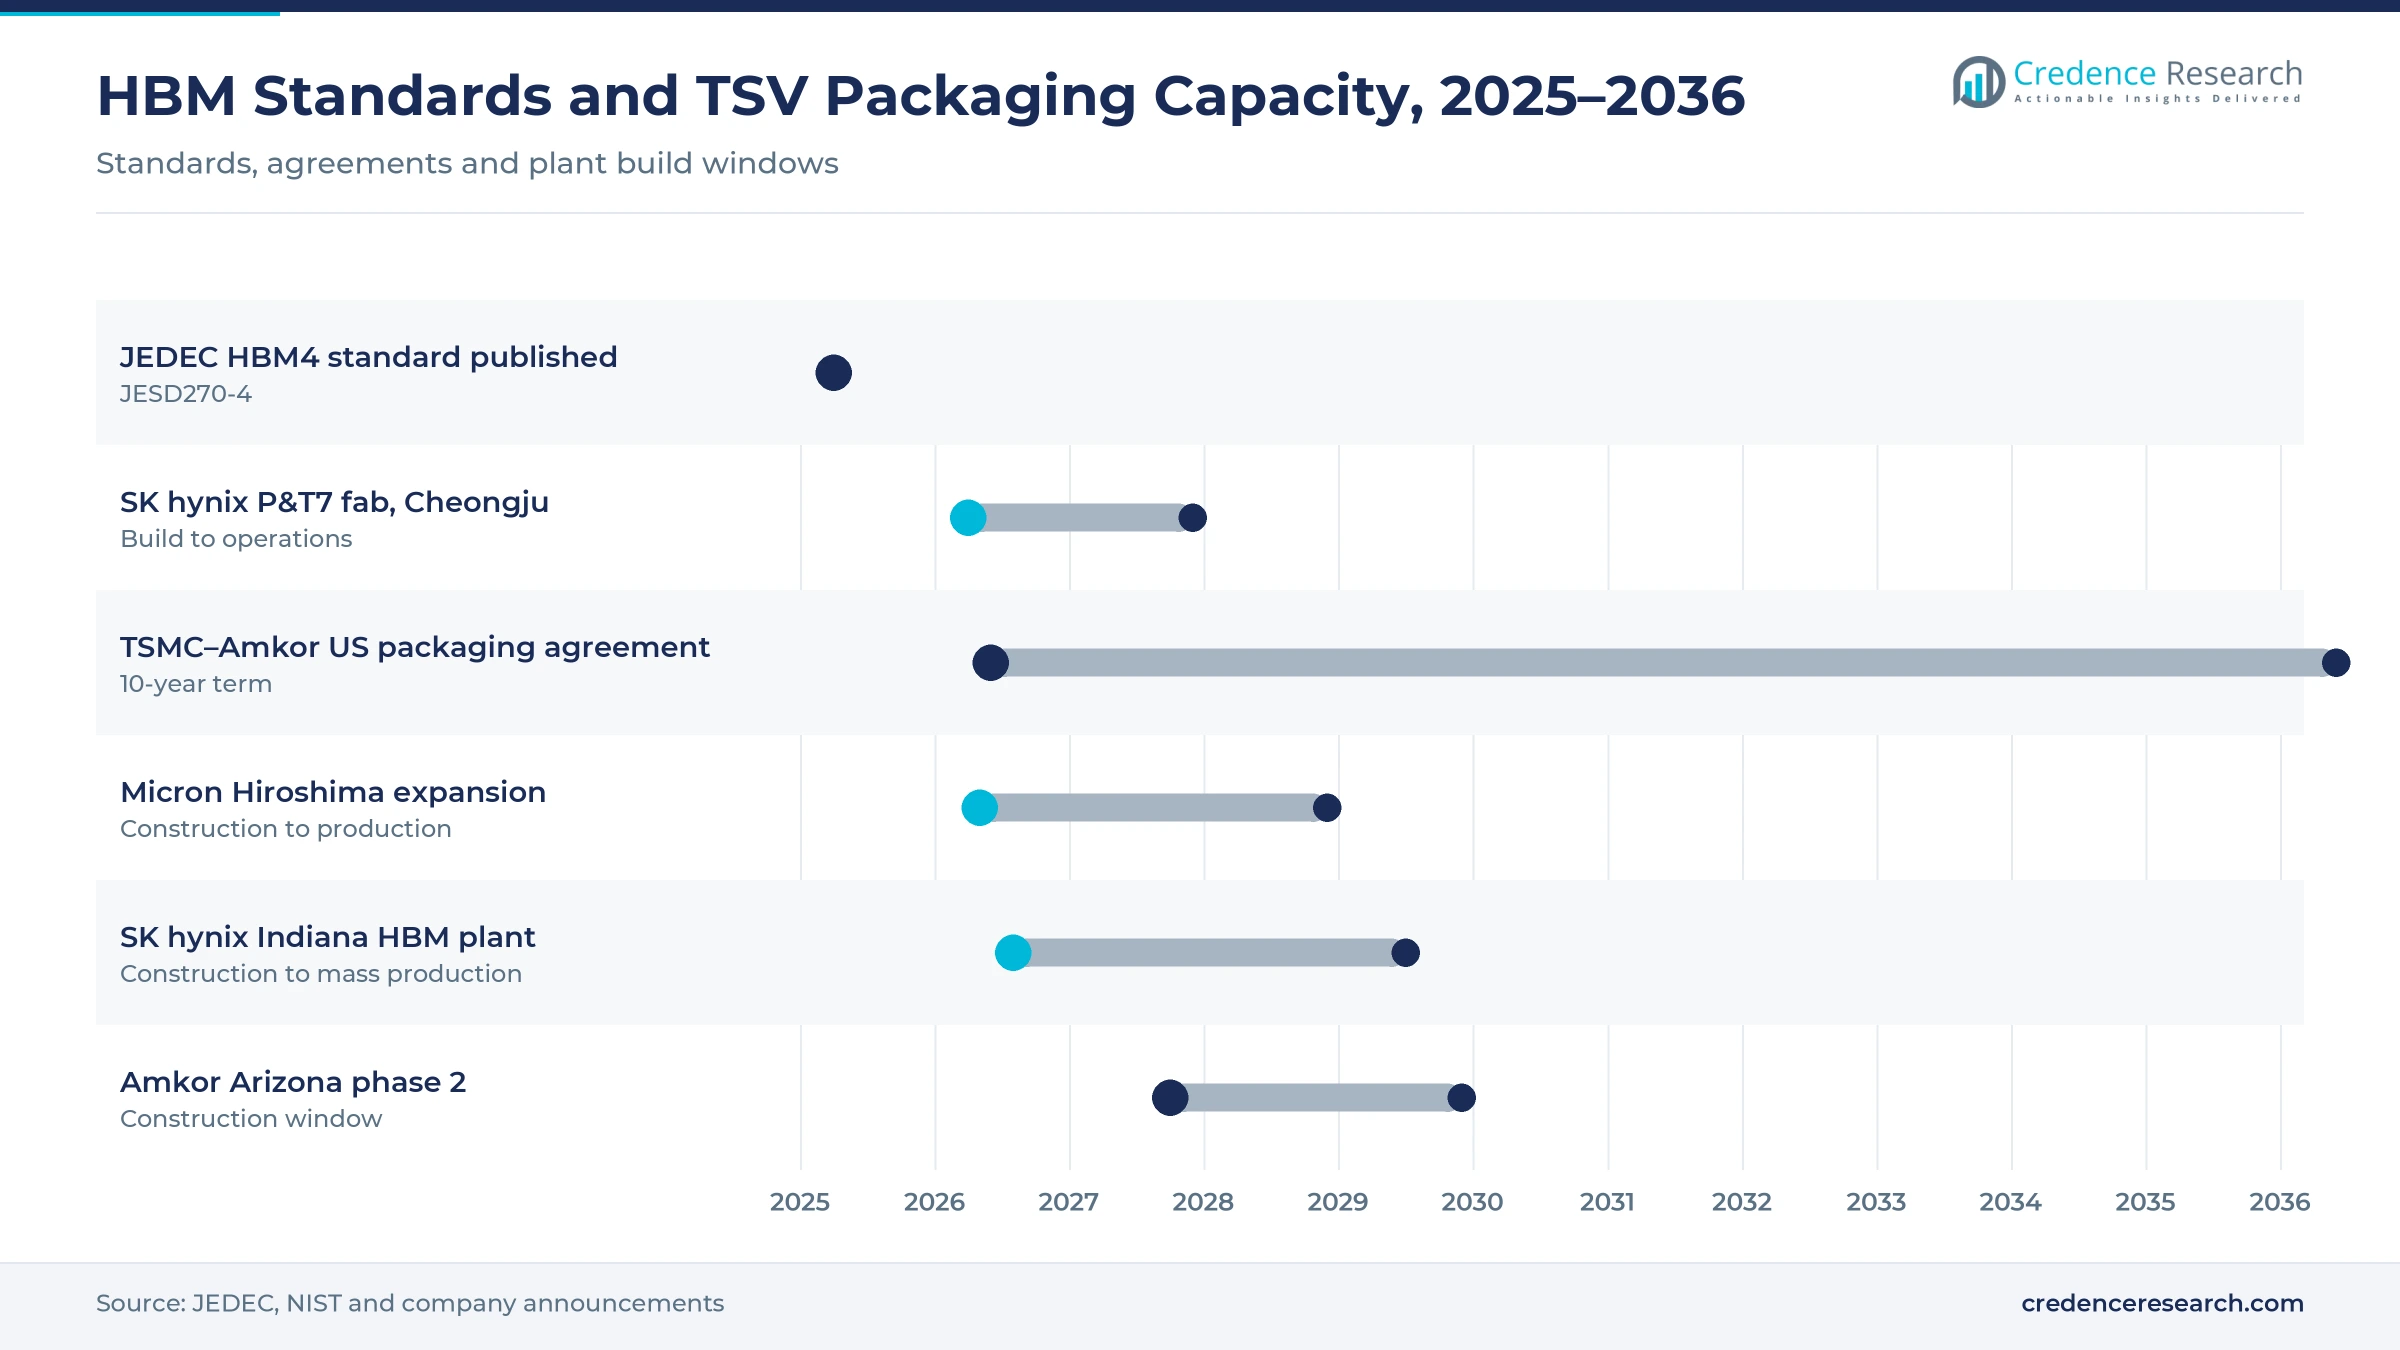
Micron's fiscal 2026 Form 10-K describes HBM as a 3D stacked DRAM architecture that uses through-silicon via connections, and reports volume production of 12-high HBM4. The JEDEC HBM4 standard, published in April 2025, allows stacks of 4 to 16 dies with up to 64 GB per stack.
Report Attributes
| Attribute | Details |
|---|---|
| Historical Period | 2018–2024 |
| Base Year | 2025 |
| Forecast Period | 2026–2035 |
| Market Size 2025 | USD 9.46 billion |
| Market Size 2026 (estimate) | USD 10.32 billion |
| Market Size 2035 (forecast) | USD 21.50 billion |
| CAGR (2026–2035) | 8.50% |
| Segments Covered | By Technology, By Application, By End Use, By Integration, By Material Type, By Provider |
| Regions Covered | North America, Europe, Asia Pacific, Latin America, Middle East & Africa |
| Companies Covered | Taiwan Semiconductor Manufacturing Co., Samsung Electronics, Intel Corporation, ASE Technology Holding, Amkor Technology, SK hynix, Micron Technology, JCET Group |
3D TSV and 2.5D Market Insights
- The 3D TSV and 2.5D market was worth USD 9.46 billion in 2025 and is forecast to reach USD 21.50 billion by 2035, a 8.50% CAGR over 2026–2035.
- Credence Research estimates the market at USD 10.32 billion in 2026, the current year.
- HBM and AI accelerators are the strongest driver, adding about 2.8 percentage points to the forecast CAGR.
- HBM and memory hold 46.0% of 2025 value; processors and AI accelerators grow fastest at 10.27% a year.
- Data centers and HPC hold 55.0% of value and grow fastest at 9.93%.
- North America is the largest region at 35.0%; the Middle East & Africa grows fastest at 9.96%.
2.5D Interposers and HBM Stacks Account for Most Value
Which technology leads?
2.5D integration leads with a 38.0% share in 2025, followed by 3D TSV stacking. Heterogeneous integration covers mixed stacks of logic, memory and other dies. Chip-on-wafer-on-substrate grows fastest at 10.05% a year.
Which application leads?
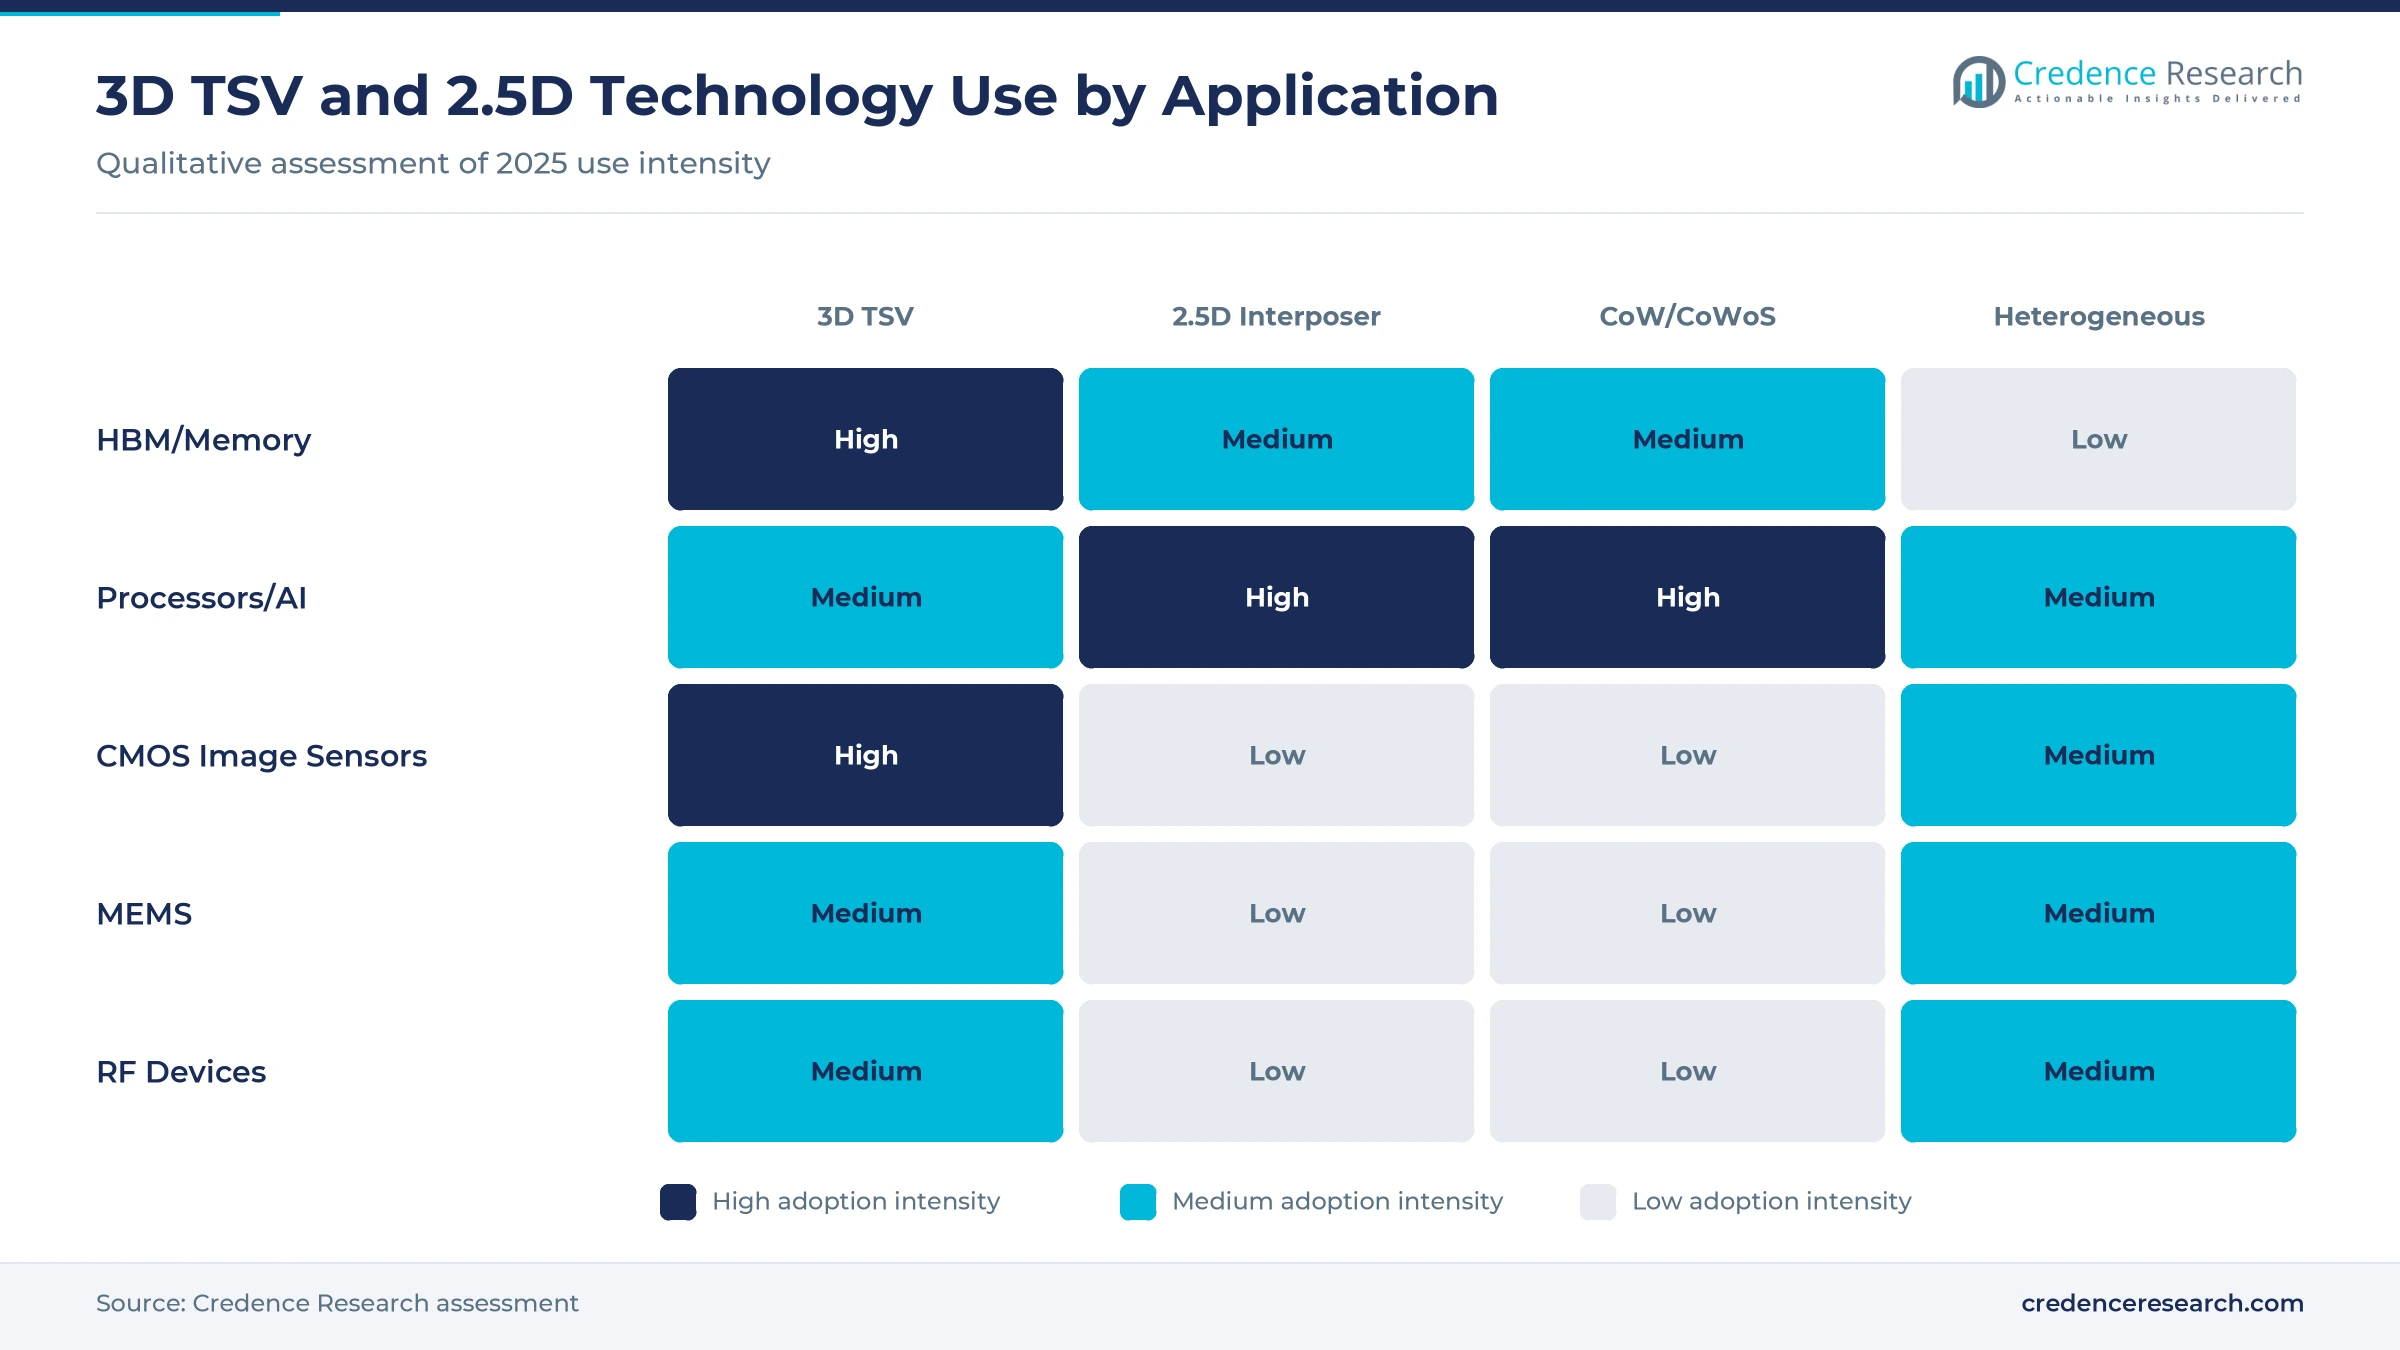
HBM and memory lead with a 46.0% share. Processors and AI accelerators grow fastest at 10.27% a year. CMOS image sensors, MEMS and RF devices are mature TSV applications that grow slowly.
Which end use leads?
Data centers and HPC lead with a 55.0% share and grow fastest at 9.93% a year. Consumer electronics, telecommunications, automotive and industrial uses follow.
Which integration method leads?
Die-to-wafer integration leads with a 48.0% share, because HBM stacks and chip-on-wafer packages place known-good dies on a wafer. Wafer-to-wafer bonding serves image sensors. Die-to-die chiplet integration grows fastest at 9.84% a year.
Which material and provider lead?
Silicon leads materials with a 45.0% share. Integrated device makers, including memory makers, lead providers with a 38.0% share; OSATs grow fastest at 9.13% a year.
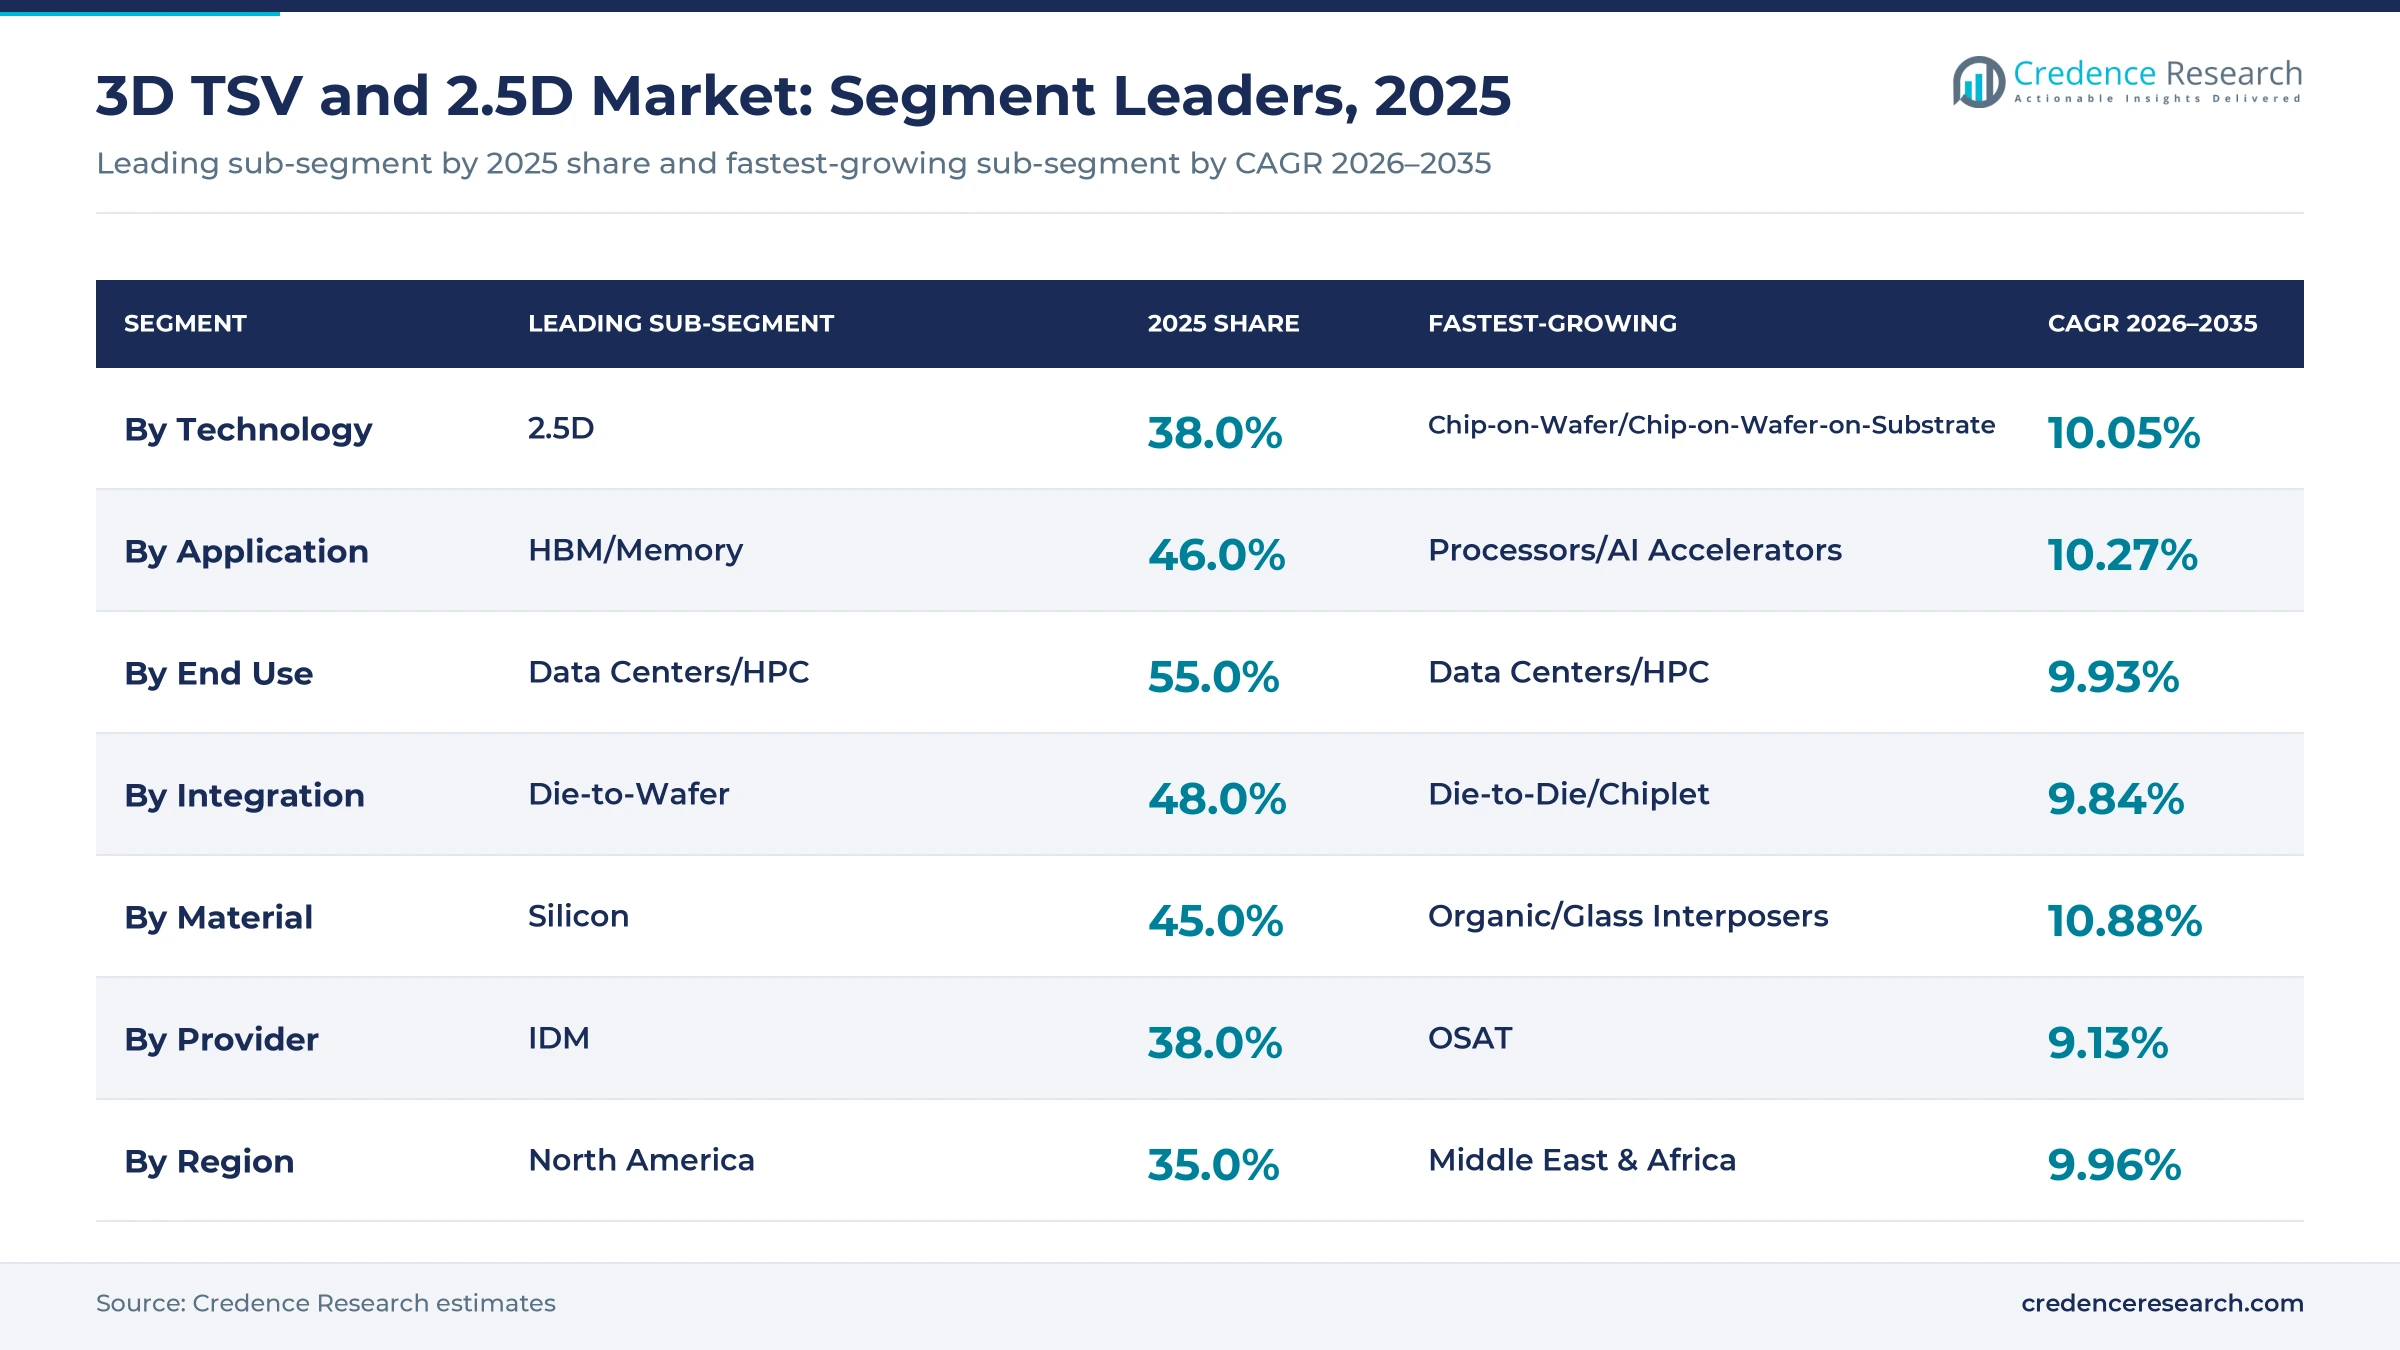
| Segment Group | Leading Sub-segment | 2025 Share | Fastest-growing Sub-segment | CAGR 2026–2035 |
|---|---|---|---|---|
| By Technology | 2.5D | 38.0% | Chip-on-Wafer/Chip-on-Wafer-on-Substrate | 10.05% |
| By Application | HBM/Memory | 46.0% | Processors/AI Accelerators | 10.27% |
| By End Use | Data Centers/HPC | 55.0% | Data Centers/HPC | 9.93% |
| By Integration | Die-to-Wafer | 48.0% | Die-to-Die/Chiplet | 9.84% |
| By Material Type | Silicon | 45.0% | Organic/Glass Interposers | 10.88% |
| By Provider | IDM | 38.0% | OSAT | 9.13% |
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
HBM Generations, Chiplets and Data-Center Integration Lift TSV Demand
Why does HBM drive the market? (~+2.8% impact on forecast CAGR)
Demand for HBM and AI accelerators, which need more vertical interconnects per package, is the strongest driver, adding an estimated 2.8 percentage points to the forecast CAGR. Each HBM stack contains 8 to 16 DRAM dies, and each die carries thousands of TSVs. Every new generation adds layers and bandwidth: Samsung began shipping 12-layer HBM4 in February 2026, and Micron says HBM uses more wafers and cleanroom space per bit than standard DRAM. The JEDEC HBM4 standard doubled the interface to 2,048 bits per stack, as HPCwire reported, which requires more TSVs per die and tighter stacking. HBM and memory lead applications with a 46.0% share of 2025 value. The limit is yield: Micron's annual report cites the need for acceptable yields on products with multiple chip layers.
How do chiplets add TSV demand? (~+2.1% impact on forecast CAGR)
Chiplet adoption and advanced heterogeneous packaging add about 2.1 percentage points to the forecast CAGR. When designers split a processor into chiplets, they need dense connections between dies, often through a silicon interposer with TSVs. Leading AI accelerators place two compute dies next to as many as eight HBM stacks on a single interposer. Die-to-die and chiplet integration grows fastest at 9.84% a year. The condition is cost: silicon interposers are expensive, and some designers choose bridges or organic interposers instead.
Which end uses add demand? (~+1.3% impact on forecast CAGR)
Data center, automotive and high-end consumer integration adds about 1.3 percentage points to the forecast CAGR. Data centers and high-performance computing lead end uses with a 55.0% share and grow fastest at 9.93% a year. Automotive radar and ADAS processors begin to use stacked memory, and premium phones use stacked image sensors.
How are governments supporting capacity?
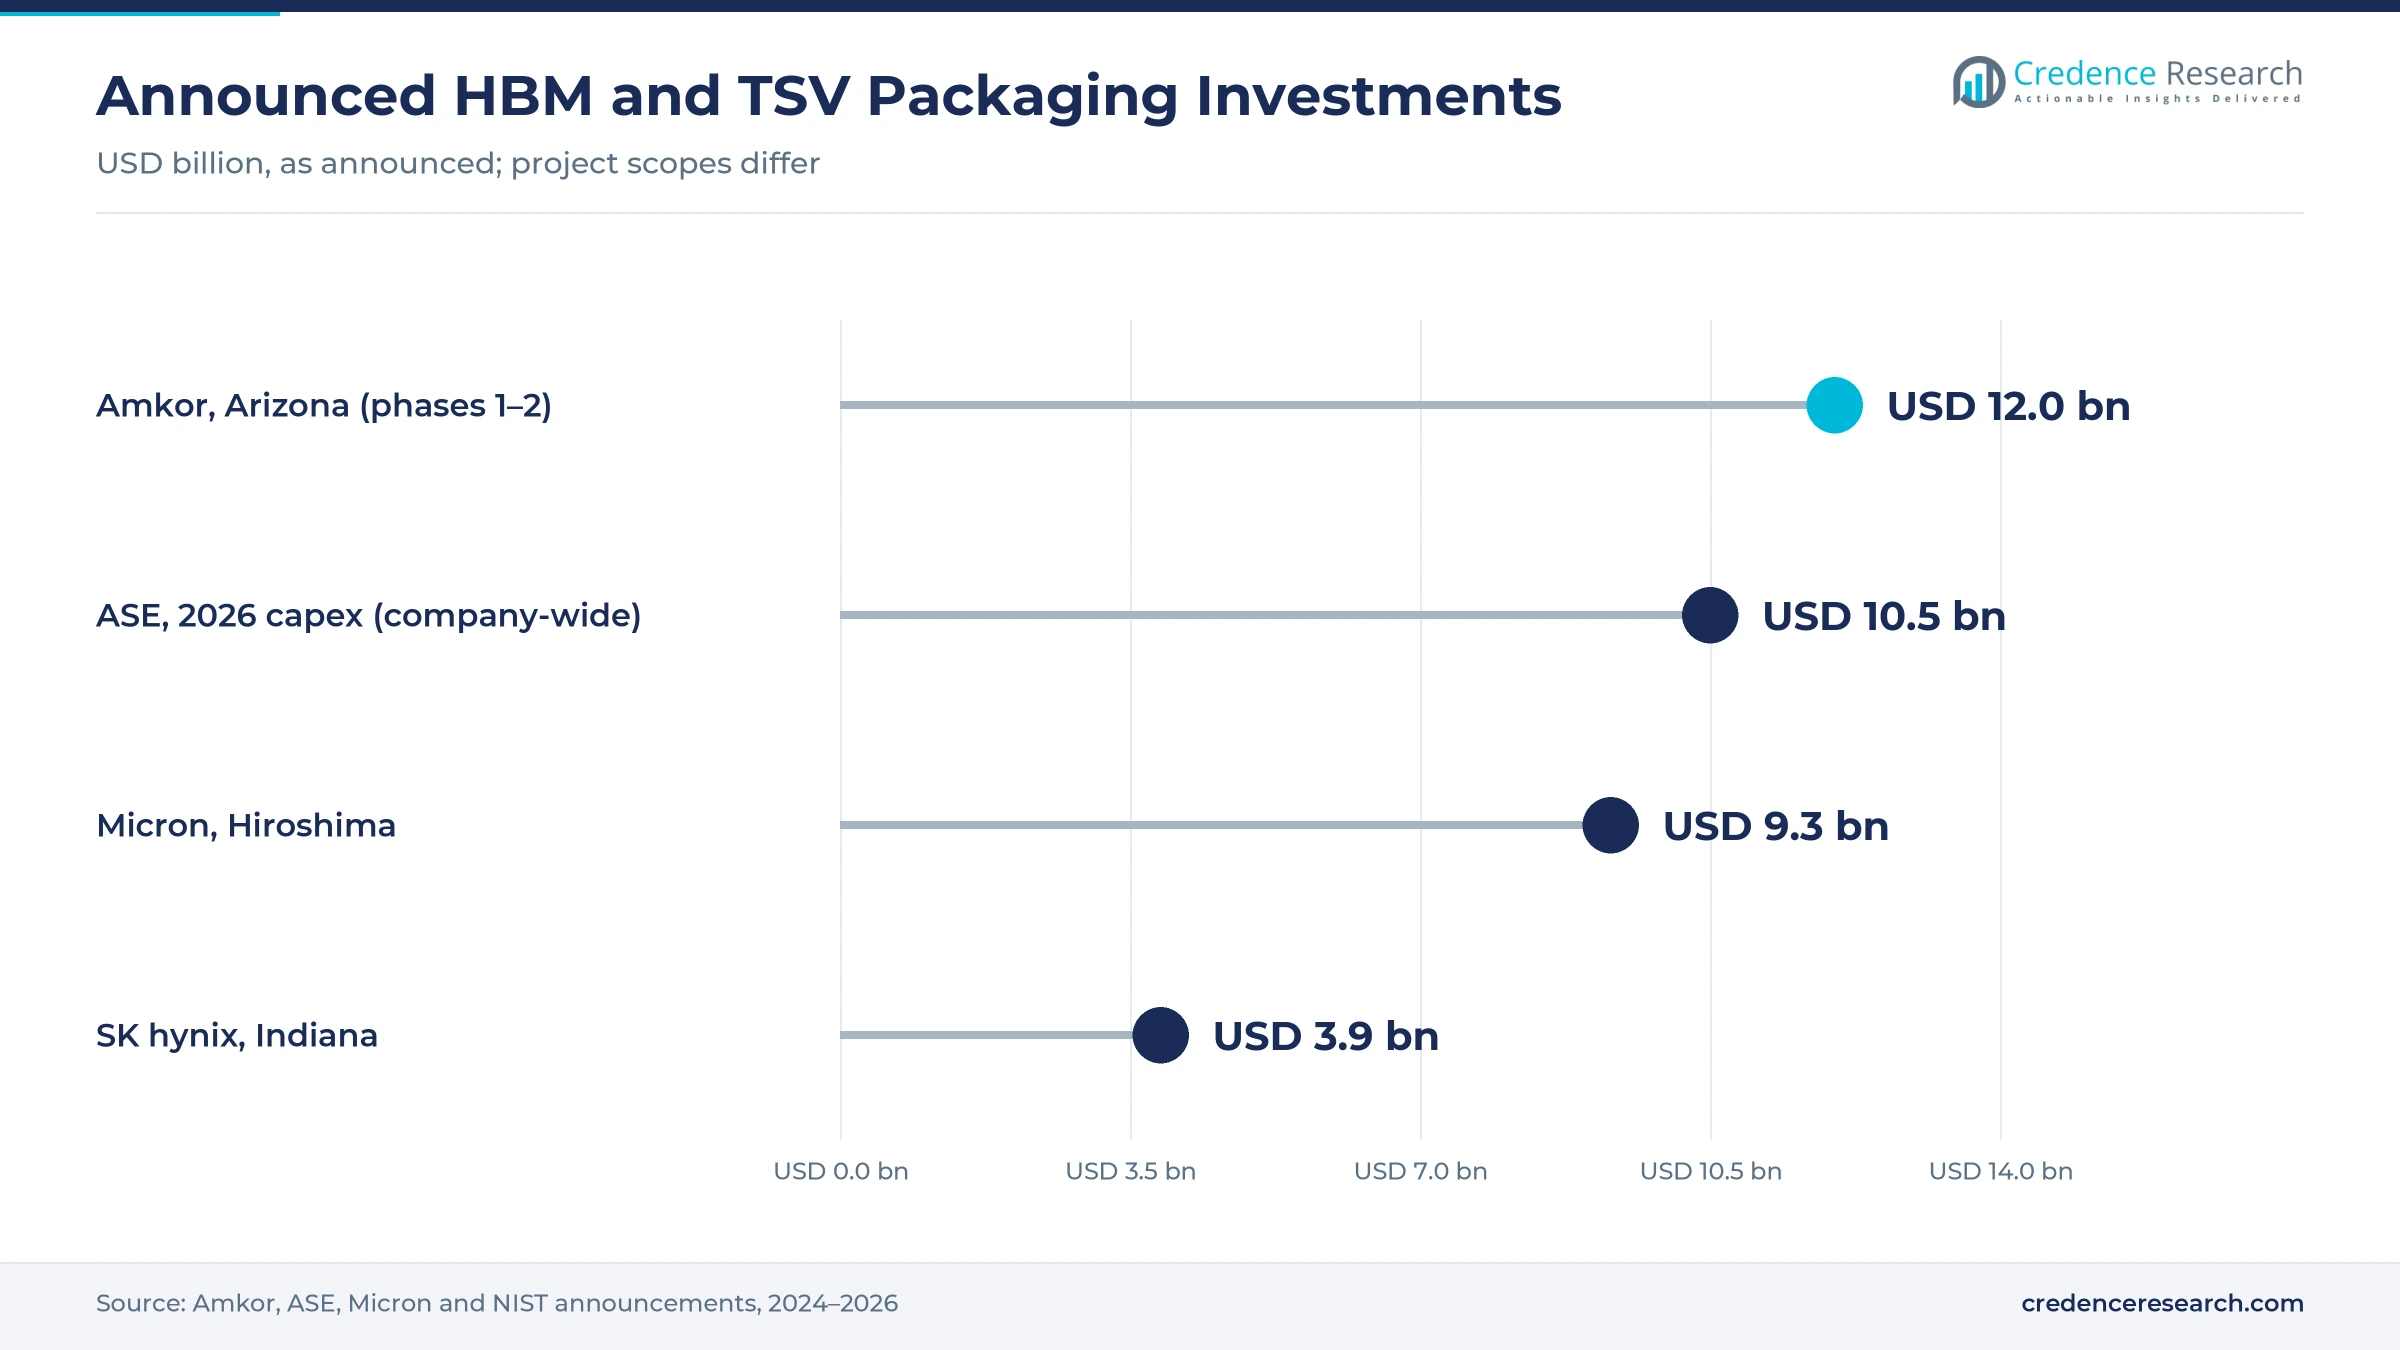
The US CHIPS program awarded up to USD 458 million to SK hynix for an HBM packaging plant in West Lafayette, Indiana, according to NIST, and USD 407 million to Amkor for its Arizona campus. Japan supports Micron's Hiroshima expansion.
Taller Stacks, Outsourced Packaging and Larger Interposers
Trend 1: Are HBM stacks getting taller?
Yes. HBM4 stacks now reach 12 and 16 layers. Micron delivered 16-high HBM4 samples and expects HBM4E volume in 2027. Taller stacks need more TSVs and thinner dies, raising process value per stack.
Trend 2: Are foundries outsourcing more?
Yes. TSMC and Amkor signed a 10-year agreement in June 2026 for TSMC to buy advanced packaging and test services from Amkor in the United States. OSATs are the fastest-growing provider type at 9.13% a year. Amkor announced a second phase of its Arizona campus in September 2026, bringing planned investment to about USD 12 billion, as stated in its investor release.
Trend 3: Are interposers getting bigger?
Yes. AI accelerators place more HBM stacks around larger logic dies, so interposers grow toward several times the size of a reticle. Chip-on-wafer-on-substrate packaging grows fastest by technology at 10.05% a year.
Trend 4: Are new materials entering?
Organic and glass interposers grow fastest by material at 10.88% a year, as designers look for cheaper alternatives to large silicon interposers.
Yield, Cost and Long Build Times Limit How Fast Supply Can Grow
Why are yields a constraint?
A TSV stack fails if any die or bond fails, so yield falls as layers increase. Memory makers have kept thermo-compression bonding for HBM4 while hybrid bonding matures, which caps stack height and pitch improvements.
Why are costs high?
Etching, lining and filling vias, then thinning and bonding wafers, add many process steps. Silicon interposers are made in front-end fabs, which makes them expensive for large designs. High costs keep TSV out of most mid-range products.
How long does new capacity take?
New HBM and packaging plants take two to four years. SK hynix's Indiana plant is expected to reach mass production in 2028 or 2029, depending on the source. Customers face allocation in the meantime.
Is demand concentrated?
Yes. A small number of AI accelerator makers and cloud providers buy most HBM and large interposers. A slowdown in AI spending would quickly reduce demand for TSV capacity.
Where are the opportunities?
Automotive and edge-AI chipmakers want stacked memory but need smaller, cheaper stacks. Suppliers that offer lower-layer HBM and smaller interposers qualified for automotive use can open a new customer base. The execution risk is long automotive qualification cycles.
North America Buys the Most, While Asia Pacific Builds and Grows
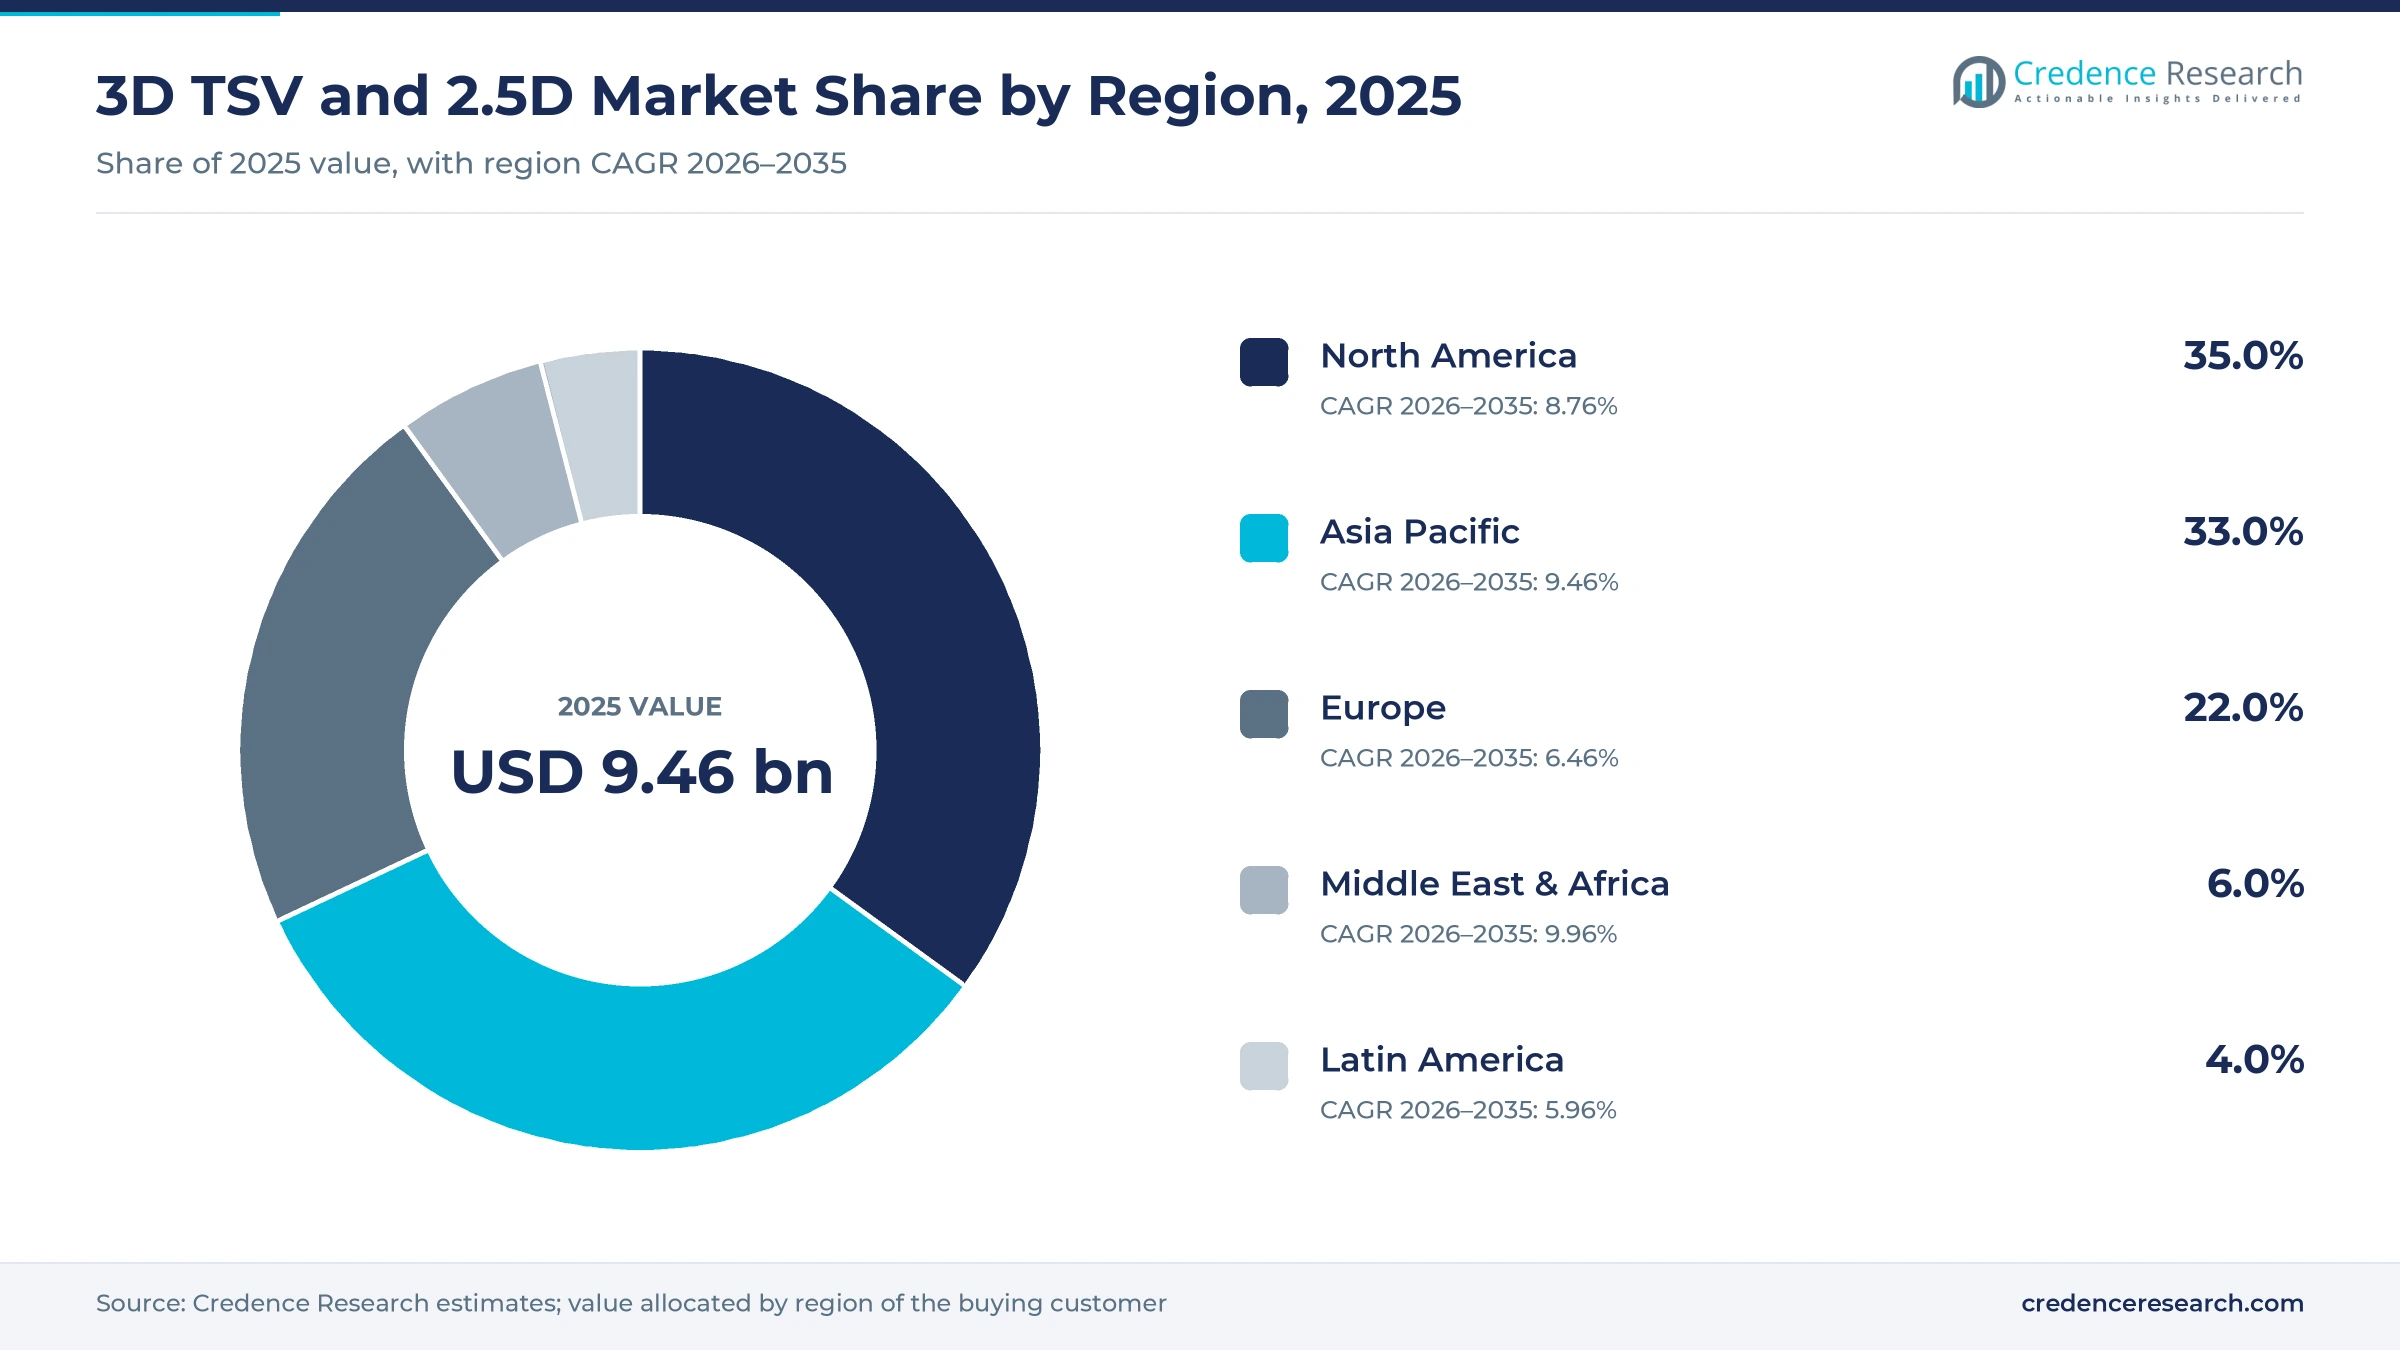
Value is allocated by the region of the customer that buys the stacked or interposer-based device.
| Region | Share 2025 | CAGR 2026–2035 |
|---|---|---|
| North America | 35.0% | 8.76% |
| Asia Pacific | 33.0% | 9.46% |
| Europe | 22.0% | 6.46% |
| Middle East & Africa | 6.0% | 9.96% |
| Latin America | 4.0% | 5.96% |
Why does North America lead?
North America holds a 35.0% share in 2025 and grows at 8.76% a year. US chip designers and cloud providers buy most AI accelerators and the HBM that goes with them. Domestic capacity is growing through Amkor in Arizona and SK hynix in Indiana.
What shapes Asia Pacific?
Asia Pacific holds 33.0% and grows at 9.46% a year. Taiwan, South Korea and Japan host the foundries and memory makers that make TSV stacks, and Chinese chipmakers buy them for domestic AI systems.
What about Europe?
Europe holds 22.0% and grows at 6.46% a year. Automotive, industrial and research customers buy stacked devices, while Intel's annual report says it discontinued planned fab and assembly expansions in Germany and Poland.
What about Latin America and the Middle East & Africa?
Latin America holds 4.0% and grows at 5.96%. The Middle East & Africa region holds 6.0% and grows fastest at 9.96% a year as Gulf states build AI data centers.
HBM Ramps, Capacity Deals and Plant Projects, 2025–2026
| Development | Status and why it matters |
|---|---|
| In October 2026, Micron announced that agreements covered the vast majority of its calendar 2027 HBM supply and that its HBM4 ramp was on track. | Reported. Signals sold-out HBM capacity into 2027. |
| In September 2026, Amkor announced a second phase of its Peoria, Arizona campus, raising planned investment to about USD 12 billion. | Announced. Expands US TSV and 2.5D capacity. |
| In August 2026, SK hynix started construction of its HBM packaging plant in West Lafayette, Indiana. | Under construction. First US HBM packaging site. |
| In July 2026, TSMC raised its 2026 capital budget to USD 60–64 billion, with part allocated to advanced packaging. | Announced. Funds more interposer capacity. |
| In July 2026, Micron broke ground on its Hiroshima expansion, an investment of about JPY 1.5 trillion with production planned from 2028. | Under construction. Adds HBM capacity in Japan. |
| In June 2026, TSMC and Amkor signed a 10-year agreement for advanced packaging and test services in the United States. | Signed. Shifts part of foundry packaging to an OSAT. |
| In February 2026, Samsung Electronics launched mass production and shipments of 12-layer HBM4. | Launched. Adds a third HBM4 supplier. |
| In January 2026, SK hynix announced a KRW 19 trillion advanced packaging fab in Cheongju, with operations by the end of 2027. | Announced. Expands HBM packaging in Korea. |
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Memory Makers and Foundries Control TSV, With OSATs Gaining
TSV value is split between memory makers that stack DRAM, foundries that build interposers and OSATs that assemble packages. No share ranking is given because suppliers do not report TSV revenue separately.
Who makes HBM?
SK hynix, Samsung Electronics and Micron Technology are the only volume HBM suppliers. SK hynix is building a packaging fab in Cheongju and a plant in Indiana. Samsung began HBM4 shipments in February 2026. Micron said in October 2026 that agreements covered most of its 2027 HBM supply.
Who builds interposers?
Taiwan Semiconductor Manufacturing Co. (TSMC) leads 2.5D silicon-interposer packaging for AI accelerators and raised its 2026 capital budget to USD 60–64 billion, with part going to advanced packaging. Intel Corporation offers EMIB and Foveros packaging, and Samsung offers foundry interposer services. Samsung is the only supplier that both makes HBM and offers foundry packaging, which lets it bundle memory and integration for some customers.
What role do OSATs play?
ASE Technology Holding and Amkor Technology provide TSV and 2.5D assembly and test for chip designers and, increasingly, for foundries. Amkor's annual report describes advanced packages that may use TSV interconnects and silicon interposers. JCET Group offers chiplet integration in China, mainly with redistribution-layer interposers.
How do they compete?
Suppliers compete on stack height, yield, thermal performance and capacity commitments. Long-term supply agreements with AI chip customers decide who gains volume. Related products are covered in the 3D IC and 2.5D IC packaging market and the advanced packaging market.
Frequently Asked Questions
How big is the 3D TSV and 2.5D market?
What is a through-silicon via?
What drives the 3D TSV and 2.5D market?
Which application is largest?
Which region leads?
Who are the main suppliers?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Technology
- 1.2.1 2.5D
- 1.2.2 3D TSV
- 1.2.3 Chip-on-Wafer/Chip-on-Wafer-on-Substrate
- 1.2.4 Heterogeneous Integration
- 1.3 By Application
- 1.3.1 HBM/Memory
- 1.3.2 Processors/AI Accelerators
- 1.3.3 CMOS Image Sensors
- 1.3.4 MEMS
- 1.3.5 RF Devices
- 1.4 By End Use
- 1.4.1 Data Centers/HPC
- 1.4.2 Consumer Electronics
- 1.4.3 Automotive
- 1.4.4 Telecommunications
- 1.4.5 Industrial
- 1.5 By Integration
- 1.5.1 Die-to-Wafer
- 1.5.2 Wafer-to-Wafer
- 1.5.3 Die-to-Die/Chiplet
- 1.6 By Material Type
- 1.6.1 Silicon
- 1.6.2 Metal Interconnects
- 1.6.3 Dielectric
- 1.6.4 Organic/Glass Interposers
- 1.7 By Provider
- 1.7.1 IDM
- 1.7.2 Foundry
- 1.7.3 OSAT
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2025: USD 9.46 billion → 2035: USD 21.50 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Historical Period: 2018-2025
- 2.6.2 Base Year: 2025
- 2.6.3 Forecast Period: 2025-2035
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2025
- 3.3 Forecast Market Size, 2035
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global 3D TSV and 2.5D Market Trends and Developments
- 4.1 Historical Industry Development, 2018-2025
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global 3D TSV and 2.5D Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis, 2018-2025
- 5.2 Demand Forecast, 2025-2035
- 5.3 Production and Output Trend, 2018-2025
- 5.4 Production and Output Forecast, 2025-2035
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global 3D TSV and 2.5D Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends, 2018-2025
- 6.3 Pricing Outlook, 2025-2035
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global 3D TSV and 2.5D Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global 3D TSV and 2.5D Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global 3D TSV and 2.5D Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global 3D TSV and 2.5D Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global 3D TSV and 2.5D Market Outlook, 2025-2035
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2025: USD 9.46 billion → 2035: USD 21.50 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size, 2018-2025
- 11.1.4 Base-Year Market Size, 2025
- 11.2 Market Forecast, 2025-2035
- 11.2.1 Revenue Forecast to 2035
- 11.2.2 Volume Forecast to 2035
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global 3D TSV and 2.5D Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2025
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Technology - Market Size and Forecast, 2025-2035
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size, 2018-2025
- 12.3.3 Revenue Forecast, 2025-2035
- 12.3.4 Volume Forecast, 2025-2035
- 12.3.5 Base-Year Market Share, 2025
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 2.5D
- 12.3.7.2 3D TSV
- 12.3.7.3 Chip-on-Wafer/Chip-on-Wafer-on-Substrate
- 12.3.7.4 Heterogeneous Integration
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2025-2035
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size, 2018-2025
- 12.4.3 Revenue Forecast, 2025-2035
- 12.4.4 Volume Forecast, 2025-2035
- 12.4.5 Base-Year Market Share, 2025
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 HBM/Memory
- 12.4.7.2 Processors/AI Accelerators
- 12.4.7.3 CMOS Image Sensors
- 12.4.7.4 MEMS
- 12.4.7.5 RF Devices
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By End Use - Market Size and Forecast, 2025-2035
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size, 2018-2025
- 12.5.3 Revenue Forecast, 2025-2035
- 12.5.4 Volume Forecast, 2025-2035
- 12.5.5 Base-Year Market Share, 2025
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Data Centers/HPC
- 12.5.7.2 Consumer Electronics
- 12.5.7.3 Automotive
- 12.5.7.4 Telecommunications
- 12.5.7.5 Industrial
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Integration - Market Size and Forecast, 2025-2035
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size, 2018-2025
- 12.6.3 Revenue Forecast, 2025-2035
- 12.6.4 Volume Forecast, 2025-2035
- 12.6.5 Base-Year Market Share, 2025
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Die-to-Wafer
- 12.6.7.2 Wafer-to-Wafer
- 12.6.7.3 Die-to-Die/Chiplet
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 By Material Type - Market Size and Forecast, 2025-2035
- 12.7.1 Segment Definition and Scope
- 12.7.2 Historical Market Size, 2018-2025
- 12.7.3 Revenue Forecast, 2025-2035
- 12.7.4 Volume Forecast, 2025-2035
- 12.7.5 Base-Year Market Share, 2025
- 12.7.6 Segment CAGR and Growth Drivers
- 12.7.7 Subsegment Market Size and Forecast
- 12.7.7.1 Silicon
- 12.7.7.2 Metal Interconnects
- 12.7.7.3 Dielectric
- 12.7.7.4 Organic/Glass Interposers
- 12.7.8 Subsegment Pricing and Adoption Trends
- 12.7.9 Leading Suppliers and Competition
- 12.7.10 Regional Demand and Opportunities
- 12.8 By Provider - Market Size and Forecast, 2025-2035
- 12.8.1 Segment Definition and Scope
- 12.8.2 Historical Market Size, 2018-2025
- 12.8.3 Revenue Forecast, 2025-2035
- 12.8.4 Volume Forecast, 2025-2035
- 12.8.5 Base-Year Market Share, 2025
- 12.8.6 Segment CAGR and Growth Drivers
- 12.8.7 Subsegment Market Size and Forecast
- 12.8.7.1 IDM
- 12.8.7.2 Foundry
- 12.8.7.3 OSAT
- 12.8.8 Subsegment Pricing and Adoption Trends
- 12.8.9 Leading Suppliers and Competition
- 12.8.10 Regional Demand and Opportunities
- 12.9 Segment Growth Comparison
- 12.10 Segment Attractiveness and Priority Matrix
Chapter 13 Global 3D TSV and 2.5D End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global 3D TSV and 2.5D Geographic Market Outlook, 2025-2035
- 14.1 Regional Market Size and Share, 2025
- 14.2 Regional Market Forecast, 2025-2035
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global 3D TSV and 2.5D Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2025-2035
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global 3D TSV and 2.5D Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2025
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2025-2035
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Taiwan Semiconductor Manufacturing Co.
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Samsung Electronics
- 18.4 Intel Corporation
- 18.5 ASE Technology Holding
- 18.6 Amkor Technology
- 18.7 SK hynix
- 18.8 Micron Technology
- 18.9 JCET Group
- 18.10 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

