
Safeguard limits and Moomba storage put CO2 storage to work
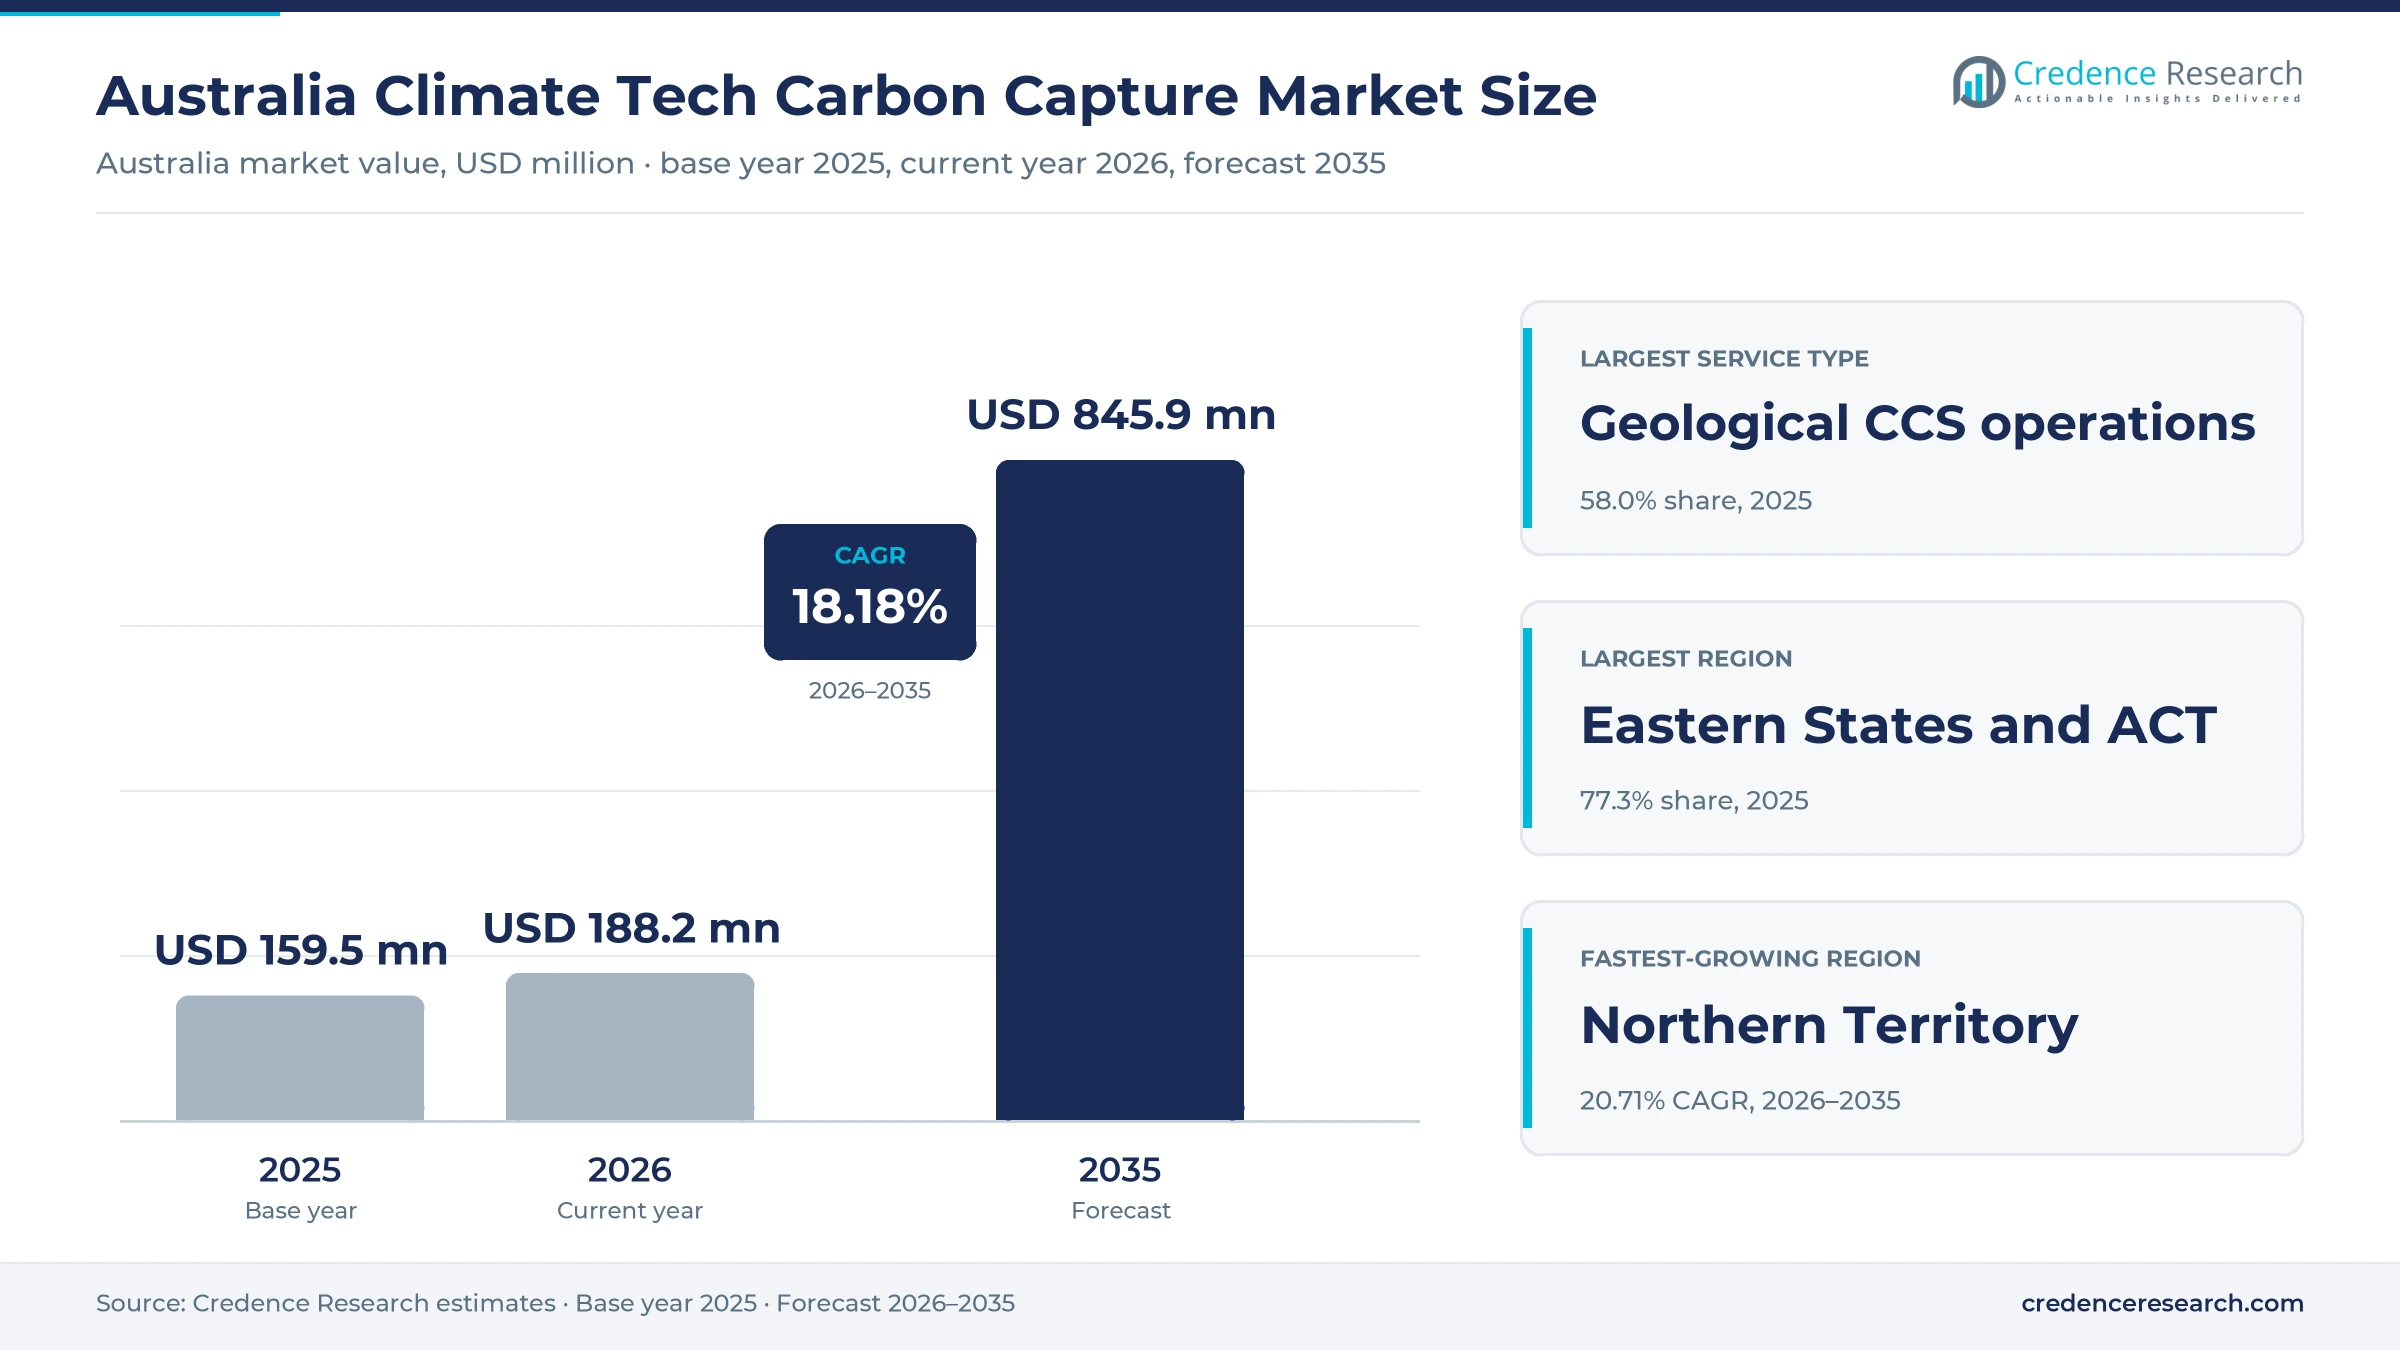
The Australia climate tech carbon capture market was valued at USD 159.5 million in 2025 and is projected to increase from USD 188.2 million in 2026 to USD 845.9 million by 2035, registering a CAGR of 18.18% during 2026–2035. Demand comes from gas processors, cement and lime makers, metals and chemicals plants, storage hub developers and public research programs that pay for CO2 separation, injection, engineering and new capture technology. Eastern States and ACT held the largest regional share, 77.3% in 2025, because the eastern seaboard hosts most of the population, manufacturing and research spending. Northern Territory is the fastest-growing region at 20.71% a year, as offshore storage sites near Darwin move toward development. Compliance rules are also tightening, because Safeguard Mechanism baselines generally decline by 4.9% each year. As a result, large emitters are turning to CO2 storage, mineral carbonation and low-cost solvents to cut emissions on site.
Which capture services, technologies and buyers does the estimate cover?
The estimate measures the value of geological CO2 storage operations, project development and engineering, capture technology sales and licensing, and research and demonstration work in Australia. Values are stated at the prices that energy operators, industrial emitters, hub developers and public research buyers pay for these services and technologies.
The estimate excludes forestry and soil carbon offsets, renewable power projects and general emissions consulting. The value chain runs from technology developers and engineering contractors through storage operators and regulators to gas processors, cement and lime plants, metals and chemicals makers and buyers of carbon removal.
Australia Climate Tech Carbon Capture Market Insights
- The Australia climate tech carbon capture market was valued at USD 159.5 million in 2025 and is projected to reach USD 845.9 million by 2035, registering a CAGR of 18.18% during 2026–2035.
- Eastern States and ACT held a 77.3% share of 2025 value, because the eastern seaboard hosts most of the population, industry and research spending.
- Geological CCS operations led with a 58.0% share of 2025 value, because the Gorgon and Moomba projects inject CO2 from gas processing into deep formations.
- The Moomba project stored about 2 million metric tons of CO2 equivalent in just over 18 months of operation, after starting up in October 2024.
- KC8 Capture Technologies raised $10 million in a round led by Woodside Energy and Cemex Ventures to scale its solvent-based capture process.
Geological operations lead as removal grows fastest
Why do geological CCS operations lead service value?
Based on service type, the market is categorized into geological CCS operations, project development and engineering, capture technology commercialisation and research and demonstration. Geological CCS Operations led with a 58.0% share of 2025 value, because large gas projects already inject CO2 at scale. Capture Technology Commercialisation grows fastest at 19.33% a year, as new solvents, calciners and mineral carbonation plants move to commercial sales.
How do integrated energy operators dominate purchases?
Based on customer type, the market is categorized into integrated energy operators, independent industrial emitters, storage hub developers and public research buyers. Integrated Energy Operators led with 62.0% of 2025 value, because gas producers run the largest storage projects. Independent Industrial Emitters grow fastest at 19.20% a year, as cement, lime and chemicals plants face falling Safeguard baselines.
Why does natural gas processing lead end use?
Based on end-use industry, the market is categorized into natural gas processing, cement and lime, metals and chemicals, and atmospheric carbon removal. Natural Gas Processing led with 72.0% of 2025 value, because reservoir CO2 is separated during gas processing and can be injected nearby. Atmospheric Carbon Removal grows fastest at 19.95% a year, as storage developers sign up direct air partners.
How do captive systems and shared hubs split delivery?
Based on delivery model, the market is categorized into captive integrated systems, shared storage hubs, distributed capture installations and demonstration facilities. Captive Integrated Systems led with 60.0% of 2025 value, because Gorgon and Moomba store CO2 from their own gas plants. Shared Storage Hubs grow fastest at 19.15% a year, as developers plan storage for third-party emitters.
| Segment Group | Leading Sub-segment | Share, 2025 | Fastest-growing Sub-segment | CAGR, 2026–2035 |
|---|---|---|---|---|
| By Service Type | Geological CCS Operations | 58.0% | Capture Technology Commercialisation | 19.33% |
| By Customer Type | Integrated Energy Operators | 62.0% | Independent Industrial Emitters | 19.20% |
| By End-Use Industry | Natural Gas Processing | 72.0% | Atmospheric Carbon Removal | 19.95% |
| By Delivery Model | Captive Integrated Systems | 60.0% | Shared Storage Hubs | 19.15% |
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Safeguard baselines and new storage sites lift spending
How does industrial compliance tightening lift spending?
Industrial compliance tightening lifts spending on CO2 storage, because large facilities must cut emissions below a falling baseline each year. Safeguard baselines generally decline by 4.9% each year, according to the Clean Energy Regulator. Covered facilities numbered 207 in 2024-25 and reported 132.7 million metric tons of CO2 equivalent, down 2.4% from the year before. The Moomba project stored about 1 million metric tons in that period, or about one-third of the total Safeguard reduction, based on the regulator's data. As a result, independent industrial emitters grow fastest among buyers at 19.20% a year, as plants without their own storage look for capture partners.
Why does operating infrastructure expansion matter?
Operating infrastructure expansion matters, because working storage sites prove that CO2 can be injected safely and at a known cost. The Moomba facility can store up to 1.7 million metric tons of CO2 a year and started up in October 2024, according to Downer, which led its construction and commissioning. The project had stored about 2 million metric tons by May 2026, and more than 1.19 million carbon credit units were awarded for injections to Sept. 30, 2025. Chevron also reports more than 11 million metric tons injected at Gorgon from August 2019 to May 2025. In turn, geological CCS operations held 58.0% of 2025 value, as operators expand geological sequestration capacity.
How does public technology demonstration funding speed adoption?
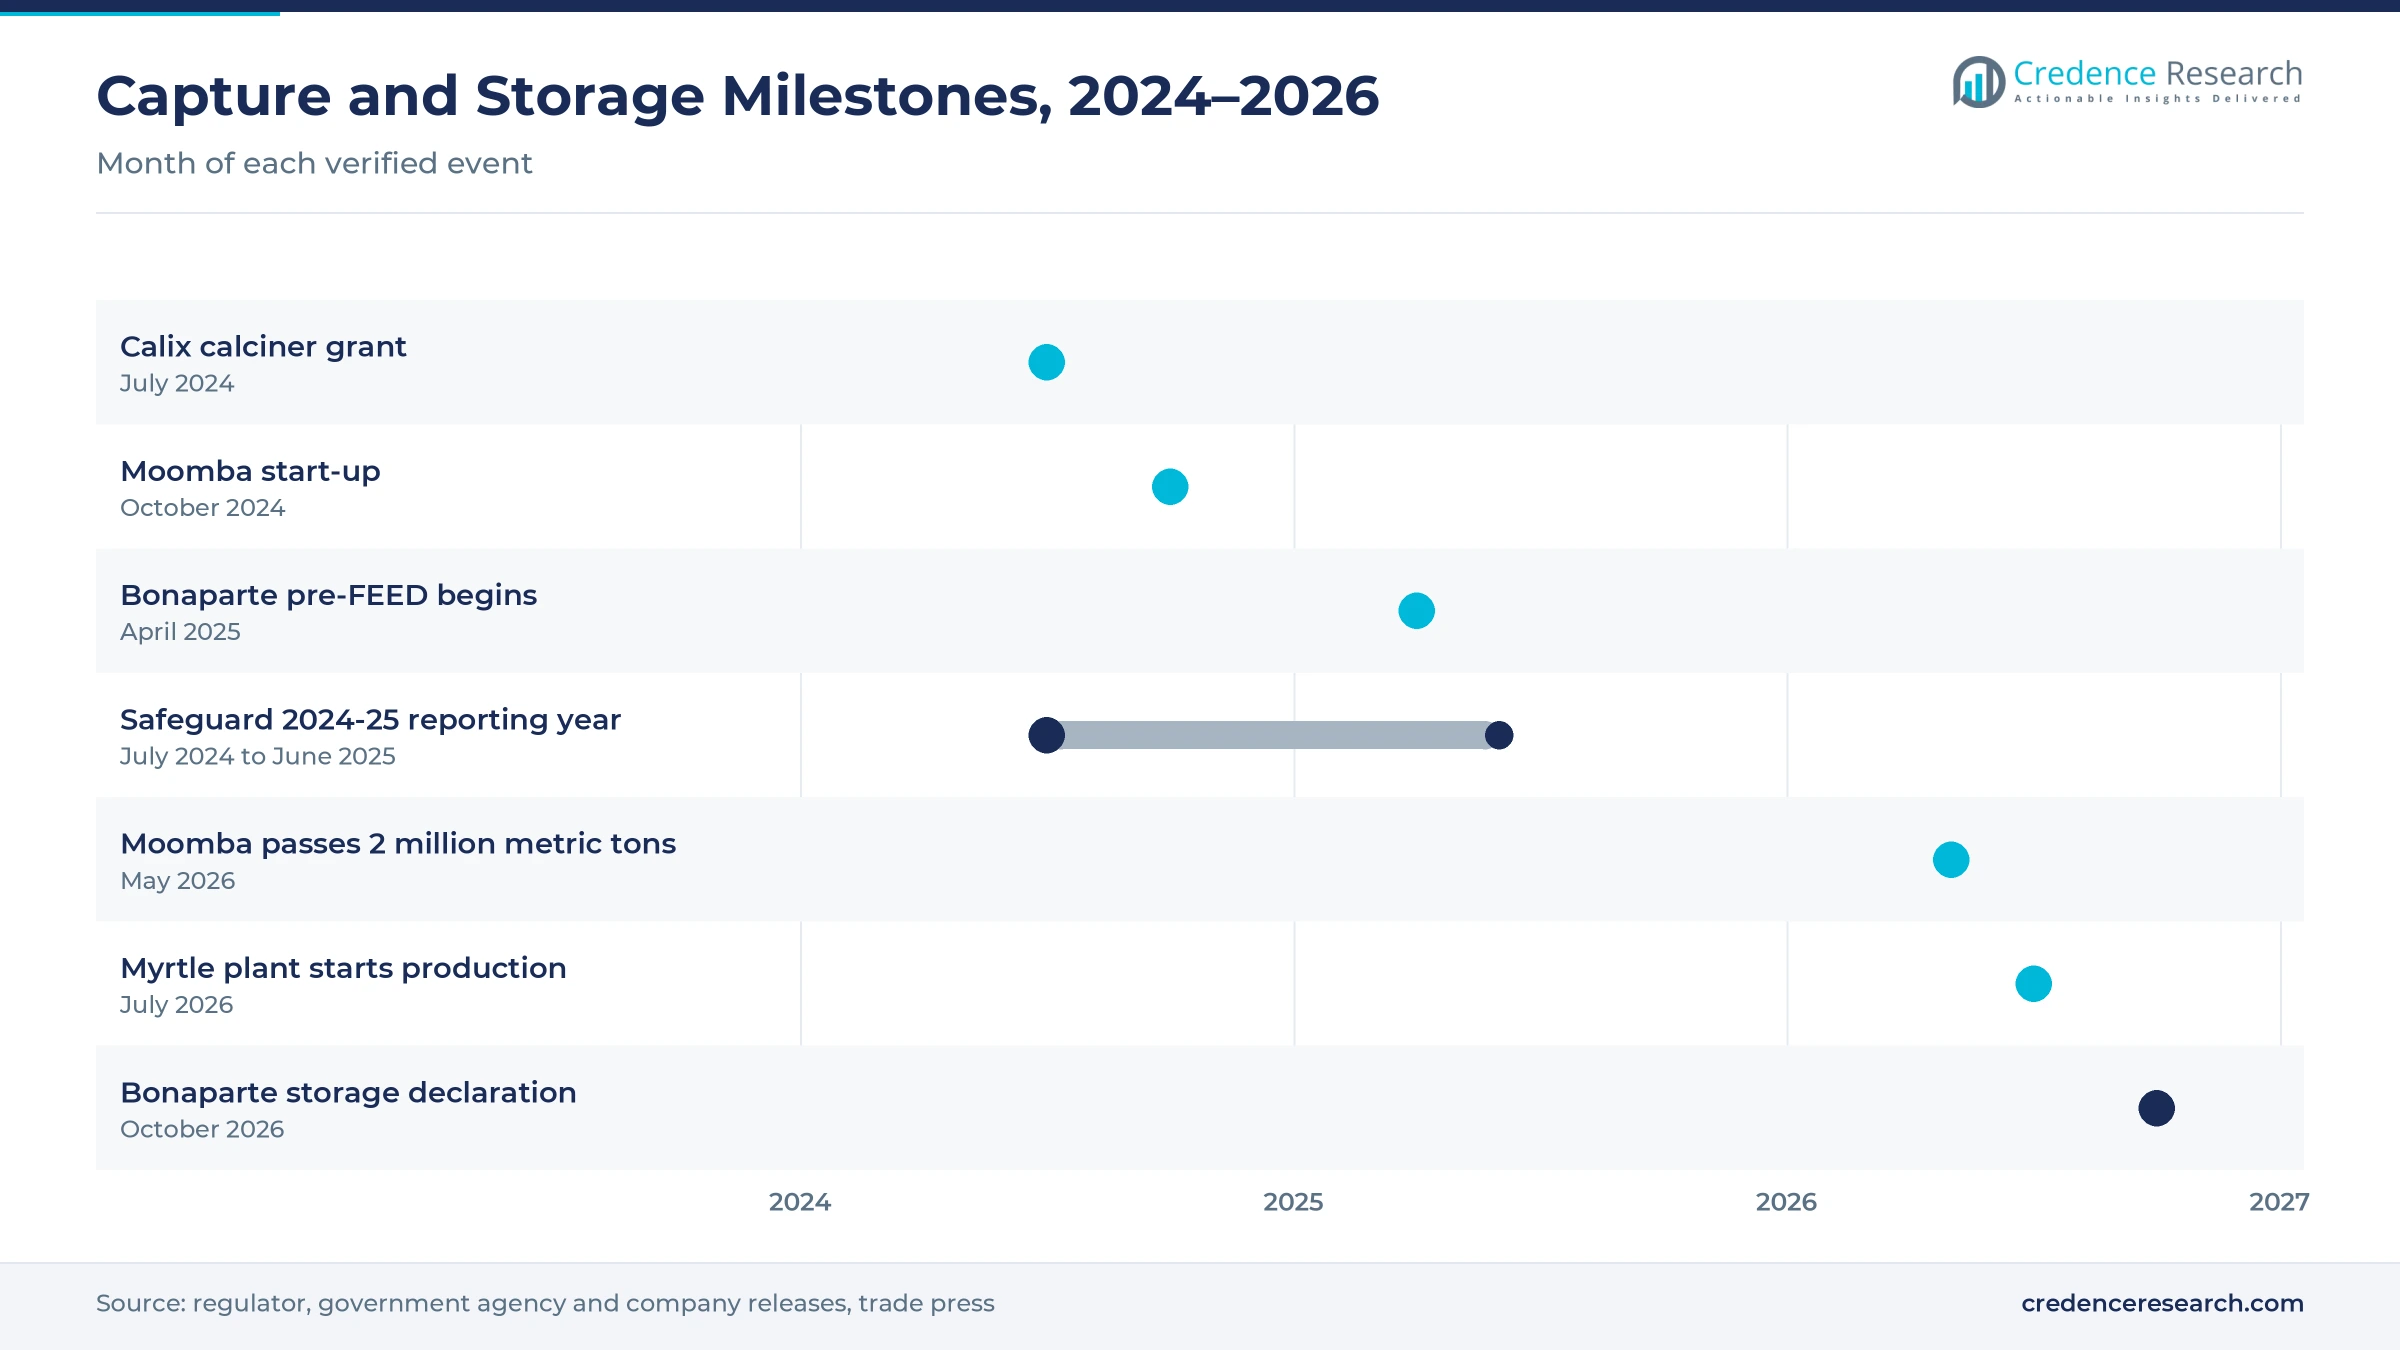
Public technology demonstration funding speeds adoption, because grants cover part of the risk of first-of-a-kind plants. Calix won a US$10 million grant from the federal Carbon Capture Technologies Program in July 2024 for an electric calciner that targets up to 20,000 metric tons of CO2 a year from lime and cement. MCi Carbon received A$14.5 million from the same program in 2024 and A$14.6 million from a separate federal CCUS fund, according to Austrade. The federal government had also committed $60 million to the Gorgon injection project through an earlier demonstration fund. As a result, capture technology commercialisation grows fastest among service types at 19.33% a year.
Why do offshore storage approvals widen the project pipeline?
Offshore storage approvals widen the project pipeline, because declared formations let developers move toward investment decisions. INPEX Browse E&P received a declaration of an identified storage formation for the Bonaparte project in October 2026, according to Oil & Gas Journal. The project, about 260 km offshore Darwin, could store up to 10 million metric tons of CO2 a year, and INPEX holds 53%, TotalEnergies 26% and Woodside 21%. Pilot Energy also secured a declaration allowing 13.4 million metric tons of storage in the Cliff Head formation off Western Australia. In turn, hub developers and engineering contractors gain a larger pipeline of offshore storage work.
Shared hubs and mineral carbonation reshape the field
How is the shift toward shared storage hubs changing projects?
The shift toward shared storage hubs is changing project design, because emitters without suitable geology can send CO2 to a hub operator. Santos is positioning Moomba to take third-party emissions from sectors such as steel and cement, and its Cooper and Eromanga acreage could inject up to 20 million metric tons a year for up to 50 years. Ichthys LNG is expected to anchor Bonaparte and could cut its emissions by about 40%. Pilot Energy also expects injection capacity above 1 million metric tons a year at its Mid West project through 2050. As a result, shared storage hubs grow at 19.15% a year, faster than captive systems.
Why is the rise of mineral carbonation notable?
The rise of mineral carbonation is notable, because it turns captured CO2 into solid products that can be sold. MCi Carbon started production at its Myrtle plant in Newcastle in 2026, and it aims to capture 2,500 metric tons of CO2 a year from ammonia production. The plant is designed to make 10,000 metric tons of carbonates and silica a year and support up to 50 jobs at peak. RHI Magnesita invested US$10 million and will run the first customer campaign at Myrtle in 2026. In turn, Calix plans to sell up to 15,000 metric tons of CO2 a year for green methanol production.
Can low-cost solvents open demand among industrial emitters?
Low-cost solvents can open demand among industrial emitters, because cheaper capture lowers the cost of meeting Safeguard baselines. KC8 Capture Technologies, founded in 2021, raised $10 million in a round led by Woodside Energy and Cemex Ventures. The company says its non-toxic solvent can capture up to 95% of CO2 at a capital cost up to 50% below amine systems. It also claims up to 15% better energy efficiency, and it targets cement, steel, power and chemicals plants. As a result, cement and lime grow fastest among industrial uses at 19.95% a year, as plants test new capture options alongside fuel and process changes.
Is there room to grow through credit generation?
Credit generation leaves room to grow, because stored CO2 can earn tradeable units that improve project returns. Moomba earned more than 1.19 million carbon credit units for injections to Sept. 30, 2025, which shows how storage can produce revenue beyond service fees. About 7 million Safeguard credit units may be eligible for issue for 2024-25 from 59 facilities below their baselines. Australia also emitted about 383.4 million metric tons of CO2 in 2024, according to World Bank data, which leaves a large base for future abatement. In turn, operators that store CO2 can sell their units into the market for compliance offset units.
Cost, permits and long-term liability slow new projects
How do high upfront costs delay new capture projects?
High upfront costs remain a key barrier, because compression, pipelines, wells and monitoring need large investment before any CO2 is stored. Smaller industrial emitters feel this risk most, since their emissions are too small to justify their own storage site. As a result, many projects wait for grants or access to a shared hub. Developers respond with shared infrastructure, staged builds and modular capture units. Lower costs per metric ton should follow as hubs scale and more emitters connect.
Why do long permit timelines slow storage development?
Long permit timelines are a major constraint, because offshore storage needs acreage awards, formation declarations and safety approvals in sequence. Developers often face several years of assessment before injection can start at a new site. In turn, capital stays tied up and investors wait longer for any return. Regulators respond with clearer guidance and major project status for leading sites. Faster approvals would bring more storage capacity online before 2035.
How does long-term liability weigh on storage operators?
Long-term liability is a lasting risk, because CO2 must stay underground for centuries after injection ends. Operators must fund monitoring and remediation plans that last well beyond the life of each project. As a result, some investors demand higher returns or clear rules on liability transfer. Governments respond with closure and transfer provisions in storage laws. Clearer liability terms should attract more private capital to new storage projects.
Why does community skepticism complicate new projects?
Community skepticism is a growing challenge, because some groups see CO2 storage as a way to extend fossil fuel production. Developers near towns and coastlines face added consultation and closer scrutiny of monitoring plans. In turn, approvals and project financing can take longer than first planned. Operators respond with public monitoring data, independent reviews and local engagement programs. Transparent performance reports should build public trust in storage over time.
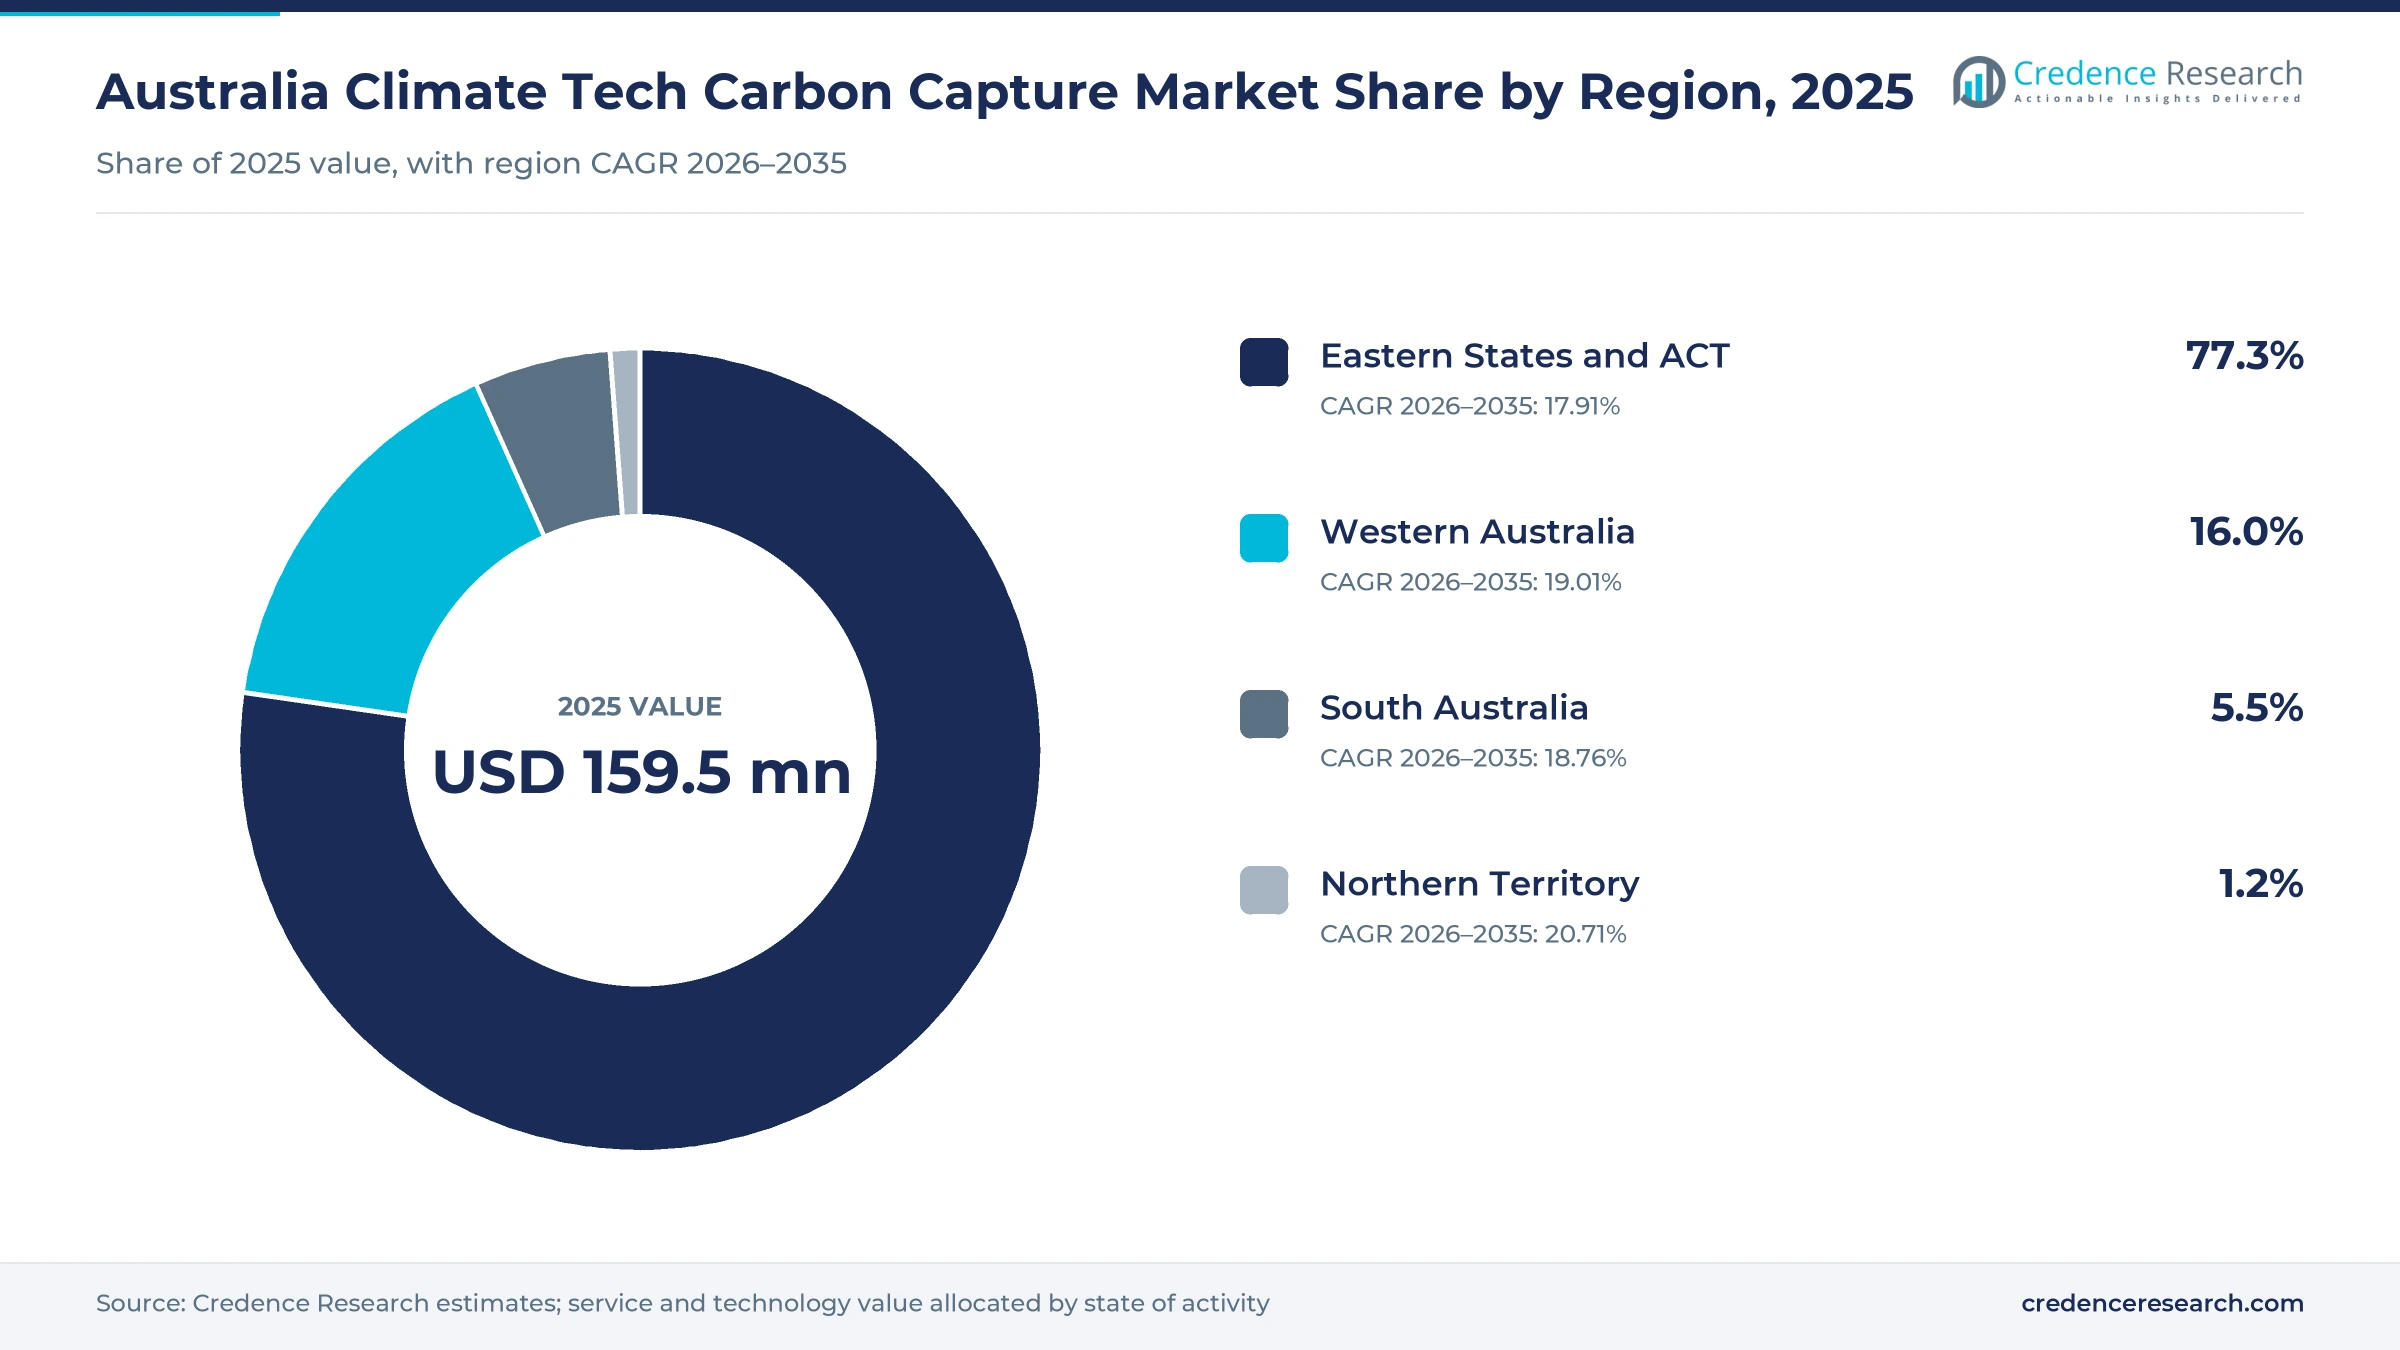
Eastern States lead while Northern Territory grows fastest
| Region | Value, 2025 (USD million) | Share, 2025 | CAGR, 2026–2035 |
|---|---|---|---|
| Eastern States and ACT | 123.3 | 77.3% | 17.91% |
| Western Australia | 25.5 | 16.0% | 19.01% |
| South Australia | 8.8 | 5.5% | 18.76% |
| Northern Territory | 1.9 | 1.2% | 20.71% |
Why do the eastern States and ACT hold the largest share?
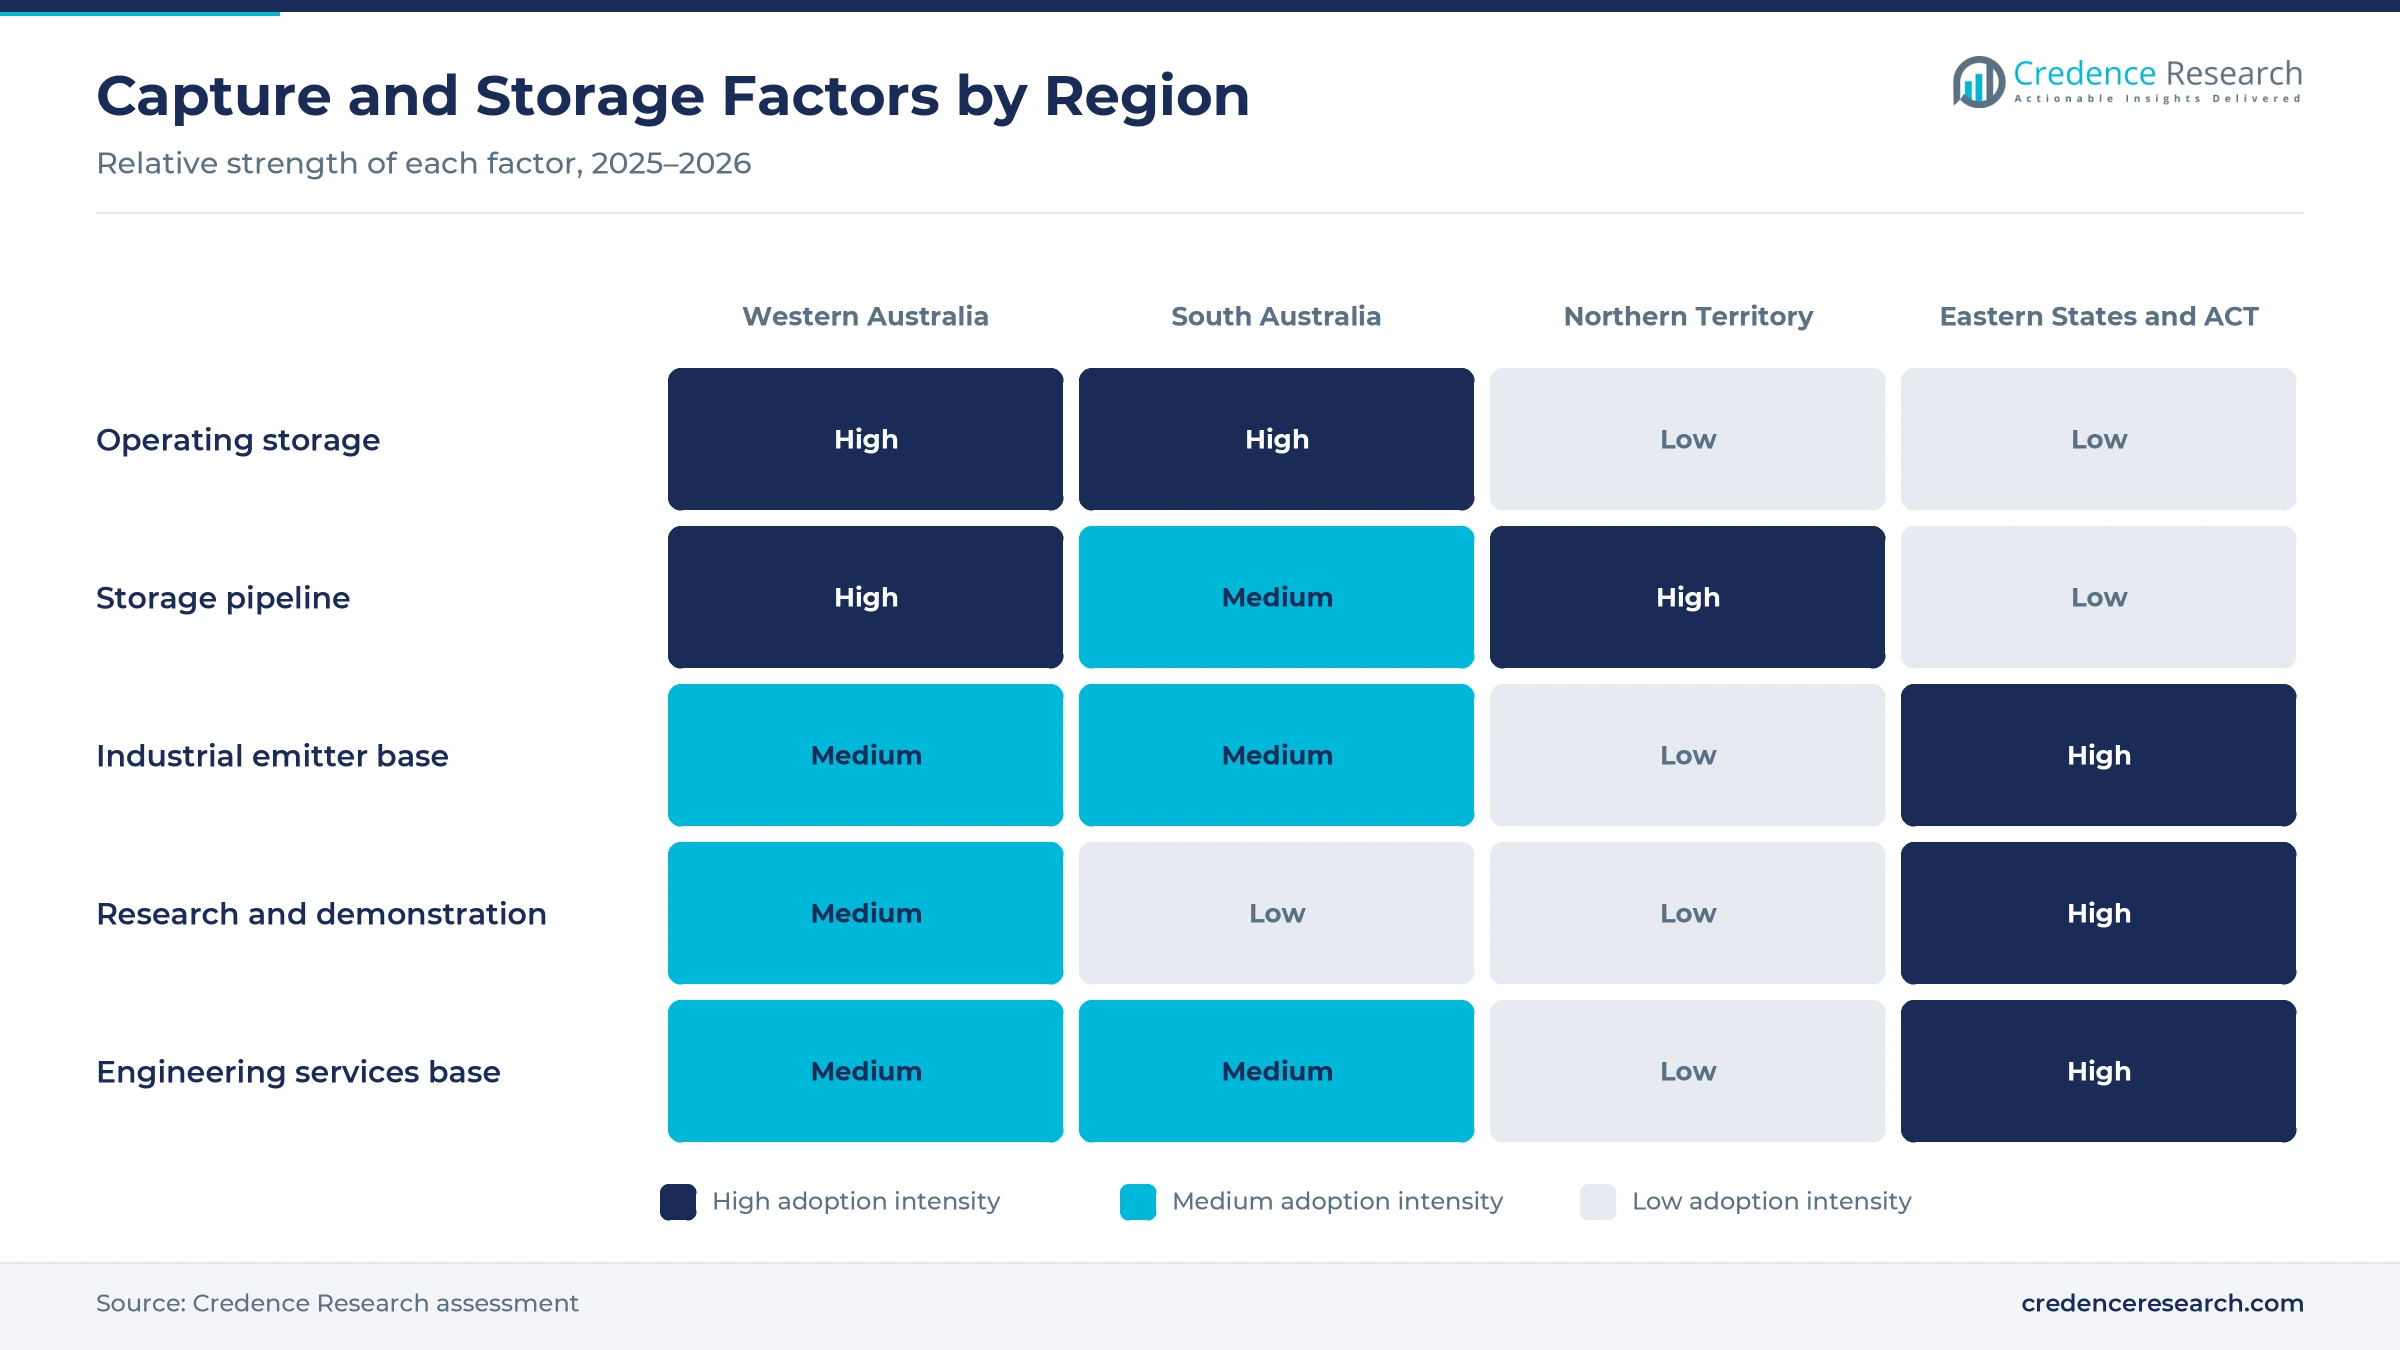
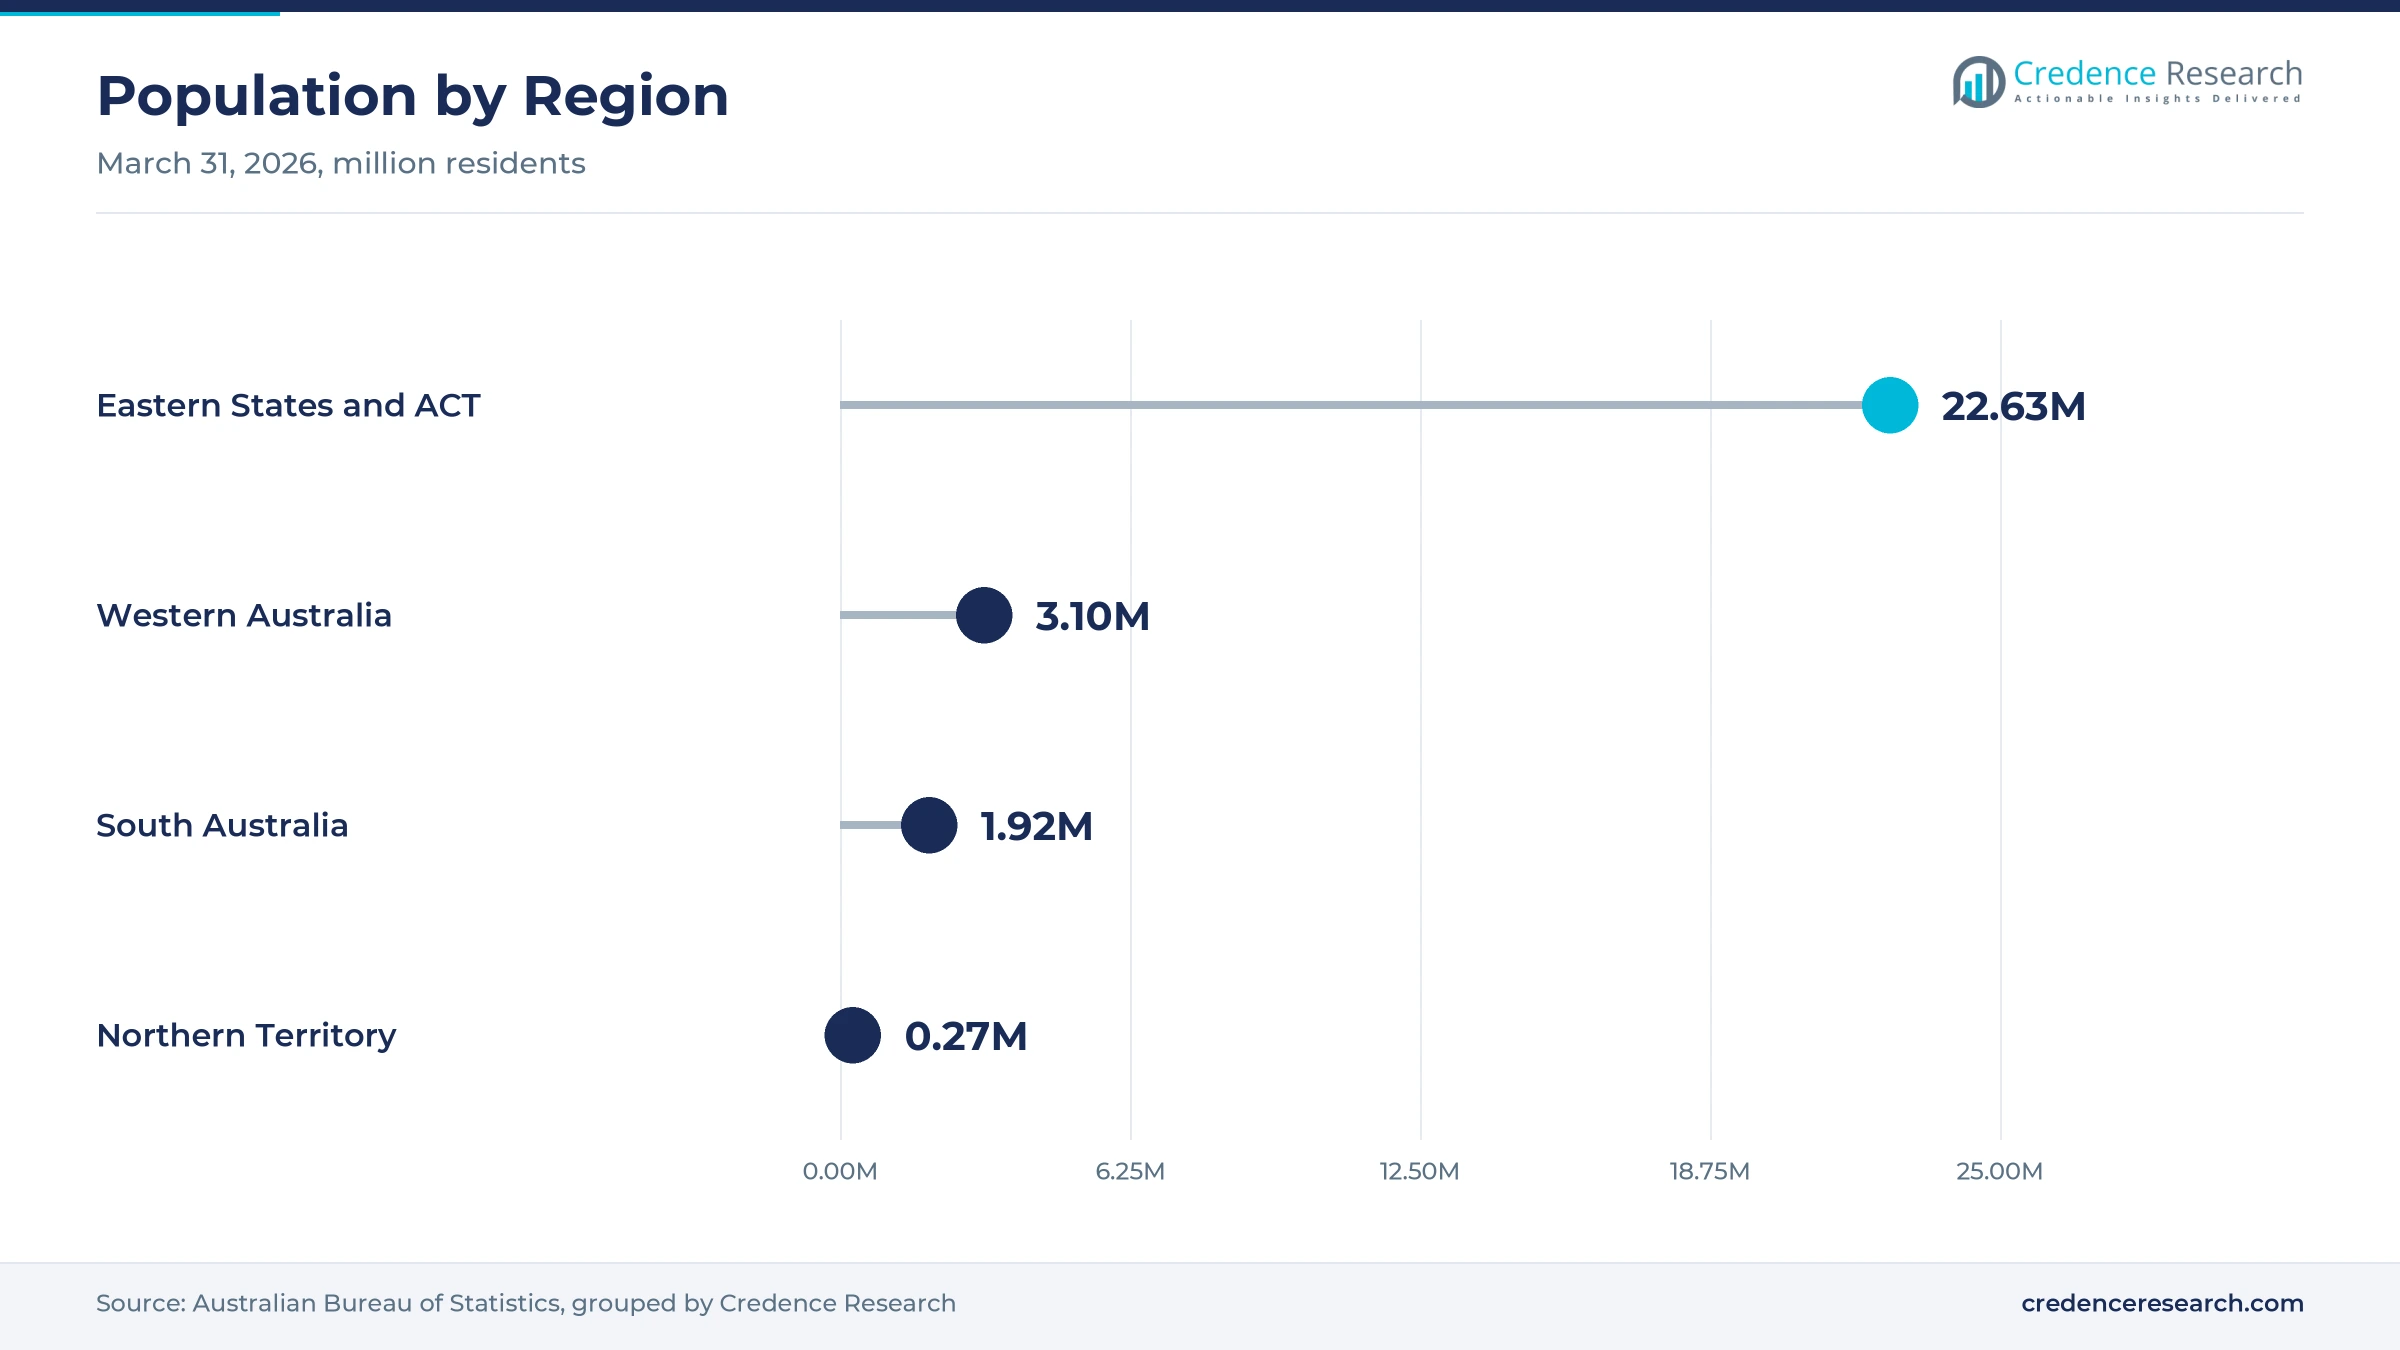
Eastern States and ACT held 77.3% of 2025 value and grow at 17.91% a year, because the region hosts most of the population, manufacturing plants, engineering firms and research programs. New South Wales, Victoria, Queensland, Tasmania and the ACT had about 22.6 million of Australia's 27.9 million residents at March 31, 2026. As a result, much of the engineering, technology and research spending is booked in the east. MCi Carbon's Myrtle plant in Newcastle adds mineral carbonation capacity in New South Wales.
How does Western Australia build on Gorgon and new sites?
Western Australia held 16.0% of 2025 value and grows at 19.01% a year, because Gorgon on Barrow Island has injected more than 11 million metric tons of CO2 since August 2019. Pilot Energy's declared Cliff Head formation adds 13.4 million metric tons of offshore storage in the Mid West. Calix's earlier lime work in Kwinana also links the state to cement and lime capture. In turn, the state has both operating and planned storage.
Why does South Australia matter through Moomba?
South Australia held 5.5% of 2025 value and grows at 18.76% a year, because the Moomba project in the Cooper Basin is the largest onshore storage site in the country. The project can store up to 1.7 million metric tons a year, and Santos and Beach Energy run it as joint venture partners. As a result, South Australia earns storage fees and credit units, while third-party capacity could add emitters from steel and cement.
How does the Northern Territory grow from a small base?
Northern Territory held 1.2% of 2025 value and grows fastest at 20.71% a year, because the Bonaparte project offshore Darwin received its storage formation declaration in October 2026. Pre-front-end engineering began in April 2025, and first injection is targeted for the early 2030s. In turn, engineering and development spending in the territory rises well before storage fees begin.
Moomba, Myrtle and Bonaparte marked 2024 to 2026
| Development | Status and market relevance |
|---|---|
| In July 2024, Calix won a US$10 million federal grant for an electric calciner to capture CO2 from lime and cement. | Supports commercial demonstration of capture in cement and lime |
| In October 2024, the Moomba carbon capture and storage facility started up in South Australia. | Adds up to 1.7 million metric tons a year of onshore storage |
| In May 2026, the Moomba project passed about 2 million metric tons of stored CO2 equivalent. | Shows steady injection and credit generation at scale |
| In July 2026, MCi Carbon started production at its Myrtle mineral carbonation plant in Newcastle. | Turns captured CO2 from ammonia production into saleable products |
| In October 2026, INPEX Browse E&P received a storage formation declaration for the Bonaparte project. | Moves a planned 10 million metric tons a year offshore hub forward |
Solvents, calciners and mineralization widen options
- Reservoir CO2 separation and injection removes CO2 from natural gas during processing and injects it into deep sandstone formations, which suits large gas projects.
- Electric calcination heats limestone without mixing fuel gases with process CO2, which yields a pure stream for storage or use.
- Mineral carbonation reacts CO2 with minerals to form stable carbonates and silica, which creates products for building and industry.
- Next-generation solvents capture CO2 from flue gas with lower energy and capital cost, which suits cement, steel and chemicals plants.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Gas producers and builders lead as startups raise funds
Competition centers on storage access, engineering capability, technology cost and public funding. Santos operates the Moomba project with joint venture partner Beach Energy, and Downer led construction and commissioning of the facility. Chevron Australia runs CO2 injection at Gorgon on Barrow Island. INPEX Browse E&P operates the Bonaparte joint venture with TotalEnergies and Woodside Energy, which is also an investor in KC8 Capture Technologies. Pilot Energy holds a storage declaration for its Mid West project. Calix Limited and MCi Carbon lead in capture technology, backed by federal grants for calcination and mineral carbonation. Because geological operations hold the largest share of 2025 value, companies with storage rights hold the strongest position, while technology firms compete for industrial emitters.
Companies profiled and their roles in this market
| Company | Type | Role in the market |
|---|---|---|
| Santos Limited | Storage operator | Operates the Moomba project in the Cooper Basin |
| Beach Energy | Joint venture partner | Partner in the Moomba storage project |
| Chevron Australia | Storage operator | Runs CO2 injection at Gorgon on Barrow Island |
| Downer Group | Engineering contractor | Led construction and commissioning of Moomba |
| INPEX Browse E&P | Hub developer | Operates the Bonaparte joint venture with a 53% interest |
| Woodside Energy | Energy operator and investor | Holds 21% of Bonaparte and backs KC8 |
| Pilot Energy | Hub developer | Holds a storage declaration for Cliff Head |
| Calix Limited | Technology developer | Develops electric calcination for lime and cement |
| MCi Carbon | Technology developer | Runs the Myrtle mineral carbonation plant |
| KC8 Capture Technologies | Technology developer | Develops a solvent-based capture process |
Credence Research view on Australian CO2 storage
Credence Research's view is that Australian spending on CO2 capture and storage will grow quickly because Safeguard baselines keep falling and operating sites have proven injection at scale. Geological operations keep the largest share, while new capture technologies grow faster as grants turn into sales. The Northern Territory should grow fastest among regions through 2035 as offshore hubs develop. However, high costs and long permits will slow some projects. Companies with storage rights and low-cost capture should gain the most share.
Regulator data and project releases anchor the model
The report uses 2025 as the base year on a calendar basis, and market values come from the Credence Research model. That model combines Clean Energy Regulator data, project capacities and storage volumes, grant announcements, storage declarations, population data and World Bank emissions data. Segment splits and regional growth rates are Credence Research estimates, while regional shares follow the client-defined split. Sources used are regulator releases, government agency releases, trade press and company releases, and no interviews or surveys were used.
Offshore hubs and industrial capture carry growth to 2035
Spending on these capture and storage services is expected to reach USD 845.9 million by 2035, an 18.18% CAGR during 2026–2035, as shared hubs and industrial capture expand. Growth should hold firm through 2030 as Safeguard baselines tighten and demonstration plants move to commercial scale. After that, offshore hubs such as Bonaparte will set the pace as first injection approaches. Faster approvals would shift value toward storage fees, while slower approvals would keep spending focused on engineering and technology. Shared storage hubs are expected to gain delivery share through 2035.
Frequently Asked Questions
How big is the Australia climate tech carbon capture market?
Which service type leads demand in Australia?
Which region leads the Australian market?
How does the Safeguard Mechanism affect demand?
How much CO2 has the Moomba project stored?
Which end use grows fastest?
Who are the leading companies in Australia?
What are the main challenges for the market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Service Type
- 1.2.1 Geological CCS Operations
- 1.2.2 Project Development and Engineering
- 1.2.3 Capture Technology Commercialisation
- 1.2.4 Research and Demonstration
- 1.3 By Customer Type
- 1.3.1 Integrated Energy Operators
- 1.3.2 Independent Industrial Emitters
- 1.3.3 Storage Hub Developers
- 1.3.4 Public Research Buyers
- 1.4 By End-Use Industry
- 1.4.1 Natural Gas Processing
- 1.4.2 Cement and Lime
- 1.4.3 Metals and Chemicals
- 1.4.4 Atmospheric Carbon Removal
- 1.5 By Delivery Model
- 1.5.1 Captive Integrated Systems
- 1.5.2 Shared Storage Hubs
- 1.5.3 Distributed Capture Installations
- 1.5.4 Demonstration Facilities
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2025: USD 159.5 million → 2035: USD 845.9 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Historical Period: 2018-2025
- 2.6.2 Base Year: 2025
- 2.6.3 Forecast Period: 2025-2035
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2025
- 3.3 Forecast Market Size, 2035
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Australia Climate Tech Carbon Capture Market Trends and Developments
- 4.1 Historical Industry Development, 2018-2025
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Australia Climate Tech Carbon Capture Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis, 2018-2025
- 5.2 Demand Forecast, 2025-2035
- 5.3 Production and Output Trend, 2018-2025
- 5.4 Production and Output Forecast, 2025-2035
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Australia Climate Tech Carbon Capture Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends, 2018-2025
- 6.3 Pricing Outlook, 2025-2035
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Australia Climate Tech Carbon Capture Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Australia Climate Tech Carbon Capture Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Australia Climate Tech Carbon Capture Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Australia Climate Tech Carbon Capture Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Australia Climate Tech Carbon Capture Market Outlook, 2025-2035
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2025: USD 159.5 million → 2035: USD 845.9 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size, 2018-2025
- 11.1.4 Base-Year Market Size, 2025
- 11.2 Market Forecast, 2025-2035
- 11.2.1 Revenue Forecast to 2035
- 11.2.2 Volume Forecast to 2035
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Australia Climate Tech Carbon Capture Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2025
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Service Type - Market Size and Forecast, 2025-2035
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size, 2018-2025
- 12.3.3 Revenue Forecast, 2025-2035
- 12.3.4 Volume Forecast, 2025-2035
- 12.3.5 Base-Year Market Share, 2025
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Geological CCS Operations
- 12.3.7.2 Project Development and Engineering
- 12.3.7.3 Capture Technology Commercialisation
- 12.3.7.4 Research and Demonstration
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Customer Type - Market Size and Forecast, 2025-2035
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size, 2018-2025
- 12.4.3 Revenue Forecast, 2025-2035
- 12.4.4 Volume Forecast, 2025-2035
- 12.4.5 Base-Year Market Share, 2025
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Integrated Energy Operators
- 12.4.7.2 Independent Industrial Emitters
- 12.4.7.3 Storage Hub Developers
- 12.4.7.4 Public Research Buyers
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By End-Use Industry - Market Size and Forecast, 2025-2035
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size, 2018-2025
- 12.5.3 Revenue Forecast, 2025-2035
- 12.5.4 Volume Forecast, 2025-2035
- 12.5.5 Base-Year Market Share, 2025
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Natural Gas Processing
- 12.5.7.2 Cement and Lime
- 12.5.7.3 Metals and Chemicals
- 12.5.7.4 Atmospheric Carbon Removal
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Delivery Model - Market Size and Forecast, 2025-2035
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size, 2018-2025
- 12.6.3 Revenue Forecast, 2025-2035
- 12.6.4 Volume Forecast, 2025-2035
- 12.6.5 Base-Year Market Share, 2025
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Captive Integrated Systems
- 12.6.7.2 Shared Storage Hubs
- 12.6.7.3 Distributed Capture Installations
- 12.6.7.4 Demonstration Facilities
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Australia Climate Tech Carbon Capture End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Australia Climate Tech Carbon Capture Geographic Market Outlook, 2025-2035
- 14.1 Domestic Market Distribution and Demand Clusters
- 14.2 State- or Province-Wise Market Size and Forecast, 2025-2035
- 14.3 City and Metropolitan Market Outlook
- 14.4 Industrial, Manufacturing and Commercial Clusters
- 14.5 Geographic Concentration of Key End Users
- 14.6 Local Pricing and Purchasing Differences
- 14.7 Domestic Production Facilities and Capacity Map
- 14.8 Local Infrastructure and Project Pipeline
- 14.9 State-Level Policy and Incentive Differences
- 14.10 Subnational Investment Hotspots and Opportunities
- 14.11 Distribution and Logistics Networks
- 14.12 Domestic Competitive Footprint
Chapter 15 Australia Climate Tech Carbon Capture Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2025-2035
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Australia Climate Tech Carbon Capture Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2025
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2025-2035
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Chevron Australia
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Santos Limited
- 18.4 Woodside Energy
- 18.5 Beach Energy
- 18.6 Downer Group
- 18.7 INPEX Browse E&P
- 18.8 Calix Limited
- 18.9 Pilot Energy
- 18.10 MCi Carbon
- 18.11 KC8 Capture Technologies
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

