
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Carbon Capture and Sequestration Market Size 2024 | USD 4202.5 Million |
| Carbon Capture and Sequestration Market, CAGR | 20.3% |
| Carbon Capture and Sequestration Market Size 2032 | USD 18434.55 Million |
Market Overview:
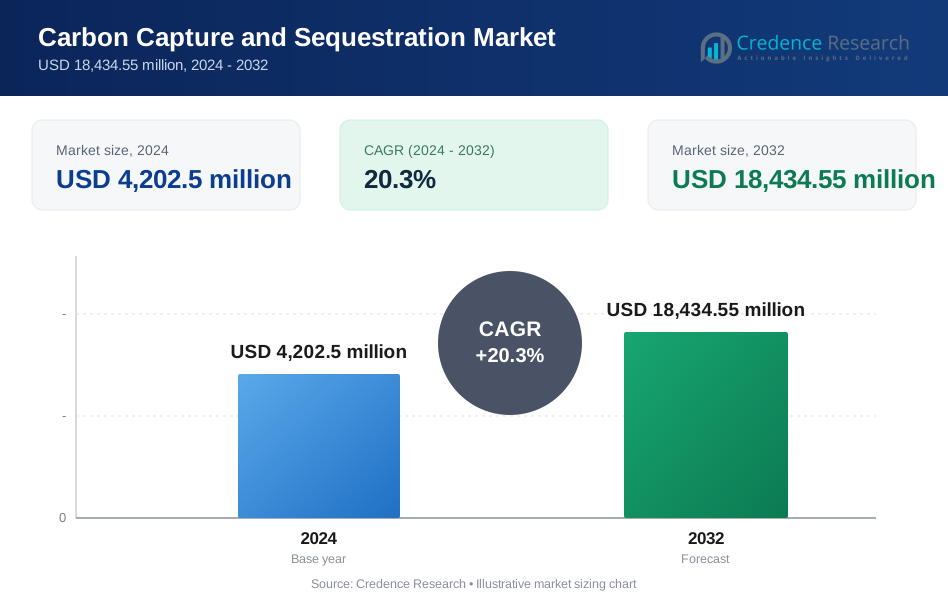
The Carbon Capture and Sequestration Market is projected to grow from USD 4202.5 million in 2024 to an estimated USD 18434.55 million by 2032, with a compound annual growth rate (CAGR) of 20.3% from 2024 to 2032.
Market drivers for the Carbon Capture and Sequestration (CCS) market include growing global efforts to combat climate change and meet international carbon reduction commitments. Stricter emission regulations, such as those outlined in the Paris Agreement, are compelling industries to adopt CCS solutions as a critical pathway toward net-zero targets. The energy, power generation, and industrial sectors, particularly oil & gas, cement, and chemicals, are at the forefront of CCS adoption due to their significant carbon emissions. Advancements in technology, including enhanced capture efficiency and cost optimization, are making CCS increasingly viable. Government incentives, tax credits like the U.S. 45Q, and funding for large-scale projects are further driving investments. Additionally, the growing interest in integrating CCS with blue hydrogen production and enhanced oil recovery (EOR) is expanding the scope of applications, creating lucrative opportunities for industry players.
Regional analysis highlights North America as the market leader, driven by substantial government support, well-established infrastructure, and large-scale projects like those in the U.S. and Canada. Europe follows closely, with its stringent emission regulations and significant investments in clean energy technologies. The Asia-Pacific region is emerging as a high-growth market, fueled by rapid industrialization, carbon neutrality initiatives in China, Japan, and Australia, and rising investments in CCS pilot projects. Meanwhile, the Middle East and Africa are leveraging CCS for sustainable fossil fuel production and energy diversification. In Latin America, growing environmental awareness and policy reforms are driving gradual adoption, positioning the region as a promising future market for CCS technologies.
Market Insights:
- The CCS market is projected to grow significantly, reaching USD 18,434.55 million by 2032, driven by a robust CAGR of 20.3% from 2024 to 2032.
- Stringent emission regulations, such as the Paris Agreement and net-zero targets, are pushing industries to adopt CCS technologies globally.
- Key sectors leading adoption include power generation, oil & gas, cement, and chemicals, which face pressure to reduce their carbon footprints.
- Technological advancements in post-combustion, pre-combustion, and oxy-fuel combustion methods are improving capture efficiency and lowering costs.
- North America holds the largest market share at 40%, driven by projects like the Alberta Carbon Trunk Line and favorable incentives such as the S. 45Q tax credit.
- Europe follows with a 30% market share, led by projects like Norway’s Longship and the UK’s Northern Endurance Partnership, supported by the EU Innovation Fund.
- Emerging regions such as Asia-Pacific (20% share), Middle East & Africa, and Latin America are witnessing rapid growth, fueled by carbon neutrality initiatives, infrastructure investments, and abundant geological storage potential.
Market Drivers:
Stringent Environmental Regulations and Climate Goals
The global push to combat climate change has placed carbon emissions at the center of regulatory frameworks. Governments worldwide are implementing strict emission reduction targets to meet commitments under international agreements like the Paris Accord and the Net-Zero by 2050 initiative. For instance, the United Kingdom has approved its first commercially viable carbon storage facility, led by BP and Equinor, aiming to capture millions of tonnes of CO₂ and store it under the North Sea. This £4 billion project is expected to start operations within four years, contributing significantly to the UK's net-zero emissions goal by 2050. Carbon Capture and Sequestration (CCS) technologies are emerging as a cornerstone solution for industries to comply with these regulations. High-emission industries, including power generation, cement, oil & gas, and chemicals, are under increasing pressure to reduce their carbon footprint. Regulatory incentives, such as tax credits, emissions trading systems, and carbon pricing mechanisms, are accelerating CCS adoption by making it economically attractive for corporations to invest in carbon reduction technologies.
Technological Advancements and Cost Optimization
Significant advancements in CCS technology are improving its efficiency and reducing associated costs, making it more accessible to a wide range of industries. Innovations in capture processes, including post-combustion, pre-combustion, and oxy-fuel combustion methods, are enhancing the effectiveness of carbon capture. Simultaneously, improvements in storage techniques, such as geological sequestration, ensure safe and long-term containment of captured carbon dioxide. For example, Mitsubishi Heavy Industries' Advanced KM CDR Process® uses a proprietary solvent to achieve a CO₂ capture efficiency of over 90%. As research and development progress, the deployment of CCS systems is becoming increasingly scalable and cost-effective. Additionally, the integration of digital solutions, including AI and IoT technologies, is optimizing operations, monitoring processes, and improving accuracy, further driving market adoption.
Rising Investments and Government Incentives
Global investments in decarbonization initiatives are creating significant momentum for the CCS market. Governments and private sector players are allocating substantial funding to support CCS projects. Programs like the U.S. 45Q tax credit and Europe’s Innovation Fund are encouraging industries to adopt CCS by providing financial support and incentives. Public-private partnerships are also playing a vital role in funding large-scale projects and infrastructure development. Oil & gas companies, in particular, are heavily investing in CCS to align with sustainability goals while ensuring operational continuity. For instance, the U.S. Department of Energy (DOE) has made substantial investments in Carbon Capture and Sequestration (CCS) projects through its Carbon Storage Assurance Facility Enterprise (CarbonSAFE) initiative. In October 2024, the DOE announced more than $518 million to support 23 projects across 19 states, focusing on developing infrastructure for permanent and safe CO₂ storage. Increasing government support for blue hydrogen production, where CCS is integrated to create cleaner hydrogen fuel, is opening new avenues for market growth and adoption.
Increased Adoption Across High-Emission Industries
The rising demand for CCS solutions across high-emission industries is a key driver of market expansion. Industries such as cement, steel, and chemicals, which face challenges in decarbonization due to process emissions, are leveraging CCS as a practical solution to reduce carbon output. For example, HeidelbergCement's Norcem Brevik project in Norway aims to capture 400,000 tonnes of CO₂ annually from its cement production. In the energy sector, power plants are deploying CCS to balance carbon reduction goals while maintaining energy security. Oil & gas producers are integrating CCS with enhanced oil recovery (EOR) to achieve both economic and environmental benefits. Furthermore, the growing awareness of CCS as a complementary technology to renewable energy is encouraging industries to adopt hybrid approaches, where carbon capture is combined with other sustainable solutions, thereby amplifying the overall impact of emission reduction efforts.
Market Trends:
Integration of CCS with Emerging Technologies
The Carbon Capture and Sequestration (CCS) market is witnessing a significant trend toward integrating CCS with emerging technologies to enhance efficiency and expand its applicability. One prominent example is the rising synergy between blue hydrogen production and CCS, which allows hydrogen to be produced while capturing associated carbon emissions. This integration not only supports cleaner energy transitions but also helps industries meet decarbonization targets cost-effectively. Additionally, Direct Air Capture (DAC) technologies, which remove carbon dioxide directly from the atmosphere, are gaining momentum as complementary solutions to CCS. Innovations in digital technologies, such as artificial intelligence, machine learning, and IoT, are further revolutionizing CCS operations by enabling real-time monitoring, predictive maintenance, and enhanced storage optimization.
Growth of Large-Scale CCS Projects
The deployment of large-scale CCS projects is increasing globally, driven by ambitious decarbonization goals and growing private and public investments. Major CCS hubs and industrial clusters are being established, particularly in North America, Europe, and parts of Asia-Pacific, to provide integrated solutions for multiple industries. Notable projects, such as Norway’s Longship Project and Alberta Carbon Trunk Line in Canada, serve as successful models for scalable carbon capture and storage. For instance, Norway's Longship project has received total funding of NOK 25.1 billion, including initial investment and a 10-year operating period, with the Norwegian state contributing NOK 16.8 billion. Furthermore, multi-industry CCS initiatives are reducing implementation costs by sharing infrastructure, including transportation pipelines and geological storage facilities. This trend of collaborative CCS deployment is creating opportunities for faster adoption and facilitating economies of scale across industries.
Focus on Carbon Utilization and Circular Economy
A growing market trend involves shifting from traditional carbon storage to carbon utilization, where captured CO₂ is transformed into valuable products. Innovations in carbon-to-chemicals, fuels, and materials are expanding the role of CCS within a circular economy framework. For example, captured carbon is increasingly being used to produce synthetic fuels, concrete, and polymers, providing industries with economic incentives to invest in CCS. For instance, Dioxycle has developed an ethylene-producing electrolyser that transforms industrial emissions into sustainable ethylene using only renewable electricity and water. Companies are exploring ways to convert CO₂ into green methanol or use it in enhanced agricultural processes, such as algae cultivation for biofuels. This approach not only reduces environmental impact but also creates revenue streams, positioning CCS as a commercially viable solution beyond emissions reduction.
Regional Expansion and Policy-Driven Adoption
The CCS market is experiencing rapid regional expansion, particularly in emerging economies that are intensifying their decarbonization efforts. Asia-Pacific countries, including China, Japan, and South Korea, are investing heavily in CCS infrastructure as part of their carbon neutrality goals. Simultaneously, Middle Eastern nations are adopting CCS to decarbonize fossil fuel production and establish themselves as leaders in clean energy solutions. Governments worldwide are driving policy frameworks, such as tax credits, grants, and emissions penalties, to encourage widespread CCS adoption. For instance, The European Union issued around $1.5 billion to CCUS projects under the Innovation Fund and over $500 million to CO2 transport and storage projects through the Connecting Europe Facility programme. This policy-driven momentum is positioning CCS as an integral component of global decarbonization strategies.
Market Challenges Analysis:
High Costs of Implementation and Infrastructure
The Carbon Capture and Sequestration (CCS) market faces significant challenges due to the high costs associated with its implementation and infrastructure development. Building capture facilities, transportation pipelines, and secure storage sites requires substantial capital investment, often deterring companies, especially small and medium enterprises. The operational costs, including energy consumption for CO₂ capture and compression, further add to the financial burden. While advancements in technology are gradually reducing these expenses, the cost-efficiency of CCS remains a concern, particularly in regions with limited government incentives or funding support.
Technological and Operational Limitations
Despite ongoing innovations, CCS technologies face certain operational and technological limitations that hinder widespread adoption. Carbon capture processes, particularly for post-combustion emissions, are energy-intensive and may reduce overall plant efficiency. Additionally, scalability challenges arise when attempting to implement CCS in existing facilities, as retrofitting infrastructure can be complex and costly. Storage security is another concern, with the need for rigorous monitoring to prevent CO₂ leakage from geological reservoirs, raising questions about long-term safety and reliability. These technological hurdles slow down the large-scale deployment of CCS solutions.
Regulatory and Public Acceptance Challenges
Regulatory uncertainty and public skepticism present notable barriers to the CCS market. While governments are setting carbon reduction targets, inconsistent policies and insufficient financial incentives in certain regions limit the adoption of CCS projects. Public perception of CCS as a temporary fix rather than a long-term solution for carbon neutrality also poses challenges. Concerns about the environmental risks of CO₂ storage, combined with limited awareness of CCS benefits, further hinder its acceptance among stakeholders and communities. Addressing these concerns through clear regulatory frameworks and public engagement remains critical for market growth.
Limited Infrastructure in Emerging Markets
Emerging economies, despite their growing need for carbon reduction technologies, face infrastructure gaps that challenge CCS implementation. Regions such as parts of Asia-Pacific, Africa, and Latin America lack the necessary pipeline networks, storage facilities, and skilled labor required to support CCS projects. The absence of well-defined policies and financial support mechanisms exacerbates these limitations. Bridging this infrastructure gap will be essential for CCS to expand globally and effectively contribute to emission reduction targets.
Market Opportunities:
The Carbon Capture and Sequestration (CCS) market presents significant opportunities as industries beyond traditional emitters recognize its potential for achieving decarbonization goals. Sectors such as blue hydrogen production, bioenergy with carbon capture and storage (BECCS), and direct air capture (DAC) are emerging as key areas for growth. The demand for low-carbon hydrogen is rising globally as governments and corporations focus on clean energy solutions, positioning CCS as a critical enabler. Additionally, the integration of CCS in bioenergy projects creates the possibility of achieving negative emissions, which are essential for balancing hard-to-abate carbon outputs. These applications not only expand the market but also enhance its economic viability by diversifying revenue streams.
Emerging markets in Asia-Pacific, the Middle East, and Latin America are witnessing increased investments and policy reforms that unlock new opportunities for CCS adoption. Countries like China, India, and Saudi Arabia are accelerating their climate commitments and directing resources toward large-scale CCS infrastructure. These regions are strategically positioned to benefit from CCS due to their high industrial activity and growing energy demands. Furthermore, government incentives, tax breaks, and public-private partnerships are driving investments in CCS hubs and integrated industrial clusters. As nations prioritize sustainable economic development, CCS will play a pivotal role in reducing emissions while supporting industrial growth, offering robust market opportunities for key stakeholders.
Market Segmentation Analysis:
The Carbon Capture and Sequestration (CCS) market is segmented based on capture source, end-use, and region, reflecting its diverse applications and growing adoption across industries.
By Capture Source Analysis, natural gas processing leads the market due to the ease of capturing CO₂ from gas streams, accounting for a significant portion of CCS deployment. Power generation is another major segment, driven by the need to decarbonize coal and gas-fired plants as part of global emission reduction goals. Industries such as fertilizer production and chemicals are also key contributors, as they face challenges in reducing process emissions. The others category includes steel and cement industries, where CCS is vital for meeting sustainability targets.
By End-use, dedicated storage and treatment dominates the segment, with a focus on secure geological sequestration of captured carbon dioxide. However, Enhanced Oil Recovery (EOR) continues to play a critical role, particularly in regions like North America and the Middle East, where CO₂ injection supports oil production while mitigating emissions.
Segmentation:
By Capture Source Analysis
- Natural Gas Processing
- Power Generation
- Fertilizer’s Production
- Chemicals
- Others
By End-use
- Dedicated Storage & Treatment
- Enhanced Oil Recovery (EOR)
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
North America holds the largest share of the Carbon Capture and Sequestration (CCS) market, accounting for approximately 40% of the global market. The United States and Canada lead the region due to strong government support, favorable policies, and substantial investments in large-scale CCS projects. In the United States, initiatives such as the 45Q tax credit, offering up to $85 per ton of CO₂ stored, incentivize industries to adopt CCS solutions across the power, oil & gas, and industrial sectors. Canada follows with ambitious projects like the Boundary Dam CCS project in Saskatchewan, which has successfully captured over 4 million tons of CO₂ since its inception. Similarly, the Alberta Carbon Trunk Line, with a capacity to transport 14.6 million tons of CO₂ annually, reflects the region’s commitment to large-scale infrastructure. North America’s robust regulatory frameworks, technological advancements in carbon capture efficiency, and focus on achieving net-zero emissions by 2050 continue to drive market growth, positioning the region as a global leader in CCS innovation.
Europe
Europe accounts for approximately 30% of the global CCS market, driven by the region's ambitious climate policies and stringent emission reduction targets under the European Green Deal, which aims to reduce emissions by 55% by 2030. Norway remains a frontrunner with projects like the Longship Project, which plans to capture and store 1.5 million tons of CO₂ annually. The United Kingdom’s Northern Endurance Partnership targets industrial emissions in the Humber and Teesside regions, aiming to capture up to 10 million tons of CO₂ per year by 2030. Europe’s focus on establishing CCS hubs, such as the Porthos project in the Netherlands, enhances cost efficiency through shared transportation and storage infrastructure. Funding initiatives, including the €10 billion EU Innovation Fund, are catalyzing CCS investments, positioning Europe as a pioneer in large-scale carbon-neutral technologies and industrial decarbonization.
Asia-Pacific
The Asia-Pacific region holds a growing share of the CCS market, accounting for approximately 20%, with strong contributions from China, Japan, South Korea, and Australia. China, the world’s largest carbon emitter, is actively scaling up CCS deployment to meet its carbon neutrality goal by 2060, with projects like the Yanchang Integrated CCS Project, which captures 400,000 tons of CO₂ annually. Japan and South Korea are investing heavily in CCS as part of their national climate strategies, with Japan’s Tomakomai CCS Demonstration Project storing 300,000 tons of CO₂ since its launch. In Australia, the Gorgon CCS project, one of the world’s largest, has a storage capacity of 4 million tons of CO₂ per year. The region’s rapid industrialization and increasing energy demand make Asia-Pacific a significant area for future CCS opportunities, supported by government-backed pilot projects and regional collaboration.
Middle East and Africa
The Middle East and Africa (MEA) region represents about 7-10% of the global CCS market but is poised for steady growth as countries adopt CCS to decarbonize fossil fuel production. Saudi Arabia’s Circular Carbon Economy (CCE) strategy includes CCS as a pillar for achieving its net-zero goal by 2060, with projects like the Uthmaniyah CCS facility, which captures 800,000 tons of CO₂ annually. Similarly, the UAE’s Al Reyadah project has become a regional leader, sequestering up to 800,000 tons of CO₂ per year from industrial sources. Africa, while in the early stages of CCS adoption, holds significant potential due to its abundant natural geological storage capacity, particularly in regions like Algeria and South Africa. As regional governments intensify sustainability initiatives, the Middle East and Africa are expected to play a critical role in the future of CCS.
Latin America
Latin America holds a smaller market share at approximately 5-7% but offers promising growth prospects as governments align with global decarbonization efforts. Brazil and Argentina are leading CCS adoption through industrial and energy-focused initiatives. Brazil, for example, is leveraging its offshore geological storage potential for projects within its oil & gas sector. International collaborations and investments are fostering regional CCS development, with growing emphasis on natural carbon sinks and geological sequestration. While CCS adoption remains gradual in Latin America, the region’s abundant natural storage sites and increasing policy support position it as a promising future market for carbon sequestration technologies.
Key Player Analysis:
- ADNOC Group (UAE)
- Aker Solutions (Norway)
- BP (U.K.)
- Carbon Engineering Ltd (Canada)
- Chevron (U.S.)
- China National Petroleum Corporation (China)
- Dakota Gasification Company (U.S.)
- Equinor (Norway)
- Exxonmobil (U.S.)
- Fluor Corporation (U.S.)
- Linde Plc (Ireland)
- NRG Energy (U.S.)
- Shell (Netherlands)
- Total Energies (France)
Competitive Analysis:
The Carbon Capture and Sequestration (CCS) market is characterized by the presence of key global players striving to expand their market share through technological innovation, strategic partnerships, and large-scale project deployments. Leading companies such as ExxonMobil, Chevron, Shell, TotalEnergies, and Equinor dominate the market with significant investments in CCS infrastructure, research, and development. For instance, ExxonMobil's LaBarge facility in Wyoming captures approximately 7 million metric tons of CO₂ annually, making it one of the largest CCS operations in the world. These organizations leverage their expertise in energy and storage technologies to implement scalable projects, such as Norway’s Longship Project (Equinor) and Australia’s Gorgon CCS project (Chevron). New entrants and technology firms are also contributing to the market through advancements in direct air capture (DAC) and enhanced monitoring solutions. Strategic collaborations between governments, research institutions, and private entities are intensifying competition and fostering innovation. Companies are increasingly adopting public-private partnerships and exploring carbon utilization solutions to differentiate themselves, creating a dynamic and competitive landscape that drives CCS market growth worldwide.
Recent Developments:
- In December 2024, Equinor, BP, and TotalEnergies finalized their investment in two of Britain’s pioneering carbon capture and storage projects located in northern England. As joint partners in the Northern Endurance Partnership (NEP) project, which will initially store up to 4 million tonnes of carbon dioxide annually, Equinor and BP each hold a 45% stake, while TotalEnergies holds 10%. Additionally, Equinor and BP co-own the Net Zero Teesside Power project, a 742-MW gas-fired power plant incorporating carbon capture, with BP owning 75% and Equinor 25%.
- In December 2024, the UK's first commercially viable carbon storage facility, led by BP and Equinor, received regulatory approval. This £4 billion project aims to capture millions of tonnes of CO₂ and store it under the North Sea, with operations expected to commence within four years. The facility is projected to inject up to 4 million tonnes of CO₂ annually for 25 years, contributing significantly to the UK's net-zero emissions goal by 2050.
- In December 2024, Chevron announced its exploration into supplying lower-carbon power to data center operators, leveraging its extensive global natural gas experience and operations. This initiative aligns with Chevron's expertise in natural gas, construction, operations, and providing low-carbon solutions via carbon capture, utilization, and storage (CCUS) and geothermal technologies.
- In October 2024, ExxonMobil executed the largest offshore carbon dioxide (CO₂) storage lease in the U.S. with the Texas General Land Office. The over 271,000-acre site complements ExxonMobil's onshore CO₂ storage portfolio, further solidifying the U.S. Gulf Coast as a carbon capture and storage leader
Market Concentration & Characteristics:
The Carbon Capture and Sequestration (CCS) market is moderately concentrated, with a few dominant players holding a significant share due to their technological expertise, extensive infrastructure, and substantial investments. Key market participants, including ExxonMobil, Chevron, Equinor, BP, and TotalEnergies, are driving the market through large-scale CCS projects and strategic collaborations. These companies leverage advanced carbon capture technologies, robust storage capabilities, and global partnerships to maintain their competitive edge. The market is characterized by high capital intensity and technological complexity, limiting entry for new players. Public-private partnerships and government incentives play a critical role in encouraging innovation and expanding CCS adoption. Additionally, the market is evolving toward integrated CCS hubs and industrial clusters, which enhance cost efficiency and scalability. As demand for decarbonization grows, the market is witnessing increased focus on carbon utilization solutions, positioning CCS as a cornerstone technology for achieving global net-zero emissions targets.
Report Coverage:
The research report offers an in-depth analysis based on By Capture Source Analysis and By End-use. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The CCS market will witness accelerated adoption as global economies push toward net-zero emissions by 2050.
- Technological advancements in capture efficiency and cost reduction will make CCS more economically viable for industries.
- Increasing integration of CCS with blue hydrogen production and direct air capture (DAC) will expand its applications.
- Government policies, tax incentives, and climate funding will play a pivotal role in scaling CCS infrastructure globally.
- The establishment of large-scale CCS hubs and industrial clusters will enhance cost efficiency and promote regional collaboration.
- Emerging markets in Asia-Pacific, the Middle East, and Latin America will experience rapid CCS adoption driven by industrialization and climate commitments.
- Carbon utilization innovations, such as turning CO₂ into fuels, chemicals, and building materials, will create new revenue streams.
- Partnerships between governments, energy companies, and technology firms will drive the development of scalable CCS projects.
- Growing public and corporate awareness of CCS as a critical climate solution will foster greater acceptance and investment.
- Long-term advancements in monitoring and storage security will improve trust and drive confidence in CCS deployment worldwide.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected growth of the CCS market?
What are the main drivers for CCS market growth?
Why is North America leading the CCS market?
What challenges are hindering CCS market growth?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Carbon Capture and Sequestration Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Carbon Capture and Sequestration Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 4,202.5 million → 2032: USD 18,434.55 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Carbon Capture and Sequestration Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Carbon Capture and Sequestration Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Carbon Capture and Sequestration Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Carbon Capture and Sequestration Market Drivers
- 3.3 Carbon Capture and Sequestration Market Restraints & Challenges
- 3.4 Carbon Capture and Sequestration Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Carbon Capture and Sequestration Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Carbon Capture and Sequestration Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Carbon Capture and Sequestration category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Carbon Capture and Sequestration Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Carbon Capture and Sequestration Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Carbon Capture and Sequestration market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Carbon Capture and Sequestration Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Carbon Capture and Sequestration Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Carbon Capture and Sequestration Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Carbon Capture and Sequestration (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Carbon Capture and Sequestration Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Carbon Capture and Sequestration Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Carbon Capture and Sequestration Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Carbon Capture and Sequestration Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Carbon Capture and Sequestration Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Carbon Capture and Sequestration Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Carbon Capture and Sequestration Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Carbon Capture and Sequestration Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Carbon Capture and Sequestration Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
