
Early-phase trials anchor outsourced lab work in Australia
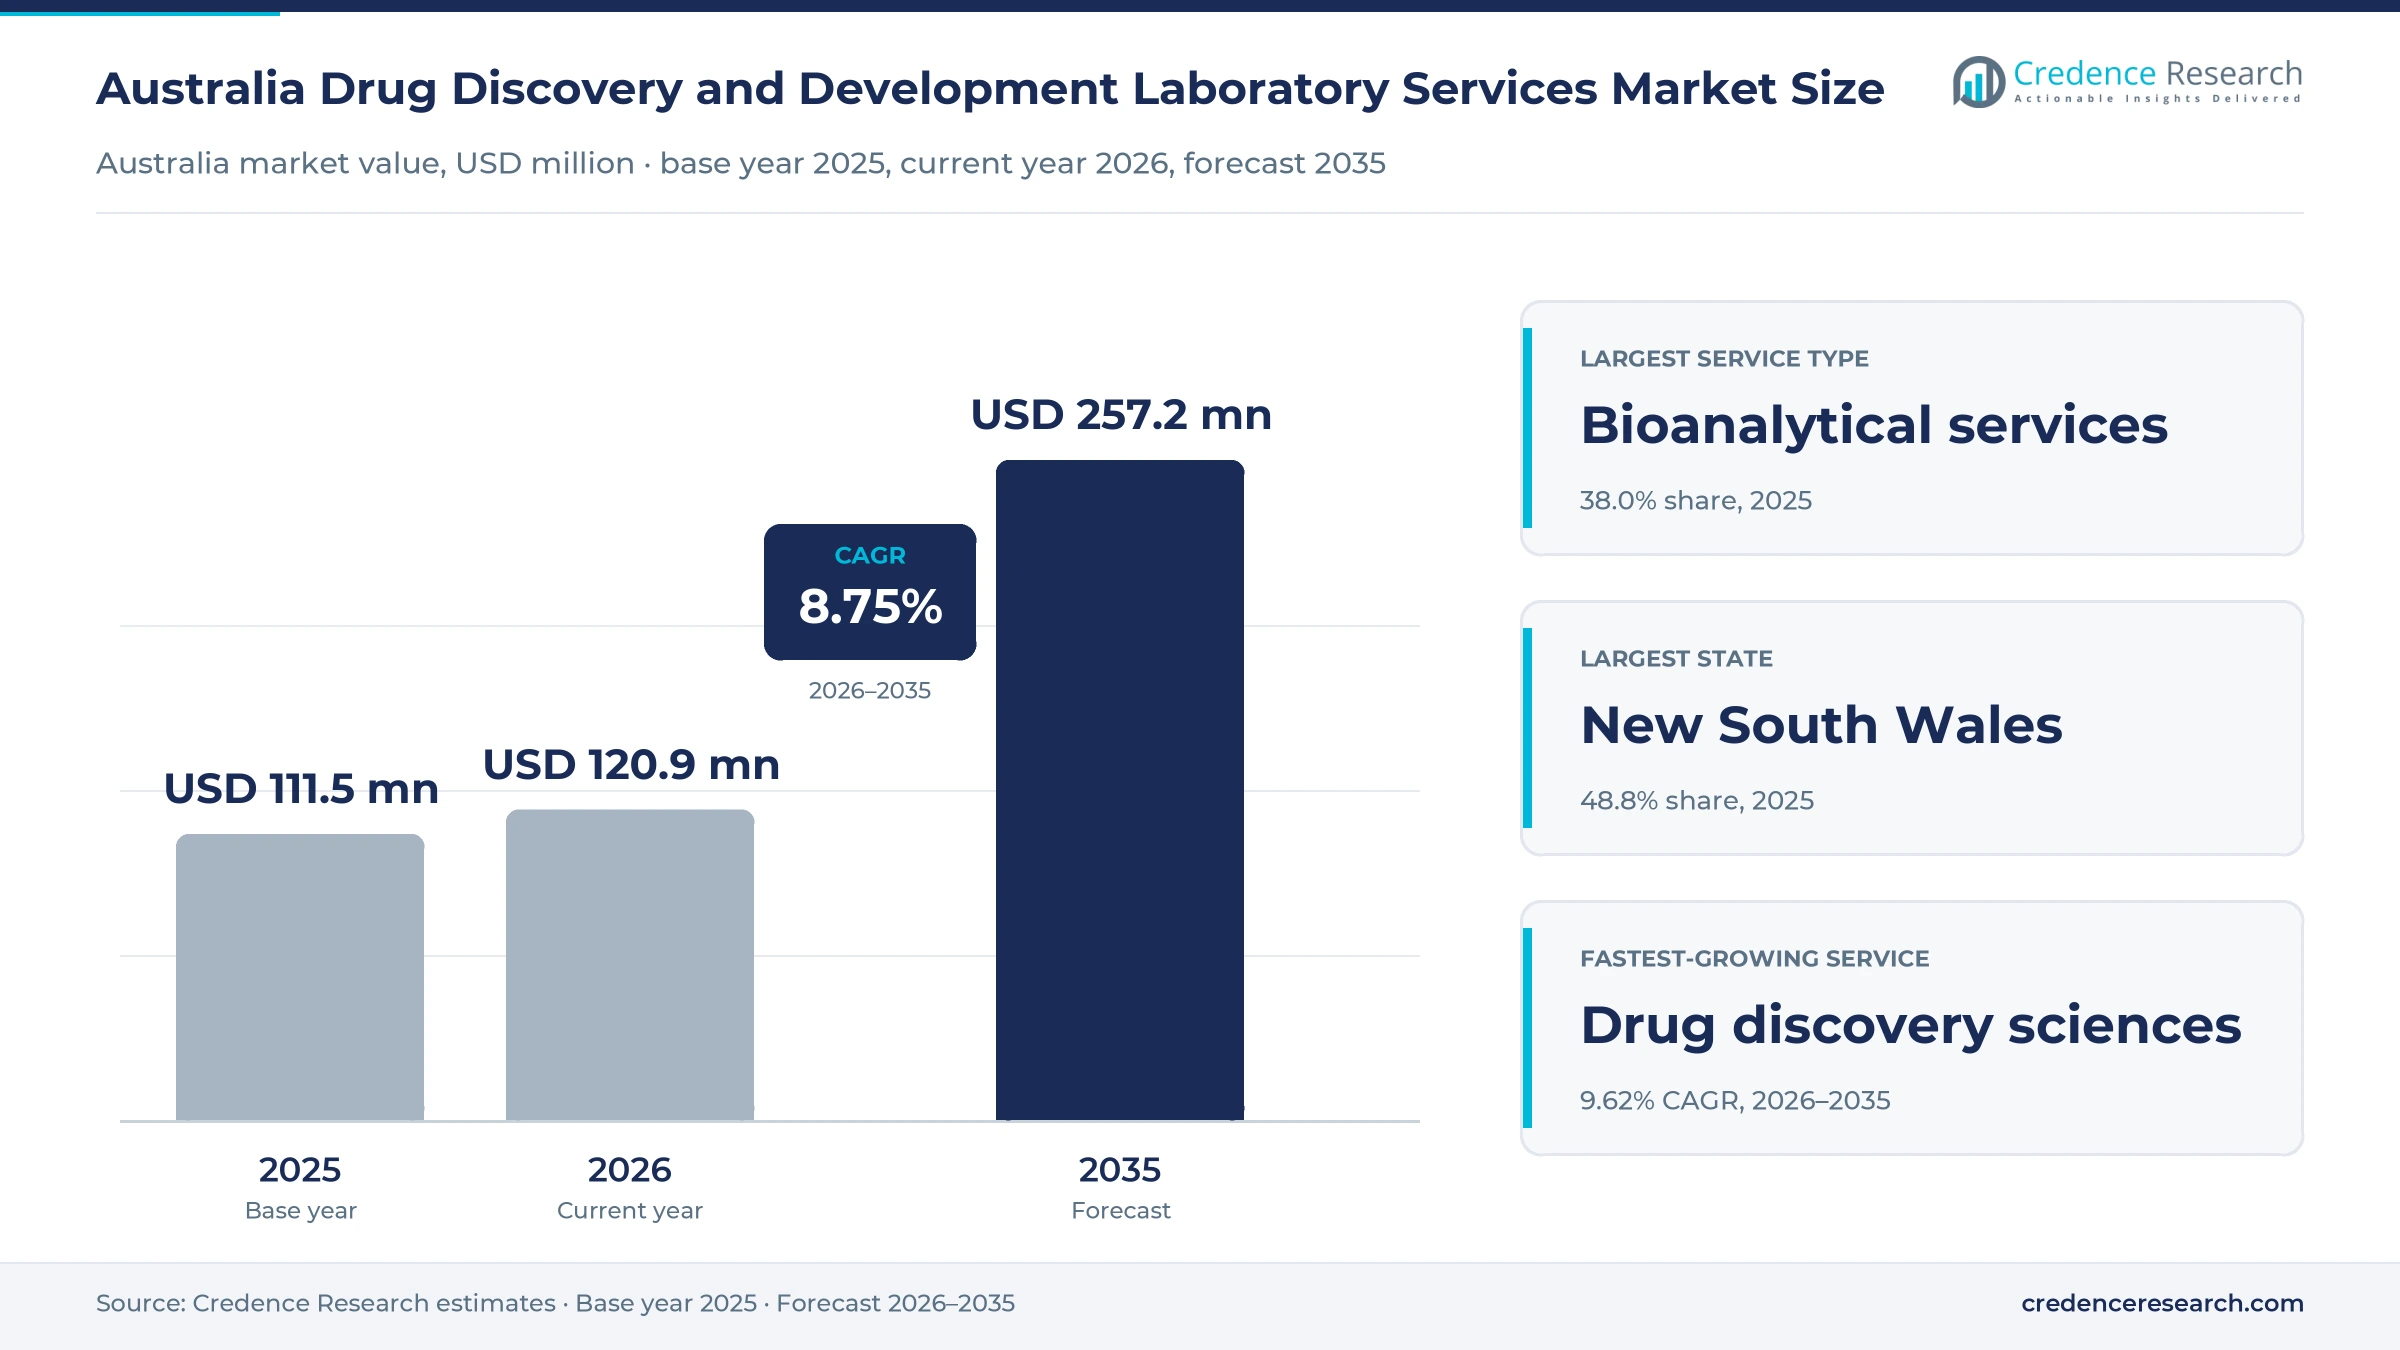
The Australia drug discovery and development laboratory services market was valued at USD 111.5 million in 2025 and is projected to increase from USD 120.9 million in 2026 to USD 257.2 million by 2035, registering a CAGR of 8.75% during 2026–2035. Demand comes from biotechnology sponsors that run first-in-human studies in Australia, from global groups that need bioanalysis, safety and formulation work close to trial sites, and from refundable research tax support that stretches small sponsor budgets. New South Wales held the largest regional share, 48.8% in 2025, because Sydney hosts the largest pool of business research spending and a growing set of trial laboratories. New South Wales is also the fastest-growing state at 8.97% a year as new bioanalytical capacity opens in Macquarie Park. In turn, consolidation is changing the commercial picture, because global research organizations are buying or partnering with Australian laboratories to give overseas sponsors one route from early studies to later trials.
Which outsourced laboratory work does the estimate count?
The estimate measures fees paid by biotechnology, pharmaceutical and public research sponsors to Australian laboratories for bioanalysis, pharmacology and safety studies, analytical chemistry, formulation work and discovery science. It counts fixed-price projects, dedicated scientist contracts and per-test fees, whether the sponsor contracts directly or reaches the laboratory through a research organization or a global network.
The estimate excludes the clinical fees of trial sites, commercial drug manufacturing, routine hospital pathology and research that sponsors run in their own laboratories. The value chain runs from overseas and local sponsors through research organizations to specialist and integrated laboratories, which test samples, build methods and prepare the data packages that regulators in Australia, the United States and Europe review.
Australia Drug Discovery and Development Laboratory Services Market Insights
- The Australia drug discovery and development laboratory services market was valued at USD 111.5 million in 2025 and is projected to reach USD 257.2 million by 2035, registering a CAGR of 8.75% during 2026–2035.
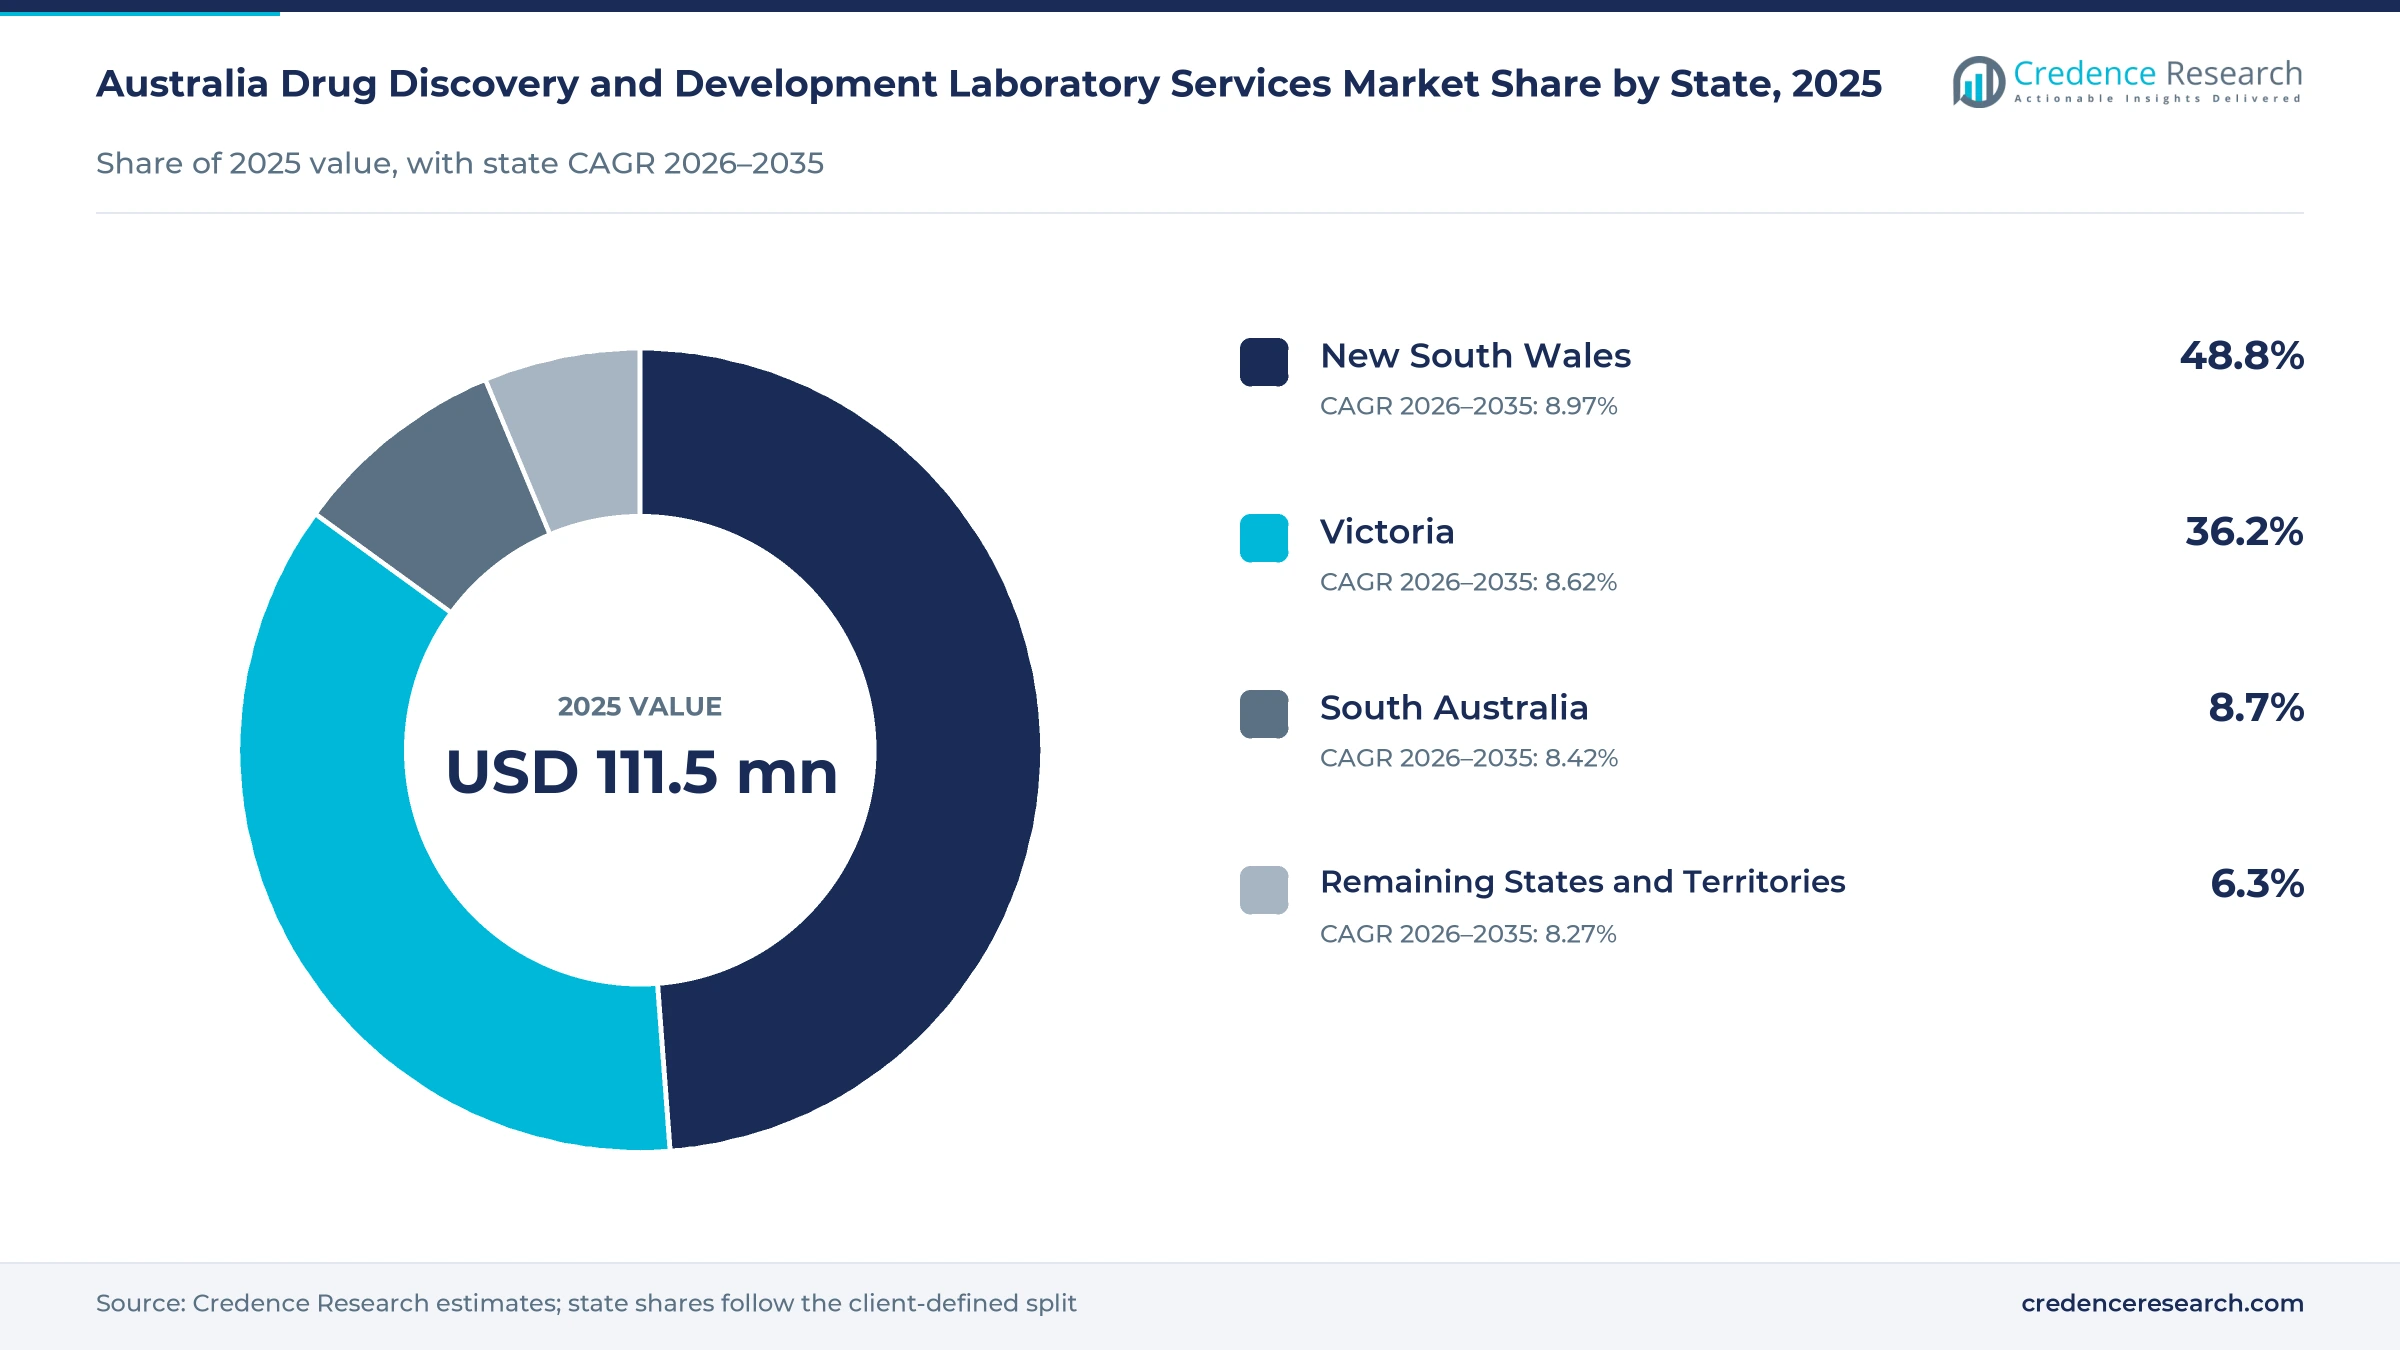
- New South Wales held a 48.8% share of 2025 value, because it hosts the largest share of business research spending in Australia.
- Bioanalytical Services led with a 38.0% share of 2025 value, because every early human study needs drug level and biomarker testing.
- Novotech agreed in September 2026 to acquire Adelaide-based Agilex Biolabs, which shows global groups buying Australian bioanalytical capacity.
- Global Laboratory Network Referrals grow fastest among sales channels at 9.53% a year, as overseas groups route sponsors to Australian sites during 2026–2035.
Bioanalysis leads while discovery sciences grow fastest
Why do bioanalytical services hold the largest share?
Based on service type, the market is categorized into Bioanalytical Services, Pharmacology and Safety Assessment, Analytical Chemistry and Formulation Development, and Drug Discovery Sciences. Bioanalytical Services led with a 38.0% share of 2025 value, because every first-in-human study needs drug level, immunogenicity and biomarker testing. Drug Discovery Sciences grows fastest at 9.62% a year, as state grants and tax offsets help young companies fund target and lead work.
Which sponsors fund most outsourced laboratory work?
Based on customer type, the market is categorized into Biotechnology Sponsors, Pharmaceutical Sponsors and Academic and Public Research Sponsors. Biotechnology Sponsors led with a 58.0% share of 2025 value, because small overseas and local biotechs bring most early studies to Australia. Academic and Public Research Sponsors grow fastest at 9.34% a year, as public research funding moves more university discoveries toward human testing.
How do early and later clinical stages split demand?
Based on application, the market is categorized into Discovery and Lead Optimisation, Preclinical Development, Early Clinical Laboratory Support, and Later Clinical Laboratory Support. Early Clinical Laboratory Support led with a 42.0% share of 2025 value, because Australia hosts many first-in-human and Phase 1 studies. Later Clinical Laboratory Support grows fastest at 9.52% a year, as sponsors keep Australian laboratories on contract when programs move into larger trials.
How do sponsors reach Australian laboratories?
Based on sales channel, the market is categorized into Direct Sponsor Contracting, Research Organisation Subcontracting and Global Laboratory Network Referrals. Direct Sponsor Contracting led with a 52.0% share of 2025 value, because many biotechs hire specialist laboratories themselves for early studies. Global Laboratory Network Referrals grow fastest at 9.53% a year, as global groups that own or partner with Australian laboratories send overseas sponsors to local sites.
| Segment Group | Leading Sub-segment | Share, 2025 | Fastest-growing Sub-segment | CAGR, 2026–2035 |
|---|---|---|---|---|
| By Service Type | Bioanalytical Services | 38.0% | Drug Discovery Sciences | 9.62% |
| By Customer Type | Biotechnology Sponsors | 58.0% | Academic and Public Research Sponsors | 9.34% |
| By Application | Early Clinical Laboratory Support | 42.0% | Later Clinical Laboratory Support | 9.52% |
| By Sales Channel | Direct Sponsor Contracting | 52.0% | Global Laboratory Network Referrals | 9.53% |
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Trial pull-through, tax offsets and new capacity lift spend
How does early-phase trial strength pull laboratory work?
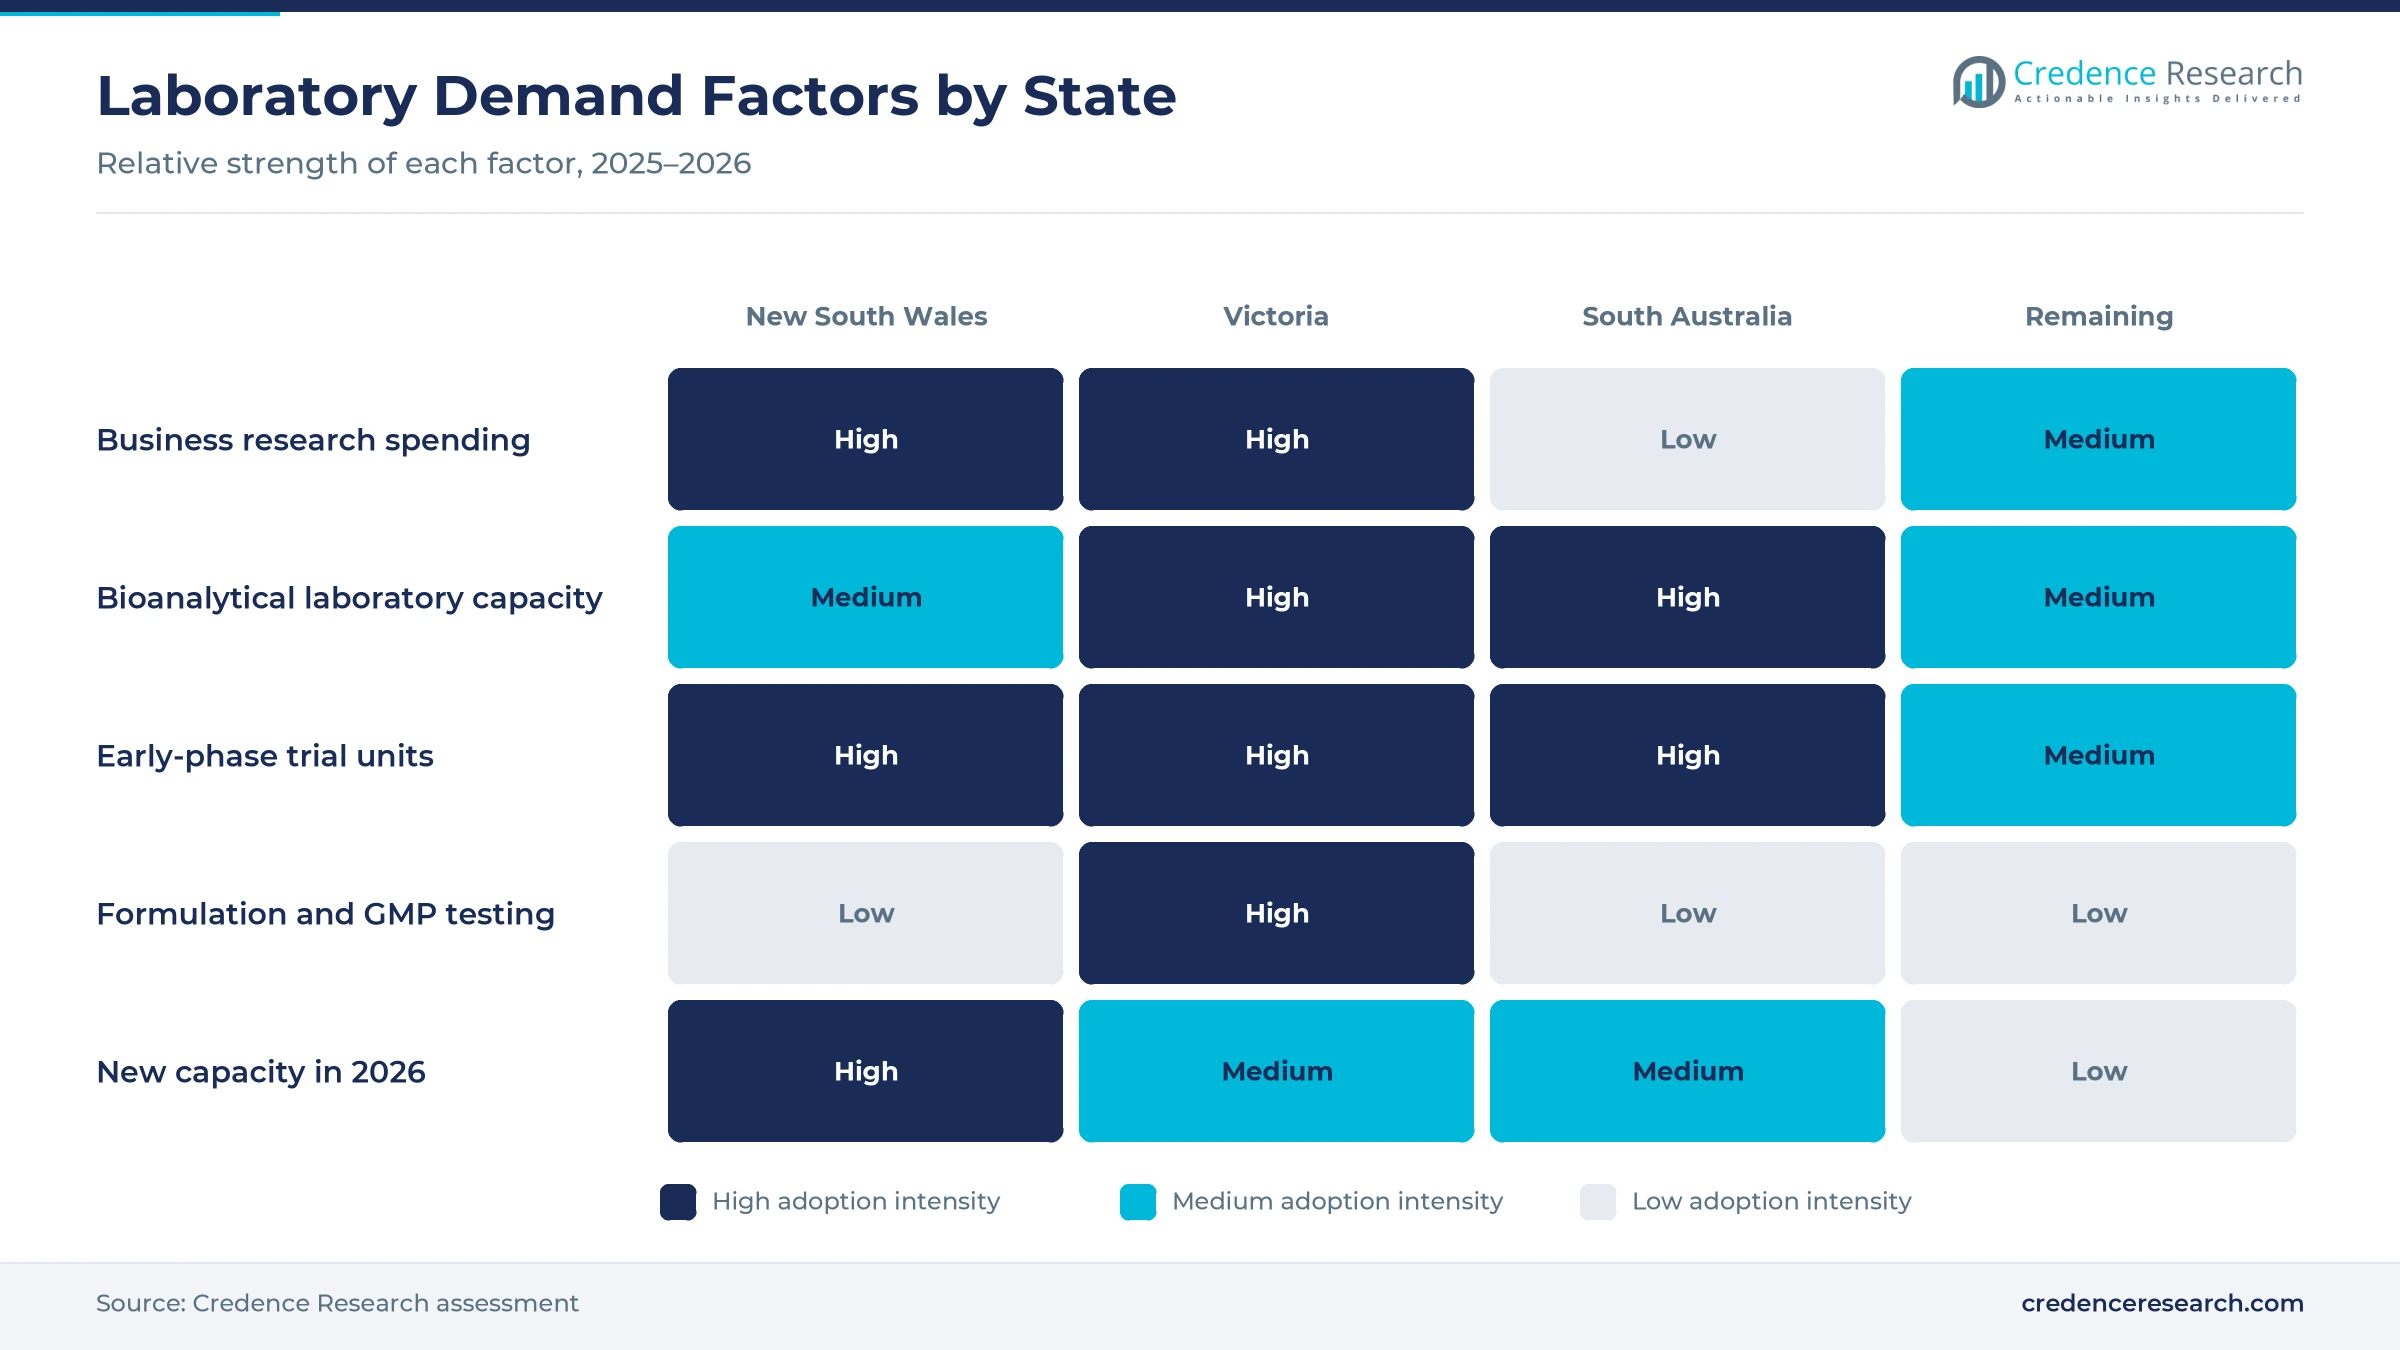
Australia's role as a first stop for human studies brings bioanalysis, safety and formulation contracts to local laboratories, because sponsors want samples tested close to the clinic. The clinical trials sector generated AUD 1.6 billion in 2022, when 1,850 trials started and about 90,000 people took part, according to MTPConnect. CMAX Clinical Research runs a 78-bed early-phase unit opposite the Royal Adelaide Hospital, according to the South Australian Department of State Development. KCAS Bio says Australian study start-up can take less than 12 weeks with no IND required, which draws United States biotechs to local sites. As a result, early clinical laboratory support holds 42.0% of 2025 value.
How do tax offsets and research funds widen sponsor budgets?
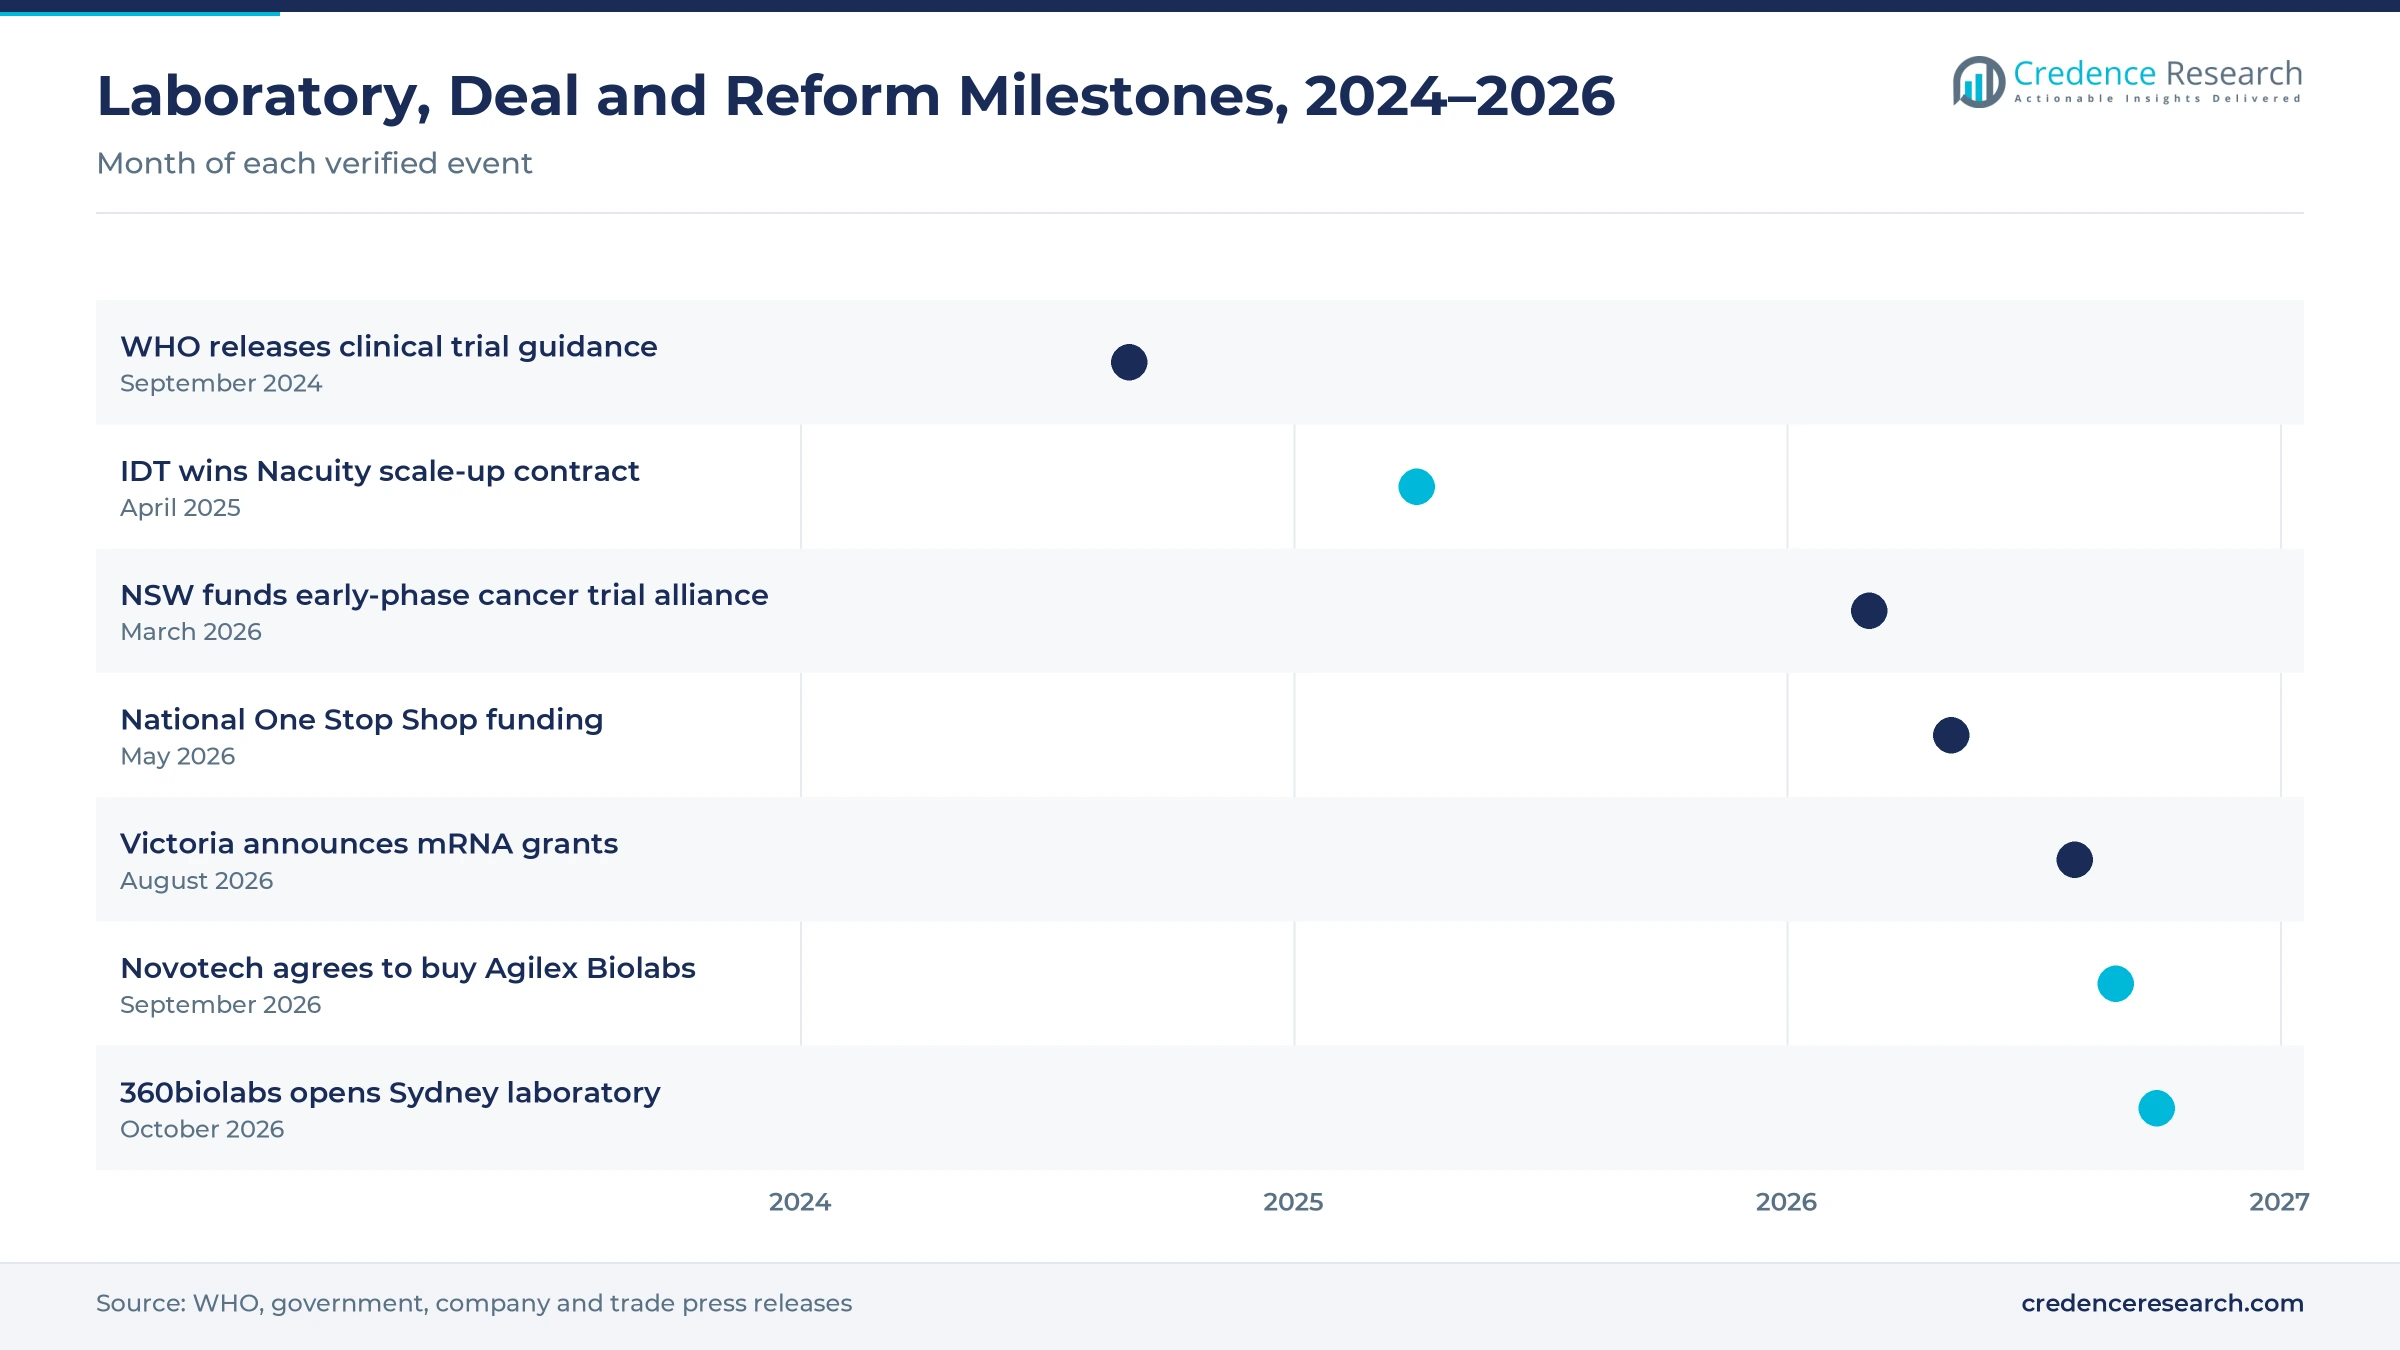
Federal tax support lowers the net cost of outsourced research, which lets small sponsors buy more laboratory work for each dollar they raise. Companies with turnover below AUD 20 million receive a refundable offset equal to their corporate tax rate plus an 18.5% premium, according to the federal government business portal. The federal government announced funding on May 12, 2026, to progress the National One Stop Shop for trial approvals, according to the Inter-Governmental Policy Reform Group. The Victorian government announced AUD 2 million in mRNA grants in August 2026, and mRNA Victoria has invested AUD 34 million in 65 projects since 2021. As a result, academic and public research sponsors grow fastest at 9.34% a year.
Why does new specialist capacity lift laboratory spending?
Laboratories are adding biosafety, cytometry and mass spectrometry space, which lets sponsors keep complex assays in Australia rather than ship samples abroad. 360biolabs opened a NATA-accredited laboratory in North Ryde in October 2026 with BSL-2 space for PBMC isolation and flow cytometry, according to BioSpectrum Asia. Resolian runs a purpose-built Brisbane laboratory of about 2,000 square meters with LC-MS, immunoassay and PCR suites, according to Wilson Architects. Crux Biolabs operates 1,070 square meters of PC2 laboratory and office space in Bayswater with storage for more than 100,000 vials at minus 80 degrees Celsius, according to KCAS Bio. In turn, demand for bioanalytical testing keeps Bioanalytical Services the largest service line.
Why do larger corporate R&D budgets widen the buyer pool?
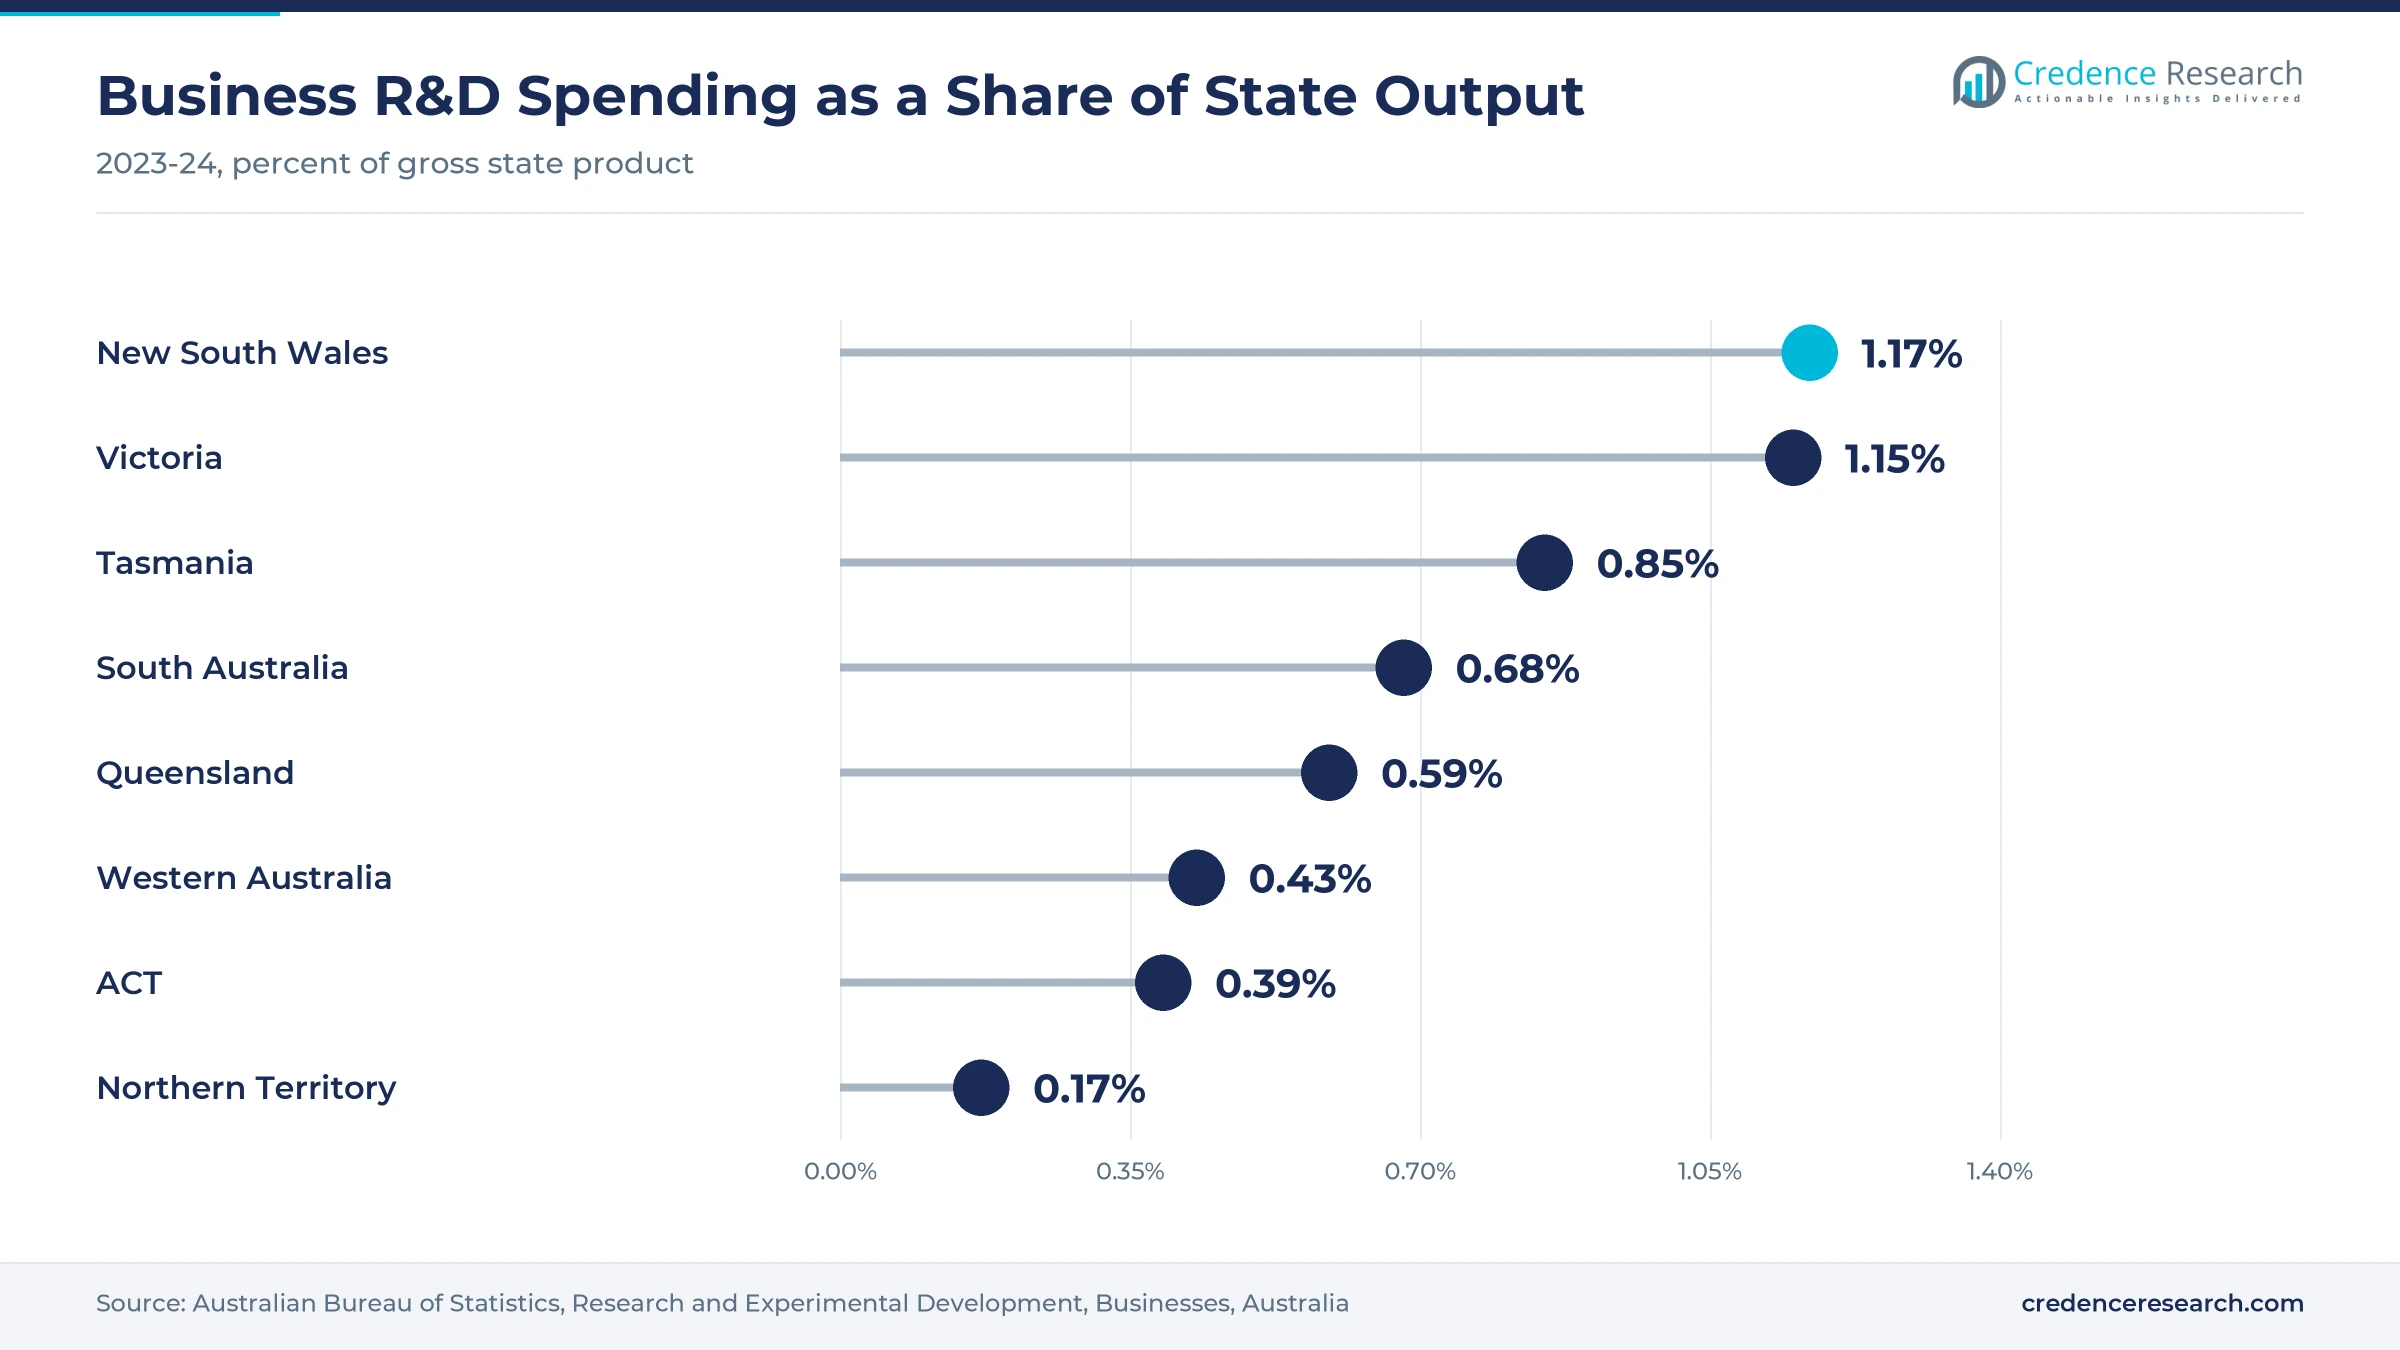
Business research budgets are rising fastest in the states that host most laboratories, which widens the pool of sponsors that buy outsourced work. Business expenditure on research and development reached AUD 24.41 billion in 2023-24, up 18% from 2021-22, according to the Australian Bureau of Statistics. New South Wales spent AUD 9.63 billion, or 39% of the total, while Victoria spent AUD 6.95 billion, or 28%, in the same year. Professional, scientific and technical services, the industry group that includes scientific research firms, raised its spending by AUD 2.2 billion. As a result, direct sponsor contracting holds 52.0% of 2025 value as local companies hire laboratories themselves.
Global networks and cell-based assays reshape the field
Why is consolidation into global laboratory networks rising?
Australian specialist laboratories are shifting into global research groups, which gives overseas sponsors one contract that runs from Australian studies to later trials abroad. Novotech agreed in September 2026 to buy Adelaide-based Agilex Biolabs from a Healius subsidiary, according to PharmaTimes, which said the deal adds Australian bioanalysis to its laboratory network across Asia. BioAgilytix completed its purchase of 360biolabs in October 2021 after Foreign Investment Review Board approval, adding Melbourne and Brisbane sites. KCAS Bio extends its harmonized cytometry work to Australia through an alliance with Crux Biolabs in Melbourne. As a result, global laboratory network referrals grow fastest at 9.53% a year.
How is the shift toward cell-based and biologic assays emerging?
Sponsors are moving more antibodies, vaccines and cell therapies into Australian trials, which shifts laboratory demand toward immunology, virology and cytometry methods. 360biolabs offers BSL-2 and BSL-3 virology and immunology laboratories, flow cytometry and PCR suites, according to BioAgilytix. Crux Biolabs runs spectral flow cytometry workflows harmonized with KCAS Bio sites in Philadelphia and Lyon, which lets sponsors compare data across continents. Victoria is the only place globally where both Moderna and BioNTech have set up research, development and manufacturing, according to the Victorian government. In turn, biologic programs raise the number of immunogenicity and biomarker tests in each early study.
Can later-phase trial support become a new opening?
Australia's early-phase reputation gives local laboratories an opening to keep sponsors through later trials, where sample volumes and contract lengths are larger. MTPConnect said in June 2024 that Australia could use its early-phase strength to attract more late-phase trials. Data generated at the Crux Biolabs site are ICH, FDA and EMA compliant and accepted for Phase 2 and Phase 3 studies run globally, according to KCAS Bio. The National Health and Medical Research Strategy 2026-2036 was released in May 2026, while governments work toward a single national ethics review decision. As a result, later clinical laboratory support grows fastest at 9.52% a year.
Is there room in formulation and scale-up work?
Sponsors that start trials in Australia often need local formulation, analytical and clinical supply work, which opens room for development laboratories with GMP capacity. IDT Australia won a five-year contract in April 2025 to scale NPI-001 for Nacuity Pharmaceuticals about tenfold to around 200 kilograms of active ingredient, according to its ASX filing. IDT, which specializes in high-potency active pharmaceutical ingredients, is recommissioning a 4,000-liter Boronia plant it calls the largest small-molecule API facility in Australia. Formulytica runs a small-scale GMP facility in Melbourne for topical and injectable formulation, according to its BIO International Convention listing. In turn, analytical chemistry and formulation development keeps a steady place in sponsor budgets.
Staff limits, approval steps and offshore rivals test labs
How do workforce limits cap laboratory capacity?
Specialist laboratories need trained bioanalysts, toxicologists and quality staff, and the trial workforce has not grown with demand. The clinical trials sector employed 7,700 people in 2022, slightly fewer than the 8,000 employed in 2019, according to MTPConnect, which named workforce growth as an area for attention. As a result, laboratories compete for the same scientists in Melbourne, Sydney and Adelaide. Operators respond with graduate programs, automation and links to overseas sister sites.
Why does fragmented trial review delay first samples?
Trial start-up still depends on several ethics and governance reviews, which can delay the first samples that laboratories are hired to test. The Inter-Governmental Policy Reform Group said building the National One Stop Shop platform could take around 18 months or more after a solution partner is appointed. In turn, sponsors may wait longer before laboratory contracts begin. Laboratories respond by starting method work early, so assays are ready when the first site opens.
How does foreign ownership review add deal risk?
Many Australian laboratories now belong to or partner with overseas groups that sell healthcare contract research outsourcing, so acquisitions need regulatory clearance before they close. BioAgilytix closed its purchase of 360biolabs only after Foreign Investment Review Board approval, and the Novotech purchase of Agilex Biolabs remains subject to customary conditions, including regulatory clearances. As a result, staff and customers can face months of uncertainty. Buyers respond by keeping local brands, teams and quality systems in place after each deal.
Why do offshore trial hubs intensify competition?
Sponsors can place early studies in many countries, which puts Australian laboratories in direct competition with lower-cost hubs in Asia. The World Health Organization counted 27,133 trials in high-income countries and 24,791 in low- and middle-income countries in 2022. In turn, Australian laboratories must justify higher labor costs with speed and data quality. Operators respond by stressing NATA accreditation, GLP compliance and data accepted by major regulators.
New South Wales leads as Sydney adds bioanalytical space
| State | Value, 2025 (USD million) | Share, 2025 | CAGR, 2026–2035 |
|---|---|---|---|
| New South Wales | 54.4 | 48.8% | 8.97% |
| Victoria | 40.4 | 36.2% | 8.62% |
| South Australia | 9.7 | 8.7% | 8.42% |
| Remaining States and Territories | 7.0 | 6.3% | 8.27% |
How does new Sydney capacity shape New South Wales?
New South Wales held a 48.8% share of 2025 value and grows fastest at 8.97% a year. The new 360biolabs laboratory sits in the Macquarie Park Innovation District, a cluster of life science and medtech companies in North Ryde. The NSW Early Phase Clinical Trials Alliance lifted the annual number of cancer trials available from 150 to more than 180 over three years, according to NSW Health. As a result, sponsors can test time-sensitive samples without leaving the region.
How do Melbourne laboratory clusters shape Victoria?
Victoria held a 36.2% share of 2025 value and grows at 8.62% a year, because Melbourne hosts the widest mix of specialist laboratories. Crux Biolabs works from Bayswater, Eurofins Biopharma Product Testing Australia runs a TGA-licensed testing laboratory in Dandenong South and IDT Australia operates in Boronia. Victoria hosts 30% of all national clinical trial sites, according to the Victorian government. In turn, formulation, safety and cytometry work stays concentrated in the Melbourne region.
Why does South Australia punch above its size?
South Australia held 8.7% of 2025 value and grows at 8.42% a year, because Adelaide combines a leading bioanalytical laboratory with a long-running early-phase unit. Agilex Biolabs is headquartered in Adelaide, and CMAX Clinical Research sits beside the BioMed City precinct. South Australia recorded the largest rise in business research spending as a share of state output between 2021-22 and 2023-24, reaching 0.68%. As a result, Adelaide remains a steady supplier of trial laboratory work.
How does Brisbane anchor the remaining states?
Remaining States and Territories held a 6.3% share of 2025 value and grow at 8.27% a year, with Brisbane as the main laboratory base. Resolian and 360biolabs both run bioanalytical laboratories in the Queensland capital. Business research spending equaled 0.59% of state output in Queensland and 0.43% in Western Australia in 2023-24. In turn, these states win selected bioanalysis contracts but send much specialist work to the larger centers.
Lab openings, acquisitions and reform funding, 2025–2026
| Development | Status and market relevance |
|---|---|
| In April 2025, IDT Australia won a five-year contract to scale NPI-001 for Nacuity Pharmaceuticals at Boronia. | Supports the restart of a large small-molecule API plant |
| In May 2026, the federal government funded the next stage of the National One Stop Shop for trial approvals. | Platform build could take 18 months or more |
| In August 2026, the Victorian government announced AUD 2 million in mRNA grants for research moving toward trials. | Adds discovery and preclinical demand in Victoria |
| In September 2026, Novotech agreed to acquire Adelaide-based Agilex Biolabs from a Healius subsidiary. | Completion subject to regulatory clearances |
| In October 2026, 360biolabs opened a NATA-accredited bioanalytical laboratory in North Ryde, Sydney. | Brings sample-critical testing closer to NSW trial sites |
Cytometry, mass spectrometry and GMP suites set capability
- Spectral flow cytometry measures many cell markers in one blood sample, which helps sponsors track immune responses to antibodies, vaccines and cell therapies in early trials.
- LC-MS and ligand-binding platforms measure drug levels and anti-drug antibodies with validated methods, which produces the pharmacokinetic data regulators expect from first-in-human studies.
- Small-scale GMP suites let development laboratories make clinical batches of topical, oral and injectable products, which shortens the step from formulation work to the first dose.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Specialist labs join global groups to win overseas sponsors
Competition is split between specialist bioanalytical laboratories that now sit inside global groups and smaller local firms that focus on formulation, safety or cytometry work. Agilex Biolabs in Adelaide is moving to Novotech, while 360biolabs operates in Melbourne, Brisbane and Sydney as part of BioAgilytix. Resolian runs a purpose-built Brisbane laboratory, and Crux Biolabs supplies spectral cytometry in Melbourne through its alliance with KCAS Bio. Eurofins Biopharma Product Testing Australia offers GMP microbiology, analytical and quality control testing, while IDT Australia and Formulytica compete in development, formulation and clinical supply. Rivals compete on NATA and GLP accreditation, assay range, turnaround for time-sensitive samples and links to overseas sites, which gives laboratories inside global networks an edge with United States and Asian sponsors.
Which laboratories serve drug developers in Australia?
| Company | Type | Role in the market |
|---|---|---|
| Agilex Biolabs | Specialist bioanalytical laboratory | Adelaide-based, being acquired by Novotech from Healius |
| 360biolabs | Specialist bioanalytical laboratory | BioAgilytix company with sites in Melbourne, Brisbane and Sydney |
| Eurofins Biopharma Product Testing Australia | GMP testing laboratory | Microbiology, analytical and QC testing in Dandenong South |
| IDT Australia | Development and manufacturing group | High-potency development and API scale-up in Boronia |
| Resolian | Bioanalytical laboratory | Purpose-built Brisbane laboratory with LC-MS and PCR suites |
| Crux Biolabs | Specialist cytometry laboratory | Bayswater site in alliance with KCAS Bio |
| Formulytica | Formulation development laboratory | Melbourne formulation, analytical and small-scale GMP work |
Early-phase strength keeps sponsors buying local lab work
Credence Research's view is that the Australia drug discovery and development laboratory services market will grow steadily because the country remains a first choice for early human studies and the tax offset keeps small sponsors spending. Bioanalytical services remain the largest value pool, while discovery sciences and later clinical support add the fastest growth. Laboratories that sit inside global networks should win more overseas sponsors, because they can follow a program into later trials. Workforce limits, slow approval reform and offshore competition will cap some gains.
Model built from trial, research spending and lab records
The report uses 2025 as the base year on a calendar basis, and market values come from the Credence Research model. That model draws on national research spending statistics, clinical trial sector data, government program releases, tax incentive rules and company releases on laboratory openings, contracts and acquisitions. Segment splits and state growth rates are Credence Research estimates, while state shares follow the client-defined split. Sources used are official statistics, government releases, trade press, company filings and company websites, and no interviews or surveys were used.
Later-phase support and discovery work carry growth to 2035
The Australia drug discovery and development laboratory services market is expected to reach USD 257.2 million by 2035, an 8.75% CAGR during 2026–2035, as early-phase studies keep arriving and laboratories add biologic assay capacity. Growth should be strongest in New South Wales while new Sydney space fills, while Victoria keeps the broadest mix of formulation and safety work. After 2030, later clinical support and discovery science should carry more of the value as sponsors keep Australian laboratories on contract. Faster approval reform would lift demand, while weaker biotech funding would slow it.
Frequently Asked Questions
How big is the Australia drug discovery and development laboratory services market?
Which service type leads outsourced laboratory spending in Australia?
Which state leads Australian laboratory spending?
How does the R&D tax incentive help sponsors?
Why are global groups buying Australian laboratories?
Which application grows fastest?
Who are the leading companies in this market?
What are the main challenges for Australian laboratories?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Service Type
- 1.2.1 Bioanalytical Services
- 1.2.2 Pharmacology and Safety Assessment
- 1.2.3 Analytical Chemistry and Formulation Development
- 1.2.4 Drug Discovery Sciences
- 1.3 By Customer Type
- 1.3.1 Biotechnology Sponsors
- 1.3.2 Pharmaceutical Sponsors
- 1.3.3 Academic and Public Research Sponsors
- 1.4 By Application
- 1.4.1 Discovery and Lead Optimisation
- 1.4.2 Preclinical Development
- 1.4.3 Early Clinical Laboratory Support
- 1.4.4 Later Clinical Laboratory Support
- 1.5 By Sales Channel
- 1.5.1 Direct Sponsor Contracting
- 1.5.2 Research Organisation Subcontracting
- 1.5.3 Global Laboratory Network Referrals
- 1.6 By State
- 1.6.1 New South Wales
- 1.6.2 Victoria
- 1.6.3 South Australia
- 1.6.4 Remaining States and Territories
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2025: USD 111.5 million → 2035: USD 257.2 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Historical Period: 2018-2025
- 2.6.2 Base Year: 2025
- 2.6.3 Forecast Period: 2025-2035
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2025
- 3.3 Forecast Market Size, 2035
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Australia Drug Discovery and Development Laboratory Services Market Trends and Developments
- 4.1 Historical Industry Development, 2018-2025
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Australia Drug Discovery and Development Laboratory Services Market Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis, 2018-2025
- 5.2 Demand Forecast, 2025-2035
- 5.3 Supply Chain Structure and Procurement Trends
- 5.4 Supply-Demand Gap and Bottlenecks
- 5.5 Import Dependence and Sourcing Structure
- 5.6 Regional Supply and Demand Concentration
Chapter 6 Australia Drug Discovery and Development Laboratory Services Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends, 2018-2025
- 6.3 Pricing Outlook, 2025-2035
- 6.4 Pricing by Product and Market Segment
- 6.5 Geographic Pricing Differences
- 6.6 Key Input, Energy, Labor and Logistics Costs
- 6.7 Contract Pricing and Purchasing Models
- 6.8 Pricing Sensitivity and Competitive Positioning
- 6.9 Price, Margin and Profitability Implications
Chapter 7 Australia Drug Discovery and Development Laboratory Services Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Australia Drug Discovery and Development Laboratory Services Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Australia Drug Discovery and Development Laboratory Services Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Data Protection, AI and Cybersecurity Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Australia Drug Discovery and Development Laboratory Services Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Australia Drug Discovery and Development Laboratory Services Market Outlook, 2025-2035
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2025: USD 111.5 million → 2035: USD 257.2 million)
- 11.1.2 Historical Market Size, 2018-2025
- 11.1.3 Base-Year Market Size, 2025
- 11.2 Market Forecast, 2025-2035
- 11.2.1 Revenue Forecast to 2035
- 11.2.2 CAGR and Year-on-Year Growth
- 11.2.3 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Australia Drug Discovery and Development Laboratory Services Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2025
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Service Type - Market Size and Forecast, 2025-2035
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size, 2018-2025
- 12.3.3 Revenue Forecast, 2025-2035
- 12.3.4 Base-Year Market Share, 2025
- 12.3.5 Segment CAGR and Growth Drivers
- 12.3.6 Subsegment Market Size and Forecast
- 12.3.6.1 Bioanalytical Services
- 12.3.6.2 Pharmacology and Safety Assessment
- 12.3.6.3 Analytical Chemistry and Formulation Development
- 12.3.6.4 Drug Discovery Sciences
- 12.3.7 Subsegment Pricing and Adoption Trends
- 12.3.8 Leading Suppliers and Competition
- 12.3.9 Regional Demand and Opportunities
- 12.4 By Customer Type - Market Size and Forecast, 2025-2035
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size, 2018-2025
- 12.4.3 Revenue Forecast, 2025-2035
- 12.4.4 Base-Year Market Share, 2025
- 12.4.5 Segment CAGR and Growth Drivers
- 12.4.6 Subsegment Market Size and Forecast
- 12.4.6.1 Biotechnology Sponsors
- 12.4.6.2 Pharmaceutical Sponsors
- 12.4.6.3 Academic and Public Research Sponsors
- 12.4.7 Subsegment Pricing and Adoption Trends
- 12.4.8 Leading Suppliers and Competition
- 12.4.9 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2025-2035
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size, 2018-2025
- 12.5.3 Revenue Forecast, 2025-2035
- 12.5.4 Base-Year Market Share, 2025
- 12.5.5 Segment CAGR and Growth Drivers
- 12.5.6 Subsegment Market Size and Forecast
- 12.5.6.1 Discovery and Lead Optimisation
- 12.5.6.2 Preclinical Development
- 12.5.6.3 Early Clinical Laboratory Support
- 12.5.6.4 Later Clinical Laboratory Support
- 12.5.7 Subsegment Pricing and Adoption Trends
- 12.5.8 Leading Suppliers and Competition
- 12.5.9 Regional Demand and Opportunities
- 12.6 By Sales Channel - Market Size and Forecast, 2025-2035
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size, 2018-2025
- 12.6.3 Revenue Forecast, 2025-2035
- 12.6.4 Base-Year Market Share, 2025
- 12.6.5 Segment CAGR and Growth Drivers
- 12.6.6 Subsegment Market Size and Forecast
- 12.6.6.1 Direct Sponsor Contracting
- 12.6.6.2 Research Organisation Subcontracting
- 12.6.6.3 Global Laboratory Network Referrals
- 12.6.7 Subsegment Pricing and Adoption Trends
- 12.6.8 Leading Suppliers and Competition
- 12.6.9 Regional Demand and Opportunities
- 12.7 By State - Market Size and Forecast, 2025-2035
- 12.7.1 Segment Definition and Scope
- 12.7.2 Historical Market Size, 2018-2025
- 12.7.3 Revenue Forecast, 2025-2035
- 12.7.4 Base-Year Market Share, 2025
- 12.7.5 Segment CAGR and Growth Drivers
- 12.7.6 Subsegment Market Size and Forecast
- 12.7.6.1 New South Wales
- 12.7.6.2 Victoria
- 12.7.6.3 South Australia
- 12.7.6.4 Remaining States and Territories
- 12.7.7 Subsegment Pricing and Adoption Trends
- 12.7.8 Leading Suppliers and Competition
- 12.7.9 Regional Demand and Opportunities
- 12.8 Segment Growth Comparison
- 12.9 Segment Attractiveness and Priority Matrix
Chapter 13 Australia Drug Discovery and Development Laboratory Services End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Australia Drug Discovery and Development Laboratory Services Geographic Market Outlook, 2025-2035
- 14.1 Domestic Market Distribution and Demand Clusters
- 14.2 State- or Province-Wise Market Size and Forecast, 2025-2035
- 14.3 City and Metropolitan Market Outlook
- 14.4 Industrial, Manufacturing and Commercial Clusters
- 14.5 Geographic Concentration of Key End Users
- 14.6 Local Pricing and Purchasing Differences
- 14.7 Domestic Production Facilities and Capacity Map
- 14.8 Local Infrastructure and Project Pipeline
- 14.9 State-Level Policy and Incentive Differences
- 14.10 Subnational Investment Hotspots and Opportunities
- 14.11 Distribution and Logistics Networks
- 14.12 Domestic Competitive Footprint
Chapter 15 Australia Drug Discovery and Development Laboratory Services Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Energy Efficiency and Resource Management
- 15.7 Sustainability, Recycling and Circularity
- 15.8 Technology Roadmap, 2025-2035
- 15.9 Risks of Obsolescence and Technology Substitution
Chapter 16 Australia Drug Discovery and Development Laboratory Services Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2025
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2025-2035
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Agilex Biolabs
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Financial Performance and Investment
- 18.2.6 Market Share and Competitive Position
- 18.2.7 Technology and Innovation Capabilities
- 18.2.8 Strategic Alliances or Partnerships
- 18.2.9 Recent Developments
- 18.2.10 Growth Strategy and Outlook
- 18.3 360biolabs
- 18.4 Eurofins Biopharma Product Testing Australia
- 18.5 IDT Australia
- 18.6 Resolian
- 18.7 Crux Biolabs
- 18.8 Formulytica
- 18.9 ICP Firefly
- 18.10 Cardinal Bioresearch
- 18.11 Attentive Science Australia
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

