
Market Overview
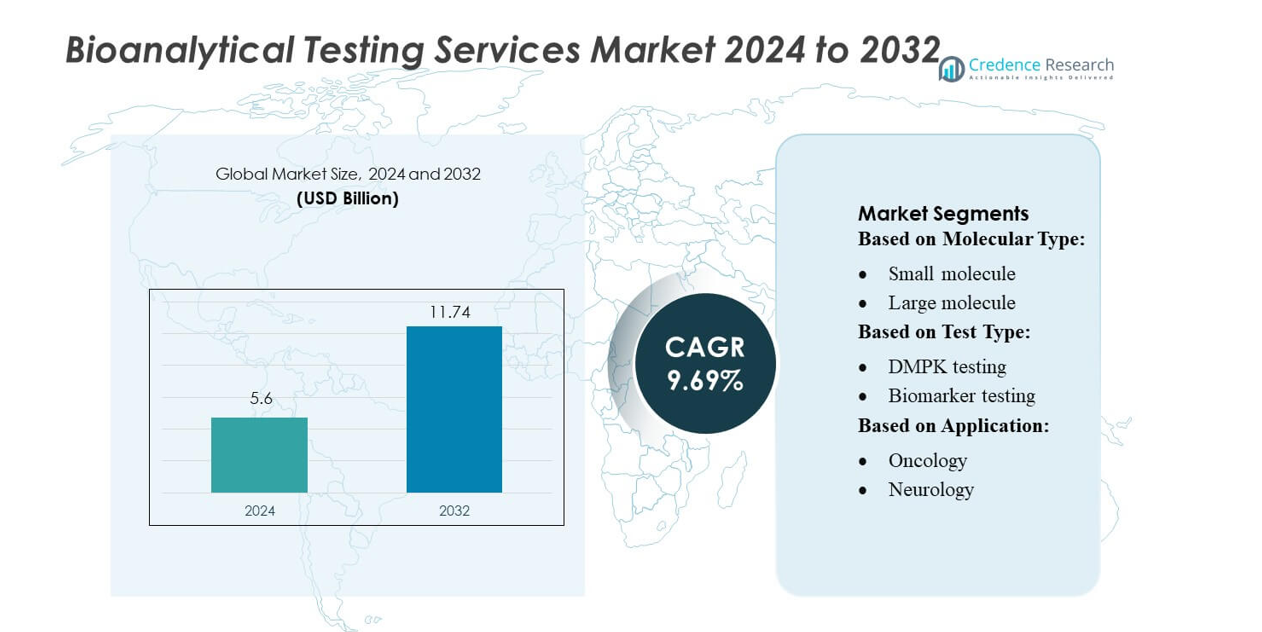
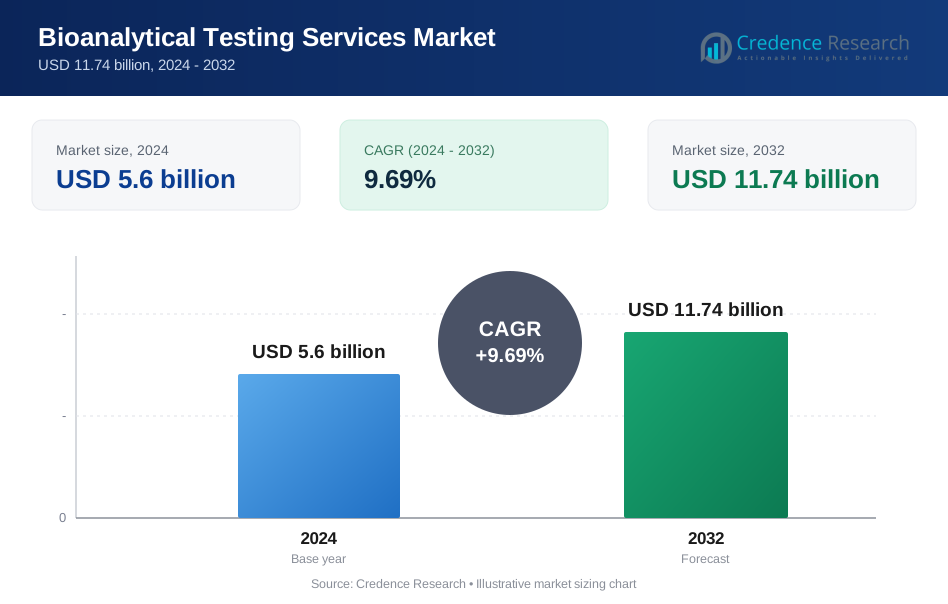
Bioanalytical Testing Services Market size was valued USD 5.6 billion in 2024 and is anticipated to reach USD 11.74 billion by 2032, at a CAGR of 9.69% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Bioanalytical Testing Services Market Size 2024 | USD 5.6 billion |
| Bioanalytical Testing Services Market, CAGR | 9.69% |
| Bioanalytical Testing Services Market Size 2032 | USD 11.74 billion |
The Bioanalytical Testing Services Market is shaped by specialized contract research organizations and global laboratories that provide advanced pharmacokinetic, immunogenicity, biomarker, and virology testing solutions. Leading providers include well-established scientific service companies recognized for their GLP/GCP-compliant infrastructure, high-sensitivity LC-MS/MS platforms, and automation-driven laboratory workflows that support large clinical pipelines across biologics and small-molecule programs. These players compete by expanding assay development capabilities, enhancing data integrity systems, and strengthening global delivery networks. North America leads the market with more than 40% market share, supported by strong biopharmaceutical R&D activity, extensive clinical trials, and high adoption of outsourced analytical services.
Market Insights
- The Bioanalytical Testing Services Market reached USD 5.6 billion in 2024 and will grow to USD 11.74 billion by 2032 at a CAGR of 9.69%, driven by rising biologics development and increasing adoption of outsourced analytical support.
- Strong demand for pharmacokinetic, immunogenicity, biomarker, and virology testing continues to accelerate market expansion, supported by high clinical trial volume across oncology, infectious diseases, and neurology.
- Competitive activity intensifies as global CROs enhance GLP/GCP-compliant facilities, integrate high-sensitivity LC-MS/MS platforms, and adopt automation to improve efficiency, data integrity, and turnaround times.
- The market faces restraints linked to complex assay validation requirements, evolving regulatory expectations, and limited availability of specialized talent for large-molecule and cell-based analytical workflows.
- North America leads with over 40% share, followed by Europe at approximately 28%, while small molecules remain the dominant segment with over 55% share, supported by extensive generics pipelines and strong demand for bioequivalence testing.
Market Segmentation Analysis:
By Molecule Type
Small molecules hold the dominant position in the Bioanalytical Testing Services Market, accounting for over 55% of the overall share due to their extensive use in generics, novel therapeutics, and complex combination formulations. Their well-established analytical pathways, shorter development cycles, and high demand for pharmacokinetic and bioequivalence studies continue to strengthen their leadership. Large molecules exhibit steady growth as biologics, cell therapies, and recombinant proteins expand in clinical pipelines. This category benefits from rising investments in antibody engineering and the growing need for sensitive assays to validate therapeutic safety and performance.
- For instance, Qualitest’s proprietary AI-led platform Qualisense supports rapid validation of complex software systems and was reported to accelerate time-to-release by approximately 6× in relevant projects.
By Test Type
DMPK testing emerges as the leading test category, capturing around 30% market share, supported by increasing requirements for absorption, distribution, metabolism, and excretion (ADME) profiling throughout early-stage drug development. The segment benefits from the rising complexity of therapeutic candidates and the need to predict in-vivo behavior with higher accuracy. Biomarker testing and immunogenicity testing follow due to strong adoption in precision medicine and biologics development. Virology testing-including in-vivo and in-vitro-continues to expand with escalating infectious disease research, vaccine development, and regulatory focus on viral safety assessment across biopharmaceutical manufacturing.
- For instance, Accenture worked with a global biopharmaceutical firm to implement its Digital Thread for Life Sciences framework: this reduced the technology-transfer cycle in manufacturing from 12 weeks to 7–8 weeks.
By Application
Oncology remains the dominant application area, contributing over 40% of the market share as cancer therapeutics increasingly rely on bioanalytical validation for targeted therapies, immunotherapies, and biomarker-driven drug development. Extensive oncology pipelines, high clinical trial activity, and the demand for companion diagnostics reinforce this leadership. Infectious diseases form the next major segment due to ongoing antiviral, vaccine, and biologics development. Neurology, cardiology, and gastroenterology applications continue to gain momentum as complex diseases require specialized assays to characterize therapeutic efficacy, safety profiles, and long-term treatment responses.
Key Growth Drivers
Expansion of Biologics and Advanced Therapeutics Pipelines
The Bioanalytical Testing Services Market grows strongly as biopharmaceutical companies accelerate investments in monoclonal antibodies, gene therapies, cell-based treatments, and recombinant proteins. These complex modalities require highly sensitive assays for pharmacokinetics, immunogenicity, and biomarker quantification, driving outsourcing to specialized laboratories with advanced platforms such as LC-MS/MS and ligand-binding technologies. Increasing regulatory scrutiny on biologic safety, rising global submissions, and expanding clinical trials strengthen the demand for validated analytical methods, ensuring accurate characterization of therapy performance across development phases.
- For instance, IBM Consulting’s generative-AI initiatives in life sciences leverage its consultancy arm's expertise and technology. The company has developed AI-automation pipelines for specific workflows, such as reducing manual labor in adverse event narrative generation by approximately 50%.
Rising Clinical Trial Volume and Outsourcing Momentum
Growing clinical trial activity across oncology, infectious diseases, neurology, and rare disorders fuels significant demand for comprehensive bioanalytical testing support. Pharmaceutical companies increasingly outsource these functions to CROs to reduce internal laboratory costs, accelerate timelines, and access specialized instrumentation. Outsourcing also improves scalability for global multicenter studies requiring large sample processing and harmonized assay protocols. The shift toward lean internal R&D structures and higher dependence on external expertise accelerates adoption of end-to-end bioanalytical solutions, strengthening market growth across preclinical and clinical stages.
- For instance, DXC’s Life Sciences Software Solutions and AI Platform reports that its regulatory-automation suite has supported 76,000+ regulatory submissions and spans 250,000 global users in pharmaceutical workflows.
Increasing Regulatory Emphasis on Standardized Analytical Validation
Regulatory authorities mandate stringent analytical validation to ensure therapeutic safety, reproducibility, and clinical relevance, reinforcing the importance of robust bioanalytical testing frameworks. Agencies such as the FDA and EMA continue updating guidance for ligand-binding assays, biomarkers, and PK/PD methodologies, driving companies to adopt high-compliance environments and standardized workflows. Growing focus on biosimilar approval pathways, trace impurity detection, and viral safety assessments also expands demand for specialized testing capabilities. These tightening requirements encourage pharmaceutical developers to rely on expert service providers with established GLP-compliant infrastructure.
Key Trends & Opportunities
Adoption of High-Sensitivity and Automation-Driven Platforms
The market sees rapid integration of high-sensitivity analytical technologies, including next-generation LC-MS/MS, multiplex immunoassays, and automated sample preparation systems. Automation reduces human error, improves precision, and accelerates turnaround times for large clinical trial cohorts. Growing use of ultra-high sensitivity detection supports complex biologics, low-concentration biomarkers, and micro-sampling-based clinical designs. Providers adopting robotics, digital data management, and integrated laboratory information systems (LIMS) gain competitive advantage as clients prioritize reliability, scalability, and regulatory-ready workflows.
- For instance, Atos Polaris AI Platform which offers pre-built autonomous AI agents that can reduce development effort by 40-50 %, QA lead-time by 50-60 %, and contract-review cycle time by 30-40 %.
Rising Demand for Biomarker-Centric and Precision Medicine Studies
Biomarker-driven clinical development creates major opportunities, particularly in oncology, neurology, and immunology. Pharmaceutical companies increasingly require multi-analyte panels, genomic markers, and longitudinal biomarker profiling to support patient stratification and therapeutic response monitoring. This trend accelerates growth in bespoke assay development and validation services. The shift toward precision medicine strengthens collaborations between CROs and biopharma companies to create specialized biomarker platforms capable of supporting early detection, mechanism-of-action studies, and adaptive trial designs, enhancing scientific and commercial value.
- For instance, Charles River Laboratories expanded its biomarker discovery capabilities through the acquisition of SAMDI Tech, enabling high-throughput, label-free mass spectrometry workflows capable of screening over 100,000 compounds per day using their proprietary SAMDI® MS platform.
Expansion of Virology and Vaccine Development Capabilities
Growing global focus on antiviral therapeutics, pandemic preparedness, and vaccine R&D drives continuous expansion of virology testing capabilities. In-vitro viral assays, viral load quantification, neutralization studies, and serological testing gain higher demand across biopharma pipelines. Opportunities grow for providers offering high-biosafety-level facilities, automated viral analytics, and rapid assay development expertise. The need for viral clearance validation in biologics manufacturing further strengthens demand, positioning virology as one of the fastest-evolving segments within bioanalytical outsourcing.
Key Challenges
High Complexity of Large Molecule and Cell-Based Assays
Bioanalytical testing for large molecules, cell therapies, and gene-based treatments presents significant methodological challenges due to structural complexity, stability issues, and matrix interference. Developing sensitive assays for immunogenicity, bioactivity, and viral vector characterization requires specialized skills, advanced platforms, and extensive validation timelines. Variability in biomarker expression across patient populations further complicates assay standardization. These technical constraints increase development costs and prolong clinical timelines, limiting some organizations’ ability to meet accelerated regulatory and commercialization targets.
Stringent Compliance Burden and Evolving Regulatory Expectations
Service providers face challenges in maintaining GLP/GCP compliance as regulatory bodies introduce continuous updates related to assay validation, biomarker qualification, and bioanalytical data integrity. Meeting these requirements demands significant investment in documentation, training, instrument calibration, and audit readiness. Global studies add complexity due to differing regional regulatory expectations for sample handling, reporting formats, and acceptance criteria. These rising compliance obligations strain smaller laboratories and increase operational overhead, creating barriers for rapid scale-up and competitive differentiation.
Regional Analysis
North America
North America leads the Bioanalytical Testing Services Market with over 40% market share, driven by a mature biopharmaceutical ecosystem, advanced clinical trial activity, and strong regulatory emphasis on validated analytical processes. The region benefits from extensive investments in biologics, biosimilars, and gene therapies, which require high-precision pharmacokinetic, immunogenicity, and biomarker testing. Major CROs and specialized laboratories maintain large GLP-compliant facilities and integrate high-sensitivity LC-MS/MS platforms, automated workflows, and digital data systems. Supportive FDA guidelines, growing outsourcing preference, and a robust pipeline of oncology and rare disease trials continue to reinforce regional leadership.
Europe
Europe holds around 28% market share, supported by strong pharmaceutical R&D clusters across Germany, the U.K., France, and Switzerland. The region benefits from rising adoption of biologics, advanced therapeutic medicinal products, and complex biosimilar programs that require extensive analytical validation and long-term stability studies. EMA’s evolving guidance on biomarkers and immunogenicity strengthens the need for standardized workflows and high-quality bioanalytical support. Growth is further driven by expanding clinical trials in oncology, neurology, and infectious diseases. Increasing collaboration between CROs and academic research centers accelerates development of next-generation testing capabilities across the European market.
Asia-Pacific
Asia-Pacific accounts for nearly 22% market share and represents the fastest-growing region due to expanding pharmaceutical manufacturing, rising biologics production, and increasing multinational clinical trial activity. China, India, South Korea, and Japan invest heavily in bioanalytical infrastructure, including high-throughput LC-MS/MS systems, immunoassay platforms, and virology testing facilities. Cost-effective outsourcing, rapid regulatory modernization, and growing domestic biotech pipelines strengthen the region’s competitive position. Increasing investment from global CROs and partnerships with regional innovators enhance service capacity, particularly across oncology, infectious disease, and biosimilar development programs, driving sustained market acceleration.
Latin America
Latin America contributes approximately 6% market share, supported by rising pharmaceutical outsourcing and expanding clinical trial networks in Brazil, Mexico, and Argentina. The region experiences growing demand for bioanalytical testing in infectious diseases, oncology, and metabolic disorders, driven by increasing therapeutic innovation and public health requirements. Providers enhance service capabilities by adopting validated immunoassays, biomarker panels, and pharmacokinetic testing frameworks. Regulatory harmonization efforts and collaborations with global CROs improve compliance standards and scientific quality. Despite infrastructure constraints, expanding local biotech activity and interest from multinational sponsors drive steady adoption of specialized testing services.
Middle East & Africa
The Middle East & Africa region holds around 4% market share, reflecting a developing but steadily expanding market supported by investments in healthcare modernization and clinical research capabilities. Countries such as the UAE, Saudi Arabia, and South Africa foster growth through improved laboratory infrastructure, rising clinical trial participation, and increasing availability of GLP-compliant analytical services. Demand for bioanalytical testing is driven by expanding infectious disease research and growing interest in biologics and vaccines. Although capacity remains limited compared with major regions, international partnerships and government-backed R&D initiatives support gradual market advancement.
Market Segmentations:
By Molecular Type:
- Small molecule
- Large molecule
By Test Type:
- DMPK testing
- Biomarker testing
By Application:
- Oncology
- Neurology
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The Bioanalytical Testing Services Market features a competitive landscape shaped by global technology and consulting leaders such as Infosys Limited, Capgemini, Qualitest Group, Accenture, Deloitte Touche Tohmatsu Limited, DeviQA Solutions, IBM Corporation, DXC Technology Company, TATA Consultancy Services Limited, and Atos SE. The Bioanalytical Testing Services Market is defined by a growing focus on scientific precision, regulatory compliance, and digital transformation across laboratory operations. Leading service providers differentiate themselves by expanding high-sensitivity analytical platforms, strengthening GLP/GCP infrastructure, and integrating automation to support large-scale clinical trial workflows. The market continues to shift toward specialized capabilities in pharmacokinetics, immunogenicity, biomarker quantification, and virology testing, driven by the increasing complexity of biologics and advanced therapies. Companies invest heavily in data integrity systems, workflow digitization, and AI-enabled analytical tools to improve accuracy, accelerate turnaround times, and support multi-regional submissions. Partnerships between CROs, biopharmaceutical innovators, and technology vendors further enhance operational scalability and global service delivery.
Key Player Analysis
- Infosys Limited
- Capgemini
- Qualitest Group
- Accenture
- Deloitte Touche Tohmatsu Limited
- DeviQA Solutions
- IBM Corporation
- DXC Technology Company
- TATA Consultancy Services Limited
- Atos SE
Recent Developments
- In June 2024, SGS SA announced the addition of new stability studies, including sample storage facilities, to its biopharmaceutical services at its Birsfelden laboratory in Switzerland. This expansion broadened the company's service portfolio and enhanced its customer reach in the Swiss market, providing critical services for biopharmaceutical products.
- In January 2024, Frontage Laboratories completed the acquisition of Accelera S.r.l.'s Bioanalytical and Drug Metabolism & Pharmacokinetics (DMPK) businesses. This strategic move was carried out through Frontage's wholly-owned subsidiary, Frontage Europe S.r.l., which expanded the company’s market presence.
- In January 2024, Capgemini SE and Orange, introduced its "trusted cloud" services. This platform aims to provide the specific cloud needs of the French State, public agencies, hospitals, regional authorities, Vital Importance Operators (OIVs), and Essential Service Operators (OSEs), enabling them to use Microsoft 365 and Microsoft Azure services within a sovereign and highly secure environment
Report Coverage
The research report offers an in-depth analysis based on Molecular Type, Test Type, Application and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will expand steadily as biologics, cell therapies, and gene therapies increase in global development pipelines.
- Demand for high-sensitivity assays will rise with growing emphasis on precision medicine and biomarker-driven clinical designs.
- Automation and digital laboratory systems will become central to improving data integrity, efficiency, and regulatory readiness.
- Advanced LC-MS/MS platforms and multiplex immunoassays will gain broader adoption across complex analytical workflows.
- Virology and serology testing capacity will expand as vaccine development and antiviral research continue to strengthen.
- Global CRO collaborations will intensify to support multicenter trials and harmonized assay validation.
- Outsourcing momentum will accelerate as biopharma companies streamline internal R&D structures.
- Data analytics, AI tools, and machine learning–driven interpretation models will enhance decision-making in PK/PD studies.
- Regulatory expectations for standardized assay validation will shape quality frameworks and investment priorities.
- Emerging markets will strengthen their position as regional bioanalytical hubs with improved infrastructure and specialized capabilities.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Expansion of Biologics and Advanced Therapeutics Pipelines
The rapid growth in monoclonal antibodies, gene therapies, and cell-based treatments is driving demand for highly sensitive and specialized bioanalytical testing services, as these complex modalities require advanced assay development and validation for regulatory approval.
Rising Clinical Trial Volume and Outsourcing Momentum
Increasing numbers of clinical trials, especially in oncology and infectious diseases, are prompting pharmaceutical companies to outsource bioanalytical testing to CROs, enabling faster timelines, cost efficiency, and access to specialized instrumentation and expertise.
Increasing Regulatory Emphasis on Standardized Analytical Validation
Stricter regulatory requirements from agencies like the FDA and EMA for assay validation, data integrity, and biosimilar approval are compelling companies to adopt robust, GLP/GCP-compliant testing frameworks, boosting demand for expert service providers.
Adoption of High-Sensitivity and Automation-Driven Platforms
The integration of next-generation LC-MS/MS, multiplex immunoassays, and laboratory automation is enhancing precision, throughput, and turnaround times, making advanced bioanalytical testing more attractive for large-scale and complex clinical studies.
Rising Demand for Biomarker-Centric and Precision Medicine Studies
The shift toward precision medicine and biomarker-driven drug development, particularly in oncology and neurology, is increasing the need for bespoke assay development, multi-analyte panels, and longitudinal biomarker profiling, fueling market growth.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Bioanalytical Testing Services Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Bioanalytical Testing Services Market projected to grow between 2025 and 2032?
What are the key drivers for the growth of the bioanalytical testing services market?
What are the primary factors fueling the growth of the Bioanalytical Testing Services Market?
Who are the leading companies in the Bioanalytical Testing Services Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Test Type
- 1.2.1 DMPK testing
- 1.2.2 Biomarker testing
- 1.2.3 Immunogenicity testing
- 1.2.4 Virology testing
- 1.3 By Application
- 1.3.1 Oncology
- 1.3.2 Infectious Diseases
- 1.3.3 Neurology
- 1.3.4 Cardiology
- 1.3.5 Gastroenterology
- 1.4 By Molecular Type
- 1.4.1 Small molecule
- 1.4.2 Large molecule
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 5.6 billion → 2032: USD 11.74 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Bioanalytical Testing Services Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Bioanalytical Testing Services Market Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Supply Chain Structure and Procurement Trends
- 5.4 Supply-Demand Gap and Bottlenecks
- 5.5 Import Dependence and Sourcing Structure
- 5.6 Regional Supply and Demand Concentration
Chapter 6 Global Bioanalytical Testing Services Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Pricing by Product and Market Segment
- 6.5 Geographic Pricing Differences
- 6.6 Key Input, Energy, Labor and Logistics Costs
- 6.7 Contract Pricing and Purchasing Models
- 6.8 Pricing Sensitivity and Competitive Positioning
- 6.9 Price, Margin and Profitability Implications
Chapter 7 Global Bioanalytical Testing Services Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Bioanalytical Testing Services Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Bioanalytical Testing Services Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Data Protection, AI and Cybersecurity Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Bioanalytical Testing Services Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Bioanalytical Testing Services Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 5.6 billion → 2032: USD 11.74 billion)
- 11.1.2 Historical Market Size
- 11.1.3 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 CAGR and Year-on-Year Growth
- 11.2.3 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Bioanalytical Testing Services Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Test Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Base-Year Market Share, 2024
- 12.3.5 Segment CAGR and Growth Drivers
- 12.3.6 Subsegment Market Size and Forecast
- 12.3.6.1 DMPK testing
- 12.3.6.2 Biomarker testing
- 12.3.6.3 Immunogenicity testing
- 12.3.6.4 Virology testing
- 12.3.7 Subsegment Pricing and Adoption Trends
- 12.3.8 Leading Suppliers and Competition
- 12.3.9 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Base-Year Market Share, 2024
- 12.4.5 Segment CAGR and Growth Drivers
- 12.4.6 Subsegment Market Size and Forecast
- 12.4.6.1 Oncology
- 12.4.6.2 Infectious Diseases
- 12.4.6.3 Neurology
- 12.4.6.4 Cardiology
- 12.4.6.5 Gastroenterology
- 12.4.7 Subsegment Pricing and Adoption Trends
- 12.4.8 Leading Suppliers and Competition
- 12.4.9 Regional Demand and Opportunities
- 12.5 By Molecular Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Base-Year Market Share, 2024
- 12.5.5 Segment CAGR and Growth Drivers
- 12.5.6 Subsegment Market Size and Forecast
- 12.5.6.1 Small molecule
- 12.5.6.2 Large molecule
- 12.5.7 Subsegment Pricing and Adoption Trends
- 12.5.8 Leading Suppliers and Competition
- 12.5.9 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Bioanalytical Testing Services End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Bioanalytical Testing Services Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Bioanalytical Testing Services Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Energy Efficiency and Resource Management
- 15.7 Sustainability, Recycling and Circularity
- 15.8 Technology Roadmap, 2024-2032
- 15.9 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Bioanalytical Testing Services Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 SGS SA
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Financial Performance and Investment
- 18.2.6 Market Share and Competitive Position
- 18.2.7 Technology and Innovation Capabilities
- 18.2.8 Strategic Alliances or Partnerships
- 18.2.9 Recent Developments
- 18.2.10 Growth Strategy and Outlook
- 18.3 Frontage Laboratories
- 18.4 Charles River Laboratories
- 18.5 Labcorp Drug Development
- 18.6 Eurofins Scientific
- 18.7 Syneos Health
- 18.8 ICON plc
- 18.9 Covance
- 18.10 PPD (Thermo Fisher Scientific)
- 18.11 WuXi AppTec
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

