
Asia-Pacific Flow Cytometry Market Overview:
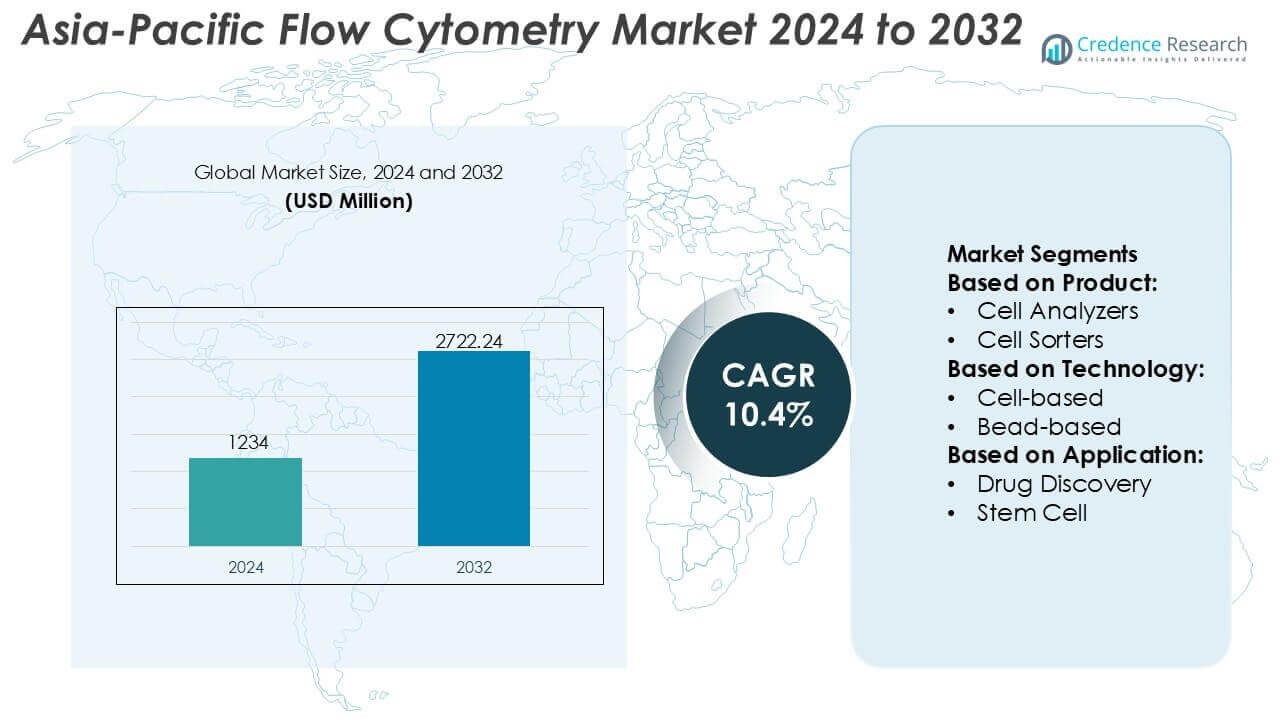
Asia-Pacific Flow Cytometry Market size was valued USD 1234 million in 2024 and is anticipated to reach USD 2722.24 million by 2032, at a CAGR of 10.4% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Asia-Pacific Flow Cytometry Market Size 2024 | USD 1234 million |
| Asia-Pacific Flow Cytometry Market, CAGR | 10.4% |
| Asia-Pacific Flow Cytometry Market Size 2032 | USD 2722.24 million |
Asia-Pacific Flow Cytometry Market Insights
- Market growth is driven by expanding life science research, rising biopharmaceutical development, and increasing clinical adoption for immunology, oncology, and hematology diagnostics across academic institutes and hospitals.
- Key trends include rising adoption of high-parameter and spectral flow cytometry, greater integration of automation and advanced software analytics, and increasing demand for reagents and consumables, which hold the largest segment share due to recurring usage.
- Competitive dynamics remain strong as global and regional players focus on advanced instrumentation, scalable platforms, regional manufacturing expansion, and localized service support to strengthen market penetration.
- Regionally, China leads the Asia-Pacific market with an exact share of 41%, supported by strong government funding, while research applications dominate the application segment due to extensive use in cell biology and immunology studies.
Asia-Pacific Flow Cytometry Market Segmentation Analysis:
By Product
In the Asia-Pacific Flow Cytometry Market, instruments represent the dominant product segment, accounting for approximately 46% market share, driven by sustained investments in laboratory infrastructure and rising adoption of advanced analytical platforms across research institutes and clinical laboratories. Within instruments, cell analyzers lead due to their widespread use in immunophenotyping, hematology, and routine diagnostics, supported by high throughput and standardized workflows. Reagents and consumables form a critical supporting segment, benefiting from recurring demand tied to instrument utilization and expanding test volumes. Software and services gain traction as laboratories prioritize data analysis efficiency, system maintenance, and workflow optimization to maximize instrument performance.
- For instance, Stratedigm, Inc. has strengthened instrument adoption through its S1000EON flow cytometer (and upgradeable legacy S1000EXi units), which supports up to 6 spatially separated lasers and 30 independent detection parameters.
By Technology
Cell-based technology dominates the Asia-Pacific Flow Cytometry Market with an estimated 71% market share, supported by its broad applicability in cellular analysis, immune profiling, and disease characterization. This technology enables multiparametric evaluation of individual cells, making it indispensable for both research and clinical workflows. Strong adoption is driven by expanding life science research, rising prevalence of chronic and infectious diseases, and increasing use of cell-based assays in translational studies. Bead-based technology, while smaller in share, continues to grow steadily due to its suitability for multiplex assays, cytokine analysis, and high-sensitivity protein detection in pharmaceutical and academic settings.
- For instance, Miltenyi Biotec’s MACSQuant X Analyzer is engineered for high-throughput screening and typically utilizes 3 spatially separated lasers (405 nm, 488 nm, and 640 nm) to support 10 optical parameters (8 fluorescence channels plus FSC and SSC).
By Application
Research applications hold the leading share of approximately 52% in the Asia-Pacific Flow Cytometry Market, driven by strong funding for academic research, expanding cell biology studies, and increasing focus on immunology and oncology research. Universities and research institutes rely heavily on flow cytometry for cell characterization, functional assays, and biomarker discovery. Pharmaceutical and drug discovery applications follow closely, supported by growing biopharmaceutical pipelines and the use of flow cytometry in target validation, toxicity assessment, and mechanism-of-action studies. Rising collaboration between academia and industry further strengthens application demand across the region.
Key Growth Drivers
Expanding Life Science and Clinical Research Infrastructure
Rapid expansion of life science research facilities and clinical laboratories across Asia-Pacific strongly drives demand for flow cytometry systems. Governments and academic institutions increase investments in biomedical research, immunology, oncology, and infectious disease studies, all of which rely heavily on cellular analysis. The growing number of well-equipped universities, contract research organizations, and diagnostic centers accelerates instrument installation and reagent consumption. Improved access to advanced laboratory infrastructure in countries such as China, India, Japan, and South Korea further supports routine and high-end flow cytometry adoption.
- For instance, Agilent Technologies’ NovoCyte Penteon Flow Cytometer integrates 5 spatially separated lasers (349 nm UV, 405 nm, 488 nm, 561 nm, and 637 nm) and supports up to 30 simultaneous detection parameters.
Rising Burden of Chronic and Infectious Diseases
The increasing prevalence of cancer, autoimmune disorders, and infectious diseases across Asia-Pacific significantly fuels flow cytometry utilization. Clinical and translational research increasingly depends on flow cytometry for immune profiling, disease monitoring, and biomarker identification. Hospitals and diagnostic laboratories integrate flow cytometry into hematology and immunophenotyping workflows to support early diagnosis and treatment monitoring. This growing clinical relevance strengthens demand for reliable analyzers, standardized reagents, and automated data analysis tools across both public and private healthcare systems.
- For instance, Cytek Biosciences’ Aurora spectral flow cytometer, as detailed in company technical documentation, employs up to 5 excitation lasers (355 nm, 405 nm, 488 nm, 561 nm, and 640 nm) and captures emitted light across 64 continuous detection channels, spanning a spectral range of approximately 365–829 nm.
Growth of Biopharmaceutical and Cell Therapy Development
The expanding biopharmaceutical sector in Asia-Pacific acts as a major growth driver for flow cytometry adoption. Drug developers increasingly use flow cytometry in target validation, mechanism-of-action studies, and quality control during biologics and cell therapy development. Rising activity in monoclonal antibodies, vaccines, and cell-based therapies increases the need for high-throughput, multiparametric analysis. Strong growth of local biopharma manufacturing hubs and increased outsourcing to regional CROs further support sustained demand for advanced flow cytometry platforms.
Key Trends & Opportunities
Integration of Automation, AI, and Advanced Data Analytics
Automation and artificial intelligence integration represent a key trend shaping the Asia-Pacific Flow Cytometry Market. Laboratories increasingly adopt automated sample preparation, standardized workflows, and AI-driven data analysis to reduce manual errors and improve reproducibility. Advanced software platforms enable faster interpretation of complex multiparametric datasets, supporting high-throughput research and clinical decision-making. This trend creates opportunities for vendors offering intelligent software, cloud-enabled data management, and end-to-end workflow solutions tailored to high-volume laboratories.
- For instance, Apogee Flow Systems’ A60-Micro PLUS is a high-speed cytometer optimized for extreme small-particle applications, such as extracellular vesicles, virions, and nanoparticles. It can be configured with up to 4 lasers and supports up to 12 simultaneous detection parameters (9 fluorescence and 3 light scatter detectors), offering the exceptional sensitivity required to resolve bionanoparticles down to approximately 80 nm.
Rising Adoption in Emerging Asia-Pacific Markets
Emerging economies across Southeast Asia and South Asia present strong growth opportunities as healthcare access and research capabilities improve. Countries such as Vietnam, Indonesia, and the Philippines expand diagnostic capacity and academic research funding, increasing demand for mid-range and compact flow cytometry systems. Growing awareness of advanced diagnostic tools among clinicians and researchers supports market penetration. Vendors focusing on cost-effective instruments, local service support, and training programs can capture long-term growth in these underpenetrated markets.
- For instance, Thermo Fisher Scientific’s Attune NxT Flow Cytometer, according to company technical specifications, uses acoustic focusing technology to achieve sample interrogation at up to 35,000 cells per second while maintaining consistent signal resolution.
Key Challenges
High Capital Costs and Operational Complexity
High acquisition costs of flow cytometry instruments and ongoing expenses for reagents, maintenance, and skilled personnel pose a significant challenge in Asia-Pacific. Smaller laboratories and hospitals often face budget constraints that limit adoption of advanced systems. In addition, complex operation, calibration, and data interpretation require specialized training, increasing operational burden. These factors slow adoption in resource-limited settings and create reliance on centralized laboratories, restricting broader market penetration.
Shortage of Skilled Professionals and Standardization Gaps
Limited availability of trained cytometrists and inconsistencies in standard operating procedures challenge effective utilization of flow cytometry systems. Variability in sample preparation, data acquisition, and analysis affects result reproducibility across laboratories. In emerging markets, insufficient technical expertise and training infrastructure further constrain adoption. Addressing this challenge requires stronger training programs, standardized protocols, and user-friendly platforms to ensure consistent performance and reliable outcomes across diverse healthcare and research environments.
Regional Analysis
North America
North America holds a leading position in the global flow cytometry market with an estimated market share of around 38%, supported by strong biomedical research funding, advanced healthcare infrastructure, and early adoption of high-end analytical technologies. The United States drives regional dominance due to extensive use of flow cytometry in oncology research, immunology, and clinical diagnostics. High concentration of biopharmaceutical companies and contract research organizations sustains demand for advanced cell analyzers, sorters, and reagents. Continuous integration of automation and data analytics further strengthens North America’s leadership in high-throughput and multiparametric flow cytometry applications.
Europe
Europe accounts for approximately 27% market share in the flow cytometry market, driven by strong academic research networks, established pharmaceutical industries, and supportive regulatory frameworks. Countries such as Germany, the United Kingdom, and France lead adoption due to significant investments in life sciences, translational research, and clinical diagnostics. Flow cytometry is widely used across immunology, hematology, and vaccine research programs. The region benefits from collaborative research initiatives and standardized laboratory practices, which enhance instrument utilization. Growing focus on precision medicine and cell-based therapies continues to support steady demand across Western and Northern Europe.
Asia-Pacific
Asia-Pacific represents a rapidly expanding region with an estimated market share of around 24%, supported by rising healthcare investments, expanding research infrastructure, and growth of the biopharmaceutical sector. China, Japan, South Korea, and India drive regional demand through increased funding for life science research, oncology studies, and infectious disease monitoring. Expanding academic institutions and contract research organizations accelerate instrument installations and reagent consumption. Adoption of mid-range and advanced flow cytometry systems increases as laboratories modernize capabilities. Strong government support and growing clinical research activity position Asia-Pacific as a key growth engine.
Latin America
Latin America holds close to 6% market share, supported by gradual improvements in healthcare infrastructure and growing research activity in countries such as Brazil and Mexico. Flow cytometry adoption increases primarily in academic research institutes, public hospitals, and reference diagnostic laboratories. The region shows rising use in immunology, hematology, and infectious disease studies. However, adoption remains concentrated in major urban centers due to cost sensitivity and limited technical expertise. Expansion of government-funded healthcare programs and international research collaborations continues to support steady, albeit moderate, market development.
Middle East & Africa
The Middle East & Africa region accounts for approximately 5% market share, with demand driven by improving healthcare infrastructure and increasing focus on advanced diagnostics. Countries such as Saudi Arabia, the United Arab Emirates, and South Africa lead regional adoption due to investments in hospital modernization and research facilities. Flow cytometry is primarily used in tertiary care hospitals and academic research centers for hematology and immunophenotyping. While market penetration remains limited in parts of Africa, rising awareness, medical tourism, and gradual expansion of diagnostic capabilities support long-term growth potential.
Asia-Pacific Flow Cytometry Market Segmentations:
By Product:
- Cell Analyzers
- Cell Sorters
By Technology:
- Cell-based
- Bead-based
By Application:
- Drug Discovery
- Stem Cell
By Geography
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East
- Africa
Key Player Analysis
- Stratedigm, Inc.
- Miltenyi Biotec
- Agilent Technologies, Inc.
- Cytek Biosciences
- Apogee Flow Systems Ltd.
- Thermo Fisher Scientific, Inc.
- Sysmex Corporation
- Bio-Rad Laboratories, Inc.
- BD
- Danaher
Recent Developments
- In November 2025, Bharat Biotech International Ltd entered the cell and gene therapy sector by launching Nucelion Therapeutics Pvt Ltd, a wholly owned CRDMO dedicated to research, development, and manufacturing in this field.
- In November 2025, StemCyte International launched its Public Bank Matching Protection Service in Taiwan, a groundbreaking initiative with Taishin Life, linking life insurance policies to StemCyte's public cord blood bank for enhanced transplant access, providing families crucial financial and medical safety nets for critical illnesses.
- In January 2025, BD (Becton, Dickinson and Company) and Biosero, a developer of laboratory automation solutions, announced a collaboration to integrate robotic arms with BD's flow cytometry instruments. This partnership aims to automate manual processes in drug discovery and development, enhancing efficiency and throughput in laboratory workflows.
- In March 2024, Beckman Coulter Life Sciences received 510(k) clearance from the FDA to distribute its DxFLEX Clinical Flow Cytometer in the U.S. This advancement makes high-complexity flow cytometry testing more accessible to laboratories without the need for additional expense.
Report Coverage
The research report offers an in-depth analysis based on Product, Technology, Application and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Flow cytometry adoption will increase as life science research and clinical diagnostics expand across Asia-Pacific.
- Advanced multi-parameter and spectral analysis systems will gain wider acceptance in research and biopharmaceutical workflows.
- Integration of automation and AI-driven data analysis will improve efficiency and result reproducibility.
- Demand for compact and mid-range systems will rise in emerging Asia-Pacific healthcare markets.
- Biopharmaceutical and cell therapy development will continue to drive high-throughput analytical requirements.
- Clinical applications in immunology, oncology, and hematology will expand steadily across hospitals.
- Reagent and consumable demand will grow in line with increasing instrument utilization rates.
- Local manufacturing and regional service networks will strengthen vendor competitiveness.
- Training programs and standardized workflows will improve adoption among new laboratory users.
- Collaboration between academia, CROs, and healthcare providers will support sustained long-term market growth.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Expanding Life Science and Clinical Research Infrastructure
Rapid growth in research facilities and clinical laboratories across Asia-Pacific, supported by increased government and institutional funding, is driving demand for flow cytometry systems for advanced cellular analysis in immunology, oncology, and infectious disease research.
Rising Burden of Chronic and Infectious Diseases
The increasing prevalence of cancer, autoimmune disorders, and infectious diseases in the region is fueling the adoption of flow cytometry for immune profiling, disease monitoring, and biomarker identification in both research and clinical settings.
Growth of Biopharmaceutical and Cell Therapy Development
The expanding biopharmaceutical sector and rising activity in monoclonal antibodies, vaccines, and cell-based therapies are increasing the need for high-throughput, multiparametric flow cytometry platforms for drug development, quality control, and translational research.
Integration of Automation, AI, and Advanced Data Analytics
Laboratories are increasingly adopting automation and AI-driven data analysis to improve efficiency, reproducibility, and throughput, creating demand for intelligent software and workflow solutions tailored to high-volume research and clinical environments.
Rising Adoption in Emerging Asia-Pacific Markets
Improved healthcare access, expanding diagnostic capacity, and growing research funding in emerging economies such as Vietnam, Indonesia, and the Philippines are driving demand for cost-effective and compact flow cytometry systems.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Asia-Pacific Flow Cytometry Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Asia-Pacific Flow Cytometry Market projected to grow between 2024 and 2032?
The market is projected to grow at a CAGR of 10.4% during the forecast period.
What are the primary factors fueling the growth of the Asia-Pacific Flow Cytometry Market?
Who are the leading companies in the Asia-Pacific Flow Cytometry Market?
Which region commanded the largest share of the Asia-Pacific Flow Cytometry Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Product
- 1.2.1 Cell Analyzers
- 1.2.2 Cell Sorters
- 1.2.3 Reagents & Consumables
- 1.2.4 Software & Services
- 1.3 By End User
- 1.3.1 Academic & Research Institutes
- 1.3.2 Hospitals & Clinical Laboratories
- 1.3.3 Pharmaceutical & Biotechnology Companies
- 1.3.4 Contract Research Organizations (CROs)
- 1.4 By Technology
- 1.4.1 Cell-based
- 1.4.2 Bead-based
- 1.5 By Application
- 1.5.1 Research
- 1.5.2 Drug Discovery
- 1.5.3 Clinical Diagnostics
- 1.5.4 Stem Cell Analysis
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 1234 million → 2032: USD 2722.24 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Asia-Pacific Flow Cytometry Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Asia-Pacific Flow Cytometry Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Asia-Pacific Flow Cytometry Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Asia-Pacific Flow Cytometry Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Asia-Pacific Flow Cytometry Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Asia-Pacific Flow Cytometry Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Asia-Pacific Flow Cytometry Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Asia-Pacific Flow Cytometry Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 1234 million → 2032: USD 2722.24 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Asia-Pacific Flow Cytometry Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Product - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Cell Analyzers
- 12.3.7.2 Cell Sorters
- 12.3.7.3 Reagents & Consumables
- 12.3.7.4 Software & Services
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By End User - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Academic & Research Institutes
- 12.4.7.2 Hospitals & Clinical Laboratories
- 12.4.7.3 Pharmaceutical & Biotechnology Companies
- 12.4.7.4 Contract Research Organizations (CROs)
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Technology - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Cell-based
- 12.5.7.2 Bead-based
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Application - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Research
- 12.6.7.2 Drug Discovery
- 12.6.7.3 Clinical Diagnostics
- 12.6.7.4 Stem Cell Analysis
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Asia-Pacific Flow Cytometry End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Asia-Pacific Flow Cytometry Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Country-Level Shares, 2024
- 14.2 Country Market Size Comparison, 2024
- 14.3 Country Market Forecasts, 2024-2032
- 14.4 Subregional Industrial and Demand Clusters
- 14.5 Intra-Regional Pricing and Cost Differences
- 14.6 Cross-Border Trade and Supply Networks
- 14.7 Regional Supply and Demand Balances
- 14.8 Country Opportunity Comparison and Prioritization
Note: Every listed country is covered on the structure shown under the first country.
Chapter 15 Asia-Pacific Flow Cytometry Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Asia-Pacific Flow Cytometry Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Stratedigm, Inc.
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Miltenyi Biotec
- 18.4 Agilent Technologies, Inc.
- 18.5 Cytek Biosciences
- 18.6 Apogee Flow Systems Ltd.
- 18.7 Thermo Fisher Scientific, Inc.
- 18.8 Sysmex Corporation
- 18.9 Bio-Rad Laboratories, Inc.
- 18.10 BD (Becton, Dickinson and Company)
- 18.11 Danaher
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

