
Supermarket apps and parcel networks reshape home supply
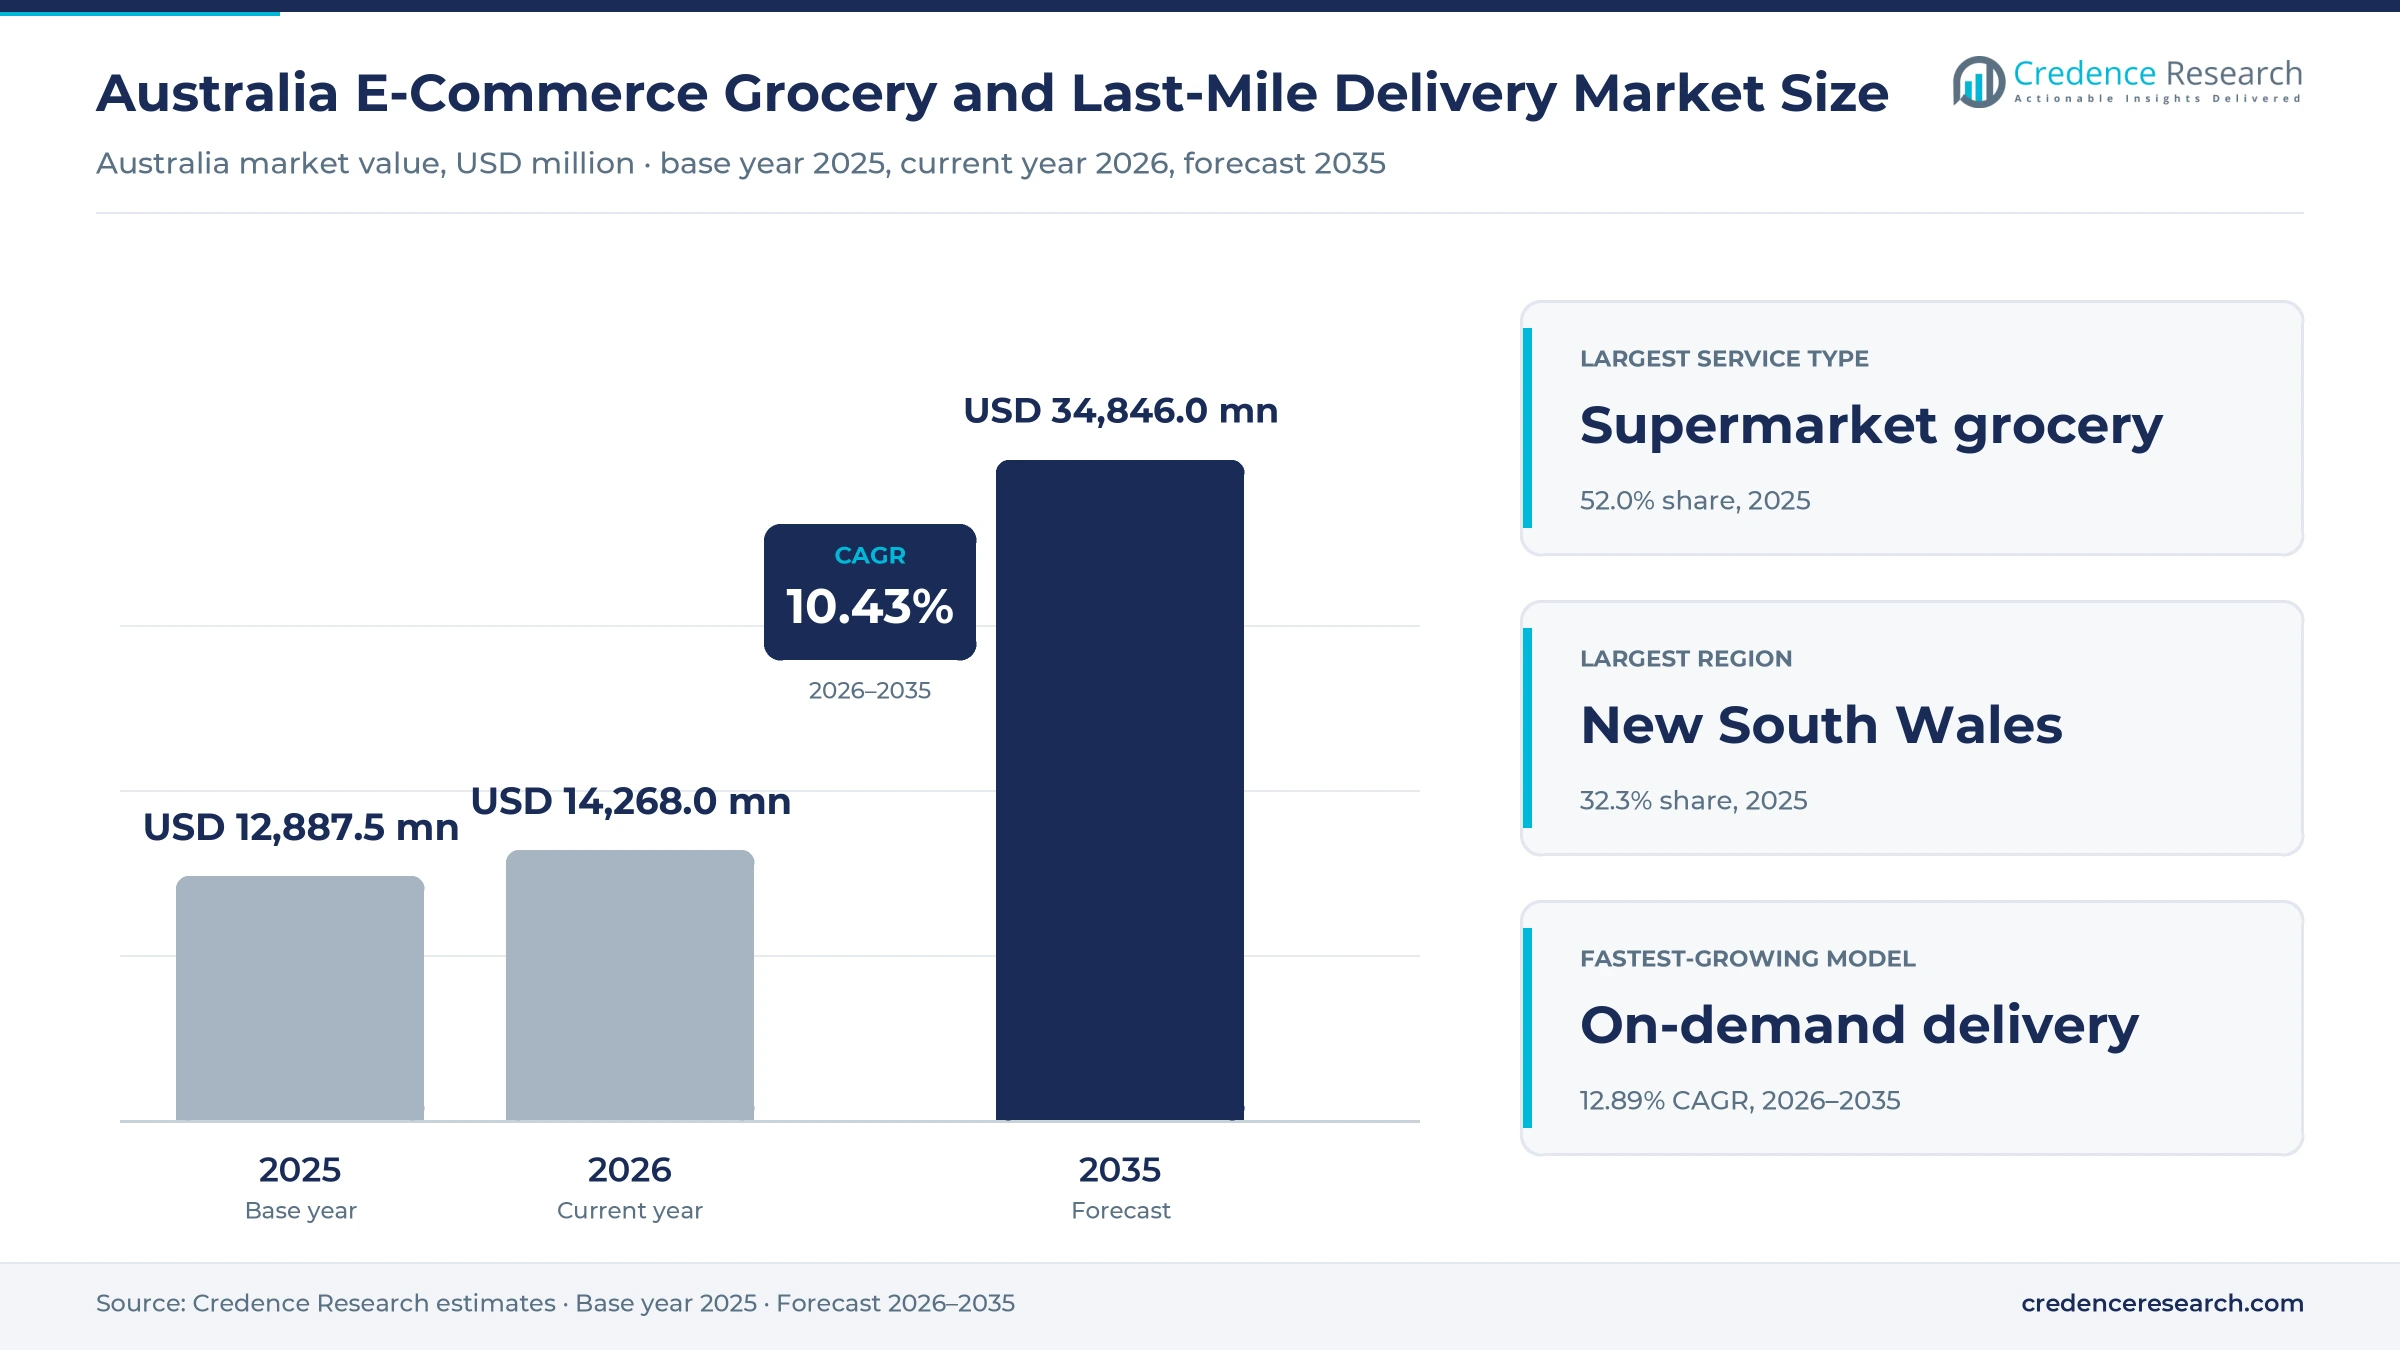
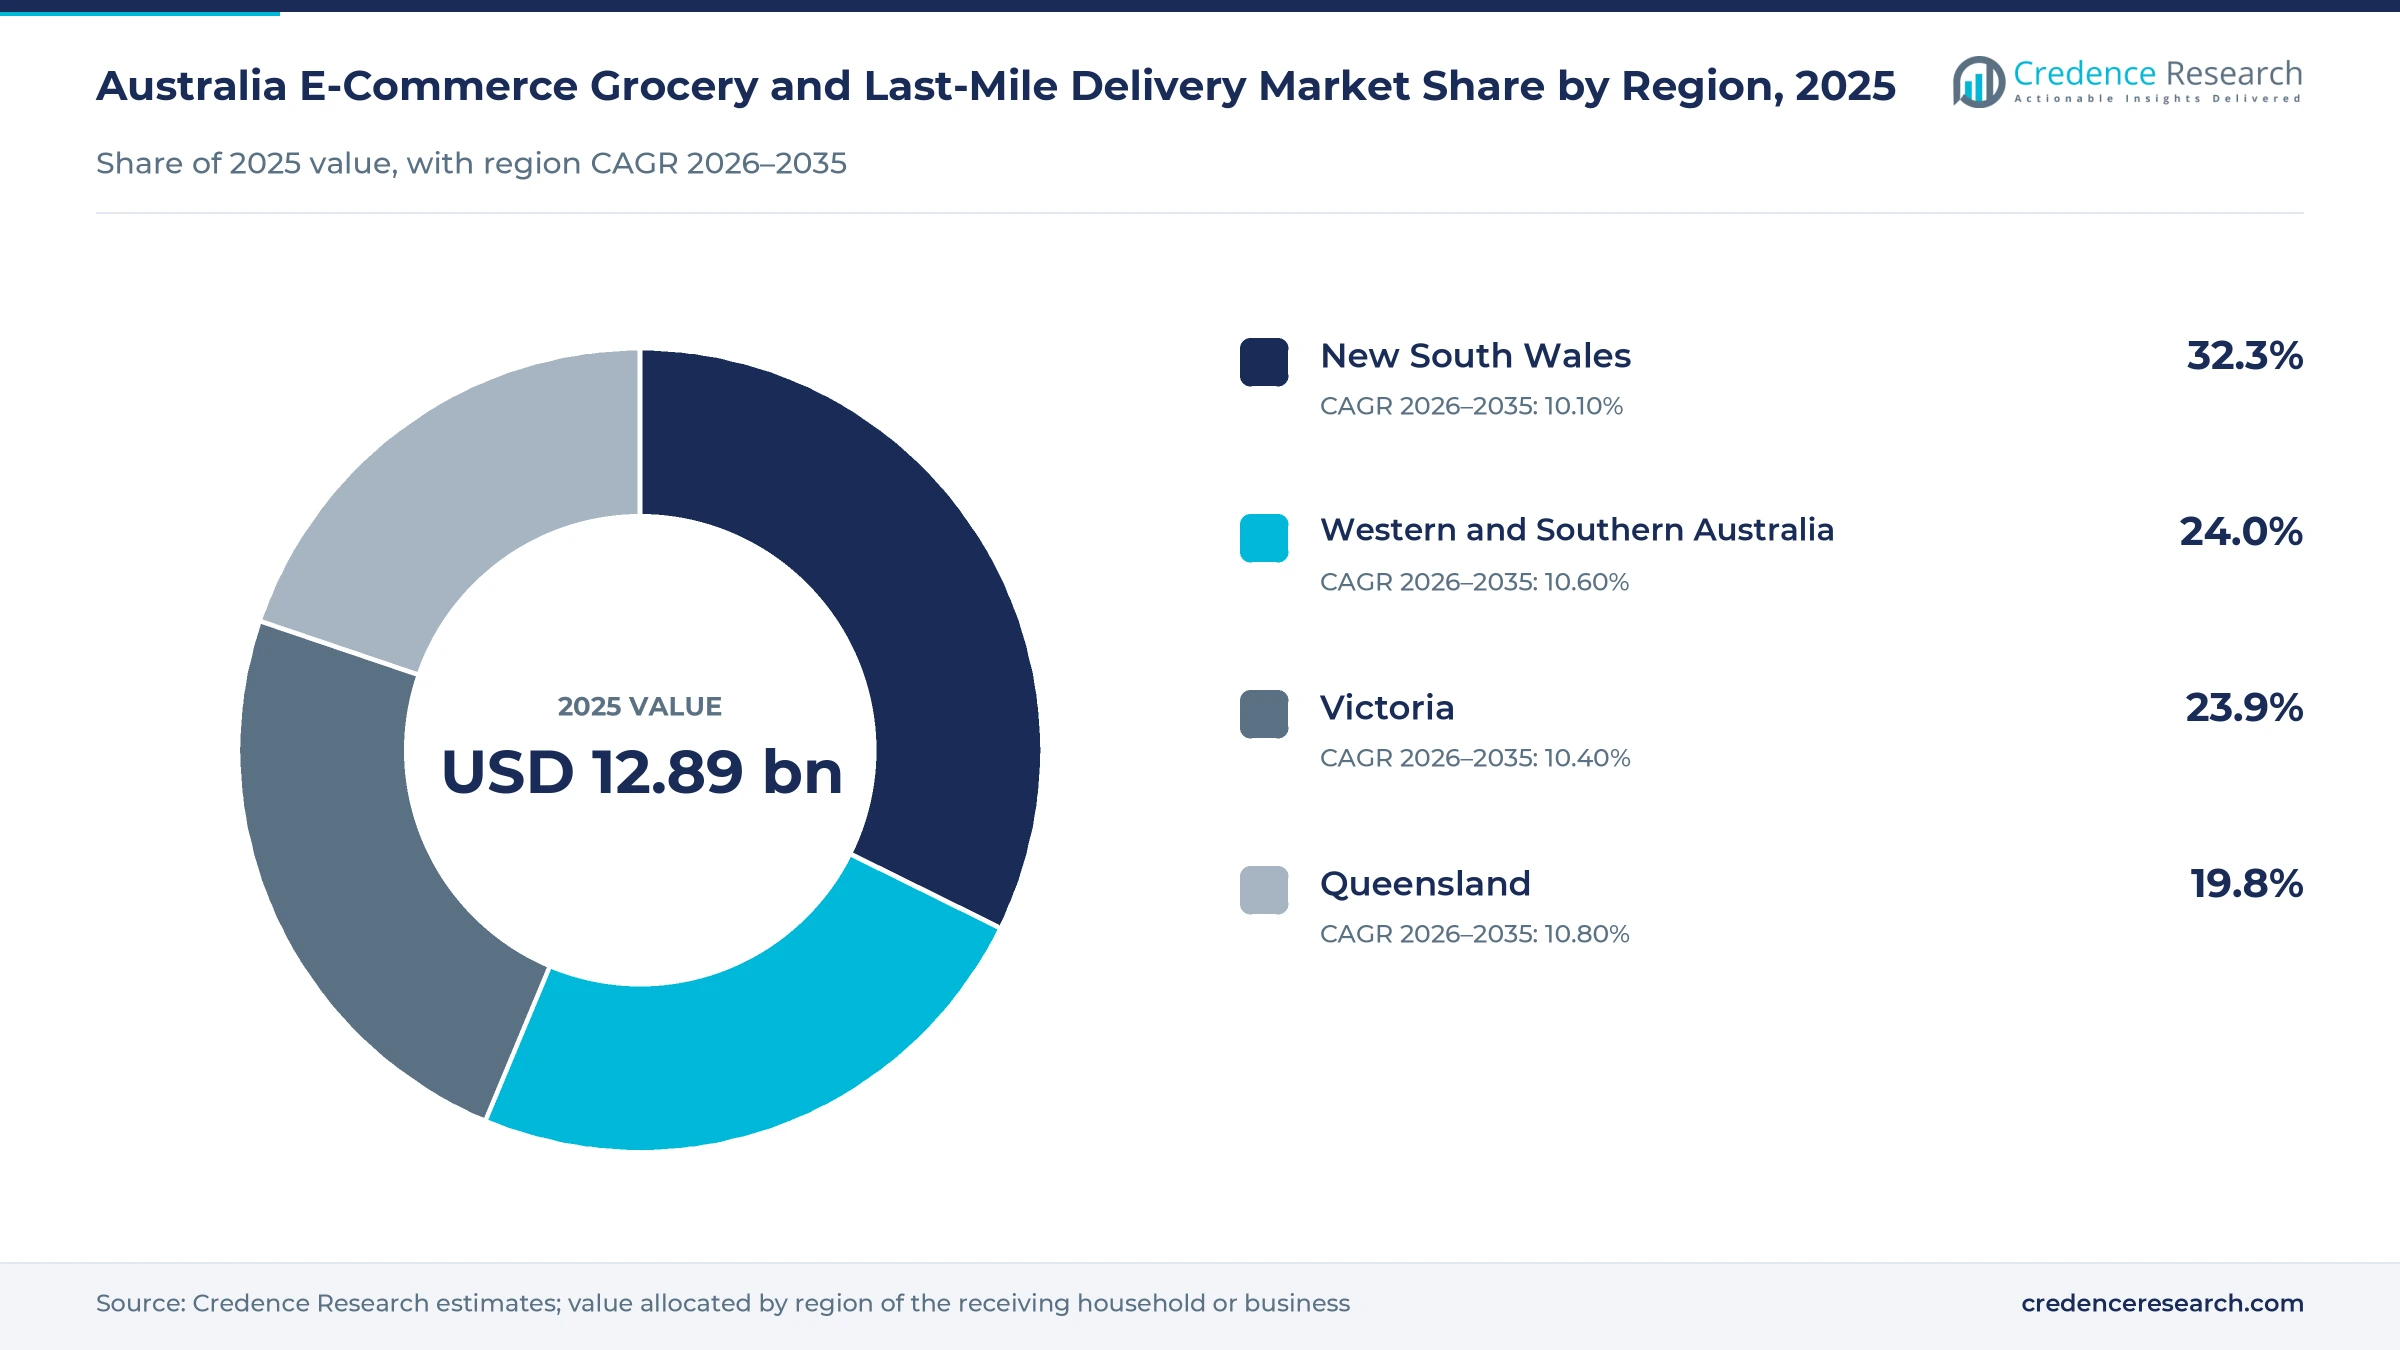
The Australia e-commerce grocery and last-mile delivery market was valued at USD 12.89 billion in 2025 and is projected to increase from USD 14.27 billion in 2026 to USD 34.85 billion by 2035, registering a CAGR of 10.43% during 2026–2035. Demand comes from households that move weekly supermarket shopping to apps and websites, shoppers who order small top-up baskets for delivery within an hour, and online merchants that ship parcels to homes across the country. New South Wales held the largest regional share, 32.3% in 2025, because Sydney concentrates online spending, supermarket fulfilment sites and parcel hubs. Queensland is the fastest-growing region at 10.80% a year, as population growth and regional online shopping widen delivery demand. In turn, the supply side changed when supermarkets opened automated fulfilment centers in Melbourne and Sydney during 2024 and moved on-demand orders onto national delivery platforms in 2025.
Which orders and deliveries does the estimate cover?
The estimate measures the value of groceries that Australian households buy through retailer websites, apps and third-party platforms, together with the value of last-mile parcel delivery services sold to retailers and merchants. It covers scheduled home delivery, rapid delivery within an hour, pick-up at stores and lockers, and standard and express parcel delivery to homes and businesses.
The estimate excludes restaurant meal delivery, freight between warehouses and business-to-business pallet transport that never reaches a household. The value chain runs from suppliers and distribution centers through store and automated fulfilment sites, carriers, couriers and gig drivers to households in every state and territory.
Australia E-Commerce Grocery and Last-Mile Delivery Market Insights
- The Australia e-commerce grocery and last-mile delivery market was valued at USD 12.89 billion in 2025 and is projected to reach USD 34.85 billion by 2035, registering a CAGR of 10.43% during 2026–2035.
- New South Wales held a 32.3% share of 2025 value, because Sydney concentrates online spending, fulfilment sites and parcel hubs.
- Supermarket grocery e-commerce led with a 52.0% share of 2025 value, because the two largest chains fill most online grocery orders from stores.
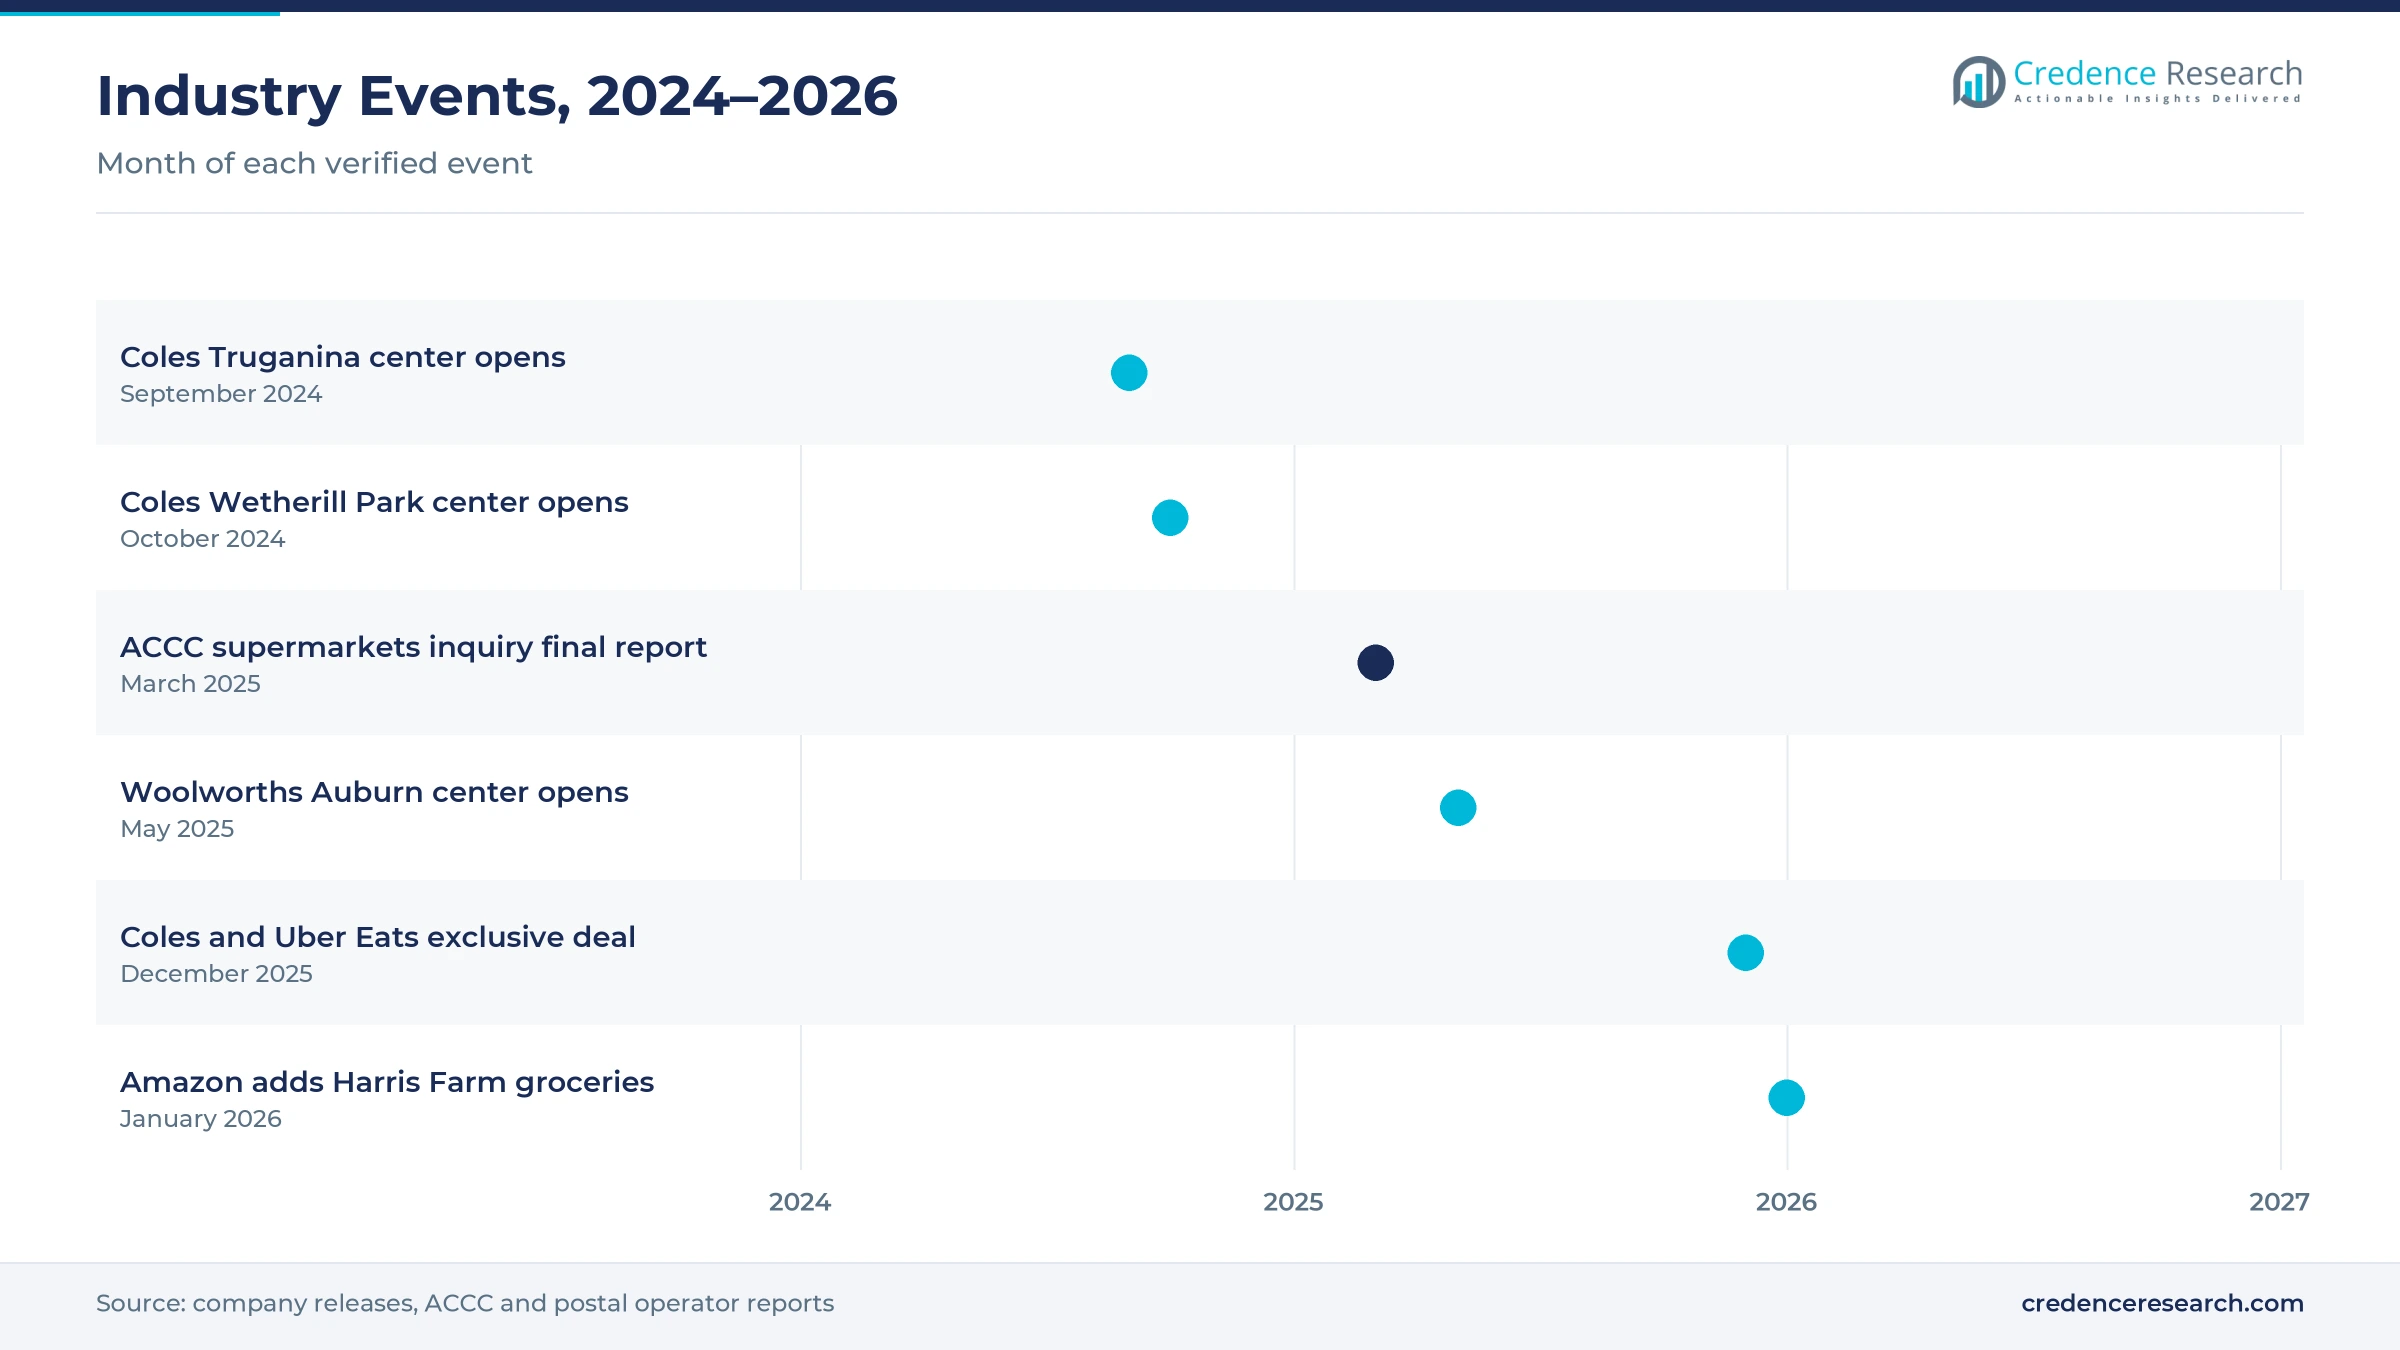
- Coles opened its first automated customer fulfilment center in Truganina, Victoria, in September 2024, with capacity for more than 10,000 orders a day.
- Australians spent a record $82.6 billion online in 2025, up 13.9% on the previous year, which lifts parcel volumes across every carrier.
Supermarket orders lead as on-demand delivery grows fastest
Why do supermarket orders lead service demand?
Based on service type, the market is categorized into supermarket grocery e-commerce, specialty grocery e-commerce, standard parcel delivery and express parcel delivery. Supermarket Grocery E-Commerce led with a 52.0% share of 2025 value, because the two largest chains fill weekly baskets from stores and automated centers. Express Parcel Delivery grows fastest at 11.69% a year, as shoppers and merchants pay more for next-day and same-day parcels.
How do households and shippers split spending?
Based on customer type, the market is categorized into household grocery buyers, enterprise retail shippers and independent merchant shippers. Household Grocery Buyers led with a 60.0% share of 2025 value, because grocery baskets are large and bought every week. Independent Merchant Shippers grow fastest at 11.54% a year, as small online stores use aggregators and lockers to reach buyers across the country.
Why is on-demand delivery the fastest-growing model?
Based on delivery model, the market is categorized into scheduled home delivery, on-demand home delivery, customer collection and standard carrier delivery. Scheduled Home Delivery led with a 38.0% share of 2025 value, because planned weekly orders still dominate online grocery spending. On-Demand Home Delivery grows fastest at 12.89% a year, as supermarkets and platforms deliver small baskets within an hour.
How do retailer apps and marketplaces share orders?
Based on channel, the market is categorized into retailer-owned digital channels, third-party grocery marketplaces, direct carrier contracts and shipping aggregators. Retailer-Owned Digital Channels led with a 55.0% share of 2025 value, because shoppers order directly from supermarket apps and websites. Third-Party Grocery Marketplaces grow fastest at 13.06% a year, as delivery platforms add full supermarket ranges and large retailers join national marketplaces.
| Segment Group | Leading Sub-segment | Share, 2025 | Fastest-growing Sub-segment | CAGR, 2026–2035 |
|---|---|---|---|---|
| By Service Type | Supermarket Grocery E-Commerce | 52.0% | Express Parcel Delivery | 11.69% |
| By Customer Type | Household Grocery Buyers | 60.0% | Independent Merchant Shippers | 11.54% |
| By Delivery Model | Scheduled Home Delivery | 38.0% | On-Demand Home Delivery | 12.89% |
| By Channel | Retailer-Owned Digital Channels | 55.0% | Third-Party Grocery Marketplaces | 13.06% |
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Online baskets, repeat orders and parcel scale lift value
How does supermarket digital channel migration lift value?
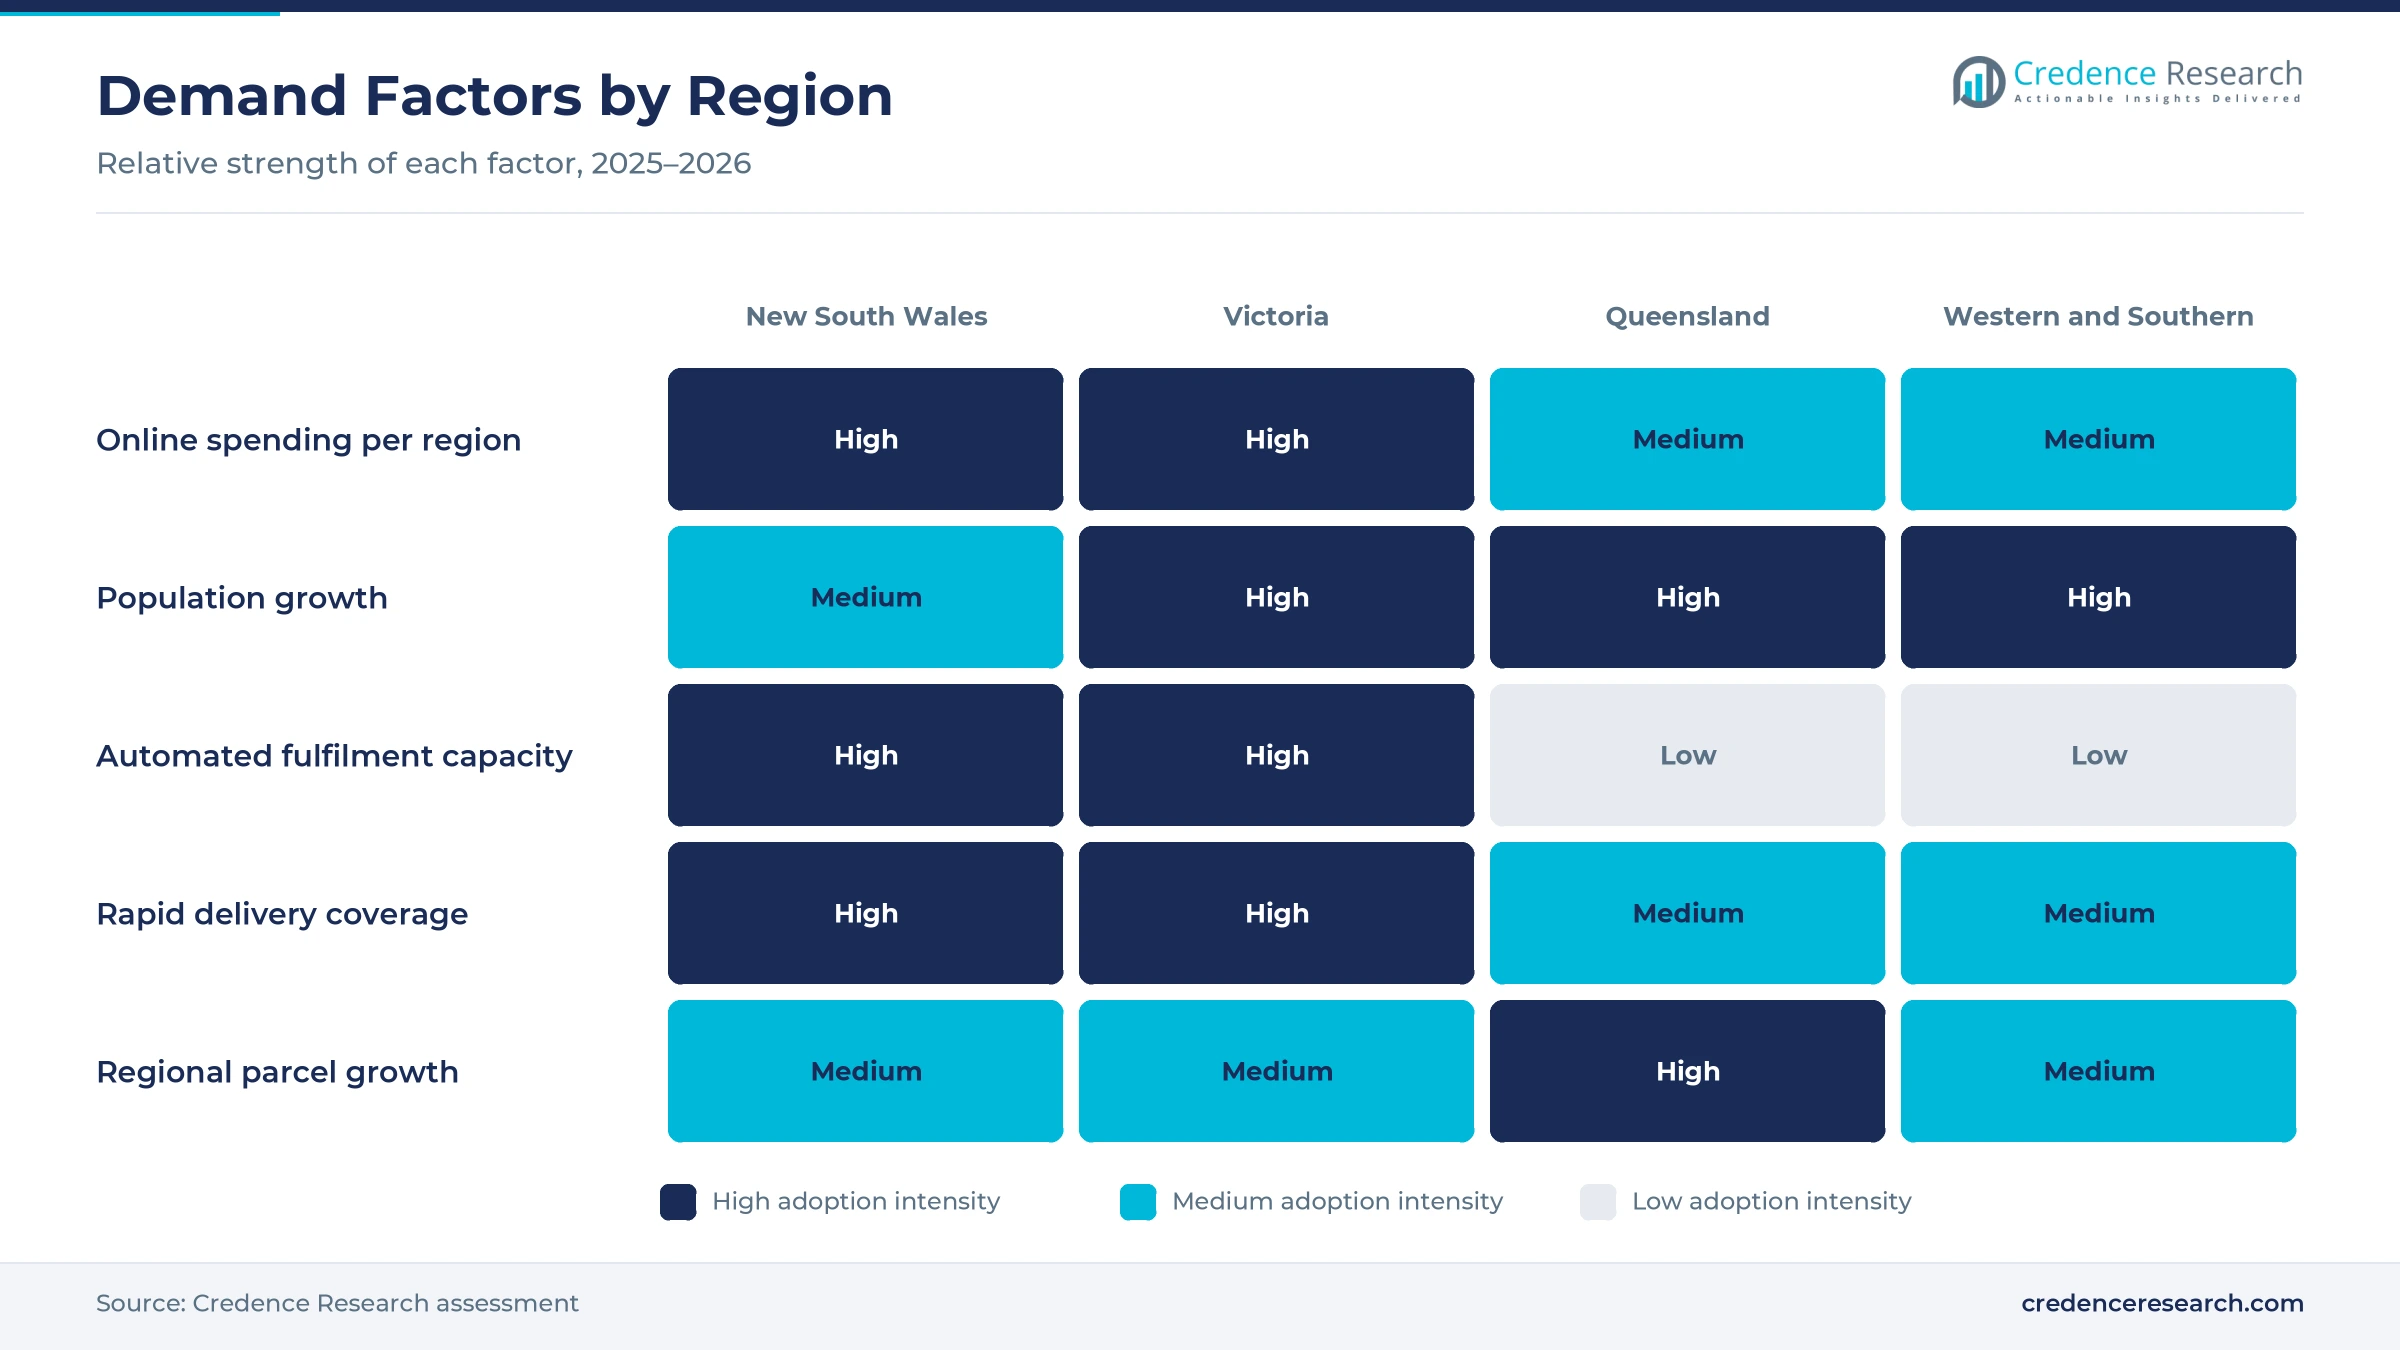
Supermarket digital channel migration lifts value, because shoppers keep moving weekly baskets from store aisles to apps and websites. Online sales made up a record 15.1% of Woolworths supermarket sales in the fourth quarter of fiscal 2025, according to its annual results filing. The same filing shows that 87% of online orders reached customers within 24 hours of being placed. Coles opened automated fulfilment centers in Truganina in September 2024 and Wetherill Park in October 2024, each able to process more than 10,000 orders a day. As a result, supermarket grocery e-commerce holds a 52.0% share of 2025 value, as store and automated supply widen online capacity.
Why does recurring household ordering support steady demand?
Recurring household ordering supports steady demand, because grocery baskets are bought every week and shoppers rarely switch once a routine forms. About 9.8 million Australian households shopped online in 2024, according to the national postal operator, and one in five shopped online every week. About 96.1% of Australians used the internet in 2024, according to World Bank data, which gives online ordering near-universal reach. Woolworths also expanded Direct to Boot pick-up to 755 locations in fiscal 2025. In turn, household grocery buyers hold a 60.0% share of 2025 value, as repeat orders give supermarkets predictable delivery volume across every week of the year.
How does parcel network scale widen delivery coverage?
Parcel network scale widens delivery coverage, because larger carrier networks cut the cost of each drop and reach regional towns more often. Australians spent a record $82.6 billion online in 2025, up 13.9% on the previous year, according to the international postal body. The national postal operator delivered 102.8 million parcels during its record Christmas peak in fiscal 2025 and grew its parcel locker banks by 18.9% to 919. More than 1,200 free parcel lockers were installed nationwide by early 2026, which supports self-service pick-up terminals. As a result, express parcel delivery grows at 11.69% a year, the fastest service rate.
Why do platform partnerships expand on-demand grocery reach?
Platform partnerships expand on-demand grocery reach, because delivery apps bring supermarket ranges to shoppers who want small baskets within an hour. Coles widened its range on Uber Eats to up to 17,000 products on Dec. 11, 2025, according to the platform newsroom, with delivery in under an hour. Uber Eats became Coles' exclusive on-demand partner from Dec. 26, 2025, while Woolworths joined DoorDash in the same month. Woolworths also delivered 41% of online delivery orders within two hours in the fourth quarter of fiscal 2025. In turn, on-demand home delivery grows at 12.89% a year, the fastest delivery model rate.
Rapid delivery, marketplaces and lockers reshape handoffs
How is the shift to rapid delivery changing store roles?
The shift to rapid delivery is changing store roles, because supermarkets now pick small baskets from local stores for delivery within an hour. Woolworths expanded its MILKRUN rapid delivery service to 515 stores during fiscal 2025, making it the fastest-growing part of its online business. Direct to Boot Now, a pick-up service ready in under 60 minutes, reached 513 stores in the same year. Coles moved its on-demand orders onto Uber Eats with up to 17,000 products from December 2025. As a result, stores act as both shopping floors and local food retail fulfilment hubs, which lifts store labor productivity in dense suburbs.
Why is the rise of automated fulfilment reshaping supply?
The rise of automated fulfilment is reshaping supply, because robotic centers pick large baskets faster and with fewer errors than store teams. Coles opened its Truganina center in September 2024 with more than 700 bots that can pick a 50-item order in about five minutes. Its Wetherill Park center in western Sydney opened in October 2024 with capacity for more than 10,000 orders a day. Woolworths opened its Auburn fulfilment center in May 2025 and plans a Melbourne North center able to serve 40,000 orders a week. In turn, scheduled home delivery keeps a 38.0% share of 2025 value as automated sites serve planned weekly orders.
Can marketplaces open new grocery supply for shoppers?
Marketplaces open new grocery supply for shoppers, because global platforms add fresh food ranges that compete with supermarket apps. Amazon Australia began selling fresh groceries from Harris Farm in more than 80 Sydney suburbs in January 2026, with same-day and next-day delivery. Online marketplaces drove about 23% of national online spending in 2024 and 39% of online spending growth. Coles and Woolworths also list their ranges on Uber Eats and DoorDash, which widens the number of entry points for shoppers. As a result, third-party grocery marketplaces grow at 13.06% a year, the fastest channel rate, as large retailers and specialist grocers join national platforms.
Is there room for growth in regional parcel delivery?
Regional parcel delivery has room to grow, because households outside capital cities are adopting online shopping faster than metro households. Regional households that shopped online grew 2.9% in 2024, compared with 2.0% for metro households. Toowoomba and Mackay in Queensland and Point Cook in Victoria were the top locations by parcel volume. Most online shoppers expect delivery within two to five days, and one in two millennials and Gen X shoppers want delivery within three days. In turn, carriers that invest in automated sorting systems and regional depots can win more merchant contracts from growing online stores outside the capitals.
Labor costs, failed drops and thin margins test operators
How do labor costs weigh on delivery margins?
Labor costs weigh on delivery margins, because picking, packing and driving make up most of the cost of each order. Wage rises and new rules for gig workers raise the cost of drivers and store pickers. As a result, small baskets and rural drops can lose money unless fees cover the extra work. Operators respond with automated picking, minimum basket values and delivery fees that rise for faster time slots.
Why do failed deliveries raise cost per parcel?
Failed deliveries raise cost per parcel, because drivers must return to depots or attempt a second drop when no one is home. Apartments and secure buildings make unattended drops harder in large cities. In turn, carriers carry extra fuel, labor and storage costs on each missed parcel. Carriers respond with lockers, collection points and live tracking that let shoppers redirect parcels before the driver arrives.
How does long-distance geography limit coverage?
Long-distance geography limits coverage, because remote towns sit far from fulfilment centers and parcel hubs. Fresh and chilled groceries need refrigerated vans and short travel times, which are hard to offer outside large cities. As a result, many regional households rely on pick-up or slower parcel services. Retailers respond with store-based picking in regional towns and partnerships with local couriers that know rural routes.
Why does price scrutiny pressure supermarket delivery fees?
Price scrutiny pressures supermarket delivery fees, because regulators and shoppers are watching grocery prices closely. The competition regulator released the final report of its supermarkets inquiry on March 21, 2025, with recommendations to the government. In turn, supermarkets face pressure to keep delivery fees and minimum spends low. Retailers respond with subscription plans, free pick-up and loyalty offers that spread delivery costs across more orders.
New South Wales leads while Queensland grows fastest
| Region | Value, 2025 (USD billion) | Share, 2025 | CAGR, 2026–2035 |
|---|---|---|---|
| New South Wales | 4.16 | 32.3% | 10.10% |
| Western and Southern Australia | 3.09 | 24.0% | 10.60% |
| Victoria | 3.08 | 23.9% | 10.40% |
| Queensland | 2.55 | 19.8% | 10.80% |
Why does new South Wales hold the largest share?
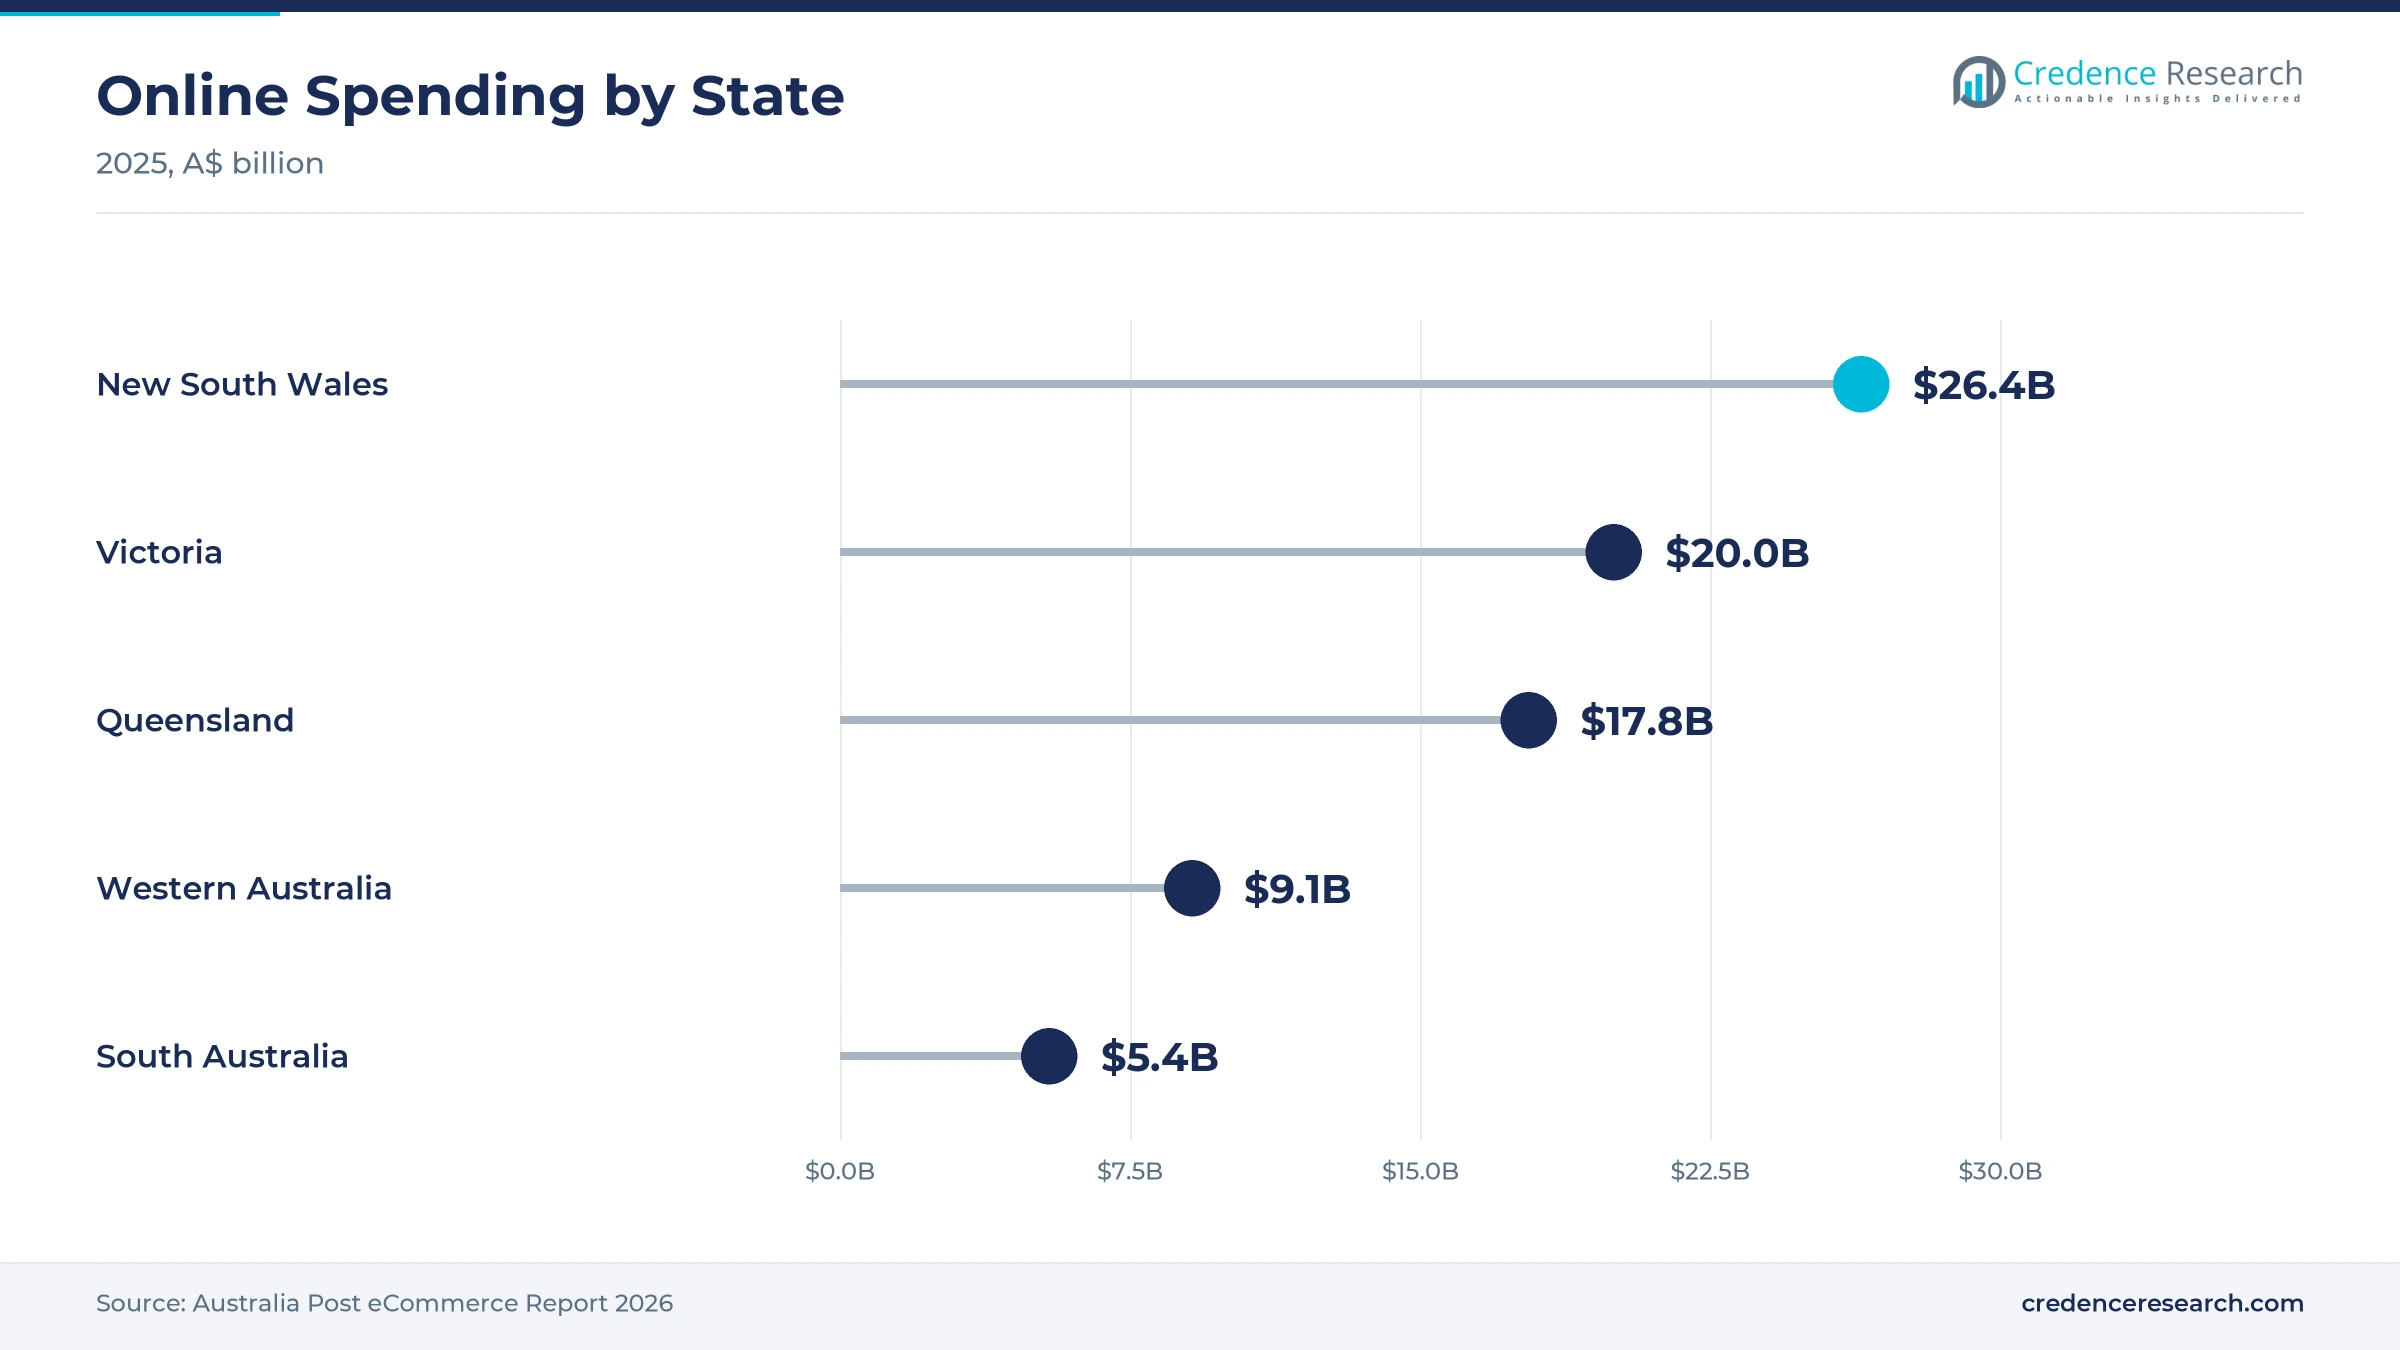
New South Wales held a 32.3% share of 2025 value and grows at 10.10% a year, because Sydney concentrates online spending, fulfilment centers and parcel hubs. Households in the state spent about $26.4 billion online in 2025, the highest of any state. However, growth is slower than in other zones because population growth was 1.1% in the year to March 2026. Automated sites in western Sydney already serve most metro grocery orders.
How does Victoria support online grocery growth?
Victoria held a 23.9% share of 2025 value and grows at 10.40% a year, because Melbourne has dense suburbs and new automated fulfilment capacity. Households in the state spent about $20 billion online in 2025. The state also added about 109,500 residents in the year to March 2026, a growth rate of 1.6%. Growth in western suburbs such as Point Cook keeps parcel volumes rising.
Why does Queensland grow fastest?
Queensland held a 19.8% share of 2025 value and grows fastest at 10.80% a year, because population growth and regional online shopping widen delivery demand. Households in the state spent about $17.8 billion online in 2025. Toowoomba and Mackay were among the top locations for parcel volume in 2024. The state added about 90,100 residents in the year to March 2026, which supports more delivery routes.
How do western and Southern Australia add demand?
Western and Southern Australia held a 24.0% share of 2025 value and grow at 10.60% a year, because Perth and Adelaide households raised online spending. Households in Western Australia spent about $9.1 billion online in 2025, while South Australia spent about $5.4 billion. Western Australia also had the fastest state population growth at 2.1% in the year to March 2026.
Automated centers and platform deals shaped 2024-2026
| Development | Status and market relevance |
|---|---|
| In September 2024, Coles opened its first automated customer fulfilment center in Truganina, Victoria. | Added capacity for more than 10,000 online orders a day in Melbourne |
| In October 2024, Coles opened its second automated fulfilment center at Wetherill Park in western Sydney. | Extended automated picking to metropolitan Sydney |
| In May 2025, Woolworths opened its Auburn eCommerce fulfilment center in Sydney. | Raised online grocery capacity in the largest state market |
| In December 2025, Coles expanded its Uber Eats range to up to 17,000 products and made the platform its exclusive on-demand partner. | Moved on-demand supermarket orders onto one national platform |
| In January 2026, Amazon Australia began selling Harris Farm fresh groceries in more than 80 Sydney suburbs. | Brought a global marketplace into fresh grocery delivery |
Robotic picking, route software and lockers cut handling
- Robotic fulfilment grids store thousands of products in dense grids and let bots pick a 50-item order in about five minutes, which cuts picking errors.
- Route optimization software plans driver routes around time slots, traffic and parcel size, which lowers the cost of each drop.
- Smart parcel lockers give shoppers secure pick-up points in shopping centers and apartment blocks, which reduces failed deliveries.
- Live tracking apps show shoppers where the driver is and let them redirect parcels, which improves first-time delivery rates.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Supermarkets, the post and couriers compete on speed
Competition is led by the two largest supermarket chains, the national postal operator and a group of express couriers and delivery platforms. Woolworths runs store-based picking, rapid delivery from 515 stores and automated centers in Sydney. Coles operates automated centers in Melbourne and Sydney and uses Uber Eats as its exclusive on-demand partner. Australia Post runs the largest parcel network and more than 1,200 lockers. Team Global Express, DHL Express, FedEx and Aramex Australia compete for business parcels and express shipments. Amazon adds marketplace reach and fresh groceries in Sydney, while Metcash supplies independent IGA stores and HelloFresh ships meal kits. Rivals compete on delivery speed, coverage, cost per drop and range.
Companies profiled and their roles in this market
| Company | Type | Role in the market |
|---|---|---|
| Woolworths Group | Supermarket retailer | Runs rapid delivery from 515 stores and automated centers |
| Coles Group | Supermarket retailer | Opened automated centers in Truganina and Wetherill Park in 2024 |
| Australia Post | National postal operator | Grew parcel locker banks by 18.9% to 919 in fiscal 2025 |
| Amazon | Online marketplace | Began selling Harris Farm fresh groceries in Sydney in 2026 |
| Uber Eats | Delivery platform | Became the exclusive on-demand partner of Coles in December 2025 |
Credence Research view on Australian home delivery
Credence Research's view is that Australian online grocery and parcel delivery will keep growing faster than retail spending, because shoppers want faster delivery and more collection points. Supermarket orders remain the core of the market, while rapid delivery, marketplaces and express parcels gain share. Automation lowers picking costs, but labor and regional distance still limit margins. Operators that combine store networks, automated centers and dense carrier routes should gain share fastest. Regional collection points and lockers are the clearest openings for new entrants and smaller carriers over the forecast period.
How the online grocery and parcel estimate was built
The report uses 2025 as the base year on a calendar basis, and market values come from the Credence Research model. That model combines postal operator reports on online spending, listed-company operating disclosures, statistics office population data, World Bank internet data and company releases. Segment splits and regional growth rates are Credence Research estimates, while regional shares follow the client-defined split. Sources used are public reports, official statistics, company releases and trade press, and no interviews or surveys were used.
Faster delivery and wider coverage carry value to 2035
Online grocery and parcel delivery value is expected to reach USD 34.85 billion by 2035, a 10.43% CAGR during 2026–2035, as shoppers move more weekly baskets online and expect faster delivery. Growth should stay strong through 2028 while automated centers and platform partnerships add capacity. After that, regional delivery, lockers and marketplaces will carry more growth as metro online penetration matures. Higher labor costs would slow margins, while wider automation would support growth. Operators with dense networks and efficient picking are expected to gain the most.
Frequently Asked Questions
How big is the Australia e-commerce grocery and last-mile delivery market?
Which service type leads the Australian market?
Which region leads the Australia e-commerce grocery and last-mile delivery market?
How much did Australians spend online in 2025?
When did Coles open its automated fulfilment centers?
Which delivery model is growing fastest?
Who are the leading companies in Australian online grocery and parcel delivery?
What are the main challenges for delivery operators?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Service Type
- 1.2.1 Supermarket Grocery E-Commerce
- 1.2.2 Specialty Grocery E-Commerce
- 1.2.3 Standard Parcel Delivery
- 1.2.4 Express Parcel Delivery
- 1.3 By Customer Type
- 1.3.1 Household Grocery Buyers
- 1.3.2 Enterprise Retail Shippers
- 1.3.3 Independent Merchant Shippers
- 1.4 By Delivery Model
- 1.4.1 Scheduled Home Delivery
- 1.4.2 On-Demand Home Delivery
- 1.4.3 Customer Collection
- 1.4.4 Standard Carrier Delivery
- 1.5 By Channel
- 1.5.1 Retailer-Owned Digital Channels
- 1.5.2 Third-Party Grocery Marketplaces
- 1.5.3 Direct Carrier Contracts
- 1.5.4 Shipping Aggregators
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2025: USD 12.89 billion → 2035: USD 34.85 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Historical Period: 2018-2025
- 2.6.2 Base Year: 2025
- 2.6.3 Forecast Period: 2025-2035
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2025
- 3.3 Forecast Market Size, 2035
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Australia E-Commerce Grocery and Last-Mile Delivery Market Trends and Developments
- 4.1 Historical Industry Development, 2018-2025
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Australia E-Commerce Grocery and Last-Mile Delivery Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis, 2018-2025
- 5.2 Demand Forecast, 2025-2035
- 5.3 Production and Output Trend, 2018-2025
- 5.4 Production and Output Forecast, 2025-2035
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Australia E-Commerce Grocery and Last-Mile Delivery Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends, 2018-2025
- 6.3 Pricing Outlook, 2025-2035
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Australia E-Commerce Grocery and Last-Mile Delivery Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Australia E-Commerce Grocery and Last-Mile Delivery Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Australia E-Commerce Grocery and Last-Mile Delivery Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Australia E-Commerce Grocery and Last-Mile Delivery Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Australia E-Commerce Grocery and Last-Mile Delivery Market Outlook, 2025-2035
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2025: USD 12.89 billion → 2035: USD 34.85 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size, 2018-2025
- 11.1.4 Base-Year Market Size, 2025
- 11.2 Market Forecast, 2025-2035
- 11.2.1 Revenue Forecast to 2035
- 11.2.2 Volume Forecast to 2035
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Australia E-Commerce Grocery and Last-Mile Delivery Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2025
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Service Type - Market Size and Forecast, 2025-2035
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size, 2018-2025
- 12.3.3 Revenue Forecast, 2025-2035
- 12.3.4 Volume Forecast, 2025-2035
- 12.3.5 Base-Year Market Share, 2025
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Supermarket Grocery E-Commerce
- 12.3.7.2 Specialty Grocery E-Commerce
- 12.3.7.3 Standard Parcel Delivery
- 12.3.7.4 Express Parcel Delivery
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Customer Type - Market Size and Forecast, 2025-2035
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size, 2018-2025
- 12.4.3 Revenue Forecast, 2025-2035
- 12.4.4 Volume Forecast, 2025-2035
- 12.4.5 Base-Year Market Share, 2025
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Household Grocery Buyers
- 12.4.7.2 Enterprise Retail Shippers
- 12.4.7.3 Independent Merchant Shippers
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Delivery Model - Market Size and Forecast, 2025-2035
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size, 2018-2025
- 12.5.3 Revenue Forecast, 2025-2035
- 12.5.4 Volume Forecast, 2025-2035
- 12.5.5 Base-Year Market Share, 2025
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Scheduled Home Delivery
- 12.5.7.2 On-Demand Home Delivery
- 12.5.7.3 Customer Collection
- 12.5.7.4 Standard Carrier Delivery
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Channel - Market Size and Forecast, 2025-2035
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size, 2018-2025
- 12.6.3 Revenue Forecast, 2025-2035
- 12.6.4 Volume Forecast, 2025-2035
- 12.6.5 Base-Year Market Share, 2025
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Retailer-Owned Digital Channels
- 12.6.7.2 Third-Party Grocery Marketplaces
- 12.6.7.3 Direct Carrier Contracts
- 12.6.7.4 Shipping Aggregators
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Australia E-Commerce Grocery and Last-Mile Delivery End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Australia E-Commerce Grocery and Last-Mile Delivery Geographic Market Outlook, 2025-2035
- 14.1 Domestic Market Distribution and Demand Clusters
- 14.2 State- or Province-Wise Market Size and Forecast, 2025-2035
- 14.3 City and Metropolitan Market Outlook
- 14.4 Industrial, Manufacturing and Commercial Clusters
- 14.5 Geographic Concentration of Key End Users
- 14.6 Local Pricing and Purchasing Differences
- 14.7 Domestic Production Facilities and Capacity Map
- 14.8 Local Infrastructure and Project Pipeline
- 14.9 State-Level Policy and Incentive Differences
- 14.10 Subnational Investment Hotspots and Opportunities
- 14.11 Distribution and Logistics Networks
- 14.12 Domestic Competitive Footprint
Chapter 15 Australia E-Commerce Grocery and Last-Mile Delivery Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2025-2035
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Australia E-Commerce Grocery and Last-Mile Delivery Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2025
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2025-2035
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Woolworths Group
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Coles Group
- 18.4 Australia Post
- 18.5 Team Global Express
- 18.6 Metcash / IGA Network
- 18.7 DHL Express
- 18.8 FedEx
- 18.9 Amazon
- 18.10 HelloFresh
- 18.11 Aramex Australia
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

