
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
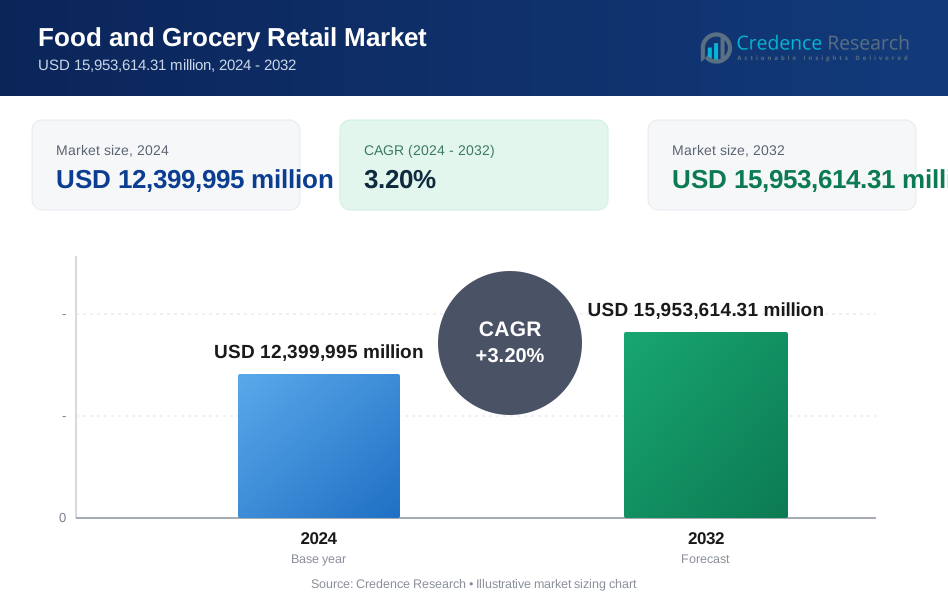
| Food and Grocery Retail Market Size 2024 | USD 12,399,995 million |
| Food and Grocery Retail Market, CAGR | 3.20% |
| Food and Grocery Retail Market Size 2032 | USD 15,953,614.31 million |
Market Overview:
The global food and grocery retail market is projected to grow from USD 12,399,995 million in 2024 to USD 15,953,614.31 million by 2032, reflecting a compound annual growth rate (CAGR) of 3.20%.
This growth is driven by the increasing demand for essential food and grocery items, coupled with the rising trend of online grocery shopping. The COVID-19 pandemic has significantly influenced consumer behaviour, leading to higher spending on groceries and increased online grocery sales. The market’s expansion is also supported by the growing population and urbanization, which drive the demand for convenient and accessible food and grocery retail options.
Several factors are driving the growth of the food and grocery retail market. The burgeoning prominence of online grocery retail channels has significantly boosted accessibility and convenience for consumers. The integration of e-commerce platforms into the food and grocery retail sector has expanded market reach and enabled retailers to tap into previously untapped customer segments. Additionally, the increasing presence of supermarkets and hypermarkets in developing countries, particularly in the Asia Pacific and Middle East & Africa regions, is contributing to market growth. The growing consumer awareness about health and wellness has led to a surge in demand for organic, natural, and health-conscious food products. Furthermore, the implementation of in-store pop-ups and events by retail companies is driving consumer engagement and boosting sales.
North America is expected to dominate the food and grocery retail market during the forecast period, owing to its advanced technology infrastructure and significant investments in research and development. The region’s high adoption rates of online grocery shopping and the presence of key market players further bolster market growth. Asia Pacific is anticipated to be the fastest-growing region, driven by the expanding use of online grocery retail channels and the increasing presence of supermarkets and hypermarkets. Countries like China, India, and Japan are major contributors to the market growth in this region. Europe is also a significant market for food and grocery retail, with a strong focus on technological innovation and the adoption of advanced retail solutions. The Middle East & Africa and Latin America regions are experiencing steady growth, driven by the rising demand for convenient and accessible food and grocery retail options.
Market Drivers:
Rise of Online Grocery Shopping:
The food and grocery retail market is significantly driven by the rise of online grocery shopping. Companies are increasingly investing in e-commerce platforms to cater to the growing demand for convenience and accessibility. For instance, Amazon’s acquisition of Whole Foods has enabled the integration of online and offline shopping experiences, providing customers with a seamless grocery shopping experience. Government surveys indicate that online grocery sales have surged, with a notable increase in the number of consumers opting for home delivery and curbside pickup services.
Expansion of Supermarkets and Hypermarkets:
The expansion of supermarkets and hypermarkets, particularly in developing countries, is another major driver of the food and grocery retail market. Retail giants like Walmart and Carrefour are continuously expanding their presence in emerging markets to tap into the growing consumer base. For example, Walmart has been rapidly opening new stores in India, enhancing its market reach and accessibility. Government data shows that the number of retail grocery outlets in India has been steadily increasing, contributing to the overall growth of the market.
Consumer Shift Towards Health and Wellness:
The growing consumer awareness about health and wellness is driving the demand for organic, natural, and health-conscious food products. Retailers are responding to this trend by expanding their product offerings to include a wide range of healthy and organic options. For instance, Whole Foods Market has seen a significant increase in sales of organic and natural products, reflecting the changing consumer preferences. Government surveys highlight that consumers are increasingly prioritizing health and wellness, leading to higher spending on nutritious and organic food items.
Innovative In-Store Experiences:
Retailers are leveraging innovative in-store experiences to drive consumer engagement and boost sales. The implementation of in-store pop-ups, events, and interactive displays is enhancing the shopping experience and attracting more customers. For example, Tesco has introduced interactive digital displays in its stores, allowing customers to explore product information and promotions. Government data indicates that such innovative retail strategies are positively impacting consumer behaviour and driving sales growth. These initiatives are helping retailers differentiate themselves in a competitive market and build stronger customer loyalty.
Market Trends:
Digital Transformation:
The food and grocery retail market is undergoing a significant digital transformation. Retailers are increasingly adopting online platforms to cater to the growing demand for convenience and contactless shopping. For instance, Walmart Inc. has expanded its online grocery services, offering same-day delivery and curbside pickup options. This shift is driven by the need to enhance customer experience and streamline operations. Government surveys indicate that approximately 500 million Indians are connected to the internet, with over 100 million transacting online. This digital adoption is reshaping the retail landscape, making it imperative for retailers to invest in robust e-commerce solutions.
Sustainability Initiatives:
Sustainability has become a focal point for food and grocery retailers. Companies are implementing eco-friendly practices to reduce their carbon footprint and appeal to environmentally conscious consumers. For instance, Tesco has committed to achieving net-zero carbon emissions by 2050 and is investing in renewable energy sources. Government data shows that consumers are increasingly prioritizing sustainable products, with a significant shift towards organic and locally sourced items. This trend is not only beneficial for the environment but also helps retailers build a positive brand image and foster customer loyalty.
Technological Advancements:
Technological advancements are revolutionizing the food and grocery retail market. Retailers are leveraging artificial intelligence (AI) and machine learning to optimize inventory management, enhance customer service, and personalize marketing efforts. For instance, Amazon.com Inc. uses AI-powered algorithms to predict consumer preferences and manage stock levels efficiently. Government surveys highlight that the adoption of AI in retail is expected to grow significantly, with a focus on improving operational efficiency and customer satisfaction. These technologies are enabling retailers to stay competitive in a rapidly evolving market.
Consumer Behaviour Shifts:
Consumer behaviour in the food and grocery retail market is evolving, driven by changing lifestyles and preferences. There is a growing demand for healthier and more convenient food options. For instance, the rise of meal kit services like Blue Apron and HelloFresh reflects consumers’ desire for quick and nutritious meal solutions. Government surveys indicate that consumers are spending less on traditional staples and more on discretionary items such as processed foods and ready-to-eat meals. Retailers must adapt to these shifts by offering diverse product ranges and personalized shopping experiences to meet the evolving needs of their customers.
Market Challenges Analysis:
Supply Chain Disruptions:
The food and grocery retail market face significant challenges due to supply chain disruptions. These disruptions can lead to product shortages, increased costs, and logistical challenges, hindering market growth and profitability. Factors such as geopolitical conflicts, natural disasters, and pandemics exacerbate these issues, making it difficult for retailers to maintain consistent inventory levels and meet consumer demand. Additionally, the reliance on global supply chains increases vulnerability to such disruptions, necessitating the need for more resilient and localized supply chain strategies.
Intense Competition:
Intense competition within the food and grocery retail market poses a major challenge for retailers. The market is highly fragmented, with numerous players ranging from large multinational corporations to small local businesses. This competitive landscape leads to price wars and aggressive marketing strategies, which can exert downward pressure on profit margins. Retailers must continuously innovate and differentiate their offerings to stay ahead of competitors, which requires significant investment in technology, marketing, and customer service.
Labor Shortages:
Labor shortages are another critical challenge affecting the food and grocery retail market. The industry relies heavily on a large workforce for various functions, including stocking shelves, managing inventory, and providing customer service. However, the sector is experiencing difficulties in attracting and retaining employees, leading to increased labor costs and operational inefficiencies. The ongoing labor shortage is driven by factors such as low wages, demanding work conditions, and competition from other industries. Retailers must address these issues by offering competitive wages, improving working conditions, and investing in employee training and development.
Rising Operational Costs:
Rising operational costs are a significant restraint on the food and grocery retail market. Costs associated with transportation, energy, and raw materials have been steadily increasing, impacting the overall profitability of retailers. Additionally, the need to invest in advanced technologies, such as e-commerce platforms and automation, further adds to the financial burden. Retailers must find ways to optimize their operations and reduce costs without compromising on the quality of products and services offered to consumers.
Market Segmentation Analysis:
By Type
The food and grocery retail market is segmented by type into fresh food, frozen food, beverages, and household products. Fresh food, including fruits, vegetables, and meat, holds a significant share due to the increasing consumer preference for healthy and organic options. Frozen food is also gaining traction, driven by the demand for convenience and longer shelf life.
By Technology
Technological advancements are playing a crucial role in transforming the food and grocery retail market. The adoption of e-commerce platforms, artificial intelligence (AI), and automation is enhancing operational efficiency and customer experience. For instance, AI-powered algorithms are being used to predict consumer preferences and manage inventory levels. Additionally, the integration of online and offline channels through omnichannel strategies is becoming increasingly prevalent.
By End User
The market is also segmented by end user into households, restaurants, and institutions. Households represent the largest segment, driven by the growing trend of home cooking and the need for daily essentials. Restaurants and institutions, such as schools and hospitals, also contribute significantly to the market, with a focus on bulk purchasing and specialized food products. The demand from these end users is influenced by factors such as convenience, quality, and cost-effectiveness.
Segmentations:
By Product:
- Fresh Food
- Frozen Food
- Food Cupboard
- Beverages
- Cleaning & Household
- Others
By Category:
- Packed
- Unpacked
By Distribution Channel:
- Supermarkets & Hypermarkets
- Convenience Stores
- Departmental Stores
- Online
By Region:
- North America
- The U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- The U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of Middle East and Africa
Regional Analysis:
North America
North America holds a significant share of the global food and grocery retail market. The region is characterized by a high level of consumer spending and a well-established retail infrastructure. The United States, in particular, is a major contributor to the market, driven by the presence of large retail chains such as Walmart and Kroger. The market share of North America is bolstered by the increasing adoption of online grocery shopping and the integration of advanced technologies like AI and automation. Additionally, the demand for organic and health-conscious food products is on the rise, further propelling market growth.
Europe
Europe is another prominent region in the food and grocery retail market, with countries like Germany, the United Kingdom, and France leading the way. The market in Europe is characterized by a strong emphasis on sustainability and eco-friendly practices. Retailers in the region are increasingly adopting measures to reduce their carbon footprint and promote sustainable sourcing. The market share of Europe is also supported by the growing popularity of online grocery shopping and the presence of well-established retail chains. The region’s focus on high-quality and locally sourced products is a key driver of market growth.
Asia-Pacific
The Asia-Pacific region holds the largest share of the global food and grocery retail market. This can be attributed to the rapidly growing population, increasing urbanization, and rising disposable incomes in countries like China and India. The market in Asia-Pacific is characterized by a high demand for convenience and ready-to-eat food products. Additionally, the region is witnessing a surge in online grocery shopping, driven by the increasing penetration of smartphones and internet connectivity. The presence of large retail chains and the expansion of e-commerce platforms are further contributing to the market’s growth in this region.
Latin America and Middle East & Africa
Latin America and the Middle East & Africa are emerging markets in the food and grocery retail sector. In Latin America, countries like Brazil and Mexico are experiencing growth due to increasing consumer spending and the expansion of retail chains. The market in the Middle East & Africa is driven by the rising demand for packaged and processed food products, as well as the growing popularity of online grocery shopping. These regions are also witnessing an increase in investments from international retail chains, which is expected to boost market growth in the coming years.
Key Player Analysis:
- Walmart Inc.
- com Inc.
- The Kroger Co.
- Costco Wholesale Corporation
- Tesco PLC
- Carrefour S.A.
- Aldi
- Lidl
- Target Corporation
- Sainsbury’s
Competitive Analysis:
The food and grocery retail market is highly competitive, characterized by the presence of numerous global and regional players. Major companies such as Walmart, Amazon, and Kroger dominate the market with their extensive distribution networks and advanced technological capabilities. These key players leverage their scale and resources to offer competitive pricing and a wide range of products, making it challenging for smaller retailers to compete. Additionally, the rise of e-commerce platforms has intensified competition, as consumers increasingly prefer the convenience of online shopping. Retailers are investing heavily in digital transformation and omnichannel strategies to enhance customer experience and retain market share. The competitive landscape is further shaped by the growing emphasis on sustainability and eco-friendly practices, with companies striving to meet the evolving preferences of environmentally conscious consumers. Overall, the market’s competitive dynamics necessitate continuous innovation and strategic investments to stay ahead.
Recent Developments:
- In September 2023, a definitive agreement was officially established between Kroger Co. and Albertsons Companies Inc., and C&S Wholesale Grocers, LLC. This agreement involved the sale of certain stores, banners, distribution centers, offices, and private label brands. This transaction is a component of their proposed merger, which was first announced on October 14, 2022.
- Also, in September 2023, C&S Wholesale Grocers, LLC, a leading entity in the U.S. for wholesale grocery supply and supply chain solutions, officially pledged to purchase 413 stores, eight distribution centers, and two offices. These assets were made available due to the impending merger of The Kroger Co. and Albertsons Companies Inc.
- Walmart has significantly expanded its online grocery services, offering same-day delivery and curbside pickup options to enhance customer convenience. This move is part of Walmart’s broader strategy to integrate digital and physical retail channels.
- Amazon’s acquisition of Whole Foods has cemented its position as a major player in the grocery retail market. This acquisition allows Amazon to offer a variety of delivery options and other advantages of online food shopping, blending e-commerce with physical storefronts.
- Tesco has committed to achieving net-zero carbon emissions by 2050 and is investing in renewable energy sources. This initiative is part of Tesco’s broader sustainability strategy to reduce its environmental impact and appeal to eco-conscious consumers.
Market Concentration & Characteristics:
The food and grocery retail market is characterized by a high level of market concentration, with a few dominant players such as Walmart, Amazon, and Kroger holding significant market shares. This concentration is driven by the extensive distribution networks, advanced technological capabilities, and competitive pricing strategies of these major retailers. The market is also marked by rapid digital transformation, with increasing adoption of e-commerce platforms and omnichannel strategies. Additionally, there is a growing emphasis on sustainability and eco-friendly practices, as consumers become more environmentally conscious. Despite the dominance of large players, the market remains highly competitive, with numerous regional and local retailers striving to differentiate themselves through unique product offerings and personalized customer experiences. This dynamic landscape necessitates continuous innovation and strategic investments to maintain market position and drive growth.
Report Coverage:
The research report offers an in-depth analysis based on Product, Category, Distribution Channel, and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The integration of e-commerce platforms will continue to grow, providing consumers with convenient online shopping options and efficient delivery services1.
- Retailers will increasingly adopt eco-friendly practices and sustainable sourcing to meet the rising demand for environmentally conscious products2.
- The use of artificial intelligence, machine learning, and automation will enhance inventory management, customer service, and personalized marketing efforts3.
- Retailers will focus on integrating online and offline channels to provide a seamless shopping experience for consumers.
- There will be a growing demand for organic, natural, and health-conscious food products as consumers become more health-aware.
- Retailers will invest in more resilient and localized supply chain strategies to mitigate the impact of disruptions.
- The food and grocery retail market will see significant growth in emerging markets, driven by increasing urbanization and rising disposable incomes.
- Retailers will leverage data analytics to offer personalized shopping experiences, catering to individual consumer preferences.
- The use of digital tools and platforms will enable retailers to engage with customers more effectively and build stronger relationships.
- Retailers will need to stay abreast of changing regulations and compliance requirements to ensure smooth operations and avoid potential legal issues.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the food and grocery retail market?
What factors are driving the growth of the food and grocery retail market?
What are some challenges faced by the food and grocery retail market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Food and Grocery Retail Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Food and Grocery Retail Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 12,399,995 million → 2032: USD 15,953,614.31 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Food and Grocery Retail Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Food and Grocery Retail Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Food and Grocery Retail Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Food and Grocery Retail Market Drivers
- 3.3 Food and Grocery Retail Market Restraints & Challenges
- 3.4 Food and Grocery Retail Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Food and Grocery Retail Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Food and Grocery Retail Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Food and Grocery Retail category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Food and Grocery Retail Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Food and Grocery Retail Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Food and Grocery Retail market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Food and Grocery Retail Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Food and Grocery Retail Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Food and Grocery Retail Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Food and Grocery Retail (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Food and Grocery Retail Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Food and Grocery Retail Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Food and Grocery Retail Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Food and Grocery Retail Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Food and Grocery Retail Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Food and Grocery Retail Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Food and Grocery Retail Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Food and Grocery Retail Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Food and Grocery Retail Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
