
Battery trucks move pallets across Australian supply chains
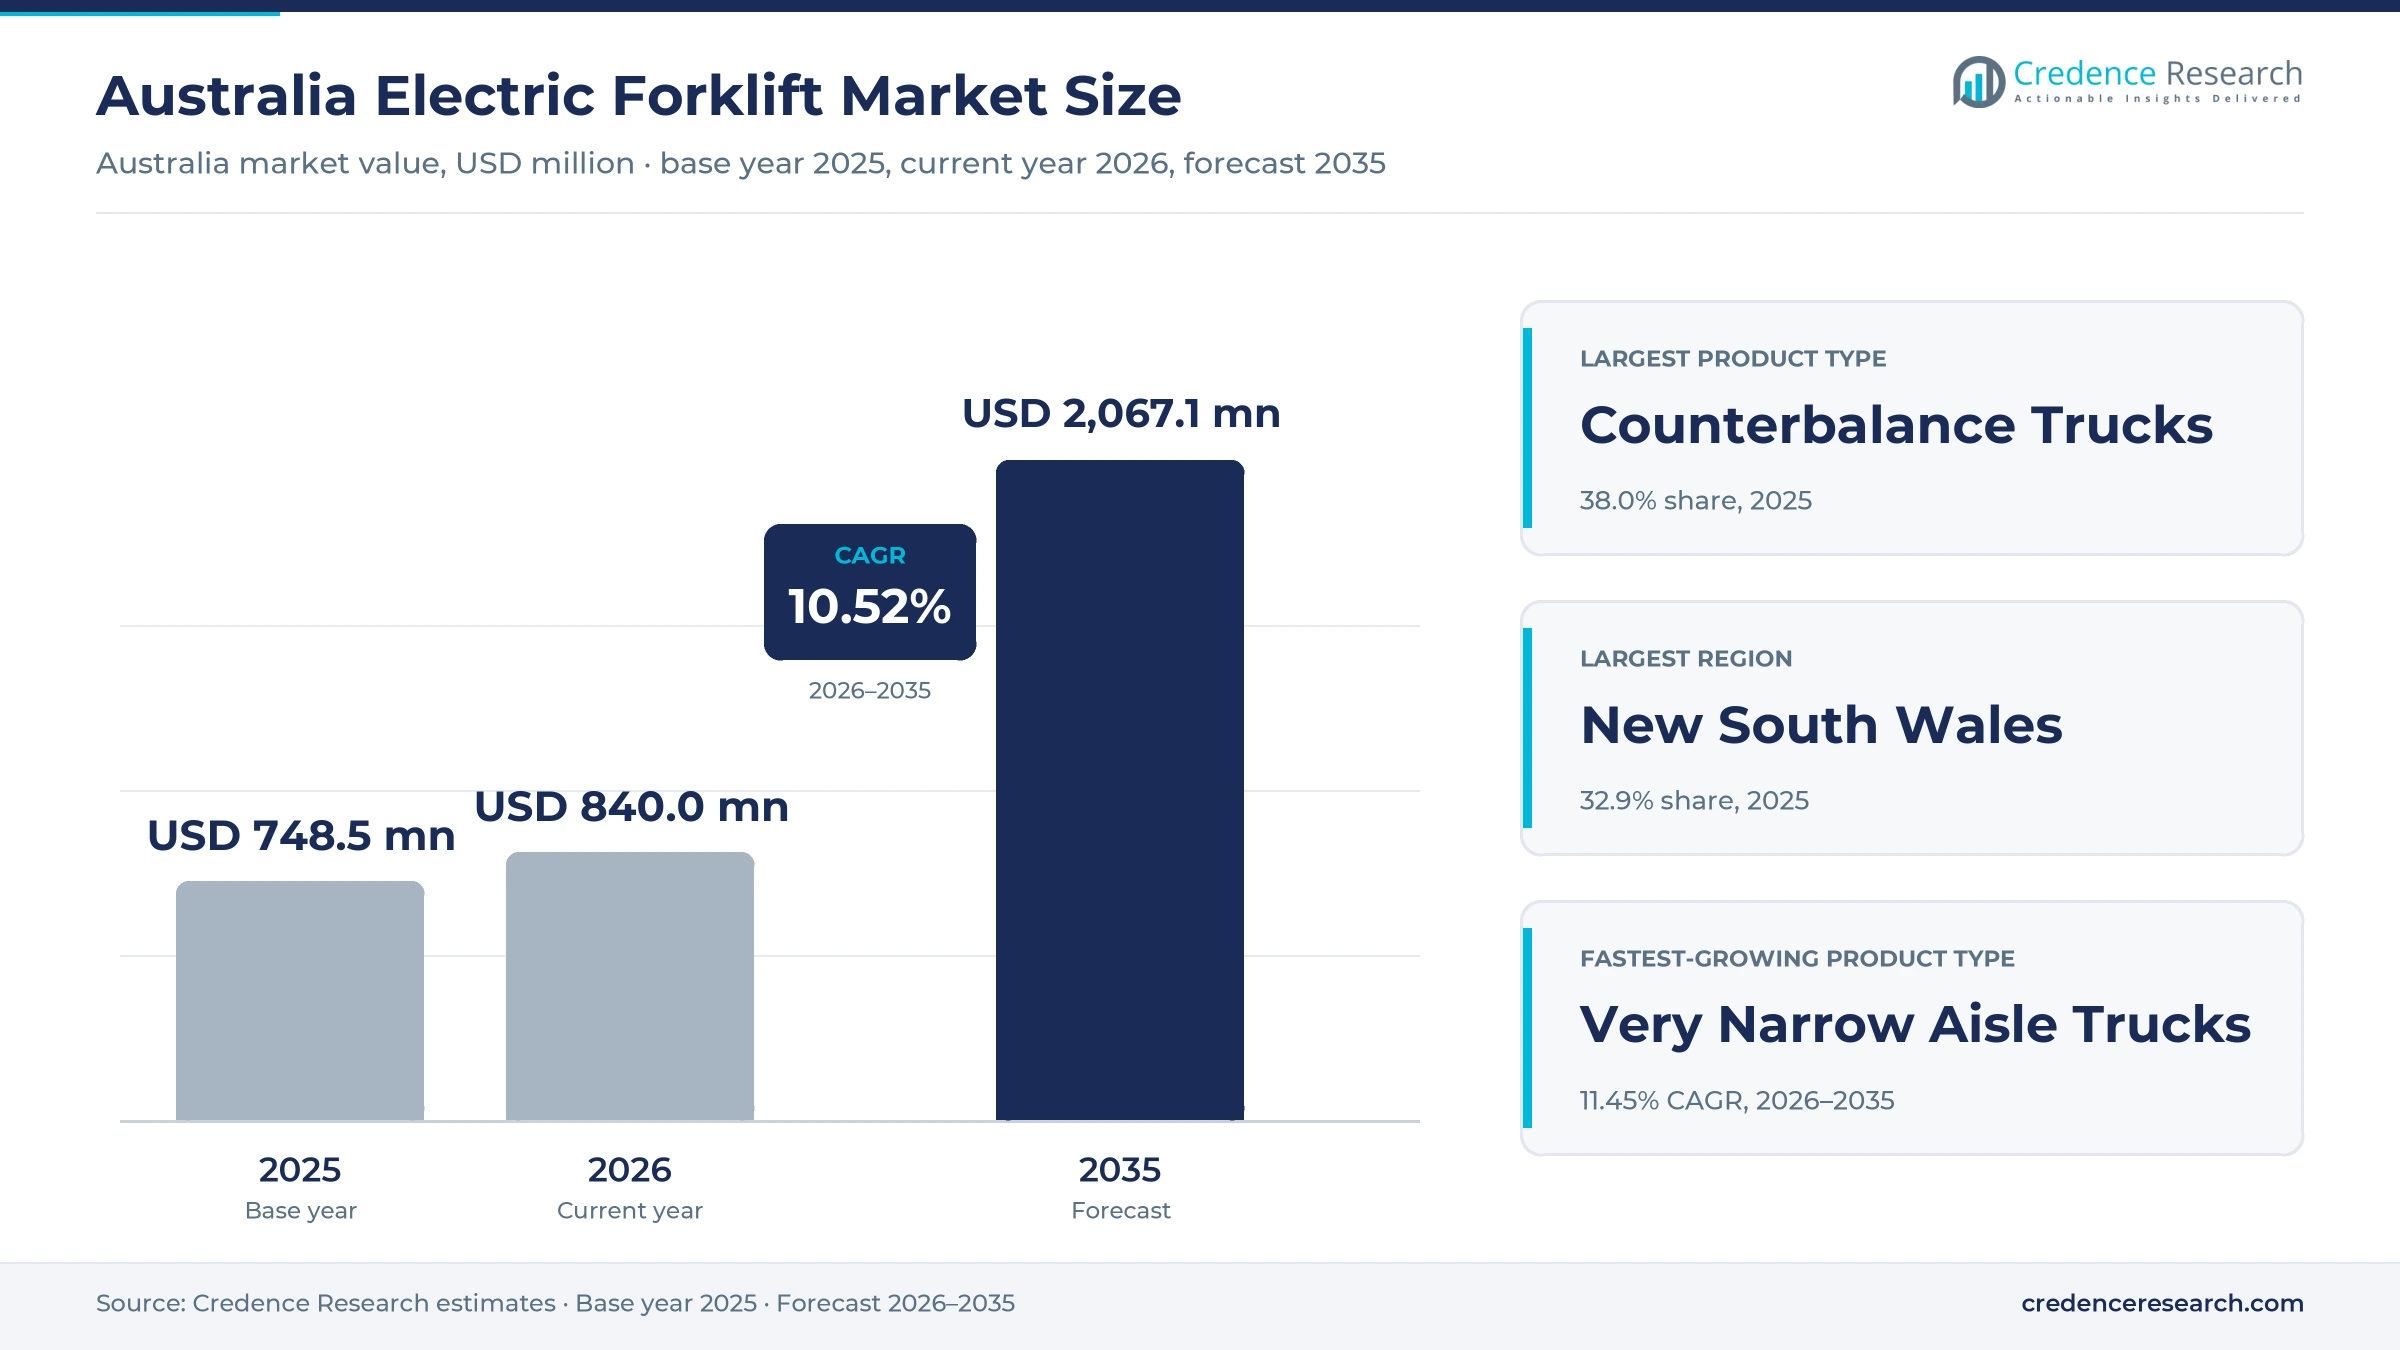
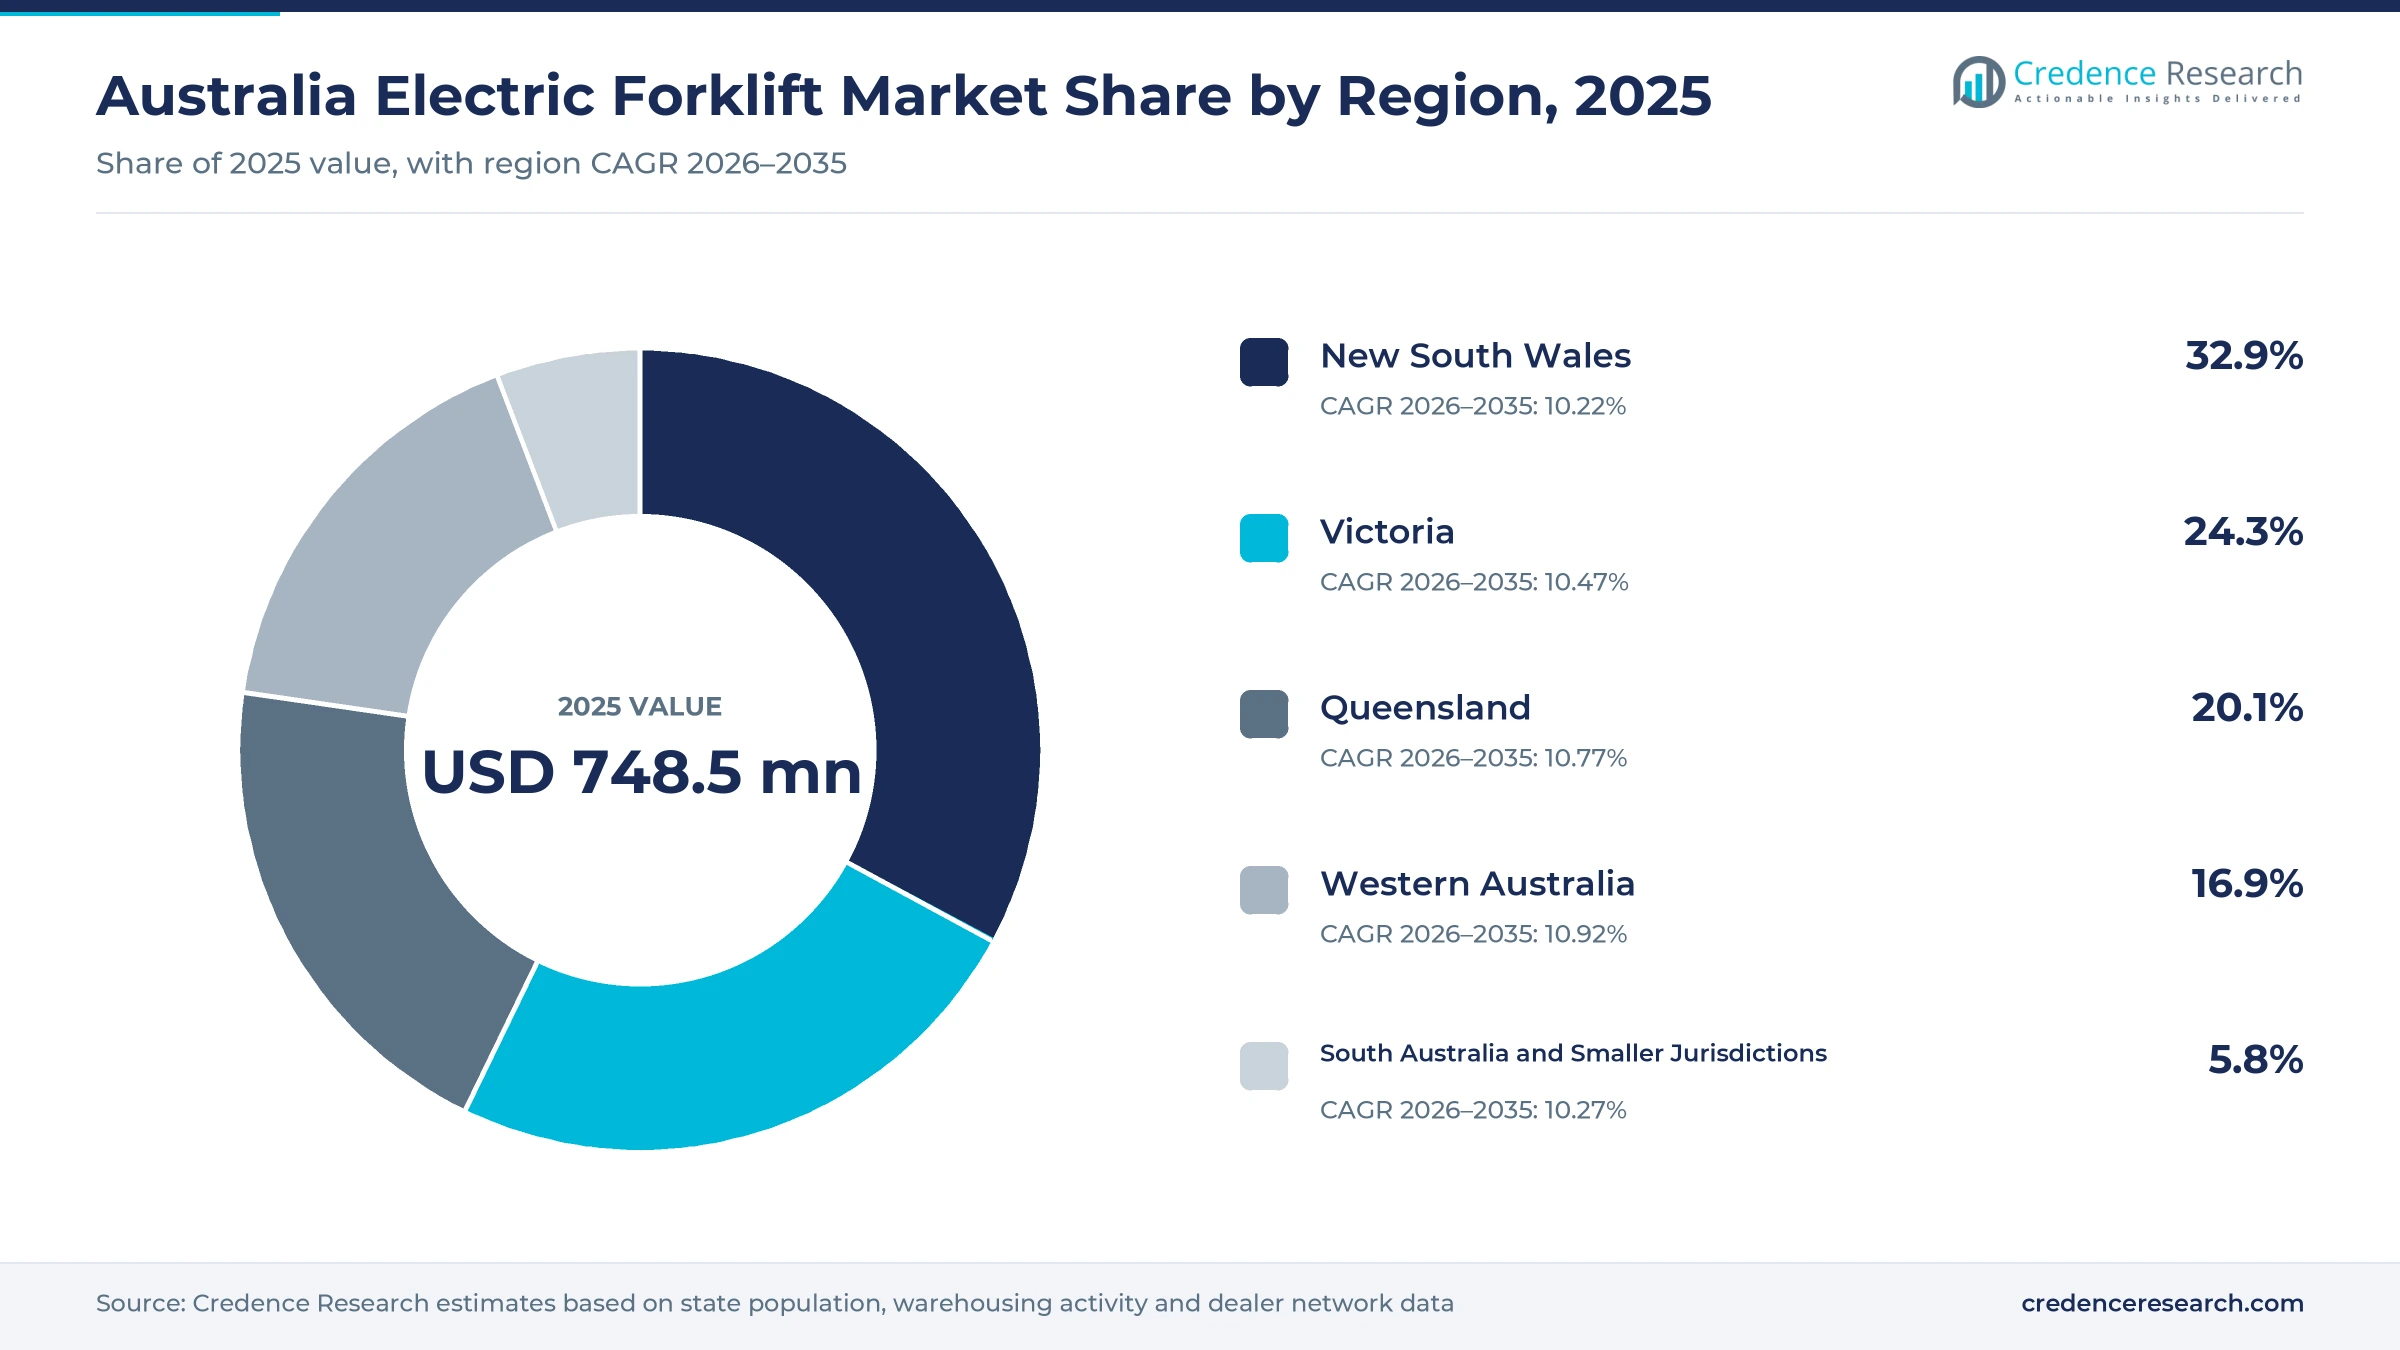
The Australia electric forklift market was valued at USD 748.5 million in 2025 and is projected to increase from USD 840.0 million in 2026 to USD 2.07 billion by 2035, registering a CAGR of 10.52% during 2026–2035. Demand comes from distribution centers run by grocers and logistics operators, from manufacturers that feed production lines indoors, and from mining and resources businesses that stock remote warehouses. New South Wales held the largest regional share, 32.9% in 2025, because Western Sydney hosts the largest cluster of new grocery and parcel distribution centers. Western Australia is the fastest-growing region at 10.92% a year, as the state adds people faster than any other and resources supply chains keep expanding. In turn, buying patterns are changing, because lithium-ion packs now ship as standard on many new trucks, and value-tier brands and new rental hubs are widening access for smaller fleet owners.
Which battery-powered trucks does the national estimate count?
Spending on new electric forklifts sold or leased in Australia forms the base of this estimate, including counterbalance trucks, reach trucks, order pickers, rider pallet trucks and stackers, and very narrow aisle trucks. It counts the value of the truck with its traction battery and charger when these are supplied as one package by an OEM branch, an authorized dealer or a rental provider.
The estimate excludes diesel and LPG trucks, used truck resales, stand-alone parts and labor contracts, and fully driverless shuttle systems sold as fixed warehouse installations. The value chain runs from overseas factories through national OEM subsidiaries and dealers to fleet owners, who buy outright, take long-term leases or hire trucks for seasonal peaks.
Australia Electric Forklift Market Insights
- The Australia electric forklift market was valued at USD 748.5 million in 2025 and is projected to reach USD 2.07 billion by 2035, registering a CAGR of 10.52% during 2026–2035.
- New South Wales held a 32.9% share of 2025 value, because Western Sydney hosts the largest cluster of new grocery and parcel distribution centers.
- Counterbalance trucks led product types with a 38.0% share of 2025 value, because they handle dock loading, yard moves and production feeding in one machine.
- Woolworths opened its Moorebank Logistics Precinct on Nov. 13, 2025, adding two automated distribution centers with 75,000 square meters of floor space in Western Sydney.
- Lithium-ion systems grow fastest among battery technologies at 12.76% a year during 2026–2035, as OEMs ship lithium packs as standard on new value-tier trucks.
Counterbalance trucks lead while narrow aisle units grow
Why do counterbalance trucks hold the largest share?
Based on product type, the market is categorized into Counterbalance Trucks, Reach Trucks, Order Pickers, Rider Pallet Trucks and Stackers, and Very Narrow Aisle Trucks. Counterbalance Trucks led with a 38.0% share of 2025 value, because one truck can load trailers, move stock across yards and feed production lines. Very Narrow Aisle Trucks grow fastest at 11.45% a year, as new high-bay sites store more pallets on each square meter of costly land.
Which industries buy the most battery trucks?
Based on end-use industry, the market is categorized into Warehousing and Third-Party Logistics, Manufacturing, Mining and Resources, Retail Distribution and Construction and Field Services. Warehousing and Third-Party Logistics led with a 41.0% share of 2025 value, because parcel and contract logistics operators run large indoor fleets. Mining and Resources grows fastest at 11.21% a year, as remote warehouses and processing sites replace engine trucks indoors.
How fast are lithium-ion packs replacing lead-acid?
Based on technology, the market is categorized into Lithium-Ion Systems, Flooded Lead-Acid Systems and Sealed Lead-Acid Systems. Lithium-Ion Systems led with a 46.0% share of 2025 value, because new trucks increasingly ship with lithium packs that charge during breaks. Lithium-Ion Systems also grow fastest at 12.76% a year, while flooded batteries remain common in older fleets with existing charging rooms.
Which sales channels reach fleet owners best?
Based on sales channel, the market is categorized into Direct OEM Sales and Service, Authorized Dealer Sales and Service, and Independent Rental and Service Providers. Direct OEM Sales and Service led with a 47.0% share of 2025 value, because large brands run their own national branches. Independent Rental and Service Providers grow fastest at 11.12% a year, as smaller fleet owners hire trucks for peaks instead of buying.
| Segment Group | Leading Sub-segment | Share, 2025 | Fastest-growing Sub-segment | CAGR, 2026–2035 |
|---|---|---|---|---|
| By Product Type | Counterbalance Trucks | 38.0% | Very Narrow Aisle Trucks | 11.45% |
| By End-Use Industry | Warehousing and Third-Party Logistics | 41.0% | Mining and Resources | 11.21% |
| By Technology | Lithium-Ion Systems | 46.0% | Lithium-Ion Systems | 12.76% |
| By Sales Channel | Direct OEM Sales and Service | 47.0% | Independent Rental and Service Providers | 11.12% |
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Distribution center growth and lithium economics lift demand
How does distribution center growth lift truck demand?
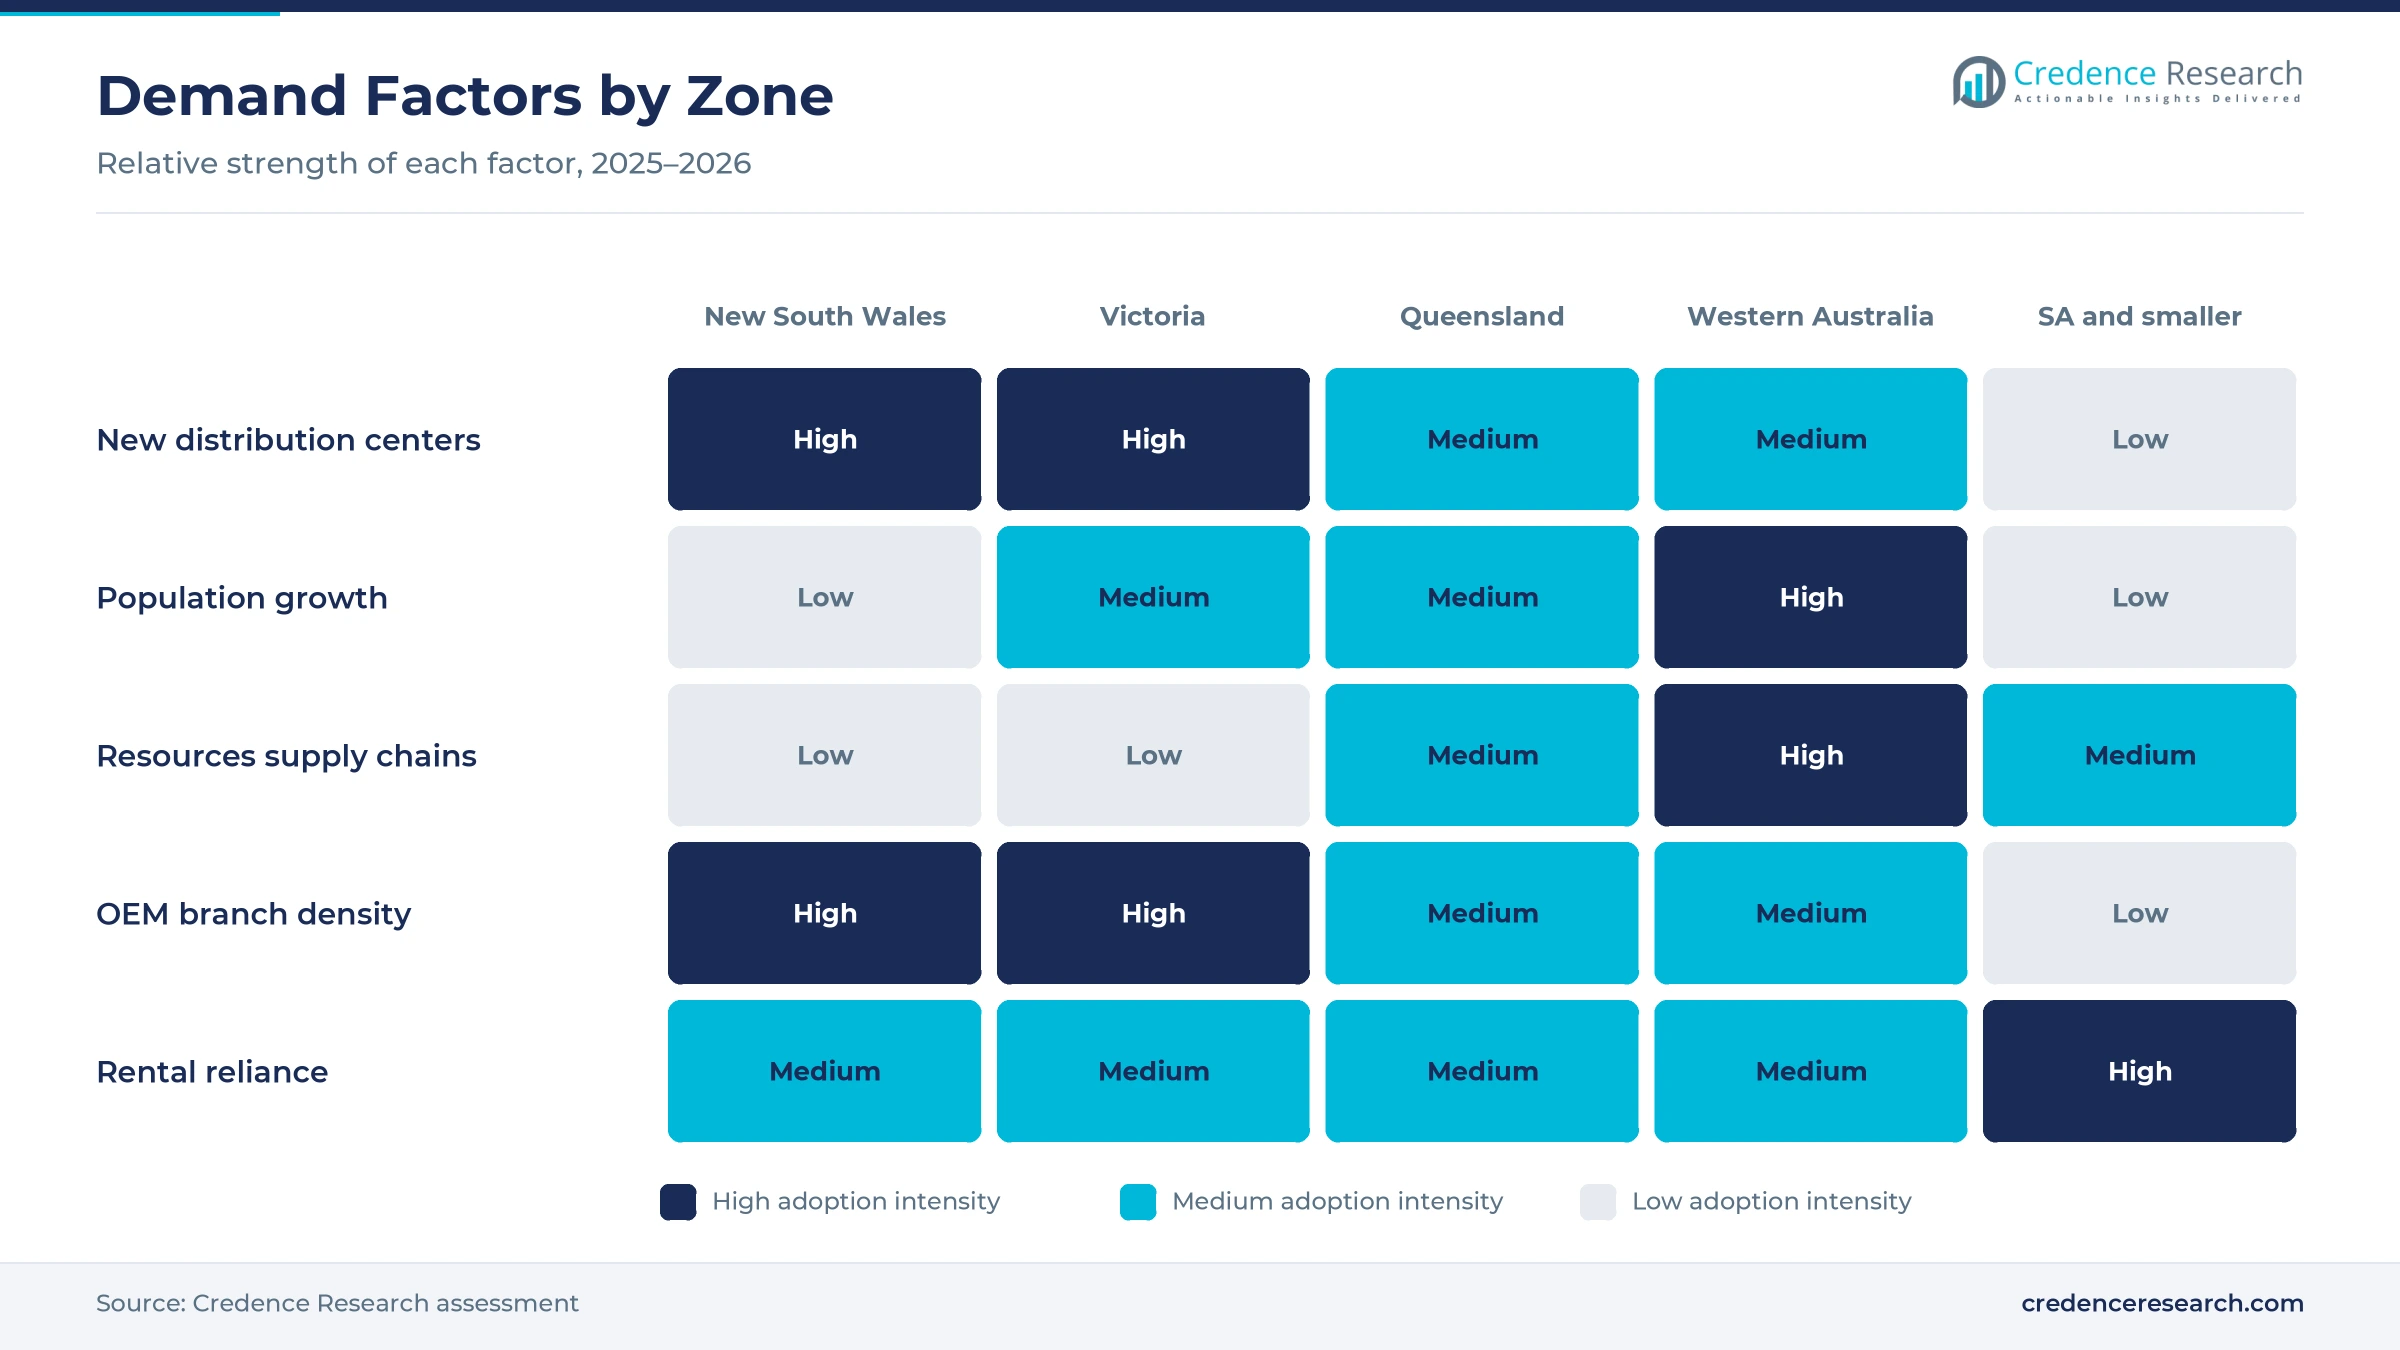
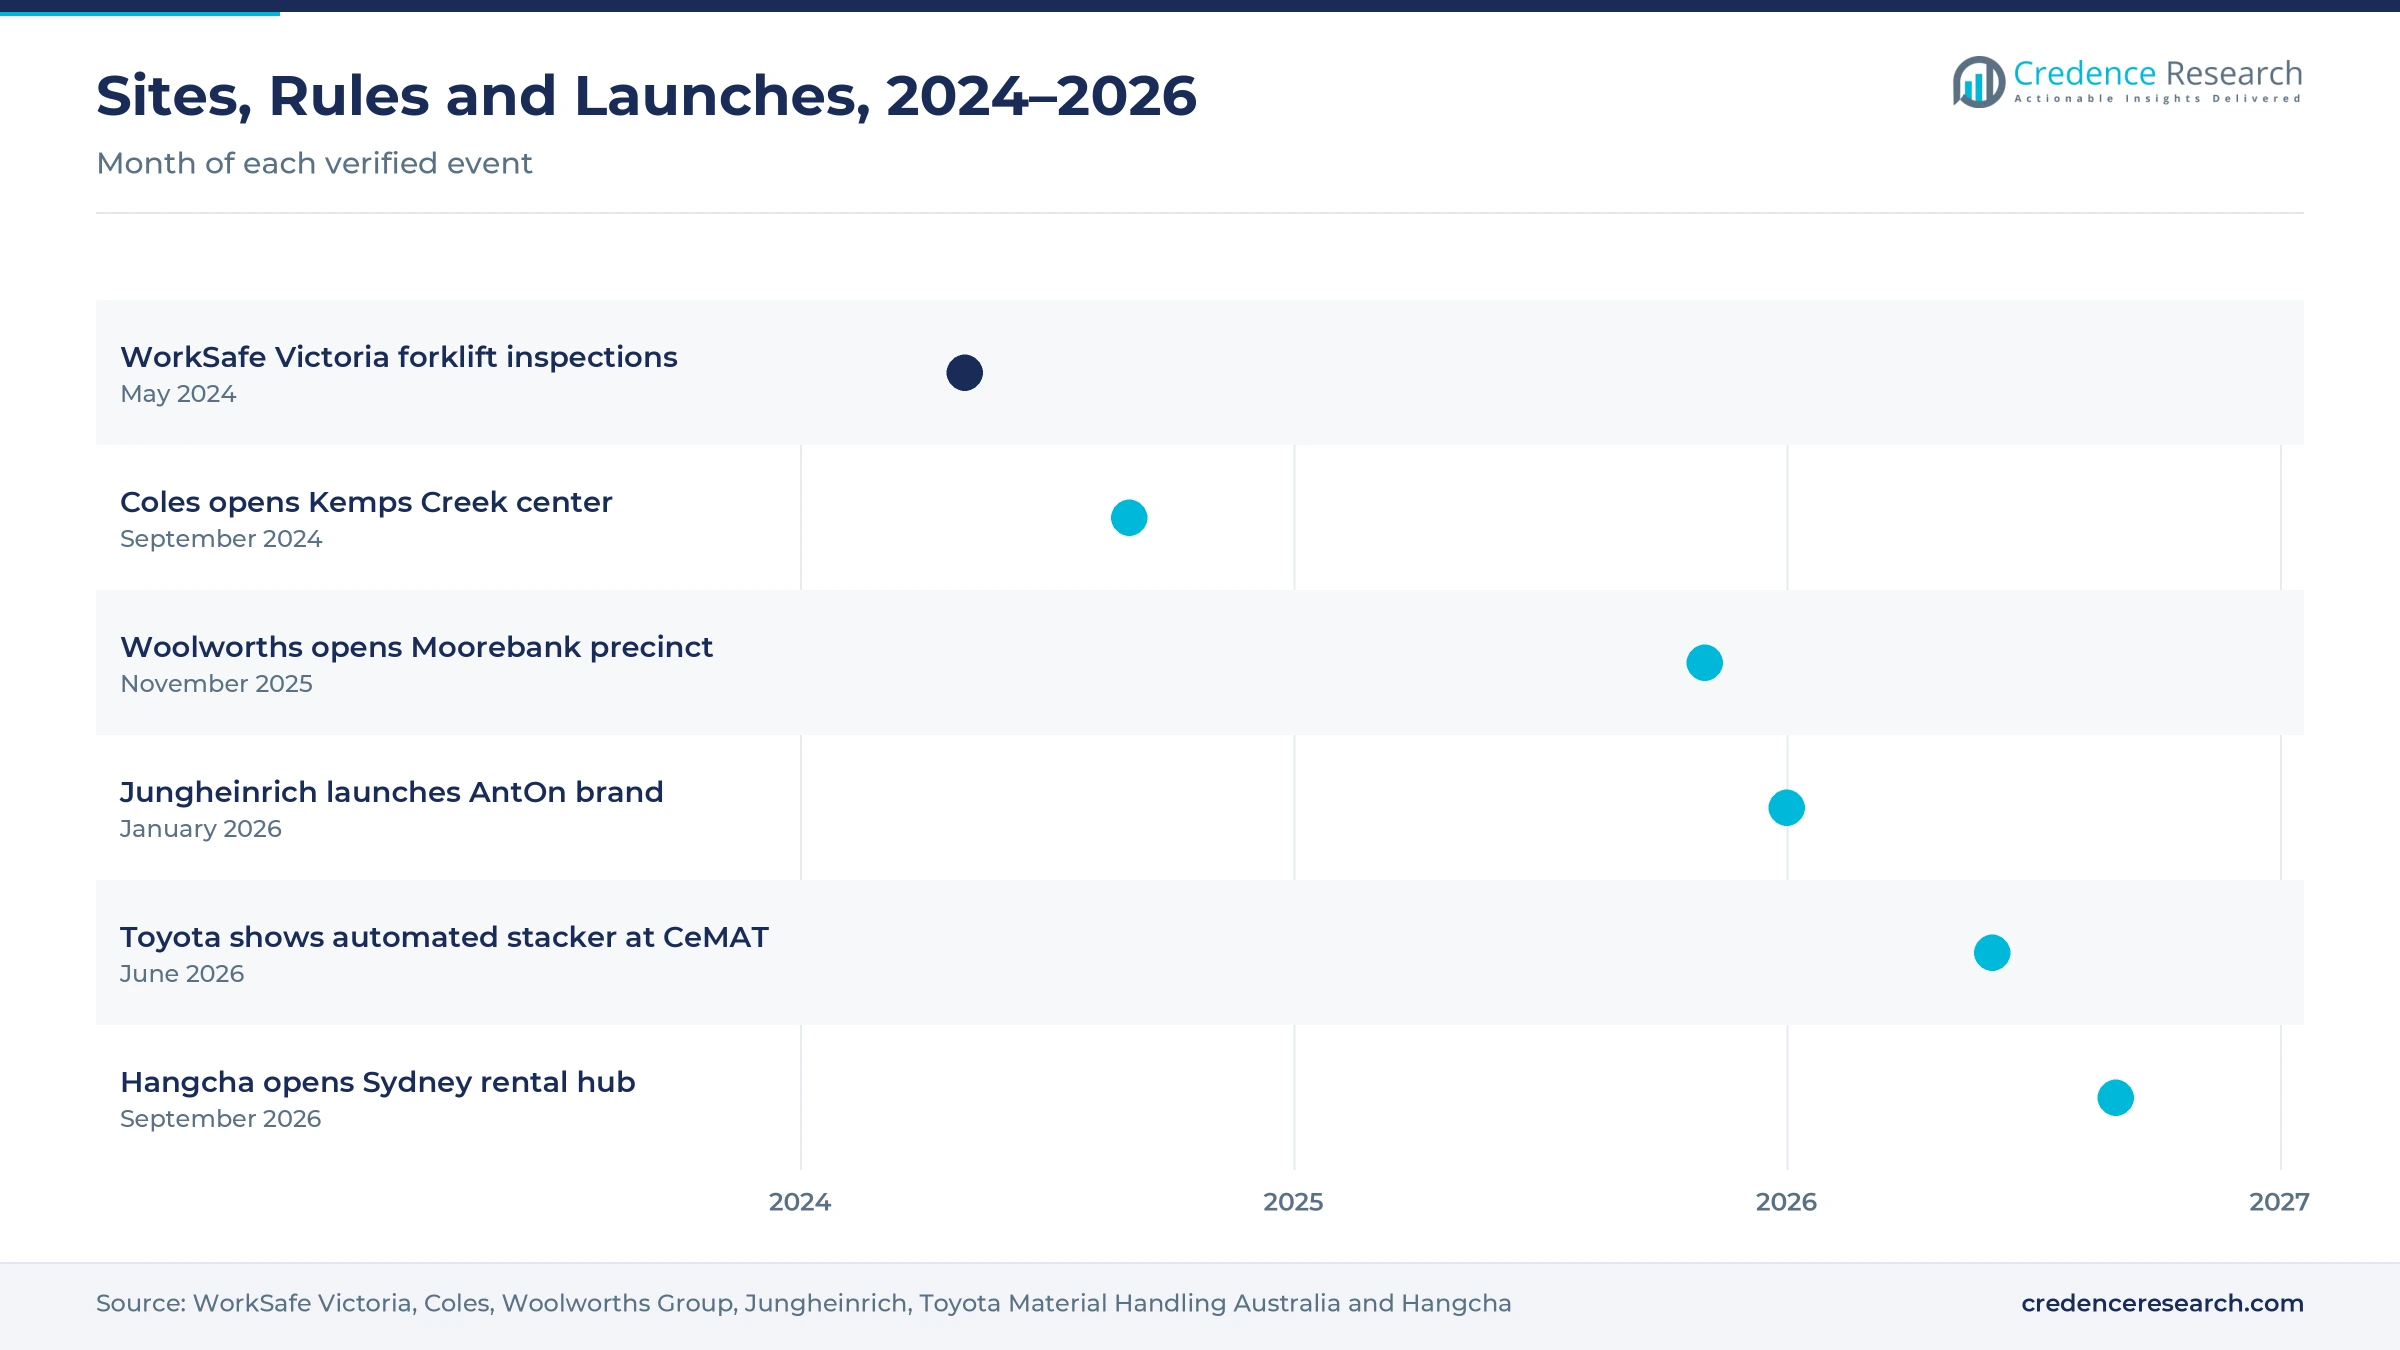
New grocery and parcel distribution centers add large indoor fleets, which lifts demand for battery trucks that run without exhaust inside closed buildings. Woolworths opened its A$1.3 billion Moorebank precinct on Nov. 13, 2025, and Woolworths Group states that it moves more than 5 million cartons a week to more than 1,000 stores. Coles opened its Kemps Creek automated distribution center in September 2024, with capacity for more than four million cartons a week for 229 stores. The warehousing and storage workforce reached 110,600 people in August 2025, according to Jobs and Skills Australia. As a result, Warehousing and Third-Party Logistics led end-use industries with 41.0% of 2025 value.
Why do lithium-ion duty cycles lower fleet running costs?
Lithium-ion packs can be charged in short breaks, which removes battery swaps and spare battery stock from multi-shift sites. Jungheinrich launched its AntOn by Jungheinrich value brand across Asia-Pacific on Jan. 20, 2026, with lithium-ion batteries for rapid charging and counterbalance models from 2,000 to 3,500 kg. The company linked the shift from combustion trucks to electric models in Australia with rising costs and environmental, social and governance expectations. Toyota Material Handling Australia showed an 8FBN lithium-ion counterbalance truck at the CeMAT Australia show in Melbourne in June 2026. As a result, Lithium-Ion Systems led battery technologies with 46.0% of 2025 value and keep gaining ground on lead-acid units.
How is wider load coverage moving heavy work to batteries?
Battery trucks now cover heavier loads, which lets fleet owners replace engine trucks in yards and factories that once needed diesel or LPG. Toyota Material Handling Australia states that its heavy-duty battery counterbalance models lift up to 8 metric tons, and that its electric range comes in lead-acid, lithium-ion and hydrogen fuel cell versions. Komatsu Forklift Australia sells a range from walk-behind pallet movers to a 52-metric-ton container handler and also represents Carer electric trucks. Modulate Group chose three 2.5-metric-ton battery trucks for its container fit-out workshop in October 2025, while keeping diesel units for container moves. In turn, Counterbalance Trucks held 38.0% of 2025 value across product types.
How do safety enforcement and licensing shape fleet choices?
Regulators have stepped up forklift inspections and prosecutions, which pushes owners toward newer trucks with speed limits, operator access control and pedestrian warning systems. WorkSafe Victoria reported in May 2024 that eight people had died in forklift-related incidents since 2019, and it started a state-wide inspection program in manufacturing, postal and warehousing. Courts imposed or accepted fines and undertakings of more than A$2.4 million across 16 forklift prosecutions in the 12 months before that release. In New South Wales, operators need a high risk work license, with separate LF and LO classes, according to SafeWork NSW. Because new trucks come with fleet systems, Direct OEM Sales and Service led sales channels with 47.0% of 2025 value.
Automation, telematics and value lithium brands gain ground
Why are automated stackers on the rise in large sites?
Suppliers now market driverless pallet stackers to large sites, because operators want repeatable moves on long night shifts and fewer people near moving trucks. Toyota Material Handling Australia showed its Staxio SAE160 automatic guided stacker at CeMAT Australia in Melbourne from June 23 to 25, 2026, alongside a lithium-ion counterbalance truck and a reach truck. Woolworths states that automation at Moorebank significantly reduces heavy manual handling across its two Western Sydney distribution centers. Coles built its Kemps Creek site on 66,000 square meters, roughly half the footprint of its two older New South Wales centers. As a result, demand for warehouse automation and battery stackers is rising together in high-volume grocery networks.
How is telematics access control shifting fleet management?
National operators now use software that locks each truck to licensed drivers, which links electric forklift purchases to safety records across many sites. Toyota Material Handling Australia states that Team Global Express runs about 1,000 Toyota trucks under one national account, and its I-Site system denies access when an operator license expires. Team Global Express also limits its fleet to a top speed of 10 km/h through the same system. SEW-EURODRIVE uses more than 30 Toyota trucks, walkie stackers and pallet movers, and it plans to standardize on one provider within one to two years. In turn, Direct OEM Sales and Service stays the leading channel, because national branches bundle telematics with service.
Can value lithium brands open the small-fleet segment?
Lower-priced ranges with built-in lithium packs give suppliers a way into single-site owners that have delayed replacing old engine trucks because of upfront cost. Jungheinrich aimed its AntOn by Jungheinrich range at businesses that want simple, cost-effective equipment for everyday work, with a 1,500 kg pallet truck and counterbalance models up to 3,500 kg. Hangcha opened Hangcha Equipment Rental Australia in Sydney in September 2026, with sales, short- and long-term rental and a 2,100-square-meter local parts warehouse. Hangcha first set up its Australian company in Melbourne in 2022. These moves widen supply of lithium-ion traction packs to buyers outside large OEM accounts.
Is long-term leasing an opening for rental providers?
Long-term leases and short-term hire offer an opening for providers that can carry battery risk and service trucks across several states. Premier Fresh Australia signed its second long-term lease with Toyota Material Handling Australia for more than 120 machines, Toyota said in April 2026. Adaptalift Group, an Australian family-owned business founded in Melbourne in 1979, lists more than 580 staff and about 10,500 units nationwide. Adaptalift also announced its acquisition of Forklogic, a forklift sales, rental and service provider, to strengthen its regional presence. As a result, Direct OEM Sales and Service and rental specialists compete for operators that prefer short-term hire fleets for peak seasons, and Independent Rental and Service Providers grow fastest at 11.12% a year.
Fire concerns, heavy outdoor duty and safety test buyers
How do lithium fire concerns slow battery approvals?
Site insurers and safety teams often link any lithium battery to thermal runaway risk, which delays sign-off for new fleets. Fire and Rescue NSW reported at least 318 lithium-ion battery fires in 2024, up from 272 in 2023 and 165 in 2022, across all device types. In turn, fleet owners ask suppliers for battery management data, charger separation and site risk plans before switching. Suppliers respond with packs built into the truck design and charging rules agreed with the site.
Why do engine trucks keep heavy outdoor work?
Diesel and LPG units still dominate rough yards and container work, because long shifts and heavy loads strain battery capacity. Modulate Group kept diesel trucks, including a 16-metric-ton unit, for container moves after buying battery trucks for indoor work. Reid Stockfeeds took three Linde H25 hydrostatic combustion trucks and three Baoli KBE25 battery trucks in July 2026. As a result, many sites run mixed fleets, which slows the full shift to battery power.
How do pedestrian incidents raise compliance costs?
Collisions with people on foot add cost for every fleet, whatever the power source of the truck. WorkSafe Victoria found that pedestrians accounted for 65 of 157 accepted forklift claims in the year before May 2024, and it released a forklift safety guidebook with its inspection campaign. In turn, buyers must fund exclusion zones, operator training and warning systems as well as new trucks. Suppliers respond with speed limits, blue lights and telematics that record impacts.
Why does the lead-acid installed base delay change?
Many sites still run flooded lead-acid batteries with paid-off chargers and battery rooms, which delays a switch to lithium packs until trucks reach the end of their leases. Manufacturing added only about 5.3% of national GDP in 2025, according to the World Bank, which limits the multi-shift factory work where lithium packs pay back fastest. Demand for motive lead-acid batteries therefore persists in single-shift sites. Suppliers respond with lithium retrofit options and lease terms that spread the higher upfront cost.
New South Wales leads as the resources west grows fastest
| Region | Value, 2025 (USD million) | Share, 2025 | CAGR, 2026–2035 |
|---|---|---|---|
| New South Wales | 246.3 | 32.9% | 10.22% |
| Victoria | 181.9 | 24.3% | 10.47% |
| Queensland | 150.4 | 20.1% | 10.77% |
| Western Australia | 126.5 | 16.9% | 10.92% |
| South Australia and Smaller Jurisdictions | 43.4 | 5.8% | 10.27% |
What keeps New South Wales ahead in fleet spending?
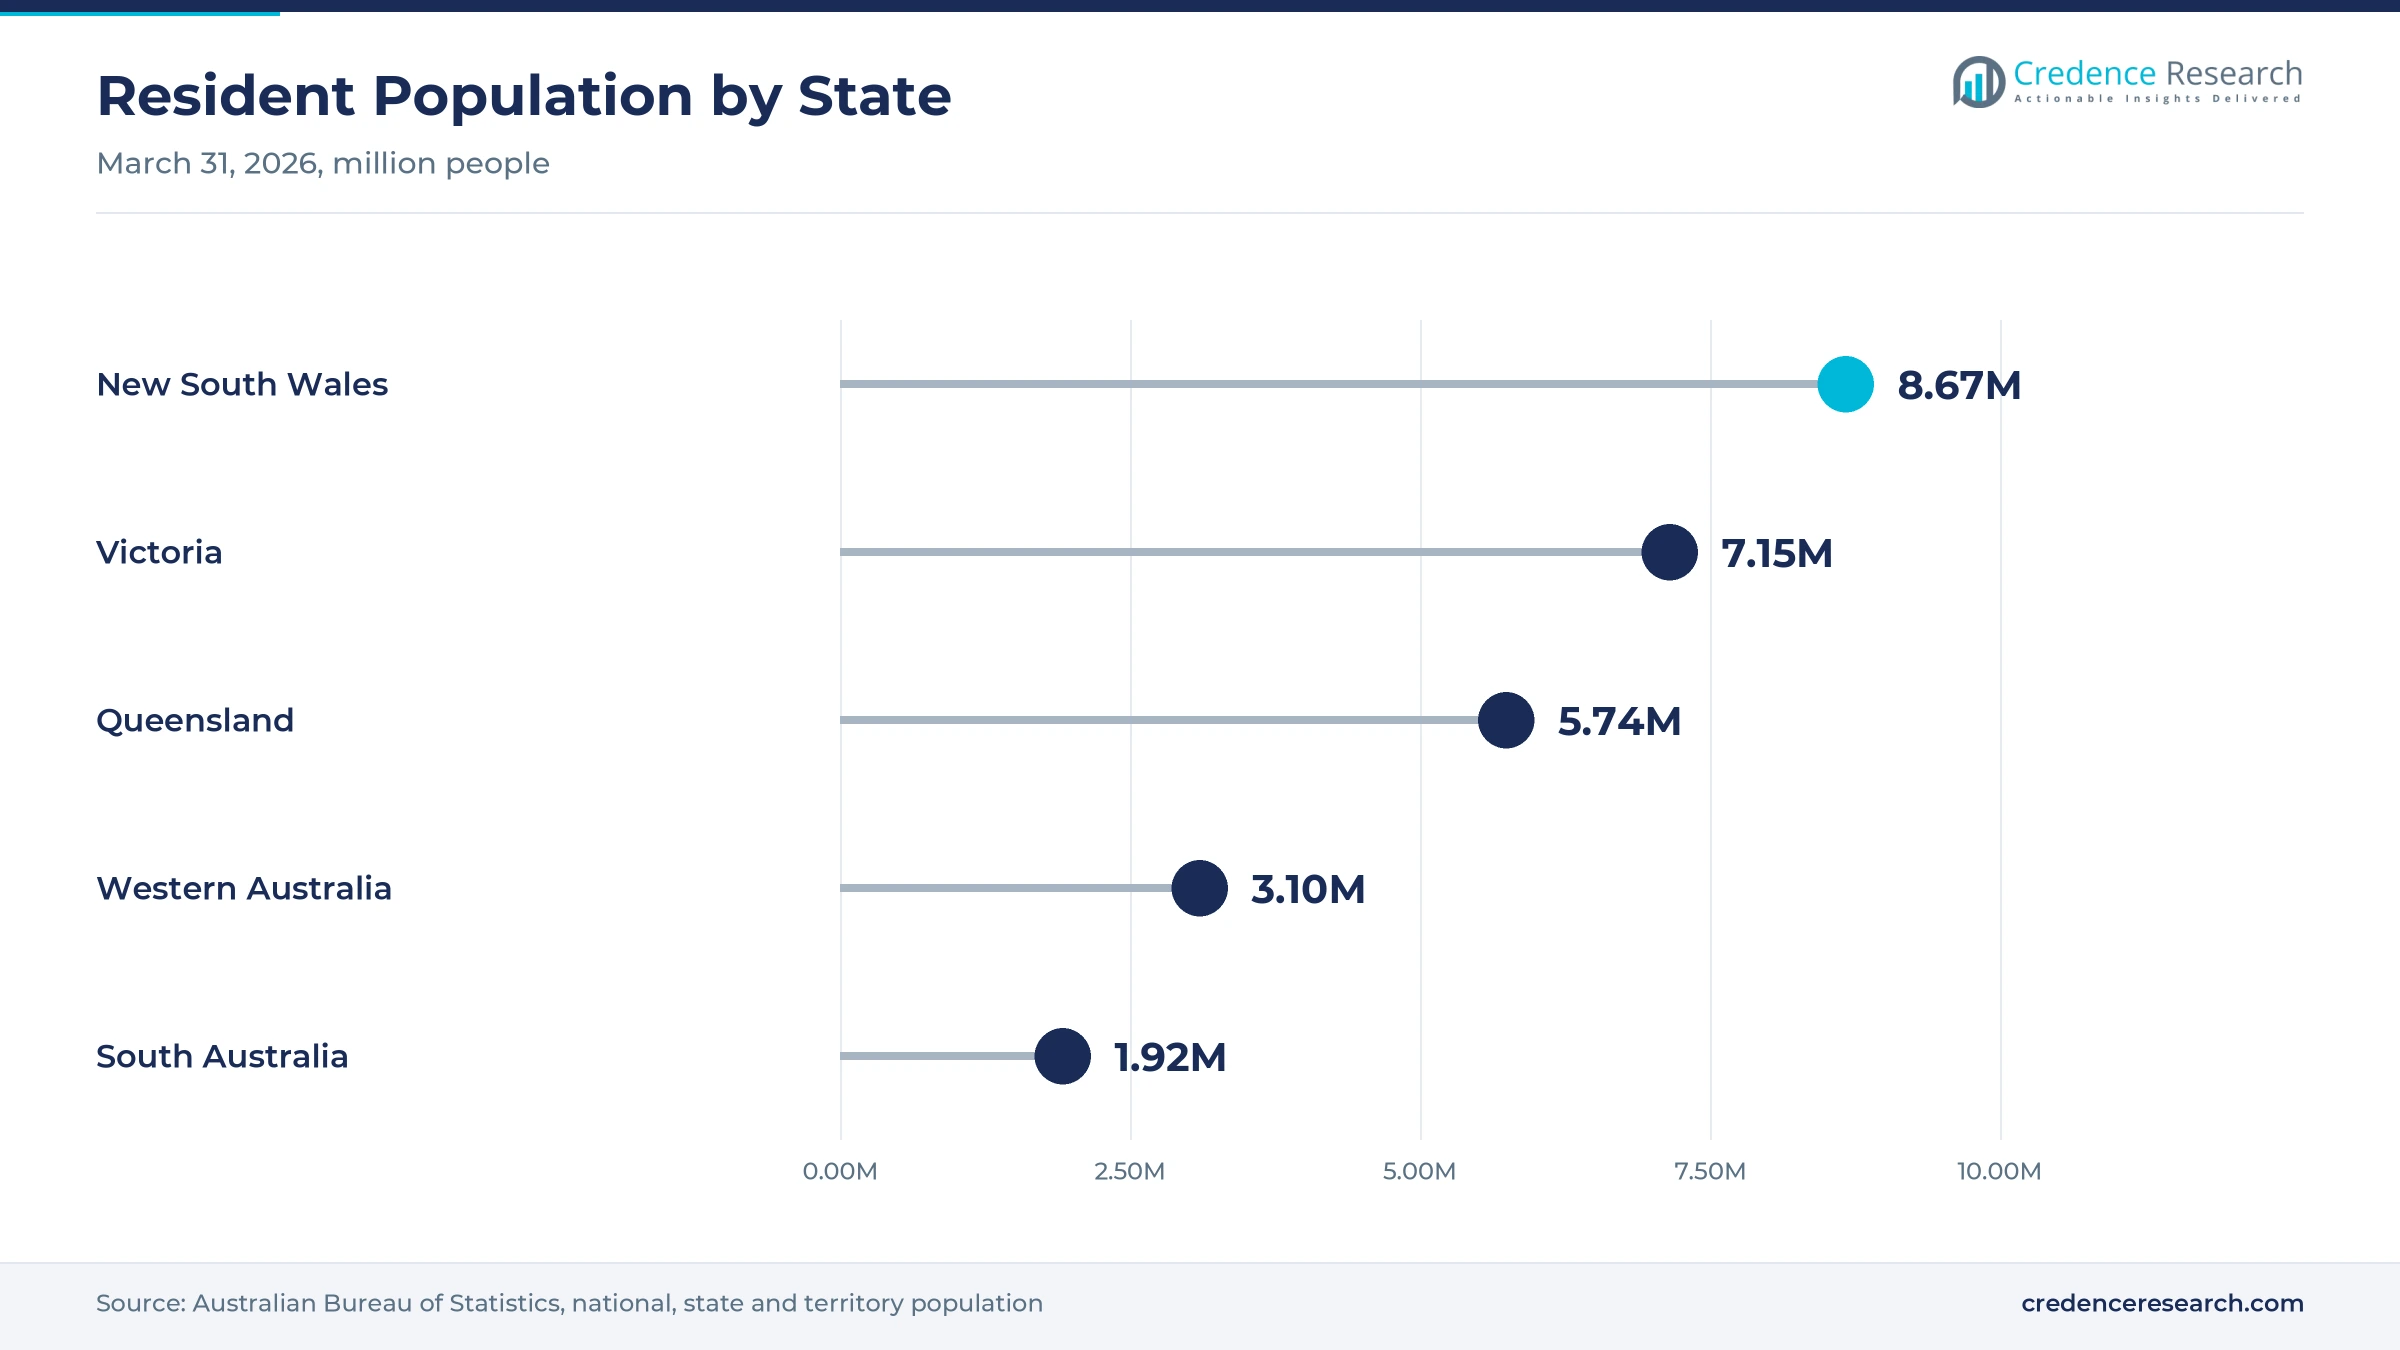
New South Wales held 32.9% of 2025 value and grows at 10.22% a year, because Western Sydney hosts the largest cluster of new grocery and parcel distribution centers. Woolworths opened its Moorebank precinct in November 2025, after Coles opened Kemps Creek in September 2024. The state had 8,670,100 residents on March 31, 2026, according to the Australian Bureau of Statistics. Toyota Material Handling Australia lists its national address in Moorebank, close to many of these sites.
How does Victoria support warehouse fleet renewal?
Victoria held a 24.3% share of 2025 value and grows at 10.47% a year, as Melbourne's outer industrial suburbs keep adding logistics space. The state had 7,154,200 residents on March 31, 2026, after growth of 1.6% over the year. WorkSafe Victoria launched a state-wide forklift inspection program in May 2024, which pushes owners to renew older trucks. Hangcha set up its Australian company in Melbourne in 2022.
Why does Queensland add battery trucks quickly?
Queensland held a 20.1% share of 2025 value and grows at 10.77% a year, because population growth and parcel networks around Brisbane lift warehouse demand. The state had 5,739,500 residents on March 31, 2026, after growth of 1.6% over the year. Team Global Express runs more than 80 pieces of Toyota equipment at its Karawatha site in Brisbane. As a result, both national OEM branches and dealers expand service teams in the state.
Why do Perth and the resources west grow fastest?
Western Australia held a 16.9% share of 2025 value and grows fastest at 10.92% a year, because resources supply chains and population growth lift warehouse demand. The state had 3,096,200 residents on March 31, 2026, after growth of 2.1%, the fastest rate nationally. United Forklift and Access Solutions has a Perth office and operations in all states. In turn, Credence Research expects resources suppliers to add battery trucks for indoor stores and workshops.
What shapes demand across the smaller jurisdictions?
South Australia and the smaller jurisdictions held 5.8% of 2025 value and grow at 10.27% a year. South Australia had 1,916,800 residents on March 31, 2026, while Tasmania grew only 0.6% over the year. Tasmanian retailer Shiploads runs 35 handling machines, all battery electric and it cites lower power costs from Tasmania's hydroelectric network. As a result, small fleets here often rely on rental and dealer service.
New sites, brand launches and rental hubs, 2024–2026
| Development | Status and market relevance |
|---|---|
| In September 2024, Coles opened its Kemps Creek automated distribution center in Western Sydney, with capacity for more than four million cartons a week for 229 stores. | Adds a high-volume grocery site that relies on automated handling and battery trucks |
| In November 2025, Woolworths opened its Moorebank Logistics Precinct, with two automated distribution centers covering 75,000 square meters and about 800 operational roles. | Expands battery truck demand in the largest regional market |
| In January 2026, Jungheinrich launched AntOn by Jungheinrich in Asia-Pacific, with lithium-ion counterbalance trucks from 2,000 to 3,500 kg and a 1,500 kg pallet truck. | Opens a value-tier lithium option for smaller fleet owners |
| In June 2026, Toyota Material Handling Australia showed its Staxio SAE160 automatic guided stacker and an 8FBN lithium-ion truck at CeMAT Australia in Melbourne. | Signals growing interest in automated and lithium-ion trucks |
| In September 2026, Hangcha opened Hangcha Equipment Rental Australia in Sydney, with sales, rental and a 2,100-square-meter parts warehouse. | Adds rental capacity and parts supply in New South Wales |
Lithium-ion packs displace flooded lead-acid batteries
- Lithium-ion systems charge during breaks without battery swaps, and new value-tier counterbalance trucks from Jungheinrich ship with lithium packs for rapid charging.
- Flooded lead-acid systems remain common in older fleets, because many sites already have charging rooms and staff trained to water and change batteries.
- Sealed lead-acid systems suit light pallet trucks and stackers in sites that want low maintenance without a full move to lithium packs.
- Fleet telematics such as Toyota I-Site lets owners limit speed, track impacts and block operators whose license has expired.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
National OEM networks and dealers compete on service reach
Competition for electric forklift fleets is led by national OEM subsidiaries that combine their own branches, long-term leases and fleet software. Toyota Material Handling Australia runs a national network from Moorebank and manages about 1,000 trucks for Team Global Express under one account. Crown Equipment marked 60 years in Australia in 2026 and uses Australia as one of four regional headquarters. Jungheinrich added its AntOn value brand in January 2026, and Hangcha opened a Sydney rental and parts business in September 2026. Linde Material Handling supplies mixed fleets, as in its July 2026 order for Reid Stockfeeds. Adaptalift Group sells Hyster and Yale trucks, while Komatsu Forklift Australia is the exclusive Komatsu distributor. Fork Force sells used electric forklifts and other trucks to buyers across the country. Rivals compete on branch reach, battery choice, lease terms and technician response times.
Which suppliers compete for battery truck fleets?
| Company | Type | Role in the market |
|---|---|---|
| Toyota Material Handling Australia | OEM subsidiary | National branches, leases and I-Site telematics from a Moorebank head office |
| Crown Equipment Australia | OEM subsidiary | Regional headquarters with own branches and V-Force lithium-ion products |
| Jungheinrich Australia | OEM subsidiary | Lithium-ion trucks and the AntOn value brand launched in January 2026 |
| Linde Material Handling Australia | OEM subsidiary | Supplies mixed battery and combustion fleets, including Baoli units |
| Adaptalift Group | Authorized dealer | Family-owned Hyster and Yale distributor with about 10,500 units nationwide |
| Komatsu Forklift Australia | Exclusive distributor | Komatsu range up to 52-metric-ton container handlers, plus Carer electric trucks |
| Hangcha Australia | OEM subsidiary | Melbourne company since 2022 and Sydney rental hub since September 2026 |
| United Forklift and Access Solutions | Independent provider | Forklift and access equipment sales and service in all states |
| Fork Force Australia | Independent provider | Used truck sales across the country, including battery models |
Credence Research view on battery truck adoption
Credence Research's view is that Australian demand for battery trucks will grow quickly because new distribution centers, lithium-ion packs and stricter safety enforcement all favor electric fleets. Counterbalance trucks remain the largest value pool, while very narrow aisle trucks add the fastest growth as high-bay sites spread. Suppliers with national branches, telematics and lease finance should hold share, while value-tier brands widen choice for small fleets. Mixed fleets and lithium fire concerns will slow the switch in heavy outdoor work and older sites.
How the national battery truck estimate was built
The report uses 2025 as the base year on a calendar basis, and market values come from the Credence Research model. That model combines distribution center openings, state population data, warehousing workforce data, supplier product ranges and company disclosures. Segment splits and zone growth rates are Credence Research estimates, while zone shares follow the regional split defined for this report. Sources used are government regulators, official statistics, international agency data, trade press and company publications, and no interviews or surveys were used.
Lithium fleets and automated sites carry growth to 2035
Value across Australian battery truck fleets is expected to reach USD 2.07 billion by 2035, a 10.52% CAGR during 2026–2035, as new distribution centers, lithium-ion packs and safety rules widen adoption. Growth should be strongest where population and resources supply chains expand together, led by Western Australia. Lithium-ion systems will take a larger share of new trucks, while lead-acid units will shrink to light and single-shift work. Suppliers that combine leases, telematics and fast service should gain the most from the shift.
Frequently Asked Questions
How big is the Australia electric forklift market?
Which product type leads battery truck spending?
Which state leads battery truck spending in Australia?
Do operators need a license to drive these trucks?
Why are buyers moving from lead-acid to lithium-ion packs?
Which industries buy the most battery trucks?
Which companies supply battery trucks in Australia?
What are the main challenges for battery truck adoption?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Product Type
- 1.2.1 Counterbalance Trucks
- 1.2.2 Reach Trucks
- 1.2.3 Order Pickers
- 1.2.4 Rider Pallet Trucks and Stackers
- 1.2.5 Very Narrow Aisle Trucks
- 1.3 By End-Use Industry
- 1.3.1 Warehousing and Third-Party Logistics
- 1.3.2 Manufacturing
- 1.3.3 Mining and Resources
- 1.3.4 Retail Distribution
- 1.3.5 Construction and Field Services
- 1.4 By Technology
- 1.4.1 Lithium-Ion Systems
- 1.4.2 Flooded Lead-Acid Systems
- 1.4.3 Sealed Lead-Acid Systems
- 1.5 By Sales Channel
- 1.5.1 Direct OEM Sales and Service
- 1.5.2 Authorized Dealer Sales and Service
- 1.5.3 Independent Rental and Service Providers
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2025: USD 748.5 million → 2035: USD 2.07 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Historical Period: 2018-2025
- 2.6.2 Base Year: 2025
- 2.6.3 Forecast Period: 2025-2035
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2025
- 3.3 Forecast Market Size, 2035
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Australia Electric Forklift Market Trends and Developments
- 4.1 Historical Industry Development, 2018-2025
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Australia Electric Forklift Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis, 2018-2025
- 5.2 Demand Forecast, 2025-2035
- 5.3 Production and Output Trend, 2018-2025
- 5.4 Production and Output Forecast, 2025-2035
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Australia Electric Forklift Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends, 2018-2025
- 6.3 Pricing Outlook, 2025-2035
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Australia Electric Forklift Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Australia Electric Forklift Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Australia Electric Forklift Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Australia Electric Forklift Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Australia Electric Forklift Market Outlook, 2025-2035
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2025: USD 748.5 million → 2035: USD 2.07 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size, 2018-2025
- 11.1.4 Base-Year Market Size, 2025
- 11.2 Market Forecast, 2025-2035
- 11.2.1 Revenue Forecast to 2035
- 11.2.2 Volume Forecast to 2035
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Australia Electric Forklift Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2025
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Product Type - Market Size and Forecast, 2025-2035
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size, 2018-2025
- 12.3.3 Revenue Forecast, 2025-2035
- 12.3.4 Volume Forecast, 2025-2035
- 12.3.5 Base-Year Market Share, 2025
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Counterbalance Trucks
- 12.3.7.2 Reach Trucks
- 12.3.7.3 Order Pickers
- 12.3.7.4 Rider Pallet Trucks and Stackers
- 12.3.7.5 Very Narrow Aisle Trucks
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By End-Use Industry - Market Size and Forecast, 2025-2035
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size, 2018-2025
- 12.4.3 Revenue Forecast, 2025-2035
- 12.4.4 Volume Forecast, 2025-2035
- 12.4.5 Base-Year Market Share, 2025
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Warehousing and Third-Party Logistics
- 12.4.7.2 Manufacturing
- 12.4.7.3 Mining and Resources
- 12.4.7.4 Retail Distribution
- 12.4.7.5 Construction and Field Services
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Technology - Market Size and Forecast, 2025-2035
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size, 2018-2025
- 12.5.3 Revenue Forecast, 2025-2035
- 12.5.4 Volume Forecast, 2025-2035
- 12.5.5 Base-Year Market Share, 2025
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Lithium-Ion Systems
- 12.5.7.2 Flooded Lead-Acid Systems
- 12.5.7.3 Sealed Lead-Acid Systems
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Sales Channel - Market Size and Forecast, 2025-2035
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size, 2018-2025
- 12.6.3 Revenue Forecast, 2025-2035
- 12.6.4 Volume Forecast, 2025-2035
- 12.6.5 Base-Year Market Share, 2025
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Direct OEM Sales and Service
- 12.6.7.2 Authorized Dealer Sales and Service
- 12.6.7.3 Independent Rental and Service Providers
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Australia Electric Forklift End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Australia Electric Forklift Geographic Market Outlook, 2025-2035
- 14.1 Domestic Market Distribution and Demand Clusters
- 14.2 State- or Province-Wise Market Size and Forecast, 2025-2035
- 14.3 City and Metropolitan Market Outlook
- 14.4 Industrial, Manufacturing and Commercial Clusters
- 14.5 Geographic Concentration of Key End Users
- 14.6 Local Pricing and Purchasing Differences
- 14.7 Domestic Production Facilities and Capacity Map
- 14.8 Local Infrastructure and Project Pipeline
- 14.9 State-Level Policy and Incentive Differences
- 14.10 Subnational Investment Hotspots and Opportunities
- 14.11 Distribution and Logistics Networks
- 14.12 Domestic Competitive Footprint
Chapter 15 Australia Electric Forklift Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2025-2035
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Australia Electric Forklift Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2025
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2025-2035
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Linde Material Handling Australia
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Crown Equipment Australia
- 18.4 Adaptalift Group
- 18.5 Toyota Material Handling Australia
- 18.6 Komatsu Forklift Australia
- 18.7 Hangcha Australia
- 18.8 Jungheinrich Australia
- 18.9 Clark Equipment Australia
- 18.10 Fork Force Australia
- 18.11 United Forklift and Access Solutions
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

