
Diesel utes and trucks keep injector demand high
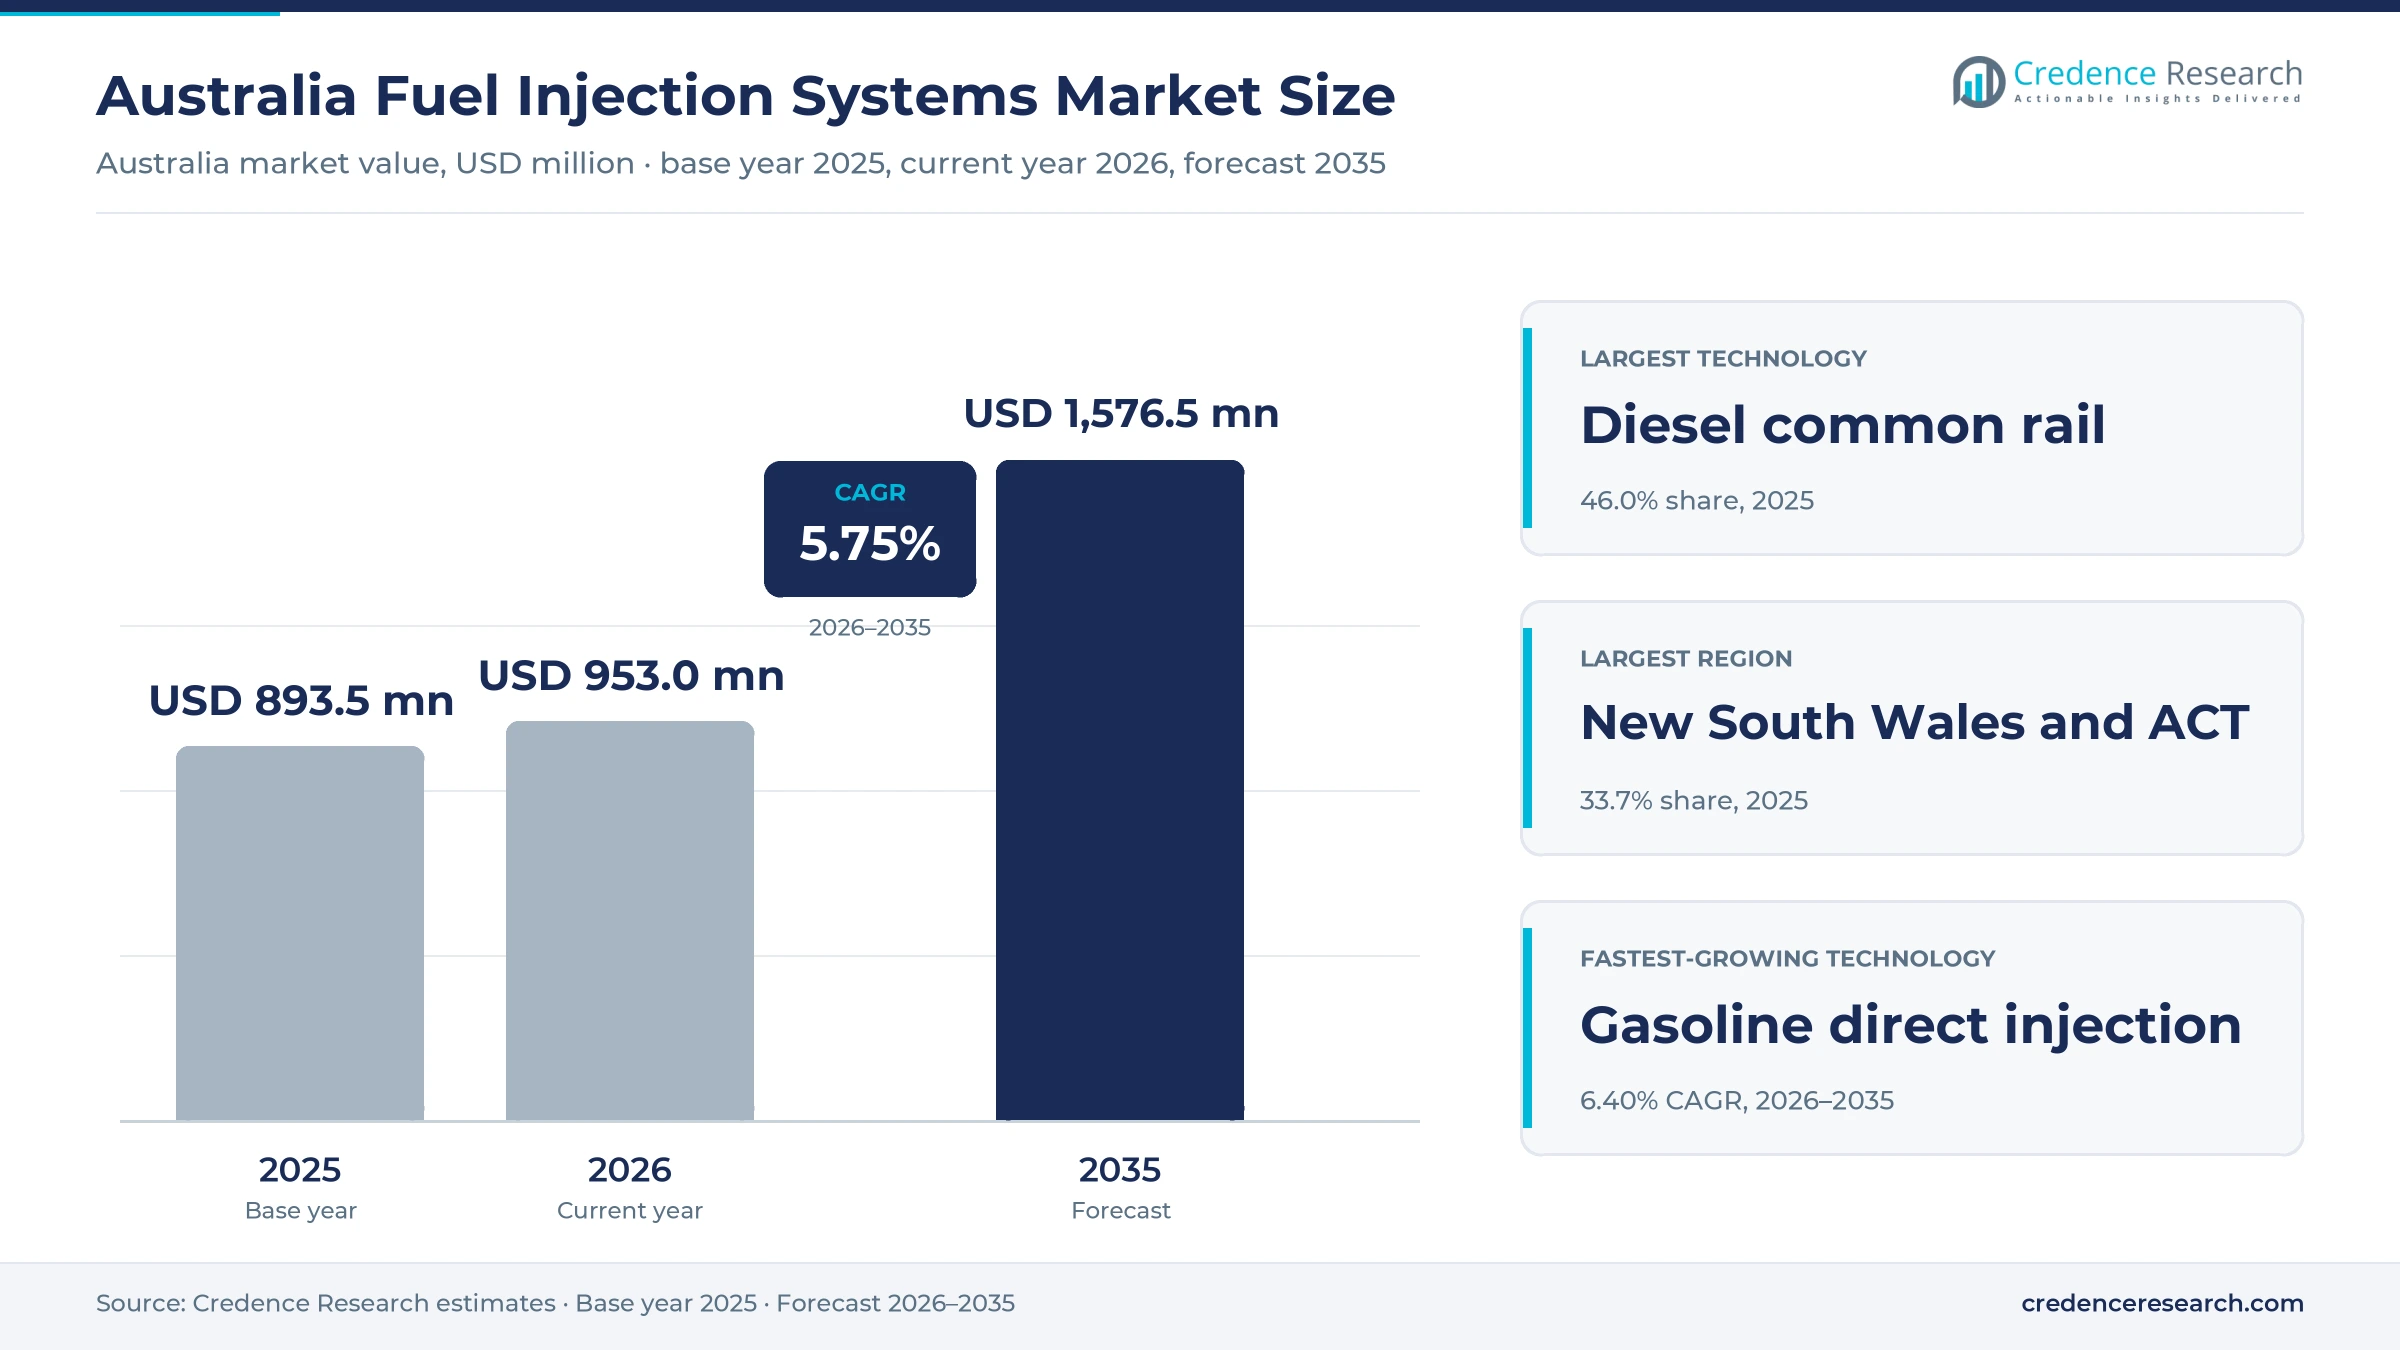
The Australia fuel injection systems market was valued at USD 893.5 million in 2025 and is projected to increase from USD 953.0 million in 2026 to USD 1.58 billion by 2035, registering a CAGR of 5.75% during 2026–2035. Demand comes from vehicle importers, dealer workshops, independent diesel specialists, fleet operators, miners and farmers that buy injectors, pumps and rails for new and aging engines. New South Wales and Australian Capital Territory held the largest regional share, 33.7% in 2025, because Sydney hosts the largest vehicle fleet and the densest network of workshops. Western Australia is the fastest-growing region at 6.09% a year, as mining fleets and population growth lift diesel service work. Rules are also changing, because Euro VI emission limits now apply to all new heavy vehicles and all petrol sold since December 2025 must meet a 10 ppm sulfur limit. As a result, workshops need more precise parts, test benches and calibration tools.
Which injectors, pumps and rails sit inside the estimate?
The estimate measures the value of diesel common rail, gasoline direct, port and specialized injection components sold in Australia, including injectors, high-pressure pumps, rails and control parts. Values cover parts fitted to imported new vehicles and machines as well as replacement, exchange and remanufactured parts bought by workshops and fleets.
The estimate excludes fuel tanks, lift pumps sold on their own, filters, engine control software sold separately and labor charges. The value chain runs from overseas component makers through local subsidiaries, importers, diesel specialists and parts distributors to dealer workshops, independent repairers, fleet depots, mines and farms in every state and territory.
Australia Fuel Injection Systems Market Insights
- The Australia fuel injection systems market was valued at USD 893.5 million in 2025 and is projected to reach USD 1.58 billion by 2035, registering a CAGR of 5.75% during 2026–2035.
- New South Wales and Australian Capital Territory held a 33.7% share of 2025 value, because Sydney hosts the largest fleet and workshop network.
- Diesel common rail led with a 46.0% share of 2025 value, because diesel utes, trucks and machines dominate high-pressure injection demand.
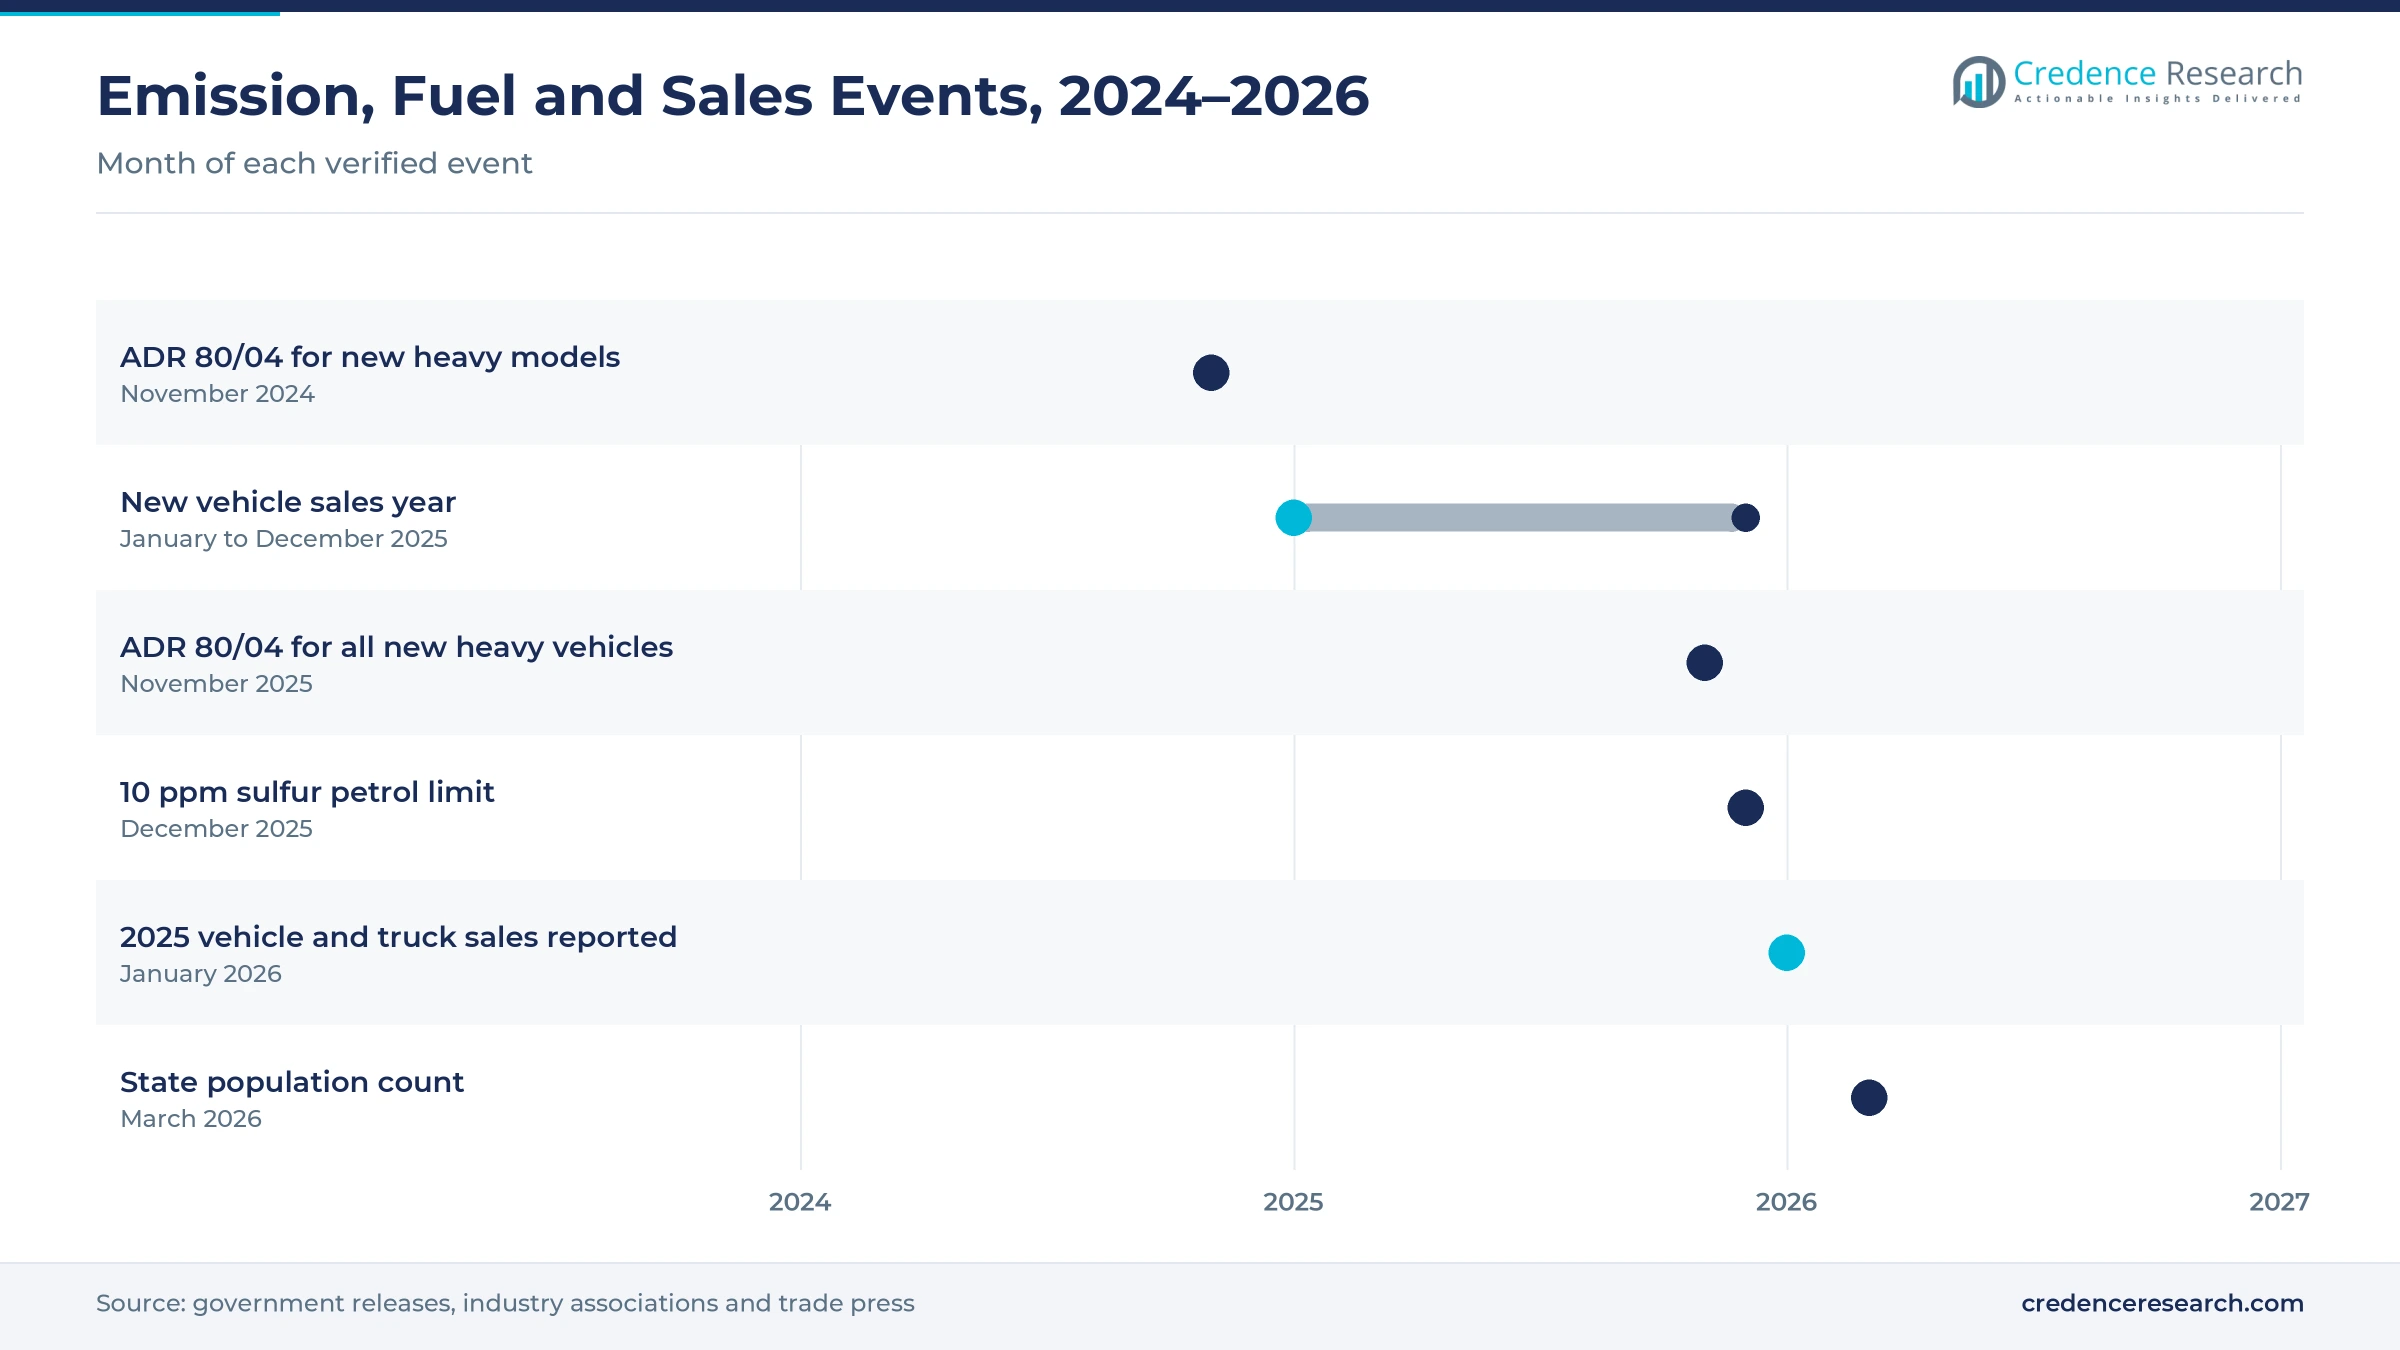
- ADR 80/04 applied Euro VI limits to new heavy vehicle models from Nov. 1, 2024, and to all new heavy vehicles supplied from Nov. 1, 2025.
- Australia had nine Bosch Diesel Centres across five states, which test, calibrate and repair pumps and injectors for diesel owners.
Common rail leads as direct petrol injection grows fastest
Why does diesel common rail lead technology demand?
Based on technology, the market is categorized into diesel common rail, gasoline direct injection, port fuel injection and specialized injection architectures. Diesel Common Rail led with a 46.0% share of 2025 value, because diesel utes, trucks and machines use costly high-pressure parts. Gasoline Direct Injection grows fastest at 6.40% a year, as hybrids and turbocharged petrol engines spread through the fleet.
How do light vehicles dominate parts demand?
Based on vehicle type, the market is categorized into light vehicles, heavy commercial vehicles and off-road equipment. Light Vehicles led with 55.0% of 2025 value, because cars, SUVs and utes make up most of the national fleet. Heavy Commercial Vehicles grows fastest at 5.94% a year, as Euro VI trucks carry more complex injection hardware.
Why does private mobility lead usage demand?
Based on usage type, the market is categorized into private mobility, freight and passenger services, and resource and agricultural operations. Private Mobility led with 46.0% of 2025 value, because households own most cars and utes. Freight and Passenger Services grows fastest at 5.93% a year, as freight and bus fleets run high annual distances that wear injectors faster.
Why does the independent aftermarket lead supply?
Based on sales channel, the market is categorized into embedded OEM supply, independent aftermarket and authorized service parts. Independent Aftermarket led with 45.0% of 2025 value, because diesel specialists and independent workshops service most vehicles after warranty. Authorised Service Parts grows fastest at 6.00% a year, as newer engines need approved parts, coding and dealer test equipment. Embedded OEM supply covers parts already fitted to imported vehicles and machines at the point of sale.
| Segment Group | Leading Sub-segment | Share, 2025 | Fastest-growing Sub-segment | CAGR, 2026–2035 |
|---|---|---|---|---|
| By Technology | Diesel Common Rail | 46.0% | Gasoline Direct Injection | 6.40% |
| By Vehicle Type | Light Vehicles | 55.0% | Heavy Commercial Vehicles | 5.94% |
| By Usage Type | Private Mobility | 46.0% | Freight and Passenger Services | 5.93% |
| By Sales Channel | Independent Aftermarket | 45.0% | Authorised Service Parts | 6.00% |
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Fleet replacement, newer engines and uptime lift demand
How does installed fleet replacement demand sustain sales?
Installed fleet replacement demand sustains sales, because diesel injectors and pumps wear with distance and fuel quality and need testing, exchange or replacement. Australians registered 364,605 new diesel vehicles in 2025, including 231,630 light commercial vehicles, according to The Canberra Times. The Ford Ranger was the best-selling vehicle with 56,555 sales, while the Toyota HiLux sold 51,297, according to the Federal Chamber of Automotive Industries. Light commercial vehicles also took 22.6% of 1,209,808 new vehicle sales in 2025, which adds diesel utes to future service queues. As a result, the independent aftermarket held 45.0% of 2025 value, as workshops that also stock engine air filters replace worn injectors after warranty.
Why does higher-value injection technology raise spending?
Higher-value injection technology raises spending per engine, because direct injection and common rail parts run at far higher pressures than older port designs. Hybrid sales rose 15.3% to 199,133 vehicles in 2025, and plug-in hybrid sales more than doubled to 53,484, according to industry figures, which keeps petrol engines in new models. The federal government also introduced a 10 ppm sulfur limit for all petrol sold from December 2025, which suits modern engines with sensitive after-treatment. Delphi, a PHINIA brand, lists more than 1,000 new diesel injection units and more than 300 remanufactured units for Asia Pacific, covering Euro 3 to Euro 7 engines. In turn, gasoline direct injection grows fastest at 6.40% a year, as these engines spread through the fleet.
How do heavy-duty uptime requirements lift demand?
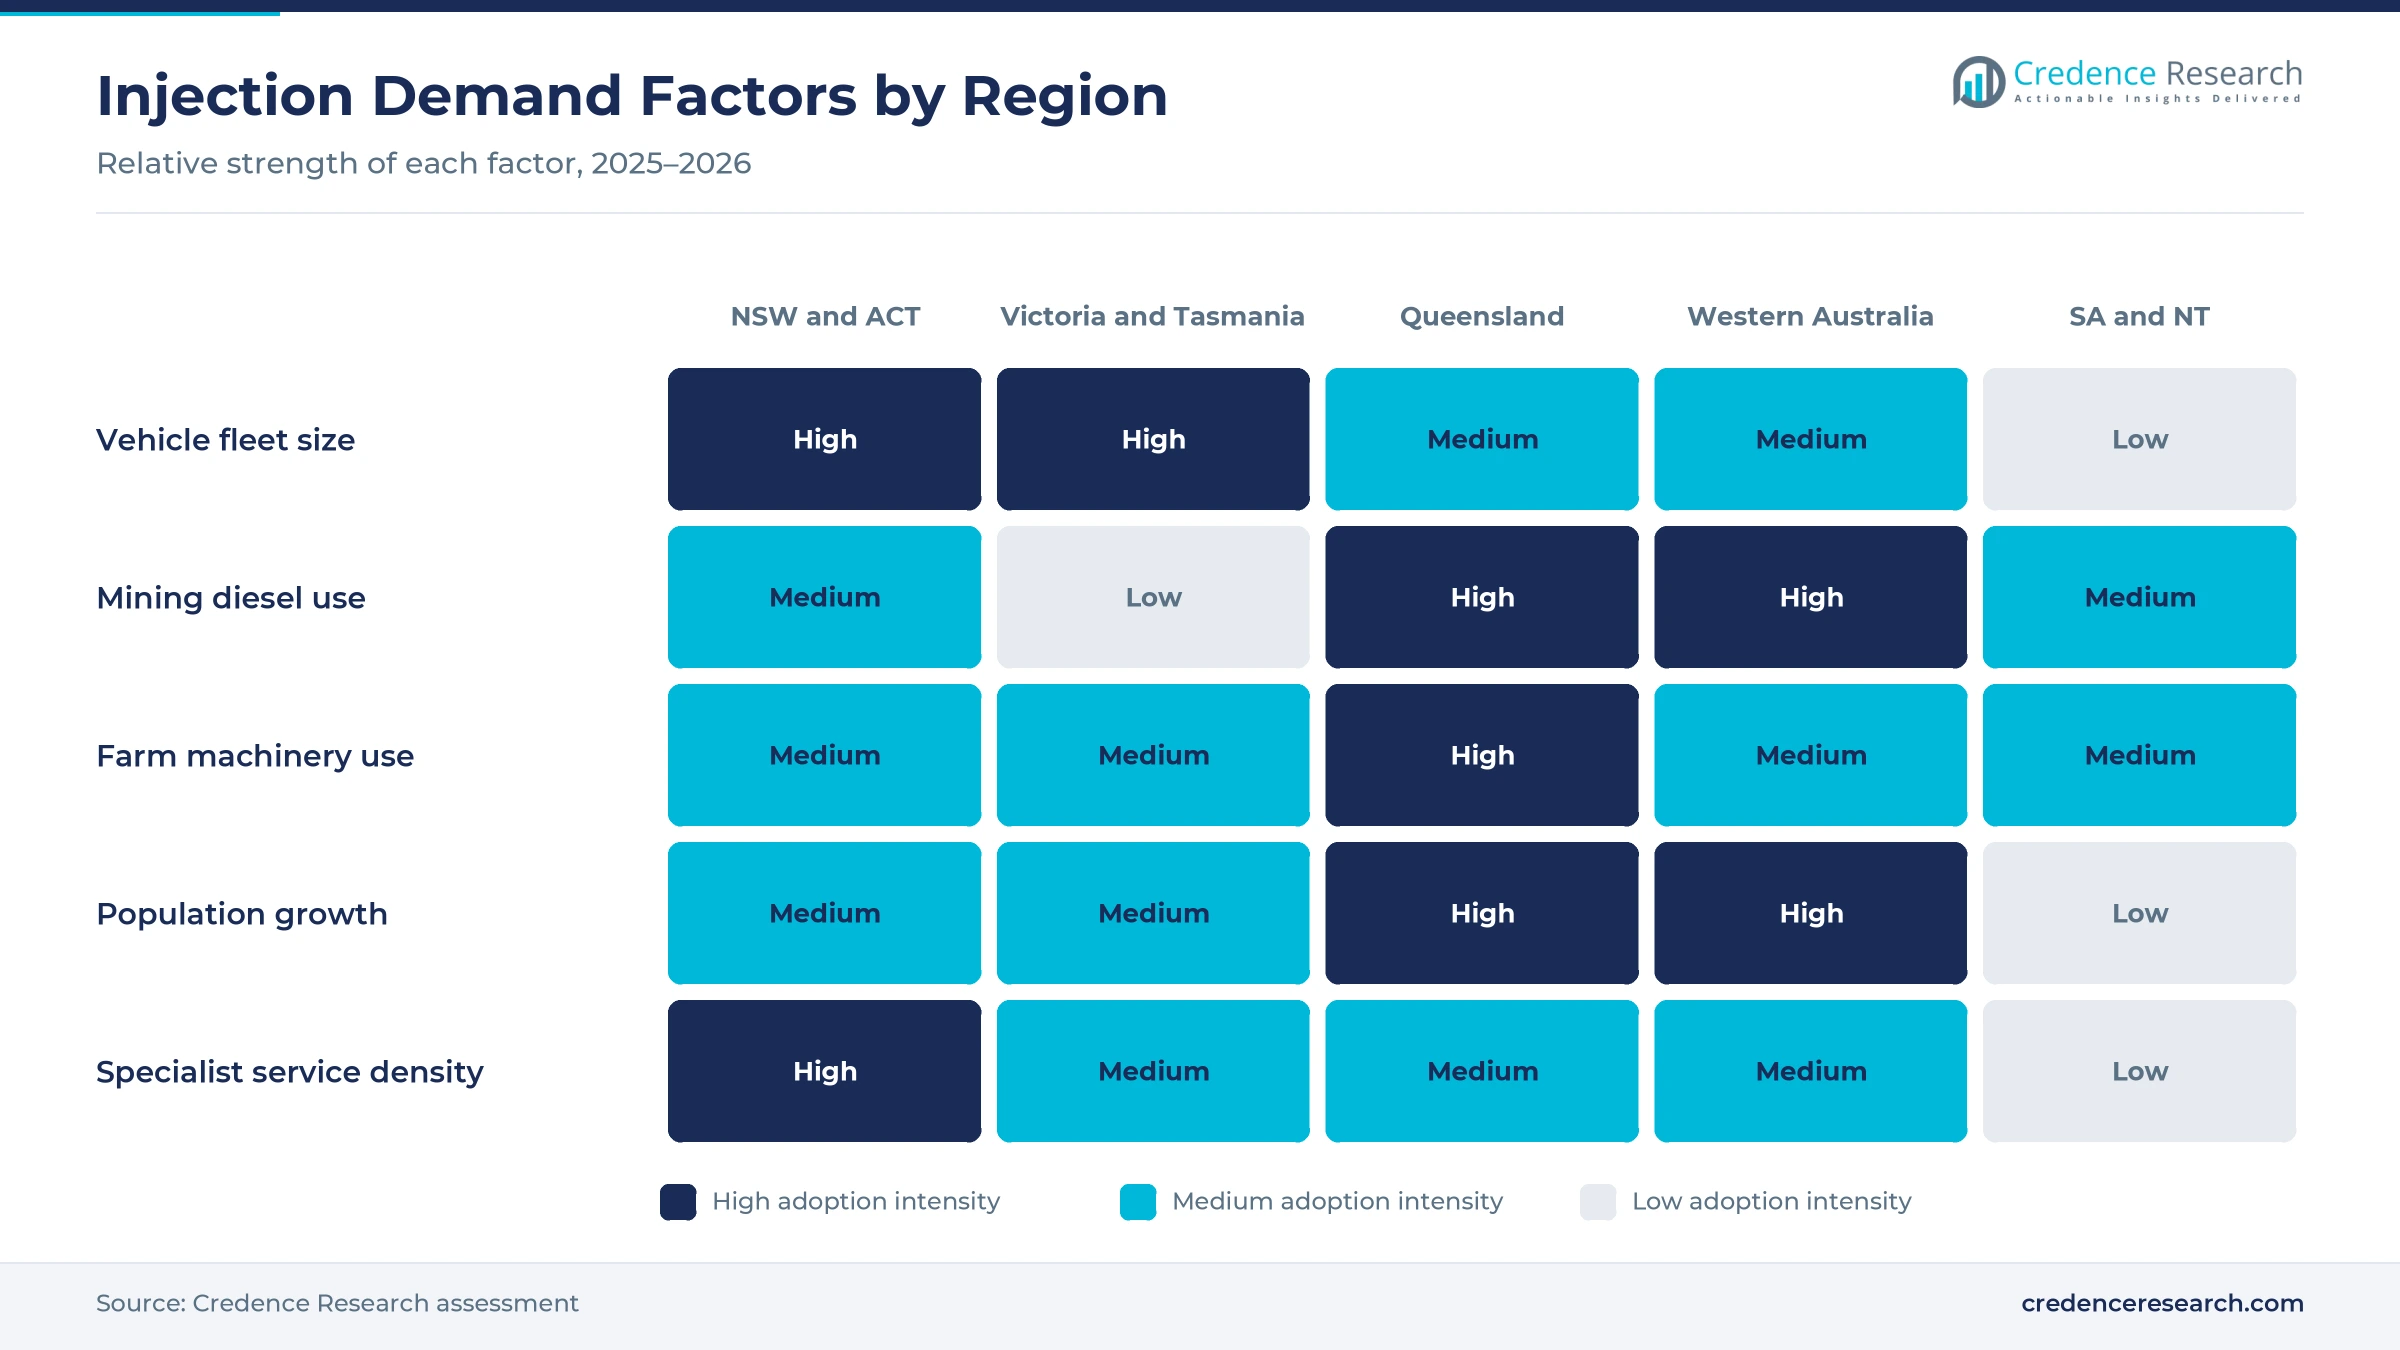
Heavy-duty uptime requirements lift demand, because trucks, buses and mining machines lose revenue every hour an engine stops. ADR 80/04 introduced Euro VI limits to new heavy vehicle models from Nov. 1, 2024, and to all new heavy vehicles from Nov. 1, 2025, according to the federal infrastructure department. The rule cuts nitrogen oxide limits by about 80% from Euro V and adds stronger on-board diagnostics. Truck Industry Council data show 45,191 new trucks and heavy vans sold in 2025, including 14,297 heavy-duty trucks. United Fuel Injection in Perth tests CAT, Cummins and MTU injectors and runs exchange programs to reduce downtime. As a result, heavy commercial vehicles grow fastest at 5.94% a year.
Why do resource and farm operations add steady demand?
Resource and farm operations add steady demand, because diesel engines power haul trucks, tractors, harvesters and generators in remote areas. The gross value of agricultural production was expected to reach about A$101 billion in 2025-26, according to the Australian Bureau of Agricultural and Resource Economics and Sciences. Industry, including mining and construction, made up about 23.9% of GDP in 2025, according to World Bank data. Engineering construction work done was also about A$37.2 billion in the June quarter of 2026. Denco Diesel and Turbo says it serves mining, heavy haulage and farm machinery buyers. In turn, resource and agricultural buyers keep high-hour engines in service, which sustains steady demand for replacement injectors and pumps.
Hybrids, remanufacturing and Euro VI reshape service work
How is the shift toward hybrid drivetrains changing demand?
The shift toward hybrid drivetrains is changing demand, because hybrids still carry petrol engines with modern injection hardware while battery electric cars carry none. Hybrid sales reached 199,133 in 2025, up 15.3%, which adds many direct and port injection engines to the fleet. Plug-in hybrid sales more than doubled to 53,484 units over the same year. Battery electric sales reached 103,269 units from all sources, which removes injection demand from part of each new vehicle cohort. As a result, gasoline direct injection gains share of petrol engine demand, while port fuel injection grows more slowly as older designs leave the fleet.
Why is the rise of remanufacturing and exchange notable?
The rise of remanufacturing and exchange programs is notable, because fleets want quick swaps instead of waiting for repairs on high-pressure parts. Delphi lists more than 300 remanufactured diesel injection units and more than 3,600 spare parts for Asia Pacific workshops. Denco Diesel and Turbo offers a Bosch exchange program for pumps and says it holds more than 3,500 genuine turbocharger and injection products. United Fuel Injection also runs exchange programs for mining fleets to reduce cost and downtime. In turn, authorized service parts grow fastest at 6.00% a year, as workshops pair exchange units with turbocharger servicing.
Is there room to grow in Western Australia and Queensland?
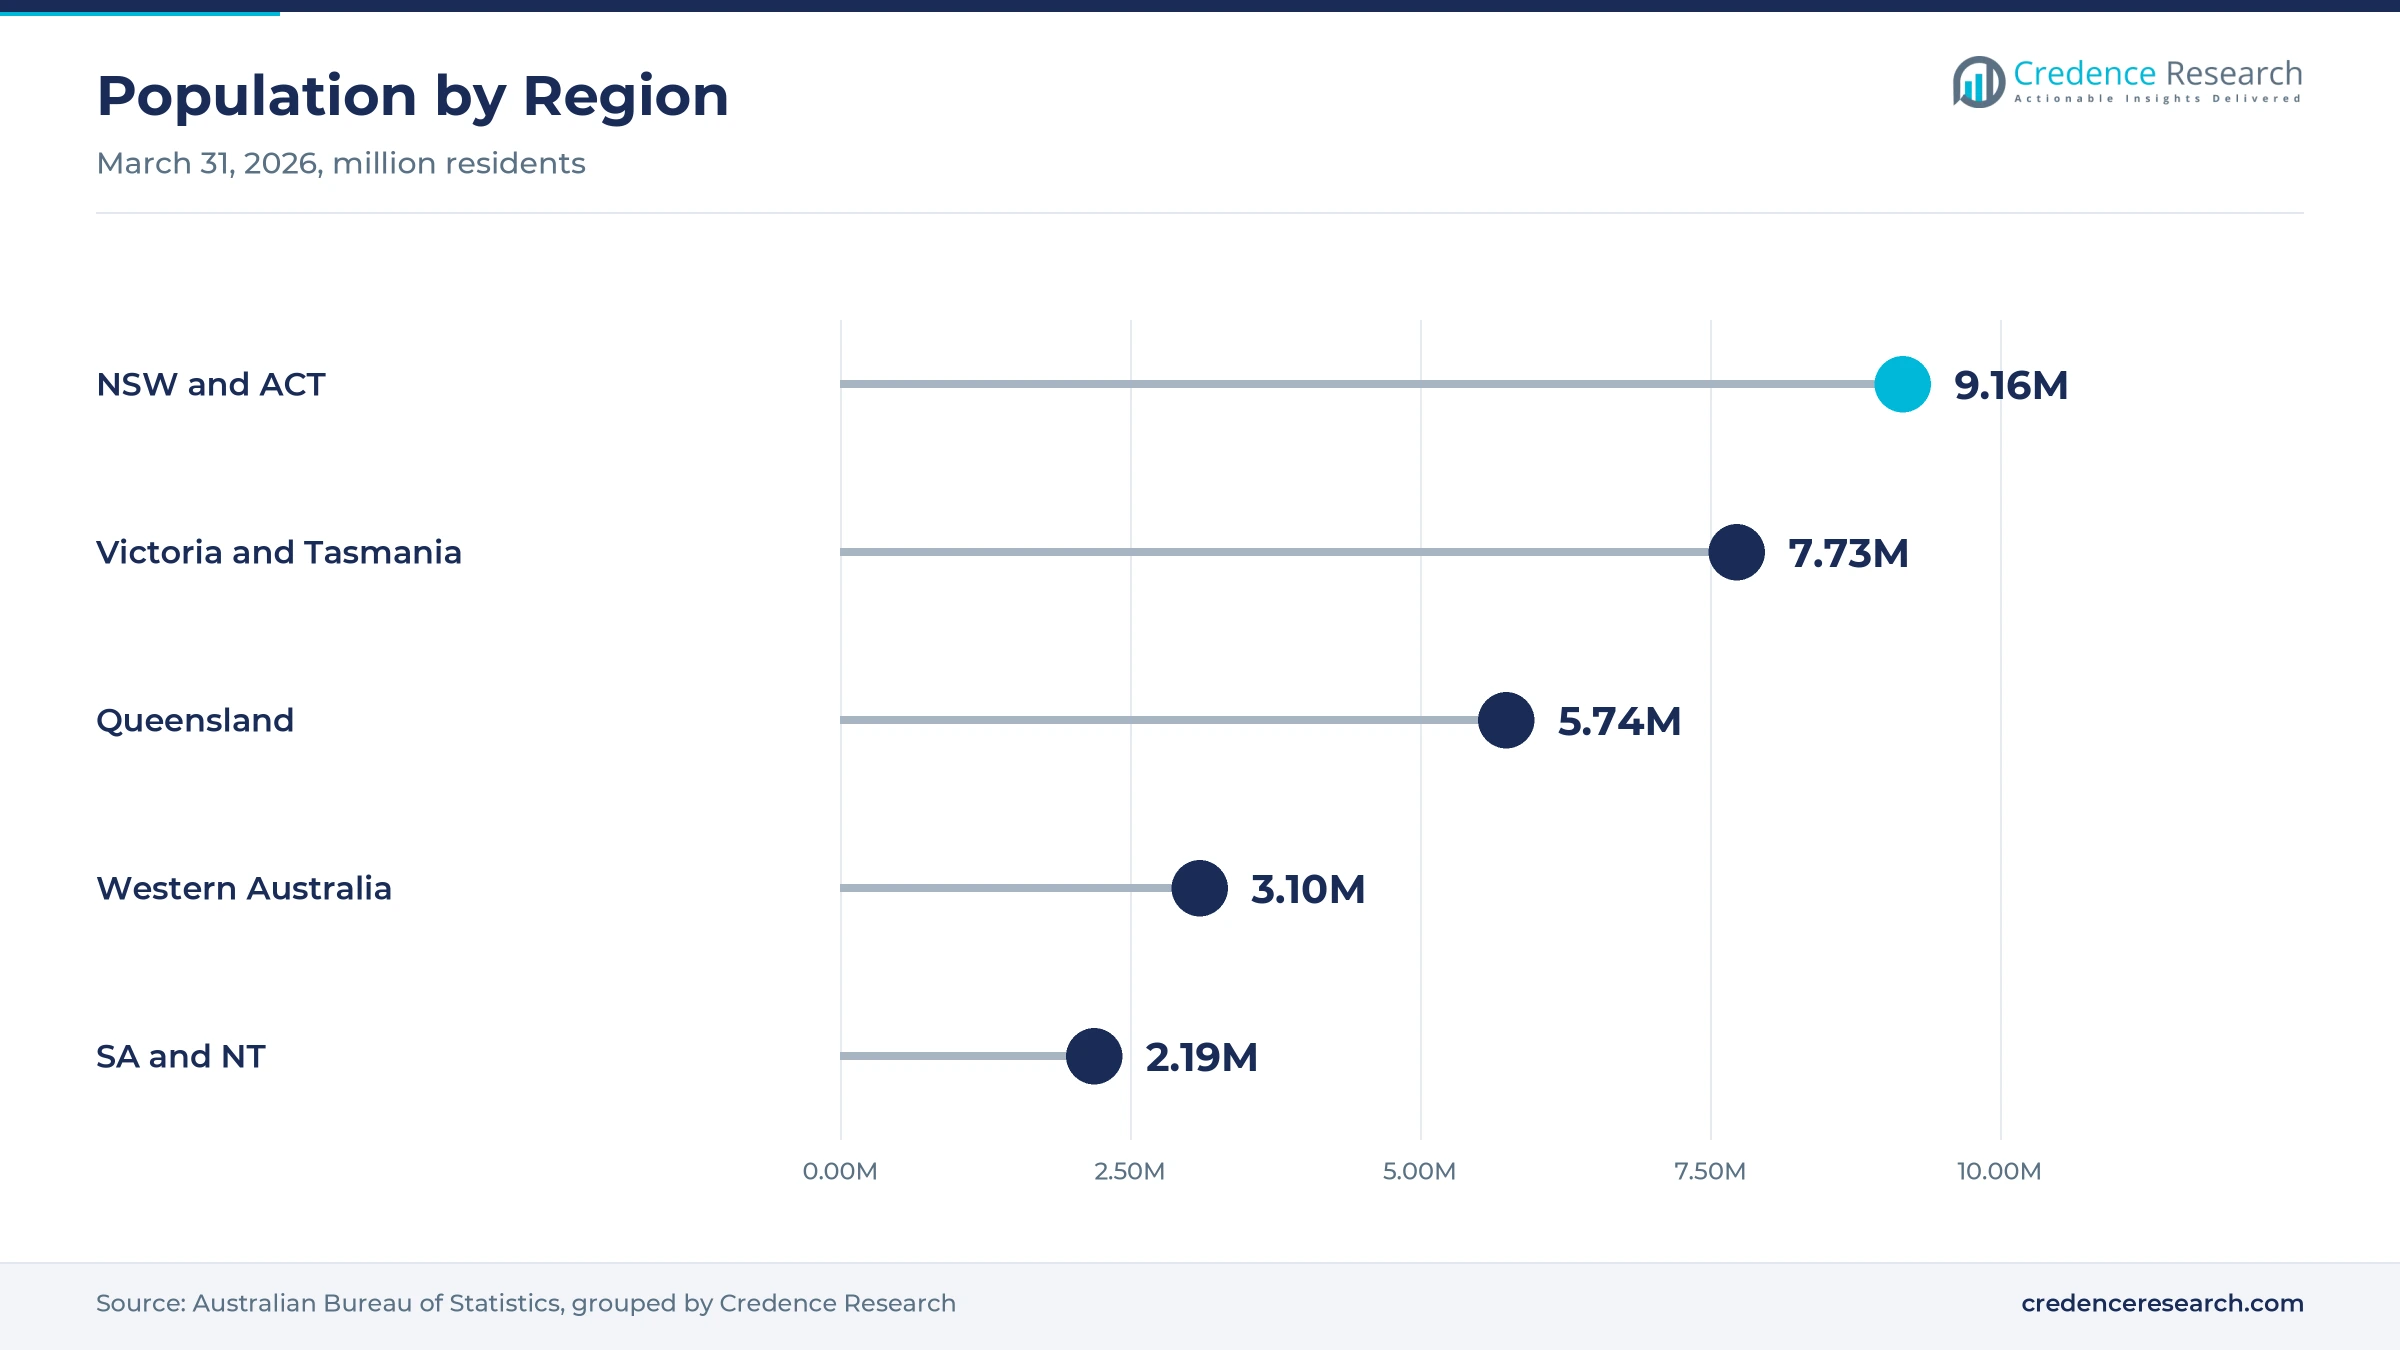
Western Australia and Queensland leave room to grow, because mining, farming and population growth add diesel engines that need service. The Australian Bureau of Statistics announced in September 2026 that Western Australia recorded the fastest state population growth at 2.1% in the year to March 31, 2026, while Queensland added about 90,100 residents. Each state also hosts two Bosch Diesel Centres, according to Bosch Aftermarket. Diesel Care runs four country centers in New South Wales and Queensland, including Toowoomba, Dalby and Goondiwindi. As a result, Western Australia is the fastest-growing region, as mine and farm fleets rely on local test benches.
Can Euro VI heavy fleets open new service value?
Euro VI heavy fleets can open new service value, because cleaner engines use tighter injection control and stronger diagnostics. All new heavy vehicles supplied from Nov. 1, 2025, must meet ADR 80/04, which cuts particulate limits to 10 mg/kWh. Light-duty truck sales reached 13,712 in 2025, which adds more modern diesel engines to urban delivery fleets. The rule also introduced stronger on-board diagnostics from 2024, which adds fault codes for injection faults. Denco Diesel and Turbo is a premium service dealer for DENSO Australia, which supplies common rail injectors for Isuzu, Toyota, John Deere and Hino engines. In turn, freight and passenger services grow at 5.93% a year, as fleets that also buy diesel exhaust fluid keep injection parts in calibration.
Electric cars, fake parts and skills gaps weigh on demand
How do battery electric vehicles reduce long-term demand?
Battery electric vehicles reduce long-term demand, because they have no engine and no injection parts to replace. Each electric car sold instead of a petrol or diesel model removes future service work from workshops. As a result, suppliers face slower growth in private car parts over the next decade. Suppliers respond by focusing on diesel utes, trucks, machines and hybrids. This challenge is limited by strong diesel use in heavy work, which should cushion the decline.
Why do counterfeit and low-quality parts weaken value?
Counterfeit and low-quality parts weaken value, because some online sellers offer injectors that look genuine but fail early. Vehicle owners who buy these parts often face poor running, higher fuel use and repeat repairs. In turn, genuine suppliers lose sales and face warranty disputes. Suppliers respond with authorized dealer networks, coded parts and buyer education. Clear warranty terms should ease this pressure and push buyers toward tested, genuine parts.
How do technician skills gaps slow repairs?
Technician skills gaps slow repairs, because common rail and direct injection work needs clean rooms, test benches and coding tools. Many regional workshops lack trained diesel technicians, which lengthens repair times for farmers and miners. As a result, owners may wait longer or travel to city specialists. Suppliers respond with training, exchange programs and approved service networks. More apprenticeships should ease this constraint and improve repair capacity over time.
Why does diagnostic equipment cost burden small workshops?
Diagnostic equipment cost burdens small workshops, because injector test benches and coding software require large upfront spending. Smaller independent repairers may send work to specialists instead of buying their own tools, which reduces their margins. In turn, specialists with benches gain volume while small shops lose repair income. Suppliers respond to this barrier with shared service programs and exchange units. Lower equipment costs would widen access to injector testing over time.
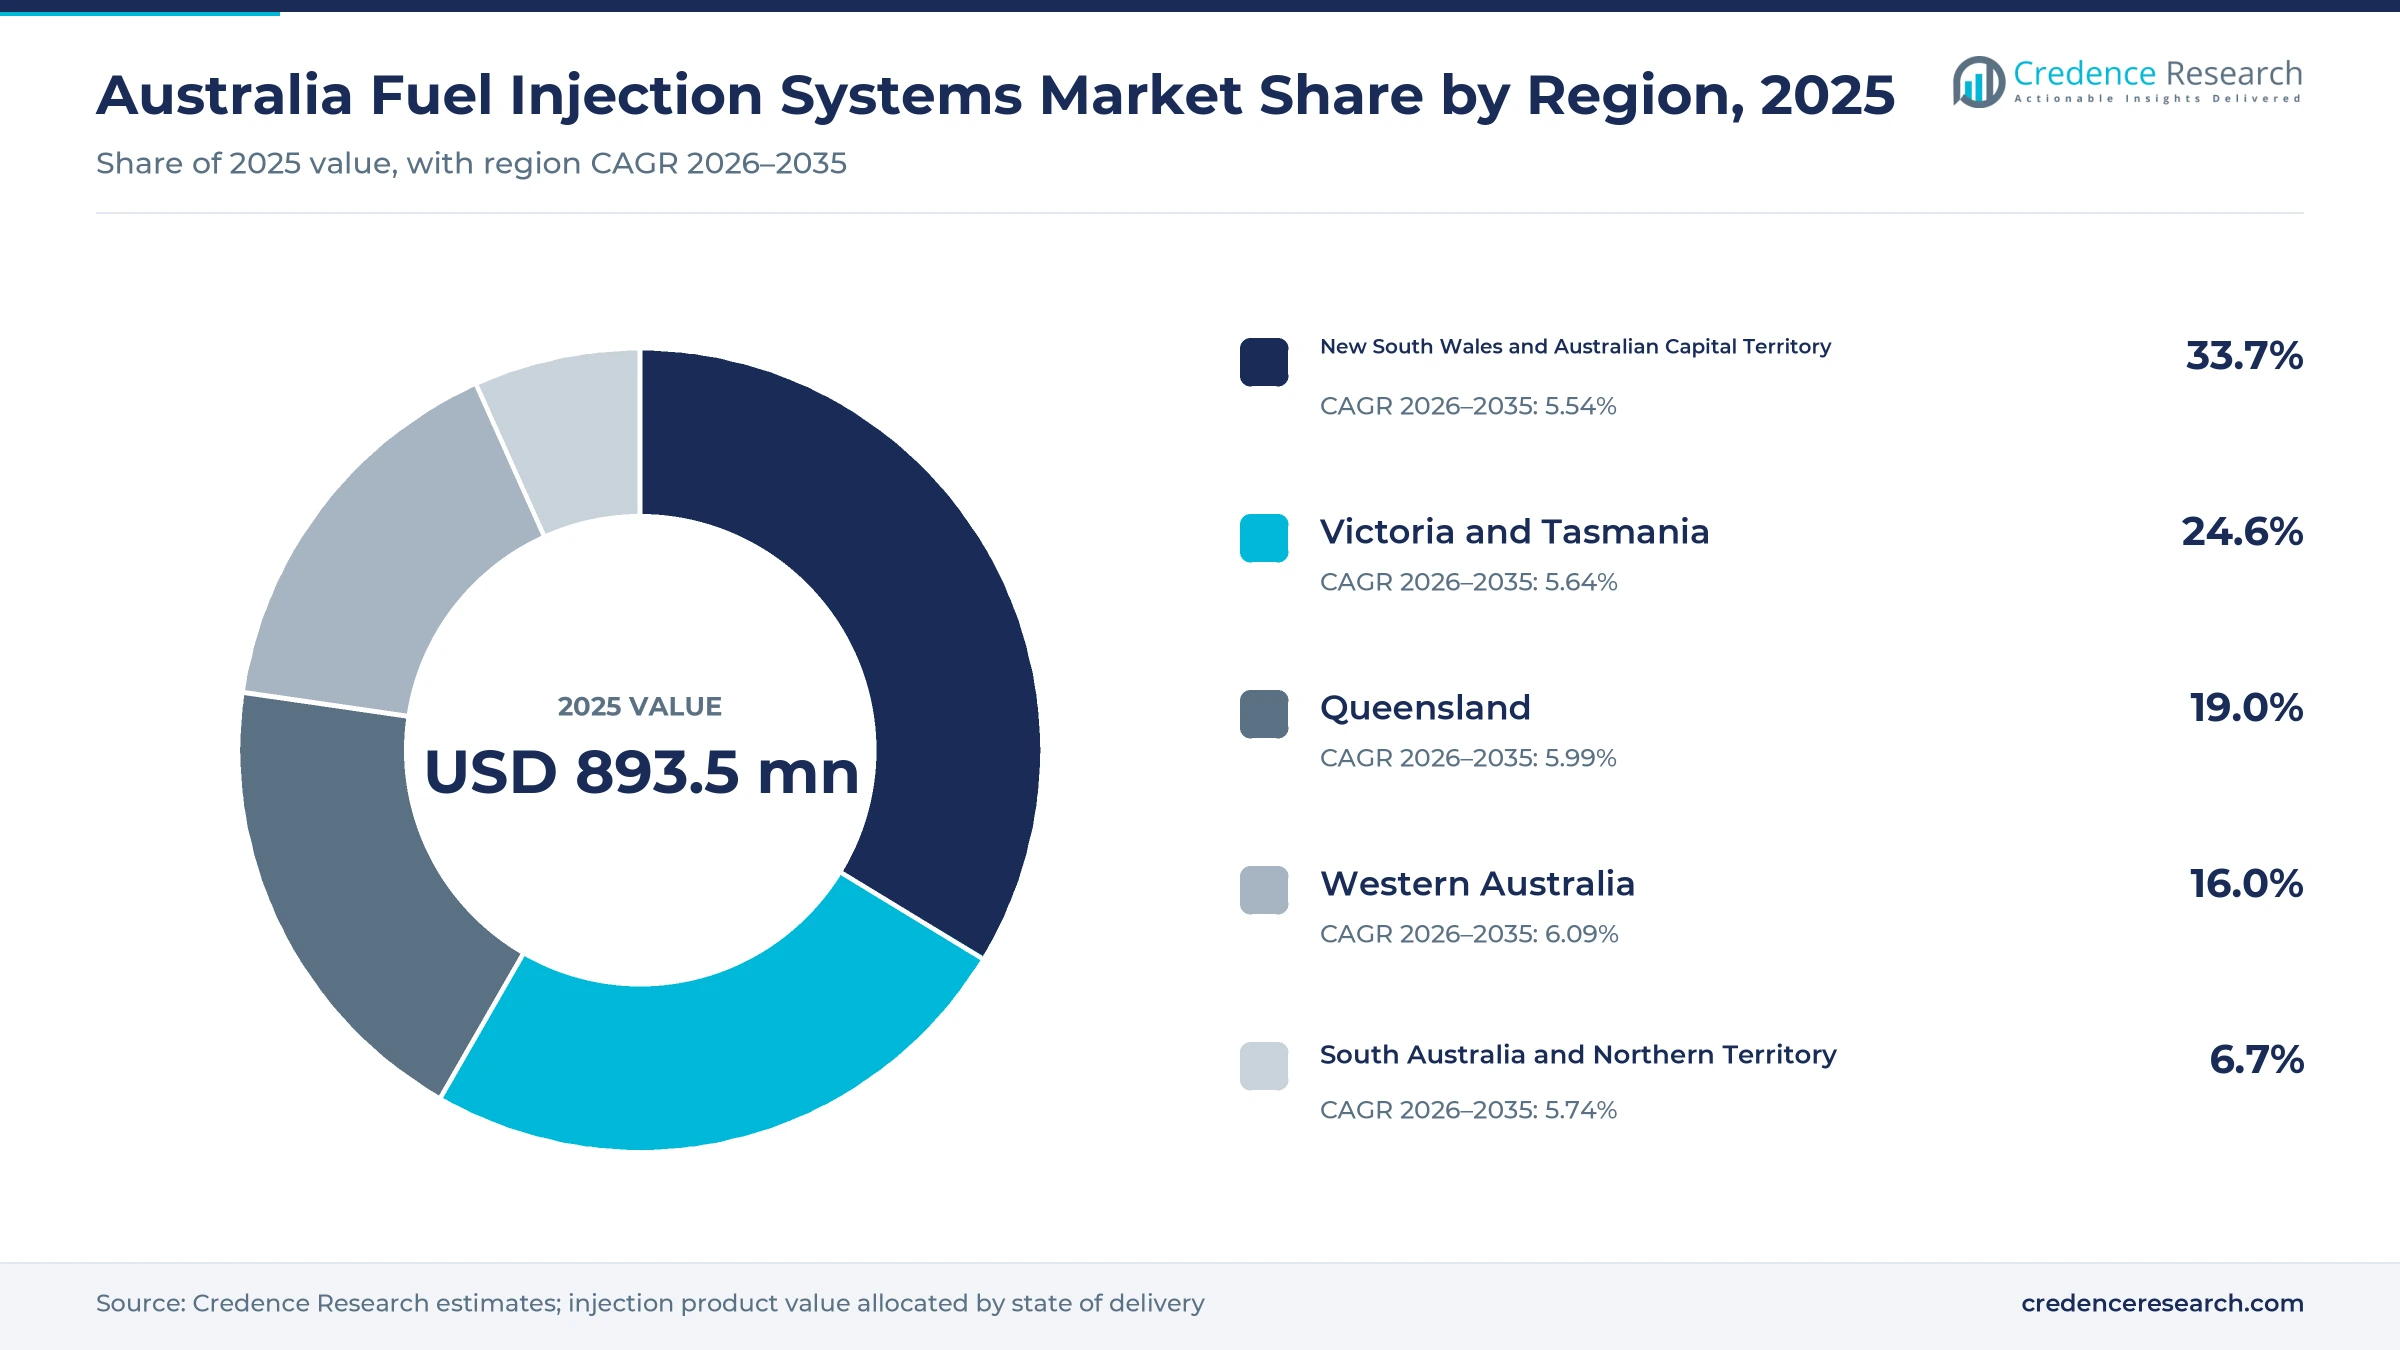
NSW and ACT lead while Western Australia grows fastest
| Region | Value, 2025 (USD million) | Share, 2025 | CAGR, 2026–2035 |
|---|---|---|---|
| New South Wales and Australian Capital Territory | 301.1 | 33.7% | 5.54% |
| Victoria and Tasmania | 219.8 | 24.6% | 5.64% |
| Queensland | 169.8 | 19.0% | 5.99% |
| Western Australia | 143.0 | 16.0% | 6.09% |
| South Australia and Northern Territory | 59.9 | 6.7% | 5.74% |
Why do New South Wales and the ACT hold the largest share?
New South Wales and Australian Capital Territory held 33.7% of 2025 value and grow at 5.54% a year, because Sydney hosts the largest fleet of cars, utes and trucks. New South Wales had about 8.67 million residents at March 31, 2026, while the ACT had about 490,000. The state also hosts three Bosch Diesel Centres, the most of any state. As a result, the region generates the largest volume of injector testing and replacement work.
How do Melbourne freight and southern farms support parts sales?
Victoria and Tasmania held 24.6% of 2025 value and grow at 5.64% a year, because Melbourne is a major freight hub with large truck and bus fleets. Victoria added about 109,500 residents in the year to March 2026, the largest increase of any state. In turn, more vehicles enter the fleet and need fuel system service. Farm machinery in regional Victoria and Tasmania also adds diesel pump and injector work.
How does Queensland support growth?
Queensland held 19.0% of 2025 value and grows at 5.99% a year, because population growth, mining and farming add diesel engines across the state. Queensland had about 5.74 million residents at March 31, 2026, after growing 1.6% over the year. The state hosts two Bosch Diesel Centres, and Diesel Care runs country centers at Toowoomba, Dalby and Goondiwindi. As a result, farm and mine fleets can test and repair parts close to where they work.
How do mine fleets make Western Australia the growth leader?
Western Australia held 16.0% of 2025 value and grows fastest at 6.09% a year, because mining fleets run diesel engines at high hours in remote areas. The state recorded the fastest population growth at 2.1% in the year to March 2026. United Fuel Injection in Redcliffe tests CAT, Cummins and MTU injectors for mine fleets. In turn, local test benches and exchange programs cut downtime for resource operators.
How do South Australia and the Northern Territory add demand?
South Australia and Northern Territory held 6.7% of 2025 value and grow at 5.74% a year, because farming, freight and remote communities depend on diesel engines. South Australia hosts one Bosch Diesel Centre, which supports injector service in Adelaide and nearby farm regions.
Emission and fuel rules marked 2024 to 2026
| Development | Status and market relevance |
|---|---|
| In November 2024, ADR 80/04 began applying Euro VI emission limits to new heavy vehicle models supplied in Australia. | Raises injection precision and diagnostic needs in new trucks |
| In November 2025, ADR 80/04 extended to all new heavy vehicles supplied in Australia. | Brings Euro VI hardware into every new truck and bus |
| In December 2025, a 10 ppm sulfur limit took effect for all petrol sold in Australia. | Suits modern direct injection engines and after-treatment |
| In January 2026, industry figures showed 1,209,808 new vehicle sales in 2025, led by the Ford Ranger. | Confirms diesel utes as a core source of injector demand |
| In January 2026, Truck Industry Council data showed 45,191 new trucks and heavy vans sold in 2025. | Adds modern diesel engines to freight fleets |
Common rail and direct petrol designs shape service
- Diesel common rail stores fuel at very high pressure in a shared rail and fires injectors electronically, which suits utes, trucks and machines through high-pressure rail designs.
- Gasoline direct injection sprays fuel straight into each cylinder, which improves efficiency in turbocharged and hybrid petrol engines.
- Port fuel injection sprays fuel into the intake port, which keeps parts simple and low-cost for older and smaller engines.
- Injector test benches measure flow and response and generate calibration codes, which lets workshops verify repaired or remanufactured parts.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Suppliers compete on parts access, test benches and reach
Competition centers on parts availability, test benches, technical training and service reach across remote areas. Robert Bosch Australia supports nine Bosch Diesel Centres in five states that test, calibrate and repair pumps and injectors. DENSO Australia supplies common rail injectors through premium service dealers such as Denco Diesel and Turbo and United Fuel Injection. PHINIA reaches Australian workshops through its Delphi brand, and Diesel Care is a premium service dealer for Delphi, DENSO and Bosch common rail. Stanadyne pumps are serviced through authorized dealers such as Diesel Care. Denco says it has worked in diesel injection and turbochargers for 55 years, while United Fuel Injection has more than 45 years of experience serving mining fleets. Because diesel service needs costly benches and approvals, specialists with original equipment backing win most fleet and mine work.
Companies profiled and their roles in this market
| Company | Type | Role in the market |
|---|---|---|
| Robert Bosch Australia | Component maker | Supports nine Bosch Diesel Centres across five states |
| DENSO Australia | Component maker | Supplies common rail injectors through premium service dealers |
| PHINIA | Component maker | Sells Delphi diesel injection parts through service dealers |
| Stanadyne | Component maker | Pumps serviced through authorized Australian dealers |
| Denco Diesel and Turbo | Diesel specialist | Holds more than 3,500 turbocharger and injection products |
| United Fuel Injection | Diesel specialist | Tests CAT, Cummins and MTU injectors for mine fleets |
| Diesel Care | Diesel specialist | Runs four country centers in New South Wales and Queensland |
Credence Research view on Australian engine fueling parts
Credence Research's view is that Australian demand for injection parts will grow steadily because diesel utes, trucks and machines stay central to work and freight. Diesel common rail keeps the largest share, while gasoline direct injection grows fastest as hybrids spread. Western Australia should grow fastest among the regions through 2035 as mining fleets expand service needs. However, battery electric cars, fake parts and skills gaps will slow some demand. Specialists with test benches, approvals and exchange stock should gain share fastest.
Vehicle data and regulator releases anchor the model
The report uses 2025 as the base year on a calendar basis, and market values come from the Credence Research model. That model combines new vehicle and truck sales data, emission and fuel rules, population statistics, farm and construction data, World Bank industry data and company releases. Segment splits and regional growth rates are Credence Research estimates, while regional shares follow the client-defined split. Sources used are official statistics, government releases, industry association releases, trade press and company releases, and no interviews or surveys were used.
Diesel service and hybrid engines carry growth to 2035
Injection parts sales are expected to reach USD 1.58 billion by 2035, a 5.75% CAGR during 2026–2035, as diesel service, hybrid engines and Euro VI trucks keep demand rising. Growth should hold firm through 2030 as the Euro VI truck fleet expands and hybrids gain share of new sales. After that, the pace of battery electric adoption will set private car demand. Faster electrification would shift value toward trucks, mines and farms, while slower electrification would keep petrol injection work strong. Authorized service parts are expected to gain channel share through 2035.
Frequently Asked Questions
How big is the Australia fuel injection systems market?
Which technology leads demand in Australia?
Which region leads the Australian market?
Why does the independent aftermarket lead sales?
How does Euro VI affect injection demand?
Which vehicle type grows fastest?
Who are the leading suppliers in Australia?
What are the main challenges for suppliers?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Technology
- 1.2.1 Diesel Common Rail
- 1.2.2 Gasoline Direct Injection
- 1.2.3 Port Fuel Injection
- 1.2.4 Specialised Injection Architectures
- 1.3 By Vehicle Type
- 1.3.1 Light Vehicles
- 1.3.2 Heavy Commercial Vehicles
- 1.3.3 Off-Road Equipment
- 1.4 By Usage Type
- 1.4.1 Private Mobility
- 1.4.2 Freight and Passenger Services
- 1.4.3 Resource and Agricultural Operations
- 1.5 By Sales Channel
- 1.5.1 Embedded OEM Supply
- 1.5.2 Independent Aftermarket
- 1.5.3 Authorised Service Parts
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2025: USD 893.5 million → 2035: USD 1.58 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Historical Period: 2018-2025
- 2.6.2 Base Year: 2025
- 2.6.3 Forecast Period: 2025-2035
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2025
- 3.3 Forecast Market Size, 2035
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Australia Fuel Injection Systems Market Trends and Developments
- 4.1 Historical Industry Development, 2018-2025
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Australia Fuel Injection Systems Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis, 2018-2025
- 5.2 Demand Forecast, 2025-2035
- 5.3 Production and Output Trend, 2018-2025
- 5.4 Production and Output Forecast, 2025-2035
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Australia Fuel Injection Systems Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends, 2018-2025
- 6.3 Pricing Outlook, 2025-2035
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Australia Fuel Injection Systems Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Australia Fuel Injection Systems Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Australia Fuel Injection Systems Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Australia Fuel Injection Systems Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Australia Fuel Injection Systems Market Outlook, 2025-2035
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2025: USD 893.5 million → 2035: USD 1.58 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size, 2018-2025
- 11.1.4 Base-Year Market Size, 2025
- 11.2 Market Forecast, 2025-2035
- 11.2.1 Revenue Forecast to 2035
- 11.2.2 Volume Forecast to 2035
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Australia Fuel Injection Systems Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2025
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Technology - Market Size and Forecast, 2025-2035
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size, 2018-2025
- 12.3.3 Revenue Forecast, 2025-2035
- 12.3.4 Volume Forecast, 2025-2035
- 12.3.5 Base-Year Market Share, 2025
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Diesel Common Rail
- 12.3.7.2 Gasoline Direct Injection
- 12.3.7.3 Port Fuel Injection
- 12.3.7.4 Specialised Injection Architectures
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Vehicle Type - Market Size and Forecast, 2025-2035
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size, 2018-2025
- 12.4.3 Revenue Forecast, 2025-2035
- 12.4.4 Volume Forecast, 2025-2035
- 12.4.5 Base-Year Market Share, 2025
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Light Vehicles
- 12.4.7.2 Heavy Commercial Vehicles
- 12.4.7.3 Off-Road Equipment
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Usage Type - Market Size and Forecast, 2025-2035
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size, 2018-2025
- 12.5.3 Revenue Forecast, 2025-2035
- 12.5.4 Volume Forecast, 2025-2035
- 12.5.5 Base-Year Market Share, 2025
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Private Mobility
- 12.5.7.2 Freight and Passenger Services
- 12.5.7.3 Resource and Agricultural Operations
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Sales Channel - Market Size and Forecast, 2025-2035
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size, 2018-2025
- 12.6.3 Revenue Forecast, 2025-2035
- 12.6.4 Volume Forecast, 2025-2035
- 12.6.5 Base-Year Market Share, 2025
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Embedded OEM Supply
- 12.6.7.2 Independent Aftermarket
- 12.6.7.3 Authorised Service Parts
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Australia Fuel Injection Systems Geographic Market Outlook, 2025-2035
- 13.1 Domestic Market Distribution and Demand Clusters
- 13.2 State- or Province-Wise Market Size and Forecast, 2025-2035
- 13.3 City and Metropolitan Market Outlook
- 13.4 Industrial, Manufacturing and Commercial Clusters
- 13.5 Geographic Concentration of Key End Users
- 13.6 Local Pricing and Purchasing Differences
- 13.7 Domestic Production Facilities and Capacity Map
- 13.8 Local Infrastructure and Project Pipeline
- 13.9 State-Level Policy and Incentive Differences
- 13.10 Subnational Investment Hotspots and Opportunities
- 13.11 Distribution and Logistics Networks
- 13.12 Domestic Competitive Footprint
Chapter 14 Australia Fuel Injection Systems Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2025-2035
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Australia Fuel Injection Systems Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2025
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2025-2035
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Robert Bosch Australia
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 DENSO Australia
- 17.4 PHINIA
- 17.5 Stanadyne
- 17.6 Denco Diesel and Turbo
- 17.7 United Fuel Injection
- 17.8 Baileys Diesel Group
- 17.9 Fremantle Fuel Injection
- 17.10 Diesel Care
- 17.11 Cornell Diesel Systems
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

