
East coast hubs hold most third-party stock in Australia
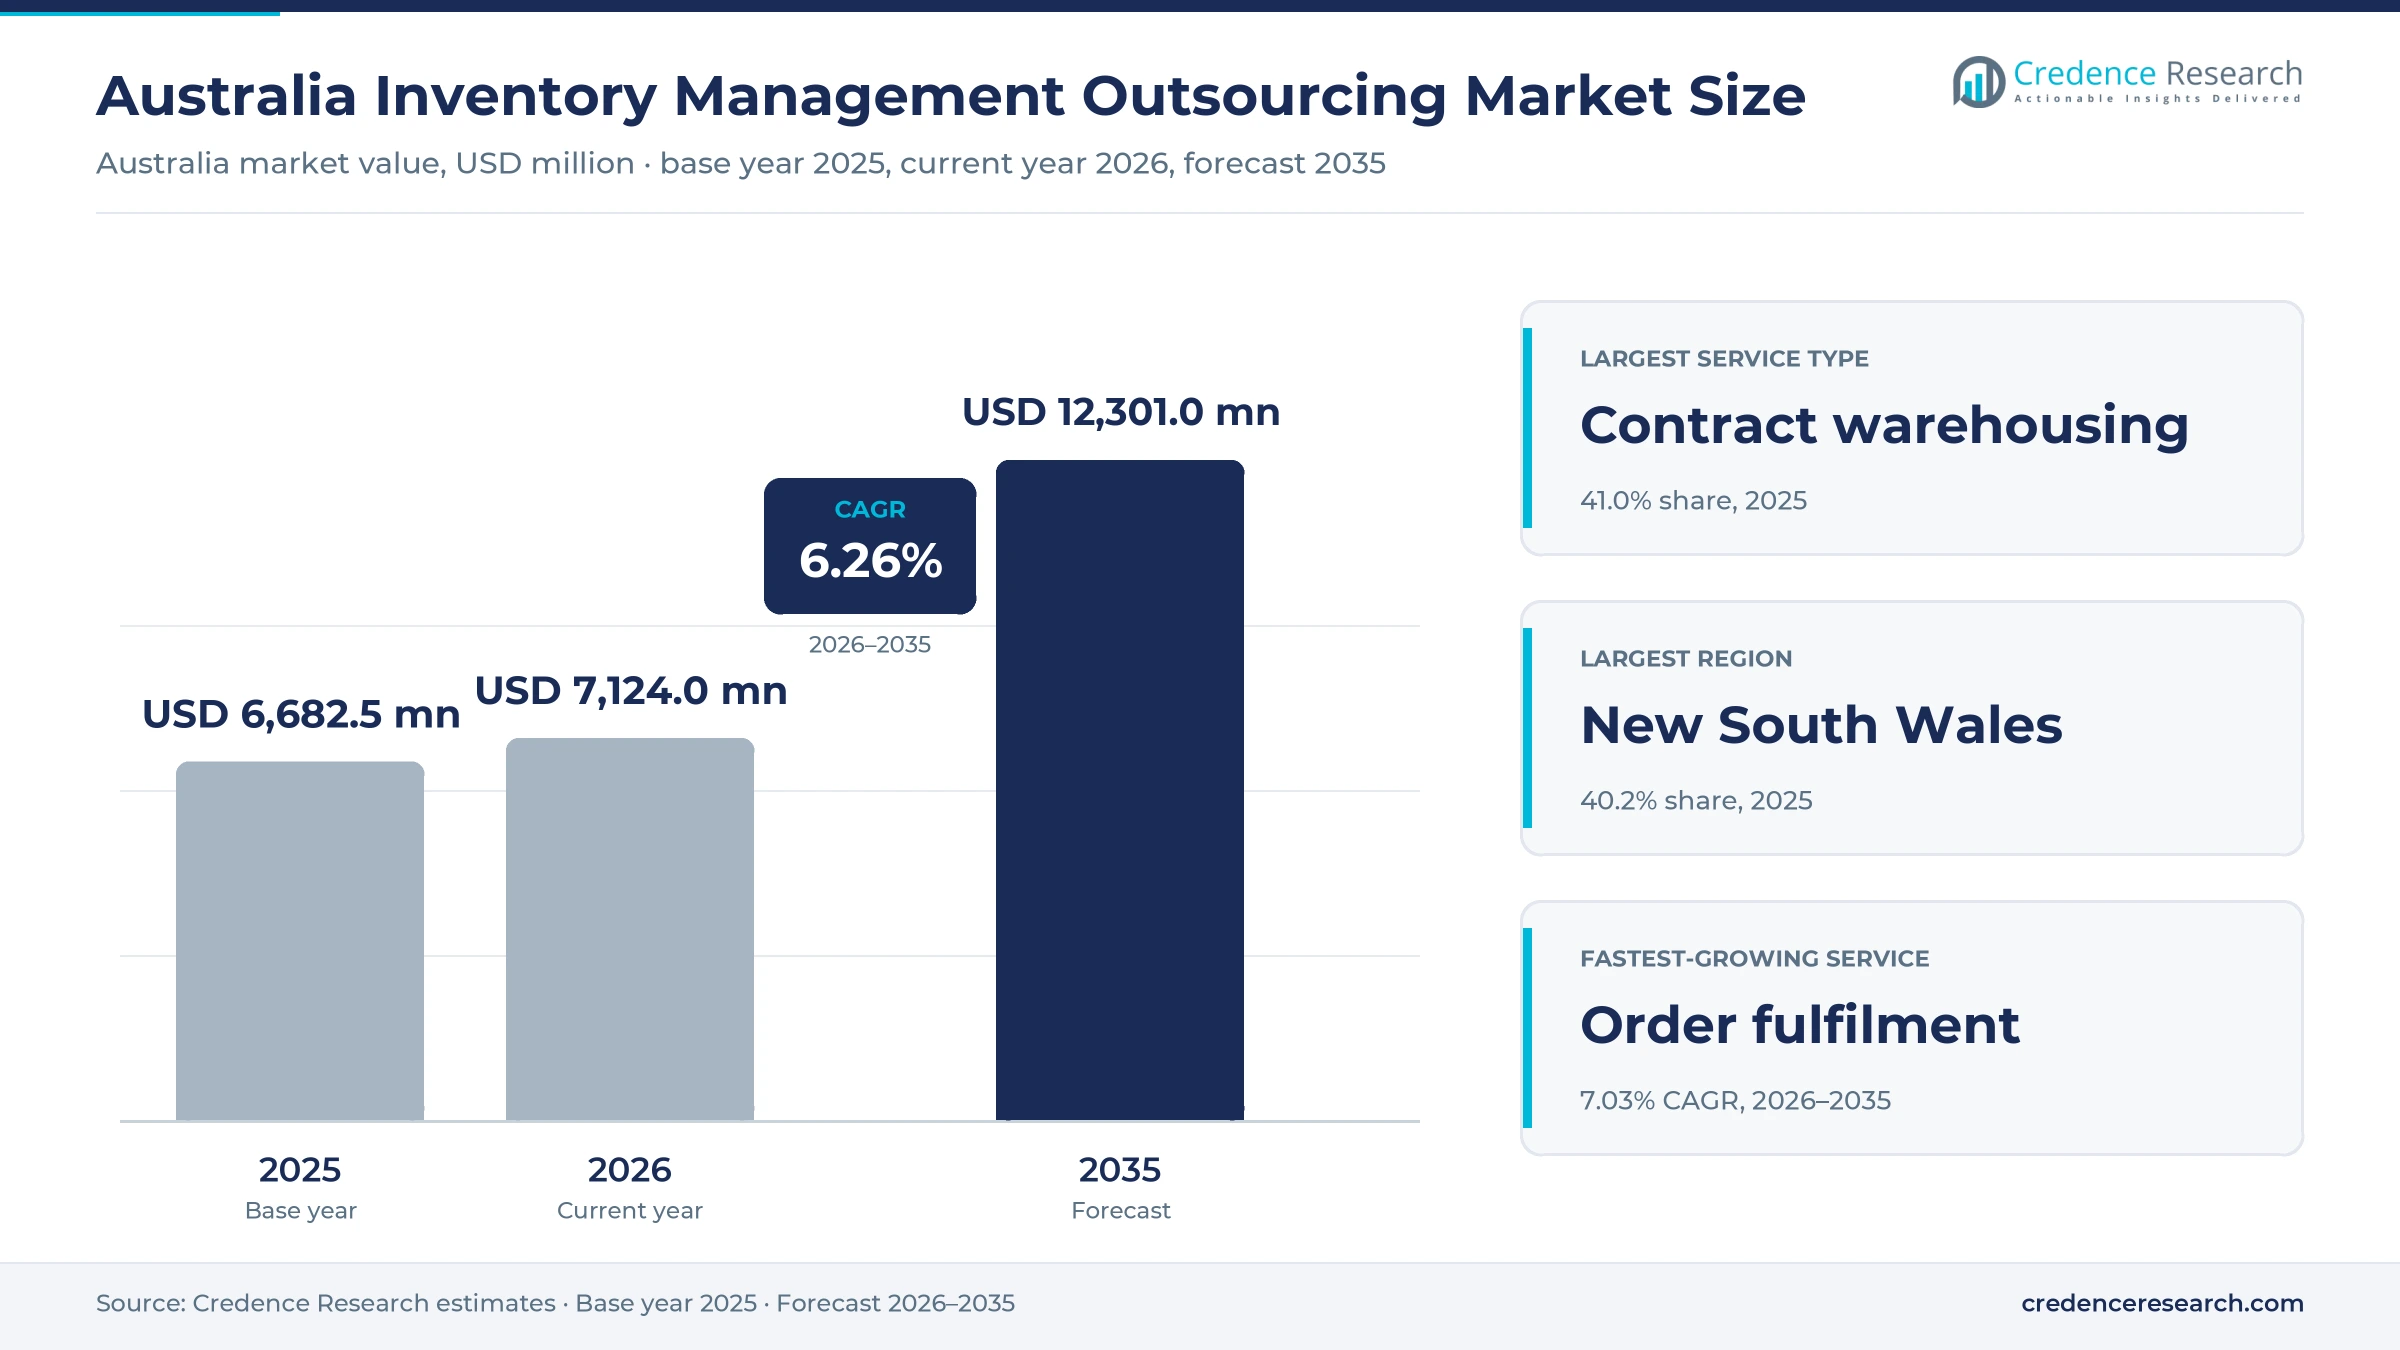
The Australia inventory management outsourcing market was valued at USD 6.68 billion in 2025 and is projected to increase from USD 7.12 billion in 2026 to USD 12.30 billion by 2035, registering a CAGR of 6.26% during 2026–2035. Demand comes from retailers, food and beverage brands, pharmaceutical suppliers, industrial distributors and government agencies that hand storage, picking, stock control and returns to third-party logistics operators. New South Wales held the largest regional share, 40.2% in 2025, because western Sydney holds the densest cluster of national distribution centers close to Port Botany. Queensland is the fastest-growing region at 6.62% a year, as population growth and new Brisbane sheds pull more stock north. Operators are investing in robotic picking and temperature-controlled rooms, which lets them serve several clients from one shared site. Australians spent a record AUD 82.6 billion online in 2025, which keeps raising the number of small orders that brands prefer to outsource.
What sits inside the scope of this estimate?
Fees paid to third-party operators are counted here for contract warehousing and storage, order fulfilment, inventory control and returns and value-added services in Australia. The scope includes dedicated sites run for one client, shared-user sites and teams that manage stock inside a customer's own building. Values are measured as operator revenue for storage, handling, labor, systems and management fees.
The estimate excludes linehaul trucking, parcel delivery, freight forwarding and warehouse property rent paid directly by owners of goods. The value chain runs from importers, manufacturers and brands through contract operators, property developers and automation suppliers to retail stores, hospitals, pharmacies and online shoppers.
Australia Inventory Management Outsourcing Market Insights
- The Australia inventory management outsourcing market was valued at USD 6.68 billion in 2025 and is projected to reach USD 12.30 billion by 2035, registering a CAGR of 6.26% during 2026–2035.
- New South Wales held a 40.2% share of 2025 value, because western Sydney hosts the largest cluster of national distribution centers.
- Contract warehousing and storage led service demand with a 41.0% share of 2025 value, because pallet storage remains the base of most contracts.
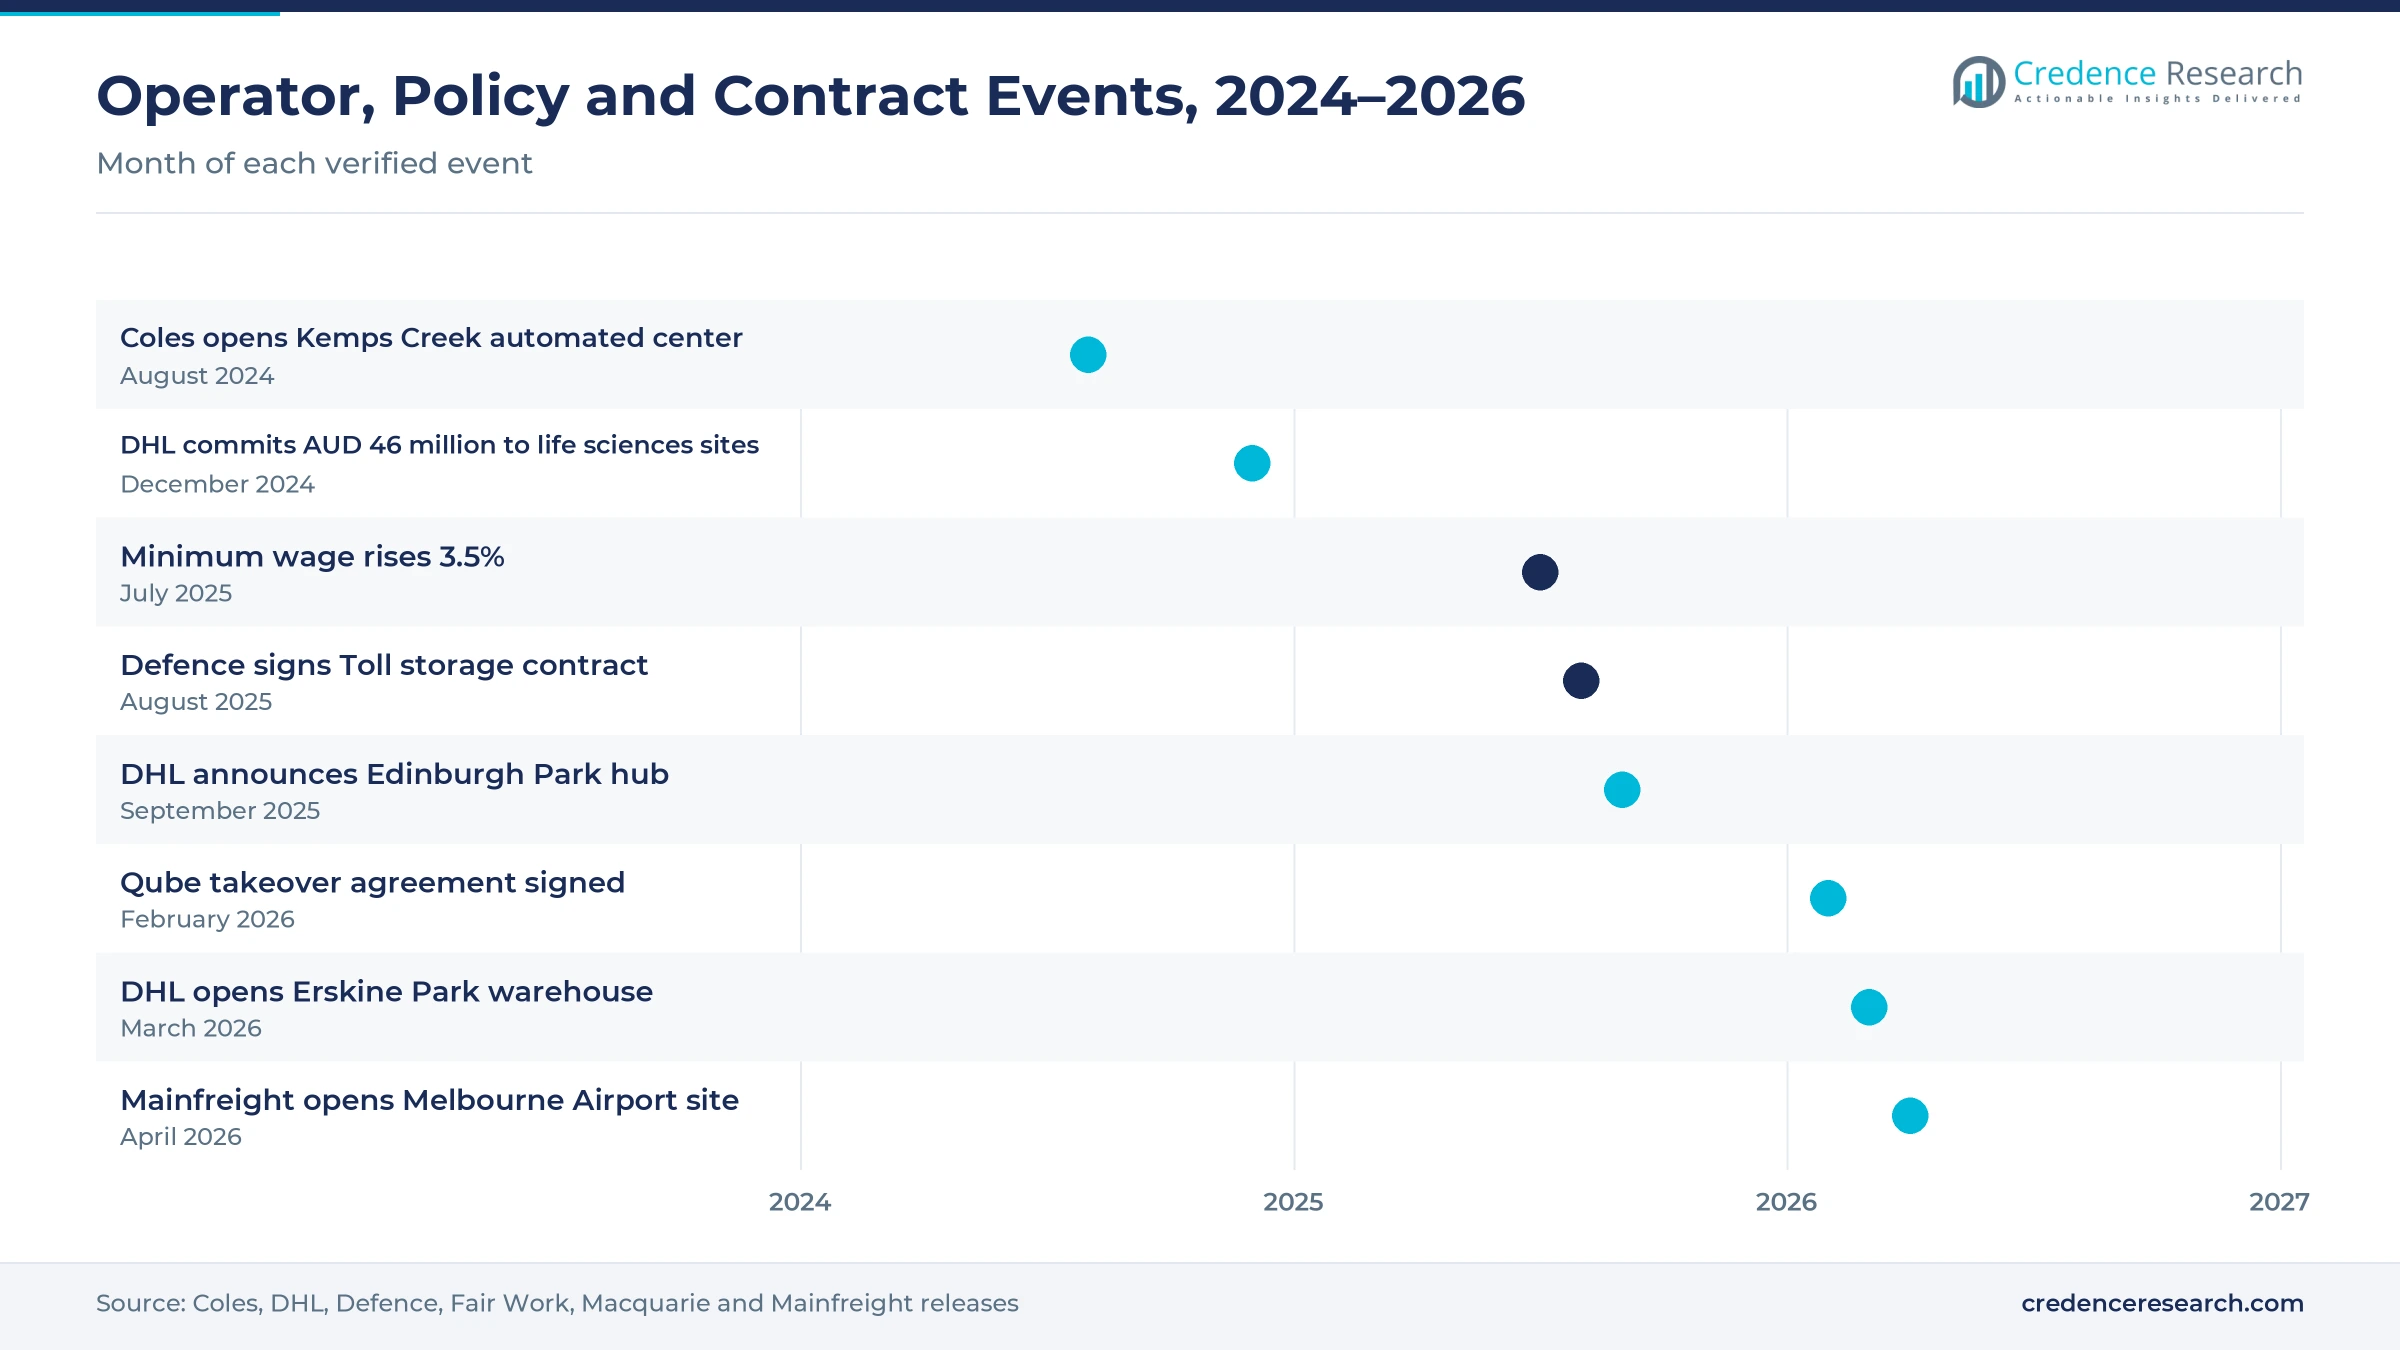
- DHL Supply Chain said in December 2024 that it was investing more than AUD 46 million in automated life sciences sites in Sydney and Auckland.
- A consortium led by Macquarie Asset Management agreed on Feb. 16, 2026, to acquire Qube Holdings in a deal valuing it at about AUD 11.7 billion.
Storage contracts lead while order picking grows fastest
Why does pallet storage still anchor most contracts?
Based on service type, the market is categorized into contract warehousing and storage, order fulfilment, inventory control and returns and value-added services. Contract warehousing and storage led with a 41.0% share of 2025 value, because most contracts start with pallet storage and replenishment for stores. Order fulfilment grows fastest at 7.03% a year, as online orders shift work from full pallets to single items.
How do retailers and pharma suppliers shape demand?
Based on end-use industry, the market is categorized into retail and consumer goods, food and beverage, healthcare and pharmaceuticals, and industrial and specialist sectors. Retail and consumer goods led with a 44.0% share of 2025 value, because apparel, electronics and household brands outsource most of their stock. Healthcare and pharmaceuticals grows fastest at 7.10% a year, as cool rooms and licensed sites become harder to build in-house.
Why are shared-user sites gaining on dedicated ones?
Based on operating model, the market is categorized into dedicated operator facilities, shared-user operator facilities and customer-site managed operations. Dedicated operator facilities led with a 46.0% share of 2025 value, because large retailers and brands sign long contracts for single-client sites. Shared-user operator facilities grow fastest at 6.87% a year, as mid-sized brands share robots and racking with other clients.
| Segment Group | Leading Sub-segment | Share, 2025 | Fastest-growing Sub-segment | CAGR, 2026–2035 |
|---|---|---|---|---|
| By Service Type | Contract warehousing and storage | 41.0% | Order fulfilment | 7.03% |
| By End-Use Industry | Retail and consumer goods | 44.0% | Healthcare and pharmaceuticals | 7.10% |
| By Operating Model | Dedicated operator facilities | 46.0% | Shared-user operator facilities | 6.87% |
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Parcel growth, robots and cold rooms push more stock to 3PLs
How does online shopping expand fulfillment workloads?
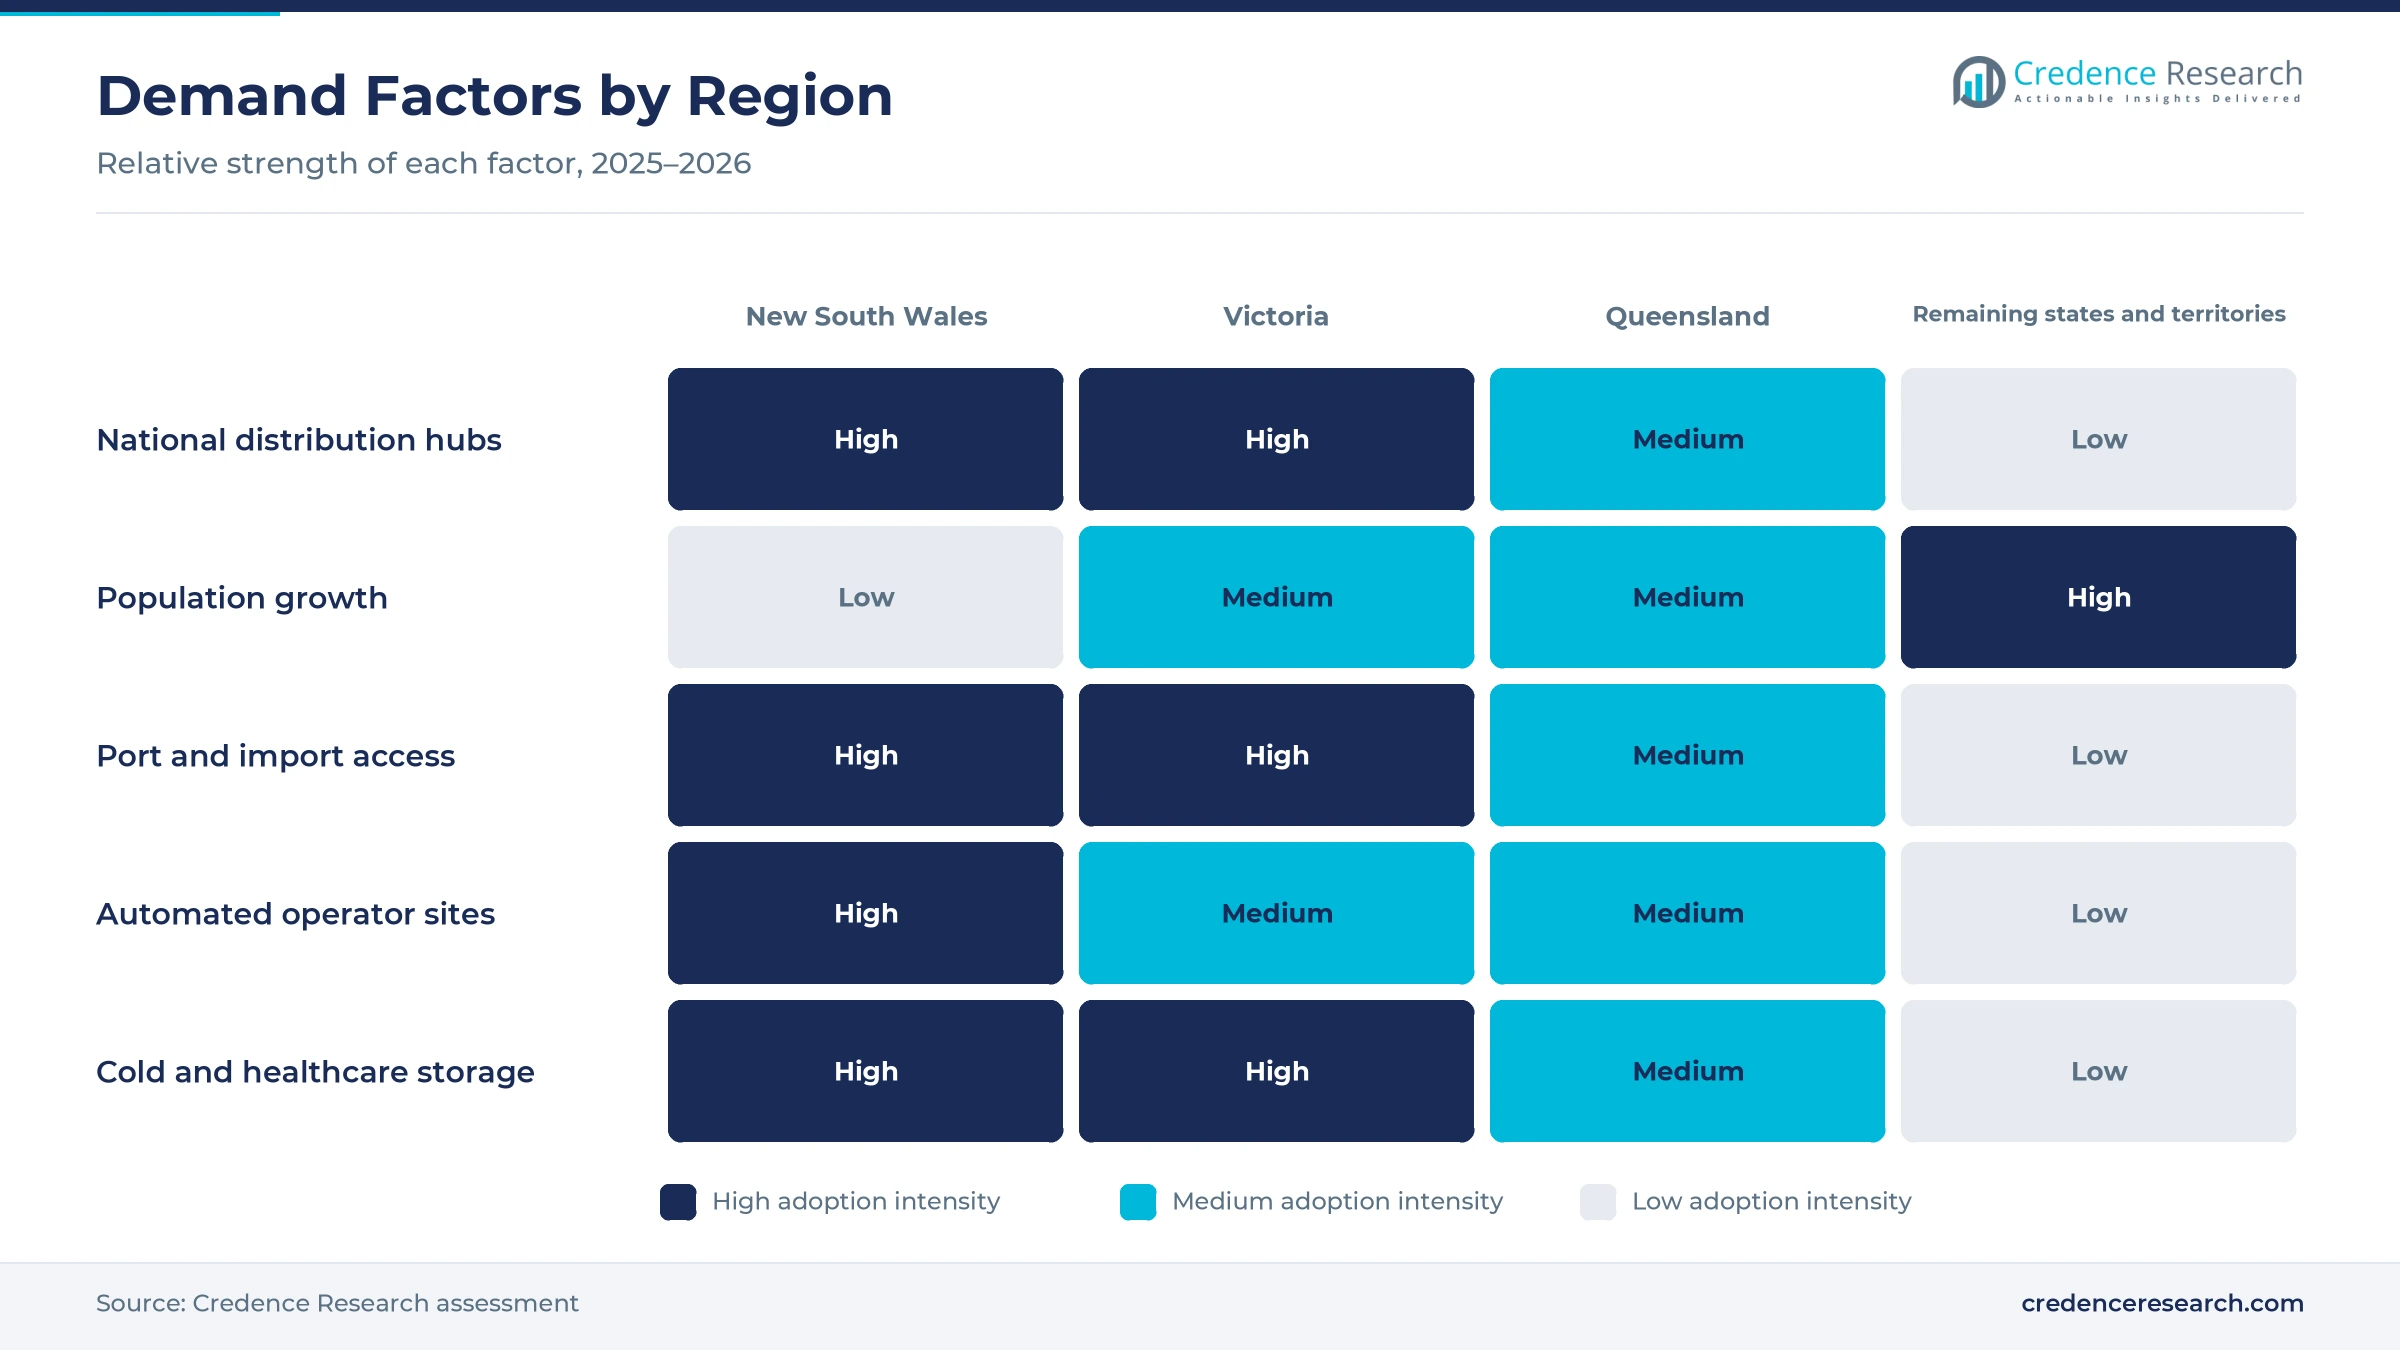
Online orders break stock into many small parcels, which raises the labor, packing and systems work that brands prefer to hand to specialists. Australians spent a record AUD 82.6 billion online in 2025, up 13.9% from 2024, according to an Australia Post report summarized by the International Post Corporation. About 9.8 million households bought online during that year, which spreads demand across every state. Toll Group leased a 67,626-square-meter warehouse at Kemps Creek in western Sydney with AUD 75 million of robotics, designed to dispatch 37 million parcels a year for retail clients. As a result, order fulfilment grows at 7.03% a year, the fastest service rate, while retail and consumer goods hold 44.0% of value.
Why does automation support more complex stock services?
Robotic picking needs capital and software skills that few brands want to own, which pushes them toward operators that spread the cost over many clients. DHL Supply Chain installed a Hai Robotics system at its Skyline site in Horningsea Park with 12 robots and capacity for more than 20 customers, according to the company. Its Erskine Park site uses Locus autonomous mobile robots, and Horsley Park will add a Dematic automated picking system from 2027. Linfox runs a 30,000-square-meter western Sydney site built on Swisslog AutoStore with 45 robots and 20,000 totes. In turn, shared-user operator facilities grow at 6.87% a year, the fastest operating model rate.
How does specialist storage strengthen the case for 3PLs?
Temperature-controlled and licensed storage costs far more to build than ambient racking, which makes pharmaceutical and food brands more willing to share it. DHL Supply Chain said in December 2024 that it was investing more than AUD 46 million in automated life sciences sites, including a 1,350-square-meter cool room at Horsley Park that serves up to 30 customers. Toll Group opened an AUD 10 million healthcare site at Richlands in Brisbane in 2023 with cool rooms and ultra-low freezers for CSL and Queensland Health. Mainfreight opened a Melbourne Airport airfreight site with three chillers and two freezers in April 2026. As a result, healthcare and pharmaceuticals grow at 7.10% a year.
Why do large government contracts widen outsourced stock?
Public agencies are handing whole storage networks to private operators, which adds large, long-term volumes to the market. The Department of Defence awarded a 10-year, AUD 1.5 billion national logistics contract to Toll Remote Logistics, according to a Defence announcement on Aug. 20, 2025. The contract merges storage, nationwide distribution and retail operations across more than 50 locations, with services rolling out from 2025. Queensland Health also uses Toll's Richlands healthcare site for vaccines, medical devices and consumer health products. Because such contracts run inside client-owned and operator sites, customer-site managed operations hold a steady base, while dedicated operator facilities lead with 46.0% of value.
Shared automated sites and site consolidation reshape supply
How is the shift to shared automated sites changing contracts?
Operators are building multi-client automated sites, which is shifting mid-sized brands away from single-client sheds and long fixed leases. DHL Supply Chain designed its Skyline robotics site for more than 20 customers and its Horsley Park life sciences site for up to 30, according to its December 2024 release. Linfox's Willawong site in Brisbane runs four temperature zones and automated guided vehicle capability for consumer and healthcare clients. DHL also opened a 21,078-square-meter Erskine Park warehouse in March 2026 with a mezzanine for rework and value-added services. As a result, shared-user sites keep gaining mid-sized clients, and returns and value-added services gain work inside these sites.
Why is network consolidation emerging among operators?
Operators are merging scattered sheds into fewer, larger hubs, which cuts double handling and makes stock easier to track across states. DHL Supply Chain announced on Sept. 16, 2025, a roughly 20,000-square-meter Edinburgh Park site in South Australia that merges three existing sites, due in the third quarter of 2026. The new site adds ambient, temperature-controlled and cold chain storage plus rooftop solar and EV charging. Mainfreight closed three overflow warehouses and moved those customers into larger sites, according to its July 2026 team review. Its Melbourne Airport site, opened in April 2026, puts a warehouse of more than 5,500 square meters next to chillers and freezers under one roof. In turn, buyers gain one inventory view per state, and inventory control grows steadily alongside storage.
Can automation-ready capacity in western Sydney win new clients?
New western Sydney sheds near motorways and intermodal terminals give operators room to add clients without long fit-outs. DHL Supply Chain's Erskine Park warehouse, opened in March 2026, serves consumer electronics, white goods and automotive clients near an upcoming DHL transport hub. Amazon's Kemps Creek robotics center spans 200,000 square meters and was expected to create more than 1,500 jobs, which shows the scale of the corridor. Moorebank Logistics Park, developed by Qube Holdings, is described as the largest intermodal logistics precinct in Australia. As a result, New South Wales keeps the largest regional share, and operators that link stock to logistics automation can win national accounts.
Is there an opening in import-linked stock near the ports?
Importers often hold buffer stock close to container terminals, which creates an opening for operators that combine port services with storage. Australia's GDP reached about USD 1.80 trillion in 2025, according to World Bank data, which supports steady import and distribution volumes. Port Botany handled 2.805 million TEUs in the year to June 2025, including 1.271 million full import TEUs, according to NSW Ports. Qube Holdings runs warehousing and container freight stations at Port Botany and other terminals, while its agriculture sites offer bulk storage and warehousing. Qube operates about 200 sites with about 10,000 workers, according to the Macquarie release of Feb. 16, 2026. In turn, operators that pair customs clearance with warehousing and distribution logistics can capture import-linked stock as trade grows.
Wage rises, retailer insourcing and slow port volumes weigh
How do wage rises squeeze fixed-price contracts?
Warehouse work is labor-intensive, so every award increase lifts operator costs before contract prices can be reset. The Fair Work Commission raised minimum wages by 3.5% from July 1, 2025, taking the national minimum to AUD 24.95 an hour. As a result, operators on fixed management fees absorb costs until their next review. Many respond with open-book cost-plus terms, indexation clauses and robots that cut labor hours per order.
Why does retailer insourcing cap the addressable volume?
The largest grocers build and run their own automated sites, which keeps a big share of national stock away from third-party operators. Coles opened an automated distribution center at Kemps Creek on Aug. 6, 2024, serving 229 stores in New South Wales and the Australian Capital Territory. In turn, contract operators compete mostly for mid-sized brands and specialist goods. They respond by offering shared automation that smaller firms cannot fund alone.
How do slow port volumes limit import-linked growth?
Container imports grew slowly in 2025, which limits how quickly import-linked buffer stock can expand. Port Botany full import volumes rose about 2.3% in the year to June 2025, according to NSW Ports. As a result, operators near the ports cannot rely on trade growth alone to fill new space. Many respond by adding value-added services such as labeling, kitting and reverse logistics for existing clients.
Why does land and construction cost slow new capacity?
Large serviced industrial sites near Sydney and Melbourne are scarce, which pushes up the cost of new warehouses and long leases. Operators must commit to 10-year leases before they secure enough clients to fill them. In turn, smaller operators struggle to add automated space without a large anchor client. Many respond by partnering with developers, signing pre-commitments and consolidating several older sites into one new hub.
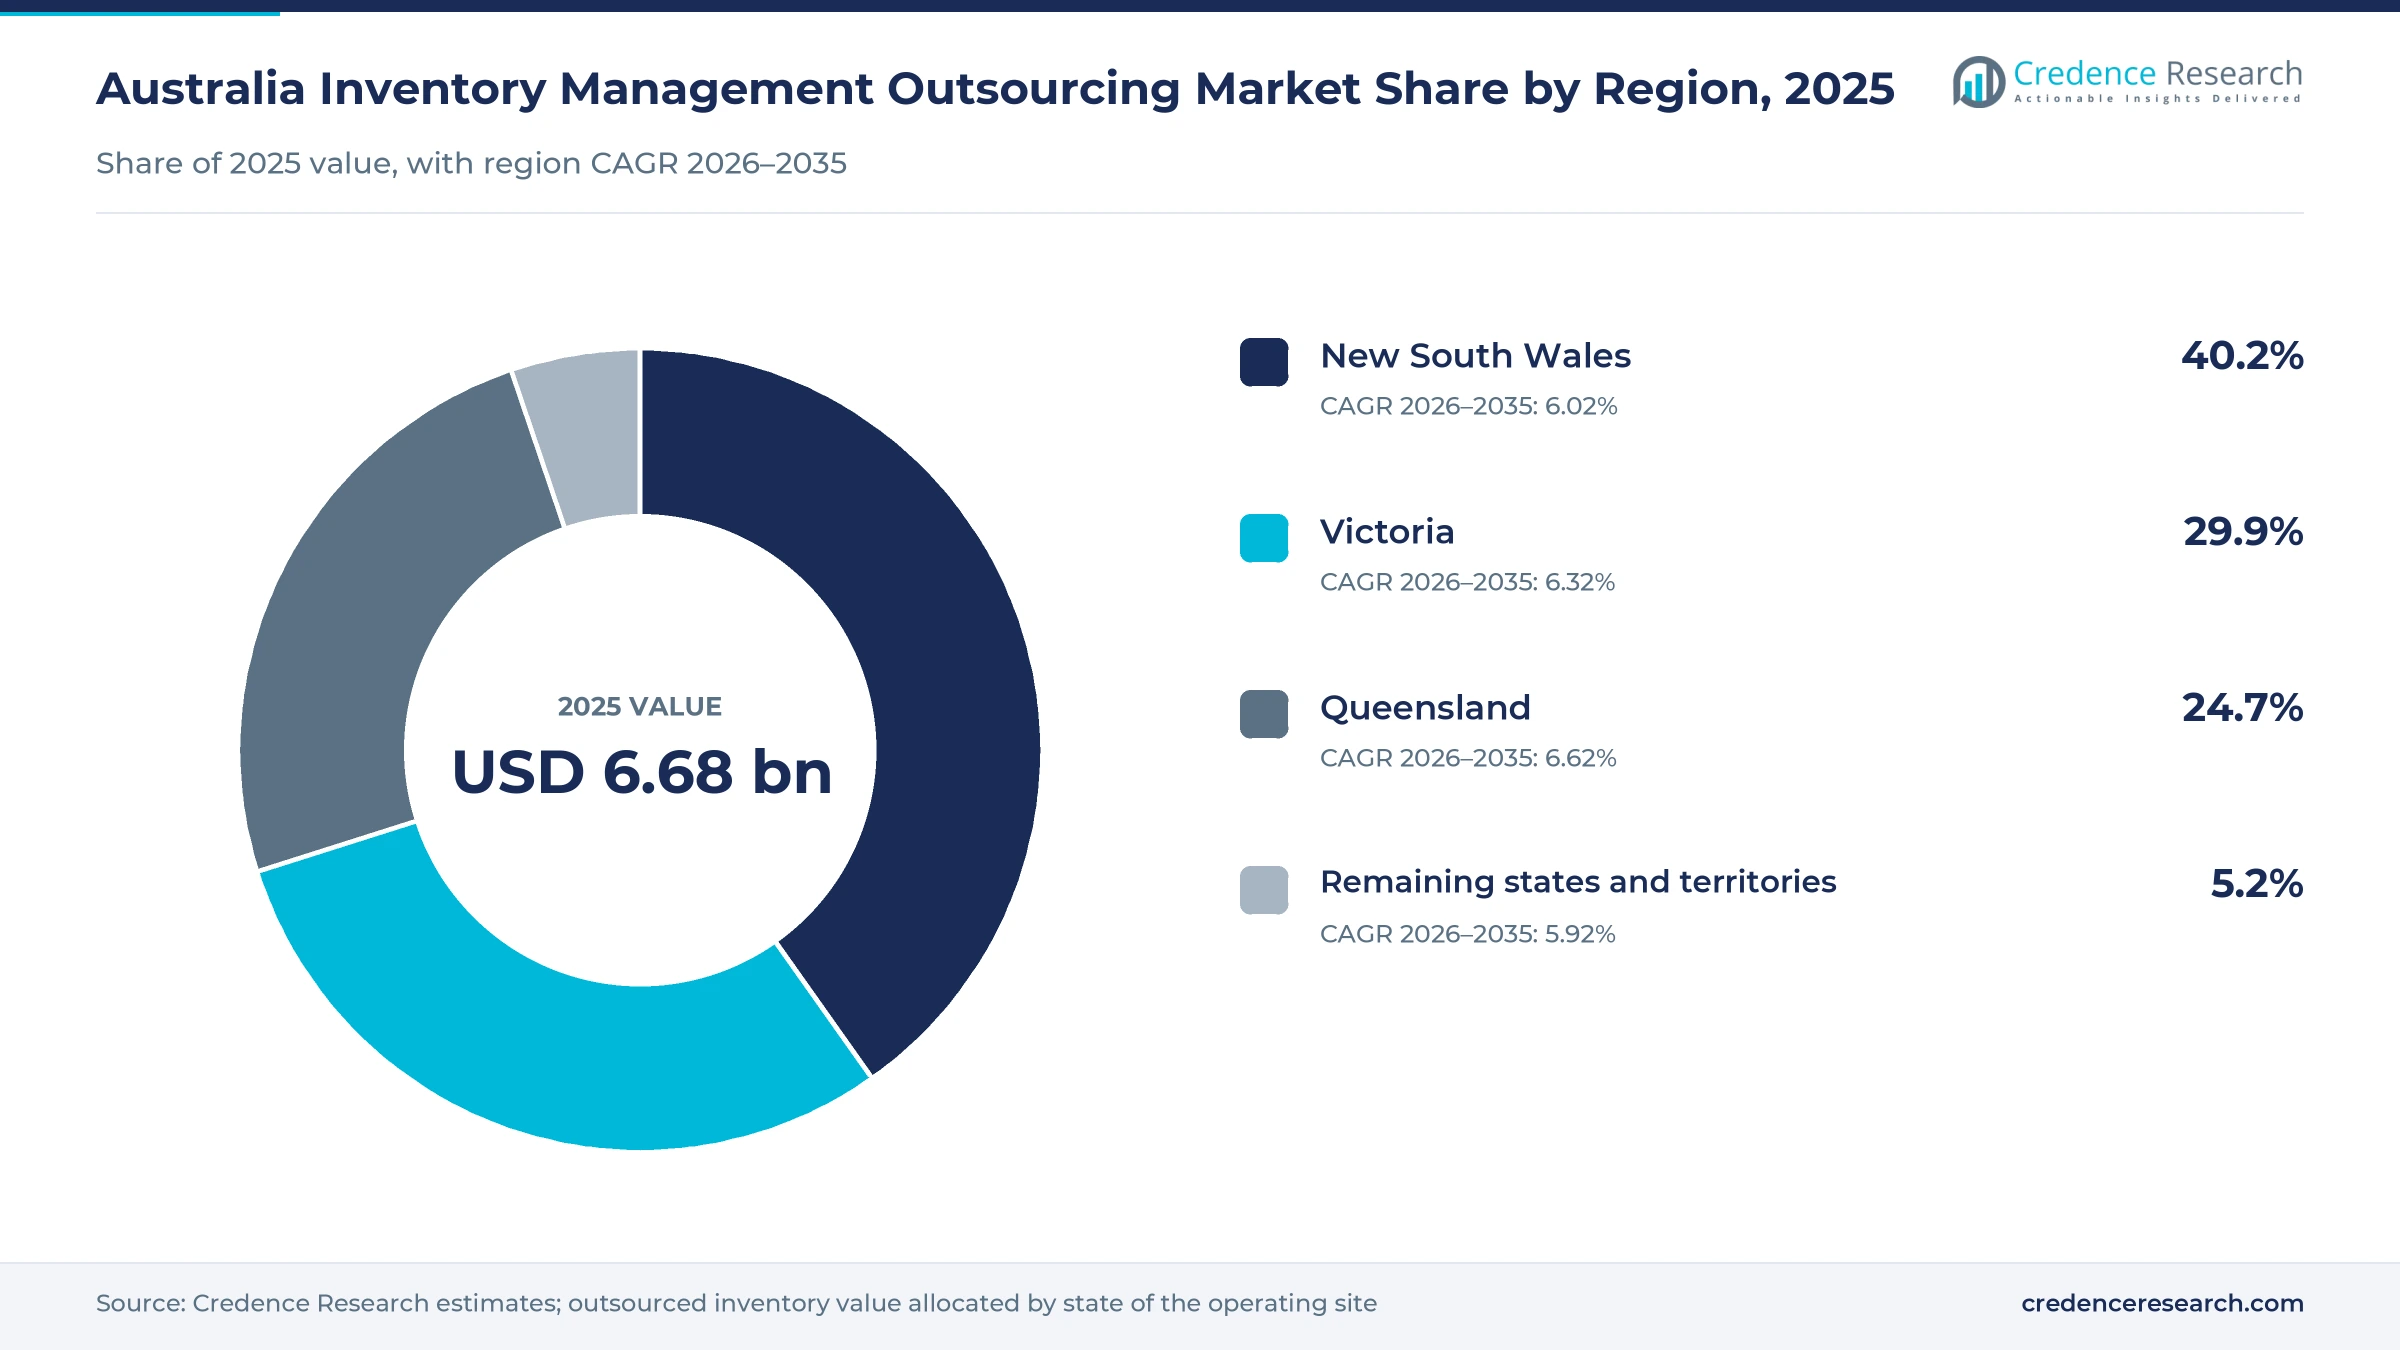
New South Wales leads while Queensland grows fastest
| Region | Value, 2025 (USD billion) | Share, 2025 | CAGR, 2026–2035 |
|---|---|---|---|
| New South Wales | 2.69 | 40.2% | 6.02% |
| Victoria | 2.00 | 29.9% | 6.32% |
| Queensland | 1.65 | 24.7% | 6.62% |
| Remaining states and territories | 0.35 | 5.2% | 5.92% |
Why does Sydney anchor the national warehouse network?
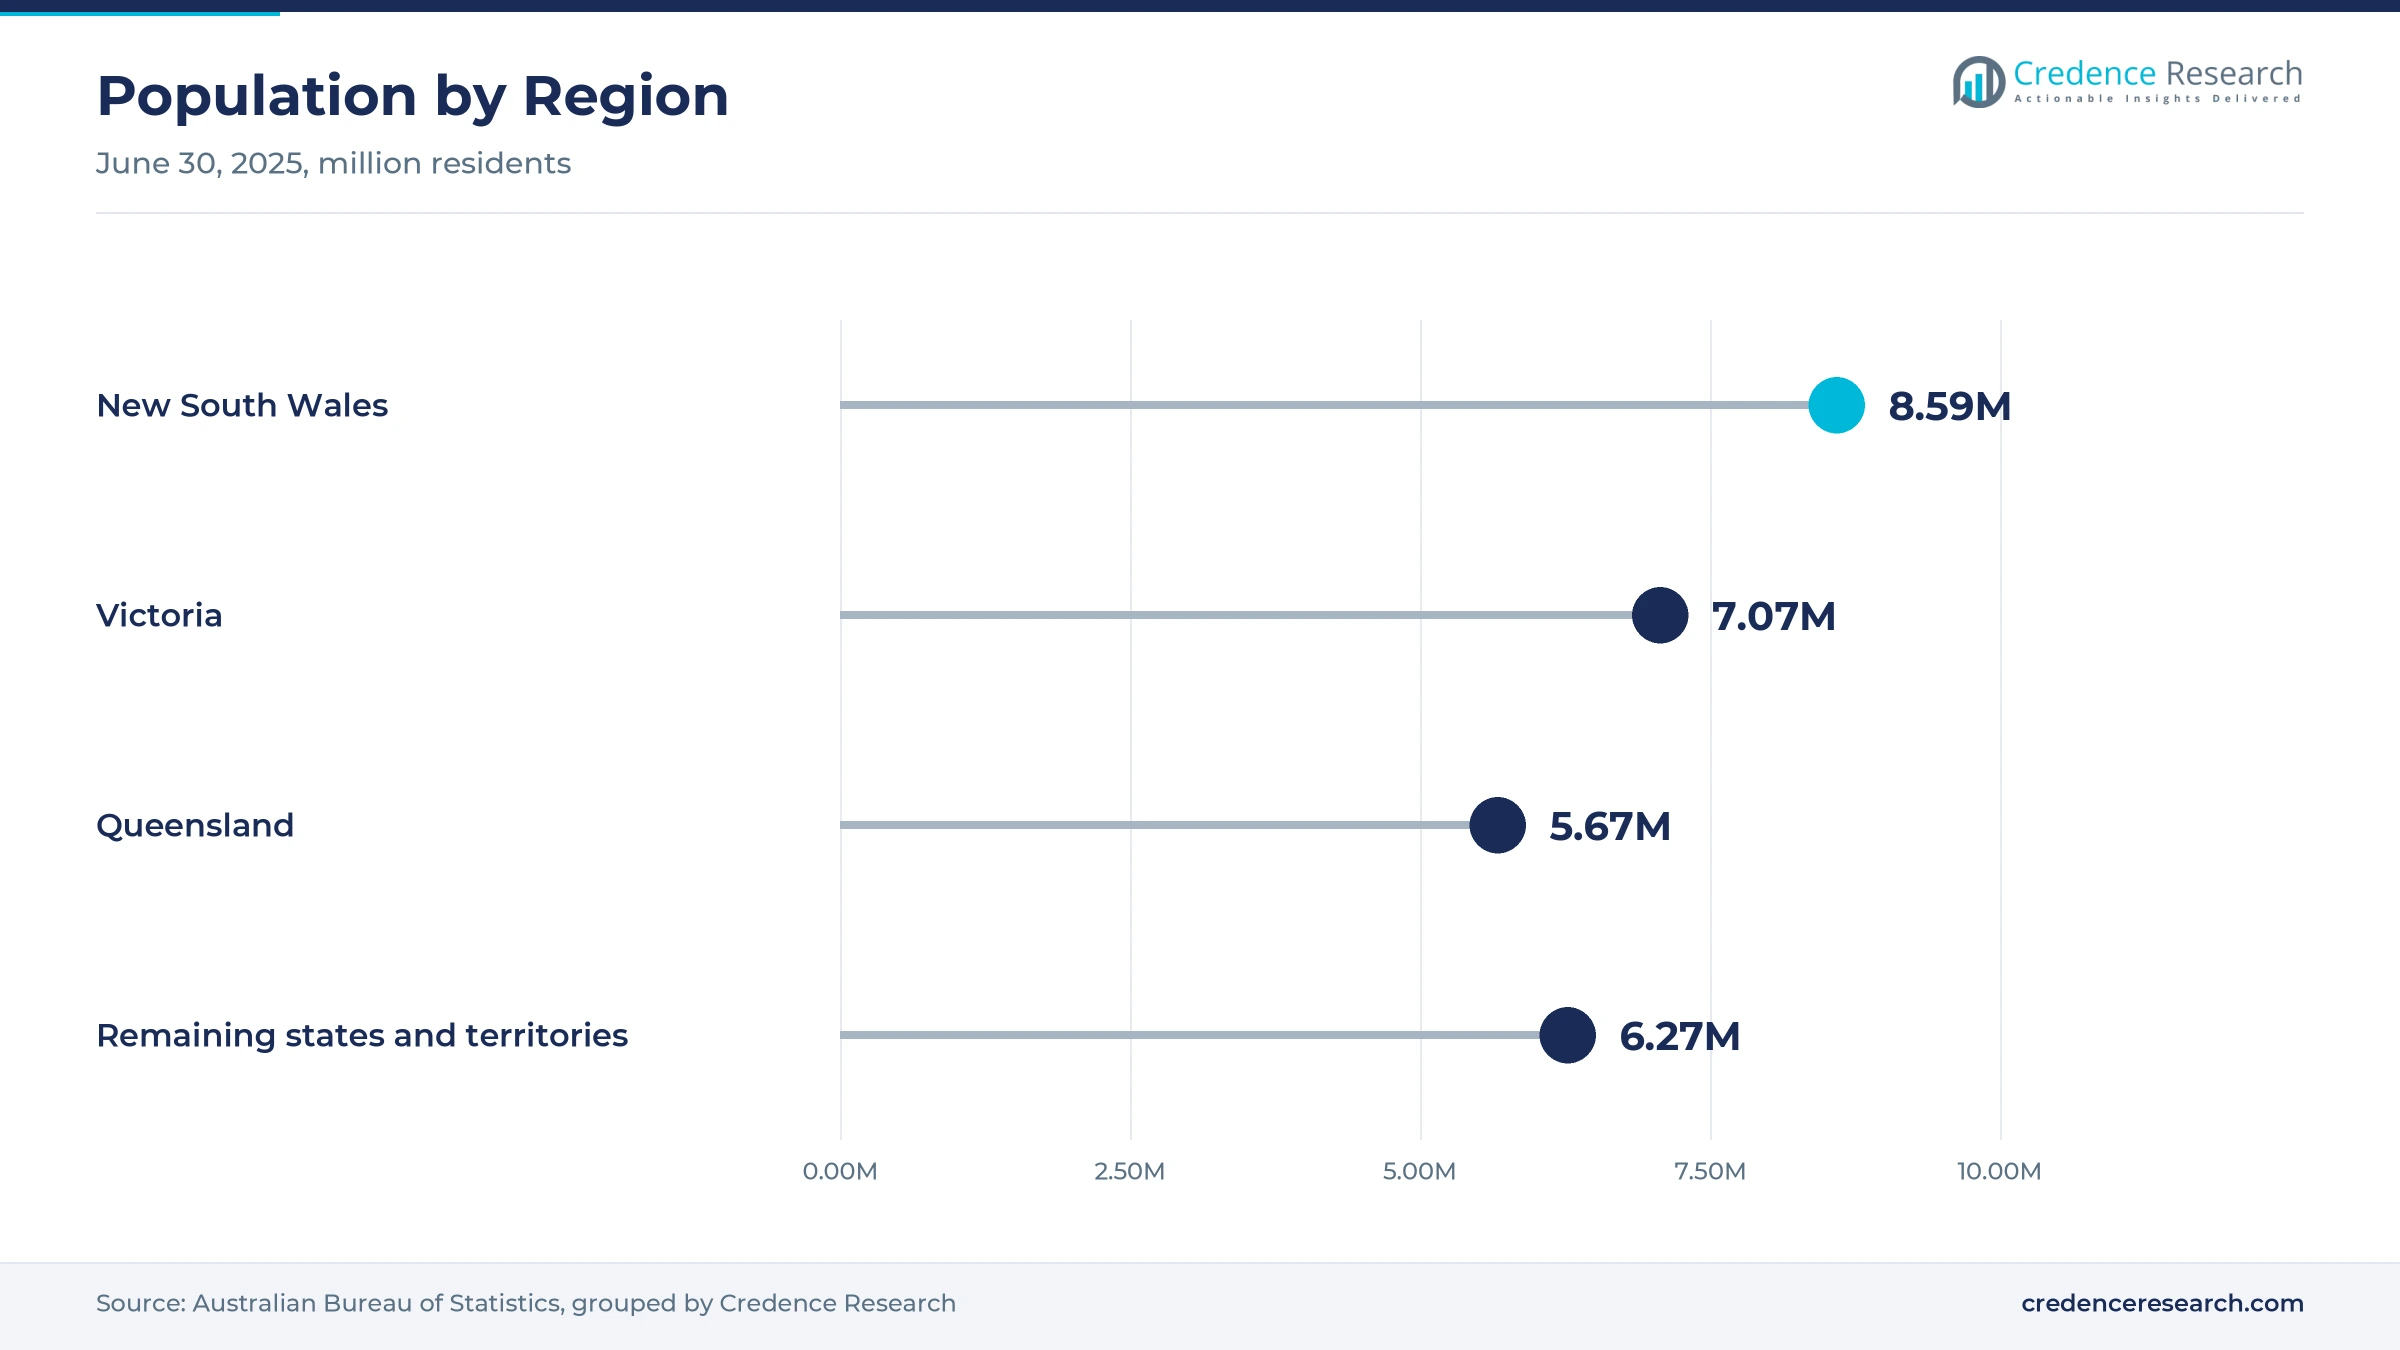
New South Wales held a 40.2% share of 2025 value and grows at 6.02% a year, because western Sydney hosts most national distribution centers. The state had 8.59 million residents at June 30, 2025, the largest of any state, according to the Australian Bureau of Statistics. Port Botany, Moorebank Logistics Park and the Kemps Creek and Erskine Park corridors all sit within reach of Sydney. However, population grew only 1.2% in that year, which keeps the state slightly below the national growth rate.
How does Victoria support national and cold storage demand?
Victoria held a 29.9% share of 2025 value and grows at 6.32% a year, because Melbourne is the second national distribution hub. The state had 7.07 million residents at June 30, 2025, after 1.8% growth, the largest numeric gain of any state. Linfox runs a 52,000-pallet multi-purpose site at Tullamarine, where Unilever is an established client. Victoria added 123,500 residents in that year, which lifts demand for stock held near Melbourne's growth corridors.
Why is Queensland the fastest-growing region?
Queensland held a 24.7% share of 2025 value and grows fastest at 6.62% a year, because Brisbane is adding population and new operator sites. The state had 5.67 million residents at June 30, 2025, after 1.8% growth. Linfox's Willawong site near the Acacia Ridge intermodal terminal has 26,000 square meters of warehouse and office space. Toll Group's Richlands healthcare site also stores vaccines and medical devices for Queensland Health.
Why do smaller states rely on east coast hubs?
Remaining states and territories held a 5.2% share of 2025 value and grow at 5.92% a year, because much national stock for South Australia, Tasmania and the territories is held in east coast hubs. These areas had about 6.27 million residents at June 30, 2025. DHL Supply Chain is building a roughly 20,000-square-meter site at Edinburgh Park in South Australia that merges three local sites.
Robotics, defense stores and new sheds marked 2024 to 2026
| Development | Status and market relevance |
|---|---|
| In December 2024, DHL Supply Chain announced more than AUD 46 million for automated life sciences sites. | Expanded shared cool rooms and robotic picking in Sydney |
| In August 2025, Defence awarded a 10-year, AUD 1.5 billion logistics contract to Toll Remote Logistics. | Moved storage across more than 50 locations under one contract |
| In September 2025, DHL Supply Chain announced a 20,000-square-meter Edinburgh Park site in South Australia. | Merges three sites into one hub due in late 2026 |
| In February 2026, a Macquarie Asset Management-led consortium agreed to acquire Qube Holdings. | Puts a major port and warehousing operator under new ownership |
| In March 2026, DHL Supply Chain opened a 21,078-square-meter warehouse at Erskine Park. | Added space for technology and automotive clients |
Goods-to-person robots and cloud WMS raise pick accuracy
- Goods-to-person robots bring totes to fixed pick stations, which cuts walking time and lifts picks per hour in shared sites.
- Autonomous mobile robots guide pickers through aisles, which lets operators add capacity in peak season without new racking.
- Cloud warehouse management systems give clients live stock and order data, which supports open-book pricing and audits.
- Temperature monitoring and zoning keep medicines and food within set ranges, which is required for licensed healthcare storage.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Global and local operators compete on network and automation
Competition combines global operators with large Australian and trans-Tasman networks. DHL Supply Chain Australia competes on automation and life sciences, with robotic sites at Horsley Park, Skyline and Erskine Park. Linfox runs large dedicated and multi-user sites in Sydney, Melbourne and Brisbane for consumer and healthcare clients. Toll Group combines retail parcel sites with healthcare and defense storage, including the Toll Remote Logistics contract awarded in 2025. Qube Holdings links port terminals, container freight stations and warehousing, and it agreed to new ownership in February 2026. Mainfreight Australia grows through airfreight, perishable and warehousing sites in Melbourne and Brisbane. Companies compete on network reach, automation, cold storage, systems and contract flexibility rather than on storage rates alone. Operators that also run cold chain and pharma logistics gain an edge in healthcare tenders.
Companies profiled and their roles in this market
| Company | Type | Role in the market |
|---|---|---|
| DHL Supply Chain Australia | Global contract operator | Runs robotic and life sciences sites in western Sydney and Adelaide |
| Linfox | Australian contract operator | Runs automated and temperature-zoned sites in Sydney, Melbourne and Brisbane |
| Toll Group | Contract and parcel operator | Runs the Kemps Creek parcel site and Defence storage network |
| Qube Holdings | Port and logistics operator | Runs warehousing and container freight stations at major ports |
| Mainfreight Australia | Trans-Tasman operator | Runs warehousing, airfreight and perishable sites in Melbourne and Brisbane |
Credence Research view on Australian third-party stock
Credence Research's view is that Australian demand for inventory management outsourcing will grow steadily because online orders and specialist storage are too costly for most brands to run alone. Contract storage remains the base, while order picking and shared automated sites grow fastest. Healthcare clients add premium cool room work, and government contracts add large, long-term volumes. However, wage rises, grocer insourcing and slow port volumes will keep pressure on margins. Operators that combine shared robotics, cold rooms and open-book pricing should gain share fastest.
How the Australian third-party stock estimate was built
The inventory management outsourcing report uses 2025 as the base year on a calendar basis, and market values come from the Credence Research model. That model combines national output and freight statistics, population data, port volumes, online spending data and company information on warehouse openings, automation and contracts. Segment splits and regional growth rates are Credence Research estimates, while regional shares follow the client-defined split. Sources used are official statistics, government and port websites and company releases, and no interviews or surveys were used.
Online orders and pharma storage carry growth to 2035
Inventory management outsourcing value in Australia is expected to reach USD 12.30 billion by 2035, a 6.26% CAGR during 2026–2035, as online orders, healthcare storage and shared robotics keep demand rising. Growth should be strongest in Queensland and western Sydney, where new sites and population growth add volume. After 2028, consolidation and automation will matter more than new floor space for winning contracts. Faster import growth would raise this outlook, while more retailer insourcing would lower it. Operators with automated multi-client sites are expected to gain the most.
Frequently Asked Questions
How big is the Australia inventory management outsourcing market?
Which service type leads the Australian market?
Which region leads outsourced stock value in Australia?
How fast did Australian online shopping grow in 2025?
Why are healthcare clients important to operators?
Why are shared-user sites growing?
Who are the leading companies in Australian contract warehousing?
What are the main challenges for the market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Service Type
- 1.2.1 Contract warehousing and storage
- 1.2.2 Order fulfilment
- 1.2.3 Inventory control
- 1.2.4 Returns and value-added services
- 1.3 By End-Use Industry
- 1.3.1 Retail and consumer goods
- 1.3.2 Food and beverage
- 1.3.3 Healthcare and pharmaceuticals
- 1.3.4 Industrial and specialist sectors
- 1.4 By Operating Model
- 1.4.1 Dedicated operator facilities
- 1.4.2 Shared-user operator facilities
- 1.4.3 Customer-site managed operations
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2025: USD 6.68 billion → 2035: USD 12.30 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Historical Period: 2018-2025
- 2.6.2 Base Year: 2025
- 2.6.3 Forecast Period: 2025-2035
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2025
- 3.3 Forecast Market Size, 2035
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Australia Inventory Management Outsourcing Market Trends and Developments
- 4.1 Historical Industry Development, 2018-2025
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Australia Inventory Management Outsourcing Market Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis, 2018-2025
- 5.2 Demand Forecast, 2025-2035
- 5.3 Supply Chain Structure and Procurement Trends
- 5.4 Supply-Demand Gap and Bottlenecks
- 5.5 Import Dependence and Sourcing Structure
- 5.6 Regional Supply and Demand Concentration
Chapter 6 Australia Inventory Management Outsourcing Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends, 2018-2025
- 6.3 Pricing Outlook, 2025-2035
- 6.4 Pricing by Product and Market Segment
- 6.5 Geographic Pricing Differences
- 6.6 Key Input, Energy, Labor and Logistics Costs
- 6.7 Contract Pricing and Purchasing Models
- 6.8 Pricing Sensitivity and Competitive Positioning
- 6.9 Price, Margin and Profitability Implications
Chapter 7 Australia Inventory Management Outsourcing Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Australia Inventory Management Outsourcing Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Australia Inventory Management Outsourcing Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Data Protection, AI and Cybersecurity Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Australia Inventory Management Outsourcing Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Australia Inventory Management Outsourcing Market Outlook, 2025-2035
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2025: USD 6.68 billion → 2035: USD 12.30 billion)
- 11.1.2 Historical Market Size, 2018-2025
- 11.1.3 Base-Year Market Size, 2025
- 11.2 Market Forecast, 2025-2035
- 11.2.1 Revenue Forecast to 2035
- 11.2.2 CAGR and Year-on-Year Growth
- 11.2.3 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Australia Inventory Management Outsourcing Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2025
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Service Type - Market Size and Forecast, 2025-2035
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size, 2018-2025
- 12.3.3 Revenue Forecast, 2025-2035
- 12.3.4 Base-Year Market Share, 2025
- 12.3.5 Segment CAGR and Growth Drivers
- 12.3.6 Subsegment Market Size and Forecast
- 12.3.6.1 Contract warehousing and storage
- 12.3.6.2 Order fulfilment
- 12.3.6.3 Inventory control
- 12.3.6.4 Returns and value-added services
- 12.3.7 Subsegment Pricing and Adoption Trends
- 12.3.8 Leading Suppliers and Competition
- 12.3.9 Regional Demand and Opportunities
- 12.4 By End-Use Industry - Market Size and Forecast, 2025-2035
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size, 2018-2025
- 12.4.3 Revenue Forecast, 2025-2035
- 12.4.4 Base-Year Market Share, 2025
- 12.4.5 Segment CAGR and Growth Drivers
- 12.4.6 Subsegment Market Size and Forecast
- 12.4.6.1 Retail and consumer goods
- 12.4.6.2 Food and beverage
- 12.4.6.3 Healthcare and pharmaceuticals
- 12.4.6.4 Industrial and specialist sectors
- 12.4.7 Subsegment Pricing and Adoption Trends
- 12.4.8 Leading Suppliers and Competition
- 12.4.9 Regional Demand and Opportunities
- 12.5 By Operating Model - Market Size and Forecast, 2025-2035
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size, 2018-2025
- 12.5.3 Revenue Forecast, 2025-2035
- 12.5.4 Base-Year Market Share, 2025
- 12.5.5 Segment CAGR and Growth Drivers
- 12.5.6 Subsegment Market Size and Forecast
- 12.5.6.1 Dedicated operator facilities
- 12.5.6.2 Shared-user operator facilities
- 12.5.6.3 Customer-site managed operations
- 12.5.7 Subsegment Pricing and Adoption Trends
- 12.5.8 Leading Suppliers and Competition
- 12.5.9 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Australia Inventory Management Outsourcing End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Australia Inventory Management Outsourcing Geographic Market Outlook, 2025-2035
- 14.1 Domestic Market Distribution and Demand Clusters
- 14.2 State- or Province-Wise Market Size and Forecast, 2025-2035
- 14.3 City and Metropolitan Market Outlook
- 14.4 Industrial, Manufacturing and Commercial Clusters
- 14.5 Geographic Concentration of Key End Users
- 14.6 Local Pricing and Purchasing Differences
- 14.7 Domestic Production Facilities and Capacity Map
- 14.8 Local Infrastructure and Project Pipeline
- 14.9 State-Level Policy and Incentive Differences
- 14.10 Subnational Investment Hotspots and Opportunities
- 14.11 Distribution and Logistics Networks
- 14.12 Domestic Competitive Footprint
Chapter 15 Australia Inventory Management Outsourcing Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Energy Efficiency and Resource Management
- 15.7 Sustainability, Recycling and Circularity
- 15.8 Technology Roadmap, 2025-2035
- 15.9 Risks of Obsolescence and Technology Substitution
Chapter 16 Australia Inventory Management Outsourcing Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2025
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2025-2035
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 DHL Supply Chain Australia
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Financial Performance and Investment
- 18.2.6 Market Share and Competitive Position
- 18.2.7 Technology and Innovation Capabilities
- 18.2.8 Strategic Alliances or Partnerships
- 18.2.9 Recent Developments
- 18.2.10 Growth Strategy and Outlook
- 18.3 Linfox
- 18.4 Qube Holdings
- 18.5 Toll Group
- 18.6 Mainfreight Australia
- 18.7 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

