
Market Overview:
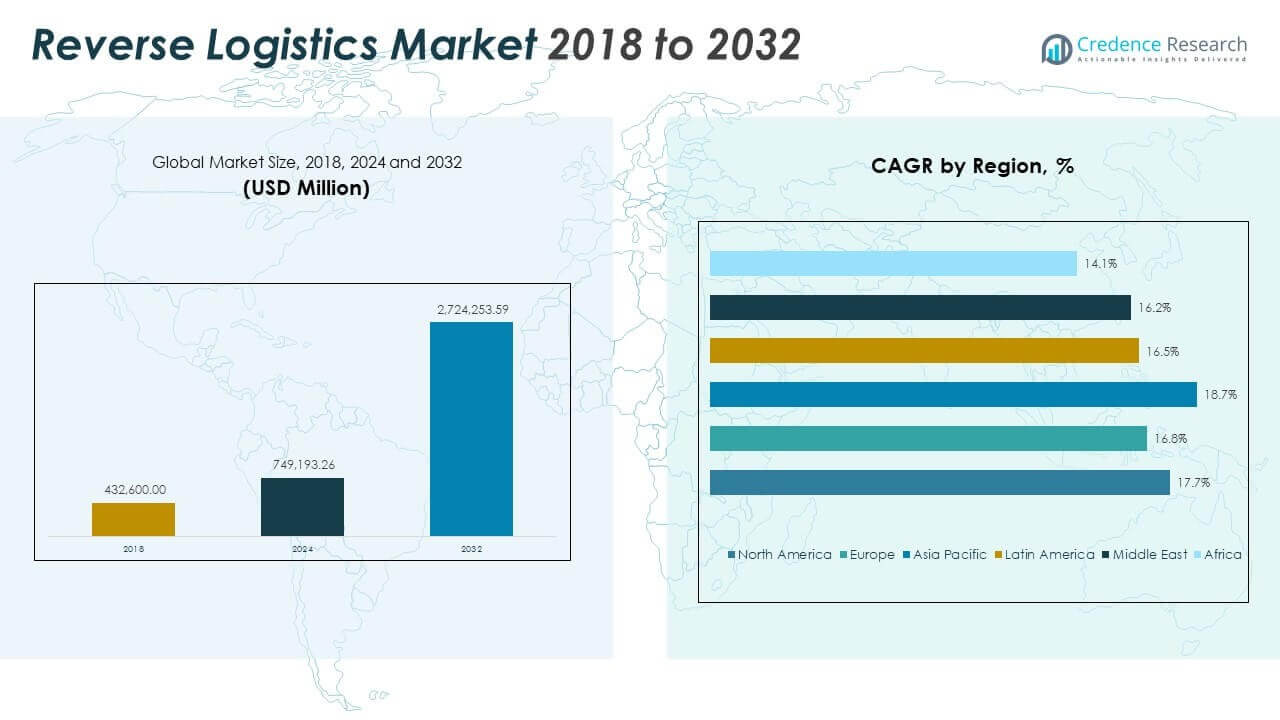
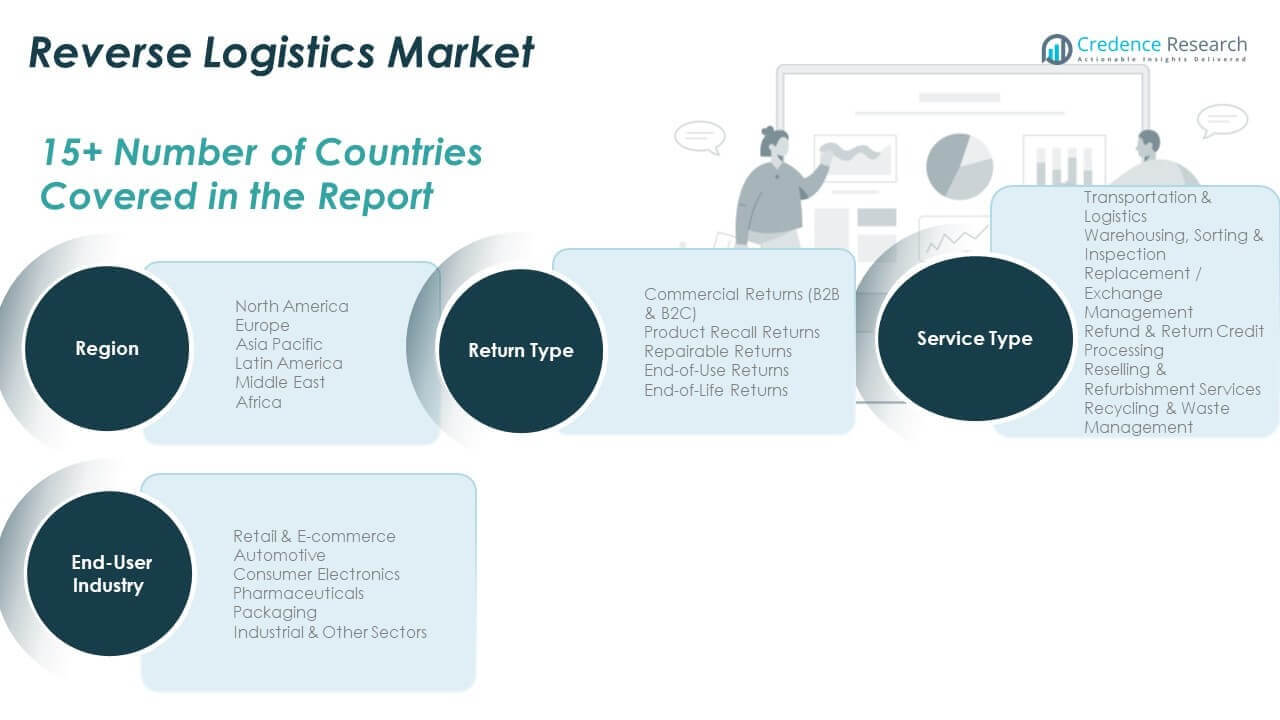
The Reverse Logistics Market size was valued at USD 432,600.00 million in 2018 to USD 749,193.26 million in 2024 and is anticipated to reach USD 2,724,253.59 million by 2032, at a CAGR of 17.65% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Reverse Logistics Market Size 2024 | USD 749,193.26 Million |
| Reverse Logistics Market, CAGR | 17.65% |
| Reverse Logistics Market Size 2032 | USD 2,724,253.59 Million |
The market grows due to rising product returns across e-commerce, retail, and electronics sectors. Companies focus on efficient return handling to reduce losses and protect brand value. Sustainability targets push firms to recover, reuse, and recycle products. Regulatory pressure supports structured take-back and disposal systems. Cost control strategies encourage asset recovery instead of write-offs. Customer demand for simple return policies increases operational focus on reverse flows. Technology adoption improves tracking, sorting, and decision accuracy. These drivers strengthen the role of reverse logistics in supply chains.
North America and Asia Pacific lead the market due to strong e-commerce activity and mature logistics networks. The United States, China, and India show high return volumes from retail and electronics. Europe follows with strong emphasis on circular economy practices and compliance-driven returns. Countries such as Germany, the UK, and France maintain advanced recovery systems. Latin America and the Middle East emerge with growing retail penetration and logistics investment. Africa shows early-stage growth supported by urbanization and digital trade expansion.
Market Insights:
- The Reverse Logistics Market size grew from USD 432,600.00 million in 2018 to USD 749,193.26 million in 2024 and is projected to reach USD 2,724,253.59 million by 2032, registering a CAGR of 17.65% during the forecast period.
- In 2024, the top three regional shares were Asia Pacific (35.68%), North America (29.27%), and Europe (23.53%), driven by advanced infrastructure, high return volumes, and regulatory focus on sustainability.
- Asia Pacific emerged as the fastest-growing region with a CAGR of 18.7%, fueled by high e-commerce penetration, large manufacturing bases, and increasing investment in return logistics systems.
- Commercial Returns (B2B & B2C) accounted for the largest segment by return type, reflecting high volumes from retail and online channels demanding efficient return processes.
- Transportation & Logistics dominated the service type segment, due to its central role in handling, collecting, and redistributing returned goods across industries and regions.
Market Drivers
Strong Growth in E-Commerce Is Fueling High Return Volumes Across Sectors
Online retail has created a sharp increase in product returns across categories like apparel, electronics, and consumer goods. The Reverse Logistics Market is expanding due to the growing need to handle these returns effectively. Companies are investing in infrastructure to support faster product collection, sorting, and reshipment. High return rates in online shopping push businesses to streamline reverse flows. Brands offering free and easy returns need reliable systems to recover product value. E-commerce also drives demand for automated return solutions to reduce operational delays. It encourages logistics providers to improve flexibility and handling speed. These factors keep return logistics central to digital retail growth.
- For instance, Amazon processed approximately 1.2–1.5 billion returned packages annually by 2025, with return rates across categories ranging from 5% to 15%, which remained slightly below the U.S. retail industry average of 16.9%, as reported by NRF and Appriss Retail.
Sustainability Commitments Are Driving Growth in Recycling and Reuse Programs
Corporate sustainability goals push firms to reduce waste and landfill use through product recovery. The Reverse Logistics Market is benefiting from growing investments in repair, refurbishing, and recycling networks. Brands now view take-back programs and asset recovery as core to environmental compliance. Governments introduce circular economy mandates, urging firms to retrieve and process used products. Retailers and manufacturers increasingly use recycled parts and packaging. It helps them meet ESG targets and reduce sourcing pressure. Recycling systems also create cost savings by extracting usable materials. This alignment of business goals and sustainability standards supports reverse logistics growth.
Cost Optimization Strategies Encourage Investments in Asset Recovery
Firms seek to reduce write-offs and optimize inventory through reverse supply chain operations. The Reverse Logistics Market supports these efforts by enabling recovery of value from damaged, excess, or obsolete goods. Businesses improve profitability by reusing returned assets, rather than discarding them. Effective reverse logistics cuts disposal costs and inventory holding expenses. It helps balance demand and supply in lean manufacturing environments. Companies adopt technologies like IoT and blockchain for better return tracking. Asset recovery extends product life cycles and reduces total cost of ownership. This operational focus increases the importance of reverse logistics in supply planning.
- For instance, Walmart leverages IoT for return tracking, reducing disposal costs in line with e-commerce trends handling millions of excess items yearly.
Manufacturer and Retailer Collaboration Enhances Process Efficiency and Customer Experience
Partnerships between brands and logistics providers are key to faster return processing and customer satisfaction. The Reverse Logistics Market gains from joint platforms and shared technology systems. Retailers outsource return management to reduce internal complexity. Logistics partners bring expertise in multi-point collection and consolidation. Efficient coordination ensures fewer delays and better asset utilization. Real-time data exchange supports visibility across product return paths. It strengthens aftersales service and brand loyalty. These collaborative frameworks support scalable and flexible reverse logistics solutions across industries.
Market Trends
Use Of Smart Technologies To Improve Reverse Logistics Visibility And Traceability
Technology adoption is transforming return management through automation, sensors, and real-time tracking. The Reverse Logistics Market is witnessing growing use of IoT, RFID, and GPS to monitor returned goods across their journey. Firms deploy AI for sorting, condition assessment, and warehouse planning. These tools improve accuracy in classification and inventory restocking. Cloud-based platforms connect retailers, customers, and logistics partners for seamless data flow. It supports precise decision-making and reduces loss or mishandling. Predictive analytics forecast return volumes for better route optimization. Smart systems minimize manual touchpoints and improve speed.
Rise Of Consumer Electronics And Appliance Take-Back Programs Across OEMs
Large volumes of electronics enter reverse flows due to upgrades, warranty returns, or end-of-life recovery. The Reverse Logistics Market is seeing expanded programs by OEMs for recycling, refurbishing, and resale of devices. Extended Producer Responsibility (EPR) laws support structured return pathways. Consumers prefer brands that offer simple pickup and refund or replacement options. Take-back systems reduce environmental impact while creating refurbished inventory channels. It helps manufacturers reduce sourcing cost and dependency on raw materials. Reverse supply chains for electronics now include diagnostics and certified refurbishment. This trend supports both sustainability and secondary sales growth.
Development Of Specialized Reverse Logistics Hubs In Urban Distribution Networks
Urban areas face pressure from high-density deliveries and rising return volumes. The Reverse Logistics Market is seeing the rise of localized return hubs to improve turnaround time. These centers handle pickup, inspection, repair, and restocking in short cycles. Logistics firms build micro-hubs to ease congestion and improve response time. Reverse flows get processed close to the customer, reducing transportation costs. Retailers benefit from faster resale or recycling of returned inventory. It also improves customer satisfaction through quicker refunds or exchanges. These urban nodes support reverse logistics scalability in large cities.
- For instance, LoadUp launched a dedicated division in June 2024 for e‑commerce furniture retailers to optimize reverse logistics revenue from returns, improve pickup coordination, and enhance resale and disposal solutions.
Growing Focus On Refurbished Goods Market And Its Integration With Reverse Supply Chains
Refurbished goods present cost-effective options for value-conscious buyers. The Reverse Logistics Market supports this shift by feeding recovered products into certified refurbishment channels. Retailers and OEMs now sell refurbished units through formal channels with warranty backing. Consumers see these products as sustainable and affordable alternatives. This supports demand across smartphones, laptops, appliances, and tools. The rise of B2B resale marketplaces accelerates product lifecycle extension. Refurbishment links closely with reverse logistics in inspection, repair, and resale workflows. This trend builds circular business models in durable goods sectors.
- For instance, LSPedia partnered with Pharma Logistics in August 2024 to enhance pharmaceutical reverse distribution with improved traceability and efficiency.
Market Challenges Analysis
Lack Of Standardization In Reverse Processes Across Industries And Regions
The Reverse Logistics Market faces challenges from fragmented workflows and varying return policies. Companies often operate without standard protocols for sorting, tracking, or restocking. This inconsistency increases operational delays and cost inefficiencies. Cross-border return logistics involves complex customs, inspection, and compliance requirements. Smaller firms lack systems to manage large return volumes efficiently. Inconsistency in labeling, documentation, and packaging adds to processing errors. It affects visibility and control across multi-party supply chains. This lack of alignment makes scale and efficiency difficult to achieve in global reverse operations.
Operational And Cost Burdens In Managing High-Volume Returns Efficiently
High return volumes place strain on warehouses, labor, and transportation systems. The Reverse Logistics Market must address cost pressure from handling, inspection, and restocking activities. Many returns involve partial damage or incomplete packaging, requiring manual intervention. These processes increase overhead without guaranteed resale value. Seasonal spikes create capacity bottlenecks in sorting and storage. Reverse logistics centers face staffing and space challenges during peak periods. IT system limitations hinder visibility across multi-channel returns. Without process automation, reverse flows reduce profit margins for sellers.
Market Opportunities
Expansion Of Circular Economy Programs Across Retail, Automotive, And Electronics Sectors
The Reverse Logistics Market holds strong potential in enabling circular supply models. Governments and corporations are scaling repair, reuse, and recycling systems to reduce waste. It supports long-term product value creation beyond initial sales. Brands invest in design-for-recovery approaches to simplify part extraction and reuse. Reverse logistics networks power these systems with efficient asset return and redistribution.
Rising Demand For Professional Reverse Logistics Providers In Emerging Markets Emerging economies offer significant opportunities for third-party reverse logistics services. Businesses seek specialized providers to manage growing returns in retail and electronics. These markets need structured return pathways to support growth in e-commerce and imports. The Reverse Logistics Market will benefit from regional investments in processing hubs, route optimization, and automation tools.
Market Segmentation Analysis:
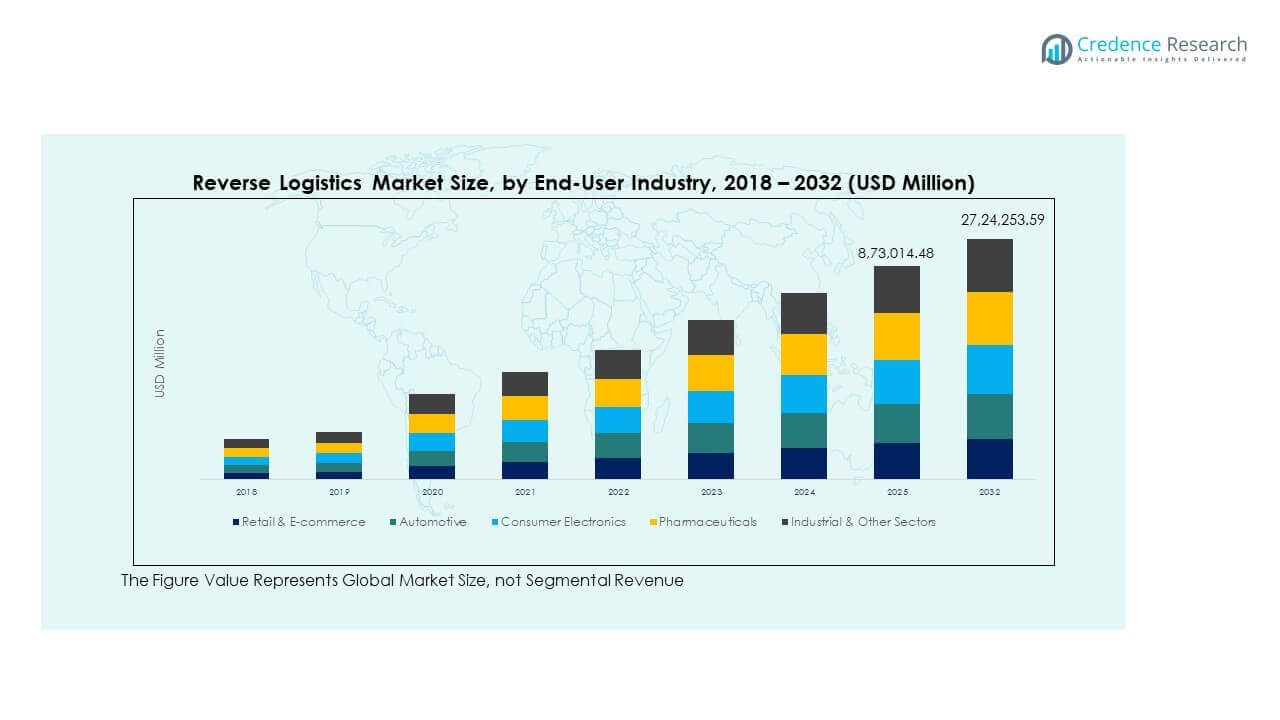
By Return Type, the Reverse Logistics Market is structured across multiple return categories, with commercial returns (B2B and B2C) forming the largest volume share. Product recall returns demand strict regulatory compliance and fast recovery cycles, especially in automotive and electronics sectors. Repairable returns support extended product lifecycles through refurbishment workflows. End-of-use returns enable asset recovery in rental, leasing, and technology sectors, while end-of-life returns are vital for sustainability-focused recycling programs.
- For instance, as of 2025, Dell Technologies has recovered over 2.8 billion pounds of used electronics globally since 2007 through its asset recovery and recycling programs. Its Asset Recovery Services (ARS) offer end-to-end reverse logistics for retiring IT assets, supporting global circular economy goals across more than 170 countries.
By service type, transportation and logistics lead the segment due to their role in product collection, redistribution, and disposal. Warehousing, sorting, and inspection services ensure accurate condition assessment and route optimization. Replacement or exchange management enhances customer satisfaction, while refund and credit processing ensures financial transparency. Reselling and refurbishment services create additional revenue from used goods. Recycling and waste management services are gaining prominence through growing environmental regulations.
By end-user segmentation shows retail and e-commerce as dominant sectors due to high product return rates and short delivery cycles. The automotive sector leverages reverse logistics for parts recovery and warranty handling. Consumer electronics contributes significantly through returns linked to upgrades, defects, and end-of-life products. Pharmaceuticals rely on secure and compliant return systems to manage expired or damaged items. Packaging and industrial sectors adopt reverse logistics to reduce waste and manage reusable materials efficiently. The Reverse Logistics Market adapts to sector-specific demands through customized return and recovery solutions.
- For instance, Dell’s Asset Recovery Services Environmental Impact Report quantifies outcomes from retiring 27,000 devices, providing real-time visibility into how many assets were resold, recycled, or harvested for parts, supporting sustainability and compliance tracking.
Segmentation:
By Return Type
- Commercial Returns (B2B & B2C)
- Product Recall Returns
- Repairable Returns
- End-of-Use Returns
- End-of-Life Returns
By Service Type
- Transportation & Logistics
- Warehousing, Sorting & Inspection
- Replacement / Exchange Management
- Refund & Return Credit Processing
- Reselling & Refurbishment Services
- Recycling & Waste Management
By End-User Industry
- Retail & E-commerce
- Automotive
- Consumer Electronics
- Pharmaceuticals
- Packaging
- Industrial & Other Sectors
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
The North America Reverse Logistics Market size was valued at USD 128,741.76 million in 2018 to USD 219,658.97 million in 2024 and is anticipated to reach USD 797,393.93 million by 2032, at a CAGR of 17.7% during the forecast period. North America accounted for approximately 29.27% of the global market in 2024. The region benefits from mature e-commerce ecosystems, advanced logistics infrastructure, and strong focus on returns processing. The U.S. drives regional dominance through high retail return rates and structured reverse supply chains. Major logistics providers operate extensive reverse networks, supported by automation and analytics. Retailers invest in omnichannel platforms that tightly integrate return services. Electronics, apparel, and automotive sectors lead return volumes. The Reverse Logistics Market here prioritizes speed, customer experience, and regulatory compliance across B2B and B2C flows.
Europe
The Europe Reverse Logistics Market size was valued at USD 106,246.56 million in 2018 to USD 176,339.61 million in 2024 and is anticipated to reach USD 603,020.78 million by 2032, at a CAGR of 16.8% during the forecast period. Europe contributed around 23.53% of the global market in 2024. The region emphasizes sustainability, driving robust systems for recycling, reuse, and refurbishment. EU directives promote circular economy principles, compelling manufacturers to recover post-consumer goods. Germany, France, and the UK lead in reverse logistics efficiency and innovation. Electronics and pharmaceuticals generate high volumes of compliant returns. Companies leverage green logistics models to minimize waste and meet emission goals. The Reverse Logistics Market here adapts to strict regulatory structures while supporting cross-border reverse flows in a unified economic zone.
Asia Pacific
The Asia Pacific Reverse Logistics Market size was valued at USD 149,679.60 million in 2018 to USD 267,346.47 million in 2024 and is anticipated to reach USD 1,044,208.58 million by 2032, at a CAGR of 18.7% during the forecast period. Asia Pacific held the largest share of the global market in 2024, estimated at 35.68%. High product consumption, manufacturing intensity, and e-commerce growth drive the region’s scale. China, India, Japan, and Southeast Asia see rising investments in reverse infrastructure. Growing awareness of environmental regulations supports expansion of recycling and refurbishment services. Logistics providers develop regional hubs to manage returns efficiently. Technology adoption supports real-time tracking and automation. The Reverse Logistics Market benefits from volume scalability and government-led circular economy initiatives across key markets.
Latin America
The Latin America Reverse Logistics Market size was valued at USD 25,090.80 million in 2018 to USD 42,996.19 million in 2024 and is anticipated to reach USD 144,031.26 million by 2032, at a CAGR of 16.5% during the forecast period. Latin America held a 5.73% share of the global market in 2024. Brazil and Mexico are leading adopters of structured reverse logistics systems. Retail, electronics, and automotive sectors generate significant return flows. Growing digital commerce accelerates demand for return management solutions. Infrastructure gaps and fragmented supply chains present operational challenges. Companies rely on third-party logistics partners to manage returns efficiently. It remains a developing market with growing demand for integrated, cost-effective solutions. The Reverse Logistics Market here is positioned for expansion through investments in network optimization and technology platforms.
Middle East
The Middle East Reverse Logistics Market size was valued at USD 16,438.80 million in 2018 to USD 26,666.41 million in 2024 and is anticipated to reach USD 87,463.52 million by 2032, at a CAGR of 16.2% during the forecast period. In 2024, the region held 3.56% of the global market. High import volumes across consumer electronics and automotive parts generate steady reverse flows. GCC countries are investing in logistics hubs to improve return processing and waste reduction. Retailers adopt omnichannel models to handle return requests across physical and online channels. Governments support recycling initiatives and electronic waste recovery. Infrastructure expansion improves regional connectivity and reduces return cycle time. It reflects growing regional awareness of circular economy models. The Reverse Logistics Market here benefits from rising consumer expectations and regulatory support.
Africa
The Africa Reverse Logistics Market size was valued at USD 6,402.48 million in 2018 to USD 16,185.61 million in 2024 and is anticipated to reach USD 48,135.52 million by 2032, at a CAGR of 14.1% during the forecast period. Africa accounted for 2.15% of the global market in 2024. The region is at an early stage of reverse logistics development, with uneven infrastructure and limited digital tracking. South Africa and Egypt lead regional activity due to stronger retail and industrial bases. Informal networks handle significant product returns in rural markets. Growth in mobile device returns and refurbished goods drives demand for organized systems. International logistics providers expand operations to capture growing volumes. It sees potential in building structured reverse supply chains for both environmental and economic gains. The Reverse Logistics Market is gaining traction through public-private collaboration and donor-backed sustainability programs.
Key Player Analysis:
- DB Schenker (Deutsche Bahn AG)
- Deutsche Post AG
- FedEx Corporation
- Kintetsu World Express, Inc.
- United Parcel Service, Inc. (UPS)
- Yusen Logistics Co., Ltd.
- RLG Systems AG
- Core Logistic Private Limited
- Safexpress Pvt. Ltd.
- H. Robinson Worldwide, Inc.
Competitive Analysis:
The Reverse Logistics Market features a mix of global logistics giants and specialized regional players. Major companies such as DB Schenker, FedEx, UPS, and Deutsche Post AG dominate with extensive infrastructure, integrated service portfolios, and global reach. It reflects strong competition driven by innovation in automation, tracking, and sustainability. Players invest in dedicated reverse hubs, AI-based sorting, and return management platforms. Regional firms like Safexpress and Core Logistic serve niche demands across local markets. Companies pursue mergers, acquisitions, and partnerships to expand service capabilities and geographic presence. Customization, speed, and cost efficiency remain key differentiators. Market leaders focus on end-to-end visibility, tech-driven returns optimization, and circular supply chain integration. The Reverse Logistics Market demands continuous process refinement and adaptability to meet industry-specific return flows and evolving regulatory standards.
Recent Developments:
- In January 2025, DHL Supply Chain acquired Inmar Supply Chain Solutions, a returns solutions provider for retail e-commerce. In this deal, DHL gained 14 return centers and around 800 associates, positioning it as the largest reverse logistics provider in North America while enhancing capabilities in product remarketing and analytics.
- In April 2025, DB Schenker, under Deutsche Bahn AG, completed its acquisition by DSV marking a major shift in the logistics sector relevant to reverse logistics through enhanced global supply chain capabilities.
Report Coverage:
The research report offers an in-depth analysis based on Return Type, Service Type and End-User Industry. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Reverse logistics will become core to circular economy strategies across electronics, automotive, and retail sectors.
- Adoption of AI-powered return management platforms will streamline sorting, inspection, and inventory reintegration.
- Retailers will integrate reverse logistics into omnichannel fulfillment systems to enhance customer satisfaction.
- Government regulations will strengthen take-back mandates, especially in packaging and electronic waste management.
- Growth of the refurbished goods market will drive higher demand for repairable and end-of-use product flows.
- Logistics providers will expand regional hubs to reduce return transit time and optimize reverse networks.
- Demand for carbon-efficient reverse transport will promote green logistics partnerships and fleet electrification.
- Data analytics will play a critical role in forecasting return volumes and optimizing resource planning.
- Emerging economies will witness rapid growth in formalized reverse logistics infrastructure and services.
- Integration of blockchain will improve traceability and compliance across multi-tier return supply chains.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
E-commerce Expansion Driving High Return Volumes
The rapid growth of online retail has led to a significant increase in product returns, especially in categories like apparel, electronics, and consumer goods. This surge requires robust reverse logistics systems to efficiently handle, process, and reintegrate returned products, fueling market growth.
Corporate Sustainability and Circular Economy Initiatives
Companies are increasingly investing in recycling, refurbishing, and take-back programs to meet sustainability targets and regulatory requirements. These initiatives drive demand for advanced reverse logistics solutions that enable product recovery, reuse, and responsible disposal.
Cost Optimization and Asset Recovery Strategies
Businesses seek to minimize write-offs and reduce inventory holding costs by recovering value from returned, excess, or obsolete goods. Effective reverse logistics operations help companies optimize costs, extend product lifecycles, and improve profitability.
Technology Adoption for Enhanced Visibility and Efficiency
The integration of IoT, AI, RFID, and real-time tracking technologies is transforming reverse logistics by improving accuracy in sorting, condition assessment, and inventory management. These advancements streamline return processes, reduce manual intervention, and support data-driven decision-making.
Regulatory Pressure and Compliance Requirements
Governments and industry bodies are enforcing stricter regulations around product take-back, recycling, and waste management, particularly in electronics and packaging. Compliance with these mandates necessitates structured and scalable reverse logistics systems, driving market expansion.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Reverse Logistics Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Reverse Logistics Market projected to grow between 2024 and 2032?
Which Reverse Logistics Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Reverse Logistics Market?
Who are the leading companies in the Reverse Logistics Market?
Which region commanded the largest share of the Reverse Logistics Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Return Type
- 1.2.1 Commercial Returns (B2B & B2C)
- 1.2.2 Product Recall Returns
- 1.2.3 Repairable Returns
- 1.2.4 End-of-Use Returns
- 1.2.5 End-of-Life Returns
- 1.3 By Service Type
- 1.3.1 Transportation & Logistics
- 1.3.2 Warehousing, Sorting & Inspection
- 1.3.3 Replacement / Exchange Management
- 1.3.4 Refund & Return Credit Processing
- 1.3.5 Reselling & Refurbishment Services
- 1.3.6 Recycling & Waste Management
- 1.4 By End-User Industry
- 1.4.1 Retail & E-commerce
- 1.4.2 Automotive
- 1.4.3 Consumer Electronics
- 1.4.4 Pharmaceuticals
- 1.4.5 Packaging
- 1.4.6 Industrial & Other Sectors
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 749,193.26 million → 2032: USD 2,724,253.59 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Reverse Logistics Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Reverse Logistics Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Reverse Logistics Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Reverse Logistics Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Reverse Logistics Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Reverse Logistics Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Reverse Logistics Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Reverse Logistics Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 749,193.26 million → 2032: USD 2,724,253.59 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Reverse Logistics Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Return Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Commercial Returns (B2B & B2C)
- 12.3.7.2 Product Recall Returns
- 12.3.7.3 Repairable Returns
- 12.3.7.4 End-of-Use Returns
- 12.3.7.5 End-of-Life Returns
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Service Type - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Transportation & Logistics
- 12.4.7.2 Warehousing, Sorting & Inspection
- 12.4.7.3 Replacement / Exchange Management
- 12.4.7.4 Refund & Return Credit Processing
- 12.4.7.5 Reselling & Refurbishment Services
- 12.4.7.6 Recycling & Waste Management
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By End-User Industry - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Retail & E-commerce
- 12.5.7.2 Automotive
- 12.5.7.3 Consumer Electronics
- 12.5.7.4 Pharmaceuticals
- 12.5.7.5 Packaging
- 12.5.7.6 Industrial & Other Sectors
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Reverse Logistics End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Reverse Logistics Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Reverse Logistics Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Reverse Logistics Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 DB Schenker (Deutsche Bahn AG)
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Deutsche Post AG
- 18.4 FedEx Corporation
- 18.5 Kintetsu World Express, Inc.
- 18.6 United Parcel Service, Inc. (UPS)
- 18.7 Yusen Logistics Co., Ltd.
- 18.8 RLG Systems AG
- 18.9 Core Logistic Private Limited
- 18.10 Safexpress Pvt. Ltd.
- 18.11 C.H. Robinson Worldwide, Inc.
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

