
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Bakery Mixes Market Size 2024 | USD 6,469.09 million |
| Bakery Mixes Market, CAGR | 7.23% |
| Bakery Mixes Market Size 2032 | USD 11,761.60 million |
Market Overview
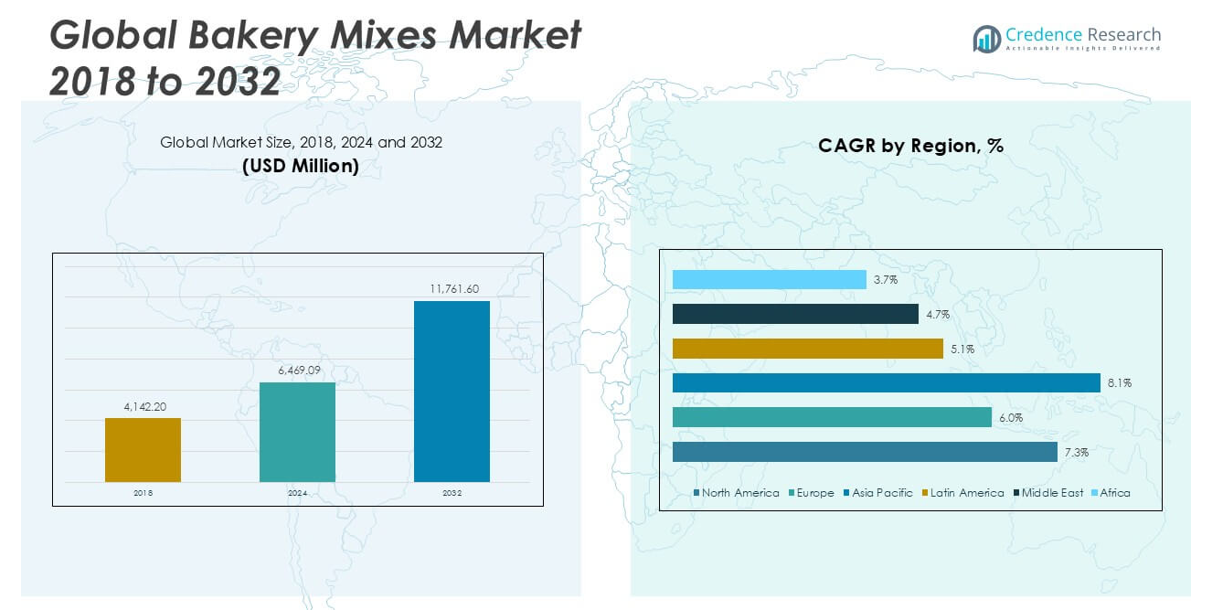
The Bakery Mixes Market size was valued at USD 4,142.20 million in 2018, increased to USD 6,469.09 million in 2024, and is anticipated to reach USD 11,761.60 million by 2032, at a CAGR of 7.23% during the forecast period.
The Bakery Mixes market is led by key players such as Archer Daniels Midland Company (ADM), Puratos Group, Cargill, Incorporated, Kerry Group, Dawn Food Products, and General Mills, Inc., each contributing significantly through innovation, global distribution, and strong brand portfolios. These companies focus on expanding clean-label and functional product offerings to align with evolving consumer preferences. North America dominates the global market, holding a 32.2% share in 2024, supported by high consumption of packaged baked goods and the presence of major foodservice chains. Asia Pacific follows with a 41.5% share, driven by rapid urbanization, rising disposable incomes, and increasing demand for Western-style bakery products.
Market Insights
- The global Bakery Mixes market was valued at USD 6,469.09 million in 2024 and is expected to reach USD 11,761.60 million by 2032, growing at a CAGR of 7.23% during the forecast period.
- Increasing demand for convenience-based baking solutions and rising home baking trends are major drivers fueling the market growth across both developed and emerging regions.
- Clean-label, organic, and gluten-free mixes are trending due to growing health awareness and dietary preferences, offering new opportunities for manufacturers.
- The market is competitive, with key players such as ADM, Cargill, General Mills, and Puratos focusing on innovation and strategic partnerships to strengthen their positions.
- North America held the largest regional share at 32.2%, followed by Asia Pacific with 41.5% in 2024; by segment, flours led the product type category, while bread dominated the application segment due to its widespread consumption and staple status.
Market Segmentation Analysis:
By Product Type:
In the Bakery Mixes market, flours emerged as the dominant product type, accounting for the largest market share in 2024. Their essential role as a base ingredient across a wide range of bakery items, including bread, cakes, and cookies, sustains their high demand. The rise in home baking and the growing availability of all-purpose, gluten-free, and specialty flours further support segment growth. In contrast, sweeteners and cocoa and chocolate are gaining traction due to evolving taste preferences and the increased popularity of indulgent products, while edible oils support product texture and shelf stability.
- For instance, in 2023, Ardent Mills opened a dedicated gluten-free facility in Denver, Colorado, with a 115,000-square-foot capacity, producing 50 million pounds of gluten-free flours annually to meet surging demand.
By Application
Bread held the largest market share in the application segment of the bakery mixes market, driven by its status as a staple in global diets. The segment benefits from consumer demand for convenience, consistent quality, and time-saving preparation methods. Rising urbanization and the expansion of quick-service restaurants have further accelerated growth. Cakes & pies and cookies & biscuits follow closely due to their increasing consumption at events and celebrations. Meanwhile, pizza dough, brownies, and pancakes & waffles mixes are experiencing steady demand, particularly in Western markets and among younger consumers seeking diverse bakery options.
- For instance, General Mills reported in 2022 that its Pillsbury line of bread and pizza mixes saw a 28% increase in North American foodservice unit sales year-over-year, driven by quick-service restaurants adopting pre-mix solutions.
By Source
Among the source types, natural bakery mixes dominated the market, capturing the largest share in 2024. Increasing health consciousness and a shift toward clean-label products have driven demand for naturally sourced ingredients without synthetic additives. Consumers are actively seeking minimally processed mixes with recognizable ingredients. Organic bakery mixes are gaining market momentum, particularly among premium buyers and environmentally conscious consumers. Although artificial mixes still maintain a presence due to their cost-effectiveness and longer shelf life, their growth is relatively limited by shifting consumer preferences toward healthier alternatives.
Market Overview
Rising Demand for Convenient Baking Solutions
The growing consumer preference for ready-to-use and time-saving food products is a significant driver in the bakery mixes market. As urban lifestyles become increasingly hectic, consumers seek baking mixes that eliminate the need for ingredient measuring and lengthy preparation. These mixes offer a reliable and efficient solution for home bakers and commercial kitchens alike. Additionally, the surge in home baking, particularly after the pandemic, has elevated the demand for easy-to-use mixes that deliver consistent results, fueling further market expansion.
- For instance, in 2021, Dawn Foods launched its “Mix It Up” product line, enabling bakers to create over 100 unique recipes from 10 core mix bases, which led to over 15,000 new customer sign-ups within the first six months.
Growth in Foodservice and Bakery Chains
The expansion of foodservice outlets, cafés, and bakery chains globally contributes significantly to the rising demand for bakery mixes. These commercial establishments prioritize consistency, efficiency, and speed in production, making bakery mixes a practical solution. With increasing consumer demand for baked goods across breakfast, snack, and dessert menus, operators are turning to pre-formulated mixes to reduce labor costs and maintain uniformity. As quick-service restaurants and specialty bakeries continue to proliferate, the demand for bakery mixes is expected to grow steadily.
- For instance, Puratos Group partnered with over 6,000 bakery outlets globally by 2023 to deploy its O-tentic natural fermentation mix, which reduces prep time by 30 minutes compared to traditional processes.
Innovation in Product Formulations
Ongoing innovation in bakery mix formulations-such as gluten-free, vegan, high-protein, and organic variants-is fueling consumer interest and driving market growth. Manufacturers are introducing clean-label and functional ingredients to align with shifting dietary preferences. These innovations not only address specific health concerns but also attract consumers looking for novelty in taste and nutrition. The growing awareness of allergen-friendly and specialty diets is further encouraging product development, helping brands to differentiate themselves and expand their consumer base in both mature and emerging markets.
Key Trends & Opportunities
Rising Popularity of Clean Label and Organic Products
Consumers are increasingly scrutinizing product labels and preferring mixes with natural, organic, and recognizable ingredients. This trend is encouraging manufacturers to reformulate bakery mixes without artificial preservatives, colors, or additives. The clean-label movement presents a significant opportunity for brands to build consumer trust and capitalize on the premium pricing potential of healthier offerings. Organic bakery mixes, in particular, are gaining traction in North America and Europe, where consumer awareness and disposable incomes are higher, offering considerable growth potential.
- For instance, in 2022, Corbion reformulated over 80 bakery mix SKUs across its North American portfolio to meet clean-label standards, eliminating 14 artificial additives including propionates and synthetic emulsifiers.
Expansion into Emerging Markets
Emerging economies in Asia-Pacific, Latin America, and the Middle East are presenting lucrative opportunities for bakery mix manufacturers. Rising disposable incomes, urbanization, and exposure to Western eating habits are driving demand for packaged baked goods and home baking products. As global brands expand their distribution networks and offer localized flavors, they can capture a growing base of aspirational consumers seeking convenient baking options. Tailoring product formats to suit regional tastes and affordability will further enhance market penetration in these high-potential regions.
- For instance, in 2023, Kerry Group opened a USD 38 million manufacturing facility in Karnataka, India, with a capacity to produce 36,000 metric tons of food ingredients annually, including regional bakery mix variants tailored for South Asian consumers.
Key Challenges
Rising Raw Material Costs
The bakery mixes market is vulnerable to price fluctuations in raw materials such as wheat, sugar, cocoa, and edible oils. These commodities are often subject to climate variability, supply chain disruptions, and geopolitical instability, which can significantly increase production costs. Manufacturers struggle to maintain competitive pricing while preserving profit margins, especially in price-sensitive markets. This volatility places pressure on smaller producers and may lead to reformulation or cost-cutting measures that compromise product quality.
Intense Market Competition
The market is highly fragmented with the presence of both global and regional players offering similar product ranges. Intense competition leads to pricing pressures, limited differentiation, and reduced brand loyalty. New entrants further intensify the challenge by introducing low-cost alternatives or targeting niche health segments with specialized offerings. To remain competitive, established companies must invest continuously in marketing, innovation, and distribution-factors that can strain financial resources and impact long-term profitability.
Limited Shelf Life and Storage Constraints
Despite offering convenience, bakery mixes often have limited shelf life due to the absence of strong preservatives in clean-label formulations. Ensuring product stability during transportation and storage, especially in tropical climates, remains a logistical challenge. Retailers may hesitate to stock large inventories of such products, impacting availability. Manufacturers must balance clean-label appeal with functional shelf-life solutions to maintain product quality and customer satisfaction across varied geographies.
Regional Analysis
North America
North America held the largest share of the global bakery mixes market in 2024, accounting for approximately 32.2% of the total revenue. The market grew from USD 1,351.77 million in 2018 to USD 2,081.79 million in 2024 and is projected to reach USD 3,799.06 million by 2032, registering a CAGR of 7.3% during the forecast period. The region benefits from a well-established baking culture, strong presence of leading bakery chains, and high consumer demand for convenience products. Continued innovation in gluten-free and organic mixes also supports growth across retail and foodservice sectors.
Europe
Europe captured a market share of approximately 19.0% in 2024, making it the third-largest regional contributor. Valued at USD 825.25 million in 2018, the market rose to USD 1,222.68 million in 2024 and is expected to reach USD 2,034.79 million by 2032, growing at a CAGR of 6.0%. The region’s demand is driven by health-conscious consumers seeking clean-label and organic mixes. Traditional baking preferences, combined with modern convenience needs, have supported the steady adoption of pre-formulated baking solutions across households and bakeries in countries like Germany, France, and the UK.
Asia Pacific
Asia Pacific was the second-largest regional market in 2024, holding a market share of approximately 41.5%. The region's value rose from USD 1,650.46 million in 2018 to USD 2,681.99 million in 2024, and it is forecast to reach USD 5,201.27 million by 2032, expanding at the highest CAGR of 8.1%. The rapid growth is attributed to rising urbanization, increasing disposable income, and the growing influence of Western diets. Countries such as China, India, and Japan are witnessing heightened consumption of packaged bakery products, creating strong demand for convenient baking mixes in both home and commercial settings.
Latin America
Latin America contributed about 3.7% to the global bakery mixes market in 2024. The market was valued at USD 154.67 million in 2018, reached USD 237.76 million in 2024, and is projected to grow to USD 369.23 million by 2032, with a CAGR of 5.1%. Growth is supported by increasing urbanization, a rising middle class, and growing popularity of baked snacks. Brazil and Mexico are key contributors, with consumers showing interest in quick and affordable baking options. Although growth is moderate, expanding retail penetration and localized product offerings are expected to stimulate future demand.
Middle East
The Middle East accounted for around 2.3% of the global bakery mixes market in 2024. The market increased from USD 104.96 million in 2018 to USD 148.36 million in 2024, and it is anticipated to reach USD 222.69 million by 2032, recording a CAGR of 4.7%. Consumer interest in Western-style bakery products and expanding bakery retail formats are driving regional demand. Countries like the UAE and Saudi Arabia are witnessing increasing bakery product consumption, supported by a growing expatriate population and rising disposable income. However, the market is still developing and offers long-term growth potential.
Africa
Africa represented the smallest regional market, contributing 1.5% to global revenue in 2024. Starting at USD 55.09 million in 2018, the market reached USD 96.53 million in 2024 and is forecast to reach USD 134.57 million by 2032, expanding at a CAGR of 3.7%. The region’s growth is constrained by lower income levels and limited access to packaged bakery products. However, urbanization and gradual retail sector development are fostering demand in countries such as South Africa, Nigeria, and Kenya. With increasing exposure to convenience foods, Africa presents an emerging opportunity for affordable and shelf-stable bakery mix products.
Market Segmentations:
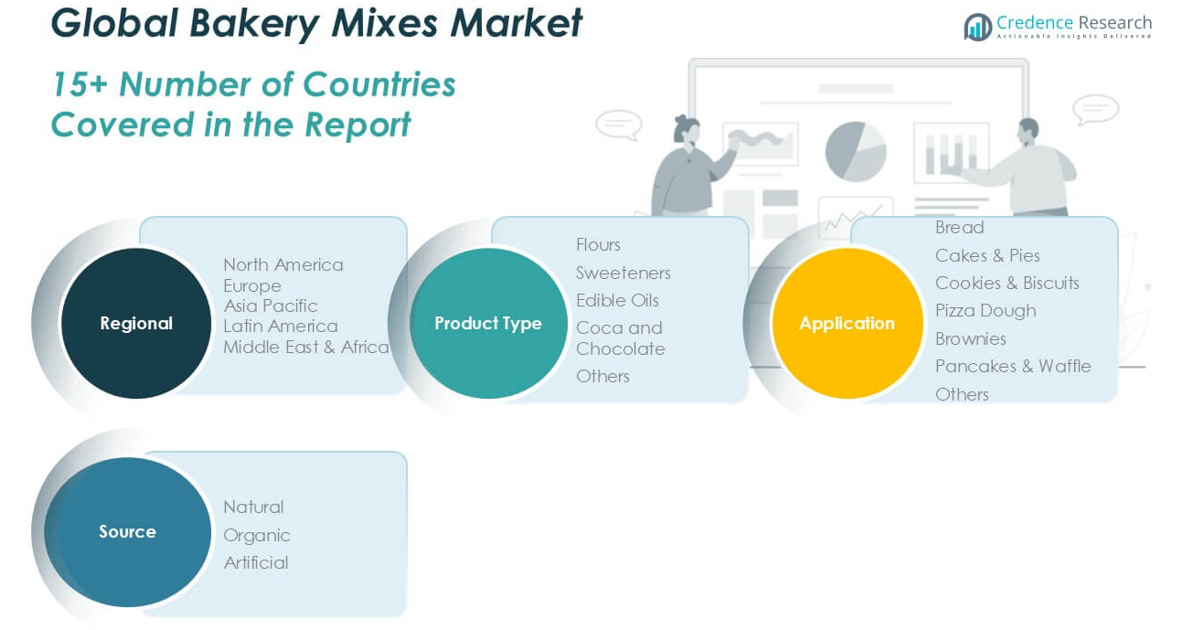
By Product Type
- Flours
- Sweeteners
- Edible Oils
- Cocoa and Chocolate
- Others
By Application
- Bread
- Cakes & Pies
- Cookies & Biscuits
- Pizza Dough
- Brownies
- Pancakes & Waffles
- Others
By Source
- Natural
- Organic
- Artificial
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The bakery mixes market is characterized by the presence of several global and regional players competing on product innovation, quality, pricing, and distribution. Major companies such as Archer Daniels Midland Company (ADM), Puratos Group, Cargill, Incorporated, and Kerry Group focus on expanding their product portfolios with clean-label, gluten-free, and functional ingredients to meet evolving consumer demands. Firms like General Mills, Nestlé, and Dawn Food Products leverage strong brand recognition and extensive retail networks to maintain market share. Strategic collaborations, mergers, and acquisitions are common as companies aim to enhance geographic reach and production capabilities. The competitive environment encourages continuous R&D investment, especially in natural and organic mixes. With rising demand for convenience baking and health-conscious offerings, competition is expected to intensify, prompting companies to differentiate through sustainability and customer engagement initiatives.
Key Player Analysis
- Archer Daniels Midland Company (ADM)
- Puratos Group
- Cargill, Incorporated
- Kerry Group
- Dawn Food Products
- General Mills, Inc.
- Nestlé
- Oy Karl Fazer Ab
- Bakels Worldwide
- Corbion
- Lesaffre
- Synova
Recent Developments
- In May 2025, At the iba 2025 trade fair, Puratos introduced three major bakery innovations, including Cubease, a highly concentrated bakery improver in cube Cubease is designed to enhance convenience, efficiency, and sustainability in baking. Each cube is precisely dosed for 10kg of flour, simplifying usage, reducing storage needs, and minimizing environmental impact.
- In May 2025, Arabian Mills launched a premium brand for both commercial and consumer use, ‘Master Mills’, as part of a strategic growth initiative. According to the brand, the new range will initially include specialty flours, bread mixes, and baking solutions designed to meet the increasing demand for convenience, quality, and consistency in the bakery and food service sectors.
- In March 2025, Birch Benders has introduced its first organic bread and muffin mixes, featuring Organic Blueberry and Organic Chocolate Chip flavors. These mixes combine real, organic ingredients with the convenience of quick preparation-just add eggs, milk, and oil to achieve bakery-quality results. According to the brand, these mixes are the first widely available organic options of their kind, catering to busy consumers who want wholesome, healthier baked goods without sacrificing taste or quality.
- In March 2025, Cargill inaugurated a new corn milling plant in Gwalior, India, with an initial output of 500 tons per day, expandable to 1,000 tons per day, to serve the food and bakery sectors.
- In June 2024, At Bakery China 2024, Angel Yeast and BakeMark launched over 40 products under the BakeMark By Angel brand, with a major focus on bakery mixes and icings that include bread mixes for bagels and sourdough, cake mixes, cookie and donut mixes, and a variety of decorative icings. According to the company, these bakery mixes and icings are designed to meet the growing demand for clean-label, nutritious, and convenient baking solutions, supporting healthier eating and catering to both professional and home bakers.
- In March 2024, King Arthur Baking Company has launched Savory Bread Mix Kits, a new line of premium mixes featuring Pull-Apart Garlic Bread, Soft & Chewy Pretzel Bites, Crisp & Airy Focaccia, and Perfectly Tender Flatbread. According to the company, each kit includes all necessary dry ingredients, yeast, mix-ins, and toppings, catering to the growing demand for easy, approachable homemade bread options and bridging a gap in the market for convenient savory baking.
Market Concentration & Characteristics
The Bakery Mixes Market demonstrates moderate to high market concentration, with a few dominant multinational players accounting for a significant share of global revenue. Companies such as ADM, Cargill, Kerry Group, and General Mills lead in terms of product innovation, global distribution, and strong brand portfolios. It features a blend of large-scale manufacturers and numerous regional firms catering to localized tastes and preferences. The market is characterized by consistent demand across both developed and emerging economies, driven by rising consumer preference for convenience, product consistency, and time efficiency. Product differentiation through clean-label, gluten-free, and organic offerings is a key competitive strategy. Consumer trends toward home baking and health-focused alternatives continue to influence product development. Distribution is broad, spanning modern trade, online retail, and foodservice channels. Despite the competitive landscape, high barriers to entry remain due to regulatory compliance, raw material sourcing, and investment in R&D, particularly for health-positioned and specialty mix formulations.
Report Coverage
The research report offers an in-depth analysis based on Product Type, Application, Source and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The bakery mixes market will continue to grow steadily, supported by increasing demand for convenience baking products.
- Rising consumer interest in home baking will drive innovation in easy-to-use and pre-measured baking solutions.
- Clean-label, organic, and gluten-free bakery mixes will see greater adoption due to growing health awareness.
- Manufacturers will expand product portfolios to include protein-rich, vegan, and allergen-free mixes to meet diverse dietary needs.
- Asia Pacific will emerge as a key growth region due to rising disposable income and westernized food preferences.
- E-commerce and direct-to-consumer channels will become more prominent for bakery mix distribution.
- Global players will invest in localized flavors and regional product customization to enhance market penetration.
- Strategic mergers, acquisitions, and partnerships will increase as companies seek to expand their global footprint.
- Automation and innovation in packaging will improve shelf life and convenience for consumers.
- Sustainability practices in sourcing and packaging will gain importance among environmentally conscious consumers.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Convenience and Time-Saving Solutions
Busy urban lifestyles and the need for quick meal preparation are driving demand for ready-to-use bakery mixes, which eliminate the need for ingredient measuring and reduce preparation time for both home bakers and commercial kitchens.
Growth of Foodservice and Bakery Chains
The expansion of foodservice outlets, cafés, and bakery chains globally is increasing the demand for bakery mixes, as these establishments prioritize consistency, efficiency, and speed in production, making pre-formulated mixes a practical solution.
Rising Popularity of Clean-Label and Health-Focused Products
Consumers are increasingly seeking bakery mixes with natural, organic, and gluten-free ingredients, prompting manufacturers to innovate and reformulate products to meet clean-label standards and cater to health-conscious dietary preferences.
Expansion in Emerging Markets
Rapid urbanization, rising disposable incomes, and exposure to Western eating habits in Asia Pacific, Latin America, and the Middle East are fueling demand for packaged bakery mixes, with global brands expanding distribution and offering localized flavors.
Innovation in Product Formulations
Manufacturers are introducing new variants such as gluten-free, vegan, high-protein, and allergen-friendly mixes, attracting consumers looking for novelty, improved nutrition, and solutions for specific dietary needs.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Bakery Mixes Market?
What are the key segments within the Bakery Mixes Market?
What are some challenges faced by the Bakery Mixes Market?
Who are the major players in the Bakery Mixes Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Source
- 1.2.1 Natural
- 1.2.2 Organic
- 1.2.3 Artificial
- 1.3 By Application
- 1.3.1 Bread
- 1.3.2 Cakes & Pies
- 1.3.3 Cookies & Biscuits
- 1.3.4 Pizza Dough
- 1.3.5 Brownies
- 1.3.6 Pancakes & Waffles
- 1.3.7 Others
- 1.4 By Product Type
- 1.4.1 Flours
- 1.4.2 Sweeteners
- 1.4.3 Edible Oils
- 1.4.4 Cocoa and Chocolate
- 1.4.5 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 6,469.09 million → 2032: USD 11,761.60 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Bakery Mixes Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Bakery Mixes Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Bakery Mixes Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Bakery Mixes Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Bakery Mixes Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Bakery Mixes Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Bakery Mixes Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Bakery Mixes Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 6,469.09 million → 2032: USD 11,761.60 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Bakery Mixes Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Source - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Natural
- 12.3.7.2 Organic
- 12.3.7.3 Artificial
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Bread
- 12.4.7.2 Cakes & Pies
- 12.4.7.3 Cookies & Biscuits
- 12.4.7.4 Pizza Dough
- 12.4.7.5 Brownies
- 12.4.7.6 Pancakes & Waffles
- 12.4.7.7 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Product Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Flours
- 12.5.7.2 Sweeteners
- 12.5.7.3 Edible Oils
- 12.5.7.4 Cocoa and Chocolate
- 12.5.7.5 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Bakery Mixes End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Bakery Mixes Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Bakery Mixes Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Bakery Mixes Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Archer Daniels Midland Company (ADM)
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Puratos Group
- 18.4 Cargill, Incorporated
- 18.5 Kerry Group
- 18.6 Dawn Food Products
- 18.7 General Mills, Inc.
- 18.8 Nestlé
- 18.9 Oy Karl Fazer Ab
- 18.10 Bakels Worldwide
- 18.11 Corbion
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

