
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Biosimilar Contract Manufacturing Market Size 2024 | USD 7,658.80 million |
| Biosimilar Contract Manufacturing Market, CAGR | 14.90% |
| Biosimilar Contract Manufacturing Market Size 2032 | USD 25,072.59 million |
Market Overview
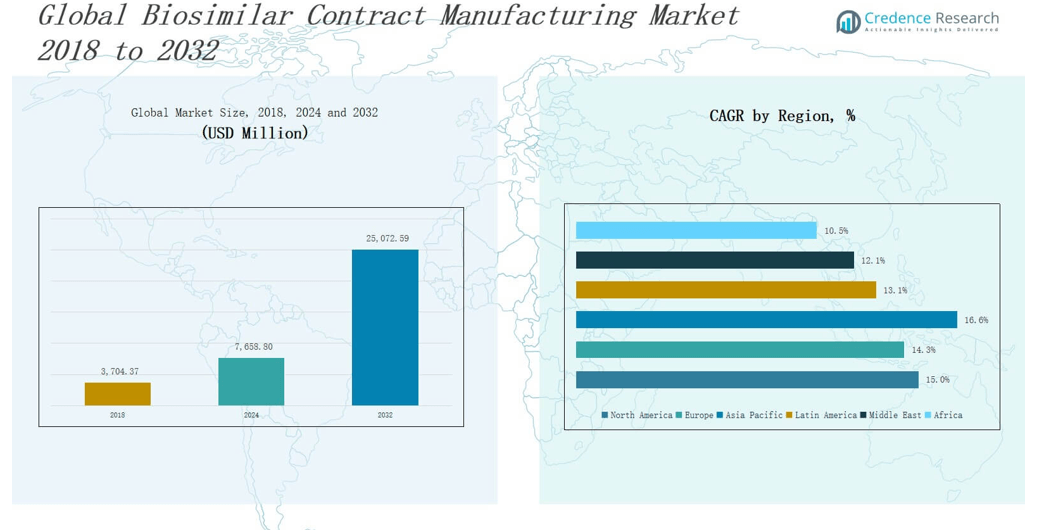
The Biosimilar Contract Manufacturing Market size was valued at USD 3,704.37 million in 2018 to USD 7,658.80 million in 2024 and is anticipated to reach USD 25,072.59 million by 2032, at a CAGR of 14.90 % during the forecast period.
The Biosimilar Contract Manufacturing Market is driven by increasing demand for cost-effective biologics, patent expirations of blockbuster biologic drugs, and the growing acceptance of biosimilars in regulated and emerging markets. Pharmaceutical companies are outsourcing manufacturing to specialized contract manufacturers to reduce operational costs, streamline production, and meet stringent regulatory requirements. Contract manufacturing organizations (CMOs) offer expertise in advanced bioprocessing technologies, scalability, and regulatory compliance, enabling faster time-to-market for biosimilar products. Market trends include rising investment in single-use bioreactors, expansion of GMP-certified facilities, and integration of automation and digital process controls to enhance manufacturing efficiency. Partnerships and strategic alliances between biopharma firms and CMOs are becoming more prevalent, aiming to optimize supply chain logistics and mitigate production risks. Additionally, the trend toward personalized medicine and complex biologics is prompting CMOs to diversify their service portfolios with modular, flexible production capabilities. The global focus on healthcare affordability continues to position biosimilars as a strategic solution, reinforcing the growth of contract manufacturing services.
The Biosimilar Contract Manufacturing Market spans key regions including North America, Europe, Asia Pacific, Latin America, the Middle East, and Africa. Europe leads the market with advanced regulatory support and established biomanufacturing infrastructure, followed by North America, which benefits from strong biosimilar uptake and innovation in biologics. Asia Pacific shows rapid growth driven by cost-efficient manufacturing hubs in China, India, and South Korea. Latin America and the Middle East are expanding through local production incentives and rising biosimilar demand, while Africa presents emerging opportunities through healthcare development and donor-funded initiatives. Key players shaping the global landscape include Samsung Biologics, Lonza, Catalent, WuXi Biologics, Boehringer Ingelheim Biopharmaceuticals GmbH, Biocon, AGC Biologics, Rentschler Biopharma SE, IQVIA Inc., Element Materials Technology, and Avid Bioservices. These companies compete through geographic reach, regulatory expertise, and integrated manufacturing solutions.
Market Insights
- The Biosimilar Contract Manufacturing Market was valued at USD 3,704.37 million in 2018 and is projected to reach USD 25,072.59 million by 2032, growing at a CAGR of 14.90%.
- Rising demand for cost-effective biologics and the expiration of major biologic patents are driving contract manufacturing across therapeutic areas.
- Advanced bioprocessing technologies, such as single-use bioreactors and automation, are enhancing production efficiency and scalability among CMOs.
- Regulatory support from agencies like the FDA and EMA is accelerating biosimilar approvals and encouraging outsourcing to specialized manufacturers.
- High regulatory complexity and limited access to originator analytics present challenges, especially for smaller CMOs and new entrants.
- Europe holds the largest market share (32%) followed by North America (28%) and Asia Pacific (20%), with Latin America, the Middle East, and Africa showing steady growth.
- Key players include Samsung Biologics, Lonza, Catalent, WuXi Biologics, Boehringer Ingelheim Biopharmaceuticals, Biocon, AGC Biologics, and others focused on global expansion and regulatory alignment.
Market Drivers
Rising Demand for Affordable Biologics
The increasing need for cost-effective treatment options is a major growth driver for the Biosimilar Contract Manufacturing Market. Biosimilars offer comparable efficacy and safety to originator biologics but at significantly lower costs, attracting healthcare providers and payers worldwide. Governments and insurance bodies actively support biosimilar adoption to manage healthcare expenditures. This shift compels pharmaceutical companies to expand production through outsourcing. Contract manufacturers provide scalable, cost-efficient solutions aligned with regulatory standards. The market benefits from rising approvals of biosimilar products, fueling manufacturing demand. It continues to gain traction in both developed and emerging economies.
- For instance, Samsung Biologics partnered with Biogen to manufacture biosimilar products, leveraging large-scale facilities to meet growing demand.
Patent Expiry of Blockbuster Biologics
A wave of patent expirations for major biologic drugs is creating substantial opportunities in the Biosimilar Contract Manufacturing Market. Blockbusters such as Humira, Enbrel, and Rituxan have either lost exclusivity or face imminent competition. This scenario opens the door for biosimilar developers seeking rapid market entry. Contract manufacturers enable faster commercialization by offering end-to-end solutions, including formulation, cell line development, and aseptic filling. It helps biopharma firms bypass significant capital investment in infrastructure. The resulting competitive landscape accelerates outsourcing contracts for high-volume, compliant production.
- For instance, Coherus Biosciences released Yusimry in July 2023, pricing it at $995 per carton-significantly lower than the originator, aiming to increase patient access through contract manufacturing efficiencies.
Regulatory Support and Streamlined Approval Pathways
Supportive regulatory environments in regions such as the U.S., EU, and Japan drive momentum in the Biosimilar Contract Manufacturing Market. Agencies including the FDA and EMA have established clear biosimilar guidelines, simplifying the approval process and reducing time-to-market. These frameworks encourage manufacturers to invest in biosimilar pipelines and outsource to expert CMOs. It supports consistent compliance with evolving GMP standards. Contract manufacturers with proven regulatory track records gain competitive advantage. The alignment of policy and industry interests strengthens global biosimilar manufacturing initiatives.
Technological Advancements in Biomanufacturing
The adoption of advanced bioprocessing technologies significantly enhances the efficiency and flexibility of the Biosimilar Contract Manufacturing Market. Single-use bioreactors, continuous manufacturing, and automation reduce contamination risks and improve yield. CMOs invest in digitalized production environments that support real-time monitoring and data integrity. It enables scalable, reproducible output critical for biosimilar quality assurance. These innovations allow faster turnaround and cost control. Technology-driven production models are becoming standard among leading biosimilar CMOs, supporting global competitiveness.
Market Trends
Expansion of Strategic Partnerships and Outsourcing Models
Biopharmaceutical companies are increasingly engaging in long-term partnerships with contract manufacturing organizations to reduce capital expenditure and mitigate production risks. These alliances range from development-stage collaborations to full-scale commercial supply agreements. The Biosimilar Contract Manufacturing Market is witnessing heightened activity in co-development and joint venture models. It strengthens supply chains and improves time-to-market. Small and mid-sized biotech firms, in particular, rely on these partnerships to access technical expertise and GMP-certified infrastructure. Outsourcing continues to evolve from transactional relationships to integrated, strategic engagements.
- For instance, Biocon Biologics entered a strategic alliance with Serum Institute of India in 2022 to leverage Serum’s manufacturing capacity for global distribution of biosimilar products.
Adoption of Single-Use and Modular Manufacturing Technologies
Single-use bioreactors and modular facilities are transforming the production landscape of the Biosimilar Contract Manufacturing Market. These technologies reduce turnaround time, minimize cross-contamination, and lower upfront investment. It allows contract manufacturers to offer flexible production capacity tailored to client needs. Modular systems support rapid scale-up and multi-product operations without long construction delays. This shift enables manufacturers to handle diverse biosimilar portfolios efficiently. CMOs with advanced, disposable-enabled setups are attracting more business from biosimilar developers.
- For instance, Thermo Fisher Scientific’s HyPerforma DynaDrive single-use bioreactors have been adopted by multiple CMOs to reduce turnaround times and minimize cleaning validation, supporting rapid changeovers between biosimilar products.
Integration of Digitalization and Automation in Production
Digital transformation is reshaping manufacturing processes in the Biosimilar Contract Manufacturing Market. CMOs are implementing automated workflows, real-time process monitoring, and AI-driven analytics to enhance productivity and maintain quality standards. It improves batch-to-batch consistency, reduces manual intervention, and ensures data integrity. These technologies support compliance with evolving regulatory requirements. Digital platforms also streamline documentation, enabling faster audits and reporting. CMOs adopting smart manufacturing systems position themselves as agile partners capable of meeting complex biosimilar production demands.
Growing Focus on Emerging Markets and Regional Hubs
Market participants are expanding biosimilar manufacturing capacity in emerging regions to serve local demand and reduce dependency on global supply chains. The Biosimilar Contract Manufacturing Market benefits from investments in Latin America, Asia-Pacific, and the Middle East, where governments promote local production. It enables faster regulatory approvals and improved market access. Regional hubs also allow CMOs to offer competitive pricing and proximity-based advantages. This trend reflects the global shift toward decentralized, region-specific biosimilar manufacturing strategies.
Market Challenges Analysis
High Regulatory Complexity and Cost of Compliance
Stringent regulatory requirements across multiple jurisdictions remain a key challenge in the Biosimilar Contract Manufacturing Market. Navigating the diverse standards of agencies such as the FDA, EMA, and PMDA demands extensive documentation, validation protocols, and continuous audits. It increases time-to-market and adds substantial compliance costs. Contract manufacturers must invest in advanced quality systems and skilled regulatory personnel to meet expectations. Delays in approvals due to changing biosimilar guidelines can disrupt manufacturing timelines. This complexity often restricts smaller CMOs from entering the market or scaling operations globally.
Limited Access to Innovator Cell Lines and Analytical Data
Biosimilar development relies heavily on reverse engineering, yet limited access to originator product cell lines and proprietary analytics creates technical barriers. The Biosimilar Contract Manufacturing Market must overcome challenges in replicating biologics’ structure, efficacy, and immunogenicity without direct reference to the innovator’s manufacturing process. It requires high-end analytical capabilities, which only a few CMOs possess at scale. Failure to match critical quality attributes can lead to regulatory rejection. These technical hurdles slow down development and raise production risks for biosimilar developers and their contract partners.
Market Opportunities
Rising Demand for Biosimilars in Emerging Economies
Expanding healthcare access and rising chronic disease prevalence are driving biosimilar demand across emerging markets. Countries in Asia-Pacific, Latin America, and the Middle East are implementing favorable regulatory frameworks and pricing policies to encourage biosimilar adoption. The Biosimilar Contract Manufacturing Market has an opportunity to support regional biopharma companies with cost-efficient, scalable manufacturing services. It can offer local production capabilities that align with regional quality and distribution requirements. CMOs with regional presence gain competitive advantage through faster response times and regulatory familiarity. These geographies represent untapped growth potential for contract manufacturing partnerships.
Increased Outsourcing from Mid-Sized Biotech Firms
Mid-sized biopharma companies are shifting toward outsourcing to focus resources on R&D and pipeline expansion. These firms often lack in-house manufacturing capacity or regulatory infrastructure, creating a strong demand for full-service CMOs. The Biosimilar Contract Manufacturing Market can meet this demand by offering flexible production models, accelerated timelines, and technical expertise. It positions CMOs as strategic enablers in bringing biosimilars to market quickly and at scale. Opportunities also arise from growing interest in differentiated biosimilars and value-added formulations. Contract manufacturers capable of supporting development and clinical trial production will capture a larger share of this expanding segment.
Market Segmentation Analysis:
By Product
The Biosimilar Contract Manufacturing Market includes recombinant non-glycosylated and recombinant glycosylated proteins. Non-glycosylated proteins such as insulin, growth hormone, and interferons hold significant share due to simpler manufacturing requirements and high demand in chronic disease treatments. Glycosylated proteins, including monoclonal antibodies and erythropoietin, require complex production processes but dominate revenue generation due to their clinical importance in oncology and autoimmune therapies. It continues to see rising outsourcing for glycosylated protein production owing to increased technical demands.
- For instance, Lonza collaborated with Celltrion in 2024 to provide large-scale production support for erythropoietin biosimilars using its mammalian cell culture platform, with batch capacity exceeding 20,000 liters.
By Production Technology
Based on production technology, the Biosimilar Contract Manufacturing Market is segmented into mammalian and non-mammalian systems. Mammalian cell culture, particularly CHO cell lines, is the preferred platform for glycosylated protein manufacturing due to its ability to perform complex post-translational modifications. It drives higher demand for mammalian-based CMO services. Non-mammalian systems, such as bacterial and yeast platforms, support cost-effective and rapid production for simpler biosimilars like insulin and growth hormone. The technology choice depends on product complexity and cost efficiency.
- For instance, Samsung Biologics manufactures biosimilar trastuzumab using CHO cells, enabling production of complex monoclonal antibodies with human-like glycosylation patterns.
By Application
Application-wise, oncology dominates the Biosimilar Contract Manufacturing Market due to widespread use of monoclonal antibodies and rising cancer prevalence. Blood disorders follow, driven by erythropoietin and related biosimilars. Growth hormonal deficiency applications maintain steady demand, supported by pediatric and adult patient needs. Chronic and autoimmune disorders show strong growth potential due to increasing biologic prescriptions. It also sees expanding opportunities in other applications, including fertility treatments and metabolic conditions, broadening the scope of contract manufacturing engagements.
Segments:
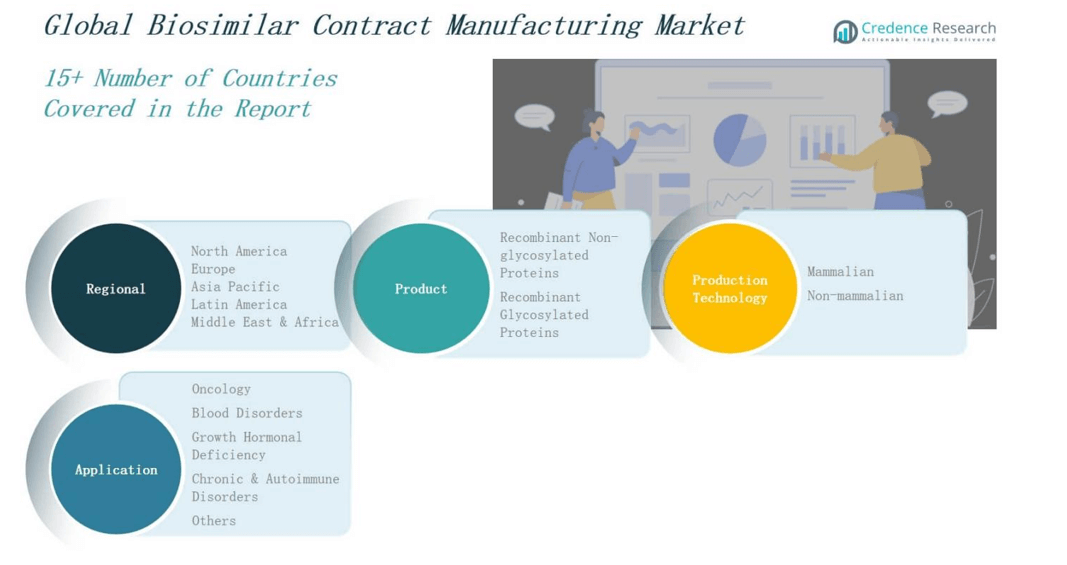
Based on Product
- Recombinant Non-glycosylated Proteins
- Recombinant Glycosylated Proteins
Based on Production Technology
- Mammalian
- Non-mammalian
Based on Application
- Oncology
- Blood Disorders
- Growth Hormonal Deficiency
- Chronic & Autoimmune Disorders
- Others
Based on Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America
The North America Biosimilar Contract Manufacturing Market size was valued at USD 1,064.41 million in 2018 to USD 2,165.95 million in 2024 and is anticipated to reach USD 7,120.74 million by 2032, at a CAGR of 15.0% during the forecast period. North America holds approximately 28% of the global market share, supported by strong biopharmaceutical infrastructure and high biosimilar adoption in the U.S. It benefits from early regulatory clarity provided by the FDA and growing pressure to reduce biologic therapy costs. Contract manufacturing organizations (CMOs) in this region are expanding capacity and investing in advanced cell-line development platforms. It supports rapid commercial-scale production of complex biosimilars. The region also sees increased outsourcing by small and mid-sized biotech firms focused on oncology and autoimmune disorders.
Europe
The Europe Biosimilar Contract Manufacturing Market size was valued at USD 1,601.16 million in 2018 to USD 3,232.06 million in 2024 and is anticipated to reach USD 10,179.64 million by 2032, at a CAGR of 14.3% during the forecast period. Europe accounts for the largest global market share at nearly 32%, driven by early biosimilar adoption and supportive regulatory policies from the European Medicines Agency (EMA). It hosts several established CMOs with GMP-certified facilities and proven experience in monoclonal antibody manufacturing. Biosimilar demand across Germany, France, and the UK continues to rise, creating sustained production contracts. The presence of strong public healthcare systems accelerates procurement of biosimilars through regional tenders. It promotes cost savings and widens access across chronic care applications.
Asia Pacific
The Asia Pacific Biosimilar Contract Manufacturing Market size was valued at USD 731.02 million in 2018 to USD 1,634.96 million in 2024 and is anticipated to reach USD 6,045.38 million by 2032, at a CAGR of 16.6% during the forecast period. Asia Pacific contributes around 20% of global revenue, driven by its rapidly expanding pharmaceutical industry and government efforts to localize biologic drug production. It benefits from lower manufacturing costs and strong clinical trial infrastructure in countries like India, China, and South Korea. Regional CMOs are investing in mammalian cell culture facilities to meet rising demand from global clients. It also attracts outsourcing due to competitive pricing and regulatory alignment with international standards. The region supports contract manufacturing growth through favorable biosimilar pricing and patient access policies.
Latin America
The Latin America Biosimilar Contract Manufacturing Market size was valued at USD 171.27 million in 2018 to USD 349.60 million in 2024 and is anticipated to reach USD 1,010.09 million by 2032, at a CAGR of 13.1% during the forecast period. Latin America holds around 5% of the global market and is gaining traction through rising biosimilar demand in Brazil, Argentina, and Colombia. Governments are adopting cost-control policies and reforming public healthcare procurement to include biosimilars. It drives regional manufacturers and international CMOs to expand operations or form local partnerships. The regulatory environment is evolving to streamline biosimilar approvals and ensure quality standards. Contract manufacturing helps regional biopharma firms overcome infrastructure limitations and scale production efficiently.
Middle East
The Middle East Biosimilar Contract Manufacturing Market size was valued at USD 93.48 million in 2018 to USD 174.83 million in 2024 and is anticipated to reach USD 472.05 million by 2032, at a CAGR of 12.1% during the forecast period. The region accounts for roughly 3% of global revenue and is seeing growing interest from multinational CMOs and investors. It benefits from healthcare modernization programs in countries like Saudi Arabia and the UAE. National health authorities are pushing for domestic biomanufacturing capacity to reduce import dependence. It creates new contract manufacturing opportunities aligned with local regulations and price controls. Biosimilars for oncology and chronic conditions represent key focus areas across hospital and retail segments.
Africa
The Africa Biosimilar Contract Manufacturing Market size was valued at USD 43.04 million in 2018 to USD 101.40 million in 2024 and is anticipated to reach USD 244.68 million by 2032, at a CAGR of 10.5% during the forecast period. Africa represents the smallest share of the global market at approximately 2%, but it holds long-term potential due to unmet medical needs and expanding healthcare infrastructure. Biosimilar adoption is rising through donor-funded programs and public-private partnerships. It enables CMOs to support cost-efficient production for high-burden diseases. Countries like South Africa and Egypt are leading early adoption and local manufacturing initiatives. It reflects the region's growing interest in building self-sufficiency in biologic medicines.
Key Player Analysis
- WuXi Biologics
- Avid Bioservices, Inc.
- Biocon
- Element Materials Technology
- Rentschler Biopharma SE
- Samsung Biologics
- AGC Biologics
- Boehringer Ingelheim Biopharmaceuticals GmbH
- IQVIA Inc.
- Catalent, Inc.
- Lonz
Competitive Analysis
The Biosimilar Contract Manufacturing Market features a competitive landscape dominated by global CDMOs with extensive biologics capabilities. Leading players such as Samsung Biologics, Lonza, WuXi Biologics, and Catalent offer end-to-end services across cell line development, process optimization, and commercial-scale production. It sees increased investments in mammalian cell culture facilities, single-use technologies, and regulatory compliance infrastructure. Mid-sized firms like AGC Biologics, Rentschler Biopharma SE, and Avid Bioservices compete by offering flexible capacity and specialized expertise in biosimilar development. Boehringer Ingelheim Biopharmaceuticals maintains a strong position through its integrated biomanufacturing platform. IQVIA supports contract manufacturing strategies with data-driven insights and clinical integration. Biocon enhances its global footprint through biosimilar production partnerships. Companies differentiate based on speed to market, cost efficiency, and ability to manage complex regulatory pathways. The market rewards firms that deliver scalable, compliant, and high-quality manufacturing services aligned with evolving client and therapeutic needs. Strategic collaborations and geographic expansion remain central to sustaining competitiveness.
Recent Developments
- In June 2025, Dr. Reddy’s Laboratories entered a strategic partnership with Alvotech to co-develop and commercialize a biosimilar of Keytruda (pembrolizumab), combining Alvotech’s development expertise with Dr. Reddy’s global reach in oncology markets.
- In 2025, Tanvex BioPharma completed the acquisition of Bora Biologics, strengthening its capabilities in biologics and biosimilar contract manufacturing.
- In October 2024, Teva Pharmaceuticals expanded its partnership with mAbxience by adding an oncology biosimilar candidate to their existing collaboration, aiming to address the growing demand for affordable cancer biologics.
- In April 2024, Alvotech signed an agreement with Teva Pharmaceuticals to manufacture a high-concentration interchangeable biosimilar of Humira (adalimumab) for Quallent Pharmaceuticals in the U.S.
Market Concentration & Characteristics
The Biosimilar Contract Manufacturing Market demonstrates moderate to high market concentration, with a few global players holding significant share due to advanced infrastructure, regulatory expertise, and global reach. Companies such as Samsung Biologics, Lonza, WuXi Biologics, and Catalent dominate based on their ability to offer end-to-end biologics services from cell line development to commercial manufacturing. It exhibits characteristics of high entry barriers, driven by capital-intensive facilities, complex regulatory requirements, and technical expertise in protein expression systems. The market favors firms with GMP-certified production sites, experience with mammalian cell cultures, and established client relationships. CMOs differentiate based on speed-to-market, capacity flexibility, and compliance with international standards. It also supports strategic partnerships, long-term contracts, and geographic diversification to mitigate risk and meet global demand. The growing trend toward outsourcing among small and mid-sized biopharma companies enhances competition among mid-tier players, while innovation and service integration shape the competitive dynamics of the market.
Report Coverage
The research report offers an in-depth analysis based on Product, Product Technology, Application and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand for biosimilar contract manufacturing will rise due to increasing approvals of biosimilars across global markets.
- Biopharma companies will continue to outsource production to reduce costs and focus on core R&D.
- Single-use technologies and modular facilities will become standard in biosimilar manufacturing.
- Regulatory frameworks will evolve to support faster biosimilar approvals and promote outsourcing.
- Asia Pacific will attract more international outsourcing contracts due to cost-efficient manufacturing capabilities.
- CMOs will invest in capacity expansion and digital infrastructure to handle complex biologics.
- Strategic alliances between CDMOs and biosimilar developers will increase to accelerate time-to-market.
- Regional production hubs will emerge to reduce dependency on centralized manufacturing and ensure supply chain resilience.
- Technical expertise in mammalian cell culture will remain critical to support high-value biosimilars.
- Competition among mid-sized CMOs will intensify as they scale capabilities to serve growing demand.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Demand for Affordable Biologics
Healthcare systems and payers are increasingly seeking cost-effective alternatives to expensive originator biologics, driving pharmaceutical companies to expand biosimilar pipelines and outsource manufacturing to specialized CMOs for scalable, compliant production.
Patent Expiry of Blockbuster Biologics
The expiration of patents for major biologic drugs such as Humira and Enbrel is creating significant opportunities for biosimilar developers, who rely on contract manufacturers to rapidly scale up production and enter the market ahead of competitors.
Regulatory Support and Streamlined Approval Pathways
Clear regulatory guidelines and accelerated approval processes from agencies like the FDA and EMA are encouraging investment in biosimilar development and outsourcing, as CMOs with proven compliance records become preferred partners.
Technological Advancements in Biomanufacturing
The adoption of single-use bioreactors, automation, and digital process controls by CMOs is enhancing production efficiency, reducing contamination risks, and enabling faster, more flexible manufacturing of complex biosimilars.
Expansion into Emerging Markets
Growing healthcare access and supportive regulatory frameworks in regions such as Asia Pacific, Latin America, and the Middle East are driving demand for local biosimilar manufacturing, prompting CMOs to establish regional hubs and partnerships.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Biosimilar Contract Manufacturing Market?
What are the key segments within the Biosimilar Contract Manufacturing Market?
What are some challenges faced by the Biosimilar Contract Manufacturing Market?
Who are the major players in the Biosimilar Contract Manufacturing Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Product
- 1.2.1 Recombinant Non-glycosylated Proteins
- 1.2.2 Recombinant Glycosylated Proteins
- 1.3 By Application
- 1.3.1 Oncology
- 1.3.2 Blood Disorders
- 1.3.3 Growth Hormonal Deficiency
- 1.3.4 Chronic & Autoimmune Disorders
- 1.3.5 Others
- 1.4 By Production Technology
- 1.4.1 Mammalian
- 1.4.2 Non-mammalian
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 7,658.80 million → 2032: USD 25,072.59 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Biosimilar Contract Manufacturing Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Biosimilar Contract Manufacturing Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Biosimilar Contract Manufacturing Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Biosimilar Contract Manufacturing Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Biosimilar Contract Manufacturing Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Biosimilar Contract Manufacturing Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Biosimilar Contract Manufacturing Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Biosimilar Contract Manufacturing Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 7,658.80 million → 2032: USD 25,072.59 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Biosimilar Contract Manufacturing Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Product - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Recombinant Non-glycosylated Proteins
- 12.3.7.2 Recombinant Glycosylated Proteins
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Oncology
- 12.4.7.2 Blood Disorders
- 12.4.7.3 Growth Hormonal Deficiency
- 12.4.7.4 Chronic & Autoimmune Disorders
- 12.4.7.5 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Production Technology - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Mammalian
- 12.5.7.2 Non-mammalian
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Biosimilar Contract Manufacturing End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Biosimilar Contract Manufacturing Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Biosimilar Contract Manufacturing Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Biosimilar Contract Manufacturing Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Samsung Biologics
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Lonza
- 18.4 Catalent
- 18.5 WuXi Biologics
- 18.6 Boehringer Ingelheim Biopharmaceuticals GmbH
- 18.7 Biocon
- 18.8 AGC Biologics
- 18.9 Rentschler Biopharma SE
- 18.10 Avid Bioservices
- 18.11 Element Materials Technology
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

