
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Aseptic Filling Market Size 2024 | USD 8,212.67 million |
| Aseptic Filling Market, CAGR | 8.92% |
| Aseptic Filling Market Size 2032 | USD 17,073.20 million |
Market Overview
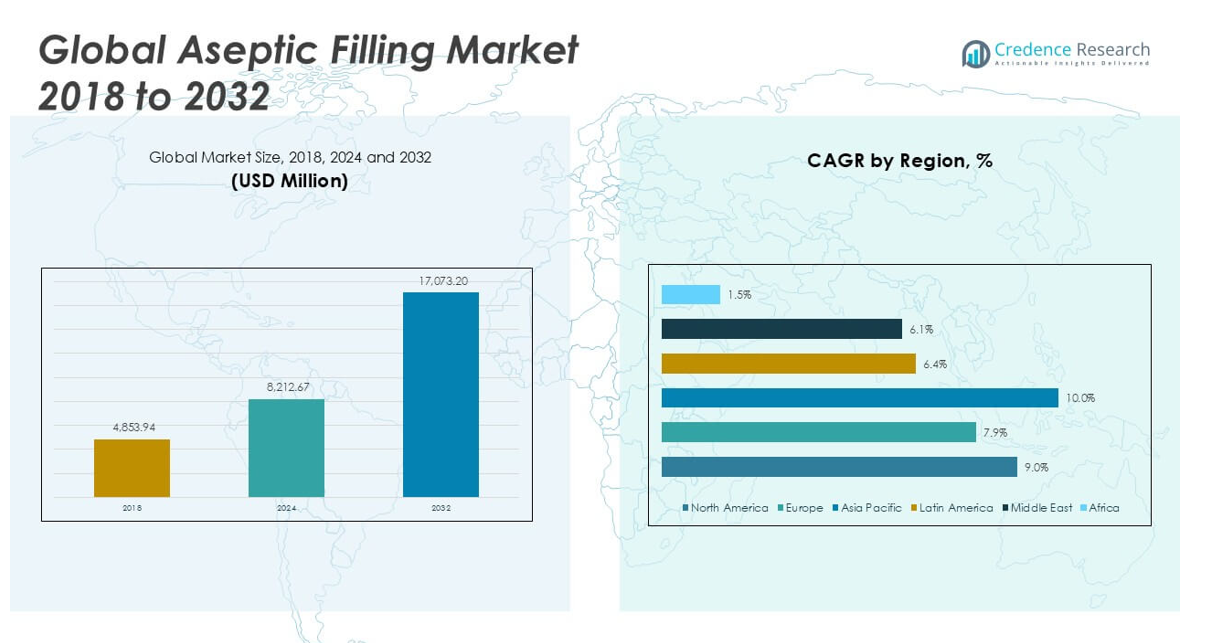
The Aseptic Filling Market is projected to grow from USD 4,853.94 million to USD 8,212.67 million, and is anticipated to reach USD 17,073.20 million, reflecting a compound annual growth rate (CAGR) of 8.92% during the forecast period.
The Aseptic Filling Market experiences robust growth driven by increasing demand for safe and extended shelf-life food and beverage products, along with expanding pharmaceutical applications requiring sterile packaging solutions. Heightened consumer awareness regarding product safety and quality, coupled with stricter regulatory standards, encourages manufacturers to adopt advanced aseptic technologies that minimize contamination risks. The rise in convenience-oriented packaging, growth of ready-to-drink beverages, and expansion of the dairy and nutraceutical sectors contribute significantly to market expansion. Technological advancements such as automation, real-time monitoring, and integration of cleanroom environments further improve operational efficiency and product integrity. Key trends include the adoption of sustainable packaging materials and the development of flexible filling lines to accommodate diverse product types. As companies focus on reducing production costs and ensuring product safety, investments in innovative aseptic filling solutions remain strong, shaping the future landscape of the market.
The Aseptic Filling Market demonstrates robust growth across key regions, with North America and Europe benefiting from advanced technological infrastructure and stringent quality standards. Asia Pacific emerges as a dynamic region, propelled by rapid industrialization, urbanization, and a rising demand for safe packaged food and pharmaceuticals. Latin America, the Middle East, and Africa show steady expansion, driven by increased investments in healthcare and food processing. Prominent industry players such as Tetra Pak, SIG Group, and Krones AG play a critical role in shaping market dynamics through innovation, strong product portfolios, and global reach. These companies focus on developing advanced aseptic filling technologies, expanding their geographical presence, and forging strategic partnerships to address evolving customer requirements. The collective efforts of these leading players drive the advancement of aseptic packaging solutions and reinforce the market’s growth trajectory worldwide.
Market Insights
- The Aseptic Filling Market is projected to grow from USD 4,853.94 million to USD 17,073.20 million, reflecting a CAGR of 8.92% during the forecast period.
- Demand for extended shelf-life, preservative-free products in food, beverage, and pharmaceutical sectors fuels market expansion.
- Rising adoption of automated filling lines and digital monitoring systems streamlines operations and reduces contamination risks.
- Key players such as Tetra Pak, SIG Group, and Krones AG focus on technology leadership and global supply capabilities to maintain a competitive edge.
- High initial investment costs, technical complexity, and stringent regulatory requirements challenge small and mid-sized manufacturers.
- Asia Pacific, North America, and Europe lead the market, with strong growth in China, the United States, and Germany, while Latin America and the Middle East see increasing investment in packaging infrastructure.
- The market trends toward sustainable packaging materials and flexible filling systems that address evolving consumer preferences and regulatory demands.
Market Drivers
Rising Demand for Extended Shelf-Life Products and Food Safety
The Aseptic Filling Market gains significant momentum from the increasing need for extended shelf-life products and heightened concerns for food safety. Consumers prioritize packaged goods that retain freshness and nutritional value without relying on preservatives. Food and beverage manufacturers focus on aseptic technology to eliminate contamination risks and reduce spoilage, ensuring product quality. The demand for ready-to-drink beverages, dairy alternatives, and minimally processed foods accelerates adoption rates across global markets. It enables companies to meet regulatory requirements and consumer expectations for safe, long-lasting products. Stricter food safety standards and growing awareness further reinforce the transition toward aseptic processes.
- For instance, the Food Safety and Standards Authority of India survey found nearly 6 out of every 10 urban households now purchase aseptically packed beverages.
Pharmaceutical Industry Expansion and Sterile Packaging Needs
Growth in the pharmaceutical sector plays a critical role in driving the Aseptic Filling Market. Drug manufacturers require sterile packaging for injectable drugs, vaccines, and biologics, prioritizing patient safety and regulatory compliance. Rising investments in biopharmaceutical research and development create a larger need for contamination-free environments. It supports a shift to aseptic filling solutions that deliver precise, reliable dosing for sensitive drug formulations. Manufacturers benefit from automated systems that improve production efficiency and minimize human error. The global expansion of healthcare infrastructure increases the requirement for advanced packaging technologies, strengthening market growth.
- For instance, the National Health Service in the UK observed a decrease from 95 to 48 contamination incidents per year after implementing aseptic packaging in hospital pharmacies.
Technological Advancements and Operational Efficiency Initiatives
Continuous advancements in filling equipment technology support operational efficiency and reliability for market participants. Integration of automation, robotics, and real-time monitoring systems enables high-speed production while maintaining stringent hygiene standards. It allows companies to minimize downtime, reduce waste, and achieve cost efficiencies throughout the manufacturing process. Equipment manufacturers invest in cleanroom-compatible designs and user-friendly interfaces, improving workforce productivity. Upgraded filling systems can handle diverse product viscosities and packaging formats, increasing flexibility for end-users. Adoption of advanced technologies positions the Aseptic Filling Market for long-term growth.
Sustainability Pressures and Shift Toward Eco-Friendly Packaging
Rising emphasis on environmental responsibility influences material choices and packaging strategies across industries. The Aseptic Filling Market responds with solutions that accommodate recyclable, lightweight, and biodegradable packaging. It aligns with consumer preferences for sustainable brands and assists manufacturers in meeting global sustainability goals. Innovative material developments and streamlined filling techniques reduce resource consumption and lower carbon footprints. Industry players focus on circular economy principles, supporting reusability and waste reduction. The transition toward eco-friendly packaging strengthens the appeal and future relevance of aseptic filling solutions.
Market Trends
Adoption of Advanced Automation and Digital Monitoring Solutions
The Aseptic Filling Market features a prominent shift toward automation and digital monitoring to increase productivity and maintain strict hygiene. Manufacturers implement automated filling lines with integrated quality control systems that ensure accuracy and reduce human error. Robotics and IoT-enabled sensors facilitate real-time data collection, allowing rapid response to operational deviations. It streamlines workflows and maximizes uptime, offering competitive advantages to early adopters. Manufacturers see value in predictive maintenance tools, which help extend equipment life and lower unplanned downtime. Advanced automation transforms the traditional filling process, driving the market toward greater efficiency and consistency.
- For instance, a beverage company in Germany reduced line downtime by 112 hours annually after adopting digital monitoring for its aseptic operations.
Flexible Packaging and Equipment Adaptation for Diverse Product Lines
Companies in the Aseptic Filling Market respond to rising product diversification by investing in flexible filling lines and adaptable machinery. Equipment capable of handling various packaging types-such as bottles, cartons, and pouches-supports rapid product launches and brand differentiation. It addresses the growing demand for convenient, single-serve, and portion-controlled packaging formats. Quick changeover features allow manufacturers to switch between products without major downtime, enhancing operational agility. The trend toward multi-format packaging helps brands cater to niche segments and evolving consumer preferences. Flexibility in equipment design positions companies to seize new market opportunities.
- For example, an Asian beverage manufacturer launched 14 new products in a single year using an aseptic line that allowed five different package shapes on the same line.
Sustainable Packaging Materials and Eco-Conscious Process Innovations
Sustainability influences major trends in the Aseptic Filling Market, with a clear focus on eco-friendly materials and process improvements. Companies explore recyclable, lightweight, and compostable packaging options that meet both environmental standards and consumer expectations. It drives innovation in barrier materials and sealing technologies to maintain product sterility while reducing environmental impact. Sustainable solutions gain traction in both food and pharmaceutical segments. Brands that prioritize green initiatives strengthen their competitive positions and appeal to environmentally conscious consumers. Regulatory developments also encourage continuous investment in eco-conscious packaging processes.
Expansion into Emerging Markets and Customization of Filling Solutions
Geographic expansion plays a key role in shaping trends across the Aseptic Filling Market, with companies targeting high-growth regions in Asia Pacific, Latin America, and Africa. Localized production facilities allow faster response to regional demand and regulatory changes. It enables companies to offer customized filling solutions tailored to local preferences and infrastructure requirements. The trend toward regionalization supports improved supply chain resilience and cost efficiency. Businesses that prioritize adaptability and innovation gain a strategic edge in capturing market share across emerging economies. Customization and regional focus continue to influence product development and market strategies
Market Challenges Analysis
High Initial Investment Costs and Technical Complexity
The Aseptic Filling Market faces significant challenges due to the high initial investment required for advanced equipment and facility upgrades. Capital expenditure on aseptic filling lines, cleanroom environments, and supporting infrastructure creates barriers for small and mid-sized companies. It demands substantial technical expertise for installation, validation, and ongoing maintenance of equipment. Complex integration with existing production systems increases operational risk and requires skilled personnel to manage transitions effectively. Companies may hesitate to invest without clear long-term demand projections or regulatory clarity. The combination of financial and technical hurdles often slows market entry and expansion.
Stringent Regulatory Compliance and Supply Chain Vulnerabilities
Strict regulatory requirements impose further challenges on the Aseptic Filling Market, demanding rigorous validation, documentation, and quality control. Manufacturers must keep up with evolving global standards while ensuring product sterility and safety throughout the supply chain. It heightens the risk of production delays, recalls, and non-compliance penalties. Fluctuations in raw material availability and logistical disruptions can compromise operational continuity, especially in regions with limited infrastructure. The need for regular audits and robust traceability systems adds complexity and cost to manufacturing processes. Maintaining compliance and reliable supply chains remains a persistent challenge for industry participants.
Market Opportunities
Growth Potential in Emerging Markets and Untapped Sectors
Emerging markets create substantial opportunities for the Aseptic Filling Market, driven by rising demand for safe packaged foods, beverages, and pharmaceuticals. Rapid urbanization and expanding middle-class populations increase consumption of ready-to-consume products. It enables manufacturers to capture new customers and build brand presence in high-growth regions. Local governments often invest in food safety initiatives and healthcare infrastructure, further supporting market expansion. Companies entering these markets benefit from lower production costs and access to untapped consumer segments. Geographic diversification remains a key strategy for securing long-term growth.
Innovation in Sustainable Packaging and Advanced Technologies
Opportunities arise from the industry’s focus on sustainability and next-generation filling solutions. The Aseptic Filling Market can capitalize on the shift toward recyclable, biodegradable, and lightweight packaging materials. It supports the development of advanced aseptic equipment that lowers energy consumption and optimizes resource use. Automation, real-time monitoring, and data-driven quality control offer new efficiencies and product safety standards. Brands that lead in eco-friendly practices and adopt innovative technologies stand to attract environmentally conscious consumers. These advancements create pathways for differentiation and competitive advantage across the global market.
Market Segmentation Analysis:
By Product Type:
Vials secure a prominent share due to their widespread use in pharmaceutical and biotechnology sectors. Their compatibility with sensitive liquid formulations and ease of transport make them the preferred choice for vaccines, injectable drugs, and diagnostic reagents. Bottles occupy a significant segment, driven by robust demand in both pharmaceuticals and food and beverage industries. Their ability to accommodate larger volumes and various viscosities broadens their appeal for juices, dairy products, and oral solutions. Syringes hold a crucial position for precise dosage delivery, supporting market demand for pre-filled formats in healthcare settings. The "others" segment, covering ampoules and cartridges, finds use in specialized or niche applications where standard packaging options do not suffice.
- For instance, a European drug manufacturer fills over 2 million vials aseptically each month to meet export demands.
By Filling Type:
The Aseptic Filling Market distinguishes itself with a strong tilt toward fully-automatic aseptic filling systems. Automated systems streamline production, enhance sterility, and reduce manual intervention, providing higher throughput and improved operational consistency. It appeals to large-scale manufacturers seeking efficiency and compliance with regulatory standards. Semi-automatic aseptic filling systems serve small to mid-sized enterprises that prioritize flexibility and lower capital investment. These systems offer manual control over certain operations, making them suitable for pilot projects or limited production runs. Both system types ensure product integrity and minimize contamination risks, but the choice depends on production scale, budget, and operational objectives.
- For instance, a South Korean food processing plant added 4 fully automatic lines in one facility, raising its daily production capacity by 320,000 units.
By Application:
Pharmaceuticals dominate with strong requirements for sterile packaging to ensure drug safety and efficacy. The segment leverages advanced filling solutions to meet rigorous quality and regulatory demands. Food and beverages follow closely, with manufacturers turning to aseptic filling for products that require extended shelf life without preservatives, such as milk, juices, and plant-based drinks. The cosmetics segment uses aseptic technology to preserve sensitive formulations, such as serums and creams, preventing microbial growth and extending product usability. The "others" category includes applications in chemicals and laboratory reagents where contamination-free packaging is essential. Each segment reflects the market’s adaptability and its critical role in supporting multiple industries with safe, high-quality packaging solutions.
Segments:
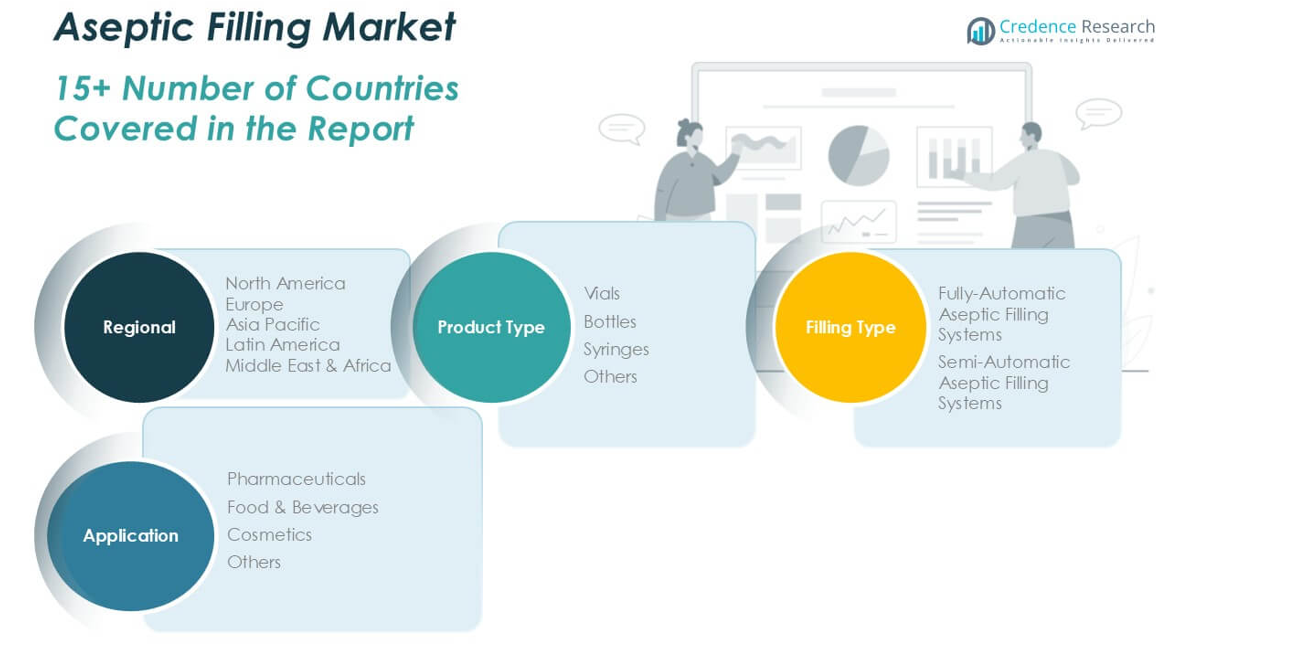
Based on Product Type:
- Vials
- Bottles
- Syringes
- Others
Based on Filling Type:
- Fully-Automatic Aseptic Filling Systems
- Semi-Automatic Aseptic Filling Systems
Based on Application:
- Pharmaceuticals
- Food & Beverages
- Cosmetics
- Others
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis
North America Aseptic Filling Market
North America Aseptic Filling Market grew from USD 1,870.42 million in 2018 to USD 3,127.43 million in 2024 and is projected to reach USD 6,522.05 million by 2032, reflecting a compound annual growth rate (CAGR) of 9.0%. North America is holding a 38% market share. The United States remains the largest contributor, supported by advanced healthcare infrastructure, regulatory compliance, and strong investments in food safety. Canada and Mexico are experiencing growth as pharmaceutical and food manufacturers upgrade production lines to meet rising demand for sterile packaging. The region benefits from technological leadership and early adoption of fully-automatic filling systems. Strategic partnerships with global packaging suppliers further support innovation and market expansion.
Europe Aseptic Filling Market
Europe Aseptic Filling Market grew from USD 1,152.57 million in 2018 to USD 1,866.11 million in 2024 and is projected to reach USD 3,606.25 million by 2032, with a CAGR of 7.9%. Europe is holding a 21% market share. Germany, France, and the United Kingdom lead growth, driven by stringent safety regulations and a focus on sustainability. Italy and Spain present strong adoption in the pharmaceutical and dairy sectors. European companies invest in eco-friendly packaging materials and energy-efficient technologies, aligning with the region’s environmental priorities. It secures its position as a hub for innovation and quality in aseptic solutions.
Asia Pacific Aseptic Filling Market
Asia Pacific Aseptic Filling Market grew from USD 1,527.05 million in 2018 to USD 2,716.22 million in 2024 and is projected to reach USD 6,118.61 million by 2032, showing a CAGR of 10.0%. Asia Pacific is holding a 36% market share. China, Japan, and India drive regional expansion, supported by rapid urbanization, a growing middle class, and a surge in packaged food and pharmaceutical products. Australia and South Korea add to market momentum with investments in automation and export-oriented manufacturing. It benefits from local government support and infrastructure improvements, enabling strong growth prospects.
Latin America Aseptic Filling Market
Latin America Aseptic Filling Market grew from USD 157.51 million in 2018 to USD 261.68 million in 2024 and is projected to reach USD 452.49 million by 2032, achieving a CAGR of 6.4%. Latin America is holding a 3% market share. Brazil and Mexico dominate demand, supported by rising investments in healthcare and food processing sectors. Argentina and Colombia witness moderate growth, benefiting from regional trade agreements and increased focus on export-quality packaging. It faces challenges in technology adoption and supply chain efficiency, but continued investment enhances the long-term outlook.
Middle East Aseptic Filling Market
Middle East Aseptic Filling Market grew from USD 114.36 million in 2018 to USD 173.73 million in 2024 and is projected to reach USD 292.87 million by 2032, recording a CAGR of 6.1%. The Middle East is holding a 2% market share. Saudi Arabia and the United Arab Emirates lead the market, driven by government-led healthcare initiatives and investment in modern food manufacturing facilities. It focuses on upgrading packaging standards and securing supply chain reliability. Regional collaboration with European technology providers supports advancements in filling solutions and quality control.
Africa Aseptic Filling Market
Africa Aseptic Filling Market grew from USD 32.04 million in 2018 to USD 67.52 million in 2024 and is projected to reach USD 80.94 million by 2032, showing a CAGR of 1.5%. Africa is holding a 1% market share. South Africa remains the primary market, while Egypt and Nigeria present emerging opportunities due to urban population growth and increased demand for packaged consumer goods. It faces constraints in infrastructure, investment, and regulatory compliance, limiting rapid market expansion. Targeted initiatives and international partnerships may help address gaps and unlock future growth potential.
Key Player Analysis
- Tetra Pak
- SIG Group
- Greatview Aseptic Packaging
- Krones AG
- GEA Group
- SPX FLOW
- Bucher Emhart Glass
- IMA Group
- OPTIMA Packaging Group
- Coesia Group
Competitive Analysis
The Aseptic Filling Market features a competitive landscape shaped by leading players including Tetra Pak, SIG Group, Greatview Aseptic Packaging, Krones AG, GEA Group, SPX FLOW, Bucher Emhart Glass, IMA Group, OPTIMA Packaging Group, and Coesia Group. These companies dominate the market by offering advanced aseptic filling solutions tailored to the evolving needs of the food, beverage, and pharmaceutical sectors. Companies invest in research and development to launch innovative equipment that supports high-speed, flexible, and contamination-free packaging operations for the food, beverage, and pharmaceutical industries. Strategic priorities include expanding geographic reach, forming alliances, and enhancing after-sales services to strengthen customer relationships. The market’s competitive edge is sharpened by a strong focus on automation, digital monitoring, and integration of sustainable practices into both equipment design and operational processes. Firms differentiate themselves by adapting to regional regulatory standards and responding quickly to shifting consumer demands. The competitive environment encourages ongoing technological progress and efficiency improvements, creating value for customers and reinforcing market growth. Continuous investment in sustainability, production capacity, and technical expertise ensures that leading companies remain well positioned to capture emerging opportunities and address industry challenges.
Recent Developments
- In May 2024, Argonaut Manufacturing Services secured USD 45 million in financing to support its new drug product fill / finish expansion in California, US. The expansion included a new dedicated facility with an advanced isolator-based filling line that will quadruple the current drug product fill / finish capacity of the company. Further, the expansion was expected to augment company’s vial filling capabilities for pre-filled syringes and cartridges for clinical and commercial supply.
- In May 2024, PCI Pharma Services began installation of a large-scale isolator filling line at its commercial sterile fill-finish facility. The integrated filler is capable of manufacturing batch sizes of up to 300,000 vials at a rate of up to 400 vials per minute, providing large-scale capacity for the filling of late phase clinical and commercial small molecules and biologics, including mAbs, oligonucleotides, fusion proteins and peptides.
Market Concentration & Characteristics
The Aseptic Filling Market exhibits a moderate to high level of market concentration, with a few established multinational firms holding significant shares and setting industry standards. It features high entry barriers due to the capital-intensive nature of aseptic technology, technical complexity, and strict regulatory requirements. Leading companies maintain strong global footprints, robust distribution networks, and dedicated research and development teams, ensuring continuous product innovation and technological leadership. The market is characterized by an emphasis on operational efficiency, advanced automation, and stringent hygiene standards, serving critical sectors such as pharmaceuticals, food, and beverages. It responds swiftly to evolving consumer preferences for safer, preservative-free, and sustainable packaging solutions, supporting product diversification across multiple end-use industries. High-value contracts, long-term partnerships, and comprehensive after-sales services play crucial roles in shaping competition and customer loyalty. The combination of technological expertise and rigorous quality control defines the market’s reputation for reliability and product integrity
Report Coverage
The research report offers an in-depth analysis based on Product Type, Filling Type, Application and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand for ready-to-drink beverages and dairy alternatives is expected to rise, further supporting aseptic filling adoption.
- Companies will prioritize product differentiation by developing customized, flexible filling lines for diverse packaging formats.
- Regulations related to food safety and drug packaging will become stricter, increasing the need for compliance-driven aseptic solutions.
- Market players will explore untapped opportunities in emerging regions with expanding middle-class populations and urbanization.
- New eco-friendly materials and lightweight packaging options will become mainstream to align with sustainability targets.
- Strategic acquisitions and partnerships will accelerate technology transfer and global market penetration.
- Digitalization will enable real-time process monitoring and predictive maintenance, reducing downtime and operational costs.
- Customer demand for transparency will drive the adoption of traceability and robust quality control across the supply chain.
- High-value contracts with multinational food, beverage, and pharmaceutical companies will drive long-term business stability.
- Focus on circular economy principles and closed-loop recycling systems will shape future innovation in aseptic packaging solutions.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Demand for Extended Shelf-Life and Food Safety
Consumers and manufacturers increasingly seek packaging solutions that ensure product freshness and safety without preservatives, driving adoption of aseptic filling technologies that minimize contamination and spoilage.
Pharmaceutical Industry Expansion and Sterile Packaging Needs
Growth in biopharmaceuticals, vaccines, and injectable drugs requires highly sterile packaging, making aseptic filling essential for compliance and patient safety, thus fueling market growth.
Technological Advancements in Automation and Monitoring
Integration of automation, robotics, and real-time digital monitoring in aseptic filling lines enhances operational efficiency, reduces human error, and supports high-speed, contamination-free production.
Sustainability and Eco-Friendly Packaging Initiatives
Rising environmental concerns and regulatory pressures are pushing manufacturers to adopt recyclable, lightweight, and biodegradable packaging materials, increasing demand for advanced aseptic filling solutions compatible with sustainable formats.
Emerging Market Growth and Urbanization
Rapid urbanization and expanding middle-class populations in Asia Pacific, Latin America, and Africa are boosting consumption of packaged foods, beverages, and pharmaceuticals, creating new opportunities for aseptic filling technologies.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Aseptic Filling Market?
What factors are driving the growth of the Aseptic Filling Market?
What are some challenges faced by the Aseptic Filling Market?
Who are the major players in the Aseptic Filling Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Application
- 1.2.1 Pharmaceuticals
- 1.2.2 Food & Beverages
- 1.2.3 Cosmetics
- 1.2.4 Others
- 1.3 By Filling Type
- 1.3.1 Fully-Automatic Aseptic Filling Systems
- 1.3.2 Semi-Automatic Aseptic Filling Systems
- 1.4 By Product Type
- 1.4.1 Vials
- 1.4.2 Bottles
- 1.4.3 Syringes
- 1.4.4 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 Base year: USD 8,212.67 million → Forecast year: USD 17,073.20 million
- 2.6 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size
- 3.3 Forecast Market Size
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Aseptic Filling Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Aseptic Filling Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Aseptic Filling Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Aseptic Filling Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Aseptic Filling Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Aseptic Filling Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Aseptic Filling Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Aseptic Filling Market Outlook
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: Base year: USD 8,212.67 million → Forecast year: USD 17,073.20 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size
- 11.2 Market Forecast
- 11.2.1 Revenue Forecast
- 11.2.2 Volume Forecast
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Aseptic Filling Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Application - Market Size and Forecast
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast
- 12.3.4 Volume Forecast
- 12.3.5 Base-Year Market Share
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Pharmaceuticals
- 12.3.7.2 Food & Beverages
- 12.3.7.3 Cosmetics
- 12.3.7.4 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Filling Type - Market Size and Forecast
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast
- 12.4.4 Volume Forecast
- 12.4.5 Base-Year Market Share
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Fully-Automatic Aseptic Filling Systems
- 12.4.7.2 Semi-Automatic Aseptic Filling Systems
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Product Type - Market Size and Forecast
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast
- 12.5.4 Volume Forecast
- 12.5.5 Base-Year Market Share
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Vials
- 12.5.7.2 Bottles
- 12.5.7.3 Syringes
- 12.5.7.4 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Aseptic Filling End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Aseptic Filling Geographic Market Outlook
- 14.1 Regional Market Size and Share
- 14.2 Regional Market Forecast
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Aseptic Filling Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Aseptic Filling Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Tetra Pak
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 SIG Group
- 18.4 Greatview Aseptic Packaging
- 18.5 Krones AG
- 18.6 GEA Group
- 18.7 SPX FLOW
- 18.8 Bucher Emhart Glass
- 18.9 IMA Group
- 18.10 OPTIMA Packaging Group
- 18.11 Coesia Group
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

