
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Oncology Biosimilars Market Size 2024 | USD 4725 million |
| Oncology Biosimilars Market, CAGR | 22.1% |
| Oncology Biosimilars Market Size 2032 | USD 23341.41 million |
Market Overview:
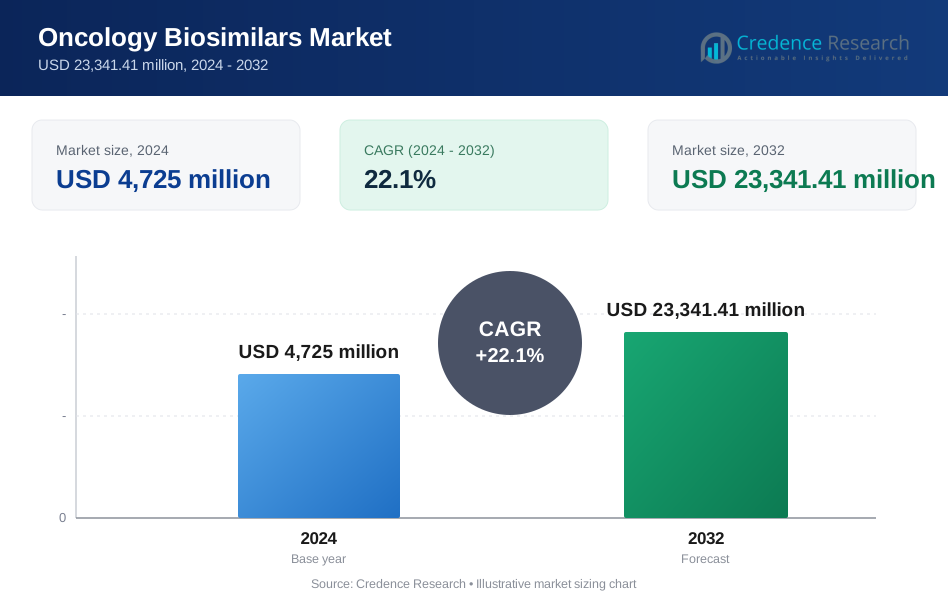
The Oncology Biosimilars Market is projected to grow from USD 4725 million in 2024 to an estimated USD 23341.41 million by 2032, with a compound annual growth rate (CAGR) of 22.1% from 2024 to 2032.
Key drivers fueling growth in the oncology biosimilars market include the rising incidence of cancer worldwide, which has created an urgent need for accessible and affordable treatment options. Governments and healthcare systems are increasingly focusing on reducing the financial burden of cancer care by promoting biosimilars, which offer comparable efficacy and safety profiles to original biologics but at a fraction of the cost. Additionally, advancements in manufacturing processes have enhanced the quality and production efficiency of biosimilars, encouraging market expansion. Growing R&D investment by pharmaceutical companies and favorable regulatory environments further support this trend, as biosimilars undergo rigorous approval processes to ensure safety and effectiveness, boosting acceptance among healthcare providers and patients.
Regionally, North America, Europe, and Asia-Pacific are the dominant players in the oncology biosimilars market. North America leads due to high healthcare expenditure, advanced infrastructure, and the presence of key biosimilar manufacturers. Europe, particularly countries like Germany and the UK, has seen significant growth as a result of supportive regulatory policies and high demand for cost-effective cancer therapies. The Asia-Pacific region, with its large patient population and rapidly improving healthcare infrastructure, is witnessing the fastest growth, particularly in emerging economies such as China and India. Favorable government policies and an increasing number of biosimilar approvals in these regions suggest continued growth potential in the coming years.
Market Drivers:
Rising Cancer Incidence and Demand for Cost-effective Therapies:
The global increase in cancer incidence has significantly contributed to the demand for oncology biosimilars. As cancer rates rise, so does the need for effective treatment options, placing a growing strain on healthcare systems worldwide. For instance, in 2024, an estimated 2,001,140 new cancer cases and 611,720 cancer deaths are projected to occur in the United States. Biosimilars provide a viable, cost-effective alternative to branded biologics, offering comparable efficacy and safety at a reduced price. This affordability appeals to both healthcare providers and patients, particularly in countries with budget constraints. The high cost of biologic cancer treatments often poses a barrier to access, and biosimilars help alleviate this burden, making cancer care more accessible to a broader population.
Expiring Patents of Major Biologics:
The oncology biosimilars market is also driven by the expiration of patents on numerous blockbuster biologic drugs. With these patents expiring, the market faces fewer barriers to entry, allowing biosimilar manufacturers to bring alternative treatments to market. As a result, competition increases, leading to further price reductions and expanded access to treatment. Pharmaceutical companies are capitalizing on this opportunity by accelerating the development of biosimilars for cancer therapies, targeting biosimilars for drugs like trastuzumab, bevacizumab, and rituximab, which are widely used in oncology. These biosimilar versions provide comparable clinical outcomes, encouraging both physicians and patients to adopt them as trusted alternatives.
Government Initiatives and Supportive Regulatory Frameworks:
Governments worldwide have recognized the value of biosimilars in controlling healthcare costs and enhancing patient access, resulting in increased regulatory support. For example, regulatory agencies such as the U.S. Food and Drug Administration (FDA) and the European Medicines Agency (EMA) have established clear pathways for the approval of biosimilars, ensuring rigorous evaluation standards for safety and efficacy. This regulatory support has encouraged pharmaceutical companies to invest in biosimilar development, knowing that there are established guidelines and pathways to market entry. Additionally, government policies in several regions promote biosimilar adoption, such as incentivizing healthcare providers and offering reimbursement options, which further drives market growth.
Advancements in Biotechnology and Enhanced Manufacturing Processes:
Advances in biotechnology and manufacturing processes have played a critical role in the development of oncology biosimilars, enhancing both their quality and accessibility. Improved cell line development, bioanalytical methods, and purification techniques have enabled manufacturers to produce biosimilars that closely resemble the reference biologics in terms of safety, efficacy, and quality. These technological improvements have also optimized production, reducing the cost per unit and allowing manufacturers to supply biosimilars at competitive prices. As biotechnological innovation continues, manufacturers are likely to see even greater efficiencies, reinforcing biosimilars as a sustainable, cost-effective option for oncology treatment in global markets.
Market Trends:
Increasing Acceptance and Utilization of Biosimilars in Oncology:
The oncology biosimilars market is witnessing an upward trend in acceptance and utilization among healthcare providers and patients. As more biosimilars receive regulatory approval and demonstrate comparable clinical efficacy and safety to original biologics, confidence in these treatments is growing. Oncologists and healthcare systems are increasingly recommending biosimilars as effective alternatives to high-cost branded biologics, especially for patients with limited financial resources. This rising acceptance is contributing to a broader shift in cancer care, where biosimilars are becoming integral to treatment regimens, providing viable options for prolonged or combination therapies at a reduced cost.
Expansion of Biosimilar Portfolios by Leading Pharmaceutical Companies:
Leading pharmaceutical companies are expanding their biosimilar portfolios to capture a greater share of the oncology market. Recognizing the market’s growth potential, many companies have accelerated R&D efforts to bring biosimilars for blockbuster oncology drugs to market. This trend includes investments in biosimilars for widely used cancer treatments like trastuzumab, rituximab, and bevacizumab, aiming to replicate their success in the biologics market. Additionally, collaborations and partnerships among pharmaceutical companies have increased, allowing firms to combine resources and expertise in biosimilar development. These alliances are not only facilitating faster biosimilar production but also driving competition, which can further reduce treatment costs and improve access to oncology care globally.
Rising Investments in Emerging Markets:
The oncology biosimilars market is also seeing a marked increase in investments across emerging markets. Countries in the Asia-Pacific, Latin America, and the Middle East regions are experiencing rising cancer incidence, and demand for affordable treatment options is at an all-time high. Recognizing this need, pharmaceutical companies are investing in these regions, establishing local manufacturing facilities, and forming partnerships with regional healthcare providers. This trend is particularly strong in Asia-Pacific countries such as China and India, where biosimilar adoption is surging due to favorable government policies, improving healthcare infrastructure, and a large, treatment-seeking patient population. For instance, Samsung Bioepis has established strategic partnerships in Brazil to expand its biosimilar reach in the market. Emerging markets are thus poised to be key growth drivers for the global oncology biosimilars market in the coming years.
Focus on Innovation and Differentiation in Biosimilar Development:
Innovation and differentiation in biosimilar development are becoming crucial trends in the oncology biosimilars market. While biosimilars are essentially replicas of original biologics, manufacturers are exploring ways to differentiate their products through improved formulations, delivery mechanisms, and patient support programs. Some companies are developing biosimilars with enhanced stability or longer shelf lives, aiming to make them more convenient and accessible, especially in regions with limited healthcare infrastructure. Additionally, many biosimilar developers are focusing on creating comprehensive patient assistance programs to support adherence and education, enhancing the overall patient experience. For instance, Sandoz, currently a division of Novartis, has eight marketed biosimilars and is expanding its pipeline from 15+ to 24 assets in various stages of development. This emphasis on innovation and patient-centered strategies is positioning biosimilars as not only cost-effective but also high-quality alternatives in oncology care, thereby solidifying their role in the market.
Market Restraints and Challenges:
High Development and Manufacturing Costs:
One of the primary challenges in the oncology biosimilars market is the high cost associated with the development and manufacturing of biosimilars. Unlike generic drugs, biosimilars are complex to produce, requiring sophisticated technology, stringent regulatory processes, and significant investment in R&D. These complexities result in higher production costs, which can be a barrier for smaller companies and limit competition. The need to maintain rigorous standards for similarity to the reference biologic in terms of safety, efficacy, and quality further escalates costs, affecting pricing flexibility and profitability for biosimilar developers.
Regulatory and Approval Challenges:
Navigating the regulatory landscape for oncology biosimilars presents a significant restraint, as approval requirements vary widely across regions. Regulatory agencies like the FDA and EMA have established frameworks for biosimilar approvals, but differing standards between countries create complications for manufacturers seeking global market entry. Additionally, regulatory processes for biosimilars often demand extensive clinical trials and post-marketing surveillance to ensure safety and efficacy, resulting in prolonged timelines and higher costs. These regulatory hurdles can delay market entry, impacting the overall competitiveness of biosimilars in oncology.
Limited Awareness and Acceptance among Healthcare Providers and Patients:
Despite rising interest, limited awareness and acceptance of biosimilars among healthcare providers and patients remain key restraints in the oncology market. Some oncologists and patients may have reservations about switching from established biologics to biosimilars, particularly in cases where patient outcomes are perceived as uncertain. Concerns about efficacy, safety, and interchangeability contribute to slow adoption rates, as do doubts regarding biosimilars’ long-term benefits in cancer care. Education initiatives are underway to build confidence, but acceptance remains an ongoing challenge that could impact market growth.
Intense Competition from Branded Biologics and New Innovator Drugs:
Intense competition from branded biologics and emerging innovator drugs also poses a challenge for the oncology biosimilars market. Many branded biologic manufacturers implement aggressive pricing strategies, patent extensions, and loyalty programs to retain market share. Additionally, the introduction of new biologics with advanced formulations or novel mechanisms of action can shift market attention away from biosimilars, making it difficult for these alternatives to gain a foothold. This competition, combined with brand loyalty to original biologics, can limit the growth potential of oncology biosimilars.
Market Segmentation Analysis:
The oncology biosimilars market is segmented into three primary categories: By Drug, By Disease Indication, and By Distribution Channel.
By Drug, the market is categorized into granulocyte-colony stimulating factors (G-CSF), monoclonal antibodies, and hematopoietic agents. Monoclonal antibodies hold a significant share due to their efficacy in targeting specific cancer cells, making them essential in oncology treatment. G-CSF biosimilars, used to stimulate white blood cell production, are widely adopted in oncology care, especially to manage chemotherapy-induced neutropenia.
By Disease Indication, the oncology biosimilars market includes breast cancer, non-small cell lung cancer, colorectal cancer, neutropenia, and various blood cancers such as leukemia (including myeloid leukemia, chronic lymphocytic leukemia, and non-Hodgkin lymphoma). The breast cancer and neutropenia segments are among the largest, driven by the high prevalence of these conditions and the demand for cost-effective treatment options. Non-small cell lung cancer and colorectal cancer biosimilars also see considerable growth, fueled by increased adoption in developed markets.
By Distribution Channel, the market is segmented into hospital pharmacies, retail pharmacies, and online pharmacies. Hospital pharmacies dominate due to the critical role hospitals play in cancer treatment administration, particularly for complex therapies like biosimilars. Retail pharmacies follow, while online pharmacies are gaining traction due to the convenience of delivery, particularly for maintenance medications in ongoing cancer care.
Segmentation:
By Drug
- G-CSF
- Monoclonal Antibody
- Hematopoietic Agents
By Disease Indication
- Breast Cancer
- Non-Small Cell Lung Cancer
- Colorectal Cancer
- Neutropenia
- Blood Cancer
- Leukemia
- Myeloid Leukemia
- Chronic Lymphocytic Leukemia (CLL)
- Non-Hodgkin Lymphoma
- Others
By Distribution Channel
- Hospital Pharmacy
- Retail Pharmacy
- Online Pharmacy
By Regional
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
North America holds a significant share of the oncology biosimilars market, driven by a combination of high cancer prevalence, advanced healthcare infrastructure, and favorable regulatory frameworks. The United States, in particular, has embraced biosimilars due to the U.S. Food and Drug Administration’s (FDA) clear guidelines and pathways for biosimilar approval. With increasing support from policymakers to control rising healthcare costs, North America accounts for around 35% of the global oncology biosimilars market. Hospitals and healthcare providers in the region are adopting biosimilars to reduce expenditures on cancer treatment, making the market highly lucrative for biosimilar developers. The presence of major biosimilar manufacturers in the region also accelerates adoption and market expansion.
Europe
Europe is one of the leading regions in the oncology biosimilars market, accounting for approximately 30% of the global share. The European Medicines Agency (EMA) has established robust regulatory processes for biosimilar approvals, which have encouraged biosimilar adoption throughout the region. Countries like Germany, the UK, and France have implemented policies favoring biosimilar use, leading to increased availability of oncology biosimilars in the healthcare system. Price reductions due to biosimilars have further driven adoption as healthcare providers seek cost-effective alternatives to biologic drugs. Additionally, Europe’s supportive reimbursement policies make biosimilars an appealing choice in oncology treatment, positioning the region as a critical market for ongoing biosimilar growth.
Asia-Pacific
The Asia-Pacific region is experiencing the fastest growth in the oncology biosimilars market, accounting for around 25% of the global share. Rapid urbanization, a high prevalence of cancer, and increasing healthcare expenditures have spurred biosimilar adoption in countries like China, India, and South Korea. Government initiatives to make cancer care more affordable have also contributed to the rising demand for biosimilars in the region. Additionally, pharmaceutical companies are investing heavily in local manufacturing facilities and forming partnerships with regional healthcare providers to meet the growing need. Favorable government policies and rising healthcare awareness are expected to further drive the market in Asia-Pacific, making it a key area for future growth in oncology biosimilars.
Latin America and the Middle East & Africa
Latin America and the Middle East & Africa (MEA) collectively hold a smaller share of the oncology biosimilars market, contributing approximately 10% of the global market share. In Latin America, Brazil and Mexico are leading adopters of oncology biosimilars, driven by increasing cancer prevalence and efforts to reduce healthcare costs. Similarly, in MEA, rising healthcare awareness and a growing emphasis on cost-effective cancer treatments are encouraging biosimilar adoption. However, limited healthcare infrastructure and varying regulatory standards pose challenges to widespread market growth in these regions. Despite these barriers, ongoing investments in healthcare and increasing awareness about biosimilars suggest future growth potential in both Latin America and MEA, particularly as regulatory frameworks become more standardized.
Key Player Analysis:
- Allergan (Ireland)
- Amneal Pharmaceuticals LLC. (U.S.)
- Apotex Inc. (Canada)
- Aurobindo Pharma (India)
- BIOCAD (Russia)
- Bristol-Myers Squibb Company (U.S.)
- Cipla Inc. (U.S.)
- Eli Lilly and Company (U.S.)
- Endo International plc (Ireland)
- Hoffmann-La Roche Ltd. (Switzerland)
- GlaxoSmithKline plc (U.K.)
- Glenmark Pharmaceuticals Limited (India)
- Lupin (India)
- Mylan N.V. (U.S.)
- Novartis AG (Switzerland)
- Pfizer Inc. (U.S.)
- Sanofi (France)
- Sun Pharmaceutical Industries Ltd. (India)
- Takeda Pharmaceutical Company Limited (Japan)
- Teva Pharmaceutical Industries Ltd.(Israel)
- Zydus Cadila (India)
Competitive Analysis:
The oncology biosimilars market is highly competitive, with key players including Amgen Inc., Pfizer Inc., Sandoz International GmbH (a Novartis division), Celltrion Inc., and Biocon Ltd. These companies leverage advanced R&D capabilities, strategic alliances, and extensive distribution networks to gain market share. Major firms focus on biosimilars for leading oncology biologics like trastuzumab, bevacizumab, and rituximab, aiming to capture demand for affordable cancer therapies. The competitive landscape is characterized by continuous innovation and collaboration; companies frequently partner to expedite product development and navigate regulatory processes efficiently. Furthermore, competition is intensifying as new entrants from emerging markets, particularly in Asia-Pacific, introduce cost-effective biosimilars. Regulatory support in regions like North America and Europe also drives competition by streamlining approval pathways. In this evolving landscape, success hinges on a company’s ability to balance quality, pricing, and availability, making strategic alliances and technological advancements critical to maintaining a competitive edge.
Recent Developments:
- Teva Pharmaceuticals and mAbxience expanded their strategic partnership on October 3, 2024, to include the development of an anti-PD-1 oncology biosimilar candidate. This marks their second collaboration since April 2024 and aligns with Teva's Pivot to Growth strategy
Market Concentration & Characteristics:
The oncology biosimilars market is moderately concentrated, with a few dominant players holding a significant share due to their advanced R&D capabilities, established distribution networks, and regulatory expertise. Companies like Amgen, Pfizer, and Sandoz have led the market due to early entry, strong biosimilar portfolios, and significant investment in clinical research. These established firms leverage economies of scale and strategic alliances to maintain competitive advantages, making it challenging for smaller companies to gain a foothold. Market characteristics include high entry barriers due to stringent regulatory requirements, complex manufacturing processes, and the need for clinical trials to demonstrate safety and efficacy. Despite these barriers, competition is intensifying with new entrants, particularly from Asia-Pacific, where cost-effective manufacturing options are prevalent. The market is also characterized by price sensitivity, driving companies to balance affordability with quality, as biosimilars must offer substantial cost savings over branded biologics to appeal to healthcare providers and patients.
Report Coverage:
The research report offers an in-depth analysis based on By Drug, By Disease Indication and By Distribution Channel. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Rising cancer incidence globally will drive increased demand for cost-effective oncology biosimilars.
- Expiring patents on major biologics will open up new opportunities for biosimilar entrants.
- Advances in biotechnology will streamline biosimilar development and reduce production costs.
- Regulatory support in North America and Europe will accelerate biosimilar approvals and market entry.
- Asia-Pacific is poised for rapid growth due to expanding healthcare access and favorable policies.
- Increased healthcare budget constraints will push providers to adopt biosimilars for cancer treatment.
- Partnerships between biotech firms and local manufacturers will enhance market reach, especially in emerging markets.
- Price competition among biosimilar developers will further lower treatment costs and boost adoption.
- Improved patient education and physician confidence in biosimilars will increase market acceptance.
- Growing investment in R&D will result in more advanced oncology biosimilars with enhanced efficacy and safety profiles.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Cancer Incidence and Demand for Cost-effective Therapies
The global increase in cancer cases is driving demand for affordable treatment options, making biosimilars attractive due to their lower cost compared to branded biologics. This is especially important for healthcare systems facing budget constraints and for patients in need of accessible therapies.
Expiring Patents of Major Biologics
The expiration of patents on blockbuster oncology biologics such as trastuzumab, bevacizumab, and rituximab is opening the market to biosimilar competition. This enables more manufacturers to enter the market, increases treatment options, and drives down prices.
Government Initiatives and Supportive Regulatory Frameworks
Governments and regulatory agencies are actively promoting biosimilar adoption through clear approval pathways, reimbursement incentives, and cost-containment policies. These measures are accelerating biosimilar development and market entry, particularly in North America and Europe.
Advancements in Biotechnology and Manufacturing
Improvements in cell line development, purification, and analytical methods have enhanced the quality and efficiency of biosimilar production. These technological advances reduce manufacturing costs and ensure biosimilars closely match reference biologics in safety and efficacy, supporting broader adoption.
Expansion in Emerging Markets
Pharmaceutical companies are investing in local manufacturing and partnerships in regions like Asia-Pacific and Latin America, where cancer incidence is rising and healthcare infrastructure is improving. Favorable government policies and increasing biosimilar approvals in these regions are fueling rapid market growth.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected growth of the oncology biosimilars market?
What factors are driving the growth of oncology biosimilars?
Which regions are the largest markets for oncology biosimilars?
What challenges does the oncology biosimilars market face?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Drug
- 1.2.1 G-CSF
- 1.2.2 Monoclonal Antibody
- 1.2.3 Hematopoietic Agents
- 1.3 By Disease Indication
- 1.3.1 Breast Cancer
- 1.3.2 Non-Small Cell Lung Cancer
- 1.3.3 Colorectal Cancer
- 1.3.4 Neutropenia
- 1.3.5 Blood Cancer
- 1.3.6 Leukemia
- 1.3.7 Myeloid Leukemia
- 1.3.8 Chronic Lymphocytic Leukemia (CLL)
- 1.3.9 Non-Hodgkin Lymphoma
- 1.3.10 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 4,725 million → 2032: USD 23,341.41 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Oncology Biosimilars Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Oncology Biosimilars Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Oncology Biosimilars Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Oncology Biosimilars Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Oncology Biosimilars Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Oncology Biosimilars Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Oncology Biosimilars Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Oncology Biosimilars Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 4,725 million → 2032: USD 23,341.41 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Oncology Biosimilars Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Drug - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 G-CSF
- 12.3.7.2 Monoclonal Antibody
- 12.3.7.3 Hematopoietic Agents
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Disease Indication - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Breast Cancer
- 12.4.7.2 Non-Small Cell Lung Cancer
- 12.4.7.3 Colorectal Cancer
- 12.4.7.4 Neutropenia
- 12.4.7.5 Blood Cancer
- 12.4.7.6 Leukemia
- 12.4.7.7 Myeloid Leukemia
- 12.4.7.8 Chronic Lymphocytic Leukemia (CLL)
- 12.4.7.9 Non-Hodgkin Lymphoma
- 12.4.7.10 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 Global Oncology Biosimilars Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Oncology Biosimilars Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Oncology Biosimilars Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Amgen Inc.
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Pfizer Inc.
- 17.4 Sandoz (Novartis AG)
- 17.5 Celltrion Inc.
- 17.6 Biocon Ltd.
- 17.7 Teva Pharmaceutical Industries Ltd.
- 17.8 Samsung Bioepis
- 17.9 Mylan N.V.
- 17.10 Roche (Hoffmann-La Roche Ltd.)
- 17.11 Cipla Inc.
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

